Release – Snail Games Highlights IP Expansion, Internal Development and Upcoming Releases at Gamescom 2026

Snail, Inc logo

Research News and Market Data on SNAL

August 27, 2026 at 9:00 AM EDT

PDF Version

CULVER CITY, Calif., Aug. 27, 2026 (GLOBE NEWSWIRE) — Snail, Inc. (Nasdaq: SNAL) (“Snail Games” or the “Company”), a leading independent global developer and publisher of interactive digital entertainment, showcased a broad portfolio of established intellectual properties, internally developed titles, major content launches, and upcoming releases during the first day of Gamescom 2026.

Snail Games CEO, Hai Shi, officially unveiled 9 Yin Sutra: Wuxia, an internally developed AAA title expanding the universe inspired by the Company’s Age of Wushu. The Age of Wushu IP now serves as the foundation for two creative universes: 9 Yin Sutra: Wuxia and 9 Yin Sutra: Immortal. While both titles originate from the same underlying IP, the games are being developed as distinct interpretations of that universe. 9 Yin Sutra: Wuxia draws more heavily from historical Wuxia traditions and represents the closest sequel to Age of Wushu, while 9 Yin Sutra: Immortal offers a more fantastical take on the fast-growing cultivation genre. This differentiated approach is intended to broaden the creative potential of the IP while providing each title with its own unique identity, setting, tone, and gameplay experience. Players can watch the Gamescom 2026 official announcement trailer and wishlist 9 Yin Sutra: Wuxia and 9 Yin Sutra: Immortal.

Snail Games also showcased For The Stars, another internally developed AAA title, through a new gameplay trailer and exclusive demos for members of the media attending Gamescom. The demos provided media with an opportunity to experience the game ahead of its broader release and offered additional insight into the title’s development.

The Company views internally developed titles For The Stars, 9 Yin Sutra: Wuxia, and 9 Yin Sutra: Immortal as an important component of its broader portfolio strategy, providing opportunities to develop new intellectual properties and expand existing franchises through proprietary development capabilities.

Snail Games also highlighted continued investment in its established portfolio. PixARK is officially launching its premium Terracrypt DLC, adding 200+ hours of new content to the survival sandbox experience. While ARK: Survival Ascended is launching a major ARK: Astraeos update alongside a new trailer, further expanding the ARK ecosystem.

Bellwright was featured at Gamescom with a new playable demonstration. The demo provides an early look at planned traversal features. The continued development of community inspired features is intended to expand player loyalty as the title progresses.

And Honeycomb: The World Beyond received an exclusive Gamescom showcase ahead of its September 8 launch. Gamescom attendees were given access to the latest playable demo, providing an opportunity to experience the game ahead of release. Players unable to attend Gamescom will also have an opportunity to experience the new demo, which is scheduled to become available on August 31, ahead of the game’s official launch.

Snail Games’ first day at Gamescom highlighted a portfolio strategy built around multiple avenues of growth: extending successful intellectual properties, launching new premium content, developing new titles internally, and expanding access through additional platforms and player experiences.

For creators interested in collaborations please contact [email protected].

About Snail, Inc.
Snail, Inc. (Nasdaq: SNAL) is a leading global independent developer and publisher of interactive digital entertainment for consumers around the world, with a premier portfolio of premium games designed for use on a variety of platforms, including consoles, PCs, and mobile devices. For more information, please visit: https://snail.com/.

Forward-Looking Statements
This press release contains statements that constitute forward-looking statements. Many of the forward-looking statements contained in this press release can be identified by the use of forward-looking words such as “anticipate,” “believe,” “could,” “expect,” “should,” “plan,” “intend,” “may,” “predict,” “continue,” “estimate” and “potential,” or the negative of these terms or other similar expressions. These forward-looking statements include information about possible or assumed future results of Snail Games’ business, financial condition, results of operations, liquidity, plans and objectives. Forward-looking statements appear in a number of places in this press release and include, but are not limited to, statements regarding the Company’s strategy of expanding established intellectual properties while investing in internally developed games and new experiences; the differentiated approach broadening the creative potential of the IP while providing each title with its own distinct identity, setting, tone, and gameplay experience; internally developed titles being an important component of Snail Games’ broader portfolio strategy; providing opportunities to develop new intellectual properties and expand existing franchises through proprietary development capabilities; continuing investment in the Company’s established portfolio; planned traversal features for Bellwright; launching Honeycomb: The World Beyond on September 8; the new demo becoming available on August 31; Snail Games’ portfolio strategy being built around multiple avenues of growth: extending successful intellectual properties, launching new premium content, developing new titles internally, and expanding access through additional platforms and player experiences; and assumptions underlying any of the foregoing. Further information on risks, uncertainties and other factors that could affect Snail Games’ financial results and business include Snail Games’ ability to develop new intellectual properties and expand existing franchises through its proprietary development capabilities; Snail Games’ ability to incorporate traversal features for Bellwright, crossplay integration across Steam, Xbox, and PlayStation and launch Honeycomb: The World Beyond and its new demo as planned; Snail Games’ ability to achieve multiple avenues of growth by extending successful intellectual properties, launching new premium content, developing new titles internally, and expanding access through additional platforms and player experiences; Snail Games’ ability to retain its key employees or maintain its Nasdaq listing; and the risks that are included in its filings with the Securities and Exchange Commission (the “SEC”) from time to time, including its annual reports on Form 10-K and quarterly reports on Form 10-Q filed, or to be filed, with the SEC. You should not rely on these forward-looking statements, as actual outcomes and results may differ materially from those expressed or implied in the forward-looking statements as a result of such risks and uncertainties. All forward-looking statements in this press release are based on management’s beliefs and assumptions and on information currently available to Snail Games, and Snail Games does not assume any obligation to update the forward-looking statements provided to reflect events that occur or circumstances that exist after the date on which they were made.

Investor Contact:
John Yi and Steven Shinmachi
Gateway Group, Inc.
949-574-3860
[email protected]
Release – Alliance Entertainment to Host Fiscal Year 2026 Results Conference Call on September 10 at 4:30 p.m. Eastern Time

Research News and Market Data on AENT

PLANTATION, Fla., Aug. 27, 2026 (GLOBE NEWSWIRE) — Alliance Entertainment Holding Corporation (Nasdaq: AENT), a premier distributor, logistics provider, and omnichannel fulfillment partner to the entertainment and pop culture collectibles industry, supplying more than 340,000 unique SKUs across physical media, video games, toys, licensed merchandise, and exclusive collectibles to over 35,000 retail and e-commerce storefronts, will hold a conference call on Thursday, September 10, at 4:30 p.m. Eastern Time to discuss its results for the fiscal year ended June 30, 2026. A press release detailing these results will be issued prior to the call.

Alliance Entertainment Chief Executive Officer Jeff Walker, Chief Financial Officer Amanda Gnecco, and Executive Chairman Bruce Ogilvie will host the conference call, which will be followed by a question-and-answer session. A presentation will accompany the call and can be viewed during the webcast or accessed via the investor relations section of the Company’s website here.

To access the call, please use the following information:

Date:Thursday, September 10, 2026
Time:4:30 p.m. Eastern Time, 1:30 p.m. Pacific Time
Toll-free dial-in number:1-877-407-0784
International dial-in number:1-201-689-8560
Conference ID:13762431

Please call the conference telephone number 5-10 minutes prior to the start time. An operator will register your name and organization. If you have any difficulty connecting with the conference call, please contact RedChip Companies at 1-407-644-4256.

The conference call will be broadcast live and available for replay at https://viavid.webcasts.com/starthere.jsp?ei=1774079&tp_key=92e32c8d84 and via the investor relations section of the Company’s website here.

A telephone replay of the call will be available approximately three hours after the call concludes and can be accessed through October 10, 2026, using the following information:

Toll-free replay number:1-844-512-2921
International replay number:1-412-317-6671
Replay ID:13762431


About Alliance Entertainment

Alliance Entertainment (NASDAQ: AENT) is a premier distributor and fulfillment partner for the entertainment and pop culture collectibles industry. With more than 340,000 unique in-stock SKUs – including over 57,300 exclusive titles across compact discs, vinyl LPs, DVDs, Blu-rays, and video games – Alliance offers the largest selection of physical media in the market. Our vast catalog also includes licensed merchandise, toys, retro gaming products, and collectibles, serving over 35,000 retail locations and powering e-commerce fulfillment for leading retailers. Alliance also owns and operates proprietary collectibles brands, including Handmade by Robots™, a stylized vinyl figure line featuring licensed characters from leading entertainment franchises, and Alliance Authentic™, a premium platform for authentic, certified, and individually numbered entertainment collectibles. In addition, Alliance operates Endstate Authentic, a dedicated NFC-enabled authentication and digital product identity platform supporting authenticated collectibles, resale, and brand protection. Leveraging decades of operational expertise, exclusive sourcing relationships, and a capital-light, scalable infrastructure, Alliance connects fans and collectors to the products, franchises, and experiences they value across formats and generations. For more information, visit www.aent.com.

For investor inquiries, please contact:

Dave Gentry
RedChip Companies, Inc.
1-800-REDCHIP (733-2447)
1-407-644-4256
[email protected]

Release – Lucky Strike Entertainment Reports Fourth Quarter and Full Year Results for Fiscal Year 2026

 Lucky Strike Entertainment Investor Relations site

Research News and Market Data on LUCK

08/27/2026

  • Total Revenue Growth of 0.9% in Fourth Quarter 2026
  • Continued expansion of Lucky Strike brand with 159 current Lucky Strike locations
  • Continued efforts to deploy capital efficiently, driving long-term returns

RICHMOND, Va.–(BUSINESS WIRE)– Lucky Strike Entertainment (NYSE: LUCK), one of the world’s premier owner/operators of location-based entertainment, today provided financial results for the fourth quarter and full year of fiscal year 2026, which ended on June 28, 2026.

Quarter Highlights:

  • Total revenue increased 0.9% to $303.9 million versus 4Q25
  • Same-Store Revenue decreased 2.5% versus 4Q25
  • Net loss of $26.2 million versus net loss of $74.7 million in 4Q25
  • Adjusted EBITDA of $74.1 million versus $88.7 million in 4Q25

Fiscal Year Highlights:

  • Revenue increased 3.7% to $1,245.3 million versus the prior year
  • Same Store Revenue decreased 0.2% versus the prior year
  • Net loss of $35.8 million versus prior year net loss of $10.0 million
  • Adjusted EBITDA of $333.2 million versus prior year of $367.7 million
  • Added six locations during the fiscal year, five through acquisitions and one new build. Additionally, closed five underperforming locations
  • Total locations in operation as of August 27, 2026, were 366

“Fiscal 2026 marked a meaningful step forward for our business, with our strongest same-store sales performance in years and clear momentum across many of our key revenue streams,” said Thomas Shannon, Founder and CEO. “Importantly, that momentum is broadening. Cumulative organic growth was positive through the first eleven months of the fiscal year, with June driving the full-year decline. Leagues grew and accelerated through the spring, food remained strongly positive, retail bowling continued to grow, and Events turned positive in late spring for the first time in years and remained positive throughout the summer. It is the strongest sustained performance we have seen from that business in a long time.”

“June temporarily interrupted that progress. The first World Cup on American soil in a generation drew millions of consumers to their screens on nights they would typically be out, resulting in sharply negative comps for the month and pulling an otherwise positive quarter and year slightly below zero. We believe it is important to distinguish that temporary disruption from the underlying health of the business. Trends improved immediately following the World Cup Final, and this headwind will not repeat next summer. At our waterparks, a cool and wet start to the summer pressured attendance, but strong pricing and disciplined cost management helped protect profitability.”

“Waterparks represented the biggest operational step forward for us this summer. A year ago, we directly managed only a couple of parks. This summer, we operated a diverse portfolio, including our newest park in Los Angeles, and the organization executed exceptionally well. Per-capita spending increased meaningfully, labor costs declined as we aligned staffing more closely with demand, and both revenue and profitability grew substantially year over year. Importantly, the majority of the summer earnings contribution will be recognized in our September quarter.”

“I have described our business as a coiled spring, and that is exactly how we see it. We are pairing operating momentum with a structurally more disciplined approach to capital allocation. Capital expenditures are down approximately $80 million from their fiscal 2024 peak, and we expect to continue reducing capital spending as we further rationalize the portfolio and complete several existing investment programs. That creates a clear path to meaningfully higher free cash flow and accelerated deleveraging as earnings improve. As we enter fiscal 2027, our guidance is intentionally prudent and reflects the way we are approaching the current environment. We believe the combination of operating momentum, declining capital intensity and financial discipline positions us to deliver profitable growth, stronger free cash flow and a meaningfully improved balance sheet.”

Fiscal Year 2027 Guidance

We remain focused on delivering sustainable, profitable growth and creating meaningful long-term shareholder value. Our strategy is centered on accelerating revenue growth, expanding operating cash flow, and driving higher free cash flow per share through earnings growth and disciplined capital allocation. Looking ahead, our outlook reflects continued organic revenue growth, targeted investments in marketing and technology to strengthen our platform, and incremental contributions from our waterparks in FY27. Together, these initiatives position us to generate stronger cash flow, improve returns on invested capital, and build a more durable earnings growth profile.

Total Revenue Growth:3% to 5%
Total Revenue:$1,280M to $1,310M
Adjusted EBITDA:$340M to $360M
Capital Expenditures:Approximately $90M

Dividend Declaration

On August 27, 2026, the Board of Directors declared a quarterly cash dividend of $0.06 per share of common stock for the first quarter of fiscal year 2027. The dividend will be payable on September 22, 2026, to stockholders of record on September 8, 2026.

Investor Webcast Information

Listeners may access an investor webcast hosted by Lucky Strike Entertainment. The webcast and results presentation will be accessible at 9:00 AM ET on August 27, 2026, in the Events & Presentations section of the Lucky Strike Entertainment Investor Relations website at https://ir.luckystrikeent.com/.

About Lucky Strike Entertainment

Lucky Strike Entertainment is one of the world’s premier location-based entertainment platforms. With over 360 locations across North America, Lucky Strike Entertainment provides experiential offerings in bowling, amusements, water parks, and family entertainment centers. The Company also owns the Professional Bowlers Association, the major league of bowling and a growing media property that boasts millions of fans around the globe. For more information on Lucky Strike Entertainment, please visit IR.LuckyStrikeEnt.com.

Forward Looking Statements

Some of the statements contained in this press release are forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, that involve risk, assumptions, and uncertainties, such as statements of our plans, objectives, expectations, intentions, and forecasts. These forward-looking statements reflect our views with respect to future events as of the date of this release and are based on our management’s current expectations, estimates, forecasts, projections, assumptions, beliefs, and information. Although management believes that the expectations reflected in these forward-looking statements are reasonable, it can give no assurance that these expectations will prove to have been correct. All such forward-looking statements are subject to risks and uncertainties, many of which are outside of our control, and could cause future events or results to be materially different from those stated or implied in this document. It is not possible to predict or identify all such risks. These risks include, but are not limited to: our ability to design and execute our business strategy; changes in consumer preferences and buying patterns; our ability to compete in our markets; the occurrence of unfavorable publicity; risks associated with long-term non-cancellable leases for our locations; our ability to retain key managers; risks associated with our substantial indebtedness and limitations on future sources of liquidity; our ability to carry out our expansion plans; our ability to successfully defend litigation brought against us; failure to hire and retain qualified employees and personnel; cybersecurity breaches, cyber-attacks and other interruptions to our and our third-party service providers’ technological and physical infrastructures; catastrophic events, including war, terrorism and other conflicts; public health emergencies and pandemics, such as the COVID-19 pandemic, or natural catastrophes and accidents; fluctuations in our operating results; economic conditions, including the impact of increasing interest rates, inflation and recession; and other factors described under the section titled “Risk Factors” in the Company’s Annual Report on Form 10-K filed with the U.S. Securities and Exchange Commission (the “SEC”) by the Company on August 27, 2026, as well as other filings that the Company will make, or has made, with the SEC, such as Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. These factors should not be construed as exhaustive and should be read in conjunction with the other cautionary statements that are included in this press release and in other filings. We expressly disclaim any obligation to publicly update or review any forward-looking statements, except as required by applicable law.

Non-GAAP Financial Measures

To provide investors with information in addition to our results as determined under Generally Accepted Accounting Principles (“GAAP”), we disclose Same Store Revenue and Adjusted EBITDA as “non-GAAP measures”, which management believes provide useful information to investors because each measure assists both investors and management in analyzing and benchmarking the performance and value of our business. Accordingly, management believes that these measurements are useful for comparing general operating performance from period to period, and management relies on these measures for planning and forecasting of future periods. Additionally, these measures allow management to compare our results with those of other companies that have different financing and capital structures. These measures are not financial measures calculated in accordance with GAAP and should not be considered as a substitute for revenue or net income as calculated in accordance with GAAP, and may not be comparable to a similarly titled measure reported by other companies. Our fiscal year 2027 guidance measures (other than revenue) are provided on a non-GAAP basis without a reconciliation to the most directly comparable GAAP measure because the Company is unable to predict with a reasonable degree of certainty certain items contained in the GAAP measures without unreasonable efforts. For the same reasons, the Company is unable to address the probable significance of the unavailable information. Such items include, but are not limited to, acquisition-related expenses, share-based compensation, and other items not reflective of the company’s ongoing operations.

Same Store Revenue represents total Revenue less Non-Location Related Revenue, Revenue from Closed Locations, Service Fee Revenue, if applicable, and Acquired Revenue. Adjusted EBITDA represents Net Income (Loss) before Interest Expense, Income Taxes, Depreciation and Amortization, Impairment and Other Charges, Share-based Compensation, EBITDA from Closed Locations, Foreign Currency Exchange Loss (Gain), Asset Disposition Loss (Gain), Transactional and other advisory costs, System modernization costs, changes in the value of earnouts, and other.

The Company considers Same Store Revenue as an important financial measure because it provides comparable revenue for locations open for the entire duration of both the current and comparable measurement periods.

The Company considers Adjusted EBITDA as an important financial measure because it provides a financial measure of the quality of the Company’s earnings. Other companies may calculate Adjusted EBITDA differently than we do, which might limit its usefulness as a comparative measure. Adjusted EBITDA is used by management in addition to and in conjunction with the results presented in accordance with GAAP. We have presented Adjusted EBITDA solely as a supplemental disclosure because we believe it allows for a more complete analysis of results of operations and assists investors and analysts in comparing our operating performance across reporting periods on a consistent basis by excluding items that we do not believe are indicative of our core operating performance. Adjusted EBITDA has limitations as an analytical tool, and you should not consider it in isolation or as a substitute for analysis of our results as reported under GAAP.

View full release here.

Lucky Strike Entertainment Corporation Investor Relations
[email protected]

Source: Lucky Strike Entertainment Corporation

Nvidia’s Quiet Growth Engine Is Now Orbiting the Earth

Nvidia posted another blowout quarter, but the number turning heads inside the report wasn’t the headline figure. It was how much of that growth is now tied to a single, increasingly inseparable partner: SpaceX.

Nvidia reported fiscal second quarter revenue of $96.2 billion, up 106% year over year, with Data Center sales reaching $89.0 billion, up 117%. Strong as those numbers are, the more interesting story sits in the guidance and buildout plans layered underneath them, specifically the expanding role SpaceX now plays in Nvidia’s roadmap.

On the earnings call, CFO Colette Kress confirmed that Nvidia’s next-generation Vera CPU is already shipping to its earliest customers, with SpaceX’s AI unit, SpaceXAI, among the first in line. Kress said Nvidia expects Vera to be deployed across every major hyperscaler, neocloud, AI lab, and system OEM, with shipments already underway to lead partners including Oracle, SpaceXAI, and, starting this quarter, Amazon.

Nvidia does not disclose customer-level revenue, so SpaceX’s exact contribution has to be estimated from outside analysis. Deepwater Asset Management’s Gene Munster estimated on social media that SpaceX now accounts for roughly 5% of Nvidia’s overall revenue, up from around 3% last quarter. He noted that Nvidia appears to have reclassified SpaceX’s revenue out of its AI, Clouds, Industrials, and Enterprise category and into its Hyperscaler category, a shift he attributed to SpaceX’s plan to bring 8 gigawatts of compute capacity online next year, putting it in the same tier as Meta and Amazon. Applied to Nvidia’s $96.2 billion in quarterly revenue, that 5% estimate works out to nearly $5 billion tied to SpaceX. It’s worth noting this figure is an outside analyst’s estimate, not a number Nvidia itself has confirmed.

The relationship goes beyond chip orders. Nvidia also highlighted that SpaceXAI will adopt its Vera CPU to power the agentic AI workloads behind Grok, xAI’s chatbot, handling code execution and data processing so that Nvidia’s GPUs can stay focused on core AI compute. SpaceXAI president Mike Nicolls said Vera gives the company the CPU performance and memory bandwidth needed to manage that orchestration and data load at scale.

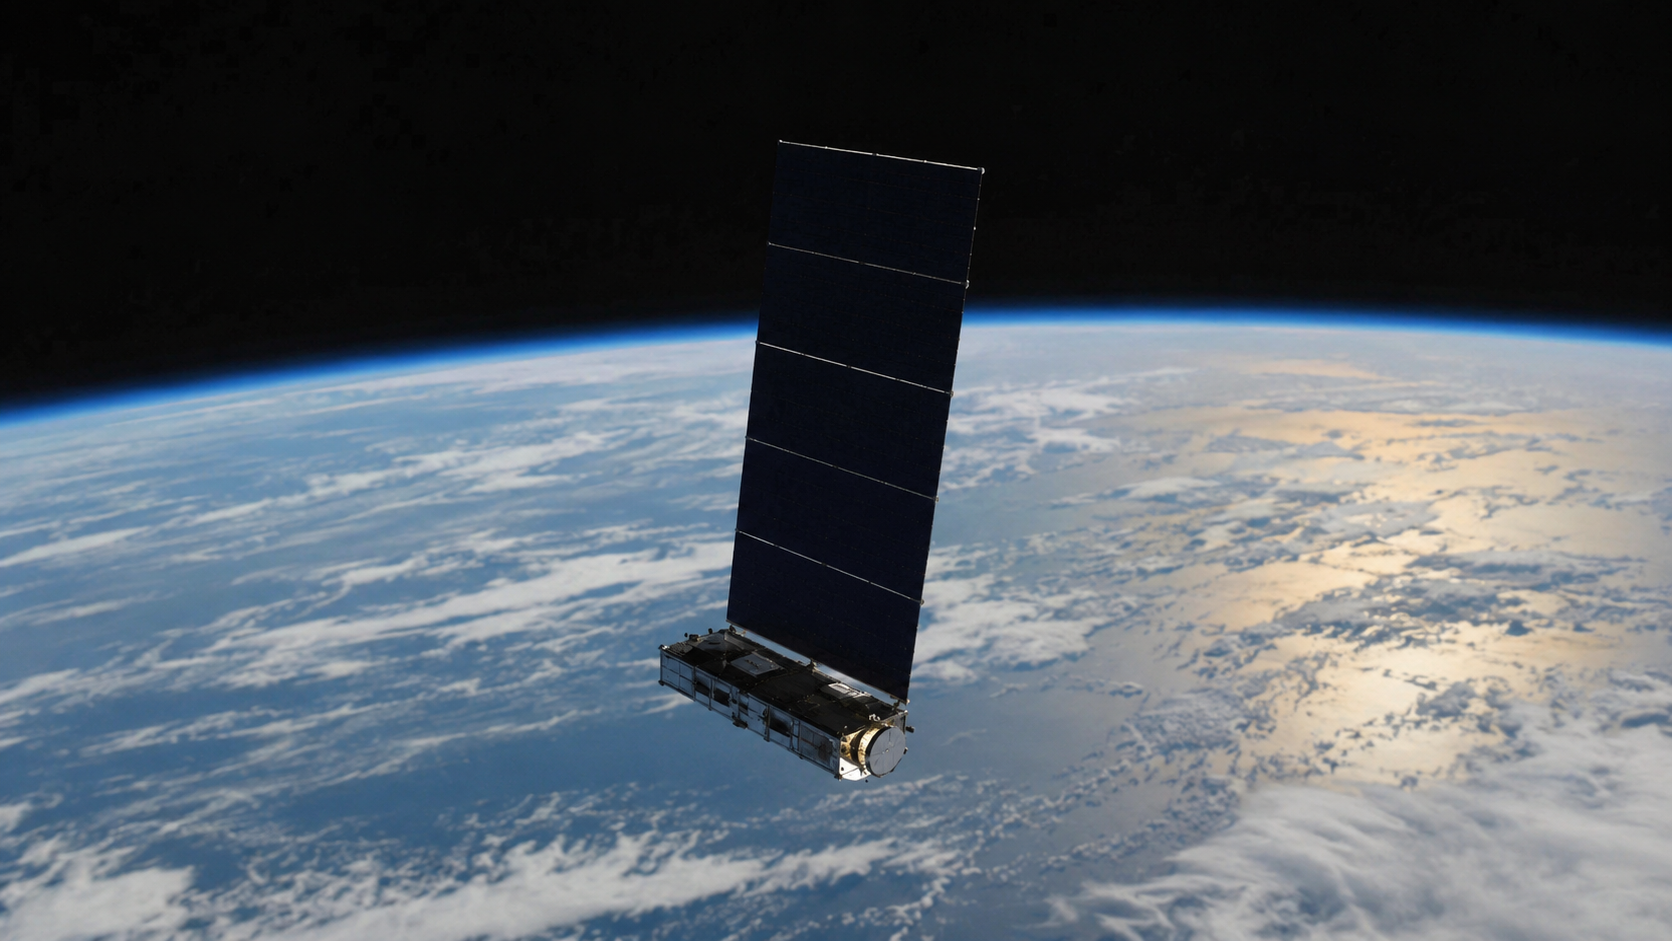
Perhaps the most striking development is where some of this hardware is headed next. Earlier this week, the two companies confirmed plans for a space-optimized Vera Rubin NVL72 rack-scale system, designed to launch aboard SpaceX’s first-generation Starmind satellite in the fourth quarter of 2027, with a larger-scale version planned for 2028. The satellite’s AI1 design carries a 120-kilowatt compute payload, peaking at 150 kilowatts, effectively taking Nvidia’s data center hardware into orbit.

Taken together, the picture is one of two companies becoming increasingly dependent on each other in different directions. For Nvidia, SpaceX has become both a major terrestrial customer and the delivery vehicle for putting its chips in space. For SpaceX, Nvidia’s hardware is becoming the computing backbone behind its AI ambitions, from Earth-based data centers to orbital compute payloads.

Direct Digital Holdings (DRCT) – Liquidity Overshadows Underlying Stability


Thursday, August 27, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q2 results. Second-quarter revenue of $7.8 million declined 23% year over year and came in 11% below our $8.8 million estimate. The shortfall was concentrated among demand-side platform customers, with spending falling to zero from $2.5 million in the prior-year quarter. Excluding DSP customers, revenue grew 3% in the quarter and 5% year-to-date, suggesting the core managed-campaign business is roughly stable even as the reported line contracts.


Gross margin held with disciplined spending. Gross profit of $2.7 million represented 34% of revenue, down modestly from 35% a year ago and flat with the first quarter. Operating expenses of $5.6 million declined 7% year over year. The adjusted EBITDA loss widened to $2.3 million from $1.5 million a year earlier, well short of our $0.35 million loss estimate, and management’s second-half breakeven target now looks difficult to reach.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

The PCE Data Just Came In. It Tilts Toward a September Rate Hike, Not Away From It

The Personal Consumption Expenditures price index, the inflation measure the Federal Reserve targets most closely, rose 3.7% year over year in July, up from 3.6% in June, the Commerce Department reported Wednesday, coming in a touch stronger than economists had expected. Core PCE, which strips out volatile food and energy prices and is viewed as the cleaner read on underlying inflation pressure, held at 3.3% year over year, showing no improvement from the prior month.

This is the exact data release we flagged as pivotal heading into Fed Chair Kevin Warsh’s upcoming Jackson Hole speech, and it landed on the more hawkish side of the range economists had modeled. The result directly conflicts with earlier reports that had shown consumer price inflation cooling over the prior couple of months, reinforcing just how genuinely unresolved the inflation picture remains heading into the fall.

The Fed has held its policy rate steady in a range of 3.50% to 3.75% since December. Warsh has publicly committed to bringing inflation back to target, but has offered no clear signal on whether he believes that can happen without additional rate increases, and Wednesday’s data does nothing to support the case that it will happen on its own. Heather Long, chief economist at Navy Federal Credit Union, put it bluntly, the United States still has an inflation problem, and argued the latest data buys Warsh some time to wait and assess, but that he will need to be considerably clearer about what specific conditions would actually prompt him to raise rates.

Markets moved quickly to reprice the odds. Fed funds futures now reflect roughly a 44% probability of a September rate hike, up from about 36% just before this report, and traders are now fully pricing in that the Fed will have raised its policy rate by year end.

For companies operating below the $2 billion market cap threshold, this shift in rate expectations carries direct and immediate consequences. Small and microcap businesses typically carry considerably more variable-rate debt than large cap companies, meaning every incremental increase in the probability of a Fed hike translates into a real, measurable increase in borrowing costs across this segment of the market. This report also sharpens the stakes for Warsh’s Jackson Hole address, which now arrives with markets meaningfully more convinced a hike is coming than they were just days ago, making his tone and language around this data the most consequential signal small cap investors will get before the Fed’s actual September decision.

Tectonic Metals Inc. (TETOF) – Black Creek Emerges as a Second Gold Center


Wednesday, August 26, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Flat is advancing rapidly. Tectonic is executing a five-rig, 40,000-meter drilling program at its flagship Flat Gold Project, with the primary objective of supporting a maiden NI 43-101 mineral resource estimate at Chicken Mountain in early 2027. The program is also targeting higher-grade mineralization and testing additional district-scale targets. The Chicken Mountain–Alpha Bowl system has already been traced for approximately 3.3 kilometers.

Black Creek is emerging as a second gold center. Tectonic released assay results from three holes drilled at the Black Creek target, including two reverse circulation and one diamond drill hole. Hole CMR26-152 returned 5.09 g/t gold over 21.34 meters, including 17.34 g/t over 6.10 meters. Hole CMR26-153 intersected a broader interval of 1.89 g/t over 57.91 meters, including 2.75 g/t over 38.10 meters, with higher-grade intervals of 6.31 g/t over 7.62 meters and 3.89 g/t over 6.10 meters. Diamond hole CMD26-041 returned 3.26 g/t over 5.06 meters and a deeper interval grading 16.73 g/t over 2.22 meters, including 29.91 g/t over 1.22 meters. Importantly, both RC holes ended in mineralization, indicating that the system remains open thus providing clear targets for deeper follow-up drilling.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

SelectQuote (SLQT) – Cash Flow Inflection Takes Center Stage


Wednesday, August 26, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q4 profitability improves despite softer revenue. Fiscal fourth quarter revenue declined 7% to $321.7 million from $345.1 million in the prior-year period, while adj. EBITDA increased to $11.9 million from $2.7 million. Operating cash usage also improved sharply to $3.3 million from $37.5 million a year earlier, highlighting the company’s improving cash conversion. 

Healthcare Services emerges as a key earnings driver. Healthcare Services generated Q4 revenue of $193.5 million and adj. EBITDA of $12.1 million, with SelectRx membership of approximately 109,000. Importantly, prescription utilization continues to increase even as membership growth moderates, while the Olathe facility provides capacity for more than 200,000 members and meaningful opportunity for additional operating leverage. 


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

GDEV (GDEV) – Profitability Outpaces Growth As Bookings Soften


Wednesday, August 26, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q2 Results. GDEV reported Q2 revenue of $93.6 million, down 22%, and adj. EBITDA of $20.1 million, only down 7% year over year. Notably, the year-over-year revenue decrease was primarily driven by a decline in bookings. As illustrated in Figure #1 Q2 Results, both revenue and adj. EBITDA missed our estimates of $115 million and $26 million, respectively, though adj. EBITDA proved far more resilient than revenue.

Marketing discipline held margins. That resilience was largely due to lower selling and marketing expenses, which fell 38% to $32.7 million from $52.5 million, lifting the adj. EBITDA margin to roughly 21% from 18% even as revenue declined. The reduction stems from the company’s more disciplined strategy for user acquisition, which focuses on higher-value cohorts rather than volume.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

A Private Aviation Company Just Signed a $500 Million Deal to Become an AI Data Center Operator

Volato Group (NYSE American: SOAR), which built its business around AI-powered software for aviation and operates the Vaunt private aviation membership marketplace, has signed a definitive agreement to merge with Alignment Engine, an Ohio-based AI infrastructure company, in a transaction valuing Alignment Engine at approximately $500 million. Volato will remain the publicly traded parent company once the deal closes, but the combination represents a complete transformation of what the company actually does, pivoting from aviation technology toward data centers, high-performance computing, and AI infrastructure.

The centerpiece of the deal is Alignment Engine’s powered industrial campus in Ohio, which currently has 154 megawatts of available power with total planned capacity of 480 megawatts. Volato intends to use that infrastructure to support high-performance GPU compute and networking for AI training and inference, along with other compute-intensive workloads, positioning the combined company to lease or operate data center capacity for AI customers rather than continuing to build aviation software.

This transaction did not appear out of nowhere. In June, Volato secured a $2.2 million strategic investment led by Catheter Precision specifically to strengthen its balance sheet while it evaluated acquisition and merger opportunities in AI infrastructure, data infrastructure, compute, and power generation. That investment came shortly after Volato terminated a previously announced transaction with a different party, and the company disclosed at the time it had already received two unsolicited, non-binding letters of intent related to AI data center and power generation opportunities. This merger with Alignment Engine appears to be the outcome of that broader strategic search.

Investors need to weigh this deal with real care. Volato is transforming from a small, aviation-focused company with no meaningful prior track record in data center development or operation into an AI infrastructure platform almost overnight. Alignment Engine’s power capacity is genuine and substantial, but having available power is only one piece of what it actually takes to build, finance, and operate a functioning data center campus at scale, additional capital for construction, cooling infrastructure, customer contracts, and specialized operational expertise all still need to come together. The company’s own recent history, including a terminated prior transaction and a small bridge investment just to fund due diligence on opportunities like this one, reflects a business still very much in transition rather than one with established execution in this space.

That said, the strategic logic behind the pivot is consistent with the broader data center construction boom we detailed in a recent cornerstone piece on this exact theme, where power availability has become one of the single largest bottlenecks constraining new AI infrastructure development nationally. A company with 154 megawatts already available, rather than merely planned, is positioning itself around a genuine scarcity in that buildout. Whether Volato can successfully execute on that opportunity, rather than simply owning the right raw materials, will be the real test in the months ahead.

The US and Canada Are in a Trade War. Here Is the One Product Both Sides Are Deliberately Leaving Alone

Trade talks between the United States and Canada collapsed over the weekend, prompting Washington to impose 50% tariffs on a wide range of Canadian goods, including furniture, dairy products, electrical equipment, and plywood. Canada’s Finance Department responded Tuesday with its own retaliatory tariffs. Markets, notably, barely flinched. The Dow, S&P 500, and Nasdaq all posted modest gains Tuesday, and the Russell 2000 advanced as well, suggesting investors are treating this escalation as manageable rather than systemically threatening, at least for now.

What makes this dispute genuinely interesting from a market perspective is not what got tariffed, it is what deliberately did not. Crude oil, one of the largest categories of trade flowing between the two countries, was left entirely out of the new 50% tariffs, and neither government appears eager to bring it into the fight.

Why Oil Is the One Line Neither Side Wants to Cross

The scale of that exemption is significant. The United States buys roughly 90% of all Canadian crude exports, worth approximately CA$126 billion of Canada’s CA$140 billion total in 2025, while Canada supplies roughly 63% of all US crude imports. That dependence reflects decades of physical infrastructure investment rather than a relationship either country could quickly unwind. Alberta’s oil sands produce heavy bitumen, and US refiners, particularly across the Midwest and Gulf Coast, spent billions of dollars building capacity specifically configured to process that heavier crude. Meanwhile, America’s own shale boom has made it the world’s largest oil producer, but that production is overwhelmingly light, sweet crude, creating a structural mismatch where the US exports large volumes of its own light oil while importing millions of barrels of heavier Canadian crude every single day.

Canada, for its part, has limited ability to simply redirect that oil elsewhere. The expanded Trans Mountain pipeline gives Alberta producers new access to Pacific coast export markets, but its roughly 890,000 barrel-per-day capacity is dwarfed by the nearly 3.9 million barrels shipped south to the US daily. President Trump acknowledged this interdependence directly in public comments this week, pointing to Canada’s own reliance on US infrastructure to move electricity, oil, and gas between its own provinces, a reference to cross-border pipeline routes like Enbridge’s Line 5, which carries Canadian oil through Wisconsin and Michigan before crossing back into Ontario. That mutual physical dependence is precisely why energy has remained exempt even as tariffs on nearly everything else have escalated sharply.

If oil were eventually pulled into this dispute, the consequences would ripple in multiple directions. US refiners, as the importers of record, would bear the tariff directly and would likely respond by demanding steeper discounts from Canadian producers, while also passing at least some of the higher input costs through to consumers at the pump, directly reversing the gas price relief seen earlier this summer. Canadian producers would face the opposite squeeze, a shrinking pool of buyers willing to pay full price for barrels with nowhere else to go at comparable volume.

For investors tracking the small and microcap space, this dispute carries two distinct layers of exposure. Companies with direct supply chain exposure to the newly tariffed categories, furniture, dairy, electrical components, and building materials like plywood, are facing real, immediate cost pressure right now. Energy-adjacent companies, meanwhile, are watching a very different, still-hypothetical risk: what happens if this trade fight eventually escalates into the one category both governments have so far treated as off-limits. Markets shrugging off Tuesday’s escalation suggests investors currently believe that line will hold. Whether it actually does may prove to be the more consequential question heading into the fall, particularly with the Fed’s Jackson Hole speech still ahead and the Treasury’s bond market intervention already testing how much stress the system can absorb at once.

Release – Euroseas Ltd. Announces 2-Year Charter Contract Extension for its Feeder Containership, M/V Jonathan P

logo

Research News and Market Data on ESEA

August 25, 2026 09:00 ET  | Source: Euroseas

ATHENS, Greece, Aug. 25, 2026 (GLOBE NEWSWIRE) — Euroseas Ltd. (NASDAQ: ESEA, the “Company” or “Euroseas”), an owner and operator of container carrier vessels and provider of seaborne transportation for containerized cargoes, announced today a time charter contract extension for its 2006-built 1,740 teu feeder containership, M/V Jonathan P, for a minimum period of 24 to a maximum period of 26 months, at the option of the charterer, at a gross daily rate of $26,000. The new period will commence at the end of October 2026, following the completion of the vessel’s scheduled dry-dock, and will run in direct continuation of the current charter contract.

Aristides Pittas, Chairman and CEO of Euroseas, commented: “We are very pleased to announce the extension of the time charter contract for our feeder containership, M/V Jonathan P, in direct continuation of her present charter, for 24-26 months at a profitable rate of $26,000/day. Despite the typical summer slowdown and ongoing geopolitical uncertainty, the containership charter market has remained active with strong operator demand and limited vessel availability continuing to firm charter terms both in terms of rates and contract periods. The charter is expected to generate approximately $12.7 million of EBITDA over the minimum contracted period and increases our charter coverage for 2026, 2027, and 2028 to about 97%, 86% and 50%, respectively.”

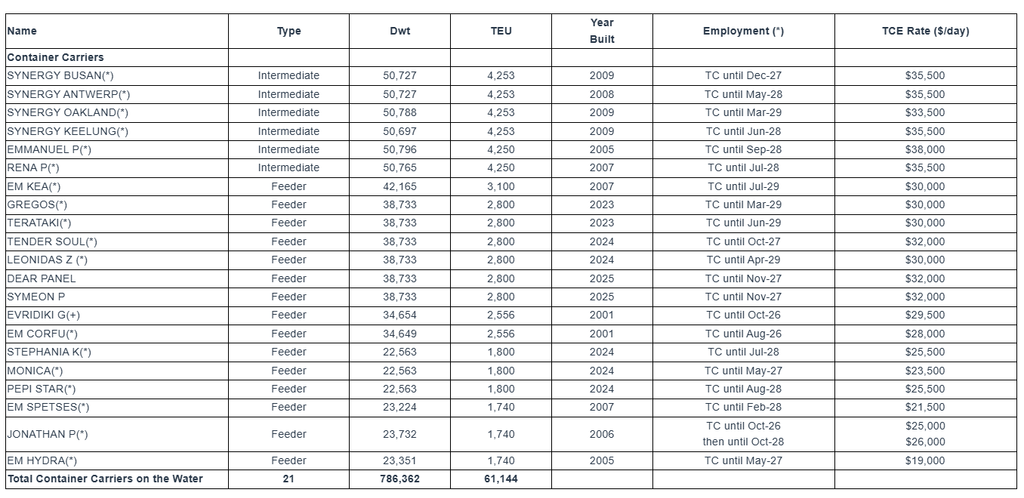
Fleet Profile:
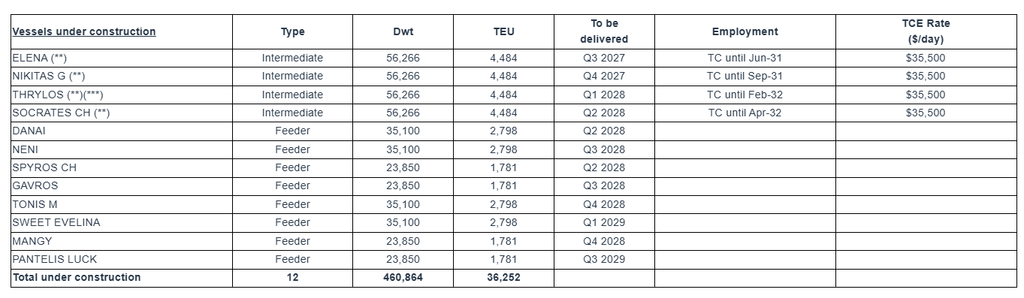
The Euroseas Ltd. fleet profile is currently as follows:


Notes:
(*) TC denotes time charter. Charter duration indicates the earliest redelivery date; all dates listed are the earliest redelivery dates under each TC unless the contract rate is lower than the current market rate in which cases the latest redelivery date is assumed; vessels with the latest redelivery date shown are marked by (+).
(**) Charterer has the option to convert to a five-year charter at $32,500/day for the entire period.
(***) The entity owning the vessel is 51% owned by Euroseas Ltd. and 49% by NRP Investors.

About Euroseas Ltd.

Euroseas Ltd. was formed on May 5, 2005 under the laws of the Republic of the Marshall Islands to consolidate the ship owning interests of the Pittas family of Athens, Greece, which has been in the shipping business over the past 150 years. Euroseas trades on the NASDAQ Capital Market under the ticker ESEA. 

Euroseas operates in the container shipping market. Euroseas’ operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company, which is responsible for the day-to-day commercial and technical management and operations of the vessels. Euroseas employs its vessels on spot and period charters and through pool arrangements. 

The Company has a fleet of 21 vessels, including 15 Feeder containerships and 6 Intermediate containerships with a cargo capacity of 61,144 teu. After the delivery of four intermediate and eight feeder containership newbuildings between 2027 and 2029, Euroseas’ fleet will consist of 33 vessels with a total carrying capacity of 97,396 teu.


Forward Looking Statement

This press release contains forward-looking statements (as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended) concerning future events and the Company’s growth strategy and measures to implement such strategy; including expected vessel acquisitions and entering into further time charters. Words such as “expects,” “intends,” “plans,” “believes,” “anticipates,” “hopes,” “estimates,” and variations of such words and similar expressions are intended to identify forward-looking statements. Although the Company believes that the expectations reflected in such forward-looking statements are reasonable, no assurance can be given that such expectations will prove to have been correct. These statements involve known and unknown risks and are based upon a number of assumptions and estimates that are inherently subject to significant uncertainties and contingencies, many of which are beyond the control of the Company. Actual results may differ materially from those expressed or implied by such forward-looking statements. Factors that could cause actual results to differ materially include, but are not limited to changes in the demand for containerships, competitive factors in the market in which the Company operates; risks associated with operations outside the United States; and other factors listed from time to time in the Company’s filings with the Securities and Exchange Commission. The Company expressly disclaims any obligations or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in the Company’s expectations with respect thereto or any change in events, conditions or circumstances on which any statement is based. 

Visit our website www.euroseas.gr

Company ContactInvestor Relations / Financial Media
Tasos Aslidis
Chief Financial Officer
Euroseas Ltd.
11 Canterbury Lane,
Watchung, NJ 07069
Tel. (908) 301-9091
E-mail: [email protected]
Nicolas Bornozis
Markella Kara
Capital Link, Inc.
230 Park Avenue, Suite 1540
New York, NY 10169
Tel. (212) 661-7566
E-mail: [email protected]

Release – GeoVax Advances GEO-MVA Toward Pivotal Phase 3 Study Implementation

GeoVax, Inc.

Research News and Market Data on GOVX

Selections of CRO and European Clinical Sites Represent Significant Milestones Toward Initiation of the GEO-MVA Immunobridging Study

ATLANTA, GA – August 25, 2026 – GeoVax Labs, Inc. (Nasdaq: GOVX), a clinical-stage biotechnology company developing vaccines and immunotherapies against infectious diseases and solid tumor cancers, today announced that it has selected the contract research organization (CRO) and European clinical trial sites planned to support the critical immunobridging portion of GEO-MVA-301, the Company’s pivotal Phase 3 clinical program evaluating GEO-MVA as a vaccine against mpox and smallpox.

The selections represent another important operational readiness milestone as GeoVax advances preparations for the European immunobridging study. The randomized, double-blind study is designed to compare the immunogenicity and safety of GEO-MVA with the licensed MVA vaccine in healthy adults.

The selected European clinical sites have extensive experience conducting late-stage vaccine studies and were evaluated for their ability to support timely recruitment across the study’s required adult age groups, intensive immunogenicity sampling, participant retention and high-quality clinical execution. GeoVax has also established contingency site capacity intended to provide additional recruitment flexibility if required.  The immunobridging study is designed to be completed within 8-12 weeks, initiated in Q4 2026, with results announced by mid-2027.

“Selection of our CRO and European clinical sites moves GEO-MVA another important step from development planning toward clinical execution,” said David Dodd, Chairman and Chief Executive Officer of GeoVax. “We now have critical components of the pivotal study infrastructure identified and aligned, and the program is increasingly taking shape as an execution-ready clinical program.”

Dodd continued, “These milestones are particularly important because they reflect progress across multiple workstreams – not simply clinical-site selection. Manufacturing readiness, regulatory planning, clinical operations, comparator strategy and site preparation are being brought together around a defined pivotal development pathway. We believe these activities position us to move efficiently toward study initiation as the remaining requirements are completed.”

A Focused Pivotal Development Strategy

The immunobridging study is planned to enroll 500 healthy adult participants at European clinical sites and evaluate whether immune responses generated by GEO-MVA are non-inferior to those generated by the licensed MVA comparator vaccine.  GeoVax expects meeting the non-inferiority criteria will form the basis for approval by the European Medicines Agency (EMA), providing eligibility for GEO-MVA procurement.

The study will evaluate neutralizing antibody responses and seroconversion against vaccinia and mpox viruses, together with additional immunogenicity and safety measures. Enrollment is planned across multiple adult age groups to support a representative clinical dataset.

The study design incorporates an initial safety lead-in cohort, followed by enrollment of the remaining immunobridging study participants. The CRO and site-selection process emphasized capabilities considered important for efficient execution of the pivotal program, including:

  • Experience conducting Phase 2 and Phase 3 vaccine trials;
  • Demonstrated ability to timely recruit healthy adult volunteers; Experience managing registration-enabling clinical programs;
  • Established clinical and regulatory infrastructure in Europe;
  • Ability to support intensive immunogenicity sampling and rigorous safety oversight; and
  • Recruitment capacity and contingency planning designed to protect program timelines.

“Our objective has been to systematically remove the operational dependencies between GEO-MVA and initiation of the pivotal study,” Dodd said. “With each readiness milestone, the program becomes more tangible: the clinical pathway is defined, the vaccine has been manufactured, and we are now putting the clinical execution infrastructure in place. There is still work ahead, including regulatory and financing requirements, but the pieces necessary to execute the program are increasingly coming together.”

About GEO-MVA

GEO-MVA is GeoVax’s MVA-based vaccine candidate being developed for prevention of mpox and smallpox. GEO-MVA is a highly attenuated, replication-deficient poxvirus vaccine derived from the same original MVA lineage as currently licensed MVA vaccines. The planned GEO-MVA-301 pivotal program is designed to evaluate the immunogenicity and safety of GEO-MVA relative to an approved MVA comparator vaccine and, if successful, support regulatory submissions seeking marketing authorization.

About GeoVax

GeoVax Labs, Inc. is a clinical-stage biotechnology company focused on the development of vaccines and immunotherapies addressing high-consequence infectious diseases and solid tumor cancers. GeoVax’s priority program is GEO-MVA, a Modified Vaccinia Ankara (MVA)–based vaccine targeting mpox and smallpox. The program is advancing under an expedited regulatory pathway, with plans to initiate a pivotal Phase 3 clinical trial in the second half of 2026, to address critical global needs for expanded orthopoxvirus vaccine supply and biodefense preparedness. In oncology, GeoVax is developing Gedeptin®, a gene-directed enzyme prodrug therapy (GDEPT) designed to enhance immune checkpoint inhibitor activity. Gedeptin has completed a multicenter Phase 1/2 clinical trial in advanced head and neck cancer and is being advanced into combination strategies, including planned neoadjuvant and first-line settings. GeoVax maintains a global intellectual property portfolio supporting its infectious disease and oncology programs and continues to evaluate strategic partnerships and funding opportunities aligned with its development priorities. For more information, visit www.geovax.com.

Forward-Looking Statements

This release contains forward-looking statements regarding GeoVax’s business plans. The words “believe,” “look forward to,” “may,” “estimate,” “continue,” “anticipate,” “intend,” “should,” “plan,” “could,” “target,” “potential,” “is likely,” “will,” “expect” and similar expressions, as they relate to us, are intended to identify forward-looking statements. We have based these forward-looking statements largely on our current expectations and projections about future events and financial trends that we believe may affect our financial condition, results of operations, business strategy and financial needs. Actual results may differ materially from those included in these statements due to a variety of factors, including whether: GeoVax is able to obtain acceptable results from ongoing or future clinical trials of its investigational products, GeoVax’s immuno-oncology products and preventative vaccines can provoke the desired responses, and those products or vaccines can be used effectively, GeoVax’s viral vector technology adequately amplifies immune responses to cancer antigens, GeoVax can develop and manufacture its immuno-oncology products and preventative vaccines with the desired characteristics in a timely manner, GeoVax’s immuno-oncology products and preventative vaccines will be safe for human use, GeoVax’s vaccines will effectively prevent targeted infections in humans, GeoVax’s immuno-oncology products and preventative vaccines will receive regulatory approvals necessary to be licensed and marketed, GeoVax raises required capital to complete development, there is development of competitive products that may be more effective or easier to use than GeoVax’s products, GeoVax will be able to enter into favorable manufacturing and distribution agreements, and other factors, over which GeoVax has no control.

Further information on our risk factors is contained in our periodic reports on Form 10-Q and Form 10-K that we have filed and will file with the SEC. Any forward-looking statement made by us herein speaks only as of the date on which it is made. Factors or events that could cause our actual results to differ may emerge from time to time, and it is not possible for us to predict all of them. We undertake no obligation to publicly update any forward-looking statement, whether as a result of new information, future developments or otherwise, except as may be required by law.

Company Contact:
[email protected]
678-384-7220

Media Contact:
Jessica Starman
[email protected]