U.S. Home Prices Rise Again as Mortgage Rates Above 7% Threaten Housing Market Recovery

U.S. home prices continued climbing in August, signaling persistent pressure on housing affordability even before mortgage rates surged above 7%, according to new data released Tuesday. The latest figures highlight the challenges facing prospective homebuyers and raise questions about whether the housing market can maintain its momentum through the final months of 2026.

The S&P Cotality Case-Shiller 20-City Composite Home Price Index increased 2.65% year over year in August, accelerating from a 2.47% gain in July. The broader National Home Price Index rose 2.09% annually, up from approximately 1.9% the previous month.

Although home prices continue to appreciate, the pace remains below overall inflation. Consumer prices increased 3.4% in August, meaning housing values declined in inflation-adjusted terms for the 15th consecutive month.

The figures suggest that the U.S. housing market is experiencing a gradual adjustment rather than a widespread decline in property values. However, affordability remains a major obstacle for buyers already facing elevated home prices, borrowing costs, and household expenses.

According to the National Association of Realtors, the median existing-home price reached $429,100 in August, the highest recorded for that month. Even modest price increases can create additional challenges for first-time buyers struggling to accumulate down payments and qualify for mortgages.

The latest Case-Shiller report also reflects transactions completed between June and August, before the sharp increase in mortgage rates that followed. That timing is particularly important because financing conditions have deteriorated considerably since late summer.

The average rate on a 30-year fixed mortgage climbed to 7.40% in mid-October before easing slightly to 7.32% during the week ending October 22, according to Freddie Mac. That compares with 6.19% a year earlier.

For prospective homeowners, the difference can significantly affect monthly payments and purchasing power. Higher borrowing costs reduce the amount buyers can afford to finance, potentially weakening demand even when housing inventory improves.

Regional housing trends also reveal a market moving in different directions. Chicago recorded the strongest annual price appreciation among major metropolitan areas, with home values rising 6.7%. New York followed with a 6.2% increase, while Cleveland posted a 4.3% gain.

Other markets experienced declines. Seattle home prices fell 2.0% from a year earlier, while Las Vegas and Denver also registered annual decreases.

These differences reflect varying levels of housing supply, local economic conditions, and buyer demand. Markets with limited inventory have generally demonstrated greater pricing resilience, while areas experiencing weaker demand have faced more downward pressure.

Separate data from the Federal Housing Finance Agency reinforced the broader trend. U.S. single-family home prices increased 0.3% in August compared with July and rose 2.4% from a year earlier.

Despite the annual gains, the Case-Shiller national index declined 0.2% month over month on a non-seasonally adjusted basis, suggesting that housing market momentum remains uneven.

For investors, the combination of high mortgage rates and slower home price appreciation has implications across several industries, including homebuilding, construction materials, mortgage lending, and real estate services.

Homebuilders may face increased pressure to offer price reductions or mortgage-rate incentives to attract buyers. Mortgage lenders and real estate brokerages could also experience weaker transaction volumes as affordability constraints discourage purchases and refinancing activity.

The Federal Reserve’s interest rate outlook adds another layer of uncertainty. Although mortgage rates are not directly determined by the central bank, they are heavily influenced by Treasury yields, inflation expectations, and broader monetary policy.

With the Fed scheduled to announce its latest policy decision Wednesday, investors will be watching for signals about whether borrowing costs could remain elevated into 2027.

The August housing data ultimately presents a mixed picture. Home prices continue to rise in nominal terms, but inflation-adjusted values are declining, regional markets are diverging, and higher mortgage rates threaten to weaken buyer demand.

For the housing market, the next test will be whether improving inventory and moderating price growth can offset borrowing costs that remain near multiyear highs.

Federal Reserve Interest Rate Decision: What to Expect Before the November Elections

The Federal Reserve faces a closely watched interest rate decision on October 28, 2026, as rising inflation raises questions about whether policymakers will increase borrowing costs again. The announcement comes just six days before the November 3 midterm elections, adding political scrutiny to a decision that could influence stock prices, bond yields, consumer borrowing, and the broader U.S. economy.

The central bank’s upcoming meeting follows September inflation data showing consumer prices increased 3.7% from a year earlier, up from 3.4% in August. With inflation remaining elevated and the Federal Reserve having already raised rates in September, investors are watching for signals about the direction of monetary policy and the potential impact on financial markets.

When Is the Next Federal Reserve Interest Rate Decision?

The Federal Open Market Committee (FOMC) is scheduled to meet October 27–28, with its interest rate decision expected on Wednesday, October 28, at 2 p.m. Eastern Time.

The announcement will be followed by a press conference at 2:30 p.m., when Federal Reserve officials are expected to explain their assessment of inflation, economic growth, and monetary policy.

The meeting follows a September rate increase that brought the federal funds target range to 3.75%–4.00%, marking the central bank’s first increase in more than three years.

Will the Federal Reserve Raise Interest Rates in October?

The possibility of another rate increase has attracted attention following the latest inflation report.

According to the Bureau of Labor Statistics, the Consumer Price Index rose 0.6% in September and 3.7% over the previous 12 months. Core inflation, which excludes food and energy prices, increased 0.3% for the month and 2.6% annually.

The figures suggest that inflation remains a challenge for policymakers attempting to maintain price stability without placing excessive pressure on economic activity.

Financial markets have adjusted expectations in response to the data, although the outcome of the October meeting remains uncertain.

A decision to raise rates would signal continued concern about inflation, while holding rates steady could indicate that policymakers prefer to assess the effects of previous tightening before making additional changes.

Why the Fed’s October Decision Matters Before the Midterm Elections

The October 28 interest rate announcement falls just six days before the November 3 midterm elections, placing monetary policy under heightened political attention.

Interest rate decisions can affect household borrowing costs, mortgage rates, consumer spending, and business investment, making them particularly relevant during an election period.

However, the Federal Reserve operates independently of the political calendar and is responsible for pursuing its congressional mandates of maximum employment and stable prices.

Policymakers must therefore weigh inflation risks and economic conditions regardless of the timing of national elections.

How the Fed Interest Rate Decision Could Affect Stocks and Bonds

Changes in Federal Reserve policy can influence financial markets through borrowing costs, bond yields, and expectations for future corporate earnings.

Higher interest rates generally increase financing expenses for businesses and consumers. They can also place downward pressure on stock valuations, particularly among growth companies whose valuations depend heavily on expected future earnings.

Bond markets are sensitive to changes in interest rate expectations, although yields also reflect inflation forecasts, economic conditions, and investor demand.

A decision to hold rates steady could provide some relief to interest-rate-sensitive sectors, but investors will also examine the Fed’s accompanying statement for indications of future policy changes.

What Higher Interest Rates Mean for Small-Cap Stocks

For small-cap and microcap companies, Federal Reserve interest rate decisions can have significant implications.

Smaller businesses often have fewer financing options than large corporations and may depend more heavily on external capital to support expansion, acquisitions, and research and development.

Higher borrowing costs can make it more expensive to refinance debt or secure funding for new projects.

These pressures may be especially relevant for early-stage biotechnology companies, emerging technology businesses, and other capital-intensive industries.

Conversely, greater stability in interest rates could improve financial planning and potentially support investor confidence, although individual company fundamentals remain important.

What Investors Should Watch After the October Fed Meeting

Beyond the immediate interest rate decision, investors will be watching the Federal Reserve’s commentary for clues about the path of monetary policy through the remainder of 2026.

Key considerations include whether inflation continues to exceed the central bank’s objectives, how employment and economic growth are evolving, and whether additional rate increases may be necessary.

The Fed’s next scheduled policy meeting is December 8–9, providing another opportunity for policymakers to reassess economic conditions.

With inflation concerns persisting and financial markets sensitive to changes in interest rate expectations, the October 28 announcement could be an important catalyst for stocks, bonds, and the broader economic outlook.

Mortgage Rates Hit 7.4%, the Highest in Nearly Three Years

The average 30-year fixed mortgage rate reached 7.4% this week, according to Freddie Mac survey data through Wednesday, up from 7.28% a week earlier and the highest level in nearly three years. Other measures are higher still. Mortgage News Daily calculated 7.59% as of Wednesday, the Mortgage Bankers Association reported a 7.49% average for the week through Friday, and Zillow data showed a 7.52% rate on a 30-year purchase loan today.

The climb has been steady. Freddie Mac’s 30-year average was 6.65% in late August, which means borrowing costs have risen by roughly three-quarters of a percentage point in about seven weeks. The average crossed 7% in late September for the first time in nearly three years and has kept climbing. On a $400,000 loan, a 7.4% rate means principal and interest of roughly $2,770 a month, about $290 more than at the 6.3% level of a year ago.

Mortgage rates are following bond yields higher as investors worry about government spending, inflation tied to the Iran war, and ongoing economic growth. The 10-year Treasury yield has hovered around 5.3% this week, retreating slightly after briefly touching its highest level since 2002. That link to long-term yields explains why mortgage rates have kept rising even as expectations for another Fed hike in October have faded, since home loan costs track the bond market more closely than the Fed’s policy rate.

The housing market is showing the strain. One housing economist said the higher rates have unsettled the market, noting that pending home sales fell from a year earlier in both August and September, before rates even crossed 7%, and that sellers are cutting prices at a pace not seen in four years. Higher rates reduce what buyers can afford, which pushes sellers to lower prices to attract them, and it keeps many existing homeowners with lower-rate loans from listing at all.

Refinancing is not offering much of an escape either. Zillow data put the average 30-year refinance rate at 7.41% today and the 15-year at 6.76%, while 15-year purchase loans averaged 6.70%. For buyers weighing alternatives, a 5/1 adjustable-rate mortgage averaged 7.13%, only modestly below the 30-year fixed, which limits the appeal of taking on adjustable-rate risk.

Several upcoming data points will show whether rates are close to a peak: next week’s Freddie Mac survey, the September inflation report, and the Fed’s October 27 and 28 meeting, where futures see only a small chance of another hike.

For small and microcap investors, the mortgage market is a useful read on how long-term rates are feeding into the real economy. Housing-linked businesses, from builders and building products suppliers to real estate services and home improvement retailers, are typically among the first to feel higher borrowing costs, and smaller companies with less pricing power and more floating-rate debt feel it more acutely. Mortgage-related financial companies face the same pressure through lower loan volumes. Because long yields, not the Fed, are driving this move, relief is likely to depend on easing concerns about deficits and inflation rather than on the central bank pausing.

Fed Was Unanimous on the September Hike, but October Odds Have Faded

Minutes from the Federal Reserve’s September 16 meeting, released Wednesday, show that every participant agreed interest rates needed to move higher. The committee voted unanimously to raise the federal funds rate, its first increase in three years, and most members projected at least one more quarter-point hike before the end of the year.

The minutes describe a committee that saw inflation as elevated and the labor market as near full employment, with some signs of strengthening. Economic activity was expanding at a solid pace. Almost all participants judged that risks to inflation were tilted to the upside, while risks to the labor market had diminished and were now broadly balanced. That balance of risks was the basis for the hike.

But the data since that meeting has shifted the picture. Core PCE inflation, the Fed’s preferred gauge, rose 3% in August, below the 3.3% economists expected and down from 3.3% in July. Then the September jobs report came in far weaker than forecast, with just 29,000 jobs added and the unemployment rate edging up to 4.2% from 4.1%. In other words, the two conditions that justified the hike, stubborn inflation and a firming labor market, both looked softer within weeks.

Several officials had already begun tempering expectations before the jobs report. Vice Chair Philip Jefferson and New York Fed President John Williams both acknowledged that inflation remains too high but said the central bank should take time to assess whether it is on a downward path. Williams said there is no need for urgency after the September increase and that the Fed has time to gather more information. That marks a notable shift from late September, when other officials were publicly arguing that more hikes were needed. Core inflation at 3% is still well above the Fed’s 2% target, so the debate now appears to be about timing rather than direction.

Markets have adjusted accordingly. The Fed meets again October 27 and 28, and futures now price only about a 17% chance of a hike at that meeting, down from roughly two-thirds in late September. The odds of a hike in December sit near 70%, which suggests traders see the Fed pausing rather than finishing.

A pause would not necessarily bring relief to long-term borrowing costs. The 10-year Treasury yield is still near 5.3%, and much of the recent rise has reflected investors demanding higher real returns to hold long-dated debt rather than the Fed’s policy rate, a dynamic that a pause in hikes may do little to change.

For small and microcap investors, the shift matters. Roughly 32% of Russell 2000 companies carry floating-rate debt, compared with about 6% of S&P 500 companies, so changes in the expected path of short-term rates flow more directly into smaller companies’ interest costs. A pause at the current range of 3.75% to 4.00% would stabilize that expense, while a December hike would extend it. The weaker jobs data cuts both ways, since easing rate pressure helps leveraged balance sheets but a cooling labor market can hurt consumer-facing companies that depend on household spending, such as restaurant operator The ONE Group Hospitality and travel deals publisher Travelzoo.

Small Caps are Bending, Not Breaking, as Credit Stress Builds

Stocks are at records, credit markets are showing strain, and small caps are in the middle of the debate. The picture is more mixed than the headlines suggest.

The S&P 500 and Nasdaq hit record highs on Tuesday. The Russell 2000 closed at 2,830, about 8% below its third-quarter high of 3,068 but still up roughly 14% this year, after finishing 2025 near 2,482. As of July, it had also outpaced the S&P 500 over six months (16.9% versus 8.9%) and one year (20.0% versus 9.9%), according to Benzinga.

The pressure is real. The 10-year Treasury yield closed at 5.27% on Tuesday, a level not seen since 2002. JPMorgan strategists say deeply distressed leveraged loans are at their highest since March 2020, and spreads on CCC-rated bonds have passed 1,000 basis points.

Those figures describe leveraged loans and junk bonds, though, not the companies in the Russell 2000.

Where small caps stand

Small caps do carry more rate risk. Interest expense takes up 31% of EBITDA at Russell 2000 companies, versus 6.7% for the S&P 500, and about 30% of their debt is floating-rate, according to July data from The Kobeissi Letter.

But that sensitivity works in both directions. When oil prices fell and rate expectations eased this spring, the Russell 2000 gained about 11.7% in the first 20 days of April, per 24/7 Wall St. The index has since recovered about 16% from its low during the Iran war selloff, breaking out of a multi-year base near 2,000 and closing the second quarter at 3,024.

Debt is concentrated, and many companies are cushioned

Not every small cap is carrying a heavy load. A 2024 Wellington analysis found that half of the Russell 2000’s debt sits with just 10% of its companies, while 33% held net cash, versus 13% for the S&P 500.

That study predates this year’s rate moves, but it points to a market where stress is concentrated rather than universal. JPMorgan’s latest data fits that pattern: technology accounts for 39% of distressed loans, with software borrowers facing more than $100 billion of maturing debt. Nearly 40% of the index’s companies are unprofitable, which also means a majority are not.

Signs of resilience

JPMorgan CEO Jamie Dimon said weeks ago, after the Federal Reserve’s September rate hike, that the labor market’s relative strength suggested higher borrowing costs had not yet turned into broader economic stress. On Tuesday, he warned that spreads could eventually widen as governments and AI spending compete for capital.

Markets are calm for now. The VIX, Wall Street’s fear gauge, closed near 15. JPMorgan projects a 2.25% default rate this year, though it expects defaults to rise next year.

What could help

Investors will be watching the 10-year yield, CCC spreads and the Fed’s next meeting under Chair Kevin Warsh. Falling yields would ease refinancing for the many small caps with debt coming due, and third-quarter earnings should show how companies are managing interest costs. Oil, trading near $90 a barrel, is another swing factor: its drop in April helped reset rate expectations.

Credit conditions are tightening, but small caps have already shown they can rebound when pressure eases. For companies with solid balance sheets, the data point to a hurdle rather than a roadblock.

Private Payrolls Reaccelerate in September, Complicating the Case for Fed Rate Cuts

Private sector hiring picked up meaningfully in September, according to payroll processor ADP, adding 90,000 jobs and comfortably beating the 75,000 economists surveyed by Bloomberg had expected. The gain also marks a sharp improvement from a revised 36,000 jobs added in August. ADP’s chief economist described it as a genuinely strong report, noting it represents the first reacceleration in hiring since May, following a three-month slowdown.

Wage growth held up alongside the stronger hiring numbers. Base pay rose 3.2% year over year, while gross pay climbed 4.7%, with workers who changed jobs seeing even larger gains than those who stayed in place. Education and healthcare, long one of the most consistent sources of job growth in this economy, added a particularly robust 55,000 positions in September. Leisure and hospitality also contributed meaningfully to the overall gain. Not every sector participated, however. Financial services shed 16,000 jobs, and business and professional services lost 11,000, a continuation of the white-collar employment softness that has shown up repeatedly in recent labor market data, and one that echoes the AI-driven efficiency pressures we detailed when covering Meta’s Muse agent launch and the broader debate over AI’s impact on hiring.

The timing of this report matters. It arrives just two days ahead of the Labor Department’s official employment report Friday, which measures job creation across both public and private employers and is the data the Federal Reserve actually uses in its policy deliberations. Economists currently expect that broader measure to show a similar gain of approximately 90,000 jobs.

That expectation lands in a delicate spot for Fed watchers. The central bank raised rates on September 16 for the first time in three years, and officials have continued striking a hawkish tone since, emphasizing that inflation remains the Fed’s predominant concern. A labor market that is reaccelerating rather than cooling gives policymakers less reason to consider easing and more justification to hold, or even raise rates further, a dynamic directly relevant to the elevated Treasury yields and higher borrowing costs we’ve tracked closely in recent weeks.

For companies operating below the $2 billion market cap threshold, Friday’s jobs report is worth watching closely for exactly that reason. Small and microcap businesses typically carry more variable-rate debt than large cap peers, making their cost of capital unusually sensitive to how the Fed reads incoming labor data. A hot jobs report this week would reinforce the higher-for-longer rate environment that has weighed on smaller companies since the September hike, while a softer print, despite this week’s encouraging ADP data, could reopen the door to a more patient Fed heading into the final months of the year. Either way, the reacceleration in hiring reported Wednesday makes Friday’s release one of the more consequential data points investors will see before the Fed’s next meeting.

Treasury Yields Keep Climbing. Even Fed-Adjacent Voices Are Taking Notice

The bond market selloff we detailed just yesterday didn’t ease up, it accelerated. The 10-year Treasury yield climbed as high as 5.12% Wednesday, extending its climb to the highest level since 2007. The 30-year yield touched 5.4%, its highest level since 2004, while the 5-year yield also jumped to levels last seen in 2007. Rates have held at these elevated levels since.

The reaction from BlackRock’s chief investment officer of global fixed income carries particular weight given his background. Rick Rieder, who was among the finalists considered for the Federal Reserve chair position that ultimately went to Kevin Warsh, described the situation plainly, calling it not a crisis but an eye-opener, and something investors genuinely need to think through carefully. Coming from someone who was seriously considered for the job now shaping the Fed’s response to exactly this kind of market stress, that framing is worth taking seriously.

The catalysts behind the move are the same ones we’ve tracked closely this week, oil prices advancing again and business activity data coming in hotter than expected, both reinforcing concerns that the Fed may need to raise rates further. Fed officials are doing little to calm those fears. New York Fed President John Williams said Thursday it would be reasonable to expect another rate hike before year-end to bring inflation under control, echoing comments Fed Governor Michael Barr made just a day earlier. That’s now two sitting Fed officials publicly reinforcing the hawkish posture Warsh struck at his Jackson Hole speech last month, a signal that this isn’t isolated commentary but a genuinely coordinated message from the committee.

What makes Rieder’s specific choice of words notable is the distinction he’s drawing. Calling something an eye-opener rather than a crisis suggests this isn’t a moment of panic or dysfunction in the bond market itself, but rather a signal worth taking seriously about where borrowing costs are actually headed, and for how long. That’s a meaningfully different read than the alarm bells some market commentary has sounded, and it’s coming from someone with genuine insider perspective on how the Fed is likely thinking about this exact tradeoff.

For companies operating below the $2 billion market cap threshold, the practical stakes haven’t changed from what we outlined yesterday, they’ve simply intensified. Small and microcap businesses carry disproportionately more variable-rate debt than large cap peers, and every additional basis point on the 10-year and 30-year yields translates into real, rising borrowing costs for exactly this segment of the market. With two Fed officials now on record supporting further hikes and yields showing no sign of retreating, the higher-cost-of-capital environment weighing on small caps looks increasingly like the new baseline rather than a temporary spike, something worth watching closely heading into year-end.

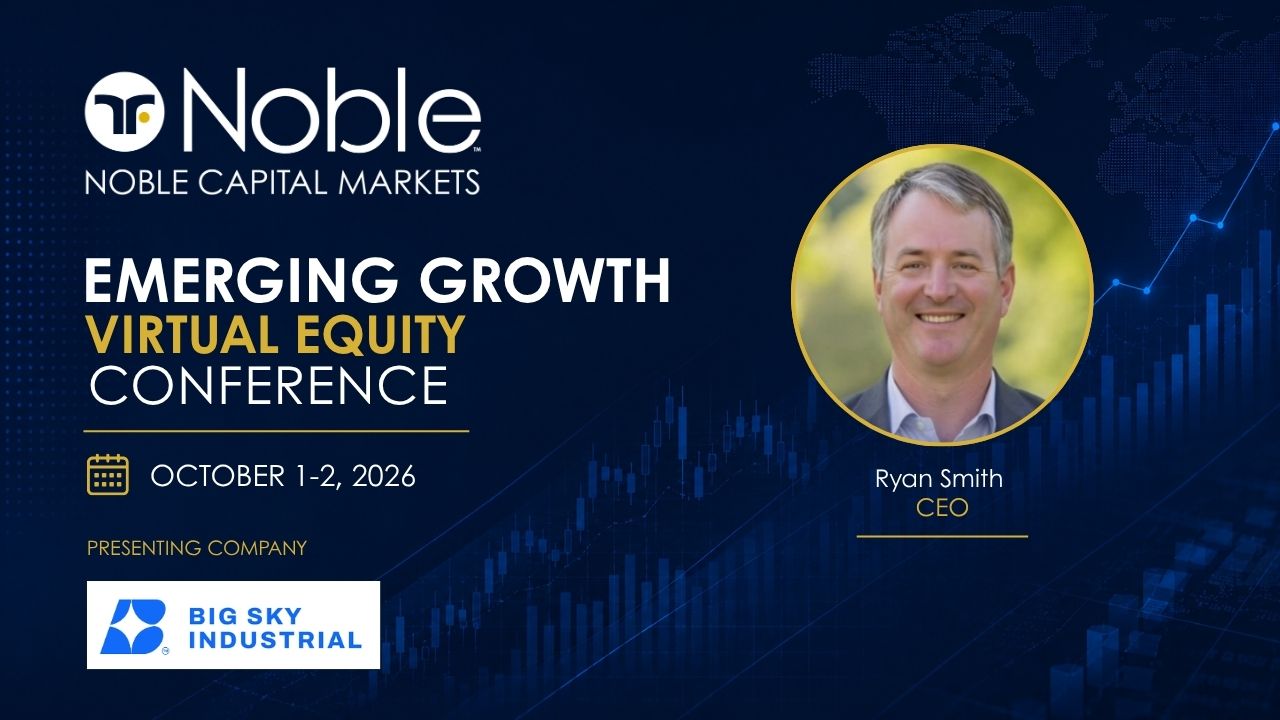
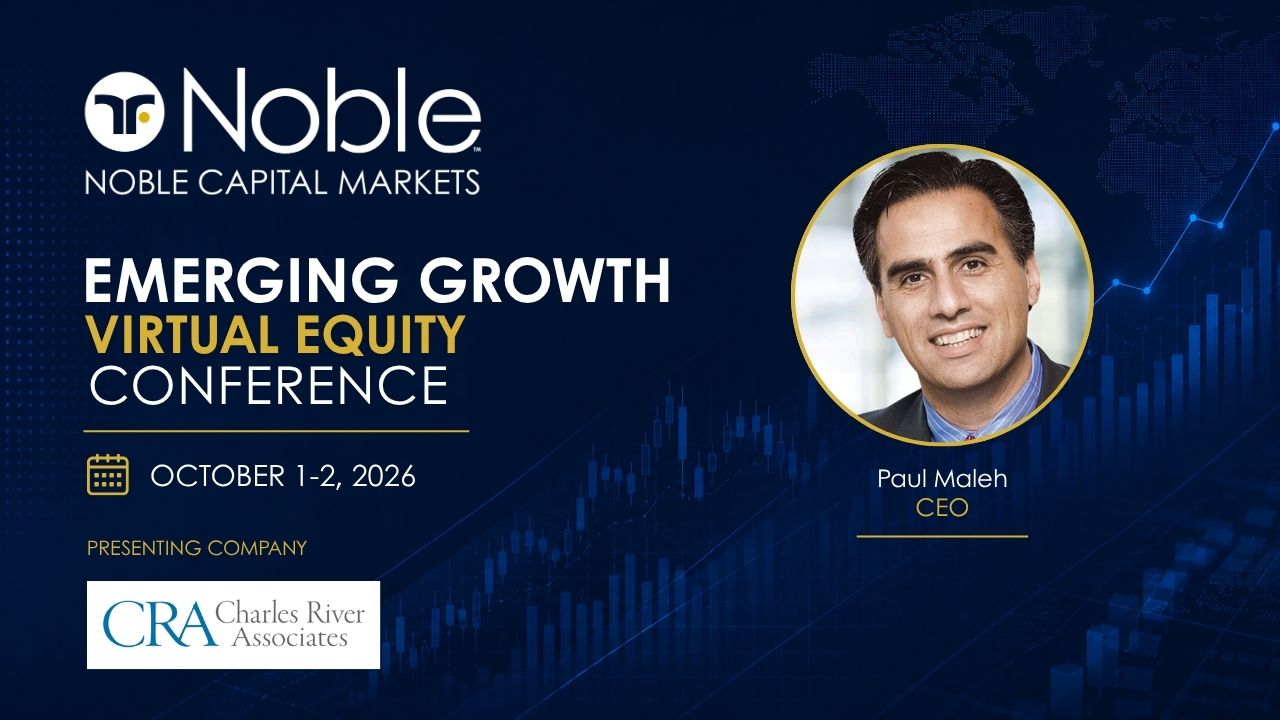
Noble Capital Markets Emerging Growth Virtual Equity Conference – October 2026 – Presenting Company Replays

October 1 Schedule

All times Eastern

October 2 Schedule

All times Eastern

Participating in 1×1 Meetings Only

Warren Buffett Steps Down as Berkshire Hathaway Chairman, Closing a Remarkable Era

Warren Buffett stepped down Friday as chairman of Berkshire Hathaway (NYSE: BRK.A, BRK.B), bringing another chapter of one of the most consequential careers in modern investing to a close.

Buffett, who recently turned 96, has been named Chairman Emeritus and will remain on Berkshire’s board, where the company says he will continue to offer his judgment and perspective. His son, Howard G. Buffett, a Berkshire director since 1993, has been elected chairman, while Greg Abel remains chief executive officer and continues to run the company’s operations.

The transition completes a process that began earlier this year when Abel succeeded Buffett as CEO. Buffett described the timing as right, writing to shareholders that Abel had exceeded his already high expectations and had been making Berkshire’s important decisions for some time. He characterized Howard’s role differently: Abel will run the company, while Howard will help guard the culture and values Buffett spent decades building.

For investors, Buffett’s departure from the chairman’s seat is less about an abrupt change in control than the culmination of a succession plan years in the making. But symbolically, it closes an extraordinary period in American business.

From Struggling Textile Company to $1 Trillion Conglomerate

Buffett took control of Berkshire Hathaway in 1965, when it was still primarily a struggling New England textile manufacturer. What followed was one of the most remarkable transformations in corporate history.

Rather than remaining a textile business, Berkshire evolved into a sprawling collection of operating companies and investments spanning insurance, rail transportation, energy, manufacturing, retailing and services. Today its businesses include GEICO, BNSF Railway, Berkshire Hathaway Energy, Dairy Queen and numerous industrial and consumer companies.

The numbers illustrate the scale of the transformation. From 1965 through 2025, Berkshire’s per-share market value compounded at 19.7% annually, compared with 10.5% for the S&P 500 including dividends. Over the full period from 1964 through 2025, Berkshire’s gain totaled more than 6 million percent, versus roughly 46,000% for the S&P 500.

That record turned Buffett from a successful investor into a central figure in global finance and transformed Berkshire from an obscure textile company into a business valued at roughly $1 trillion.

A Different Approach to Building a Company

Much of Buffett’s success came from a model that was unusual when he began using it and remains difficult to replicate.

Berkshire’s insurance operations generated large amounts of float – premiums collected before claims are paid – that could be invested elsewhere. Buffett used that capital to buy public-company stakes and, increasingly, entire businesses.

Over time, Berkshire accumulated large positions in companies such as Coca-Cola and Apple while acquiring businesses ranging from GEICO and BNSF Railway to utilities, manufacturers and retailers. Buffett’s investment approach also evolved alongside longtime partner Charlie Munger, moving beyond simply buying statistically cheap companies toward acquiring strong businesses with durable competitive advantages, capable management and attractive long-term economics.

Berkshire then allowed many acquired companies to operate with significant autonomy rather than imposing a heavily centralized corporate structure. The combination of patient capital, decentralized management and an unusually long investment horizon became a defining part of Berkshire’s identity.

Crisis Investing Helped Build the Buffett Reputation

Buffett’s reputation was also reinforced by his willingness to deploy capital when markets were under severe stress.

During the 2008 financial crisis, Berkshire invested billions of dollars in companies including Goldman Sachs and General Electric at a time when access to capital had become extremely valuable. Those investments demonstrated one of Berkshire’s recurring advantages: maintaining enough liquidity to act aggressively when other investors were forced to retreat.

That philosophy remains visible today. As of June 30, Berkshire’s insurance and other businesses held approximately $359 billion in cash, cash equivalents and U.S. Treasury bills, giving the company an enormous pool of liquidity for investments, acquisitions or share repurchases. Buffett has long viewed that liquidity not as idle capital, but as both protection against unexpected events and optionality when attractive opportunities emerge.

Buffett Also Changed How Investors Think

Buffett’s influence extends well beyond Berkshire’s financial results. His annual shareholder letters became widely read explanations of investing, corporate governance, accounting and capital allocation, while Berkshire’s annual meeting in Omaha evolved into one of the largest gatherings of investors in the world.

Among the ideas Buffett repeatedly emphasized were relatively simple concepts that often proved difficult to practice: focus on long-term business value rather than short-term stock movements, avoid excessive leverage, understand what you own and remain disciplined when markets become euphoric or fearful.

His emphasis on treating shareholders as long-term business partners also helped shape Berkshire’s unusually loyal investor base. In his final message as chairman, Buffett returned to that idea, noting that he and Munger had always sought shareholders who thought in decades rather than quarters.

What Happens to Berkshire Now?

The most important question for Berkshire investors is how much the company changes without Buffett holding either the CEO or chairman title. Operationally, the transition is already well underway.

Greg Abel became CEO at the beginning of 2026 and is responsible for running Berkshire and making capital-allocation decisions. Buffett said Friday that Abel has fully taken control of the CEO role and that he has not had reason to question the decisions Abel has made.

Howard Buffett’s position as chairman is expected to be more focused on governance and protecting Berkshire’s corporate culture than managing day-to-day operations. Buffett described his son as a safeguard for the values he believes are central to the company.

Berkshire also enters the post-Buffett era with substantial financial strength. At June 30, the company reported roughly $1.26 trillion in total assets and nearly $748 billion in Berkshire shareholders’ equity, alongside its large holdings of cash and Treasury bills. That gives Abel considerable flexibility, but also presents one of Berkshire’s biggest challenges: its enormous size makes finding investments capable of materially moving the company increasingly difficult.

The Next Berkshire Will Inevitably Look Different

No successor can realistically replicate Buffett’s exact role. For decades, he served simultaneously as chief executive, chairman, chief capital allocator, public face of the company and one of its largest shareholders.

Berkshire’s next generation of leadership is intentionally more distributed, with Abel managing the business, Howard Buffett overseeing the board and Berkshire’s existing managers continuing to run individual subsidiaries. Investors will therefore be watching whether the company can preserve the elements of Buffett’s system that made it distinctive: disciplined capital allocation, conservative financing, decentralized operations and a willingness to wait for attractive opportunities.

There are reasons for continuity. Buffett remains a director and major shareholder, and the current succession structure was developed over many years rather than assembled suddenly. But Berkshire is unquestionably entering a new era.

Buffett took control of a struggling textile operation more than six decades ago and turned it into one of the largest and most financially powerful companies in the world. Few investors have produced comparable long-term returns, and fewer still have had such a lasting influence on how generations of investors think about businesses, markets and capital.

In his letter Friday, Buffett acknowledged the inevitability of the transition with characteristic simplicity: “Father Time always wins.” He added that Berkshire had reached a point where he was more confident than ever about what lies ahead.

That confidence will now be tested under a new generation of leadership. For Berkshire shareholders, the Buffett era may be ending – but the company he built is designed to continue long after him.

SEC Opens Door to Tokenized U.S. Stocks as Broader Crypto Legislation Stalls

The U.S. Securities and Exchange Commission took a major step toward bringing tokenized equities into mainstream American markets Thursday, approving a temporary regulatory framework that allows certain trading venues to offer blockchain-based representations of publicly traded U.S. stocks.

The SEC’s new Innovation Exemption creates a five-year conditional pathway for approved onchain venues to trade tokenized National Market System stocks, while also providing limited relief from dealer-registration requirements for liquidity providers operating in those markets. The order is effective immediately.

The move could accelerate efforts to bring traditional equities onto blockchain infrastructure, potentially enabling faster settlement, fractional ownership, expanded trading hours and new forms of custody. It also arrives just two days after the Senate failed to advance the Clarity Act, a broader digital-asset market structure bill that would have created a more comprehensive statutory framework for cryptocurrencies and other digital assets.

For investors, the contrast is important. Congress may remain divided over comprehensive crypto legislation, but regulators and market operators are continuing to build a more targeted framework for tokenized securities specifically.

What the SEC Actually Approved

The exemption does not simply allow any crypto platform to create synthetic versions of U.S. stocks. Under the SEC framework, qualifying Tokenized Securities Venues, or TSVs, may facilitate trading in tokenized versions of National Market System stocks. The tokenized securities must represent actual securities and provide holders with the same core rights and privileges associated with the traditional shares, including dividend and voting rights. Synthetic tokens that merely track a stock’s price without conveying equivalent ownership rights are excluded.

Issuers also retain an important degree of control. Platforms must notify a public company before offering a tokenized version of its shares, and the company can object and prevent that tokenized security from being listed on the venue.

That provision addresses one of the largest concerns surrounding early tokenized-stock products offered outside the United States. Some offshore products have provided investors with economic exposure to a stock without necessarily giving them the full legal rights of a shareholder.

The SEC itself drew that distinction earlier this year when it formally described tokenized securities as traditional securities represented through crypto or distributed-ledger technology and differentiated issuer-backed tokenization from third-party structures. In other words, the regulator is attempting to allow the technology to change while preserving the legal nature of the underlying security.

Why Tokenization Matters

Tokenization means representing ownership in an asset through a digital token recorded on a blockchain or similar distributed ledger. For equities, the underlying investment does not necessarily change. An investor may still own an interest tied to the same public company, receive dividends and possess voting rights. What potentially changes is the infrastructure used to record, transfer and settle that ownership.

Advocates argue that this could eventually support round-the-clock trading, faster settlement, fractional ownership and more efficient movement of assets between financial platforms. The potential significance is therefore broader than simply putting stocks on a blockchain.

The traditional U.S. equity system involves exchanges, brokers, custodians, clearing organizations, transfer agents and settlement infrastructure working together. Tokenization could ultimately change how some of those functions interact, particularly if ownership records and settlement increasingly move onto programmable digital ledgers. That transition, however, is likely to be gradual rather than immediate.

The Infrastructure Is Already Being Built

Thursday’s action does not arrive in isolation. The Depository Trust & Clearing Corporation, which sits at the center of U.S. securities clearing and settlement, has already been testing tokenized securities with financial institutions and market participants and has been developing a broader tokenization service.

Private-sector platforms have also moved rapidly. Custodial tokenized-security structures, regulated onchain trading platforms and blockchain-based settlement systems are progressing from pilot projects toward real market infrastructure. Taken together, those developments suggest tokenized equities are moving beyond the proof-of-concept stage.

Nasdaq Is Already Positioning for This Transition

Nasdaq has been particularly active in preparing for tokenized markets. Earlier this year, the SEC approved Nasdaq’s proposal to enable securities to trade on its exchange in tokenized form. Nasdaq subsequently announced an equity-token framework designed to preserve issuer control, shareholder rights, regulatory protections and corporate governance as equities move onto blockchain infrastructure.

Last week, Nasdaq went another step further, agreeing to invest $100 million in Payward, the parent company of Kraken, while expanding the companies’ work on Nasdaq Equity Tokens and always-on trading infrastructure.

That development was the subject of a recent Channelchek article, ‘Nasdaq Deepens Push Into Tokenized Stocks With $100 Million Payward Investment.’ Today’s SEC action provides additional regulatory context for that strategy: the market infrastructure Nasdaq and Payward are developing now has a clearer path toward deployment in the United States.

The Clarity Act Failed – But Tokenization Is Still Moving Forward

Thursday’s regulatory progress comes only two days after a significant legislative setback for the broader digital-asset industry. The Senate failed to advance the Clarity Act in a procedural vote, falling short of the votes required to move the measure forward. The bill would have established a comprehensive regulatory structure for digital assets and clarified responsibilities between agencies including the SEC and Commodity Futures Trading Commission.

For investors, however, the distinction between cryptocurrencies and tokenized securities is important. Tokenized stocks are still securities. Their underlying economic and legal characteristics remain governed by securities law even if blockchain technology is used to represent ownership or process transactions.

That allows the SEC to address some tokenization questions through its existing authority even while Congress continues debating a much broader framework for digital assets. The result is an unusual regulatory picture: comprehensive crypto legislation remains unresolved, while specific pieces of tokenized capital-market infrastructure continue advancing.

Investor Protections Remain Part of the Debate

Not everyone agrees that exemptions are the best way to introduce tokenized equities. Traditional market participants have raised concerns about liquidity fragmentation, price discovery and whether tokenized venues could weaken protections embedded in the National Market System.

The SEC’s temporary framework appears designed partly to address those concerns by limiting eligible products, preserving shareholder rights and allowing issuers to block tokenized versions of their securities. The five-year duration is also significant: rather than establishing a permanent regulatory regime immediately, the SEC is effectively creating a controlled period in which tokenized markets can develop while regulators gather data and determine what longer-term rules may be appropriate.

Could 24/7 Stock Trading Actually Happen?

One of the most visible potential changes is extended trading hours. Cryptocurrency markets operate continuously, while U.S. stock markets still revolve around defined sessions even as exchanges gradually expand overnight trading.

Blockchain-based securities infrastructure could make continuous trading easier technically because tokenized assets can move between investors without relying on exactly the same operating hours as existing market systems. But technology is only part of the equation. Liquidity, market surveillance, corporate actions, settlement, investor disclosures and price discovery all become more complicated if trading occurs around the clock.

The arrival of tokenized equities therefore does not mean the traditional market structure disappears overnight. More likely, conventional exchanges, clearing systems and blockchain-based platforms will increasingly overlap.

A Potentially Important Shift for Public Companies

The development could eventually matter for public issuers as much as it does for trading platforms. Tokenized ownership records could potentially improve shareholder communications, automate corporate actions and make it easier to manage voting, dividends and other ownership rights.

Nasdaq has emphasized that issuers should remain at the center of tokenization rather than simply having third-party platforms create digital representations of their shares without their involvement. The SEC’s issuer-objection provision moves in the same direction.

That could ultimately produce a tokenization model that looks less like the crypto industry replacing traditional markets and more like existing capital markets gradually adopting blockchain technology underneath their current legal structure.

The Bigger Story Is Market Infrastructure

Tokenized stocks can easily be described as another crypto product, but that may understate what is happening. The larger story is the modernization of the infrastructure underlying capital markets.

DTCC is preparing tokenized securities infrastructure. Nasdaq is developing tokenized equity systems. Major banks, brokers, asset managers and trading firms are participating in industry efforts. Regulated platforms have begun executing tokenized securities transactions. And now the SEC has created a temporary pathway for additional onchain trading venues to enter the U.S. market.

None of that guarantees tokenized equities will replace the existing system, nor does it resolve every regulatory issue surrounding digital assets. But it suggests the conversation has moved considerably beyond whether tokenization is theoretically possible. The more relevant question is becoming how much of the traditional financial system will ultimately adopt it.

Tuesday’s failed Clarity Act vote demonstrated that broad digital-asset legislation remains politically and legally difficult. Thursday’s SEC action demonstrates something equally important: the development of tokenized securities does not necessarily have to wait for Congress to resolve every question surrounding cryptocurrency.

For investors, that distinction may prove important. The broader crypto regulatory framework remains unsettled, but the infrastructure for putting traditional securities onchain continues moving forward – and increasingly, some of the largest institutions in U.S. capital markets are helping build it.
Nasdaq Deepens Push Into Tokenized Stocks With $100 Million Payward Investment

Nasdaq (NASDAQ: NDAQ) announced Thursday that it is expanding its relationship with Payward, the parent company of Kraken, as part of a broader effort to bring tokenized equities into mainstream capital markets infrastructure.

The agreement includes a $100 million investment by Nasdaq Ventures in Payward, continued development of the Nasdaq Equity Token (NET) framework, and a new market-surveillance agreement covering Payward’s trading venues. Nasdaq said it expects NETs to launch in the second quarter of 2027, subject to the necessary regulatory and operational work.

For Nasdaq, the appeal is not simply adding blockchain technology to stock trading. The company is positioning tokenization as a way to make capital markets more continuous, efficient and globally connected while preserving the investor protections, issuer rights and market-integrity standards that underpin traditional exchanges.

What Is a Tokenized Stock?

At its simplest, a tokenized equity is a digital representation of ownership in a company recorded on a blockchain or distributed ledger. The underlying economic exposure can resemble that of a traditional share, but the ownership record and transfer mechanics are handled through blockchain-based infrastructure rather than solely through conventional securities systems.

That distinction matters because tokenization can potentially change how securities are transferred, settled and used as collateral. Proponents argue that blockchain-based securities could support faster settlement, fractional ownership, broader access and more automated handling of functions such as dividends or voting. At the same time, tokenized equities remain securities and still have to operate within applicable regulatory frameworks.

Nasdaq’s approach is particularly notable because it is trying to avoid creating a separate parallel market that sits outside traditional exchange protections. Under its framework, a security could exist in either conventional or tokenized form while preserving the same economic rights and, in Nasdaq’s model, the same issuer protections.

Why Nasdaq Thinks Tokenization Could Improve Markets

One of the biggest potential benefits is settlement efficiency. Today, U.S. equity trades generally settle one business day after execution. Before that settlement occurs, clearing institutions must manage counterparty exposure and require collateral against outstanding obligations. Payward co-CEO Arjun Sethi noted in Thursday’s announcement that more than $2 trillion of stock trades move through the U.S. clearing system each day, with trades netted down by roughly 98% before final settlement.

Moving securities onto blockchain-based rails could reduce the amount of time assets and cash remain in transit between counterparties. In theory, faster or even near-instant settlement could lower collateral requirements, improve capital efficiency and allow investors and institutions to redeploy assets more quickly.

That fits into Nasdaq’s broader vision of always-on market infrastructure — systems capable of moving capital, collateral and securities more continuously across markets instead of being tied entirely to traditional trading and settlement windows. Nasdaq is already moving in that direction elsewhere, including plans to extend trading on the Nasdaq Stock Market toward a 24-hour structure.

Kraken Brings the Crypto Infrastructure

Payward gives Nasdaq an established digital-asset partner. Kraken is one of the largest global cryptocurrency trading platforms, while Payward also operates the infrastructure behind xStocks, a tokenized-equities ecosystem designed to provide blockchain-based exposure to publicly traded stocks.

Earlier this year, Nasdaq and Payward began working together on an equities transformation gateway intended to connect regulated securities infrastructure with digital networks. The goal is to allow tokenized equities to move between traditional, permissioned market systems and blockchain-based environments without stripping away the rights associated with the underlying shares.

Thursday’s $100 million investment deepens that relationship and signals that Nasdaq views the project as more than an experimental blockchain initiative. The companies will now work on the global distribution, trading and post-trade infrastructure needed to support broader adoption of NETs. Payward will also deploy Nasdaq’s surveillance technology across its crypto, equities, tokenized-equities, futures and options venues.

That surveillance agreement is important because one of the central questions surrounding digital-asset markets has been whether blockchain-based trading can offer the same level of transparency and oversight investors expect from regulated securities exchanges. Nasdaq is effectively betting that tokenization will gain broader acceptance if the technology is paired with familiar market controls rather than positioned as a replacement for them.

Tokenization Is Already Moving Into Traditional Finance

The Nasdaq initiative is part of a much larger shift underway across financial markets. Blockchain-based assets were once largely associated with cryptocurrencies, but major financial institutions have increasingly begun experimenting with tokenized versions of traditional assets such as U.S. Treasuries, money-market funds, private credit and securities.

BlackRock’s tokenized U.S. dollar institutional liquidity fund, BUIDL, has been one of the most visible examples. The fund uses blockchain infrastructure to represent ownership interests and facilitate eligible on-chain transfers while continuing to invest primarily in traditional short-term assets such as Treasury bills and repurchase agreements.

The next step is equities. If tokenized stocks can preserve traditional shareholder rights while operating on digital rails, they could potentially allow investors to transfer securities more easily between platforms, use stocks more efficiently as collateral and eventually trade or settle assets across a broader range of hours and jurisdictions.

The Infrastructure May Matter More Than the Token

For investors, it can be tempting to focus on the novelty of owning a stock as a blockchain token. But the more significant change may be happening behind the scenes. Modern equity markets already operate electronically. The potential advantage of tokenization is therefore less about converting a paper certificate into a digital object and more about redesigning the infrastructure used for ownership, settlement, collateral and asset transfers.

Nasdaq’s involvement gives that effort additional credibility because the company already operates some of the core infrastructure underlying global securities markets. Its strategy is not to abandon the existing system, but to create a bridge between conventional capital markets and blockchain-based networks.

If that model works, tokenized equities could gradually become another format in which investors hold and transfer securities rather than an entirely separate asset class.

A 2027 Test for Mainstream Adoption

The planned second-quarter 2027 launch of Nasdaq Equity Tokens will be an important test of whether tokenized equities can move beyond crypto-native platforms and become part of mainstream market infrastructure.

There are still significant challenges. Regulatory requirements remain complex, cybersecurity risks are real, and the industry has not yet settled on common standards for how tokenized securities should move across exchanges, wallets and blockchain networks.

But Nasdaq’s decision to commit $100 million to Payward suggests that one of the world’s largest exchange operators believes the technology has moved beyond the proof-of-concept stage.

The broader question is no longer simply whether stocks can be tokenized. Technically, that has already been demonstrated. The more important question is whether tokenized shares can deliver faster settlement, improved capital efficiency and broader market access without sacrificing the regulatory protections and market integrity investors already expect.

Nasdaq and Payward are now betting that they can.

August Jobs Report Just Blew Past Every Forecast. That Might Be Bad News for Rate Cuts

US employers added 162,000 jobs in August, nearly tripling the 55,000 economists surveyed by Bloomberg had expected, the Labor Department reported Friday. The unemployment rate held steady at 4.1%. Heather Long, chief economist at Navy Federal Credit Union, summed up the reaction in three words on social media, calling it a huge report.

The strength ran across several sectors. Food services added 59,000 jobs, public education gained 42,000 positions, and healthcare, which has driven much of this year’s job growth, added another 13,000, though at a notably slower pace than earlier in the year. Not every corner of the economy shared in the strength. The information sector lost 23,000 positions, a continuation of the white-collar employment pressure that has shown up repeatedly in recent months.

Just as notable as August’s headline number were the revisions attached to it. July’s initially reported job loss, a figure that rattled markets when it first came out, was revised into positive territory. June’s numbers were also revised modestly higher. Taken together, the picture emerging is considerably stronger than what the raw data suggested just a month ago, a meaningful shift from the low hire, low fire stagnation that recent labor market data, including the JOLTS report we covered earlier this week, had pointed toward.
That shift matters enormously for what happens next. This is the last major jobs report the Federal Reserve will see before its September 16-17 meeting, and it lands with the committee genuinely split on what to do. Fed Chair Kevin Warsh signaled in his Jackson Hole speech last week that the central bank needs to do more to bring inflation under control, a stance we detailed closely at the time. Fed Governor Christopher Waller struck a different tone Thursday, saying he would lean toward holding rates steady if incoming data continues showing inflation improving. A labor market this strong genuinely complicates the case for anyone hoping a softening job market would tip the Fed toward patience, and it hands ammunition to the more hawkish members of the committee heading into their final deliberations.
For companies operating below the $2 billion market cap threshold, this report carries real weight. Small and microcap businesses typically carry more variable-rate debt than large cap companies, making their borrowing costs unusually sensitive to shifts in how confident the Fed feels about the broader economy. A jobs report this much stronger than expected reduces the odds the Fed sees any urgency to ease, and increases the odds that Warsh’s more hawkish read on the economy carries the day at this month’s meeting. With the labor market and inflation data now sending genuinely conflicting signals, the September decision looks less like a formality and more like a real, live debate.

The 10-Year Treasury Just Hit Its Highest Level Since 2023

The 10-year Treasury yield touched 4.814% Wednesday, its highest level since November 2023, before easing slightly to 4.77%. The 30-year yield sat at 5.26%, still hovering near the multi-decade highs that rattled markets last month. This is not a new, isolated story. It is the direct convergence of three separate threads that have each been building independently over recent weeks.

The first is oil. Crude prices pushed toward $95 a barrel this week after fresh US strikes on Iran, extending the renewed escalation we covered when fighting resumed after the earlier ceasefire lapsed. Elevated energy prices continue feeding directly into inflation expectations, and rising inflation expectations are one of the most reliable drivers of higher long-term bond yields.

The second is the Fed itself. Chair Kevin Warsh’s hawkish tone at his debut Jackson Hole speech last week set the stage, and Fed Governor Michelle Barr reinforced that posture Tuesday, stating the central bank should raise rates in September if inflation does not show sufficient signs of moderating. Prediction markets responded accordingly, with odds of a September rate hike on Polymarket climbing to 56% following Warsh’s initial remarks, up meaningfully from where they stood before Jackson Hole.

The third thread is less obvious but genuinely important. Rising yields are not only about oil and Fed policy, they also reflect growing investor concern over government debt levels and expanding fiscal deficits, alongside a separate but related dynamic in corporate debt markets. Technology companies building out AI infrastructure are increasingly turning to bond markets to fund that buildout, since the scale of spending required has outpaced what free cash flow alone can cover, a dynamic we detailed closely when BlackRock priced its $12.3 billion data center bond offering for Meta and when CoreWeave raised its own capital expenditure guidance earlier this summer. That wave of new corporate debt issuance adds further supply pressure to long-term bond markets at the exact moment government borrowing is already elevated, a combination that tends to push yields higher independent of any single catalyst.

The market reaction Wednesday reflected this convergence clearly. Rate-sensitive technology and growth stocks sold off sharply, with several names in the AI infrastructure and networking space falling double digits on the day, a pattern consistent with what happens whenever long-term borrowing costs move decisively higher.

For companies operating below the $2 billion market cap threshold, this is precisely the kind of environment worth watching closely. Small and microcap companies carry disproportionately more variable-rate debt than large cap peers, and when oil, Fed policy expectations, and corporate debt supply are all pushing in the same direction simultaneously, the resulting pressure on borrowing costs tends to be more durable and harder to reverse with any single piece of good news. The individual pieces of this story are all familiar. What matters now is that they are no longer moving independently, they are compounding.