Release – SelectQuote, Inc. Reports First Quarter of Fiscal Year 2027 Results

Select Quote

Research News and Market Data on SLQT

11/04/2026

First Quarter of Fiscal Year 2027 – Consolidated Earnings Highlights

  • Revenue of $280.0 million
  • Net loss of $(20.3) million
  • Adjusted EBITDA* of $(17.0) million

Fiscal Year 2027 Guidance Ranges:

  • Revenue expected in the range of $1.35 billion to $1.45 billion
  • Adjusted EBITDA* expected in the range of $90 million to $115 million
  • Operating Cash Flow expected to be more than $60 million

First Quarter Fiscal Year 2027 – Segment Highlights

Senior

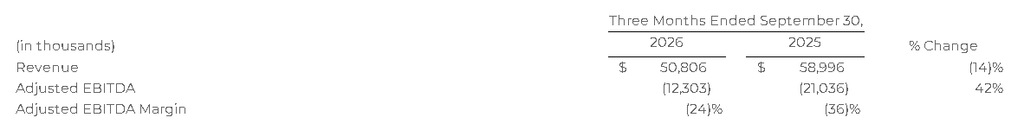
  • Revenue of $50.8 million
  • Adjusted EBITDA of $(12.3) million
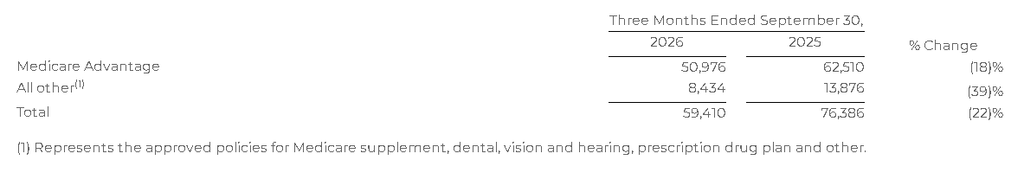
  • Approved Medicare Advantage policies of 50,976

Healthcare Services

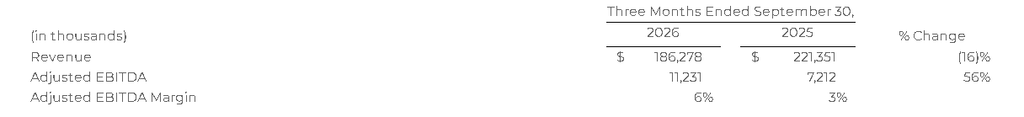
  • Revenue of $186.3 million
  • Adjusted EBITDA of $11.2 million
  • 99,753 SelectRx members

Life

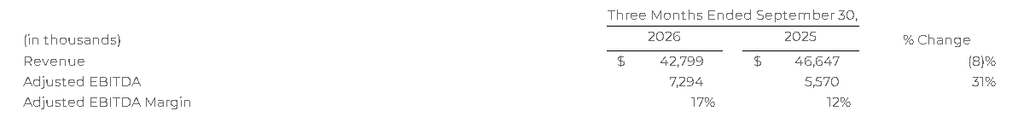
  • Revenue of $42.8 million
  • Adjusted EBITDA of $7.3 million

OVERLAND PARK, Kan.–(BUSINESS WIRE)– SelectQuote, Inc. (NYSE: SLQT) reported consolidated revenue for the first quarter of fiscal year 2027 of $280.0 million compared to consolidated revenue for the first quarter of fiscal year 2026 of $328.8 million. Consolidated net loss for the first quarter of fiscal year 2027 was $20.3 million compared to consolidated net loss for the first quarter of fiscal year 2026 of $30.5 million. Consolidated Adjusted EBITDA* for the first quarter of fiscal year 2027 was $(17.0) million compared to consolidated Adjusted EBITDA* for the first quarter of fiscal year 2026 of $(32.1) million. Consolidated cash used in operations during the first quarter of fiscal year 2027 was $17.2 million compared to $21.6 million used during the first quarter of fiscal year 2026.

Tim Danker, SelectQuote’s Chief Executive Officer, remarked, “We are proud of another strong quarter across both our Senior and Healthcare Services segments, resulting in a material year-over-year improvement in adjusted EBITDA and operating cash flow. We have high confidence in our current and long-term strategy to drive value for stakeholders, and we are pleased to reiterate our full-year financial targets for fiscal 2027. Our confidence stems primarily from growing efficiencies and process management that are within our control. The company’s foundational commitment to technology- and agent-led service have increasingly driven operating leverage in our business, which has only been accelerated through the use of AI. Now that AEP has kicked off, we are excited to see that our tenured agent force is helping a highly-engaged Medicare beneficiary population find the right plans to meet their unique needs. We firmly believe SelectQuote is well-positioned to drive meaningful growth in profit and cash flow for shareholders, both in fiscal 2027 and in an improving Medicare Advantage environment which we believe is on the horizon.”

Mr. Danker continued, “SelectQuote’s performance, in our seasonally slowest quarter, showcases the continued impact of our strategy to optimize profitability and cash flow. Despite lower revenue across both Senior and Healthcare Services, SelectQuote drove a 30% improvement in our year-over-year trailing twelve month adjusted EBITDA, and we remain on track to drive over $60 million in operating cash flow in fiscal 2027. Better yet, we are achieving these results in an environment where we strategically lowered agent headcount for Senior and continue to scale Healthcare Services despite the revenue headwind from the Inflation Reduction Act.”

* See “Non-GAAP Financial Measures” below.

Segment Results

We currently have three reportable segments: 1) Senior, 2) Healthcare Services and 3) Life. The performance measures of the segments include total revenue and adjusted EBITDA. Costs of commissions and other services revenue, cost of goods sold-pharmacy revenue, marketing and advertising, selling, general, and administrative, and technical development operating expenses that are directly attributable to a segment are reported within the applicable segment. Indirect costs of revenue, marketing and advertising, selling, general, and administrative, and technical development operating expenses are allocated to each segment based on varying metrics such as headcount.

Senior

Financial Results

The following table provides the financial results for the Senior segment for the periods presented:
Operating Metrics

Submitted Policies

Submitted policies are counted when an individual completes an application with our licensed agent and provides authorization to the agent to submit the application to the insurance carrier partner. The applicant may have additional actions to take before the application will be reviewed by the insurance carrier.

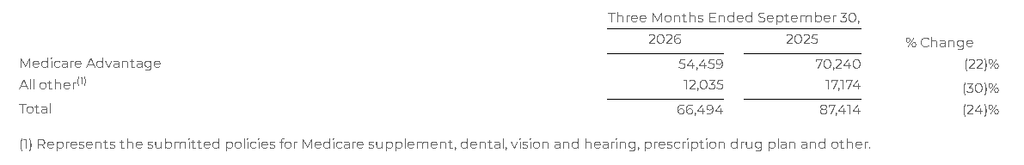
The following table shows the number of submitted policies for the periods presented:
Approved Policies

Approved policies represents the number of submitted policies that were approved by our insurance carrier partners for the identified product during the indicated period. Not all approved policies will go in force.

The following table shows the number of approved policies for the periods presented:
Lifetime Value of Commissions per Approved Policy

Lifetime value of commissions per approved policy represents commissions estimated to be collected over the estimated life of an approved policy based on multiple factors, including but not limited to, contracted commission rates, carrier mix and expected policy persistency with applied constraints. The lifetime value of commissions per approved policy is equal to the sum of the commission revenue due upon the initial sale of a policy, and when applicable, an estimate of future renewal commissions.

The following table shows the lifetime value of commissions per approved policy for the periods presented:
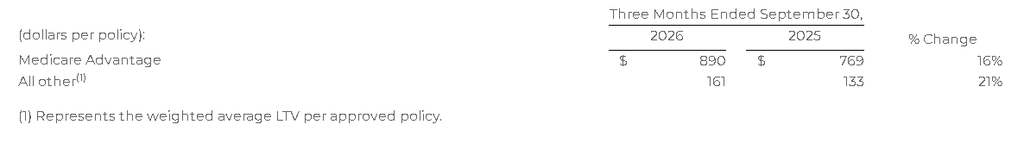
Healthcare Services

Financial Results

The following table provides the financial results for the Healthcare Services segment for the periods presented:
Operating Metrics

Members

The total number of SelectRx members represents the amount of active customers to which an order has been shipped and the prescriptions per day represents the total average prescriptions shipped per business day. These two metrics are the primary drivers of revenue for Healthcare Services.

The following table shows the total number of SelectRx members as of the periods presented:

The total number of SelectRx members decreased by 7% as of September 30, 2026, compared to September 30, 2025, primarily due to refined customer qualification with a focus on long-term profitability and operational efficiency. Profitability per SelectRx member increased 60% compared to a year ago from $67.1 per member to $107.6 per member. Profitability per member is calculated as Healthcare Services divisional Adjusted EBITDA for the period divided by average members, represented by the mean of ending membership in the prior period and ending membership in the current period.

The following table shows the average prescriptions shipped per day for the periods presented:

Combined Senior and Healthcare Services – Consumer Per Unit Economics

Combined Senior and Healthcare Services consumer per unit economics represents total MA and MS commissions; other product commissions; other revenues, including revenues from Healthcare Services; and operating expenses associated with Senior and Healthcare Services, each shown per number of approved MA and MS policies over a given time period. Management assesses the business on a per-unit basis to help ensure that the revenue opportunity associated with a successful policy sale is attractive relative to the marketing acquisition cost. Because not all acquired leads result in a successful policy sale, all per-policy metrics are based on approved policies, which is the measure that triggers revenue recognition.

The MA and MS commission per MA/MS policy represents the LTV for policies sold in the period. Other commission per MA/MS policy represents the LTV for other products sold in the period, including DVH prescription drug plan, and other products, which management views as additional commission revenue on our agents’ core function of MA/MS policy sales. Pharmacy revenue per MA/MS policy represents revenue from SelectRx, and other revenue per MA/MS policy represents revenue from Healthcare Select, production bonuses, marketing development funds, lead generation revenue, and adjustments from the Company’s reassessment of its cohorts’ transaction prices. Total operating expenses per MA/MS policy represents all of the operating expenses within Senior and Healthcare Services. The revenue to customer acquisition cost (“CAC”) multiple represents total revenue as a multiple of total marketing acquisition cost, which represents the direct costs of acquiring leads. These costs are included in marketing and advertising expense within the total operating expenses per MA/MS policy.

The following table shows combined Senior and Healthcare Services consumer per unit economics for the periods presented. Based on the seasonality of Senior and the fluctuations between quarters, we believe that the most relevant view of per unit economics is on a rolling 12-month basis. All per MA/MS policy metrics below are based on the sum of approved MA/MS policies, as both products have similar commission profiles.
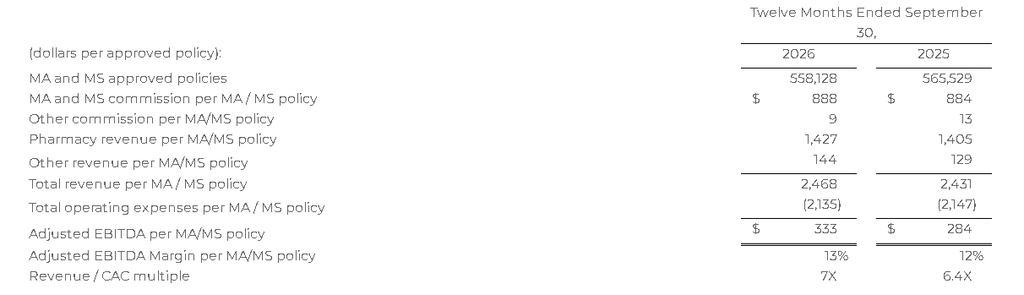
Total revenue per MA/MS policy increased 2% for the twelve months ended September 30, 2026, compared to the twelve months ended September 30, 2025, primarily due to the increase in pharmacy revenue during the twelve month period. Total operating expenses per MA/MS policy decreased 1% for the twelve months ended September 30, 2026, compared to the twelve months ended September 30, 2025.

Life

Financial Results

The following table provides the financial results for the Life segment for the periods presented:
Operating Metrics

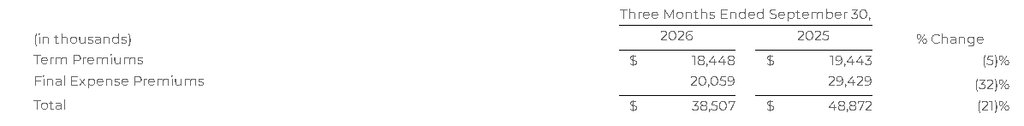
Life premium represents the total premium value for all policies that were approved by the relevant insurance carrier partner and for which the policy document was sent to the policyholder and payment information was received by the relevant insurance carrier partner during the indicated period. Because our commissions are earned based on a percentage of total premium, total premium volume for a given period is the key driver of revenue for our Life segment.

The following table shows term and final expense premiums for the periods presented:
Earnings Conference Call

SelectQuote, Inc. will host a conference call with the investment community on November 4, 2026, beginning at 8:30 a.m. ET. We encourage interested parties to access the live webcast of the event via our investor relations website https://ir.selectquote.com/investor-home/default.aspx or via this link: https://events.q4inc.com/attendee/147967155.

For those interested in dialing into the conference call, please register using this link: https://events.q4inc.com/analyst/147967155?pwd=mzE1TBCI. After registering, a confirmation will be sent via email, including dial-in details and unique conference call codes for entry. Registration is open through the live call, but to ensure you are connected for the full call we suggest registering at least 10 minutes before the start of the call.

Non-GAAP Financial Measures

This release includes certain non-GAAP financial measures intended to supplement, not substitute for, comparable GAAP measures. To supplement our financial statements presented in accordance with GAAP and to provide investors with additional information regarding our GAAP financial results, we have presented in this release Adjusted EBITDA, which, when presented on a consolidated basis, is a non-GAAP financial measure. This non-GAAP financial measure is not based on any standardized methodology prescribed by GAAP and is not necessarily comparable to any similarly titled measure presented by other companies. We define Adjusted EBITDA as net income (loss) plus interest expense, income taxes, depreciation and amortization, changes in fair value of warrant liabilities, loss on extinguishment of debt, and certain add-backs for non-cash or non-recurring expenses, including restructuring and share-based compensation expenses. The most directly comparable GAAP measure is net income (loss). We monitor and have presented in this release Adjusted EBITDA because it is a key measure used by our management and Board of Directors to understand and evaluate our operating performance, establish budgets, and develop operational goals for managing our business. In particular, we believe that excluding the impact of these expenses in calculating Adjusted EBITDA can provide a useful measure for period-to-period comparisons of our core operating performance.

A reconciliation of the differences between Adjusted EBITDA and its most directly comparable GAAP measure, net income (loss), is presented below on page 12. The Company is unable to provide a quantitative reconciliation of forward-looking Adjusted EBITDA to its most directly comparable GAAP measure without unreasonable effort because it is not possible to predict certain information included in the calculation of such GAAP measure, including the fair value of outstanding warrants to purchase shares of the Company’s common stock. The unavailable information could have a significant impact on the Company’s GAAP financial results.

Forward Looking Statements

This release contains forward-looking statements. These forward-looking statements reflect our current views with respect to, among other things, future events and our financial performance. These statements are often, but not always, made through the use of words or phrases such as “may,” “should,” “could,” “predict,” “potential,” “believe,” “will likely result,” “expect,” “continue,” “will,” “anticipate,” “seek,” “estimate,” “intend,” “plan,” “projection,” “would” and “outlook,” or the negative version of those words or other comparable words or phrases of a future or forward-looking nature. These forward-looking statements are not historical facts, and are based on current expectations, estimates and projections about our industry, management’s beliefs and certain assumptions made by management, many of which, by their nature, are inherently uncertain and beyond our control. Accordingly, we caution you that any such forward-looking statements are not guarantees of future performance and are subject to risks, assumptions and uncertainties that are difficult to predict. Although we believe that the expectations reflected in these forward-looking statements are reasonable as of the date made, actual results may prove to be materially different from the results expressed or implied by the forward-looking statements. There are or will be important factors that could cause our actual results to differ materially from those indicated in these forward-looking statements, including, but not limited to, the following: our reliance on a limited number of insurance carrier partners and any potential termination of those relationships or failure to develop new relationships; existing and future laws and regulations affecting the health insurance market; changes in health insurance products offered by our insurance carrier partners and the health insurance market generally; insurance carriers offering products and services directly to consumers; changes to commissions paid by insurance carriers and underwriting practices; competition with brokers, exclusively online brokers and carriers who opt to sell policies directly to consumers; competition from government-run health insurance exchanges; developments in the U.S. health insurance system; our dependence on revenue from carriers in our senior segment and downturns in the senior health as well as life, automotive and home insurance industries; our ability to develop new offerings and penetrate new vertical markets; risks from third-party products; failure to enroll individuals during the Medicare annual enrollment period; our ability to attract, integrate and retain qualified personnel; our dependence on lead providers and ability to compete for leads; failure to obtain and/or convert sales leads to actual sales of insurance policies; access to data from consumers and insurance carriers; accuracy of information provided from and to consumers during the insurance shopping process; cost-effective advertisement through internet search engines; ability to contact consumers and market products by telephone;our use of artificial intelligence and other emerging technologies;global economic conditions, including inflation; disruption to operations as a result of future acquisitions; significant estimates and assumptions in the preparation of our financial statements; impairment of goodwill; potential litigation and other legal proceedings or inquiries; our existing and future indebtedness; our ability to maintain compliance with our debt covenants; access to additional capital; our ability to regain and maintain compliance with NYSE listing standards; failure to protect our intellectual property and our brand; fluctuations in our financial results caused by seasonality; accuracy and timeliness of commissions reports from insurance carriers; timing of insurance carriers’ approval and payment practices; factors that impact our estimate of the constrained lifetime value of commissions per policyholder; changes in accounting rules, tax legislation and other legislation; disruptions or failures of our technological infrastructure and platform; failure to maintain relationships with third-party service providers; cybersecurity breaches or other attacks involving our systems or those of our insurance carrier partners or third-party service providers; our ability to protect consumer information and other data; failure to market and sell Medicare plans effectively or in compliance with laws; and other factors related to our pharmacy business, including manufacturing or supply chain disruptions, access to and demand for prescription drugs, changes in reimbursement rates under our contracts with pharmacy benefit managers, and regulatory changes or other industry developments that may affect our pharmacy operations. For a further discussion of these and other risk factors that could impact our future results and performance, see the section entitled “Risk Factors” in the most recent Annual Report on Form 10-K (the “Annual Report”) and subsequent periodic reports filed by us with the Securities and Exchange Commission. Accordingly, you should not place undue reliance on any such forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and, except as otherwise required by law, we do not undertake any obligation to publicly update or review any forward-looking statement, whether as a result of new information, future developments or otherwise.

About SelectQuote:

Founded in 1985, SelectQuote (NYSE: SLQT) pioneered the model of providing unbiased comparisons from multiple, highly-rated insurance companies, allowing consumers to choose the policy and terms that best meet their unique needs. Two foundational pillars underpin SelectQuote’s success: a strong force of highly-trained and skilled agents who provide a consultative needs analysis for every consumer, and proprietary technology that sources and routes high-quality leads. Today, the Company operates an ecosystem offering high touchpoints for consumers across insurance, pharmacy, and virtual care.

With an ecosystem offering engagement points for consumers across insurance, Medicare, pharmacy, and value-based care, the company now has three core business lines: SelectQuote Senior, SelectQuote Healthcare Services, and SelectQuote Life. SelectQuote Senior serves the needs of a demographic that sees around 10,000 people turn 65 each day with a range of Medicare Advantage and Medicare Supplement plans. SelectQuote Healthcare Services is comprised of the SelectRx Pharmacy, a Patient-Centered Pharmacy Home™ (PCPH) accredited pharmacy, SelectPatient Management, a provider of chronic care management services, and Healthcare Select which proactively connects consumers with a wide breadth of healthcare services supporting their needs.

View full release here.

Investor Relations:
Sloan Bohlen
877-678-4083
[email protected]

Media:
Matt Gunter
913-286-4931
[email protected]

Source: SelectQuote, Inc.
Beam Therapeutics Reports Breakthrough Gene-Editing Results as Patients Show Improved Glucose Control

Beam Therapeutics (NASDAQ: BEAM) has reported encouraging early clinical results from its experimental gene-editing treatment, BEAM-301, demonstrating the potential to significantly improve glucose regulation in patients with glycogen storage disease type Ia (GSDIa), a rare inherited metabolic disorder.

The Cambridge, Massachusetts-based biotechnology company announced results from its ongoing Phase 1/2 clinical trial on October 27, revealing that two patients receiving the higher treatment dose achieved 15 hours of controlled fasting without requiring the frequent starch supplementation typically necessary to manage the disease.

The findings represent an important early milestone for Beam’s base-editing technology, which is designed to correct specific genetic mutations rather than simply manage symptoms.

GSDIa is a rare genetic condition that prevents the liver from properly converting stored glycogen into glucose. Patients can experience dangerously low blood sugar levels and must carefully manage their diets, often consuming uncooked cornstarch throughout the day and night to maintain stable glucose levels.

BEAM-301 is designed to address the underlying genetic cause of the disease by correcting the R83C mutation in the G6PC1 gene. The treatment uses lipid nanoparticles to deliver gene-editing components directly to the liver.

Unlike traditional treatments that require ongoing medication or dietary management, Beam’s approach aims to provide lasting benefits following a single administration.

The initial clinical results included six patients who received BEAM-301, with three treated at a 20-milligram dose and three receiving 40 milligrams.

In the higher-dose group, the median time patients could fast before experiencing low blood sugar increased from 2.5 hours before treatment to 15 hours at the Day 36 assessment.

Two of the three patients in that group reached the study’s maximum controlled fasting duration of 15 hours. Those same two patients eventually eliminated their daily starch supplementation requirements at their latest reported assessments.

Patients also demonstrated improvements in glucose regulation, providing additional evidence that the treatment may help restore the body’s ability to produce glucose naturally.

However, the study remains in its early stages, and the small number of participants limits conclusions about long-term effectiveness.

Safety findings also warrant continued monitoring. Four of the six patients experienced serious treatment-related adverse events, including infusion reactions. The company reported no dose-limiting toxicities, and the serious events had resolved by the data cutoff.

Beam has modified its premedication and infusion procedures as development continues.

Following the results, the company is advancing BEAM-301 into a higher 60-milligram dose cohort and plans to engage with the U.S. Food and Drug Administration regarding a potential regulatory pathway.

For investors, the announcement offers early clinical evidence supporting Beam’s precision genetic medicine platform. Successful development could establish base editing as a potential treatment strategy for certain inherited metabolic diseases.

The technology differs from conventional gene-editing approaches because it can make targeted changes to individual DNA bases without requiring double-strand DNA breaks.

That distinction could have broader implications for biotechnology companies developing therapies for diseases caused by specific genetic mutations.

Nevertheless, significant clinical and regulatory hurdles remain. Larger studies, longer patient follow-up, and additional safety evaluations will be necessary before BEAM-301 can be considered for approval.

Beam’s latest results highlight the growing potential of next-generation gene-editing treatments while illustrating the substantial development risks associated with bringing innovative therapies to market.

Release – As Ebola Spreads to Multiple Countries, the Importance of NV-387 Oral Gummies Treatment Cannot be Understated – Phase II Clinical Trial Advancing Towards the Second Part, Says NanoViricides

Shelton, Connecticut – Tuesday, October 27, 2026.


NanoViricides, Inc. (NYSE American: NNVC) (the “Company”), a clinical stage leader
developing antiviral drugs that viruses cannot escape, explained today that the Phase IIA Ebola Treatment
Clinical Trial of NV-387 Oral Gummies is progressing well, and the drug is expected to advance into the
Phase IIB clinical trial part as soon as the Phase IIA part is completed.

“The importance of the NV-387 Oral Gummies treatment for this Ebola Bundibugyo virus disease
cannot be understated, considering the potential of the disease for rapid spread and the heavy toll it is
taking in affected areas in terms of both deaths and economic costs of containment and response,” said
Anil R. Diwan, PhD, President and Executive Chairman of the Company.

The NV-387 Oral Gummies as a Treatment for Ebola Phase II Clinical Trial in DRC is divided
into two parts. The first part, Phase IIA, is designed to evaluate dosing regimens based on the severity of
the disease, and requires approximately 20 patients. Enrollment began on September, 23, 2026. The end
point is 28-day survival, as with other Ebola clinical trials. As such, the Phase IIA part will be completed
once the last enrolled person completes 28 days.

The course of the clinical trial suggests that the trial will continue into Phase IIB part upon completion of
the Phase IIA part.

Ebola has escaped the main epidemic affected country of Democratic Republic Congo (DRC) in
multiple instances, and cases have started occurring in Kenya as well as Nigeria, one of the most
populous countries in Africa . Previously, an infected person had traveled from DRC to Uganda, causing 1
a small outbreak, but there have been no new cases reported in Uganda recently. A person that traveled
recently from DRC to Kenya died, and infected at least 8 others, one of whom has also died, and at least
134 contacts were traced . Kenya has released some of the quarantined contacts. The case in Nigeria was 2
a Swiss national and was evacuated to a Swiss hospital for treatment. Previously, medical personnel
working with the Doctors Without Borders (MSF/DWB) have been evacuated to Europe for treatment.

This East to West Africa spread has occurred in spite of substantive travel restrictions. Additional
restrictions have been effected by many countries as a result . Importantly, the instances of single 3
infected persons creating multiple cases have demonstrated the significant global risk and challenge posed
by this Ebola outbreak. As many as 8 or more cases have occurred from contact with a single infected
person during this outbreak. Such persons causing a large number of transmissions are often called
“superspreaders”.

As the outbreak continues, the number of confirmed cases in DRC have reached 10,060, with
4,887 deaths since this Ebola-Bundibugyo virus outbreak was identified. It is the fastest growing Ebola
outbreak, and largest in DRC, with the potential to eclipse, in a few months, the West Africa 2014-16
Ebola-Zaire outbreak that killed 11,000 people.

A clinical trial of Infusions of an antibody cocktail, Infusion of remdesivir, and Infusion of both
of them given to the patient is in progress, called the “PARTNERS” clinical trial, since July 2, 2026.
There have been no public updates, other than that more than 350 patients were already enrolled about a
month ago.

A clinical trial to evaluate vaccines, called “Tumaini” (meaning “Hope” in Swahili) has started as
of last week. The first candidate vaccine in this trial is Ervebo, which is specific to Ebola Zaire, and it is
not known how effective it could be against Ebola Bundibugyo virus. Two other vaccine candidates, one
developed by University of Oxford, ChAdOx1-BDBV, and another, a BDBV-mRNA vaccine developed
by Moderna, are expected to be added into this clinical trial when the supplies become available . This 4
vaccines trial will employ a “ring vaccination” protocol.

Ervebo vaccine is not specific to BDBV, which means it is an unmatched vaccine. Unmatched
Page 1 of 4vaccines can cause rapid occurrence of escape mutants. Also, in vaccinated persons, later infection can
even cause a more aggressive disease, a phenomenon called “Antibody-Dependent Enhancement” of
disease, promoted by the inaccurate antibodies created in response to the vaccine. Vaccines in general can
lead to escape mutants. Ebola virus is an RNA virus and thus very capable of generating escape mutants.
Vaccines are not useful for a person after infection. Also, a vaccine requires about 2-3 weeks for
antibody response to be generated, and therefore is minimally protective before 3 weeks. If a second dose
of vaccine is needed, it complicates the situation further, because the first dose only creates partial
immunity.

Thus an effective treatment is essential for combatting a spreading epidemic such as the current
Ebola epidemic. Infusions such as of antibody cocktails or small chemical drugs are only useful, if
effective, when patients can be hospitalized for the duration until recovery, and are costly to store,
transport, and administer. Thus, to combat a widely spreading disease in the community, oral drugs are the
most preferred.

There is no treatment or vaccine approved for Ebola BDBV at present. NV-387 Oral Gummies is
the only oral drug product in clinical trials, to the best of our knowledge, underscoring its importance for
fighting the current Ebola BDBV epidemic, and future epidemics.
The same drug product, NV-387 Oral Gummies, is also in a Phase II clinical trial for the
treatment of Mpox (Monkeypox) in DRC.

NV-387 is a novel, revolutionary broad-spectrum antiviral that is poised to change the way
humanity treats viral infections.

ABOUT NANOVIRICIDES
NanoViricides, Inc. (the “Company”) (www.nanoviricides.com) is a clinical stage company that is creating
special purpose nanomaterials for antiviral therapy. The Company’s novel nanoviricide™ class of drug candidates
and the nanoviricide™ technology are based on intellectual property, technology and proprietary know-how of
TheraCour Pharma, Inc. The Company has a Memorandum of Understanding with TheraCour for the development
of drugs based on these technologies for all antiviral infections. The MoU does not include cancer and similar
diseases that may have viral origin but require different kinds of treatments.

The Company has obtained broad, exclusive, sub-licensable, field licenses to drugs developed in several
licensed fields from TheraCour Pharma, Inc. The Company’s business model is based on licensing technology from
TheraCour Pharma Inc. for specific application verticals of specific viruses, as established at its foundation in 2005.
Our lead drug candidate is NV-387, a broad-spectrum antiviral drug that we plan to develop as a treatment
of RSV, COVID, Long COVID, Influenza, and other respiratory viral infections, as well as MPOX/Smallpox
infections. Our other advanced drug candidate is NV-HHV-1 for the treatment of Shingles. The Company cannot
project an exact date for filing an IND for any of its drugs because of dependence on a number of external
collaborators and consultants. The Company is currently focused on advancing NV-387 into Phase II human clinical
trials.

NV-CoV-2 (API NV-387) is our nanoviricide drug candidate for COVID-19 that does not encapsulate
remdesivir. NV-CoV-2-R is our other drug candidate for COVID-19 that is made up of NV-387 with remdesivir
encapsulated within its polymeric micelles. The Company believes that since remdesivir is already US FDA
approved, our drug candidate encapsulating remdesivir is likely to be an approvable drug, if safety is comparable.
Remdesivir is developed by Gilead. The Company has developed both of its own drug candidates NV-CoV-2 and
NV-CoV-2-R independently.

The Company is also developing drugs against a number of viral diseases including oral and genital
Herpes, viral diseases of the eye including EKC and herpes keratitis, H1N1 swine flu, H5N1 bird flu, seasonal
Influenza, HIV, Hepatitis C, Rabies, Dengue fever, and Ebola virus, among others. NanoViricides’ platform
technology and programs are based on the TheraCour® nanomedicine technology of TheraCour, which TheraCour
licenses from AllExcel. NanoViricides holds a worldwide exclusive perpetual license to this technology for several
drugs with specific targeting mechanisms in perpetuity for the treatment of the following human viral diseases:
Human Immunodeficiency Virus (HIV/AIDS), Hepatitis B Virus (HBV), Hepatitis C Virus (HCV), Rabies, Herpes
Page 2 of 4Simplex Virus (HSV-1 and HSV-2), Varicella-Zoster Virus (VZV), Influenza and Asian Bird Flu Virus, Dengue
viruses, Japanese Encephalitis virus, West Nile Virus, Ebola/Marburg viruses, and certain Coronaviruses. The
Company intends to obtain a license for RSV, Poxviruses, and/or Enteroviruses if the initial research is successful.
As is customary, the Company must state the risk factor that the path to typical drug development of any
pharmaceutical product is extremely lengthy and requires substantial capital. As with any drug development efforts
by any company, there can be no assurance at this time that any of the Company’s pharmaceutical candidates would
show sufficient effectiveness and safety for human clinical development. Further, there can be no assurance at this
time that successful results against coronavirus in our lab will lead to successful clinical trials or a successful
pharmaceutical product.

This press release contains forward-looking statements that reflect the Company’s current expectation
regarding future events. Actual events could differ materially and substantially from those projected herein and
depend on a number of factors. Certain statements in this release, and other written or oral statements made by
NanoViricides, Inc. are “forward-looking statements” within the meaning of Section 27A of the Securities Act of
1933 and Section 21E of the Securities Exchange Act of 1934. You should not place undue reliance on forwardlooking statements since they involve known and unknown risks, uncertainties and other factors which are, in some
cases, beyond the Company’s control and which could, and likely will, materially affect actual results, levels of
activity, performance or achievements. The Company assumes no obligation to publicly update or revise these
forward-looking statements for any reason, or to update the reasons actual results could differ materially from those
anticipated in these forward-looking statements, even if new information becomes available in the future. Important
factors that could cause actual results to differ materially from the company’s expectations include, but are not
limited to, those factors that are disclosed under the heading “Risk Factors” and elsewhere in documents filed by the
company from time to time with the United States Securities and Exchange Commission and other regulatory
authorities. Although it is not possible to predict or identify all such factors, they may include the following:
demonstration and proof of principle in preclinical trials that a nanoviricide is safe and effective; successful
development of our product candidates; our ability to seek and obtain regulatory approvals, including with respect to
the indications we are seeking; the successful commercialization of our product candidates; and market acceptance
of our products.

The phrases “safety”, “effectiveness” and equivalent phrases as used in this press release refer to research
findings including clinical trials as the customary research usage and do not indicate evaluation of safety or
effectiveness by the US FDA.

FDA refers to US Food and Drug Administration. IND application refers to “Investigational New Drug”
application. cGMP refers to current Good Manufacturing Practices. CMC refers to “Chemistry, Manufacture, and
Controls”. CHMP refers to the Committee for Medicinal Products for Human Use, which is the European Medicines
Agency’s (EMA) committee responsible for human medicines. API stands for “Active Pharmaceutical Ingredient”.
WHO is the World Health Organization. R&D refers to Research and Development.

Contact:
NanoViricides, Inc.
[email protected]
Public Relations Contact:
[email protected]
Source: NanoViricides, Inc.

Eledon Pharmaceuticals (ELDN) – Phase 2 BESTOW Analysis Shows Improved Quality Of Life and Reduced Symptom Burden


Tuesday, October 27, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

New Data Presentation On Quality of Life and Symptoms. Eledon presented data from the Phase 2 BESTOW trial at the American Society of Nephrology Annual Kidney Week 2026 meeting. The presentation compared patients receiving tegoprubart with those receiving tacrolimus, showing improvements in quality of life and reductions in symptom burden at 12 months. We believe these findings support prior data on efficacy, safety, and tolerability.

Patient Evaluations. Data from two accepted clinical evaluations, MTSOSD-59R and KDQOL-SF, showed substantial, lasting improvements in quality of life and reductions in transplant-related side effects. We see these patient-reported outcomes as consistent with prior reductions in BPAR (Biopsy-Proven Acute Rejection), improvements in eGFR, and improvements in factors that contribute to long-term graft failure.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – Eledon Pharmaceuticals Presents Phase 2 BESTOW Trial Data Showing Sustained Improvements in Quality of Life and Symptom Burden with Tegoprubart Compared to Tacrolimus at American Society of Nephrology Kidney Week 2026 Annual Meeting

October 26, 2026

Tegoprubart-treated patients demonstrated a mean improvement on the total MTSOSD-59R symptom occurrence scale at 12 months while tacrolimus-treated patients experienced a mean worsening of symptom occurrence

Statistically significant improvement on the KDQOL-SF Symptoms and Problems Scale among tegoprubart-treated patients through 12 months following kidney transplantation versus tacrolimus

Results further validate the differentiated clinical profile of tegoprubart and potential to transform standard of care in kidney transplantation

IRVINE, Calif., Oct. 26, 2026 (GLOBE NEWSWIRE) — Eledon Pharmaceuticals, Inc. (“Eledon”) (Nasdaq: ELDN) today announced new positive patient-reported outcomes data from the Phase 2 BESTOW clinical trial of tegoprubart, its novel investigational immunosuppression therapy. The data showed significant, sustained improvements in health-related quality of life and symptom burden through 12 months compared with standard of care tacrolimus following kidney transplantation. The results were featured in an oral presentation at the American Society of Nephrology (ASN) Kidney Week 2026 Annual Meeting held October 21-25, 2026, in Denver, Colorado.

“The patient-reported outcomes presented at ASN Kidney Week provide perhaps the clearest picture yet of what tegoprubart’s differentiated profile means for transplant patients in everyday life,” said David-Alexandre C. Gros, M.D., Chief Executive Officer of Eledon. “We previously reported encouraging BESTOW results across efficacy, kidney function and safety measures, which alone strengthened our belief in tegoprubart. The additional findings presented demonstrate that these clinical outcomes were accompanied by substantial and importantly sustained improvements in quality of life and reductions in transplant-related symptom burden. Giving transplant patients an effective, safer and more tolerable alternative to tacrolimus addresses one of the most important unmet needs in organ transplantation, and collectively, these data further support the potential of tegoprubart to become a transformative new treatment option for kidney transplant recipients.”

“Success after kidney transplantation is measured not only by preventing rejection and preserving graft function, but also by how patients feel and function in their everyday lives,” said presenting author Andrew Adams, M.D., Ph.D., Professor of Surgery and Chief, Division of Transplantation, John S. Najarian Surgical Chair in Clinical Transplantation, Department of Surgery, University of Minnesota. “What is particularly compelling about these BESTOW results is the consistency of the patient-reported benefits when treated with tegoprubart compared with tacrolimus following kidney transplant. We observed broad improvements in quality-of-life measures together with remarkably favorable outcomes in transplant-specific symptom reporting. The extent of separation between treatment groups suggests patients receiving tegoprubart may experience meaningful quality of life advantages while maintaining strong clinical outcomes as previously reported from BESTOW.”

Patient-Reported Outcomes Results

Patient-reported outcomes were assessed using the Modified Transplant Symptom Occurrence and Symptom Distress Scale (MTSOSD-59R) and the Kidney Disease Quality of Life Short Form (KDQOL-SF) Symptoms and Problems Scale, both validated measures of symptom burden. Baseline scores were similar between treatment groups. Collectively, the consistency of findings across both the KDQOL-SF and MTSOSD-59R assessments suggests that reductions in transplant-related symptom burden with tegoprubart may contribute to the improvements observed in patient-reported quality of life and further supports the differentiated clinical profile of tegoprubart compared to tacrolimus observed in the Phase 2 BESTOW clinical trial.

On the MTSOSD-59R assessment, tegoprubart-treated patients reported continued reductions in symptom occurrence from baseline at Months 6 and 12, whereas symptom occurrence in the tacrolimus arm initially declined through Month 6 before returning to slightly above baseline levels at Month 12.

Total MTSOSD-59R
Scores represent symptom occurrence
(higher scores reflect greater symptom occurrence)

Total MTSOSD-59R

CI, confidence interval; KDQOL-SF, Kidney Disease Quality of Life Short Form; MTSOSD-59R, Modified Transplant Symptom Occurrence Scale- 59 Items Revised; SEM, standard error of the mean; tac, tacrolimus; tego, tegoprubart.

Tegoprubart demonstrated greater symptom improvement than tacrolimus in 22 of 23 domains where differential improvement was observed, including neurological, gastrointestinal, metabolic, and physical symptom categories. In addition, tacrolimus demonstrated greater symptom worsening in 22 of 22 domains where differential symptom worsening was observed.

On the KDQOL-SF assessment, kidney transplant patients treated with tegoprubart demonstrated improvements from baseline across all five subscales through Month 12. In the KDQOL-SF scale, a change of 3-5 points can be considered clinically significant, and tegoprubart was thus associated with a clinically and statistically significant improvement in the symptoms and problems subscale compared with tacrolimus at Month 12, with mean changes from baseline of 9.0 and 3.3 points, respectively (p<0.05). Consistent with these findings, the SF-12 mental component summary score increased by 1.5 points in the tegoprubart arm compared to a decline of 1.6 points in the tacrolimus arm, representing a 3.1-point between-group difference.

KDQOL-SF: Change from Baseline

a Higher scores indicate better HRQoL; a change of 3–5 points can be considered clinically significant1. Baseline values were similar across all outcomes. *p < 0.05. HRQoL, health-related quality of life; KDQOL-SF, Kidney Disease Quality of Life Short-Form instrument; SEM, standard error of the mean; SF-12, 12-item short-form survey; tac, tacrolimus; tego, tegoprubart.1. KDOQI. Am J Kidney Dis 2007;50:471–530.

Details of the oral presentation at ASN Kidney Week 2026 are below:

Title: Patient-Reported Outcomes in the Phase 2 BESTOW Trial Comparing Tegoprubart to Tacrolimus in Kidney Transplant Recipients
Presenter: Andrew B. Adams, M.D., Ph.D., Department of Surgery, University of Minnesota Medical School; Minneapolis, Minnesota
Abstract Publication Number: FR-OR084
Session Title: The Changing Landscape of Kidney Transplantation: Clinical Innovation, Outcomes, and Healthy Policy
Session Date and Time: Friday, October 23, 2026, from 4:30 p.m. to 6:00 p.m. MDT
Session Room: Mile High Ballroom 4A (Convention Center)
Presentation Time: 4:40 p.m. to 4:50 p.m. MDT

About Eledon Pharmaceuticals and tegoprubart

Eledon Pharmaceuticals, Inc. is a clinical stage biotechnology company that is developing immune-modulating therapies for the management and treatment of life-threatening conditions. The Company’s lead investigational product is tegoprubart, an anti-CD40L antibody with high affinity for the CD40 Ligand, a well-validated biological target that has broad therapeutic potential. The central role of CD40L signaling in both adaptive and innate immune cell activation and function positions it as an attractive target for non-lymphocyte depleting, immunomodulatory therapeutic intervention. The Company is building upon a deep historical knowledge of anti-CD40L biology to conduct preclinical and clinical studies in kidney allograft transplantation, xenotransplantation, islet cell transplantation, liver transplantation and amyotrophic lateral sclerosis (ALS). Eledon is headquartered in Irvine, California. For more information, please visit the Company’s website at www.eledon.com.

Follow Eledon Pharmaceuticals on social media: LinkedIn; X

Forward-Looking Statements

This press release contains forward-looking statements that involve substantial risks and uncertainties. Any statements about the company’s future expectations, plans and prospects, including statements about planned clinical trials, the development of product candidates, expected timing for initiation of future clinical trials, expected timing for receipt of data from clinical trials, as well as other statements containing the words “believes,” “anticipates,” “plans,” “expects,” “estimates,” “intends,” “predicts,” “projects,” “targets,” “looks forward,” “could,” “may,” and similar expressions, constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Specifically, our ability to achieve our anticipated future development and corporate milestones depends on our ability to obtain additional financing on acceptable terms. Forward-looking statements are inherently uncertain and are subject to numerous risks and uncertainties, including: our short operating history and shifts in our business strategy; our operating losses since inception; our need for additional funding to develop our lead drug candidate and our ability to secure additional funding on acceptable terms or at all; the impact of issuances of our common stock, including in the possibility of dilution or a decline in our stock price; our ability to successfully develop our product candidates; unfavorable global economic and financial market conditions; the regulatory environment of our business and our ability to obtain required regulatory approvals; results of non-clinical studies and clinical trials, and risks that non-clinical studies or early clinical trials may not be predictive of results of later-stage clinical trials; delays or difficulties in enrollment of patients in clinical trials; our ability to attract and retain our executives and key employees; legislation of the pharmaceutical and healthcare industries; cybersecurity and data privacy risks; the ability of our products to achieve marketing approval; competition in our industry; our ability to obtain insurance coverage; our dependence on contract research organizations; our ability to protect our intellectual property; public health crises; our ability to maintain proper and effective internal control over financial reporting and other risks disclosed in our Annual Report on Form 10-K for the year ended December 31, 2025, filed with the Securities and Exchange Commission on March 19, 2026. Actual results may differ materially from those indicated by such forward-looking statements as a result of various factors. These risks and uncertainties, as well as other risks and uncertainties that could cause the company’s actual results to differ materially from the forward-looking statements contained herein, are discussed in our Annual 10-K, and other filings with the U.S. Securities and Exchange Commission, which can be found at www.sec.gov. Any forward-looking statements contained in this press release speak only as of the date hereof and not of any future date, and the company expressly disclaims any intent to update any forward-looking statements, whether as a result of new information, future events or otherwise.

Investor Contact:

Stephen Jasper
Gilmartin Group
(858) 525 2047
[email protected]

Media Contact:

Jenna Urban
CG Life
(212) 253 8881
[email protected]

Eledon Pharmaceuticals Reports Positive Kidney Transplant Trial Data as Tegoprubart Improves Quality of Life

Eledon Pharmaceuticals (NASDAQ: ELDN) announced new positive Phase 2 clinical trial results Monday showing that its investigational kidney transplant therapy, tegoprubart, delivered sustained improvements in patient-reported quality of life and transplant-related symptoms compared with tacrolimus, a commonly used immunosuppressive treatment.

The findings, presented at the American Society of Nephrology’s Kidney Week 2026 meeting in Denver, add to previously reported results from Eledon’s Phase 2 BESTOW trial and highlight the potential for a new approach to managing immune suppression following kidney transplantation.

Kidney transplant recipients typically require lifelong immunosuppressive medications to prevent their immune systems from rejecting donated organs. Although existing treatments have significantly improved transplant outcomes, they can produce side effects that affect patients’ daily lives and long-term health.

Eledon’s tegoprubart is designed to address this challenge by targeting CD40 ligand, a protein involved in activating immune responses. Unlike traditional immunosuppressive therapies, the investigational antibody aims to regulate immune activity through a different biological pathway.

The latest BESTOW findings focused on patient-reported outcomes, including physical symptoms, emotional well-being, and overall quality of life during the first year following transplantation.

Researchers evaluated patients using two established assessment tools: the Modified Transplant Symptom Occurrence and Symptom Distress Scale and the Kidney Disease Quality of Life Short Form.

At 12 months, patients receiving tegoprubart demonstrated continued improvements in overall symptom occurrence, while patients treated with tacrolimus experienced a slight worsening compared with their baseline measurements.

Tegoprubart also showed greater symptom improvement in 22 of 23 categories where differences between the treatment groups were observed. These included neurological, gastrointestinal, metabolic, and physical symptoms.

One of the most notable findings involved the Kidney Disease Quality of Life assessment. Patients receiving tegoprubart reported an average nine-point improvement on the Symptoms and Problems Scale, compared with a 3.3-point improvement among patients receiving tacrolimus.

The difference was statistically significant, with Eledon noting that a change of three to five points on the scale can be considered clinically meaningful.

Additional findings suggested potential benefits for mental well-being. Patients treated with tegoprubart experienced a 1.5-point improvement in the mental component summary score, compared with a 1.6-point decline in the tacrolimus group.

The findings suggest that tegoprubart’s potential benefits may extend beyond preventing organ rejection to improving how transplant recipients feel and function in everyday life.

For Eledon, the results provide additional evidence supporting the differentiated clinical profile of its lead drug candidate. Previous BESTOW findings addressed measures of efficacy, kidney function, and safety, while the newly presented data provide further insight into the patient experience.

The development is relevant to investors because kidney transplantation represents a specialized therapeutic market in which effective treatments that reduce medication-related complications could address an important unmet medical need.

However, tegoprubart remains investigational and has not received regulatory approval. Additional clinical development and regulatory review will be necessary before its potential commercial use can be established.

Eledon is also exploring the broader applications of its anti-CD40L technology across other transplantation settings and immune-related conditions, including islet cell transplantation, liver transplantation, and amyotrophic lateral sclerosis.

The latest results underscore growing interest in developing more targeted immunosuppressive treatments that balance the prevention of organ rejection with patients’ long-term quality of life.

For small-cap biotechnology investors, Eledon’s findings represent another clinical development milestone as the company works to advance tegoprubart and demonstrate its potential as an alternative to existing kidney transplant therapies.

Take a moment to read more equity research on Eledon Pharmaceuticals here.

Cosmos Health (COSM) – Building a Higher-Margin Healthcare Platform


Monday, October 26, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Richard Magnusen, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Initiating coverage with an Outperform rating. We believe Cosmos Health is positioned for a meaningful improvement in profitability as its revenue mix shifts toward higher-margin proprietary healthcare products and pharmaceutical manufacturing. The company’s established wholesale distribution business provides a revenue base, while its expanding U.S. direct-to-consumer operations could become an increasingly important driver of earnings growth.

U.S. direct-to-consumer sales are gaining momentum. Management expects approximately $15 million in fourth-quarter 2026 U.S. e-commerce revenue and $10.5 million in gross profit, reflecting the rapid expansion of its proprietary nutraceutical business. Active U.S. subscriptions reached 8,940 as of October 19, although customer retention and marketing efficiency remain important considerations as the business scales.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Roche Signs $813 Million Zymeworks Cancer Drug Deal as Biotech Partnerships Accelerate

Roche is expanding its oncology pipeline through a licensing agreement with Zymeworks (NASDAQ: ZYME) valued at up to $813 million, highlighting continued interest from major pharmaceutical companies in experimental cancer treatments developed by smaller biotechnology firms.

The agreement, announced October 23, 2026, gives Swiss pharmaceutical giant Roche exclusive worldwide rights to develop and commercialize ZW209, an investigational therapy designed to treat certain cancers, including small-cell lung cancer.

Under the agreement, Zymeworks will receive an upfront payment of $55 million, followed by an additional $40 million if Roche initiates a planned Phase 1b clinical trial. The biotechnology company could also receive up to $718 million in development, commercial, and sales-related milestone payments, along with royalties on future sales of approved treatments.

The full $813 million value is contingent on achieving specified milestones and does not represent guaranteed revenue.

ZW209 belongs to an emerging class of cancer therapies known as trispecific T-cell engagers. These treatments are designed to help the immune system recognize and attack cancer cells by connecting immune cells with specific targets found on tumors.

The experimental drug targets DLL3, a protein frequently expressed in small-cell lung cancer and certain other neuroendocrine tumors but generally found at low levels in healthy tissue.

ZW209 is designed to engage DLL3 while simultaneously interacting with two proteins on immune cells, CD3 and CD28. This approach aims to stimulate an immune response against cancer cells while potentially improving the effectiveness and durability of treatment.

The drug remains in early clinical development, and its safety and effectiveness in patients have not yet been established.

Zymeworks will conduct the Phase 1a portion of the clinical program in collaboration with Roche, which will fund the study. Roche will subsequently assume responsibility for global development and commercialization.

The first patient is expected to enter the study before the end of 2026, according to Zymeworks management.

For investors, the transaction illustrates an important strategy in the biotechnology industry: smaller drug developers can use licensing agreements to secure funding and share clinical development risks while retaining opportunities for future milestone payments and royalties.

These partnerships can be particularly valuable for emerging biotechnology companies, where clinical trials require substantial investment and successful commercialization often depends on extensive manufacturing, regulatory, and distribution capabilities.

Roche’s decision to partner on ZW209 before human efficacy data are available also underscores the importance pharmaceutical companies place on differentiated scientific platforms and promising early-stage research.

The agreement reflects broader interest in innovative oncology treatments, including immunotherapies and therapies designed to target specific biological mechanisms involved in cancer.

Within Noble Capital Markets’ research coverage universe, Greenwich LifeSciences (NASDAQ: GLSI) is developing an investigational immunotherapy for breast cancer, while Cardiff Oncology (NASDAQ: CRDF) is advancing onvansertib, an experimental cancer treatment targeting the PLK1 enzyme. Although their technologies differ from ZW209, these companies illustrate the range of oncology approaches being pursued by emerging biotechnology developers. Neither company is involved in the Roche-Zymeworks agreement.

The transaction also highlights the potential financial importance of early-stage biotechnology partnerships. Rather than acquiring entire companies, larger pharmaceutical businesses can license individual drug candidates, gaining access to promising technologies while limiting their initial financial commitments.

However, significant risks remain. Experimental cancer treatments face lengthy clinical trials, regulatory scrutiny, and uncertainty surrounding patient outcomes. Milestone payments depend on future progress, and many investigational therapies never reach commercialization.

The Roche-Zymeworks agreement remains subject to customary closing conditions, including applicable antitrust clearance.

For small-cap biotechnology investors, the deal provides another example of how innovative drug-development platforms can attract major pharmaceutical partners. As competition for differentiated cancer treatments continues, licensing agreements may remain an important source of funding and strategic validation for emerging biotech companies.

Unicycive Therapeutics (UNCY) – NDA Resubmission Accepted For FDA Review


Thursday, October 22, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

OLC Resubmission Given March 25, 2027 PDUFA Date. Unicycive announced that the FDA has accepted its NDA (New Drug Application) resubmission for OLC (oxylanthanum carbonate) for review. This follows the 30-day period after resubmission in which the FDA determined that it was sufficiently complete for review. The application received a PDUFA (Prescription Drug User Fee Act) date of March 25, 2027. This is the date the FDA must respond to the application by statute and aligns with the TDAPA program deadlines.

The NDA Contains Data From A New Manufacturing Partner. As we had expected, the resubmission was classified as Class 2 and received a six-month review. The CMC (Chemistry, Manufacturing, and Controls) section includes product manufacturing data from a new third-party manufacturing partner. The FDA inspected this manufacturer’s plant in March 2024 and gave a “No Action Indicated” status, the equivalent of a passing grade.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – Unicycive Therapeutics Announces FDA Acceptance of Oxylanthanum Carbonate New Drug Application Resubmission and PDUFA Date of March 25, 2027

October 21, 2026 7:05am EDT

Primary Logo

MOUNTAIN VIEW, Calif., Oct. 21, 2026 (GLOBE NEWSWIRE) — Unicycive Therapeutics, Inc. (“Unicycive” or the “Company”) (Nasdaq: UNCY), a clinical-stage biotechnology company developing therapies for patients with kidney disease, today announced that the U.S. Food and Drug Administration (FDA) has accepted the resubmission of its New Drug Application (NDA) for oxylanthanum carbonate (OLC), the Company’s investigational oral phosphate binder for the treatment of hyperphosphatemia in patients with chronic kidney disease (CKD) on dialysis. The NDA was resubmitted following a Complete Response Letter (CRL) received in June 2026. The FDA has deemed the OLC resubmission a Class II with a six-month review period from the resubmission date, and set a Prescription Drug User Fee Act (PDUFA) target action date of March 25, 2027.

“We are pleased that the FDA has accepted the resubmission of our NDA for OLC and assigned a PDUFA date,” said Shalabh Gupta, M.D., Chief Executive Officer of Unicycive. “This resubmission includes CMC data from a new third-party drug product manufacturing vendor. The new vendor’s facility was last inspected by the FDA in March 2024 and received ‘No Action Indicated’ status. We hope to continue working with the FDA toward potential approval of this important medication to patients with CKD on dialysis who need additional treatment options for managing hyperphosphatemia.”

The Company does not know whether the FDA will decide to conduct a pre-approval inspection of the new third-party DP vendor. Additionally, if the original third-party manufacturing vendor is inspected in the near term and finds that its facility complies with current Good Manufacturing Practice (cGMP), the Company plans to seek FDA alignment on a shorter approval timeline.

The Company resubmitted the NDA following the second CRL, which cited deficiencies previously identified at the original third-party manufacturer of the drug product, which the FDA had not been able to re-inspect during the prior submission review.

The timing and outcome of any FDA inspection of the original third-party vendor will be determined solely by the FDA.

The NDA is supported by data from three clinical studies (a Phase 1 study in healthy volunteers, a bioequivalence study in healthy volunteers, and a tolerability study of OLC in CKD patients on dialysis), multiple preclinical studies, as well as CMC data. The FDA did not raise any concerns regarding OLC’s preclinical or clinical data, including safety data, included in the original NDA submission.

About Oxylanthanum Carbonate
OLC is an investigational oral phosphate binder that leverages proprietary nanoparticle technology to deliver high phosphate binding potency, reducing the number and size of pills that patients must take to treat hyperphosphatemia in patients with chronic kidney disease (CKD) on dialysis. Its potential best-in-class profile may have meaningful patient adherence benefits over currently available treatment options as it requires a lower pill burden. Unicycive is seeking FDA approval of OLC via the 505(b)(2) regulatory pathway. OLC is protected by a strong global patent portfolio including issued patents on composition of matter with exclusivity until 2031, and with the potential for patent term extension until 2035.

About Hyperphosphatemia
Hyperphosphatemia is a serious medical condition that occurs in nearly all patients with End Stage Renal Disease (ESRD). Annually there are over 450,000 individuals in the U.S. that require medication to control their phosphate levels.1 Uncontrolled hyperphosphatemia is strongly associated with increased death and hospitalization for CKD patients on dialysis. Treatment of hyperphosphatemia is aimed at lowering serum phosphate levels via two means: (1) restricting dietary phosphorus intake; and (2) using, on a daily basis, and with each meal, oral phosphate binding drugs that facilitate fecal elimination of dietary phosphate rather than its absorption from the gastrointestinal tract into the bloodstream.

1Flythe JE. Dialysis-Past, Present, and Future: A Kidney360 Perspectives Series. Kidney360. 2023 May 1;4(5):567-568. doi: 10.34067/KID.0000000000000145.

About Unicycive Therapeutics
Unicycive Therapeutics is a biotechnology company developing novel treatments for kidney diseases. Unicycive’s lead investigational treatment is oxylanthanum carbonate, a novel phosphate binding agent for the treatment of hyperphosphatemia in patients with chronic kidney disease who are on dialysis. Unicycive’s second investigational treatment UNI-494 is intended for the treatment of conditions related to acute kidney injury. It has been granted orphan drug designation (ODD) by the FDA for the prevention of Delayed Graft Function (DGF) in kidney transplant patients and has completed a Phase 1 dose-ranging safety study in healthy volunteers. For more information, please visit Unicycive.com and follow us on LinkedIn and X.

Forward-looking statements
Certain statements in this press release are forward-looking within the meaning of the Private Securities Litigation Reform Act of 1995. These statements may be identified using words such as “anticipate,” “believe,” “forecast,” “estimated” and “intend” or other similar terms or expressions that concern Unicycive’s expectations, strategy, plans or intentions. These forward-looking statements are based on Unicycive’s current expectations and actual results could differ materially. There are several factors that could cause actual events to differ materially from those indicated by such forward-looking statements. These factors include, but are not limited to, clinical trials involve a lengthy and expensive process with an uncertain outcome, and results of earlier studies and trials may not be predictive of future trial results; Unicycive’s clinical trials may be suspended or discontinued due to unexpected side effects or other safety risks that could preclude approval of our product candidates; Unicycive’s dependence on third parties for manufacturing; the possibility that FDA may require inspection of any vendor prior to approval, which could delay or prevent approval of its NDA; the risk that the inspection of the original or new third-party manufacturing vendor may not occur within a timeframe that benefits its regulatory timeline, or may result in adverse findings; risks related to business interruptions, which could seriously harm its financial condition and increase its costs and expenses; dependence on key personnel; substantial competition; uncertainties of patent protection and litigation; dependence upon third parties; market acceptance of its products; and risks related to failure to obtain FDA clearances or approvals and noncompliance with FDA regulations. Actual results may differ materially from those indicated by such forward-looking statements as a result of various important factors, including: the uncertainties related to market conditions and other factors described more fully in the section entitled ‘Risk Factors’ in Unicycive’s Annual Report on Form 10-K for the year ended December 31, 2025, and other periodic reports filed with the Securities and Exchange Commission. Any forward-looking statements contained in this press release speak only as of the date hereof, and Unicycive specifically disclaims any obligation to update any forward-looking statement, whether as a result of new information, future events or otherwise.

Investor Contacts:
Kevin Gardner
LifeSci Advisors
[email protected]

Media Contact:
Unicycive Therapeutics
[email protected] 

SOURCE: Unicycive Therapeutics, Inc.

Release – Cardiff Oncology Receives FDA Orphan Drug Designation for Onvansertib in Chronic Myelomonocytic Leukemia

October 21, 2026

PDF Version

SAN DIEGO, Oct. 21, 2026 (GLOBE NEWSWIRE) — Cardiff Oncology, Inc. (Nasdaq: CRDF), a clinical-stage biotechnology company leveraging PLK1 inhibition to develop novel cancer therapies, today announced that the U.S. Food and Drug Administration (FDA) has granted Orphan Drug Designation to onvansertib for the treatment of patients with chronic myelomonocytic leukemia (CMML).

“CMML remains a difficult-to-treat hematologic malignancy with limited treatment options for patients, and 40-50% of myeloproliferative CMML1 patients harbor RAS-pathway mutations, which are associated with more aggressive disease,” said Mani Mohindru, PhD, President and Chief Executive Officer of Cardiff Oncology. “Receiving Orphan Drug Designation for onvansertib in CMML further validates the therapeutic potential of PLK1 inhibition in cancers with significant unmet need and adds to the growing body of evidence supporting this mechanism across both solid tumors and hematologic malignancies. We believe this designation highlights the broader clinical opportunity for onvansertib as a monotherapy as we continue advancing therapies for patients across cancers where new therapeutic approaches are urgently needed.”

Onvansertib is being evaluated in both company-sponsored and investigator-initiated clinical studies, including a Phase 1 investigator-initiated study in relapsed/refractory CMML. As presented at the 2025 American Society of Hematology (ASH) Annual Meeting, onvansertib was relatively well-tolerated as a monotherapy and demonstrated preliminary efficacy in approximately 40% of myeloproliferative CMML patients in the dose ranging trial. The responses included three patients experiencing clinical benefits (38%), with one each of the following: a 100% platelet response, normalization of White Blood Cells, WBC (baseline WBC count > 50 x 109/L), and spleen response. Additionally, one patient (12.5%) had optimal marrow response with bone marrow blast reduction from 8% to 2% facilitating for allogeneic hematopoietic stem transplant and 3 patients experienced stable disease (38%).

Orphan Drug Designation is granted by the FDA to support the development of therapies intended to treat rare diseases or conditions affecting fewer than 200,000 people in the United States. Benefits of the designation may include tax credits for qualified clinical trials, exemption from certain FDA user fees, and up to seven years of market exclusivity upon regulatory approval. Orphan Drug Designation does not alter the standard regulatory requirements or approval process.

About Onvansertib
Onvansertib is a highly specific, oral PLK1 inhibitor advancing toward a registrational trial in first-line RAS-mutated metastatic colorectal cancer (mCRC). In a randomized Phase 2 trial, onvansertib in combination with FOLFIRI/bevacizumab (first-line standard-of-care) demonstrated dose-dependent improvements in overall response rate and progression-free survival compared to standard-of-care alone, building on findings from a prior Phase 2 trial in second-line RAS-mutated mCRC. Based on these results, the Company has selected the 30 mg dose of onvansertib in combination with FOLFIRI/bevacizumab as the regimen to advance into the planned registrational trial in first-line patients with RAS-mutated mCRC.

Onvansertib is also being evaluated in multiple other cancers through investigator-initiated studies, including metastatic pancreatic ductal adenocarcinoma (mPDAC), small cell lung cancer (SCLC), triple-negative breast cancer (TNBC), and chronic myelomonocytic leukemia (CMML).

About Chronic Myelomonocytic Leukemia
Chronic myelomonocytic leukemia (CMML) is a rare and aggressive hematologic malignancy characterized by features of both myelodysplastic syndromes and myeloproliferative neoplasms. CMML primarily affects older adults and is associated with poor clinical outcomes, including progressive bone marrow failure and risk of transformation to acute myeloid leukemia (AML). Current treatment options remain limited, highlighting the need for novel targeted therapies that can improve outcomes for patients with this disease.

About Cardiff Oncology, Inc.
Cardiff Oncology is a clinical-stage biotechnology company advancing innovative cancer treatments focused on PLK1 inhibition, a validated oncology target with practice-changing potential. Our lead asset, onvansertib, is a highly specific, oral PLK1 inhibitor currently being evaluated for first-line treatment of RAS-mutated metastatic colorectal cancer (mCRC), addressing a large, underserved patient population with high unmet need. Onvansertib is also under investigation in other PLK1-driven cancers through ongoing investigator-initiated trials and has shown robust single agent clinical activity in hard-to-treat tumors. By targeting tumor vulnerabilities, we aim to overcome treatment resistance and deliver improved clinical outcomes for patients.

For more information, please visit https://www.cardiffoncology.com.

Forward-Looking Statements
Certain statements in this press release are forward-looking within the meaning of the Private Securities Litigation Reform Act of 1995. These statements may be identified using words such as “anticipate,” “believe,” “forecast,” “estimated” and “intend” or other similar terms or expressions that concern Cardiff Oncology’s expectations, strategy, plans or intentions. These forward-looking statements are based on Cardiff Oncology’s current expectations and actual results could differ materially. There are several factors that could cause actual events to differ materially from those indicated by such forward-looking statements. These factors include, but are not limited to, clinical trials involve a lengthy and expensive process with an uncertain outcome, and results of earlier studies and trials may not be predictive of future trial results; our clinical trials may be suspended or discontinued due to unexpected side effects or other safety risks that could preclude approval of our product candidate; results of preclinical studies or clinical trials for our product candidate could be unfavorable or delayed; our need for additional financing; risks related to business interruptions, including cyber-attacks on our information technology infrastructure, which could seriously harm our financial condition and increase our costs and expenses; uncertainties of government or third party payer reimbursement; dependence on key personnel; limited experience in marketing and sales; substantial competition; uncertainties of patent protection and litigation; dependence upon third parties; and risks related to failure to obtain FDA clearances or approvals and noncompliance with FDA regulations. There are no guarantees that our product candidate will be utilized or prove to be commercially successful. Additionally, there are no guarantees that future clinical trials will be completed or successful or that our product candidate will receive regulatory approval for any indication or prove to be commercially successful. Investors should read the risk factors set forth in Cardiff Oncology’s Form 10-K for the year ended December 31, 2025, and other periodic reports filed with the Securities and Exchange Commission. While the list of factors presented here is considered representative, no such list should be considered to be a complete statement of all potential risks and uncertainties. Unlisted factors may present significant additional obstacles to the realization of forward-looking statements. Forward-looking statements included herein are made as of the date hereof, and Cardiff Oncology does not undertake any obligation to update publicly such statements to reflect subsequent events or circumstances.

Investor Contact:
Candice Masse
astr partners
[email protected]

Media Contact:
Amy Bonanno
Lyra Strategic Advisory
[email protected]

Cencora to Acquire American Oncology Network for $2.4 Billion in Major Cancer Care Expansion

Cencora (NYSE: COR) has announced an agreement to acquire American Oncology Network (OTCQX: AONC) in a transaction valued at up to $2.4 billion, expanding the pharmaceutical distribution giant’s presence in community-based cancer care. The deal, announced October 21, 2026, will add a physician-led network of more than 350 oncology providers operating across 21 states to Cencora’s growing healthcare services platform.

The acquisition represents another significant step in Cencora’s strategy to expand beyond traditional pharmaceutical distribution and strengthen its relationships with healthcare providers. By integrating American Oncology Network’s clinical infrastructure and practice management capabilities, Cencora aims to support independent cancer specialists while improving patient access to advanced treatments.

Under the agreement, American Oncology Network is valued at $2.3 billion at closing, with an additional $100 million potentially payable through contingent value rights tied to specified conditions. Cencora already owns approximately 4% of the company and has agreed to acquire the remaining equity interests, subject to a potential ownership rollover by existing shareholders.

If eligible shareholders retain a combined 25% stake, Cencora expects to pay approximately $1.7 billion at closing to increase its ownership to 75%. The transaction remains subject to regulatory approvals, shareholder approval, and customary closing conditions.

Founded in 2018, American Oncology Network provides operational and administrative support to independent oncology practices, allowing physicians to concentrate on patient care. Its services include practice management, technology, and access to integrated healthcare resources designed to help smaller cancer treatment centers compete in an increasingly complex healthcare environment.

For Cencora, the acquisition expands its physician-led oncology management services organization into 12 additional states. The company expects the combination to create opportunities to strengthen cancer treatment delivery, expand practice support capabilities, and improve operational efficiency.

The transaction also highlights the growing importance of community oncology as cancer treatments become increasingly specialized and expensive. Independent oncology practices face mounting challenges involving reimbursement, drug procurement, technology investment, and administrative costs. Larger healthcare organizations are responding by building networks that provide centralized resources while allowing physicians to retain control over clinical decisions.

The expansion comes as biotechnology companies continue developing innovative cancer treatments that could eventually reach patients through community oncology practices. Companies such as Greenwich LifeSciences (NASDAQ: GLSI), which is developing an investigational immunotherapy for breast cancer, and MAIA Biotechnology (NYSE American: MAIA), which is advancing a telomere-targeting cancer treatment, illustrate the broader pipeline of emerging oncology therapies. Neither company is involved in the announced transaction.

For investors, the deal underscores how pharmaceutical distribution companies are seeking additional growth opportunities in specialized healthcare services. Expanding into oncology practice management could provide Cencora with deeper relationships across the cancer treatment market while supporting demand for pharmaceutical products and services.

Cencora expects the acquisition to contribute positively to adjusted diluted earnings per share beginning in the second year following completion. The company also raised its fiscal 2026 adjusted earnings outlook to at least $17.90 per share, reflecting strength in its U.S. Healthcare Solutions business.

The acquisition illustrates a broader shift toward integrated cancer care, where pharmaceutical distribution, clinical services, and healthcare technology increasingly operate within connected networks. As cancer treatments continue evolving, companies capable of supporting both drug delivery and community-based medical practices could play a larger role in shaping the future of oncology care.

Lycia Therapeutics Targets $250 Million IPO as Biotech Market Rebounds

Lycia Therapeutics is preparing to raise approximately $250 million through an initial public offering, becoming the latest biotechnology company seeking to capitalize on renewed investor interest in emerging drug developers. The South San Francisco-based company announced plans Tuesday to offer 14.7 million shares priced between $16 and $18 each, potentially valuing the business at approximately $950 million on a fully diluted basis.

The company intends to list on the Nasdaq under the ticker symbol LYCA, adding another early-stage biotechnology developer to a growing pipeline of healthcare IPOs. The offering comes as investors increasingly look beyond established pharmaceutical companies toward emerging businesses developing innovative treatments for diseases with significant unmet medical needs.

Lycia is developing a new class of medicines designed to eliminate disease-causing proteins from the body. Its proprietary LYTAC technology, short for Lysosomal Targeting Chimera, works by directing specific proteins toward the body’s natural cellular disposal system. Unlike traditional drugs that primarily block the activity of harmful proteins, Lycia’s approach aims to remove them altogether.

The technology is based on research associated with Nobel Prize-winning chemist Carolyn Bertozzi, who helped establish the company in 2019. Lycia is initially targeting autoimmune, inflammatory, and allergic diseases, areas where conventional treatments often require ongoing symptom management.

Its lead experimental treatment, LCA-0061, is being developed for food allergies and other allergic conditions. The therapy targets immunoglobulin E, or IgE, an antibody responsible for triggering many allergic reactions. Early Phase 1 results showed a mean maximum IgE reduction of 96% from baseline among treated participants in an initial small cohort, although larger studies will be needed to determine its safety and effectiveness in patients.

Lycia is also developing LCA-0321, an experimental treatment for Graves’ disease, an autoimmune condition affecting the thyroid. The candidate is designed to selectively eliminate disease-causing antibodies rather than broadly suppress the immune system.

Lycia’s focus on targeted therapies for autoimmune and inflammatory conditions also reflects broader innovation across the biotechnology sector. Eledon Pharmaceuticals (NASDAQ: ELDN) is developing tegoprubart, an investigational treatment designed to regulate immune system activity by targeting the CD40 ligand pathway, with applications in organ transplantation. Meanwhile, Gyre Therapeutics (NASDAQ: GYRE) is focused on developing treatments for inflammatory and fibrotic diseases, including liver-related conditions. Although these companies employ different scientific approaches, their development programs highlight growing interest in therapies that address specific biological mechanisms underlying complex diseases.

Proceeds from the IPO are expected to support clinical development of these programs, additional research activities, and general corporate operations. The company has already raised approximately $267 million from private investors, including several prominent life sciences investment firms.

The planned offering follows a series of biotechnology IPOs that suggest improving conditions for companies seeking public-market financing. City Therapeutics and Iambic Therapeutics recently completed offerings that raised approximately $350 million combined, highlighting investor interest in RNA-based medicines and artificial intelligence-driven drug discovery.

While these companies are pursuing different technologies, their emergence reflects a broader shift toward specialized drug development platforms that could generate multiple treatments across different diseases.

For investors, Lycia’s proposed IPO offers exposure to an emerging area of biotechnology known as targeted protein degradation. The technology could eventually expand treatment possibilities for diseases where existing therapies have limited effectiveness, although its clinical and commercial potential remains unproven.

The offering also carries substantial risks. Lycia remains an early-stage clinical developer without an approved commercial product, and its future valuation will depend heavily on clinical trial results, regulatory progress, and its ability to finance continued research.

As more biotechnology companies test public-market demand, Lycia’s offering could provide another indication of whether investor appetite for early-stage drug developers is strengthening heading into the final months of 2026.