Junior Mining Consolidation Isn’t Coming. It’s Already Underway

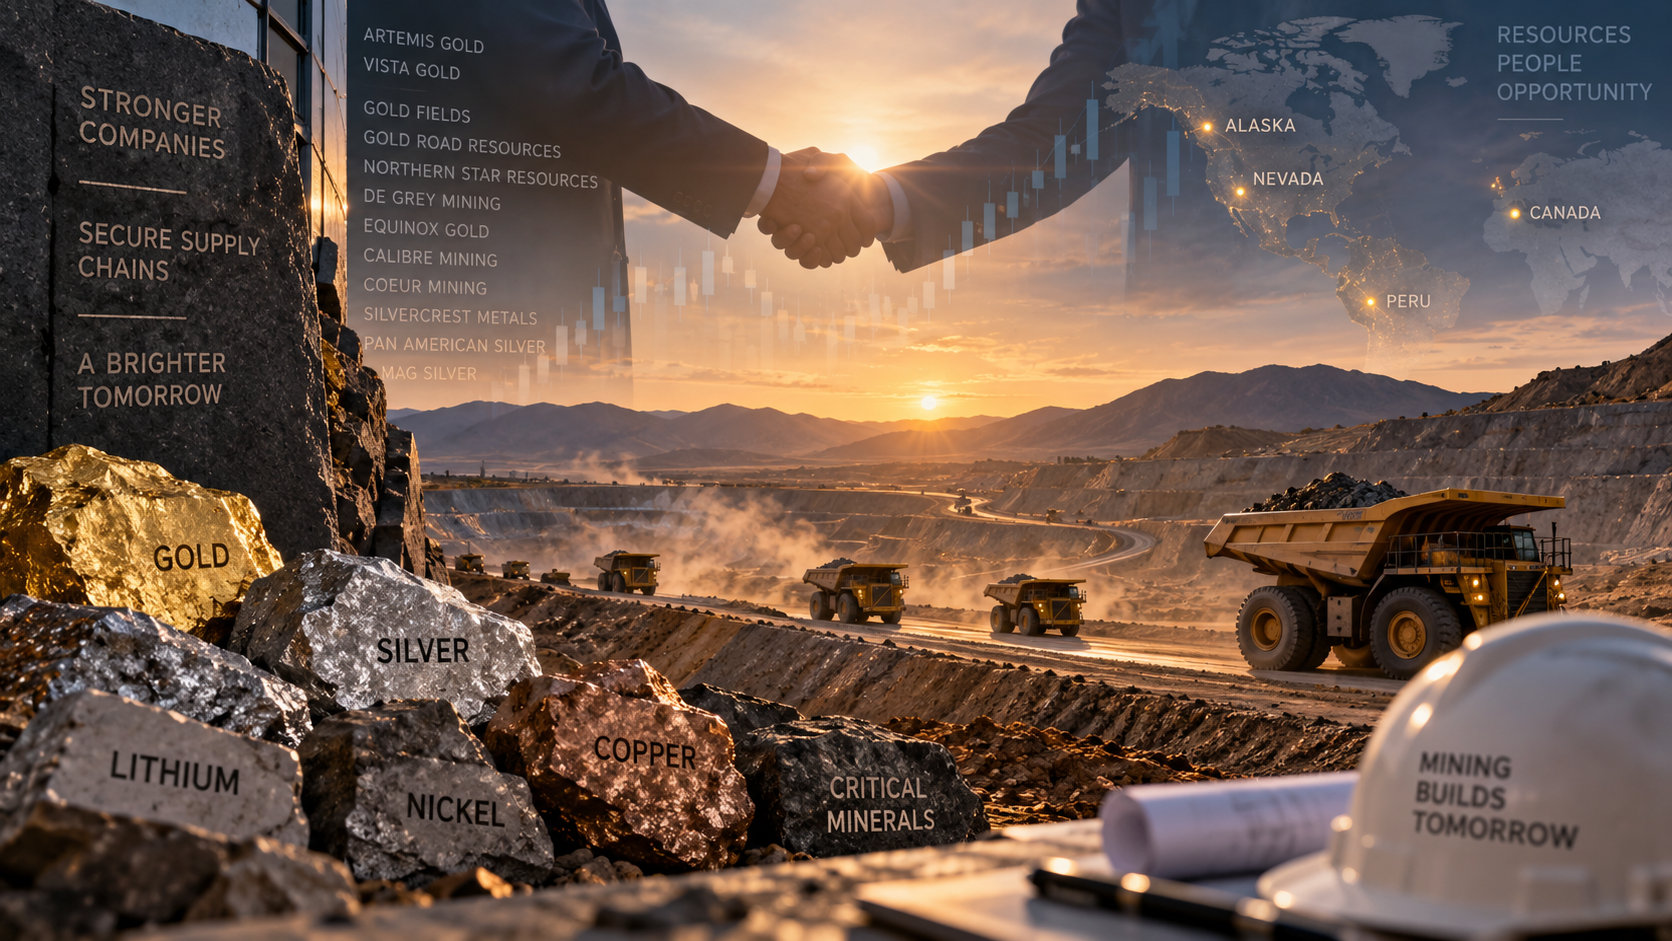
The Artemis Gold acquisition of Vista Gold we covered earlier this week wasn’t an isolated event. It was one data point in what industry data increasingly confirms is a genuine, extended wave of consolidation sweeping through the junior and intermediate mining sector, and the drivers behind it suggest this cycle has real staying power rather than representing a short-term spike.

The numbers tell a clear story. Global mining M&A totaled roughly $93.7 billion in completed deals during 2025, and gold and silver assets alone accounted for more than 77% of total deal volume in early 2026. The list of major transactions reads like a sector-wide roll-up already in progress, Gold Fields acquiring Gold Road Resources for approximately $2.4 billion, Northern Star Resources buying De Grey Mining for roughly $3.3 billion, Equinox Gold’s $2.8 billion purchase of Calibre Mining, Coeur Mining’s $1.7 billion acquisition of SilverCrest Metals, and Pan American Silver’s $2.1 billion takeover of MAG Silver. Mining stocks claimed a record 60% of the spots on this year’s TSX30, the annual ranking of Canada’s top-performing stocks, a genuinely striking signal of where investor capital has been flowing.

Three forces are converging to drive this cycle, and each appears structural rather than cyclical. First, reserve depletion. Major producers spent much of the 2010s underinvesting in exploration during a prolonged bear market, and many are now confronting genuinely thinning production pipelines that organic exploration alone cannot refill quickly enough. Acquiring juniors with already-defined, advanced-stage resources is simply faster than starting from scratch. Second, sustained strength in gold and silver prices has given larger producers the cash flow and equity currency to pursue acquisitions, while depressed valuations among smaller developers following years of underperformance have made those same juniors attractively priced targets. Third, and increasingly important, critical minerals supply security has become an explicit policy priority, with roughly a third of surveyed industry executives specifically expecting consolidation in this category as governments and producers alike race to secure supply chains independent of Chinese dominance, a theme we detailed closely when covering the Greenland security agreement earlier this year.

Industry analysts point to a fairly consistent profile among likely takeover targets, advanced-stage resources located in stable, Tier-1 mining jurisdictions, high-grade or district-scale potential, reasonable valuations following recent market corrections, and experienced management teams with a track record of either developing or successfully exiting projects.

That profile is worth keeping in mind when evaluating smaller companies in this space. Junior developers advancing resources in favorable jurisdictions such as Century Lithium, working a lithium project in Nevada, Kuya Silver, developing precious metals assets in Peru, Tectonic Metals, advancing gold exploration in Alaska, and Power Metallic Mines, exploring nickel and copper deposits in Quebec, all sit in exactly the category this consolidation wave has been targeting, smaller companies with defined, advanced-stage projects in stable jurisdictions that larger, cash-generative producers are actively seeking to acquire.

None of this guarantees any individual company becomes a takeover target, and early-stage mining developers carry substantial execution, financing, and geological risk regardless of broader sector M&A trends. But the structural case for continued consolidation, depleted major-producer pipelines, strong commodity prices, and mounting critical minerals policy pressure, looks considerably more durable than a passing trend.
Take a moment and take a look at more small cap mining companies by taking a look at Noble Capital Markets’ Analyst Mark Reichman’s coverage list.

Oil Just Fell to a Two-Week Low. Saudi Arabia and Iraq Are Quietly Rerouting Around the Strait of Hormuz

Oil prices extended a six-session decline Wednesday, with Brent crude falling to $98.16 a barrel and West Texas Intermediate dropping to $89.01, both settling at roughly two-week lows. Brent closed below $100 a barrel Tuesday for the first time since September 8, a notable reversal after weeks of escalation-driven price spikes that we’ve tracked closely throughout this conflict.

Two forces are driving the decline, and both matter for understanding where oil heads next. The first is diplomatic. President Trump warned Tuesday that the US could take severe action against Iran, while simultaneously saying his envoys had held productive talks with Iranian mediators in New York and describing real momentum toward reaching a deal to end the nearly seven-month war. Markets appear to be choosing to price in the possibility of talks succeeding, even amid continued tough rhetoric on both sides.

The second, more concrete factor is supply, and it’s arguably the more important development. Saudi Arabia restarted its East-West Pipeline to the Red Sea on Tuesday, a route that reroutes roughly 4 million barrels per day, about 4% of global oil supply, around the Strait of Hormuz entirely. The pipeline had been shut since September 11 following drone attacks Saudi Arabia has blamed on Iraqi militia forces. Saudi Arabia is also now offering additional barrels to Asian refiners for pickup outside the strait altogether. Iraq is following a similar playbook, with its oil minister confirming exports have climbed above 3 million barrels per day and stating the country expects to boost shipments routed through Turkey to more than 600,000 barrels per day. Shiptracking data shows Iraqi exports climbing in August from July’s levels, though they still remain below the roughly 3.4 to 3.7 million barrel per day pace seen before the war began.

Adding further downward pressure, industry data released Tuesday showed US crude inventories rose by 1.8 million barrels last week, catching analysts off guard, who had broadly expected a decline.

For investors tracking the small and microcap space, this shift is worth watching closely, and it cuts in the opposite direction from what we detailed when covering diesel’s all-time high and the broader oil surge earlier this month. Consumer-facing companies in transportation, logistics, and hospitality, squeezed hard by the run-up in fuel costs, stand to benefit if this decline holds and extends toward the pump, a group that includes companies like Commercial Vehicle Group, a supplier to the trucking industry, and The ONE Group Hospitality, a restaurant operator directly exposed to consumer discretionary spending. Domestic energy producers, conversely, face renewed margin pressure as prices retreat from the highs that supported their economics all summer, a dynamic worth watching for companies like InPlay Oil and Alliance Resource Partners. Whether this reversal proves durable likely depends on whether the diplomatic momentum Trump described translates into an actual agreement, or whether these alternative supply routes simply prove temporary workarounds to a conflict still very much unresolved.

Century Lithium Corp. (CYDVF) – Advancing Plans for a Stand-Alone Merchant Chlor-Alkali Plant


Wednesday, September 23, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Advancing a merchant chlor-alkali plant. Century Lithium plans to develop a commercial-scale chlor-alkali plant in the Western United States that would produce chlorine, hydrochloric acid, and sodium hydroxide from sodium chloride, water, and electricity. The plant is expected to initially produce at a rate of 300 short tons per day (st/d) of chlorine, with potential expansion to 600 st/d depending on regional demand and the supply needs of Angel Island.

Early offtake interest provides commercial support. Century has signed eight non-binding Memorandums of Understanding (MOUs) that could collectively fully utilize the plant’s initial production, while discussions with additional customers are ongoing. The company is evaluating sites in Nevada and Utah based on power, feedstock, rail access, permitting, and proximity to customers, with final site selection expected following completion of due diligence.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Artemis Gold to Acquire Vista Gold in $427 Million All-Stock Deal for Australia’s Mt Todd Project

Artemis Gold (TSXV: ARTG) has agreed to acquire Vista Gold (NYSE American, TSX: VGZ) in an all-stock transaction valued at approximately $427 million, the companies announced September 20, 2026. Under the deal, Vista Gold shareholders will receive 0.0966 Artemis Gold shares for each share they hold, implying a value of $2.83 per Vista Gold share, a 29% premium to Vista Gold’s 20-day volume-weighted average price and a 25% premium to its last closing price. The transaction is expected to close in January 2027, pending shareholder, court, and regulatory approval, including sign-off from Australia’s Foreign Investment Review Board.

The acquisition gives Artemis Gold full ownership of the Mt Todd gold project in Australia’s Northern Territory, a feasibility-stage development asset hosting 9.1 million ounces of measured and indicated gold resources plus 1.4 million ounces of inferred resources. Mt Todd already holds key permits for a 50,000 tonne per day processing facility, meaning the project arrives with major regulatory hurdles already cleared, a significant factor in its valuation. No cash or new debt is involved in the deal, and existing Artemis Gold shareholders will own approximately 95% of the combined company once it closes.

Importantly, Artemis Gold has been clear that this acquisition does not change its near-term priorities. The company’s Blackwater mine in British Columbia, specifically its Phase 1A and EP2 expansion projects, remains the primary focus and funding priority. Blackwater is expected to produce more than 500,000 ounces of gold annually with industry-leading costs following the completion of EP2 in mid-2028. Construction spending at Mt Todd is not expected to begin until after that Blackwater expansion is fully operational, meaning the two projects are sequenced rather than competing for capital simultaneously. Combined, Artemis Gold has outlined a pathway toward producing more than one million ounces of gold annually once both assets are fully developed.

For Vista Gold shareholders, the deal offers an immediate cash-free premium along with continued exposure to Mt Todd’s development, now backed by a management team with a demonstrated track record building large-scale gold mines, along with the financial strength of a larger, cash-generating producer rather than a single-asset developer.

This transaction reflects a broader pattern in the gold mining sector this year, as sustained strength in gold prices has made permitted, advanced-stage development assets increasingly valuable acquisition targets for producers with the balance sheet to fund construction, a dynamic we detailed when covering gold’s sharp rally earlier this year. For investors tracking the small and microcap mining space, this deal is a useful example of how a single-asset developer with strong technical merit but limited standalone funding capacity can create real shareholder value by combining with a larger, better-capitalized producer, rather than attempting to finance construction independently.

That dynamic extends well beyond this single transaction. Smaller precious metals developers such as Tectonic Metals, Aurania Resources, and Kuya Silver Corporation occupy a similar position in the market today, advancing early or mid-stage gold and precious metals projects with real technical merit but the same standalone funding constraints Vista Gold faced before this deal. As gold prices remain elevated, larger producers continue to have strong incentive to seek out exactly these kinds of development-stage assets, making consolidation activity like the Artemis-Vista transaction a trend worth watching rather than an isolated event.

Why Diesel Just Hit an All-Time High, Even as Oil Prices Cool

US retail diesel prices climbed to $5.85 per gallon Friday, according to AAA data, surpassing the previous all-time high of $5.816 set in June 2022 in the aftermath of Russia’s invasion of Ukraine. Diesel is often called the workhorse fuel of the global economy, powering the trucking fleets and cargo vessels that move goods across the country and around the world, which makes a record this significant a genuine economic pressure point rather than just another data point at the pump.

What makes this move particularly notable is what’s actually driving it. Crude oil prices have eased somewhat off their wartime highs from earlier this year and are up only about 5% since their July 18 low. Diesel, by contrast, has surged roughly 40% over that same stretch. This is not primarily a crude oil story, it is a refined product story, and the distinction matters for understanding just how structurally tight this market has become.

Two separate conflicts are compounding the pressure simultaneously. The ongoing war in Iran has cut off refined product flows from the Persian Gulf, a region we’ve tracked closely throughout this conflict, while Ukrainian strikes on Russian oil refineries have taken capacity offline from one of the world’s other major diesel exporters. Together, the Middle East and Russia accounted for roughly a third of global diesel exports in 2025, and losing meaningful capacity from both simultaneously has left the market with essentially no cushion. US distillate stockpiles are now at their lowest levels on record for this time of year, and East Coast inventories, the region most dependent on diesel and heating oil for winter demand, are at all-time lows just as the heating season approaches.

The obvious question is why domestic refiners can’t simply ramp up production to meet the shortfall. President Trump pressed refining executives on this directly at the White House this week, with midterm elections approaching and fuel affordability an increasingly visible political issue. The honest answer is capacity. Major refiners including Marathon Petroleum and Shell have both indicated in recent earnings reports that their systems are already running near full capacity, leaving little room to meaningfully increase throughput even under direct pressure to do so.

For investors tracking the small and microcap space, this dynamic cuts in two directions that mirror exactly what we’ve seen play out with gasoline prices throughout this conflict. Consumer-facing companies dependent on trucking and freight, along with any business reliant on diesel-powered logistics, face real and mounting cost pressure heading into the fall. Domestic energy producers and refiners with available capacity, meanwhile, continue benefiting from a pricing environment that shows no near-term sign of easing. With winter heating demand still ahead and refined product inventories already at record lows, this is a story likely to remain relevant well beyond the current news cycle.

Kuya Silver (KUYAF) – Thoughts on Recent Drilling at the Umm-Hadid Project


Thursday, September 03, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Encouraging Drill Results. Kuya Silver reported strong drilling results from the Umm-Hadid Project in Saudi Arabia, advancing toward a maiden NI 43-101 mineral resource estimate. Highlights include 26.10 meters grading 77.8 grams of silver per tonne and 9.17 meters grading 137.1 grams of silver per tonne, with both intervals containing exceptionally high-grade silver and gold zones. The new Target 01 drill results are part of an ongoing 10,000-meter drill program to define the continuity, geometry, and grade distribution of the silver-gold vein system and support delivery of a maiden mineral resource estimate and accompanying NI 43-101 technical report. 

Establishing Continuity. The current resource-definition work is focused on Target 01. High-grade mineralization has been encountered across multiple holes and drill sections, supporting the continuity of the broader silver-gold system. Target 01 covers approximately 4.5 kilometers by 2.5 kilometers, with the latest mineralized intervals occurring at relatively shallow depths averaging about 58 meters below surface.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Enbridge Just Bought 500 Miles of Pipeline in the Busiest Oil Field in America

Enbridge announced Wednesday it has agreed to acquire Salt Creek Midstream’s crude oil gathering business for $600 million in cash, extending its footprint deeper into the Permian Basin’s Delaware sub-basin, one of the most productive and competitive crude-producing regions in North America. The deal gives Enbridge full ownership of the Orla and Wink North gathering systems, along with a 50% interest in the Delaware Crossing system, a joint venture it will now share with Chevron. Together, the acquired infrastructure spans roughly 500 miles of crude gathering pipeline, serving more than 20 producers across approximately 320,000 net dedicated acres under long-term agreements averaging about 10 years remaining. The transaction is expected to close later in 2026 and Enbridge says it will be immediately accretive to both distributable cash flow and earnings per share, with the company’s full-year 2026 guidance left unchanged.

While $600 million is a relatively modest transaction for a company with more than $7 billion in annual growth capital capacity, the strategic logic behind it is worth understanding, because it reflects a broader pattern reshaping the entire energy value chain right now, not just Enbridge’s balance sheet. These gathering systems connect directly into several major Permian takeaway pipelines, including Enbridge’s own majority-owned Gray Oak Pipeline, and ultimately feed into the company’s Ingleside Energy Center, the largest crude export terminal in North America. In other words, Enbridge isn’t just buying pipe in the ground, it’s buying the wellhead connections that feed its existing export infrastructure, capturing more of the value chain from the point oil is produced all the way to the point it leaves the country.

That wellhead-to-water strategy matters for a specific reason tied to where Permian production is heading. Output from the Delaware Basin has continued climbing even as producers maintain tighter capital discipline elsewhere, and long-haul export capacity out of the region has been tightening as a result. Owning the gathering systems that feed into export terminals, rather than just the long-haul pipelines themselves, positions Enbridge to capture additional volumes if and when the next wave of Permian takeaway constraints materializes, a bet on the structural trajectory of US shale production rather than a short-term volume play.

For investors tracking the small and microcap energy space, this deal is a useful signal of where consolidation pressure continues to build. Midstream infrastructure, the pipelines, storage, and gathering systems that move crude and natural gas from wellhead to market, has become one of the more actively contested corners of the energy sector this year, as both large integrated players and smaller specialized operators compete for scarce, strategically located assets. Companies like Summit Midstream Corporation, which operates gathering and processing infrastructure across multiple US shale basins, sit in exactly this part of the value chain, and deals of this size and structure offer a useful read on the kind of asset characteristics, long-term contracts, direct export connectivity, and diversified producer bases, that strategic buyers are willing to pay a premium for right now. On the upstream side, smaller independent producers such as InPlay Oil continue benefiting from the same underlying dynamic driving this transaction, sustained demand for Permian and broader shale production that keeps pressure on the infrastructure required to move it to market.

The Enbridge-Salt Creek deal is not a headline-grabbing transaction on its own. But it is a clean, concrete example of the consolidation logic playing out across the entire energy infrastructure landscape, one that smaller midstream and upstream companies operating in the same basins are positioned to benefit from as that trend continues.

Summit Midstream Corp (SMC) – Double E Expansion Reaches Final Investment Decision


Tuesday, September 01, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Double E Compression Expansion Project. Summit Midstream reached a final investment decision (FID) on the Double E Pipeline mainline compression expansion following a successful open season that secured 550 million cubic feet per day (MMcf/d) of new long-term take-or-pay commitments. The project will add approximately 900 MMcf/d of forward haul capacity to the Waha Hub through a new bi-directional compressor station, plant connections, and related infrastructure. The expansion is expected to cost approximately $100 million net to Summit’s 70% interest and enter service in the fourth quarter of 2028, subject to regulatory approvals.

Commercial Momentum. A new 200 MMcf/d agreement with an investment-grade shipper brings total contracted firm capacity on Double E to approximately 2.2 billion cubic feet per day (Bcf/d), supported primarily by investment-grade customers. Summit is pursuing contracts for the remaining 450 MMcf/d of incremental expansion capacity and expects strong Delaware Basin production growth to support further commitments. If the project becomes fully subscribed, management expects Permian Segment Adjusted EBITDA to increase from approximately $37 million in 2026 to more than $100 million by 2030.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Aurania Resources (AUIAF) – Near-Term Catalysts and Outlook


Tuesday, September 01, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Strategic Shift to Europe. Aurania has repositioned its exploration strategy from Ecuador toward Europe, where it is advancing gold and critical metals opportunities in Iceland, Italy, and France. The company’s Lost Cities project in Ecuador remains geologically prospective, but exploration is suspended because of uncertainty surrounding Ecuador’s Mining Service Fee (TASA) and unpaid concession fees. Meanwhile, Aurania may earn up to a 70% interest in Iceland’s Thor’s Valley gold project, is evaluating nickel and cobalt recovery from the Balangero tailings project in Italy, and is advancing three exploration permits in Brittany, France.

Near-Term Catalysts. The most immediate catalyst is drilling at Thor’s Valley, where Aurania has commenced an initial six-hole, 770-meter program to verify historically high-grade gold mineralization and test extensions of the system. Additional catalysts include permitting for sonic drilling and bulk sampling at Balangero, advancement of exploration targets in France, and resolution of obligations associated with Ecuador’s Mining Service Fee. Confirmation that a TASA exemption applies retroactively to 2025 could materially reduce Aurania’s liabilities and influence whether it retains or restructures its Lost Cities concession portfolio.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Oil Jumps Above $90 After the First US-Iran Exchange of Fire in a Month

Oil prices surged Monday after the United States and Iran exchanged direct military fire for the first time in roughly a month, ending a relatively quiet stretch in a war now entering its seventh month. Brent crude futures climbed to an intraday high above $91 a barrel, gaining roughly 3% to cross $90 for the first time in about a week, while US benchmark WTI crude gained roughly 4% to trade above $86.

The exchange began when US forces struck Iranian targets on Larak Island, a small landmass inside the Strait of Hormuz that functions as a key monitoring point for Iran’s Revolutionary Guard Corps. US Central Command said the strikes targeted launchers it believed were being prepared to fire rockets carrying sea mines into the strait. Iran retaliated with drone strikes on sites inside Jordan and the United Arab Emirates and said it had seized a bulk carrier vessel near the port of Bandar Abbas. Tehran also claimed an oil tanker struck a mine while attempting an unauthorized transit through the strait, though US Central Command stated it had already cleared that section of the waterway.

Even with this renewed exchange, the physical oil market tells a more nuanced story than headline crude prices alone. Goldman Sachs estimates Persian Gulf crude exports have recovered to roughly two-thirds of pre-war levels, near 15 million barrels per day. The more persistent constraint now sits downstream, in refined products like gasoline and diesel, where capacity has been squeezed by Iranian strikes on regional refineries and, separately, Ukrainian strikes on Russian refining infrastructure. Goldman’s commodities strategists now expect global refined product output to decline by roughly 7 million barrels per day, a constraint that keeps pressure on fuel prices even as crude export volumes have partially normalized.

The policy response is shifting as well. Treasury Secretary Scott Bessent has threatened severe economic consequences for any nation found doing business with Tehran, signaling a pivot from direct military engagement toward economic pressure as the primary tool going forward. Last week, Treasury sanctioned the Emirati branches of a major Egyptian bank it accused of funneling roughly $1.8 billion to the Iranian regime. Critics of that approach note such measures carry limited practical impact unless they eventually target China, which continues purchasing an estimated 90% of Iran’s crude exports. A senior UAE foreign policy adviser put the broader dilemma plainly this week, noting that a state of neither war nor peace cannot be a sustainable solution.

For investors, the national average price of gasoline sitting at $4.08 a gallon despite recent modest declines is worth watching closely, both for its direct effect on consumer-facing small caps already navigating tight household budgets, a dynamic we detailed in earlier coverage of the ceasefire’s collapse, and for its political relevance heading into US midterm elections roughly two months away, where fuel affordability is likely to factor into races that will determine control of Congress. With refined product capacity constrained independent of crude export volumes, sustained pressure on pump prices may persist even if this latest exchange does not escalate further.

Tectonic Metals Inc. (TETOF) – Black Creek Emerges as a Second Gold Center


Wednesday, August 26, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Flat is advancing rapidly. Tectonic is executing a five-rig, 40,000-meter drilling program at its flagship Flat Gold Project, with the primary objective of supporting a maiden NI 43-101 mineral resource estimate at Chicken Mountain in early 2027. The program is also targeting higher-grade mineralization and testing additional district-scale targets. The Chicken Mountain–Alpha Bowl system has already been traced for approximately 3.3 kilometers.

Black Creek is emerging as a second gold center. Tectonic released assay results from three holes drilled at the Black Creek target, including two reverse circulation and one diamond drill hole. Hole CMR26-152 returned 5.09 g/t gold over 21.34 meters, including 17.34 g/t over 6.10 meters. Hole CMR26-153 intersected a broader interval of 1.89 g/t over 57.91 meters, including 2.75 g/t over 38.10 meters, with higher-grade intervals of 6.31 g/t over 7.62 meters and 3.89 g/t over 6.10 meters. Diamond hole CMD26-041 returned 3.26 g/t over 5.06 meters and a deeper interval grading 16.73 g/t over 2.22 meters, including 29.91 g/t over 1.22 meters. Importantly, both RC holes ended in mineralization, indicating that the system remains open thus providing clear targets for deeper follow-up drilling.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Resolution Minerals Ltd (RLMLF) – Initial Assays Return Significant Gold Mineralization


Tuesday, August 25, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Golden Gate South Discovery. Resolution Minerals confirmed a significant near-surface gold discovery at Golden Gate South within its 100%-owned Horse Heaven Antimony-Tungsten-Gold-Silver Project in Idaho. All three initial 2026 diamond holes intersected broad gold mineralization, extending the known mineralized system at least 2,000 meters south from Golden Gate North. The results, combined with gold-in-soil anomalies between the two areas, strengthen the potential that Golden Gate North and South are part of a much larger mineralized system along the Golden Gate Fault Zone.

Broad Gold Intercepts. The most significant hole, HH-GG26-003C, returned 305.7 meters grading 0.64 g/t gold from surface to the end of the hole, including several higher-grade zones of up to 17.25 meters at 1.19 g/t gold. The other two holes also encountered broad near-surface mineralization, including 87.87 meters at 0.52 g/t and 49.5 meters at 0.58 g/t gold. Collectively, the results are important because they demonstrate substantial widths of pervasive gold mineralization rather than isolated narrow intercepts, although additional drilling is required to establish true widths, continuity, and ultimately the potential size of the system.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

First Phosphate Corp. (PHOS) – Definitive Mineral Resource Supports Transition to Feasibility


Tuesday, August 25, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

A stronger resource supports the transition to feasibility. First Phosphate’s definitive NI 43-101 report confirms approximately 204.7 million tonnes of measured and indicated resources grading roughly 6.05% phosphorus pentoxide (P2O5), including a 378% increase in indicated resources. Strong geological continuity, favorable metallurgy, and additional expansion potential at depth provide a stronger foundation for the Begin-Lamarche feasibility study.

The focus is shifting toward project development. With resource drilling mostly completed, First Phosphate is targeting completion of the feasibility study around January or February 2027, followed by permitting, financing, and a potential final investment decision. Development risk is further reduced by definitive offtake agreements, Canadian government funding, and potential international financing support.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.