Release – NeuroSense Unveils Accelerated, Capital-Efficient Strategy to Advance PrimeC Toward Potential Approval in ALS

Research News and Market Data on NRSN

Three-part program – AI-enabled characterization of PrimeC’s formulation advantage, an active-comparator trial against edaravone, and a streamlined pivotal pathway – is designed to strengthen PrimeC’s differentiation, shorten the time to potential commercialization, and significantly reduce overall development costs, complemented by a parallel regulatory pathway in Canada.

CAMBRIDGE, Mass., Aug. 31, 2026 /PRNewswire/ — NeuroSense Therapeutics Ltd. (NASDAQ: NRSN) (“NeuroSense”), a late-stage clinical biotechnology company focused on developing disease-modifying treatments for neurodegenerative diseases, today announced a redesigned development plan for PrimeC in amyotrophic lateral sclerosis, structured to reach a potential path for regulatory submission and approval faster and at materially lower cost than the Company’s previously planned development path.

Continue Reading

ALS drug development has been shaped by a single model: large, long, expensive confirmatory trials that few companies can fund and that people with ALS wait years to read out. NeuroSense’s plan replaces that single large commitment with three shorter, focused studies, each designed to answer a specific question that regulators, physicians, partners or payers routinely ask.

The redesigned strategy builds on the totality of evidence generated in NeuroSense’s Phase 2b PARADIGM study, including clinically meaningful effects on functional decline, statistically significant modulation of extracellular vesicle-associated TDP-43, consistent findings across multiple disease-related biomarkers, and encouraging long-term survival results. NeuroSense has already received FDA clearance to initiate its pivotal Phase 3 PARAGON trial. Together, these clinical, biomarker and regulatory advances provide the foundation for a more focused and capital-efficient development pathway.

AI-enabled characterization of PrimeC’s formulation advantage. PrimeC is an extended-release fixed-dose combination engineered to synchronize the pharmacokinetic profiles of its two active components. In a completed clinical pharmacokinetic study, PrimeC produced a synchronized exposure profile that was not reproduced when the individual components were administered together. NeuroSense is now applying AI-enabled modeling to these clinical data to quantify the magnitude of that difference, assess its consistency across individual patients and further characterize the contribution of PrimeC’s proprietary formulation. This work builds upon PrimeC’s established intellectual property position and is intended to support potential additional patent protection while providing clinicians, payers and prospective partners with an objective basis for distinguishing PrimeC from any co-administration of its individual components.

A direct comparative study against edaravone. NeuroSense plans to conduct an active-comparator clinical study designed to evaluate PrimeC directly against edaravone, an established ALS therapy. Head-to-head trials are not common in ALS, and differentiated results could provide people with ALS, clinicians, payers and prospective partners with compelling evidence of PrimeC’s relative clinical value and commercial potential.

A streamlined pivotal pathway. NeuroSense is evaluating an optimized design for its planned Phase 3 study (PARAGON) that would be substantially smaller and shorter in duration than previously planned, enriched for participants earlier in their disease course and intended to support an earlier regulatory submission. Any such pivotal design remains subject to alignment with FDA. The Company plans to discuss with the FDA whether its existing data may support full approval or, alternatively, an Accelerated Approval pathway, with an additional study conducted post-approval as required.

A parallel path to earlier access in Canada. NeuroSense has completed the pre-New Drug Submission process with Health Canada and is preparing a New Drug Submission for PrimeC, which the Company continues to target for December 2026. If accepted and ultimately approved, this pathway has the potential to make PrimeC available to Canadian patients on the strength of data already generated.

“One of the hardest constraints in ALS is not scientific – it is that the standard development path takes longer than patients have,” said Alon Ben-Noon, Co-Founder and Chief Executive Officer of NeuroSense. “We have asked a straightforward question: what is the shortest reasonable route from the data we already hold to a therapy people can actually receive? This plan is our answer. It is faster, it costs less, and it produces a stronger package – pharmacology, comparative clinical context, and a pivotal dataset – than the single-trial approach would have.”

About NeuroSense

NeuroSense Therapeutics is a late-clinical stage biotechnology company developing novel treatments for severe neurodegenerative diseases, including amyotrophic lateral sclerosis (ALS) and Alzheimer’s disease. The Company’s lead product candidate, PrimeC, is a novel oral therapy designed to target multiple key biological pathways underlying disease progression, including neuroinflammation, oxidative stress and dysregulated iron metabolism.

NeuroSense has recently completed analysis of long-term follow-up data from its Phase 2b PARADIGM study in ALS, with results published in JAMA Neurology showing slowing of functional decline relative to placebo. The Company also reported changes across multiple biomarkers associated with ALS, including microRNAs, consistent with PrimeC’s multi-target mechanism of action.

NeuroSense has received clearance from the U.S. Food and Drug Administration (FDA) to initiate its pivotal Phase 3 clinical trial (PARAGON) in ALS, to be conducted primarily in the United States. As described above, the Company is working with FDA on an optimized design for the study.

For additional information, we invite you to visit our website and follow us on LinkedIn, YouTube and X. Information that may be important to investors may be routinely posted on our website and these social media channels.

About PrimeC

PrimeC, NeuroSense’s lead drug candidate, is a novel extended-release oral formulation composed of a unique fixed-dose combination of two FDA-approved drugs: ciprofloxacin and celecoxib. PrimeC is designed to target several key mechanisms that contribute to neuron degeneration, inflammation, iron accumulation and impaired ribonucleic acid (“RNA”) regulation, with the potential to inhibit disease progression.

About ALS

Amyotrophic lateral sclerosis (“ALS”) is an incurable neurodegenerative disease that causes complete paralysis and death within 3 years from diagnosis. Every year, more than 5,000 people are diagnosed with ALS in the U.S. alone, with an annual disease burden of $1 billion. The number of people living with ALS is expected to grow by 24% by 2040 in the U.S. and EU.

Forward-Looking Statements

This press release contains “forward-looking statements” that are subject to substantial risks and uncertainties. All statements, other than statements of historical fact, contained in this press release are forward-looking statements. Forward-looking statements contained in this press release may be identified by the use of words such as “anticipate,” “believe,” “contemplate,” “could,” “estimate,” “expect,” “intend,” “seek,” “may,” “might,” “plan,” “potential,” “predict,” “project,” “target,” “aim,” “should,” “will,” “would,” or the negative of these words or other similar expressions, although not all forward-looking statements contain these words. Forward-looking statements are based on NeuroSense Therapeutics’ current expectations and are subject to inherent uncertainties, risks and assumptions that are difficult to predict and include statements regarding the potential benefits of the Company’s redesigned development strategy for PrimeC. Further, certain forward-looking statements, including statements regarding the potential regulatory pathways for PrimeC, are based on assumptions as to future events that may not prove to be accurate. The future events and trends may not occur and actual results could differ materially and adversely from those anticipated or implied in the forward-looking statements. These risks include the potential for delay in the timing of the Phase 3 clinical trial (PARAGON) in ALS; potential delay in the Canadian New Drug Submission; the risk that the Company will not be able to obtain financing on acceptable terms, or at all; the risk that the Company will not regain and maintain compliance with the Nasdaq listing requirements; the risk that the strategic opportunities described will not materialize or result in the anticipated benefits to the Company; uncertainty regarding outcomes and the timing of current and future clinical trials; the risk that PrimeC will not advance towards later-stage development; timing for reporting data, including from the study of PrimeC in Alzheimer’s disease; that the study will not be successful; and other risks and uncertainties set forth in NeuroSense’s filings with the Securities and Exchange Commission (SEC). You should not rely on these statements as representing our views in the future. More information about the risks and uncertainties affecting NeuroSense is contained under the heading “Risk Factors” in the Annual Report on Form 20-F filed with the Securities and Exchange Commission on March 31, 2026 and NeuroSense’s subsequent filings with the SEC. Forward-looking statements contained in this announcement are made as of this date, and NeuroSense undertakes no duty to update such information except as required under applicable law.

For further information: Email: [email protected] | Tel: +972 (0)9 799 6183

Logo – https://mma.prnewswire.com/media/1707291/NeuroSense_Therapeutics_Logo.jpg

SOURCE NeuroSense

For further information: Investor Relations: Or Eisenberg, Email: [email protected], Tel: +1315517554134
Release – Cadrenal Therapeutics Announces Positive Outcome from FDA Type D Meeting for Phase 3 Registration Study of CAD-1005 in Heparin-Induced Thrombocytopenia

Primary Logo

Research News and Market Data on CVKD

FDA Alignment on Primary Endpoint and Path Forward for Phase 3 Registration Study

CAD-1005 Targets a Significant Unmet Need, with Approximately 50,000 Confirmed Acute HIT Diagnoses Annually in the U.S. and an Estimated $2 Billion in Peak Annual Revenue Opportunity

PONTE VEDRA, Fla., Aug. 31, 2026 (GLOBE NEWSWIRE) — Cadrenal Therapeutics, Inc. (Nasdaq: CVKD), a late-stage biopharmaceutical company advancing specialized therapies for critical care cardiology and orphan cardiovascular conditions, today announced positive feedback from a Type D Meeting with the U.S. Food and Drug Administration (FDA) held on July 28, 2026. During the meeting, Cadrenal and the FDA aligned on key aspects of the protocol and Statistical Analysis Plan (SAP) for the Phase 3 registrational study of CAD-1005, the Company’s first-in-class 12-lipoxygenase (12-LOX) inhibitor in development to treat heparin-induced thrombocytopenia (HIT). HIT is a potentially life-threatening immune reaction to heparin, a widely used blood thinner, and can lead to dangerous blood clots.

In the U.S., heparin-induced thrombocytopenia (HIT) is a high-stakes emergency that affects approximately 50,000 patients with acute HIT each year. Current therapeutic options rely on standard anticoagulants to reduce thrombotic risk; however, they do not target the underlying immune mechanisms that drive this destructive cardiovascular cascade. CAD-1005 is a novel 12-LOX inhibitor designed to halt the core immune signaling pathway that drives platelet activation and vascular thrombosis. Developed as an essential add-on to standard anticoagulation, CAD-1005 targets a critical population and is projected to generate $2 billion in peak annual revenue.

During the Type D meeting, the FDA agreed on an optimized definition of worsening HIT for the primary endpoint, based on progression of thrombotic events through Day 14 of treatment or hospital discharge. To ensure high-quality, reliable endpoint evaluation across clinical sites, the worsening component of the primary endpoint will also include extension of an existing thrombus into a new vascular segment or bed, avoiding potential site-to-site variability from manual size measurements. The updated composite primary endpoint will measure the proportion of Serotonin Release Assay-positive (SRA+) participants with adjudicated new or worsening composite thromboembolic events (CTEs) through Day 14 or hospital discharge. Additionally, the FDA agreed to use placebo control in the Phase 3 trial, with standard anticoagulation therapeutics for both the CAD-1005 and placebo control arms.

“We are very pleased with the collaborative, constructive feedback from the FDA during this Type D meeting,” said Quang X. Pham, Chief Executive Officer of Cadrenal Therapeutics. “Securing agreement on the primary endpoint definition and the blinding protocols for our saline control provides greater clarity on the regulatory path forward for CAD-1005. We have incorporated the Agency’s recommendations into our Phase 3 protocol and Statistical Analysis Plan, strengthening the design of a registration study intended to evaluate whether CAD-1005 can reduce dangerous thrombotic events that persist in patients with HIT despite current anticoagulant therapies.”

The Phase 3 trial design will also assess bleeding as a major safety endpoint using standard International Society on Thrombosis and Haemostasis (ISTH) criteria. All safety analyses will be conducted in the safety population of patients who receive at least one dose of the study drug.

About Cadrenal Therapeutics, Inc.

Cadrenal Therapeutics, Inc. is a late-stage biopharmaceutical company advancing specialized therapies for critical care cardiology and orphan cardiovascular conditions. The Company’s pipeline includes CAD-1005, tecarfarin, and frunexian. CAD-1005 is a novel investigational therapeutic in development for the treatment of heparin-induced thrombocytopenia (HIT) and Cardiac Surgery-Associated Acute Kidney Injury (CSA-AKI). CAD-1005 is designed to selectively inhibit 12-lipoxygenase (12-LOX), an enzyme central to platelet immune activation and thrombo-inflammatory signaling in HIT. CAD-1005 is intended to be used alongside existing standards of care and is being developed to address the underlying biological mechanisms that drive disease progression. CAD-1005 has an Orphan Drug Designation (“ODD”) from the U.S. Food and Drug Administration (“FDA”) for prophylaxis of thrombosis in patients with HIT, FDA Fast Track designation for the treatment and prevention of HIT, and an orphan designation from the European Medicines Agency for the treatment of platelet-activating factor 4 disorders. Second-generation 12-LOX oral therapeutics (CAD-2000) are also in development for chronic indications.

The Company’s broader pipeline includes tecarfarin, a late-stage oral vitamin K antagonist designed to prevent heart attacks, strokes, and deaths from blood clots in patients requiring chronic anticoagulation, including those with end-stage kidney disease and atrial fibrillation, those with left ventricular assist devices, and potentially those with Kawasaki disease (KD), an acute, self-limited, febrile illness that primarily affects children under 5 years old and is the leading cause of acquired heart disease in developed countries. The Company recently submitted a request to the FDA for Rare Pediatric Disease Designation (RPDD) for tecarfarin for “Prevention of the Formation of Life-Threatening Blood Clots Inside Coronary Artery Aneurysms in Children with Kawasaki Disease”. Tecarfarin has also received Orphan Drug and Fast Track designations from the FDA.

For more information, visit https://www.cadrenal.com/ and connect with the Company on LinkedIn.

Safe Harbor

Any statements in this press release about future expectations, plans, and prospects, as well as any other statements regarding matters that are not historical facts, may constitute “forward-looking statements.” The words “anticipate,” “believe,” “continue,” “could,” “estimate,” “expect,” “intend,” “may,” “plan,” “potentially,” “predict,” “project,” “should,” “target,” “will,” “would” and similar expressions are intended to identify forward-looking statements, although not all forward-looking statements contain these identifying words. These statements include, without limitation, statements regarding the planned Phase 3 registration study of CAD-1005, the development of CAD-1005 to treat HIT; CAD-1005 potentially halting the core immune signaling pathway that drives platelet activation and vascular thrombosis; CAD-1005 being an essential add-on to standard anticoagulation; CAD-1005 unlocking a projected $2 billion in peak annual revenue; the worsening component of the primary endpoint of optimized definition of worsening HIT assessing extension of an existing thrombus into a new vascular segment or bed, avoiding potential site-to-site variability from manual size measurements; the updated composite primary endpoint measuring the proportion of Serotonin Release Assay-positive (SRA+) participants with adjudicated new or worsening composite thromboembolic events (CTEs) through Day 14 or hospital discharge; the regulatory path forward for CAD-1005; the registration study evaluating whether CAD-1005 can reduce dangerous thrombotic events that continue to occur in patients with HIT despite current anticoagulant therapies; the Phase 3 trial design evaluating bleeding as a major safety endpoint using standard International Society on Thrombosis and Haemostasis (ISTH) criteria; all safety analyses in the Phase 3 trial being conducted in the true safety population of patients who receive at least one dose of the study drug; the Company advancing specialized therapies for critical care cardiology and orphan cardiovascular conditions; CAD-1005 being successfully developed to treat HIT and CSA-AKI; CAD-1005 selectively inhibiting 12-LOX, an enzyme central to platelet immune activation and thrombo-inflammatory signaling in HIT; CAD-1005 being intended to be used alongside existing standards of care and being developed to address the underlying biological mechanisms that drive disease progression; second-generation 12-LOX oral therapeutics (CAD-2000) being developed for chronic indications; tecarfarin, a late-stage oral vitamin K antagonist, potentially preventing heart attacks, strokes, and deaths from blood clots in patients requiring chronic anticoagulation, including those with end-stage kidney disease and atrial fibrillation, those with left ventricular assist devices, and potentially those with Kawasaki disease; and the FDA’s ultimate decision regarding the Company’s request for RPDD for tecarfarin for the prevention of life-threatening blood clots inside coronary artery aneurysms in children with Kawasaki Disease; Actual results may differ materially from those indicated by such forward-looking statements as a result of various important factors, including the Company’s ability to advance its programs to clinical trial readiness; the Company’s ability to enter into development, licensing, and commercialization transactions for CAD-1005, frunexian, and tecarfarin; the Company’s ability to secure nondilutive grants to advance its programs; and the other risk factors described in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025, and the Company’s subsequent filings with the Securities and Exchange Commission, including subsequent periodic reports on Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. Any forward-looking statements contained in this press release speak only as of the date hereof and, except as required by federal securities laws, the Company specifically disclaims any obligation to update any forward-looking statement, whether as a result of new information, future events, or otherwise.

For more information, please contact:

Lytham Partners, LLC

Robert Blum, Managing Partner

602-889-9700

[email protected]

Release – Kratos Receives $35 Million National Security Related Military-Grade Hardware Production Program Award

Primary Logo

Research News and Market Data on KTOS

August 31, 2026

PDF Version

SAN DIEGO, Aug. 31, 2026 (GLOBE NEWSWIRE) — Kratos Defense & Security Solutions, Inc. (Nasdaq: KTOS), a technology company in defense, national security, and global markets, today announced that it recently received an approximate $35 million National Security-related military-grade hardware production program award. It is expected that the hardware and related systems being produced and supported under this recent award will be in direct support of the warfighter in the field.

Kratos is an industry leader in the engineering, design, development and production of military grade hardware and systems in support of the United States and its Allies’ mission critical national security priorities. Kratos is currently in large-scale production in support of multiple national security related systems and programs of record, including in the areas of hypersonics, counter-unmanned aerial systems, air defense, missiles, radars, and high-powered directed energy and other initiatives.

Tom Mills, President of Kratos C5ISR, said, “Kratos is a recognized industry leader in the engineering and large-scale production of military grade hardware in support of certain of the United States’ and its allies’ most important National Security programs and initiatives. If a customer wants its product or system engineered correctly up front, for successful, on-schedule, on-budget production, we believe that we are the preferred, go to partner.”

Eric DeMarco, Kratos’ President and CEO, said, “Kratos’ C5ISR Business is a crown jewel of Kratos and a national asset for our country. Kratos has the workforce, infrastructure, technical capability and past performance qualifications to successfully complete the mission and engineer and build mil-spec hardware and weapon systems correctly the first time for our partners and customers.”

Work under this program award will be performed at a secure Kratos facility. Due to customer, National Security related and other considerations, no additional information will be provided related to this contract award.

About Kratos Defense & Security Solutions
Kratos Defense & Security Solutions, Inc. (Nasdaq: KTOS) is a technology, products, system and software company addressing the defense, national security, and global markets. Kratos makes true internally funded research, development, capital and other investments, to rapidly develop, produce and field solutions that address our customers’ mission critical needs and requirements. At Kratos, affordability is a technology, and we seek to utilize proven, leading-edge approaches and technology, not unproven bleeding-edge approaches, with Kratos’ approach designed to reduce cost, schedule and risk, enabling us to be first to market with cost effective solutions. We believe that Kratos is known as an innovative disruptive change agent in the industry, a company that is an expert in designing products and systems up front for successful rapid, large quantity, low-cost future manufacturing which is a value-add competitive differentiator for our large traditional prime system integrator partners and also to our government and commercial customers. Kratos’ primary business areas include virtualized ground systems for satellites and space vehicles; jet-powered unmanned aerial drone systems; advanced vehicles and rocket systems; propulsion systems for drones, missiles, loitering munitions, supersonic systems, spacecraft, and launch systems; C5ISR and microwave electronic products for missile, radar, missile defense, space, satellite, counter-UAS, directed energy, communication, and other systems; and virtual and augmented reality training systems for the warfighter. For more information, visit www.KratosDefense.com and follow Kratos on LinkedIn and X.

Notice Regarding Forward-Looking Statements
Certain statements in this press release may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are made on the basis of the current beliefs, expectations and assumptions of the management of Kratos and are subject to significant risks and uncertainty. Investors are cautioned not to place undue reliance on any such forward-looking statements. All such forward-looking statements speak only as of the date they are made, and Kratos undertakes no obligation to update or revise these statements, whether as a result of new information, future events or otherwise. Although Kratos believes that the expectations reflected in these forward-looking statements are reasonable, these statements involve many risks and uncertainties that may cause actual results to differ materially from what may be expressed or implied in these forward-looking statements. For a further discussion of risks and uncertainties that could cause actual results to differ from those expressed in these forward-looking statements, as well as risks relating to the business of Kratos in general, see the risk disclosures in the Annual Report on Form 10-K of Kratos for the year ended December 29, 2025, and in subsequent reports on Forms 10-Q and 8-K and other filings made with the SEC by Kratos.

Press Contact: 
Claire Cantrell
[email protected]

Investor Relations: 
877-934-4687
[email protected]

Release – Summit Midstream Corporation Announces Final Investment Decision on Double E Pipeline Mainline Compression Expansion

Summit Midstream Partners Logo. (PRNewsFoto/Summit Midstream Partners)

Research News and Market Data on SMC

PDF Version

HOUSTON, Aug. 31, 2026 /PRNewswire/ — Summit Midstream Corporation (NYSE: SMC) (“Summit”, “SMC” or the “Company”) announced today that Double E Pipeline, LLC (“Double E”) has concluded a successful open season and reached a final investment decision on its previously announced mainline compression expansion project, supported by a new long-term firm transportation agreement with an investment-grade shipper.

Highlights

  • Reached a final investment decision on the mainline compression expansion, with an expected in-service date in the fourth quarter of 2028
  • Executed a new long-term take-or-pay firm transportation agreement with an investment-grade shipper for 200 MMcf/d, bringing total contracted firm capacity on Double E to approximately 2.2 Bcf/d
  • Converted the $50 million uncommitted accordion at Summit Permian Transmission to committed, bringing total committed financing capacity to $100 million and fully funding Summit’s expected Double E capital contributions
  • Robust future growth opportunities associated with data center developments in Texas and New Mexico and connectivity with additional egress pipelines

Management Commentary

Heath Deneke, President, Chief Executive Officer and Chairman, commented, “Today’s announcement is a significant milestone for Summit and Double E and further demonstrates the importance of the pipeline to producers and processors in the Delaware Basin. Double E provides reliable gas transmission service with access to multiple downstream markets, and we continue to expand that connectivity as the basin grows. The strong shipper interest we have seen through the open season reinforces the value of that position and our confidence in the long-term growth opportunity for Double E.

“The open season resulted in 550 MMcf/d of new long-term take-or-pay commitments which underpinned the final investment decision to move forward with the compression expansion and we continue to advance discussions with multiple shippers to subscribe the remaining 450 MMcf/d of incremental forward haul capacity. With these newly signed contracts, we expect to invest approximately $100 million, net to Summit’s 70% interest, to install the mainline compression station, incremental plant connections and related infrastructure, all of which will be funded entirely with the previously announced term loan at Summit Permian Transmission and the now-committed $50 million accordion. We continue to see tremendous production growth surrounding our Delaware Basin operating footprint and fully expect to enter into long-term contracts for the remaining expansion capacity in the coming months. When the project is fully subscribed, we expect our Permian Segment Adjusted EBITDA to grow from approximately $37 million in 2026 to over $100 million by 2030.”

“As we look into the future for the Double E Pipeline beyond filling the mainline compression expansion capacity to Waha, we are very excited about a new phase of demand-pull growth opportunities that are emerging from data center development in Texas and New Mexico as well as additional egress pipelines that are hungry for enhanced access to Permian gas supply. With our connectivity to numerous gas processing facilities in the basin and the Waha Hub, we are incredibly well positioned to attract those markets to the Double E Pipeline and leverage the bi-directional capability of the system to nearly double the outlook for the business in the years ahead.”

Double E Mainline Compression Expansion

The expansion project consists of the installation of a bi-directional mainline compressor station on the Double E system, which will increase the pipeline’s forward haul capacity to Waha by approximately 900 MMcf/d. The compression project along with new plant connections and related infrastructure is expected to cost approximately $100 million net to Summit’s 70% interest and is expected to be placed in service by the fourth quarter of 2028.

The Double E joint venture has already placed a purchase order for the long-lead gas turbine compression units required for the project, securing manufacturing slots necessary to support the targeted in-service date. The project remains subject to FERC and other customary regulatory approvals.

With the new 200 MMcf/d agreement, Double E has secured approximately 550 MMcf/d of binding long-term take-or-pay commitments through the compression expansion open season. Total contracted firm capacity on the pipeline is now approximately 2.2 Bcf/d, held by a diversified group of primarily investment-grade shippers. Double E continues to advance discussions with additional prospective shippers regarding remaining capacity on the expansion.

Summit Permian Transmission Financing

In connection with the final investment decision, Summit Permian Transmission converted the previously uncommitted $50 million accordion under its existing $440 million senior secured term facility maturing in March 2031 into a committed facility. Combined with the $50 million committed delayed draw term facility established at closing in March 2026, Summit expects to have sufficient commitments to fund all of its expected capital contributions to Double E over the next several years. The Summit Permian Transmission term facility remains non-recourse to SMC.

About Double E Pipeline, LLC

Double E is a 135-mile FERC-regulated interstate natural gas transmission pipeline that commenced operations in November 2021 and provides transportation service from receipt points in the Delaware Basin to various delivery points in and around the Waha Hub in Texas.

Double E is owned by subsidiaries of Summit Midstream Corporation (NYSE: SMC) and ExxonMobil (NYSE: XOM) with an ownership interest of 70% and 30%, respectively. Summit Midstream Permian II, LLC is the operator of Double E.

About Summit Midstream Corporation

SMC is a value-driven corporation focused on developing, owning and operating midstream energy infrastructure assets that are strategically located in the core producing areas of unconventional resource basins, primarily shale formations, in the continental United States. SMC provides natural gas, crude oil and produced water gathering, processing and transportation services pursuant to primarily long-term, fee-based agreements with customers and counterparties in five unconventional resource basins: (i) the Williston Basin, which includes the Bakken and Three Forks shale formations in North Dakota; (ii) the Denver-Julesburg Basin, which includes the Niobrara and Codell shale formations in Colorado and Wyoming; (iii) the Fort Worth Basin, which includes the Barnett Shale formation in Texas; (iv) the Arkoma Basin, which includes the Woodford and Caney shale formations in Oklahoma; and (v) the Piceance Basin, which includes the Mesaverde formation as well as the Mancos and Niobrara shale formations in Colorado. SMC has an equity method investment in Double E Pipeline, LLC, which provides interstate natural gas transportation service from multiple receipt points in the Delaware Basin to various delivery points in and around the Waha Hub in Texas. SMC is headquartered in Houston, Texas.

Forward-Looking Statements

This press release includes certain statements concerning expectations for the future that are forward-looking within the meaning of the federal securities laws. Forward-looking statements include, without limitation, any statement that may project, indicate or imply future results, events, performance or achievements and may contain the words “expect,” “intend,” “plan,” “anticipate,” “estimate,” “believe,” “will be,” “will continue,” “will likely result,” and similar expressions, or future conditional verbs such as “may,” “will,” “should,” “would” and “could.” In addition, any statement concerning future financial performance (including future revenues, earnings or growth rates), payment of dividends on any series of stock, ongoing business strategies and possible actions taken by SMC or its subsidiaries are also forward-looking statements. Forward-looking statements also contain known and unknown risks and uncertainties (many of which are difficult to predict and beyond management’s control) that may cause SMC’s actual results in future periods to differ materially from anticipated or projected results. An extensive list of specific material risks and uncertainties affecting SMC is contained in its 2025 Annual Report on Form 10-K filed with the Securities and Exchange Commission (the “SEC”) on March 16, 2026, as amended and updated from time to time. Any forward-looking statements in this press release are made as of the date of this press release and SMC undertakes no obligation to update or revise any forward-looking statements to reflect new information or events.

Cision View original content to download multimedia:https://www.prnewswire.com/news-releases/summit-midstream-corporation-announces-final-investment-decision-on-double-e-pipeline-mainline-compression-expansion-302864529.html

SOURCE Summit Midstream Corporation

832-413-4770, [email protected]

Release – T3 Defense Subsidiary Tiltan to Deliver Majestic.ai as Licensed Software 

logo

Research News and Market Data on DFNS

Engagement set to mark the first delivery of Majestic.ai as customer-operated licensed software, adding a software licensing model to Tiltan’s project-based services

August 26, 2026 09:30 ET  | Source: T3 Defense Inc.

NEW YORK and NETANYA, Israel, Aug. 26, 2026 (GLOBE NEWSWIRE) — T3 Defense Inc. (Nasdaq: DFNS) (“T3 Defense” or the “Company”), today announced that its wholly owned subsidiary, Tiltan Software Engineering Ltd. (“Tiltan”), has been selected by a sensor systems developer and manufacturer to license Majestic.ai, Tiltan’s generative artificial intelligence (AI) synthetic data platform. This marks the first time Majestic.ai will be delivered as software the customer operates itself, rather than as a service Tiltan performs.

Majestic.ai

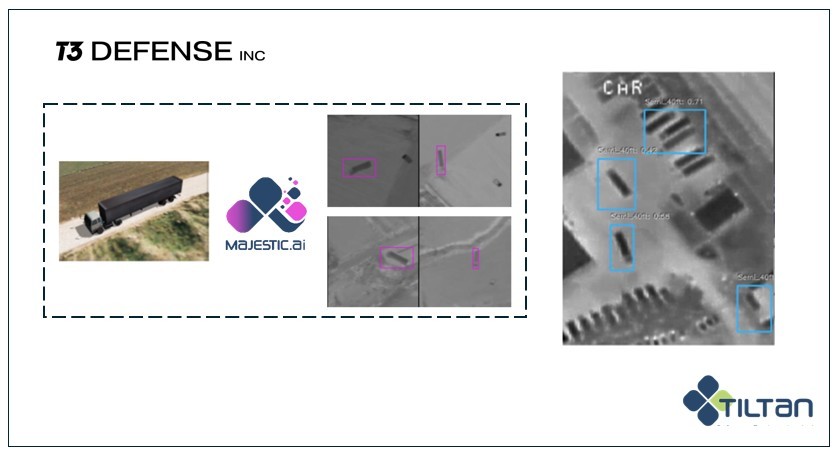
Majestic.ai is Tiltan’s AI platform for synthetic data generation. The physics-based platform produces labeled image and video datasets that defense customers use to train and validate AI systems when real world data is costly or impossible to collect. The platform covers electro-optical (EO), infrared (IR), light detection and ranging (LiDAR), and synthetic aperture radar (SAR) across land, maritime, air, and space environments, and also supports sensor and hardware development programs.

To date, Majestic.ai has been sold as a managed service, with Tiltan producing each dataset for the customer. This engagement is set to mark the platform’s first delivery as licensed software operated by the customer. Management believes a licensed model can support more repeatable revenue per customer and allow Tiltan to serve more programs without adding project labor for each one.

The Majestic.ai license will be paired with Tiltan’s T-VERSE geospatial 3D content, so the customer receives both the generation engine and the underlying data. Bundling the two also gives Tiltan a second product to attach to future licenses.

Photo

Management Commentary

“Synthetic data has become one of the constraints on how quickly advanced sensors and AI systems can be developed and fielded,” said Menny Shalom, Chairman and Chief Executive Officer of T3 Defense. “Tiltan has spent years producing that data for its customers. Licensing Majestic.ai puts the engine, and the content behind it, directly into the customer’s hands. That is a different business than project-by-project services, and we believe it is a meaningful step towards a more scalable, repeatable revenue source from the AI and simulation assets we already own.”

“Our customers must train and validate systems against conditions they cannot practically capture in the field,” said Ehud Shafir, Chief Executive Officer of Tiltan. “With Majestic.ai delivered as licensed software and paired with T-VERSE content, this customer will be able to generate the volume of datasets it needs on its required schedules. Being selected for the first engagement of this kind validates the maturity of the platform and the demand for customer-operated synthetic data generation.”

Commercial Status

The Company is not disclosing the value, scope, or customer identity of the engagement. Majestic.ai has not yet been delivered under this engagement and no revenue has been recognized to date. There can be no assurance as to the timing of delivery, the amount or timing of any revenue recognition, the customer’s continued use or expansion of the license, or that the engagement will result in additional licensed-software programs with this or any other customer.

About Tiltan Software Engineering Ltd.

Tiltan Software Engineering Ltd., a wholly owned subsidiary of T3 Defense, is a leading solution provider specializing in simulation, 3D engines, generative AI training, geo-systems, 3D content, and operations center systems and tools. With over 30 years of experience, Tiltan’s simulation products provide a comprehensive one-stop solution for training, development, and hardware-in-the-loop systems, powered by a proprietary 3D engine and generative AI. Tiltan’s geo-system products support space, aerial, manned, and unmanned vehicles, addressing registration, localization, and navigation challenges, as well as geo-mapping systems. Its in-house content production delivers high-fidelity, geo-specific visual databases, 3D models, and mapping data for VIS, IR, LiDAR, and SAR applications. For more information, visit www.tiltan-se.com.

About T3 Defense Inc.

T3 Defense Inc. (Nasdaq: DFNS) is a defense company that acquires and operates mission-critical defense businesses involved in national security programs. It focuses on manufacturers with strong customer relationships and solid order backlogs, often capacity- and resource-constrained, in specialized areas such as drones and autonomous vehicles, counter-drone systems, advanced manufacturing, tactical robotics, and AI software and system integration. Through disciplined acquisitions, centralized capital and strategy, and decentralized day-to-day operations, T3 Defense aims to strengthen essential defense capabilities and build long-term value. For more information, visit www.t3dfns.com.

Forward-Looking Statements

This press release contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. All statements other than statements of historical fact are forward-looking statements, including, without limitation, statements regarding Tiltan’s selection to deliver Majestic.ai as a licensed software product; the expectation that the engagement will mark the first delivery of Majestic.ai in a self-service, customer-operated model; the anticipated capabilities, configurations, and performance of Majestic.ai and T-VERSE; the timing or completion of delivery; expected demand for licensed, customer-operated synthetic data generation; the potential for additional orders, licenses, production programs, or recurring revenue; the potential for integration across T3 Defense’s portfolio companies; and the Company’s growth strategy. These statements are based on management’s current expectations and assumptions and involve known and unknown risks and uncertainties that could cause actual results to differ materially from those expressed or implied, including risks related to the absence of executed follow-on orders for the licensed model described herein; delivery, integration, and customer acceptance risk; market adoption and customer qualification and testing requirements; defense program funding, procurement cycles, and timing; dependence on government contracts and defense OEM relationships; protection of intellectual property in a licensed-software model; customer concentration; competitive and geopolitical conditions, including conditions in Israel; the Company’s liquidity and capital resources; the Company’s ability to maintain compliance with Nasdaq listing requirements; integration of acquired businesses; and other risks described in the Company’s filings with the Securities and Exchange Commission, including its Annual Report on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K. Forward-looking statements speak only as of the date of this release, and the Company undertakes no obligation to update or revise them, except as required by law.

Contact Us:

T3 Defense Inc.

575 5th Avenue

New York, NY 10017

[email protected]

www.t3dfns.com

Tiltan Software Engineering Ltd.

Ehud Shafir, Chief Executive Officer

www.tiltan-se.com

Investor Relations

The Equity Group Inc.

Lena Cati

[email protected]

+1 212 836-9611

Val Ferraro

[email protected]

+1 212 836-9633

A photo accompanying this announcement is available at https://www.globenewswire.com/NewsRoom/AttachmentNg/3d481ed1-bf71-4cbf-8fb1-867b7b75fe2d

Release – While Measles Cases Continue to Increase in The USA and Globally, NanoViricides is Getting Ready for Clinical Trials of Its Revolutionary Broad-spectrum Drug Candidate NV-387 as A Treatment for Measles

Research News and Market Data on NNVC

Monday, 31 August 2026 08:30 AM

SHELTON, CT / ACCESS Newswire / August 31, 2026 / NanoViricides, Inc., a publicly traded company (NYSE American:NNVC) (the “Company”), and a clinical stage, leading global pioneer in the development of broad-spectrum antivirals based on host-mimetic nanomedicine technology that viruses cannot escape, provides an update on its Measles Drug Treatment Program.

While CDC is reviewing the two recent measles-related fatalities in Pennsylvania, the total number of confirmed measles cases in the USA has reached 2,903 as of August 27, 2026, in comparison to 2,289 confirmed cases in the whole year of 2025, indicating continuing expansion of measles1. Cases of Measles have been rising globally for different reasons. The measles outbreak in Bangladesh has continued to proliferate, claiming 19,218 confirmed cases with 99 fatalities in confirmed cases from 15 March to 30 August, 2026. During this period, a total of 1,37,347 patients with suspected measles were admitted to hospitals and 868 children have died of suspected measles, whereas 1,151 suspected measles cases with 4 deaths were reported in just the last 24 hours in Bangladesh2. The measles outbreak in Bangladesh has continued despite aggressive vaccination campaign that was undertaken since April-May 2026.

In the USA, since COVID-19 days, the MMR vaccination rate has fallen from 95.2% in 2019-2020 to an average of 92.4% in 2025-26, which can be clearly ascribed to the general public vaccine hesitancy that has resulted from the aggressive COVID vaccination policies. The current MMR vaccination rate is well below the 95% putative threshold that is generally agreed as necessary to block spread of measles, with approximately 280,000 unvaccinated kindergartners at risk of measles, according to CDC (ibid #1). The rate of “breakthrough” measles cases in the USA has remained steady at about 6% (~3% in single dose and ~3% in full 2-dose vaccinated individuals) (CDC data).

There is currently no approved drug for measles. Vaccine does not help a patient already infected with the measles virus. Vaccinating already measles-exposed persons to avoid disease spread is attempted yet measles has continued to spread in the USA.

Thus an effective treatment for Measles is an unmet medical need. NV-387 is the only drug candidate to our knowledge that has demonstrated strong in vivo activity against lethal infection with the Measles virus in a humanized animal model study.

NanoViricides is currently developing a Phase II clinical trial protocol for evaluating NV-387 as a treatment for measles. A draft is being circulated. The Company intends to bring this protocol under the purview of the US FDA in an IND process. Therefore, this work is expected to take some time.

NV-387 has been granted a “Rare Pediatric Disease Drug” (RPDD) Designation by the US FDA Office of Orphan Products Development (OOPD).

This RPDD designation enables that a Priority Review Voucher (PRV) can be issued to the Company upon a successful Marketing Application (i.e. New Drug Application) for the use of NV-387 as a treatment for Measles, provided all of the required conditions are met.

The Company can use the PRV, if granted, to reduce review times on another of its drug applications. Importantly, a PRV can be sold to another Pharma Company for accelerating their drug program as well, which provides a high value to the purchaser. Recently, a PRV has been sold for $195 Million3.

Sale of a PRV can bring cash to the Company even prior to revenues from commercialization of a drug product.

“The Rare Pediatric Disease Drug Designation and associated Priority Review Voucher that can be issued make a strong business case for development of NV-387 as a drug for the treatment of Measles,” said Anil R. Diwan, PhD., adding, “NV-387, as an effective drug would be an important tool to fight Measles resurgence in the USA and worldwide, when approved.”

FDA has granted both ODD and RPDD for NV-387 as a Treatment of Measles.

In addition to the PRV eligibility provided by the RPDD for NV-387 as a treatment of Measles, the Orphan Drug Designation qualifies NanoViricides for incentives including:

  • Tax credits for qualified clinical trials;
  • Exemption from certain user fees;
  • Potential seven years of market exclusivity after approval;

according to the US FDA4.

Measles continues to be a rare disease in the USA, with annual incidence rates well below 200,000 cases. Measles primarily affects children. These facts have qualified NV-387 for Measles Treatment for an Orphan Drug Designation, and also for a Rare Pediatric Disease Drug Designation. In a rare disease scenario, commercial revenue from the drug may be slow and small. The PRV is designed to incentivize drug development for rare pediatric diseases by providing additional business value.

Measles cases are rising across the Western world including several European countries and the UK, as well as the USA and Canada. Additionally Mexico and several other Central and South American countries have also been suffering from rising Measles outbreaks.

Measles is endemic globally; many countries that had achieved an elimination status for Measles have by now lost this status, due to severe outbreaks over the last three years5.

Measles is a highly contagious disease, and spreads via virus particles in bodily fluids upon close contact. A population vaccination rate of at least 95% is required to provide “herd immunity” and block community spread. Such a high rate is difficult to maintain for several reasons. Firstly, vaccine hesitancy is rising globally. Secondly, persons with co-morbidities such as immune-compromise status, diabetes, obesity, etc. do not respond fully to any vaccination. Even if vaccinated, such a person can still get Measles, suffering from possibly a mild disease, but will still be contagious and spread Measles. Additionally, the Measles virus continues to change, with the B and D genotypes in circulation currently, while the vaccines in use are still the ones developed for the A genotype in the 1960’s.

Further, very high rates of infections in vaccinated subjects (called “breakthrough cases”), from 14% to 57%, have occurred in some outbreaks6 suggesting that resistant virus strains may have been involved.

Therefore, an effective treatment for Measles is an unmet medical need, that is expected to become even more important in the near future than it is today. Only an effective treatment can help the patient and can avoid the potential severe disease scenarios such as encephalitis, neurological disabilities, and potential fatalities as well as immune amnesia that can result from severe disease.

Quicker recovery of a patient means less chances for spread and thus better ability to control an outbreak. This would require an effective treatment.

NV-387 is an extremely broad-spectrum antiviral drug that has demonstrated strong effectiveness in relevant animal models of multiple human viral infections. These include RSV, COVID, Influenza, Mpox, Smallpox, and Measles.

ABOUT NANOVIRICIDES

NanoViricides, Inc. (the “Company”) (www.nanoviricides.com) is a publicly traded (NYSE-American, stock symbol NNVC) clinical stage company that is creating special purpose nanomaterials for antiviral therapy. The Company’s novel nanoviricide™ class of drug candidates and the nanoviricide™ technology are based on intellectual property, technology and proprietary know-how of TheraCour Pharma, Inc. The Company has a Memorandum of Understanding with TheraCour for the development of drugs based on these technologies for all antiviral infections. The MoU does not include cancer and similar diseases that may have viral origin but require different kinds of treatments.

The Company has obtained broad, exclusive, sub-licensable, field licenses to drugs developed in several licensed fields from TheraCour Pharma, Inc. The Company’s business model is based on licensing technology from TheraCour Pharma Inc. for specific application verticals of specific viruses, as established at its foundation in 2005.

Our lead drug candidate is NV-387, a broad-spectrum antiviral drug that we plan to develop as a treatment of RSV, COVID, Long COVID, Influenza, and other respiratory viral infections, as well as MPOX/Smallpox infections. Our other advanced drug candidate is NV-HHV-1 for the treatment of Shingles. The Company cannot project an exact date for filing an IND for any of its drugs because of dependence on a number of external collaborators and consultants. The Company is currently focused on advancing NV-387 into Phase II human clinical trials.

The Company is also developing drugs against a number of viral diseases including oral and genital Herpes, viral diseases of the eye including EKC and herpes keratitis, H1N1 swine flu, H5N1 bird flu, seasonal Influenza, HIV, Hepatitis C, Rabies, Dengue fever, and Ebola virus, among others. NanoViricides’ platform technology and programs are based on the TheraCour® nanomedicine technology of TheraCour, which TheraCour licenses from AllExcel. NanoViricides holds a worldwide exclusive perpetual license to this technology for several drugs with specific targeting mechanisms in perpetuity for the treatment of the following human viral diseases: Human Immunodeficiency Virus (HIV/AIDS), Hepatitis B Virus (HBV), Hepatitis C Virus (HCV), Rabies, Herpes Simplex Virus (HSV-1 and HSV-2), Varicella-Zoster Virus (VZV), Influenza and Asian Bird Flu Virus, Dengue viruses, Japanese Encephalitis virus, West Nile Virus, Ebola/Marburg viruses, and certain Coronaviruses. The Company intends to obtain a license for RSV, Poxviruses, and/or Enteroviruses if the initial research is successful. As is customary, the Company must state the risk factor that the path to typical drug development of any pharmaceutical product is extremely lengthy and requires substantial capital. As with any drug development efforts by any company, there can be no assurance at this time that any of the Company’s pharmaceutical candidates would show sufficient effectiveness and safety for human clinical development. Further, there can be no assurance at this time that successful results against coronavirus in our lab will lead to successful clinical trials or a successful pharmaceutical product.

This press release contains forward-looking statements that reflect the Company’s current expectation regarding future events. Actual events could differ materially and substantially from those projected herein and depend on a number of factors. Certain statements in this release, and other written or oral statements made by NanoViricides, Inc. are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. You should not place undue reliance on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and which could, and likely will, materially affect actual results, levels of activity, performance or achievements. The Company assumes no obligation to publicly update or revise these forward-looking statements for any reason, or to update the reasons actual results could differ materially from those anticipated in these forward-looking statements, even if new information becomes available in the future. Important factors that could cause actual results to differ materially from the company’s expectations include, but are not limited to, those factors that are disclosed under the heading “Risk Factors” and elsewhere in documents filed by the company from time to time with the United States Securities and Exchange Commission and other regulatory authorities. Although it is not possible to predict or identify all such factors, they may include the following: demonstration and proof of principle in preclinical trials that a nanoviricide is safe and effective; successful development of our product candidates; our ability to seek and obtain regulatory approvals, including with respect to the indications we are seeking; the successful commercialization of our product candidates; and market acceptance of our products.

The phrases “safety”, “effectiveness” and equivalent phrases as used in this press release refer to research findings including clinical trials as the customary research usage and do not indicate evaluation of safety or effectiveness by the US FDA.

FDA refers to US Food and Drug Administration. IND application refers to “Investigational New Drug” application. cGMP refers to current Good Manufacturing Practices. CMC refers to “Chemistry, Manufacture, and Controls”. CHMP refers to the Committee for Medicinal Products for Human Use, which is the European Medicines Agency’s (EMA) committee responsible for human medicines. API stands for “Active Pharmaceutical Ingredient”. WHO is the World Health Organization. R&D refers to Research and Development.

Contact:
NanoViricides, Inc.
[email protected]

Public Relations Contact:
[email protected]

1 https://www.cdc.gov/measles/data-research/index.html

2 https://www.tbsnews.net/bangladesh/health/measles-death-toll-rises-967-4-more-die-24hrs-1528786

3 https://prvwatch.com/

4 https://www.fda.gov/industry/medical-products-rare-diseases-and-conditions/designating-orphan-product-drugs-and-biological-products

5 https://www.cfr.org/articles/many-countries-eliminated-measles-why-is-it-coming-back-in-the-u-s-and-globally

6 Fappani,et al. Breakthrough Infections: A Challenge towards Measles Elimination?. Microorganisms 2022, 10, 1567. https://doi.org/10.3390/microorganisms10081567

SOURCE: NanoViricides

Oil Jumps Above $90 After the First US-Iran Exchange of Fire in a Month

Oil prices surged Monday after the United States and Iran exchanged direct military fire for the first time in roughly a month, ending a relatively quiet stretch in a war now entering its seventh month. Brent crude futures climbed to an intraday high above $91 a barrel, gaining roughly 3% to cross $90 for the first time in about a week, while US benchmark WTI crude gained roughly 4% to trade above $86.

The exchange began when US forces struck Iranian targets on Larak Island, a small landmass inside the Strait of Hormuz that functions as a key monitoring point for Iran’s Revolutionary Guard Corps. US Central Command said the strikes targeted launchers it believed were being prepared to fire rockets carrying sea mines into the strait. Iran retaliated with drone strikes on sites inside Jordan and the United Arab Emirates and said it had seized a bulk carrier vessel near the port of Bandar Abbas. Tehran also claimed an oil tanker struck a mine while attempting an unauthorized transit through the strait, though US Central Command stated it had already cleared that section of the waterway.

Even with this renewed exchange, the physical oil market tells a more nuanced story than headline crude prices alone. Goldman Sachs estimates Persian Gulf crude exports have recovered to roughly two-thirds of pre-war levels, near 15 million barrels per day. The more persistent constraint now sits downstream, in refined products like gasoline and diesel, where capacity has been squeezed by Iranian strikes on regional refineries and, separately, Ukrainian strikes on Russian refining infrastructure. Goldman’s commodities strategists now expect global refined product output to decline by roughly 7 million barrels per day, a constraint that keeps pressure on fuel prices even as crude export volumes have partially normalized.

The policy response is shifting as well. Treasury Secretary Scott Bessent has threatened severe economic consequences for any nation found doing business with Tehran, signaling a pivot from direct military engagement toward economic pressure as the primary tool going forward. Last week, Treasury sanctioned the Emirati branches of a major Egyptian bank it accused of funneling roughly $1.8 billion to the Iranian regime. Critics of that approach note such measures carry limited practical impact unless they eventually target China, which continues purchasing an estimated 90% of Iran’s crude exports. A senior UAE foreign policy adviser put the broader dilemma plainly this week, noting that a state of neither war nor peace cannot be a sustainable solution.

For investors, the national average price of gasoline sitting at $4.08 a gallon despite recent modest declines is worth watching closely, both for its direct effect on consumer-facing small caps already navigating tight household budgets, a dynamic we detailed in earlier coverage of the ceasefire’s collapse, and for its political relevance heading into US midterm elections roughly two months away, where fuel affordability is likely to factor into races that will determine control of Congress. With refined product capacity constrained independent of crude export volumes, sustained pressure on pump prices may persist even if this latest exchange does not escalate further.

DeepSeek’s Founder Is Playing a Different Game With His Hedge Fund

DeepSeek founder Liang Wenfeng’s hedge fund, High-Flyer Quant, has built pre-IPO positions in several of China’s most closely watched technology listings this year, including memory chipmaker CXMT and humanoid robot maker Unitree Robotics.

Two High-Flyer affiliates, Zhejiang High-Flyer Asset Management and Ningbo High-Flyer Quantitative Investment Management, took positions across a range of sectors ahead of these companies’ public debuts, spanning chip packaging, electronic components, renewable energy, and semiconductor supply-chain businesses. Nearly half of the funds’ allocations this year went to semiconductors and related supply-chain companies.

CXMT was the largest single position, with the two funds holding a combined pre-IPO stake estimated at $26 million. The stock surged 466% on its Shanghai debut last month, briefly making it China’s most valuable listed company, and has gained an additional 20% since then.

The funds also held a pre-IPO stake in Unitree Robotics estimated at $5.8 million. Unitree closed 460% above its IPO price on its first day of trading in Shanghai last week, though the stock has since fallen back about 27% from that peak.

DeepSeek itself took a separate and distinct position in Unitree, acquiring a 2.31% strategic allocation and agreeing to a 36-month lock-up period, three times longer than the 12-month hold most other strategic investors accepted in the same deal. This reflects a different objective than High-Flyer’s approach: DeepSeek’s stake functions as a long-term strategic holding tied to its position in the broader AI supply chain, while High-Flyer’s stake was structured as a return-seeking investment.

These pre-IPO opportunities have emerged in part because Beijing has been encouraging strategically important technology companies to list domestically rather than overseas, creating an environment where funds positioned early in sectors aligned with state industrial priorities, such as semiconductors and robotics, have captured outsized returns.

The strategy has carried real risk. During a global AI-chip selloff in July, only one of High-Flyer’s nine investment products avoided losses that month, according to state-backed media reporting. Chinese quant funds broadly recovered those losses by August.

Separately, DeepSeek’s own capital needs have grown substantially and now diverge sharply from High-Flyer’s scale. DeepSeek opened itself to outside investors for the first time this year, raising 50 billion yuan in its initial funding round, an amount exceeding half of High-Flyer’s total assets under management of 80 billion yuan. DeepSeek is reportedly now in discussions to raise at least $7.4 billion more in a second funding round, which would value the company at $74 billion. High-Flyer and DeepSeek did not respond to requests for comment on these transactions.

The Small-Cap Rally Is Real. Is It Just Getting Started?

The Russell 2000 is having a year most investors thought they’d never see again. After more than a decade of trailing large-cap stocks, the small-cap benchmark has turned in its best first-half performance in 35 years, gaining about 22% by the midpoint of 2026 and outperforming the Nasdaq by roughly nine percentage points. For a market that has spent years defined by a handful of mega-cap tech names, that’s a meaningful shift in leadership. Here’s the case for why it may have room to continue.

The valuation gap is still historically wide. Even after the rally, small-cap stocks continue to trade at a discount to large caps, despite the gap narrowing in recent months. Some strategists put numbers on that gap directly: the Russell 2000 trades at its cheapest level relative to the Russell 1000 in 25 years. Cheap valuations alone don’t guarantee outperformance, but they mean small caps aren’t rallying from a stretched starting point the way parts of the large-cap market are.

Rate relief is doing real work. Small companies tend to carry more floating-rate debt than their large-cap peers, which makes them more sensitive to the direction of interest rates. Analysts have pointed to the lagged benefits of Federal Reserve rate cuts from late 2025, which have eased financial pressures on companies carrying floating-rate debt, as a real tailwind behind this year’s move. Lower borrowing costs flow through to smaller-company balance sheets faster and more directly than they do for cash-rich mega-caps.

The rally is broadening, not narrowing. Rather than a rotation away from AI, strategists have framed this move as a broadening of market participation beyond the small group of companies that have driven the market for years. Some analysts go further, arguing the market is now rewarding AI exposure more than current earnings, with unprofitable small caps leading their profitable peers — a sign investors are hunting for the next layer of AI beneficiaries beyond the Magnificent Seven.

There’s also a domestic and macro angle. Part of the appeal is that small caps carry less exposure to global trade tensions and mega-cap concentration risk, making them a relatively direct way to bet on U.S. economic resilience rather than global supply chains or a handful of concentrated tech bets.

The case isn’t unanimous. Not every strategist is convinced this is durable. Wolfe Research, for one, has attributed early-2026 strength largely to technical factors, including seasonal flows, year-end asset reallocation and a January reversal following tax-loss selling, and the firm’s stated view has been to “sell the rip in small caps and stick with large-cap leadership” rather than chase the move. That’s a useful reminder that a valuation discount and a rate tailwind don’t eliminate the sector’s historically higher volatility.

The bottom line is small caps enter the back half of 2026 with a rare combination — a historically wide valuation discount, a genuine rate tailwind, and a market that appears to be broadening its search for growth beyond mega-cap tech. Whether that turns into a multi-year cycle of outperformance or proves to be a technical catch-up trade will likely hinge on two things worth watching closely: whether the Fed continues easing, and whether small-cap earnings growth starts catching up to the price action that’s already happened.

Vince Holding Corp. (VNCE) – OVO Acquisition Establishes Multi-Brand Platform


Friday, August 28, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

A multi-brand platform expansion. On August 24, the company completed the acquisition of Drake’s October’s Very Own (OVO) operating business, including its 12 stores, e-commerce platform, wholesale relationships, employees, assets, and liabilities across Canada, the United States, and the United Kingdom.

Acquisition details. OVO’s intellectual property was valued at approximately $117.6 million, with Authentic Brands Group owning 51%, Drake retaining 44%, and Vince purchasing the remaining 5% for $6 million. A portion of the proceeds from the IP sale was used to repay OVO’s debt and provide additional liquidity for its operating business, which Vince acquired for a nominal equity price of $3.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Lucky Strike Entertainment (LUCK) – From Investment To Cash Flow


Friday, August 28, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

A softer finish to the year. The company reported Q4 revenue of $303.9 million, modestly below our estimate of $314.0 million, while adj. EBITDA of $74.1 million missed our $88.0 million estimate by nearly 16%. Management attributed the revenue softness to unfavorable weather at its largest water parks and high viewership of the World Cup and NBA Finals.

June weighed on results. Management estimated the sports-related revenue impact at $7 million to $12 million and the incremental weather impact on the water parks at $3 million to $5 million. Despite these pressures, the underlying trends were stronger than the quarterly results suggest. Full-year same-store sales declined just 0.2%, marking the company’s best comp since fiscal 2023.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Unemployment Claims Drop While the Trade Deficit Hits a One-Year High

New unemployment filings dropped for a second straight week, pointing to a labor market that stays steady even as hiring cools, giving the Federal Reserve room to focus on inflation. But a separate report showed the goods trade deficit widening to its largest in over a year, a reminder that the growth story beneath the calm jobs data is more complicated.

Initial claims for state unemployment benefits fell by 4,000 to a seasonally adjusted 203,000 for the week ended August 22, the Labor Department said, below the 208,000 economists expected and a second straight weekly decline. Claims have spent the year in a tight 189,000–230,000 band and are now near the low end, signaling that employers aren’t shedding workers even if they aren’t hiring aggressively. Despite a surprise dip in July payrolls, unemployment edged down again to a historically low 4.1%.

Continuing claims, a rough proxy for how hard it is to find new work, fell 18,000 to 1.778 million, the lowest in a month. That week also aligned with the survey period for the August payrolls report, giving it extra weight.

Some analysts argue the picture is steadier than the official figures imply. Private data from payroll processors and labor-market analytics firms point to a job market in better balance than the choppier government numbers suggest, with modest but consistent private hiring roughly at the pace needed to keep unemployment flat.

A stable labor market frees the Fed to keep leaning against inflation, which has run above its 2% target for 65 consecutive months. That’s the backdrop as policymakers gather in Jackson Hole, where Chair Kevin Warsh delivers a closely watched keynote Friday, under pressure to address whether inflation is still a threat.

He isn’t short on colleagues sounding the alarm. Three voting members dissented last month against holding rates at 3.50%–3.75%, and the Fed’s preferred inflation gauge held at 3.7%. Kansas City Fed President Jeffrey Schmid called inflation stubborn and sticky; Chicago Fed President Austan Goolsbee named it his top worry.

The goods trade deficit widened to $118.8 billion in July from $101.4 billion in June, the largest since March 2025, when importers front-loaded ahead of “Liberation Day” tariffs. It’s an awkward figure for a White House leaning on tariffs to shrink the gap.

Exports slipped 2.9% to $199.4 billion, dragged by an 11.2% drop in industrial goods. Imports climbed 3.7% to $318.2 billion, powered by an 11.3% surge in capital-goods imports tied to the AI buildout. Oxford Economics’ Matthew Martin expects that demand to persist into 2027. But the near-term cost is to GDP, with trade likely a drag for a fourth straight quarter, an estimated one-point hit in Q3 after subtracting 1.14 points in Q2.

Two reports, two signals. Jobs data says the foundation is intact, giving the Fed cover to focus on prices; trade data says the AI boom lifting markets is also weighing on output. Warsh’s Friday remarks are the next place to look.

Release – Vince Holding Corp. Acquires OVO to Create Multi-Brand Platform

Vince Holding Corp.

Research News and Market Data on VNCE

08/27/2026

VNCE Will Own OVO’s Operating Business and a 5% Stake in OVO’s Intellectual Property Alongside Authentic Brands Group and OVO Co-Founder Aubrey “Drake” Graham

Transaction Expected to be Accretive to VNCE in Fiscal 2027

VNCE Expects to Deliver Second Quarter Fiscal 2026 Results At the High End of Guidance

NEW YORK–(BUSINESS WIRE)– Vince Holding Corp. (Nasdaq: VNCE) (“VNCE” or the “Company”), a global retail platform today announced it has completed the acquisition of the operating business of October’s Very Own (“OVO”), a globally recognized lifestyle brand. VNCE now will own and operate OVO’s business as OVO’s core apparel and retail licensee, marking the first expansion of its multi-brand platform strategy beyond Vince, and will build on OVO’s existing operations using its scale and infrastructure to support the brand’s next phase of growth.

This transaction also further deepens VNCE’s partnership with Authentic Brands Group (“Authentic”), a global entertainment platform, who has acquired a majority stake in OVO’s intellectual property (“OVO IP”). A portion of the proceeds from the sale of OVO IP will be used to strengthen OVO’s balance sheet and support VNCE’s growth strategy for the business. This transaction combines Authentic’s brand management expertise with VNCE’s proven capabilities in merchandising and operating ready-to-wear brands, creating a new revenue stream for VNCE. As part of this expanded partnership, VNCE will own 5% of the OVO IP and has entered into a long-term license agreement for use of the OVO IP.

This transaction advances VNCE’s strategy to diversify its revenue and earnings by leveraging its platform and operating expertise. This transaction is expected to:

  • Provide VNCE access to the fast growing global streetwear market.
  • Fuel OVO’s U.S. growth by:
    • Store and e-commerce expansion by leveraging VNCE’s scale and infrastructure.
    • Launch OVO’s wholesale business through VNCE’s established wholesale relationships with key national department store partners.
  • Optimize OVO’s operations while design and creative functions for each brand remain separate.
  • Give VNCE the Canadian-based infrastructure to open Vince stores and expand e-commerce and wholesale.

Founded by Aubrey “Drake” Graham, Oliver El-Khatib, and Noah “40” Shebib, OVO has established itself as one of the most recognized brands in contemporary streetwear. Known for its distinctive owl logo and black-and-gold aesthetic, the brand has built its reputation on collaboration-led product drops and a close connection to its customer base. OVO currently operates 12 stores across Canada, the United States, and the United Kingdom, in addition to its e-commerce platform.

“We are thrilled to welcome OVO into our portfolio and to partner with Drake and Authentic in building on the brand’s strong foundation to support its next phase of growth,” said Brendan Hoffman, Chief Executive Officer of VNCE. “This transaction also deepens our relationship with Authentic Brands Group, a partner supporting our multi-brand platform strategy to broaden our portfolio of brands, business models, and distribution channels, and drive long-term value for all stakeholders. We are committed to preserving the authenticity and meaningful customer relationships that have driven OVO’s success to date.”

“We are proud to welcome OVO to Authentic and to expand our partnership with VNCE, whose operating expertise makes them an ideal partner to grow the business,” said Jamie Salter, Founder and Executive Chairman of Authentic. “Together, we see significant opportunity to introduce OVO into new categories, channels, and markets while staying true to the creative vision and community that have made the brand so special. The success we’ve had partnering with VNCE gives us great confidence in their stewardship of OVO’s business and we look forward to exploring future opportunities to utilize the VNCE platform.”

“We’re just a couple kids from Toronto who started something we believed in, here we are 20 years later, same kids with bigger dreams. Authentic and VNCE are the perfect partners to help us continue to grow,” said Drake.

Transaction Details

Under the terms of the transaction, Authentic formed a new subsidiary which holds OVO’s IP, under which Authentic owns 51%, Drake owns 44%, and VNCE owns the remaining 5%. A portion of the proceeds from the sale of OVO’s IP was used to strengthen the balance sheet of OVO’s operating business, which VNCE then acquired. VNCE remains well-capitalized, with a strong balance sheet that supports both this transaction and its continued growth in the Vince business.

VNCE and Authentic have entered into a license agreement granting VNCE the exclusive right to use OVO’s IP to manufacture and sell licensed apparel worldwide, in exchange for payment of a royalty fee to Authentic.

VNCE’s acquisition includes all of OVO’s existing operating companies, assets and liabilities, including its retail stores, e-commerce platform, and wholesale relationships across Canada, the United States, and the United Kingdom. VNCE will retain OVO’s existing team and continue to operate the business from its Toronto headquarters as it builds out the brand’s next phase of growth.

Vince and OVO will maintain separate brand operations and creative teams, with VNCE serving its contemporary customer and OVO continuing to serve its streetwear audience.

Second Quarter Fiscal 2026 Outlook

Based on continued momentum in the business, VNCE expects to deliver Q2 fiscal 2026 results at the high-end of its prior guidance ranges, excluding any benefit from tariff refunds.

These amounts are based on currently available information and are subject to change, including potential adjustments related to customary financial closing procedures and period-end accruals for the fiscal quarter ending August 1, 2026.

The Company plans to share more on its results when its report its second quarter fiscal 2026 results by September 15, 2026.

DISCLOSURES REGARDING FORWARD-LOOKING STATEMENTS

This document, and any statements incorporated by reference herein, contain forward-looking statements under the Private Securities Litigation Reform Act of 1995. Forward-looking statements include the statements under “Transaction Details” and “Second Quarter Fiscal 2026 Outlook” above as well as statements regarding, among other things, our current expectations about possible or assumed future results of operations of the Company and are indicated by words or phrases such as “may,” “will,” “should,” “believe,” “expect,” “seek,” “anticipate,” “intend,” “estimate,” “plan,” “target,” “project,” “forecast,” “envision” and other similar phrases. Although we believe the assumptions and expectations reflected in these forward-looking statements are reasonable, these assumptions and expectations may not prove to be correct and we may not achieve the results or benefits anticipated. These forward-looking statements are not guarantees of actual results, and our actual results may differ materially from those suggested in the forward-looking statements. These forward-looking statements involve a number of risks and uncertainties, some of which are beyond our control, including, without limitation: the expected effects of the acquisition of OVO’s existing operations, assets and liabilities (the “OVO Acquisition”) on the Company; our ability to integrate OVO with the Company, changes to and unpredictability in the trade policies and tariffs imposed by the U.S. and the governments of other nations; general economic conditions; our ability to maintain adequate cash flow from operations or availability under our revolving credit facility to meet our liquidity needs; restrictions on our operations under our credit facilities; our ability to improve our profitability; our ability to maintain our larger wholesale partners; our ability to accurately forecast customer demand for our products; our ability to maintain the license agreement relating to the Vince brand with ABG Vince; ABG Vince’s expansion of the Vince brand into other categories and territories; ABG Vince’s approval rights and other actions; our ability to realize the benefits of our strategic initiatives; our ability to make lease payments when due; our ability to open retail stores under favorable lease terms and operate and maintain new and existing retail stores successfully; our operating experience and brand recognition in international markets; our ability to remediate the identified material weakness in our internal control over financial reporting; our ability to comply with domestic and international laws, regulations and orders; increased scrutiny regarding our approach to sustainability matters and environmental, social and governance practices; competition in the apparel and fashion industry; our ability to attract and retain key personnel; seasonal and quarterly variations in our revenue and income; the protection and enforcement of intellectual property rights relating to the Vince brand; the extent of our foreign sourcing; our reliance on independent manufacturers; our ability to ensure the proper operation of the distribution facilities by third-party logistics providers; fluctuations in the price, availability and quality of raw materials; the ethical business and compliance practices of our independent manufacturers; our ability to mitigate system or data security issues, such as cyber or malware attacks, as well as other major system failures; our ability to adopt, optimize and improve our information technology systems, processes and functions; our ability to comply with privacy-related obligations; our status as a “controlled company”; our status as a “smaller reporting company”; and other factors as set forth from time to time in our Securities and Exchange Commission filings, including those described in our Annual Report on Form 10-K and Quarterly Reports on Form 10-Q. We intend these forward-looking statements to speak only as of the time of this release and do not undertake or revise them as more information becomes available, except as required by law.

About Vince Holding Corp.

Vince Holding Corp. is a global retail platform that operates the Vince brand women’s and men’s ready-to-wear business. Vince, established in 2002, is a leading global luxury apparel and accessories brand best known for creating elevated yet understated pieces for everyday effortless style. Vince Holding Corp. operates 42 full-price retail stores, 12 outlet stores, and its e-commerce site, as well as through premium wholesale channels globally. Please visit www.vince.com for more information.

About October’s Very Own

October’s Very Own (OVO) is a Canadian lifestyle brand led by CEO Drex Jancar and founded by Aubrey “Drake” Graham, Oliver El-Khatib, and Noah “40” Shebib. OVO offers premium apparel and accessories and is known for its distinctive owl logo and black-and-gold aesthetic. The brand has grown into a globally recognized enterprise with 12 flagship stores and a worldwide e-commerce presence.

About Authentic Brands Group

Authentic Brands Group (Authentic) is a global brand and entertainment platform that owns and invests in iconic intellectual property and cultural assets. It accelerates brands through a set of specialized businesses that combine powerful storytelling, premium content, unforgettable live experiences and global commerce. Through a network of more than 1,700 best-in-class licensees and strategic partners across 150 countries and expansive distribution, Authentic’s brands drive more than $38 billion in annual systemwide retail sales worldwide.

Authentic’s diversified portfolio spans more than 50 brands and reaches nearly one billion social media followers. Its roster includes Reebok, Champion, Shaquille O’Neal, David Beckham, Kevin Hart, Sports Illustrated, Elvis Presley, Muhammad Ali, Marilyn Monroe, GUESS, Care Bears, Aéropostale, Nautica, Eddie Bauer, Lucky Brand, Nine West, Brooks Brothers, Juicy Couture, Vince Camuto, Izod, Van Heusen, Dockers, Ted Baker, Hart Schaffner Marx, Vince, OVO, Barneys New York, Judith Leiber, Quiksilver, Spyder, Billabong, Volcom, Roxy, RVCA, DC Shoes, Prince, Sperry and Hunter.

For more information, visit corporate.authentic.com. Follow Authentic on LinkedIn, Instagram and WeChat.

Vince Holding Corp.
Lividini & Co.
Jaqui Lividini
[email protected]

ICR, Inc.
Caitlin Churchill / Devin Broda
[email protected] / [email protected]

October’s Very Own
Melissa Nathan, The Agency
[email protected]

Authentic Brands Group
Haley Steinberg
[email protected]

Source: Vince Holding Corp.