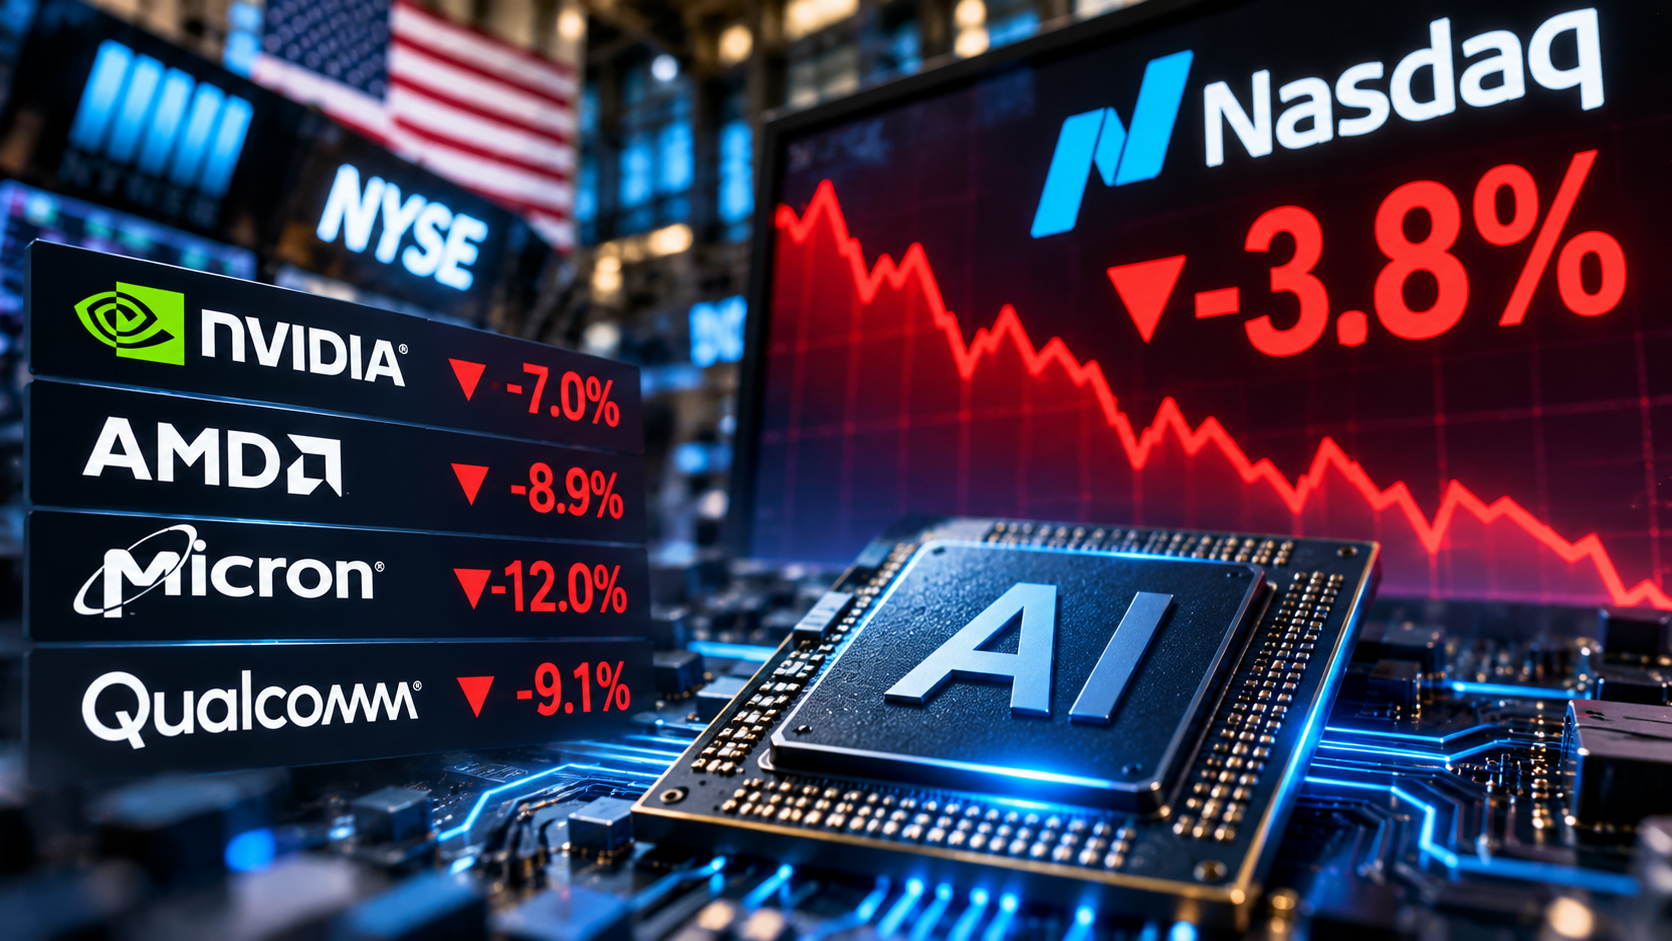
U.S. stocks tumbled Thursday as a sharp selloff in semiconductor and artificial intelligence-related companies reversed much of Wall Street’s post-election rally. The Nasdaq Composite fell nearly 4% during morning trading as investors reassessed the outlook for AI infrastructure spending following the 2026 midterm elections.
The technology-heavy Nasdaq declined approximately 3.8%, while the S&P 500 dropped 2.1% and the Dow Jones Industrial Average fell about 1%. The Philadelphia Semiconductor Index plunged more than 9%, reflecting widespread selling pressure across companies involved in AI chips, memory, and data-center infrastructure.
The downturn came just one day after U.S. stocks rallied following Tuesday’s midterm elections. Wednesday’s gains reflected optimism surrounding the new political landscape, but that sentiment quickly faded as investors evaluated potential challenges facing the artificial intelligence industry.
Semiconductor companies experienced some of Thursday’s steepest declines. Nvidia (NVDA) fell approximately 7%, while Micron Technology (MU) dropped around 12%. Advanced Micro Devices (AMD), Qualcomm (QCOM), and other chipmakers also faced substantial selling pressure.
The declines extended to AI infrastructure providers, including CoreWeave (CRWV) and Nebius Group (NBIS), as concerns intensified over the pace and sustainability of data-center expansion.
Investors are increasingly focused on whether additional regulatory scrutiny, permitting requirements, and infrastructure constraints could delay large-scale data-center projects. Concerns surrounding electricity consumption, water usage, and environmental impacts have already created opposition to new facilities in several communities.
According to Reuters, UBS strategists warned that potential delays could affect approximately 30% of data-center capacity additions expected in 2028.
Such disruptions could have significant implications for semiconductor manufacturers that have benefited from billions of dollars in AI infrastructure spending. Companies supplying processors, memory, electrical equipment, and cooling systems depend heavily on continued investment in computing capacity.
The selloff also reflects broader questions about the profitability of artificial intelligence investments. Major technology companies have committed substantial capital to expanding AI capabilities, but investors are increasingly questioning how quickly those investments will generate sufficient returns.
Qualcomm added to the semiconductor industry’s weakness after issuing a disappointing outlook for smartphone-related chip sales, raising additional concerns about demand across the technology sector.
For small-cap investors, the implications extend beyond major chipmakers.
Smaller businesses involved in data-center construction, power generation, specialized cooling, and computing infrastructure have benefited from AI expansion. However, these companies may face heightened risks if major technology customers delay projects or reduce capital expenditures.
Smaller companies often have fewer financial resources to absorb unexpected changes in demand, making them particularly sensitive to shifts in infrastructure spending and borrowing costs.
The broader market decline also comes amid uncertainty surrounding Federal Reserve policy and economic growth. Wednesday’s ADP employment report showed that private employers added 86,000 jobs in October, suggesting continued labor market resilience despite uneven hiring.
Investors are now awaiting Friday’s government employment report for additional insight into the economy and potential interest-rate decisions.
While Thursday’s selloff highlights growing concerns about AI infrastructure investment, it does not necessarily signal an end to the industry’s long-term growth.
For Wall Street, the central question is whether the decline represents a temporary reassessment of technology valuations or the beginning of a broader shift away from companies most exposed to the AI investment cycle.
As markets digest the election results and upcoming economic data, semiconductor stocks and AI infrastructure companies will remain important indicators of investor confidence heading into 2027.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Overview. The third quarter was active for CoreCivic, with the Company delivering strong financial results, driven by increased demand from ICE, including higher utilization of recently activated facilities, as well as the contribution from the acquisition of Clinical Solutions Pharmacy earlier this year. In addition, CoreCivic completed the sale of four facilities to the Federal government, generating $2.2 billion in gross proceeds.
3Q26 Results. Revenue in 3Q totaled $744.1 million, up 28.2% y-o-y and exceeding our $690 million projections. Adjusted EBITDA in 3Q26 was $117.8 million, up 32.6% y-o-y and above our $109 million estimate. Adjusted EPS was $0.49, up over 100% y-o-y and exceeding our $0.42 per share projection.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Noble Capital Markets Research Report Thursday, November 5, 2026
Companies contained in today’s report:
CoreCivic, Inc. (CXW)/OUTPERFORM – First Look at 3Q26 Results Ocugen (OCGN)/OUTPERFORM – 3Q26 Reported With Expected Progress In All Three Trials SelectQuote (SLQT)/OUTPERFORM – Cost Discipline Begins to Pay Off Townsquare Media (TSQ)/OUTPERFORM – Balancing Growth and Financial Flexibility
CoreCivic, Inc. (CXW/$30.52 | Price Target: $42) Joe Gomes [email protected] | 561-999-2262 First Look at 3Q26 Results Rating: OUTPERFORM
Overview. The third quarter was active for CoreCivic, with the Company delivering strong financial results, driven by increased demand from ICE, including higher utilization of recently activated facilities, as well as the contribution from the acquisition of Clinical Solutions Pharmacy earlier this year. In addition, CoreCivic completed the sale of four facilities to the Federal government, generating $2.2 billion in gross proceeds.
3Q26 Results. Revenue in 3Q totaled $744.1 million, up 28.2% y-o-y and exceeding our $690 million projections. Adjusted EBITDA in 3Q26 was $117.8 million, up 32.6% y-o-y and above our $109 million estimate. Adjusted EPS was $0.49, up over 100% y-o-y and exceeding our $0.42 per share projection.
Ocugen (OCGN/$0.87 | Price Target: $12) Robert LeBoyer [email protected] | (212) 896-4625 3Q26 Reported With Expected Progress In All Three Trials Rating: OUTPERFORM
3Q26 Reported With Start Of OCU410 Phase 2/3 Trial. Ocugen reported a loss of $3.6 million, or $(0.01) per share, including a non-cash gain of $16.6 million from Change In Fair Value of Derivatives. Without this gain, Net Loss would have been $20.2 million, or $(0.06) per share. This adjusted Net Loss is consistent with previous quarters and our estimates for 3Q26. Cash and equivalents were $84.6 million as of September 30, 2026, which we expect to fund operations through 2028.
OCU400 In Retinitis Pigmentosa. The Phase 3 liMeliGhT (pronounced Limelight) trial continues, with data expected to be announced in 1Q2027. The Process Performance Qualification (PPQ) batches for the CMC section of the BLA have been completed. As discussed in our Research Note on September 28, the Bahamas has granted Provisional Approval and Priority Designation for OCU400. We continue to expect submission of the BLA to the FDA and an MAA in Europe, with approval later in FY2027.
SelectQuote (SLQT/$0.49 | Price Target: $3) Jacob Mutchler [email protected] | Michael Kupinski [email protected] | (561) 994-5734 Cost Discipline Begins to Pay Off Rating: OUTPERFORM
Q1 Results Exceed Expectations. SelectQuote reported fiscal first-quarter 2027 revenue of $280.0 million, down 14.8% year over year but above our estimate of $270.9 million. The adjusted EBITDA loss narrowed to $17.0 million from $32.1 million in the prior-year period, exceeding our forecast for a $25.4 million loss. The results highlight improving profitability despite continued revenue pressure.
Lower Costs Drive Profitability Improvement. Revenue declined amid lower pharmacy volumes, fewer Medicare Advantage policy sales, and reduced carrier-sponsored payments. However, marketing expenses decreased 25.0%, while improving pharmacy economics helped Healthcare Services adjusted EBITDA increase 55.7% to $11.2 million. In Senior, lower acquisition costs and greater use of internally generated leads narrowed the adj. EBITDA loss to $12.3 million from $21.0 million.
Townsquare Media (TSQ/$2.18 | Price Target: $15) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Balancing Growth and Financial Flexibility Rating: OUTPERFORM
Q3 Results. Townsquare Media reported third-quarter revenue of $110.9 million, an increase of 3.9% year over year and above our estimate of $108.9 million. Adjusted EBITDA increased 2.7% to $22.6 million, modestly below our forecast of $23.5 million. Results benefited from strong Digital Advertising growth and higher political spending, partially offset by weakness in Interactive and Broadcast.
Mixed Performance Across Digital Businesses. Digital Advertising revenue increased 12.7%, driven by programmatic growth and stronger direct sales of owned-and-operated properties. However, profitability lagged as the expanding Media Partnerships business contributed to lower segment margins. Meanwhile, Interactive’s customer churn remained historically low, and profit margin improved 300 basis points to 36.3%, despite continued weakness in new-customer sales as the company rebuilds its salesforce.
Noble Capital Markets Research Report Wednesday, November 4, 2026
Companies contained in today’s report:
Commercial Vehicle Group (CVGI)/OUTPERFORM – Revenue Momentum Continued in 3Q VivoPower International PLC (VIVO)/OUTPERFORM – Laying the Groundwork for AI
Commercial Vehicle Group (CVGI/$3.34 | Price Target: $7) Joe Gomes [email protected] | 561-999-2262 Revenue Momentum Continued in 3Q Rating: OUTPERFORM
Overview. In the third quarter of 2026, CVG delivered year-over-year revenue growth across all 3 segments, reflecting ongoing efforts to reduce end-market concentration in cyclical North American Class 8 truck exposure through geographic and end-market diversification. While there are still macroeconomic uncertainties to monitor, we believe CVG is hitting its stride as new business wins are ramping up coincidentally with a recovery in key end markets.
3Q26 Numbers. Revenue of $208.1 million rose 36.5%. We had forecast $195 million. Gross margin expanded 300 bp to 13.5% and was up 80 bp sequentially. Adjusted EBITDA came in at $8.5 million, versus $4.6 million in 3Q25. Adjusted EPS was $0.03 compared to an adjusted net loss of $0.14/sh last year. We had forecast $10 million and $0.03, respectively.
VivoPower International PLC (VIVO/$1.6 | Price Target: $10) Jacob Mutchler [email protected] | Michael Kupinski [email protected] | (561) 994-5734 Laying the Groundwork for AI Rating: OUTPERFORM
FY2026 Operating Results. VivoPower reported fiscal 2026 revenue of $2.6 million, primarily reflecting $2.5 million from Mo i Rana following its May 12 acquisition. The adjusted EBITDA loss from continuing operations widened to $24.4 million from $11.1 million in FY 2025. Excluding $13.1 million in non-cash share-based expenses, the loss was $11.3 million.
Mo i Rana Drives Fourth Quarter Revenue. The data center contributed $2.5 million in revenue and approximately $0.04 million in operating profit during the final 50 days of fiscal 2026. Revenue came from existing Bitcoin mining hosting rather than AI leases, while one-time acquisition costs, downtime for site improvements and maintenance, and lower Bitcoin prices weighed on profitability.
Noble Capital Markets Research Report Tuesday, November 3, 2026
Companies contained in today’s report:
Information Services Group (III)/OUTPERFORM – Riding the AI Wave NeuroSense Therapeutics Ltd. (NRSN)/OUTPERFORM – New Data To Be Added To Canadian NDS Application For PrimeC Tectonic Metals Inc. (TETOF)/OUTPERFORM – Black Creek Discovery Gains Momentum The GEO Group (GEO)/OUTPERFORM – Activating Idle Facilities V2X (VVX)/OUTPERFORM – Strong Third Quarter Results
Information Services Group (III/$6.28 | Price Target: $7) Joe Gomes [email protected] | 561-999-2262 Riding the AI Wave Rating: OUTPERFORM
3Q26 Overview. ISG delivered a robust financial performance in the third quarter, with strong cash generation, expanding margins, and solid revenue growth. Revenue in the quarter was driven by a return to growth in Asia Pacific, up 47%, AI-related revenues reaching over $30 million for the first time, and recurring revenues continuing to build, up 7%. This mix of growth helped drive adjusted EBITDA margin expansion to 15.4%, the highest quarterly margin in four years.
3Q26 Results. Revenues for 3Q26 were $65.1 million, up 4.4% from $62.4 million in the prior year. Revenues were $41.9 million in the Americas, down 1%; revenues in Europe were $17.0 million, up 6% on a reported basis; and Asia Pacific revenues were $6.2 million, up 47% on a reported basis. ISG reported GAAP net income of $3.4 million, compared with net income of $3.1 million in the prior year. Fully diluted earnings per share were $0.07, compared with fully diluted earnings per share of $0.06 in the prior year. Adjusted EPS was $0.10, up from $0.09 in the prior year’s third quarter. Adjusted EBITDA was $10.0 million, up 19% from the prior year.
NeuroSense Therapeutics Ltd. (NRSN/$1.43 | Price Target: $9) Robert LeBoyer [email protected] | (212) 896-4625 New Data To Be Added To Canadian NDS Application For PrimeC Rating: OUTPERFORM
Additional Data To Strengthen NDS Application. NeuroSense announced it will add data from new analyses of the PrimeC Phase 2b PARADIGM trial to its New Drug Submission (NDS) in Canada. These additional analyses strengthen the application, but have moved the NDS submission date from December 2026 to March 2027. We have not expected this to be a financially important market and do not see this delay as significant.
New, Unpublished Analyses Will Be Included. One of the new analyses to be included in the NDS is data on neurofilament light chain (NfL) levels. This structural protein in neurons serves as a biomarker for neuronal damage and death in ALS. PrimeC patients had greater reductions in NfL than placebo patients, correlating with other clinical findings in the trial. We believe these data further support previous findings of slowed disease progression.
Tectonic Metals Inc. (TETOF/$1.08 | Price Target: $3.5) Mark Reichman [email protected] | (561) 999-2272 Black Creek Discovery Gains Momentum Rating: OUTPERFORM
Recent drilling results. Tectonic Metals reported results from six additional drill holes at its Flat Gold Project in Alaska, highlighted by Hole CMR26-159, which intersected 2.86 grams per tonne (g/t) of gold over 91.44 meters, including 5.61 g/t over 41.15 meters and 12.94 g/t over 13.72 meters. The hole represents the longest mineralized intercept reported at Black Creek and ended in high-grade mineralization, leaving the system open at depth.
Results strengthen evidence of mineralization continuity. Hole CMR26-159 was drilled 100 meters south of the 2025 discovery hole and 30 meters south of two previously reported mineralized holes. Drilling has now intersected gold in 17 of 18 holes across a footprint measuring approximately 100 by 200 meters. Several higher-grade intersections remain open at depth, supporting additional drilling to establish the geometry and continuity of mineralization.
The GEO Group (GEO/$27.89 | Price Target: $40) Joe Gomes [email protected] | 561-999-2262 Activating Idle Facilities Rating: OUTPERFORM
Activation. Yesterday, The GEO Group announced the activation of its previously idle Big Spring Complex in Texas. The Big Spring Complex is expected to generate approximately $200 million in annual revenues for GEO in the first full year of operations. The announcement is the second contract update in the past week. Not only do these contracts reinforce GEO’s ability to help its government partners meet their needs, but they also suggest ICE detainee populations should continue to rise, in our view.
Details. The contract is a 10-year intergovernmental service agreement between the City of Big Springs, Texas, and ICE. The facilities include the 1,404-bed Flightline Facility and the 925-bed Cedar Hill Facility. GEO will provide support services at the Big Springs Complex, which are expected to include the exclusive use of the Facility by ICE, along with security, maintenance, and food services, as well as access to recreational amenities, medical care, and transportation services.
V2X (VVX/$83.2 | Price Target: $92) Joe Gomes [email protected] | 561-999-2262 Strong Third Quarter Results Rating: OUTPERFORM
Overview. V2X delivered another strong quarter, with revenue growth and double-digit increases in net income and diluted EPS. Results reflect consistent execution and continued demand for V2X’s mission-critical capabilities. V2X experienced another quarter of strong cash generation and maintained a healthy balance sheet. With this flexibility, the Company is continuing to invest in priority growth areas, including expanding capacity in engineering and product capabilities.
3Q26 Results. Third-quarter revenue of $1.271 billion was up from $1.167 billion and exceeded our $1.19 billion estimate. Adjusted EBITDA came in at $88.6 million, up from $85.2 million in 3Q25 and above our $86 million estimate. Adjusted EPS was $1.64, up 19% y-o-y, and exceeded our $1.46 projection.
Thoughts on the Quarter. We view the quarter as evidence of progress in cash generation and portfolio repositioning, with an organic earnings recovery still to be demonstrated. Cost actions, school brand performance, and International margin improvement support the operating base. However, acquisitions and currency continue to offset declining comparable sales, and tariff recoveries explain more than the entire quarterly increase in adjusted operating income. A sustained improvement in peripherals sell-through and margins would provide stronger support for a recovery thesis.
Key Quarter Metrics. Back-to-school was a bright spot. Management reported mid-single-digit seasonal growth in the United States and Canada and nearly 20% growth in Mexico. Workspace Solutions segment sales were off low single digits overall, while the Tech Peripherals business was down low double digits.
NN (NNBR/$3.93 | Price Target: $6) Joe Gomes [email protected] | 561-999-2262 Opportunity, Opportunity, Opportunity Rating: OUTPERFORM
Opportunity. The biggest takeaway from the quarter is the tremendous amount of opportunity available to NN. The pipeline in the key end markets-Data Center and Electric Grid, Defense and Electronics, and Medical-exceeds $270 million, with an overall pipeline of $750 million, and the prospect list is over $1 billion in additional opportunities being tracked that have yet to be quoted.
Growth. New-business awards totaled $106 million through September, and management expects more than 150 program launches during 2026. Data-center cooling, defense products, and robotic surgery components are expanding NN’s addressable applications. Management raised its full-year awards target to $110 million to $130 million.
Commercial Preparations Continue. Nutriband continues to prepare for the AVERSA Fentanyl clinical trial, now expected to begin in 1H27. The NDA will be submitted through the 505(b)(2) pathway and requires a single Phase 1 trial demonstrating abuse deterrence with AVERSA Fentanyl technology.
Opioid Crisis Is Getting Worse. The Opioid Crisis was declared a National Public Health Emergency in October 2017. While overdose deaths have declined from their 2023 peak, the number of people living with opioid addiction has increased. CEO Garth Sheridan recently appeared in a video with Nick Shirley, a well-known YouTuber. The segment featured a walking tour in Los Angeles, speaking with people who live with fentanyl addiction. The segment can be viewed at https://www.youtube.com/watch?v=zyDQOBp4nn4&t=1357s.
Noble Capital Markets Research Report Friday, October 30, 2026
Companies contained in today’s report:
ACCO Brands (ACCO)/OUTPERFORM – Third Quarter 2026 First Look Kuya Silver (KUYAF)/OUTPERFORM – Laying the Foundation for Production Growth The GEO Group (GEO)/OUTPERFORM – Updated Contract For Northwest ICE Processing Center Titan International (TWI)/OUTPERFORM – Still Working Through Headwinds Xerox Holdings Corporation (XRX)/OUTPERFORM – Cost Savings Face Mounting Headwinds
ACCO Brands (ACCO/$4.36 | Price Target: $9) Joe Gomes [email protected] | 561-999-2262 Third Quarter 2026 First Look Rating: OUTPERFORM
Quarterly Overview. ACCO delivered third-quarter sales consistent with management’s outlook, driven by a solid back-to-school season in both North America and Mexico and stabilizing trends in Workspace Solutions. Adjusted EPS included net tariff refunds, with underlying operations in line with outlook. ACCO generated strong cash flows and continued to pay down debt, ending September with a consolidated leverage ratio of 3.6x.
3Q26 Numbers. Third quarter net sales decreased 0.9% to $380.3 million from $383.7 million in 2025, reflecting 4.9% growth from the EPOS acquisition and 0.4% from favorable foreign exchange, which were more than offset by a 6.2% decline in comparable sales. Net income was $11.5 million, or $0.12 per share, compared with $4.0 million, or $0.04 per share, in 2025. Adjusted net income increased to $27.2 million from $19.5 million in 2025, and adjusted earnings per share rose to $0.28 from $0.21 in 2025.
Kuya Silver (KUYAF/$0.31 | Price Target: $1.7) Mark Reichman [email protected] | (561) 999-2272 Laying the Foundation for Production Growth Rating: OUTPERFORM
Record underground development supports production growth. Kuya Silver reported record underground development at its Bethania silver mine in Peru during the third quarter of 2026, advancing 575 meters and excavating 4,713 tonnes of development material. Management prioritized mine development over near-term production to establish additional working areas and support higher mining rates. Quarterly production totaled 3,401 tonnes of mineralized material, with increased output expected beginning in the fourth quarter and continuing into 2027.
Infrastructure and processing agreements establish a path to higher throughput. An upgraded underground winch system is expected to support the targeted mining rate of 350 tonnes per day (tpd) without completing the planned access ramp. Separately, a strategic agreement with the Camila processing plant secures dedicated capacity of 3,000 tonnes monthly through March 2027, increasing to 4,000 tonnes beginning in April. The agreement supports near-term production growth while allowing Kuya Silver to prioritize construction of its fully permitted 350 tpd Bethania processing plant.
The GEO Group (GEO/$28.54 | Price Target: $40) Joe Gomes [email protected] | 561-999-2262 Updated Contract For Northwest ICE Processing Center Rating: OUTPERFORM
New Contract. The GEO Group entered into a new 10-year contract for the continued provision of support services at the GEO-owned 1,635-bed Northwest ICE Processing Center located in Tacoma, Washington. The new 10-year contract is expected to generate approximately $140 million in annual revenues for GEO and continue through October 27, 2036. We believe this demonstrates the ongoing attractiveness of GEO’s assets for its government partners.
Services. Support services at the Northwest ICE Processing Center are expected to include security, maintenance, and food services, as well as access to recreational amenities, medical care, and transportation services.
Titan International (TWI/$4.91 | Price Target: $8) Joe Gomes [email protected] | 561-999-2262 Still Working Through Headwinds Rating: OUTPERFORM
Quarterly Overview. Inclusive of ITM, which is reported in the 3Q26 financials as discontinued operations, Titan’s revenues of $454 million were above the midpoint of the guidance, while adjusted EBITDA of $28 million was also within the guidance range. Titan’s One Stop Shop strategy continues to enable the Company to deliver solid financial results despite challenging current market conditions.
3Q26 Results. Focused on reported results, which exclude ITM from continuing operations, revenue came in at $335.2 million compared to $357.3 million in the comparable period of 2025. Gross margin was 14.7% of net sales versus 15.7% in 3Q26. Titan reported adjusted EBITDA of $16.4 million, down from $20.3 million last year. Adjusted loss was $0.03/sh compared to adjusted EPS of $0.04 in 3Q25.
Xerox Holdings Corporation (XRX/$1.67 | Price Target: $2.5) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Cost Savings Face Mounting Headwinds Rating: OUTPERFORM
Third quarter falls short of expectations. Xerox reported third-quarter revenue of $1.87 billion, largely in line with our estimate, while adjusted EBITDA of $193 million was 12.8% below our forecast. Gross margin of 29.2% was approximately 370 basis points below our estimate, reflecting higher input costs and an unfavorable equipment mix, which more than offset lower operating expenses.
Lexmark savings remain on track. Following our discussions with management, we believe the company remains confident in achieving approximately $100 million of incremental Lexmark integration savings in 2027. Additional opportunities in automation, AI, organizational simplification, and facility consolidation could deliver further benefits, though the timing and magnitude of these savings remain uncertain.
Noble Capital Markets Research Report Thursday, October 29, 2026
Companies contained in today’s report:
Bimergen Energy (BESS)/OUTPERFORM – Powering Up a 2 GW Opportunity NN (NNBR)/OUTPERFORM – First Look at 3Q26 Results
Bimergen Energy (BESS/$2.12 | Price Target: $6) Mark Reichman [email protected] | (561) 999-2272 Richard Magnusen [email protected] | Powering Up a 2 GW Opportunity Rating: OUTPERFORM
Initiating coverage with an Outperform rating. Bimergen Energy develops, finances, owns, and operates utility-scale battery energy storage systems (BESS). The company has assembled 23 development projects representing approximately 2.0 gigawatts (GW) of capacity across several regional U.S. power markets. We believe the portfolio provides a range of options to unlock value as Bimergen advances projects through development, monetization, financing, construction, and ultimately commercial operation.
Multiple paths to value creation. Bimergen can monetize projects by retaining minority interests alongside strategic partners or owning completed assets and generate recurring operating revenue. The company has begun demonstrating this flexibility through the sale of the 100-megawatt (MW) Redbird project and two smaller ERCOT projects to Frontier Power while retaining a 7.5% economic interest. We believe this transaction provides initial evidence that development-stage projects can create tangible value before commercial operation.
NN (NNBR/$3.8 | Price Target: $6) Joe Gomes [email protected] | 561-999-2262 First Look at 3Q26 Results Rating: OUTPERFORM
Quarterly Overview. NN delivered a strong 3Q26, significantly exceeding our expectations for sales, adjusted EBITDA, and adjusted net income. NN’s new business program has continued to outperform expectations, with the Company now winning more than 1 new program per day. And NN’s 5 Pillar growth program is working well, with the Company investing its time and resources to strategically pivot the portfolio to high-growth, high-value markets and products.
3Q26 Numbers. Net sales for 3Q26 were $131.1 million, an increase of 26.2% compared to net sales of $103.9 million for 3Q25. The increase was primarily driven by higher selling prices, higher volumes, and favorable foreign exchange effects. Adjusted EBITDA was $18.5 million, an increase of 49.7% compared to adjusted EBITDA of $12.4 million for the same period in 2025. Adjusted net income was $5.3 million, or $0.07 per diluted common share, an increase of $5.6 million or $0.08 per diluted common share, y-o-y.
Noble Capital Markets Research Report Wednesday, October 28, 2026
Companies contained in today’s report:
T3 Defense (DFNS)/OUTPERFORM – A New Acquisition Travelzoo (TZOO)/OUTPERFORM – Membership Momentum Sets Up 2027 Earnings Growth
T3 Defense (DFNS/$3.85 | Price Target: $30) Joe Gomes [email protected] | 561-999-2262 A New Acquisition Rating: OUTPERFORM
Acquisition. T3 Defense has entered into a definitive agreement to acquire KeepZone AI from Nexera Technologies. KeepZone expands T3’s offerings into the Homeland Security vertical. The acquisition allows T3 to expand its commercial reach while providing the Company with a U.S. presence and active channels in North America, Latin America, and the Gulf. We view the proposed acquisition as another building block in T3’s efforts to build a mission-critical defense business embedded at critical chokepoints.
Details. Initial consideration is $1.0 million, payable in common stock (and, to the extent required by a 4.9% beneficial ownership limitation, pre-funded warrants), priced at the average closing price of T3 Defense common stock for the five trading days preceding closing. Nexera is also eligible for an earn-out equal to 50% of KeepZone’s standalone net profit generated during the 24 months following the closing, calculated on the first $10.0 million of net profit and therefore capped at $5.0 million, payable in cash. Closing is expected within 60 days.
Travelzoo (TZOO/$4.98 | Price Target: $16) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | Membership Momentum Sets Up 2027 Earnings Growth Rating: OUTPERFORM
Investment weighs on Q3. Revenue increased 3% to $22.9 million, in line with expectations. Adjusted EBITDA fell to a loss of $2.2 million, modestly wider than our estimated loss of $1.5 million. The earnings shortfall largely reflected higher sales and marketing expenditures associated with the company’s transition to a paid membership model.
Membership growth accelerates. Club Members increased 65% year over year, supported by $5.8 million in direct membership acquisition spending during the quarter. Encouragingly, average U.S. customer acquisition cost fell to $54 from $62 in the second quarter, while deferred revenue rose to $13.5 million, providing greater visibility into future recurring membership revenue.
Noble Capital Markets Research Report Tuesday, October 27, 2026
Companies contained in today’s report:
1-800-Flowers.com (FLWS)/OUTPERFORM – Transformation Efforts Progressing; Financial Flexibility Remains a Focus Alliance Resource Partners (ARLP)/OUTPERFORM – Strong Third Quarter Results Reinforce Constructive 2027 Outlook Eledon Pharmaceuticals (ELDN)/OUTPERFORM – Phase 2 BESTOW Analysis Shows Improved Quality Of Life and Reduced Symptom Burden Resolution Minerals Ltd (RML)/OUTPERFORM – Golden Gate North Gold Zone Expands SKYX Platforms (SKYX)/OUTPERFORM – Another Homebuilder Deal Star Equity Holdings, Inc. (STRR)/OUTPERFORM – A Tuck-in; Updated Model VivoPower International PLC (VIVO)/OUTPERFORM – Advancing Mo i Rana Development and Sovereign AI Strategy
Additional cost savings identified. The company highlighted $50 million in annualized run-rate cost savings achieved ahead of schedule in fiscal 2026 and identified an additional $15 million to $20 million in potential annualized savings for fiscal 2027. We believe these initiatives could support a recovery in profitability, although the timing and extent of the EBITDA contribution remain uncertain.
Focus on financial flexibility. The company highlighted an amendment to its credit agreement that extends covenant relief and provides greater flexibility in using asset-sale proceeds. In addition, the company is evaluating financing alternatives, including potential debt or equity transactions and nonstrategic asset divestitures.
Alliance Resource Partners (ARLP/$26.4 | Price Target: $35) Mark Reichman [email protected] | (561) 999-2272 Strong Third Quarter Results Reinforce Constructive 2027 Outlook Rating: OUTPERFORM
Third Quarter Financial Results. Alliance Resource Partners reported third-quarter 2026 revenue of $603.0 million, up 5.5% year-over-year and 9.3% sequentially. Net income attributable to ARLP increased 46.8% to $139.6 million, or $1.08 per unit, compared with $0.73 a year ago and $0.61 in the second quarter. Adjusted EBITDA attributable to ARLP increased 26.3% to $233.9 million, reflecting stronger coal operations and record oil and gas royalty contributions.
Operating Performance Strengthens. Coal sales increased 7.4% year-over-year to 9.35 million tons, supported by resumed production at Hamilton and strong performance at River View and Tunnel Ridge. Segment Adjusted EBITDA expense per ton decreased 13.1% to $35.64, contributing to an 18.6% increase in Coal Operations Segment Adjusted EBITDA to $186.8 million. The AllDale III and IV acquisition contributed to record oil and gas royalty production of 1.45 million barrels of oil equivalent, while attributable segment Adjusted EBITDA increased 61.4% to $43.6 million.
Eledon Pharmaceuticals (ELDN/$2.21 | Price Target: $10) Robert LeBoyer [email protected] | (212) 896-4625 Phase 2 BESTOW Analysis Shows Improved Quality Of Life and Reduced Symptom Burden Rating: OUTPERFORM
New Data Presentation On Quality of Life and Symptoms. Eledon presented data from the Phase 2 BESTOW trial at the American Society of Nephrology Annual Kidney Week 2026 meeting. The presentation compared patients receiving tegoprubart with those receiving tacrolimus, showing improvements in quality of life and reductions in symptom burden at 12 months. We believe these findings support prior data on efficacy, safety, and tolerability.
Patient Evaluations. Data from two accepted clinical evaluations, MTSOSD-59R and KDQOL-SF, showed substantial, lasting improvements in quality of life and reductions in transplant-related side effects. We see these patient-reported outcomes as consistent with prior reductions in BPAR (Biopsy-Proven Acute Rejection), improvements in eGFR, and improvements in factors that contribute to long-term graft failure.
Resolution Minerals Ltd (RML/$3.82 | Price Target: $30) Mark Reichman [email protected] | (561) 999-2272 Golden Gate North Gold Zone Expands Rating: OUTPERFORM
Drilling expands the gold zone. Resolution Minerals reported additional drill results from Golden Gate North at its 100%-owned Horse Heaven project in Idaho, confirming gold mineralization over an area measuring at least 500 meters along strike, 200 meters in width, and 300 meters in depth. The results expand the known mineralized footprint and strengthen the potential for a sizable near-surface gold system.
Broad mineralized intervals. Three newly reported drill holes intersected extensive gold mineralization beginning at the surface, including 324 meters grading 0.49 grams per tonne (g/t) gold and 322 meters grading 0.37 g/t gold. Although grades remain relatively modest, the continuity and scale of mineralization are encouraging and support further evaluation of potential bulk tonnage mineralization.
SKYX Platforms (SKYX/$0.78 | Price Target: $5) Joe Gomes [email protected] | 561-999-2262 Another Homebuilder Deal Rating: OUTPERFORM
New Deal. Hot on the heels of the Maronda Homes announcement, SKYX Platforms revealed an agreement to supply 60,000 units of its smart home technologies for over 700 homes to be built by Home Creations. The units are expected to be provided over the next 12 months. We believe these are the first of many agreements to be awarded in the future for SKYX products in the home builder vertical.
Home Creations. Founded in 1981, Home Creations is a family-founded homebuilder serving Oklahoma and the Houston, Texas, market. Significantly, Home Creations combines energy-efficient construction with smart home features. The firm’s Oklahoma City homes are nearly 53% more energy-efficient than typical new homes and include Deako smart lighting, a smart thermostat, smart locks, and an app-enabled garage door. Every home is HERS-verified by a certified RESNET energy rater and backed by a 10-year structural warranty.
Star Equity Holdings, Inc. (STRR/$9.89 | Price Target: $16) Joe Gomes [email protected] | 561-999-2262 A Tuck-in; Updated Model Rating: OUTPERFORM
A Tuck-in. Yesterday, Star Equity announced that its Energy Services division acquired a privately held Vernal, Utah-based machine shop that provides repair, rebuild, and machining services for well fishing tools, drill pipe, and other drilling equipment. The transaction closed on October 23, 2026, and the shop will work alongside Alliance Drilling Tool’s (ADT) existing Vernal operation. No financial details were provided.
Additional Detail. Adding these in-house capabilities makes ADT’s Vernal operation a full-service location. ADT can support customers across more of the tool life cycle while gaining more direct control over service quality and turnaround time. The expanded capabilities also position ADT to more actively pursue oil and gas drilling work in the Uinta Basin, as well as mining and geothermal opportunities across the region.
VivoPower International PLC (VIVO/$2.45 | Price Target: $10) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Advancing Mo i Rana Development and Sovereign AI Strategy Rating: OUTPERFORM
Construction mobilized at Mo i Rana. On October 12, 2026, VivoPower announced the start of construction for the initial 40MW AI data center at its Mo i Rana facility in Norway. While a definitive lease agreement has not yet been announced, the company confirmed that it has selected a global AI industry leader as its preferred tenant, with the facility’s design and construction tailored to the prospective customer’s requirements.
Existing operations maintained during construction. VivoPower has engaged local contractors to complete site preparation and structural works ahead of the specialized mechanical and electrical fit-out. Under the original development plan, construction will proceed on adjacent land while existing Bitcoin mining and grid-balancing operations continue. After the mining lease expires in June 2027, the existing power capacity is earmarked for AI applications, with an additional 40MW development planned thereafter.
Noble Capital Markets Research Report Monday, October 26, 2026
Companies contained in today’s report:
Cosmos Health (COSM)/OUTPERFORM – Building a Higher-Margin Healthcare Platform
Cosmos Health (COSM/$0.26 | Price Target: $1.4) Michael Kupinski [email protected] | (561) 994-5734 Richard Magnusen [email protected] | Building a Higher-Margin Healthcare Platform Rating: OUTPERFORM
Initiating coverage with an Outperform rating. We believe Cosmos Health is positioned for a meaningful improvement in profitability as its revenue mix shifts toward higher-margin proprietary healthcare products and pharmaceutical manufacturing. The company’s established wholesale distribution business provides a revenue base, while its expanding U.S. direct-to-consumer operations could become an increasingly important driver of earnings growth.
U.S. direct-to-consumer sales are gaining momentum. Management expects approximately $15 million in fourth-quarter 2026 U.S. e-commerce revenue and $10.5 million in gross profit, reflecting the rapid expansion of its proprietary nutraceutical business. Active U.S. subscriptions reached 8,940 as of October 19, although customer retention and marketing efficiency remain important considerations as the business scales.
Metallurgical work begins. Kodiak Copper has commenced an additional metallurgical program at its 100%-owned MPD copper-gold porphyry project in southern British Columbia. The new work builds on positive results reported earlier this year and is focused on flowsheet development and optimization. The program is intended to improve the technical foundation for future economic studies while MPD continues to advance through ongoing exploration and resource growth.
Project-wide testing. The program is broad in scope and will include representative material from all seven deposits included in MPD’s mineral resource estimate: 1) Gate, 2) Ketchan, 3) Man, 4) Dillard, 5) West, 6) Adit, and 7) South. Four composite samples representing the Southern Area, Northern Area, Ketchan, and Gate will undergo mineralogical, comminution, gravity, flotation, locked cycle, and concentrate quality testing. In our view, this should help determine whether a common processing flowsheet can be applied across multiple deposits, which could simplify future development and provide greater flexibility in mine planning and deposit sequencing.
Increasing third-quarter estimates. We have increased our third-quarter revenue, adj. EBITDA, and adj. EPS estimates to $55.4 million, $35.0 million, and $0.95, respectively, from $53.4 million, $32.0 million, and $0.86. Our revised estimates reflect a higher average time charter equivalent (TCE) rate of $32,750 per day. Moreover, we have increased our FY 2026 revenue, adj. EBITDA and adj. EPS estimates to $209.4 million, $139.7 million, and $3.85, respectively, from $205.9 million, $134.2 million, and $3.70.
Looking ahead. We expect Seanergy’s fleet renewal program to support earnings growth in 2027, with four newbuild vessels scheduled for delivery during the year. These additions should enhance revenue growth, improve operating efficiency, and reduce average vessel age. We also anticipate selective disposals of older vessels, partially offsetting fleet growth while advancing the company’s modernization strategy. While dry dockings, delivery timing, and freight-rate volatility could affect 2027 results, we expect the new vessels to contribute more meaningfully to earnings and cash flow in 2028.
Noble Capital Markets Research Report Thursday, October 22, 2026
Companies contained in today’s report:
SKYX Platforms (SKYX)/OUTPERFORM – Proof of Concept Unicycive Therapeutics (UNCY)/OUTPERFORM – NDA Resubmission Accepted For FDA Review
SKYX Platforms (SKYX/$0.9 | Price Target: $5) Joe Gomes [email protected] | 561-999-2262 Proof of Concept Rating: OUTPERFORM
Proof. It didn’t take long for SKYX Platforms and new subsidiary Deako to supply proof of concept on one of the key elements of the merger: i.e., cross-selling. Yesterday, SKYX announced that it will supply over 80,000 units of its advanced technologies to over 1,000 homes for Maronda Homes. We believe this announcement will be the first of many.
Details. The Company expects to deliver over 80,000 units of its advanced plug-and-play and smart home technologies to over 1,000 Maronda Homes residences in several states, including Ohio, Georgia, Maryland, and Pennsylvania. If the contract is similar to the $50/unit revenue previously disclosed, the contract would represent some $4 million in revenue.
Unicycive Therapeutics (UNCY/$3.87 | Price Target: $40) Robert LeBoyer [email protected] | (212) 896-4625 NDA Resubmission Accepted For FDA Review Rating: OUTPERFORM
OLC Resubmission Given March 25, 2027 PDUFA Date. Unicycive announced that the FDA has accepted its NDA (New Drug Application) resubmission for OLC (oxylanthanum carbonate) for review. This follows the 30-day period after resubmission in which the FDA determined that it was sufficiently complete for review. The application received a PDUFA (Prescription Drug User Fee Act) date of March 25, 2027. This is the date the FDA must respond to the application by statute and aligns with the TDAPA program deadlines.
The NDA Contains Data From A New Manufacturing Partner. As we had expected, the resubmission was classified as Class 2 and received a six-month review. The CMC (Chemistry, Manufacturing, and Controls) section includes product manufacturing data from a new third-party manufacturing partner. The FDA inspected this manufacturer’s plant in March 2024 and gave a “No Action Indicated” status, the equivalent of a passing grade.
Noble Capital Markets Research Report Wednesday, October 21, 2026
Companies contained in today’s report:
FreightCar America (RAIL)/OUTPERFORM – Outlook Reset Following Tank Car Retrofit Order Removal NetSol Technologies, Inc. (NTWK)/OUTPERFORM – Transcending to the Next Stage of Growth
FreightCar America (RAIL/$4.02 | Price Target: $10) Mark Reichman [email protected] | (561) 999-2272 Outlook Reset Following Tank Car Retrofit Order Removal Rating: OUTPERFORM
Tank car retrofit order removed from backlog. FreightCar America removed 1,285 railcars associated with a tank car retrofit contract from its backlog after determining that the customer was unlikely to fulfill its contractual obligations. The order included deliveries scheduled for the second half of 2026 and throughout 2027. Management emphasized that the cancellation is specific to one customer and does not affect other orders. Following the adjustment, the September 30, 2026, backlog totaled 2,660 railcars valued at $284.5 million.
Preliminary Q3 2026 results reflect lower production volumes. FreightCar America expects third-quarter revenue of $75 million to $77 million, down approximately 53% from $160.5 million in the prior-year period. Railcar deliveries declined 49% to 662 units, while adjusted EBITDA is expected to be approximately breakeven, compared with $17.0 million a year earlier. We now forecast revenue of $76.1 million, adjusted EBITDA of $0.0 million, and a loss of $(0.13) per share.
NetSol Technologies, Inc. (NTWK/$6.54 | Price Target: $9) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Transcending to the Next Stage of Growth Rating: OUTPERFORM
Initiating coverage. We are initiating coverage of NetSol Technologies, a global provider of lending, leasing, and digital retail software to auto captives, banks, and equipment lenders. In our view, NetSol’s long-standing customer relationships and Transcend platform position it to benefit as lenders replace aging systems and to shift more revenue from one-time licenses to recurring subscriptions.
A record year. Fiscal 2026 revenue rose 12.5% to a record $74.4 million. Recurring subscription and support revenue grew 8.7% to $35.8 million and accounts for nearly half of total revenue. We believe the increased adoption of the Transcend platform’s subscription model should improve revenue visibility and reduce reliance on individual contract wins.
Noble Capital Markets Research Report Tuesday, October 20, 2026
Companies contained in today’s report:
Euroseas (ESEA)/OUTPERFORM – Strong Charter Rates and Attractive Vessel Sale
Euroseas (ESEA/$66.59 | Price Target: $95) Mark Reichman [email protected] | (561) 999-2272 Strong Charter Rates and Attractive Vessel Sale Rating: OUTPERFORM
New charter at an attractive rate. Euroseas announced a new time charter for its 2001-built, 2,556 twenty-foot equivalent unit (TEU) feeder containership, M/V EM Corfu, at a gross daily rate of $62,500 for a minimum period of 12 to a maximum period of 14 months. The charter, expected to commence in mid-December following a scheduled dry-dock, represents a significant increase from the previous rate of $28,000 per day. The new charter is expected to generate approximately $17.8 million in EBITDA over the minimum 12-month period. The agreement increases charter coverage to approximately 100% for 2026, 91% for 2027, and 49% for 2028.
Monetizing an older vessel. Euroseas also agreed to sell the M/V Evridiki G, a 2001-built sister vessel of the EM Corfu, for approximately $26 million. The transaction is expected to generate a gain of $22.5 million, or $3.19 per share. We view the sale favorably given the vessel’s age and the opportunity to realize an attractive price while reducing the fleet’s exposure to older tonnage.
Noble Capital Markets Research Report Monday, October 19, 2026
Companies contained in today’s report:
Conduent (CNDT)/OUTPERFORM – Conduent Moves To Resolve Major Litigation Overhang First Phosphate Corp. (PHOS)/OUTPERFORM – Advancing Toward Feasibility Kodiak Copper Corp. (KDKCF)/OUTPERFORM – Kodiak Extends Ketchan Mineralization, Strengthening Resource Potential Kratos Defense & Security (KTOS)/OUTPERFORM – A Tuck-in and Other News
Conduent (CNDT/$1.39 | Price Target: $5) Michael Kupinski [email protected] | (561) 994-5734 Conduent Moves To Resolve Major Litigation Overhang Rating: OUTPERFORM
Reaches $80 million class action settlement. Conduent agreed to settle consolidated class action litigation related to its previously disclosed January 2025 cybersecurity incident. The incident involved unauthorized access to the company’s networks beginning in October 2024 and exposed personal information belonging to approximately 62 million individuals. The agreement remains subject to court approval.
Addresses significant litigation exposure. The settlement seeks to resolve litigation stemming from the cybersecurity incident, including claims involving Conduent and affected clients. Upon final approval, the agreement would release Conduent, its affected clients, and their affected customers from covered claims arising from the incident. We believe the agreement provides greater visibility into a significant legal uncertainty that has weighed on the company’s broader turnaround efforts.
First Phosphate Corp. (PHOS/$12.8 | Price Target: $25.5) Mark Reichman [email protected] | (561) 999-2272 Advancing Toward Feasibility Rating: OUTPERFORM
Significant progress toward development. First Phosphate continues to advance its North American LFP battery materials strategy, supported by its inclusion in a G7-backed critical minerals initiative, international financing interest, accelerated permitting coordination in Quebec, and expanded mineral resources. These developments strengthen the company’s strategic position as Bégin-Lamarche advances toward feasibility.
Strengthening project economics and financing prospects. With the updated mineral resource estimate, indicated mineral resources increased by 378%, providing greater geological confidence for feasibility-level mine planning. Canadian government contributions and potential export credit support from Swiss and Danish agencies could reduce future funding requirements. Management is targeting completion of the Bégin-Lamarche feasibility study in the first quarter of calendar 2027.
Ketchan deposit expands significantly. Kodiak Copper recently reported encouraging results from seven drill holes totaling 1,583 meters at its 100%-owned MPD copper-gold project in British Columbia. Step-out drilling extended the known mineralized envelope at Ketchan by at least 450 meters southeast of its existing 1.4-kilometer resource footprint, increasing the known extent of the mineralized system and supporting potential resource growth.
Near-surface copper-gold mineralization. Hole AG-26-034 intersected 122.5 meters grading 0.41% copper equivalent (CuEq), beginning just 5.5 meters below the surface. Hole AG-26-021 returned 202.5 meters grading 0.20% CuEq, while infill hole AG-26-015 intersected 207.3 meters grading 0.31% CuEq. The results demonstrate mineralization both beyond and within the existing resource boundaries.
Kratos Defense & Security (KTOS/$40.42 | Price Target: $100) Joe Gomes [email protected] | 561-999-2262 A Tuck-in and Other News Rating: OUTPERFORM
A Tuck-in. Last week, Kratos acquired Jetset Airmotive from its founders. Jetset’s MRO operations on PT6A turbine engines complement Kratos’ existing MRO operations conducted through its Oklahoma-based CTS subsidiary. Based on previous such transactions, we believe the acquisition was structured as 50% KTOS shares and 50% cash, which would imply roughly $50 million in total. With an estimated $40-$50 million in revenue and typical 13-14% EBITDA margins, Jetset was purchased for approximately 1x revenue and 9x EBITDA. The acquisition should add about $5+ million to annual EBITDA.
New Contracts. Kratos has been awarded more than $100 million over multiple contracts to develop prototype mission applications and cyber capabilities, providing space intelligence data in support of joint operations across the space and cyberspace domains. The contracts will leverage Kratos’ software products, analytics, and expertise in RF, signal processing, cybersecurity, and software development, establishing a proven technology base that can be adapted and integrated to meet emerging space and cyber mission requirements.
High-grade results strengthen exploration outlook. Tectonic Metals reported encouraging results from 19 drill holes at its Flat Gold Project in Alaska. At the Alpha Bowl target, drilling intersected 2.41 grams per tonne (g/t) gold over 59.44 meters, including 11.82 g/t over 10.67 meters and 39.96 g/t over 3.05 meters, within a broader interval of 1.86 g/t over 80.77 meters beginning at the surface. The results strengthen the potential for a large, near-surface gold system containing higher-grade zones.
Alpha Bowl emerges as a priority target. Alpha Bowl extends approximately 820 meters along strike and 600 meters in width, with mineralization encountered beyond 300 meters of vertical depth. Recent and historical drilling demonstrate gold mineralization across multiple locations, with higher-grade intersections suggesting opportunities to enhance future resource quality. Drilling is evaluating mineralization continuity and expansion potential, with several holes awaiting assays.
Noble Capital Markets Research Report Thursday, October 15, 2026
Companies contained in today’s report:
AZZ (AZZ)/OUTPERFORM – Record Results Reinforce Growth Outlook NanoViricides (NNVC)/OUTPERFORM – Ebola Trial Reports Ongoing Enrollment Progress Ocugen (OCGN)/OUTPERFORM – Ocugen Completes Licensing Agreement For MENA Region SKYX Platforms (SKYX)/OUTPERFORM – Transformative Acquisition Completed
AZZ (AZZ/$137.66 | Price Target: $170) Mark Reichman [email protected] | (561) 999-2272 Record Results Reinforce Growth Outlook Rating: OUTPERFORM
FY 2027 Second Quarter Results Exceed Expectations. AZZ reported adjusted net income of $60.1 million, or $2.00 per diluted share, compared with $46.9 million, or $1.55 per share, in the prior-year period. Results exceeded our estimates of $54.9 million, or $1.81 per share, by 9.5% and 10.5%, respectively. Revenue increased 16.7% to a record $486.9 million, while adjusted EBITDA rose 25.0% to $110.9 million, exceeding our $101.6 million estimate. Adjusted EBITDA margin expanded 150 basis points to 22.8%. Metal Coatings revenue increased 22.9% to $233.5 million, while Precoat Metals revenue rose 11.5% to $253.4 million. Segment adjusted EBITDA margins were 30.7% and 21.2%, respectively.
FY 2027 Corporate Guidance Raised. Reflecting strong first-half results and sustained operating momentum, management increased FY 2027 revenue guidance to $1.825 to $1.875 billion from $1.800 to 1.850 billion. Adjusted EBITDA guidance increased to $380 to $420 million from $375 to $415 million, while adjusted diluted EPS guidance rose to $7.00 to $7.30 from $6.75 to $7.15.
Patient Enrollment and Treatment Continue. Nanoviricides provided an update on the progress of its Phase 2a trial in Ebola, including additional details on its design, endpoints, and objectives. The Phase 2a trial began treating patients with NV-387 in the Democratic Republic of Congo (DRC) in late September. The company reported that enrollment is continuing, with data expected in 1Q27.
Stages Of Infection Are Emerging. The current outbreak of Ebola virus disease (EVD) in the DRC has been caused by a new variant of the Bundibugyo Ebolavirus (BDBV). The development of symptoms varies between patients, and its diagnosis is still being refined. During the first 5 to 7 days after initial infection, mild symptoms may not even be noticeable. Patients typically seek treatment after about 5 to 7 days, when they begin vomiting and have severe diarrhea. The trial is expected to enroll most patients at this stage.
Ocugen (OCGN/$0.84 | Price Target: $12) Robert LeBoyer [email protected] | (212) 896-4625 Ocugen Completes Licensing Agreement For MENA Region Rating: OUTPERFORM
Licensing Agreement Finalizes Terms Announced In July. Ocugen and Roots Pharmaceuticals have finalized a licensing agreement for the commercialization of OCU400 in the Middle East and North Africa. The license finalizes the terms that the two companies announced in July 2026. This advances Ocugen’s plan to market OCU400 worldwide.
Collaboration Covers A Large Territory. The agreement gives Kuwait-based Roots Pharmaceuticals and its strategic partner, Al-Dhow International Holding, exclusive rights for the Middle East and North Africa coastal countries (MENA region). Retinitis pigmentosa (RP) is estimated to have a higher incidence in this region than in the US and Europe, although we cannot project sales at this time.
Deako. SKYX Platforms has closed the merger with Deako, Inc., which we first covered in our September 11th report. As we noted then, the merger enables SKYX to offer an A-to-Z AI and smart home plug-and-play solution for homes and buildings. The merger significantly expands SKYX’s addressable market and also opens additional avenues of cross-selling opportunities for both companies, in our view.
New Pipeline Details. SKYX noted the combined Company pipeline is over 4 million units with an expected average selling price of approximately $50/product, suggesting a $200 million+ current pipeline. With cross-selling opportunities, SKYX’s full product line is expected to create an opportunity to increase Deako’s revenue per home by up to fivefold; we expect to see strong pipeline growth going forward. And there is the opportunity to cross-sell Deako products into SKYX’s existing projects.
Noble Capital Markets Research Report Wednesday, October 14, 2026
Companies contained in today’s report:
Aurania Resources (AUIAF)/OUTPERFORM – Drilling Completed at Thor’s Valley; Assays Expected in November AZZ (AZZ)/OUTPERFORM – Record Earnings Drive Increased Guidance
Aurania Resources (AUIAF/$0.13 | Price Target: $0.3) Mark Reichman [email protected] | (561) 999-2272 Drilling Completed at Thor’s Valley; Assays Expected in November Rating: OUTPERFORM
2026 drilling program completed. Aurania completed eight diamond drill holes totaling 780.7 meters at its Thor’s Valley gold-silver project in Iceland, compared with six holes originally planned. The program included six holes twinning historical drilling, one drilled in the same direction as a historical hole but at a different inclination, and a step-out hole 50 meters northwest of the historic area. The program was intended to confirm historical results and assess the continuity and extent of mineralization. Assay results are expected in November 2026.
Core recovery improves geological confidence. Aurania achieved nearly 100% core recovery in most holes, compared with approximately 50% or less historically. Using HQ3 diamond drilling, the company recovered fragmented, clay rich vein material frequently lost during earlier programs. More representative samples should improve the assessment of historical gold grades and mineralized widths.
AZZ (AZZ/$136.71 | Price Target: $170) Mark Reichman [email protected] | (561) 999-2272 Record Earnings Drive Increased Guidance Rating: OUTPERFORM
Q2 FY 2027 Financial Results. AZZ reported adj. net income of $60.1 million, or $2.00 per share, versus $46.9 million, or $1.55 per share, a year ago. Results exceeded our estimates of $54.9 million, or $1.81 per share, by 9.5% and 10.5%, respectively. Revenue increased 16.7% to a record $486.9 million, while adj. EBITDA rose 25.0% to $110.9 million, exceeding our $101.6 million estimate. Adj. EBITDA margin expanded 150 basis points to 22.8%. Metal Coatings revenue increased 22.9% to $233.5 million, while Precoat Metals revenue rose 11.5% to $253.4 million. Segment adj. EBITDA margins were 30.7% and 21.2%, respectively.
FY 2027 Corporate Guidance Raised. Reflecting strong performance and sustained sales momentum, management raised FY 2027 revenue guidance to $1.825–$1.875 billion from $1.800–$1.850 billion. Adj. EBITDA guidance increased to $380–$420 million from $375–$415 million, while adj. EPS guidance rose to $7.00–$7.30 from $6.75–$7.15. The revised outlook reflects contributions from the new Washington, Missouri facility, improved operations, and lower interest expense. Capital expenditures are expected to total $80–$100 million, with debt reduction of $100–$140 million.
Noble Capital Markets Research Report Thursday, October 8, 2026
Companies contained in today’s report:
Alliance Resource Partners (ARLP)/OUTPERFORM – Coal Operations Anchor Cash Flow as Oil and Gas Royalties Expand Resources Connection (RGP)/OUTPERFORM – Pricing Holds as the Recovery Remains Elusive Xcel Brands (XELB)/OUTPERFORM – Performance-Based Partnership Could Accelerate Royalty Growth
Alliance Resource Partners (ARLP/$24.65 | Price Target: $33.5) Mark Reichman [email protected] | (561) 999-2272 Coal Operations Anchor Cash Flow as Oil and Gas Royalties Expand Rating: OUTPERFORM
Coal fundamentals support a constructive outlook. Alliance Resource Partners is the second-largest coal producer in the eastern United States and benefits from a competitive cost structure and strong earnings visibility based on contracted sales. More than 99% of expected 2026 coal volumes are committed and priced, while approximately 85% of anticipated 2027 volumes are contracted. Growing electricity demand and a more supportive regulatory environment could extend coal-fired power plant lives and strengthen demand for thermal coal.
Royalties strengthen the growth profile. Alliance continues to expand its high-margin oil and gas royalty business, supported by more than $1 billion invested in mineral interests. The recent $206.2 million AllDale acquisition expanded its portfolio to approximately 115,680 net royalty acres, including more than 44,770 acres in the Permian Basin. We expect royalties to contribute increasingly to earnings and cash flow without the capital requirements of operated properties.
Resources Connection (RGP/$2.99 | Price Target: $6) Joe Gomes [email protected] | 561-999-2262 Pricing Holds as the Recovery Remains Elusive Rating: OUTPERFORM
Overview. Resources Connection’s first-quarter results were within management’s revenue and gross margin outlook, while lower operating expenses helped profitability exceed our July projections. However, the Company has yet to demonstrate sustained revenue improvement. We believe pricing discipline and ongoing cost actions provide a foundation for recovery, but weak consultant utilization and recent cash consumption leave less room for an extended turnaround.
1Q27 Results. Revenue was $98.1 million compared to $120.2 million in 1Q26 and our $100 million estimate. Adjusted EBITDA was a loss of $3.6 million compared to $3.1 million in 1Q26 and our projected $5.5 million loss. Adjusted net loss was $0.16/sh. versus EPS of $0.03 in 1Q26 and our $0.22/sh. loss estimate. The earnings improvement relative to our forecast is encouraging, although it does not change the need for higher billable activity.
Xcel Brands (XELB/$0.64 | Price Target: $5) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | Performance-Based Partnership Could Accelerate Royalty Growth Rating: OUTPERFORM
An important evolution of the creator-commerce model. Xcel Brands announced a partnership with Paradium.AI to launch PetHelpful x Trust·Respect·Love by Cesar Millan, combining Parade’s extensive digital publishing network with Cesar Millan’s global recognition and authentic content. We believe the collaboration marks an important evolution in Xcel’s strategy, leveraging AI-powered content to convert strong consumer awareness into retail sales.
A compelling performance-based marketing model. Paradium.AI commits significant marketing resources through its media platforms to participating retailers at no cost, while Paradium.AI, Cesar Millan, and Xcel share performance-based royalties. We believe this creates an attractive proposition for retailers by providing substantial promotional support while aligning all parties’ interests around generating sales.
Noble Capital Markets Research Report Thursday, October 8, 2026
Companies contained in today’s report:
MAIA Biotechnology (MAIA)/OUTPERFORM – Patient Enrollment Completed In THIO-101, Enrollment Milestone Reached In THIO-104
MAIA Biotechnology (MAIA/$1.18 | Price Target: $14) Robert LeBoyer [email protected] | (212) 896-4625 Patient Enrollment Completed In THIO-101, Enrollment Milestone Reached In THIO-104 Rating: OUTPERFORM
MAIA Reported Two Important Clinical Trial Milestones. MAIA announced the completion of enrollment for the Part C Expansion Stage of the THIO-101 trial. This part of THIO-101 has enrolled 150 patients. Separately, the Phase 3 THIO-104 trial reached enrollment of 65 patients, putting it on schedule to enroll 100 patients by YE2026. Reaching the full-year enrollment goal could allow an interim analysis in FY2027.
Results From THIO-101 Part C Have Been Positive To Date. As discussed in our Research Note on September 22, MAIA recently announced initial efficacy data from the THIO-101 Part C. The evaluable population, consisting of patients with at least one post-treatment evaluation by tumor scan, showed a disease control rate (DCR) of 90.5%. This far exceeds published studies that show a 25%–35% DCR for standard third-line chemotherapy regimens.
Noble Capital Markets Research Report Wednesday, October 7, 2026
Companies contained in today’s report:
Beasley Broadcast Group (BBGI)/OUTPERFORM – Positioning For The Next Step Conduent (CNDT)/OUTPERFORM – Transit Sale Closes; Deleveraging Story Advances Lucky Strike Entertainment (LUCK)/OUTPERFORM – Q1 Headwinds, Full-Year Outlook Intact The GEO Group (GEO)/OUTPERFORM – To Redeem Debt, Extend Credit Facility
Beasley Broadcast Group (BBGI/$10.07 | Price Target: $28) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | Positioning For The Next Step Rating: OUTPERFORM
Revising estimates. We are lowering our second-half 2026 revenue expectations to reflect a softer advertising environment, including lower expectations for core and political advertising. We now forecast Q3 revenue of $42.7 million and adjusted EBITDA of $3.9 million, followed by Q4 revenue of $49.5 million and adjusted EBITDA of $6.5 million.
Cost reductions are providing support. Despite the challenging revenue environment, we believe Beasley’s significantly lower operating cost structure is beginning to meaningfully benefit profitability. We forecast full-year 2026 revenue to decline 13.1% to $178.9 million, while adjusted EBITDA increases 45.2% to $15.3 million and the adjusted EBITDA margin expands to 8.5% from 5.1% in 2025.
Conduent (CNDT/$1.62 | Price Target: $5) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | Transit Sale Closes; Deleveraging Story Advances Rating: OUTPERFORM
Transit sale completed. Conduent completed the previously announced sale of its public transit and fare collection business to Modaxo on October 1. In our view, the closing represents another important step in the company’s efforts to simplify its portfolio, reduce financial leverage, and focus resources on its core Commercial and Government businesses.
$125 million earmarked for debt reduction. Conduent received $140 million in cash consideration at closing and expects to use $125 million of net proceeds to repay borrowings under its revolving credit facility. We view the debt reduction favorably and believe the improved balance sheet should enhance the company’s financial flexibility as management executes its ASCEND strategy.
Lucky Strike Entertainment (LUCK/$5.29 | Price Target: $14.5) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | Q1 Headwinds, Full-Year Outlook Intact Rating: OUTPERFORM
Q1 expectations reset. We are lowering our fiscal Q1 revenue and adj. EBITDA forecasts to $299.0 million and $72.5 million, down from $307.0 million and $77.0 million, respectively. The revision largely reflects softer-than-expected water-park results due to unfavorable weather, pricing, and season-pass decisions, as well as lingering disruption from the World Cup.
Water-park weakness appears fixable. While weather and an aggressive, roughly 30% price increase pressured attendance, per-capita spending improved, and labor costs declined. Management plans to recalibrate pricing, start selling season passes earlier, and further optimize admissions to position the parks for improved performance next season.
The GEO Group (GEO/$29.94 | Price Target: $40) Joe Gomes [email protected] | 561-999-2262 To Redeem Debt, Extend Credit Facility Rating: OUTPERFORM
Debt Redemption. The GEO Group is redeeming all of its $650 million 8.625% Senior Secured Notes due in 2029. The redemption will be funded from net proceeds of the facility sale announced Monday. We view this as a significant positive for the Company, reducing outstanding debt, eliminating interest payments, and setting the Company up to be more aggressive in its share repurchase program.
Details. The redemption price for the 2029 Senior Secured Notes will be equal to $1,043.13 per $1,000.00 original principal amount, or approximately $678 million, plus any accrued and unpaid interest. GEO is receiving a net $705 million from the facility sale and had another $55 million of cash on the balance sheet as of June 30th. The redemption of the 2029 Senior Secured Notes will occur on October 15, 2026. GEO will save some $56 million in annual interest expense.
Noble Capital Markets Research Report Tuesday, October 6, 2026
Companies contained in today’s report:
Alliance Entertainment Holding (AENT)/OUTPERFORM – Building A Higher-Margin Entertainment Platform NN (NNBR)/OUTPERFORM – A Deeper Look Into the Implications of the PIPE Transaction Tectonic Metals Inc. (TETOF)/OUTPERFORM – Preparing for the Next Phase of Growth The GEO Group (GEO)/OUTPERFORM – A Sale; Increased Buyback Authorization
Alliance Entertainment Holding (AENT/$4.69 | Price Target: $9) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | Building A Higher-Margin Entertainment Platform Rating: OUTPERFORM
Noble Virtual Conference Highlights. On October 1, 2026, Bruce Ogilvie, Executive Chairman of Alliance Entertainment, presented at Noble’s October Virtual Emerging Growth Conference. The presentation highlighted an optimistic outlook for fiscal 2027 and opportunities to expand margins through licensing, collectibles, authentication, and fulfillment. A replay is available here.
Favorable revenue and margin expansion outlook. Management expects continued revenue growth and margin expansion in fiscal 2027, supported by continued demand for physical media products and a full year of the company’s high-margin licensing deal with Amazon MGM. Additionally, the company’s return to direct movie sales to Walmart eliminates third-party intermediary fees and restores access to supply chain financing, supporting faster cash collection and higher margins. Management expects the full benefit to become more apparent in fiscal Q2.
NN (NNBR/$4.24 | Price Target: $6) Joe Gomes [email protected] | 561-999-2262 A Deeper Look Into the Implications of the PIPE Transaction Rating: OUTPERFORM
Transaction. As noted, NN is eliminating its outstanding Preferred stock, which will eliminate the associated dividends that cost the Company approximately $19 million in 2025. NN issued 11.3 million shares in the PIPE transaction and an additional 4.8 million pre-funded warrants. Eliminating the dividends and increasing the share count would lower our 4Q26 estimated loss per share to $0.03 from a prior $0.06. The elimination of $122.1 million of outstanding preferred stock as of June 30th significantly improves NN’s capital structure.
Term Loan. At the end of June, NN had $133.5 million outstanding under its term loan facility at a 13.5% interest rate. We believe the elimination of the preferred, along with solid operating performance, gives management the opportunity to refi the term debt at a lower rate. For illustrative purposes, reducing the interest rate to 10% from 13.5% would save the Company $4.6 million in annual interest costs, or about $0.04/sh, based on 100 million shares outstanding.
Tectonic Metals Inc. (TETOF/$1.32 | Price Target: $3.5) Mark Reichman [email protected] | (561) 999-2272 Preparing for the Next Phase of Growth Rating: OUTPERFORM
Senior leadership team appointment. Effective October 1, Tectonic appointed Mr. Eduard Epshtein, CPA, CA, as Chief Financial Officer and Corporate Secretary. Mr. Epshtein has more than 20 years of capital markets, project development, transactions, and corporate finance experience, including 16 years as Chief Financial Officer of Lithium Americas (NYSE: LAC, TSX: LAC). During his tenure, Lithium Americas evolved from an exploration-stage company into a NYSE-listed producer with a market capitalization exceeding US$5 billion.
Experience aligned with Tectonic’s next phase. We view the appointment positively given Mr. Epshtein’s experience advancing major resource projects from exploration through construction and production. His experience with project finance, strategic partnerships, joint ventures, offtake arrangements, M&A, and corporate governance should become increasingly relevant as Tectonic moves Flat from exploration toward resource definition and economic evaluation.
The GEO Group (GEO/$32.34 | Price Target: $40) Joe Gomes [email protected] | 561-999-2262 A Sale; Increased Buyback Authorization Rating: OUTPERFORM
Facilities Sale. The GEO Group has sold its Adelanto, California ICE Processing Center complex to the Federal government for $950 million, or a net of $705 million. This is the first facility sale by GEO to the Department of Homeland Security and follows similar transactions earlier this year by competitor CoreCivic to DHS. The sale provides a solid foundation for the value of GEO’s assets in our view.
Details. The Adelanto complex consists of 3 buildings with a total of 2,644 beds. On a consolidated basis, the sale price equates to over $359,000/bed. GEO expects to continue providing support services to the Federal government at these locations under the existing contract agreement, although we would expect some changes to the contract as GEO no longer owns the facilities. The current contract runs through mid-December 2029 with a 5-year option period.
Noble Capital Markets Research Report Monday, October 5, 2026
Companies contained in today’s report:
NN (NNBR)/OUTPERFORM – Another Milestone In Cleaning Up The Capital Structure Sky Harbour Group (SKYH)/OUTPERFORM – Noble October Virtual Conference. SKYX Platforms (SKYX)/OUTPERFORM – Noble October Virtual Conference Star Equity Holdings, Inc. (STRR)/OUTPERFORM – Noble October Virtual Conference Vince Holding Corp. (VNCE)/OUTPERFORM – OVO Growth Roadmap Comes Into Focus
NN (NNBR/$4.51 | Price Target: $6) Joe Gomes [email protected] | 561-999-2262 Another Milestone In Cleaning Up The Capital Structure Rating: OUTPERFORM
Capital Structure. On Friday, NN announced it had entered into a securities purchase agreement for a private investment in public equity financing (PIPE) that is expected to result in net proceeds of approximately $50 million. A majority of the proceeds will be used to eliminate the outstanding Series D preferred stock. NNBR shares rose 24% on the news, closing at $4.51. We view Friday’s announcement positively, placing NN in a much stronger financial position to pursue extensive growth opportunities.
Details. NN will issue an aggregate of 16.1 million shares of common stock (or prefunded warrants in lieu thereof) at a price of $3.30 per share (or $3.29 per pre-funded warrant). Each pre-funded warrant has an exercise price of $0.01 per share of common stock and will be immediately exercisable. There are 10 investors making this investment, a mix of existing shareholders and new shareholders. The deal was significantly oversubscribed. The deal is expected to close on October 5th.
Macro Tailwinds. The total square footage of the aviation fleet continues to increase, driven by an increased number of aircraft operating-driven by both business and consumer demand-and the increasing size of the aircraft fleet. U.S. Business-Class total square footage, Sky Harbour’s target market, has risen by 73% over the past 15 years. On the supply side, no new major airports have been built since the early 1990s. The available land at or surrounding airports continues to shrink.
Deako Acquisition. Management does expect cost synergies, but the larger piece of the pie, in our view, is the ability to provide an A-to-Z solution across the electronic real estate of homes, buildings, and hotels, where power, control, sensing, and AI intelligence will reside. The combination will put SKYX at the forefront of data sharing in smart home systems, opening multiple high-margin revenue opportunities, in our opinion.
Harte Hanks. Harte Hanks has completed its go-shop period, and while other proposals were received, the Harte Hanks Board has not determined that any proposal constitutes a Superior Proposal to the Star proposal. Mr. Eberwein noted that both companies are moving forward to complete the announced deal, hopefully by year-end.
Vince Holding Corp. (VNCE/$10.5 | Price Target: $14) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | OVO Growth Roadmap Comes Into Focus Rating: OUTPERFORM
Insights From Noble’s Emerging Growth Conference. We recently hosted Vince Holding Corp. CEO Brendan Hoffman and CFO Yuji Okumura for a fireside chat at Noble Capital Markets’ Emerging Growth Virtual Equity Conference. The discussion provided additional insight into the strength of the core Vince business and, importantly, management’s strategy to leverage its operating platform to accelerate growth at the recently acquired OVO business. Click here to view the presentation. Vince participated in the conference on October 2.
Core Vince Momentum Remains Healthy. We believe the underlying Vince business remains on solid footing, supported by strength across both direct-to-consumer and wholesale. Second-quarter revenue rose 11.7% to $81.8 million, with DTC up 13.7% and wholesale up 10.4%, providing a solid foundation as management begins integrating OVO.
Noble Capital Markets Research Report Thursday, October 1, 2026
Companies contained in today’s report:
Conduent (CNDT)/OUTPERFORM – Laying Out the Path to Profitable Growth Kodiak Copper Corp. (KDKCF)/OUTPERFORM – Kay Copper Advances Resolution Minerals Ltd (RML)/OUTPERFORM – Horse Heaven Advances on Multiple Fronts
Conduent (CNDT/$1.56 | Price Target: $5) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Laying Out the Path to Profitable Growth Rating: OUTPERFORM
A clearer path forward. At its Investor Day held on September 30 in New York, Conduent outlined ASCEND 2026-28, a three-year framework to transition the company from restructuring and portfolio simplification to consistent, profitable growth. The strategy centers on three priorities: Standardize operations and infrastructure, Specialize in core solutions, and Scale the company’s go-to-market capabilities.
Targets provide visibility through 2028. Management expects revenue of $2.15 billion-$2.25 billion in both 2026 and 2027, increasing to $2.25 billion-$2.35 billion in 2028. Adjusted EBITDA is expected to increase from $140 million-$170 million in 2026 to $170 million-$200 million in 2027 and $210 million-$250 million in 2028, with meaningful margin expansion anticipated.
Kodiak Copper Corp. (KDKCF/$0.49 | Price Target: $1.5) Mark Reichman [email protected] | (561) 999-2272 Kay Copper Advances Rating: OUTPERFORM
Transaction moves toward closing. Kodiak Copper has filed the initial TSX Venture Exchange listing application for Kay Copper and executed definitive agreements covering the combination of Kodiak’s Mohave project with Teck’s Copper Hill project in Arizona. The transaction is intended to create a well-funded, U.S.-focused copper explorer with two drill-ready porphyry projects. Completion is expected in October 2026, subject to TSX Venture Exchange (TSXV) acceptance and other customary closing conditions.
Financing is in place. In connection with the transaction, approximately C$5.37 million was raised through a subscription receipt financing at C$0.25 per receipt, in addition to an earlier C$830,000 financing. The proceeds are intended to fund exploration at Mohave and Copper Hill during 2026 and 2027. Following closing, Kodiak and Teck are each expected to own approximately 26.4% of Kay Copper.
Horse Heaven takes center stage. In fiscal 2026, Resolution Minerals repositioned the company around its 100%-owned Horse Heaven Antimony-Tungsten-Gold-Silver Project in Idaho following its acquisition in July 2025. During the year, Resolution initiated and expanded drilling, made gold discoveries at Golden Gate North and South, advanced the high-grade Antimony Ridge system, acquired the Johnson Creek processing site and historical tungsten stockpiles, and initiated metallurgical programs across gold, antimony, and tungsten.
Golden Gate continues to expand. Following the June 30 fiscal year-end, Resolution completed its 2026 Golden Gate drilling program with 42 diamond holes totaling 12,236 meters. Recent assays from Golden Gate South extended the mineralized zone to approximately 600 meters in width and returned the highest gold grades reported to date at Horse Heaven, including one meter grading 14.8 g/t Au and 10.2 meters grading 1.83 g/t Au. Assays remained pending for 36 holes, providing a pipeline of additional results.
Noble Capital Markets Research Report Wednesday, September 30, 2026
Companies contained in today’s report:
1-800-Flowers.com (FLWS)/OUTPERFORM – Sharpening the Focus Power Metallic Mines Inc. (PNPNF)/OUTPERFORM – Deep Drilling Extends Lion Zone at Depth Unicycive Therapeutics (UNCY)/OUTPERFORM – Unicycive Announces NDA Resubmission For OLC, Ahead Of Our Expected Timeframe
1-800-Flowers.com (FLWS/$2.6 | Price Target: $5) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Sharpening the Focus Rating: OUTPERFORM
Portfolio simplification. FLWS agreed to sell PersonalizationMall and Things Remembered to PlanetArt for approximately $45 million. We believe the transaction advances management’s strategy to simplify the business and concentrate resources behind its core brands and higher-return growth opportunities. The transaction is expected to close within the next several weeks.
Debt amendment increases flexibility. Importantly, a recent amendment to the credit agreement allows FLWS to retain a portion of the sale proceeds rather than directing the entire amount toward debt reduction. We estimate that roughly $22.5 million will reduce term debt, while approximately $22.5 million will be available to reinvest in the business.
Power Metallic Mines Inc. (PNPNF/$0.81 | Price Target: $2) Mark Reichman [email protected] | (561) 999-2272 Deep Drilling Extends Lion Zone at Depth Rating: OUTPERFORM
Deep drilling expands the Lion Zone. Power Metallic recently released new drill results that extend the known depth of the Lion Zone, with Hole PML-26-125 intersecting 5.70 meters grading 14.00% copper equivalent recovered (CuEqRec) at nearly 800 meters vertical depth. The intercept was drilled roughly 150 meters below the previous deepest high-grade hole and lies well beneath the limits of the recently announced mineral resource estimate, providing additional evidence that Lion remains open at depth.
Grades remain strong below the current resource. Hole PML-26-125 returned 11.42% copper within the broader 5.70-meter interval, including 2.15 meters grading 24.62% CuEqRec and 20.30% copper. A second hole, PML-26-121a, intersected 7.70 meters grading 3.28% CuEqRec, including 1.70 meters at 11.93% CuEqRec. Together, the results suggest that high-grade copper-platinum group elements (PGE) mineralization continues below the current resource envelope rather than tapering out at depth.
Unicycive Therapeutics (UNCY/$4.55 | Price Target: $40) Robert LeBoyer [email protected] | (212) 896-4625 Unicycive Announces NDA Resubmission For OLC, Ahead Of Our Expected Timeframe Rating: OUTPERFORM
NDA For OLC Has Been Resubmitted. Unicycive has resubmitted its NDA (New Drug Application) for OLC (oxylanthanum carbonate) to control phosphate levels in patients with chronic kidney disease (CKD) on dialysis. Typically, the FDA accepts the submission for filing within 30 days and provides a PDUFA date, the statutory date for the agency to respond. This date is expected to be six months later, for a PDUFA date around March 30, 2026.
An Alternate Manufacturing Vendor Has Been Added. The resubmission included CMC (Chemistry, Manufacturing, and Controls) product data from a new third-party manufacturing vendor similar to the original vendor, including OLC manufacturing and 12-month stability studies. The NDA also includes data from bridging studies showing the vendors’ products are equivalent, as recommended by the FDA.
A New Task Order. DLH has been awarded a task order to provide risk management framework and cybersecurity operations support services to the National Institutes of Health (“NIH”) Center for Information Technology (“CIT”). CIT provides the NIH community with a secure and reliable IT infrastructure in support of its mission-critical research activities. In our view, not only does the award expand DLH’s support for NIH, but the award aligns with management’s strategy to grow technology-powered solutions in core markets.
Details. Notably, the task order is new work for DLH. The award has a potential value of $19.1 million inclusive of all option periods. The base period and multiple options aggregate to a three-year period of performance. This new business comes hot on the heels of recent awards for DLH, supporting our thesis that the multi-year lull in awards has broken. We anticipate DLH to continue to win its fair share of business going forward.
Noble Capital Markets Research Report Monday, September 28, 2026
Companies contained in today’s report:
CoreCivic, Inc. (CXW)/OUTPERFORM – A CEO Transition Metals & Mining (Metals & Mining) – Observations from the 2026 Precious Metals Summit Ocugen (OCGN)/OUTPERFORM – New Designations In The Bahamas To Lead To First Commercial Approval For OCU400
CoreCivic, Inc. (CXW/$32.13 | Price Target: $42) Joe Gomes [email protected] | 561-999-2262 A CEO Transition Rating: OUTPERFORM
Transition. On Friday, CoreCivic announced that Patrick Swindle was stepping down as President and Chief Executive Officer due to health reasons. Mr. Swindle also resigned from CoreCivic’s Board. The Board named Lucibeth N. Mayberry as President and Chief Executive Officer of the Company. Ms. Mayberry also joined the Board. We believe CoreCivic’s deep bench of executives should make this a seamless transition.
Ms. Mayberry’s Background. Ms. Mayberry has served as the Executive Vice President and Chief Strategy Officer since May 2025. From October 2022 to May 2025, Ms. Mayberry served as the Executive Vice President and Chief Innovation Officer. Prior to assuming that role, Ms. Mayberry served as Executive Vice President, Real Estate from May 2015 until October 2022. She has previously served in various roles at CoreCivic since May 2003, including as Vice President, Deputy Chief Development Officer; Vice President, Research, Contract and Proposals; and Managing Director, State Partnership Relations.
Ocugen (OCGN/$1.02 | Price Target: $12) Robert LeBoyer [email protected] | (212) 896-4625 New Designations In The Bahamas To Lead To First Commercial Approval For OCU400 Rating: OUTPERFORM
First Commercialization Could Be Coming Soon. Ocugen has received Provisional Approval and Priority Designation from the Bahamian government for OCU400. Ocugen can now supply OCU400 through an Expanded Access Program (EAP). If the first patient is treated within 90 days, OCU400 will receive full regulatory approval, allowing for commercialization in Retinitis Pigmentosa (RP). We see this as a significant regulatory and commercial milestone.
Regulatory Approval Is More Significant Than Potential Sales. This would be the first approval to allow commercial sales of OCU400. While some countries allow compassionate-use treatments before approval at the company’s break-even cost, Ocugen will be allowed to charge full price and earn profit on the treatments. We expect only a handful of patients to be treated in the coming quarters and do not expect a material impact on quarterly Net Losses, as the company has three late-stage clinical trials in progress at this time.
Metals & Mining Industry Report Mark Reichman [email protected] | (561) 999-2272 Observations from the 2026 Precious Metals Summit
Precious Metals Summit. Weattended the Precious Metals Summit last week at the Beaver Creek Resort in Colorado. While strong increases in metal prices led to exceptional investment returns in 2025, returns have moderated in 2026. Year-to-date through September 25, mining companies (as measured by the XME) appreciated 4.6% compared to a gain of 13.1% for the S&P 500 Index. The VanEck Vectors Gold Miners (GDX) and Junior Gold Miners (GDXJ) ETFs were up 8.3% and 6.4%, respectively. While metals prices remain strong, gold, silver, nickel, and lead prices have retreated modestly since the end of last year, while copper and zinc prices have continued to advance. While rising rate expectations may pose a headwind for gold, an uncertain geopolitical environment and other factors may provide an offset.
Investors are more discerning. Sentiment remains constructive, supported by strong metals prices, robust industry cash flows, and continued institutional interest in the sector. Conference participation was strong, including executive teams from over 225 mining companies and a broad mix of institutional investors, sell-side brokerage firms, and other industry participants. Investors appear to be increasingly focused on companies with scale, grade, strong metallurgy, manageable capital requirements, and an identifiable path for converting exploration success into economic value
Get the Full Report
Noble Capital Markets Research Report Thursday, September 24, 2026
Companies contained in today’s report:
NanoViricides (NNVC)/OUTPERFORM – Phase 2 Clinical Trial For HV-387 In MPox Begins NN (NNBR)/OUTPERFORM – Raises Full Year Revenue and Adjusted EBITDA Guide V2X (VVX)/OUTPERFORM – Follow-on Award
NanoViricides (NNVC/$1.51 | Price Target: $6) Robert LeBoyer [email protected] | (212) 896-4625 Phase 2 Clinical Trial For HV-387 In MPox Begins Rating: OUTPERFORM
Phase 2 Trial Patient Enrollment Has Started. NanoViricides has begun enrolling patients in the Phase 2 clinical trial testing NV-387 for MPox Virus Infection in the Democratic Republic of Congo (DRC). This meets our expected timeframe for the start of the trial, with preliminary results expected in late 4Q26. We anticipate a second trial testing NV-387 to start shortly in the same region.
Phase 2 Trial Design. The trial is an open-label study designed to evaluate the efficacy and safety of NV-387 compared with the standard of care. The trial is being conducted in Lodja, Sankuru Province, DRC, a remote province not (yet) affected by the Ebola outbreaks seen in other regions. NV-387 is formulated as an oral solid (gummies) that does not require refrigeration or cold storage, making it practical to administer in remote regions.
NN (NNBR/$3.86 | Price Target: $6) Joe Gomes [email protected] | 561-999-2262 Raises Full Year Revenue and Adjusted EBITDA Guide Rating: OUTPERFORM
A Raise. For the third time in 2026, NN management raised full-year guidance, reflecting the positive momentum of the business, in our view. Full-year revenue is now expected to be in the $470-$490 million range, with adjusted EBITDA now projected to be in the $58-$68 million range, up from a prior $460-$480 million and $55-$65 million, respectively. Initial 2026 guidance called for revenue in the $445-$465 million range and adjusted EBITDA in the $50-$60 million range.
Management Commentary. NN management noted, “Our business continues to build momentum as we ramp up in our key growth markets of Data Center, Defense & Electronics, and Medical, where demand for our solutions remains strong and actively expanding. Our year-to-date results and year-to-go forecast underpin this improved guidance and reflect the steady performance of our growth and cost programs.”
V2X (VVX/$74.94 | Price Target: $92) Joe Gomes [email protected] | 561-999-2262 Follow-on Award Rating: OUTPERFORM
Business. V2X continues to add business with a recent follow-on award from the Air Force for base support services and a position on an ID/IQ supporting the Air Force’s Carriage Equipment Production Effort for the Long Range Standoff (LRSO) cruise missile program. Such awards demonstrate V2X’s strong position to bid for and win new and expanded business, in our opinion.
Follow-on. The Department of War announced that V2X Systems has been awarded an undefinitized contract action with a not-to-exceed ceiling price of $231.8 million, a modification to a previously awarded contract for base support services in support of the Iraq F-16 program. The modification brings the total cumulative face value of the contract to $594.2 million. Work will be performed at Martyr BG Ali Flaih Air Base, Iraq, and is expected to be completed by July 17, 2027. Foreign Military Sales funds in the amount of $115.9 million are being obligated at the time of award.
Noble Capital Markets Research Report Wednesday, September 23, 2026
Companies contained in today’s report:
Century Lithium Corp. (CYDVF)/OUTPERFORM – Advancing Plans for a Stand-Alone Merchant Chlor-Alkali Plant Eledon Pharmaceuticals (ELDN)/OUTPERFORM – Tegoprubart Extension Study Maintains Improvement Over Tacrolimus
Century Lithium Corp. (CYDVF/$0.18 | Price Target: $2.3) Mark Reichman [email protected] | (561) 999-2272 Advancing Plans for a Stand-Alone Merchant Chlor-Alkali Plant Rating: OUTPERFORM
Advancing a merchant chlor-alkali plant. Century Lithium plans to develop a commercial-scale chlor-alkali plant in the Western United States that would produce chlorine, hydrochloric acid, and sodium hydroxide from sodium chloride, water, and electricity. The plant is expected to initially produce at a rate of 300 short tons per day (st/d) of chlorine, with potential expansion to 600 st/d depending on regional demand and the supply needs of Angel Island.
Early offtake interest provides commercial support. Century has signed eight non-binding Memorandums of Understanding (MOUs) that could collectively fully utilize the plant’s initial production, while discussions with additional customers are ongoing. The company is evaluating sites in Nevada and Utah based on power, feedstock, rail access, permitting, and proximity to customers, with final site selection expected following completion of due diligence.
Eledon Pharmaceuticals (ELDN/$2.89 | Price Target: $10) Robert LeBoyer [email protected] | (212) 896-4625 Tegoprubart Extension Study Maintains Improvement Over Tacrolimus Rating: OUTPERFORM
Long-Term Data Updated At Transplant Conference. Eledon presented an update to the Phase 2 BESTOW Extension study at the International Congress of The Transplantation Society. Analysis up to 24 months after transplantation showed that patients treated with tegoprubart had statistically significant improvements in kidney function compared with patients treated with tacrolimus. Separately, tegoprubart has also received Fast Track designation from the FDA in the kidney transplant indication.
Updated Extension Study Data. Patients completing the BESTOW trial were entered into an Extension Stage to follow outcomes after the trial period ended. At 18, 21, and 24 months, tegoprubart patients had a higher eGFR of about 71 mL/min/1.73m2 compared with 58 mL/min/1.73m2 for tacrolimus, with differences that were statistically significant. Tegoprubart patients showed a continued improvement in eGFR after the trial, while tacrolimus patients showed a gradual but steady decline.
Noble Capital Markets Research Report Tuesday, September 22, 2026
Companies contained in today’s report:
MAIA Biotechnology (MAIA)/OUTPERFORM – Heading Into 4Q After Strong Clinical Progress Titan International (TWI)/OUTPERFORM – To Sell ITM Business
MAIA Biotechnology (MAIA/$1.33 | Price Target: $14) Robert LeBoyer [email protected] | (212) 896-4625 Heading Into 4Q After Strong Clinical Progress Rating: OUTPERFORM
Phase 2 Extension Stage Has Begun Treatment At US Sites. MAIA began treating patients at three US sites in the Part C Expansion Phase of its Phase 2 THIO-101 trial. The trial tests ateganosine (aka THIO) in non-small cell lung cancer (NSCLC) and had completed the planned patient enrollment at international sites worldwide. Two additional US sites are expected to open during 2026.
Initial Data Shows Consistent Efficacy. In June 2026, MAIA announced initial efficacy data from the ongoing Phase 2 THIO-101 Part C Expansion Stage. Patients with at least one post-treatment evaluation by tumor scan showed a disease control rate (DCR) of 90.5% in the evaluable population. We believe that data consistent with Parts A and B could allow the company to apply for Accelerated Approval and Priority Review.
Titan International (TWI/$7.36 | Price Target: $11) Joe Gomes [email protected] | 561-999-2262 To Sell ITM Business Rating: OUTPERFORM
A Sale. Titan International entered into an agreement to sell its Italtractor ITM undercarriage business. The sale is expected to generate cash value of approximately $285 million, which includes a $207 million initial purchase price, $6 million of potential earnout proceeds, $23 million of customary adjustments based on ITM’s net assets and financial position at closing, and $49 million of dividends, consisting of $38 million received in recent years and $11 million expected prior to closing. The deal is expected to close in early January.
Focus. We expect Titan to use the proceeds to sharpen its focus on the core global wheel and tire operations serving the agriculture, construction, and consumer markets. Investments are expected to be focused on the Company’s highest growth opportunities and may include the purchase of adjacent businesses. A portion of the proceeds may be used to reduce outstanding net debt, which totaled $413 million as of June 30th.
Noble Capital Markets Research Report Monday, September 21, 2026
Companies contained in today’s report:
Codere Online (CDRO)/OUTPERFORM – Adding the NFL to the Mexico Playbook Xerox Holdings Corporation (XRX)/OUTPERFORM – A Clearer Path Through the Turnaround
Codere Online (CDRO/$9 | Price Target: $16) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Adding the NFL to the Mexico Playbook Rating: OUTPERFORM
High-visibility NFL Agreement. Codere recently announced a multi-year agreement with the NFL, establishing it as the league’s Official Betting Partner in Mexico. In our view, the high-visibility partnership strengthens its presence in a key market, increases brand awareness, deepens customer engagement opportunities, and enhances brand credibility.
Details. The agreement is set to run for three years and includes annual sponsorship of one NFL game in Mexico City and Super Bowl sponsorship rights in Mexico. The agreement kicks off with the November 22, 2026, 49ers–Vikings matchup and Super Bowl LXI in Los Angeles in February 2027. The partnership also creates fan engagement opportunities through hospitality programs, VIP experiences, promotional events across multiple Mexican cities, and official NFL merchandise.
Xerox Holdings Corporation (XRX/$3.42 | Price Target: $5) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | A Clearer Path Through the Turnaround Rating: OUTPERFORM
Xerox Roadshow. On September 16th, Louis Pastor, CEO, Chuck Butler, CFO, and Greg Stein, SVP & Head of IR, presented to investors at a non-deal roadshow in St. Louis. The presentation highlighted the company’s turnaround strategy, focusing on its efforts to stabilize revenue, expand margins, and reduce debt.
Broadening the revenue base. Earlier this month, the company announced a strategic partnership with Flint Group Digital Xeikon to utilize its digital press technology in Xerox-branded products. The partnership bolsters Xerox’s position in the production print market by providing access to digital packaging, labels, and commercial print without the cost of developing the technology internally.
Noble Capital Markets Research Report Thursday, September 17, 2026
Companies contained in today’s report:
DLH Holdings (DLHC)/OUTPERFORM – $43.7 Million Follow-On Award First Phosphate Corp. (PHOS)/OUTPERFORM – SERV Adds a Significant New Export Credit Agency (ECA) Financing Component GeoVax Labs (GOVX)/OUTPERFORM – MVA Technology Platform Produces New Vaccine For Ebola Kodiak Copper Corp. (KDKCF)/OUTPERFORM – Advancing a District-Scale Copper-Gold Porphyry Project in British Columbia
DLH Holdings (DLHC/$3.99 | Price Target: $7) Joe Gomes [email protected] | 561-999-2262 $43.7 Million Follow-On Award Rating: OUTPERFORM
Follow-on Order. DLH has been awarded a task order to continue providing high-quality information technology services for the National Heart, Lung, and Blood Institute. DLH has performed on this mission since 2018. The task order, valued at up to $43.7 million, includes a base period and multiple options aggregating to a two-and-a-half-year period of performance. We view this most recent award as further confirmation that the backlog of contracts and task orders is being freed up which will benefit DLH going forward.
Details. Under this task order, DLH will build on its existing implementation of artificial intelligence for IT operations and automation to improve service efficiency, system reliability, data integrity, cybersecurity, and compliance- all strengths of DLH. The Company will provide services in support of approximately 2,000 NHLBI scientific and administrative employees and contractors.
First Phosphate Corp. (PHOS/$15.37 | Price Target: $25.5) Mark Reichman [email protected] | (561) 999-2272 SERV Adds a Significant New Export Credit Agency (ECA) Financing Component Rating: OUTPERFORM
Swiss support adds another financing layer. First Phosphate has received a Letter of Support from Swiss Export Risk Insurance (SERV) for approximately US$212.5 million in potential financing tied to Swiss machinery, equipment, goods, and services for the Bégin-Lamarche mine and processing facility. The contemplated financing is based on an assumed US$250 million eligible Swiss export contract, with SERV prepared to consider financing 85% of the contract value.
European and G7 support is converging around the project. The SERV announcement follows EIFO’s earlier letter of intent for up to €170 million in guaranteed financing support, while the Canadian government’s G7 Critical Minerals Resilience and Production Alliance announcement also highlighted Danish support for the Bégin-Lamarche mine and Italian financial and industrial support for First Phosphate’s downstream phosphoric acid facility. Switzerland is not a G7 member, but SERV’s participation adds another significant European state-backed export finance institution to a project already receiving support through G7-related initiatives.
GeoVax Labs (GOVX/$0.41 | Price Target: $10) Robert LeBoyer [email protected] | (212) 896-4625 MVA Technology Platform Produces New Vaccine For Ebola Rating: OUTPERFORM
BDBV Vaccine Construct Developed With GeoVax’s Proprietary Technology. GeoVax has developed a new vaccine construct against Bundibugyo virus (BDBV). This is the virus causing the Ebola Virus Disease (EVD) outbreak in the Democratic Republic of Congo (DRC), now the largest Ebola outbreak and the fastest-spreading outbreak in the DRC. We see this new vaccine construct as proof of principle for the GeoVax MVA technology platform and its ability to respond to infectious diseases with new vaccines.
We See This As An Example Of The MVA Technology Capabilities. GeoVax has proprietary technology based on the MVA (Modified Vaccinia Ankara) virus that it can use to develop and manufacture new vaccines. This technology provides a common foundation for developing new vaccines and responding to infectious disease outbreaks. Previous vaccines developed with the MVA technology platform can stimulate both antibody and cellular immune responses, resulting in long durability, high tolerability, and improved safety profiles.
Kodiak Copper Corp. (KDKCF/$0.52 | Price Target: $1.5) Mark Reichman [email protected] | (561) 999-2272 George Proost [email protected] | Advancing a District-Scale Copper-Gold Porphyry Project in British Columbia Rating: OUTPERFORM
A large copper resource with room to grow. We have initiated coverage of Kodiak Copper Corp. with an Outperform rating and a price target of C$2.10, or approximately US$1.50 per share. Kodiak’s 100%-owned MPD Copper-Gold Project in southern British Columbia contains 439.2 million tonnes of Indicated and Inferred Resources across seven deposits, all open to expansion. Resource growth and improved project definition could support a higher valuation against a favorable long-term outlook for copper.
Ketchan drilling supports higher-grade potential. Hole AG-26-019 returned 283.5 meters at 0.70% copper equivalent (CuEq) from 37.5 meters downhole, including 108 meters at 1.02% CuEq. The result highlights shallow mineralization that could improve the grade and confidence of the existing resource.
Noble Capital Markets Research Report Tuesday, September 15, 2026
Companies contained in today’s report:
GeoVax Labs (GOVX)/OUTPERFORM – GEO-MVA Phase 3 Trial Moves Forward With Laboratory Testing Agreement For Patient Samples
GeoVax Labs (GOVX/$0.43 | Price Target: $10) Robert LeBoyer [email protected] | (212) 896-4625 GEO-MVA Phase 3 Trial Moves Forward With Laboratory Testing Agreement For Patient Samples Rating: OUTPERFORM
Agreement With CEPI Lab Network Establishes Standardized Sample Testing. GeoVax announced an agreement with CEPI (Coalition for Epidemic Preparedness Innovations) to test patient samples from its Phase 3 GEO-MVA study through the CEPI Centralized Laboratory Network. CEPI is an internationally recognized laboratory network that uses standardized assays and laboratory methods. We see this as an important development that can provide reliable results for both regulatory approval and comparison with other therapeutics.
An Important Step For The GEO-MVA Trial. GeoVax reiterated its plan to begin its GEO-MVA immunobridging study in Mpox/smallpox in 4Q26. The trial is expected to enroll about 500 patients, with results expected in mid-2027. The EMA (European Medicines Agency) has given Scientific Advice stating that a single immune bridging study showing that an immune response elicited by the GEO-MVA vaccine is non-inferior to the approved vaccine would be sufficient to apply for approval from the European Union.
Noble Capital Markets Research Report Monday, September 14, 2026
Companies contained in today’s report:
Resolution Minerals Ltd (RML)/OUTPERFORM – Thoughts on the Golden Gate Drilling Program
Resolution Minerals Ltd (RML/$7.76 | Price Target: $30) Mark Reichman [email protected] | (561) 999-2272 Thoughts on the Golden Gate Drilling Program Rating: OUTPERFORM
Golden Gate 2026 drilling program. Resolution has completed its planned 2026 Golden Gate drilling program at the Horse Heaven Project in Idaho, completing 42 diamond core holes totaling 12,236 meters. The program, the largest exploration campaign undertaken at Horse Heaven, was designed to define the scale and extent of both gold and tungsten mineralization across Golden Gate North and the recently established Golden Gate South discovery. Core logging is complete, and final samples are being sent to the laboratory for analysis, leaving assay results from 39 of the 42 holes as the principal near-term catalyst.
Early results suggest a potentially large gold system. Results from the first three 2026 holes extended gold mineralization at least 2,000 meters south of Golden Gate North and established Golden Gate South as a new discovery. The strongest 2026 result reported to date was 305.7 meters grading 0.64 g/t gold from surface in Hole HH-GG26-003C, while the 2025 program returned higher-grade intervals including 189.2 meters at 1.30 g/t gold and 253 meters at 1.5 g/t gold. Along with a broad gold-in-soil anomaly between the two areas, the results provide increasing evidence that Golden Gate may represent a considerably larger mineralized system than initially recognized.
Noble Capital Markets Research Report Friday, September 11, 2026
Companies contained in today’s report:
1-800-Flowers.com (FLWS)/OUTPERFORM – Cost Reset Complete; Focus Shifts To Growth Alliance Entertainment Holding (AENT)/OUTPERFORM – Momentum Builds Into Fiscal 2027 SKYX Platforms (SKYX)/OUTPERFORM – Now Offering an A-to-Z Solution for the Smart Electronic Grid T3 Defense (DFNS)/OUTPERFORM – Another Award Tectonic Metals Inc. (TETOF)/OUTPERFORM – Chicken Mountain Drilling Expands Gold System Vince Holding Corp. (VNCE)/OUTPERFORM – Core Momentum Builds Ahead of OVO
1-800-Flowers.com (FLWS/$3.04 | Price Target: $5) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Cost Reset Complete; Focus Shifts To Growth Rating: OUTPERFORM
Q4 results reflect continued top-line pressure. Fiscal Q4 revenue declined 12.9% to $293.1 million, with Consumer Floral & Gifts down 13.4% and Gourmet Foods & Gift Baskets down 15.4%, partially offset by 1.9% growth at BloomNet. Adjusted EBITDA was a loss of $31.0 million compared with a loss of $24.2 million in the prior-year period, as revenue deleverage and cost pressures more than offset operating efficiencies.
Underlying trends provide signs of progress. Importantly, Consumer Floral & Gifts gross margin rose 220 basis points to 40.7%, while contribution margin remained relatively stable. Management also indicated that the flowers category is now generating positive sales on many days and weeks, providing early evidence that changes to merchandising, fulfillment, and the digital customer experience may be improving the underlying revenue trajectory.
Alliance Entertainment Holding (AENT/$5.51 | Price Target: $9) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Momentum Builds Into Fiscal 2027 Rating: OUTPERFORM
A strong finish to fiscal 2026. Fiscal Q4 revenue was $268.1 million, up 18% from the prior-year period, capping a solid year in which revenue increased 8% to $1.15 billion. Full-year adjusted EBITDA increased 14% to $41.5 million, while gross margin expanded 80 basis points to 13.3%, reflecting favorable product mix and improved operating performance.
Growth is broadening across the portfolio. Physical entertainment remained healthy, with fiscal 2026 vinyl revenue increasing 13%, CDs up 25%, and physical movies up 22%, supported by strong consumer demand and expanded studio relationships with Paramount and Amazon MGM. Higher-value businesses are also gaining traction, with collectibles revenue up 45% and distribution and fulfillment fees up 26%.
SKYX Platforms (SKYX/$1.32 | Price Target: $5) Joe Gomes [email protected] | 561-999-2262 Now Offering an A-to-Z Solution for the Smart Electronic Grid Rating: OUTPERFORM
Merger. Yesterday, SKYX Platforms announced an agreement to merge with Deako, Inc., a smart home AI platform and intelligent lighting company. The merger agreement between SKYX and Deako will enable SKYX to address from A-to-Z the smart electronic real estate of electrical outlet boxes in homes and buildings including wall outlets, wall switches, and ceiling outlet boxes for smart home and safety products, lighting, ceiling fans, smoke detectors, among others, all with advanced and smart home plug & play solutions.
Synergistic. Management does expect cost synergies, but the larger piece of the pie, in our view, is the ability to provide an A-to-Z solution across the electronic real estate of homes, buildings, and hotels, where power, control, sensing, and AI intelligence will reside. SKYX products will be introduced into Deako’s 50-plus home builders market, while Deako’s products will be introduced into SKYX’s existing projects, such as European hotels and the $4 billion Miami Smart City. We view this as a win-win for SKYX.
T3 Defense (DFNS/$9.84 | Price Target: $30) Joe Gomes [email protected] | 561-999-2262 Another Award Rating: OUTPERFORM
Award. Yesterday, T3 subsidiary Rimon announced receipt of a purchase order valued at $1.3 million from a leading Israeli defense prime contractor. The new award is further validation of management’s game plan to focus on mission-critical hardware and systems used in defense and counter-drone programs. The Company’s portfolio spans launcher systems, tactical mobility, power generation, positioning and navigation, command-and-control, and training and simulation capabilities that support the deployment, operation, and sustainment of layered defense architectures.
Details. Rimon will supply engineered power-generation systems for a European production line supporting a critical air-defense system. The equipment will be built and configured to the prime contractor’s specifications and the requirements of serial defense production, with deliveries scheduled for the customer’s European production facility. Notably, this is a production-line award, not a one-off delivery, which should result in additional volume not only from this customer but potentially from other customers.
Tectonic Metals Inc. (TETOF/$1.61 | Price Target: $3.5) Mark Reichman [email protected] | (561) 999-2272 Chicken Mountain Drilling Expands Gold System Rating: OUTPERFORM
Initial 2026 drilling results. Tectonic Metals reported the first assays from its 2026 program at Chicken Mountain, with results from 15 holes totaling 2,276 meters, demonstrating extensions of mineralization both at depth and along the southern margin. The strongest diamond hole, CMD26-036, returned 1.40 g/t gold (Au) over 30.00 meters, including 4.58 g/t Au over 4.50 meters, followed by a 118.16-meter interval grading 0.51 g/t Au that continued to the end of the hole. The result extends Central Corridor 2 to more than 300 meters of vertical depth and supports the interpretation of Chicken Mountain as a large, bulk-tonnage reduced intrusion-related gold system potentially amenable to heap-leach processing.
The mineralized footprint continues to grow. Approximately 1.2 kilometers south of Hole CMD26-036, step-out holes CMR26-141 and CMR26-142 extended the southernmost tested mineralization by approximately 200 meters, increasing its interpreted length to roughly 600 meters. Hole CMR26-142 returned 0.56 g/t Au over 38.10 meters, including 3.06 g/t Au over 4.57 meters, while Hole CMR26-141 intersected 0.31 g/t Au over 25.91 meters and ended in mineralization. The results confirm lateral continuity and expand the mineralized volume that could contribute to a maiden resource.
Vince Holding Corp. (VNCE/$5.03 | Price Target: $11) Michael Kupinski [email protected] | (561) 994-5734 Jacob Mutchler [email protected] | Core Momentum Builds Ahead of OVO Rating: OUTPERFORM
Strong Q2 Results. The company reported Q2 revenue of $81.8 million and adj. EBITDA of $18.0 million, both of which were above our estimates of $80.8 million and $6.8 million, respectively. Solid Q2 results were driven by double-digit revenue growth across DTC and wholesale channels, improved operating leverage, and a $10.4 million tariff refund benefit. Notably, when excluding the refund, adj. EBITDA was approximately $7.6 million, still above our estimate.
DTC and Wholesale Gain Momentum. Direct-to-Consumer (DTC) revenue increased 13.7% to $32.4 million, while wholesale revenue grew 10.4% to $49.4 million. DTC benefited from strength across stores and e-commerce, while an expanding full-price customer base and favorable demand for women’s and men’s collections supported both channels.
Noble Capital Markets Research Report Thursday, September 10, 2026
Companies contained in today’s report:
Century Lithium Corp. (CYDVF)/OUTPERFORM – Angel Island Permitting Advances Ocugen (OCGN)/OUTPERFORM – Interim Analysis Report Recommends Continuing Stargardt Phase 2/3 Trial, But Causes Confusion Resolution Minerals Ltd (RML)/OUTPERFORM – Nasdaq Listing Expands U.S. Investor Access
Century Lithium Corp. (CYDVF/$0.19 | Price Target: $3.05) Mark Reichman [email protected] | (561) 999-2272 Angel Island Permitting Advances Rating: OUTPERFORM
A major milestone. Century Lithium reached a major permitting milestone at its 100%-owned Angel Island Lithium Project in Nevada with the submission of its Mine Plan of Operations and Nevada Reclamation Permit Application. The Plan of Operations formally defines the proposed project for federal environmental review and moves Angel Island into the National Environmental Policy Act (NEPA) process.
Angel Island lithium project. Angel Island will be a large, long-life surface mine designed to produce battery-grade lithium carbonate on site. Development would be phased from approximately 8,300 tons per day during the first four years to as much as 16,500 tons per day from years five through 40, supported by direct lithium extraction, closed-loop water recycling, and significant power and water infrastructure.
The DMC Recommends Continuing The GARDian Trial. Data Monitoring Committee (DMC) has completed its planned interim analysis of the Phase 2/3 GARDian trial of OCU410ST in Stargardt disease. The analysis included 26 patients out of the planned enrollment of about 50, evaluating 16 treated patients and 10 controls. The DMC recommended continuing the trial as planned, with an evaluation of the entire patient population at 8 months after treatment. We believe the disclosure has led to misinterpretation of the recommendation.
The Evaluation Included Just Half The Enrollment In An Orphan-Sized Trial. Stargardt is an Orphan disease with a Phase 2/3 trial based on a small enrollment of about 50 patients. While this helps enrollment, each patient’s data has a larger impact than in larger trials.
Nasdaq listing enhances Resolution’s U.S. market presence. Resolution Minerals’ American Depositary Shares, or ADSs, commenced trading on the Nasdaq Capital Market on September 9, 2026, under the ticker RML. Each ADS represents 200 ordinary Resolution shares, while the ASX remains the company’s primary listing. Resolution did not conduct a U.S. capital raise in connection with the Nasdaq listing.
The listing supports Resolution’s broader U.S. strategy. We expect the Nasdaq listing to increase the company’s visibility among U.S. retail and institutional investors and strengthen its ability to raise capital in the United States. The timing is favorable given heightened U.S. interest in securing domestic supplies of critical minerals, particularly tungsten and antimony.
Noble Capital Markets Research Report Wednesday, September 9, 2026
Companies contained in today’s report:
Aurania Resources (AUIAF)/OUTPERFORM – Drilling is Underway at the Thor’s Valley Gold Project in Iceland Power Metallic Mines Inc. (PNPNF)/OUTPERFORM – High-Grade Lion Maiden Resource with Significant Expansion Potential
Aurania Resources (AUIAF/$0.14 | Price Target: $0.3) Mark Reichman [email protected] | (561) 999-2272 Drilling is Underway at the Thor’s Valley Gold Project in Iceland Rating: OUTPERFORM
Drilling has commenced at Thor’s Valley. Aurania has commenced a six-hole, approximately 770-meter diamond drilling program at the Thor’s Valley gold project in Iceland. The program is expected to take about one month. Five holes will twin historical holes to validate previously reported high-grade intercepts using modern drilling and standards, while a sixth will test a new target associated with surface rock chip boulders grading up to 102 grams per tonne (g/t) gold.
Thor’s Valley has a history of high-grade gold. Historical mining between 1911 and 1924 identified a productive vein approximately one meter wide and at least one kilometer long, with grades ranging from 11 g/t to 315 g/t gold. More recent exploration has reinforced the project’s high-grade characteristics, with 32 holes drilled in 2005 and 2006 returning results of up to 415.4 g/t gold, and another 11 holes completed in 2020 returning grades of up to 113 g/t gold.
Power Metallic Mines Inc. (PNPNF/$0.94 | Price Target: $2.65) Mark Reichman [email protected] | (561) 999-2272 High-Grade Lion Maiden Resource with Significant Expansion Potential Rating: OUTPERFORM
Maiden resource establishes Lion as a high-grade polymetallic deposit. Power Metallic’s inaugural maiden resource estimate (MRE) defined approximately 4.75 million tonnes at roughly 3.9% copper equivalent (CuEq), containing approximately 406 million pounds of CuEq, with more than 85% of the resource classified as Indicated. Importantly, mineralization begins at the surface, with approximately 59% of the current tonnage contained within the conceptual open pit resource, and the underground Indicated resource grading 4.71% CuEq.
Strong metallurgy and favorable infrastructure. Locked-cycle testing achieved copper recoveries above 98% while producing concentrates grading more than 25% copper, alongside strong recoveries for palladium, platinum, gold, and silver. The Lion Zone’s near-surface mineralization and proximity to all-season roads and major Hydro-Québec power infrastructure could support a relatively efficient development scenario, potentially beginning with an open pit before transitioning underground. Power Metallic is now preparing for a preliminary economic assessment (PEA), expected to be released in December 2026, that may include integration of the Nisk resource.
Noble Capital Markets Research Report Friday, September 4, 2026
Companies contained in today’s report:
Eledon Pharmaceuticals (ELDN)/OUTPERFORM – Clinical Milestones For Tegoprubart Trials In 2H26 Reiterated Lands’ End (LE)/OUTPERFORM – Underlying Momentum Remains Intact
Eledon Pharmaceuticals (ELDN/$2.93 | Price Target: $10) Robert LeBoyer [email protected] | (212) 896-4625 Clinical Milestones For Tegoprubart Trials In 2H26 Reiterated Rating: OUTPERFORM
Eledon Reiterated Plans For Tegoprubart Trials In Kidney Transplantation and Diabetes. Eledon has confirmed plans to initiate its Phase 3 LEGACY trial, testing tegoprubart to prevent rejection after kidney transplants. The trial will have two arms, comparing an immuno- suppressive regimen with tegoprubart to a regimen with tacrolimus. Each arm has a target enrollment of about 300 patients at clinical sites worldwide. The primary endpoint will be a composite of BRAR, graft loss, and death. Secondary endpoints include measures of kidney function and side effects associated with tacrolimus.
IND For Islet Cell Transplantation In Diabetes Has Been Filed. The company has submitted an IND (Investigational New Drug) application to begin testing tegoprubart to prevent rejection of islet cell allograft transplants in type 1 diabetes (T1D). To date, 12 patients treated in the first trial have achieved cell engraftment and normalized blood glucose. Their recent HbA1c levels averaged 5.4%, comfortably below the standard 6.5% threshold for diabetes. The upcoming trial will be multicenter and intended to meet requirements for FDA approval.
Lands’ End (LE/$10.82 | Price Target: $20) Michael Kupinski [email protected] | (561) 994-5734 George Proost [email protected] | Underlying Momentum Remains Intact Rating: OUTPERFORM
Q2 Revenue Rebounds. Fiscal second-quarter revenue increased 2.7% to $302.0 million, modestly above our $300.0 million estimate, as U.S. eCommerce revenue increased 9.0% and Outfitters increased 4.4%. Importantly, regular consumer fulfillment has normalized following the Q1 WMS disruption.
Underlying eCommerce Trends Are Encouraging. U.S. eCommerce revenue increased to $182.4 million, well above our $172.3 million estimate, supported in part by shipments carried over from Q1. Given the improved performance, we modestly increased our fiscal 2026 U.S. eCommerce revenue estimate to $842.2 million from $840.4 million.
U.S. stocks surged Wednesday, November 4, with the Dow Jones Industrial Average climbing more than 1,000 points after Democrats won control of both chambers of Congress in the 2026 midterm elections. The rally reflected investors’ reassessment of the political landscape in Washington, with expectations that divided government could limit sweeping policy changes while creating new opportunities and risks across major sectors.
By late morning, the Dow had gained approximately 1,325 points, or 2.6%, while the S&P 500 advanced 1.5% and the Nasdaq Composite rose 1.7%. The gains followed a volatile period for technology stocks as investors weighed concerns about artificial intelligence spending, corporate earnings, and geopolitical uncertainty.
Tuesday’s election results marked a significant change in Washington, ending two years of unified Republican control of Congress and giving Democrats majorities in both the House of Representatives and Senate.
President Donald Trump will remain in office, creating a divided government in which major legislative proposals may face greater challenges securing congressional approval.
For Wall Street, the prospect of legislative gridlock can sometimes provide reassurance by reducing uncertainty surrounding major changes to tax policy, government spending, and business regulation. However, the implications will depend on how lawmakers approach negotiations over federal budgets, healthcare, energy policy, and other economic priorities.
Several sectors experienced notable moves following the election.
Renewable energy stocks rallied as investors considered whether Democratic control of Congress could influence federal energy policy and oversight. Solar and wind companies attracted renewed attention, while traditional oil producers faced pressure amid declining crude prices and changing expectations for energy legislation.
Healthcare companies also advanced, particularly hospitals and businesses exposed to federal healthcare programs. Investors assessed whether the new congressional balance could affect healthcare funding and previous changes to government assistance programs.
Technology stocks delivered a mixed performance.
Apple and Microsoft helped support the broader market, while several semiconductor companies faced selling pressure amid concerns that new political leadership could increase scrutiny of artificial intelligence infrastructure and data-center construction.
The election also raised questions about the future of federal support for rapidly expanding AI facilities, particularly as concerns grow about electricity consumption, environmental impacts, and the cost of new infrastructure.
For smaller technology companies supplying components, equipment, and services to data centers, potential changes in permitting and infrastructure policy could influence future investment decisions.
Treasury yields declined during Wednesday’s session, with the benchmark 10-year yield falling to approximately 4.92%. Lower yields can improve borrowing conditions and support stock valuations, particularly among companies that depend on external financing.
Small-cap businesses are often more sensitive to changes in interest rates because they generally have less access to capital markets than larger corporations and may rely more heavily on bank loans or floating-rate debt.
The election outcome could also affect federal spending priorities in defense, infrastructure, and healthcare, industries where government contracts and reimbursement policies play an important role in corporate revenue.
However, congressional control does not automatically translate into immediate changes in economic policy.
The president retains significant executive authority over trade, tariffs, and foreign policy, while major legislative changes typically require agreement between Congress and the White House.
Investors must also consider broader economic conditions beyond the election.
Wednesday’s market rally coincided with new employment data showing that U.S. private employers added 86,000 jobs in October, exceeding economists’ expectations and suggesting that hiring activity remains resilient despite concerns about a slowing labor market.
Corporate earnings, inflation trends, and Federal Reserve policy will continue to influence market performance in the months ahead.
Although historical data suggests stocks have frequently performed well following midterm elections, past results do not guarantee future returns.
For investors, Wednesday’s rally demonstrates how quickly markets can respond to political developments, but the longer-term outlook will depend on how the new congressional balance affects economic legislation, corporate investment, and business confidence.
As Washington prepares for a new political environment, attention will increasingly shift from election results to the policies that emerge and their implications for publicly traded companies heading into 2027.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Activation. Yesterday, The GEO Group announced the activation of its previously idle Big Spring Complex in Texas. The Big Spring Complex is expected to generate approximately $200 million in annual revenues for GEO in the first full year of operations. The announcement is the second contract update in the past week. Not only do these contracts reinforce GEO’s ability to help its government partners meet their needs, but they also suggest ICE detainee populations should continue to rise, in our view.
Details. The contract is a 10-year intergovernmental service agreement between the City of Big Springs, Texas, and ICE. The facilities include the 1,404-bed Flightline Facility and the 925-bed Cedar Hill Facility. GEO will provide support services at the Big Springs Complex, which are expected to include the exclusive use of the Facility by ICE, along with security, maintenance, and food services, as well as access to recreational amenities, medical care, and transportation services.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Oil prices tumbled Monday, November 2, as renewed diplomatic efforts involving Iran and the United States raised hopes that months of conflict in the Middle East could move toward a resolution, potentially easing disruptions to global energy supplies and reducing inflationary pressures.
Brent crude, the international oil benchmark, fell more than 4% to approximately $108.66 per barrel during Monday’s trading session, while U.S. West Texas Intermediate (WTI) crude dropped to around $99.83. The decline marked a sharp reversal from recent gains that had pushed oil prices to six-month highs amid fears of further military escalation.
The selloff followed reports that Iranian officials held discussions with Qatari mediators over the weekend regarding a possible agreement to end the conflict involving Iran, the United States, and Israel.
Iranian Foreign Minister Abbas Araqchi indicated that diplomatic consultations were continuing, although no formal agreement had been reached. Reports also suggested that Washington was willing to allow additional time for negotiations before considering further military action.
The developments prompted traders to reduce some of the geopolitical risk premium that had accumulated in crude oil prices during October.
A central concern remains the Strait of Hormuz, one of the world’s most strategically important shipping routes for oil and natural gas. Disruptions to tanker traffic through the waterway have constrained energy shipments and increased transportation and insurance costs.
Recent attacks on commercial vessels have heightened concerns about the reliability of Middle Eastern energy exports. Although some regional producers have managed to increase shipments through alternative routes, the broader supply situation remains fragile.
The conflict has also contributed to a substantial drawdown in global petroleum inventories. According to the chief executive of Abu Dhabi National Oil Company, approximately one billion barrels have been withdrawn from worldwide oil inventories since the war disrupted shipping through the Strait of Hormuz earlier this year.
Those depleted inventories could leave the market vulnerable to renewed price increases if negotiations collapse or additional energy infrastructure is damaged.
Despite Monday’s decline, crude oil remains significantly more expensive than it was a year ago, reflecting the lasting effects of supply disruptions and geopolitical uncertainty.
Goldman Sachs recently raised its oil price forecasts, warning that Brent crude could reach $140 per barrel in 2027 if Persian Gulf production remains substantially below previous levels.
Marvell Technology (NASDAQ: MRVL) announced Monday, November 2, that it has agreed to acquire optical networking specialist Lumentum Holdings (NASDAQ: LITE) in an all-stock transaction valued at approximately $115 billion, marking one of the largest technology acquisitions in history and a major bet on the continued expansion of artificial intelligence infrastructure.
The agreement brings together two important suppliers of technology used to connect high-performance computing systems, positioning the combined company to compete more aggressively in the rapidly growing market for AI data-center networking.
Under the terms of the transaction, Lumentum shareholders will receive 4.5 shares of Marvell common stock for each Lumentum share they own. The agreement implies a value of approximately $1,132 per Lumentum share, representing a 23.9% premium based on the companies’ unaffected closing prices on October 28.
Following completion, existing Marvell shareholders are expected to own approximately 67% of the combined company, while Lumentum shareholders will hold the remaining 33%.
The acquisition reflects the growing importance of optical connectivity as technology companies invest heavily in increasingly powerful AI computing infrastructure.
Modern artificial intelligence systems require thousands of specialized processors to operate together, creating enormous demand for high-speed connections capable of transferring information between chips, servers, and data centers.
Traditional electrical connections face increasing limitations as computing systems become larger and more complex. Optical technologies, which transmit data using light, offer the potential for higher bandwidth and improved power efficiency across critical networking applications.
Marvell develops custom semiconductor solutions, networking processors, and connectivity technology used by major cloud computing and enterprise customers. Lumentum specializes in optical components, lasers, and photonics technologies that support high-speed communications.
Combining those capabilities could allow Marvell to offer customers a broader portfolio of integrated semiconductor and optical networking products.
Marvell estimates that the acquisition will expand the combined company’s total addressable market to approximately $550 billion, reflecting opportunities across AI connectivity and related infrastructure.
The companies also expect to generate more than $1 billion in annual run-rate cost savings through manufacturing efficiencies, product integration, and operational improvements.
Management anticipates that the transaction will increase Marvell’s adjusted earnings per share during the first year following completion.
Marvell Chairman and Chief Executive Officer Matt Murphy will continue leading the combined company. Three Lumentum directors, including Chief Executive Officer Michael Hurlston, are expected to join Marvell’s board.
The transaction is expected to close during the first half of 2028, subject to shareholder approvals, regulatory clearance, and customary closing conditions.
Despite the strategic rationale, the deal introduces significant financial and operational considerations.
The approximately $115 billion valuation represents a substantial commitment at a time when investors are increasingly questioning whether massive AI infrastructure expenditures will generate sufficient long-term returns.
Marvell will also face the challenge of integrating complex semiconductor and optical manufacturing operations while maintaining relationships with major technology customers.
The acquisition could intensify competition with Broadcom and other suppliers developing custom chips and advanced networking solutions for hyperscale data centers.
For smaller semiconductor, photonics, and networking companies, the transaction highlights the strategic value of specialized technologies that enable faster and more efficient AI computing.
It may also encourage additional partnerships and acquisitions as larger technology suppliers seek capabilities in optical communications, advanced packaging, and specialized semiconductor manufacturing.
However, the industry’s growth remains closely tied to continued capital investment by major cloud providers, creating risks if AI infrastructure spending slows.
Marvell’s proposed acquisition of Lumentum demonstrates how the artificial intelligence boom is reshaping the semiconductor industry, with connectivity technology emerging as a critical component of the next generation of computing infrastructure.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Thoughts on the Quarter. We view the quarter as evidence of progress in cash generation and portfolio repositioning, with an organic earnings recovery still to be demonstrated. Cost actions, school brand performance, and International margin improvement support the operating base. However, acquisitions and currency continue to offset declining comparable sales, and tariff recoveries explain more than the entire quarterly increase in adjusted operating income. A sustained improvement in peripherals sell-through and margins would provide stronger support for a recovery thesis.
Key Quarter Metrics. Back-to-school was a bright spot. Management reported mid-single-digit seasonal growth in the United States and Canada and nearly 20% growth in Mexico. Workspace Solutions segment sales were off low single digits overall, while the Tech Peripherals business was down low double digits.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Bitcoin and other major cryptocurrencies came under heavy selling pressure Friday, October 30, after Binance disclosed a massive security breach involving approximately $6.3 billion in digital assets, potentially marking the largest cryptocurrency theft in history and raising fresh concerns about the security of centralized trading platforms.
Bitcoin fell more than 3% to a six-week low near $76,368 before recovering some losses, while Ethereum dropped to approximately $2,178, its lowest level in two months. Binance-linked BNB also declined sharply as investors reassessed the risks surrounding the world’s largest cryptocurrency exchange.
The attack occurred Thursday, October 29, when hackers transferred billions of dollars from Binance-linked wallets across multiple blockchains in approximately 20 minutes. Blockchain analytics firms TRM Labs and Chainalysis have linked the operation to North Korean hackers, citing similarities to previous attacks attributed to the country’s cybercriminal networks.
Binance initially identified a compromised employee laptop as a possible entry point. However, the company’s investigation subsequently uncovered additional security breaches, suggesting a more sophisticated attack involving weaknesses in transaction authorization and wallet controls.
Binance co-CEO Richard Teng said Friday that attackers exploited Ethereum’s account-delegation functionality to bypass normal approval procedures and gain control of a cryptocurrency wallet. Investigators are still working to establish the complete sequence of events.
The exchange has temporarily suspended withdrawals while rebuilding and testing its security infrastructure. Binance is targeting Sunday for the restoration of withdrawal services and plans to publish updated proof-of-reserves information Monday.
Binance has pledged to cover the losses using company resources. The exchange also reported that approximately $3 billion in affected assets had been frozen through cooperation with blockchain networks, stablecoin issuers, and other industry participants.
Despite those assurances, the incident has triggered a broader reassessment of cryptocurrency market risk.
The selloff has been particularly damaging for leveraged traders. Approximately $1.5 billion in cryptocurrency futures positions were liquidated as falling prices forced investors to close positions, adding to downward market pressure.
Publicly traded cryptocurrency companies also faced selling pressure. Shares of Coinbase Global and Strategy declined in extended trading, illustrating how concerns about digital-asset security can quickly spread into traditional equity markets.
The breach comes at a difficult time for cryptocurrencies, which were already facing pressure from elevated U.S. interest rates and softer demand from exchange-traded fund investors.
For Bitcoin, the immediate concern is whether the security incident leads to sustained withdrawals from centralized exchanges or further liquidation of leveraged positions.
A prolonged disruption at Binance could reduce market liquidity, increase trading volatility, and weaken investor confidence. Additional selling could also emerge if stolen assets are transferred to exchanges and converted into other cryptocurrencies or cash.
Ethereum and smaller digital assets may face even greater volatility because their markets generally have less liquidity than Bitcoin.
However, the market impact will depend heavily on how quickly Binance restores normal operations, demonstrates sufficient reserves, and provides clarity regarding the security failures.
Standard Chartered’s digital-assets research team has warned that cryptocurrency prices could remain under pressure until more details emerge and frozen assets are addressed.
The incident may also accelerate interest in decentralized exchanges and self-custody solutions, although those alternatives carry their own technological and security risks.
For investors, the Binance attack highlights a fundamental challenge facing the cryptocurrency industry: even as digital assets become more integrated into mainstream financial markets, cybersecurity vulnerabilities and exchange-related risks remain significant.
With billions of dollars potentially at stake, the coming days could prove critical in determining whether the selloff represents a temporary reaction to a major security incident or the beginning of a broader decline in cryptocurrency prices.
Intel (NASDAQ: INTC) shares plunged as much as 26% on Friday, October 30, putting the semiconductor giant on pace for one of its worst trading days in more than five decades after the company issued a disappointing fourth-quarter forecast and warned that weakness in the personal computer market could extend into 2027.
The sharp decline threatened to erase more than $100 billion in market capitalization, underscoring growing investor concerns about Intel’s turnaround strategy despite stronger-than-expected third-quarter earnings and rapid growth in its data center business.
Intel reported third-quarter revenue of $16.51 billion, up 21% from a year earlier and slightly above Wall Street expectations. Adjusted earnings reached $0.52 per share, exceeding analysts’ estimates of approximately $0.40.
However, the company’s outlook for the final quarter of 2026 disappointed investors. Intel projected revenue between $15 billion and $16 billion, below Wall Street’s expectations of approximately $17.1 billion. Adjusted earnings are expected to reach $0.25 per share, compared with forecasts of roughly $0.43.
The weaker guidance reflects mounting challenges in the global PC market, where rising memory chip prices are increasing production costs and reducing demand for new computers.
Intel now expects worldwide PC shipments to decline approximately 12% in 2026, followed by another 10% decrease in 2027. The company warned that market conditions could remain difficult through at least the first half of next year.
A major factor behind the slowdown is the rapid expansion of artificial intelligence infrastructure. Data center operators are consuming increasing amounts of memory capacity, contributing to higher component prices for consumer laptops and desktop computers.
The trend highlights an emerging divide within the semiconductor industry, as AI-related demand supports certain chipmakers while creating cost pressures across other technology markets.
Intel’s own results illustrate that contrast. Revenue from its data center and AI business jumped 78% year over year to $7.3 billion, supported by strong demand for server processors. Meanwhile, its client computing business generated approximately $8.1 billion in revenue, representing a 5% annual decline.
The company also faces manufacturing challenges following an accident at its semiconductor facility in Israel earlier this month. Intel expects the disruption to reduce fourth-quarter revenue by approximately $300 million.
Chief Executive Officer Lip-Bu Tan, who is leading Intel’s restructuring efforts, acknowledged that rebuilding the company will require several years.
Intel is investing heavily in advanced manufacturing capacity as it works to strengthen its competitive position against semiconductor rivals including Nvidia and Advanced Micro Devices.
The company maintained its 2026 capital expenditure outlook of approximately $20 billion but expects spending to increase substantially in 2027. Management also indicated that Intel does not expect to generate positive free cash flow next year.
For investors, the combination of rising capital expenditures and weaker near-term demand raises questions about how quickly Intel can translate its manufacturing investments into sustainable profitability.
The selloff also weighed on broader semiconductor sentiment, with PC manufacturers and other technology companies facing renewed scrutiny over demand expectations and capital spending.
Despite Friday’s decline, Intel shares remain substantially higher for the year following a powerful rally fueled by optimism surrounding its restructuring and domestic semiconductor manufacturing ambitions.
The latest earnings report demonstrates that strong AI demand alone may not be enough to offset weakness in traditional computing markets.
As Intel enters 2027, investors will be watching for signs of stabilization in PC demand, improvements in manufacturing execution, and evidence that the company’s ambitious turnaround can deliver sustainable financial returns.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
New Contract. The GEO Group entered into a new 10-year contract for the continued provision of support services at the GEO-owned 1,635-bed Northwest ICE Processing Center located in Tacoma, Washington. The new 10-year contract is expected to generate approximately $140 million in annual revenues for GEO and continue through October 27, 2036. We believe this demonstrates the ongoing attractiveness of GEO’s assets for its government partners.
Services. Support services at the Northwest ICE Processing Center are expected to include security, maintenance, and food services, as well as access to recreational amenities, medical care, and transportation services.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Quarterly Overview. ACCO delivered third-quarter sales consistent with management’s outlook, driven by a solid back-to-school season in both North America and Mexico and stabilizing trends in Workspace Solutions. Adjusted EPS included net tariff refunds, with underlying operations in line with outlook. ACCO generated strong cash flows and continued to pay down debt, ending September with a consolidated leverage ratio of 3.6x.
3Q26 Numbers. Third quarter net sales decreased 0.9% to $380.3 million from $383.7 million in 2025, reflecting 4.9% growth from the EPOS acquisition and 0.4% from favorable foreign exchange, which were more than offset by a 6.2% decline in comparable sales. Net income was $11.5 million, or $0.12 per share, compared with $4.0 million, or $0.04 per share, in 2025. Adjusted net income increased to $27.2 million from $19.5 million in 2025, and adjusted earnings per share rose to $0.28 from $0.21 in 2025.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
The Federal Reserve is preparing to announce its latest interest rate decision Wednesday, October 28, as investors assess whether persistent inflation and elevated borrowing costs could create additional challenges for U.S. stocks, particularly smaller companies that depend heavily on access to capital.
The Federal Open Market Committee began its two-day policy meeting Tuesday, with economists broadly expecting policymakers to maintain the benchmark federal funds rate at its current range of 3.75% to 4.00%. While an immediate rate increase appears unlikely, attention is shifting toward the central bank’s outlook for December and whether inflation could require additional monetary tightening.
The upcoming announcement arrives at a sensitive moment for financial markets. Inflation remains above the Federal Reserve’s 2% target, while higher energy prices and persistent price pressures have complicated expectations for the direction of interest rates.
For investors, the most important development may not be Wednesday’s decision itself, but what Federal Reserve Chair Kevin Warsh communicates about the central bank’s willingness to keep borrowing costs elevated or raise rates further.
Market expectations currently favor an unchanged policy rate this week. However, interest rate futures indicate investors are assigning considerably greater probability to an increase at the Fed’s December meeting, underscoring concerns that inflation may remain difficult to control.
The prospect of sustained higher interest rates carries particular significance for small-cap companies. Unlike many large corporations with substantial cash reserves and established access to debt markets, smaller businesses frequently depend on bank financing, revolving credit facilities, and capital markets to support expansion and operations.
Higher interest rates can increase debt servicing expenses, reduce profitability, and make new investment projects more expensive. Companies with significant refinancing requirements may face additional pressure as existing debt matures and must be replaced at higher borrowing costs.
These conditions can also influence equity valuations. When Treasury yields rise, investors may demand higher returns from riskier assets, potentially placing downward pressure on stocks with earnings expected further into the future.
The Russell 2000 Index, a widely followed benchmark for smaller publicly traded U.S. companies, is particularly sensitive to changes in financing conditions and expectations for economic growth.
For emerging biotechnology companies, elevated interest rates can make equity financing more challenging and increase the importance of maintaining sufficient cash to fund clinical trials and regulatory development. Smaller industrial and consumer businesses may face a different combination of pressures, including financing expenses, higher input costs, and changes in customer demand.
Meanwhile, companies in energy and materials must balance borrowing costs against the effects of commodity prices, which can influence both revenue expectations and inflation trends.
The Federal Reserve’s decision also comes as longer-term Treasury yields remain elevated. The benchmark 10-year Treasury yield has approached 5%, adding pressure to borrowing costs across the economy, including mortgages and corporate financing.
Wednesday’s announcement could therefore influence investor sentiment even if policymakers leave the benchmark rate unchanged. A statement emphasizing persistent inflation or the possibility of further tightening could push Treasury yields higher, while signs of greater confidence in inflation moderation could provide some relief to rate-sensitive sectors.
Investors will also monitor any disagreements among Federal Reserve officials, particularly whether policymakers favoring tighter monetary policy signal growing concern about inflation.
For small-cap investors, the central question is whether the Federal Reserve can bring inflation under control without creating additional financial strain for businesses that rely on affordable c