Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Overview. In the third quarter, Kelly delivered results above the midpoint of guidance, driven by meaningful progress on growth and efficiency initiatives along with increasingly constructive demand trends. Year-over-year revenue improved sequentially for a third consecutive quarter, and the Company had adjusted EBITDA margin expansion over the prior-year period. We believe Kelly remains well positioned to capitalize on increasing demand while continuing to drive margin expansion.
3Q Numbers. Kelly reported 3Q26 revenue of $927.2 million, down 0.8% year-over-year, an improvement of 500 bps versus the prior quarter; underlying revenue, which excludes previously disclosed discrete impacts, grew 2.3% year-over-year. We were at $930 million. Adjusted EBITDA was $21.3 million and adjusted EBITDA margin was 2.3%. We had projected $19 million and 2%, respectively. Adjusted EPS was $0.07 in the third quarter of 2026 compared to $0.17 per share in the corresponding quarter of 2025. We were at $0.14.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q3 Results. Conduent reported Q3 2026 revenue of $534 million, down 11.7% year over year and slightly below our $537 million estimate, though up from the second quarter. Despite the year-over-year decline, adjusted EBITDA rose 16.1% to $36 million, modestly ahead of our $35 million estimate, with margins expanding 160 basis points to 6.7%. The improvement reflects progress on management’s cost-reduction initiatives.
Segment Financial Performance. Commercial revenue declined 16% to $308 million, reflecting the wind-down of its largest customer. Adjusted EBITDA margins fell 70 basis points year over year to 9.4% but improved approximately 180 basis points sequentially. Government revenue declined 5% to $226 million, although margins expanded 230 basis points to 27.9%, driven primarily by cost efficiencies.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q3 Operating Results. The company reported Q3 revenue of $534 million, down 11.7% year over year but up slightly from $531 million in Q2, as contract losses and lower client volumes continued to weigh on results. Adj. EBITDA increased 16.1% to $36 million, with margins expanding 160 basis points to 6.7%, reflecting cost reductions that more than offset the impact of lower revenue.
Underlying Business Trends. Commercial revenue declined 16% to $308 million, reflecting the completed wind-down of the company’s largest Commercial customer. Government revenue declined 5% to $226 million due to completed implementations, lost business, and lower volumes. Despite these headwinds, Government adj. EBITDA margins expanded 230 basis points to 27.9%, supported by cost-efficiency initiatives.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
TROY, Mich., Nov. 05, 2026 (GLOBE NEWSWIRE) — Kelly (Nasdaq: KELYA, KELYB), a leading specialty talent solutions provider, today announced results for the third quarter of 2026.
Q3revenue of$0.9 billion, down0.8%year-over-year, an improvement of 500 basis points (“bps”) versus the prior quarter; underlying revenue, which excludes previously disclosed discrete impacts, grew 2.3% year-over-year
ETM underlying revenue grew 7.7% (2.4%reported) while SET underlying revenue decreased 0.8% (2.0%reported). The underlying performance for ETM and SET improved 460 bps and 220 bps versus the prior quarter, respectively
Q3operating earnings of$0.6 million;$6.1 millionof operating earnings on an adjusted basis
Adjusted EBITDA of$21.3 millionand adjusted EBITDA margin of2.3%, which expanded 50 bps on a year-over-year basis resulting from improved gross profit rate and continued SG&A discipline
Chris Layden, chief executive officer, said, “In the third quarter, we delivered results above the midpoint of our guidance, driven by meaningful progress on our growth and efficiency initiatives along with increasingly constructive demand trends. Year-over-year revenue improved sequentially for a third consecutive quarter, and we drove adjusted EBITDA margin expansion over the prior year period. Our performance reflects positive operational momentum across much of our portfolio, as ETM pivoted to positive year-over-year revenue growth in the quarter and SET delivered another quarter of sequential revenue improvement. We remain well positioned to capitalize on increasing demand while continuing to drive margin expansion and long-term value creation.”
Financial Results for the13-week period endedSeptember 27, 2026:
Revenue of $0.9 billion, a 0.8% decrease compared to the corresponding quarter of 2025 and an improvement of 500 bps versus the prior quarter. Discrete impacts associated with the previously disclosed reduced demand for U.S. federal government contractors in the SET segment and from three large commercial customers in the ETM segment totaled approximately 3.1%, resulting in an underlying revenue increase of approximately 2.3%. Underlying revenue performance includes overall growth from improved demand and new business in the ETM segment, including growth in staffing and each of the talent solutions specialties. Offsetting the growth were declines in SET, which showed continued sequential improvement, and Education segments. Within the SET segment, the Science and Engineering specialties grew year-over-year, while the Technology specialty continued to strengthen sequentially. The Education segment continues to be impacted by declines in demand primarily driven by reduced student enrollment in key markets.
Operating earnings of $0.6 million, compared to a loss of $102.1 million reported in the third quarter of 2025. Prior year operating loss reflected a non-cash goodwill impairment charge totaling $102.0 million. Adjusted operating earnings1 were $6.1 million in the third quarter of 2026 and $4.3 million in the third quarter of 2025. Adjusted EBITDA1 of $21.3 million, an increase of 29.1% versus the prior year period. Adjusted EBITDA margin of 2.3%, an increase of 50 bps versus the prior year, reflects 20 bps higher gross margin and volume-related and structural expense management actions including benefits from our acquisition integration and technology modernization efforts. ETM and SET showed year-over-year improvement in their adjusted EBITDA margin while Education was negative due to the school year seasonality. Both ETM and SET improved their adjusted EBITDA margins measurably versus the prior quarter.
Income tax expense of $1.2 million, compared to income tax expense of $46.4 million reported in the third quarter of 2025, with the change primarily driven by the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, income tax expense of $2.6 million, compared to income tax benefit of $3.8 million in the third quarter of 2025.
Loss per share was $0.05 compared to loss per share of $4.26 in the third quarter of 2025, and reflects the impact of the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, earnings per share was $0.07 in the third quarter of 2026 compared to $0.17 per share in the corresponding quarter of 2025.
Financial Results for the39-week period endedSeptember 27, 2026:
Revenue of $3.0 billion, a 6.1% decrease compared to the corresponding period in 2025. Discrete impacts associated with the reduced demand for U.S. federal government contractors in the SET segment and from three large commercial customers in the ETM segment totaled approximately 5.4%, resulting in an underlying revenue decline of approximately 0.7%. Underlying revenue performance includes overall growth from improved demand in the ETM segment, including growth in each of the talent solutions specialties, along with growth in the Telecom specialty and improved performance in the Science and Engineering specialties within the SET segment. Offsetting this growth was continued lower demand in the other specialties within the SET segment, largely the Technology specialty, along with a decline in the Education segment driven by delayed prior year contract decisions and declines in demand primarily driven by reduced student enrollment in key markets.
Operating earnings of $11.6 million, compared to a loss of $69.1 million reported over the same period in 2025. Prior year operating loss reflected a non-cash goodwill impairment charge totaling $102.0 million. Adjusted operating earnings1 were $29.5 million in the first nine months of 2026 and $51.0 million in the corresponding period of 2025. Adjusted EBITDA1 of $68.2 million, a decrease of 22.9% versus the prior year period. Adjusted EBITDA margin of 2.3%, a decrease of 50 bps, reflects near-term margin pressure in ETM, Education, and SET driven by lower gross margins and timing of revenue trends, partially offset by volume-related and structural expense management actions including benefits from our acquisition integration and technology modernization efforts.
Income tax expense of $3.4 million, compared to income tax expense of $49.1 million reported over the same period in 2025, with the change primarily driven by the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, income tax expense of $7.9 million, compared to income tax expense of $3.4 million in the corresponding period of 2025.
Earnings per share was $0.10, compared to loss per share of $3.56 in the same period of 2025, and reflects the impact of the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, earnings per share was $0.46 for the first nine months of 2026 compared to $1.10 per share in the corresponding period of 2025.
1 Adjusted measures represent non-GAAP financial measures. Refer to our reconciliation of non-GAAP financial measures to the most closely related GAAP measure included in this document.
Financial Outlook for Fiscal Fourth Quarter 2026
The Company’s financial outlook assumes no material change in the macroeconomic environment relative to the third quarter, and is consistent with the full year expectations set in February of this year. For the fourth quarter, expectations for revenue growth and adjusted EBITDA margin have been adjusted relative to our prior view largely due to the delayed return to growth in our Education business and near-term incremental demand pressure from one discrete ETM customer, and are as follows:
Fourth Quarter of 2026 – Expect revenue to be flat to up 1% on a year-over-year basis and adjusted EBITDA margin expansion of 180 to 200 bps year-over-year resulting in a margin of 3.8% to 4.0%.
Outlook includes the impact of an extra fiscal week in the fourth quarter, which benefits revenue growth by approximately 3 points in the fourth quarter, but negatively impacts adjusted EBITDA.
Full Year 2026 – On a full year basis, expect a mid-single digit total revenue decline and adjusted EBITDA margin of 2.6% to 2.7%, reflecting flat to 10 bps of year-over-year improvement.
Quarterly Cash Dividend and Share Repurchase Renewal and Extension:
Kelly also reported that on November 4, 2026, its board of directors declared a dividend of $0.075 per share. The dividend is payable on December 2, 2026 to stockholders of record as of the close of business on November 18, 2026.
On November 4, 2026, the board of directors approved the renewal and extension of the Company’s share repurchase program without an expiration date, which authorized the repurchase of up to $50.0 million of Class A common stock. The new authorization is inclusive of the amount that remained available under the prior authorization, which was superseded and replaced.
In conjunction with its earnings release, Kelly has published a financial presentation and will host a live webcast of a conference call at 9 a.m. ET on November 5 to review the financial and operational results from the quarter. The presentation and a link to the live webcast will be accessible through the Company’s public website on the Investor Relations page under Events & Presentations. The webcast will be recorded, and a replay will be available within one hour of completion of the event through the same link as the live webcast.
Forward-Looking Statements:
This release contains statements that are forward-looking in nature and, accordingly, are subject to risks and uncertainties. These statements are made under the “safe harbor” provisions of the U.S. Private Securities Litigation Reform Act of 1995. Statements that are not historical facts, including statements about Kelly’s financial expectations, are forward-looking statements. Factors that could cause actual results to differ materially from those contained in this release include, but are not limited to, (i) changing market and economic conditions, (ii) disruption in the labor market and weakened demand for human capital resulting from technological advances, competitive pressures and pricing, loss of large corporate customers and government contractor requirements, (iii) the impact of laws and regulations (including federal, state and international tax laws), (iv) unexpected changes in claim trends on workers’ compensation, unemployment, disability and medical benefit plans, (v) litigation and other legal liabilities (including tax liabilities) in excess of our estimates, (vi) our ability to achieve our business’s anticipated growth strategies, (vii) our future business development, results of operations and financial condition, (viii) damage to our brands, (ix) dependence on third parties for the execution of critical functions, (x) conducting business in foreign countries, including foreign currency fluctuations, (xi) availability of temporary workers with appropriate skills required by customers, (xii) cyberattacks or other breaches of network or information technology security, and (xiii) other risks, uncertainties and factors discussed in this release and in the Company’s filings with the Securities and Exchange Commission. In some cases, forward-looking statements can be identified by words or phrases such as “may,” “will,” “expect,” “anticipate,” “target,” “aim,” “estimate,” “intend,” “plan,” “believe,” “potential,” “continue,” “is/are likely to” or other similar expressions. All information provided in this press release is as of the date of this press release and we undertake no obligation to update any forward-looking statement, whether as a result of new information, future events, or otherwise, except as required by law.
About Kelly®
Kelly Services, Inc. (Nasdaq: KELYA, KELYB) helps companies recruit and manage skilled workers and helps job seekers find great work. Since inventing the staffing industry in 1946, we have become experts in the many industries and local and global markets we serve. With a network of suppliers and partners around the world, we connect approximately 375,000 people with work every year. Our suite of outsourcing and consulting services and solutions ensures companies have the people they need, when and where they are needed most. Headquartered in Troy, Michigan, we empower businesses and individuals to access limitless opportunities in industries such as science, engineering, technology, education, manufacturing, retail, finance, and energy. Revenue in 2025 was $4.3 billion. Learn more at kellyservices.com.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
3Q26 Overview. ISG delivered a robust financial performance in the third quarter, with strong cash generation, expanding margins, and solid revenue growth. Revenue in the quarter was driven by a return to growth in Asia Pacific, up 47%, AI-related revenues reaching over $30 million for the first time, and recurring revenues continuing to build, up 7%. This mix of growth helped drive adjusted EBITDA margin expansion to 15.4%, the highest quarterly margin in four years.
3Q26 Results. Revenues for 3Q26 were $65.1 million, up 4.4% from $62.4 million in the prior year. Revenues were $41.9 million in the Americas, down 1%; revenues in Europe were $17.0 million, up 6% on a reported basis; and Asia Pacific revenues were $6.2 million, up 47% on a reported basis. ISG reported GAAP net income of $3.4 million, compared with net income of $3.1 million in the prior year. Fully diluted earnings per share were $0.07, compared with fully diluted earnings per share of $0.06 in the prior year. Adjusted EPS was $0.10, up from $0.09 in the prior year’s third quarter. Adjusted EBITDA was $10.0 million, up 19% from the prior year.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Third quarter falls short of expectations. Xerox reported third-quarter revenue of $1.87 billion, largely in line with our estimate, while adjusted EBITDA of $193 million was 12.8% below our forecast. Gross margin of 29.2% was approximately 370 basis points below our estimate, reflecting higher input costs and an unfavorable equipment mix, which more than offset lower operating expenses.
Lexmark savings remain on track. Following our discussions with management, we believe the company remains confident in achieving approximately $100 million of incremental Lexmark integration savings in 2027. Additional opportunities in automation, AI, organizational simplification, and facility consolidation could deliver further benefits, though the timing and magnitude of these savings remain uncertain.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
STAMFORD, Conn.–(BUSINESS WIRE)– Enterprises are using agentic AI to redistribute work between people and machines, giving it defined operational responsibilities while keeping humans in the loop, according to two new global research reports published today by Information Services Group (ISG) (Nasdaq: III), a global AI-centered technology research and advisory firm.
The 2026 ISG Provider Lens® Agentic AI Services report finds that the technical capabilities of agents are progressing faster than companies are delegating responsibility to them. In most organizations, it is more common for agentic AI platforms to coordinate and perform defined tasks than to independently own consequential processes. This measured approach reflects concerns about accountability, permissions, security and operational risk in areas where technology can alter records or trigger actions.
“Organizations are focusing on work that intelligent platforms can perform reliably within defined limits,” said Steve Hall, chief AI officer, ISG. “The goal is allocation of responsibility between machines and people, with safeguards that preserve accountability for consequences. With clear operating conditions, companies can delegate responsibility to AI without exceeding acceptable business limits.”
The 2026 ISG Provider Lens® Agentic AI Services — Specialists report finds that specialist providers are advancing from isolated task agents toward multi-step workflows and multi-agent orchestration. They are industrializing delivery through libraries of reusable agents and embedding governance controls throughout the lifecycle of an agent rather than treating governance as a checkpoint.
Before assigning responsibilities to agents, enterprises are assessing whether decisions are bounded, outcomes are observable and exceptions are manageable. Multi-step processes with clear operating parameters are the strongest candidates for giving AI greater agency. The objective is to reduce human effort and handoffs across workflows while shortening cycle times and making organizations more responsive.
As more responsibility is delegated to AI agents, humans’ roles are shifting toward validation, approvals, exception handling and supervision. Authentication, audit trails, thresholds and escalation paths establish the conditions for permitting actions by agents and determining when responsibility returns to people. Enterprises are imposing rules and policy constraints to limit unexpected results. While 79 percent of enterprises plan to increase AI technology spending, improved governance is the most significant change companies say they would make based on their experience so far, ISG says.
“The real measure of agentic AI is not an individual agent’s sophistication, but its ability to move work forward reliably across the enterprise,” said Gowtham Kumar Sampath, ISG principal analyst and lead author of the report. “That requires dependable connections among systems, clear responsibilities and outcomes that can be observed at each step of a workflow.”
The reports also explore other trends in agentic AI services, including the increasing importance of validation, recovery and escalation when actions produce unexpected results and the growing demand for controls on agent access to tools, applications and data.
For more insights into the agentic AI-related challenges faced by enterprises, along with ISG’s advice for addressing them, see the ISG Provider Lens Focal Points briefing here.
The Agentic AI Services report evaluates 60 large and midsize providers across two quadrants: Agentic AI Development and Deployment Services — Large Providers and Agentic AI Development and Deployment Services — Midsize Providers.
The report names Accenture, Accion Labs, Apexon, Ascendion, Atos, Birlasoft, Brillio, Capgemini, Cognizant, Cybage, DXC Technology, EXL, Firstsource, HCLTech, Hexaware, IBM, Infosys, Konecta, NTT DATA, Persistent Systems, Softtek, Sutherland, TCS, Trigent, Unisys and Virtusa as Leaders in one quadrant each.
In addition, Genpact and HTC Global Services are recognized as Rising Stars — companies with a “promising portfolio” and “high future potential” by ISG’s definition — in one quadrant each.
The Agentic AI Services― Specialists report evaluates 21 providers in one quadrant: Agentic AI Development and Deployment — Specialist Providers.
The report names 66degrees, Fractal Analytics, Lingaro, Network Science, Quantiphi, Straive, Tiger Analytics, Tredence and Version 1 as Leaders in the quadrant.
In addition, Sigmoid is recognized as a Rising Star — a company with a “promising portfolio” and “high future potential” by ISG’s definition — in the quadrant.
In the area of customer experience, HCLTech, Persistent Systems and 66Degrees are named the global ISG CX Star Performers for 2026 among large, midsize and specialist Agentic AI Services providers, respectively. HCLTech, Persistent Systems and 66Degrees earned the highest customer satisfaction scores in ISG’s Voice of the Customer survey, part of the ISG Star of Excellence™ program, the premier quality recognition for the technology and business services industry.
The 2026 ISG Provider Lens Agentic AI Services report is available to subscribers or for one-time purchase on this webpage. The Agentic AI Services — Specialists report is available here.
About ISG
ISG (Nasdaq: III) is a global AI-centered technology research and advisory firm. A trusted partner to more than 900 clients, including 75 of the world’s top 100 enterprises, ISG is a long-time leader in technology and business services that is now at the forefront of leveraging AI to help organizations achieve operational excellence and faster growth. The firm, founded in 2006, is known for its proprietary market data and research, in-depth knowledge and governance of provider ecosystems, and the expertise of its 1,500 professionals worldwide working together to help clients maximize the value of their technology investments.Source: Information Services Group, Inc.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
A Tuck-in. Yesterday, Star Equity announced that its Energy Services division acquired a privately held Vernal, Utah-based machine shop that provides repair, rebuild, and machining services for well fishing tools, drill pipe, and other drilling equipment. The transaction closed on October 23, 2026, and the shop will work alongside Alliance Drilling Tool’s (ADT) existing Vernal operation. No financial details were provided.
Additional Detail. Adding these in-house capabilities makes ADT’s Vernal operation a full-service location. ADT can support customers across more of the tool life cycle while gaining more direct control over service quality and turnaround time. The expanded capabilities also position ADT to more actively pursue oil and gas drilling work in the Uinta Basin, as well as mining and geothermal opportunities across the region.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Conduent Incorporated (Nasdaq: CNDT) (“Conduent” or the “Company”), a global technology-enabled operating partner, today announced the successful closing of a comprehensive $447 million refinancing transaction. The transaction extends the Company’s $357 million revolving credit facility through May 2029 and adds $90 million in additional commitments from its existing bank lenders, including a $15 million letter of credit facility, reflecting confidence in the Company’s strategy. Together with the Company’s recent and announced divestitures, including the use of proceeds to repay debt, these actions advance Conduent’s strategy to delever and de-risk its business and create greater flexibility to execute ASCEND 2026–28, the Company’s strategic plan outlined at its recent Investor Day.
The transaction establishes new revolving credit facilities with a group of existing bank lenders and rolls certain commitments under the existing revolver into the new facilities, extending maturities from October 2026 and May 2028 to May 2029.
The transaction builds on Conduent’s recently completed sale of its Public Transit business and the announced sale of its Tolling business. Together, these portfolio actions and the refinancing are expected to reduce the Company’s surety bond and letter-of-credit portfolio by approximately $550 million upon completion of the announced Tolling sale, significantly reducing financial encumbrances and releasing capital currently supporting those instruments.
With maturities extended to 2029, Conduent can continue investing in its core businesses and executing ASCEND 2026–28, the Company’s plan to accelerate profitable growth by standardizing its operations, specializing in the core solutions where it can lead and win, and scaling its go-to-market capabilities. The Company’s government and commercial programs, which millions of people rely on every day, continue without interruption.
“Deleveraging and de-risking are important priorities as we advance ASCEND 2026–28. We’ve extended our maturities, secured additional commitments from our banking partners and used divestiture proceeds to repay debt. Together with a meaningful reduction in our surety bond and letter-of-credit requirements, these actions strengthen our financial foundation and give us greater flexibility to invest in our core businesses and execute our strategy. They also support our mission to be the premier AI-led and technology-enabled business process partner for Government and Commercial clients, helping them modernize operations, enhance customer and constituent experiences, and achieve measurable business outcomes. Our banking partners’ commitment of new capital reflects their confidence in our strategy and our ability to execute ASCEND 2026–28,” said Harsha V. Agadi, Conduent President and Chief Executive Officer.
Lazard served as strategic advisor to Conduent.
About Conduent Conduent is a global technology-enabled operating partner that helps businesses and governments simplify complexity, modernize mission-critical operations and deliver measurable outcomes through AI, automation, data and human expertise. Learn more at www.conduent.com.
Forward-Looking Statements This press release may contain “forward-looking statements” as defined in the Private Securities Litigation Reform Act of 1995, as amended. The words “anticipate,” “believe,” “estimate,” “expect,” “plan,” “intend,” “will,” “aim,” “should,” “could,” “forecast,” “target,” “may,” “continue to,” “endeavor,” “if,” “growing,” “projected,” “potential,” “likely,” “see,” “ahead,” “further,” “going forward,” “on the horizon,” and similar expressions (including the negative and plural forms of such words and phrases), as they relate to us, are intended to identify forward-looking statements, but the absence of these words does not mean that a statement is not forward-looking. These statements include, but may not be limited to, statements regarding the Company’s Public Transit and Tolling business sales and our ability to meet the requirements and obligations under the new revolving credit facilities entered into in connection with the Transaction. These statements reflect our current views with respect to future events and are subject to certain risks, uncertainties and assumptions, many of which are outside of our control, that could cause actual results to differ materially from those expected or implied by such forward-looking statements contained in this press release, any exhibits to this press release and other public statements we make. Important factors and uncertainties that could cause our actual results to differ materially from those in our forward-looking statements include, but are not limited to: our significant indebtedness and the terms of such indebtedness; our ability to refinance, extend or replace our indebtedness on acceptable terms or at all; our failure to obtain or maintain a satisfactory credit rating and financial performance; and other factors that are set forth in the “Risk Factors” and other sections of our Annual Report on Form 10-K, as well as in our Quarterly Reports on Form 10-Q and Current Reports on Form 8-K filed with or furnished to the Securities and Exchange Commission. Any forward-looking statements made by us in this press release speak only as of the date on which they are made. We are under no obligation to, and expressly disclaim any obligation to, update or alter our forward-looking statements, whether because of new information, subsequent events or otherwise, except as required by law.
Trademarks Conduent is a trademark of Conduent Incorporated in the United States and/or other countries. Other names may be trademarks of their respective owners.
Conduent Incorporated (Nasdaq: CNDT), a global technology-driven business solutions and services company, today announced its collaboration with the New Jersey Department of Human Services to provide people in need across the state with chip-enabled EBT cards designed to prevent benefit theft and protect their funds. The new cards, which are available to clients of the Supplemental Nutrition Assistance Program (SNAP) and the Work First New Jersey (WFNJ) cash assistance program, also allow for tap-to-pay functionality – making it the first Conduent-supported state to include this capability.
“We are excited to make these more secure cards available to all residents who participate in SNAP or the WFNJ program. The chip-enabled cards provide an added layer of security and are an important tool in our ongoing efforts to safeguard benefits and protect residents who rely on this assistance from this type of widespread benefit fraud,” said New Jersey Human Services Commissioner Stephen Cha.
EBT cards for SNAP and other benefits have traditionally relied on magnetic stripes that are vulnerable to skimming, where criminals install devices on point-of-sale terminals or ATMs to steal card information. With chips, New Jersey cardholders can now insert their cards into the terminals rather than swiping them, adding a critical layer of protection.
Beneficiaries in New Jersey can also use their EBT cards to access benefits using tap-to-pay functionality. This means cardholders can simply tap their cards at enabled terminals, reducing the risk of benefit theft while improving speed and ease of use.
Cardholders should continue to lock their card when not in use. New Jersey EBT cards can be locked and unlocked at NJFamiliesFirst.gov or by using the ConnectEBT app, which is available in Apple App Store or Google Play Store. In addition to engaging card lock features, cardholders should always maintain the privacy of their four-digit personal identification number (PIN) and identifying card information.
“As thieves increasingly have targeted taxpayer-funded government benefits in recent years, chip-enabled payment technology has emerged as a key tool to reduce EBT theft, improve account security and ensure critical funds go to rightful recipients,” said Anna Sever, President, Government Solutions at Conduent. “Conduent is proud to help states deploy this technology that also offers more flexible, fast and convenient payment options, such as tap-to-pay.”
Aside from New Jersey, Conduent continues to work with several other states that have transitioned, or are in the process of transitioning, to chip-enabled cards. Earlier this year, the company announced a collaboration with Alabama to become the second state to roll out chipped EBT cards to all its beneficiaries statewide.
The chip-enabled technology is among Conduent’s VeriSight Anti-Fraud Solutions , a suite of innovative offerings that help agencies address fraud and theft risks in public benefit programs. The suite also includes the lock and unlock capabilities with ConnectEBT, plus adaptive theft detection tools for EBT customer service centers that can identify and block suspicious activity, such as unusual phone numbers or high call volumes.
Conduent is a national leader in government payment disbursements, having disbursed approximately $80 billion in government benefit payments in 2025. Conduent also supports U.S. government agencies with end-to-end solutions for healthcare claims processing, eligibility and enrollment, and child support administration.
About Conduent
Conduent is a global technology-enabled operating partner that helps businesses and governments simplify complexity, modernize mission-critical operations and deliver measurable outcomes through AI, automation, data and human expertise. Learn more at www.conduent.com .
Conduent is a trademark of Conduent Incorporated in the United States and/or other countries. Other names may be trademarks of their respective owners.
Media Contact: Neil Franz, Conduent, [email protected] , +1-240-687-0127
The $47.50-per-share deal represents a 58% premium as Salesforce expands its customer engagement capabilities and strengthens its position in AI-driven enterprise software.
Salesforce (NYSE: CRM) has announced an agreement to acquire customer engagement platform Braze (NASDAQ: BRZE) for approximately $5.66 billion in enterprise value, marking another major investment in artificial intelligence and enterprise software. The all-cash transaction, announced October 20, offers Braze shareholders $47.50 per share, representing a roughly 58% premium to the company’s previous closing price of $30.04.
The acquisition is designed to strengthen Salesforce’s marketing technology capabilities by combining its customer relationship management platform with Braze’s real-time customer engagement tools. The deal reflects growing demand for AI-powered software that helps businesses personalize customer interactions, improve marketing efficiency, and increase customer retention.
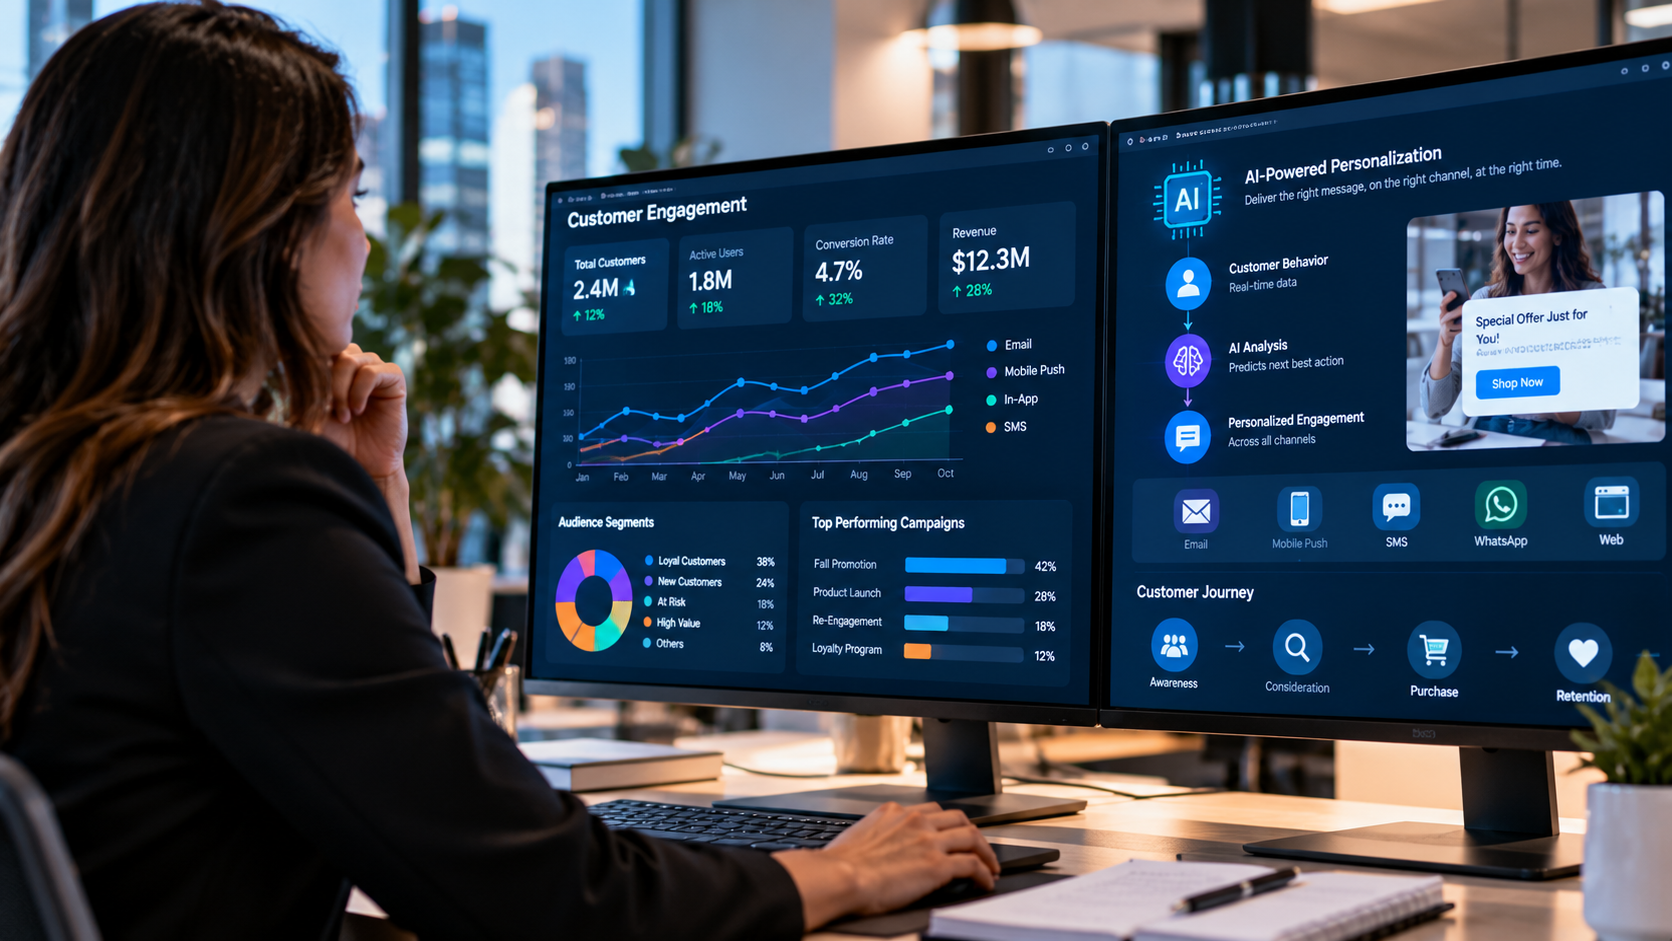
Braze specializes in helping companies communicate with customers across multiple digital channels, including email, mobile applications, websites, text messaging, and WhatsApp. Its technology analyzes customer behavior and allows businesses to deliver personalized messages based on individual preferences, purchasing activity, and engagement patterns.
The company serves approximately 2,770 customers, including Canva, Instacart, Urban Outfitters, Venmo, and Equinox. Its AI-powered platform, BrazeAI, helps businesses determine the most effective content, communication channels, and timing for customer interactions.
For Salesforce, the acquisition represents an opportunity to expand its Marketing Cloud platform while integrating Braze’s capabilities with its broader artificial intelligence strategy. Salesforce has increasingly focused on developing autonomous AI agents through Agentforce, enabling businesses to automate customer service, sales, and marketing activities.
Combining these technologies could allow businesses to move beyond traditional marketing automation toward more intelligent systems capable of responding to customer behavior in real time. For example, an AI-powered platform could identify when a customer abandons an online purchase and automatically deliver a personalized offer through the most effective communication channel.
The transaction also highlights intensifying competition across the enterprise software industry as major technology providers race to incorporate artificial intelligence into their products. Companies are investing heavily in automation, predictive analytics, and customer data platforms to help businesses improve productivity and generate measurable returns from AI adoption.
Investor reaction reflected the significant premium attached to the acquisition. Braze shares surged approximately 51% in early trading following the announcement, while Salesforce shares declined around 2% as investors evaluated the purchase price and potential integration costs.
The acquisition values Braze at more than six times projected annual revenue, illustrating the substantial valuations being placed on software companies offering differentiated AI capabilities and recurring subscription revenue.
For investors, the transaction reinforces the strategic importance of customer data and personalized engagement as businesses increasingly adopt artificial intelligence. It also raises questions about whether larger software companies can successfully integrate acquired technologies while maintaining profitability and delivering meaningful returns on investment.
The deal is expected to close during Salesforce’s fiscal year 2028, subject to shareholder approval, regulatory clearance, and customary closing conditions. Salesforce indicated that the acquisition is not expected to change its fiscal 2027 financial guidance.
The $5.7 billion transaction underscores a broader shift in enterprise technology, where artificial intelligence is transforming how companies interact with customers. As competition intensifies, businesses offering advanced automation, real-time analytics, and AI-driven personalization could become increasingly attractive acquisition targets for larger technology companies seeking to expand their capabilities.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Reaches $80 million class action settlement. Conduent agreed to settle consolidated class action litigation related to its previously disclosed January 2025 cybersecurity incident. The incident involved unauthorized access to the company’s networks beginning in October 2024 and exposed personal information belonging to approximately 62 million individuals. The agreement remains subject to court approval.
Addresses significant litigation exposure. The settlement seeks to resolve litigation stemming from the cybersecurity incident, including claims involving Conduent and affected clients. Upon final approval, the agreement would release Conduent, its affected clients, and their affected customers from covered claims arising from the incident. We believe the agreement provides greater visibility into a significant legal uncertainty that has weighed on the company’s broader turnaround efforts.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Overview. Resources Connection’s first-quarter results were within management’s revenue and gross margin outlook, while lower operating expenses helped profitability exceed our July projections. However, the Company has yet to demonstrate sustained revenue improvement. We believe pricing discipline and ongoing cost actions provide a foundation for recovery, but weak consultant utilization and recent cash consumption leave less room for an extended turnaround.
1Q27 Results. Revenue was $98.1 million compared to $120.2 million in 1Q26 and our $100 million estimate. Adjusted EBITDA was a loss of $3.6 million compared to $3.1 million in 1Q26 and our projected $5.5 million loss. Adjusted net loss was $0.16/sh. versus EPS of $0.03 in 1Q26 and our $0.22/sh. loss estimate. The earnings improvement relative to our forecast is encouraging, although it does not change the need for higher billable activity.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.