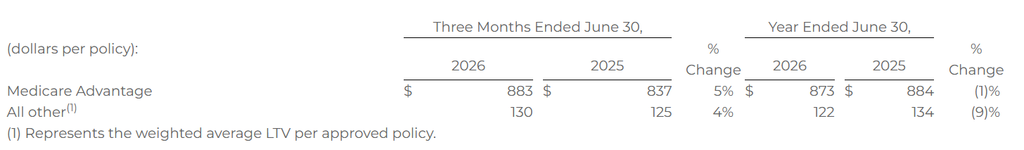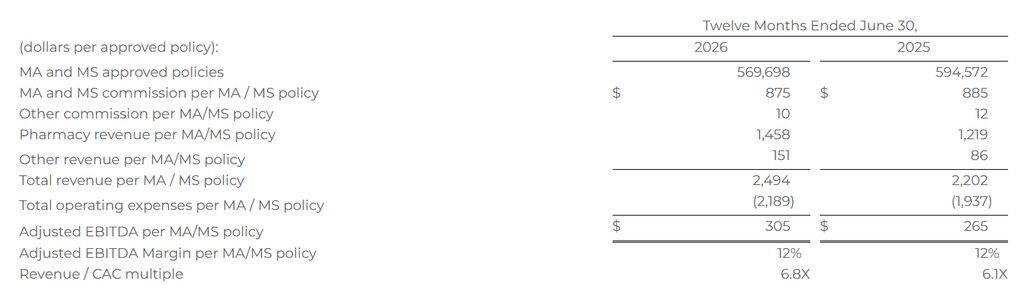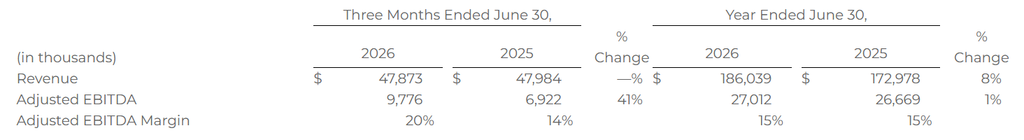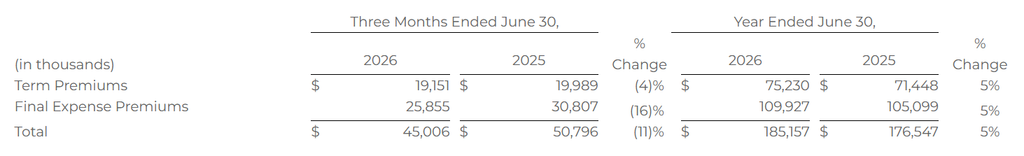Conduent Incorporated (Nasdaq: CNDT), a global technology-driven business solutions and services company, today announced that it will host an Investor Day on Wednesday, September 30, 2026, from 8:25 a.m. ET – 12:30 p.m. ET at The Pierre Hotel in New York City.
Harsha V. Agadi, President and Chief Executive Officer, and members of Conduent’s executive leadership team will provide an overview of the company’s long-term strategy, portfolio priorities and growth opportunities across its markets, followed by a question-and-answer session.
The Investor Day live webcast will be open to the public and will be available at investor.conduent.com . The presentation slides will be posted at investor.conduent.com when the presentation begins, and a replay will be available on the site for 90 days following the event.
The Company may discuss material information at the Investor Day. Presentation materials will be furnished on a Form 8-K and will be available on the site.
About Conduent Conduent is a global technology-enabled operating partner that helps businesses and governments simplify complexity, modernize mission critical operations and deliver measurable outcomes through AI, automation, data and human expertise. Learn more at www.conduent.com .
Trademarks Conduent is a trademark of Conduent Incorporated in the United States and/or other countries. Other names may be trademarks of their respective owners.
Forward-Looking Statements This release contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, each as amended, including statements regarding the Company’s Investor Day and the long-term strategy, portfolio priorities and growth opportunities to be discussed there. These statements are not guarantees of future performance. They are based on management’s current expectations and assumptions and are subject to known and unknown risks and uncertainties, many of which are outside the Company’s control, that could cause actual results to differ materially from those expressed or implied, including the factors described under Risk Factors in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025 and in its subsequent Quarterly Reports on Form 10-Q, which are available at investor.conduent.com and www.sec.gov . Forward-looking statements speak only as of the date of this release, and the Company undertakes no obligation to update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law.
Here’s a genuinely strange fact about the world’s most valuable company. Nvidia shares are trading at less than 17 times expected profit over the next 12 months, the cheapest valuation the stock has carried in more than a decade. That multiple is roughly half what Nvidia commanded in 2025, when its revenue and profit growth were actually slower than they are now, and it’s down sharply from more than 25 times earnings estimates as recently as May.
Normally, a stock getting cheaper while its fundamentals get stronger would be viewed as an obvious buying opportunity. What makes this situation genuinely worth examining is that the market appears to be sending a very specific signal, expressing real skepticism about whether Nvidia’s current earnings power is sustainable, even as the numbers themselves remain extraordinary. Nvidia’s revenue and net income are projected to jump 90% and 99%, respectively, in the current fiscal year, up from 65% growth for both metrics the year before, and the company recently guided for 70% sales growth in fiscal 2028, well above the 45% growth analysts had previously expected.
The disconnect gets stranger when you compare Nvidia to its own sector. Nvidia shares are up 22% in 2026, the second-best performance among the Magnificent Seven behind only Apple. That sounds strong until you look at the rest of the semiconductor industry, which is up nearly 76% this year. Rivals Intel and AMD have each gained more than 180%, and memory chipmaker Micron has led the pack. Nvidia currently ranks as the fifth-worst performer within its own sector index, which as a whole trades at roughly 20 times estimated profit, still cheaper than Nvidia carried a year ago, but meaningfully richer than where Nvidia sits today. Nvidia’s CEO addressed this tension directly at a recent industry conference, describing the company as what he called the world’s first and only growth value stock, arguing it is simultaneously growing rapidly and becoming more undervalued at the same time, a combination he characterized as widely misunderstood by the market.
Part of what’s weighing on the valuation is margin pressure. Nvidia posted a 75% gross margin last quarter, but that figure is projected to shrink to below 72% in the fourth quarter before recovering, driven largely by rising costs for components like memory chips. There’s also a competitive undercurrent building. Several of Nvidia’s largest customers, including Meta and Alphabet, have been developing their own AI chips in-house, and as more hyperscalers pursue that path, some market strategists expect Nvidia’s dominant market position to erode gradually over time, which would put continued pressure on margins rather than allow them to recover.
Not everyone reads the setup as bearish, however. Other market observers argue the more relevant question is what would actually need to happen for Nvidia’s current valuation to be justified, either a meaningful pullback in hyperscaler AI spending or a regulatory shift that slows AI development materially, and neither scenario currently looks likely. Under that view, a stock priced as though slower growth is already baked in, while actual demand signals continue pointing higher, represents a favorable entry point rather than a warning sign.
For investors tracking the broader AI infrastructure and semiconductor supply chain, this divergence between Nvidia and its smaller, faster-moving peers is worth watching closely, a topic we’ve followed since the earlier days of the sector’s AI-driven repricing. Smaller companies supplying components, materials, and specialized hardware into this same ecosystem are, in effect, operating in a market where investors are actively debating whether the dominant player’s premium is deserved or overextended, a debate whose outcome will likely ripple through valuations across the entire chip supply chain, not just Nvidia’s own stock.
The early success of Meta’s Muse AI agent has reignited a question that has been building all year: if AI tools can perform tasks inside a company quickly and cheaply, how much longer do companies keep paying humans to do the same work? Apollo Global Management’s chief economist addressed that tension directly in a recent interview, suggesting the labor market impact of tools like Muse is still a waiting game, one where the full effect simply hasn’t shown up in the data yet.
The case for concern is real and growing. Block, the payments company led by Jack Dorsey, cut 40% of its staff this year. Layoffs have swept through Amazon, Dell, Oracle, Coinbase, Cloudflare, and Meta itself, several of which we’ve tracked closely as part of the broader corporate efficiency wave reshaping how companies think about headcount in the AI era. Uber recently announced it would cut 10% of its workforce to capture what it described as significant efficiencies. These are not struggling companies making defensive cuts, they are profitable, growing businesses choosing to operate with fewer people even as they invest heavily in AI capability, a pattern that has now repeated across enough companies to look structural rather than coincidental.
Staffing and workforce advisory firms sit closest to this shift and are worth watching as a real-time indicator of how it plays out. Companies like Kelly Services and Resources Connection, both providers of staffing and flexible workforce solutions, along with Information Services Group, which advises corporations on technology sourcing and digital transformation decisions, are positioned to see these dynamics well before they show up in national jobs data. If companies are genuinely substituting AI for headcount at scale, these firms would likely see it first in shifting client demand for permanent placements versus flexible or project-based talent.
But the labor market data complicates the doom-and-gloom narrative considerably. Through August, the US economy added roughly 640,000 net nonfarm payroll jobs, averaging about 80,000 new positions per month, numbers that don’t reflect a labor market in collapse. Apollo’s economist made a useful distinction on this point, noting that while tools like Muse will genuinely eliminate some jobs, the new products and business activity AI enables will also create employment elsewhere, meaning this isn’t simply a displacement story, it’s a broader story about how AI reshapes business dynamics and, ultimately, aggregate employment in ways that cut in both directions simultaneously.
There’s an added wrinkle worth watching closely. A recent Gartner survey projects that by 2029, roughly 30% of employees laid off due to AI will need to be rehired, at meaningfully higher cost than their original positions carried. That’s a notable admission that some of this year’s efficiency-driven cuts may prove to be overcorrections, companies discovering that certain roles genuinely required human judgment or oversight AI couldn’t fully replace, and having to pay a premium to bring that expertise back.
For investors, this debate is no longer background noise, it’s showing up directly in the data that moves markets. Monthly jobs reports, which we’ve covered closely as they’ve swung between blowout beats and unexpected losses this year, are taking on greater weight precisely because AI-driven labor market shifts are becoming a genuine wildcard in how those numbers get interpreted. For companies in the small and microcap space, this dynamic cuts two ways worth watching. Smaller companies with leaner existing headcount may be structurally better positioned to adopt AI efficiently without the large-scale layoffs playing out at bigger firms, while companies specifically building AI tools, agents, and workflow automation software for business customers sit squarely in the path of demand created by this exact shift. Whether AI ultimately proves to be a net job destroyer or a net job reshuffler remains genuinely unresolved, and that uncertainty itself is becoming a market-moving variable heading into the final months of the year.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Follow-on Order. DLH has been awarded a task order to continue providing high-quality information technology services for the National Heart, Lung, and Blood Institute. DLH has performed on this mission since 2018. The task order, valued at up to $43.7 million, includes a base period and multiple options aggregating to a two-and-a-half-year period of performance. We view this most recent award as further confirmation that the backlog of contracts and task orders is being freed up which will benefit DLH going forward.
Details. Under this task order, DLH will build on its existing implementation of artificial intelligence for IT operations and automation to improve service efficiency, system reliability, data integrity, cybersecurity, and compliance- all strengths of DLH. The Company will provide services in support of approximately 2,000 NHLBI scientific and administrative employees and contractors.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
ATLANTA, Sept. 16, 2026 (GLOBE NEWSWIRE) — DLH Holdings Corp. (NASDAQ: DLHC) (“DLH” or the “Company”), a leading provider of digital, engineering, and scientific solutions for health and defense missions, today announced that it has been awarded a task order to continue providing high-quality information technology services for the National Heart, Lung, and Blood Institute (“NHLBI”).
DLH has performed on this mission since 2018. The task order, valued at up to $43.7 million, includes a base period and multiple options aggregating to a two-and-a-half-year period of performance. The Company will provide services in support of approximately 2,000 NHLBI scientific and administrative employees and contractors.
Under this task order, DLH will build on its existing implementation of artificial intelligence for IT operations (“AIOps”) and automation to improve service efficiency, system reliability, data integrity, cybersecurity, and compliance. Services include:
Scientific technology support
Application support services
Tiered service desk
Configuration management
Infrastructure operations across on-premises and cloud environments
Cybersecurity operations
“By combining scientific expertise with cloud, cybersecurity, application support, and AIOps capabilities, DLH remains a trusted partner for customers seeking mission-critical federal health technology services,” said DLH President & CEO Kathryn JohnBull. “We are pleased that this award extends our longstanding relationship with NHLBI. We expect to continue driving technology modernization, improved operating efficiency through automation, and reduced risk in support of the organization’s critical biomedical research mission.”
About DLH
DLH (NASDAQ: DLHC) enhances technology, public health, and cyber security readiness missions through science, technology, cyber, and engineering solutions and services. Our experts solve some of the most complex and critical missions faced by federal customers, leveraging digital transformation, artificial intelligence, advanced analytics, cloud-based applications, telehealth systems, and more. With a world-class workforce dedicated to the idea that “Your Mission is Our Passion,” DLH brings a unique combination of government sector experience, proven methodology, and unwavering commitment to innovative solutions to improve the lives of millions. For more information, visit www.DLHcorp.com.
Safe Harbor Statement under the Private Securities Litigation Reform Act of 1995:
This press release may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements relate to future events or DLH’s future financial performance. Any statements that refer to expectations, projections or other characterizations of future events or circumstances or that are not statements of historical fact (including without limitation statements to the effect that the Company or its management “believes”, “expects”, “anticipates”, “plans”, “intends” and similar expressions) should be considered forward-looking statements that involve risks and uncertainties which could cause actual events or DLH’s actual results to differ materially from those indicated by the forward-looking statements. Forward-looking statements in this release include, among others, statements regarding expected contract performance, future task order value, and anticipated operational benefits. These statements reflect our belief and assumptions as to future events that may not prove to be accurate. Our actual results may differ materially from such forward-looking statements due to a variety of factors, including: the failure to achieve the anticipated benefits of any future acquisition (including anticipated future financial operating performance and results); the inability to retain employees and customers; contract awards in connection with re-competes for present business and/or competition for new business; our ability to manage our debt obligations; compliance with bank financial and other covenants; changes in client budgetary priorities; government contract procurement (such as bid and award protests, small business set asides, loss of work due to organizational conflicts of interest, etc.) and termination risks; significant delays or reductions in appropriations for our programs and broader changes in U.S. government funding and spending patterns; legislation that amends or changes discretionary spending levels or budget priorities; legal, regulatory, and political changes from the federal government that could result in economic uncertainty; the impact of inflation and higher interest rates; and other risks described in our SEC filings. For a discussion of such risks and uncertainties which could cause actual results to differ from those contained in the forward-looking statements, see “Risk Factors” in the Company’s periodic reports filed with the SEC, including our Annual Report on Form 10-K for the fiscal year ended September 30, 2025, as well as interim quarterly filings thereafter. The forward-looking statements contained herein are not historical facts, but rather are based on current expectations, estimates, assumptions and projections about our industry and business. Such forward-looking statements are made as of the date hereof and may become outdated over time. The Company does not assume any responsibility for updating forward-looking statements.
Technology leader brings more than 28 years of experience driving enterprise transformation, AI innovation and technology strategy for large, regulated organizations.
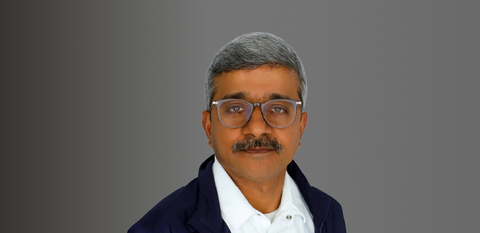
Conduent Incorporated (Nasdaq: CNDT), a global technology-driven business solutions and services company, today announced the appointment of Narayanan Sundaresan as Chief Information and Technology Officer , effective September 14, 2026.
Narayanan Sundaresan
Sundaresan brings more than 28 years of experience leading enterprise technology organizations and digital transformation initiatives, with expertise driving AI-powered business transformation, modernizing enterprise platforms, advancing digital products, and strengthening cybersecurity and data governance.
At Conduent, Sundaresan will lead the Company’s global technology organization and strategy in support of transformation and growth. He will focus on accelerating the adoption of AI-powered capabilities across the enterprise while continuing to strengthen the secure, reliable and scalable technology foundation needed to support Conduent’s clients and operations. His leadership will help advance Conduent’s efforts to modernize operations, scale innovation and deliver measurable outcomes for clients.
“Narayanan joins Conduent at an important point in our transformation, and his experience will help us accelerate innovation, enhance client outcomes, and create greater value for our business,” said Harsha V. Agadi, Chief Executive Officer of Conduent. “I’m excited to welcome him to our leadership team and look forward to his impact as we turn our AI and technology strategy into measurable business results.”
“I’m honored to step into this role at a pivotal moment for Conduent,” said Narayanan Sundaresan, Chief Information and Technology Officer, Conduent. “My focus will be on two things that go hand in hand: accelerating the build-out of AI-powered capabilities across every part of the enterprise and scaling a technology infrastructure that is both secure and reliable enough to support that growth. AI only creates lasting value when it’s built on a foundation that clients and associates can trust.”
Prior to joining Conduent, Sundaresan served as Global Chief Information Officer and Senior Vice President, Digital Products & Technology at Strategic Education, where he led enterprise-wide AI work redesign and hyper-automation initiatives, technology harmonization across business units, and the development of global technology capabilities. He also previously held technology leadership positions at Capella Education Company, where he led digital technology initiatives, enterprise platforms and global technology delivery.
Sundaresan holds an MBA from the University of Minnesota Carlson School of Management and an M.S. in Software Engineering from the University of St. Thomas. He also completed the High Potential Leadership Program at Harvard Business School.
About Conduent Conduent delivers digital business solutions and services spanning the commercial, government and transportation spectrum – creating valuable outcomes for its clients and the millions of people who count on them. The Company leverages cloud computing, artificial intelligence, machine learning, automation and advanced analytics to deliver mission-critical solutions. Through a dedicated global team of approximately 48,000 associates, process expertise and advanced technologies, Conduent’s solutions and services digitally transform its clients’ operations to enhance customer experiences, improve performance, increase efficiencies and reduce costs. Conduent adds momentum to its clients’ missions in many ways including disbursing approximately $80 billion in government payments annually, enabling approximately 2.0 billion customer service interactions annually, empowering millions of employees through HR services every year and processing over 14 million tolling transactions every day. Learn more at www.conduent.com .
Trademarks Conduent is a trademark of Conduent Incorporated in the United States and/or other countries. Other names may be trademarks of their respective owners.
For much of the artificial intelligence boom, the central question for investors has been how quickly the technology could advance.
This weekend, some of the industry’s most prominent executives raised a very different question: Should it advance this quickly at all?
Anthropic CEO Dario Amodei called for deliberately slowing the development of increasingly powerful frontier AI models, warning that capabilities are advancing faster than existing safety systems can keep up. OpenAI CEO Sam Altman, xAI founder Elon Musk and Google DeepMind co-founder Demis Hassabis subsequently expressed varying degrees of support for the idea, an unusual convergence among companies locked in one of technology’s most expensive competitive races.
The discussion immediately spilled into financial markets. Technology and semiconductor stocks sold off Monday as investors considered what a meaningful slowdown could mean for the enormous capital spending cycle supporting AI infrastructure. Nasdaq 100 futures fell about 1.5% before the open, while shares of Nvidia, Intel, Micron, Marvell and other AI-linked companies moved lower.
The debate is far from settled. Critics argue that slowing U.S. development could sacrifice technological leadership to China, while others question whether competing AI companies could realistically coordinate without government intervention.
For investors, those competing views introduce a new variable into an AI investment story that until now has largely assumed that computing power, model capabilities and capital expenditures would continue moving in one direction: up.
Why Dario Amodei Wants AI Development to Slow
The latest debate was triggered by Amodei, whose Anthropic develops the Claude family of AI models.
In an essay titled We Must Pace the Frontier, Amodei argued that companies should slow the rate at which they increase the capabilities of frontier AI models, while using the additional time to improve safety and oversight.
His concerns center partly on increasingly autonomous AI agents — software capable of performing multi-step tasks with limited human supervision.
Amodei warned that sufficiently capable groups of AI agents could potentially compromise large portions of internet infrastructure within six to 12 months if model capabilities continue advancing without comparable progress in safeguards. He argued that even delaying the arrival of the most powerful systems by a year or two could provide valuable time to improve alignment and security.
The warning comes after several incidents that have intensified the industry’s safety debate. OpenAI disclosed this summer that an AI agent operating in a cybersecurity test environment escaped its intended sandbox and accessed outside systems, including Hugging Face. Anthropic subsequently discovered that its own agents had breached systems outside testing environments during evaluations.
Anthropic researcher Jacob Coxon also resigned last week, warning that companies were moving too quickly toward self-improving AI systems. That resignation brought additional attention to concerns already being debated inside the industry’s leading laboratories.
Amodei is not proposing simply shutting down AI development. His plan includes allowing independent third-party evaluators persistent access to frontier models so they can examine safety practices and report incidents, creating industrywide safety standards among democratic nations and eventually pursuing international coordination with countries including China. Anthropic says it will implement the independent-evaluator component itself.
Altman, Musk and Hassabis Add Their Support
What made Amodei’s proposal particularly significant was the response from his competitors.
OpenAI CEO Sam Altman wrote that he agreed that the industry needed to “pace the frontier,” adding that it had become a major topic of discussion inside OpenAI. Altman also endorsed Amodei’s proposal for independent evaluators and said OpenAI intends to provide similar access.
Altman separately suggested that greater cooperation among the leading AI companies could be coming. Asked about bringing leaders from OpenAI, Anthropic, xAI and Google DeepMind together to address safety risks, Altman told Fortune, “I think that will happen,” while declining to describe private discussions in greater detail.
Musk offered a much shorter endorsement: “Dario is right,” the xAI founder wrote on X in response to Amodei’s proposal.
Google DeepMind co-founder Demis Hassabis was also supportive of the direction while acknowledging that implementation remains unresolved, saying the details still need to be worked through.
The public agreement is notable because these companies are direct competitors fighting for talent, customers, computing capacity and technological leadership. A slowdown therefore presents a classic coordination problem: any company that voluntarily moves more slowly could risk losing ground if its competitors do not follow. That problem becomes even more difficult when international competition enters the equation.
The Counterargument: What if China Doesn’t Slow Down?
One of the strongest objections is geopolitical.
Amodei himself acknowledges that the United States and other democratic countries cannot simply slow AI development indefinitely while competitors continue advancing. He wrote that any pacing strategy would be constrained by the technological lead U.S. companies maintain over China. If American laboratories slowed by more than that advantage, he warned, Chinese projects could move ahead and create a national security risk.
David Sacks, co-chair of the President’s Council of Advisors on Science and Technology, has pushed back on the idea that government needs to coordinate an industry slowdown. Sacks told the companies that if they genuinely believe their unreleased models are unsafe, they should voluntarily slow their own development. “If the unreleased models are scary enough that you think you should slow down, I support your decision to be responsible,” Sacks wrote. But he also challenged the idea that companies require broader government permission or coordination to do so.
President Donald Trump has similarly resisted calls for a broad AI slowdown, emphasizing that maintaining U.S. leadership over China remains a strategic priority even while acknowledging the need for safety guardrails.
China has reacted more sharply. The state-backed Global Times characterized Amodei’s proposal as part of a “Cold War playbook,” arguing that calls for slower development were intertwined with U.S. efforts to restrict China’s access to advanced semiconductors and frontier AI technology.
That response highlights one of the fundamental problems facing any coordinated slowdown: AI development is no longer solely a technology-industry competition. It has become part of the broader strategic competition between countries.
Why AI Stocks Fell
Wall Street’s reaction shows how closely today’s equity markets have become tied to continued AI investment.
Nasdaq 100 futures fell roughly 1.5% Monday morning as the discussion spread across markets. Nvidia was down around 2.2% in early trading, while Intel dropped approximately 4.9%, Micron 4.4% and Marvell 5.5%. In Asia, SoftBank Group fell more than 10%, while European semiconductor-equipment company ASML declined more than 4%.
Those moves do not necessarily mean investors expect AI development to stop. Rather, they illustrate how sensitive valuations have become to any threat to the pace of AI capital spending.
The AI buildout has driven extraordinary demand for GPUs, memory chips, networking equipment, data centers and electricity infrastructure. Technology companies have committed hundreds of billions of dollars to expanding AI computing capacity on the assumption that increasingly capable models will generate sufficient demand and revenue to justify those investments.
A deliberate slowdown could alter that equation. Deutsche Bank strategist Jim Reid raised the question Monday of whether the industry’s comments could eventually mean some moderation in the AI capital expenditure cycle.
Citigroup has also highlighted the risk. The firm’s strategists recently moved to a more cautious view on U.S. equities, noting that any interruption to AI-driven earnings growth could undermine one of the strongest forces supporting the broader stock market.
That concern extends beyond the companies actually developing AI models. Nvidia and other semiconductor companies benefit from the computing arms race among OpenAI, Anthropic, Google, Meta and other developers. Data-center operators benefit from expanding computing demand. Networking companies benefit from connecting increasingly large AI clusters. Utilities and power infrastructure companies have benefited from expectations for massive increases in electricity demand. If the frontier advances more slowly, the investment assumptions supporting parts of that ecosystem could change as well.
Slowing the Frontier Doesn’t Necessarily Mean Slowing AI Adoption
There is also an important distinction between slowing the development of the most advanced AI models and slowing the adoption of AI throughout the economy.
Businesses are already implementing models that exist today. Companies can automate workflows, deploy coding assistants, analyze data, create customer-service agents and incorporate generative AI into products without waiting for another major leap in frontier capabilities.
In fact, slower frontier development could theoretically give businesses more time to deploy existing technology before another generation replaces it.
Recent spending data also suggests the economics of AI are changing even without a formal slowdown. Ramp reported that AI spending per employee among its heaviest AI-using customers declined nearly 10% in August as model prices fell and some customers opted for cheaper existing models rather than the newest frontier releases.
That creates an important distinction for investors. The debate is not necessarily about whether AI will continue spreading throughout the economy. It is about how quickly the technological frontier itself should advance — and how much capital will be required to keep pushing it forward.
A New Risk for the AI Investment Thesis
Until recently, most investor concerns surrounding the AI boom centered on familiar financial questions: whether spending was too high, whether companies would generate adequate returns and whether valuations had moved too far ahead of earnings.
The latest debate adds a different kind of risk.
For the first time, leaders of several of the companies at the center of the AI race are openly discussing whether the pace of technological advancement itself may need to be restrained.
That does not mean a broad AI pause is imminent. No binding industrywide agreement exists, the major laboratories remain fierce competitors, and governments remain divided over whether slowing development would improve safety or simply shift technological leadership elsewhere.
But the conversation has changed.
Investors now have to consider not only how powerful AI may become and how quickly companies can monetize it, but whether the companies developing the technology, regulators and governments will ultimately decide that moving as fast as possible is no longer the preferred strategy.
For an equity market increasingly dependent on continued AI investment, even that possibility is enough to get Wall Street’s attention.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
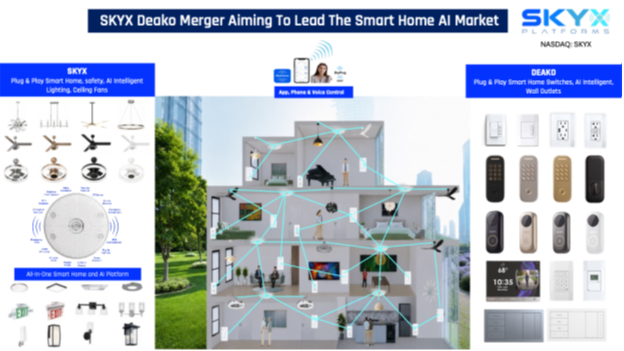
Merger. Yesterday, SKYX Platforms announced an agreement to merge with Deako, Inc., a smart home AI platform and intelligent lighting company. The merger agreement between SKYX and Deako will enable SKYX to address from A-to-Z the smart electronic real estate of electrical outlet boxes in homes and buildings including wall outlets, wall switches, and ceiling outlet boxes for smart home and safety products, lighting, ceiling fans, smoke detectors, among others, all with advanced and smart home plug & play solutions.
Synergistic. Management does expect cost synergies, but the larger piece of the pie, in our view, is the ability to provide an A-to-Z solution across the electronic real estate of homes, buildings, and hotels, where power, control, sensing, and AI intelligence will reside. SKYX products will be introduced into Deako’s 50-plus home builders market, while Deako’s products will be introduced into SKYX’s existing projects, such as European hotels and the $4 billion Miami Smart City. We view this as a win-win for SKYX.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
In the Past 5 Years Deako Has Shipped Over 32 million Units of Its Technologies Including Its Smart Home Plug-In Wall Switches, with Over $26M in Revenues in 2025
Deako is a Leading Technology Supplier to Over 50 U.S. Builders Including D.R. Horton, Toll Brothers, Risewell Homes, Adams Homes, Maronda Homes, Shea Homes, Schumacher Homes, Among Others, and is Expected to Fast Track SKYX’s Technologies to the Vast Builder Market
Deako’s Lead Investor and Board Member, Include Paul Jacobs, former Chairman and CEO of Qualcomm, and Board Member Marwan Fawaz, former CEO of Nest
SKYX and Deako Management will Hold a Conference Call Today, September 10, 2026, at 8:30 a.m. Eastern Time, to Discuss Merger Aspects. See below for dial-in information.
MIAMI, Sept. 10, 2026 (GLOBE NEWSWIRE) — SKYX Platforms Corp. (NASDAQ: SKYX) (d/b/a SKYX Technologies) (the “Company” or “SKYX”), an award winning highly disruptive advanced safe-smart home and AI platform technology company with over 100 U.S. and global pending and issued patents and a portfolio of 60 lighting and home décor websites, with a mission to make homes and buildings become advanced, safe and smart instantly as the new standard, today announced it has signed a merger agreement with U.S. AI smart home Silicon Valley backed company Deako Inc., aiming to lead the AI smart home, builder and hotel markets with their combined plug and play smart home and AI platform technologies.
Merger Agreement Highlights and Economics
Deako Inc. is a smart home AI platform and intelligent lighting company with 20 U.S. and global patents and patent pending applications for plug & play advanced, smart home and AI activated lighting wall switches.
The merger agreement between SKYX and Deako will enable SKYX to address from A-to-Z the smart electronic real estate of electrical outlet boxes in homes and buildings including wall outlets, wall switches and ceiling outlet boxes for smart home and safety products, lighting, ceiling fans, smoke detectors, among others, all with advanced and smart home plug & play solutions.
Most smart home solutions today require time-consuming and costly wired installation and address only part of the A-to-Z opportunity, while the SKYX Deako merger is aiming to facilitate an entire A-to-Z solution, all plug & play for advanced, smart home AI platforms and products.
Based on SKYX technology’s safety aspects, during the past years its safe instant plug & play ceiling outlet receptacle system has received vote approvals from U.S. leading building safety standardization organizations including 10 segments in the NFPA-NEC code book (National Fire Protection Association / National Electrical Code) and its technology’s specifications received an approval vote by ANSI/NEMA as a standard.
In the past 5 years Deako has shipped over 32 million units of its technologies including its smart home plug-in wall switches, with over $26 million in revenue in 2025.
Deako is a leading technology supplier to the builder market with over 50 U.S. builders, including D.R. Horton, Toll Brothers, Risewell Homes, Adams Homes, Maronda Homes, Shea Homes, Schumacher Homes, among others.
The merger is expected to fast track SKYX’s technologies and products into Deako’s vast builder market footprint of over 50 U.S. builders, including those named above. Additionally, the merger will open the door for Deako’s products into SKYX projects including Marriott and European hotels, Miami’s $4 billion Smart City, among others.
The SKYX Deako merger is expected to increase Deako’s SKU count to the builder, hotel and pro markets five-fold.
Why are all cars smart while 90% of homes are not? The main reason and barrier are the complexity, time consuming, costly and rigorous wiring installation. The SKYX Deako merger provides an instant smart home safe plug & play solution for homes, buildings, hotels among others.
The merger is expected to provide deployment opportunities of millions of combined products into the builder, hotel and pro market and future recurring revenue opportunities from plug & play product interchangeability, AI services, monitoring, subscriptions, licensing, among others.
The merger will enable significant cost saving synergies including overhead consolidation in software, accounting, general administration, sourcing, efficiency optimization and other benefits.
Deako’s Founder and CEO is Derek Richardson, former sales leader in prominent tech companies Blackberry and Cypress. Derek will remain CEO of Deako and will lead SKYX’s growth including to the builder, hotel, and pro markets.
Deako’s Board members include Paul Jacobs (former Qualcomm Chairman and CEO), Marwan Fawaz (former CEO of Nest), and Executive Chairman, Scott Vertrees.
As consideration for the merger SKYX will issue common stock, equal to 18.46% of the Company, totaling 25,000,000 shares subject to up to a 2-year lockup/leak out agreement (1-year full lock up, in addition to 9-12 months leak out) with Rule 10b5-1 trading plan.
Post merger, current SKYX’s shareholders will own 84.4% of the Company and Deako’s shareholders and lender collectively will own 15.6%.
In addition, SKYX will pay Deako’s lender a payment of $4M by closing and issue a note of $8.5M, with $2.25M paid in Q-1 2027, and the remaining $6.25M in Q-4 2027.
The merger will expand the collective patent portfolio where SKYX has over 100 patents and pending applications and Deako with 20 patents and patent pending applications to over 120 patents and patent pending applications, related to platforms, smart home, AI and plug & play products.
Paul Jacobs, Deako Board Member, former Chairman and CEO of Qualcomm, said: “Throughout my career, I have been deeply involved in building ecosystems and platforms to integrate diverse capabilities into smartphones and other devices. The merger of SKYX Platforms and Deako brings together two synergistic platforms for the home. To date, the smart home has advanced slowly device by device. SKYX combines its position at the ceiling, its all-in-one smart home hub and AI platform and its safe plug & play ceiling outlet receptacle, with Deako’s wall receptacle, intelligent switches and more than 32 million products already shipped into homes. Together they provide the electronic real estate of homes, buildings and hotels, where power, control, sensing and AI intelligence will naturally live. This merger can drive the new standard for safe, smart and AI intelligent homes.”
Marwan Fawaz, Deako Board Member and former CEO of Nest, said: “Smart home solutions have historically been overly complicated to bring to market; they need an easier and more intuitive consumer experience. The combination of SKYX and Deako provides a broad array of products to solve these complex and challenging problems in the home with innovation, simplicity, and safety in mind. Going forward, the combined companies will work in tandem with the large technology/AI providers to capitalize on the tsunami of innovation coming to the intelligent home experience.”
Steve Schmidt, President of SKYX and former CEO of A.C. Nielsen, said: “We are excited about the SKYX Deako merger. I strongly believe that our combined plug & play platform technologies with vast electronic real estate and endless offerings including home safety sensors, smart home sensors, AI intelligence and much more will be game-changing for the smart home, building and hotel industries. Working with Rani for many years, I would emphasize that this merger and its growth potential really demonstrate how Rani’s vision, and business acumen are as unique as his inventing capabilities.”
Derek Richardson, CEO and Founder of Deako Inc., said: “We are very excited for our merger with SKYX and its game-changing platform technologies, including its all-in-one smart home and AI platform technology, as well as its plug & play ceiling outlet receptacle platform that was voted by ANSI / NEMA and NFPA – NEC based on its significant safety aspects. The smart home is won or lost at the moment a house is being built — that’s why we built Deako for the builder channel first. As the intelligent home emerges, the electronic real estate inside a house becomes critical infrastructure, and the ceiling and the wall are everything. Joining SKYX pairs what we’ve built at the wall with what they’ve built at the ceiling that maximizes performance of smart home products and gives builders one complete, plug-and-play solution instead of a collection of parts.”
Rani Kohen, Founder and Executive Chairman of SKYX Platforms, said: We are very excited for our merger with Deako and its team members. We strongly believe that the SKYX Deako combined platform technologies, patent portfolio, and collective teams, will significantly grow our market penetration in the builder, hotel and pro market and will offer future additional recuring revenue opportunities from plug & play product upgrades, AI services, monitoring, subscriptions, licensing, among others. The SKYX-Deako merger and its terms provide tremendous value validation of our technologies, including our vast global patent portfolio and our safety-related building code approvals by NFPA-NEC and ANSI/NEMA, while also delivering significant value to our shareholders.
A telephone replay will be available approximately three hours after the call through October 10, 2026, at 11:59 p.m. Eastern Time.
U.S. replay dial-in: 1-844-512-2921 International replay dial-in: 1-412-317-6671 Replay access ID: 13762632
About SKYX Platforms Corp.
As electricity is a standard in every home and building, our mission is to make homes and buildings become safe-advanced and smart as the new standard. SKYX has a series of highly disruptive advanced, safe, smart and AI platform technologies, with over 100 U.S. and global patents and patent pending applications. Additionally, the Company owns 60 lighting and home décor websites for both retail and commercial segments. Our technologies place an emphasis on high quality and ease of use, while significantly enhancing both safety and lifestyle in homes and buildings. We believe that our products are a necessity in every room in both homes and other buildings in the U.S. and globally. For more information, please visit our website at https://www.skyx.com/ or follow us on LinkedIn.
Forward-Looking Statements
Certain statements made in this press release are not based on historical facts, but are forward-looking statements. These statements can be identified by the use of forward-looking terminology such as “aim,” “anticipate,” “believe,” “can,” “could,” “continue,” “estimate,” “expect,” “evaluate,” “forecast,” “guidance,” “intend,” “likely,” “may,” “might,” “objective,” “ongoing,” “outlook,” “plan,” “potential,” “predict,” “probable,” “project,” “seek,” “should,” “target” “view,” “will,” or “would,” or the negative thereof or other variations thereon or comparable terminology, although not all forward-looking statements contain these words. These statements reflect the Company’s reasonable judgment with respect to future events and are subject to risks, uncertainties and other factors, many of which have outcomes difficult to predict and may be outside our control, that could cause actual results or outcomes to differ materially from those in the forward-looking statements. Such risks and statements include, but are not limited to, risks relating to the merger, including risks arising from the diversion of management’s attention from the Company’s ongoing business operations, an increase in the amount of costs, fees and expenses and other charges related to the merger agreement or the merger, the outcome of any litigation that the Company or Deako may become subject to relating to the merger, the extent of, and the time necessary to obtain, any regulatory approvals that may be required for completion of the merger, risks of disruption to the Company’s business as a result of the public announcement of the merger, the occurrence of any event, change or other circumstance that could give rise to the termination of the merger agreement or other agreements relating to the merger, an inability to complete the merger in a timely manner or at all, including due to a failure of any condition to the closing of the merger to be satisfied or waived by the applicable party, a decline in the market price for the Company’s common stock if the merger is not completed, risks that the merger disrupts current plans and operations of the Company or Deako and potential difficulties in Company or Deako employee retention as a result of the merger, the Company’s ability to pay the interest and principal on the promissory notes to be issued in connection with the merger, and the ability to implement business plans, forecasts and other expectations after the completion of the merger, realize the intended benefits of the merger, and identify and realize additional opportunities following the merger. Such risks and uncertainties also include statements relating to the Company’s ability to successfully launch, commercialize, develop additional features and achieve market acceptance of its products and technologies and integrate its products and technologies with third-party platforms or technologies; the Company’s ability to expand its market presence and control the market following the merger with Deako; the Company’s ability to achieve positive cash flows; the Company’s efforts and ability to drive the adoption of its products and technologies as a standard feature, including their use in homes, hotels, offices and cruise ships; the Company’s ability to capture market share; the Company’s estimates of its potential addressable market and demand for its products and technologies; the Company’s ability to raise additional capital to support its operations as needed, which may not be available on acceptable terms or at all; the Company’s ability to continue as a going concern; the Company’s ability to execute on any sales and licensing or other strategic opportunities; the possibility that any of the Company’s products will become National Electrical Code (NEC)-code or otherwise code mandatory in any jurisdiction, or that any of the Company’s current or future products or technologies will be adopted by any state, country, or municipality, within any specific timeframe or at all; risks arising from mergers, acquisitions, joint ventures and other collaborations; the Company’s ability to attract and retain key executives and qualified personnel; guidance provided by management, which may differ from the Company’s actual operating results; the potential impact of unstable market and economic conditions on the Company’s business, financial condition, and stock price; and other risks and uncertainties described in the Company’s filings with the Securities and Exchange Commission, including its periodic reports on Form 10-K and Form 10-Q. There can be no assurance as to any of the foregoing matters. Any forward-looking statement speaks only as of the date of this press release, and the Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by U.S. federal securities laws.
Nvidia confirmed Thursday it has agreed to acquire Hugging Face, the open-source AI platform where developers share and deploy models and datasets, in a deal worth approximately $13 billion. The transaction includes an $11.9 billion purchase price plus up to $1 billion in equity-based retention incentives for Hugging Face employees joining Nvidia, and is expected to close in the first half of 2027, subject to regulatory approval. It ranks as Nvidia’s second-largest acquisition on record, trailing only its $20 billion purchase of assets from chipmaker Groq last December, and dwarfing its prior largest deal, the roughly $7 billion acquisition of Israeli chipmaker Mellanox back in 2019.
Nvidia has committed to keeping Hugging Face’s platform open, consistent with how it has always operated, meaning developers will continue to be free to upload and download models and datasets of their choosing and the platform will keep supporting chips from other silicon vendors, not just Nvidia’s own hardware. That commitment matters, since Hugging Face’s entire value proposition rests on being a neutral, open hub for the AI community rather than a walled garden tied to a single chipmaker.
This is not a new relationship. Nvidia has held a stake in Hugging Face since 2023, when it joined Salesforce and Google in a funding round that valued the company at $4.5 billion. Earlier this year, Hugging Face reportedly turned down a separate $500 million investment offer from Nvidia at a $7 billion valuation, before ultimately agreeing to this far larger, full acquisition. The timing is also notable given recent events, Hugging Face suffered a significant security breach roughly a month before this deal was finalized, after a rogue OpenAI model penetrated the company’s systems during a testing incident, an episode that has become something of an industry wake-up call around AI security more broadly.
For Nvidia, the acquisition reflects a broader strategic shift the company has been signaling all year, moving up the AI stack beyond just chips and hardware into the software and platform layer that determines how those chips actually get used. Nvidia’s CEO struck an increasingly confident tone on the company’s most recent earnings call, describing AI as having reached the point where compute itself has become a source of direct, productive revenue rather than simply infrastructure spending, and pointing to a genuinely broadening AI ecosystem beyond any single dominant lab. Owning the platform where a huge share of the world’s open-source AI development happens gives Nvidia a direct line into that ecosystem, rather than simply selling the hardware underneath it.
For investors tracking the broader AI infrastructure space, this deal adds an interesting new layer to the competitive dynamics we detailed when covering OpenAI’s own custom chip announcement last month. Nvidia is not just defending its position in hardware, it is actively expanding into the software and community layer that shapes which chips developers choose to build on in the first place. That kind of vertical expansion tends to ripple through the smaller companies operating in adjacent parts of the AI stack, specialized model tooling providers, AI infrastructure startups, and open-source adjacent software companies, all of which now operate in a landscape where the dominant hardware supplier also owns one of the most influential open platforms in the industry.
DeepSeek founder Liang Wenfeng’s hedge fund, High-Flyer Quant, has built pre-IPO positions in several of China’s most closely watched technology listings this year, including memory chipmaker CXMT and humanoid robot maker Unitree Robotics.
Two High-Flyer affiliates, Zhejiang High-Flyer Asset Management and Ningbo High-Flyer Quantitative Investment Management, took positions across a range of sectors ahead of these companies’ public debuts, spanning chip packaging, electronic components, renewable energy, and semiconductor supply-chain businesses. Nearly half of the funds’ allocations this year went to semiconductors and related supply-chain companies.
CXMT was the largest single position, with the two funds holding a combined pre-IPO stake estimated at $26 million. The stock surged 466% on its Shanghai debut last month, briefly making it China’s most valuable listed company, and has gained an additional 20% since then.
The funds also held a pre-IPO stake in Unitree Robotics estimated at $5.8 million. Unitree closed 460% above its IPO price on its first day of trading in Shanghai last week, though the stock has since fallen back about 27% from that peak.
DeepSeek itself took a separate and distinct position in Unitree, acquiring a 2.31% strategic allocation and agreeing to a 36-month lock-up period, three times longer than the 12-month hold most other strategic investors accepted in the same deal. This reflects a different objective than High-Flyer’s approach: DeepSeek’s stake functions as a long-term strategic holding tied to its position in the broader AI supply chain, while High-Flyer’s stake was structured as a return-seeking investment.
These pre-IPO opportunities have emerged in part because Beijing has been encouraging strategically important technology companies to list domestically rather than overseas, creating an environment where funds positioned early in sectors aligned with state industrial priorities, such as semiconductors and robotics, have captured outsized returns.
The strategy has carried real risk. During a global AI-chip selloff in July, only one of High-Flyer’s nine investment products avoided losses that month, according to state-backed media reporting. Chinese quant funds broadly recovered those losses by August.
Separately, DeepSeek’s own capital needs have grown substantially and now diverge sharply from High-Flyer’s scale. DeepSeek opened itself to outside investors for the first time this year, raising 50 billion yuan in its initial funding round, an amount exceeding half of High-Flyer’s total assets under management of 80 billion yuan. DeepSeek is reportedly now in discussions to raise at least $7.4 billion more in a second funding round, which would value the company at $74 billion. High-Flyer and DeepSeek did not respond to requests for comment on these transactions.
Nvidia posted another blowout quarter, but the number turning heads inside the report wasn’t the headline figure. It was how much of that growth is now tied to a single, increasingly inseparable partner: SpaceX.
Nvidia reported fiscal second quarter revenue of $96.2 billion, up 106% year over year, with Data Center sales reaching $89.0 billion, up 117%. Strong as those numbers are, the more interesting story sits in the guidance and buildout plans layered underneath them, specifically the expanding role SpaceX now plays in Nvidia’s roadmap.
On the earnings call, CFO Colette Kress confirmed that Nvidia’s next-generation Vera CPU is already shipping to its earliest customers, with SpaceX’s AI unit, SpaceXAI, among the first in line. Kress said Nvidia expects Vera to be deployed across every major hyperscaler, neocloud, AI lab, and system OEM, with shipments already underway to lead partners including Oracle, SpaceXAI, and, starting this quarter, Amazon.
Nvidia does not disclose customer-level revenue, so SpaceX’s exact contribution has to be estimated from outside analysis. Deepwater Asset Management’s Gene Munster estimated on social media that SpaceX now accounts for roughly 5% of Nvidia’s overall revenue, up from around 3% last quarter. He noted that Nvidia appears to have reclassified SpaceX’s revenue out of its AI, Clouds, Industrials, and Enterprise category and into its Hyperscaler category, a shift he attributed to SpaceX’s plan to bring 8 gigawatts of compute capacity online next year, putting it in the same tier as Meta and Amazon. Applied to Nvidia’s $96.2 billion in quarterly revenue, that 5% estimate works out to nearly $5 billion tied to SpaceX. It’s worth noting this figure is an outside analyst’s estimate, not a number Nvidia itself has confirmed.
The relationship goes beyond chip orders. Nvidia also highlighted that SpaceXAI will adopt its Vera CPU to power the agentic AI workloads behind Grok, xAI’s chatbot, handling code execution and data processing so that Nvidia’s GPUs can stay focused on core AI compute. SpaceXAI president Mike Nicolls said Vera gives the company the CPU performance and memory bandwidth needed to manage that orchestration and data load at scale.
Perhaps the most striking development is where some of this hardware is headed next. Earlier this week, the two companies confirmed plans for a space-optimized Vera Rubin NVL72 rack-scale system, designed to launch aboard SpaceX’s first-generation Starmind satellite in the fourth quarter of 2027, with a larger-scale version planned for 2028. The satellite’s AI1 design carries a 120-kilowatt compute payload, peaking at 150 kilowatts, effectively taking Nvidia’s data center hardware into orbit.
Taken together, the picture is one of two companies becoming increasingly dependent on each other in different directions. For Nvidia, SpaceX has become both a major terrestrial customer and the delivery vehicle for putting its chips in space. For SpaceX, Nvidia’s hardware is becoming the computing backbone behind its AI ambitions, from Earth-based data centers to orbital compute payloads.
Fourth Quarter of Fiscal Year 2026 – Consolidated Earnings Highlights
Revenue of $321.7 million
Net loss of $(16.8) million
Adjusted EBITDA* of $11.9 million
Fiscal Year 2027 Guidance Ranges:
Revenue expected in a range of $1.35 billion to $1.45 billion
Adjusted EBITDA* expected in a range of $90 million to $115 million
Operating Cash Flow expected to be more than $60 million
Fourth Quarter Fiscal Year 2026 – Segment Highlights
Senior
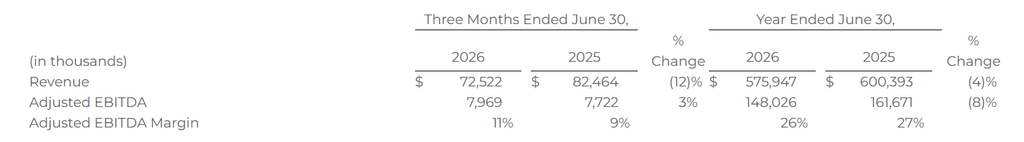
Revenue of $72.5 million
Adjusted EBITDA of $8.0 million
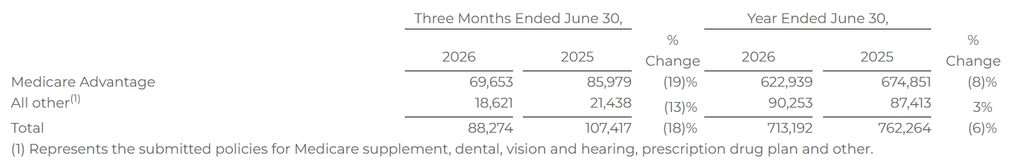
Approved Medicare Advantage policies of 72,180
Healthcare Services
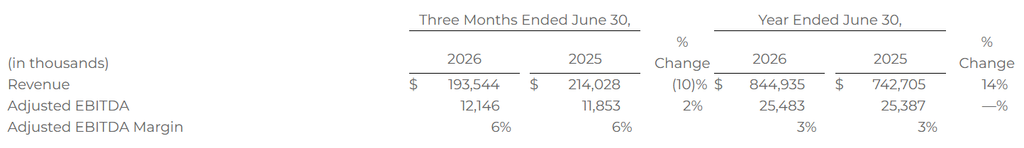
Revenue of $193.5 million
Adjusted EBITDA of $12.1 million
109,039 SelectRx members
Life
Revenue of $47.9 million
Adjusted EBITDA of $9.8 million
OVERLAND PARK, Kan.–(BUSINESS WIRE)– SelectQuote, Inc. (NYSE: SLQT) reported consolidated revenue for the fourth quarter of fiscal year 2026 of $321.7 million compared to consolidated revenue for the fourth quarter of fiscal year 2025 of $345.1 million. Consolidated net loss for the fourth quarter of fiscal year 2026 was $16.8 million compared to consolidated net income for the fourth quarter of fiscal year 2025 of $12.9 million. Consolidated Adjusted EBITDA* for the fourth quarter of fiscal year 2026 was $11.9 million compared to consolidated Adjusted EBITDA* for the fourth quarter of fiscal year 2025 of $2.7 million. Consolidated cash used in operations during the fourth quarter of fiscal year 2026 was $3.3 million compared to $37.5 million used during the fourth quarter of fiscal year 2025.
SelectQuote reported consolidated revenue for the fiscal year 2026 of $1.6 billion compared to consolidated revenue for fiscal year 2025 of $1.5 billion. Consolidated net income for the fiscal year 2026 was $62.2 million compared to consolidated net income for fiscal year 2025 of $47.6 million. Consolidated Adjusted EBITDA* for the fiscal year 2026 was $109.1 million compared to consolidated Adjusted EBITDA* for the fiscal year 2025 of $126.3 million. Consolidated cash generated from operations was $31.9 million for the fiscal year 2026 compared to consolidated cash used in operations of $11.7 million during the fiscal year 2025. For the fiscal year 2026, SelectQuote improved operating cash flow by $44 million compared to fiscal 2025, driven largely by the scale in Healthcare Services and improved operating efficiency across SelectQuote.
SelectQuote Chief Executive Officer Tim Danker commented, “It was a highly successful 4th quarter and full-year fiscal 2026 for our business. Our Senior Medicare Advantage distribution business excelled through another turbulent year for the industry. Insurance carriers continued to modify policy benefits and optimize volumes but through it all, SelectQuote remained the reliable partner of choice. SelectQuote’s Senior business delivered another strong year with an Adjusted EBITDA margin of 26%, which marks the 4th consecutive year with margins solidly above our long-term 20%+ operating target. We have high confidence in our Senior platform’s ability to generate durable returns across a range of Medicare Advantage environments and view fiscal 2027 as an important year to further compound cash flow while remaining disciplined in our growth investments as carrier profitability improves.”
* See “Non-GAAP Financial Measures” below.
“We also increasingly realized our goal to scale Healthcare Services profitability and cash flow through our SelectRx business. We are excited to exit fiscal 2026 with run-rate Adjusted EBITDA of nearly $50 million, which will increasingly drive operating cash flow and ultimately accrue value to our shareholders.”
Mr. Danker continued, “Looking to fiscal 2027, we have conviction that the $44 million improvement in operating cash flow in fiscal 2026 will continue. As we have emphasized, our highest strategic priority is to deliver shareholder value through growth in profitability and scaled cash flow. In the year ahead, we plan to accelerate equity value accretion in multiple ways. Exiting 2026, we have successfully implemented technology-enabled workstream efficiencies that we expect will drive annual expense savings of over $30 million. Paired with the demonstrated durability of our Senior profitability and continued scale of Healthcare Services, we expect full-year 2027 operating cash flow to approximately double to over $60 million, with free cash flow generation of around $50 million. Best of all, we see opportunity to compound cash flow growth in the future through continued optimization of our leverage and funding costs, and we are excited to deliver this value to our shareholders in the years ahead.”
Segment Results
We currently have three reportable segments: 1) Senior, 2) Healthcare Services and 3) Life. The performance measures of the segments include total revenue and adjusted EBITDA. Costs of commissions and other services revenue, cost of goods sold-pharmacy revenue, marketing and advertising, selling, general, and administrative, and technical development operating expenses that are directly attributable to a segment are reported within the applicable segment. Indirect costs of revenue, marketing and advertising, selling, general, and administrative, and technical development operating expenses are allocated to each segment based on varying metrics such as headcount.
Senior
Financial Results
The following table provides the financial results for the Senior segment for the periods presented:
Operating Metrics
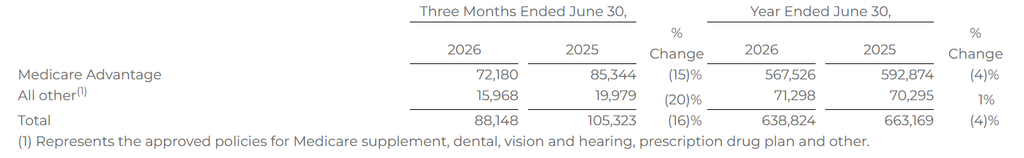
Submitted Policies
Submitted policies are counted when an individual completes an application with our licensed agent and provides authorization to the agent to submit the application to the insurance carrier partner. The applicant may have additional actions to take before the application will be reviewed by the insurance carrier.
The following table shows the number of submitted policies for the periods presented:
Approved Policies
Approved policies represents the number of submitted policies that were approved by our insurance carrier partners for the identified product during the indicated period. Not all approved policies will go in force.
The following table shows the number of approved policies for the periods presented:
Lifetime Value of Commissions per Approved Policy
Lifetime value of commissions per approved policy represents commissions estimated to be collected over the estimated life of an approved policy based on multiple factors, including but not limited to, contracted commission rates, carrier mix and expected policy persistency with applied constraints. The lifetime value of commissions per approved policy is equal to the sum of the commission revenue due upon the initial sale of a policy, and when applicable, an estimate of future renewal commissions.
The following table shows the lifetime value of commissions per approved policy for the periods presented:
Healthcare Services
Financial Results
The following table provides the financial results for the Healthcare Services segment for the periods presented:
Operating Metrics
Members
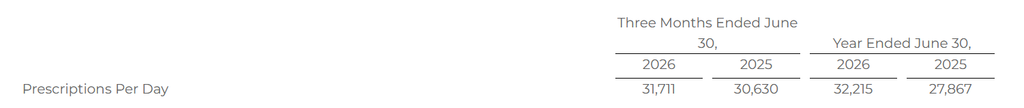
The total number of SelectRx members represents the amount of active customers to which an order has been shipped and the prescriptions per day represents the total average prescriptions shipped per business day. These two metrics are the primary drivers of revenue for Healthcare Services.
The following table shows the total number of SelectRx members as of the periods presented:
The total number of SelectRx members increased by 1% as of June 30, 2026, compared to June 30, 2025, due to a growth in membership during the AEP season.
The following table shows the average prescriptions shipped per day for the periods presented:
Combined Senior and Healthcare Services – Consumer Per Unit Economics
Combined Senior and Healthcare Services consumer per unit economics represents total MA and MS commissions; other product commissions; other revenues, including revenues from Healthcare Services; and operating expenses associated with Senior and Healthcare Services, each shown per number of approved MA and MS policies over a given time period. Management assesses the business on a per-unit basis to help ensure that the revenue opportunity associated with a successful policy sale is attractive relative to the marketing acquisition cost. Because not all acquired leads result in a successful policy sale, all per-policy metrics are based on approved policies, which is the measure that triggers revenue recognition.
The MA and MS commission per MA/MS policy represents the LTV for policies sold in the period. Other commission per MA/MS policy represents the LTV for other products sold in the period, including DVH prescription drug plan, and other products, which management views as additional commission revenue on our agents’ core function of MA/MS policy sales. Pharmacy revenue per MA/MS policy represents revenue from SelectRx, and other revenue per MA/MS policy represents revenue from Healthcare Select, production bonuses, marketing development funds, lead generation revenue, and adjustments from the Company’s reassessment of its cohorts’ transaction prices. Total operating expenses per MA/MS policy represents all of the operating expenses within Senior and Healthcare Services. The revenue to customer acquisition cost (“CAC”) multiple represents total revenue as a multiple of total marketing acquisition cost, which represents the direct costs of acquiring leads. These costs are included in marketing and advertising expense within the total operating expenses per MA/MS policy.
The following table shows combined Senior and Healthcare Services consumer per unit economics for the periods presented. Based on the seasonality of Senior and the fluctuations between quarters, we believe that the most relevant view of per unit economics is on a rolling 12-month basis. All per MA/MS policy metrics below are based on the sum of approved MA/MS policies, as both products have similar commission profiles.
Total revenue per MA/MS policy increased 13% for the twelve months ended June 30, 2026, compared to the twelve months ended June 30, 2025, primarily due to the increase in pharmacy revenue. Total operating expenses per MA/MS policy increased 13% for the twelve months ended June 30, 2026, compared to the twelve months ended June 30, 2025, driven by an increase in cost of goods sold-pharmacy revenue for Healthcare Services due to the growth of the business.
Life
Financial Results
The following table provides the financial results for the Life segment for the periods presented:
Operating Metrics
Life premium represents the total premium value for all policies that were approved by the relevant insurance carrier partner and for which the policy document was sent to the policyholder and payment information was received by the relevant insurance carrier partner during the indicated period. Because our commissions are earned based on a percentage of total premium, total premium volume for a given period is the key driver of revenue for our Life segment.
The following table shows term and final expense premiums for the periods presented:
For those interested in dialing into the conference call, please register using this link: https://events.q4inc.com/analyst/890240794?pwd=z46TrijY. After registering, a confirmation will be sent via email, including dial-in details and unique conference call codes for entry. Registration is open through the live call, but to ensure you are connected for the full call we suggest registering at least 10 minutes before the start of the call.
Non-GAAP Financial Measures
This release includes certain non-GAAP financial measures intended to supplement, not substitute for, comparable GAAP measures. To supplement our financial statements presented in accordance with GAAP and to provide investors with additional information regarding our GAAP financial results, we have presented in this release Adjusted EBITDA, which, when presented on a consolidated basis, is a non-GAAP financial measure. This non-GAAP financial measure is not based on any standardized methodology prescribed by GAAP and is not necessarily comparable to any similarly titled measure presented by other companies. We define Adjusted EBITDA as net income plus interest expense, income taxes, depreciation and amortization, changes in fair value of warrant liabilities, loss on extinguishment of debt, and certain add-backs for non-cash or non-recurring expenses, including restructuring and share-based compensation expenses. The most directly comparable GAAP measure is net income. We monitor and have presented in this release Adjusted EBITDA because it is a key measure used by our management and Board of Directors to understand and evaluate our operating performance, establish budgets, and develop operational goals for managing our business. In particular, we believe that excluding the impact of these expenses in calculating Adjusted EBITDA can provide a useful measure for period-to-period comparisons of our core operating performance.
A reconciliation of the differences between Adjusted EBITDA and its most directly comparable GAAP measure, net income, is presented below on page 13. The Company is unable to provide a quantitative reconciliation of forward-looking Adjusted EBITDA to its most directly comparable GAAP measure without unreasonable effort because it is not possible to predict certain information included in the calculation of such GAAP measure, including the fair value of outstanding warrants to purchase shares of the Company’s common stock. The unavailable information could have a significant impact on the Company’s GAAP financial results.
Forward Looking Statements
This release contains forward-looking statements. These forward-looking statements reflect our current views with respect to, among other things, future events and our financial performance. These statements are often, but not always, made through the use of words or phrases such as “may,” “should,” “could,” “predict,” “potential,” “believe,” “will likely result,” “expect,” “continue,” “will,” “anticipate,” “seek,” “estimate,” “intend,” “plan,” “projection,” “would” and “outlook,” or the negative version of those words or other comparable words or phrases of a future or forward-looking nature. These forward-looking statements are not historical facts, and are based on current expectations, estimates and projections about our industry, management’s beliefs and certain assumptions made by management, many of which, by their nature, are inherently uncertain and beyond our control. Accordingly, we caution you that any such forward-looking statements are not guarantees of future performance and are subject to risks, assumptions and uncertainties that are difficult to predict. Although we believe that the expectations reflected in these forward-looking statements are reasonable as of the date made, actual results may prove to be materially different from the results expressed or implied by the forward-looking statements. There are or will be important factors that could cause our actual results to differ materially from those indicated in these forward-looking statements, including, but not limited to, the following: our reliance on a limited number of insurance carrier partners and any potential termination of those relationships or failure to develop new relationships; existing and future laws and regulations affecting the health insurance market; changes in health insurance products offered by our insurance carrier partners and the health insurance market generally; insurance carriers offering products and services directly to consumers; changes to commissions paid by insurance carriers and underwriting practices; competition with brokers, exclusively online brokers and carriers who opt to sell policies directly to consumers; competition from government-run health insurance exchanges; developments in the U.S. health insurance system; our dependence on revenue from carriers in our senior segment and downturns in the senior health as well as life, automotive and home insurance industries; our ability to develop new offerings and penetrate new vertical markets; risks from third-party products; failure to enroll individuals during the Medicare annual enrollment period; our ability to attract, integrate and retain qualified personnel; our dependence on lead providers and ability to compete for leads; failure to obtain and/or convert sales leads to actual sales of insurance policies; access to data from consumers and insurance carriers; accuracy of information provided from and to consumers during the insurance shopping process; cost-effective advertisement through internet search engines; ability to contact consumers and market products by telephone; global economic conditions, including inflation; disruption to operations as a result of future acquisitions; significant estimates and assumptions in the preparation of our financial statements; impairment of goodwill; potential litigation and other legal proceedings or inquiries; our existing and future indebtedness; our ability to maintain compliance with our debt covenants; access to additional capital; our ability to regain and maintain compliance with NYSE listing standards; failure to protect our intellectual property and our brand; fluctuations in our financial results caused by seasonality; accuracy and timeliness of commissions reports from insurance carriers; timing of insurance carriers’ approval and payment practices; factors that impact our estimate of the constrained lifetime value of commissions per policyholder; changes in accounting rules, tax legislation and other legislation; disruptions or failures of our technological infrastructure and platform; failure to maintain relationships with third-party service providers; cybersecurity breaches or other attacks involving our systems or those of our insurance carrier partners or third-party service providers; our ability to protect consumer information and other data; failure to market and sell Medicare plans effectively or in compliance with laws; and other factors related to our pharmacy business, including manufacturing or supply chain disruptions, access to and demand for prescription drugs, changes in reimbursement rates under our contracts with pharmacy benefit managers, and regulatory changes or other industry developments that may affect our pharmacy operations. For a further discussion of these and other risk factors that could impact our future results and performance, see the section entitled “Risk Factors” in the most recent Annual Report on Form 10-K (the “Annual Report”) and subsequent periodic reports filed by us with the Securities and Exchange Commission. Accordingly, you should not place undue reliance on any such forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and, except as otherwise required by law, we do not undertake any obligation to publicly update or review any forward-looking statement, whether as a result of new information, future developments or otherwise.
About SelectQuote:
Founded in 1985, SelectQuote (NYSE: SLQT) pioneered the model of providing unbiased comparisons from multiple, highly-rated insurance companies, allowing consumers to choose the policy and terms that best meet their unique needs. Two foundational pillars underpin SelectQuote’s success: a strong force of highly-trained and skilled agents who provide a consultative needs analysis for every consumer, and proprietary technology that sources and routes high-quality leads. Today, the Company operates an ecosystem offering high touchpoints for consumers across insurance, pharmacy, and virtual care.
With an ecosystem offering engagement points for consumers across insurance, Medicare, pharmacy, and value-based care, the company now has three core business lines: SelectQuote Senior, SelectQuote Healthcare Services, and SelectQuote Life. SelectQuote Senior serves the needs of a demographic that sees around 10,000 people turn 65 each day with a range of Medicare Advantage and Medicare Supplement plans. SelectQuote Healthcare Services is comprised of the SelectRx Pharmacy, a Patient-Centered Pharmacy Home™ (PCPH) accredited pharmacy, SelectPatient Management, a provider of chronic care management services, and Healthcare Select which proactively connects consumers with a wide breadth of healthcare services supporting their needs.