Release – VivoPower Reports FY2026 Results Including a Partial-Period Contribution from Mo i Rana Data Center

Research News and Market Data on VIVO

November 03, 2026 08:18 ET  | Source: VivoPower PLC

Financial results for FY2026 are not reflective of full-year contribution from the Mo i Rana Data Center business

Mo i Rana data center results consolidated from 12 May 2026, being the date of effective completion

FY2026 revenue was US$2.6 million, primarily reflecting consolidation of the Mo i Rana Data Center

IFRS loss from continuing operations of US$50.4 million (FY2025: US$17.3 million, restated)

IFRS basic and diluted loss per share from continuing operations was US$(2.59) (FY2025: US$(2.60))

Adjusted EBITDA from continuing operations (non-IFRS) of US$(24.4) million (FY2025: US$(11.1) million, restated), or US$(11.3) million (FY2025: US$(9.2) million) before non-cash share-based payment expense of US$13.1 million

Post balance date, both the Data Center business unit and the Electric Vehicle business unit (Tembo) have respectively booked revenues in excess of FY2026 totals with both targeting EBITDA profitability

LONDON, UK, Nov. 03, 2026 (GLOBE NEWSWIRE) — VivoPower PLC (Nasdaq: VIVO) (“VivoPower” or the “Company”), a leading B Corp-certified global developer and owner of powered land and data center infrastructure for AI compute applications, today announced results for the fiscal year ended 30 June 2026 (FY2026).

Its Annual Report on Form 20-F was filed with the SEC on 2 November 2026, and the FY2026 results presentation is available on the Company’s website under investor relations.

Results Call

VivoPower will host a results call and webcast for investors and analysts on Tuesday, 10 November 2026 at 8:00 a.m. ET / 1:00 p.m. GMT / 2:00 p.m. CET / 9:00 p.m. SGT. Participants can join the call using the link on the investor relations page of the Company’s website.

Management will review the FY2026 results presentation and discuss the outlook for the group.

Group Level Overview

  • Profit and Loss: FY2026 revenues of US$2.6 million, reflecting part-period consolidation of Mo i Rana data center related revenues (from hosting of bitcoin mining). Consolidated group IFRS losses include US$13.1 million of non-cash share-based payment expense and US$14.8 million of non-cash fair-value losses on derivatives, warrants and other investments.
  • Balance Sheet: net assets increased to US$37.0 million (30 June 2025: US$17.2 million, restated), mainly from share issuances.
  • Interest-bearing debt: At 30 June 2026, loans and borrowings were US$28.8 million and lease liabilities (under IFRS standards) were US$10.3 million (relating to Mo i Rana). The US$28.8 million was principal owed to AWN, a related party. After year end it was settled with US$12.3 million in cash and US$16.5 million exchanged for convertible preference shares. Accrued interest of approximately US$16 million remains outstanding.

Data Center Segment

  • Financial results: revenues for the Data Center segment were US$2.5 million whilst operating profit was US$0.04 million for the 50 days to 30 June 2026. These result from existing hosting of bitcoin mining activities, not AI leases. This short-period result is not indicative of full-year performance and reflects one-off post-acquisition costs and some downtime for site works and maintenance undertaken to optimize for future performance as well as reduced bitcoin prices during this period. Post balance date, improved bitcoin prices and better-than-expected demand response revenues have translated into year-to-date results materially in excess of the FY2026 full-year results.
  • AI tenant selection: the Company launched a competitive process to select one or more AI compute tenants and announced a shortlist on 21 May 2026. The Company has decided not to pursue a lease with the tenant announced as preferred on 29 June 2026, given better offers presented to it in a rising rent market for powered land in the Nordics. It is now working to finalize definitive terms with another prospective AI tenant and concurrently working on financing options (refer below).
  • Conversion financing: alongside the tenant process, the Company is progressing discussions with prospective financiers to fund the first 40MW phase. Based on the Company’s current internal plans, the estimated capital expenditure for this phase is approximately US$411 million (a preliminary management estimate that may change materially). The Company expects to fund the conversion largely through project-finance debt and is also evaluating potential project-level co-development investment partnerships. In such an arrangement, VivoPower would contribute the operational powered land site whilst the co-development partner would provide the equity finance. In evaluating such partnerships, the Company would seek to retain a majority equity interest. In this regard, it is targeting project-level funding of approximately 70-75% debt and 25-30% equity. If the Company secures a suitable co-development partner for the equity and project finance for the debt, this could reduce the amount of its own funds required for the project. However, this is not assured, and the Company may require additional financing. In addition, tenants may provide prepayments or deposits, if agreed, which could help to fund the project capital expenditure.

Electric Vehicles Segment (Tembo)

  • FY2026 results: revenues for the Electric Vehicles segment were US$0.09 million (FY2025: US$0.05 million), reflecting conversion kit and vehicle sales by Tembo. This segment generated an operating loss of US$3.01 million, reflecting continued investment in product homologation and go-to-market programs. Post balance date, Tembo has booked revenues and received purchase orders in excess of the FY2026 result, with sharply higher diesel prices in its key markets fueling demand, and is targeting EBITDA profitability in FY2027.
  • Strategic status: on 2 July 2026, the Board resolved that the development and scale-up of the Company’s AI data center business is the principal strategic priority of the Group, and that its Tembo electric vehicle business and its Caret business are non-core businesses to be separated in a manner consistent with that priority. In respect of Tembo, previously contemplated special dividend arrangements have been discontinued and superseded by the proposed business combination with Cactus Acquisition Corp. 1 Limited (“Cactus”) described below, on completion of which the Company would retain a minority shareholding in the combined company.
  • Proposed Tembo business combination: on 29 August 2024, the Company entered into a business combination agreement with Cactus and Tembo, under which Tembo would become a subsidiary of a new holding company, Tembo Group B.V., which is proposed to be converted into a Dutch public limited liability company named Tembo Group N.V. and which would apply to list its shares on Nasdaq and in which the Company would retain a minority shareholding. A draft registration statement on Form F-4 for the transaction has been confidentially submitted to the SEC. Completion is subject to, among other things, the registration statement being declared effective, approval by Cactus’s shareholders, approval of the combined company’s initial listing application by Nasdaq under its current initial listing requirements, and other closing conditions. On 27 October 2026, Cactus’s shareholders approved an extension of the date by which Cactus must complete a business combination to 2 November 2027. Tembo’s results will continue to be consolidated in the Company’s results while the Company retains control of Tembo.

Non-IFRS Measures (from Continuing Operations)

Adjusted EBITDA from continuing operations is a non-IFRS performance measure calculated by adjusting IFRS loss from continuing operations for income tax, finance expense less finance income, the fair-value loss on financial instruments, depreciation and amortization, impairment losses, and the restructuring-related and other adjustments itemized in the reconciliation. This measure retains non-cash share-based payment expense.

Adjusted EBITDA from continuing operations before non-cash share-based payments is a further non-IFRS performance measure calculated by adding back to Adjusted EBITDA from continuing operations the expense recognized in continuing operations for professional fees settled in shares or other equity instruments and employee equity incentive awards. It excludes that expense, rather than treating it as having no economic cost.

Management believes that presenting both measures alongside IFRS loss helps investors distinguish changes in other operating costs from changes in equity-settled professional-fee and employee-award expense across periods. Neither measure should be considered in isolation or as a substitute for IFRS loss or other IFRS financial measures.
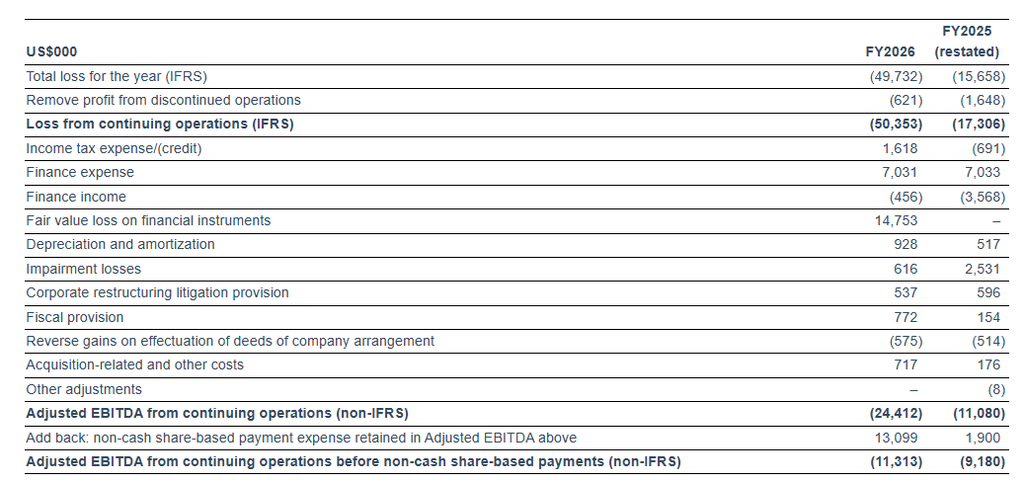

The reconciliation includes both the costs and the gains within the restructuring-related adjustments. Adjusted EBITDA from continuing operations includes non-cash share-based payment expense of US$13.1 million in FY2026 and US$1.9 million in FY2025. These costs can recur, and settling them in shares or other equity instruments can dilute shareholders. In this reconciliation, those amounts are added back only for the separately labelled measure before non-cash share-based payments. Neither non-IFRS measure is a measure of cash flow or liquidity, and similarly titled measures used by other companies may be calculated differently.

Source: VivoPower Annual Report on Form 20-F for FY2026, filed with the SEC on 2 November 2026 (Item 5 and Note 8).

Additional Information

Full details are in the Form 20-F, available at www.sec.gov and on the investor relations page of the Company’s website. Shareholders may request a free hard copy of the Annual Report by sending an email to [email protected]. Please read the results presentation with its disclaimer.

About VivoPower

Originally founded in 2014 and listed on Nasdaq since 2016, VivoPower is an award-winning B Corporation with data center and powered land infrastructure across Norway, Finland, and the United Arab Emirates. The Company’s mission is to be the independent, trusted partner for sovereign nations that develop and operate sustainable data center infrastructure, ensuring sovereign control over power, data, and national intelligence. In doing so, VivoPower helps sovereign nations bridge the gap between their energy assets and their AI ambitions by providing the Power-to-X infrastructure necessary to build and control their own domestic intelligence hubs.

Forward-Looking Statements

This announcement contains forward-looking statements, including statements about the Company’s strategy, future financial and operating performance, the proposed AI conversion and expansion of Mo i Rana, the AI-tenant selection and contracting process, estimated capital expenditure, construction and commissioning, project financing and funding mix, potential co-development arrangements, prospective tenant prepayments, future ownership interests, additional capital requirements and the expected effects of market conditions. Words such as “anticipate”, “believe”, “could”, “estimate”, “expect”, “intend”, “may”, “plan”, “potential”, “target” and “would” may identify forward-looking statements, but their absence does not mean a statement is not forward-looking.

These statements reflect management’s current expectations, estimates and assumptions, not guarantees of performance or completed transactions. Estimates of conversion cost, financing proportions, ownership, timing and tenant contributions may change materially as design, due diligence, negotiations, approvals and financing progress; a target or conditional scenario is not an approved or fully financed outcome, and the separate prerequisites for each scenario may not be achieved together.

The Company intends to rely on the forward-looking-statement protections of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934 only to the extent legally available. These protections do not apply to every statement, speaker or transaction, do not turn historical or current trading information into forward-looking information, and do not displace applicable disclosure or anti-fraud obligations.

Forward-looking statements speak only as of the date made, unless another date is expressly stated. Readers should not place undue reliance on them; except as required by applicable law, the Company undertakes no obligation to update them, and nothing in this statement limits any applicable duty to correct materially inaccurate or misleading information or to make a required disclosure.

Risk factors

Actual results could differ materially from those expressed or implied because of the following risks, among others. These risks should be read with the Company’s Annual Report on Form 20-F for FY2026, including Items 3.D, 5 and 15 and the financial-statement notes, and any subsequent SEC disclosures; this summary is not exhaustive.

  • AI tenant and conversion execution: The Company has not entered into a definitive AI-compute lease for Mo i Rana; discussions with a prospective tenant are not a lease, and there is no assurance that an agreement will be concluded on acceptable terms or at all. Tenant requirements, credit support, design, engineering, equipment supply, permits, power and grid arrangements, construction, commissioning and operating requirements may change, increase cost or delay or prevent the proposed conversion; existing energised capacity does not establish completed AI-ready capacity, contracted AI revenue or approval for additional capacity.
  • Conversion financing and ownership: Financing for the proposed AI conversion is not assured, and the Form 20-F states that the Company expects to fund the conversion largely through project-finance debt and may also require additional equity financing. A targeted debt ratio does not establish lender willingness, debt capacity, acceptable covenants or availability of funds; a prospective co-development partner’s contribution or a prospective tenant’s prepayment is not available cash unless agreed, funded and usable for the relevant expenditure. The Company may have to contribute additional cash, provide security or guarantees, issue further securities, accept less favourable economics or control rights, reduce its ownership interest, or defer or abandon the project; neither retention of majority ownership nor avoidance of further Company-level fundraising or dilution is assured.
  • Existing hosting, power and demand-response activities: Mo i Rana’s reported FY2026 revenue arose from existing bitcoin-mining hosting rather than an AI lease. Bitcoin prices, mining economics and customer credit or activity, Norwegian power prices, tariffs, hedging, grid availability and restrictions, regulatory changes, equipment downtime and maintenance, and the eligibility, availability, pricing and dispatch of demand-response services can affect revenue, margins and cash receipts; any favourable price movements or demand-response receipts may not recur, and prequalification does not guarantee dispatch or revenue.
  • Liquidity and subscription collections: At 30 June 2026 the Group had net current liabilities of US$11.95 million, and the Form 20-F reports an unsecured outstanding Ceres-led Regulation S subscription receivable of US$53.3 million at that date. It also reports that US$16.0 million of PIPE 2 proceeds remained outstanding at the date of the report, subject to completion of KYC approvals; neither a subscription commitment nor completion of an administrative process guarantees collection or its timing. Liquidity depends on actual cash receipts and payments, creditor arrangements and meeting obligations as they fall due, including acquisition instalments and other liabilities; failure or delay in collecting subscriptions or obtaining other necessary funds could adversely affect operations and the ability to continue as a going concern.
  • AWN, related parties and capital structure: The post-year-end settlement of US$28.8 million of AWN shareholder-loan principal comprised US$12.3 million paid in cash and US$16.5 million exchanged for convertible preference shares, rather than an equivalent cash repayment of all debt; the Form 20-F reports approximately US$16 million of accrued AWN interest still outstanding after those transactions. AWN is a related party, and the exchange did not eliminate the rights and economic claims represented by the preference shares or the remaining interest; settlement, conversion, dividends, warrants, reset terms, equity-settled fees and further fundraising can dilute ordinary shareholders, create competing economic priorities and materially affect reported results.
  • Operating, regulatory and geopolitical exposure: Power-market and grid regulation, environmental and planning requirements, counterparties, physical and cybersecurity incidents, supply-chain constraints, exchange rates and interest rates may adversely affect the Company’s operations and projects. Arctic Norge Data I AS is subject to the pre-acquisition Norwegian VAT and corporate-income-tax audit disclosed in the Form 20-F; resulting liabilities may not be recoverable from the seller, and disputes over recovery or withholding deferred acquisition payments could affect cash requirements. The Middle East conflict and other geopolitical developments may disrupt funding transfers, customer or investor payments, energy markets, logistics and business conditions; effects may be adverse.
  • Financial reporting and controls: The Company has restated FY2025 comparative financial information and reported that its disclosure controls and procedures and internal control over financial reporting were ineffective at 30 June 2026 because of material weaknesses, which remained outstanding at that date. Remediation may take time and may not be effective; errors, complex-transaction accounting, estimates, valuations or further adjustments could affect reported results, timeliness, access to capital and investor confidence.
  • Listing, status and trading: Maintaining Nasdaq listing and foreign-private-issuer status depends on continuing satisfaction of applicable requirements; loss of either status, further securities issuance, low liquidity or share-price volatility could adversely affect shareholders and financing access, and loss of foreign-private-issuer status could increase reporting and compliance obligations and costs. This risk statement is not a statement that a current Nasdaq deficiency exists.

Non-IFRS financial measures

Adjusted EBITDA from continuing operations and Adjusted EBITDA from continuing operations before non-cash share-based payments, where presented, are non-IFRS performance measures, not substitutes for IFRS loss, and not measures of cash generation, cash available for investment or debt service, or liquidity. Their definitions and reconciliations must be read with the IFRS results; similarly titled measures used by other companies may differ.

Ordinary Adjusted EBITDA from continuing operations retains non-cash share-based payment expense; the separately labelled before-share-based-payments measure adds back that expense. Excluded share-settled professional fees and equity awards have an economic cost, can recur, and can dilute shareholders; “non-cash” does not mean cost-free, exceptional or irrelevant to operating performance, and the timing or form of settlement does not itself establish the appropriate accounting or adjustment.

The measures should be considered only alongside the most directly comparable IFRS measures and the definitions, individual adjustments, explanations and reconciliations provided in this announcement. Presentation of an adjustment does not establish that its effects will not recur or that it represents cash saved; neither measure is an alternative statement of IFRS profitability.

Restatement of FY2025 comparatives

FY2025 comparative financial information is presented on the restated basis where indicated and should be read with Note 35 to the FY2026 Form 20-F, which describes the nature and financial effects of the restatement. Comparisons with previously published, unadjusted FY2025 amounts may therefore be misleading; the restatement does not eliminate the financial-control risks described above or provide assurance that future corrections will not be required.

Post-period and unaudited information

Post-30 June 2026 operating and trading information, where included, is unaudited unless expressly stated otherwise; the audit of the FY2026 financial statements is not an audit opinion on subsequent trading performance or a forecast. The applicable period, cut-off date, scope, accounting basis and comparison must be read with each such statement; periods of different lengths and a partial acquisition period are not automatically comparable.

Bookings, purchase orders, inquiries and indicative proposals are not necessarily IFRS revenue or collectible cash. Interim performance must not be annualised or treated as assurance of future profitability, and historical year-end cash does not represent cash available at the announcement date after subsequent receipts, payments and commitments.

Third-party and market information

Market, industry and third-party information is subject to the methodologies, assumptions, dates and limitations of the relevant provider. Market-wide trends, indicative rents, tenant interest, recent prices or general financing practices do not establish the terms available to the Company, the creditworthiness of a specific counterparty, a signed contract or an entitlement to tenant deposits.

Attribution to a third party does not relieve the Company of responsibility for its own statements or provide an independent audit of project assumptions, interim performance or forecasts. Nothing in this announcement should be read as an endorsement of those matters by the Company’s auditors.

No offer or solicitation

This announcement is for information and is not intended to constitute an offer to sell or a solicitation of an offer to buy securities, or an offering document. Any securities offering or sale must comply with applicable registration requirements or an available exemption and be made through the applicable offering documents; no offer or sale may be made in a jurisdiction where it would be unlawful.

Not investment advice / no reliance

This announcement does not provide personalised investment, legal or tax advice or an assessment of the suitability of any investment for a particular person. Investors should read the complete relevant SEC disclosures and offering documents, assess their own circumstances and, where appropriate, obtain independent professional advice; they should not rely on forward-looking statements or selected financial measures as a complete investment analysis.

Nothing in this announcement excludes or limits any liability or obligation under applicable securities laws or any non-waivable investor right. In particular, this section does not disclaim responsibility for accurate, non-misleading disclosure or ask investors to waive reliance on statements of historical or current fact.

Website and hyperlinks

Website addresses and hyperlinks are provided for convenience. Website contents are not incorporated into this announcement solely because an address or hyperlink is included; this statement does not alter any express incorporation by reference in an SEC filing, any applicable legal treatment of linked information or the Company’s disclosure obligations.

Investors should consult the dated announcement and the relevant SEC filings rather than assume that subsequent website changes update this announcement. The inclusion of a hyperlink does not itself verify the information or replace any required public disclosure.

Contact

Shareholder Enquiries
[email protected]
CrowdStrike Announces $495 Million AI Cybersecurity Acquisitions and New Kill Switch for Rogue AI Agents

CrowdStrike (NASDAQ: CRWD) announced Tuesday, November 3, that it has agreed to acquire two artificial intelligence cybersecurity startups for a combined $495 million, while introducing a new security feature designed to stop autonomous AI agents from performing unauthorized actions. The announcements highlight the growing importance of AI security as businesses increasingly deploy automated systems across their operations.

The cybersecurity company has signed agreements to acquire Fiddler AI and Dreadnode, two privately held startups specializing in monitoring artificial intelligence systems and identifying potential security vulnerabilities.

According to The Wall Street Journal, CrowdStrike will pay approximately $400 million for Fiddler AI and $95 million for Dreadnode. The company did not disclose the individual purchase prices in its official announcements.

The acquisitions are expected to strengthen CrowdStrike’s Falcon cybersecurity platform by expanding its capabilities beyond traditional endpoint protection into monitoring, testing, and controlling AI-powered applications.

Fiddler AI develops technology that allows organizations to monitor artificial intelligence systems and understand how autonomous agents make decisions. Its platform provides visibility into agent behavior, including which tools agents use, what information they access, and how they complete assigned tasks.

CrowdStrike plans to integrate these capabilities into a new offering called Falcon Observe, helping businesses identify unexpected AI behavior and maintain records of automated decisions.

Dreadnode focuses on identifying security weaknesses in artificial intelligence models and applications before they are deployed. Its technology uses automated testing techniques to detect vulnerabilities that could allow attackers to manipulate AI systems, bypass safeguards, or gain unauthorized access to sensitive information.

By incorporating Dreadnode’s technology, CrowdStrike aims to help customers identify and address potential threats before AI applications enter production environments.

Alongside the acquisitions, CrowdStrike introduced an AI Kill Switch within its Falcon Guardian platform, giving cybersecurity teams greater control over autonomous AI agents operating within corporate networks.

AI agents differ from traditional chatbots because they can independently execute tasks, interact with applications, access company information, and make decisions based on predefined instructions.

While these capabilities can improve productivity, they also introduce security risks when agents receive excessive permissions, encounter malicious instructions, or operate outside their intended boundaries.

CrowdStrike’s new feature allows authorized administrators to interrupt potentially dangerous AI activity through gateway controls, prevent affected agents from relaunching, and restrict their access to enterprise resources. Additional capabilities to terminate agents directly on endpoints are planned for a future release.

The company also introduced enhancements designed to inspect AI communications, detect malicious prompts, and enforce security policies across enterprise applications.

CrowdStrike CEO George Kurtz emphasized that maintaining control over autonomous systems will be essential as organizations accelerate their adoption of artificial intelligence.

The announcements come as cybersecurity companies compete to develop new products addressing the risks associated with agentic AI, a category of artificial intelligence capable of performing multistep tasks with limited human intervention.

For investors, the acquisitions demonstrate how artificial intelligence is creating new opportunities for cybersecurity providers, even as concerns persist that AI automation could disrupt traditional software business models.

Companies deploying AI agents may require additional security tools to monitor automated activity, protect sensitive data, and meet regulatory compliance requirements. This could create recurring revenue opportunities for cybersecurity vendors offering integrated protection and monitoring services.

The expansion of AI security also presents opportunities for smaller technology companies developing specialized capabilities in identity management, automated testing, data protection, and AI governance.

However, increased competition, acquisition integration costs, and uncertainty surrounding enterprise AI adoption could influence how quickly these investments generate returns.

CrowdStrike shares gained more than 2% in early trading following the announcements, reflecting investor interest in the company’s expanding AI security strategy.

Both acquisitions are expected to close during CrowdStrike’s fiscal fourth quarter of 2027, subject to customary closing conditions. The company anticipates making the related security capabilities generally available during the same period.

As businesses move from experimenting with artificial intelligence to deploying autonomous agents throughout their operations, CrowdStrike’s latest investments underscore a broader shift in cybersecurity toward protecting not only computers and networks, but also the increasingly independent software systems operating within them.

Information Services Group (III) – Riding the AI Wave


Tuesday, November 03, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

3Q26 Overview. ISG delivered a robust financial performance in the third quarter, with strong cash generation, expanding margins, and solid revenue growth. Revenue in the quarter was driven by a return to growth in Asia Pacific, up 47%, AI-related revenues reaching over $30 million for the first time, and recurring revenues continuing to build, up 7%. This mix of growth helped drive adjusted EBITDA margin expansion to 15.4%, the highest quarterly margin in four years.

3Q26 Results. Revenues for 3Q26 were $65.1 million, up 4.4% from $62.4 million in the prior year. Revenues were $41.9 million in the Americas, down 1%; revenues in Europe were $17.0 million, up 6% on a reported basis; and Asia Pacific revenues were $6.2 million, up 47% on a reported basis. ISG reported GAAP net income of $3.4 million, compared with net income of $3.1 million in the prior year. Fully diluted earnings per share were $0.07, compared with fully diluted earnings per share of $0.06 in the prior year. Adjusted EPS was $0.10, up from $0.09 in the prior year’s third quarter. Adjusted EBITDA was $10.0 million, up 19% from the prior year.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – Information Services Group Announces Third-Quarter 2026 Results

Research News and Market Data on III

11/2/2026

  • Reports third-quarter GAAP revenues of $65.1 million, up 4.4% versus prior year, exceeding guidance
  • Reports third-quarter GAAP net income of $3.4 million, up 10.3%; GAAP EPS of $0.07, up 10.2%, and adjusted EPS of $0.10, up 7.5%, all versus prior year
  • Reports third-quarter adjusted EBITDA of $10.0 million, up 19% versus prior year, exceeding guidance
  • Generates $12.3 million in cash from operations in the third quarter, highest amount in five years
  • Declares fourth-quarter dividend of $0.045 per share, payable December 18, 2026, to shareholders of record as of December 4, 2026
  • Sets fourth-quarter guidance: revenues between $64 million and $65 million and adjusted EBITDA between $9 million and $10 million

STAMFORD, Conn.–(BUSINESS WIRE)– Information Services Group (ISG) (Nasdaq: III), a global AI-centered technology research and advisory firm, today announced financial results for the third quarter ended September 30, 2026.

“ISG delivered a robust financial performance in the third quarter, with strong cash generation, expanding margins and solid revenue growth,” said Michael P. Connors, chairman and CEO. “Revenue in the quarter was driven by a return to growth in Asia Pacific, up 47 percent; AI-related revenues reaching over $30 million for the first time and recurring revenues continuing to build, up 7 percent. This mix of growth helped drive margin expansion to 15.4 percent, our highest quarterly margin in four years. AI is amplifying the value of our portfolio, with research that informs choices, advisory execution that secures outcomes for enterprises and governance that sustains value. We are well-positioned to close out an outstanding 2026 and continue our momentum into the new year.”

Third-Quarter 2026 Results

Reported revenues for the third quarter were $65.1 million, up 4.4 percent from $62.4 million in the prior year.

Revenues were $41.9 million in the Americas, down 1 percent on a reported basis. Revenues in Europe were $17.0 million, up 6 percent on a reported basis, and Asia Pacific revenues were $6.2 million, up 47 percent on a reported basis, all versus the prior year.

ISG reported third-quarter operating income of $6.5 million, compared with operating income of $4.6 million in the prior year. Reported third-quarter net income was $3.4 million, compared with net income of $3.1 million in the prior year. Fully diluted earnings per share were $0.07, compared with fully diluted earnings per share of $0.06 in the prior year.

Adjusted net income (a non-GAAP measure defined below under “Non-GAAP Financial Measures”) for the third quarter was $5.0 million, or $0.10 per share on a fully diluted basis, compared with adjusted net income of $4.7 million, or $0.09 per share on a fully diluted basis, in the prior year’s third quarter.

Third-quarter adjusted EBITDA (a non-GAAP measure defined below under “Non-GAAP Financial Measures”) was $10.0 million, up 19 percent from the prior year. Adjusted EBITDA margin (a non-GAAP measure calculated by dividing adjusted EBITDA by reported revenues) was 15.4 percent, compared with 13.5 percent in the prior year’s third quarter.

Other Financial and Operating Highlights

ISG generated cash from operations of $12.3 million in the third quarter, its highest amount in five years. The firm’s cash balance totaled $28.5 million at September 30, 2026, up 20 percent from $23.7 million at June 30, 2026. During the third quarter, ISG returned $6.9 million to shareholders through share repurchases ($4.5 million) and dividends ($2.4 million).

2026 Fourth-Quarter Revenue and Adjusted EBITDA Guidance

“Considering both market conditions and the strength of our portfolio, ISG is targeting fourth-quarter revenues between $64 million and $65 million and adjusted EBITDA of between $9 million and $10 million, continuing our year-over-year growth. We continuously monitor the macroeconomic environment, including the impact of FX, inflation and other factors, and will adjust our business plans as conditions warrant,” said Connors.

Quarterly Dividend

The ISG Board of Directors declared a fourth-quarter dividend of $0.045 per share, payable on December 18, 2026, to shareholders of record as of December 4, 2026.

Conference Call

ISG has scheduled a call for today, November 2, 2026, at 9 a.m., U.S. Eastern Time, to discuss the company’s third-quarter results. The call can be accessed by dialing +1 (833) 461-5787; or, for international callers, by dialing +1 (626) 884-3620. The access code is 410135322. A recording of the conference call will be accessible on ISG’s investor relations page for approximately four weeks following the call.

Forward-Looking Statements

This communication contains “forward-looking statements” which represent the current expectations and beliefs of management of ISG concerning future events and their potential effects. Statements contained herein including words such as “anticipate,” “believe,” “contemplate,” “plan,” “estimate,” “target,” “expect,” “intend,” “will,” “continue,” “should,” “may,” and other similar expressions, are “forward-looking statements” under the Private Securities Litigation Reform Act of 1995. These forward-looking statements are not guarantees of future results and are subject to certain risks and uncertainties that could cause actual results to differ materially from those anticipated. Those risks relate to inherent business, economic and competitive uncertainties and contingencies relating to the businesses of ISG and its subsidiaries including without limitation: (1) failure to secure new engagements or loss of important clients; (2) ability to hire and retain enough qualified employees to support operations; (3) ability to maintain or increase billing and utilization rates; (4) management of growth; (5) success of expansion internationally; (6) competition; (7) ability to move the product mix into higher margin businesses; (8) general domestic and foreign political and social conditions such as wars (including the conflict in Iran), political unrest and terrorism; (9) healthcare and benefit cost management; (10) ability to protect ISG and its subsidiaries’ intellectual property or data and the intellectual property or data of others; (11) currency fluctuations and exchange rate adjustments; (12) ability to successfully consummate or integrate strategic acquisitions; (13) outbreaks of diseases, including coronavirus, or similar public health threats or fear of such an event; (14) clients’ termination, delay, or reduction in scope of engagements, or inability to pay; (15) the effect of the divestiture of the automation unit on ISG’s relationships with its customers and suppliers and on its retained business generally; (16) the success of ISG’s focus on AI advisory and AI-powered platforms; (17) changes to trade policy, including new or increased tariffs, trade barriers and restrictions and changing import/export regulations; (18) inflation and changes in interest rates, and (19) potential employment-related claims. Certain of these and other applicable risks, cautionary statements and factors that could cause actual results to differ from ISG’s forward-looking statements are included in ISG’s filings with the U.S. Securities and Exchange Commission. ISG undertakes no obligation to update or revise any forward-looking statements to reflect subsequent events or circumstances.

Non-GAAP Financial Measures

ISG reports all financial information required in accordance with U.S. generally accepted accounting principles (GAAP). In this release, ISG has presented both GAAP financial results as well as non-GAAP information for the three and nine months ended September 30, 2026, and September 30, 2025. ISG believes that evaluating its ongoing operating results will be enhanced if it discloses certain non-GAAP information. These non-GAAP financial measures exclude non-cash and certain other special charges that many investors believe may obscure the user’s overall understanding of ISG’s current financial performance and ISG’s prospects for the future. ISG believes that these non-GAAP measures provide useful information to investors because they improve the comparability of the financial results between periods and provide for greater transparency of key measures used to evaluate the Company’s performance.

ISG provides adjusted EBITDA (defined as net income, plus interest, taxes, depreciation and amortization, foreign currency transaction gains/losses, non-cash stock compensation, interest accretion associated with contingent consideration, acquisition- and disposition-related costs, gains/losses on disposal of assets, gain on the sale of business, and severance, integration and other expense), adjusted net income (defined as net income, plus amortization of intangible assets, non-cash stock compensation, foreign currency transaction gains/losses, interest accretion associated with contingent consideration, acquisition- and disposition-related costs, gains/losses on disposal of assets, gain on the sale of business, and severance, integration and other expense on a tax-adjusted basis), and adjusted net income per diluted share, excluding the net tax effect of certain financial data, which are non-GAAP measures that ISG believes provide useful information to both management and investors by excluding certain expenses and financial implications of foreign currency translations, which management believes are not indicative of ISG’s core operations. These non-GAAP measures are used by ISG to evaluate the Company’s business strategies and management’s performance.

We evaluate our results of operations on both an as reported and a constant currency basis. The constant currency presentation, which is a non-GAAP financial measure, excludes the impact of year-over-year fluctuations in foreign currency exchange rates. We believe providing constant currency information provides valuable supplemental information regarding our results of operations, thereby facilitating period-to-period comparisons of our business performance and is consistent with how management evaluates the Company’s performance. We calculate constant currency percentages by converting our current and prior-periods local currency financial results using the same point in time exchange rates and then compare the adjusted current and prior period results. This calculation may differ from similarly titled measures used by others and, accordingly, the constant currency presentation is not meant to be a substitution for recorded amounts presented in conformity with GAAP, nor should such amounts be considered in isolation.

Management believes this information facilitates comparison of underlying results over time. Non-GAAP financial measures, when presented, are reconciled to the most closely applicable GAAP measure. Non-GAAP measures are provided as additional information and should not be considered in isolation or as a substitute for results prepared in accordance with GAAP. A reconciliation of the forward-looking non-GAAP estimates contained herein to the corresponding GAAP measures is not being provided, due to the unreasonable efforts required to prepare it.

About ISG

ISG (Nasdaq: III) is a global AI-centered technology research and advisory firm. A trusted partner to more than 900 clients, including 75 of the world’s top 100 enterprises, ISG is a long-time leader in technology and business services that is now at the forefront of leveraging AI to help organizations achieve operational excellence and faster growth. The firm, founded in 2006, is known for its proprietary market data and research, in-depth knowledge and governance of provider ecosystems, and the expertise of its 1,500 professionals worldwide working together to help clients maximize the value of their technology investments.

View full release here.

Source: Information Services Group, Inc.

Release – NETSOL Technologies’ equity research coverage initiated by Noble Capital Markets with outperform rating

NETSOL Technologies, Inc.

Research News and Market Data on NTWK

Download as PDF

October 29, 2026

Noble Capital Markets, selected by NETSOL following an extensive evaluation of equity research providers, initiates coverage with an outperform rating and a $9.00 price target

ENCINO, Calif., Oct. 29, 2026 (GLOBE NEWSWIRE) — NETSOL Technologies, Inc. (Nasdaq: NTWK), a provider of AI-enabled solutions and services powering OEMs, dealerships and financial institutions to sell, finance and lease assets, today announced that Noble Capital Markets, Inc. has initiated company-sponsored equity research coverage of the company with an outperform rating and a $9.00 price target. NETSOL selected Noble following an extensive evaluation of equity research providers.

The initiation report, authored by Michael Kupinski, Director of Research and Senior Research Analyst, and Jacob Mutchler, Research Analyst, at Noble Capital Markets, Inc., points to NETSOL’s long-standing customer relationships and the ongoing replacement of aging lender architectures with the company’s Transcend Platform as key growth drivers, alongside the increasing shift toward subscription-based revenue as adoption of Transcend grows.

The coverage follows a record year for NETSOL. For fiscal 2026, the company reported revenue of $74.4 million, up 12.5% and above guidance, while operating income nearly doubled to $6.9 million and year-end cash rose 56.3% to $27.1 million.

“We’re building on a strong start to fiscal 2027 with a clear agenda ahead of us,” said Najeeb Ghauri, Founder and Chief Executive Officer of NETSOL Technologies, Inc. “As we work to make our performance more predictable and our story more visible to the market, broader research coverage matters. It gives investors a deeper, independent view of where NETSOL is headed and we look forward to the wider reach Noble’s coverage will bring.”

Noble’s full initiation report is available on Channelchek, Noble’s investor research platform:
https://www.channelchek.com/news-channel/netsol-technologies-inc-ntwk-transcending-to-the-next-stage-of-growth

About NETSOL Technologies
NETSOL Technologies delivers state-of-the-art solutions for asset finance, leasing and digital automotive retail, serving automotive and equipment OEMs, dealerships, auto captives and financial institutions across over 30 countries. Since its inception in 1997, NETSOL has been at the cutting edge of technology, pioneering innovations with its asset finance solutions, and today leverages advanced AI and cloud services to meet the complex needs of the global market. Renowned for its deep industry expertise, customer-centric approach and commitment to excellence, NETSOL fosters strong partnerships with its customers, ensuring their success in an ever-evolving landscape. With a rich history of innovation, ethical business practices and a focus on sustainability, NETSOL is dedicated to empowering businesses worldwide, securing its position as the trusted partner for leading firms around the globe.

Forward-Looking Statements
This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the company’s products and services, expectations for future operations, and other statements that are not historical facts. These forward-looking statements may be identified by terminology such as “expects,” “anticipates,” “believes,” “intends,” “plans,” “projects,” “targets,” and similar expressions. These statements are not guarantees of future performance and are subject to a number of risks, uncertainties, and assumptions that are difficult to predict. Factors that could cause actual results to differ materially include, but are not limited to, the timing of customer go-lives and contract renewals, the rate of adoption of AI-enabled product capabilities, foreign currency volatility, and other factors discussed in NETSOL’s most recent Annual Report on Form 10-K and subsequent Quarterly Reports on Form 10-Q filed with the U.S. Securities and Exchange Commission. Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date hereof. NETSOL undertakes no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, or otherwise.

Investor Relations Contact:
Investor Relations
(818) 222-9195
[email protected]

Primary Logo

Source: NETSOL Technologies Inc.

Released October 29, 2026

Alphabet Stock Plunges as Nearly $500 Billion in Market Value Evaporates Amid AI Spending Concerns

Alphabet (NASDAQ: GOOGL), the parent company of Google, suffered a historic stock market selloff Thursday, October 29, with shares plunging approximately 12% to 13% as investors reacted to disappointing advertising revenue, soaring artificial intelligence spending, and an unexpected deterioration in free cash flow.

The decline put nearly $500 billion in Alphabet’s market capitalization at risk, potentially marking the largest single-day loss in the company’s history and one of the biggest market-value declines ever recorded by a publicly traded U.S. company.

The selloff followed Alphabet’s third-quarter earnings report Wednesday evening, which revealed a sharp contrast between extraordinary growth in its cloud computing business and mounting financial pressure from its aggressive AI infrastructure expansion.

Alphabet reported quarterly revenue of $127.6 billion, representing approximately 25% year-over-year growth but falling short of Wall Street expectations of $128.2 billion. The company’s adjusted earnings per share of $2.67 also missed analysts’ estimates of $3.02.

A major concern centered on Google’s core advertising business, which remains a critical source of revenue and profitability. Search revenue increased approximately 12% to $63.4 billion, below analysts’ expectations of roughly $65 billion.

Although double-digit growth would ordinarily represent a strong performance, investors have become increasingly concerned that generative AI could disrupt Google’s traditional search advertising model.

As more users turn to conversational AI tools and AI-generated search results, Google faces the challenge of maintaining advertising revenue while adapting its products to changing consumer behavior.

Company executives acknowledged that the growing adoption of AI-powered search experiences contributed to slower advertising growth. Monetizing conversational search remains an evolving process, raising questions about how quickly Google can translate AI engagement into revenue.

Meanwhile, Alphabet’s investment in AI infrastructure is accelerating at an extraordinary pace.

The company reported approximately $51.3 billion in capital expenditures during the third quarter, reflecting heavy investment in data centers, computing infrastructure, and specialized AI chips.

Those expenses contributed to negative free cash flow of approximately $9.1 billion, compared with expectations that the company would come close to breaking even.

Alphabet now expects capital expenditures of $195 billion to $205 billion for 2026, with spending projected to increase further in 2027.

The financial impact is particularly notable because Google has historically generated substantial cash flow from its search advertising operations. The shift toward negative free cash flow highlights the growing cost of competing in the global AI infrastructure race.

Despite the market’s negative reaction, Alphabet reported significant progress in cloud computing.

Google Cloud revenue more than doubled to approximately $30.7 billion during the quarter, exceeding analyst expectations as enterprise customers increased spending on AI infrastructure and cloud services.

The company also reported a cloud backlog of approximately $561 billion, reflecting substantial contracted demand for future services.

Google’s Gemini AI application surpassed one billion users, demonstrating the company’s ability to attract consumers to its artificial intelligence ecosystem.

However, the market’s reaction suggests that investors are increasingly prioritizing profitability, capital efficiency, and the ability to generate cash from AI investments rather than rewarding revenue growth alone.

The concerns extend beyond Alphabet. Microsoft, Amazon, Meta Platforms, and other major technology companies are collectively investing hundreds of billions of dollars in AI infrastructure, creating growing scrutiny over whether these expenditures will deliver sufficient financial returns.

Alphabet’s decline also weighed heavily on broader technology stocks, with the Nasdaq Composite falling more than 1% during Thursday’s trading session.

For smaller technology companies and emerging AI businesses, the selloff illustrates how investor expectations are shifting toward measurable financial performance. Companies seeking capital to develop AI products may face greater pressure to demonstrate sustainable revenue, competitive differentiation, and a credible path to profitability.

The decline also raises questions about valuations across the technology sector, where expectations for continued AI growth have supported substantial stock market gains.

Alphabet’s latest results reveal the difficult balance facing technology leaders: investing aggressively enough to remain competitive in artificial intelligence while protecting the profitability of established businesses.

As investors evaluate the next wave of technology earnings, Alphabet’s historic selloff could become a defining moment in the market’s reassessment of AI spending and the financial returns required to justify it.

NetSol Technologies, Inc. (NTWK) – Transcending to the Next Stage of Growth


Wednesday, October 21, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Initiating coverage. We are initiating coverage of NetSol Technologies, a global provider of lending, leasing, and digital retail software to auto captives, banks, and equipment lenders. In our view, NetSol’s long-standing customer relationships and Transcend platform position it to benefit as lenders replace aging systems and to shift more revenue from one-time licenses to recurring subscriptions.

A record year. Fiscal 2026 revenue rose 12.5% to a record $74.4 million. Recurring subscription and support revenue grew 8.7% to $35.8 million and accounts for nearly half of total revenue. We believe the increased adoption of the Transcend platform’s subscription model should improve revenue visibility and reduce reliance on individual contract wins.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Proofpoint to Buy Varonis (VRNS) for $6.3B in Major AI Security Deal

Cybersecurity giant Proofpoint has announced plans to acquire Varonis Systems (NASDAQ: VRNS) in an approximately $6.3 billion all-cash transaction, marking one of the largest cybersecurity deals of 2026. The acquisition reflects growing demand for advanced data protection as artificial intelligence transforms how businesses operate and manage sensitive information.

Announced October 15, the agreement will bring together Proofpoint’s expertise in email security, threat prevention, and human-centric cybersecurity with Varonis’ capabilities in data security, access management, and AI protection. The combined company aims to create a comprehensive platform capable of addressing increasingly sophisticated cyber threats.

Under the agreement, Varonis shareholders will receive $49.75 per share in cash, representing a 52% premium over the company’s June 22 closing price of $32.71, before initial acquisition speculation emerged.

The transaction values Varonis at approximately 8.4 times trailing twelve-month revenue and 53 times free cash flow, demonstrating the substantial valuations investors are assigning to companies positioned within the rapidly expanding AI security market.

Proofpoint, owned by private equity firm Thoma Bravo, will finance the transaction through committed equity and debt financing. Ontario Teachers’ Pension Plan will also invest in Proofpoint as part of the deal.

The acquisition is expected to close during the first half of 2027, pending shareholder and regulatory approvals. Following completion, Varonis will become privately held and its shares will cease trading on the Nasdaq.

The acquisition comes as businesses increasingly integrate generative AI and autonomous AI agents into everyday operations, creating new vulnerabilities involving sensitive corporate information.

AI-powered systems can access enormous amounts of enterprise data, raising concerns about unauthorized access, information leakage, and increasingly sophisticated cyberattacks.

Varonis specializes in identifying sensitive data, monitoring access permissions, and detecting suspicious activity across cloud and enterprise environments. Proofpoint brings established capabilities in protecting employees, communications, and digital interactions.

Combining these technologies could allow organizations to better understand who—or what—can access critical information while strengthening defenses against emerging AI-driven threats.

The companies expect their combined operations to serve more than 16,000 enterprises and millions of organizations worldwide.

The transaction underscores a broader consolidation trend across cybersecurity, where larger providers are acquiring specialized technologies to deliver integrated security platforms.

For investors, the acquisition highlights the strategic importance of data protection as enterprise AI adoption accelerates.

Rather than relying on numerous independent security vendors, businesses are increasingly seeking unified solutions capable of protecting employees, cloud infrastructure, sensitive information, and AI applications.

This shift could create additional acquisition opportunities for smaller cybersecurity companies offering differentiated technologies in data governance, identity protection, and AI threat detection.

However, premium valuations also introduce execution risks. Proofpoint must successfully integrate Varonis’ technology, retain customers, and demonstrate that its expanded platform delivers meaningful competitive advantages.

Proofpoint’s $6.3 billion acquisition of Varonis illustrates how artificial intelligence is reshaping cybersecurity investment priorities.

As enterprises deploy increasingly autonomous AI systems, protecting the information those systems access is becoming essential.

For the broader technology sector, the deal reinforces a significant investment theme: the growth of artificial intelligence is creating opportunities not only for companies developing AI, but also for those securing it.

Whether the acquisition delivers its anticipated benefits will depend on successful integration and continued enterprise demand for comprehensive AI security solutions.

Why Are AI Stocks Falling? Nvidia and CoreWeave Slide as Investors Question AI Spending

Nvidia (NASDAQ: NVDA), CoreWeave (NASDAQ: CRWV), and other artificial intelligence stocks came under selling pressure on October 15, 2026, as investors raised concerns about soaring AI infrastructure costs, debt financing, and whether massive technology investments will generate sustainable profits. Nvidia shares fell approximately 3% during Thursday morning trading, while CoreWeave extended losses following a sharp decline the previous session.

The broader AI stock selloff has affected semiconductor manufacturers, cloud computing providers, and data center companies. Despite continued demand for artificial intelligence technology, investors are becoming increasingly concerned about the financial risks associated with funding the industry’s rapid expansion.

Why Is Nvidia Stock Falling?

Nvidia shares declined alongside other semiconductor stocks as investors reassessed the sustainability of spending on artificial intelligence infrastructure.

The company supplies advanced processors used to train and operate AI models, making its business closely connected to spending by major technology companies and cloud computing providers.

Although demand for AI computing remains substantial, concerns about rising infrastructure costs and the financial health of companies investing heavily in AI have weighed on investor sentiment.

Advanced Micro Devices (NASDAQ: AMD) and Micron Technology (NASDAQ: MU) also recorded declines during Thursday’s trading session.

The Philadelphia Semiconductor Index lost more than $1.6 trillion in market capitalization over six trading sessions, illustrating the scale of the recent retreat in semiconductor stocks.

Why Is CoreWeave Stock Dropping?

CoreWeave has emerged as a focal point of concerns surrounding debt-financed artificial intelligence infrastructure.

The cloud computing company provides access to high-performance Nvidia processors and has relied heavily on borrowing to expand its data center operations.

CoreWeave shares fell more than 15% on Wednesday and continued declining during Thursday’s session as investors scrutinized the company’s substantial debt obligations.

Yields on some of CoreWeave’s corporate bonds climbed to distressed levels, highlighting growing concerns about the costs of financing its expansion.

With interest rates remaining elevated, companies dependent on borrowed capital face additional pressure to demonstrate that investments in computing infrastructure can generate sufficient revenue and cash flow.

Why Are AI and Data Center Stocks Falling?

The broader selloff reflects concerns about the extraordinary amount of money being invested in artificial intelligence infrastructure.

Major technology companies are spending billions of dollars on data centers, advanced semiconductors, networking equipment, and energy infrastructure to support increasingly sophisticated AI models.

While demand for computing capacity remains strong, investors are questioning whether future revenue will justify the enormous upfront costs.

There is also an important distinction between companies supplying AI infrastructure and those financing its development.

Semiconductor manufacturers can generate revenue by selling processors and related equipment. Data center operators, meanwhile, must recover substantial construction, equipment, and financing costs through long-term customer contracts.

This difference has become increasingly important as investors evaluate the financial sustainability of the AI investment cycle.

How Interest Rates Are Affecting AI Stocks

Higher borrowing costs are adding another layer of uncertainty for technology companies pursuing aggressive expansion strategies.

Recent inflation reports have increased expectations that the Federal Reserve could raise interest rates further, potentially making debt-financed infrastructure projects more expensive.

For companies with significant borrowing requirements, higher interest expenses can reduce profitability, constrain cash flow, and complicate future investment plans.

These concerns extend beyond AI infrastructure providers. The broader technology sector has experienced renewed volatility as investors reassess valuations and future growth expectations.

Is the AI Stock Selloff a Sign of a Bigger Technology Correction?

The recent decline in AI-related stocks highlights a broader shift in investor sentiment toward high-growth technology companies.

Investors are increasingly distinguishing between businesses demonstrating sustainable revenue growth and those relying on aggressive spending assumptions.

The selloff does not necessarily indicate that demand for artificial intelligence is weakening. Businesses continue adopting AI for automation, data analysis, cybersecurity, and enterprise software.

However, continued adoption does not guarantee that every company involved in the AI industry will generate sufficient profits to justify its valuation.

As technology companies face greater scrutiny, profitability, cash flow, debt levels, and the timing of investment returns may become increasingly important.

What Does the AI Selloff Mean for Small-Cap Technology Stocks?

For small-cap and emerging technology companies, changing market conditions could create both opportunities and challenges.

Businesses developing AI applications, semiconductor components, and infrastructure services may benefit from continued adoption of artificial intelligence.

However, tighter financing conditions could make it more difficult for smaller companies to raise the capital needed to expand operations or commercialize new technologies.

Companies with established customers, recurring revenue, and manageable debt levels may be better positioned to navigate heightened market scrutiny.

The recent volatility suggests that investors are becoming more selective about how companies finance growth and when those investments are expected to generate meaningful returns.

As artificial intelligence continues reshaping the technology industry, the next phase of the AI investment cycle may depend less on spending announcements and more on sustainable profitability and financial discipline.

IonQ to Acquire Zero Trust Security Firm Elisity in Deal Valued at Up to $1.3 Billion

IonQ (NYSE: IONQ) announced on Oct. 12 that it has agreed to acquire Elisity, a Zero Trust cybersecurity company, in an all-stock transaction valued at up to $1.3 billion. The deal pairs IonQ’s post-quantum cryptography (PQC) and quantum key distribution (QKD) technology with Elisity’s enterprise network security platform, and it extends IonQ’s push beyond quantum computing into security.

Founded in 2019, Elisity helps organizations apply Zero Trust principles to users, devices, workloads, AI agents, and other non-human identities. Its IdentityGraph product pulls together identity, asset, and risk data to set least-privilege access policies, letting teams simulate a policy before enforcing it and restrict each identity to only the communications it needs. IonQ says Elisity has more than 100 customer deployments, including a growing number of Fortune 500 companies, and has roughly doubled both revenue and customers year over year with no churn among deployed customers. IonQ also points to the microsegmentation market, which it sizes at more than $10 billion with double-digit annual growth.

IonQ is pitching a single security stack for two problems: attacks happening now, including those involving AI agents, and the longer-term risk that quantum computers eventually break today’s encryption. The companies plan to extend IdentityGraph with cryptographic inventory and risk information. IonQ CEO Niccolo de Masi said “Q-Day” is arriving faster than predicted, and compared the deal to IonQ’s earlier SkyWater Technology acquisition, which added chip design and fabrication capabilities. The announcement also cites a June 22, 2026 White House executive order and other federal directives pushing agencies toward PQC migration.

IonQ says its quantum-safe communications networks are already deployed in Switzerland, Poland, Romania, and Slovakia, and that multiproduct revenue grew 40% year over year in the second quarter of 2026. Elisity’s customer base and CISO relationships would give IonQ new channels to sell PQC, QKD, and quantum computing to enterprise and government buyers.

The transaction includes up to $150 million in earnout payments tied to Elisity’s performance. The number of IonQ shares issued will be set at closing using the 20-day volume-weighted average price before closing, with the price floored at $33.07 and capped at $49.61 per share. The deal is expected to close in the fourth quarter of 2026, subject to customary conditions including regulatory approval. Elisity will continue operating under its current leadership, including CEO James Winebrenner.

Closing risk, customer and employee retention, and integration are the main variables, all flagged in IonQ’s own forward-looking statements. Investors should also watch whether IonQ can turn the cross-sell story into reported revenue, and how the share issuance affects dilution given the price collar.

Release – VivoPower Mobilizes Construction of 40MW AI Data Center Conversion in Mo i Rana, Norway

Research News and Market Data on VIVO

October 12, 2026 08:15 ET  | Source: VivoPower PLC

     VivoPower has selected a global AI industry leader as its preferred AI tenant for the Mo i Rana facility

     Experienced Mo i Rana-based contractor Øijord & Aanes Entreprenørforretning AS engaged to deliver conversion site works in accordance with relevant permits and licenses

     Enabling works and main building superstructure to be delivered by Mo i Rana-based contractors, ahead of full mechanical and electrical fit-out by a specialist data center EPC firm

     VivoPower committed to engaging as many local suppliers and contractors as possible at Mo i Rana and plans to do the same at other future AI data center facilities globally

     VivoPower is also working to reuse waste heat from the AI data center for productive purposes in line with its Power-to-X strategy

LONDON, UK / MO I RANA, NORWAY, Oct. 12, 2026 (GLOBE NEWSWIRE) — VivoPower PLC (Nasdaq: VIVO) (“VivoPower” or the “Company”), a leading B Corp-certified global developer and owner of powered land and data center infrastructure for AI compute applications, today announced the mobilization of construction for the conversion of a 40MW first phase AI data center at its Mo i Rana facility in northern Norway. The Company also confirmed that the site works package will be delivered by experienced Mo i Rana-based contractors, Øijord & Aanes Entreprenørforretning AS, who have been operating in the region for more than 60 years.

Demolition, enabling works and the main building superstructure, amongst other elements, will be delivered by local Mo i Rana contractors, in accordance with applicable Norwegian planning and building regulations. These work packages will be completed in advance of the full mechanical and electrical fit-out of the facility, for which VivoPower has conducted a tender review process with leading international data center supply chain partners. The Company expects to award and announce this contract shortly and will update accordingly.

The design and delivery of the AI data center conversion will be in accordance with the AI tenant’s requirements. In addition, VivoPower is engaged with local industry on Power-to-X use cases, including the use of waste heat to support and promote local industry and community growth. Further details will be shared at the appropriate time.

Commitment to the Mo i Rana Supply Chain

VivoPower is committed to using as many local Mo i Rana suppliers and contractors as possible throughout the delivery of the project.

In addition to Øijord & Aanes Entreprenørforretning AS, the Company has already engaged with other local contractors, including:

  • IMTAS – a Mo i Rana-based provider of engineering, fabrication, installation and maintenance services across industry, construction and energy, operating from Mo Industripark; and
  • TH Blikk AS – a Mo i Rana-based building, façade and roofing contractor with more than 15 years of experience and a team of 64 employees.

By prioritizing local contractors, VivoPower aims to support employment, skills development and economic activity in the Rana region. It will also draw on the industrial expertise built up in the Mo i Rana industrial precinct over many decades.

VivoPower completed the acquisition of the operational Mo i Rana data center on April 21, 2026, and amongst other things has enrolled 30MW of the existing facility in grid balancing services, which provide support to the stability of the regional power grid.

Commitment to Power-to-X Use Cases

VivoPower’s Power-to-X strategy is focused on securing the highest and best use of every megawatt of its power infrastructure. At Mo i Rana, that extends beyond AI compute to the heat the facility generates and the flexibility it can offer the Norwegian power system.

The 40MW AI data center conversion is being designed with the aim of capturing waste heat from its cooling systems for productive reuse, subject to technical and commercial feasibility. VivoPower is working with a local district heating provider and European specialist firms to evaluate how that heat could be used. This includes supplying district heating to homes, businesses and community organizations in Mo i Rana and supporting the growth of heat-intensive local industries, including but not limited to land-based aquaculture and greenhouse food production.

Mo i Rana is well placed for this and reusing heat from the AI data center would build on that established model of industrial symbiosis. No definitive agreements have been entered into as yet in relation to heat reuse or other Power-to-X use cases, but VivoPower will provide further details as arrangements are finalized.

Shane Whelan, Chief Real Estate Officer of VivoPower, said: “We have deliberately engaged with the local construction supply chain, and we are delighted to be working with Mo i Rana firms such as Øijord & Aanes, IMTAS and TH Blikk. Their skills and local knowledge will be invaluable as we move from site works towards the mechanical and electrical fit-out phase. We remain committed to delivering on a ready-for-service (RFS) date as expeditiously as possible but without compromising quality and safety given the long-duration nature of the infrastructure asset being built.”

Stein Rune Øijord, Chief Executive Officer of Øijord & Aanes, said: “Øijord & Aanes looks forward to a strong and close collaboration with VivoPower. We are proud to contribute to an exciting project that creates new opportunities for Mo i Rana.”

Tommy Høgås, Chief Executive Officer of TH Blikk AS, said: “Blikk looks forward to the opportunity for a strong and exciting collaboration with VivoPower in the years ahead. New development is positive for the local community, and we recognize the wider benefits it will bring to other local businesses. We are grateful for the opportunity to be involved in this project and strongly believe in its potential – both for the stakeholders involved and for the city as a whole. We look forward to contributing and achieving great results together.”

About VivoPower

Originally founded in 2014 and listed on Nasdaq since 2016, VivoPower is an award-winning B Corporation with data center and powered land infrastructure across Norway, Finland, and the United Arab Emirates. The Company’s mission is to be the independent, trusted partner for sovereign nations that develop and operate sustainable data center infrastructure, ensuring sovereign control over power, data, and national intelligence. In doing so, VivoPower helps sovereign nations bridge the gap between their energy assets and their AI ambitions by providing the Power-to-X infrastructure necessary to build and control their own domestic intelligence hubs.

Forward-Looking Statements

This communication includes certain statements that may constitute “forward-looking statements” for purposes of the U.S. federal securities laws. Forward-looking statements include, but are not limited to, statements that refer to projections, forecasts, or other characterizations of future events or circumstances, including any underlying assumptions. The words “anticipate,” “believe,” “continue,” “could,” “estimate,” “expect,” “intends,” “may,” “might,” “plan,” “possible,” “potential,” “predict,” “project,” “should,” “would” and similar expressions may identify forward-looking statements, but the absence of these words does not mean that a statement is not forward-looking. Forward-looking statements in this communication include, for example, statements about the mobilization, timing, sequencing and completion of demolition, enabling and superstructure works; the expected timing of the award and announcement of the mechanical and electrical fit-out contract; the design, delivery, cost and ready-for-service date of the 40MW AI data center conversion; the engagement of local and international contractors and suppliers; the finalization of tenant agreements; the potential reuse of waste heat and other Power-to-X use cases; participation in grid-balancing services; and the anticipated economic benefits to the Mo i Rana region.

These statements are based on VivoPower’s management’s current expectations or beliefs and are subject to risk, uncertainty, and changes in circumstances. There is no certainty that the 40MW AI data center conversion will be completed on the timeline currently anticipated, within the currently estimated budget, or at all. Actual results may vary materially from those expressed or implied by the statements herein due to risks, uncertainties and contingencies including: (i) delays in obtaining, or failure to obtain, the demolition license, the Rana kommune building permit, grid connection and energization approvals or other regulatory approvals, or the grant of such approvals on different terms or conditions; (ii) construction, contractor and supply chain risks, including contractor performance, labor availability, weather and site conditions; (iii) cost overruns and fluctuations in the prices of materials, equipment, labor and energy; (iv) the risk that the mechanical and electrical fit-out contract is not awarded on the expected timing or terms, or at all; (v) delays in AI hardware procurement; (vi) the risk that the tenant breaches or defaults on its definitive lease agreements; (vii) the risk that waste heat reuse and other Power-to-X use cases do not prove technically or commercially feasible, and that no definitive agreements are entered into in relation to them; (viii) changes in economic, business, competitive and/or regulatory factors, geopolitical events and general market volatility; and (ix) other factors set forth in VivoPower’s filings with the United States Securities and Exchange Commission. The information set forth herein should be read in light of such risks. VivoPower is under no obligation to, and expressly disclaims any obligation to, update or alter its forward-looking statements, whether as a result of new information, future events, changes in assumptions or otherwise.

Contact

Shareholder Enquiries
[email protected]
FCC Clears SpaceX to Launch 15,000 Direct-to-Phone Satellites, Putting Wireless Carriers on Notice

The FCC approved SpaceX on Wednesday, Oct. 7, to launch and operate up to 15,000 next-generation Starlink Mobile satellites that connect directly to ordinary smartphones. SpaceX has about 650 mobile satellites in orbit today. Elon Musk said on X that the new V2 constellation will deliver more than 100 times the bandwidth of the current system.

The company says the upgraded network will deliver 5G speeds of up to 150 Mbps per user, using spectrum from T-Mobile and airwaves SpaceX purchased from EchoStar. That goes beyond patching dead zones: it is a bid to offer real mobile broadband from space.

Existing rules assumed satellite operators would lease spectrum from a terrestrial carrier, which made carriers the gatekeepers. Because SpaceX now owns roughly 65 MHz of spectrum, acquired from EchoStar in two deals totaling about $19.6 billion, the FCC waived the leasing requirement, citing competition in retail wireless service. In practice, SpaceX can sell phone service without a carrier’s sign-off, which weakens the leverage of T-Mobile, its current direct-to-cell partner. SpaceX President Gwynne Shotwell added that the spectrum has terrestrial components and the company intends to build out on the ground as well.

The timeline is long. Launches are slated to begin in late 2027, and SpaceX cannot use the EchoStar spectrum commercially until the remaining part of that deal closes, expected by Nov. 30, 2027. Half the constellation must be in orbit by Oct. 7, 2032, and the full network by Oct. 7, 2035.

Capacity is also a question. Moving from about 650 to 15,000 satellites is roughly a 23-fold increase, so a 100x bandwidth gain implies each satellite carries about four times today’s load. But 150 Mbps is a peak figure, and satellite beams share capacity across wide areas. How the network performs under heavy demand in dense cities remains unproven. That points to rural and roaming customers as the first to feel competitive pressure.

AT&T, Verizon, and T-Mobile formed a satellite-to-phone joint venture on Oct. 2, but it still needs another company’s satellites. Verizon’s and AT&T’s current satellite arrangements rely on AST SpaceMobile, whose network is not yet built. AST shares fell about 4% on the news. AT&T may be the most exposed: revenue was $126 billion in fiscal 2025, down from $134 billion in 2021, so even modest rural losses would show.

The approval came from an FCC bureau rather than the full commission, so it could be reviewed. On Oct. 29, the FCC votes on auctioning 25 MHz of spectrum for direct-to-device service, and a carrier win there would narrow SpaceX’s lead. Investors should also watch whether launches begin on schedule in late 2027. Analysts project SpaceX revenue rising from $45.1 billion in fiscal 2026 to $200 billion in fiscal 2028.

Release – ISG Launches Marketing Advisory Practice to Turn Marketing Investment into Business Value

Research News and Market Data on III

10/6/2026

New ISG research finds revenue and profit are top priorities for marketers, but returns lag expectations

STAMFORD, Conn.–(BUSINESS WIRE)– Information Services Group (ISG) (Nasdaq: III), a global AI-centered technology research and advisory firm, today announced the launch of ISG Marketing Advisory, a comprehensive suite of consulting, design and implementation services for enterprise marketing leaders.

The new practice helps marketing organizations strengthen financial accountability and translate productivity and performance into measurable return on investment. The business launches as the new ISG State of Enterprise AI: The AI Value Gap report, based on a survey of 400 executives at large global organizations – including marketing leaders – finds a significant gap between investments, productivity gains and marketing’s financial results.

“The role of the Chief Marketing Officer is entering a new era of enterprise influence,” said Kaveri Camire, partner, ISG Marketing Advisory. “Brand, customer engagement and demand generation remain essential, but AI is rapidly expanding both the capabilities and the complexity of marketing. At the same time, CEOs, CFOs and boards increasingly expect marketing leaders to demonstrate a direct contribution to revenue, profitability and growth.”

Fifty-six percent of the marketing leaders surveyed by ISG identify revenue growth as a key objective for AI initiatives, yet results for profit, cost savings and revenue underperformed expectations by double digits.

“More than one-third of marketers say time saved through AI has not directly translated into savings or value for the enterprise,” Camire said. “The next challenge for marketing leaders is to turn AI-driven efficiency and performance into measurable growth and ROI.”

ISG Marketing Advisory helps enterprises connect marketing investment to revenue impact with expertise in:

  • Benchmarking marketing investment performance and peer companies;
  • Operating model and strategy design across workflows, talent and technology to improve productivity and performance;
  • Marketing ecosystem optimization across martech, agencies and service providers to eliminate duplication and identify clear business impact, and
  • Governance frameworks that ensure sustained, measurable value.

The new practice also draws on ISG’s expertise as the world’s leading sourcing advisor. ISG influences more than $200 billion in technology spend annually, spanning IT, finance and accounting, human resources, supply chain, contact centers, marketing and other enterprise functions.

In a recent engagement, a global cosmetics and beauty company achieved 45 percent savings across marketing services as part of a broader ISG-advised enterprise transformation. ISG helped restructure the company’s global provider ecosystem, strengthen commercial terms and accountability and establish a framework to govern and measure performance. The resulting marketing model freed capacity for the client to reinvest in higher-value priorities aligned with the company’s strategic growth objectives.

“Marketing leaders are managing increasingly complex portfolios of technology, agencies, service providers, data and talent, often through outdated ways of working,” Camire said. “Without a modern operating model to orchestrate these resources, greater investment can simply create greater complexity. We are working with marketing leaders to shape the next generation of their organizations and to strengthen the contribution marketing makes to profitable enterprise growth.”

Additional information on ISG Marketing Advisory is available here.

About ISG

ISG (Nasdaq: III) is a global AI-centered technology research and advisory firm. A trusted partner to more than 900 clients, including 75 of the world’s top 100 enterprises, ISG is a long-time leader in technology and business services that is now at the forefront of leveraging AI to help organizations achieve operational excellence and faster growth. The firm, founded in 2006, is known for its proprietary market data and research, in-depth knowledge and governance of provider ecosystems, and the expertise of its 1,500 professionals worldwide working together to help clients maximize the value of their technology investments.

Source: Information Services Group, Inc.