Release – Graham Corporation Reports Second Quarter Fiscal 2027 Results

Graham Corporation

Research News and Market Data on GHM

November 05, 2026 6:30am ESTDownload as PDF

Second Quarter Fiscal 2027 Highlights:

  • Net sales of $69.8 million, increased 6% compared to the prior year reflecting strength of diversified revenue base and the addition of FlackTek
  • Gross profit increased 38% to $19.7 million; Gross profit margin was 28.2%, up 650 basis points compared to the prior year reflecting improved mix and operational efficiencies
  • Net income per diluted share was $0.39 an increase of 39%; Adjusted net income per diluted share(1) was $0.52 an increase of 68%
  • Adjusted EBITDA (1) increased 64% to $10.3 million; Adjusted EBITDA margin(1) was 14.8%, up 530 basis points compared to the prior year
  • Orders (2) were $73.7 million; Book-to-Bill (2) ratio of 1.1x and record backlog (2) of $561.3 million marking the seventh consecutive quarter of record quarterly backlog(2)
  • Strong cash generation with $46.7 million of cash provided by operating activities during the second quarter; cash of $71.4 million and no outstanding debt at quarter end
  • Reaffirming full year fiscal 2027 guidance for net sales and adjusted EBITDA

BATAVIA, N.Y.–(BUSINESS WIRE)– Graham Corporation (NYSE: GHM) (“GHM” or the “Company”), a global leader in the design and manufacture of mission critical fluid, power, heat transfer, vacuum, and advanced mixing technologies for the Defense, Space, and Energy & Process industries, today reported financial results for its second quarter for the fiscal year ending March 31, 2027 (“fiscal 2027”).

Graham’s President and Chief Executive Officer, Matthew J. Malone stated, “Our second quarter results reflect strong execution across the business, highlighted by growth in Defense and Space, significant margin expansion and continued momentum across our end markets. Our record backlog of $561 million provides strong visibility into future growth and reinforces our confidence in the long-term opportunities ahead.”

Mr. Malone continued, “We are very pleased with the progress of FlackTek’s integration and the continued execution of our strategic initiatives, including the successful completion of our first customer test at our new cryogenic testing facility and the groundbreaking of our new facility in Arvada. We believe these investments position us to capitalize on expanding opportunities in Space and Defense, as well as emerging high-growth markets such as advanced defense systems and small modular reactors, while advancing toward our long-term financial targets.”

1 Adjusted net income per diluted share, Adjusted EBITDA and Adjusted EBITDA margin are non-GAAP measures. See attached tables and other information for important disclosures regarding Graham’s use of these non-GAAP measures.
2 Orders, backlog and book-to-bill ratio are key performance metrics. See “Key Performance Indicators” below for important disclosures regarding Graham’s use of these metrics.

Second Quarter Fiscal 2027 Performance Review
(All comparisons are with the same prior-year period unless noted otherwise.)
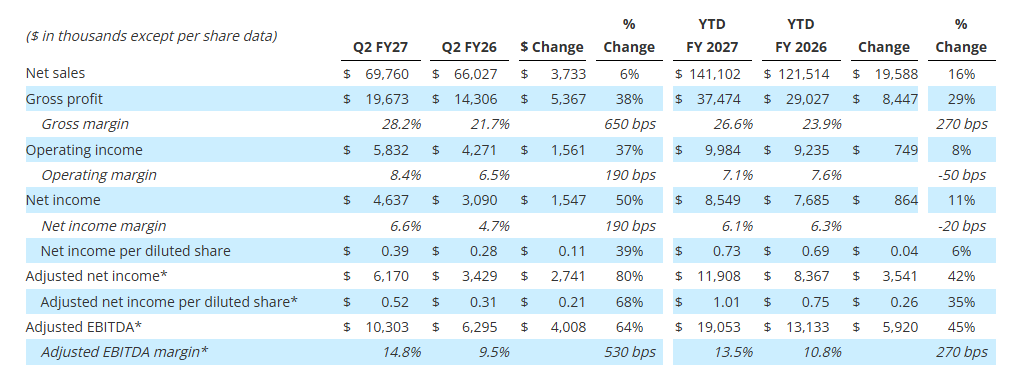
*Graham believes that, when used in conjunction with measures prepared in accordance with U.S. generally accepted accounting principles (“GAAP”), adjusted net income, adjusted net income per diluted share, adjusted EBITDA and adjusted EBITDA margin, which are non-GAAP measures, help in the understanding of its operating performance. See attached tables and other information provided at the end of this press release for important disclosures regarding Graham’s use of these non-GAAP measures.

Net sales for the second quarter of fiscal 2027 were $69.8 million, up $3.7 million, or 6%, compared with the second quarter of fiscal 2026, a result of our diversified revenue base and the acquisition of FlackTek, which contributed $9.5 million of revenue in the quarter. The increase was across multiple markets, including a $5.1 million, or 12%, increase in sales to the Defense market, driven by the timing of project milestones, new programs, growth of existing programs and capacity, and the addition of FlackTek, partially offset by approximately $10.0 million of lower material receipts in the second quarter of fiscal 2027. Defense represented 66% of net sales for the quarter. Sales to the Space market increased $2.4 million, or 59%, over the prior year second quarter, primarily due to the impacts of commercialization and accelerated launch cadences, the ramp up of existing programs, and the FlackTek acquisition. Sales to the Energy & Process markets decreased $3.7 million, or 17%, primarily due to softness in investments on large capital project activity caused by geopolitical uncertainties and decreases in sales to customers outside the U.S., partially offset by growth in New Energy markets and the addition of FlackTek. Aftermarket sales to the Energy & Process and Defense markets of $8.6 million decreased 3% from the prior year quarter but remained at high levels.

Gross profit for the second quarter of fiscal 2027 was $19.7 million or 28.2% of sales, compared with $14.3 million, or 21.7% of sales, in the prior-year period. The 650-basis point increase in gross profit margin reflects operational improvements on new and existing programs, the addition of FlackTek, and the mix of sales, in particular the composition of the current mix of programs in the Space and Defense markets, as well as a high level of material receipts in the second quarter of fiscal 2026, which carry a lower profit margin.

Selling, general and administrative expense (“SG&A”), including intangible amortization, for the second quarter of fiscal 2027 increased $3.4 million, or 34%, over the prior year second quarter. Acquisition and integration expenses contributed $0.7 million of the increase, and incremental SG&A from the acquisition of FlackTek accounted for $2.3 million. The balance of the increase mainly reflects ongoing investment in people, processes and technology, expected to total approximately $2.5 million of incremental cost in fiscal 2027, partially offset by a reduction to the Barber-Nichols Performance Bonus, which ended in fiscal 2026. During the second quarter of fiscal 2026, the Company recorded $1.1 million related to the Barber-Nichols Performance Bonus, inclusive of applicable payroll taxes and no corresponding expense was recorded in the second quarter of fiscal 2027.

Cash Management and Balance Sheet

Cash and cash equivalents as of September 30, 2026, were $71.4 million, compared with $27.0 million at the end of the previous quarter and $6.6 million at March 31, 2026.

Net cash provided by operating activities was $46.7 million during the second quarter of fiscal 2027 and $34.1 million for the first six months of the fiscal year, primarily reflecting the timing of accounts receivable collections and customer deposits, as well as higher cash net income.

Capital expenditures, net for the second quarter of fiscal 2027 were $2.2 million, and $4.9 million for the first six months, supporting the Company’s growth and productivity improvement initiatives.

As of September 30, 2026, the Company had no debt outstanding and $74.7 million available under its revolving credit facility.

Orders, Backlog, and Book-to-Bill Ratio

See supplemental data filed with the Securities and Exchange Commission on Form 8-K and provided on the Company’s website for a further breakdown of orders and backlog by market. See “Key Performance Indicators” below for important disclosures regarding Graham’s use of these metrics ($ in millions).

Orders for the second quarter of fiscal 2027 were $73.7 million, compared with $83.2 million in the prior year second quarter. Defense orders in the quarter were $41.8 million. Space market orders totaled $10.6 million, or 1.7x net Space sales for the quarter and $25.0 million, or 2.0x net Space sales, for the first six months of fiscal 2027. Total Aftermarket orders for the Energy & Process and Defense markets increased 91% to $18.3 million for the second quarter of fiscal 2027.

Note that our orders can be lumpy given the nature of our business, particularly large capital projects and multi-year Defense orders, which can be significantly larger.

Backlog at quarter end was a record $561.3 million, a 12% increase over the prior-year period, with Defense backlog up 10% and Space backlog up 108%. For the quarter, the Company achieved a book-to-bill ratio of 1.1x, and 1.2x for the first six months of fiscal 2027, ahead of the Company’s annual target of 1.1x. Management expects approximately 30% to 35% of backlog to convert to sales within the next twelve months, 20% to 25% within one to two years, and the remainder beyond two years. Approximately 83% of our backlog as of September 30, 2026, was to the Defense market, which provides stability and visibility for future revenue growth.

Fiscal 2027 Outlook
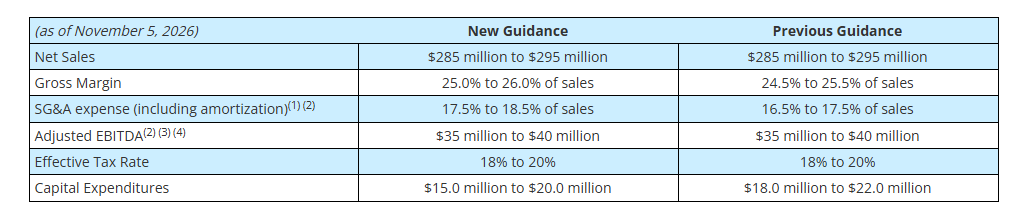
(1)Includes approximately $4.5 million to $5.5 million of equity-based compensation, net acquisition & integration costs, and enterprise resource planning (“ERP”) conversion costs included in SG&A expense.
(2)Includes approximately $2.5 million of incremental costs to invest in people, processes, and technology to enable future growth and accelerate the commercialization of Graham products and technologies.
(3)Excludes net interest (income) expense, income taxes, depreciation, and amortization from net income, as well as approximately $6.0 million to $7.0 million of equity-based compensation, net acquisition & integration costs, and ERP conversion costs.
(4)See “Forward-Looking Non-GAAP Measures” below for additional information.

Graham’s Chief Financial Officer, Christopher J. Thome, said, “Our second quarter results demonstrate continued improvement in profitability, with adjusted EBITDA increasing 64% year-over-year and adjusted EBITDA margin expanding 530 basis points. We generated $46.7 million in operating cash flow during the second quarter and ended the quarter with $71.4 million in cash and no outstanding debt, providing significant financial flexibility to support our organic and inorganic growth initiatives.”

Mr. Thome continued, “Based on our first-half performance and expectations for the remainder of the year, we are reaffirming our full-year fiscal 2027 guidance of net sales and adjusted EBITDA, have made minor updates to full-year fiscal 2027 guidance on gross margin based on mix and better execution, SG&A expense based on higher acquisition and integration related expenses, and updates to capital expenditures based on timing of major projects. We remain focused on maintaining financial discipline and driving continued operational improvements as we execute against our long-term objectives.”

Webcast and Conference Call

GHM’s management will host a conference call and live webcast on November 5, 2026, at 11:00 a.m. Eastern Time (“ET”) to review its financial results as well as its strategy and outlook. The review will be accompanied by a slide presentation, which will be made available immediately prior to the conference call on GHM’s investor relations website.

A question-and-answer session will follow the formal presentation. GHM’s conference call can be accessed by calling (877) 407-0784, or (201) 689-8560 (International). Alternatively, the webcast can be monitored from the events section of GHM’s investor relations website.

A telephonic replay will be available from 3:00 p.m. ET today through Thursday, November 12, 2026. To listen to the archived call, dial (844) 512-2921 and enter conference ID number 13762712, or access the webcast replay via the Company’s website at ir.grahamcorp.com, where a transcript will also be posted once available.

About Graham Corporation

Graham is a global leader in the design and manufacture of mission critical fluid, power, heat transfer, vacuum, and advanced mixing technologies for the Defense, Space, Energy & Process industries. Graham Corporation and its family of global brands are built upon world-renowned engineering expertise, proprietary technologies, as well as its responsive and flexible service and the unsurpassed quality customers have come to expect from the Company’s products and systems. Graham Corporation routinely posts news and other important information on its website, grahamcorp.com, where additional information on Graham Corporation and its businesses can be found.

Safe Harbor Regarding Forward Looking Statements

This news release contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended.

Forward-looking statements are subject to risks, uncertainties and assumptions and are identified by words such as “continue,” “estimate,” “expects,” “focus,” “future,” “opportunities,” “outlook,” “believes,” “could,” “guidance,” “may”, “will,” “plan,” “strategy,” and other similar words. All statements addressing operating performance, events, or developments that Graham Corporation expects or anticipates will occur in the future, including but not limited to, profitability of future projects and the business, its ability to deliver to plan, its ability to continue to strengthen relationships with customers in the Defense industry, its ability to secure future projects and applications, expected expansion and growth opportunities, anticipated sales, revenues, adjusted EBITDA, adjusted EBITDA margins, capital expenditures and SG&A expenses, the timing of conversion of backlog to sales, orders, market presence, profit margins, tax rates, foreign sales operations, customer preferences, changes in market conditions in the industries in which it operates, changes in general economic conditions and customer behavior, forecasts regarding the timing and scope of the economic recovery in its markets, and its acquisition and growth strategy, are forward-looking statements. Because they are forward-looking, they should be evaluated in light of important risk factors and uncertainties. These risk factors and uncertainties are more fully described in Graham Corporation’s most recent Annual Report filed with the Securities and Exchange Commission (the “SEC”), included under the heading entitled “Risk Factors”, and in other reports filed with the SEC.

Should one or more of these risks or uncertainties materialize or should any of Graham Corporation’s underlying assumptions prove incorrect, actual results may vary materially from those currently anticipated. In addition, undue reliance should not be placed on Graham Corporation’s forward-looking statements. Except as required by law, Graham Corporation disclaims any obligation to update or publicly announce any revisions to any of the forward-looking statements contained in this news release.

View full release here.

View source version on businesswire.com: https://www.businesswire.com/news/home/20261105758252/en/

For more information, contact:

Christopher J. Thome
Vice President – Finance and CFO
Phone: (585) 343-2216

Tom Cook
Investor Relations
(203) 682-8250
[email protected]

Source: Graham Corporation

Released November 5, 2026
Commercial Vehicle Group (CVGI) – Revenue Momentum Continued in 3Q


Wednesday, November 04, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. In the third quarter of 2026, CVG delivered year-over-year revenue growth across all 3 segments, reflecting ongoing efforts to reduce end-market concentration in cyclical North American Class 8 truck exposure through geographic and end-market diversification. While there are still macroeconomic uncertainties to monitor, we believe CVG is hitting its stride as new business wins are ramping up coincidentally with a recovery in key end markets.

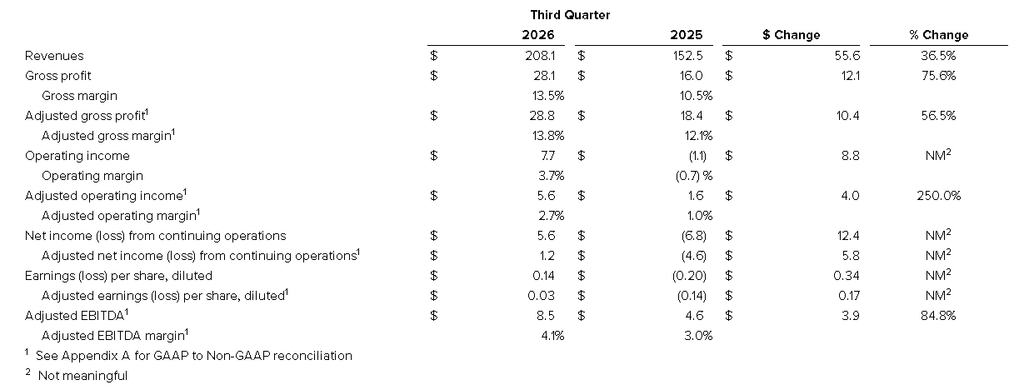
3Q26 Numbers. Revenue of $208.1 million rose 36.5%. We had forecast $195 million. Gross margin expanded 300 bp to 13.5% and was up 80 bp sequentially. Adjusted EBITDA came in at $8.5 million, versus $4.6 million in 3Q25. Adjusted EPS was $0.03 compared to an adjusted net loss of $0.14/sh last year. We had forecast $10 million and $0.03, respectively.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – CVG Reports Third Quarter 2026 Results and Announces CEO Succession Plan

CVG-Corporate

Research News and Market Data on CVGI

November 2, 2026

Delivered strong revenue growth and margin expansion
Returned to positive GAAP and Adjusted EPS
Raises revenue outlook and narrows Adjusted EBITDA guidance range
Appoints David Ruppel as President and CEO and a member of the Board

NEW ALBANY, Ohio, Nov. 02, 2026 (GLOBE NEWSWIRE) — CVG (NASDAQ: CVGI), a diversified industrial products and services company, today announced financial results for its third quarter ended September 30, 2026.

Third Quarter 2026 Highlights (Results from Continuing Operations; compared with prior year, where comparisons are noted)

  • Revenues of $208.1 million, up 36.5%, primarily driven by increased demand across all three segments.
  • Gross margin expansion of 300 basis points versus Q3 2025 and 80 basis points sequentially versus Q2 2026 primarily from volume leverage and operational efficiency improvements.
  • Operating income of $7.7 million, which included $3.1 million gain on sale of assets, up $8.7 million, compared to an operating loss of $1.1 million. Adjusted operating income of $5.6 million, compared to $1.6 million.
  • Net income from continuing operations of $5.6 million, or $0.14 per diluted share and adjusted net income of $1.2 million, or $0.03 per diluted share, compared to net loss from continuing operations of $6.8 million, or $(0.20) per diluted share and adjusted net loss of $4.6 million, or $(0.14) per diluted share. Net income includes a $4.1 million pre-tax warrant liability revaluation benefit.
  • Adjusted EBITDA of $8.5 million, compared to $4.6 million, with an adjusted EBITDA margin of 4.1%, up from 3.0%.

James Ray, President and Chief Executive Officer, said, “The third quarter demonstrated the earnings potential of a leaner, more efficient, and more focused CVG. Strong volume growth across all three segments, together with productivity gains, drove meaningful revenue growth and improvement in gross margin, adjusted operating income, and adjusted EBITDA. We see further opportunities to improve performance, particularly through driving plant efficiencies and recovering higher commodity and freight costs.”

Mr. Ray continued, “Trim Systems & Components delivered the strongest year-over-year growth, benefiting from higher North American Class 8 production volumes and new program launches. Global Electrical Systems benefited from new program ramps and increased demand in construction markets, and we continue to work closely with Zoox to support their production plans. Global Seating delivered solid growth while executing the footprint initiatives in China, the U.S., and the U.K. We expect these initiatives to lower our cost base over time. We expect the combination of new business ramps, continued operational improvement and execution in our key end markets to support further earnings growth into 2027.”

Angie O’Leary, Chief Financial Officer, added, “The third quarter marks a meaningful step in our transition toward profitable growth, with stronger volume translating into higher adjusted margins and positive adjusted EPS. As growth accelerates, our financial priorities remain clear: converting higher earnings into cash, strengthening the balance sheet and investing in the working capital and capacity needed to support new business. We made progress in each area this quarter, including reducing net leverage to approximately 2.7 times. We remain focused on driving profitable growth and progressing toward our net leverage goal of approximately two times. Based on our performance through the first nine months of the year, and our expectations for the fourth quarter, we are raising our full-year revenue outlook. We are also reducing the top end of the Adjusted EBITDA guidance range, reflecting incremental expenses related to the CEO succession.”

CEO Succession Plan

The Company also announced that its Board of Directors (the “Board”) has appointed David Ruppel as the Company’s next President and Chief Executive Officer and a member of the Board, in each case effective November 9, 2026. Mr. Ruppel will succeed James Ray, who will step down as President and Chief Executive Officer and as a member of the Board on November 9, 2026 and will remain with CVG as a Senior Advisor through his retirement on January 5, 2027.

The Board extends its sincere gratitude to Mr. Ray for his outstanding leadership and the significant contributions he has made to CVG during his tenure and appreciates his continued counsel as Senior Advisor to support a seamless transition. During his nearly three years as CEO, Mr. Ray guided the Company through challenging end market conditions, refinanced its balance sheet, and transformed its operating structure to sharpen CVG’s focus on profitable growth. Mr. Ray’s resignation did not result from any disagreement with the Company on any matter relating to its operations, policies or practices.

Mr. Ruppel brings more than 25 years of operational and general management experience across many of CVG’s key end markets, including commercial vehicles, electrical systems, and industrials. He currently serves as Senior Vice President and General Manager, Transportation & Logistics at Littelfuse, Inc., with global P&L responsibility for a $700 million segment, having previously led its Commercial Vehicle products business. His career also spans automotive and aerospace & defense, giving him a broad perspective on the customers, technologies, and demand cycles that shape CVG’s business. Prior to Littelfuse, Mr. Ruppel served as President of IDEX Optical Technologies and President of Montevideo Technology, Inc., leading global businesses through growth, acquisition integration, and operational transformation. Prior to that, he spent approximately 20 years in operational and general management roles at Herman Miller, Eaton, and Cooper Industries, including deep experience in electrical power management and manufacturing at Cooper and Eaton.

Mr. Ruppel holds an Executive Master of Business Administration from Marquette University and a Bachelor of Science in Management from Cardinal Stritch University.

“We have found an exceptional leader whose deep operating experience and strong record of execution position him well to advance CVG’s strategy and drive growth,” said William C. Johnson, Chairman of the Board. “David is a seasoned, results-oriented executive who has led complex global businesses, including in the commercial vehicle and electrical markets that are central to the Company. He is the right leader to guide CVG through its next phase of growth, and I am confident that this transition will be smooth.”

Mr. Ruppel said, “I am honored to be appointed President and CEO and thank the Board for its confidence. I look forward to partnering with our talented employees around the world as we execute our strategy and deliver value for our customers and shareholders. CVG is a diverse organization with a global footprint and broad product portfolio, and I am excited for the opportunity to lead it. Having spent my career in markets closely aligned with CVG’s, I see a strong foundation with clear potential to deliver profitable growth.”

Third Quarter Financial Results from Continuing Operations
(amounts in millions except per share data and percentages)

Consolidated Results from Continuing Operations

Third Quarter 2026 Results

  • Third quarter 2026 revenues were $208.1 million, compared to $152.5 million in the prior year period, an increase of 36.5%. The overall increase in revenues was primarily due to increased customer demand in global markets and the ramp of previously awarded new business wins across all three of our segments. 
  • Operating income in the third quarter 2026 was $7.7 million, which included $3.1 million gain on sale of assets, up $8.7 million compared to an operating loss of $1.1 million in the prior year period. Third quarter 2026 adjusted operating income was $5.6 million, compared to adjusted operating income of $1.6 million in the prior year period. The increase in adjusted operating income was primarily attributable to the impact of higher sales volumes and operational efficiency improvements, partially offset by higher SG&A expense, driven primarily by share-based compensation, increased performance-based incentive compensation, and recruiting costs related to the CEO succession process.
  • Interest associated with debt and other expenses was $3.4 million and $4.1 million for the third quarter 2026 and 2025, respectively, with the decrease for the third quarter 2026 due to lower debt balances.
  • Net income from continuing operations was $5.6 million, or $0.14 per diluted share, for the third quarter 2026 compared to net loss of $6.8 million, or $(0.20) per diluted share, in the prior year period. Net income includes a $4.1 million pre-tax warrant liability revaluation benefit. Third quarter 2026 adjusted net income from continuing operations was $1.2 million, or $0.03 per diluted share, compared to adjusted net loss of $4.6 million, or $(0.14) per diluted share.

On September 30, 2026, the Company had $34.2 million of outstanding borrowings on its U.S. revolving credit facility and $1.5 million outstanding borrowings on its China credit facility, $39.8 million of cash and $83.3 million of availability from the credit facilities (subject to customary borrowing base and other conditions), resulting in total liquidity of $123.1 million.

Third Quarter 2026 Segment Results

Global Seating Segment

  • Revenues were $84.7 million compared to $68.7 million for the prior year period, an increase of 23.3%, due primarily to increased customer demand in North America and Asia-Pacific markets.
  • Operating income was $3.6 million, compared to $1.4 million in the prior year period, an increase of $2.2 million, driven by higher sales and improved gross margin performance. Third quarter 2026 adjusted operating income was $4.6 million compared to $2.9 million in the prior year period.

Global Electrical Systems Segment

  • Revenues were $64.4 million compared to $49.5 million in the prior year period, an increase of 30.2%, primarily as a result of ramping new business wins and increased customer demand in construction markets.
  • Operating income was $3.7 million compared to operating income of $0.8 million in the prior year period. The increase in operating income was primarily attributable to higher volume and product mix.

Trim Systems and Components Segment

  • Revenues were $58.9 million compared to $34.3 million in the prior year period, an increase of 71.9%, primarily due to higher sales volume as a result of increased customer demand in North America, including improved product mix.
  • Operating income was $5.8 million compared to operating loss of $0.9 million in the prior year period. The increase in operating income was primarily attributable to higher demand, improved operational efficiencies, and a gain on sale of assets. Third quarter 2026 adjusted operating income was $2.7 million compared to an adjusted operating loss of $0.3 million in the prior year period.

Outlook

CVG updated the Company’s outlook for the full year 2026, based on current market conditions:

MetricPrior 2026 Outlook ($ millions)Updated 2026 Outlook ($ millions)
Revenues$725 – $755$755 – $775
Adjusted EBITDA$26 – $31$26 – $29
Free Cash FlowPositivePositive

This outlook reflects, among others, current industry forecasts for North America Class 8 truck builds. According to ACT Research, 2026 North American Class 8 truck production levels are expected to be at 272,442 units, up 8% versus the 2025 actual Class 8 truck builds of 251,251 units.

The outlook for the Construction end market reflects high-single digit growth in 2026.

Our long-term incentive awards are designed to align executive compensation with shareholder returns. Our adjusted EBITDA outlook incorporates current estimates of long-term performance shares settled in cash. Under GAAP accounting, such awards are remeasured each reporting period. Therefore, changes in our share price could materially affect our Adjusted EBITDA outlook. While this creates periodic earnings volatility under GAAP, it does not represent a corresponding change in our underlying cost structure. (see Appendix A)

GAAP to Non-GAAP Reconciliation

A reconciliation of GAAP to non-GAAP financial measures referenced in this release is included as Appendix A to this release.

Conference Call

A conference call to discuss this press release is scheduled for Tuesday, November 3, 2026, at 8:30 a.m. ET. Management intends to reference the Q3 2026 Earnings Call Presentation during the conference call. To participate, dial (833) 461-5787 using conference code 592968497. International participants dial (585) 542-9983 using conference code 592968497.

This call is being webcast and can be accessed through the “Investors” section of CVG’s website at ir.cvgrp.com, where it will be archived and available for replay for one year.

Company Contact
Michelle Hards
Vice-President, Investor Relations / Corporate Financial Planning & Analysis
CVG
[email protected]

Investor Relations Contact
Ross Collins or Nathan Skown
Alpha IR Group
[email protected]

About CVG

CVG is a global provider of systems, assemblies and components to global commercial vehicle markets and electric vehicle markets. We deliver real solutions to complex design, engineering and manufacturing problems while creating positive change for our customers, industries and communities we serve. Information about the Company and its products is available on the internet at www.cvgrp.com.

Forward-Looking Statements

This press release contains forward-looking statements that are subject to risks and uncertainties. These statements often include words such as “believe”, “anticipate”, “plan”, “expect”, “intend”, “will”, “should”, “could”, “would”, “project”, “continue”, “likely”, and similar expressions. In particular, this press release may contain forward-looking statements about the Company’s expectations for future periods with respect to its plans to improve financial results, the future of the Company’s end markets, including, but not limited to, global commercial vehicle markets and electric vehicle markets, changes in the North America Class 8 and Class 5-7 truck build rates, performance of the global construction and agricultural equipment businesses, the Company’s prospects in the global commercial vehicle markets and electric vehicle markets, the Company’s initiatives to address customer needs, organic growth, the Company’s strategic plans and plans to focus on certain segments, competition faced by the Company, volatility in and disruption to the global economic environment including global supply chain constraints, inflation and labor shortages, tariffs and counter-measures, financial covenant compliance, anticipated effects of acquisitions or divestitures, production of new products, plans for capital expenditures, and the Company’s financial position or other financial information. These statements are based on certain assumptions that the Company has made in light of its experience as well as its perspective on historical trends, current conditions, expected future developments and other factors it believes are appropriate under the circumstances. Actual results may differ materially from the anticipated results because of certain risks and uncertainties, including those included in the Company’s filings with the SEC. There can be no assurance that statements made in this press release relating to future events will be achieved. The Company undertakes no obligation to update or revise forward-looking statements to reflect changed assumptions, the occurrence of unanticipated events or changes to future operating results over time. All subsequent written and oral forward-looking statements attributable to the Company or persons acting on behalf of the Company are expressly qualified in their entirety by such cautionary statements.

Other Information

Throughout this document, certain numbers in the tables or elsewhere may not sum due to rounding. Rounding may have also impacted the presentation of certain year-on-year percentage changes.

View full release here.

Primary Logo

Source: Commercial Vehicle Group, Inc.

Titan International (TWI) – Still Working Through Headwinds


Friday, October 30, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Quarterly Overview. Inclusive of ITM, which is reported in the 3Q26 financials as discontinued operations, Titan’s revenues of $454 million were above the midpoint of the guidance, while adjusted EBITDA of $28 million was also within the guidance range. Titan’s One Stop Shop strategy continues to enable the Company to deliver solid financial results despite challenging current market conditions.

3Q26 Results. Focused on reported results, which exclude ITM from continuing operations, revenue came in at $335.2 million compared to $357.3 million in the comparable period of 2025. Gross margin was 14.7% of net sales versus 15.7% in 3Q26. Titan reported adjusted EBITDA of $16.4 million, down from $20.3 million last year. Adjusted loss was $0.03/sh compared to adjusted EPS of $0.04 in 3Q25.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – Titan International, Inc. Reports Third Quarter Financial Results

Titan International, Inc. logo. (PRNewsFoto/Titan International)

Research News and Market Data on TWI

Oct 29, 2026, 06:00 ET

WEST CHICAGO, Ill., Oct. 29, 2026 /PRNewswire/ — Titan International, Inc. (NYSE: TWI) (“Titan” or the “Company”), a leading global manufacturer of off-highway wheels, tires, assemblies, and undercarriage products, today reported financial results for the third quarter ended September 30, 2026.  The full earnings release including a reconciliation of GAAP to Non-GAAP figures can be found in the investor relations section of the Company’s website at https://ir.titan-intl.com/news-and-events/news-releases/default.aspx. 

Q3 2026 Key Figures for Continuing Operations

  • Revenues of $335 million ($454 million, inclusive of discontinued operations)
  • Gross margin of 14.7%
  • Adjusted EBITDA of $16 million ($28 million, inclusive of discontinued operations)
  • Generated Free Cash Flows of $23 million

Paul Reitz, President and Chief Executive Officer, commented, “Inclusive of ITM, which is reported in our Q3 financials as discontinued operations, our revenues for the quarter of $454 million were above the midpoint of our guidance while Adjusted EBITDA of $28 million was also within our guidance range.  Our One Stop Shop strategy enabled us to deliver solid financial results despite current market conditions.  Focusing on our reported results which exclude ITM from continuing operations, EMC sales grew 5% with improved margins during the quarter while Consumer segment sales were down 3% albeit versus an abnormally strong Q3 last year.  Our Ag segment declined 12% as farmers remained on the sidelines due to high interest rates, diesel and fertilizer costs and other macro concerns that continue to impact overall economic activity.”

Mr. Reitz continued, “Toward the end of the quarter we announced an agreement to sell our ITM business.  As we noted in that announcement, our Board of Directors believe that the sale of ITM empowers Titan to focus on growing our global wheel and tire businesses while also utilizing the proceeds to reduce our debt.  ITM is a high-quality business but has limited synergies relative to our wheel and tire operations.  As we continue to execute our strategic plan, we expect to energize our value creation by extending our leadership position in our wheel and tire businesses and intend to utilize proceeds from the transaction to support that strategy.  We are progressing through the regulatory process and continue to expect the transaction to close in early January 2027.”  

Mr. Reitz concluded, “Macro uncertainty along with elevated interest rates, fuel and fertilizer costs continue to weigh on activity in our end markets, which has been the story throughout 2026.  At the same time, we believe the building blocks for a resumption of growth are present.  An aging machinery fleet continues to create pent-up replacement demand, while wheel and tire inventories across our distribution channels remain at relatively low levels.  Although corn prices are down from recent highs in August, they are still above year-ago levels, as are soybean prices, which bode well for farmer incomes. I am confident that a resumption in end market demand will flow through to suppliers such as Titan rather quickly. We have also strengthened our strategic position with customers through innovative products and solutions, which we expect will support growth despite challenging market conditions.”

Third Quarter and Fiscal Year 2026 Outlook

Tony Eheli, Chief Financial Officer added, “Inclusive of ITM operations, we are updating our fourth quarter and full-year guidance to reflect the effect of current market conditions.  We currently expect fourth quarter sales of between $410 million and $430 million, and Adjusted EBITDA of between break even and $7 million.  Our current expectations for FY 2026 are for sales between $1.85 and $1.87 billion and Adjusted EBITDA of between $91 million and $101 million.”

Results for the 2026 third quarter and nine months reflect the classification of the Company’s Italtractor ITM undercarriage business (“ITM”) as discontinued operations in connection with its previously announced pending sale to USCO S.p.A. (“USCO”). The transaction is scheduled to close in January 2027.  

About Titan

Titan International, Inc. (NYSE: TWI) is a leading global manufacturer of off-highway wheels, tires, assemblies, and undercarriage products.  Headquartered in West Chicago, Illinois, the Company globally produces a broad range of products to meet the specifications of original equipment manufacturers (OEMs) and aftermarket customers in the agricultural, earthmoving/construction, and consumer markets. For more information, visit www.titan-intl.com.

Safe Harbor Statement

This press release contains forward-looking statements. These forward-looking statements are covered by the safe harbor for “forward-looking statements” provided by the Private Securities Litigation Reform Act of 1995. The words “believe,” “expect,” “anticipate,” “plan,” “would,” “could,” “potential,” “may,” “will,” and other similar expressions are intended to identify forward-looking statements, which are generally not historical in nature. These forward-looking statements are based on our current expectations and beliefs concerning future developments and their potential effect on us. Although we believe the assumptions upon which these forward-looking statements are based are reasonable, these assumptions are subject to significant risks and uncertainties, and are subject to change based on various factors, some of which are beyond Titan International, Inc.’s control. As a result, any of these assumptions could prove to be inaccurate and the forward-looking statements based on these assumptions could be incorrect. The matters discussed in these forward-looking statements are subject to risks, uncertainties, and other factors that could cause actual results and trends to differ materially from those made, projected, or implied in or by the forward-looking statements depending on a variety of uncertainties or other factors including, but not limited to, the effect of a recession on the Company and its customers and suppliers; changes in the Company’s end-user markets into which the Company sells its products as a result of domestic and world economic or regulatory influences or otherwise; changes in the marketplace, including new products and pricing changes by the Company’s competitors; the Company’s ability to maintain satisfactory labor relations; unfavorable outcomes of legal proceedings; the Company’s ability to comply with current or future regulations applicable to the Company’s business and the industry in which it competes or any actions taken or orders issued by regulatory authorities; availability and price of raw materials; levels of operating efficiencies; the effects of the Company’s indebtedness and its compliance with the terms thereof; changes in the interest rate environment and their effects on the Company’s outstanding indebtedness; unfavorable product liability and warranty claims; actions of domestic and foreign governments, including the imposition of additional tariffs; geopolitical and economic uncertainties relating to the countries in which the Company operates or does business; risks associated with acquisitions, including difficulty in integrating operations and personnel, disruption of ongoing business, and increased expenses; results of investments; the effects of potential processes to explore various strategic transactions, including potential dispositions; fluctuations in currency translations; risks associated with environmental laws and regulations; risks relating to our manufacturing facilities, including that any of our material facilities may become inoperable; risks relating to financial reporting, internal controls, tax accounting, and information systems; and the other risks and factors detailed in the Company’s periodic reports filed with the Securities and Exchange Commission, including the disclosures under “Risk Factors” in those reports. These forward-looking statements are made only as of the date hereof. The Company cautions that any forward-looking statements included in this press release are subject to a number of risks and uncertainties, and the Company undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, changed circumstances or future events, or for any other reason, except as required by law.

SOURCE Titan International, Inc.

Release – NN, Inc. Reports Third Quarter 2026 Results

Primary Logo

Research News and Market Data on NNBR

PDF Version

NN Delivers Another Quarter of Growth in Net Sales, Adjusted EBITDA, and New Wins; Raises 2026 Outlook Again

CHARLOTTE, N.C., Oct. 28, 2026 (GLOBE NEWSWIRE) — NN, Inc. (NASDAQ: NNBR) (“NN” or the “Company”), an entrepreneurial growth company that engineers and manufactures high-precision components and assemblies, today reported results for the third quarter ended September 30, 2026.

Q3 2026 Financial Highlights, compared to Q3 2025

  • Net sales of $131.1 million, up $27.2 million or 26.2%
  • Gross margin of $18.3 million, up $0.8 million or 4.6%
  • Adjusted gross margin of $25.3 million, up $5.8 million or 29.5%
  • Adjusted gross margin percentage of 19.3%, up 50 basis points
  • Loss from operations of $3.3 million, up $1.1 million from a loss of $2.2 million
  • Adjusted income from operations of $8.5 million, up $4.4 million or 109.5% 
  • GAAP net loss of $4.6 million, improving by $2.1 million or 31.3% 
  • Adjusted net income of $5.3 million, up $5.6 million
  • Adjusted EBITDA of $18.5 million, up $6.1 million or 49.7%
  • Adjusted EBITDA margin percentage of 14.1%, up 220 basis points                

Performance Highlights:

  • During 2026, NN has completed a multi-step process to transform its balance sheet. The preferred stock payoff and equity raise has unlocked growth potential. NN now has the financial flexibility to accelerate and optimize its business results. The Company had been severely constrained by its capital structure for multiple years. The Company looks forward to achieving higher results at a faster pace.
  • NN’s new business program has continued to outperform expectations. On a trailing 12 months basis ended September 30, 2026, the Company has secured $130 million of annualized new business awards, a significant portion of which is not yet reflected in the Company’s run-rate. The Company is now winning more than 1 new program per day. The Company will continue to update results during quarterly earnings calls.
  • NN’s 5 Pillar growth program is working well and the Company is investing its time and resources to strategically pivot the portfolio to high-growth, high-value markets and products. The Company has been aided by strong underlying market growth.
    • Data Center: NN’s top targeted end market and one of its fastest growing businesses. NN is ramping up the business by installing over 50 new machines dedicated to this market through Q1 2027. This business has a growing $66 million pipeline, including liquid cooling components for next generation chip designs.
    • Defense: NN has secured multiple new awards in this market in 2026 and recently became a supplier to a leading firearm accessories OEM with multiple programs currently in ramp-up mode.
    • Medical: NN has secured multiple new awards in this market in 2026 and became a supplier to a leading medical equipment OEM with 30 core platforms. The Company is significantly increasing the size of the business with multiple programs in ramp-up mode.
  • NN’s cost-out program is on track to deliver $12 million of cost-out via 335 projects globally. These cost improvements are not yet fully reflected in the Company’s run-rate results. NN’s global operations team is also leading an ongoing continuum of new product development and business launches. In 2026, NN expects to launch more than 150 new programs worth approximately $100 million in peak annual sales.
  • NN is underway with an intentional sales growth investment program. Overall, the Company is growing its net sales by approximately $68 million in 2026 based on updated guidance. The Company has achieved excellent working capital performance of 16.5% – 16.7% of sales over the trailing 6 months.

Management Commentary:

Harold Bevis, President and Chief Executive Officer, commented, “NN has delivered several consecutive years of improved adjusted EBITDA and sales growth wins, is now benefitting from the launching of these programs, and has a solid multi-year outlook for continued growth. This enabled the Company to initiate a transformation of its equity and debt structure. We paid off all of our preferred stock via several debt-for-equity transactions over the last 4 months. We also raised strategic capital to fund additional programs that were previously on hold due to lack of funding. Taken together, this represented $143 million of capital transactions. We executed decisively and I want to thank our Board of Directors, our new investors, and our advisors. This transformation is behind us now and we are already underway leveraging our newly enhanced flexibility.

We are operating under a new reality whereby we can move faster and improve on multiple fronts at once. While we are on track for our best year ever in 2026, our momentum is continuing into 2027, as part of an achievable multi-year growth outlook. We have a full basket of opportunities to improve, and we are taking on the next set of big improvements during 2027 now that we have the financial capacity to do so. The last remaining balance sheet financial improvements are with regards to our ABL and Term Loan, which we will fix at the right time.

While we are happy with our last four years of sustained results improvement, we are at the same time determined to continue elevating the business to a higher plane of performance.  This will require us to continue shifting our portfolio. We are taking forward actions on targeted sales growth, exiting low profit auto programs, and continuously taking out costs. We are on track for our multi-year targets. We are pleased that we have secured many new customers and introduced multiple new products in 2026. Further, we have a refreshed investor roster with growth-minded investors aligned with our forward goals. We are already accelerating our pace of improvement with our newfound financial flexibility.”

Bevis continued, “Our 5 Pillar growth program is our touchstone. Now we are in a position to also explore logical, small bolt-on acquisitions to further enhance our goals and growth trajectory. We are pleased that many of our new sales programs require ‘Immediate Startup’. Overall, the new wins numbers are very good, but we have areas where we want a significantly higher level of wins and growth, especially Data Center, Medical, and Defense. We are disciplined about improving our margins at the same time, walking away from dilutive business, and exiting minimal margin, minimal ROI business. We believe we have more room to increase our gross margins, adjusted EBITDA margins, and ROIs.”

Bevis concluded, “Given the results we have delivered in 2026 year to date and our strong forward outlook, we are raising our full-year 2026 guidance. We will be more specific about 2027 when we have completed our 2027 business planning process which is underway now. We are updating our thinking now that we have more financial firepower that has been enabled by our balance sheet transformation of 2026.”

Third Quarter NN Results

Net sales for the third quarter were $131.1 million, an increase of 26.2% compared to net sales of $103.9 million for the same period in 2025. The increase was primarily driven by higher selling prices, reflecting the pass-through of increased raw material costs to customers, higher volumes, and favorable foreign exchange effects.

Loss from operations for the third quarter was $3.3 million, an increase of $1.1 million compared to a loss from operations of $2.2 million for the same period in 2025.  The decline was primarily due to higher labor costs associated with increasing headcount to support new business and higher professional fees driven by the various strategic initiatives.

Net loss for the third quarter was $4.6 million, an improvement of 31.3% compared to net loss of $6.7 million for the same period in 2025.  The improvement was primarily driven by a gain related to a favorable tax ruling in Brazil and higher income from our joint venture in China.

Third Quarter 2026 NN Adjusted Results

Adjusted EBITDA was $18.5 million, an increase of 49.7% compared to adjusted EBITDA of $12.4 million for the same period in 2025, primarily driven by improved sales mix, operating performance and higher income from our joint venture in China.

Adjusted income from operations was $8.5 million, an increase of 109.5% compared to adjusted income from operations of $4.0 million for the same period in 2025. The increase was driven primarily by higher volumes and improved mix to higher margin products, partially offset by increased selling, general and administrative expenses.

Adjusted net income was $5.3 million, or $0.07 per diluted common share, an increase of $5.6 million or $0.08 per diluted common share, compared to adjusted net loss of $0.3 million, or $(0.01) per diluted common share for the same period in 2025.

Third Quarter Power Solutions Results 
Net sales for the third quarter of 2026 were $63.2 million, an increase of 40.6% compared to net sales of $44.9 million for the same period in 2025. The increase was driven primarily by higher selling prices, reflecting the pass-through of increased raw material costs to customers, increased volumes, and favorable foreign exchange effects.

Income from operations for the third quarter of 2026 was $9.2 million, an increase of 69.4% compared to income from operations of $5.4 million for the same period in 2025. The increase was primarily due to higher selling prices and increased volumes. The increase was partially offset by higher material costs and labor costs.

Adjusted income from operations for the third quarter of 2026 was $12.4 million, an increase of 53.1% compared to adjusted income from operations of $8.1 million for the same period in 2025. The increase was primarily due to the improved operating performance from higher selling prices and volumes.

Third Quarter Mobile Solutions Results

Net sales for the third quarter of 2026 were $68.2 million, an increase of 15.3% compared to net sales of $59.1 million in the same period of 2025. The increase was primarily due to higher volumes and favorable foreign exchange effects.

Loss from operations for the third quarter was $6.3 million, a decline of $3.4 million compared to $2.9 million for the same period in 2025. The increase was primarily due to higher costs from volume increases, increased labor costs due to the start-up of new programs, material cost increases, and facility costs. 

Adjusted income from operations for the third quarter was $4.0 million, an increase of 75.2% compared to adjusted income from operations of $2.3 million in the same period of 2025. The increase in adjusted income from operations was primarily due to higher sales volumes and increased net income from our joint venture.

2026 Outlook
NN is revising its guidance ranges upward in several areas. 

  • Net sales are expected to range between $480 to $500 million
    • This reflects a $68 million improvement over 2025, or 16% growth year-over-year at the midpoint.
  • Adjusted EBITDA is expected to range between $64 and $68 million.
    • This reflects a $17 million improvement over 2025, or 35% growth year-over-year at the midpoint.
  • New business wins are expected to range between $110 to $130 million.
    • This reflects a $50 million improvement over 2025, or 71% growth year-over-year at the midpoint.

Chris Bohnert, Senior Vice President and Chief Financial Officer, commented, “Given the strength of our results year to date and the continued momentum in our targeted growth markets, we are again raising our full-year 2026 guidance across our key metrics. As we look ahead to the final quarter of 2026 and into 2027, our outlook reflects continued profitable growth and keeps us well on track to maintain pace with our 2029 financial goals. Our new capital structure enables NN to enter 2027 with a stronger balance sheet and greater financial flexibility to invest in our growth.” 

Conference Call

NN will discuss its results during its quarterly investor conference call on October 29, 2026, at 9 a.m. ET.  The call and supplemental presentation may be accessed via NN’s website, www.nninc.com. The conference call can also be accessed by dialing (833) 461-5787 (domestic) or (585) 542-9983 (international) and entering Conference ID number 100337183. For those who are unavailable to listen to the live broadcast, a replay will be available shortly after the call.

NN discloses in this press release the non-GAAP financial measures of adjusted gross margin, adjusted gross margin %, adjusted income from operations, adjusted EBITDA, adjusted EBITDA margin, adjusted net income (loss), and adjusted net income (loss) per diluted common share. Each of these non-GAAP financial measures provides supplementary information about the impacts of acquisition, divestiture and integration related expenses, foreign-exchange impacts on inter-company loans, reorganizational and impairment charges.

The financial tables found later in this press release include a reconciliation of adjusted gross margin, adjusted gross margin %, adjusted income from operations, adjusted operating margin, adjusted EBITDA, adjusted EBITDA margin, adjusted net income (loss), and adjusted net income (loss) per diluted common share to the U.S. GAAP financial measures of gross margin, income (loss) from operations, net loss, net loss per diluted common share.

About NN, Inc.

NN, Inc. (NASDAQ: NNBR) is an entrepreneurial manufacturing company specializing in manufacturing micron-tolerance precision metal componentry for high-growth end markets, especially Data Center, Electric Grid, Medical, Defense, and High-Value Vehicle systems. Founded in 1980, NN serves over 700 customers on 4 continents through its 2,700 person workforce operating out of 27 global plants. This footprint enables rapid innovation and globally scaled solutions. For more information, visit nninc.com.

This press release may contain forward-looking statements regarding our business, operations, and financial performance. Such statements are based on current expectations and assumptions that are subject to a number of risks and uncertainties. Actual results could differ materially. Please refer to our most recently filed Form 10-K and our Form 10-Q for the period following that Form 10-K, including the risk factors described therein. We undertake no obligation to update any forward-looking statement, except as required by law. Given these risks and uncertainties, investors are cautioned not to place undue reliance on such forward-looking statements.

Primary Logo

Investor & Media Contacts:
Joseph Caminiti
[email protected]
312-445-2870

View full release here.

SKYX Platforms (SKYX) – Another Homebuilder Deal


Tuesday, October 27, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

New Deal. Hot on the heels of the Maronda Homes announcement, SKYX Platforms revealed an agreement to supply 60,000 units of its smart home technologies for over 700 homes to be built by Home Creations. The units are expected to be provided over the next 12 months. We believe these are the first of many agreements to be awarded in the future for SKYX products in the home builder vertical.

Home Creations. Founded in 1981, Home Creations is a family-founded homebuilder serving Oklahoma and the Houston, Texas, market. Significantly, Home Creations combines energy-efficient construction with smart home features. The firm’s Oklahoma City homes are nearly 53% more energy-efficient than typical new homes and include Deako smart lighting, a smart thermostat, smart locks, and an app-enabled garage door. Every home is HERS-verified by a certified RESNET energy rater and backed by a 10-year structural warranty.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

SKYX Platforms (SKYX) – Proof of Concept


Thursday, October 22, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Proof. It didn’t take long for SKYX Platforms and new subsidiary Deako to supply proof of concept on one of the key elements of the merger: i.e., cross-selling. Yesterday, SKYX announced that it will supply over 80,000 units of its advanced technologies to over 1,000 homes for Maronda Homes. We believe this announcement will be the first of many.

Details. The Company expects to deliver over 80,000 units of its advanced plug-and-play and smart home technologies to over 1,000 Maronda Homes residences in several states, including Ohio, Georgia, Maryland, and Pennsylvania. If the contract is similar to the $50/unit revenue previously disclosed, the contract would represent some $4 million in revenue.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – SKYX and Its Subsidiary Deako Announce They Will Supply Over 80,000 Units of Their Smart Home Technologies to Over 1,000 Homes of Prominent Home Builder Maronda Homes, as the Company Continues to Grow Its Market Penetration

MIAMI, Oct. 21, 2026 (GLOBE NEWSWIRE) — SKYX Platforms Corp. (NASDAQ: SKYX) (the “Company” or “SKYX”), a highly disruptive platform technology company with over 120 patents and pending applications globally and over 60 lighting and home décor websites, with a mission to make homes and buildings become safe and smart as the new standard, today announced that it will supply over 80,000 units of its advanced technologies to over 1,000 homes of prominent community and home builder Maronda Homes as it continues to grow its market penetration

Maronda Homes is a private, family-owned home builder founded in 1972 by William J. Wolf. Maronda has built over 70,000 homes across the United States and is currently building homes and communities across Florida, Ohio, Georgia, Alabama, Indiana, Kentucky, Maryland, Pennsylvania, South Carolina, Virginia, and West Virginia.

As a community and home builder many of Maronda Homes communities include resort-style pools and clubhouses to fitness centers, pickleball courts, dog parks, walking trails and playgrounds. Maronda communities are designed to bring families together.

The Company expects to deliver over 80,000 units of its advanced plug-and-play and smart home technologies to over 1,000 Maronda Homes residences in several states including Ohio, Georgia, Maryland, and Pennsylvania.

Maronda Homes offers a Certified Energy Efficient package designed to pair everyday comfort with smart home technology. Electrical and smart home package features may vary by market, community, and home.

For information about Maronda Homes, click here: www.marondahomes.com

For more information about SKYX and Deako, go to www.SKYX.com and www.Deako.com

Derek Richardson, Founder and CEO of Deako, stated: “This program with Maronda is a natural next step for Deako. Every new Maronda home in these communities starts with a smart home foundation that is simple for the builder to deliver and easy for the homeowner to grow. Pairing that package with the communities Maronda builds, from resort-style pools to walking trails, is the kind of home people are looking for, and it gives us a model we can repeat with builders across the country.”

Rani Kohen, Founder and Executive Chairman of SKYX Platforms, said: “We are very pleased to be working with such a prominent home builder, Maronda Homes. We expect to keep expanding our builder programs with our subsidiary Deako and look forward to continuing to grow our market penetration while creating safer, more advanced, and smarter homes and buildings of the future.”

About SKYX Platforms Corp.

As electricity is a standard in every home and building, our mission is to make homes and buildings become safe-advanced and smart as the new standard. SKYX has a series of highly disruptive advanced, safe, smart and AI platform technologies, with over 120 U.S. and global patents and patent pending applications. Additionally, the Company owns 60 lighting and home décor websites for both retail and commercial segments. Our technologies place an emphasis on high quality and ease of use, while significantly enhancing both safety and lifestyle in homes and buildings. We believe that our products are a necessity in every room in both homes and other buildings in the U.S. and globally. For more information, please visit our website at https://www.skyx.com/ or follow us on LinkedIn.

Forward-Looking Statements

Certain statements made in this press release are not based on historical facts, but are forward-looking statements. These statements can be identified by the use of forward-looking terminology such as “aim,” “anticipate,” “believe,” “can,” “could,” “continue,” “estimate,” “expect,” “evaluate,” “forecast,” “guidance,” “intend,” “likely,” “may,” “might,” “objective,” “ongoing,” “outlook,” “plan,” “potential,” “predict,” “probable,” “project,” “seek,” “should,” “target” “view,” “will,” or “would,” or the negative thereof or other variations thereon or comparable terminology, although not all forward-looking statements contain these words. These statements reflect the Company’s reasonable judgment with respect to future events and are subject to risks, uncertainties and other factors, many of which have outcomes difficult to predict and may be outside our control, that could cause actual results or outcomes to differ materially from those in the forward-looking statements. Such risks and uncertainties include statements relating to the Company’s ability to successfully launch, commercialize, develop additional features and achieve market acceptance of its products and technologies and integrate its products and technologies with third-party platforms or technologies; the Company’s ability to achieve positive cash flows; the Company’s efforts and ability to drive the adoption of its products and technologies as a standard feature, including their use in homes, hotels, offices and cruise ships; the Company’s ability to capture market share; the Company’s estimates of its potential addressable market and demand for its products and technologies; the Company’s ability to raise additional capital to support its operations as needed, which may not be available on acceptable terms or at all; the Company’s ability to continue as a going concern; the Company’s ability to execute on any sales and licensing or other strategic opportunities; the possibility that any of the Company’s products will become National Electrical Code (NEC)-code or otherwise code mandatory in any jurisdiction, or that any of the Company’s current or future products or technologies will be adopted by any state, country, or municipality, within any specific timeframe or at all; risks arising from mergers, acquisitions, joint ventures and other collaborations; the Company’s ability to attract and retain key executives and qualified personnel; guidance provided by management, which may differ from the Company’s actual operating results; the potential impact of unstable market and economic conditions on the Company’s business, financial condition, and stock price; and other risks and uncertainties described in the Company’s filings with the Securities and Exchange Commission, including its periodic reports on Form 10-K and Form 10-Q. There can be no assurance as to any of the foregoing matters. Any forward-looking statement speaks only as of the date of this press release, and the Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by U.S. federal securities laws.

Investor Relations Contacts:

Jeff Ramson
PCG Advisory
[email protected]

Ronald A. Both
Encore Investor Relations
[email protected]

Release – Titan International, Inc. to Announce Third Quarter 2026 Financial Results on October 29, 2026

Titan International, Inc. logo. (PRNewsFoto/Titan International)

Research News and Market Data on TWI

Oct 8, 2026

    CHICAGO, Oct. 8, 2026 /PRNewswire/ — Titan International, Inc. will release its third quarter 2026 financial results before the opening of the market on Thursday, October 29, 2026 to be followed by a teleconference and webcast on Thursday, October 29, 2026 at 9:00 a.m. Eastern Time.

    The real-time, listen-only webcast can be accessed using the following link https://events.q4inc.com/attendee/761783309 or on our website at www.titan-intl.com within the “Investor Relations” page under the “News & Events” menu (https://ir.titan-intl.com/news-and-events/events/default.aspx). Listeners should access the website at least 10 minutes prior to the live event.

    In order to participate in the real-time teleconference, with live audio Q&A, participants should use the following dial in number:

    United States (Toll-Free): 1 833 461 5787
    All Other Locations: https://help.events.q4inc.com/eahc/international-dial-in-numbers
    Participants Access Code / Meeting ID: 761 783 309

    A webcast replay of the teleconference will be available on our website (https://ir.titan-intl.com/news-and-events/events/default.aspx) soon after the live event. 

    About Titan: Titan International, Inc. (NYSE: TWI) is a leading global manufacturer of off-highway wheels, tires, assemblies, and undercarriage products. Headquartered in West Chicago, Illinois, the company globally produces a broad range of products to meet the specifications of original equipment manufacturers (OEMs) and aftermarket customers in the agricultural, earthmoving/construction, and consumer markets. For more information, visit www.titan-intl.com.

    Titan International, Inc. logo. (PRNewsFoto/Titan International)

    Cision View original content to download multimedia:https://www.prnewswire.com/news-releases/titan-international-inc-to-announce-third-quarter-2026-financial-results-on-october-29-2026-302902602.html

    SOURCE Titan International, Inc.

    Release – NN, Inc. Eliminates all of its Preferred Stock

    Primary Logo

    Research News and Market Data on NNBR

    PDF Version

    CHARLOTTE, N.C., Oct. 08, 2026 (GLOBE NEWSWIRE) — NN, Inc. (“NN” or the “Company”) (NASDAQ: NNBR), a global leader in precision manufacturing, today announced that it had completed an important balance sheet transaction.

    The Company has redeemed, paid off and eliminated all of its remaining 18,400 outstanding shares of its Series D Perpetual Preferred Stock, par value $0.01 per share (the “Preferred Stock”) for approximately $30.7 million.

    The redemption was funded with proceeds raised from the Company’s $53.1 million private investment in public equity (PIPE) private placement completed on October 5, 2026. Additionally, the timing of this action enabled the Company to take advantage of a $5.0 million incentive provided under a prior agreement with the sole holder of the security. Thus, the $35.7 million value of the security was redeemed for $30.7 million.

    This security has now been eliminated from NN’s balance sheet. No shares of the Preferred Stock remain outstanding. All of the holder’s rights associated with the Preferred Stock have also been eliminated. This completes an important stepping stone in the transformation of NN, its capital structure, and its business plan.

    Harold Bevis, President and CEO of NN, commented, “NN has significantly deleveraged during 2026. We will use this newly created capital flexibility to accelerate our business plans. We also intend to refinance our Term Loan at the right time and further improve our capital structure. The Company will provide updated guidance during our next earnings call on October 29th, 2026.”

    About NN, Inc.

    NN, Inc. (NASDAQ: NNBR) is an entrepreneurial manufacturing company specializing in manufacturing micron-tolerance precision metal componentry for high-growth end markets, especially Data Center, Electric Grid, Medical, Defense, and High-Value Vehicle systems. Founded in 1980, NN serves over 700 customers on 4 continents through its 2,700 person workforce operating out of 27 global plants. This footprint enables rapid innovation and globally scaled solutions. For more information, visit nninc.com.

    Forward Looking Statements

    This press release may contain forward-looking statements regarding our business, operations, and financial performance. Such statements are based on current expectations and assumptions that are subject to a number of risks and uncertainties. Actual results could differ materially. Please refer to our most recently filed Form 10-K and our Form 10-Q for the period following that Form 10-K, including the risk factors described therein. We undertake no obligation to update any forward-looking statement, except as required by law. Given these risks and uncertainties, investors are cautioned not to place undue reliance on such forward-looking statements.

    Investor Relations: 
    Joe Caminiti
    [email protected]  
    312-445-2870 

    US Trade Deficit Jumps Above $100 Billion as Oil and Gold Imports Surge

    The US trade deficit jumped to $105.6 billion in August, a 13.8% increase from July’s revised $92.8 billion and the widest gap since early 2025, the Commerce Department reported Tuesday. Imports rose 4.3% to $420.8 billion, while exports rose just 1.4% to $315.2 billion.

    The timing is notable. August was the first month after a new phase of tariffs took effect in late July, including a 10% tariff on top allies such as the European Union and a 12.5% tariff on other nations, including China. Importers also kept bringing in components for AI data centers. Semiconductor imports rose $2.4 billion, though computer accessory imports fell $1.6 billion, leaving overall AI-related imports little changed from July but still elevated.

    A more significant driver was industrial supplies. Crude oil imports jumped $3.3 billion and nonmonetary gold imports rose $3.1 billion. The oil figure comes as crude prices have stayed elevated through the Iran conflict, and the gold figure arrives in a year when precious metals have rallied. The surge in goods imports lifted the goods deficit to $136.6 billion, while the services surplus stayed essentially flat.

    Mexico remained the largest deficit at $27.7 billion. The gap with Canada widened by $4.1 billion to $7.1 billion in the month talks between the two countries collapsed and new 50% tariffs took effect, a dispute in which crude oil was left out of the tariffs. The deficit with China rose to $16.4 billion from $15.2 billion in July. That was before a visit by Chinese President Xi Jinping, which extended the current trade truce by two months, set a new early 2027 deadline for talks, and produced tariff cuts on an estimated $60 billion worth of goods.

    The widening gap matters for growth. One forecasting firm said the jump in imports suggests third-quarter GDP growth will come in well below its 4.0% forecast, possibly closer to 2.5%, noting that the rise in goods imports was broad-based and left net trade as a drag overall. Imports subtract from GDP in the national accounts, so a surge can lower headline growth even when it reflects strong demand.

    The next trade report will show whether August’s jump was a one-month surge or the start of a new run higher, and the early 2027 China deadline sets the next hard date for trade policy. Until then, a deficit above $100 billion suggests demand for imported goods remains strong even with higher tariffs in place.

    For small and microcap investors, the report is a reminder that trade policy remains a live cost variable. Smaller manufacturers and importers have less room than multinationals to absorb tariff-driven input costs or reroute supply chains, though the extended China truce and announced tariff cuts offer some relief. Russell 2000 companies earn most of their revenue at home, so growth data matter as much as trade headlines, and a third-quarter GDP reading nearer 2.5% than 4.0% would feed into how investors read the Fed’s path after September’s rate hike.

    Release – NN, Inc. Raises Full-Year 2026 Guidance Ranges for Net Sales and Adjusted EBITDA

    Primary Logo

    Research News and Market Data on NNBR

    PDF Version

    CHARLOTTE, N.C., Sept. 22, 2026 (GLOBE NEWSWIRE) — NN, Inc. (NASDAQ: NNBR) a global leader in precision manufacturing, today announced that it is raising its full-year 2026 guidance ranges for Net Sales and Adjusted EBITDA.

    Updated Full-Year 2026 Guidance

    MetricPrior GuidanceUpdated Guidance
    Net Sales$460 million – $480 million$470 million – $490 million
    Adjusted EBITDA$55 million – $65 million$58 million – $68 million
       

    Management’s updated guidance for 2026 Net Sales at midpoint is $480 million, up $58 million, or 14% versus full-year 2025 Net Sales.

    Management’s updated guidance for 2026 Adjusted EBITDA at midpoint is $63 million, up $14 million, or 29% versus full-year 2025 Adjusted EBITDA.

    Chief Executive Officer Harold Bevis commented, “Our business continues to build momentum as we ramp up in our key growth markets of Data Center, Defense & Electronics, and Medical, where demand for our solutions remains strong and actively expanding. Our year-to-date results and year-to-go forecast underpin this improved guidance and reflect the steady performance our growth and cost programs.

    NN is continuing to invest forward in its 5 Pillar growth end markets and this is translating to increased success and higher results. Raising our full-year 2026 guidance for net sales and adjusted EBITDA reflects our confidence in the performance of the business. We remain focused on our balanced plans for delivering profitable growth and improved cost productivity for our customers and shareholders.”

    NN, Inc. will provide additional detail and updated guidance when it reports third quarter 2026 results on October 28, 2026.

    About NN, Inc.
    NN, Inc. (NASDAQ: NNBR) is an entrepreneurial manufacturing company specializing in manufacturing micron-toleranced precision metal componentry for high-growth end markets, especially Data Center, Electric Grid, Medical, Defense, and High-Value Vehicle systems. Founded in 1980, NN serves over 700 customers on 4 continents through its 2,550 person workforce operating out of 27 global plants. This footprint enables rapid innovation and global scaled solutions. For more information, visit nninc.com.

    Forward Looking Statements
    This press release may contain forward-looking statements regarding our business, operations, and financial performance. Such statements are based on current expectations and assumptions that are subject to a number of risks and uncertainties. Actual results could differ materially. Please refer to our most recently filed Form 10-K and our Form 10-Q for the period following that Form 10-K, including the risk factors described therein. We undertake no obligation to update any forward-looking statement, except as required by law. Given these risks and uncertainties, investors are cautioned not to place undue reliance on such forward-looking statements.

    This press release contains certain financial measures not presented in accordance with U.S. generally accepted accounting principles (“GAAP”) such as adjusted EBITDA (the “non-GAAP financial measures”). These non-GAAP financial measures are not calculated in accordance with GAAP and should not be considered in isolation from, or as a substitute for, the most directly comparable GAAP measures, and may not be comparable to similarly titled measures used by other companies. Management uses these non-GAAP financial measures, together with the comparable GAAP measures, to evaluate the Company’s operating performance and underlying business trends across periods on a consistent basis, and to assist in operational and financial decision-making, including with respect to internal budgeting and resource allocation. Reconciliations of each non-GAAP financial measure to its most directly comparable GAAP measure are set forth in the tables accompanying this presentation. A reconciliation of forward-looking non-GAAP financial measures to the most directly comparable GAAP measures is not provided because the Company cannot reasonably predict certain items necessary for such reconciliation without unreasonable efforts.

    Investor Relations: 
    Joe Caminiti
    [email protected]  
    312-445-2870