The race for the largest IPO of 2026 has a new challenger, and it hasn’t even filed a public prospectus yet. Prediction market data from Polymarket shows Anthropic rapidly closing the gap with SpaceX for the title of the year’s biggest public offering, driven by revenue growth that is accelerating faster than most analysts had modeled just months ago. Bloomberg reported that Anthropic’s annualized revenue for 2026 is now on track to top $65 billion, up sharply from a $47 billion pace in May, positioning the company for a potential fourth quarter market debut.
Notably, OpenAI, Anthropic’s chief rival and another company that could plausibly go public later this year, is not currently registering as a serious contender in the same prediction market data, despite its own scale and continued speculation about a near-term listing.
SpaceX Still Holds the Crown, for Now
For context on what Anthropic would actually need to beat, SpaceX priced its historic offering at $135 per share on June 11, selling 555.6 million shares and valuing the company at $1.78 trillion. The stock opened for trading the following day around $150 and climbed steadily through the session on heavy institutional and retail demand, closing its first day at $160.95, a 19.2% gain that instantly pushed SpaceX’s market capitalization to $2.1 trillion. Shares later peaked near $225 before falling to lows around $104 as investors grew concerned about upcoming lockup expirations and the scale of the company’s capital expenditure plans, a volatility pattern we detailed closely in our coverage of the debut itself. SpaceX has since recovered to roughly $146 a share, valuing the company at $1.93 trillion.
One market strategist covering the name recently argued that betting against Elon Musk has historically been a losing strategy and expects that to remain true here as well, while cautioning investors to prepare for continued sharp swings in either direction.
What the Anthropic Comparison Actually Reveals
Anthropic is currently valued at approximately $1 trillion in private markets, compared to $894 billion for OpenAI, according to Yahoo Finance private market tracking data. That $65 billion annualized revenue run rate is the more important number in this story, since prediction markets are not simply betting on company size, they are betting on whether Anthropic’s growth trajectory can support an offering large enough to eclipse SpaceX’s historic debut, an event we covered as it happened back on June 12.
For investors watching the 2026 IPO calendar, and by extension the broader capital rotation such offerings tend to trigger across public markets, this is worth tracking closely for a specific reason. When Anthropic filed confidentially for its IPO this summer at a reported valuation approaching $965 billion, we noted that the AI capital cycle had entered a genuinely new phase. A fourth quarter debut that could rival or exceed SpaceX’s own historic listing would represent the clearest confirmation yet of that thesis, and would likely reignite the same kind of capital rotation into smaller AI infrastructure and services companies that followed SpaceX’s own debut in June.
The 30-year US Treasury yield climbed to 5.327% on Tuesday, its highest level in 19 years, as stalled talks to end the US-Iran war and renewed fears of escalation pushed oil prices above $90 a barrel and reignited inflation concerns across global markets. The benchmark 10-year yield rose to 4.739%. The selloff was not contained to US markets either, spreading to Japan, where the 10-year government bond yield hit a 30-year peak, and to Europe, where Germany’s 10-year Bund yield touched its highest level since 2011 and France’s 10-year yield reached a 17-year high.
The proximate trigger is the same conflict that has driven energy markets and inflation expectations for much of the year. Iran told officials it would shift to a fully offensive military posture after negotiations toward a permanent end to the war stalled, while Washington has ruled out extending the ceasefire agreement reached in June. With the Strait of Hormuz still effectively shut, the best-case scenario according to strategists covering the region is a prolonged standoff that continues restricting crude flows, while the worst case is a resumption of active fighting.
This Is Not Just an Oil Story
What makes this move genuinely notable is that oil and geopolitics are only part of the explanation. Analysts covering global rates point to at least three additional structural forces pushing long-term yields higher independent of the Iran conflict. The surge in borrowing from AI hyperscalers, whose capital expenditure plans have accelerated sharply throughout 2026, is forcing bond buyers to demand higher returns to absorb the flood of new debt hitting markets. A rising US budget deficit is compounding that pressure, with recent Treasury auctions drawing unusual attention, a 10-year note auction clearing at 4.683%, its highest yield in 19 years, and a 30-year bond auction stopping at 5.216%, a 25-year peak.
Notably, one strategist covering the move specifically named Federal Reserve Chair Kevin Warsh’s shift toward a more opaque communication style as a contributing factor to rising yields, a shift in tone that has drawn scrutiny ahead of his upcoming Jackson Hole address and the market confusion that followed his July press conference. Reduced clarity from the Fed appears to be compounding, rather than easing, the uncertainty already priced into long-duration debt.
For companies operating below the $2 billion market cap threshold, this combination of forces is directly consequential. Small and microcap companies carry disproportionately more variable-rate debt than large cap peers, and a 30-year yield at its highest level since 2007 signals that the higher-cost-of-capital environment weighing on smaller businesses is not easing, it is intensifying. One market strategist noted that for much of the past 15 years, investors operated in a market where stable-to-falling rates consistently supported higher stock prices, but recent Treasury auctions suggest that landscape is genuinely shifting, with investors increasingly focused on the growing scale of US debt and questions about fiscal discipline. For small cap investors, that shift deserves close attention heading into the fall.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Initiating coverage with an Outperform rating and a $5 price target. Our constructive view reflects the company’s multiyear transformation through the Lexmark acquisition, expansion of IT Solutions and Digital Services, and continued focus on operating efficiency. We believe these initiatives can moderate revenue declines, improve profitability and cash generation, and ultimately support a multiyear earnings recovery and valuation re-rating.
Lexmark Integration Positioned to Drive Significant Profit Growth. The acquisition of Lexmark expands Xerox’s global scale and is expected to generate at least $350 million in gross cost synergies by the end of 2027. In our view, it provides a clear path toward ameaningful improvement in operating leverage and competitive positioning.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Small-cap stocks just delivered their best first half on record, and almost nobody is talking about where the money went next.
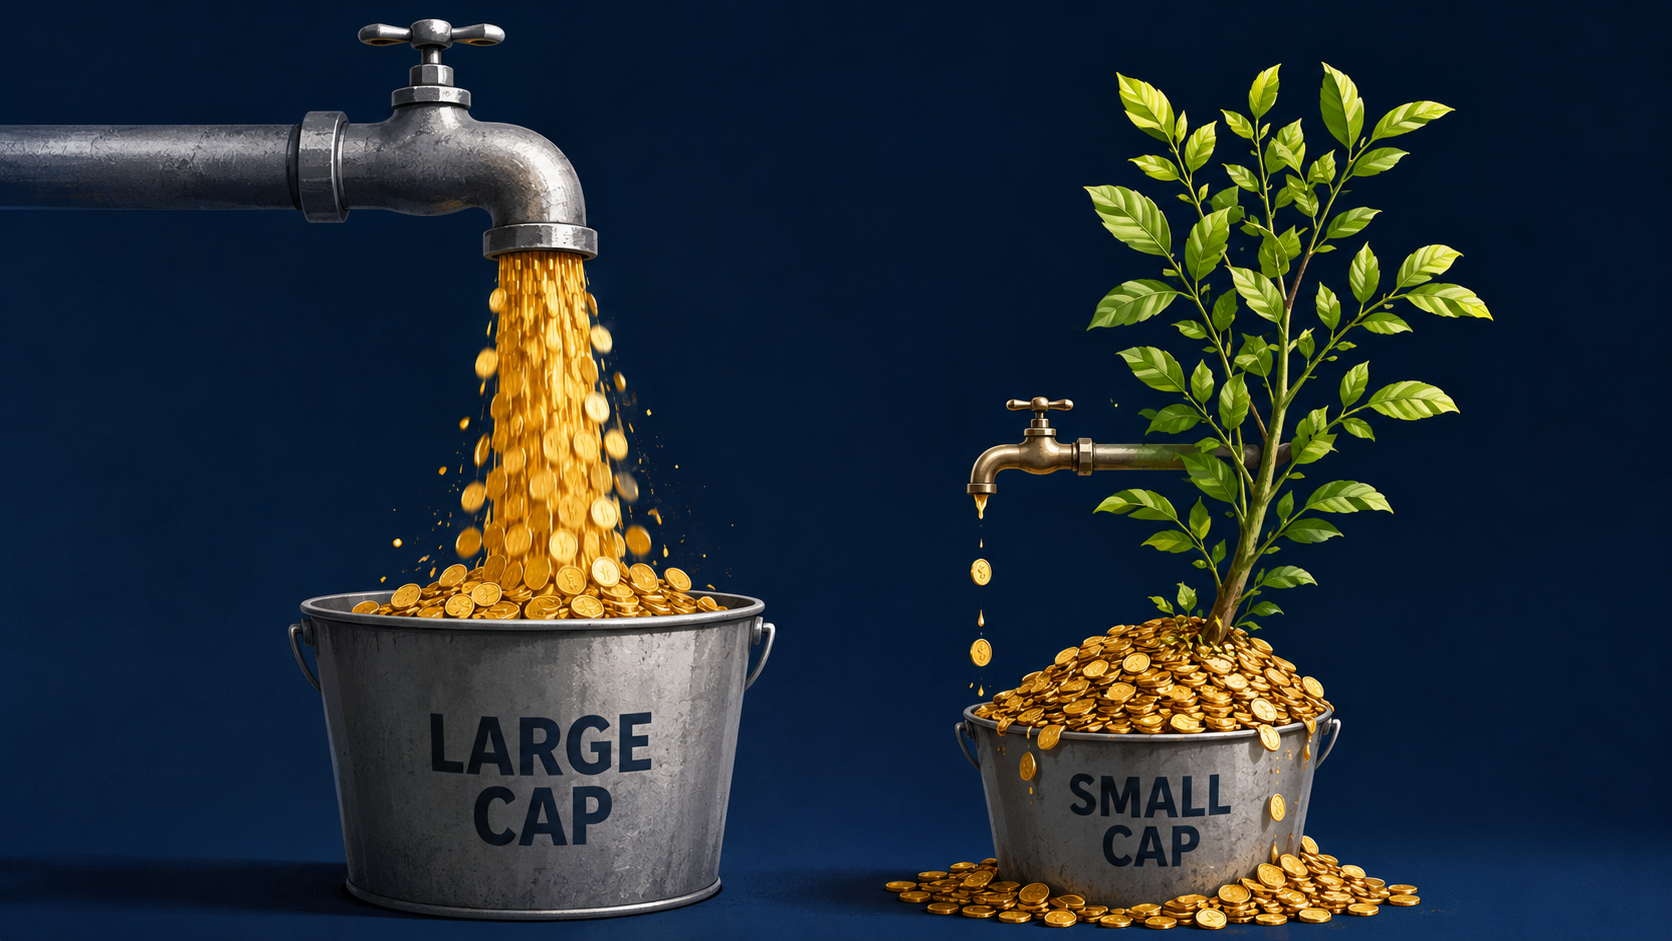
U.S. small caps returned 22.93% in the first half of 2026, outpacing large caps at 9.55% by the widest margin in history for that stretch. It is the kind of number that normally sends investors scrambling to add exposure. Yet the flow of capital into small-cap funds tells a different story, one that raises an obvious question: if small caps are winning this decisively, why hasn’t the money followed?
The data shows a real disconnect. Small-cap ETFs pulled in roughly $7 billion during the first half of the year. Large-cap ETFs, by comparison, absorbed $309 billion over the same period. On the mutual fund side, small-cap funds have seen about $8 billion in net inflows year to date, a modest turnaround after $8 billion in outflows the year before. Actively managed small-cap funds have fared even worse, continuing to lose assets as investors keep shifting toward passive strategies more broadly.
In other words, small caps are outperforming while investors remain largely on the sidelines. That gap between performance and participation is unusual, and some market strategists see it as meaningful. State Street has pointed to the lag as a sign the rally may have room to keep running, arguing that a rotation this significant with so little capital chasing it is not the profile of a crowded trade. If allocators eventually catch up to the performance numbers, the argument goes, the current move could extend further rather than reverse.
Not everyone is convinced. BlackRock has reportedly kept a more cautious stance on small caps as a group, citing ongoing uncertainty around financing conditions and the broader macro backdrop. Smaller companies tend to carry more floating-rate debt and less balance sheet cushion than their large-cap counterparts, which makes them more sensitive to shifts in interest rates and credit availability. That sensitivity cuts both ways. It can amplify gains when conditions turn favorable, but it can just as easily amplify losses if the environment shifts.
There is also a more speculative data point worth noting with some caution. MoneyFlows, a firm that tracks proprietary money-flow signals, claims that nearly 98% of its tracked equity inflows this year have gone into companies with market capitalizations under $300 billion, which it frames as evidence of institutional accumulation building beneath the surface. Unlike the ETF and mutual fund flow data from sources such as Morningstar and State Street, this is a promotional research product, and the claim should be weighed accordingly.
What is clear is that small caps have already made their move on performance. Whether capital flows catch up, stall, or reverse from here may say more about the durability of this rally than the first-half numbers themselves. For investors watching the space, the next few months of fund flow data could matter as much as the earnings results that got small caps here in the first place.
Federal Reserve officials gather in Jackson Hole in two weeks for a symposium that arrives at a genuinely pivotal moment for the central bank. All eyes will be on Chair Kevin Warsh’s first speech in that role, historically a venue Fed chairs use to set the table for upcoming policy decisions or signal structural shifts in approach. This year, the stakes are higher than usual, following a July 29 meeting that left markets confused and a policy committee that appears genuinely divided.
At that meeting, the Fed held rates steady at 3.50% to 3.75% for a fifth consecutive session, as expected. What rattled markets was Warsh’s press conference performance, where he repeatedly deflected questions about why the Fed was not raising rates and suggested that rising bond yields themselves were doing some of the Fed’s tightening work. Markets responded by aggressively pricing in more than two rate hikes in the weeks that followed, alongside genuine uncertainty about whether the committee has a coherent strategy at all.
Since that meeting, the incoming data has offered modest relief. Core CPI rose 2.5% year over year in July, marking a second consecutive month of cooling from 2.6% in June and 2.9% in May. Producer price data told a more mixed story. Core PPI, excluding food, energy, and trade services, rose 4.7% year over year, slightly hotter than expected though down from June’s 5.1% pace, while the monthly reading cooled to 0.2% from an upwardly revised 0.4% in June.
Both figures feed into the Personal Consumption Expenditures price index, the Fed’s preferred inflation gauge, due for release August 26, just days before the Jackson Hole gathering. Economists estimate core PCE rose somewhere between 0.16% and 0.3% in July, a range wide enough that it genuinely could push the committee in either direction.
The range of professional forecasts illustrates just how unresolved this debate is. Some economists estimate July’s core PCE reading held firm enough to keep the annual rate sticky near 3.3%, arguing that could actually harden the resolve of policy hawks rather than ease it. Others view the broader disinflation trend, tied to fading tariff effects and easing oil prices following the resolution of Strait of Hormuz disruptions, as evidence the Fed can remain patient through year-end, while still leaving the door open to tightening if price pressures reaccelerate. A third camp sees the data pointing toward a soft enough reading to pull the three-month annualized core PCE rate down to 2.5%, which would make a September hike look considerably less likely than markets currently expect.
That range of outside opinion mirrors a genuine split inside the Fed itself. Cleveland Fed President Beth Hammack, who dissented in favor of a hike at the July meeting, has continued arguing publicly that more than one rate increase is needed to bring inflation fully under control. Meanwhile, New York Fed President John Williams has suggested that if monthly core PCE consistently prints around 0.2% through the second half of the year, it would signal inflation returning to target on its own, without further tightening. Former Atlanta Fed President Dennis Lockhart, now outside the institution, has cautioned that one or two encouraging months of data is not persuasive evidence that underlying inflation pressure, elevated for more than five years, is genuinely breaking, particularly with the labor market still near full employment.
For companies operating below the $2 billion market cap threshold, this unresolved debate matters directly. Small and microcap companies carry disproportionately more variable-rate debt than large cap peers, making their borrowing costs highly sensitive to exactly the kind of uncertainty currently surrounding the Fed’s next move. The market will receive one more full month of inflation data, including the volatile August CPI report, before the September meeting itself, meaning the path forward remains almost entirely data-dependent. Warsh’s Jackson Hole speech will be the first real signal of how he is weighing that data, and small cap investors watching the cost of capital heading into the fall would do well to treat it as required listening.
Mobix Labs (Nasdaq: MOBX), a semiconductor and defense electronics company, announced Wednesday it has signed a definitive all-stock agreement to acquire Special Project Delivery, a pre-revenue infrastructure development platform pursuing rare earth elements, critical minerals, energy storage, and Western US water resources. The deal is structured with consideration capped at 4.8 million Mobix shares, with closing targeted before the end of 2026, subject to shareholder approval.
Shares of Mobix climbed 5% in premarket trading following the announcement, recovering from a nearly 6% decline the prior session.
This is not a typical semiconductor company acquisition. Mobix currently supplies advanced wireless components and RF technology used in aerospace, defense, and homeland security systems, work that includes existing relationships with Boeing on 737 aircraft programs. The SPD deal adds an entirely different layer to that business: upstream control over the raw materials, energy infrastructure, and water resources that defense manufacturing and critical mineral processing actually depend on.
Mobix Chairman Jim Peterson framed the deal as central to the company’s broader National Security Matters initiative, describing control of strategic domestic mineral rights as fundamental to America’s long-term industrial strength. That initiative, launched earlier this year, has already included a separate acquisition of drone maker Vision Aerial, positioning Mobix as a company trying to assemble components, autonomous systems, and now raw materials under a single national security platform, rather than remaining a narrow RF and semiconductor supplier.
Investors need to understand what this transaction is and is not. SPD is explicitly described as pre-revenue, meaning it currently generates no sales. The company’s positioning across rare earth elements, critical minerals, energy storage, and water infrastructure remains largely conceptual at this stage, with no specific mineral deposits, resource grades, separation technology, capital expenditure estimates, permitting status, or customer commitments disclosed publicly as part of this announcement. Mobix itself is a microcap company that has carried substantial losses and limited liquidity in its own recent financial history.
This combination of a loss-making microcap acquirer and a pre-revenue target operating in a capital-intensive, multi-year development category, rare earth and critical mineral processing, is a materially higher-risk profile than a typical revenue-generating acquisition. The strategic thesis, positioning around America’s push to reduce dependence on foreign rare earth supply chains, is genuinely timely and aligned with a broader theme playing out across defense and industrial policy in 2026. But thematic alignment and executable, funded infrastructure are two very different things at this stage of the deal.
Why the Theme Itself Is Worth Watching Regardless
Independent of this specific transaction’s execution risk, the broader push toward domestic rare earth and critical mineral supply chains remains one of the more significant structural themes in the small cap space this year. Government-backed investment in quantum computing, semiconductor manufacturing, and critical minerals has accelerated sharply, and smaller companies positioning early in that supply chain, whether through actual production assets or, as in this case, an earlier-stage development platform, are drawing real investor attention as a result.
For investors tracking this space, the Mobix-SPD deal is a useful case study in distinguishing between a company aligning itself with a compelling macro theme and a company that has actually built or acquired producing assets within that theme. The rare earth and critical minerals buildout in the United States is real and accelerating. Whether any single microcap deal successfully executes on that opportunity is a separate question entirely, one that depends on capital access, permitting, technical validation, and years of infrastructure development still ahead.
CALGARY, AB, Aug. 13, 2026 /CNW/ — InPlay Oil Corp. (TSX: IPO) (TASE: IPO) (OTCQX: IPOOF) (“InPlay” or the “Company”) is pleased to announce its financial and operating results for the three and six months ended June 30, 2026. InPlay’s unaudited interim financial statements and notes, and Management’s Discussion and Analysis (“MD&A”) for the three and six months ended June 30, 2026 will be available at “www.sedarplus.ca” and the Company’s website at “www.inplayoil.com“. An updated corporate presentation will be available on our website in due course.
Second Quarter 2026 Highlights:
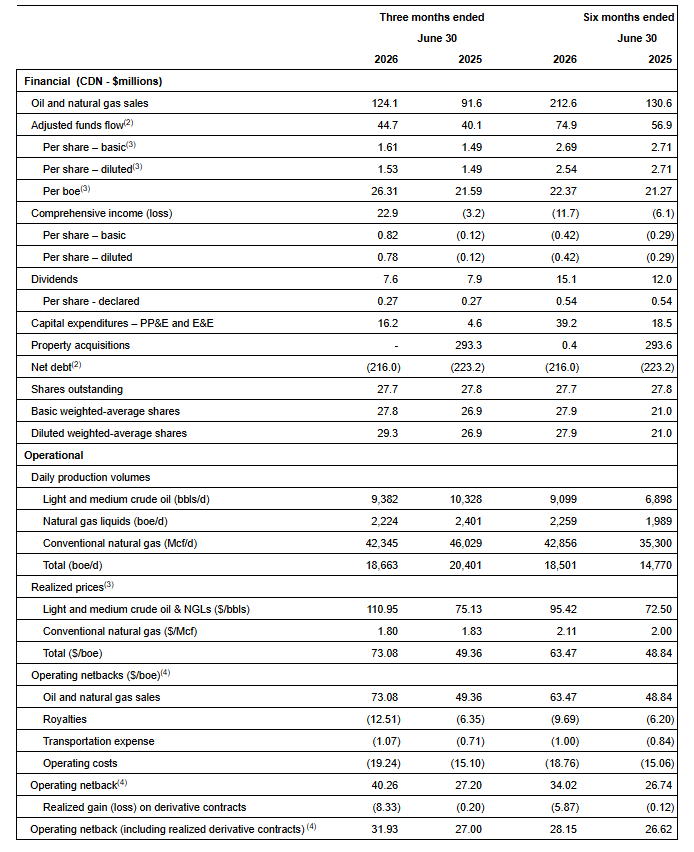
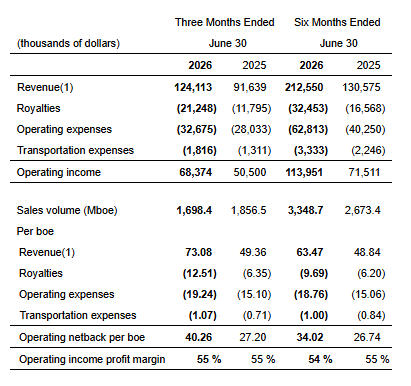
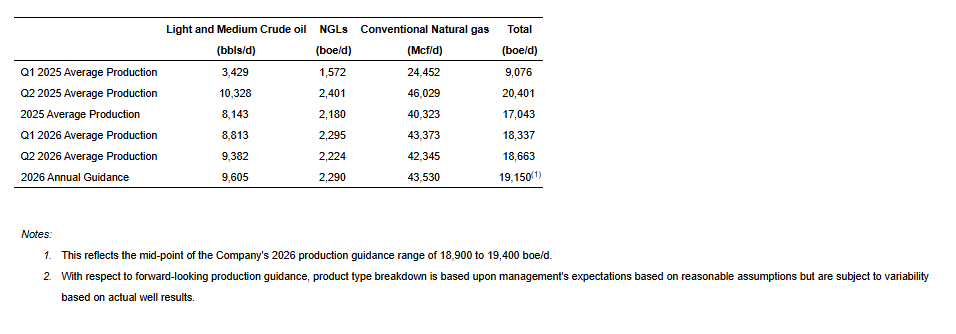
Achieved average quarterly production of 18,663 boe/d(1) (62% light crude oil and NGLs), a 2% increase from Q1 2026.
Improved light oil production to 9,382 bbl/d, a 6% increase from Q1 2026. Light crude oil weighting improved by 3% from Q1 2026 driving stronger per boe netbacks and returns.
Realized strong operating income of $68.4 million, a 50% increase from Q1 2026, resulting in an operating income profit margin(4) of 55%, a 7% improvement from Q1 2026. Field operating netbacks(4) improved to $40.26/boe, an increase of 46% compared to Q1 2026.
Delivered Adjusted Funds Flow (“AFF”)(2) of $44.7 million ($1.61 per weighted average basic share(3)), a 48% increase from Q1 2026.
Generated significant Free Adjusted Funds Flow (“FAFF”)(4) of $28.4 million.
Returned $7.6 million to shareholders via monthly dividends (7.2% yield relative to current share price). Since November 2022, InPlay has returned $82 million ($4.14/share) to shareholders through dividends, including dividends declared to date in the third quarter.
Under the Normal Course Issuer Bid initiated on May 21, 2026, began repurchasing shares in June and 0.5% of outstanding shares were cancelled.
Subsequent Events:
On August 5, 2026, the Company announced it had entered into a definitive agreement to acquire a private oil and gas producer for cash consideration of $54.25 million, prior to closing adjustments adding 1,400 boe/d of current production and 50 additional net drilling locations all in our core Pembina area.
On July 24, 2026, the Company renewed its Senior Credit Facility, which now consists of committed amounts of a $140 million revolving line of credit and a $50 million operating line of credit. In addition, the borrowing base was expanded by $60 million, for a total borrowing base of $250 million.
Message to Shareholders:
The second quarter of 2026 was another period of strong execution for InPlay. Operationally, InPlay’s first half capital program was executed under budget and ahead of schedule, continuing our track-record of doing more with less. InPlay’s H1 2026 drilling program also achieved IP rates that were 30% – 48% ahead of our internal projections, resulting in corporate oil production exceeding internal forecasts.
The combination of high oil prices and strong oil production led to InPlay delivering quarterly AFF of $44.7 million, the highest quarterly level in its 10- year history as a public company. InPlay also returned $7.6 million ($0.27/share) to shareholders through dividends and repurchased $2.2 million (0.5% of shares outstanding), while also reducing net debt.
InPlay’s financial strength positioned the Company to be able to sign a definitive agreement to acquire a private oil and gas producer for cash consideration of $54.25 million (the “Acquisition“), funded entirely through our recently expanded credit capacity. Completing an acquisition of this quality without dilution to shareholders directly enhances per share growth and accretion. The Acquisition is expected to be 18% accretive on both AFF per share and FAFF per share, while adding 1,400 boe/d of production (85% liquids) and 50 net drilling locations in our core areas.
The Acquisition builds on InPlay’s decade-long track record of value-add M&A, utilizing conservative leverage ratios to acquire high-quality, free cash flow generating assets to generate sustainable long-term shareholder returns while maintaining a conservative balance sheet. This approach supports the rapid repayment of acquisition debt, positioning the Company for the next accretive opportunity. The Acquisition advances InPlay’s strategy of building a disciplined, sustainable light oil growth company by increasing production, AFF and FAFF per share while expanding its high-quality drilling inventory. The complementary assets of the Acquisition directly offset InPlay’s existing operations and infrastructure, delivering immediate operational synergies.
InPlay’s year to date capital program has been completed below budget, allowing the Company to increase the number of planned wells by 30% with only a 15% increase in capital (from mid-point). InPlay expanded its pre-acquisition capital program to drill a total of 15.0 net Cardium wells, an increase from 13.0 net (mid-point) Cardium wells in our original capital budget. In addition, 2.0 net Belly River wells are planned on the acquired assets, resulting in a pro forma capital program of $80 – $82 million drilling 17.0 net horizontal wells.
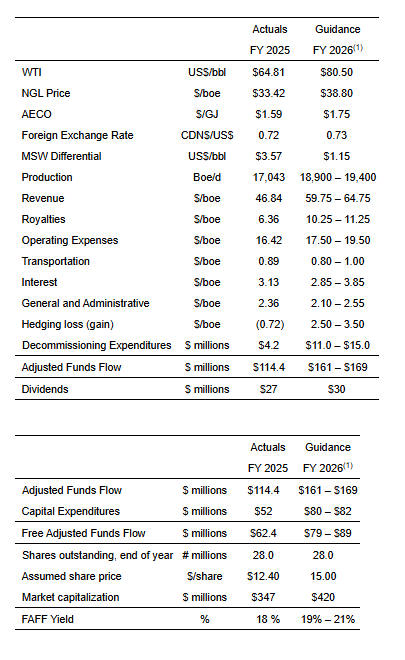
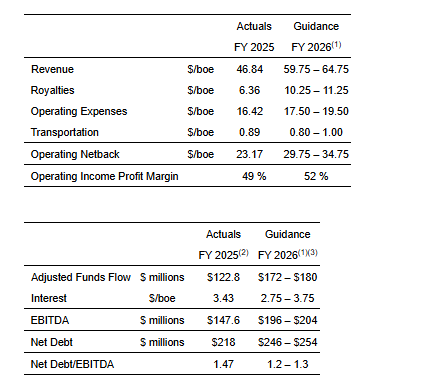
InPlay has increased 2026 average annual production guidance to 18,900 boe/d – 19,400 boe/d(1) (61% – 63% light oil and NGLs). The Company also increased 2026 AFF by 12% to $165 million (mid-point) from $147 million (mid-point), with no change to commodity price assumptions. This is expected to increase FAFF by 9% from $77 million (mid-point) to $84 million (mid-point), equating to a FAFF yield(4) of 20% (mid-point). The Company’s leverage metrics are projected to remain strong with net debt to Q4 2026 EBITDA(4) now forecasted to be 1.25x (mid-point).
Further information related to the Acquisition and revised pro forma guidance is outlined in the Company’s August 5, 2026 Press Release (Press Release – August 5, 2026).
Second Quarter 2026 Financial & Operations Overview:
InPlay completed an active capital program during the second quarter, investing $16.3 million to complete and bring on production three (3.0 net) Pembina Cardium wells drilled in the first quarter of 2026, and to drill and complete three (3.0 net) additional Pembina Cardium wells. Operational execution remained strong during the quarter, with drilling and completion operations under budget. The three most recent wells were drilled approximately 40 days ahead of schedule, as field access occurred earlier than typically anticipated following spring break-up, which was beneficial as wet weather in the second half of June and into mid-July caused delays to the start of our H2 2026 drilling program.
Quarterly production averaged 18,663 boe/d(1) (62% light crude oil and NGLs), representing a 2% increase from the first quarter of 2026. Quarterly crude oil production averaged 9,382 bbl/d, a 6% increase from the first quarter of 2026. Oil production remained strong throughout the quarter and exceeded internal forecasts.
The second quarter was our largest to date for turnaround activity and resulted in slightly increased operating costs compared to the first quarter of 2026, as well as the reactivation of shut-in, low-rate wells that went down in a lower commodity environment and are economic to return to production in the strong commodity price environment.
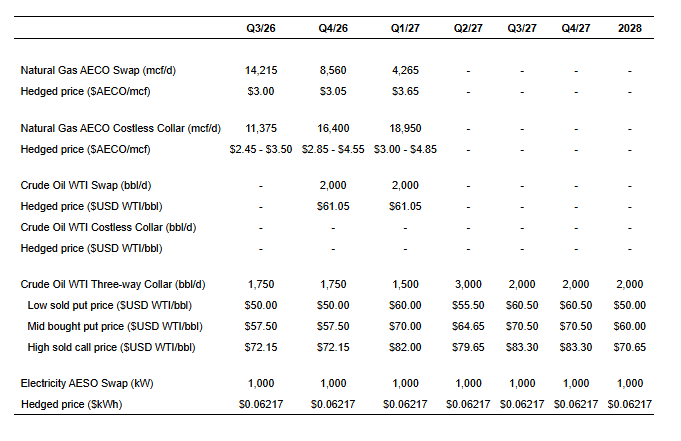
InPlay generated record quarterly AFF of $44.7 million ($1.61 per basic share), representing a 48% increase from the first quarter of 2026. These results were achieved despite realizing $14.1 million in hedging losses, primarily reflecting the significant increase in WTI during the quarter relative to the hedges required by our first-lien lenders to facilitate the 2025 acquisition. The Company expects minimal hedge losses in the future at our current commodity price forecast as significantly less crude oil volumes are hedged going forward and due to our strong natural gas hedges. This is reflected in the mark-to-market value of the Company’s hedges, which was an asset of $6.9 million at June 30, 2026 compared to a liability of $30.5 million at March 31, 2026. Details of the Company’s current hedges are provided in the “Hedging Summary” section of the Reader Advisories.
During the quarter, InPlay paid dividends of $7.6 million to shareholders, representing a 7.2% yield relative to our current share price. Since November 2022, InPlay has distributed $82 million ($4.14/share) in dividends, including dividends declared to date in the third quarter.
Net income of $22.9 million ($0.82 per basic share; $0.78 per diluted share), was realized in the second quarter of 2026 which includes a $37 million unrealized mark-to-market gain on the Company’s hedge portfolio.
Financial and Operating Results:
On behalf of our employees, management team and Board of Directors, we thank our shareholders for their continued support. With a high-quality asset base, a strengthened outlook and the recently announced acquisition, InPlay is well positioned to continue generating sustainable free cash flow and long-term shareholder value.
For further information please contact: Doug Bartole, President and Chief Executive Officer, InPlay Oil Corp., Telephone: (587) 955-0632; Kevin Leonard, Vice President Corporate & Business Development, InPlay Oil Corp., Telephone: (587) 955-0635
Reader Advisories
Hedging Summary
Commodity Hedges
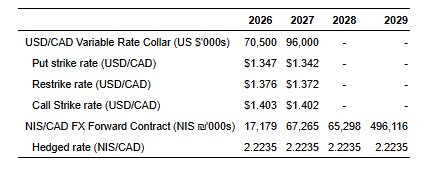
Foreign Exchange Hedges
Currency
USD refers to United States Dollars, NIS or ILS refers to New Israeli Shekels and CAD refers to Canadian Dollars.
Non-GAAP and Other Financial Measures
Throughout this document and other materials disclosed by the Company, InPlay uses certain measures to analyze financial performance, financial position and cash flow. These non-GAAP and other financial measures do not have any standardized meaning prescribed under GAAP and therefore may not be comparable to similar measures presented by other entities. The non-GAAP and other financial measures should not be considered alternatives to, or more meaningful than, financial measures that are determined in accordance with GAAP as indicators of the Company performance. Management believes that the presentation of these non-GAAP and other financial measures provides useful information to shareholders and investors in understanding and evaluating the Company’s ongoing operating performance, and the measures provide increased transparency and the ability to better analyze InPlay’s business performance against prior periods on a comparable basis.
Non-GAAP Financial Measures and Ratios
Included in this document are references to the terms “free adjusted funds flow”, “operating income”, “operating netback per boe”, “operating income profit margin” and “Net Debt to EBITDA”. Management believes these measures and ratios are helpful supplementary measures of financial and operating performance and provide users with similar, but potentially not comparable, information that is commonly used by other oil and natural gas companies. These terms do not have any standardized meaning prescribed by GAAP and should not be considered an alternative to, or more meaningful than “profit before taxes”, “profit and comprehensive income”, “adjusted funds flow”, “capital expenditures”, “net debt” or assets and liabilities as determined in accordance with GAAP as a measure of the Company’s performance and financial position.
Free Adjusted Funds Flow / FAFF Yield
Management considers FAFF and FAFF Yield as important measures to identify the Company’s ability to improve its financial condition through debt repayment and its ability to provide returns to shareholders. FAFF should not be considered as an alternative to or more meaningful than AFF as determined in accordance with GAAP as an indicator of the Company’s performance. FAFF is calculated by the Company as AFF less exploration and development capital expenditures and property dispositions (acquisitions) and is a measure of the cashflow remaining after capital expenditures before corporate acquisitions that can be used for additional capital activity, corporate acquisitions, repayment of debt or decommissioning expenditures or potentially return of capital to shareholders. Free adjusted funds flow yield is calculated by the Company as free adjusted funds flow divided by the market capitalization of the Company. Refer to the “Forward Looking Information and Statements” section for a calculation of forecast FAFF and FAFF yield.
Operating Income/Operating Netback per boe/Operating Income Profit Margin
InPlay uses “operating income”, “operating netback per boe” and “operating income profit margin” as key performance indicators. Operating income is calculated by the Company as oil and natural gas sales less royalties, operating expenses and transportation expenses and is a measure of the profitability of operations before administrative, share-based compensation, financing and other non-cash items. Management considers operating income an important measure to evaluate its operational performance as it demonstrates its field level profitability. Operating income should not be considered as an alternative to or more meaningful than net income as determined in accordance with GAAP as an indicator of the Company’s performance. Operating netback per boe is calculated by the Company as operating income divided by average production for the respective period. Management considers operating netback per boe an important measure to evaluate its operational performance as it demonstrates its field level profitability per unit of production. Operating income profit margin is calculated by the Company as operating income as a percentage of oil and natural gas sales. Management considers operating income profit margin an important measure to evaluate its operational performance as it demonstrates how efficiently the Company generates field level profits from its sales revenue. Refer below for a calculation of operating income, operating netback per boe and operating income profit margin. Refer to the “Forward Looking Information and Statements” section for a calculation of forecast operating income, operating netback per boe and operating income profit margin.
Net Debt to EBITDA
Management considers Net Debt to EBITDA an important measure as it is a key metric to identify the Company’s ability to fund financing expenses, net debt reductions and other obligations. EBITDA is calculated by the Company as adjusted funds flow before interest expense. When this measure is presented quarterly, EBITDA is annualized by multiplying by four. When this measure is presented on a trailing twelve month basis, EBITDA for the twelve months preceding the net debt date is used in the calculation. This measure is consistent with the EBITDA formula prescribed under the Company’s Credit Facility. Net Debt to EBITDA is calculated as Net Debt divided by EBITDA. Refer to the “Forward Looking Information and Statements” section for a calculation of forecast Net Debt to EBITDA.
Capital Management Measures
Adjusted Funds Flow
Management considers adjusted funds flow to be an important measure of InPlay’s ability to generate the funds necessary to finance capital expenditures. Adjusted funds flow is a GAAP measure and is disclosed in the notes to the Company’s financial statements for the three and six months ended June 30, 2026. All references to adjusted funds flow throughout this document are calculated as funds flow adjusting for foreign exchange loss, transaction and integration costs and decommissioning expenditures. Foreign exchange loss is primarily an unrealized movement on the Company’s NIS denominated Bonds due to movements in the CAD/NIS exchange rate. In addition, InPlay has effectively mitigated its exposure to fluctuations in the CAD to NIS exchange rate on the NIS denominated Bond by entering into NIS/CAD foreign exchange hedges with notional amounts and terms that align with the future cash outflow requirements of the Bonds. Therefore, at the end of the life of the Bonds, the FX impact on the Company will be insignificant. Transaction and integration costs are non-recurring costs for the purposes of an acquisition, making the exclusion of these items relevant in Management’s view to the reader in the evaluation of InPlay’s operating performance. Decommissioning expenditures are adjusted from funds flow as they are incurred on a discretionary and irregular basis and are primarily incurred on previous operating assets. The Company also presents adjusted funds flow per share whereby per share amounts are calculated using weighted average shares outstanding consistent with the calculation of profit per common share.
Net Debt
Net debt is a GAAP measure and is disclosed in the notes to the Company’s financial statements for the three and six months ended June 30, 2026. The Company closely monitors its capital structure with the goal of maintaining a strong balance sheet to fund the future growth of the Company. The Company monitors net debt as part of its capital structure. The Company uses net debt (Long-term debt (Bond at inception value) plus accounts payable and accrued liabilities less accounts receivables and accrued receivables, restricted cash, cash and cash equivalents, prepaid expenses and deposits and inventory) as an alternative measure of outstanding debt. Management considers net debt an important measure to assist in assessing the liquidity of the Company.
Supplementary Measures
“Average realized crude oil price” is comprised of crude oil commodity sales from production, as determined in accordance with IFRS, divided by the Company’s crude oil volumes. Average prices are before deduction of transportation costs and do not include gains and losses on financial instruments.
“Average realized NGL price” is comprised of NGL commodity sales from production, as determined in accordance with IFRS, divided by the Company’s NGL volumes. Average prices are before deduction of transportation costs and do not include gains and losses on financial instruments.
“Average realized natural gas price” is comprised of natural gas commodity sales from production, as determined in accordance with IFRS, divided by the Company’s natural gas volumes. Average prices are before deduction of transportation costs and do not include gains and losses on financial instruments.
“Average realized commodity price” is comprised of commodity sales from production, as determined in accordance with IFRS, divided by the Company’s volumes. Average prices are before deduction of transportation costs and do not include gains and losses on financial instruments.
“Adjusted funds flow per weighted average basic share” is comprised of adjusted funds flow divided by the basic weighted average common shares.
“Adjusted funds flow per weighted average diluted share” is comprised of adjusted funds flow divided by the diluted weighted average common shares.
“Adjusted funds flow per boe” is comprised of adjusted funds flow divided by total production.
Forward-Looking Information and Statements
This document contains certain forward-looking information and statements within the meaning of applicable securities laws. The use of any of the words “expect”, “anticipate”, “continue”, “estimate”, “may”, “will”, “project”, “should”, “believe”, “plans”, “intends”, “forecast” and similar expressions are intended to identify forward-looking information or statements. In particular, but without limiting the foregoing, this document contains forward-looking information and statements pertaining to the following: the Company’s business strategy, milestones and objectives; the anticipated funding and timing of the Acquisition, including the use of the Company’s credit facility and anticipated borrowing capacity; the anticipated timing of the closing of the Acquisition; the anticipated benefits of the Acquisition, including the impact of the Acquisition on the Company’s operations, inventory and development opportunities; financial results and shareholder returns; anticipated production from the acquired assets associated with the Acquisition; anticipated production following completion of the Acquisition; anticipated increases in light oil production and product mix; expected accretion to AFF per share; FAFF per share, production per share and funds flow netback metrics; anticipated FAFF and FAFF yield; anticipated dividends and dividend yield; anticipated benefits of the Company’s NCIB and shareholder return strategy; anticipated operating netbacks, operating income and FAFF generated by the acquired assets associated with the Acquisition; anticipated operating, infrastructure, administrative and other synergies associated with the Acquisition, including anticipated annual cost savings and the expectation that no additions to corporate office personnel will be required; anticipated Belly River production, development opportunities and drilling inventory associated with the acquired assets, including identified drilling locations and expected payout periods; the satisfaction or waiver of the closing conditions to the Acquisition; anticipated future liquidity, financial flexibility, borrowing capacity and financial capacity; anticipated net debt and Net Debt to EBITDA ratios; future development, exploration, acquisition and infrastructure activities and related capital expenditures; the Company’s planned 2026 capital program; the amount and timing of capital projects; the number of wells expected to be drilled and completed; the Company’s asset retirement and decommissioning activities; the Company’s 2026 guidance; the Company’s anticipated 2026 annual average production and product mix; future oil, natural gas and NGL prices; future results from operations and operating metrics, including AFF, FAFF, operating income, operating netbacks, operating income profit margins and Net Debt to EBITDA; future costs, expenses and royalty rates; future interest costs; the exchange rates between USD and CAD and between NIS and CAD; methods of funding the Company’s capital program; future debt levels, leverage ratios, dividends, share repurchase and other shareholder return initiatives; and other similar statements.
The internal projections, expectations, or beliefs underlying the 2026 capital budget and associated guidance are subject to change in light of, among other factors, changes to U.S. economic, regulatory and/or trade policies (including tariffs), the impact of world events including the Russia/Ukraine conflict and wars in the Middle East, ongoing results, prevailing economic circumstances, volatile commodity prices, and changes in industry conditions and regulations. InPlay’s 2026 financial outlook and guidance provides shareholders with relevant information on management’s expectations for results of operations, excluding any potential acquisitions or dispositions (other than the Acquisition), for such time periods based upon the key assumptions outlined herein. Readers are cautioned that events or circumstances could cause capital plans and associated results to differ materially from those predicted and InPlay’s guidance for 2026 may not be appropriate for other purposes. Accordingly, undue reliance should not be placed on same.
Forward-looking statements or information are based on a number of material factors, expectations or assumptions of InPlay which have been used to develop such statements and information, but which may prove to be incorrect. Although InPlay believes that the expectations reflected in such forward-looking statements or information are reasonable, undue reliance should not be placed on forward-looking statements because InPlay can give no assurance that such expectations will prove to be correct. In addition to other factors and assumptions which may be identified herein, assumptions have been made regarding, among other things: the current U.S. economic, regulatory and/or trade policies; the impact of increasing competition; the general stability of the economic and political environment in which InPlay operates; the timely receipt of any required regulatory approvals; the ability of InPlay to obtain qualified staff, equipment and services in a timely and cost efficient manner; drilling results; the ability of the operator of the projects in which InPlay has an interest in to operate the field in a safe, efficient and effective manner; the ability of InPlay to obtain debt financing on acceptable terms; the anticipated tax treatment of the monthly base dividend; that (i) the tariffs that are currently in effect on goods exported from or imported into Canada continue in effect for an extended period of time, the tariffs that have been threatened are implemented, that tariffs that are currently suspended are reactivated, the rate or scope of tariffs are increased, or new tariffs are imposed, including on oil and natural gas, (ii) the U.S. and/or Canada imposes any other form of tax, restriction or prohibition on the import or export of products from one country to the other, including on oil and natural gas, and (iii) the tariffs imposed or threatened to be imposed by the U.S. on other countries and retaliatory tariffs imposed or threatened to be imposed by other countries on the U.S., will trigger a broader global trade war which could have a material adverse effect on the Canadian, U.S. and global economies, and by extension the Canadian oil and natural gas industry and the Company, including by decreasing demand for (and the price of) oil and natural gas, disrupting supply chains, increasing costs, causing volatility in global financial markets, and limiting access to financing; the duration and impact of tariffs that are currently in effect on goods exported from or imported into Canada, and that other than the tariffs that are currently in effect, neither the U.S. nor Canada (i) increases the rate or scope of such tariffs, reenacts tariffs that are currently suspended, or imposes new tariffs, on the import of goods from one country to the other, including on oil and natural gas, and/or (ii) imposes any other form of tax, restriction or prohibition on the import or export of products from one country to the other, including on oil and natural gas; changes in political and economic conditions, including risks associated with tariffs, export taxes, export restrictions or other trade actions; impacts of any tariffs imposed on Canadian exports into the United States by the Trump administration and any retaliatory steps taken by the Canadian federal government; that InPlay’s results and operations could be adversely affected by economic or geopolitical developments, including protectionist trade policies such as tariffs, or other events; conditions in international markets, including social and political conditions, civil unrest, terrorist activity, governmental changes, restrictions on the ability to transfer capital across borders, tariffs and other protectionist measures; field production rates and decline rates; the ability to replace and expand oil and natural gas reserves through acquisition, development and exploration; the timing and cost of pipeline, storage and facility construction and the ability of InPlay to secure adequate product transportation; future commodity prices; that various conditions to a shareholder return strategy can be satisfied; the ongoing impact of the Russia/Ukraine conflict and wars in the Middle East; currency, exchange and interest rates; regulatory framework regarding royalties, taxes and environmental matters in the jurisdictions in which InPlay operates; and the ability of InPlay to successfully market its oil and natural gas products.
Without limitation of the foregoing, readers are cautioned that the Company’s future dividend payments to shareholders of the Company, if any, and the level thereof will be subject to the discretion of the Board of Directors of InPlay. The Company’s dividend policy and funds available for the payment of dividends, if any, from time to time, is dependent upon, among other things, levels of FAFF, leverage ratios, financial requirements for the Company’s operations and execution of its growth strategy, fluctuations in commodity prices and working capital, the timing and amount of capital expenditures, credit facility availability and limitations on distributions existing thereunder, and other factors beyond the Company’s control. Further, the ability of the Company to pay dividends will be subject to applicable laws, including satisfaction of solvency tests under the Business Corporations Act (Alberta), and satisfaction of certain applicable contractual restrictions contained in the agreements governing the Company’s outstanding indebtedness. Further, the actual amount, the declaration date, the record date and the payment date of any dividend are subject to the discretion of the Board of Directors of InPlay. There can be no assurance that InPlay will pay dividends in the future.
The forward-looking information and statements included herein are not guarantees of future performance and should not be unduly relied upon. Such information and statements, including the assumptions made in respect thereof, involve known and unknown risks, uncertainties and other factors that may cause actual results or events to differ materially from those anticipated in such forward-looking information or statements including, without limitation: changes in industry regulations and legislation (including, but not limited to, tax laws, royalties, and environmental regulations); that (i) the tariffs that are currently in effect on goods exported from or imported into Canada continue in effect for an extended period of time, the tariffs that have been threatened are implemented, that tariffs that are currently suspended are reactivated, the rate or scope of tariffs are increased, or new tariffs are imposed, including on oil and natural gas, (ii) the U.S. and/or Canada imposes any other form of tax, restriction or prohibition on the import or export of products from one country to the other, including on oil and natural gas, and (iii) the tariffs imposed or threatened to be imposed by the U.S. on other countries and retaliatory tariffs imposed or threatened to be imposed by other countries on the U.S., will trigger a broader global trade war which could have a material adverse effect on the Canadian, U.S. and global economies, and by extension the Canadian oil and natural gas industry and the Company, including by decreasing demand for (and the price of) oil and natural gas, disrupting supply chains, increasing costs, causing volatility in global financial markets, and limiting access to financing; the continuing impact of the Russia/Ukraine conflict and war in the Middle East; potential changes to U.S. economic, regulatory and/or trade policies as a result of a change in government; inflation and the risk of a global recession; changes in our planned capital program; changes in our approach to shareholder returns; changes in commodity prices and other assumptions outlined herein; the risk that dividend payments may be reduced, suspended or cancelled; the potential for variation in the quality of the reservoirs in which InPlay operates; changes in the demand for or supply of InPlay’s products; unanticipated operating results or production declines; changes in tax or environmental laws, royalty rates or other regulatory matters; changes in development plans or strategies of InPlay or by third party operators of InPlay’s properties; changes in InPlay’s credit structure, increased debt levels or debt service requirements; inaccurate estimation of InPlay’s light crude oil and natural gas reserve and resource volumes; limited, unfavorable or a lack of access to capital markets; increased costs; a lack of adequate insurance coverage; the impact of competitors; and certain other risks detailed from time-to-time in InPlay’s continuous disclosure documents filed on SEDAR+ including InPlay’s Annual Information Form dated March 30, 2026 and InPlay’s annual management’s discussion & analysis for the year ended December 31, 2025.
This document contains future-oriented financial information and financial outlook information (collectively, “FOFI“) about InPlay’s financial and leverage targets and objectives, potential dividends, and beliefs underlying our 2026 capital budget, anticipated 2026 production and associated guidance, all of which are subject to the same assumptions, risk factors, limitations, and qualifications as set forth in the above paragraphs. The actual results of operations of InPlay and the resulting financial results will likely vary from the amounts set forth in this document and such variation may be material. InPlay and its management believe that the FOFI has been prepared on a reasonable basis, reflecting management’s reasonable estimates and judgments. However, because this information is subjective and subject to numerous risks, it should not be relied on as necessarily indicative of future results. Except as required by applicable securities laws, InPlay undertakes no obligation to update such FOFI. FOFI contained in this document was made as of the date of this document and was provided for the purpose of providing further information about InPlay’s anticipated future business operations and strategy. Readers are cautioned that the FOFI contained in this document should not be used for purposes other than for which it is disclosed herein.
The forward-looking statements and FOFI contained in this document speak only as of the date hereof and InPlay does not assume any obligation to publicly update or revise any of the included forward-looking statements or FOFI, whether as a result of new information, future events or otherwise, except as may be required by applicable securities laws.
Risk Factors to FLI
Risk factors that could materially impact successful execution and actual results of the Company’s 2026 capital program and associated guidance and estimates include:
risks related to an international trade war, including the risk that the U.S. government imposes additional tariffs on Canadian goods, including crude oil and natural gas, and that such tariffs (and/or the Canadian government’s response to such tariffs) adversely affect the demand and/or market price for the Company’s products and/or otherwise adversely affects the Company;
volatility of petroleum and natural gas prices and inherent difficulty in the accuracy of predictions related thereto;
changes in Federal and Provincial regulations;
the Company’s ability to secure financing for the 2026 capital program and longer-term capital plans sourced from AFF, bank or other debt instruments, asset sales, equity issuance, infrastructure financing or some combination thereof; and
those additional risk factors set forth in the Company’s MD&A and most recent Annual Information Form filed on SEDAR+.
Key Budget and Underlying Material Assumptions to FLI
The key budget and underlying material assumptions used by the Company in the development of its 2026 guidance are as follows:
Test Results and Initial Production Rates
Any references in this press release to initial production (“IP”) rates are useful in confirming the presence of hydrocarbons, however, such rates are not determinative of the rates at which such wells will continue production and decline thereafter and are not indicative of long-term performance or ultimate recovery. Test results and IP rates disclosed herein, particularly those short in duration, may not necessarily be indicative of long-term performance or of ultimate recovery. A pressure transient analysis or well-test interpretation has not been carried out and thus certain of the test results provided herein should be considered to be preliminary until such analysis or interpretation has been completed. While encouraging, readers are cautioned not to place reliance on such rates in calculating the aggregate production of the Company.
Production Breakdown by Product Type:
Disclosure of production on a per boe basis in this document consists of the constituent product types as defined in National Instrument 51-101, Standards of Disclosure for Oil and Gas Activities (“NI 51-101“) and their respective quantities disclosed in the table below:
References to crude oil, light oil, NGLs or natural gas production in this press release refer to the light and medium crude oil, natural gas liquids and conventional natural gas product types, respectively, as defined in NI 51-101.
BOE Equivalent
Barrel of oil equivalents or BOEs may be misleading, particularly if used in isolation. A BOE conversion ratio of 6 mcf: 1 bbl is based on an energy equivalency conversion method primarily applicable at the burner tip and does not represent a value equivalency at the wellhead. Given that the value ratio based on the current price of crude oil as compared to natural gas is significantly different than the energy equivalency of 6:1, utilizing a 6:1 conversion basis may be misleading as an indication of value.
Dividends
InPlay’s future shareholder distributions, including but not limited to the payment of dividends, if any, and the level thereof is uncertain. Any decision to pay dividends on InPlay’s shares (including the actual amount, the declaration date, the record date and the payment date in connection therewith and any special dividends) will be subject to the discretion of the Board of Directors and may depend on a variety of factors, including, without limitation, InPlay’s business performance, financial condition, financial requirements, growth plans, expected capital requirements and other conditions existing at such future time including, without limitation, contractual restrictions and satisfaction of the solvency tests imposed on InPlay under applicable corporate law. Further, the actual amount, the declaration date, the record date and the payment date of any dividend are subject to the discretion of the Board of Directors. There can be no assurance that InPlay will pay dividends in the future.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Second Quarter FY 2026 Financial Results. Summit Midstream generated $155.0 million of revenue, up 10.6% from the prior-year quarter, and reported net income attributable to Summit Midstream Corp. of $1.6 million, or $0.11 per share, compared with a net loss of $8.0 million, or $(0.66) per share, during the prior year period. Adj. EBITDA amounted to $60.7 million compared to $61.1 million during the prior year period, as stronger Rockies and Permian performance was offset by weaker Mid-Con and Piceance segment results. We had forecast revenue of $144.4 million and adj. EBITDA of $59.7 million. Distributable cash flow increased to $36.8 million from $32.4 million, and free cash flow increased modestly to $9.4 million compared to $9.2 million during the second quarter of 2025. Sequentially, SMC’s second quarter results demonstrated meaningful improvement, supported by stronger producer activity and higher throughput volume across much of the portfolio.
Guidance Narrowed. Management narrowed its FY 2026 guidance range for adj. EBITDA to $235 million to $255 million from $225 million to $265 million, and increased capital expenditure guidance to $100 million to $120 million from $85 million to $105 million. The increased capital budget is primarily tied to approximately 30 additional Williston Basin well connections and incremental investment in the Double E pipeline, while accelerating producer activity, additional firm transportation agreements, and a potential Double E compression expansion support the longer-term growth outlook.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Teledyne Technologies (NYSE: TDY) announced Monday it has entered into a definitive agreement to acquire Varex Imaging Corporation (Nasdaq: VREX) in an all-cash transaction valued at approximately $1.1 billion. Under the terms of the deal, Teledyne will pay $18.90 per share, a striking 88% premium over where Varex stock was trading as recently as late May, when shares changed hands near $10 against a market capitalization of just $424 million. Varex shares surged 48.3% in premarket trading the day the deal was announced.
The boards of both companies unanimously approved the transaction, which is expected to close in early 2027, subject to regulatory approvals and Varex shareholder consent.
A Genuinely Small Company Commanding a Big Premium
The scale of this premium is worth sitting with. Varex was trading as a sub-$500 million microcap just weeks before this deal was announced. For a company that size to command an 88% premium and a $1.1 billion transaction value signals that Teledyne identified something strategically essential in Varex’s technology that could not easily be replicated or acquired elsewhere.
Varex has spent decades developing X-ray sources, digital X-ray detectors, high-voltage interconnects, and imaging software for global OEM manufacturers across medical diagnostics, security screening, non-destructive industrial testing, and analytical measurement. The company posted preliminary third quarter revenue of $210.5 million, with adjusted earnings of $0.31 per share, evidence of a business generating real, sustained commercial revenue rather than a speculative pre-revenue target.
The Specific Gap Teledyne Is Filling
What makes this deal particularly interesting is how directly Teledyne’s own leadership described the strategic rationale. Teledyne currently produces X-ray detectors but does not offer detectors suited for high-radiation environments such as oncology, a category Varex has built specifically. That is a rare instance of an acquirer publicly naming the exact product gap being solved, rather than relying on generic language about synergies or portfolio expansion.
Varex is also recognized as the world’s only commercially ready independent supplier of photon-counting CT detectors, a next-generation imaging technology that improves image resolution and reduces radiation dose in computed tomography scanning. As major medical imaging OEMs including GE HealthCare, Siemens Healthineers, and Philips continue advancing toward photon-counting CT platforms, owning the independent supplier of that core detector technology gives Teledyne a genuinely differentiated position in a critical, high-growth segment of medical imaging.
Why the Combination Makes Sense
Teledyne’s existing digital imaging, vacuum electronics, and instrumentation businesses already serve overlapping end markets in aerospace, defense, industrial inspection, and healthcare. Varex’s X-ray sources and detectors slot directly into that existing customer base and distribution infrastructure, giving Teledyne the ability to offer a more complete imaging component solution to OEM customers who previously had to source detector and tube technology from separate specialized suppliers.
Varex’s own leadership has pointed to Teledyne’s resources as a way to accelerate adoption of its advanced imaging solutions and speed development of next-generation products, suggesting the deal is expected to benefit commercialization timelines on both sides rather than simply consolidating market share.
What It Means for Small Cap Investors
For investors tracking small and microcap companies in medical imaging, industrial inspection, and specialized electronics components, this deal is a meaningful data point. A company with a market cap under $500 million just months ago commanded an $1.1 billion acquisition price because it controlled genuinely differentiated, hard-to-replicate technology in a high-growth medical imaging niche. That is a reminder that scale alone does not determine acquisition value. Owning a critical, difficult-to-replicate technology position within a larger company’s supply chain can command a premium disproportionate to a company’s size, particularly when that technology sits at the center of where an entire industry is heading next.
Dream Finders Homes finally got its target. After pursuing Beazer Homes in public for three months, the two builders agreed Wednesday to a deal — and the way it came together says a lot about what beaten-down small-caps are actually worth.
The terms: Dream Finders (NYSE: DFH) will acquire Beazer (NYSE: BZH) in an all-cash transaction worth roughly $2.2 billion in enterprise value, paying $33.50 a share. The combination creates the sixth-largest homebuilder in the country, spanning 26 markets and about 520 active communities across the Southeast, Mid-Atlantic, Texas, the West and the Midwest. Dream Finders expects more than $100 million in annual cost synergies and says the deal will be double-digit-percentage accretive to earnings in year one. It’s targeted to close in the fourth quarter, pending Beazer shareholder and regulatory approval.
This didn’t come out of nowhere. Dream Finders first bid for Beazer back in May, took its case public to pressure Beazer’s board, then raised its offer — from an initial proposal, to $32 a share in late June, to the final $33.50. Beazer resisted, then came to the table. Its CEO framed the outcome plainly: a significant, certain cash return for shareholders in an uncertain market. A persistent acquirer wore down a reluctant target, and both sides decided a bird in hand beat the alternative.
Now the part worth slowing down for. That $33.50 is roughly a 70% premium to where Beazer traded before Dream Finders’ pursuit went public — and it’s still only 0.8 times Beazer’s book value. Both numbers are true at once. Beazer’s stock, like much of the homebuilding sector, had been trading well below the accounting value of its land and finished homes, because high mortgage rates and shaky affordability had the market pricing builders for a downturn. So Dream Finders is buying hard assets for less than book value while handing Beazer’s shareholders a fat premium over where those same assets were being valued. The public market underpriced the balance sheet; a strategic buyer pounced.
That’s the pattern small-cap investors should file away, because it’s the same one running through deal after deal this year. When public markets discount an entire sector below the value of its assets, buyers with a longer horizon step in and roll up the cheap ones. Homebuilding is consolidating — scale drives down costs on purchasing, overhead, and in-house mortgage and title — and the cheapest way to buy scale right now is to buy a rival trading below book. Expect more of it while rates stay high and small builders stay cheap.
None of this is free money. Dream Finders is layering on financing and integration risk, housing demand is genuinely uncertain, and buying below book only pays if those assets hold their value. Beazer’s holders get certainty; Dream Finders’ holders are making a leveraged bet that scale wins.
The headline is “sixth-largest homebuilder.” The quieter lesson is the useful one: in a market that’s written off rate-sensitive sectors, real value is sitting in plain view on small-cap balance sheets — and patient buyers are the ones collecting it.
Nielsen is buying DoubleVerify for $13.60 a share in cash — a 30% premium, the press release says. That premium is real. It’s also about half of what DoubleVerify’s stock fetched the day it went public. Both things are true at once, and the gap between them is the most instructive part of this deal.
Here’s what happened. On Wednesday, Nielsen — itself taken private by a private equity consortium a few years back — agreed to acquire DoubleVerify (NYSE: DV) in an all-cash deal worth roughly $2.15 billion in enterprise value. Shareholders get $13.60 per share, a 30% premium to the stock’s 60-trading-day average through August 5. The deal should close by the first quarter of 2027, after which DoubleVerify delists from the NYSE, becomes a private company under Nielsen, and keeps its name. Providence Equity, which owns about 12%, has agreed to vote in favor.
DoubleVerify isn’t a broken company — and that’s the point. It’s the leading independent platform for ad verification: the plumbing that confirms a digital ad impression was actually seen by a real person, in a brand-safe place, free of fraud. It’s accredited, embedded in the workflows of the world’s biggest advertisers, and it works — 2025 revenue landed around $748 million, up roughly 14%, with real profit and strong free cash flow. A healthy, growing, cash-generative business.
So why is it being bought at $13.60?
Because the market stopped paying up for it. DoubleVerify went public in April 2021 at $27 a share and ran to nearly $47 within months, briefly worth more than $5 billion. Then ad-tech multiples collapsed. Even as the company kept growing revenue and profit year after year, the stock got cut in half, then cut again, bottoming below $8 last year. The business went up and to the right; the multiple went down and to the left. By this week the whole company was worth under $2 billion — less than half its peak value, despite being bigger and more profitable than it was then.
That’s the lesson for anyone hunting the small end of the market. A 30% premium sounds generous until you notice it’s measured off a badly depressed base. IPO buyers are being cashed out at roughly half their money; anyone who chased the 2021 hype is down far more. The premium is genuine against last month’s price — and a permanent loss against the promise the stock once carried.
It also explains the take-private wave we’ve watched all week. When public markets abandon a profitable company and refuse to re-rate it no matter how well it executes, someone with a longer horizon eventually buys the cash flows on the cheap. That’s exactly what Nielsen is doing — and it’s the same logic behind deal after deal in 2026: good small and mid-cap businesses quietly pulled off the public market at prices that reflect the market’s indifference, not the company’s quality.
For DoubleVerify shareholders, it’s a bittersweet exit — a premium today that locks in yesterday’s de-rating. For everyone else, it’s a map. The hunting ground right now is full of profitable, overlooked small-caps trading far below what they’re worth to a patient owner. And the public market keeps losing them, one deal at a time.
Everyone will watch Friday’s jobs report for what it says about the Fed. Small-cap investors should watch it more closely than anyone — because no corner of the market is more exposed to the number, and none needs a more specific outcome.
Here’s the setup. Economists expect the US economy added about 80,000 jobs in July, with unemployment holding steady at 4.2%. That would be a step up from June’s soft 57,000. The supporting data this week has been a mixed bag that mostly leans benign: job openings barely moved, ADP’s private hiring gauge came in light but wages for job-switchers ticked higher, and the outplacement firm Challenger reported fewer planned layoffs and more planned hiring. A Bank of America analysis even suggested payroll growth may have picked up in July, with the gains skewed toward lower-income households — whose after-tax pay is now growing faster than higher earners’ for the first time since late 2024.
So why does this matter more to small caps than to the giants at the top of the index?
Because small companies live and die on the cost of capital. They carry more floating-rate debt, they refinance more often, and they lack the fortress balance sheets and overseas cash piles that insulate the mega-caps. When the Fed’s rate path shifts, it moves small caps first and hardest. And the jobs report is the single biggest input into that path. They’re also overwhelmingly domestic, so the health of the US labor market is the health of their customers.
Now the part that makes Friday genuinely tricky: small caps need a Goldilocks number.
Too hot, and the story turns against them. A blowout print sends Treasury yields higher and pushes rate cuts further out — exactly what played out midweek, with yields climbing and the Russell 2000 slipping while the Dow gave back its record run. Too cold, and a different fear takes over: small caps are the most economically sensitive part of the market, so a number weak enough to whisper “recession” hits them harder than anyone. What they want is the narrow middle — cooling enough to keep the Fed cutting, steady enough to keep the expansion intact.
The timing raises the stakes. This lands just as small-cap earnings growth has finally started outpacing large-caps and the market’s rally is broadening beyond a handful of AI names. A friendly jobs number could be the spark that extends that rotation. An ugly one could smother it before it gets going.
One caution worth keeping in view: don’t overtrade a single data point. Payroll figures have been noisy and heavily revised lately — June disappointed, earlier months were marked down — and the reliability of the data itself has been a live debate. One print is a data point, not a trend.
Still, watch Friday closely. The headlines will fixate on the top-line number and the Fed. The more interesting question sits one rung down the market-cap ladder: whether small caps get the number they need to keep their moment alive.
Tarsus Pharmaceuticals (Nasdaq: TARS) announced Thursday it has entered into a definitive agreement to acquire privately held Alkeus Pharmaceuticals, adding gildeuretinol, an investigational once-daily oral therapy for Stargardt disease, to its growing eye care pipeline. Under the terms of the agreement, Tarsus will pay approximately $450 million upfront, including $270 million in cash, with up to $350 million in additional milestone payments and low-to-mid single digit royalties on future product sales.
Alongside the acquisition, Tarsus secured $125 million in gross proceeds through an oversubscribed private placement equity financing, giving the company additional capital to fund the integration and continued clinical development of its expanding pipeline. The deal is expected to close later in 2026, subject to customary closing conditions.
What Alkeus Brings to Tarsus
Stargardt disease is a rare, inherited retinal disorder that currently has no FDA-approved treatments, making it exactly the kind of high unmet need indication that commands significant strategic value despite years remaining before any potential approval. Gildeuretinol has already been studied in more than 400 individuals, demonstrating a favorable tolerability and efficacy profile, and has received both Breakthrough Therapy and Orphan Drug designations from the FDA, two regulatory signals that typically accelerate development timelines and reflect meaningful confidence in a drug’s underlying science.
The catch, and the reason this deal is genuinely a long-term bet, is timing. Topline data from the pivotal Phase 3 NORTHSTAR trial is not expected until the second half of 2029, meaning Tarsus is paying $450 million upfront for an asset that will not produce a definitive readout for roughly three more years.
A Pattern, Not a One-Off Deal
This is not Tarsus’s first eye care acquisition this year. The Alkeus deal builds directly on the company’s recent acquisition of iRenix Medical, which brought IRX-101, a potential ocular antiseptic, into the fold. Combined with its existing pipeline, which includes TP-04 for ocular rosacea and TP-05 for Lyme disease prevention, both currently in Phase 2, Tarsus is deliberately assembling one of the more comprehensive eye care pipelines in the industry rather than remaining a single-product company.
That strategy is being funded by genuine commercial strength. Tarsus reported second quarter 2026 net product sales of $173.9 million for its lead commercial product XDEMVY, an increase of more than 69% year over year, and raised its full-year 2026 XDEMVY sales guidance to a range of $685 million to $705 million. That accelerating commercial performance gives Tarsus the balance sheet flexibility to fund a multi-year pipeline bet like Alkeus while continuing to invest across its broader portfolio.
What It Means for Investors Tracking Ophthalmology and Rare Disease
For investors tracking small and mid cap companies in ophthalmology and inherited retinal disease, this transaction reinforces just how much strategic value the market continues to assign to differentiated science addressing conditions with no approved treatment options, even when the definitive clinical proof point sits years in the future. The broader inherited retinal disease space remains an area of active development, with companies like Ocugen continuing to advance gene therapy programs targeting similar categories of rare, previously untreatable retinal conditions.
Tarsus is betting that being the eye care company with the deepest pipeline, not just the strongest single product, is what builds durable value over the next decade. The market’s initial reaction, with shares pulling back modestly in premarket trading, suggests investors are still digesting the size of the bet relative to how far away the payoff actually is.