NanoViricides (NNVC) – Ebola Trial Reports Ongoing Enrollment Progress

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Patient Enrollment and Treatment Continue. Nanoviricides provided an update on the progress of its Phase 2a trial in Ebola, including additional details on its design, endpoints, and objectives. The Phase 2a trial began treating patients with NV-387 in the Democratic Republic of Congo (DRC) in late September. The company reported that enrollment is continuing, with data expected in 1Q27. 

Stages Of Infection Are Emerging. The current outbreak of Ebola virus disease (EVD) in the DRC has been caused by a new variant of the Bundibugyo Ebolavirus (BDBV). The development of symptoms varies between patients, and its diagnosis is still being refined. During the first 5 to 7 days after initial infection, mild symptoms may not even be noticeable. Patients typically seek treatment after about 5 to 7 days, when they begin vomiting and have severe diarrhea. The trial is expected to enroll most patients at this stage.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – Ocugen and Roots Pharmaceutical Complete License Agreement for OCU400 Modifier Gene Therapy for Retinitis Pigmentosa in the Middle East and North Africa

October 14, 2026

MALVERN, Pa., Oct. 14, 2026 (GLOBE NEWSWIRE) — Ocugen, Inc. (“Ocugen” or the “Company”) (NASDAQ: OCGN), a pioneering biotechnology leader in gene therapies for blindness diseases, today announced the execution of a licensing agreement with Roots Pharmaceutical, and its strategic partner Al-Dhow International Holding, for the exclusive rights to OCU400, Ocugen’s novel modifier gene therapy for the treatment of Retinitis Pigmentosa (RP), in the Middle East and North Africa (MENA) region.

Subject to the terms of the License Agreement, Ocugen will receive an upfront license fee and potential initial development milestone payments of up to $4 million, in the aggregate, as well as potential sales milestone payments of up to $255 million, and royalties equaling 22% of OCU400 net sales generated by Roots Pharmaceutical. Ocugen will manufacture the commercial supply of OCU400 under terms of a related supply agreement.

Ocugen believes RP is a leading cause of inherited vision loss globally, with a particularly significant unmet need across the MENA region, where the prevalence of RP is estimated to be 10 to 20 times higher than in the U.S. and EU. Through OCU400, Roots Pharmaceutical aims to help address this substantial unmet need by potentially providing a treatment option for people in the MENA region living with RP and facing progressive vision loss and potential blindness.

“By partnering with Roots Pharmaceutical, an established leader with strong reach across the Middle East and North Africa, we are expanding our ability to bring our potential one-time gene therapy to patients in a region where retinitis pigmentosa is highly prevalent and the unmet medical need is significant,” said Dr. Shankar Musunuri, Chairman, Chief Executive Officer and Co-founder of Ocugen. “This agreement represents another important step in our strategy to build strong regional partnerships and expand global access to our potentially transformational gene therapies.”

Roots Pharmaceutical is an established and rapidly growing pharmaceutical company serving key markets across the MENA region. With more than two decades of operating experience and expertise in commercializing innovative medicines, the company’s regional capabilities and established healthcare relationships position it as a strong partner for bringing OCU400 to RP patients across MENA.

“This partnership reflects Roots’ commitment to bringing breakthrough gene therapies to the Middle East and North Africa, leading and shaping the treatment paradigm for our patients, which is our main objective,” said Dr. Islam Zayed, Chief Executive Officer and Co-Founder of Roots Pharmaceutical. “OCU400 has the potential to change the outlook, and the lives, of patients living with retinitis pigmentosa. We look forward to working closely with Ocugen to build the diagnosis-to-treatment pathway that gene therapy requires across our markets, and to exploring further collaboration across Ocugen’s ophthalmology pipeline.”

Ocugen continues to advance OCU400 through its Phase 3 liMeliGhT clinical trial with a topline data readout expected in the first quarter of 2027, followed by global regulatory submissions, including a Biologics License Application in the U.S. and a Marketing Authorization Application in Europe.

About Ocugen, Inc.
Ocugen, Inc. is a pioneering biotechnology company developing gene therapies for blindness diseases. The Company’s breakthrough modifier gene therapy platform has the potential to address significant unmet medical needs across large patient populations through a gene-agnostic approach. Unlike traditional gene therapies and gene-editing technologies that target a single gene mutation, Ocugen’s modifier gene therapies are designed to address the underlying disease biology by restoring balance across multiple gene networks. The Company is currently advancing programs for inherited retinal diseases and other causes of blindness that affect millions worldwide, including retinitis pigmentosa, Stargardt disease, and geographic atrophy, an advanced form of dry age-related macular degeneration. Discover more at www.ocugen.com and follow the Company on LinkedIn and X.

About Roots Pharmaceutical Company
Founded in Kuwait in 2006, Roots Pharmaceutical is a fully integrated healthcare provider specializing in commercializing innovative therapies, medical devices, and an aesthetic line across the Middle East and North Africa. It is led by a team with over 25 years of pharmaceutical industry experience.

Roots Pharmaceuticals has established a direct commercial presence in the MENA region (Middle East and North Africa), mainly in GCC countries and key North African countries, with a therapeutic portfolio spanning neurology, hematology, oncology, rare diseases, dermatology, cardiovascular, medical devices and aesthetic line.

With 30+ global partners and a $300M+ product pipeline, Roots Pharmaceutical and its strategic partner Al-Dhow Group are committed to delivering meaningful healthcare impact across the MENA region through innovation, access and excellence. Its operations are ISO 9001:2015-certified and externally audited by PwC.

Cautionary Note on Forward-Looking Statements
This press release contains forward-looking statements within the meaning of The Private Securities Litigation Reform Act of 1995, including, but not limited to, statements regarding the anticipated benefits to Ocugen of the definitive license agreement and supply agreement with Roots Pharmaceutical Company, as well as statements regarding strategy, the potential amounts of milestone payments and royalty payments that may be received under the license agreement, business plans and objectives for Ocugen’s clinical programs, plans and timelines for the preclinical and clinical development of Ocugen’s product candidates, including the therapeutic potential, clinical benefits and safety thereof, expectations regarding timing, success and data announcements of current ongoing preclinical and clinical trials, including the timing of data readouts and marketing applications, the ability to initiate new clinical programs, statements regarding qualitative assessments of available data, potential benefits, expectations for ongoing clinical trials, anticipated regulatory filings and anticipated development timelines, statements regarding potential market size and commercial possibilities of Ocugen’s product candidates, which are subject to risks and uncertainties. Ocugen may, in some cases, use terms such as “predicts,” “believes,” “potential,” “proposed,” “continue,” “estimates,” “anticipates,” “expects,” “plans,” “intends,” “may,” “could,” “might,” “will,” “should,” or other words that convey uncertainty of future events or outcomes to identify these forward-looking statements. Such statements are subject to numerous important factors, risks, and uncertainties that may cause actual events or results to differ materially from Ocugen’s current expectations, including, but not limited to, the risks that the license agreement and supply agreement with Roots Pharmaceutical Company will not lead to the current anticipated benefits to Ocugen; that preliminary, interim and top-line clinical trial results may not be indicative of, and may differ from, final clinical data; that unfavorable new clinical trial data may emerge in ongoing clinical trials or through further analyses of existing clinical trial data; that earlier non-clinical and clinical data and testing may not be predictive of the results or success of later clinical trials; and that clinical trial data are subject to differing interpretations and assessments, including by regulatory authorities. These and other risks and uncertainties are more fully described in Ocugen’s filings with the Securities and Exchange Commission (SEC), including the risk factors described in the section entitled “Risk Factors” in the quarterly and annual reports that Ocugen files with the SEC. Any forward-looking statements that Ocugen makes in this press release speak only as of the date of this press release. Except as required by law, Ocugen assumes no obligation to update forward-looking statements contained in this press release whether as a result of new information, future events, or otherwise, after the date of this press release.

Contacts:

Investors:
Candice Masse, astr partners
[email protected]

Media:
Chris Clark, Ocugen
[email protected]
Big Pharma’s Patent Cliff Could Spark a New Wave of Small-Cap Biotech Acquisitions

As major pharmaceutical companies face billions in potential revenue losses from expiring patents, smaller biotechnology firms could become increasingly attractive acquisition targets.

The biotechnology sector could be approaching another wave of merger and acquisition activity as major pharmaceutical companies confront a growing challenge: the expiration of patent protection on blockbuster medications. With an estimated $300 billion to $400 billion in pharmaceutical revenue facing patent-related pressure beginning in 2028, large drugmakers are increasingly focused on replenishing their development pipelines, potentially creating opportunities for smaller biotechnology companies.

The industry’s so-called “patent cliff” occurs when branded medications lose market exclusivity, allowing generic or biosimilar competitors to enter the market. These alternatives can rapidly erode sales, forcing pharmaceutical manufacturers to identify new sources of revenue.

For small-cap biotechnology investors, this dynamic could become an important catalyst for dealmaking.

Pharmaceutical companies have several options for replacing revenue from aging products, including internal research, licensing agreements, strategic partnerships, and acquisitions. Purchasing smaller biotechnology companies with promising clinical assets can provide access to new treatments without starting development programs from scratch.

Merger and acquisition activity across the pharmaceutical and life sciences sectors continues to reflect growing demand for innovative treatments and promising drug development pipelines. Oncology, immunology, rare diseases, and other specialized therapeutic areas remain key areas of strategic interest as major pharmaceutical companies seek new opportunities for long-term growth.

Among emerging biotechnology companies advancing treatments in these fields is Cardiff Oncology (NASDAQ: CRDF), which is developing onvansertib, a PLK1 inhibitor being studied in combination with standard therapies for metastatic colorectal cancer. The company reported encouraging Phase 2 results and has outlined plans for a registrational trial, subject to additional financing.

Such programs illustrate the type of clinical innovation occurring across the smaller biotechnology sector.

Biotechnology companies frequently operate without commercial revenue, relying on capital markets to finance expensive clinical trials and regulatory development.

This funding environment can make partnerships particularly valuable.

Ocugen (NASDAQ: OCGN), which is developing gene therapies targeting inherited retinal diseases, has pursued regional licensing opportunities as part of its broader development strategy. Such arrangements demonstrate how smaller biotechnology companies can access additional resources while retaining certain commercial rights.

Meanwhile, Eledon Pharmaceuticals (NASDAQ: ELDN) is developing therapies involving immune modulation, including tegoprubart, an investigational treatment being studied in kidney transplantation.

These companies represent different approaches to addressing significant medical needs, highlighting the range of assets that larger pharmaceutical companies may evaluate when expanding their portfolios.

Their inclusion does not imply that acquisition discussions are underway.

Although pharmaceutical patent expirations create incentives for acquisitions, clinical progress remains central to company valuations.

Investors should monitor trial results, regulatory milestones, cash reserves, intellectual property protection, and licensing announcements. Companies approaching pivotal clinical milestones may attract greater strategic attention, but they also face substantial development risks.

Another consideration is whether pharmaceutical buyers favor outright acquisitions or licensing agreements that provide access to promising treatments without assuming full development costs.

Following a slowdown in biotechnology dealmaking over the summer, industry observers anticipate renewed acquisition interest as companies prepare for upcoming patent expirations.

For investors following the small-cap biotechnology sector, the implications extend beyond potential takeover premiums. Increased dealmaking could improve sentiment, provide additional financing opportunities, and establish valuation benchmarks for emerging therapeutic platforms.

As the pharmaceutical industry prepares for significant revenue losses from patent expirations, innovative smaller biotechnology companies could play an increasingly important role in shaping the next generation of treatments.

Viatris to Acquire Pacira BioSciences for $1.65 Billion, Expanding Into Non-Opioid Pain Therapies

Viatris (Nasdaq: VTRS) announced Thursday it has agreed to acquire Pacira BioSciences (Nasdaq: PCRX) for $36.50 per share in cash, an aggregate equity value of $1.65 billion. The deal gives Viatris two marketed, patent-protected non-opioid pain medicines and positions the company as a leader in a category where patients and physicians continue to look for alternatives to opioids.

Pacira’s portfolio rests on EXPAREL, a long-acting local anesthetic used to manage pain after surgery, and ZILRETTA, an extended-release injection for osteoarthritis knee pain. Company materials cite up to a 78% decrease in opioid consumption with EXPAREL, though the release notes the clinical benefit of that reduction was not demonstrated. Over the twelve months ended June 30, 2026, Pacira generated about $746 million in revenue and $177 million in adjusted EBITDA. On equity value alone, the price works out to roughly 2.2 times revenue and 9.3 times adjusted EBITDA. GAAP net income over the same period was a much smaller $14.6 million, reflecting significant amortization of acquired intangibles and stock-based compensation.

Viatris says the acquisition advances its push to build an innovative medicines business, and that the products complement its fast-acting meloxicam opportunity in pain. The company also gains Pacira’s U.S. commercial, market access, medical affairs, and research capabilities, along with a pipeline led by a Phase 2 gene therapy candidate for knee osteoarthritis. Viatris plans to apply its expertise in intellectual property and product lifecycle management to extend the portfolio’s reach, including across select international markets where it already operates.

Viatris expects to fund the deal primarily from excess cash, with the remainder from short-term borrowings, and says the impact on its gross leverage ratio will be minimal. The transaction is expected to be immediately accretive to its financial guidance metrics. It will be structured as a tender offer followed by a second-step merger at the same price, with both boards having unanimously approved and Pacira’s board recommending that shareholders tender. Closing requires that a majority of Pacira’s outstanding shares be tendered and that the regulatory waiting period expire, and is expected by the end of 2026. Once complete, Pacira will be delisted from Nasdaq. Viatris will discuss the transaction when it reports third-quarter results on November 5.

Pacira’s leadership said the company has helped nearly 20 million patients access non-opioid pain management and that Viatris’ scale and resources will help bring its therapies to more patients.

The thesis behind the deal is worth examining. Viatris highlighted its record of sustaining sales after competition arrives, a reminder that protected products do not stay protected forever and that part of what Viatris is paying for is its ability to manage that transition.

For small and microcap investors, the takeaway is that commercial-stage healthcare companies with profitable, differentiated products are drawing strategic interest at disciplined valuations. Roughly nine times adjusted EBITDA on equity value is a useful benchmark for smaller specialty pharma and medical technology companies with established revenue, and it reinforces a theme running through this year’s healthcare deal activity, including Supernus’s merger with Indivior and MiMedx’s acquisition of Sanara MedTech. Companies still in development are a different proposition, since their deal values depend far more on clinical milestones than on current earnings.

Take a moment to take a look at more emerging growth biotech companies by looking at Noble’s Research Analyst Robert LeBoyer’s coverage list.

MAIA Biotechnology (MAIA) – Patient Enrollment Completed In THIO-101, Enrollment Milestone Reached In THIO-104


Thursday, October 08, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

MAIA Reported Two Important Clinical Trial Milestones. MAIA announced the completion of enrollment for the Part C Expansion Stage of the THIO-101 trial. This part of THIO-101 has enrolled 150 patients. Separately, the Phase 3 THIO-104 trial reached enrollment of 65 patients, putting it on schedule to enroll 100 patients by YE2026. Reaching the full-year enrollment goal could allow an interim analysis in FY2027.

Results From THIO-101 Part C Have Been Positive To Date. As discussed in our Research Note on September 22, MAIA recently announced initial efficacy data from the THIO-101 Part C. The evaluable population, consisting of patients with at least one post-treatment evaluation by tumor scan, showed a disease control rate (DCR) of 90.5%. This far exceeds published studies that show a 25%–35% DCR for standard third-line chemotherapy regimens.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Gate Bioscience Expands Its Lilly Deal to More Than $870 Million, Adding a New Drug Target

Gate Bioscience, a privately held drug discovery company, announced Monday that it has expanded its research and licensing agreement with Eli Lilly (NYSE: LLY) in a deal now potentially worth more than $870 million. The original agreement, announced in July 2025, was worth up to $856 million. The expansion adds one drug target, with an option to add a second.

Gate will receive an upfront payment and research funding for the added target, plus an additional payment if the second target is selected. Neither company disclosed the size of the upfront payment. Gate is also eligible for milestone payments and royalties on global sales of any products that result.

The science behind the partnership takes a different approach to disease. Gate uses its platform to discover oral small-molecule drugs designed to eliminate proteins that have been difficult to target with existing medicines. Many conventional drugs work by blocking a protein’s activity, but some disease-driving proteins offer no good place for a drug to bind. A drug built to remove the protein altogether can reach targets once considered out of reach.

The two companies have split the work along familiar lines. Gate leads discovery, while Lilly takes over late-stage preclinical and clinical development, manufacturing, and commercialization. Lilly holds exclusive worldwide rights to products developed against the selected targets.

The deal fits a pattern in Lilly’s strategy this year. The company has acquired Merida Biosciences, which is developing biologics that eliminate disease-causing autoantibodies, and AtaiBeckley, a clinical-stage mental health company, while also signing earlier-stage platform partnerships like this one. Buying finished assets and renting promising discovery engines are two ways of filling the same pipeline.

The headline number deserves context. The expansion lifts the potential value by only about $14 million over the original agreement, which shows how these figures work. Partnership values are usually quoted at their maximum, with most of the money tied to development and sales milestones that may never be paid. The undisclosed upfront payment is the figure that actually reaches the company’s balance sheet.

The same partnership playbook is open to smaller companies pursuing oral small-molecule medicines. Cocrystal Pharma, which uses a structure-based discovery platform to develop antiviral drugs, and Cardiff Oncology, whose lead candidate onvansertib is an oral small molecule being studied in colorectal cancer, work in different therapeutic areas than Gate, and neither focuses on protein elimination. But both illustrate the model investors are watching: a differentiated discovery approach or oral drug candidate that could eventually attract a larger development partner.

For investors tracking small and microcap biotech, the takeaway cuts both ways. Large pharma remains willing to sign collaborations worth hundreds of millions of dollars with private platform companies before any drug reaches the clinic, a sign of continued appetite for differentiated discovery technology. But a platform deal is not an approved product. The upfront cash, the pace of milestone payments, and whether the partner keeps selecting targets matter most, and investors weighing smaller developers with similar partnership ambitions should read the fine print on all three.

Unicycive Therapeutics (UNCY) – Unicycive Announces NDA Resubmission For OLC, Ahead Of Our Expected Timeframe


Wednesday, September 30, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

NDA For OLC Has Been Resubmitted. Unicycive has resubmitted its NDA (New Drug Application) for OLC (oxylanthanum  carbonate) to control phosphate levels in patients with chronic kidney disease (CKD) on dialysis. Typically, the FDA accepts the submission for filing within 30 days and provides a PDUFA date, the statutory date for the agency to respond. This date is expected to be six months later, for a PDUFA date around March 30, 2026.

An Alternate Manufacturing Vendor Has Been Added.  The resubmission included CMC (Chemistry, Manufacturing, and Controls) product data from a new third-party manufacturing vendor similar to the original vendor, including OLC manufacturing and 12-month stability studies. The NDA also includes data from bridging studies showing the vendors’ products are equivalent, as recommended by the FDA.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

MAIA Biotechnology (MAIA) – Heading Into 4Q After Strong Clinical Progress


Tuesday, September 22, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Phase 2 Extension Stage Has Begun Treatment At US Sites. MAIA began treating patients at three US sites in the Part C Expansion Phase of its Phase 2 THIO-101 trial. The trial tests ateganosine (aka THIO) in non-small cell lung cancer (NSCLC) and had completed the planned patient enrollment at international sites worldwide. Two additional US sites are expected to open during 2026.

Initial Data Shows Consistent Efficacy. In June 2026, MAIA announced initial efficacy data from the ongoing Phase 2 THIO-101 Part C Expansion Stage. Patients with at least one post-treatment evaluation by tumor scan showed a disease control rate (DCR) of 90.5% in the evaluable population. We believe that data consistent with Parts A and B could allow the company to apply for Accelerated Approval and Priority Review.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Moderna Doubled Today on a Cancer Vaccine Breakthrough

Moderna (Nasdaq: MRNA) shares more than doubled Wednesday after the company and Merck (NYSE: MRK) announced their personalized mRNA cancer vaccine met its primary and key secondary endpoints in a pivotal Phase 3 trial, the first positive late-stage result ever recorded for an individualized neoantigen cancer therapy and for any mRNA-based cancer treatment. The rally lifted biotech stocks broadly, with investors treating the result as validation for an entirely new category of oncology treatment that has been in development for more than a decade.

The trial, called INTerpath-001, enrolled 1,137 patients with completely resected stage IIB-IV melanoma, the deadliest form of skin cancer. Patients received either the vaccine, known as intismeran autogene, alongside Merck’s Keytruda, or Keytruda alone. The combination produced statistically significant and clinically meaningful improvements in recurrence-free survival, the trial’s primary endpoint, along with a secondary measure of how long patients went without their cancer spreading to distant parts of the body. No new safety signals emerged.

How the Vaccine Actually Works

What makes intismeran genuinely novel is that it is not a single, mass-produced product. Each dose is manufactured individually based on the specific mutational fingerprint of a patient’s own tumor, sequenced from surgically removed tissue, and designed to train the immune system to recognize as many as 34 distinct targets unique to that patient’s cancer. Neoantigen vaccines built on this personalized model have been discussed as a theoretical possibility in oncology for years. This is the first randomized Phase 3 trial to actually prove the concept works in a large patient population, which is precisely why the result is being described across the biotech industry as a landmark moment rather than an incremental clinical update. Notably, the trial was stopped at its first interim analysis, meaning the question of whether the vaccine ultimately extends overall survival, not just delays recurrence, remains open and could take years to fully answer. The companies have indicated they intend to pursue regulatory filings quickly, describing a timeline measured in months rather than years.

What It Means for Smaller Biotech Companies

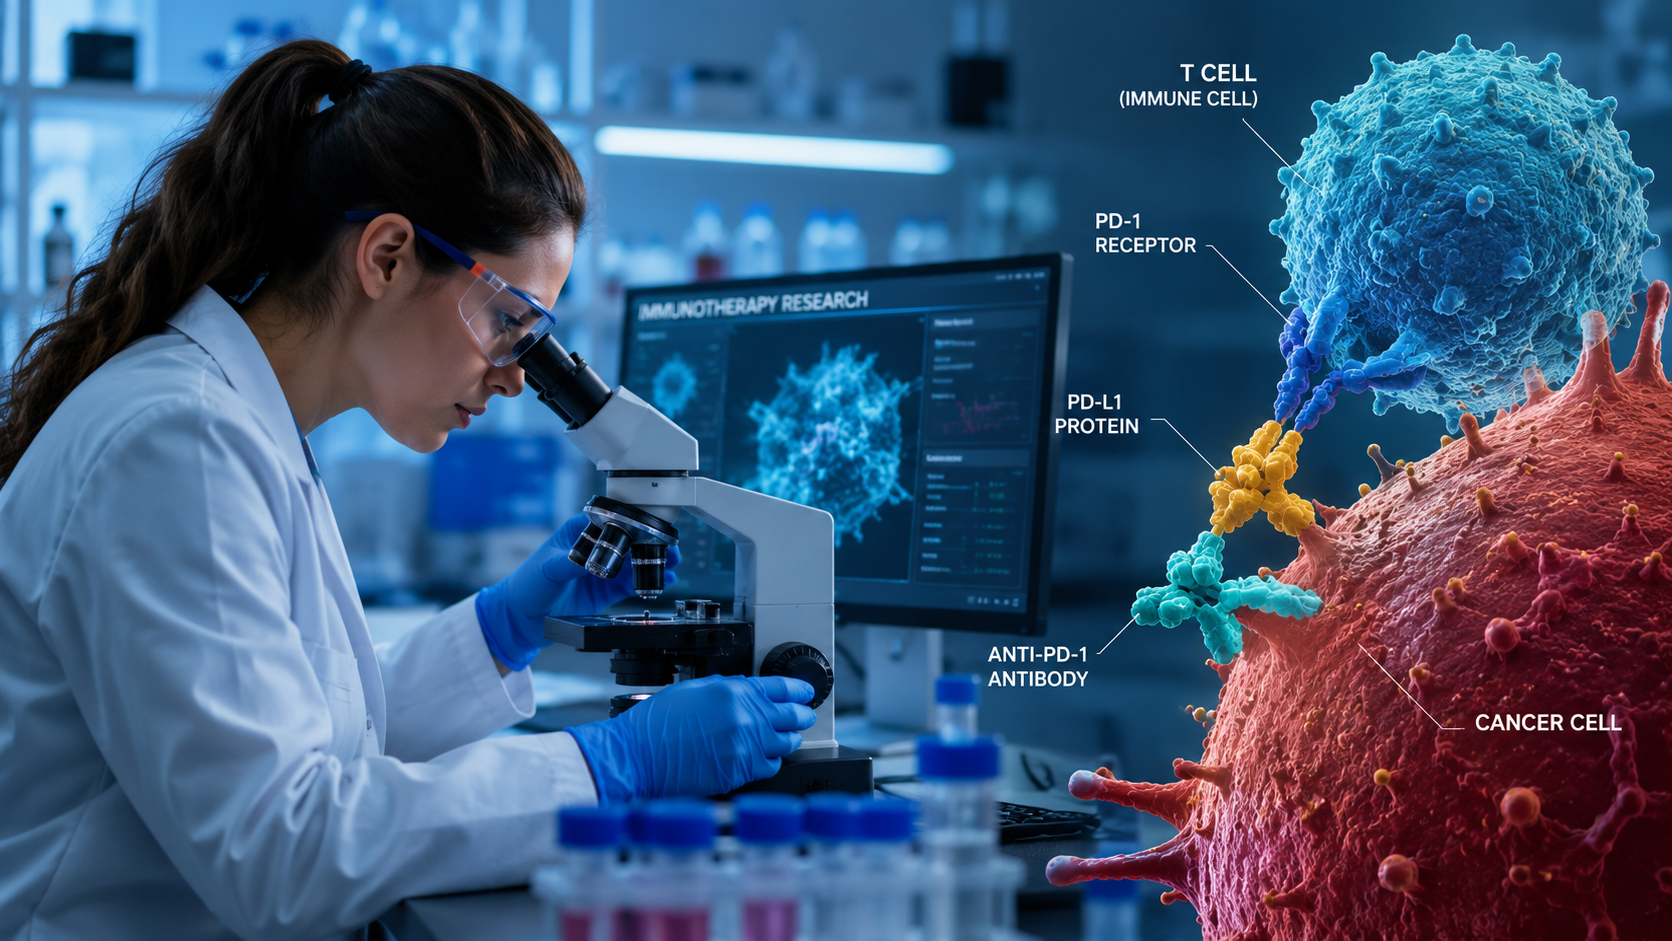
For investors tracking small and microcap biotech, a validation event of this scale rarely stays contained to the two companies involved. Proof that personalized, sequencing-based cancer vaccines can succeed in a randomized Phase 3 trial provides real clinical and regulatory validation for an entire mechanism, and that validation tends to lift sentiment and capital allocation across every smaller company pursuing related or adjacent immuno-oncology approaches, not just the two large caps that generated today’s headline. Smaller oncology-focused biotechs, including companies like MAIA Biotechnology, both advancing their own differentiated approaches to hard-to-treat cancers, operate in exactly the kind of therapeutic environment where a breakthrough of this magnitude tends to draw renewed institutional attention to the broader category, even when their own mechanisms differ meaningfully from Moderna and Merck’s personalized vaccine platform.

This pattern is consistent with what we detailed in our recent look at the current biotech catalyst environment, where clinical breakthroughs at any point in the sector, whether at a large pharma partnership or a clinical-stage microcap, tend to reprice risk and opportunity across the entire space rather than staying isolated to a single company’s stock.

Cadrenal Therapeutics (CVKD) – 2Q26 Reported With Review Of New “Three Pillars” Strategy


Monday, August 17, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

2Q26 Reported With Review Of New Strategy and Product Data. Cadrenal reported a 2Q26 loss of $3.3 million, or $(1.14) per share. The company modified its strategy and plans to develop its products through collaborations, out-licensing agreements, and non-dilutive grants to conserve capital resources. On June 30, 2026, cash and cash equivalents were $4.2 million, excluding proceeds from the private placement completed July 1. The private placement raised about $3.0 million, with warrants that could raise another $5.8 million upon exercise.

The Pipeline Has Been Reorganized Into “Three Pillars”.  The company has divided the pipeline into products for Cardiac Acute Critical Care, Orphan Diseases, and Post-Operative Care. These divisions emphasize how the products can address important needs before and after cardiac surgery, as well as for patient populations with few options.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Unicycive Therapeutics (UNCY) – 2Q26 Reported As OLC Moving Forward With FDA Manufacturing Inspection


Thursday, August 13, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

OLC Is Moving Forward. Unicycive reported a 2Q26 loss of $1.7 million, or $(0.06) per share. The Operating Loss of $10.1 million was offset by $8.0 million in Change In Fair Value Of Warrant Liabilities, leading to a Net Loss To Common Shareholders of $1.7 million. Importantly, the FDA has given written notice of facility inspection to one of the OLC third-party manufacturers. Assuming the inspection results are positive, Unicycive will be able to resubmit its NDA for OLC. Cash and equivalents on June 30, 2026, were $61.4 million.

The Third-Party Inspection Could Complete The Missing Part Of The NDA. In June 2026, Unicycive received a CRL (Complete Response Letter) to its NDA for OLC. The stated reason was that the required FDA inspection of one of its third-party manufacturing vendors had not been performed. The notification of an inspection is good news that could allow the NDA to be resubmitted.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Ocugen (OCGN) – Q2 2026 Reported With Three Late-Stage Trials Advancing With A Stronger Balance Sheet


Friday, August 07, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Ocugen Raised Cash and Prepared To Begin Phase 3. Ocugen reported a 2Q26 loss of $24.9 million, or $(0.07) per share. The Operating Loss of $16.4 million was in line with our estimate, while a Loss on Extinguishment of Debt contributed $2.4 million to the Net Loss. Importantly, the company is planning to start the Phase 3 trial for OCU410 in GA-dAMD during 3Q, consistent with our expectations. In May 2026, the company issued Convertible Notes that raised approximately $112.5 million, ending the quarter with $100.4 million in cash.

Convertible Notes Balance Cash Needs With Dilution. In May 2026, the company issued $130.0 million in 6.75% Convertible Notes, adding net cash of approximately $112.5 million. About $32.7 million of the proceeds were used to repay a  12.25% interest loan. The remaining proceeds brought cash on hand to $100.4 million. This should provide sufficient cash to fund its three products through clinical trials, regulatory approval, and product launches through FY2028.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Ocugen (OCGN) – OCU410 Granted RMAT Designation in Geographic Atrophy


Thursday, July 30, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

RMAT Designation Brings Regulatory Advantages For OCU410. Ocugen announced that the FDA has granted Regenerative Medicine Advanced Therapy (RMAT) designation to OCU410 for Geographic Atrophy secondary to Age-Related Macular Degeneration (GA-AMD). The RMAT designation was granted after FDA evaluation of Phase 2 data and provides significant benefits, including Fast Track and Breakthrough Therapy designations.

RMAT Designation Carries Benefits During Clinical Development. The RMAT designation is granted to drugs that address a serious condition with significant unmet need. There are several benefits, including more frequent FDA communications and guidance during clinical trials and the BLA process. This increased FDA contact could allow Ocugen to address development questions earlier, reducing regulatory uncertainty and streamlining the review.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.