A Microcap Just Raised $200 Million to Chase a Single Drug Across Three Diseases at Once

Processa Pharmaceuticals (Nasdaq: PCSA) announced Tuesday it has acquired clinical-stage biotechnology company Vidya Therapeutics in a stock-for-stock transaction, adding Vidya’s lead asset VT-7208 to Processa’s pipeline. Alongside the acquisition, the company secured an oversubscribed private placement expected to raise approximately $200 million in gross proceeds from a syndicate of healthcare-focused institutional investors, including Bain Capital Life Sciences, Janus Henderson Investors, and RA Capital Management.

The financing transforms the balance sheet of a company that just months ago was a small, thinly capitalized biotech. Management expects the proceeds to fund operations into the second half of 2029, well past the point where multiple clinical readouts are expected to determine whether this bet pays off.

What VT-7208 Actually Is

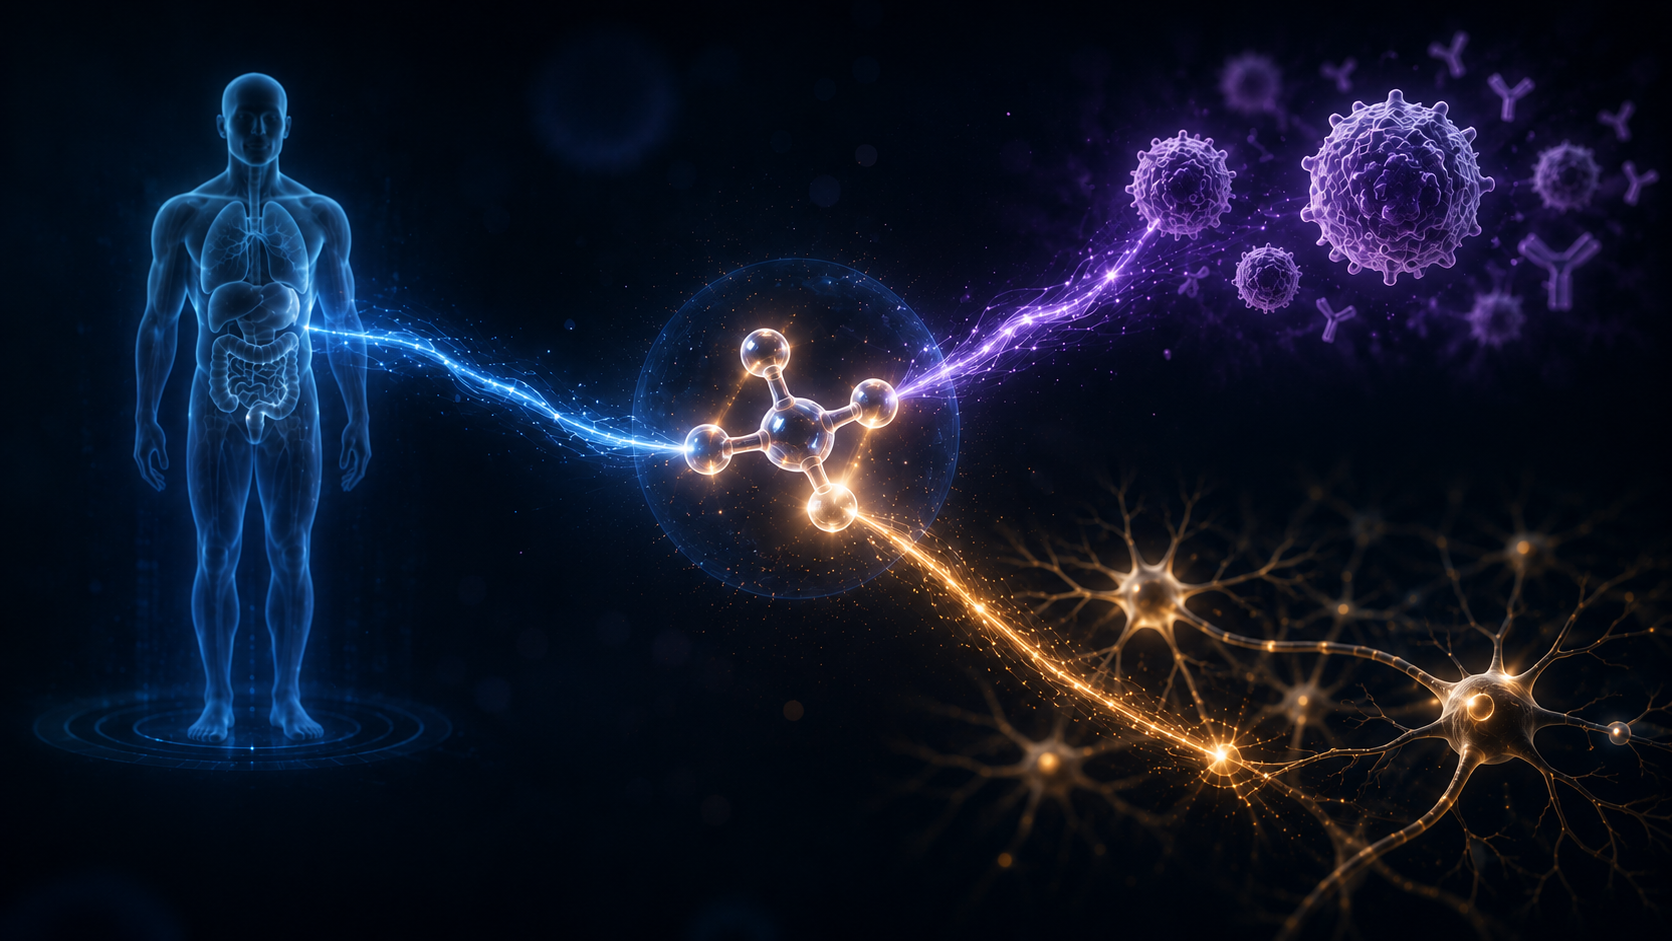
VT-7208 is a next-generation, CNS-penetrant, once-daily oral Bruton’s tyrosine kinase inhibitor, designed specifically to overcome the efficacy and safety limitations that have held back earlier BTK inhibitor programs. BTK is a validated node in B-cell activation, mast cell signaling, and innate immune function, which is why a single well-designed BTK inhibitor can plausibly be tested across autoimmune, allergic, and neuroinflammatory conditions rather than being confined to one narrow indication.

In a Phase 1 clinical trial, VT-7208 demonstrated robust and sustained target engagement at low milligram doses, validating the signaling pathway mechanism and supporting predictable, dose-dependent activity. The compound’s selectivity profile was also designed to minimize off-target kinase activity, which Vidya believes may reduce hepatotoxicity risk compared to earlier BTK inhibitors, a meaningful differentiator in a drug class where liver safety concerns have previously limited development.

The Strategy: Parallel Development Instead of Sequential

Rather than advancing VT-7208 in a single disease and waiting years for that program to read out before moving to the next, Processa plans to run parallel Phase 2 proof-of-concept studies simultaneously across food allergy, chronic spontaneous urticaria, and relapsing multiple sclerosis. Studies in food allergy and CSU are expected to begin in the second half of 2026, with the RMS program following in the first half of 2027. Multiple clinical milestones are anticipated over the next 12 to 24 months.

That parallel approach is precisely what the $200 million financing enables. Running three Phase 2 programs concurrently requires substantially more capital upfront than a single-indication strategy, but it compresses the overall timeline to determine whether the drug works across its full potential addressable market.

A Dramatic Recapitalization

The deal terms reveal just how significant this transaction is relative to Processa’s prior scale. Under the agreement, existing Processa shareholders are expected to own approximately 0.9% of the combined company on a fully diluted basis, while Vidya equity holders receive approximately 46% and private placement investors receive the remainder through Series A non-voting convertible preferred stock. That level of dilution reflects a company essentially being rebuilt around a single new asset, with the institutional investor syndicate effectively taking control of the capital structure in exchange for funding the buildout.

Vidya founder and Executive Chair Dr. Sheila Gujrathi will join Processa’s board following the transaction.

What It Means for Small Cap Biotech Investors

This deal is a clear example of a pattern playing out across small cap biotech in 2026: companies with promising early clinical data but insufficient capital merging into public shells or smaller Nasdaq-listed companies, then immediately recapitalizing through large institutional private placements to fund a fully resourced development plan. For investors, the scale of dilution here is real and needs to be understood clearly, but the resulting company enters a multi-year, well-funded window with three distinct shots at clinical validation from a single molecule.

GeoVax Labs (GOVX) – GeoVax Reports 2Q26 With Clinical Study Plans Moving Forward


Wednesday, July 29, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

GeoVax Reported 2Q26 With Updates For GEO-MVA and Oncology Programs. GeoVax reported a 2Q26 net loss of $4.4 million or $(0.97) per share, lower than our expected loss of $5.8 million. R&D expenses were lower than we projected due to strategic changes, with priority given to preparations for the upcoming Phase 3 trial of GEO-MVA in MPox and the Phase 2 trial of Gedeptin in oncology. Cash on June 30, 2026 was approximately $3.1 million.

Strategic Changes Lowered The 2Q26 Loss. As discussed in our Research Note on May 27, GeoVax will focus on GEO-MVA in infectious diseases and Gedeptin in oncology. These programs have established regulatory pathways, patient needs, and market potential.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

argenx Pays an 86% Premium for Forte Biosciences. What Made a Clinical-Stage Biotech Worth $2.2 Billion

argenx (Euronext & Nasdaq: ARGX) announced Monday it has entered into a definitive agreement to acquire Forte Biosciences (Nasdaq: FBRX) for $77 per share in cash, a total equity value of approximately $2.2 billion. The price represents an 86% premium to Forte’s volume-weighted average trading price since July 9, when the company reported positive Phase 1b data in vitiligo. That is an unusually large premium even by the standards of this year’s active biotech M&A market, and it reflects just how quickly clinical data can transform a small cap company’s valuation.

The transaction is structured as a cash tender offer funded entirely from argenx’s existing cash on hand, with no financing condition attached. Closing is expected in the third quarter of 2026, subject to a majority of Forte shares being tendered and clearance under the Hart-Scott-Rodino Antitrust Improvements Act.

From Strategic Investor to Full Acquirer

This deal did not appear out of nowhere. argenx had already made a strategic investment in Forte Biosciences prior to this announcement, giving it an early window into the company’s clinical progress before committing to a full buyout. That structure, investing first and acquiring later once the data supports it, reflects a disciplined approach that reduces risk for the acquirer while still preserving the option to move quickly once a program proves itself out.

The proof came fast. Forte’s lead asset, FB102, is a first-in-class anti-CD122 antibody that recently delivered statistically significant Phase 1b results in vitiligo, following earlier positive Phase 1b data in celiac disease reported last year, with Phase 2 celiac data expected in the second half of 2026. Those clinical readouts were the direct trigger for argenx’s decision to convert its strategic stake into a full acquisition.

Why CD122 Biology Matters

FB102’s mechanism targets pathogenic T-cell and NK-cell activity through CD122 biology, a distinct approach from the antibody mechanisms already in argenx’s portfolio, which includes efgartigimod, empasiprubart, adimanebart, and ARGX-121. Rather than duplicating existing capability, the acquisition broadens argenx’s ability to address autoimmune disease through an entirely different dimension of immune system dysfunction.

The commercial upside extends well beyond vitiligo and celiac disease. Management described FB102 as having pipeline-in-a-product potential, meaning the same molecule could eventually address multiple autoimmune conditions including alopecia areata, each representing a separate commercial opportunity from a single clinical asset. That kind of multi-indication potential is precisely what allows a clinical-stage company with no approved products to command a multibillion-dollar acquisition price.

What It Signals for Small Cap Biotech Investors

For investors tracking clinical-stage companies in the small and microcap immunology and autoimmune disease space, the Forte transaction reinforces a pattern that has defined biotech M&A throughout 2026. Large, well-capitalized immunology and oncology platforms are increasingly using strategic minority investments as a low-risk way to monitor promising early-stage science, then moving decisively to full acquisitions once clinical data de-risks the program. Statistically significant Phase 1b results, even well ahead of any approval pathway, are proving sufficient to justify premiums approaching 90% over recent trading prices.

That dynamic matters for the broader small cap biotech landscape. Companies advancing differentiated mechanisms in autoimmune disease, a therapeutic area with persistent unmet need and limited recent innovation, are demonstrating that credible early clinical validation can translate into outsized valuation outcomes well before a drug ever reaches the market. The Forte deal is the latest evidence that the current biotech M&A cycle rewards genuine scientific differentiation over scale.

Repligen Pays $1.5 Billion for BioLife Solutions to Lock In Recurring Revenue in the Cell Therapy Boom

The life sciences tools sector produced another significant consolidation this week. Repligen Corporation (Nasdaq: RGEN), a bioprocessing technology company, announced Wednesday it has entered into a definitive agreement to acquire BioLife Solutions (Nasdaq: BLFS), a leading supplier of cell processing tools for the cell and gene therapy market, in a deal valued at approximately $1.5 billion in total enterprise value. The boards of both companies unanimously approved the transaction.

Under the terms of the agreement, BioLife stockholders will receive $11.25 per share in cash and 0.1442 shares of Repligen common stock, together valued at $31.00 per share. The consideration mix is roughly 64% stock and 36% cash, representing a 24% premium to BioLife’s 90-day volume-weighted average price. The deal is expected to close in the fourth quarter of 2026, pending regulatory approvals and BioLife shareholder approval.

What Makes BioLife Valuable

BioLife’s core franchise is biopreservation media, the specialized solutions used to protect the health and function of biologic materials during collection, processing, storage, and distribution. Its lead product line, CryoStor, currently supports 18 commercially approved cell and gene therapies and is used in the majority of U.S. commercially sponsored cell-based therapy clinical trials. That kind of deep embedding in active clinical and commercial workflows is precisely what makes the business attractive to a strategic acquirer.

The revenue profile reinforces the thesis. BioLife reported preliminary second quarter revenue of $28.5 million, up 21% year over year, a growth rate well above what most established life sciences tools companies are currently posting. Repligen, for its part, reported preliminary second quarter revenue growth of approximately 12% as reported and 13% on an organic basis, giving the combined company a meaningfully accelerated top-line growth profile once the two businesses are integrated.

The Financial Case for the Deal

Repligen expects the acquisition to be accretive to top-line growth, adjusted margins, and adjusted earnings per share by at least 5 cents in year one and at least 25 cents in year two. Management is targeting at least $20 million in synergies in the first year and at least $30 million in the second, driven by the elimination of public company costs, general and administrative efficiencies, and manufacturing and supply chain optimization. Notably, those projections assume only modest revenue synergies from cross-selling, leaving room for additional upside if the combined commercial teams execute well.

The deal is structured conservatively from a balance sheet perspective. Repligen expects to fund the cash portion entirely from cash on hand and still maintain more than $300 million in pro forma cash and cash equivalents after closing, preserving flexibility for future acquisitions or other investments.

Why Cell Therapy Consolidation Is Accelerating

Cell therapy represents one of the fastest-growing segments of the global pharmaceutical pipeline, with commercial revenues in the space projected to grow more than 20% annually through the end of the decade. That growth rate has made the tools and consumables companies supporting cell therapy manufacturing, storage, and logistics increasingly attractive acquisition targets for larger life sciences platforms looking to embed themselves deeper into high-growth, high-margin recurring revenue streams.

For investors tracking the life sciences tools and diagnostics space in the small and microcap range, the Repligen-BioLife transaction reinforces a consolidation pattern playing out across the sector. Companies with differentiated, deeply embedded consumables businesses tied to active clinical pipelines are commanding premium valuations, particularly when that embedding creates durable, recurring revenue rather than one-time equipment sales. The growth of the underlying cell and gene therapy market itself is worth watching closely, with companies like Ocugen advancing gene therapy programs that depend on exactly the kind of specialized processing and preservation infrastructure BioLife provides. As the cell and gene therapy pipeline continues to mature toward commercial approval, the tools companies positioned earliest in that workflow are likely to remain prime targets for strategic buyers with the balance sheet capacity to act.

Eli Lilly Pays $3.8 Billion for AtaiBeckley as Big Pharma’s Push Into Mental Health Enters a New Phase

The pharmaceutical industry’s appetite for neuroscience innovation just produced one of the most significant mental health deals in years. Eli Lilly (NYSE: LLY) announced Wednesday it has entered into a definitive agreement to acquire AtaiBeckley (Nasdaq: ATAI), a clinical-stage biopharmaceutical company developing rapid-acting therapies for treatment-resistant depression and other serious mental health conditions. The deal values AtaiBeckley at approximately $2.8 billion in upfront equity consideration, with an additional $1.0 billion in potential milestone-based contingent value rights, bringing the total potential transaction value to approximately $3.8 billion.

AtaiBeckley shareholders will receive $6.75 per share in cash at closing, representing a 40% premium to the stock’s 30-day volume-weighted average trading price. The contingent value rights are tied to specific development and regulatory milestones across the company’s two most advanced programs. The transaction is expected to close in the third quarter of 2026.

What Lilly Is Acquiring

AtaiBeckley’s pipeline is built around a class of compounds called rapid-acting neuroplastogens, therapies designed to restore the brain’s ability to form and strengthen neural connections in regions critical to mood regulation. This is a fundamentally different approach from conventional antidepressants, which primarily target neurotransmitter levels. The distinction matters because treatment-resistant depression, by definition, persists after multiple conventional treatments have failed. Millions of Americans live with it, and the clinical need for a genuinely new mechanism of action is substantial.

The lead asset, BPL-003, is a synthetic form of 5-MeO-DMT delivered as a nasal spray. In a Phase 2b study, the compound demonstrated rapid and durable reductions in depressive symptoms following a single in-clinic visit lasting approximately two hours on average, with beneficial effects persisting for months. The FDA has granted BPL-003 Breakthrough Therapy Designation and Phase 3 activities are already underway.

The second program, VLS-01, is a buccal film formulation of DMT currently advancing in a Phase 2b study for treatment-resistant depression. A third asset, EMP-01, is an R-MDMA compound in Phase 2 development for social anxiety disorder. Together, the pipeline represents one of the most clinically advanced portfolios in the emerging psychedelic-derived therapeutics space.

The Bigger Picture for Neuroscience M&A

Lilly’s move into mental health through the AtaiBeckley acquisition reflects a growing recognition across the pharmaceutical industry that neuroscience, and specifically psychiatry, represents one of the largest underserved therapeutic markets remaining. The company framed the deal explicitly as an expansion of its neuroscience pipeline to address conditions where existing treatments consistently fall short.

The deal structure itself reveals how large pharma is approaching risk in this space. The $2.8 billion upfront payment secures the pipeline and the Phase 3 asset immediately. The $1.0 billion in CVRs ties additional payments to clearly defined regulatory and development milestones, aligning incentives between buyer and seller while limiting downside if programs do not advance as planned.

What It Signals for Small Cap Biotech

For investors tracking clinical-stage neuroscience and CNS-focused companies in the small and microcap space, the Lilly-AtaiBeckley transaction sends a direct signal. Large pharma is now willing to pay nearly $4 billion for a pre-revenue mental health company with Breakthrough Therapy Designation and Phase 3 readiness. That valuation framework applies to other companies advancing differentiated CNS programs through mid-to-late-stage development, including names like NeuroSense Therapeutics, both of which are developing therapies targeting neurological and psychiatric conditions with significant unmet need.

The biotech M&A wave that began with GSK-Nuvalent and AbbVie-Apogee earlier this year has now expanded beyond oncology into neuroscience. The message from large pharma is consistent: validated clinical data, Breakthrough Therapy Designation, and clear regulatory paths in large patient populations are commanding premium valuations regardless of therapeutic area. The pipeline of small cap companies fitting that profile remains deep.

Biotech IPOs Doubled in the First Half of 2026. The Funding Window for Small Cap Drug Developers Has Not Been This Wide in Years

The biotech sector spent the better part of three years locked out of the public markets. That era appears to be decisively over. Eighteen biotech companies completed initial public offerings in the first half of 2026, exactly double the eight that went public during the same period in 2025, according to data from BioSpace. Two of those listings, Kailera Therapeutics at $625 million and Parabilis Medicines at $670 million, shattered the previous record for the largest biotech IPO ever, a title Moderna had held since 2018.

The numbers are not just higher in volume. They are higher in conviction. The median biotech IPO in 2026 raised approximately $287.5 million, more than double the equivalent figure from early 2025 and the highest quarterly median since the pandemic-era peak of 2021. Eleven of the thirteen venture-backed biotechs that priced offerings in the first half secured at least $250 million. Investors are writing larger checks for fewer companies, and the companies receiving that capital are performing after they get to Wall Street. Most of the 2026 class is currently trading at or above its debut price.

Why the Window Opened

Two forces converged to create this environment, and they are reinforcing each other. The first is a surge in mergers and acquisitions. In Q1 2026 alone, the biopharma sector recorded 19 exits valued at $13.3 billion, the highest exit value since the fourth quarter of 2021. Deals like GSK’s $10.6 billion acquisition of Nuvalent and AbbVie’s $10.9 billion purchase of Apogee Therapeutics have demonstrated that large pharma will pay significant premiums for clinical-stage assets in high-priority therapeutic areas. That M&A activity is directly fueling IPO appetite because the companies going public increasingly resemble the exact profiles that large pharma is hunting.

The second force is a return to regulatory predictability at the FDA. The agency has moved toward greater use of advisory committees and is re-evaluating applications that previously received complete response letters, creating a more navigable path for companies with mid-to-late-stage clinical programs. The combination of active acquirers and a more transparent regulatory environment has restored investor confidence in the sector’s ability to generate returns.

What It Means for Existing Small Cap Biotechs

The implications extend well beyond the companies actually going public. A healthy IPO market lifts the entire clinical-stage biotech ecosystem. When newly public companies trade well, it signals to institutional investors that the sector is functioning again, which draws capital back into the broader small cap biotech universe, including the hundreds of companies already listed and advancing their own programs.

The therapeutic areas attracting the most capital align closely with where patent cliffs are creating the most urgency for large pharma acquirers. Oncology remains a dominant focus, with companies like Cardiff Oncology, MAIA Biotechnology, and Greenwich LifeSciences all advancing clinical programs in areas where large pharma has demonstrated a clear willingness to pay for innovation. Cardiovascular disease emerged as a significant theme in H1, with Kardigan’s $400 million offering anchored around late-stage cardiac assets. Immunology, neuroscience, and rare disease continue to draw investor interest as well, with companies like Eledon Pharmaceuticals developing differentiated programs in therapeutic areas where unmet need and commercial opportunity intersect.

The second half is expected to accelerate further. Nasdaq has estimated that a dozen additional biotech IPOs could price in Q3 alone, and companies like Scribe Therapeutics, co-founded by CRISPR pioneer Jennifer Doudna, are already in the filing process. The biotech funding window has not been this open since 2021. The difference this time is that the market is rewarding discipline, clinical data, and clear regulatory paths rather than early-stage platforms and promises. That distinction is what makes this cycle more durable than the last one.

NanoViricides (NNVC) – NanoViricides Announces Phase 2 Ebola Trial Approval and Prepares Next Regulatory Filing


Tuesday, July 14, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Phase 2 Ebola Trial Advancing As Expected. Nanoviricides announced that it has received approval from the National Ethics Committee in the Democratic Republic of Congo (DRC) for its Phase 2 clinical trial of NV-387 in Ebola. The next step is the filing of a Clinical Trial Application with ACOREP, the DRC regulatory authority. This meets one of our expected milestones to start of patient treatment during summer 2026.

Two Phase 2 Trials Should Begin In A Matter of Weeks. The approval by the National Ethics Committee was a step in the process of starting clinical trials in the DRC. The company has shipped the clinical supplies of NV-387 and is preparing for a Phase 2 trial in MPox and a separate Phase 2 trial in Ebola. We expect regulatory approvals in the next several weeks to allow both trials to begin treating patients during summer 2026 through fall 2026.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Cadrenal Therapeutics (CVKD) – CAD-1005 Phase 2 Trial Data In HIT Presented at ISTH Meeting


Tuesday, July 14, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

CAD-1005 Phase 2 Study Reported At Medical Meeting. Cadrenal presented data from its Phase 2 trial testing CAD-1005 in HIT (Heparin Induced Thrombocytopenia) at the International Society on Thrombosis and Haemostasis (ISTH) 2026 Congress. As discussed in our Research Note on February 25, the trial did not meet its Primary Endpoint, but successfully characterized CAD-1005 and had unanticipated findings that were better than expected.

CAD-1005 Reduced Thrombotic Events Without Platelet Recovery. The Phase 2 placebo-controlled trial was designed to test CAD-1005 with standard anticoagulant therapy. Its Primary Endpoint was an improvement in platelet recovery, a biomarker for predicting thrombotic events and outcome. This primary endpoint did not meet statistical significance, although the secondary endpoint of reduction in thrombotic events showed a clinically meaningful improvement.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

MAIA Biotechnology (MAIA) – First Data From Phase 2 Part C Trial Shows Data Consistent With Earlier Studies


Thursday, July 09, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Data From Part C Announced. MAIA announced data from Part C (Expansion stage) of its Phase 2 THIO-101 trial in non-small cell lung cancer (NSCLC). This open-label stage of the trial tests the combination of ateganosine and cemiplimab (Libtayo, from Regeneron) as a third-line (3L) therapy for patients with advanced disease that no longer respond to other therapies. The data after the first evaluation have a Disease Control Rate (DCR) of 90.5% (19 out of 21 patients), compared with published rates of 25% to 35%. We view this as a good sign that patient responses are consistent with previous data.

Design Of the Phase 2 THIO-101 Trial. The Phase 2 THIO-101 Expansion stage is the third part of the Phase 2 trial. Part A tested safety, while Part B was for dose optimization and selection. Part C is currently testing the combination of the 180 mg dose of ateganosine with cemiplimab. If positive, the data could be used to apply for accelerated approval from the FDA.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

NanoViricides (NNVC) – Novel Technology With Broad-Spectrum Antiviral Applications In Development


Monday, July 06, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

We Are Initiating Coverage With An Outperform Rating. NanoViricides has a proprietary technology platform that it has used to formulate antivirals with a unique mechanism of action. These drugs, called nanoviricides, have been designed to carry a peptide sequence that the virus recognizes as a binding site on a host cell, effectively acting as decoys that the virus binds to instead of healthy cells. Once bound to the drug, the virus is trapped and neutralized.

NV-387 Addresses Viral Outbreaks and Pandemic Preparedness. The lead product, NV-387, is in development for MPox, Ebola, and smallpox. A Phase 2a trial evaluating NV-387 for treating MPox in the Democratic Republic of Congo (DRC) is expected to begin treatment in mid-2027, followed by a Phase 2a in Ebola. Initial data is expected to be available toward the end of 2027.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – Cadrenal Therapeutics Announces up to $8.8 Million Private Placement Priced At-The-Market Under Nasdaq Rules

PONTE VEDRA, Fla., June 30, 2026 (GLOBE NEWSWIRE) — Cadrenal Therapeutics, Inc. (Nasdaq: CVKD) (the “Company”), a biopharmaceutical company advancing late-stage novel therapies for life-threatening immune and thrombotic conditions, today announced that it has entered into a definitive agreement with a single healthcare-focused institutional investor for the issuance and sale of 960,000 shares of its common stock (or pre-funded warrants in lieu thereof), series C-1 warrants to purchase up to an aggregate of 960,000 shares of common stock and series C-2 warrants to purchase up to an aggregate of 960,000 shares of common stock, at a combined purchase price of $3.125 per share (or pre-funded warrant in lieu thereof) and accompanying warrants in a private placement priced at-the-market under Nasdaq rules.

H.C. Wainwright & Co. is acting as the exclusive placement agent for the offering.

The series C-1 warrants will have an exercise price of $3.00 per share, will be exercisable beginning on the effective date of stockholder approval of the issuance of the shares of common stock issuable upon exercise of the series C-1 warrants (the “Stockholder Approval Date”) and will expire five years after the later of (i) the Stockholder Approval Date and (ii) the effective date of a resale registration statement registering for resale all of the shares of common stock underlying the series C-1 warrants. The series C-2 warrants will have an exercise price of $3.00 per share, will be exercisable immediately upon issuance, and will expire twenty-four months after the effective date of a resale registration statement registering for resale all of the shares of common stock and the shares of common stock underlying the series C-2 warrants.

The aggregate gross proceeds to the Company from the offering are expected to be $3 million, before deducting placement agent fees and other offering expenses. The potential additional gross proceeds to the Company from the series C-1 warrants and the series C-2 warrants, if fully exercised on a cash basis, will be approximately $5.8 million. No assurance can be given that any of the warrants will be exercised, or that the Company will receive cash proceeds from the exercise of the warrants. The offering is expected to close on or about July 1, 2026, subject to the satisfaction of customary closing conditions. The Company intends to use the net proceeds from the offering for working capital purposes.

The securities described above were offered in a private placement under Section 4(a)(2) of the Securities Act of 1933, as amended (the “Act”) and Regulation D promulgated thereunder and, along with the shares of common stock underlying the warrants sold in the offering, have not been registered under the Act or applicable state securities laws. Accordingly, such securities may not be offered or sold in the United States absent registration with the Securities and Exchange Commission (“SEC”) or an applicable exemption from such registration requirements. Pursuant to a registration rights agreement, the Company has agreed to file one or more registration statements with the SEC covering the resale of the unregistered securities to be issued in the offering.

This press release shall not constitute an offer to sell or the solicitation of an offer to buy these securities, nor shall there be any sale of these securities in any state or jurisdiction in which such offer, solicitation, or sale would be unlawful prior to registration or qualification under the securities laws of any such state or jurisdiction.

About Cadrenal Therapeutics, Inc.

Cadrenal Therapeutics, Inc. is a late-stage biopharmaceutical company advancing novel therapies for life-threatening immune and thrombotic conditions. Its lead program, CAD-1005, is being investigated as a first-in-class 12-LOX inhibitor for heparin-induced thrombocytopenia (HIT), a deadly immune-mediated thrombotic disorder, and Cardiac Surgery-Associated Acute Kidney Injury (CSA-AKI). CAD-1005 has received Orphan Drug and Fast Track designations from the U.S. Food and Drug Administration and orphan drug status from the European Medicines Agency. Second-generation 12-LOX oral therapeutics are also in development for chronic indications.

The Company’s broader pipeline includes tecarfarin, a late-stage oral vitamin K antagonist designed to prevent heart attacks, strokes, and deaths from blood clots in patients requiring chronic anticoagulation, including those with end-stage kidney disease, those with left ventricular assist devices, and potentially, those with Kawasaki disease (KD), an acute self-limited febrile illness that primarily affects children <5 years old, and the leading cause of acquired heart disease in developed countries.

Safe Harbor

Any statements in this press release about future expectations, plans, and prospects, as well as any other statements regarding matters that are not historical facts, may constitute “forward-looking statements.” The words “anticipate,” “believe,” “continue,” “could,” “estimate,” “expect,” “intend,” “may,” “plan,” “potentially,” “predict,” “project,” “should,” “target,” “will,” “would” and similar expressions are intended to identify forward-looking statements, although not all forward-looking statements contain these identifying words. These statements include, without limitation, statements regarding the closing of the offering, the satisfaction of customary closing conditions related to the offering, the expected gross proceeds from the offering, the Company seeking stockholder approval, receipt of stockholder approval, the filing of one or more registration statements with the SEC covering the resale of the unregistered securities to be issued in the offering, the intended use of net proceeds from the offering, the potential exercise of the warrants for cash prior to their expiration and the Company’s receipt of potential proceeds therefrom, net proceeds anticipated to extend the Company’s cash runway into first quarter of 2027; and the Company’s cash runway anticipated to be extended into second half of 2027 to advance partnering opportunities for tecarfarin in Kawasaki Disease (potential rare pediatric disease designation) and CAD-1005 in CSA-AKI and HIT.

Actual results may differ materially from those indicated by such forward-looking statements as a result of various important factors, including the ability to close the offering, the ability of the Company to obtain stockholder approval, the ability of the Company to advance partnering opportunities for tecarfarin in Kawasaki Disease (potential rare pediatric disease designation) and CAD-1005 in CSA-AKI and HIT; the ability to raise sufficient capital to continue progress of its product candidates; the ability to derive the results needed for an NDA submission; and the other risk factors described in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025, and the Company’s subsequent filings with the Securities and Exchange Commission, including subsequent periodic reports on Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. Any forward-looking statements contained in this press release speak only as of the date hereof and, except as required by federal securities laws, the Company specifically disclaims any obligation to update any forward-looking statement, whether as a result of new information, future events, or otherwise.

For more information, visit https://www.cadrenal.com/ and connect with the Company on LinkedIn.

For more information, please contact:

Lytham Partners, LLC, Robert Blum, Managing Partner, 602-889-9700, [email protected]

Unicycive Therapeutics (UNCY) – Delay in Manufacturing Inspection Leads To Complete Response Letter (CRL)


Wednesday, July 01, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

We Now Expect Product Approval Around YE2026. Unicycive announced it has received a CRL (Complete Response Letter) stating that the NDA for OLC (oxylanthanum carbonate), its phosphate binder for patients on dialysis, has not been approved. The reason stated is that the FDA has not conducted its required inspection of the third-party manufacturing vendor. This step is expected to be completed during the summer, allowing for an NDA resubmission and approval near YE2026.

All Other Steps In The NDA Review Appear To Be Complete. The FDA inspection appears to have been the only remaining step for OLC approval. After a meeting with the FDA, steps to resolve manufacturing issues with the third-party vendor were identified, addressed, and the plant readied for inspection. The review of clinical efficacy and safety data was completed in 2025, with no new issues raised. Product labeling and packaging discussions have been ongoing, typically the last step before approval.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

NeuroSense Therapeutics Ltd. (NRSN) – Phase 2 RoAD Trial Findings In Alzheimer’s Disease Reported


Thursday, June 25, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

New Data Supports Mechanism of Action. NeuroSense reported data from its Phase 2 RoAD trial testing PrimeC in Alzheimer’s Disease (AD). The study was designed to evaluate safety, efficacy, and disease-associated biomarkers. The results showed changes consistent with the prevention of degeneration and neuronal cell death. We believe these data support PrimeC’s mechanism and its benefits, providing proof of concept for further studies.

Study Design. The Phase 2 RoAD trial was a placebo-controlled study testing PrimeC in Alzheimer’s disease. The trial enrolled eight patients who were randomized to receive PrimeC or placebo for 52 weeks. Three participants completed a 12-month follow-up period, with CSF and plasma samples evaluated at three timepoints.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.