Graham (GHM) – New Awards


Thursday, August 06, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Awards. Graham Corporation was awarded two contracts for a combined value of over $43 million. These awards reflect the continued demand the Company is seeing across its defense platforms. The revenue for the contracts will be reflected in the Company’s first and second fiscal year 2027 backlog.

MK48 Mod 7 Heavyweight Torpedo. The first award is a follow-on fourth option year supporting the MK48 Mod 7 Heavyweight Torpedo program, awarded in the first quarter of fiscal 2027, which ended June 30, 2026. The Company will continue to provide alternators and regulators under this option year.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Everyone’s Watching Record Highs. Smart Money Is Watching Oil and Small Caps

Wall Street woke up Wednesday to more of what it’s gotten all week: record highs, falling oil, and a fragile peace headline out of the Middle East. The financial press will lead with the Dow. The more useful question for anyone investing below the mega-cap tier is what cheaper crude actually does to small caps.

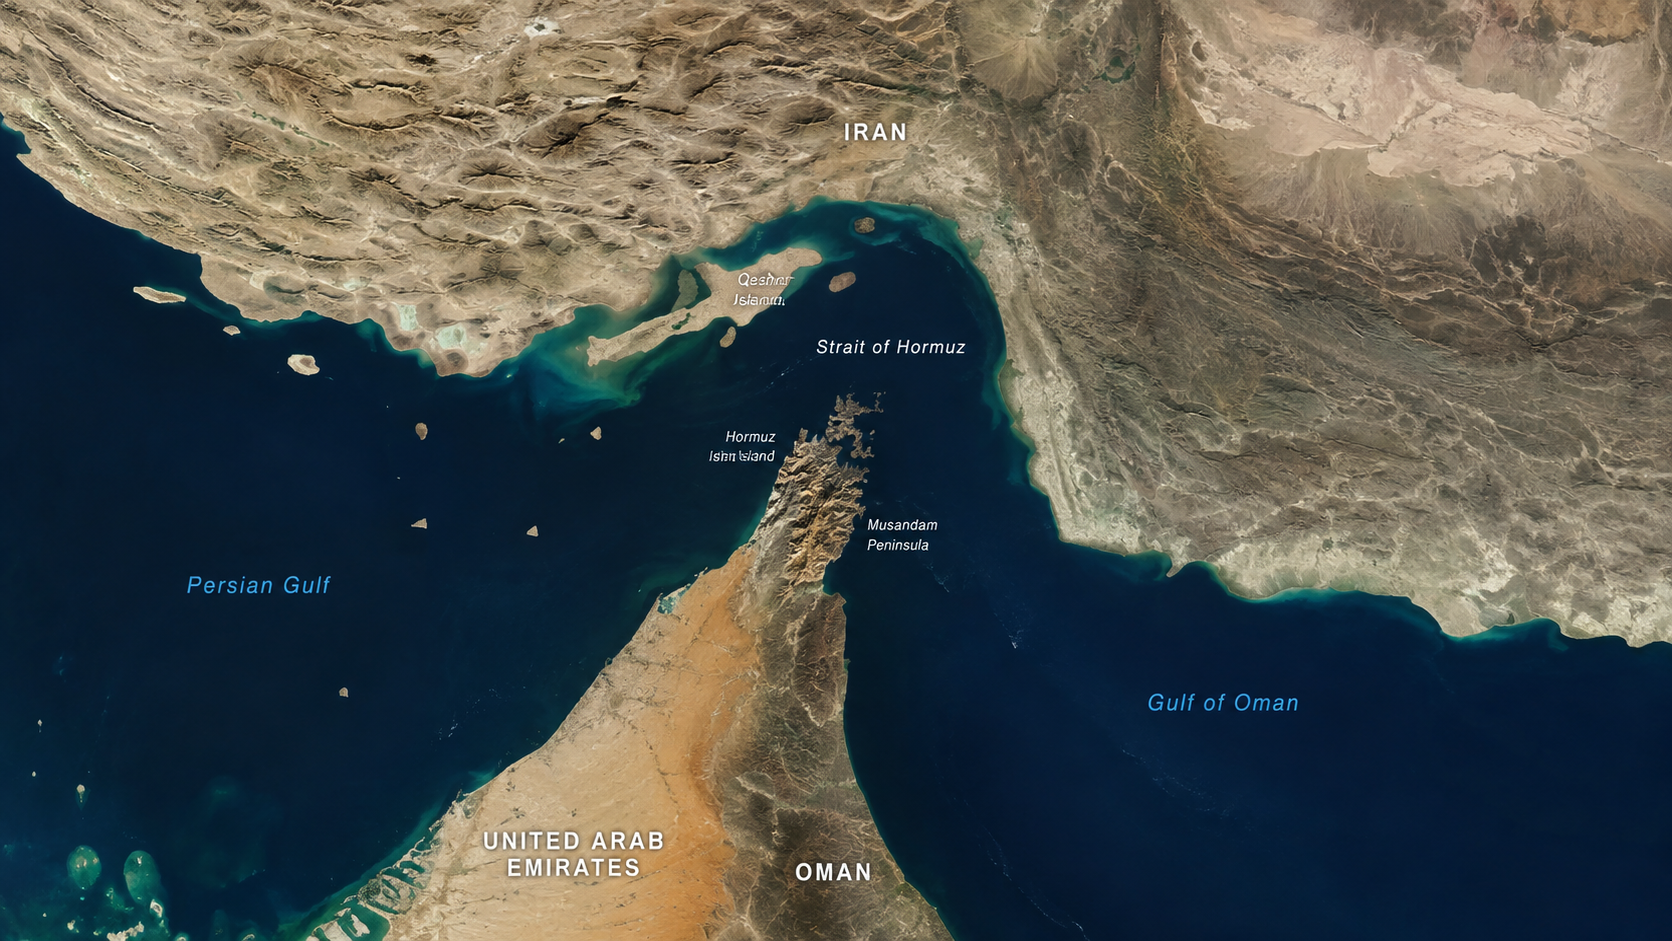
Start with the setup. After a searing rally that pushed the S&P 500 and Dow to record closes Tuesday, US futures steadied Wednesday morning. Oil fell for a third straight session — Brent slipped near $78 and WTI dropped under $75 — on growing hope that the Strait of Hormuz, the chokepoint for roughly a fifth of the world’s oil, could reopen. Qatar said a US–Iran proposal has been drafted, and Iran is reportedly weighing whether to let European navies clear mines from the waterway. Asia cheered it overnight, with South Korea’s KOSPI jumping 4%. Gold pushed higher, the VIX stayed calm, and Russell 2000 futures held firm.

Here’s why small-cap investors should care more than the headline suggests.

Small companies are the most exposed to the price of energy — and the most helped when it falls. They’re overwhelmingly domestic, they run thinner margins, and they lack the global hedging desks and pricing power of the mega-caps. When crude drops, the input-cost relief flows straight to the bottom line of small-cap industrials, transports, manufacturers, and consumer names. Cheaper oil is, in effect, a stealth margin boost for the exact companies that live closest to the edge on the income statement.

There’s a second-order effect that matters even more. Lower oil feeds disinflation, disinflation keeps the Fed’s rate-cut path alive, and small caps are the single most rate-sensitive corner of the market. Pair that with this week’s soft ADP jobs number and you get a macro mix that has historically favored the little guys.

Now the honest other side, because it cuts both ways. Energy is a meaningful slice of the Russell 2000, and cheaper crude squeezes small-cap exploration and production names hard. If your small-cap exposure leans toward oil and gas, this is a headwind, not a tailwind. The net effect depends entirely on what you own.

Step back, though, and the direction of travel is the story. The rally is finally broadening beyond the handful of AI mega-caps that carried it for two years — the Russell is joining the record run, not watching from the sidelines. A de-risking geopolitical backdrop, falling oil, and an easing Fed is the kind of trifecta that tends to reward the laggards. For two years, small caps have been the laggard.

One caveat to keep front and center: this peace is fragile, and a single headline could send oil right back up. Don’t build a thesis on a diplomatic maybe. But watch the setup. While everyone fixates on the Dow printing another record, the more interesting move may be one rung down the market-cap ladder — where the companies most helped by cheap oil and cheap money have been overlooked the longest.

FreightCar America (RAIL) – RAIL Provides Updated Outlook; Webinar at 11:00 AM ET


Tuesday, August 04, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Second Quarter FY 2026 Financial Results. RAIL generated a 2Q FY26 adjusted net loss to common stockholders of $821.0 thousand, or $(0.02) per share, compared to adjusted net income of $3.8 million, or $0.11 per share, during the prior year period. We had projected net income of $350 thousand or $0.01 per share. Gross margin as a percentage of revenue amounted to 5.5% compared to 15.0% in 2Q FY 2025. Revenue and rail car deliveries declined to $113.1 million and 927, compared to $118.6 million and 939 during the prior year period. We had forecast revenue of $112.3 million and deliveries of 923. Adj. EBITDA amounted to $1.2 million compared to $9.3 million in 2Q FY 2025 and our estimate of $5.7 million. We had projected higher gross margin.

Updated FY 2026 Guidance. Management updated its FY 2026 guidance. Railcar deliveries are expected to be in the range of 3,500 to 3,900, revenue in the range of $410 to $460 million, and adj. EBITDA in the range of $36 to $44 million. Prior guidance projected railcar deliveries in the range of 4,000 to 4,500, revenue in the range of $500 to $550 million, and adj. EBITDA in the range of $41 to $50 million. Our current estimates are at the low end of prior guidance. We will update our estimates following today’s investor call.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Supernus and Indivior Are Merging to Build a $2.2 Billion CNS Powerhouse

Supernus Pharmaceuticals (Nasdaq: SUPN) and Indivior Pharmaceuticals (Nasdaq: INDV) announced Monday they have entered into a definitive agreement to combine in a tax-free, all-stock merger of equals, creating a new company focused entirely on central nervous system disease. The combined entity will be named Supernus, Inc., trade on the Nasdaq Global Market under the ticker SUPN, and be headquartered in Rockville, Maryland.

The transaction is expected to generate pro forma net revenue of approximately $2.2 billion and pro forma adjusted EBITDA of $888 million, alongside roughly $125 million in expected annual cost synergies. Closing is targeted for the fourth quarter of 2026, subject to shareholder and regulatory approvals, and the boards of both companies have unanimously approved the deal.

How the Merger Is Structured

The deal terms reveal a genuine merger of equals rather than a straightforward acquisition. Supernus stockholders will receive 1.5401 shares of Indivior common stock for each Supernus share they hold, resulting in Indivior stockholders owning approximately 56.5% of the combined company and Supernus stockholders owning approximately 43.5%, on a fully diluted basis.

Ahead of closing, Indivior stockholders will also receive a one-time special cash dividend totaling $1.0 billion. That dividend will be funded through a combination of existing cash on hand and a $650 million term loan facility committed by Citibank. Jack Khattar, currently President and CEO of Supernus, will lead the combined company in that same role, while Tony Kingsley, currently a member of Indivior’s board, will serve as Board Chair.

Two Complementary CNS Franchises Coming Together

The strategic logic centers on scale and portfolio diversification within neuroscience. Supernus has built its business around psychiatric and neurological conditions, while Indivior has focused heavily on addiction treatment. Together, the combined company will market 11 differentiated commercial medicines spanning psychiatry, neurology, and addiction, a breadth that neither company could offer independently at this scale.

That diversification matters strategically because CNS drug development is notoriously difficult, with high clinical failure rates and long development timelines. A combined commercial portfolio spanning multiple CNS subcategories reduces the company’s dependence on any single therapeutic area or product cycle, while giving it a broader sales and marketing infrastructure to support both existing products and future pipeline candidates.

A Financially Disciplined Combination

Alongside the merger announcement, Supernus also raised its fiscal 2026 sales guidance, moving its prior range of $1.215 billion to $1.285 billion up to a new range of $1.295 billion to $1.365 billion, above the consensus estimate of $1.245 billion, a signal of underlying business strength independent of the transaction itself.

The combined company is projected to carry net debt of roughly $878 million against its earnings base, translating to a net leverage ratio below 1 times EBITDA. That conservative balance sheet is a notable feature of the deal, giving the newly formed Supernus, Inc. meaningful financial flexibility to continue investing in its internal pipeline while also pursuing additional strategic acquisitions once the merger closes.

What It Means for Investors Tracking Specialty Pharma

For investors following small and mid cap pharmaceutical companies, this deal illustrates a consolidation pattern that continues to play out across specialty therapeutic areas. Two mid-sized companies, each strong in a narrower CNS niche, are combining to build the kind of commercial scale, balance sheet strength, and portfolio diversification that increasingly determines competitive positioning in specialty pharma, without either company needing to be acquired outright by a larger strategic buyer. The broader CNS space remains one of the more active areas of biopharmaceutical development, with clinical-stage companies like NeuroSense Therapeutics continuing to advance novel approaches to neurological disease even as larger, more established players consolidate around commercial scale.

Amazon Surged 10% After AWS Posted Its Best Quarter in Years. The Company Is Raising Its AI Spending to $220 Billion

Amazon shares jumped 10% in premarket trading Friday after the company topped second quarter expectations, driven by an acceleration in Amazon Web Services that one analyst covering the stock described as a genuine home run for the company. The results stood in sharp contrast to the mixed reception several other mega cap earnings reports have received this season.

AWS generated $42.2 billion in second quarter revenue, up 36.7% year over year, with strength across both its core cloud business and its expanding AI services. Amazon disclosed that its AI and custom chip businesses have each individually surpassed a $25 billion annualized revenue run rate, a figure that underscores just how quickly the AI infrastructure side of the business has scaled. The company’s custom chip business is now growing at a triple-digit year-over-year rate.

A Record Quarter of Growth

CEO Andy Jassy told investors on the earnings call that AWS added over $4.6 billion in revenue quarter over quarter, roughly 80% more than the company’s largest previous quarterly increase. The segment’s backlog now stands at $496 billion, growing at a triple-digit rate year over year. Jassy noted that customers continue choosing AWS for the breadth of its capabilities, particularly the ability to run AI inference near existing applications and data, a capability AWS offers more extensively than its competitors.

AWS is now running at approximately a $170 billion annual revenue run rate, more than four times larger than it was in 2019, illustrating the scale of growth the cloud division has achieved over the past several years.

The Capex Number That Matters

Heading into the report, Wall Street had been closely watching two things: AWS growth and capital expenditures tied to AI infrastructure. Amazon delivered on both fronts, but not in the direction some investors might have expected given the market’s recent skepticism toward AI spending. The company raised its full-year capital expenditure guidance to approximately $220 billion, up from its prior guidance of roughly $200 billion.

In a market environment where companies like Oracle and Tesla have seen their stocks punished for similarly aggressive AI-related spending increases, Amazon’s reception was notably different. Wall Street appeared willing to look past the higher spending given AWS’s accelerating growth and expanding operating margins, a combination that suggests the capital is translating into measurable revenue rather than simply funding future capacity that has yet to prove out. Jassy indicated that demand for AI and cloud computing continues to outstrip available server capacity, with planned 2027 expansion already largely booked into 2028.

What It Means for Smaller Companies in the AI Supply Chain

For investors tracking the broader technology and infrastructure ecosystem, Amazon’s report offers a useful counterpoint to the AI spending anxiety that has weighed on chip and infrastructure names throughout the summer. When a hyperscaler raises capital expenditure guidance and the market responds positively rather than punitively, it signals renewed confidence that AI infrastructure demand remains durable, at least when that spending is paired with visible, accelerating revenue growth like AWS delivered this quarter.

That distinction matters considerably for smaller companies supplying components, power infrastructure, cooling systems, and specialized hardware into the broader AI buildout. A $220 billion capital expenditure plan does not get executed through Amazon’s own engineering teams alone. It flows through an extensive supplier base, and this quarter’s results suggest that demand signal remains firmly intact even as some large cap names in the space have faced renewed investor scrutiny in recent weeks.

Release – Summit Midstream Corporation Schedules Second Quarter 2026 Earnings Call

Summit Midstream Partners Logo. (PRNewsFoto/Summit Midstream Partners)

Research News and Market Data on SMC

PDF Version

HOUSTON, July 30, 2026 /PRNewswire/ — Summit Midstream Corporation (NYSE: SMC) (“Summit”, “SMC” or the “Company”) announced today that it will report operating and financial results for the second quarter of 2026 on Monday, August 10, 2026, after the close of trading on the New York Stock Exchange.

Second Quarter 2026 Earnings Call

SMC will host a conference call at 10:00 a.m. Eastern on August 11, 2026, to discuss its quarterly operating and financial results. The call can be accessed via teleconference at: Q2 2026 Summit Midstream Corporation Earnings Conference Call (https://register-conf.media-server.com/register/BI8cebf785fce846a9bb80ae80660d3cbc). Once registration is completed, participants will receive a dial-in number along with a personalized PIN to access the call. While not required, it is recommended that participants join 10 minutes prior to the event start. The conference call, live webcast and archive of the call can be accessed through the Investors section of SMC’s website at www.summitmidstream.com.

About Summit Midstream Corporation

SMC is a value-driven corporation focused on developing, owning and operating midstream energy infrastructure assets that are strategically located in the core producing areas of unconventional resource basins, primarily shale formations, in the continental United States. SMC provides natural gas, crude oil and produced water gathering, processing and transportation services pursuant to primarily long-term, fee-based agreements with customers and counterparties in five unconventional resource basins: (i) the Williston Basin, which includes the Bakken and Three Forks shale formations in North Dakota; (ii) the Denver-Julesburg Basin, which includes the Niobrara and Codell shale formations in Colorado and Wyoming; (iii) the Fort Worth Basin, which includes the Barnett Shale formation in Texas; (iv) the Arkoma Basin, which includes the Woodford and Caney shale formations in Oklahoma; and (v) the Piceance Basin, which includes the Mesaverde formation as well as the Mancos and Niobrara shale formations in Colorado. SMC has an equity method investment in Double E Pipeline, LLC, which provides interstate natural gas transportation service from multiple receipt points in the Delaware Basin to various delivery points in and around the Waha Hub in Texas. SMC is headquartered in Houston, Texas.

Forward-Looking Statements

This press release includes certain statements concerning expectations for the future that are forward-looking within the meaning of the federal securities laws. Forward-looking statements include, without limitation, any statement that may project, indicate or imply future results, events, performance or achievements and may contain the words “expect,” “intend,” “plan,” “anticipate,” “estimate,” “believe,” “will be,” “will continue,” “will likely result,” and similar expressions, or future conditional verbs such as “may,” “will,” “should,” “would” and “could.” In addition, any statement concerning future financial performance (including future revenues, earnings or growth rates), payment of dividends on any series of stock, ongoing business strategies and possible actions taken by SMC or its subsidiaries are also forward-looking statements. Forward-looking statements also contain known and unknown risks and uncertainties (many of which are difficult to predict and beyond management’s control) that may cause SMC’s actual results in future periods to differ materially from anticipated or projected results. An extensive list of specific material risks and uncertainties affecting SMC is contained in its 2025 Annual Report on Form 10-K filed with the Securities and Exchange Commission (the “SEC”) on March 16, 2026, as amended and updated from time to time. Any forward-looking statements in this press release are made as of the date of this press release and SMC undertakes no obligation to update or revise any forward-looking statements to reflect new information or events.

Cision View original content to download multimedia:https://www.prnewswire.com/news-releases/summit-midstream-corporation-schedules-second-quarter-2026-earnings-call-302839502.html

SOURCE Summit Midstream Corporation

[email protected]

ICE Just Paid $6 Billion to Fix One of Finance’s Last Analog Corners

Intercontinental Exchange announced this morning it will acquire MarketAxess Holdings for $167 per share in cash, a 33% premium that values the fixed income trading platform at roughly $6 billion in equity value and $5.7 billion in total enterprise value. It’s a deal aimed squarely at a problem that has persisted through decades of financial market modernization: the bond market still trades like it’s 1995.

That is not an exaggeration. The global fixed income market carries an estimated $145.1 trillion in outstanding debt, dwarfing the equity markets in size, yet bond trading remains disproportionately manual, conducted bilaterally over phone calls and instant messages between dealers, with wide bid-ask spreads and limited price transparency. Stocks solved this problem years ago through centralized, electronic exchanges. Bonds never fully did, and that gap is exactly what ICE is paying to close.

MarketAxess brings the piece ICE has been missing. The platform connects roughly 2,100 institutional investors and broker-dealers across more than 90 countries, enabling electronic trading in corporate bonds, municipal debt, emerging market bonds, and U.S. Treasuries. ICE, meanwhile, has spent years building out the surrounding infrastructure, a retail and wealth-focused bond trading franchise, fixed income data and analytics, and a global index business, without ever owning the institutional execution network to tie it all together. ICE Chair and CEO Jeff Sprecher framed the deal as a continuation of a strategy the company has run for two decades: find the largest, least efficient corners of finance and rebuild them with better technology, the same playbook ICE has already applied to energy markets, credit default swaps, and mortgage technology.

The financial structure of the deal is worth noting for what it signals about ICE’s confidence in the combination. The transaction is being financed entirely in cash through newly issued debt, a mix of bonds, a term loan, and commercial paper, and ICE is simultaneously increasing its quarterly share repurchase baseline to $400 million from $350 million rather than pausing buybacks to conserve cash. The company expects the deal to be accretive to adjusted earnings per share in its first full year, with $100 million in annual run-rate cost synergies expected within three years. ICE’s gross leverage will begin at 3.4 times pro forma EBITDA, with a target of returning to 3.0 times or below within 18 to 24 months, a timeline that suggests management views the combined business as strongly cash generative even while absorbing new debt.

For a deal of this size in market infrastructure, the strategic logic is straightforward enough that it barely needs translation. Consolidated liquidity pools tend to produce tighter pricing and lower transaction costs for everyone trading on them, which is the same network effect that has driven exchange consolidation across asset classes for years. MarketAxess CEO Chris Concannon pointed to the complementary nature of the two businesses, MarketAxess brings the institutional trading network, ICE brings retail protocols, data, and connectivity, as the combination’s core rationale.

The deal still requires MarketAxess shareholder approval and customary regulatory clearances, with closing targeted for the first half of 2027. Boards at both companies have already approved it unanimously.

Grant Thornton Just Paid a 54% Premium to Buy CBIZ. It Is the Biggest Accounting Deal in 25 Years

Grant Thornton Advisors announced Wednesday it has entered into a definitive agreement to acquire CBIZ (NYSE: CBZ), a professional services firm listed on the New York Stock Exchange, in an all-cash transaction with an enterprise value of $5 billion. Under the terms of the deal, CBIZ shareholders will receive $55.00 per share, representing a 54% premium to the company’s 30-day volume-weighted average price and roughly an 18% premium to CBIZ’s most recent closing price. The transaction is described as the largest of its kind in more than 25 years.

The deal is backed by New Mountain Capital, which previously led a May 2024 investment in Grant Thornton Advisors and has now committed $5.2 billion in financing to support this acquisition as well. CBIZ’s board unanimously approved the transaction and is recommending shareholders vote in favor of it. Closing is targeted for the fourth quarter of 2026, subject to shareholder and regulatory approval.

A Genuine Industry Heavyweight

The combination reshapes the upper tier of the professional services industry. CBIZ currently ranks No. 8 on Accounting Today’s 2026 Top 100 Firms list with $2.8 billion in revenue, while Grant Thornton sits at No. 9 with $2.5 billion. Once combined, the merged firm is expected to become the fifth-largest professional services provider in the United States, generating more than $5 billion in domestic revenue and nearly $7.5 billion globally, operating across more than 20 countries with a workforce exceeding 34,500 professionals.

CBIZ President and CEO Jerry Grisko called it a historic combination with a strong cultural and strategic fit, framing the deal as one that creates new opportunity for employees while delivering significant value to shareholders.

What the Deal Is Actually Built Around

The stated strategic rationale centers on three areas: expanding Grant Thornton’s AI-enabled service delivery capabilities, growing its multinational footprint, and deepening industry specialization across both firms’ combined client base. As part of the restructuring, CBIZ’s Benefits and Insurance Services segment will be spun off as an independent, growth-oriented company, a signal that the combined entity intends to sharpen its focus on core advisory, tax, and accounting services rather than retain every existing business line.

The deal includes a go-shop period running through August 27, 2026, during which CBIZ may solicit superior competing proposals, alongside standard no-shop and termination provisions once that window closes. CBIZ’s board also adopted change-in-control severance, retention, and transaction bonus programs the same day the deal was announced, a customary step designed to retain key personnel through the transition.

The Numbers Behind the Timing

The announcement landed alongside CBIZ’s own second quarter results. For the first half of 2026, the company reported revenue of $1.53 billion, up modestly year over year, with net income rising 4.1% to $171.4 million and adjusted diluted earnings per share increasing 3.6% to $3.44. CBIZ also repurchased approximately 2.5 million shares for roughly $70 million during the period, while reducing net leverage to 3.4 times, down from the prior year.

Why This Matters Beyond Accounting

For investors tracking consolidation trends across professional and business services, this deal reinforces a pattern playing out broadly this year. Private equity-backed platforms are aggressively pursuing scale in fragmented service industries, betting that combining AI capability, specialized talent, and multinational reach creates durable competitive advantages that smaller, standalone firms increasingly struggle to match on their own.

Apple Passed Nvidia as the World’s Most Valuable Company. Spending Less on AI Just Became a Winning Strategy

Apple reclaimed the title of the world’s most valuable public company Monday, overtaking Nvidia as its stock pushed toward a record high close. Apple’s market capitalization reached approximately $4.94 trillion, edging past Nvidia’s $4.83 trillion. The shift caps a remarkable turnaround for a company that spent much of the past two years being criticized for lagging behind its peers on artificial intelligence investment.

Apple shares have climbed more than 22% year to date, outperforming every other member of the so-called Magnificent Seven. The reason is almost the inverse of what drove the group’s dominance over the past two years. Investors are increasingly rewarding Apple precisely because it has not spent aggressively on AI infrastructure, treating capital discipline as a genuine strength rather than a competitive weakness.

The Capex Divide Reshaping Big Tech

Data tracked through Yahoo Finance’s AlphaSpace shows Apple’s capital expenditures have actually declined over the past three quarters, a striking contrast to nearly every other major technology company racing to build AI infrastructure. That restraint stands in sharp relief against Alphabet, which raised its capital spending outlook last week to fund its AI infrastructure buildout, and Tesla, which increased spending to support its robotaxi and robotics ambitions. Shares of both companies fell following their respective earnings reports. Alphabet is up only about 3% year to date, and Tesla has tumbled roughly 30% over the same period.

The market’s message has become increasingly clear this earnings season. Companies spending aggressively on AI capacity are being asked hard questions about return on that investment, while companies demonstrating they can capture AI-driven demand without ballooning capital expenditures are being rewarded with premium valuations.

A Pivotal Week Ahead

Apple reports earnings Thursday after the closing bell, and the report carries added significance beyond the usual quarterly scrutiny. Investors will be watching closely for signs the company can scale its Apple Intelligence features across its device lineup without a meaningful increase in capital expenditures or pressure on operating margins. If Apple can demonstrate that its AI strategy works within its existing capital-light framework, it would validate the market’s current thesis in dramatic fashion.

The timing carries additional weight. Thursday will mark Tim Cook’s final earnings call as CEO before he steps down September 1 to become executive chairman, with John Ternus, a longtime hardware engineering veteran at Apple, taking over as chief executive. Microsoft, Amazon, and Meta all report later this week as well, and all three are expected to announce further increases in AI-related spending, setting up a direct contrast with Apple’s approach in real time.

What This Means for the Broader Market

For investors tracking the AI infrastructure ecosystem, the leadership change at the top of the market matters beyond Apple and Nvidia individually. It reinforces a theme that has run through this entire earnings season: the market is no longer rewarding AI spending simply because it is AI spending. It is scrutinizing whether that capital is translating into visible product outcomes and sustainable margins.

That distinction has real implications down the market cap spectrum. Smaller companies supplying components, software, and infrastructure into the AI buildout are increasingly being evaluated on the same terms, whether their growth is funded responsibly or whether it depends on the kind of unchecked capital expenditure that has weighed on stocks like Alphabet and Tesla this earnings season. Apple’s ascent back to the top is, in part, the market rewarding exactly the kind of capital discipline that investors are now demanding across the board.

Tesla Stock Falls 14% After Missing Profit Estimates. Full-Year Capex Spend of $25 Billion Confirmed

Tesla reported second quarter results Wednesday that missed Wall Street’s profit expectations by a wide margin, and the stock fell 14% the following session as investors weighed the earnings shortfall against the company’s confirmed plan to spend $25 billion on capital expenditures for the full year.

Adjusted earnings per share came in at $0.33, well below the approximately $0.50 analysts had expected, a miss of roughly 34%. Operating margin collapsed to 1.4% from 4.1% a year earlier, and operating income fell 57% to just $398 million. Adjusted EBITDA landed at $3.2 billion versus the $4 billion expected. On the profitability side of the ledger, this was a clear and significant miss.

Revenue told a different story. Tesla reported $28.24 billion, up 26% year over year and above the $26.32 billion Bloomberg consensus estimate. Vehicle deliveries came in at 480,126 units, up 25% year over year and well ahead of the 406,000 consensus. For the first time in company history, Tesla crossed $100 billion in trailing twelve month revenue. The top line beat. The bottom line did not, and it was the bottom line that drove the stock’s decline.

Where the Profit Miss Came From

Part of the shortfall traces back to regulatory credit income. For the first time in many quarters, those credits, which had historically contributed $700 million to $900 million per quarter to Tesla’s bottom line, came in far below that level, removing a cushion that had quietly supported margins for years.

The larger driver is capital spending. Capital expenditures surged 142% year over year to $5.79 billion for the quarter, pushing free cash flow negative at $1.09 billion. Management confirmed on the earnings call that full-year capex will total approximately $25 billion, directed almost entirely at scaling Cybercab production, building out Optimus manufacturing lines, and expanding the company’s Cortex AI compute infrastructure in Texas. CFO Vaibhav Taneja told investors that operating expenditures will continue growing through 2026 and beyond, and that commodity price increases and interest rate changes will keep adding to costs.

The Bet Behind the Spending

Every dollar of that $25 billion is aimed at a future well beyond electric vehicles. Cybercab began production and public-road testing during the quarter at Gigafactory Texas. Robotaxi service is now live in seven US metro areas. First-generation Optimus assembly lines are being installed at the Fremont factory, on space freed up after Tesla decommissioned its Model S and X production lines, with initial production targeted for later this year. Tesla Semi and Megapack 3 remain on schedule to begin production in 2026 as well.

CEO Elon Musk described this as Tesla’s largest and most exciting period of investment, acknowledging that scaling would be non-linear and reiterating a long-term value creation focus over near-term margin optimization.

What It Means for Investors Tracking the Broader Market

Tesla’s quarter fits a pattern that has now repeated across multiple high-profile earnings reports this season. TSMC beat estimates and fell. Netflix missed guidance by roughly 1% and lost $100 billion in value. Tesla beat revenue significantly, missed profit estimates badly, and confirmed a massive year of spending ahead, and the stock dropped 14% because the market is scrutinizing margin quality and cash generation with a level of skepticism it did not apply a year ago.

For companies at every market capitalization, the message from this earnings season is consistent. Strong top-line growth alone is no longer sufficient to satisfy investors who are increasingly focused on whether that growth translates into cash flow and margin durability. Companies funding aggressive expansion through negative free cash flow, regardless of how compelling the long-term vision, are being held to a higher standard of proof than they were earlier in this market cycle.

Release – As Ebola Death Toll Surpasses 930 Within Two Months, NanoViricides Has Applied to the DR Congo Regulatory Agency for Approval for a Phase II Clinical Trial of NV-387 Oral Gummies as a Treatment for Ebola

As Ebola Death Toll Surpasses 930 Within Two Months, NanoViricides Has Applied to the DR Congo Regulatory Agency for Approval for a Phase II Clinical Trial of NV-387 Oral Gummies as a Treatment for Ebola

Research News and Market Data on NNVC

Wednesday, 22 July 2026 08:30 AM

SHELTON, CT / ACCESS Newswire / July 22, 2026 / NanoViricides, Inc. (NYSE American:NNVC) (the “Company”), a clinical stage leader developing antiviral drugs that viruses cannot escape, announces that it has applied to the regulatory agency, ACOREP, for approval to begin a Phase II Clinical Trial of NV-387 Oral Gummies as a Treatment for the Current Bundibugyo Ebolavirus in the Democratic Republic of Congo (DRC).

NanoViricides has retained Om Sai Clinical Research Private Limited, India, as the CRO for this Phase II clinical trial for Ebola in DRC. Om Sai CRO has been instrumental in putting together a team with a renowned Principal Investigator and other renowned experts and with support from a well known University in the Ebola-affected region to lead and execute the clinical trial of NV-387 Oral Gummies as a Treatment for Ebolaviruses in DRC. The Principal Investigator has sent in the application for the clinical trial.

Om Sai is also the CRO leading the Company’s Phase II clinical trial of NV-387 Oral Gummies as a Treatment for Mpox in DRC.

“We believe NanoViricides is well positioned to provide an Oral Ebola treatment to save lives with our NV-387 Oral Gummies drug product that is already in place in DRC,” said Anil R. Diwan, PhD, President of the Company, adding, “This unique and revolutionary oral broad-spectrum antiviral drug deserves to be tested in a clinical trial more than any antibodies or other infusion drugs.” He further commented, “Viruses readily escape antibodies after exposure to them as we know from COVID-19. Infusions are not scalable to combat an outbreak of the size that is seen in DRC.”

NV-387 is the only orally active agent under consideration for clinical trial as a treatment of Ebola to the best of our knowledge. In an epidemic scenario in resource limited settings such as in DRC, oral drug is a highly advantageous feature.

Other treatments require infusions. Infusions are difficult to implement and also are not scalable in a large outbreak scenario if this Ebola virus outbreak continues to grow, as has been widely expected.

A clinical trial of Remdesivir infusion, an antibody cocktail MBP134 infusion, and MBP134 infusion plus Remdesivir infusion, has started as per WHO with first patient having received infusion of the antibody cocktail on July 2, 2026 1. Monoclonal antibodies are highly specific to a particular strain of the virus and usually are not very effective against variants of the same virus that arise in the field, nor are they effective against unrelated strains of the same virus.

The Company notes that NV-387 was previously found to be superior to Remdesivir in a lethal animal model of a viral disease. The Company believes this superiority of NV-387 is reasonably expected to extend to the current novel Bundibugyo ebolavirus strain.

Sufficient quantity of NV-387 Oral Gummies Drug Product for starting the clinical trial against Ebola is already available in DRC. This drug product was shipped to DRC for the ensuing Phase II clinical trial of NV-387 for the Treatment of Mpox and also to support a Phase II clinical trial for the Treatment of Ebola if approved by the regulatory agency.

The current 17th Ebola outbreak in DRC has already claimed over 930 lives, with close to 2,400 confirmed cases, in just two months since it was declared on May 15th, becoming the fastest growing Ebola outbreak to date, as per the WHO 2. This Ebola outbreak continues to increase in spread and is now present in five provinces in DRC. More concerning is the fact that over 80% of new cases are outside of known contact lists, leading to the projection that the extent of the outbreak is at least two times or more larger than the reported confirmed cases 3.

There is thus a tremendous urgency to validate a drug that works against this ebolavirus in clinical trials for minimizing further spread by treating patients and for saving lives.

There is no approved Treatment or Vaccine for the new variant of the Bundibugyo Ebolavirus (BDBV) that is causing the current rapidly expanding outbreak of the Ebolavirus Disease (EVD) in DR Congo. The rare Bundibugyo strain of Ebola virus causing the current outbreak appears to be its new variant, likely freshly introduced from some animal source 4, such as fruit bats.

“We believe NV-387 could be revolutionary in this fight against Ebola, if it is found to be effective,” said Anil R. Diwan, PhD, adding, “It is an oral drug, in contrast to others that are infusions. Thus evaluating if NV-387 treatment works is of paramount importance to combat this and future Ebola and Marburg outbreaks.”

NV-387 is a broad-spectrum antiviral that mimics the host-side features that the virus requires, and is likely to be effective against Ebola viruses because they use the same host-side feature mimicked by NV-387. It is highly unlikely that viruses can escape NV-387, because this drug mimics the features on host cells that the viruses continue to require even as they mutate or evolve in the field.

Additionally, NV-387 Oral Gummies is a drug product readily delivered orally. It does not even require swallowing effort or water, because it dissolves in the mouth by itself, simplifying delivery for even sick individuals with swallowing difficulties.

This oral delivery is an important feature that puts NV-387, a broad-spectrum antiviral, as being superior to the other approaches.

While there is currently minimal risk of Ebola in the USA, the CDC’s mathematical models suggested this Central African outbreak could grow to 10,000 to 20,000 cases and 2,000 to 4,000 deaths within just three months, rivaling the largest outbreak to date in 2014-2016 5. Unfortunately, the outbreak appears to be on track to realize these dire predictions.

The outbreak which was declared a Public Health Emergency of International Concern (“PHEIC”) by the WHO on May 17, 2026, continues to rapidly expand, outpacing containment efforts. The outbreak arose in a high traffic region bordering the Democratic Republic of Congo (DRC), with travel contacts to Uganda, and South Sudan and with 11 more nations in Africa at risk 6.

NV-387 is a broad-spectrum antiviral that mimics the host-side feature called heparan sulfate proteoglycan that over 90-95% of human pathogenic viruses require for infecting cells. No matter how much the virus changes in the field, it continues to use HSPG, and therefore it cannot escape the drug NV-387. In contrast, Remdesivir is a small molecule inhibitor of the viral RDRP enzyme needed for making copies of the viral genome, and the virus can possibly escape by small number of mutations.

All Ebola viruses utilize HSPG as the attachment receptor, followed by entry into the cell inside endosomes. The virus substantially dismantles in the endosome and hitches a cognate receptor called NPC1 to enter the cytoplasm where the next steps in its replication begin.

Thus there is a strong rationale that NV-387 could be highly effective against Ebola virus infections, not just Bundibugyo, but also the Sudan and other viruses for which there are no treatments.

NV-387 is available as an oral medication that has excellent stability at room temperature, enabling ease of transport, distribution, and delivery to patient. NV-387 oral gummies dissolve naturally in the mouth and do not require tablet swallowing, which is difficult for children, seniors, and also patients with sore throat.

If NV-387, as a broad-spectrum antiviral, is found to be effective against the Bundibugyo virus, it will likely be effective against all ebolaviruses and possibly all filoviruses; that would be a game changer for pandemic preparedness.

All previous anti-Ebola efforts have been focused on vaccines and antibodies7. This has led to approval of therapies that are specific to the Ebolavirus Zaire strain only, albeit with limited effectiveness. This leaves out all other filoviruses of consequence: Sudan, Marburg, and the more rare Bundibugyo with no treatment or vaccine.

The US Government is active in ensuring that suspected or confirmed ebolavirus cases do not enter the general population in the USA. To this end, travel from DRC has been restricted, with pre-travel quarantine requirements imposed, and suspect travelers are directed to screening at specific airports and may be further quarantined.

The case fatality rate of ebolaviruses has generally been around 50% in recent outbreaks, with improvements in care, including hydration therapy, corticosteroids, and other usual symptomatic treatments. Ebola viruses spread via bodily fluid secretions including fomites/sputum, as well as semen/genital secretions. Ebola virus can remain in survivors even as many as 965 days after the disease without symptoms, and can transmit through bodily secretions, suggesting possible latency. Many recent outbreaks have been ignited as a result of such reawakened-transmitted virus from a survivor. Sexual transmission was documented even as late as 482 days after disease. This persistence and possible latency of ebolavirus in immune-privileged organs (e.g. brain, eyes, gonads, where antibodies are not operative) makes it a uniquely serious threat for global transmission and sustained outbreaks.

An irony is that because of the high case fatality rate (CFR) approaching 50%, the spread of ebolavirus remains rather limited. If a variant emerges with a reduced CFR, say in the range of 5-15%, the potential threat of global pandemic from such an outbreak would increase substantially.

So far, BDBV has demonstrated variable CFR ranging from under 15% (in Uganda, 2026), to almost 40% (in DRC, based on current confirmed cases and fatalities numbers, as of July 18, 2026). Therefore, BDBV is of great concern as a potential pandemic disease. However, it is believed that ebolaviruses do not transmit via respiratory droplets or aerosols, and require extensive contact with bodily fluids of an infected person. In addition, within DRC and internationally, certain protective quarantine measures for travel from the outbreak areas have been implemented. Therefore, currently there is no apparent threat of a global pandemic.

With ever-increasing global travel, local outbreaks such as ebola can quickly travel far and wide potentially causing global pandemics, as was the case with COVID-19, if not caught in time. It is not feasible to produce a new vaccine and a new set of antibody drugs to combat every possible virus. Even if vaccines and antibodies are produced, the virus would escape by generating variants, as the world has witnessed during the COVID-19 pandemic.

“Only safe and effective broad-spectrum antiviral drugs that can effectively combat most viral infections will enable the world to combat viruses and defend the global population in the war against known and unknown nanoscopic enemies that are viruses,” commented Dr. Diwan, adding, “NV-387 is the only drug with such potential that is in clinical development today, to the best of our knowledge.”

ABOUT NANOVIRICIDES

NanoViricides, Inc. (the “Company”) (www.nanoviricides.com) is a clinical stage company that is creating special purpose nanomaterials for antiviral therapy. The Company’s novel nanoviricide™ class of drug candidates and the nanoviricide™ technology are based on intellectual property, technology and proprietary know-how of TheraCour Pharma, Inc. The Company has a Memorandum of Understanding with TheraCour for the development of drugs based on these technologies for all antiviral infections. The MoU does not include cancer and similar diseases that may have viral origin but require different kinds of treatments.

The Company has obtained broad, exclusive, sub-licensable, field licenses to drugs developed in several licensed fields from TheraCour Pharma, Inc. The Company’s business model is based on licensing technology from TheraCour Pharma Inc. for specific application verticals of specific viruses, as established at its foundation in 2005.

Our lead drug candidate is NV-387, a broad-spectrum antiviral drug that we plan to develop as a treatment of RSV, COVID, Long COVID, Influenza, and other respiratory viral infections, as well as MPOX/Smallpox infections. Our other advanced drug candidate is NV-HHV-1 for the treatment of Shingles. The Company cannot project an exact date for filing an IND for any of its drugs because of dependence on a number of external collaborators and consultants. The Company is currently focused on advancing NV-387 into Phase II human clinical trials.

NV-CoV-2 (API NV-387) is our nanoviricide drug candidate for COVID-19 that does not encapsulate remdesivir. NV-CoV-2-R is our other drug candidate for COVID-19 that is made up of NV-387 with remdesivir encapsulated within its polymeric micelles. The Company believes that since remdesivir is already US FDA approved, our drug candidate encapsulating remdesivir is likely to be an approvable drug, if safety is comparable. Remdesivir is developed by Gilead. The Company has developed both of its own drug candidates NV-CoV-2 and NV-CoV-2-R independently.

The Company is also developing drugs against a number of viral diseases including oral and genital Herpes, viral diseases of the eye including EKC and herpes keratitis, H1N1 swine flu, H5N1 bird flu, seasonal Influenza, HIV, Hepatitis C, Rabies, Dengue fever, and Ebola virus, among others. NanoViricides’ platform technology and programs are based on the TheraCour® nanomedicine technology of TheraCour, which TheraCour licenses from AllExcel. NanoViricides holds a worldwide exclusive perpetual license to this technology for several drugs with specific targeting mechanisms in perpetuity for the treatment of the following human viral diseases: Human Immunodeficiency Virus (HIV/AIDS), Hepatitis B Virus (HBV), Hepatitis C Virus (HCV), Rabies, Herpes Simplex Virus (HSV-1 and HSV-2), Varicella-Zoster Virus (VZV), Influenza and Asian Bird Flu Virus, Dengue viruses, Japanese Encephalitis virus, West Nile Virus, Ebola/Marburg viruses, and certain Coronaviruses. The Company intends to obtain a license for RSV, Poxviruses, and/or Enteroviruses if the initial research is successful. As is customary, the Company must state the risk factor that the path to typical drug development of any pharmaceutical product is extremely lengthy and requires substantial capital. As with any drug development efforts by any company, there can be no assurance at this time that any of the Company’s pharmaceutical candidates would show sufficient effectiveness and safety for human clinical development. Further, there can be no assurance at this time that successful results against coronavirus in our lab will lead to successful clinical trials or a successful pharmaceutical product.

This press release contains forward-looking statements that reflect the Company’s current expectation regarding future events. Actual events could differ materially and substantially from those projected herein and depend on a number of factors. Certain statements in this release, and other written or oral statements made by NanoViricides, Inc. are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. You should not place undue reliance on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and which could, and likely will, materially affect actual results, levels of activity, performance or achievements. The Company assumes no obligation to publicly update or revise these forward-looking statements for any reason, or to update the reasons actual results could differ materially from those anticipated in these forward-looking statements, even if new information becomes available in the future. Important factors that could cause actual results to differ materially from the company’s expectations include, but are not limited to, those factors that are disclosed under the heading “Risk Factors” and elsewhere in documents filed by the company from time to time with the United States Securities and Exchange Commission and other regulatory authorities. Although it is not possible to predict or identify all such factors, they may include the following: demonstration and proof of principle in preclinical trials that a nanoviricide is safe and effective; successful development of our product candidates; our ability to seek and obtain regulatory approvals, including with respect to the indications we are seeking; the successful commercialization of our product candidates; and market acceptance of our products.

The phrases “safety”, “effectiveness” and equivalent phrases as used in this press release refer to research findings including clinical trials as the customary research usage and do not indicate evaluation of safety or effectiveness by the US FDA.

FDA refers to US Food and Drug Administration. IND application refers to “Investigational New Drug” application. cGMP refers to current Good Manufacturing Practices. CMC refers to “Chemistry, Manufacture, and Controls”. CHMP refers to the Committee for Medicinal Products for Human Use, which is the European Medicines Agency’s (EMA) committee responsible for human medicines. API stands for “Active Pharmaceutical Ingredient”. WHO is the World Health Organization. R&D refers to Research and Development.

Contact:
NanoViricides, Inc.
[email protected]

Public Relations Contact:
[email protected]

Source: NanoViricides, Inc.

1 https://www.reuters.com/business/healthcare-pharmaceuticals/trial-bundibugyo-ebola-treatment-starts-drc-who-says-2026-07-02/

2 https://www.aljazeera.com/news/2026/7/20/ebola-death-toll-in-drc-surges-to-at-least-930-as-outbreak-gathers-pace

https://www.aljazeera.com/news/2026/7/16/ebola-spreading-more-quickly-in-drc-while-uganda-is-close-to-being-virus-free

3 https://www.msn.com/en-us/health/other/congos-ebola-outbreak-spreads-to-two-more-provinces/ar-AA27NkjT

4 b https://virological.org/t/initial-genomes-from-may-2026-bundibugyo-virus-disease-outbreak-in-the-democratic-republic-of-the-congo-and-uganda/1032

5 https://www.cdc.gov/media/releases/2026/update-on-ebola-outbreak-in-the-democratic-republic-of-the-congo-and-uganda-6-5-2026.html

6 https://www.forbes.com/sites/maryroeloffs/2026/05/25/african-health-officials-on-ebola-this-is-too-much-live-updates/

7 Substantial work was also performed to develop small chemical potentially broad-spectrum agents. Remdesivir was the only small chemical that entered the PALM clinical trials ca. 2018-2019 but failed to show effectiveness. Small chemicals are readily escaped by viruses often with just single mutations.

SOURCE: NanoViricides
Treasury Yields Hit a Two-Month High as Oil Surges Again

The bond market just erased weeks of progress in a single trading session. The 10-year Treasury yield climbed to 4.64% on Tuesday, its highest level since late May, while yields across the curve rose two to four basis points as a fresh surge in crude oil prices reignited concerns that the Federal Reserve may need to raise interest rates rather than hold them steady. The move wiped out the rally that followed this month’s softer-than-expected inflation report, and it arrives just one week before the Fed’s next policy meeting.

The timing could not be more consequential. Interest rate futures now show traders pricing in roughly a 20% probability of a rate hike at next week’s FOMC meeting, up from levels near zero just days ago. Fed Chair Kevin Warsh has repeatedly emphasized that inflation remains a central concern for the committee, a position echoed by other officials in recent weeks. Policymakers are now in their customary quiet period ahead of the meeting, meaning the bond market is left to interpret incoming data without any fresh guidance from the Fed itself.

What’s Driving the Reversal

The catalyst is energy prices. Brent crude climbed to $91 a barrel Tuesday as the US and Iran exchanged strikes for a tenth consecutive day, with mediators simultaneously working to revive a fragile truce between the two countries. The renewed military escalation has pushed oil prices back toward levels that stoke inflation concerns just as markets had begun pricing in relief following the ceasefire framework from earlier this summer.

Rates strategists have pointed to a technical dimension compounding the move. The 10-year yield broke back above the closely watched 4.60% level, and the two-year yield pushed through 4.20%, both thresholds that traders monitor closely for momentum signals. That technical breakout, combined with typically thinner summer trading conditions, appears to have amplified a move that was already underway on the back of rising energy prices.

Economic data released Tuesday added further support to the case for higher yields. The Philadelphia Fed’s services sector survey showed activity expanding for the first time since October 2024, reinforcing the picture of a resilient domestic economy that gives the Fed less reason to ease and potentially more reason to consider tightening if inflation pressures continue building.

Why This Matters for Small Caps

For companies in the sub-$2 billion market cap space, this reversal is a direct reminder of how quickly the rate environment can shift against smaller, more leveraged businesses. Small and microcap companies carry disproportionately more variable-rate debt than large cap peers, which means every basis point move in Treasury yields translates into real borrowing cost changes for the companies your audience tracks most closely.

The renewed Iran escalation also revives the two-sided energy trade that has defined 2026. Consumer-facing small caps in transportation, logistics, and retail face renewed margin pressure if oil continues climbing toward $95 or higher, while domestic energy producers benefit directly from sustained prices above $90. That dynamic has whipsawed throughout the year as the conflict has cycled through ceasefires, escalations, and renewed negotiations, and Tuesday’s move suggests the pattern is far from finished.

With the Fed entering its quiet period and next week’s meeting now carrying a nontrivial probability of a hike, the coming days will be defined by how oil prices and geopolitical developments evolve, rather than by any new signal from policymakers themselves. The bond market has already cast its vote. The Fed’s response comes next Wednesday.

Release – Kuya Silver Achieves Record Q2 Production at Bethania Mine, Increasing Quarterly Tonnage by 66% and Posts Record Monthly Silver Production in June

Corporate Logo

Research News and Market Data on KUYAF

All references to dollar amounts are references to U.S. Dollars, unless otherwise stated

Toronto, Ontario–(Newsfile Corp. – July 21, 2026) – Kuya Silver Corporation (CSE: KUYA) (OTCQB: KUYAF) (FSE: 6MR1) (the “Company” or “Kuya Silver“) is pleased to report record quarterly production and provide an operational update for the second quarter of 2026 at the Bethania silver project, which again delivered record daily and quarterly production rates as the ramp-up continued to show significant progress during the quarter. Although the short-term progress at Bethania is encouraging, preparations are underway for upward step change in production later this year as additional underground development is completed.

Operational Highlights

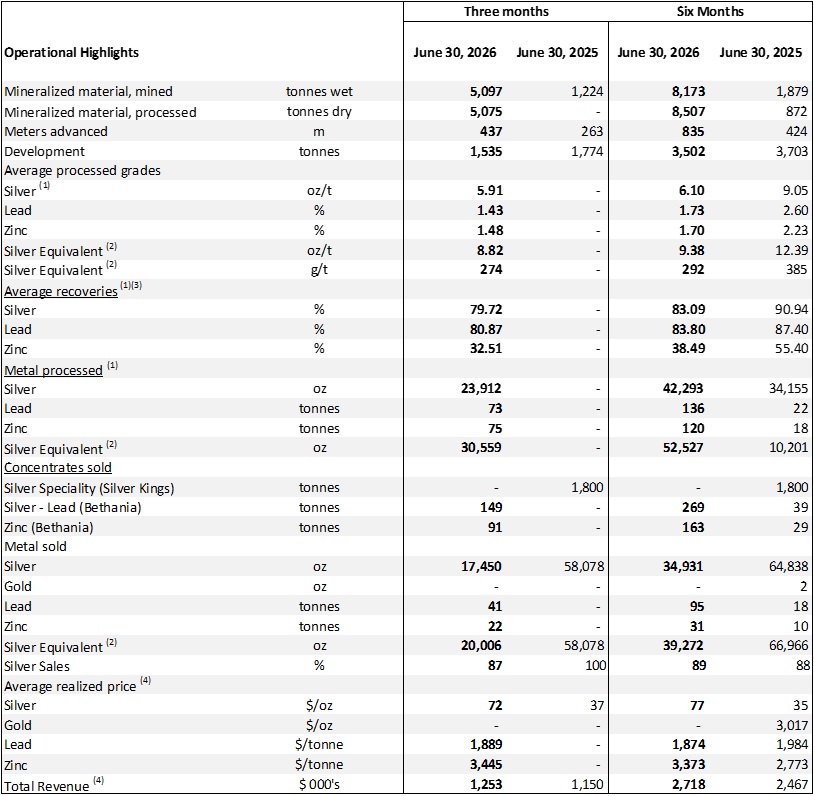
  • 5,097 metric tonnes of mineralized material mined at Bethania, a 66% increase quarter over quarter.
  • Record 23,912 oz silver (30,559 silver equivalent) processed during the quarter.
  • Record monthly production in June of 13,273 silver equivalent ounces as grades improved toward the end of the quarter.
  • Continued strong underground development with record 437 meters advanced while drilling and blasting 1,535 metric tonnes of development material to support the expansion of underground mining operations.
  • Silver production was 87% of the quarterly revenue from Bethania in Q2 with an average selling price of $72/oz.
  • The Company continued to develop partnerships with local contractors to accelerate our exploration and mine development objectives.

Kuya Silver Delivers Steady Progress at Bethania in Q2

Production of mineralized material at the Bethania Project totalled 5,097 metric tonnes, another quarterly record and a 66% improvement over Q1 2026 as production continues to steadily ramp up. Development activities achieved total of 437 metres of underground advancement and 1,535 tonnes of development material in the quarter. Kuya Silver achieved a record daily production of 124 tonnes and a record monthly production of 2,040 tonnes (68 tpd) in Q2, as well as a monthly record for silver production (13,273 oz Ag eq.) demonstrating that the Company’s methodical ramp-up process is generating positive results.

Silver recoveries averaged 79.7% during Q2 2026, directly reflecting the lower-grade development material and stope scheduling early in the quarter, which resulted in an average grade of 5.9 oz/t silver (8.8 oz/t or 274 g/t Ag equivalent). Mine sequencing optimizations implemented by the Kuya Silver team began delivering positive results mid-quarter. By June, silver grades increased to 6.66 oz/t exceeding management’s expectations, and silver recoveries improved to approximately 82%. Kuya Silver has previously achieved silver recoveries exceeding 90% when processing higher-grade batches, the Company expects recoveries to continue improving toward these levels as the mine reaches steady-state production. Furthermore, Kuya Silver has launched a metallurgical testing campaign to further optimize recoveries.

In addition, Kuya Silver approved the installation of a dual-car hoisting winch system at Bethania, expected to be commissioned in October 2026. This infrastructure upgrade is expected to improve efficiency of the mine’s ore extraction by enabling simultaneous haulage of two ore cars. This improvement will support the ongoing production ramp-up and provide flexibility and redundancy to materials handling as the Company advances the underground ramp project.

David Stein, Kuya Silver’s President and CEO, stated, “The ramp up strategy to produce at the Bethania mine while taking on ambitious mine development to expand production to our Phase 1 target of 350 tpd has allowed the Company to generate significant revenue and reduce our burn rate. The revenue from mining operations on top of the Company’s already strong balance sheet puts Kuya Silver in an excellent position, for the first time in our history, to deliver on its near-term production targets while at the same time expanding our exploration efforts to delineate more silver at the Bethania mine and the six other silver veins systems we control in the Bethania district.”


To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/5945/305919_kuya-silver.jpg

Table 1: Production highlights from the Bethania silver mine

(1) Information has been revised from amounts previously disclosed in the Company’s press release dated April 22, 2026. The revisions relate primarily to the correction of previously reported production metrics.

(2) prices for silver equivalent calculations use period ending spot prices and are as follows: June 30, 2026 $61/oz, lead $1,877/tonne, zinc$3,552/tonne Mar. 31 2026 silver $74/oz, lead $1,909/tonne, zinc$3,230/tonne June 30, 2025 $36/oz, lead $2,205/tonne, zinc$2,764/tonne Mar. 31 2026 silver $74/oz, lead $1,909/tonne Mar. 31, 2025 period; silver $34/oz, gold $3122.80/oz, lead $2,002/tonne, zinc $2,829/tonne.

(3) includes only payable recovery i.e. lead in the silver- lead concentrate and zinc in the zinc concentrate and silver in both concentrates.

(4) may include provisional settlements at the end of the period, net of treatment and refining costs.

Developing Partnerships with Local Mining and Exploration Contractors

As part of its strategy to sustain production growth and expand exploration efforts at the Bethania project, Kuya Silver is in the process of onboarding up to three specialized contractors to support development, drilling and operations at the project. The underground drilling contract to operate three drill rigs at Bethania has been formally awarded to Safasermin S.A.C., an experienced Peruvian drilling and exploration contractor, pending the finalization of contract details. All three rigs are initially planned to operate underground at the Bethania mine; however, surface drilling is expected to be added and become a significant component of the drilling program during the second half of 2026.

Following a competitive bidding process, comprehensive site visits and final negotiations, Kuya Silver has issued a formal Letter of Award to Minera Tauro S.A.C. to perform additional underground development at the Bethania mine. The contractor has officially confirmed its acceptance. Pending final execution of the contract, Minera Tauro is expected to mobilize in the coming weeks to accelerate underground development. This partnership will allow Kuya Silver’s in-house operations staff to focus on achieving greater production levels as the ramp-up continues.

Kuya Silver has also commenced portal development for the new internal ramp project and advanced a rigorous, competitive bidding process to shift the majority of the ramp development to a specialized mining contractor. Following comprehensive site visits and detailed evaluations of the project’s technical data and Terms of Reference, Kuya Silver has finalized the receipt of complete technical and economic proposals from four highly respected mining contractors. The Company is currently evaluating the final submissions and expects to formally award the contract and mobilize the selected contractor shortly.

In parallel, Kuya Silver has completed a geomechanical assessment and ground-support design study for the ramp project, characterizing rock-mass conditions and establishing the optimal reinforcement system for each section of the planned corridor. This engineering work enables the Company to move directly from contractor award to mobilization without delay. The preparatory work is expected to provide greater confidence in both the execution timeline and the cost profile of this critical infrastructure investment.

Christian Aramayo, Kuya Silver’s Chief Operating Officer, remarked, “At Bethania, our development decisions are driven by geology, not short-term price volatility. We are partnering with elite contractors and expanding our team to optimize development ahead of completing our Phase 1 ramp-up. We are committing to disciplined, high-return infrastructure, such as advancing our new internal ramp project, to unlock the deeper, and higher-grade vein structures within the Bethania system. Our strong balance sheet allows us to build our infrastructure the right way, ensuring we develop a safe and flexible operation, capable of maximizing the margin of every ounce we mine.”

Camila Plant Update

Kuya Silver continues to process its mineralized material at the Camila Plant. The Company announced an LOI on January 27, 2026 (see press release) and plans to make a separate announcement.

Support for Local Districts and Earthquake Relief Efforts

While Kuya Silver’s Bethania mine and infrastructure reported no measurable impact from the July 19th 5.5 magnitude earthquake in the Junin region, we recognize the severe toll this seismic event has taken on the surrounding towns and districts, particularly in the district of Chongos Bajo and the highly affected area of Chupuro. Kuya Silver extends its deepest sympathies to the people of Junin and is actively working to support recovery efforts.

As part of our commitment to our local workforce and neighboring populations, Kuya Silver is providing direct assistance to our employees who have family members in the affected areas. Furthermore, the Company is making direct donations to support the local emergency relief efforts.

For our partners, contractors, and stakeholders who wish to join these relief efforts, local institutions have established official donation reception centers to support the victims. Donations of drinking water, non-perishable food, warm clothing, and essential medicines are currently being received at the following collection point: Municipalidad Distrital de Chongos Bajo: Main municipal offices.

Quality Assurance and Quality Control

Quality assurance and quality control include two sampling procedures. Underground vein material from stopes are sampled to confirm vein grades and to reconcile against the mine model; and sampling of freshly mined material in stockpiles to determine dilution and the head grade that is sent to the processing plant.

Underground vein sampling was conducted systematically every 4 meters along the galleries. This involved excavating a narrow and continuous channel either parallel to the vein or perpendicular to its orientation. The entire volume of material excavated from the channel was collected as a sample.

Freshly mined material in the stockpiles and concentrate stockpiles were sampled using trenching, a method involving the excavation of narrow trenches perpendicular to the major axis of the pile. Trenches were systematically dug at regular intervals across all depths of the pile. The location of each trench was referenced to a topographic control point and recorded in the sampling log.

All material was carefully collected on plastic sheets, then pulverized at the mine site. The pulverized material was quartered, and one quarter was labeled and secured in vinyl sample bags. The samples were then transported to Dmtri I. Mendelejeff laboratory in Huancayo for processing using fire assay followed by atomic absorption spectroscopy (AAS).

All concentrate assay results are cross-checked against independent analyses conducted by the buyer. Furthermore, sample security protocols include sealed trucks for transporting run-of-mine (ROM) material and concentrate trucks with tamper-proof devices with safety seals, and a documented custody chain overseen by the mine superintendent (Bethania).

National Instrument 43-101 Disclosure

The technical content of this news release has been reviewed and approved by Mr. Kevin J. O’Connell, P.E., Independent Technical Advisor to of Kuya Silver and a Qualified Person as defined by National Instrument 43-101.

About Kuya Silver Corporation

Kuya Silver is a Canadian‐based, growth-oriented mining company with a focus on silver. Kuya Silver operates the Bethania silver mine in Peru, while developing district-scale silver projects in mining-friendly jurisdictions including Peru and Canada.

For more information, please contact:

David Stein, President and Chief Executive Officer
Telephone: (604) 398‐4493
[email protected]
www.kuyasilver.com

Reader Advisory

This news release contains statements that constitute “forward-looking information,” including statements regarding the plans, intentions, beliefs, and current expectations of the Company, its directors, or its officers with respect to the future business activities of the Company. The words “may,” “would,” “could,” “will,” “intend,” “plan,” “anticipate,” “believe,” “estimate,” “expect,” “must,” “next,” “propose,” “new,” “potential,” “prospective,” “target,” “future,” “verge,” “favorable,” “implications,” and “ongoing,” and similar expressions, as they relate to the Company or its management, are intended to identify such forward-looking information. Investors are cautioned that statements including forward-looking information are not guarantees of future business activities and involve risks and uncertainties, and that the Company’s future business activities may differ materially from those described in the forward-looking information as a result of various factors, including but not limited to fluctuations in market prices, successes of the operations of the Company, continued availability of capital and financing, and general economic, market, and business conditions. There can be no assurances that such forward-looking information will prove accurate, and therefore, readers are advised to rely on their own evaluation of the risks and uncertainties. The Company does not assume any obligation to update any forward-looking information except as required under the applicable securities laws.

Neither the Canadian Securities Exchange nor the Investment Industry Regulatory Organization of Canada accepts responsibility for the adequacy or accuracy of this release.

Corporate Logo

To view the source version of this press release, please visit https://www.newsfilecorp.com/release/305919