Noble Capital Markets, selected by NETSOL following an extensive evaluation of equity research providers, initiates coverage with an outperform rating and a $9.00 price target
ENCINO, Calif., Oct. 29, 2026 (GLOBE NEWSWIRE) — NETSOL Technologies, Inc. (Nasdaq: NTWK), a provider of AI-enabled solutions and services powering OEMs, dealerships and financial institutions to sell, finance and lease assets, today announced that Noble Capital Markets, Inc. has initiated company-sponsored equity research coverage of the company with an outperform rating and a $9.00 price target. NETSOL selected Noble following an extensive evaluation of equity research providers.
The initiation report, authored by Michael Kupinski, Director of Research and Senior Research Analyst, and Jacob Mutchler, Research Analyst, at Noble Capital Markets, Inc., points to NETSOL’s long-standing customer relationships and the ongoing replacement of aging lender architectures with the company’s Transcend Platform as key growth drivers, alongside the increasing shift toward subscription-based revenue as adoption of Transcend grows.
The coverage follows a record year for NETSOL. For fiscal 2026, the company reported revenue of $74.4 million, up 12.5% and above guidance, while operating income nearly doubled to $6.9 million and year-end cash rose 56.3% to $27.1 million.
“We’re building on a strong start to fiscal 2027 with a clear agenda ahead of us,” said Najeeb Ghauri, Founder and Chief Executive Officer of NETSOL Technologies, Inc. “As we work to make our performance more predictable and our story more visible to the market, broader research coverage matters. It gives investors a deeper, independent view of where NETSOL is headed and we look forward to the wider reach Noble’s coverage will bring.”
About NETSOL Technologies NETSOL Technologies delivers state-of-the-art solutions for asset finance, leasing and digital automotive retail, serving automotive and equipment OEMs, dealerships, auto captives and financial institutions across over 30 countries. Since its inception in 1997, NETSOL has been at the cutting edge of technology, pioneering innovations with its asset finance solutions, and today leverages advanced AI and cloud services to meet the complex needs of the global market. Renowned for its deep industry expertise, customer-centric approach and commitment to excellence, NETSOL fosters strong partnerships with its customers, ensuring their success in an ever-evolving landscape. With a rich history of innovation, ethical business practices and a focus on sustainability, NETSOL is dedicated to empowering businesses worldwide, securing its position as the trusted partner for leading firms around the globe.
Forward-Looking Statements This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the company’s products and services, expectations for future operations, and other statements that are not historical facts. These forward-looking statements may be identified by terminology such as “expects,” “anticipates,” “believes,” “intends,” “plans,” “projects,” “targets,” and similar expressions. These statements are not guarantees of future performance and are subject to a number of risks, uncertainties, and assumptions that are difficult to predict. Factors that could cause actual results to differ materially include, but are not limited to, the timing of customer go-lives and contract renewals, the rate of adoption of AI-enabled product capabilities, foreign currency volatility, and other factors discussed in NETSOL’s most recent Annual Report on Form 10-K and subsequent Quarterly Reports on Form 10-Q filed with the U.S. Securities and Exchange Commission. Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date hereof. NETSOL undertakes no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, or otherwise.
BOCA RATON, Fla.–(BUSINESS WIRE)–Oct. 29, 2026– The GEO Group, Inc. (NYSE: GEO) (“GEO” or the “Company”) announced today that it has entered into a new 10-year management contract for the continued provision of support services at the GEO-owned 1,635-bed Northwest ICE Processing Center located in Tacoma, Washington.
Support services at the Northwest ICE Processing Center are expected to include security, maintenance, and food services, as well as access to recreational amenities, medical care, and transportation services. The new 10-year contract is expected to generate approximately $140 million in annual revenues for GEO and continue through October 27, 2036.
George C. Zoley, GEO’s Chairman, Chief Executive Officer and Founder, said, “The Northwest ICE Processing Center plays an important role in helping meet the need for federal immigration processing center bedspace. We are proud of our 40-year public-private partnership with ICE, and we stand ready to continue to assist the federal government in meeting its immigration enforcement priorities.”
About The GEO Group
The GEO Group, Inc. (NYSE: GEO) is a leading diversified government service provider, specializing in design, financing, development, and support services for secure facilities, processing centers, and community reentry centers in the United States, Australia, South Africa, and the United Kingdom. GEO’s diversified services include enhanced in-custody rehabilitation and post-release support through the award-winning GEO Continuum of Care®, secure transportation, electronic monitoring, community-based programs, and correctional health and mental health care. GEO’s worldwide operations include the ownership and/or delivery of support services for 97 facilities totaling approximately 76,000 beds, including idle facilities and projects under development, with a workforce of up to approximately 20,000 employees.
Use of forward-looking statements
This news release may contain “forward-looking statements” within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended, and the U.S. Private Securities Litigation Reform Act of 1995. Readers are cautioned not to place undue reliance on these forward-looking statements and any such forward-looking statements are qualified in their entirety by reference to the cautionary statements and risk factors contained in GEO’s filings with the U.S. Securities and Exchange Commission including its Form 10-K, 10-Q and 8-K reports. All forward-looking statements speak only as of the date of this news release and are based on current expectations and involve a number of assumptions, risks and uncertainties that could cause the actual results to differ materially from such forward-looking statements. Readers are strongly encouraged to read the full cautionary statements and risk factors contained in GEO’s filings with the U.S. Securities and Exchange Commission, including those referenced above. GEO disclaims any obligation to update or revise any forward-looking statements, except as required by law.
NORWALK, Conn.–(BUSINESS WIRE)–Oct. 29, 2026– Xerox Holdings Corporation (NASDAQ: XRX) today announced an exchange transaction (the “Exchange Transaction”) that will address approximately $174 million of its senior notes due in 2028 (the “2028 Notes”), extending those maturities to 2030 while reducing overall debt principal and preserving cash. The transaction represents another step in the company’s ongoing efforts to strengthen its balance sheet and reduce leverage.
“Following the open market purchases earlier this year, this transaction is yet another step that we’ve taken to proactively address our upcoming maturities. It addresses more than 30% of our outstanding 2028 Notes while reducing debt principal and preserving liquidity to support the business,” said Chuck Butler, chief financial officer at Xerox. “We appreciate the constructive partnership with our largest lenders and remain focused on strengthening our balance sheet and reducing leverage.”
Transaction Details The Exchange Transaction is anchored by an ad hoc group of first lien lenders and provides for holders of approximately $174 million of 2028 Notes to exchange their notes for a combination of Xerox Corporation’s newly issued first lien senior secured notes due October 2030 (the “New First Lien Notes”), and shares of Xerox common stock.
For each $1,000 principal amount of 2028 Notes exchanged, participating holders will receive $690 principal amount of New First Lien Notes and $60 in value of Xerox common stock (based on a discount to the pre-announcement VWAP), or additional New First Lien Notes in certain limited circumstances.
The New First Lien Notes will be largely identical to the existing first lien notes due October 2030 and will rank pari passu with the company’s existing first lien debt. The transaction is structured as a cashless exchange, other than transaction expenses, and is expected to keep cash interest approximately neutral. It is expected to close on or about November 13, 2026, subject to certain limited conditions.
Upon completion, the transaction is expected to reduce overall debt principal by approximately $53 million and extend $121 million of debt maturing in 2028 to 2030.
This communication is for informational purposes only and does not constitute an offer to sell, or a solicitation of an offer to buy, any security and does not constitute an offer, solicitation or sale of any security in any jurisdiction in which such offer, solicitation or sale would be unlawful.
Advisors Lazard is serving as financial advisor to Xerox and Simpson Thacher & Bartlett LLP is serving as legal advisor. Moelis & Company LLC is serving as financial advisor to the ad hoc group of first lien lenders and Gibson, Dunn & Crutcher LLP is serving as legal advisor.
Forward-Looking Statement This presentation and other written or oral statements made from time to time by management contain “forward-looking statements” as defined in the Private Securities Litigation Reform Act of 1995 and involve certain risks and uncertainties. The words “anticipate”, “believe”, “estimate”, “expect”, “intend”, “will”, “would”, “could”, “can”, “should”, “targeting”, “projecting”, “driving”, “future”, “plan”, “predict”, “may” and similar expressions are intended to identify forward-looking statements. The Company’s actual results may differ significantly from the results discussed in the forward-looking statements. These statements reflect management’s current beliefs and assumptions and are subject to a number of other factors that may cause actual results to differ materially.
Such factors include but are not limited to: applicable market conditions; global macroeconomic conditions, including inflation, slower growth or recession, delays or disruptions in the global supply chain, higher interest rates, and wars and other conflicts, including the current conflict between Russia and Ukraine; our ability to succeed in a competitive environment, including by developing new products and service offerings and preserving our existing products and market share as well as repositioning our business in the face of customer preference, technological, and other change, such as evolving return-to-office and hybrid working trends; failure of our customers, vendors, and logistics partners to perform their contractual obligations to us; our ability to attract, train, and retain key personnel; execution risks around our Reinvention; the risk of breaches of our security systems due to cyber, malware, or other intentional attacks that could expose us to liability, litigation, regulatory action or damage our reputation; our ability to obtain adequate pricing for our products and services and to maintain and improve our cost structure; changes in economic and political conditions, licensing requirements, and tax laws in the United States and in the foreign countries in which we do business; the risk that multi-year contracts with governmental entities could be terminated prior to the end of the contract term and that civil or criminal penalties and administrative sanctions could be imposed on us if we fail to comply with the terms of such contracts and applicable law; interest rates, cost of capital, and access to credit markets; risks related to our indebtedness; the imposition of new or incremental trade protection measures such as tariffs and import or export restrictions; funding requirements associated with our employee pension and retiree health benefit plans; changes in foreign currency exchange rates; the risk that we may be subject to new or heightened regulatory or operation risks as a result of our, or third parties,’ use or anticipated use of artificial intelligence technologies; the risk that our operations and products may not comply with applicable worldwide regulatory requirements, particularly environmental regulations and directives and anti-corruption laws; the outcome of litigation and regulatory proceedings to which we may be a party; laws, regulations, international agreements and other initiatives to limit greenhouse gas emissions or relating to climate change, as well as the physical effects of climate change; our ability to successfully integrate the Lexmark business and realize the anticipated benefits thereof, including expected synergies; and other factors that are set forth from time to time in the Company’s Securities and Exchange Commission filings, including the combined Annual Report on Form 10-K of Xerox Holdings and Xerox Corporation.
These forward-looking statements speak only as of the date hereof or of the date to which they refer, and the Company assumes no obligation to update or revise any forward-looking statements as a result of new information or future events or developments, except as required by law.
About Xerox Holdings Corporation (NASDAQ: XRX) Xerox is a global technology company with more than 120 years of innovation leadership. We design, manufacture, deliver, and support print, IT, and digital services for nearly 200,000 clients worldwide. Our integrated, AI-powered portfolio includes managed and production print, document management, workflow automation, cybersecurity, cloud managed services, IT infrastructure, and collaboration technology. Serving clients from growing SMBs to 90 percent of the Fortune 500, Xerox supports leading healthcare, government, financial services, education, legal, retail, and commercial organizations. Through direct sales and a global network of channel partners, we deliver the technology, expertise, and support organizations need to operate efficiently, securely, and at scale.
Alphabet (NASDAQ: GOOGL), the parent company of Google, suffered a historic stock market selloff Thursday, October 29, with shares plunging approximately 12% to 13% as investors reacted to disappointing advertising revenue, soaring artificial intelligence spending, and an unexpected deterioration in free cash flow.
The decline put nearly $500 billion in Alphabet’s market capitalization at risk, potentially marking the largest single-day loss in the company’s history and one of the biggest market-value declines ever recorded by a publicly traded U.S. company.
The selloff followed Alphabet’s third-quarter earnings report Wednesday evening, which revealed a sharp contrast between extraordinary growth in its cloud computing business and mounting financial pressure from its aggressive AI infrastructure expansion.
Alphabet reported quarterly revenue of $127.6 billion, representing approximately 25% year-over-year growth but falling short of Wall Street expectations of $128.2 billion. The company’s adjusted earnings per share of $2.67 also missed analysts’ estimates of $3.02.
A major concern centered on Google’s core advertising business, which remains a critical source of revenue and profitability. Search revenue increased approximately 12% to $63.4 billion, below analysts’ expectations of roughly $65 billion.
Although double-digit growth would ordinarily represent a strong performance, investors have become increasingly concerned that generative AI could disrupt Google’s traditional search advertising model.
As more users turn to conversational AI tools and AI-generated search results, Google faces the challenge of maintaining advertising revenue while adapting its products to changing consumer behavior.
Company executives acknowledged that the growing adoption of AI-powered search experiences contributed to slower advertising growth. Monetizing conversational search remains an evolving process, raising questions about how quickly Google can translate AI engagement into revenue.
Meanwhile, Alphabet’s investment in AI infrastructure is accelerating at an extraordinary pace.
The company reported approximately $51.3 billion in capital expenditures during the third quarter, reflecting heavy investment in data centers, computing infrastructure, and specialized AI chips.
Those expenses contributed to negative free cash flow of approximately $9.1 billion, compared with expectations that the company would come close to breaking even.
Alphabet now expects capital expenditures of $195 billion to $205 billion for 2026, with spending projected to increase further in 2027.
The financial impact is particularly notable because Google has historically generated substantial cash flow from its search advertising operations. The shift toward negative free cash flow highlights the growing cost of competing in the global AI infrastructure race.
Despite the market’s negative reaction, Alphabet reported significant progress in cloud computing.
Google Cloud revenue more than doubled to approximately $30.7 billion during the quarter, exceeding analyst expectations as enterprise customers increased spending on AI infrastructure and cloud services.
The company also reported a cloud backlog of approximately $561 billion, reflecting substantial contracted demand for future services.
Google’s Gemini AI application surpassed one billion users, demonstrating the company’s ability to attract consumers to its artificial intelligence ecosystem.
However, the market’s reaction suggests that investors are increasingly prioritizing profitability, capital efficiency, and the ability to generate cash from AI investments rather than rewarding revenue growth alone.
The concerns extend beyond Alphabet. Microsoft, Amazon, Meta Platforms, and other major technology companies are collectively investing hundreds of billions of dollars in AI infrastructure, creating growing scrutiny over whether these expenditures will deliver sufficient financial returns.
Alphabet’s decline also weighed heavily on broader technology stocks, with the Nasdaq Composite falling more than 1% during Thursday’s trading session.
For smaller technology companies and emerging AI businesses, the selloff illustrates how investor expectations are shifting toward measurable financial performance. Companies seeking capital to develop AI products may face greater pressure to demonstrate sustainable revenue, competitive differentiation, and a credible path to profitability.
The decline also raises questions about valuations across the technology sector, where expectations for continued AI growth have supported substantial stock market gains.
Alphabet’s latest results reveal the difficult balance facing technology leaders: investing aggressively enough to remain competitive in artificial intelligence while protecting the profitability of established businesses.
As investors evaluate the next wave of technology earnings, Alphabet’s historic selloff could become a defining moment in the market’s reassessment of AI spending and the financial returns required to justify it.
Revenue Trajectory and Adjusted1Operating Income Improve; Higher Input Costs and Market Headwinds Weigh on Full-Year Outlook
Financial Summary
Q3 2026
Revenue of $1.87 billion, down 4.7 percent, or down 4.5 percent in constant currency1.
GAAP net (loss)2 of $(1,015) million, or $(7.73) per share, down $255 million or $1.72 per share, year-over-year, respectively.
Adjusted1 net income of $7 million, or $0.02 per share, down $20 million or $0.18 per share, year-over-year, respectively.
Adjusted1 operating income of $124 million, up $59 million year-over-year.
Adjusted1 operating margin of 6.6 percent, up 330 basis points year-over-year.
Operating cash flow of $30 million, down $86 million year-over year.
Free cash flow1 of $7 million, down $81 million year-over-year.
NORWALK, Conn.–(BUSINESS WIRE)–Oct. 29, 2026– Xerox Holdings Corporation (NASDAQ: XRX) today announced its 2026 third-quarter results.
“This quarter, Print equipment revenue grew and adjusted operating margin doubled as we continued to execute against our three priorities: stabilize revenue, increase profitability and reduce leverage,” said Louie Pastor, chief executive officer at Xerox. “We are seeing results in the areas where we have focused our execution, but the headwinds affecting our outlook have intensified, creating greater near-term pressure than we expected. As a result, we are lowering our full-year adjusted operating income and free cash flow guidance. We’re responding with actions and cost measures to mitigate these pressures, improve profitability, and preserve cash, including the suspension of our common and preferred dividends, while maintaining our focus on reducing debt.”
Progress Against Strategic Priorities
Q3 2026
Double-digit equipment revenue growth in both Entry and Production
Announced three new Production devices at PRINTING United Expo, as well as a partnership with Xeikon to enter the Packaging and Labels market
$8 million non-cash debt reduction through our warrant program, retiring 2030 convertible notes
Announced Exchange of $174 million in 5.50% 2028 Senior Notes for:
$121 million of 10.25% 2030 Senior Secured Notes
$9 million in equity
Third-Quarter Key Financial Results
(in millions, except per share data)
Q3 2026
Q3 2025
B/(W)YOY
Revenue
$1,868
$1,961
(4.7)% AC(4.5)% CC1
Gross Profit
$545
$445
$100
Gross Margin
29.2%
22.7%
650 bps
RD&E %
3.0%
3.8%
80 bps
SAG %
20.0%
24.3%
430 bps
Pre-Tax (Loss)
$(1,006)
$(300)
$(706)
Pre-Tax (Loss) Margin
(53.9)%
(15.3)%
NM
Gross Profit – Adjusted1
$551
$566
$(15)
Gross Margin – Adjusted1
29.5%
28.9%
60 bps
Operating Income – Adjusted1
$124
$65
$59
Operating Income Margin – Adjusted1
6.6%
3.3%
330 bps
GAAP Diluted (Loss) per Share2
$(7.73)
$(6.01)
$(1.72)
Diluted Earnings Per Share – Adjusted1
$0.02
$0.20
$(0.18)
Third-Quarter Segment Results
(in millions)
Q3 2026
Q3 2025
B/(W)YOY
Revenue
Print and Other
$1,688
$1,739
(2.9)%
IT Solutions
187
226
(17.3)%
Intersegment Elimination3
(7)
(4)
NM
Total Revenue
$1,868
$1,961
(4.7)%
Profit
Print and Other
$136
$64
112.5%
IT Solutions
8
18
(55.6)%
Corporate Other4
(20)
(17)
17.6%
Total Profit
$124
$65
90.8%
_____________
1.
Refer to the “Non-GAAP Financial Measures” section of this release for a discussion of these non-GAAP measures and their reconciliation to the reported GAAP measures.
2.
Third quarter 2026 includes an after-tax non-cash goodwill impairment charge of $955 million ($959 million pre-tax), or $6.87 per diluted share. Third quarter 2025 includes an inventory-related purchase accounting adjustment, related to the acquisition of Lexmark, of $85 million ($102 million pre-tax), or $0.67 per diluted share, as well as a tax expense charge of $467 million, or $3.69 per diluted share, related to the establishment of a valuation allowance against certain deferred tax assets to reflect their realizability.
3.
Reflects primarily IT hardware, software solutions and services, sold by the IT Solutions segment to the Print and Other segment.
4.
Corporate Other reflects certain administrative and general expenses, which primarily relate to corporate functions, and are not allocated to either of our reportable segments.
Updated 2026 Guidance
Revenue: Approximately $7.6 billion
Adjusted1,2 Operating Income: $450-475 million
Free Cash Flow1,2: $50-100 million
Non-GAAP Measures
This release refers to the following non-GAAP financial measures:
Adjusted1 EPS excludes Restructuring and related costs, net, Amortization of intangible assets, non-service retirement-related costs, Goodwill impairment charge, and other discrete adjustments from GAAP EPS, as applicable.
Adjusted1 operating income and margin, which exclude the EPS adjustments noted above, except the tax expense charge related to the establishment of a valuation allowance against certain deferred tax assets, as well as the remainder of Other expenses (income), net from pre-tax (loss) and margin.
Constant currency1 (CC) revenue change, which excludes the effects of currency translation.
Free cash flow 1, which is operating cash flow less capital expenditures.
_____________
1.
Refer to the “Non-GAAP Financial Measures” section of this release for a discussion of these non-GAAP measures and their reconciliation to the reported GAAP measures.
2.
Adjusted operating income guidance reflects a benefit from the recognition of a $105 million pre-tax IEEPA tariff receivable associated with the recent Supreme Court ruling on IEEPA tariffs. The benefit to free cash flow guidance, resulting from Xerox’s sale of the IEEPA tariff receivable to a third party, is $80 million.
Forward-Looking Statement
This presentation and other written or oral statements made from time to time by management contain “forward-looking statements” as defined in the Private Securities Litigation Reform Act of 1995 and involve certain risks and uncertainties. The words “anticipate”, “believe”, “estimate”, “expect”, “intend”, “will”, “would”, “could”, “can”, “should”, “targeting”, “projecting”, “driving”, “future”, “plan”, “predict”, “may” and similar expressions are intended to identify forward-looking statements. The Company’s actual results may differ significantly from the results discussed in the forward-looking statements. These statements reflect management’s current beliefs and assumptions and are subject to a number of other factors that may cause actual results to differ materially.
Such factors include but are not limited to: applicable market conditions; global macroeconomic conditions, including inflation, slower growth or recession, delays or disruptions in the global supply chain, higher interest rates, and wars and other conflicts, including the current conflict between Russia and Ukraine; our ability to succeed in a competitive environment, including by developing new products and service offerings and preserving our existing products and market share as well as repositioning our business in the face of customer preference, technological, and other change, such as evolving return-to-office and hybrid working trends; failure of our customers, vendors, and logistics partners to perform their contractual obligations to us; our ability to attract, train, and retain key personnel; execution risks around our Reinvention; the risk of breaches of our security systems due to cyber, malware, or other intentional attacks that could expose us to liability, litigation, regulatory action or damage our reputation; our ability to obtain adequate pricing for our products and services and to maintain and improve our cost structure; changes in economic and political conditions, licensing requirements, and tax laws in the United States and in the foreign countries in which we do business; the risk that multi-year contracts with governmental entities could be terminated prior to the end of the contract term and that civil or criminal penalties and administrative sanctions could be imposed on us if we fail to comply with the terms of such contracts and applicable law; interest rates, cost of capital, and access to credit markets; risks related to our indebtedness; the imposition of new or incremental trade protection measures such as tariffs and import or export restrictions; funding requirements associated with our employee pension and retiree health benefit plans; changes in foreign currency exchange rates; the risk that we may be subject to new or heightened regulatory or operation risks as a result of our, or third parties,’ use or anticipated use of artificial intelligence technologies; the risk that our operations and products may not comply with applicable worldwide regulatory requirements, particularly environmental regulations and directives and anti-corruption laws; the outcome of litigation and regulatory proceedings to which we may be a party; laws, regulations, international agreements and other initiatives to limit greenhouse gas emissions or relating to climate change, as well as the physical effects of climate change; our ability to successfully integrate the Lexmark business and realize the anticipated benefits thereof, including expected synergies; and other factors that are set forth from time to time in the Company’s Securities and Exchange Commission filings, including the combined Annual Report on Form 10-K of Xerox Holdings and Xerox Corporation.
These forward-looking statements speak only as of the date hereof or of the date to which they refer, and the Company assumes no obligation to update or revise any forward-looking statements as a result of new information or future events or developments, except as required by law.
WEST CHICAGO, Ill., Oct. 29, 2026 /PRNewswire/ — Titan International, Inc. (NYSE: TWI) (“Titan” or the “Company”), a leading global manufacturer of off-highway wheels, tires, assemblies, and undercarriage products, today reported financial results for the third quarter ended September 30, 2026. The full earnings release including a reconciliation of GAAP to Non-GAAP figures can be found in the investor relations section of the Company’s website at https://ir.titan-intl.com/news-and-events/news-releases/default.aspx.
Q3 2026 Key Figures for Continuing Operations
Revenues of $335 million ($454 million, inclusive of discontinued operations)
Gross margin of 14.7%
Adjusted EBITDA of $16 million ($28 million, inclusive of discontinued operations)
Generated Free Cash Flows of $23 million
Paul Reitz, President and Chief Executive Officer, commented, “Inclusive of ITM, which is reported in our Q3 financials as discontinued operations, our revenues for the quarter of $454 million were above the midpoint of our guidance while Adjusted EBITDA of $28 million was also within our guidance range. Our One Stop Shop strategy enabled us to deliver solid financial results despite current market conditions. Focusing on our reported results which exclude ITM from continuing operations, EMC sales grew 5% with improved margins during the quarter while Consumer segment sales were down 3% albeit versus an abnormally strong Q3 last year. Our Ag segment declined 12% as farmers remained on the sidelines due to high interest rates, diesel and fertilizer costs and other macro concerns that continue to impact overall economic activity.”
Mr. Reitz continued, “Toward the end of the quarter we announced an agreement to sell our ITM business. As we noted in that announcement, our Board of Directors believe that the sale of ITM empowers Titan to focus on growing our global wheel and tire businesses while also utilizing the proceeds to reduce our debt. ITM is a high-quality business but has limited synergies relative to our wheel and tire operations. As we continue to execute our strategic plan, we expect to energize our value creation by extending our leadership position in our wheel and tire businesses and intend to utilize proceeds from the transaction to support that strategy. We are progressing through the regulatory process and continue to expect the transaction to close in early January 2027.”
Mr. Reitz concluded, “Macro uncertainty along with elevated interest rates, fuel and fertilizer costs continue to weigh on activity in our end markets, which has been the story throughout 2026. At the same time, we believe the building blocks for a resumption of growth are present. An aging machinery fleet continues to create pent-up replacement demand, while wheel and tire inventories across our distribution channels remain at relatively low levels. Although corn prices are down from recent highs in August, they are still above year-ago levels, as are soybean prices, which bode well for farmer incomes. I am confident that a resumption in end market demand will flow through to suppliers such as Titan rather quickly. We have also strengthened our strategic position with customers through innovative products and solutions, which we expect will support growth despite challenging market conditions.”
Third Quarter and Fiscal Year 2026 Outlook
Tony Eheli, Chief Financial Officer added, “Inclusive of ITM operations, we are updating our fourth quarter and full-year guidance to reflect the effect of current market conditions. We currently expect fourth quarter sales of between $410 million and $430 million, and Adjusted EBITDA of between break even and $7 million. Our current expectations for FY 2026 are for sales between $1.85 and $1.87 billion and Adjusted EBITDA of between $91 million and $101 million.”
Results for the 2026 third quarter and nine months reflect the classification of the Company’s Italtractor ITM undercarriage business (“ITM”) as discontinued operations in connection with its previously announced pending sale to USCO S.p.A. (“USCO”). The transaction is scheduled to close in January 2027.
About Titan
Titan International, Inc. (NYSE: TWI) is a leading global manufacturer of off-highway wheels, tires, assemblies, and undercarriage products. Headquartered in West Chicago, Illinois, the Company globally produces a broad range of products to meet the specifications of original equipment manufacturers (OEMs) and aftermarket customers in the agricultural, earthmoving/construction, and consumer markets. For more information, visit www.titan-intl.com.
Safe Harbor Statement
This press release contains forward-looking statements. These forward-looking statements are covered by the safe harbor for “forward-looking statements” provided by the Private Securities Litigation Reform Act of 1995. The words “believe,” “expect,” “anticipate,” “plan,” “would,” “could,” “potential,” “may,” “will,” and other similar expressions are intended to identify forward-looking statements, which are generally not historical in nature. These forward-looking statements are based on our current expectations and beliefs concerning future developments and their potential effect on us. Although we believe the assumptions upon which these forward-looking statements are based are reasonable, these assumptions are subject to significant risks and uncertainties, and are subject to change based on various factors, some of which are beyond Titan International, Inc.’s control. As a result, any of these assumptions could prove to be inaccurate and the forward-looking statements based on these assumptions could be incorrect. The matters discussed in these forward-looking statements are subject to risks, uncertainties, and other factors that could cause actual results and trends to differ materially from those made, projected, or implied in or by the forward-looking statements depending on a variety of uncertainties or other factors including, but not limited to, the effect of a recession on the Company and its customers and suppliers; changes in the Company’s end-user markets into which the Company sells its products as a result of domestic and world economic or regulatory influences or otherwise; changes in the marketplace, including new products and pricing changes by the Company’s competitors; the Company’s ability to maintain satisfactory labor relations; unfavorable outcomes of legal proceedings; the Company’s ability to comply with current or future regulations applicable to the Company’s business and the industry in which it competes or any actions taken or orders issued by regulatory authorities; availability and price of raw materials; levels of operating efficiencies; the effects of the Company’s indebtedness and its compliance with the terms thereof; changes in the interest rate environment and their effects on the Company’s outstanding indebtedness; unfavorable product liability and warranty claims; actions of domestic and foreign governments, including the imposition of additional tariffs; geopolitical and economic uncertainties relating to the countries in which the Company operates or does business; risks associated with acquisitions, including difficulty in integrating operations and personnel, disruption of ongoing business, and increased expenses; results of investments; the effects of potential processes to explore various strategic transactions, including potential dispositions; fluctuations in currency translations; risks associated with environmental laws and regulations; risks relating to our manufacturing facilities, including that any of our material facilities may become inoperable; risks relating to financial reporting, internal controls, tax accounting, and information systems; and the other risks and factors detailed in the Company’s periodic reports filed with the Securities and Exchange Commission, including the disclosures under “Risk Factors” in those reports. These forward-looking statements are made only as of the date hereof. The Company cautions that any forward-looking statements included in this press release are subject to a number of risks and uncertainties, and the Company undertakes no obligation to publicly update or revise any forward-looking statements, whether as a result of new information, changed circumstances or future events, or for any other reason, except as required by law.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Richard Magnusen, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Initiating coverage with an Outperform rating. Bimergen Energy develops, finances, owns, and operates utility-scale battery energy storage systems (BESS). The company has assembled 23 development projects representing approximately 2.0 gigawatts (GW) of capacity across several regional U.S. power markets. We believe the portfolio provides a range of options to unlock value as Bimergen advances projects through development, monetization, financing, construction, and ultimately commercial operation.
Multiple paths to value creation. Bimergen can monetize projects by retaining minority interests alongside strategic partners or owning completed assets and generate recurring operating revenue. The company has begun demonstrating this flexibility through the sale of the 100-megawatt (MW) Redbird project and two smaller ERCOT projects to Frontier Power while retaining a 7.5% economic interest. We believe this transaction provides initial evidence that development-stage projects can create tangible value before commercial operation.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Quarterly Overview. NN delivered a strong 3Q26, significantly exceeding our expectations for sales, adjusted EBITDA, and adjusted net income. NN’s new business program has continued to outperform expectations, with the Company now winning more than 1 new program per day. And NN’s 5 Pillar growth program is working well, with the Company investing its time and resources to strategically pivot the portfolio to high-growth, high-value markets and products.
3Q26 Numbers. Net sales for 3Q26 were $131.1 million, an increase of 26.2% compared to net sales of $103.9 million for 3Q25. The increase was primarily driven by higher selling prices, higher volumes, and favorable foreign exchange effects. Adjusted EBITDA was $18.5 million, an increase of 49.7% compared to adjusted EBITDA of $12.4 million for the same period in 2025. Adjusted net income was $5.3 million, or $0.07 per diluted common share, an increase of $5.6 million or $0.08 per diluted common share, y-o-y.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
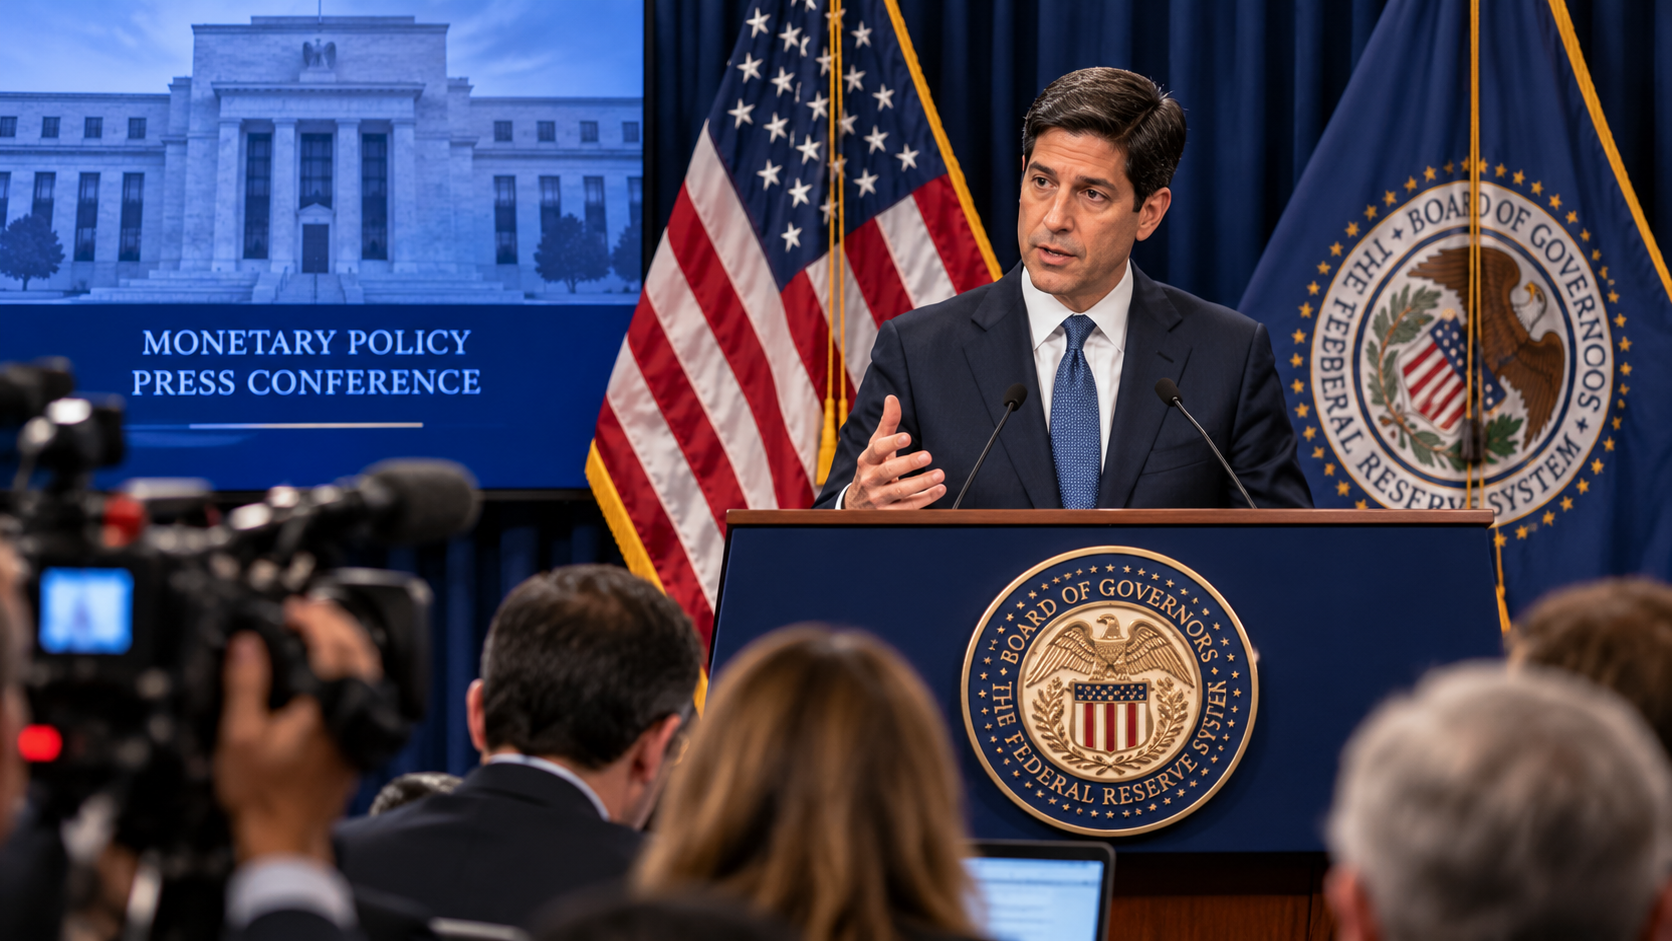
The Federal Reserve held interest rates steady Wednesday, October 28, maintaining its benchmark federal funds rate at 3.75% to 4.00% as policymakers weighed resilient economic growth against persistent inflation pressures. The widely anticipated decision followed September’s quarter-percentage-point rate increase and revealed a notable division among central bank officials over whether additional tightening is needed.
The Federal Open Market Committee voted 10–2 to leave rates unchanged, with Federal Reserve Governor Lisa Cook and Cleveland Fed President Beth Hammack dissenting in favor of another 25-basis-point increase. The split underscores growing concerns among some policymakers that inflation remains too elevated to justify a prolonged pause in monetary tightening.
In its official statement, the Federal Reserve acknowledged that inflation remains elevated while emphasizing the need for additional economic data before determining its next policy move. The central bank reiterated its commitment to returning inflation to its 2% target, signaling that further rate increases remain possible.
The decision comes after the Fed raised interest rates in September for the first time in more than three years. That move marked a shift toward tighter monetary policy as higher energy prices, persistent consumer spending, and broader price pressures complicated efforts to control inflation.
Recent economic data illustrate the challenge. Consumer prices rose 3.7% year over year in September, remaining well above the Fed’s target. Elevated energy costs have contributed to inflation, while price increases across other goods and services suggest that pressures are extending beyond fuel markets.
Despite those concerns, the Federal Reserve delivered a more optimistic assessment of overall economic activity. Policymakers described the economy as expanding at a strong pace, an upgrade from the characterization of solid growth used at their September meeting.
The statement highlighted resilient domestic spending, strong productivity growth, and robust capital investment. Officials also noted that job gains have generally kept pace with growth in the labor force, while the unemployment rate has changed relatively little.
This combination of economic strength and persistent inflation creates a difficult balancing act. Raising interest rates further could help reduce price pressures, but additional tightening would also increase borrowing costs for businesses and consumers.
For small-cap companies, the Fed’s decision carries particular significance. Smaller publicly traded businesses often depend more heavily on external financing than large corporations with substantial cash reserves and established access to capital markets.
Higher interest rates can increase the cost of refinancing debt, limit expansion opportunities, and reduce investor appetite for companies that require additional capital to fund operations.
Emerging biotechnology companies may be especially sensitive to these conditions because clinical development frequently requires significant funding before products generate commercial revenue. Small industrial manufacturers, technology companies, and consumer businesses can also face pressure from higher financing expenses and slower customer spending.
The Russell 2000 Index, which tracks smaller publicly traded U.S. companies, remains an important benchmark for investors assessing how changes in monetary policy influence the small-cap market.
The Fed’s decision also has implications for the housing market. Mortgage rates have climbed above 7% in recent weeks, weighing on affordability even as home prices continue rising in many parts of the country. Although mortgage rates are not directly set by the Federal Reserve, they are influenced by Treasury yields and expectations for future monetary policy.
Attention now turns to the Fed’s final scheduled policy meeting of 2026 in December. Investors have increasingly considered the possibility of another rate increase before year-end, particularly if inflation remains stubbornly above the central bank’s target.
Federal Reserve Chair Kevin Warsh’s post-meeting remarks will be closely examined for additional insight into how officials are evaluating inflation, economic growth, and the timing of potential future policy changes.
Wednesday’s decision leaves borrowing costs unchanged for now, but the dissenting votes and the Fed’s continued emphasis on price stability suggest that the debate over further tightening is far from settled.
For investors, particularly those focused on smaller companies, the direction of interest rates over the coming months could play a significant role in determining financing conditions, equity valuations, and market sentiment heading into 2027.
NN Delivers Another Quarter of Growth in Net Sales, Adjusted EBITDA, and New Wins; Raises 2026 Outlook Again
CHARLOTTE, N.C., Oct. 28, 2026 (GLOBE NEWSWIRE) — NN, Inc. (NASDAQ: NNBR) (“NN” or the “Company”), an entrepreneurial growth company that engineers and manufactures high-precision components and assemblies, today reported results for the third quarter ended September 30, 2026.
Q3 2026 Financial Highlights, compared to Q3 2025
Net sales of $131.1 million, up $27.2 million or 26.2%
Gross margin of $18.3 million, up $0.8 million or 4.6%
Adjusted gross margin of $25.3 million, up $5.8 million or 29.5%
Adjusted gross margin percentage of 19.3%, up 50 basis points
Loss from operations of $3.3 million, up $1.1 million from a loss of $2.2 million
Adjusted income from operations of $8.5 million, up $4.4 million or 109.5%
GAAP net loss of $4.6 million, improving by $2.1 million or 31.3%
Adjusted net income of $5.3 million, up $5.6 million
Adjusted EBITDA of $18.5 million, up $6.1 million or 49.7%
Adjusted EBITDA margin percentage of 14.1%, up 220 basis points
Performance Highlights:
During 2026, NN has completed a multi-step process to transform its balance sheet. The preferred stock payoff and equity raise has unlocked growth potential. NN now has the financial flexibility to accelerate and optimize its business results. The Company had been severely constrained by its capital structure for multiple years. The Company looks forward to achieving higher results at a faster pace.
NN’s new business program has continued to outperform expectations. On a trailing 12 months basis ended September 30, 2026, the Company has secured $130 million of annualized new business awards, a significant portion of which is not yet reflected in the Company’s run-rate. The Company is now winning more than 1 new program per day. The Company will continue to update results during quarterly earnings calls.
NN’s 5 Pillar growth program is working well and the Company is investing its time and resources to strategically pivot the portfolio to high-growth, high-value markets and products. The Company has been aided by strong underlying market growth.
Data Center: NN’s top targeted end market and one of its fastest growing businesses. NN is ramping up the business by installing over 50 new machines dedicated to this market through Q1 2027. This business has a growing $66 million pipeline, including liquid cooling components for next generation chip designs.
Defense: NN has secured multiple new awards in this market in 2026 and recently became a supplier to a leading firearm accessories OEM with multiple programs currently in ramp-up mode.
Medical: NN has secured multiple new awards in this market in 2026 and became a supplier to a leading medical equipment OEM with 30 core platforms. The Company is significantly increasing the size of the business with multiple programs in ramp-up mode.
NN’s cost-out program is on track to deliver $12 million of cost-out via 335 projects globally. These cost improvements are not yet fully reflected in the Company’s run-rate results. NN’s global operations team is also leading an ongoing continuum of new product development and business launches. In 2026, NN expects to launch more than 150 new programs worth approximately $100 million in peak annual sales.
NN is underway with an intentional sales growth investment program. Overall, the Company is growing its net sales by approximately $68 million in 2026 based on updated guidance. The Company has achieved excellent working capital performance of 16.5% – 16.7% of sales over the trailing 6 months.
Management Commentary:
Harold Bevis, President and Chief Executive Officer, commented, “NN has delivered several consecutive years of improved adjusted EBITDA and sales growth wins, is now benefitting from the launching of these programs, and has a solid multi-year outlook for continued growth. This enabled the Company to initiate a transformation of its equity and debt structure. We paid off all of our preferred stock via several debt-for-equity transactions over the last 4 months. We also raised strategic capital to fund additional programs that were previously on hold due to lack of funding. Taken together, this represented $143 million of capital transactions. We executed decisively and I want to thank our Board of Directors, our new investors, and our advisors. This transformation is behind us now and we are already underway leveraging our newly enhanced flexibility.
We are operating under a new reality whereby we can move faster and improve on multiple fronts at once. While we are on track for our best year ever in 2026, our momentum is continuing into 2027, as part of an achievable multi-year growth outlook. We have a full basket of opportunities to improve, and we are taking on the next set of big improvements during 2027 now that we have the financial capacity to do so. The last remaining balance sheet financial improvements are with regards to our ABL and Term Loan, which we will fix at the right time.
While we are happy with our last four years of sustained results improvement, we are at the same time determined to continue elevating the business to a higher plane of performance. This will require us to continue shifting our portfolio. We are taking forward actions on targeted sales growth, exiting low profit auto programs, and continuously taking out costs. We are on track for our multi-year targets. We are pleased that we have secured many new customers and introduced multiple new products in 2026. Further, we have a refreshed investor roster with growth-minded investors aligned with our forward goals. We are already accelerating our pace of improvement with our newfound financial flexibility.”
Bevis continued, “Our 5 Pillar growth program is our touchstone. Now we are in a position to also explore logical, small bolt-on acquisitions to further enhance our goals and growth trajectory. We are pleased that many of our new sales programs require ‘Immediate Startup’. Overall, the new wins numbers are very good, but we have areas where we want a significantly higher level of wins and growth, especially Data Center, Medical, and Defense. We are disciplined about improving our margins at the same time, walking away from dilutive business, and exiting minimal margin, minimal ROI business. We believe we have more room to increase our gross margins, adjusted EBITDA margins, and ROIs.”
Bevis concluded, “Given the results we have delivered in 2026 year to date and our strong forward outlook, we are raising our full-year 2026 guidance. We will be more specific about 2027 when we have completed our 2027 business planning process which is underway now. We are updating our thinking now that we have more financial firepower that has been enabled by our balance sheet transformation of 2026.”
Third Quarter NN Results
Net sales for the third quarter were $131.1 million, an increase of 26.2% compared to net sales of $103.9 million for the same period in 2025. The increase was primarily driven by higher selling prices, reflecting the pass-through of increased raw material costs to customers, higher volumes, and favorable foreign exchange effects.
Loss from operations for the third quarter was $3.3 million, an increase of $1.1 million compared to a loss from operations of $2.2 million for the same period in 2025. The decline was primarily due to higher labor costs associated with increasing headcount to support new business and higher professional fees driven by the various strategic initiatives.
Net loss for the third quarter was $4.6 million, an improvement of 31.3% compared to net loss of $6.7 million for the same period in 2025. The improvement was primarily driven by a gain related to a favorable tax ruling in Brazil and higher income from our joint venture in China.
Third Quarter 2026 NN Adjusted Results
Adjusted EBITDA was $18.5 million, an increase of 49.7% compared to adjusted EBITDA of $12.4 million for the same period in 2025, primarily driven by improved sales mix, operating performance and higher income from our joint venture in China.
Adjusted income from operations was $8.5 million, an increase of 109.5% compared to adjusted income from operations of $4.0 million for the same period in 2025. The increase was driven primarily by higher volumes and improved mix to higher margin products, partially offset by increased selling, general and administrative expenses.
Adjusted net income was $5.3 million, or $0.07 per diluted common share, an increase of $5.6 million or $0.08 per diluted common share, compared to adjusted net loss of $0.3 million, or $(0.01) per diluted common share for the same period in 2025.
Third Quarter Power Solutions Results Net sales for the third quarter of 2026 were $63.2 million, an increase of 40.6% compared to net sales of $44.9 million for the same period in 2025. The increase was driven primarily by higher selling prices, reflecting the pass-through of increased raw material costs to customers, increased volumes, and favorable foreign exchange effects.
Income from operations for the third quarter of 2026 was $9.2 million, an increase of 69.4% compared to income from operations of $5.4 million for the same period in 2025. The increase was primarily due to higher selling prices and increased volumes. The increase was partially offset by higher material costs and labor costs.
Adjusted income from operations for the third quarter of 2026 was $12.4 million, an increase of 53.1% compared to adjusted income from operations of $8.1 million for the same period in 2025. The increase was primarily due to the improved operating performance from higher selling prices and volumes.
Third Quarter Mobile Solutions Results
Net sales for the third quarter of 2026 were $68.2 million, an increase of 15.3% compared to net sales of $59.1 million in the same period of 2025. The increase was primarily due to higher volumes and favorable foreign exchange effects.
Loss from operations for the third quarter was $6.3 million, a decline of $3.4 million compared to $2.9 million for the same period in 2025. The increase was primarily due to higher costs from volume increases, increased labor costs due to the start-up of new programs, material cost increases, and facility costs.
Adjusted income from operations for the third quarter was $4.0 million, an increase of 75.2% compared to adjusted income from operations of $2.3 million in the same period of 2025. The increase in adjusted income from operations was primarily due to higher sales volumes and increased net income from our joint venture.
2026 Outlook NN is revising its guidance ranges upward in several areas.
Net sales are expected to range between $480 to $500 million
This reflects a $68 million improvement over 2025, or 16% growth year-over-year at the midpoint.
Adjusted EBITDA is expected to range between $64 and $68 million.
This reflects a $17 million improvement over 2025, or 35% growth year-over-year at the midpoint.
New business wins are expected to range between $110 to $130 million.
This reflects a $50 million improvement over 2025, or 71% growth year-over-year at the midpoint.
Chris Bohnert, Senior Vice President and Chief Financial Officer, commented, “Given the strength of our results year to date and the continued momentum in our targeted growth markets, we are again raising our full-year 2026 guidance across our key metrics. As we look ahead to the final quarter of 2026 and into 2027, our outlook reflects continued profitable growth and keeps us well on track to maintain pace with our 2029 financial goals. Our new capital structure enables NN to enter 2027 with a stronger balance sheet and greater financial flexibility to invest in our growth.”
Conference Call
NN will discuss its results during its quarterly investor conference call on October 29, 2026, at 9 a.m. ET. The call and supplemental presentation may be accessed via NN’s website, www.nninc.com. The conference call can also be accessed by dialing (833) 461-5787 (domestic) or (585) 542-9983 (international) and entering Conference ID number 100337183. For those who are unavailable to listen to the live broadcast, a replay will be available shortly after the call.
NN discloses in this press release the non-GAAP financial measures of adjusted gross margin, adjusted gross margin %, adjusted income from operations, adjusted EBITDA, adjusted EBITDA margin, adjusted net income (loss), and adjusted net income (loss) per diluted common share. Each of these non-GAAP financial measures provides supplementary information about the impacts of acquisition, divestiture and integration related expenses, foreign-exchange impacts on inter-company loans, reorganizational and impairment charges.
The financial tables found later in this press release include a reconciliation of adjusted gross margin, adjusted gross margin %, adjusted income from operations, adjusted operating margin, adjusted EBITDA, adjusted EBITDA margin, adjusted net income (loss), and adjusted net income (loss) per diluted common share to the U.S. GAAP financial measures of gross margin, income (loss) from operations, net loss, net loss per diluted common share.
About NN, Inc.
NN, Inc. (NASDAQ: NNBR) is an entrepreneurial manufacturing company specializing in manufacturing micron-tolerance precision metal componentry for high-growth end markets, especially Data Center, Electric Grid, Medical, Defense, and High-Value Vehicle systems. Founded in 1980, NN serves over 700 customers on 4 continents through its 2,700 person workforce operating out of 27 global plants. This footprint enables rapid innovation and globally scaled solutions. For more information, visit nninc.com.
This press release may contain forward-looking statements regarding our business, operations, and financial performance. Such statements are based on current expectations and assumptions that are subject to a number of risks and uncertainties. Actual results could differ materially. Please refer to our most recently filed Form 10-K and our Form 10-Q for the period following that Form 10-K, including the risk factors described therein. We undertake no obligation to update any forward-looking statement, except as required by law. Given these risks and uncertainties, investors are cautioned not to place undue reliance on such forward-looking statements.
Investor & Media Contacts: Joseph Caminiti [email protected] 312-445-2870
Targeted for Launch in 2028, Freedom Will Be the First U.S. Nuclear Fission Reactor-Powered Interplanetary Spacecraft
SAN DIEGO, Oct. 28, 2026 (GLOBE NEWSWIRE) — Kratos Defense & Security Solutions, Inc. (Nasdaq: KTOS), a leading technology company in the defense, national security, and space domains, today announced a $33.6 million contract award to design, build, and deliver the power conversion system for NASA’s Space Reactor-1 Freedom. Kratos will be executing this work as a subcontractor to Sierra Lobo, Inc., under their NASA SpaceDOC III contract. Targeted for launch in 2028, SR-1 Freedom will be the first nuclear fission reactor-powered interplanetary spacecraft, designed to travel beyond Earth’s orbit to Mars, demonstrate advanced nuclear electric propulsion (NEP), and successfully deliver the SkyFall payload.
Space Reactor-1 Freedom will be the first spacecraft ever to demonstrate fission power beyond Earth’s orbit, traveling to Mars to deliver a sciece payload called SkyFall. Photo Credit: NASA/Alberto Bertolin
Under this subcontract, Kratos will provide a compact, space-qualified closed Brayton cycle power conversion system. This crucial component serves as the mechanical bridge between SR-1 Freedom’s onboard fission reactor and the spacecraft’s power distribution and electric propulsion subsystems. It converts the thermal energy generated by the reactor into the vital electrical power required to drive SR-1’s propulsion thrusters and sustain all critical spacecraft operations.
Nuclear electric propulsion utilizes a fission-based, nuclear power module to generate electricity, powering highly efficient electric thrusters rather than relying solely on conventional chemical thrusters. By accelerating charged particles to create a gentle but relentless thrust, NEP allows the spacecraft to gradually build immense velocity. Because they can operate continuously for months or years, NEP-equipped spacecraft can reach Mars utilizing significantly less propellant than traditional chemically propelled spacecraft. This unprecedented efficiency drastically reduces fuel requirements, freeing up critical mass for scientific instruments, cargo, and future crew-support equipment.
“Being selected to power SR-1 Freedom is a generational honor for Kratos,” said Stacey Rock, President of Kratos Turbine Technologies Division. “SR-1 is the spacecraft that turns space nuclear propulsion from concept into reality; it is the vehicle that will help answer whether America leads the third space race or watches it from the sidelines. By delivering the power conversion heart of SR-1 Freedom, Kratos is helping NASA give birth to the ‘Nuclear NASA’ that will open the outer solar system, shorten the path to Mars, and strengthen our national security in space.”
NASA has positioned the SR-1 Freedom mission as a cornerstone in a broader space nuclear initiative. The mission aims to launch the first U.S. space reactor since 1965, paving the way for a transformative era of deep space exploration. SR-1 Freedom is strategically structured to mitigate development risks and cultivate the necessary industrial base for future deep-space operations and will facilitate follow-on concepts like Lunar Reactor-1 (LR-1), which is envisioned as a sun-independent power source for NASA’s upcoming Moon Base efforts. The SR-1 Freedom contract adds to Kratos’ expanding portfolio of advanced propulsion, power, and hypersonics work. This milestone reinforces the company’s broader corporate strategy of leveraging strategic internal investments to support critical national security and next-generation space programs.
For more information on Kratos and its advanced space and hypersonic programs, visit www.kratosdefense.com.
About Kratos Defense & Security Solutions Kratos Defense & Security Solutions, Inc. (NASDAQ: KTOS) is a technology, products, system and software company addressing the defense, national security, and commercial markets. Kratos makes true internally funded research, development, capital and other investments, to rapidly develop, produce and field solutions that address our customers’ mission critical needs and requirements. At Kratos, affordability is a technology, and we seek to utilize proven, leading-edge approaches and technology, not unproven bleeding edge approaches or technology, with Kratos’ approach designed to reduce cost, schedule and risk, enabling us to be first to market with cost effective solutions. We believe that Kratos is known as an innovative disruptive change agent in the industry, a company that is an expert in designing products and systems up front for successful rapid, large quantity, low-cost future manufacturing which is a value-add competitive differentiator for our large traditional prime system integrator partners and also to our government and commercial customers. Kratos intends to pursue program and contract opportunities as the prime or lead contractor when we believe that our probability of win (PWin) is high and any investment required by Kratos is within our capital resource comfort level. We intend to partner and team with a large, traditional system integrator when our assessment of PWin is greater or required investment is beyond Kratos’ comfort level. Kratos’ primary business areas include virtualized ground systems for satellites and space vehicles including software for command & control (C2) and telemetry, tracking and control (TT&C), jet powered unmanned aerial drone systems, hypersonic vehicles and rocket systems, propulsion systems for drones, missiles, loitering munitions, supersonic systems, space craft and launch systems, C5ISR and microwave electronic products for missile, radar, missile defense, space, satellite, counter UAS, directed energy, communication and other systems, and virtual & augmented reality training systems for the warfighter. For more information, visit www.KratosDefense.com and follow Kratos on LinkedIn and X.
Notice Regarding Forward-Looking Statements Certain statements in this press release may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are made on the basis of the current beliefs, expectations and assumptions of the management of Kratos and are subject to significant risks and uncertainty. Investors are cautioned not to place undue reliance on any such forward-looking statements. All such forward-looking statements speak only as of the date they are made, and Kratos undertakes no obligation to update or revise these statements, whether as a result of new information, future events or otherwise. Although Kratos believes that the expectations reflected in these forward-looking statements are reasonable, these statements involve many risks and uncertainties that may cause actual results to differ materially from what may be expressed or implied in these forward-looking statements. For a further discussion of risks and uncertainties that could cause actual results to differ from those expressed in these forward-looking statements, as well as risks relating to the business of Kratos in general, see the risk disclosures in the Annual Report on Form 10-K of Kratos for the year ended December 28, 2025, and in subsequent reports on Forms 10-Q and 8-K and other filings made with the SEC by Kratos.
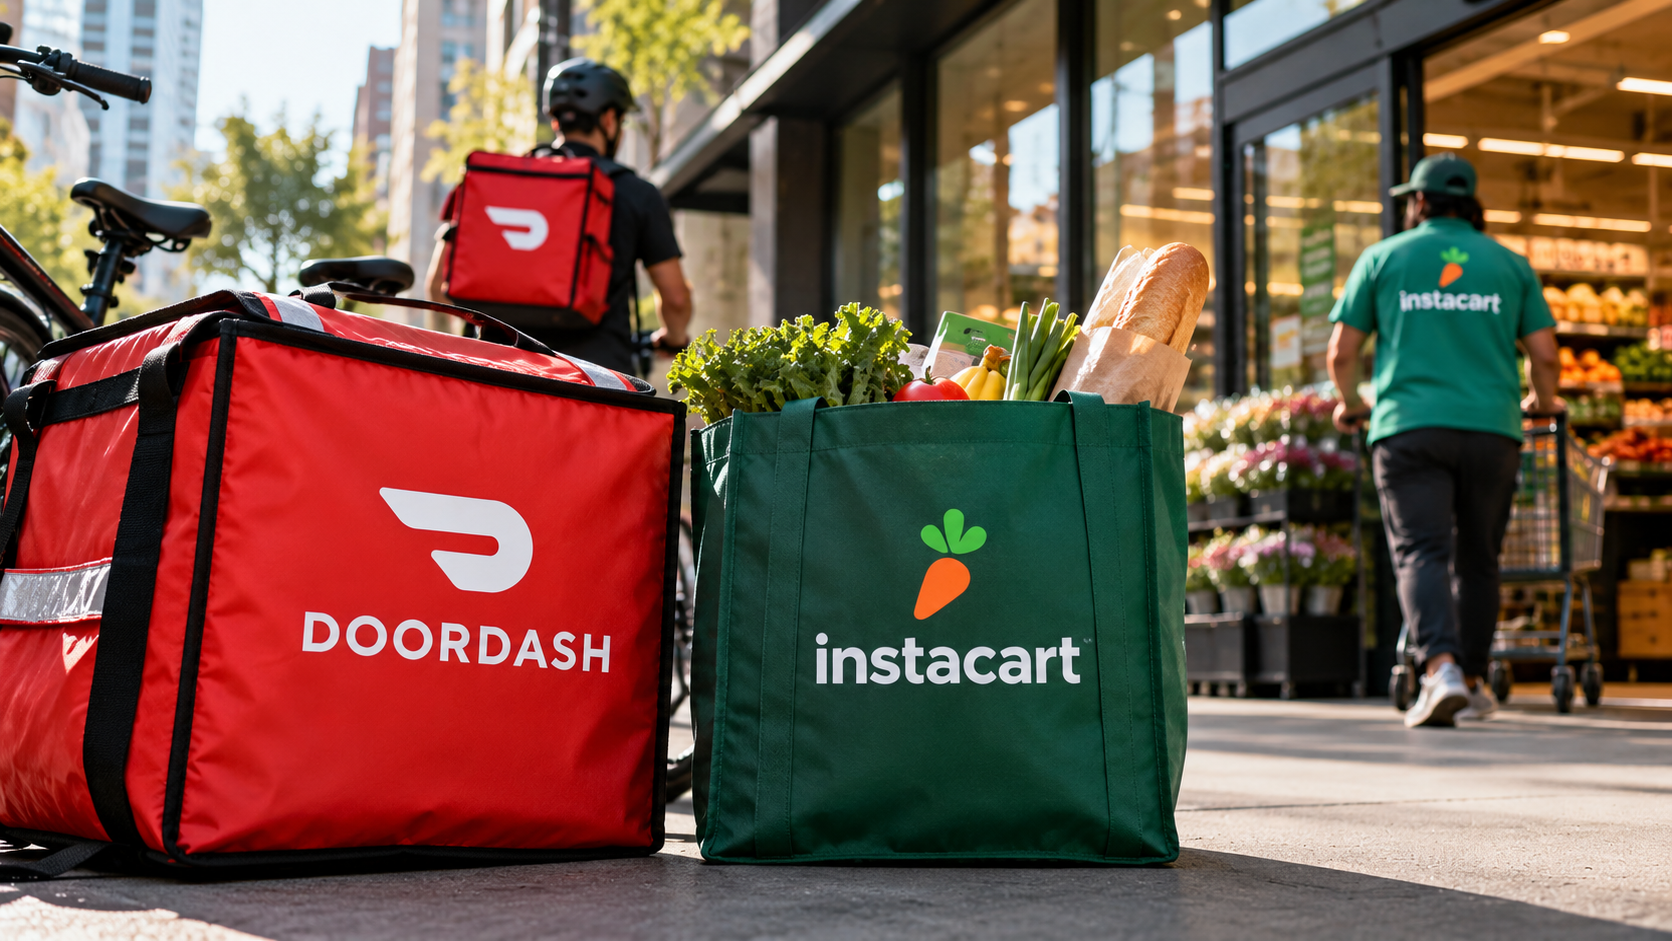
DoorDash (NASDAQ: DASH) is reportedly in advanced negotiations to acquire grocery delivery platform Instacart (NASDAQ: CART) in a deal that could value the company at approximately $17 billion, potentially creating one of the largest combined food and grocery delivery platforms in the United States.
According to reports from The Wall Street Journal and Reuters, an agreement could be announced as soon as this week, although negotiations remain ongoing and there is no guarantee a transaction will be completed. The potential acquisition would represent a significant expansion of DoorDash’s business beyond restaurant delivery as competition intensifies across the online grocery and retail markets.
Investors responded sharply to news of the negotiations. Instacart shares climbed approximately 8% on Monday, while DoorDash stock declined roughly 6%, reflecting enthusiasm about a potential takeover premium alongside concerns about the cost and complexity of the acquisition.
Before reports of a possible sale emerged, Instacart had a market capitalization of approximately $12 billion. A transaction valued at $17 billion would represent a substantial premium and mark one of the more significant technology acquisitions of 2026.
The proposed combination would bring together two major players with complementary strengths. DoorDash has established an extensive delivery network through its restaurant business and expanded into convenience stores, grocery chains, and general merchandise retailers. Instacart, meanwhile, specializes in grocery shopping and delivery, maintaining established relationships with supermarket operators and providing technology that supports online ordering and retail advertising.
Together, the companies could offer consumers a broader range of delivery options while creating opportunities to consolidate logistics, improve delivery efficiency, and expand advertising services.
The strategic motivation comes as traditional delivery platforms face increasing competition from Amazon and Walmart, both of which have invested heavily in grocery fulfillment, same-day delivery, and customer loyalty programs.
DoorDash already works with retailers including Kroger, Safeway, Aldi, CVS, Macy’s, and Target. Acquiring Instacart could deepen its relationships with grocery chains and accelerate its efforts to become a comprehensive local commerce platform rather than primarily a restaurant delivery service.
For Instacart, the potential transaction comes after several years of adjusting to slower growth following the pandemic-driven surge in online grocery shopping. The company went public in 2023 but has faced mounting competitive pressure from larger technology platforms and retailers developing their own digital ordering capabilities.
Instacart has also expanded beyond delivery into advertising and software services for retailers, businesses that could become important components of DoorDash’s longer-term growth strategy.
However, the financial implications of a potential acquisition remain uncertain. The companies have not disclosed a proposed transaction structure, including whether the purchase would be financed through cash, stock, or a combination of both.
Analysts have also raised questions about whether the potential cost savings and additional revenue opportunities would justify the reported acquisition price. Integrating two large delivery networks could create efficiencies, but overlapping operations, technology systems, and retail partnerships may present challenges.
Regulatory scrutiny represents another consideration. Because DoorDash and Instacart compete in portions of the grocery delivery market, a combination could attract attention from antitrust regulators evaluating its potential impact on competition, merchants, and consumers.
The reported negotiations follow an earlier attempt by DoorDash to acquire Instacart in 2021, when the grocery delivery company’s private-market valuation was considerably higher. Those discussions ultimately failed to produce an agreement.
Uber Technologies (NYSE: UBER) also reportedly explored acquiring Instacart, although those discussions are no longer active.
The potential deal underscores a broader shift in the delivery industry, where companies are increasingly pursuing acquisitions, operational efficiencies, and diversified revenue streams as growth becomes more competitive.
For investors, the key questions will be whether DoorDash can translate greater scale into improved profitability, how much it must pay to secure Instacart, and whether regulators would approve the combination.
If completed, the acquisition could significantly reshape the competitive landscape for online grocery delivery, creating a larger challenger to Amazon and Walmart while accelerating consolidation across the digital commerce industry.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Investment weighs on Q3. Revenue increased 3% to $22.9 million, in line with expectations. Adjusted EBITDA fell to a loss of $2.2 million, modestly wider than our estimated loss of $1.5 million. The earnings shortfall largely reflected higher sales and marketing expenditures associated with the company’s transition to a paid membership model.
Membership growth accelerates. Club Members increased 65% year over year, supported by $5.8 million in direct membership acquisition spending during the quarter. Encouragingly, average U.S. customer acquisition cost fell to $54 from $62 in the second quarter, while deferred revenue rose to $13.5 million, providing greater visibility into future recurring membership revenue.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.