Lindblad Expeditions Expands Experiential Travel Portfolio With White Desert and Echo Charlie Acquisition

Lindblad Expeditions Holdings (NASDAQ: LIND) is making the largest acquisition in its history, acquiring a 60% majority stake in White Desert Antarctica and Echo Charlie for approximately $61 million in cash, plus roughly $6 million for cash on the balance sheet and customary adjustments.

The transaction gives Lindblad a stronger position in high-end experiential travel by adding a luxury Antarctic operator and a new aviation-focused adventure brand to a portfolio that already spans expedition cruising, wildlife travel, cycling, cultural trips and other specialty experiences. Lindblad said White Desert and Echo Charlie will continue to operate as stand-alone brands while gaining access to the company’s broader distribution, resources and operating platform.

For investors, the deal is notable not only because of its size relative to Lindblad’s acquisition history, but because it extends the company beyond its traditional marine-expedition roots and further into premium land- and air-based travel.

Adding Luxury Antarctica and Aviation to the Portfolio

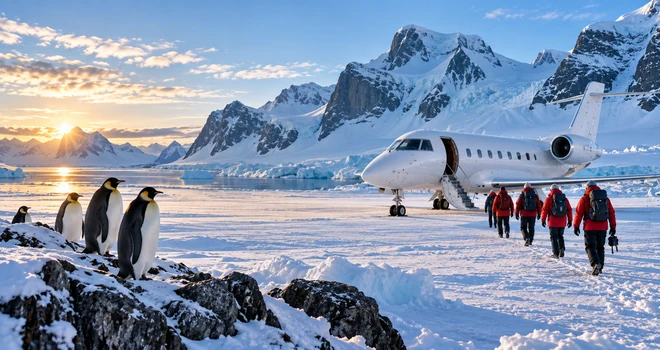
White Desert was founded in 2005 by polar explorer Patrick Woodhead and specializes in flying guests directly into the Antarctic interior.

Its itineraries include trips to the Geographic South Pole and visits to an Emperor penguin colony of more than 20,000 birds, combining access to remote areas with luxury accommodations and extensive logistics. The company employs more than 150 people from 18 nationalities and has built its brand around aviation, safety and small-scale high-end travel.

Echo Charlie takes the aviation concept outside Antarctica. The newer brand operates luxury adventure journeys aboard a restored DC-3 carrying just 12 guests, with itineraries designed around remote destinations including Colombia, Patagonia, the Faroe Islands and Greenland. Lindblad sees the platform as a way to broaden its reach into places that are difficult to access through conventional commercial travel.

Woodhead will remain chairman of White Desert and CEO of Echo Charlie and will also join Lindblad as Strategic Innovation Advisor. That founder-led continuity appears deliberate. Lindblad has used a similar model in prior acquisitions, allowing specialty brands to retain their identity while plugging into the parent company’s broader infrastructure and customer base.

Lindblad Continues Building a Multi-Brand Travel Platform

The transaction fits a strategy Lindblad has been pursuing for years: expanding from expedition cruising into a broader collection of differentiated travel businesses.

The company now describes itself as operating across air, land and sea, with brands including National Geographic-Lindblad Expeditions, Natural Habitat Adventures, Off the Beaten Path, DuVine Cycling + Adventure Co., Classic Journeys and Wineland-Thomson Adventures, along with White Desert and Echo Charlie.

Natural Habitat Adventures, for example, expanded Lindblad into land-based wildlife and ecotourism, including polar bear expeditions in Canada, Alaskan wildlife trips and African safaris. That acquisition helped establish the template for adding specialty experiential brands rather than simply expanding the company’s cruise fleet.

White Desert and Echo Charlie push that strategy further. Rather than purchasing additional ship capacity, Lindblad is adding specialized aviation capabilities and premium experiences that potentially allow it to serve existing customers in different ways. That could be important because affluent adventure travelers often purchase multiple types of trips rather than remaining loyal to a single travel format.

The Deal Comes as Lindblad’s Core Business Is Growing

Lindblad is making the acquisition from a position of improving operating momentum.

In the second quarter of 2026, total revenue increased 19% to $199.2 million, while adjusted EBITDA rose 31% to $32.5 million. Occupancy increased to 91% from 86%, and the Lindblad segment posted a record second-quarter net yield of $1,294 per available guest night.

The company also raised its full-year guidance alongside the acquisition announcement. Lindblad now expects 2026 tour revenue of $850 million to $880 million and adjusted EBITDA of $140 million to $148 million, reflecting both the additions of White Desert and Echo Charlie and continued strength in the existing business.

That backdrop matters because acquisitions are generally easier to absorb when the underlying platform is already growing. Lindblad is not relying solely on M&A to generate momentum; its existing operations have also been posting higher revenue, occupancy and yields.

Why Experiential Travel Is Attracting Investment

The broader industry backdrop helps explain the strategic appeal.

Adventure and experiential travel have moved well beyond a niche segment. The Adventure Travel Trade Association estimates the global outbound adventure-travel market at approximately $1.16 trillion, with 67% of international travelers classified as “open to adventure.” The organization says travelers increasingly prioritize new experiences, cultural connection, off-the-beaten-path destinations and sustainability.

Its 2026 industry survey also found that nearly 60% of adventure-tour operators reported revenue growth in 2025, while 61% expect higher net profits in 2026. Operators cited new customers, geographic expansion and product diversification as important drivers.

The luxury end of the market is particularly relevant to Lindblad’s acquisition. Virtuoso’s 2026 Luxe Report ranked Antarctica as the top adventure destination and one of the leading destinations on the rise. Expedition cruising was also among the year’s leading travel trends, while 45% of surveyed advisors reported increasing demand for “ultraluxe” travel such as highly private and hyper-personalized experiences.

Those trends line up closely with what White Desert and Echo Charlie offer: small guest counts, difficult-to-reach destinations and experiences that are difficult to replicate independently.

Luxury Travel Has Been More Resilient

Another factor is the relative strength of affluent travelers.

The broader travel market has become increasingly bifurcated, with value-conscious consumers becoming more selective while wealthier travelers continue spending on premium experiences. Travel industry analysts have noted that luxury cruising and highly differentiated experiences have generally held up better than mass-market categories in 2026.

That has encouraged more travel companies to move upscale. Luxury hotel brands including Ritz-Carlton, Four Seasons and others have been expanding into yachts and cruises, while expedition operators increasingly combine remote destinations with hotel-level service. The common theme is that the product is becoming less about transportation and more about access, exclusivity and the experience itself.

White Desert fits directly into that trend.

A Different Kind of Scale

Unlike conventional cruise acquisitions, the strategic value here is not necessarily about adding thousands of passengers.

Echo Charlie carries just 12 travelers at a time, and White Desert is built around small-scale Antarctic access. That scarcity is part of the product.

For Lindblad, the opportunity is therefore to expand the value of each customer relationship rather than simply add capacity. A traveler who has already booked a National Geographic-Lindblad expedition or a Natural Habitat wildlife trip may also be a potential customer for a White Desert Antarctic journey or a highly specialized Echo Charlie itinerary.

That creates cross-selling opportunities across brands while preserving the exclusivity that supports premium pricing. It also diversifies Lindblad geographically and operationally. The company remains heavily associated with ships and expedition cruising, but the portfolio increasingly includes land and aviation experiences that do not depend on adding cruise capacity.

Travelzoo Offers Another View Into Experiential Travel Demand

Investors interested in the broader experiential travel theme can also look at Travelzoo (NASDAQ: TZOO), which is covered by Noble Capital Markets.

Travelzoo operates a global travel and experiences platform that connects its members with curated travel, entertainment and lifestyle offers. While its business model differs significantly from Lindblad’s direct ownership of expedition brands, both companies participate in a travel market increasingly shaped by consumers seeking distinctive experiences rather than simply transportation and lodging.

Noble Capital Markets provides research coverage of Travelzoo, giving Channelchek readers another publicly traded company through which to follow trends in premium and experiential travel.

Building a Broader Experiential Travel Company

The White Desert and Echo Charlie acquisition represents more than an expansion of Lindblad’s Antarctica business.

It advances the company’s transformation from a primarily expedition-cruise operator into a diversified experiential travel platform spanning ships, wildlife expeditions, cycling tours, cultural travel and now specialized aviation.

The immediate financial contribution remains relatively modest compared with Lindblad’s overall revenue base, but strategically the transaction opens another avenue for selling premium experiences to a customer base already inclined toward remote and adventure-oriented travel.

With adventure tourism becoming increasingly mainstream while affluent travelers continue prioritizing highly personalized experiences, Lindblad is betting that the next stage of growth will come not simply from carrying more passengers, but from offering more ways to reach places most travelers cannot easily reach on their own.

Travelzoo (TZOO) – Investment Quarter Masks Long-Term Value


Wednesday, July 29, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Accelerated membership investment weighed heavily on Q2 results. Revenue declined 3% to $23.2 million, while Travelzoo reported a $2.8 million operating loss and a non-GAAP operating loss of $2.1 million. The decline reflected geopolitical uncertainty across Travelzoo’s markets and a deliberate increase in member-acquisition spending.

The recurring-revenue strategy is gaining measurable traction. Membership and subscription revenue increased to approximately $5.0 million in Q2 from $3.0 million in the prior-year period, while deferred revenue rose 54% from year-end to $13.4 million. Membership renewals reached a record level.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

What Spirit Airlines’ Collapse Means for the Budget Travel Market

Spirit Airlines is gone. In the early morning hours of May 2, 2026, the ultra-low-cost carrier that helped reshape American air travel for more than three decades ceased all global operations, effective immediately — becoming the first major U.S. airline to go out of business due to financial failure in 25 years.

The collapse came after a last-ditch effort to secure a $500 million government bailout fell apart. The Trump administration had proposed a rescue package that would have given the federal government a stake of up to 90% in the airline, but a key group of bondholders rejected the deal. With no financial lifeline and no runway left, Spirit pulled the plug overnight — canceling all flights, shutting down customer service, and leaving thousands of passengers stranded at airports across the country.

Spirit’s downfall wasn’t a single event — it was a slow unraveling. The airline had filed for bankruptcy twice since 2024, each time attempting to emerge leaner and more competitive. But the math stopped working. Soaring jet fuel costs driven by the U.S.-Iran conflict hit low-cost carriers hardest, and Spirit’s core competitive advantage — the ability to undercut legacy airlines on price — had been steadily eroded.

The bigger carriers had watched Spirit’s playbook for years and eventually adopted it themselves, rolling out their own basic economy fares and stripping down ticket prices on key routes. When the major airlines started playing Spirit’s game, Spirit had little left to differentiate itself. A proposed $3.8 billion merger with JetBlue in 2023 was blocked by the Department of Justice on antitrust grounds — a decision that, in hindsight, may have sealed the airline’s fate.

By February 2026, Spirit’s market share had already slipped to under 4% of U.S. passengers, and projections for May had it falling to 1.8%. The writing had been on the wall for some time.

The closure leaves a real void, and consumers are likely to feel it — whether they ever flew Spirit or not. At its peak, Spirit operated roughly 300 flights per day, serving price-sensitive travelers across the U.S., Caribbean, and Latin America. That capacity doesn’t simply disappear; it creates an opening for surviving carriers to fill — and price accordingly.

In the immediate aftermath, United, Delta, Southwest, JetBlue, and American all moved to cap fares at roughly $200 one-way to absorb stranded Spirit customers. That goodwill is likely short-lived. Once the dust settles, the removal of an aggressive low-fare competitor from key routes historically results in higher average ticket prices across the board. Consumers flying routes that Spirit served — particularly leisure-heavy markets in Florida, the Caribbean, and secondary cities — should expect less pricing pressure moving forward.

The airline’s shutdown also puts 17,000 direct and indirect jobs at risk, including 14,000 Spirit employees. While major carriers have opened hiring pipelines and extended travel benefits to displaced workers, the broader labor impact on aviation support industries at affected airports remains to be seen.

Spirit’s collapse creates a consolidation opportunity for surviving ultra-low-cost carriers. Frontier Airlines, Avelo, and Allegiant now stand to absorb market share on routes where Spirit had been the primary budget option. Fleet assets, airport gate slots, and route authorities will become valuable commodities as Spirit winds down through bankruptcy proceedings.

For the broader airline industry, this moment raises a pointed question about the long-term viability of the ultra-low-cost model in a post-pandemic, high-fuel-cost environment. When legacy carriers can effectively replicate your pricing strategy, and geopolitical shocks can wipe out your margin overnight, the business case becomes nearly impossible to sustain.

Spirit may have been the butt of every travel meme for years — but its presence kept prices honest. With those yellow planes grounded for good, budget-conscious travelers will be the ones paying the price.

Travelzoo (TZOO) – Positioned For Earnings Upside as Subscription Model Scales


Friday, April 24, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q1 results reflect steady growth with investment-driven earnings pressure. Revenue increased 5% year-over-year to $24.3 million, in line with our estimate, while adj. EBITDA beat our estimate ($3.5 million versus our estimate of $2.9 million). EPS declined modestly as the company continued to prioritize member acquisition, highlighting the trade-off between near-term profitability and long-term value creation.

Subscription growth and renewals drove the quarter. Record membership renewals and continued Club Member acquisition were key drivers, reinforcing the strength of the subscription model and improving underlying unit economics despite upfront marketing costs. Membership Fee revenue, which represented 19% of total company revenue, increased by a solid 91%.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Travelzoo (TZOO) – CEO Incentives Signal Turnaround Upside


Tuesday, April 21, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Shareholders approve CEO option grant. Travelzoo shareholders approved a 600,000-share non-qualified stock option grant to CEO Holger Bartel, formalizing a performance-based compensation structure tied directly to stock price appreciation and marking a clear inflection point in management incentives. The grant represents a significant 5.5% of the current total shares outstanding. 

Structure emphasizes near-term performance and meaningful upside. The options carry a $5.05 exercise price, vest semi-annually over two years, and have a five-year term, creating a relatively short execution window in which management must deliver results to realize value.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Allegiant and Sun Country Clear a Major Merger Hurdle

Allegiant Travel Company (NASDAQ: ALGT) and Sun Country Airlines (NASDAQ: SNCY) cleared a critical regulatory hurdle this morning, announcing the early termination of the Hart-Scott-Rodino antitrust waiting period — meaning the U.S. Department of Justice has signed off on Allegiant’s proposed acquisition of Sun Country without objection. The milestone moves one of the more strategically compelling small-cap airline consolidations in years meaningfully closer to the finish line.

The deal, originally announced in January 2026, is structured as a $1.5 billion cash-and-stock transaction that offered Sun Country shareholders a premium of nearly 20% over the stock’s last close before the announcement. With DOJ clearance now secured, the primary remaining conditions are approval from the U.S. Department of Transportation and a shareholder vote from both companies. Closing is targeted for the second or third quarter of 2026.

Both carriers occupy a niche that the major airlines have largely ignored — leisure travelers flying from small and mid-sized cities to vacation destinations. Allegiant, based in Las Vegas, has built its entire model around non-stop routes linking secondary markets to resort towns. Sun Country, operating out of Minneapolis, runs a hybrid model combining scheduled passenger service, charter operations, and an Amazon cargo business that generated record full-year revenue of $1.13 billion in 2025 — its fifth consecutive profitable year.

Together, the combined carrier would serve roughly 22 million annual customers, operate across nearly 175 cities, and cover more than 650 routes with a fleet of 195 aircraft. Neither airline competes heavily for the same routes, which likely explains why the DOJ review resolved quickly and without required divestitures — a favorable signal for deal certainty.

At the time of the deal announcement, Allegiant carried a market cap of approximately $1.37 billion and Sun Country traded below $700 million — both firmly in small-cap territory. This transaction is a reminder that some of the most structurally sound consolidation plays in the market are happening below the radar of mainstream financial media, which remains fixated on mega-cap M&A.

The leisure travel segment has proven more resilient than traditional scheduled carriers across multiple economic cycles. Consumers continue to prioritize experiences and affordable vacation travel, and both Allegiant and Sun Country have built disciplined, asset-light models well-suited to capitalize on that demand. Sun Country’s diversified revenue streams — cargo, charter, and scheduled service — add a layer of earnings stability to the combined entity that pure-play passenger carriers often lack.

The DOT’s interim exemption approval is the next significant milestone, followed by formal shareholder votes at both companies. Neither hurdle is considered unusually high risk at this stage, and most observers expect the transaction to close on schedule. Allegiant has flagged the combination as accretive to earnings power and expects meaningful cost synergies from consolidating operations, maintenance programs, and corporate overhead.

For small-cap investors tracking consolidation trends in the airline sector, the Allegiant-Sun Country merger is a case study in how smaller carriers are quietly reshaping the competitive landscape — one nonstop leisure route at a time.

Oil Spike Sends Airline Stocks Lower as Fuel Costs Surge

Airline stocks moved sharply lower Monday as oil prices surged above $100 per barrel, raising concerns about rising jet fuel costs and pressure on industry profitability.

Shares of major U.S. carriers fell after crude oil briefly climbed above $110 per barrel, the highest level since 2022. The move followed escalating geopolitical tensions in the Middle East that disrupted shipping traffic through the Strait of Hormuz, one of the world’s most critical oil transit routes.

Delta Air Lines, American Airlines, and United Airlines all declined in early trading before trimming some losses. Domestic-focused carriers including Southwest Airlines, JetBlue Airways, and Alaska Air Group also traded lower as investors weighed the financial impact of higher fuel prices.

Fuel represents one of the largest operating expenses for airlines, typically accounting for roughly one-fifth to one-quarter of total costs. When oil prices climb quickly, airlines often face immediate margin pressure, particularly if ticket prices cannot be adjusted quickly enough to offset the increase.

Jet fuel prices have climbed significantly in recent weeks, rising by as much as $1.75 per gallon. At those levels, the largest U.S. airlines could see quarterly fuel expenses increase by roughly $1.5 billion each if elevated prices persist. Across the three largest carriers, the additional costs could approach $5 billion.

Higher fuel costs often translate into higher ticket prices as airlines attempt to protect margins. Carriers may adjust fares, reduce promotional pricing, or alter route capacity in response to sustained increases in fuel expenses.

The current price spike also highlights the industry’s increased exposure to energy market volatility. Many airlines previously used fuel hedging strategies to limit the impact of oil price swings. Over the past decade, however, most carriers have moved away from large-scale hedging programs after experiencing losses during periods of falling oil prices. Southwest Airlines, long known for its fuel hedging approach, ended its program in 2025.

In addition to rising energy costs, airlines are facing operational disruptions tied to the conflict. Thousands of flights have been grounded globally as airlines reroute aircraft away from affected airspace, leaving travelers stranded and adding complexity to airline scheduling.

European airline stocks also declined amid the developments. Lufthansa shares dropped roughly 5%, while International Consolidated Airlines Group, the parent company of British Airways and Aer Lingus, fell about 3%. Air France-KLM also moved lower during the session.

The latest selloff adds to a difficult year for airline equities. Shares of Delta, American, and United are down roughly 20% to 30% year to date. Domestic carriers such as JetBlue, Southwest, and Alaska Air have also experienced steep declines in recent weeks.

For investors, the move underscores how closely airline performance remains tied to global energy markets. Even with steady travel demand, sudden spikes in oil prices can quickly reshape the profitability outlook for carriers.

If crude oil remains elevated, airlines may continue adjusting pricing strategies and operating plans as they navigate the industry’s most volatile cost variable.

Travelzoo (TZOO) – Near Term Revenue Growth Throttles Back


Friday, February 20, 2026

Travelzoo® provides its 30 million members with exclusive offers and one-of-a-kind experiences personally reviewed by our deal experts around the globe. We have our finger on the pulse of outstanding travel, entertainment, and lifestyle experiences. We work in partnership with more than 5,000 top travel suppliers—our long-standing relationships give Travelzoo members access to irresistible deals.

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Softer than expected Q4 Results. The company reported Q4 revenue of $22.5 million, an increase of 9%, and adj. EBITDA of $1.0 million, both of which were below our estimates of $23.0 million and $3.3 million, respectively.  Importantly, the modestly softer than expected results were largely driven by weakness in advertising and commerce revenue. Increased marketing spend and elevated G&A expenses due to a non-recurring corporate event adversely affected EBITDA.

Customer acquisition efficiency. Customer acquisition costs averaged $34 per member in Q4, compared to $28 in Q1, $38 in Q2, and $40 in Q3, reflecting continued investment in subscriber growth. Management highlighted rapid payback economics, with annual membership fees collected upfront and supplemented by transaction revenue. Acquisition costs are expensed immediately, impacting near-term profitability, though the strategy is intended to expand recurring revenue and strengthen the advertising platform over time.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Allegiant to Acquire Sun Country, Forming a Major U.S. Leisure Airline Powerhouse

Allegiant Air and Sun Country Airlines have announced a definitive merger agreement that will combine two of the most established leisure-focused carriers in the United States, creating a larger, more competitive airline designed to thrive in a demand-driven travel market. Under the terms of the deal, Allegiant will acquire Sun Country in a cash-and-stock transaction valuing Sun Country at approximately $1.5 billion, including net debt.

Sun Country shareholders will receive $4.10 in cash and 0.1557 shares of Allegiant stock for each share they own, representing a nearly 20% premium over Sun Country’s recent trading price. Upon completion, Allegiant shareholders will own roughly 67% of the combined company, with Sun Country shareholders holding the remaining 33%. The transaction is expected to close in the second half of 2026, subject to regulatory and shareholder approvals.

The merger brings together two airlines with similar operating philosophies centered on flexibility, cost discipline, and leisure demand. Together, the combined airline will serve approximately 22 million passengers annually, operate nearly 195 aircraft, and offer more than 650 routes across nearly 175 cities. The companies’ networks are highly complementary, with Allegiant focused on small and mid-sized markets and Sun Country maintaining a stronger presence in larger metropolitan areas, particularly Minneapolis–St. Paul.

A major strategic benefit of the deal is expanded access to international leisure destinations. Sun Country’s existing routes to Mexico, Central America, Canada, and the Caribbean will significantly broaden Allegiant’s reach beyond domestic markets, allowing travelers from underserved U.S. cities to reach international vacation destinations more easily and affordably.

Financially, the companies expect meaningful upside. Allegiant projects the merger will generate approximately $140 million in annual synergies by the third year following closing, driven by network optimization, fleet efficiencies, and scale benefits. The transaction is expected to be accretive to earnings per share in the first year after closing, while maintaining a conservative balance sheet with net adjusted debt below three times EBITDAR.

Diversification is another key advantage of the combination. In addition to scheduled passenger service, Sun Country operates long-term charter and cargo businesses, including a multi-year agreement with Amazon Prime Air. When combined with Allegiant’s existing charter operations, the merged airline will benefit from more stable, year-round revenue streams that help offset the seasonality of leisure travel.

Customers are also expected to see improvements through a larger and more valuable loyalty program. The combined frequent flyer base will exceed 23 million members, offering expanded earning opportunities, enhanced rewards, and greater flexibility across a broader route network.

Leadership of the combined company will remain with Allegiant, which will continue as the publicly traded parent. Allegiant CEO Gregory C. Anderson will lead the merged airline, while Sun Country CEO Jude Bricker will join the board and serve as an advisor during the integration process. Allegiant will remain headquartered in Las Vegas, with a continued significant presence in Minneapolis–St. Paul.

Overall, the Allegiant–Sun Country merger represents a strategic bet on leisure travel demand, operational flexibility, and diversified revenue, positioning the combined airline to compete more effectively while delivering long-term value to shareholders, employees, and travelers alike.

Travelzoo (TZOO) – Hits A Little Turbulence On Its Ascent


Wednesday, October 29, 2025

Travelzoo® provides its 30 million members with exclusive offers and one-of-a-kind experiences personally reviewed by our deal experts around the globe. We have our finger on the pulse of outstanding travel, entertainment, and lifestyle experiences. We work in partnership with more than 5,000 top travel suppliers—our long-standing relationships give Travelzoo members access to irresistible deals.

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Softer than expected Q3 Results. The company reported Q3 revenue of $22.2 million, an increase of a solid 10.4%, and adj. EBITDA of $0.9 million, both of which were below our estimates of $23.0 million and $2.9 million, respectively. Importantly, the modestly softer than expected results were largely driven by weakness in advertising and increased marketing spend on customer acquisition.

Customer acquisition. Notably, in Q3, customer acquisition costs increased to $40 per customer, up from $38 in Q2 and $28 in Q1, reflecting the company’s strategic efforts to grow its subscriber base. Furthermore, despite higher acquisition spend per customer, return on spend remains positive. Total return per customer in Q3 was $55, which consists of $40 from annual subscription fees and $15 from in-quarter transactions. While this strategy impacted adj. EBITDA in Q3, it’s supportive of a favorable long term growth outlook.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – Travelzoo Reports Third Quarter 2025 Results

Travelzoo logo

Research News and Market Data on TZOO

Oct 28, 2025, 09:46 ET

NEW YORK, Oct. 28, 2025 /PRNewswire/ — Travelzoo® (NASDAQ: TZOO):

  • Revenue of $22.2 million, up 10% year-over-year
  • Consolidated operating profit of $0.5 million
  • Non-GAAP consolidated operating profit of $1.1 million
  • Cash flow from operations of ($0.4) million
  • Earnings per share (EPS) of $0.01

Travelzoo, the club for travel enthusiasts, today announced financial results for the third quarter ended September 30, 2025. Consolidated revenue was $22.2 million, up 10% from $20.1 million year-over-year. In constant currencies, revenue was $21.9 million, up 9% year-over-year. Travelzoo’s reported revenue consists of advertising revenues and commissions, derived from and generated in connection with purchases made by Travelzoo members, and membership fees.

In Q3, Travelzoo continued to invest significantly in acquiring more Club Members when we saw that we can achieve a payback and positive return on investment (ROI) within a quarter. Marketing costs were expensed immediately. Membership fees revenue is recognized ratably over the subscription period of 12 months. The effect is a sizable reduction in EPS. We refer to our investor presentation.

Net income attributable to Travelzoo was $0.2 million for Q3 2025, or $0.01 per share, compared with $0.26 per share in the prior-year period.

Non-GAAP operating profit was $1.1 million. Non-GAAP operating profit excludes amortization of intangibles ($2,000), stock option expenses ($399,000), and severance-related expenses ($167,000). Please refer to “Non-GAAP Financial Measures” and the tabular reconciliation below.

“We will continue to leverage Travelzoo’s global reach, trusted brand, and strong relationships with top travel suppliers to negotiate more Club Offers for Club Members and add new benefits, such as our popular complementary airport lounge access worldwide in case of a delayed flight,” said Holger Bartel, Travelzoo’s Global CEO. “Travelzoo members are affluent, active, and open to new experiences. We inspire travel enthusiasts to travel to places they never imagined they could. Travelzoo is the must-have membership for those who love to travel as much as we do.”

Travelzoo North America
North America business segment revenue increased 11% year-over-year to $14.2 million. Operating profit for Q3 2025 was $1.1 million, or 8% of revenue, compared to operating profit of $3.2 million or 25% of revenue in the prior-year period.

Travelzoo Europe
Europe business segment revenue increased 9% year-over-year to $6.6 million. Operating loss for Q3 2025 was $640,000, or 10% of revenue, compared to operating profit of $1.0 million, or 17% of revenue in the prior-year period. The reported operating loss occurred because we acquired more Club Members.

Jack’s Flight Club
Jack’s Flight Club is a membership subscription service in which Travelzoo has a 60% ownership interest. Revenue increased 12% year-over-year to $1.4 million. The number of premium subscribers increased 8% year-over-year. Jack’s Flight Club’s revenue from subscriptions is recognized ratably over the subscription period (quarterly, semi-annually, annually). Operating profit for Q3 2025 was $20,000, compared to operating profit of $27,000 in the prior-year period.

New Initiatives
New Initiatives business segment revenue, which includes Licensing and Travelzoo META, was $27,000. Operating loss for Q3 2025 was $20,000.

In 2020, Travelzoo entered into royalty-bearing licensing agreements with local licensees for the exclusive use of Travelzoo’s brand, business model, and members in  Australia, Japan, New Zealand, and Singapore. Under these arrangements, Travelzoo’s existing members in Australia, Japan, New Zealand, and Singapore will continue to be owned by Travelzoo as the licensor. Licensing revenue from the licensee in Australia was $9,000 for Q3 2025. Licensing revenue from the licensee in Japan was $7,000 for in Q3 2025. Licensing revenue is expected to increase going forward.

Reach
Travelzoo reaches 30 million travelers. This includes Jack’s Flight Club. Comparisons to prior periods are no longer meaningful due to strategic developments of the Travelzoo membership.

Income Taxes
The reported income tax provision and reserves for Q3 2025 are $244,000. Travelzoo intends to utilize available net operating losses (NOLs) to largely offset its tax liability for Q3 2025.

Balance Sheet
As of September 30, 2025, cash, cash equivalents and restricted cash were $9.2 million. Cash flow from operations was ($0.4) million.

Deferred revenue increased because membership fees revenue is recognized ratably over the subscription period.

Share Repurchase Program
During Q3 2025, the Company repurchased 148,602 shares of its outstanding common stock.

L ooking Ahead
For Q4 2025, we expect year-over-year revenue growth to continue. We expect revenue growth to accelerate as a trend in subsequent quarters, as membership fees revenue is recognized ratably over the subscription period of 12 months, as we acquire new members, and as more Legacy Members become Club Members. Over time, we expect profitability to substantially increase as recurring membership fees revenue will be recognized. In the short-term, fluctuations in reported net income are possible. We might see attractive opportunities to increase marketing. We expense marketing costs immediately.

In 2024, we introduced a membership fee for Travelzoo. Legacy Members, who joined prior to 2024, continue to receive certain travel offers. However, Club Offers and new benefits are only available to Club Members, who pay the membership fee. Therefore, we are seeing many Legacy Members become Club Members over time—in addition to new members who join.

Non-GAAP Financial Measures
Management calculates non-GAAP operating income when evaluating the financial performance of the business. Calculation of non-GAAP operating income, also called “non-GAAP operating profit” in this press release and today’s earnings conference call, excludes the following items: amortization of intangibles, stock option expenses, and severance-related expenses. This press release includes a table which reconciles GAAP operating income to the calculation of non-GAAP operating income. Non-GAAP operating income is not required by, or presented in accordance with, generally accepted accounting principles in the United States of America (“GAAP”). This information should be considered as supplemental in nature and should not be considered in isolation or as a substitute for the financial information prepared in accordance with GAAP. In addition, these non-GAAP financial measures may not be the same as similarly titled measures reported by other companies.

Conference Call
Travelzoo will host a conference call to discuss third quarter 2025 results today at 11:00 a.m. ET. Please visit http://ir.travelzoo.com/events-presentations to

  • download the management presentation (PDF format) to be discussed in the conference call
  • access the webcast.

About Travelzoo
We, Travelzoo®, are the club for travel enthusiasts. We reach 30 million travelers. Club Members receive Club Offers personally reviewed by our deal experts around the globe. We have our finger on the pulse of outstanding travel, entertainment, and lifestyle experiences. We work in partnership with thousands of top travel suppliers—our long-standing relationships give us access to irresistible deals.

Certain statements contained in this press release that are not historical facts may be forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities and Exchange Act of 1934. These forward-looking statements may include, but are not limited to, statements about our plans, objectives, expectations, prospects and intentions, markets in which we participate and other statements contained in this press release that are not historical facts. When used in this press release, the words “expect”, “predict”, “project”, “anticipate”, “believe”, “estimate”, “intend”, “plan”, “seek” and similar expressions are generally intended to identify forward-looking statements. Because these forward-looking statements involve risks and uncertainties, there are important factors that could cause actual results to differ materially from those expressed or implied by these forward-looking statements, including changes in our plans, objectives, expectations, prospects and intentions and other factors discussed in our filings with the SEC. We cannot guarantee any future levels of activity, performance or achievements. Travelzoo undertakes no obligation to update forward-looking statements to reflect events or circumstances occurring after the date of this press release.

View full release here.

Investor Relations:
[email protected]

SOURCE Travelzoo

Release – Travelzoo Q3 2025 Earnings Conference Call on October 28 at 11:00 AM ET

Travelzoo logo

Research News and Market Data on TZOO

Oct 22, 2025, 11:24 ET

NEW YORK, Oct. 22, 2025 /PRNewswire/ — Travelzoo® (NASDAQ: TZOO):

WHAT:Travelzoo, the club for travel enthusiasts, will host a conference call to discuss the Company’s financial results for the third quarter ended September 30, 2025. Travelzoo will issue a press release reporting its results before the market opens on October 28, 2025.
WHEN:  October 28, 2025 at 11:00 AM ET
HOW:  A live webcast of Travelzoo’s Q3 2025 earnings conference call can be accessed at http://ir.travelzoo.com/events-presentations. The webcast will be archived within 2 hours of the end of the call and will be available through the same link.
CONTACT:  Travelzoo Investor Relations
 [email protected]

A b ou t Travelzoo
We, Travelzoo®, are the club for travel enthusiasts. We reach 30 million travelers. Club Members receive Club Offers personally reviewed by our deal experts around the globe. We have our finger on the pulse of outstanding travel, entertainment, and lifestyle experiences. We work in partnership with thousands of top travel suppliers—our long-standing relationships give us access to irresistible deals.

SOURCE Travelzoo

Travelzoo (TZOO) – Steps On The Customer Acquisition Accelerator


Thursday, July 24, 2025

Travelzoo® provides its 30 million members with exclusive offers and one-of-a-kind experiences personally reviewed by our deal experts around the globe. We have our finger on the pulse of outstanding travel, entertainment, and lifestyle experiences. We work in partnership with more than 5,000 top travel suppliers—our long-standing relationships give Travelzoo members access to irresistible deals.

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Mixed second quarter results. Revenues significantly increased 13.1% to $23.9 million, a sequential quarterly increase from 5.3% in Q1, reflecting its strategic shift toward a subscription based model. Adj. EBITDA fell short of our expectations, however, due to a step up in customer acquisition spend and the purchase of “distressed” vouchers. 

Favorable customer acquisition dynamics. Customer acquisition costs went up in Q2 to $38 from $28 in Q1, but still remains positive. Total return is $58, $40 from the annual subscription fee and $18 from transactions. Management anticipates to continue to aggressively spend on customer acquisition in light of the favorable Return on Investment. These moves support a longer term attractive revenue outlook, but have a near term adverse impact on adj. EBITDA.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.