MAIA Biotechnology (MAIA) – Heading Into 4Q After Strong Clinical Progress


Tuesday, September 22, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Phase 2 Extension Stage Has Begun Treatment At US Sites. MAIA began treating patients at three US sites in the Part C Expansion Phase of its Phase 2 THIO-101 trial. The trial tests ateganosine (aka THIO) in non-small cell lung cancer (NSCLC) and had completed the planned patient enrollment at international sites worldwide. Two additional US sites are expected to open during 2026.

Initial Data Shows Consistent Efficacy. In June 2026, MAIA announced initial efficacy data from the ongoing Phase 2 THIO-101 Part C Expansion Stage. Patients with at least one post-treatment evaluation by tumor scan showed a disease control rate (DCR) of 90.5% in the evaluable population. We believe that data consistent with Parts A and B could allow the company to apply for Accelerated Approval and Priority Review.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Titan International (TWI) – To Sell ITM Business


Tuesday, September 22, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

A Sale. Titan International entered into an agreement to sell its Italtractor ITM undercarriage business. The sale is expected to generate cash value of approximately $285 million, which includes a $207 million initial purchase price, $6 million of potential earnout proceeds, $23 million of customary adjustments based on ITM’s net assets and financial position at closing, and $49 million of dividends, consisting of $38 million received in recent years and $11 million expected prior to closing. The deal is expected to close in early January.

Focus. We expect Titan to use the proceeds to sharpen its focus on the core global wheel and tire operations serving the agriculture, construction, and consumer markets. Investments are expected to be focused on the Company’s highest growth opportunities and may include the purchase of adjacent businesses. A portion of the proceeds may be used to reduce outstanding net debt, which totaled $413 million as of June 30th.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Greenland Stocks Doubled Today. The Rare Earths Aren’t Here Yet

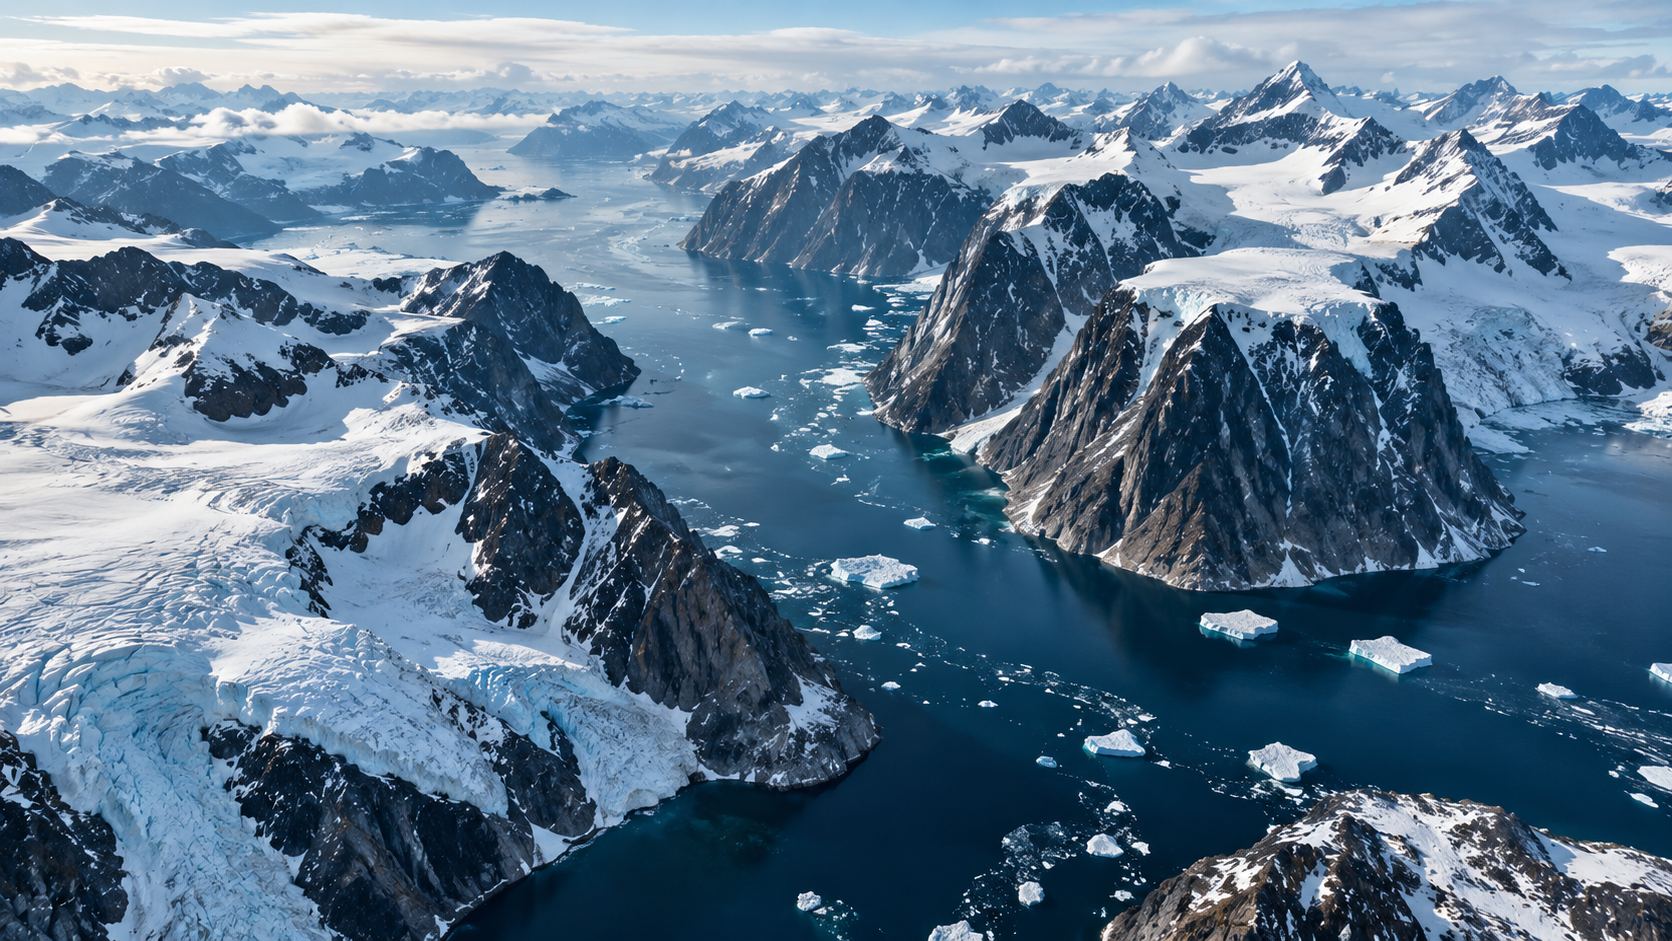
Shares of several US-listed companies with exposure to Greenland exploded higher Monday after the United States, Denmark, and Greenland reached an agreement on expanded American security arrangements on the Arctic territory. Greenland Energy surged more than 165% in premarket trading, Greenland Mines climbed over 110%, and Critical Metals Corp rose nearly 30%. The moves reflect genuine excitement about what this agreement could eventually unlock, though the timeline and feasibility of actually extracting Greenland’s mineral wealth remain far less certain than the stock charts suggest.

The framework, announced September 18 and expected to be formally signed this week during the United Nations General Assembly, expands US defense construction rights on the island, granting Washington unilateral authority to build and expand military infrastructure without case-by-case approval from Copenhagen or Nuuk. It also guarantees permanent basing, transit, and overflight rights, while formally restricting adversary nations, specifically China and Russia, from establishing military positions or making what the agreement calls sensitive investments, a provision that appears squarely aimed at critical minerals and mining. Importantly, Greenland’s sovereignty remains fully with the Kingdom of Denmark under the deal, and the agreement still requires parliamentary approval before taking effect, meaning this is a framework, not yet a finalized, binding arrangement.

The strategic logic is straightforward on paper. Greenland sits on substantial untapped reserves of rare earth elements, the materials essential to defense systems, electric vehicles, and advanced electronics, and a security agreement that locks out Chinese and Russian involvement positions the island as a potential Western alternative to China’s current dominance of the global rare earth supply chain, a theme we detailed closely when covering Energy Fuels’ recent mine-to-magnet acquisition earlier this year.

The three companies driving today’s rally each have a distinct claim to that opportunity. Critical Metals Corp is developing the Tanbreez rare earths mine in southern Greenland and already holds a 15-year offtake partnership with magnet manufacturer REalloys covering up to 15% of the project’s future production. Greenland Mines is advancing the Skaergaard project, one of the world’s largest undeveloped palladium, gold, and platinum deposits, alongside a separate neodymium-praseodymium rare earths project. Greenland Energy is pursuing oil and gas exploration rather than rare earths specifically, though it recently delayed its own drilling plans after Greenland’s government issued a formal warning to its joint venture partner over bringing equipment ashore without proper authorization, a reminder that operating in Greenland carries real regulatory friction even with Washington’s backing.

Independent industry analysts have raised serious and specific concerns about how quickly, or whether, any of this translates into actual production. Multiple recent assessments from mining and metals consultancies note that Greenland’s rare earth deposits face unresolved processing economics, significant Arctic infrastructure deficits, no existing non-Chinese separation capacity anywhere on the island, and in some cases genuine radioactive waste concerns tied to the specific mineralogy of these deposits. Outside the capital city of Nuuk, much of Greenland depends on ships, aircraft, and dog sleds for basic transport, and its harsh climate and remoteness substantially raise the cost of any extraction effort. As several analysts have put it, security guarantees may attract Western capital, but they cannot substitute for proven metallurgy, functioning ports, reliable power, skilled labor, and an actual mine-to-magnet supply chain, all of which still need to be built essentially from scratch.

Greenland is not the only place this strategic push is playing out, and investors don’t need direct exposure to the island itself to participate in the broader theme. A wider push toward allied, non-Chinese critical mineral development has been building across North America for the past several years, with junior mining companies in the United States and Canada working to establish domestic and allied supply chains for materials the world currently sources overwhelmingly from China. Companies like Century Lithium Corp and Tectonic Metals Inc, both developing projects in North American jurisdictions, are not connected to today’s Greenland agreement in any way, but they operate in the same strategic category, positioning allied-nation mineral resources as an alternative to Chinese dominance, that is fueling investor enthusiasm for Greenland right now.

For investors, today’s moves are a clear example of a security and geopolitical catalyst driving share prices far ahead of underlying commercial reality. That doesn’t mean the opportunity isn’t real, both the Trump administration’s strategic interest and the individual companies’ project economics could genuinely develop over time. But the gap between a triple-digit percentage stock move today and a functioning rare earth supply chain years from now is substantial, and investors should weigh the extraction and infrastructure challenges just as carefully as the geopolitical tailwind.

Release – Titan International Signs Definitive Agreement to Sell ITM Business to USCO S.p.A.

Titan Logo

Research News and Market Data on TWI

Sep 21, 2026

Transaction expected to generate up to approximately $285 million in total cash value

WEST CHICAGO, Ill., Sept. 21, 2026 /PRNewswire/ — Titan International, Inc. (NYSE: TWI) (“Titan” or the “Company”), a leading global manufacturer of off-highway wheels, tires and undercarriage products, today announced that it has entered into a definitive agreement to sell its Italtractor ITM undercarriage business (“ITM”) to USCO S.p.A. (“USCO”).

Under the terms of the agreement, Titan will receive an initial purchase price of $207 million, plus the opportunity to receive an additional $6 million in earnout proceeds based on ITM’s achievement of specified performance criteria for 2026. The transaction is also subject to customary adjustments based on ITM’s specified net asset and financial position at closing, which Titan currently expects will provide approximately $23 million of additional cash value. In connection with the transaction, Titan has received or expects to receive $49 million in dividends from ITM, consisting of $38 million received in recent years and $11 million expected prior to closing. Taken together, these amounts are expected to provide Titan with up to approximately $285 million in total cash value, including the potential earnout.

For Titan, the transaction will allow the Company to sharpen its strategic focus on its core global wheel and tire operations serving the agricultural, construction and consumer markets. It will also significantly strengthen Titan’s financial position and provide greater flexibility to invest behind the Company’s highest-priority growth opportunities.

“It has been approximately ten (10) years since I left the President/CEO position to Paul Reitz and forty-three (43) years since Titan started with no employees and no sales. So, you might say I have seen a lot. The potential sale of ITM was first discussed with Titan’s Board of Directors over ten (10) years when Titan was approached with an offer of less than $100 million. The deal Paul and his team completed has required a lot of patience and I know I could not have gotten this deal done because I do not have that level of patience. This deal is good for Titan and good for USCO. TWI received a fair price, and USCO will now have a strong track manufacturing business with a good brand and great people.

Looking back a decade ago, the primary task for me was finding my replacement. Well, there is no doubt I chose the right man! Paul has led this team for over ten (10) years and done an excellent job. The last ten (10) years have been tough, but as President Trump said we are going into the Golden Age. India has been flooding our country with offroad tires and wheels using unfair practices as we have proven with the International Trade Commission. President Trump is focused on bringing back manufacturing to the USA, but it’s a difficult situation in our industry that requires people understanding real manufacturing of converting raw materials into finished products. I feel that the White House sometimes loses its way with financial people having too much of a say and not enough people that understand real manufacturing.

Our Board of Directors feels there are good opportunities out there to utilize the sale proceeds to explore the purchase of other businesses. TWI has a very bright future because of the depth of our product portfolio and manufacturing footprint. Titan is the world leader in both wheels and tires in the farm industry and let’s not forget the decades of investment we have made with technical engineering and tooling into the large Ag wheels and tires that we produce. Our innovation pipeline of new products has been strong in recent years for farm, industrial and consumer products, and we have been achieving this at competitive cost levels for our customers at the same time.

I am inflating my own ego, because of what Paul and his team pulled off with this transaction and how good I feel that Titan is entering the Golden Age of manufacturing. Paul has also put a group in TWI to make a push into Defense business. Which could be very large for Titan in the next few years. I am betting most of you reading this did not know that TWI made the first aluminum wheels for auto/pickup in the early 90’s. Today 100% of vehicle/passenger wheels are made in China, India and Japan. That means all cars and pickups could be stopped without wheels in USA! 80 million wheels each year are imported. That is $8 Billion dollars each year in income. Yes, I believe the Golden years are ahead, and TWI has proven leadership in Paul Reitz and his team. As the Pointer Sisters song goes ‘I’m so excited’ – that’s me an old man.

The last acquisition that Titan made was the Carlstar Group Wheels & Tires. So far, it has proven to be a really good deal. I should also mention that over the last few years, TWI has bought back over $100 million shares of TWI Common Stock with its cash flow. Paul’s team has done an excellent job. I hope the Golden Age of Manufacturing comes to the USA for TWI has the capacity to easily double production in wheels and tires. There are very few in this world that could make that statement. Thank you for taking the time to read this note.

In conclusion, I want to thank Cecilia La Manna for her invaluable service and many contributions to ITM and Titan. I’ve known Cecilia for nearly 30 years, and I’ve watched her grow into an incredible global business leader. Her determination and commitment is a significant reason why ITM is the business that it is today. USCO is getting much more than a good business and plants, they are getting a strong management team. Cecilia and her team will continue to do great things for USCO and lead them well into a prosperous future.

If you are ever in Illinois – Quincy or Freeport; Tennessee – Union City or Clinton; Bryan, Ohio, Sao Paulo, Brazil, Kidderminster, UK; Meizhou, China and Finale Emilia (list locations), I invite you as a Shareholder to stop in and see how our products are made.

— Maurice M. Taylor, Jr., Chairman of Titan’s Board of Directors

“This transaction is an important step forward in Titan’s transformation. We have worked hard to reach an agreement that delivers strong value for Titan and provides ITM with an owner that understands the undercarriage business and is committed to its future. The transaction will allow Titan to focus our people, capital and resources on our core global wheel and tire operations while giving us the financial capacity to pursue accretive growth opportunities and reduce debt. This transaction helps Titan to reshape its portfolio, accelerate strategic investments, pursue transformative acquisitions and partnerships, and create long-term value for our shareholders.”

— Paul Reitz, President and Chief Executive Officer of Titan

The transaction represents an important strategic step for both organizations. As part of USCO, ITM will have the opportunity to build on its position as a global provider of undercarriage components and complete undercarriage solutions, with additional focus and resources to support long-term growth, customer service, product innovation and geographic expansion. ITM designs, manufactures and distributes undercarriage systems and components for construction, mining, forestry, road-building and agricultural applications through a global manufacturing and distribution network.

Titan currently intends to use a portion of the transaction proceeds to reduce existing debt and strengthen its balance sheet. In future periods, the Company also expects to deploy capital toward key growth investments, including accretive acquisitions and strategic partnerships that expand Titan’s capabilities, strengthen its market positions and support the Company’s long-term transformation.

The transaction is expected to close early in January 2027, subject to the satisfaction of customary closing conditions, including required regulatory approvals and other customary conditions. Until closing, ITM and Titan will continue to operate in the ordinary course of business. The parties anticipate completion shortly following receipt of all required regulatory approvals.

Titan and ITM were advised by the law firm Gianni & Origoni on legal matters and by Poggi & Associati on tax matters. USCO has been assisted by Eidos Partners as financial advisor, by the law firm Simmons+Simmons and by BDO and KPMG as due-diligence consultants

ITM is a global designer, manufacturer and service provider of undercarriage components and complete undercarriage solutions. The business serves original equipment and aftermarket customers across construction, mining, forestry, road-building, agricultural and other specialized applications through an international manufacturing, service and distribution network. ITM is also a pioneer in undercarriage sensor technology, including its TRUST ITM® monitoring solution.

About Titan International, Inc.

Titan International, Inc. (NYSE: TWI) is a leading global manufacturer and supplier of wheels, tires and undercarriage products for a wide variety of off-the-road equipment. Titan serves aftermarket dealers and original equipment manufacturers across the agricultural, earthmoving, mining, construction and consumer sectors.

Forward-Looking Statements

This press release contains forward-looking statements, including statements regarding the expected closing of the transaction, the anticipated purchase-price adjustments and earnout payment, the total value expected to be realized by Titan, the intended use of proceeds, debt reduction, potential acquisitions and partnerships, future investments, and the expected benefits of the transaction to Titan and ITM. These statements are based on Titan’s current expectations and are subject to risks and uncertainties that could cause actual outcomes to differ materially.

These risks and uncertainties include, among others, the ability to obtain required regulatory approvals and satisfy other closing conditions; the timing or failure of the transaction to close; changes in ITM’s net financial or asset position; ITM’s ability to achieve the performance criteria associated with the earnout; foreign-exchange-rate fluctuations; Titan’s ability to reduce debt or identify and complete attractive acquisitions, partnerships or investments; and other risks described in Titan’s filings with the Securities and Exchange Commission. Titan undertakes no obligation to update any forward-looking statement except as required by law.

Exchange-rate note: U.S. dollar amounts are approximate and were translated using an exchange rate of €1.00 to $1.148 as of September 18, 2026.

Titan International, Inc. logo. (PRNewsFoto/Titan International)

Cision View original content to download multimedia:https://www.prnewswire.com/news-releases/titan-international-signs-definitive-agreement-to-sell-itm-business-to-usco-spa-302884962.html

SOURCE Titan International, Inc.

Release – Kratos and GE Aerospace Achieve Significant Program Milestone with Successful Ignition of GEK800 Turbofan Cruise Missile Propulsion System

Primary Logo

Research News and Market Data on KTOS

September 21, 2026

PDF VersionTest at Kratos X-58 Test Facility Keeps Cost-Effective, Advanced Strike Technology on Schedule as High-Performance Jet Engine Advances Toward Production

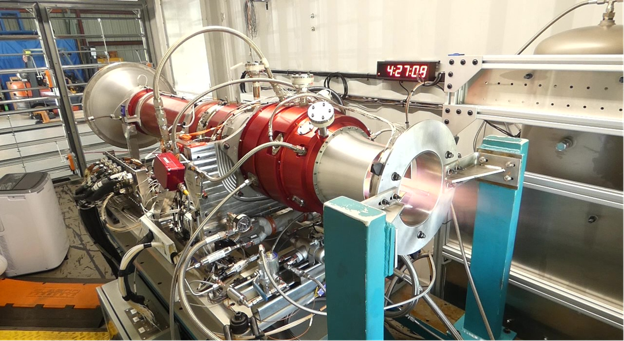
SAN DIEGO, Sept. 21, 2026 (GLOBE NEWSWIRE) — Kratos Defense & Security Solutions, Inc., (NASDAQ: KTOS) a technology company in the defense, national security and global markets, and GE Aerospace (NYSE: GE) announced a key program milestone with the successful ignition of the GEK800 turbofan cruise missile propulsion system. Recently, the GEK800 Serial Number 1 was tested at the X-58 test facility, igniting successfully. This achievement initiates a new testing campaign and demonstrates a 100 percent success rate for this critical phase of development, keeping the program on schedule.

Recently designated the F143 and designed to meet the defined requirements of the Department of War for long-range, stand-off strike capabilities, the GEK800 represents a significant advancement in affordable, high-performance cruise missile technology. By leveraging modern engineering and cost-effective manufacturing processes, Kratos and GE Aerospace are positioned to deliver substantial capability and value to the warfighter.

“The combined Kratos, GE Aerospace, and Government test team has demonstrated exceptional focus, discipline, and schedule execution,” said Chris Rawlings, Vice President of Kratos’ Defense Engine Portfolio. “This team sets the benchmark for operational efficiency and provides a refreshing reminder that our nation can develop turbine engines affordably and at pace.”

“With this latest milestone, the GEK800 engine continues to demonstrate strong performance and durability,” said Jorge Perez, General Manager of Edison Works Advanced Combat Engines at GE Aerospace. “Our collaboration with Kratos is delivering a highly capable propulsion system designed to meet the demanding requirements of cruise missile applications.”

Delivering Capability to the Department of War and Industry Partners 
For the Department of War and allied defense prime contractors, the GEK800 provides a practical solution to the demand for rapid capability deployment and attritable strike assets. The successful test at X-58 validates the system’s technological architecture, reliability, and readiness for integration. Kratos and GE Aerospace remain focused on providing cruise missile solutions that maintain performance while lowering lifecycle costs, enabling prime contractors to offer highly competitive missile solutions to government procurement programs.

Stacey Rock, President of Kratos’ Turbine Technologies Division, said, “Kratos continues to achieve milestones and accelerate program schedules as we prepare for large volume production of our GEK800 engine to support advanced cruise missile systems.”

GEK800 Tested at Kratos X-58 Test Facility

GEK800 Tested at Kratos X-58 Test Facility

A photo accompanying this announcement is available at https://www.globenewswire.com/NewsRoom/AttachmentNg/b46c295c-8483-402d-a748-e8b158e577fd

About Kratos Defense & Security Solutions
Kratos Defense & Security Solutions, Inc. (NASDAQ: KTOS) is a technology, products, system and software company addressing the defense, national security, and commercial markets. Kratos makes true internally funded research, development, capital and other investments, to rapidly develop, produce and field solutions that address our customers’ mission critical needs and requirements. At Kratos, affordability is a technology, and we seek to utilize proven, leading-edge approaches and technology, not unproven bleeding edge approaches or technology, with Kratos’ approach designed to reduce cost, schedule and risk, enabling us to be first to market with cost effective solutions. We believe that Kratos is known as an innovative disruptive change agent in the industry, a company that is an expert in designing products and systems up front for successful rapid, large quantity, low-cost future manufacturing which is a value-add competitive differentiator for our large traditional prime system integrator partners and also to our government and commercial customers. Kratos intends to pursue program and contract opportunities as the prime or lead contractor when we believe that our probability of win (PWin) is high and any investment required by Kratos is within our capital resource comfort level. We intend to partner and team with a large, traditional system integrator when our assessment of PWin is greater or required investment is beyond Kratos’ comfort level. Kratos’ primary business areas include virtualized ground systems for satellites and space vehicles including software for command & control (C2) and telemetry, tracking and control (TT&C), jet powered unmanned aerial drone systems, hypersonic vehicles and rocket systems, propulsion systems for drones, missiles, loitering munitions, supersonic systems, space craft and launch systems, C5ISR and microwave electronic products for missile, radar, missile defense, space, satellite, counter UAS, directed energy, communication and other systems, and virtual & augmented reality training systems for the warfighter. For more information, visit www.KratosDefense.com and follow Kratos on LinkedIn and X.

About GE Aerospace
GE Aerospace is a global aerospace propulsion, services, and systems leader with an installed base of approximately 50,000 commercial and 30,000 military aircraft engines. With a global team of approximately 57,000 employees building on more than a century of innovation and learning, GE Aerospace is committed to inventing the future of flight, lifting people up, and bringing them home safely. Learn more about how GE Aerospace and its partners are defining flight for today, tomorrow, and the future at www.geaerospace.com.

Notice Regarding Forward-Looking Statements
Certain statements in this press release may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are made on the basis of the current beliefs, expectations and assumptions of the management of Kratos and are subject to significant risks and uncertainty. Investors are cautioned not to place undue reliance on any such forward-looking statements. All such forward-looking statements speak only as of the date they are made, and Kratos undertakes no obligation to update or revise these statements, whether as a result of new information, future events or otherwise. Although Kratos believes that the expectations reflected in these forward-looking statements are reasonable, these statements involve many risks and uncertainties that may cause actual results to differ materially from what may be expressed or implied in these forward-looking statements. For a further discussion of risks and uncertainties that could cause actual results to differ from those expressed in these forward-looking statements, as well as risks relating to the business of Kratos in general, see the risk disclosures in the Annual Report on Form 10-K of Kratos for the year ended December 28, 2025, and in subsequent reports on Forms 10-Q and 8-K and other filings made with the SEC by Kratos.

Kratos Press Contact:
Claire Cantrell
[email protected]

Kratos Investor Information:
877-934-4687
[email protected]

GE Aerospace Press Contact:
Deb Case
[email protected]

Release – First Phosphate Reports Publication of Peer-Reviewed Study of the Bégin-Lamarche Igneous Phosphate Deposit in Ore Geology Reviews

First Phosphate Corp.

Research News and Market Data on PHOS

September 21, 2026 7:07 AM EDT | Source: First Phosphate Corp.

Saguenay, Quebec–(Newsfile Corp. – September 21, 2026) – First Phosphate Corp. (NASDAQ: PHOS) (CSE: PHOS) (OTCQX: FRSPF) (FSE: KD0) (“First Phosphate” or the “Company“) is pleased to announce that the Company’s Bégin-Lamarche Igneous Phosphate Deposit has been subject of a peer-reviewed study in Ore Geology Reviews (published on ScienceDirect), a premier scientific journal focusing on ore genesis and exploration.

The study highlights how economic, phosphate-rich layers in the Bégin-Lamarche deposit were formed. Results indicate these layers are low in chlorine and other trace elements making them suitable as a potential high-purity source of phosphate for production of purified phosphoric acid (“PPA”), a critical precursor in the manufacture of lithium iron phosphate (“LFP”) battery cathode active material.

The full peer-reviewed publication is accessible via ScienceDirect at:

https://www.sciencedirect.com/science/article/pii/S0169136826000375?via%3Dihub

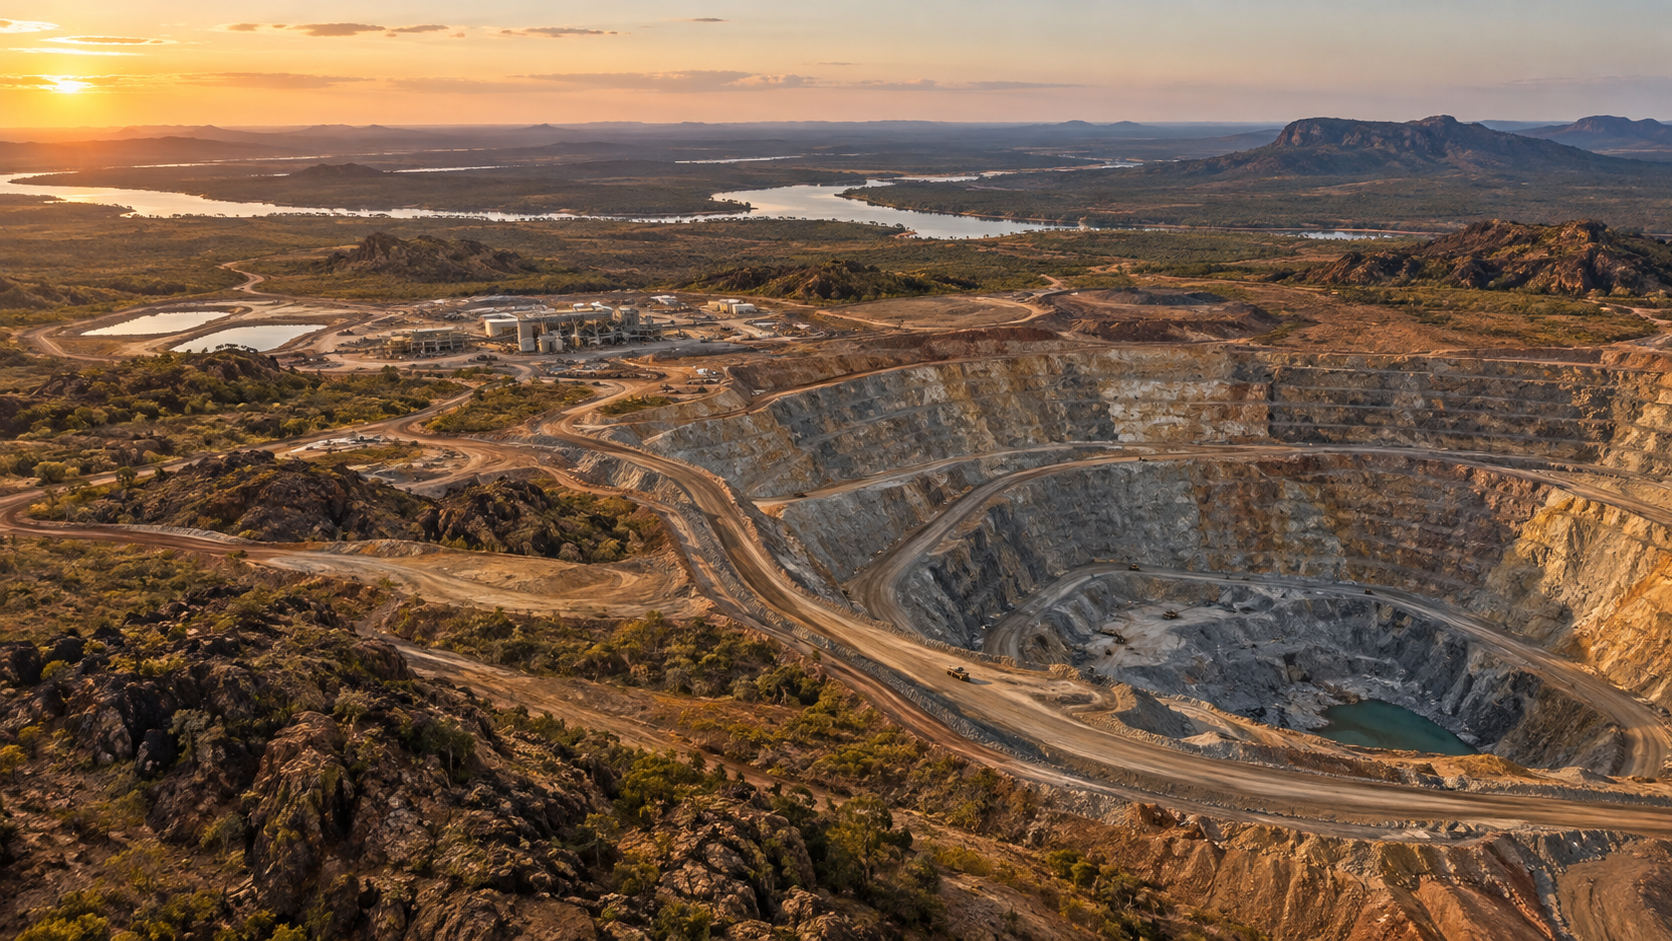
The research, authored by scientists from Queen’s University and Université du Québec à Chicoutimi (UQAC), focuses on the geological characterization of the Mountain, North and South Zones of the Company’s Bégin-Lamarche igneous phosphate deposit, part of the 1.14 Ga Lac-Saint-Jean Anorthositic (“LSJA”) Suite – the largest anorthosite complex in the world.

Through detailed mineralogical, petrological and geochemical analysis, the study further reinforces the strategic importance of Québec igneous phosphate as a secure North American feedstock source capable of supporting First Phosphate’s vertical integration strategy along the LFP battery supply chain.

The conclusions of the study are summarized below:

  1. The Bégin-Lamarche deposit is hosted in massif anorthosite and associated nelsonite and oxide-apatite-mafic to ultramafic rocks of the Lac-Saint-Jean Anorthositic Suite. Apatite represents the primary phosphatic mineralization confirming the magmatic origin and geological continuity of the phosphate-bearing zones across the Mountain, North and South Zones.
  2. Analytical results demonstrate that the phosphate mineralization is capable of producing a high-grade phosphate concentrate. Testing indicates concentrate levels around ~40% P₂O₅, which aligns above global averages for igneous phosphate concentrates and supports suitability for PPA production.
  3. Geochemical characterization demonstrates low levels of deleterious trace elements unlike those which are commonly associated with sedimentary phosphate deposits. Such low concentrations of deleterious trace elements enhance the potential for producing high-purity PPA suitable for LFP cathode active material applications.
  4. The geometry, thickness and near-surface occurrence of certain phosphate layers suggest favorable conditions for potential open-pit mining scenarios, subject to further engineering and mine planning studies, thereby supporting the long-term development potential of the deposit.

These findings provide the foundation for the exploration of other igneous phosphate layers throughout the Québec anorthosite that are suitable for LFP battery production. Results may apply to other phosphatic anorthosites globally offering new insights for high-purity phosphate resource development.

Qualified Person

The scientific and technical disclosure for First Phosphate included in this news release has been reviewed and approved by Steeve Lavoie, P.Geo. Mr. Lavoie is Chief Geologist of First Phosphate and a Qualified Person under National Instrument 43-101 – Standards of Disclosure of Mineral Projects (“NI 43-101”).

About ScienceDirect

ScienceDirect, operated by Elsevier, is the premier platform for peer-reviewed scientific, technical and health literature. It provides access to millions of journal articles and book chapters across more than 3,000 peer-reviewed journals and tens of thousands of books. ScienceDirect supports interdisciplinary research and delivers trusted, high-quality scientific content to researchers, engineers, academics and industry professionals worldwide. Through advanced search tools and AI-powered features, ScienceDirect enables efficient discovery and exploration of validated scientific evidence to accelerate innovation and informed decision-making.

About First Phosphate Corp.

First Phosphate (NASDAQ: PHOS) (CSE: PHOS) (OTCQX: FRSPF) (FSE: KD0) is a mineral exploration and development and clean technology company dedicated to building and reshoring a vertically integrated mine-to-market supply chain for production of LFP batteries in North America. Target markets include energy storage, data centers, robotics, mobility, and national security. First Phosphate’s flagship Bégin-Lamarche property, located in Saguenay-Lac-Saint-Jean, Québec, Canada, represents a rare North American igneous phosphate resource producing high-purity phosphate characterized by very low levels of impurities.

For further information, please contact:

Steeve Lavoie
Chief Geologist
Tel: +1 (418) 815-5416

Investor Relations: https://firstphosphate.com/investors
Media Relations: https://firstphosphate.com/contact
Website: www.FirstPhosphate.com

Follow First Phosphate:

Twitter: https://twitter.com/FirstPhosphate
LinkedIn: https://www.linkedin.com/company/first-phosphate/

– 30 –

Forward-Looking Information and Cautionary Statements

This press release contains certain statements and information that may be considered “forward-looking statements” and “forward-looking information” within the meaning of applicable securities laws. In some, but not necessarily all, cases, forward-looking statements and forward-looking information can be identified by the use of forward-looking words such as “expects,” “aims,” “anticipates” or “does not expect,” “should,” “is likely to,” “estimates,” “intends,” “assumes,” “anticipates” or “does not anticipate,” or “believes,” or variations of such words and phrases, or by statements indicating that certain actions, events or results “may,” “could,” “should,” “are likely to,” “will,” or “will be undertaken,” “occur,” or “be achieved,” and other similar expressions. Furthermore, statements in this press release that are not historical facts are forward-looking statements, including, but not limited to: expectations regarding the potential mineralization, geological merit and economic feasibility of the Company’s projects, including the layers’ suitability as a potential high-purity source of phosphate for the production of PPA, Québec igneous phosphate being a source capable of supporting First Phosphate’s vertical integration strategy into the LFP battery supply chain, the future production and grade of phosphate concentrate, the potential for producing high-purity phosphoric acid suitable for LFP cathode active material applications, favorable conditions for potential open-pit mining scenarios and the long-term development potential of the property. Although the Company believes that the expectations expressed in these forward-looking statements are based on reasonable assumptions, these statements are not guarantees of future performance, and actual results or developments may differ materially from those anticipated in the forward-looking statements. Factors that could cause actual results to differ materially from those expressed in the forward-looking statements include development and exploration successes, the continued availability of capital and financing, and general economic, market, or business conditions. These statements are based on a number of assumptions, including: that the engineering and construction schedules and capital costs associated with the Company’s exploration, development, and expansion projects are correctly estimated and will not be affected by unforeseen circumstances; the ability to obtain financing for the proposed activities on acceptable terms; the absence of a material deterioration in general commercial and economic conditions; the absence of significant delays in obtaining permits and other approvals; and the absence of significant disruptions affecting the Company’s operations or its ability to access the operating equipment, services, and supplies required for the project.in sufficient quantities and in a timely manner; the maintenance of inflation and project input prices at levels approximately in line with expectations; the ability to carry out exploration and development programs in accordance with the Company’s expectations; expectations regarding commodity prices, including assumptions concerning P2O5; the maintenance of the Company’s relationships with local municipalities and First Nations in accordance with its expectations; the maintenance of the Company’s relationships with its other partners and third-party suppliers in accordance with its expectations; and the maintenance of relationships with governments and government actions in accordance with the Company’s expectations. Investors are cautioned that these statements are not guarantees of future performance and that actual results or developments may differ materially from those projected in forward-looking statements. Accordingly, readers should not place undue reliance on the forward-looking information contained in this press release. The Company assumes no obligation to update or revise its forward-looking statements, whether as a result of new information, future events or otherwise, except as required by applicable law. All forward-looking information contained in this press release is subject to these cautionary statements.

info

Source: First Phosphate Corp.

Artemis Gold to Acquire Vista Gold in $427 Million All-Stock Deal for Australia’s Mt Todd Project

Artemis Gold (TSXV: ARTG) has agreed to acquire Vista Gold (NYSE American, TSX: VGZ) in an all-stock transaction valued at approximately $427 million, the companies announced September 20, 2026. Under the deal, Vista Gold shareholders will receive 0.0966 Artemis Gold shares for each share they hold, implying a value of $2.83 per Vista Gold share, a 29% premium to Vista Gold’s 20-day volume-weighted average price and a 25% premium to its last closing price. The transaction is expected to close in January 2027, pending shareholder, court, and regulatory approval, including sign-off from Australia’s Foreign Investment Review Board.

The acquisition gives Artemis Gold full ownership of the Mt Todd gold project in Australia’s Northern Territory, a feasibility-stage development asset hosting 9.1 million ounces of measured and indicated gold resources plus 1.4 million ounces of inferred resources. Mt Todd already holds key permits for a 50,000 tonne per day processing facility, meaning the project arrives with major regulatory hurdles already cleared, a significant factor in its valuation. No cash or new debt is involved in the deal, and existing Artemis Gold shareholders will own approximately 95% of the combined company once it closes.

Importantly, Artemis Gold has been clear that this acquisition does not change its near-term priorities. The company’s Blackwater mine in British Columbia, specifically its Phase 1A and EP2 expansion projects, remains the primary focus and funding priority. Blackwater is expected to produce more than 500,000 ounces of gold annually with industry-leading costs following the completion of EP2 in mid-2028. Construction spending at Mt Todd is not expected to begin until after that Blackwater expansion is fully operational, meaning the two projects are sequenced rather than competing for capital simultaneously. Combined, Artemis Gold has outlined a pathway toward producing more than one million ounces of gold annually once both assets are fully developed.

For Vista Gold shareholders, the deal offers an immediate cash-free premium along with continued exposure to Mt Todd’s development, now backed by a management team with a demonstrated track record building large-scale gold mines, along with the financial strength of a larger, cash-generating producer rather than a single-asset developer.

This transaction reflects a broader pattern in the gold mining sector this year, as sustained strength in gold prices has made permitted, advanced-stage development assets increasingly valuable acquisition targets for producers with the balance sheet to fund construction, a dynamic we detailed when covering gold’s sharp rally earlier this year. For investors tracking the small and microcap mining space, this deal is a useful example of how a single-asset developer with strong technical merit but limited standalone funding capacity can create real shareholder value by combining with a larger, better-capitalized producer, rather than attempting to finance construction independently.

That dynamic extends well beyond this single transaction. Smaller precious metals developers such as Tectonic Metals, Aurania Resources, and Kuya Silver Corporation occupy a similar position in the market today, advancing early or mid-stage gold and precious metals projects with real technical merit but the same standalone funding constraints Vista Gold faced before this deal. As gold prices remain elevated, larger producers continue to have strong incentive to seek out exactly these kinds of development-stage assets, making consolidation activity like the Artemis-Vista transaction a trend worth watching rather than an isolated event.

Xerox Holdings Corporation (XRX) – A Clearer Path Through the Turnaround


Monday, September 21, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Xerox Roadshow. On September 16th, Louis Pastor, CEO, Chuck Butler, CFO, and Greg Stein, SVP & Head of IR, presented to investors at a non-deal roadshow in St. Louis. The presentation highlighted the company’s turnaround strategy, focusing on its efforts to stabilize revenue, expand margins, and reduce debt.

Broadening the revenue base. Earlier this month, the company announced a strategic partnership with Flint Group Digital Xeikon to utilize its digital press technology in Xerox-branded products. The partnership bolsters Xerox’s position in the production print market by providing access to digital packaging, labels, and commercial print without the cost of developing the technology internally.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Codere Online (CDRO) – Adding the NFL to the Mexico Playbook


Monday, September 21, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

High-visibility NFL Agreement. Codere recently announced a multi-year agreement with the NFL, establishing it as the league’s Official Betting Partner in Mexico.  In our view, the high-visibility partnership strengthens its presence in a key market, increases brand awareness, deepens customer engagement opportunities, and enhances brand credibility.

Details. The agreement is set to run for three years and includes annual sponsorship of one NFL game in Mexico City and Super Bowl sponsorship rights in Mexico. The agreement kicks off with the November 22, 2026, 49ers–Vikings matchup and Super Bowl LXI in Los Angeles in February 2027. The partnership also creates fan engagement opportunities through hospitality programs, VIP experiences, promotional events across multiple Mexican cities, and official NFL merchandise.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Warren Buffett Steps Down as Berkshire Hathaway Chairman, Closing a Remarkable Era

Warren Buffett stepped down Friday as chairman of Berkshire Hathaway (NYSE: BRK.A, BRK.B), bringing another chapter of one of the most consequential careers in modern investing to a close.

Buffett, who recently turned 96, has been named Chairman Emeritus and will remain on Berkshire’s board, where the company says he will continue to offer his judgment and perspective. His son, Howard G. Buffett, a Berkshire director since 1993, has been elected chairman, while Greg Abel remains chief executive officer and continues to run the company’s operations.

The transition completes a process that began earlier this year when Abel succeeded Buffett as CEO. Buffett described the timing as right, writing to shareholders that Abel had exceeded his already high expectations and had been making Berkshire’s important decisions for some time. He characterized Howard’s role differently: Abel will run the company, while Howard will help guard the culture and values Buffett spent decades building.

For investors, Buffett’s departure from the chairman’s seat is less about an abrupt change in control than the culmination of a succession plan years in the making. But symbolically, it closes an extraordinary period in American business.

From Struggling Textile Company to $1 Trillion Conglomerate

Buffett took control of Berkshire Hathaway in 1965, when it was still primarily a struggling New England textile manufacturer. What followed was one of the most remarkable transformations in corporate history.

Rather than remaining a textile business, Berkshire evolved into a sprawling collection of operating companies and investments spanning insurance, rail transportation, energy, manufacturing, retailing and services. Today its businesses include GEICO, BNSF Railway, Berkshire Hathaway Energy, Dairy Queen and numerous industrial and consumer companies.

The numbers illustrate the scale of the transformation. From 1965 through 2025, Berkshire’s per-share market value compounded at 19.7% annually, compared with 10.5% for the S&P 500 including dividends. Over the full period from 1964 through 2025, Berkshire’s gain totaled more than 6 million percent, versus roughly 46,000% for the S&P 500.

That record turned Buffett from a successful investor into a central figure in global finance and transformed Berkshire from an obscure textile company into a business valued at roughly $1 trillion.

A Different Approach to Building a Company

Much of Buffett’s success came from a model that was unusual when he began using it and remains difficult to replicate.

Berkshire’s insurance operations generated large amounts of float – premiums collected before claims are paid – that could be invested elsewhere. Buffett used that capital to buy public-company stakes and, increasingly, entire businesses.

Over time, Berkshire accumulated large positions in companies such as Coca-Cola and Apple while acquiring businesses ranging from GEICO and BNSF Railway to utilities, manufacturers and retailers. Buffett’s investment approach also evolved alongside longtime partner Charlie Munger, moving beyond simply buying statistically cheap companies toward acquiring strong businesses with durable competitive advantages, capable management and attractive long-term economics.

Berkshire then allowed many acquired companies to operate with significant autonomy rather than imposing a heavily centralized corporate structure. The combination of patient capital, decentralized management and an unusually long investment horizon became a defining part of Berkshire’s identity.

Crisis Investing Helped Build the Buffett Reputation

Buffett’s reputation was also reinforced by his willingness to deploy capital when markets were under severe stress.

During the 2008 financial crisis, Berkshire invested billions of dollars in companies including Goldman Sachs and General Electric at a time when access to capital had become extremely valuable. Those investments demonstrated one of Berkshire’s recurring advantages: maintaining enough liquidity to act aggressively when other investors were forced to retreat.

That philosophy remains visible today. As of June 30, Berkshire’s insurance and other businesses held approximately $359 billion in cash, cash equivalents and U.S. Treasury bills, giving the company an enormous pool of liquidity for investments, acquisitions or share repurchases. Buffett has long viewed that liquidity not as idle capital, but as both protection against unexpected events and optionality when attractive opportunities emerge.

Buffett Also Changed How Investors Think

Buffett’s influence extends well beyond Berkshire’s financial results. His annual shareholder letters became widely read explanations of investing, corporate governance, accounting and capital allocation, while Berkshire’s annual meeting in Omaha evolved into one of the largest gatherings of investors in the world.

Among the ideas Buffett repeatedly emphasized were relatively simple concepts that often proved difficult to practice: focus on long-term business value rather than short-term stock movements, avoid excessive leverage, understand what you own and remain disciplined when markets become euphoric or fearful.

His emphasis on treating shareholders as long-term business partners also helped shape Berkshire’s unusually loyal investor base. In his final message as chairman, Buffett returned to that idea, noting that he and Munger had always sought shareholders who thought in decades rather than quarters.

What Happens to Berkshire Now?

The most important question for Berkshire investors is how much the company changes without Buffett holding either the CEO or chairman title. Operationally, the transition is already well underway.

Greg Abel became CEO at the beginning of 2026 and is responsible for running Berkshire and making capital-allocation decisions. Buffett said Friday that Abel has fully taken control of the CEO role and that he has not had reason to question the decisions Abel has made.

Howard Buffett’s position as chairman is expected to be more focused on governance and protecting Berkshire’s corporate culture than managing day-to-day operations. Buffett described his son as a safeguard for the values he believes are central to the company.

Berkshire also enters the post-Buffett era with substantial financial strength. At June 30, the company reported roughly $1.26 trillion in total assets and nearly $748 billion in Berkshire shareholders’ equity, alongside its large holdings of cash and Treasury bills. That gives Abel considerable flexibility, but also presents one of Berkshire’s biggest challenges: its enormous size makes finding investments capable of materially moving the company increasingly difficult.

The Next Berkshire Will Inevitably Look Different

No successor can realistically replicate Buffett’s exact role. For decades, he served simultaneously as chief executive, chairman, chief capital allocator, public face of the company and one of its largest shareholders.

Berkshire’s next generation of leadership is intentionally more distributed, with Abel managing the business, Howard Buffett overseeing the board and Berkshire’s existing managers continuing to run individual subsidiaries. Investors will therefore be watching whether the company can preserve the elements of Buffett’s system that made it distinctive: disciplined capital allocation, conservative financing, decentralized operations and a willingness to wait for attractive opportunities.

There are reasons for continuity. Buffett remains a director and major shareholder, and the current succession structure was developed over many years rather than assembled suddenly. But Berkshire is unquestionably entering a new era.

Buffett took control of a struggling textile operation more than six decades ago and turned it into one of the largest and most financially powerful companies in the world. Few investors have produced comparable long-term returns, and fewer still have had such a lasting influence on how generations of investors think about businesses, markets and capital.

In his letter Friday, Buffett acknowledged the inevitability of the transition with characteristic simplicity: “Father Time always wins.” He added that Berkshire had reached a point where he was more confident than ever about what lies ahead.

That confidence will now be tested under a new generation of leadership. For Berkshire shareholders, the Buffett era may be ending – but the company he built is designed to continue long after him.

Taboola to Acquire Dianomi, Expanding Its Reach in Financial Advertising

Taboola (NASDAQ: TBLA) has agreed to acquire UK-based digital advertising company Dianomi, a move that will significantly expand Taboola’s presence in financial services advertising and deepen its access to premium business and finance publishers.

The acquisition is expected to close before the end of 2026, subject to customary regulatory conditions and approval by Dianomi shareholders. Financial terms were not disclosed.

Dianomi specializes in connecting financial, business and lifestyle advertisers with high-intent audiences across premium digital publications. Its clients include major financial institutions and asset managers such as Charles Schwab, Invesco and Bank of America, while its publisher relationships include Reuters, CNN Business, The Times and The Wall Street Journal.

For Taboola, the acquisition adds a specialized advertising network in one of the most commercially valuable segments of digital media.

Why Dianomi Fits Taboola’s Strategy

Taboola has spent years expanding beyond the content-recommendation widgets that first made the company widely known.

Its current strategy centers on Realize, Taboola’s performance advertising platform, which uses the company’s publisher relationships, first-party data and artificial intelligence to help advertisers drive measurable outcomes across the open web. Taboola said Dianomi’s network will be integrated with Realize, creating a more specialized offering for advertisers seeking finance-oriented audiences.

That is important because financial advertisers often place a premium on context, trust and audience quality. Someone reading investment research, retirement planning content or business news is often a more attractive advertising target for financial institutions than a generic web user. Dianomi has built its business specifically around that distinction.

Founded in 2003, the company focuses on contextual advertising across finance, business and lifestyle publications, using what it describes as privacy-first and identity-free targeting rather than relying solely on third-party cookies.

A Premium Finance Advertising Network

Dianomi says its marketplace reaches more than 500 million devices interested in finance, business and lifestyle content and serves more than 8 billion native advertising impressions per month. The company also has relationships with more than 320 premium publishers.

Its customer base is particularly concentrated in financial services. Dianomi says it works with eight of the world’s ten largest asset managers and more than half of the largest U.S. banks. Its audience products include segments aimed at investors, retirement planners, financial advisers, C-suite executives and other affluent or professionally oriented users.

That specialization differentiates Dianomi from broader ad networks. Rather than competing primarily on raw audience scale, the company has built its proposition around placing financial advertising adjacent to relevant, premium editorial content. That positioning has become increasingly valuable as advertisers seek alternatives to broad behavioral targeting and as privacy restrictions reduce reliance on traditional cookies.

Taboola Continues Building Beyond Native Advertising

The Dianomi acquisition also fits a broader pattern in Taboola’s evolution.

Taboola has steadily expanded its capabilities through acquisitions and partnerships designed to increase the types of advertisers and publishers it can serve. In 2021, the company acquired Connexity, expanding into e-commerce advertising and product recommendations across the open web. Taboola later entered a long-term commercial agreement with Yahoo, giving it access to one of the internet’s largest consumer audiences and significantly increasing the scale of its native advertising operations.

More recently, the company has been positioning Realize as a broader performance advertising platform rather than simply a recommendation engine. The addition of Dianomi gives Taboola something different from pure scale: vertical specialization.

Finance represents a category where advertisers typically care deeply about audience quality, regulatory considerations, brand safety and trusted publishing environments. Dianomi has spent more than two decades building relationships specifically around those needs.

Contextual Advertising Becomes More Important

The deal also reflects changes occurring across digital advertising.

For years, online advertising relied heavily on third-party cookies and user-level behavioral tracking. That model has come under increasing pressure from privacy regulations, browser restrictions and changing consumer expectations.

Dianomi’s approach is more context-driven. Rather than depending primarily on an individual user’s identity, its platform analyzes the content being consumed and places advertising around relevant subject matter. A retirement-services advertisement, for example, might appear alongside investing or retirement-planning content where reader intent is already high.

Dianomi says its platform is designed to operate without third-party cookies, an approach that could become increasingly important as advertisers and publishers look for privacy-conscious methods of reaching targeted audiences. Taboola has similarly emphasized first-party data and contextual signals as part of its open-web advertising strategy.

Bringing the two together could give advertisers access to Dianomi’s specialized financial audiences while adding Taboola’s broader technology, AI capabilities and performance measurement tools.

Benefits for Publishers Could Matter Too

The combination is not only about advertisers.

Premium publishers increasingly face pressure to generate more revenue from digital audiences without sacrificing reader experience or exposing valuable first-party data.

Dianomi offers publishers native, display, video and podcast advertising across websites, apps, email, Apple News and other digital formats. The company says its model allows publishers to monetize inventory while maintaining control over their first-party audience data.

For Taboola, that could deepen relationships with publishers already operating in financially valuable categories. The company has repeatedly described its ambition as becoming an economic infrastructure provider for the open web, helping publishers generate revenue while giving advertisers alternatives to large closed advertising platforms. Dianomi expands that strategy further into a category where publisher credibility is particularly important.

A Smaller Deal With Strategic Value

Without disclosed financial terms, investors cannot yet evaluate the acquisition based on purchase multiple, expected accretion or return on invested capital. That makes the strategic rationale more important than the transaction economics for now.

Dianomi brings Taboola a concentrated network of finance-focused advertisers, premium publishers and high-value audiences. Taboola brings a much larger performance advertising platform, broader publisher distribution, first-party data and AI-driven optimization.

The combination could allow Dianomi’s specialized network to scale more quickly while giving Taboola a stronger position in financial advertising. The acquisition also comes as Taboola continues expanding partnerships across major media companies, reinforcing its push to increase premium publisher inventory available through Realize.

A Related Digital Advertising Theme in Noble Coverage

The deal also highlights the growing importance of digital and programmatic advertising across the broader media ecosystem. Noble Capital Markets covers Townsquare Media (NYSE: TSQ), which has increasingly shifted toward a digital-first business model.

Noble’s recent research has highlighted continued growth in Townsquare’s digital advertising operations, including programmatic advertising, owned-and-operated digital properties and its expanding Media Partnerships platform. While Townsquare’s model differs from Taboola and Dianomi, all three are exposed to the continued migration of advertising budgets toward measurable, data-driven digital channels.

What Investors Should Watch

The key question will be whether Taboola can preserve what makes Dianomi valuable while integrating it into a much larger advertising platform.

Dianomi’s appeal rests partly on specialization, trusted publisher relationships and its reputation within financial services. If Taboola can combine that niche positioning with greater scale and technology without diluting it, the acquisition could strengthen Realize in a category that offers both high-value advertisers and attractive audiences.

Investors will also be watching for additional details around the transaction price, expected financial contribution and integration plans as the deal moves toward closing.

For now, the acquisition reinforces a broader direction for Taboola. The company is increasingly building a portfolio of specialized capabilities around performance advertising, rather than relying solely on its traditional native recommendation business.

With Dianomi, Taboola is adding something particularly valuable to that portfolio: a deeply established position inside the financial advertising ecosystem.

Release – The Office Gurus Strengthens Executive Leadership Team to Accelerate Next Phase of Global Growth

Research News and Market Data on SGC

Veteran BPO executives Mark Lyndsell and Troy Sanders join TOG as the company expands its global delivery capabilities and advances its Experience Process Outsourcing strategy

ST. PETERSBURG, Fla., Sept. 17, 2026 (GLOBE NEWSWIRE) — The Office Gurus (TOG), a business segment of Superior Group of Companies, Inc. (NASDAQ: SGC), announced the appointments of Mark Lyndsell as Executive Vice President of Global Operations and Troy Sanders as Vice President of Business Development. Together, they bring more than six decades of BPO, contact center, operations and sales leadership experience to TOG.

“TOG has reached an important point in our evolution,” said Dominic Leide, President of The Office Gurus. “Mark and Troy bring the experience and leadership to help us significantly scale the successful, technology-driven platform we’ve built.”

Lyndsell brings more than 30 years of global operations experience, most recently as Senior Vice President, Delivery, Americas at TTEC, leading a multi-country delivery organization generating approximately $850 million in annual revenue. As EVP of Global Operations, he will lead TOG’s global operations, focusing on operational excellence and advancing the company’s Experience Process Outsourcing (EPO) delivery model.

Sanders brings more than 30 years of BPO and contact center sales leadership experience, including new business development for organizations such as iQor and Startek. As VP of Business Development, he will focus on expanding TOG’s new-client pipeline and brings the relationship-based sales mentality that TOG values.

The appointments support TOG’s continued advancement of its EPO strategy and its investment in GuruSuite iX, its AI-enabled technology ecosystem supporting agent performance, quality assurance, training and customer interaction automation. “Our objective isn’t simply to become bigger – it’s to become a better, more capable partner for our clients,” Leide said.

Disclosure Regarding Forward-Looking Statements

Certain matters discussed in this press release are “forward-looking statements” intended to qualify for the safe harbors from liability established by the Private Securities Litigation Reform Act of 1995. These forward-looking statements can generally be identified by use of the words “may,” “will,” “should,” “could,” “expect,””anticipate,” “estimate,” “believe,” “intend,” “project,” “potential,” or “plan” or the negative of these words or other variations on these words or comparable terminology. Forward-looking statements in this press release include statements regarding the Company’s capital allocation strategy and growth. Such forward-looking statements are subject to certain risks and uncertainties that may materially adversely affect the anticipated results. Such risks and uncertainties include, but are not limited to, the factors described in the Company’s filings with the Securities and Exchange Commission (“SEC”), including those risks described in Item 1A of our Annual Report on Form 10-K for the fiscal year ended December 31, 2025 entitled “Risk Factors” and the Quarterly Report on Form 10-Q for the quarter ended June 30, 2026. Shareholders, potential investors and other readers are urged to consider these factors carefully in evaluating the forward-looking statements made herein and are cautioned not to place undue reliance on such forward-looking statements. The forward-looking statements made herein are only made as of the date of this press release and we disclaim any obligation to publicly update such forward-looking statements to reflect subsequent events or circumstances, except as may be required by law.

About The Office Gurus

The Office Gurus is a global provider of customer experience and business process outsourcing solutions, combining engaged people, operational expertise and AI-enabled technology to help organizations improve customer experience and business performance.

About Superior Group of Companies, Inc. (SGC)

Established in 1920, Superior Group of Companies is comprised of three attractive business segments each serving large, fragmented and growing addressable markets. Across Healthcare Apparel, Branded Products and Contact Centers, each segment enables businesses to create extraordinary brand engagement experiences for their customers and employees. SGC’s commitment to service, quality, advanced technology, and omnichannel commerce provides unparalleled competitive advantages. We are committed to enhancing shareholder value by continuing to pursue a combination of organic growth and strategic acquisitions. For more information, visit www.superiorgroupofcompanies.com.

Contact:
Investor Relations
[email protected]

GeoVax Labs (GOVX) – MVA Technology Platform Produces New Vaccine For Ebola


Thursday, September 17, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

BDBV Vaccine Construct Developed With GeoVax’s Proprietary Technology. GeoVax has developed a new vaccine construct against Bundibugyo virus (BDBV). This is the virus causing the Ebola Virus Disease (EVD) outbreak in the Democratic Republic of Congo (DRC), now the largest Ebola outbreak and the fastest-spreading outbreak in the DRC. We see this new vaccine construct as proof of principle for the GeoVax MVA technology platform and its ability to respond to infectious diseases with new vaccines.

We See This As An Example Of The MVA Technology Capabilities. GeoVax has proprietary technology based on the MVA (Modified Vaccinia Ankara) virus that it can use to develop and manufacture new vaccines. This technology provides a common foundation for developing new vaccines and responding to infectious disease outbreaks. Previous vaccines developed with the MVA technology platform can stimulate both antibody and cellular immune responses, resulting in long durability, high tolerability, and improved safety profiles.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.