First Phosphate Corp. (PHOS) – SERV Adds a Significant New Export Credit Agency (ECA) Financing Component


Thursday, September 17, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Swiss support adds another financing layer. First Phosphate has received a Letter of Support from Swiss Export Risk Insurance (SERV) for approximately US$212.5 million in potential financing tied to Swiss machinery, equipment, goods, and services for the Bégin-Lamarche mine and processing facility. The contemplated financing is based on an assumed US$250 million eligible Swiss export contract, with SERV prepared to consider financing 85% of the contract value.

European and G7 support is converging around the project. The SERV announcement follows EIFO’s earlier letter of intent for up to €170 million in guaranteed financing support, while the Canadian government’s G7 Critical Minerals Resilience and Production Alliance announcement also highlighted Danish support for the Bégin-Lamarche mine and Italian financial and industrial support for First Phosphate’s downstream phosphoric acid facility. Switzerland is not a G7 member, but SERV’s participation adds another significant European state-backed export finance institution to a project already receiving support through G7-related initiatives.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Kodiak Copper Corp. (KDKCF) – Advancing a District-Scale Copper-Gold Porphyry Project in British Columbia


Thursday, September 17, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

A large copper resource with room to grow. We have initiated coverage of Kodiak Copper Corp. with an Outperform rating and a price target of C$2.10, or approximately US$1.50 per share. Kodiak’s 100%-owned MPD Copper-Gold Project in southern British Columbia contains 439.2 million tonnes of Indicated and Inferred Resources across seven deposits, all open to expansion. Resource growth and improved project definition could support a higher valuation against a favorable long-term outlook for copper.

Ketchan drilling supports higher-grade potential. Hole AG-26-019 returned 283.5 meters at 0.70% copper equivalent (CuEq) from 37.5 meters downhole, including 108 meters at 1.02% CuEq. The result highlights shallow mineralization that could improve the grade and confidence of the existing resource.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

DLH Holdings (DLHC) – $43.7 Million Follow-On Award


Thursday, September 17, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Follow-on Order. DLH has been awarded a task order to continue providing high-quality information technology services for the National Heart, Lung, and Blood Institute. DLH has performed on this mission since 2018. The task order, valued at up to $43.7 million, includes a base period and multiple options aggregating to a two-and-a-half-year period of performance. We view this most recent award as further confirmation that the backlog of contracts and task orders is being freed up which will benefit DLH going forward.

Details. Under this task order, DLH will build on its existing implementation of artificial intelligence for IT operations and automation to improve service efficiency, system reliability, data integrity, cybersecurity, and compliance- all strengths of DLH. The Company will provide services in support of approximately 2,000 NHLBI scientific and administrative employees and contractors.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

SEC Opens Door to Tokenized U.S. Stocks as Broader Crypto Legislation Stalls

The U.S. Securities and Exchange Commission took a major step toward bringing tokenized equities into mainstream American markets Thursday, approving a temporary regulatory framework that allows certain trading venues to offer blockchain-based representations of publicly traded U.S. stocks.

The SEC’s new Innovation Exemption creates a five-year conditional pathway for approved onchain venues to trade tokenized National Market System stocks, while also providing limited relief from dealer-registration requirements for liquidity providers operating in those markets. The order is effective immediately.

The move could accelerate efforts to bring traditional equities onto blockchain infrastructure, potentially enabling faster settlement, fractional ownership, expanded trading hours and new forms of custody. It also arrives just two days after the Senate failed to advance the Clarity Act, a broader digital-asset market structure bill that would have created a more comprehensive statutory framework for cryptocurrencies and other digital assets.

For investors, the contrast is important. Congress may remain divided over comprehensive crypto legislation, but regulators and market operators are continuing to build a more targeted framework for tokenized securities specifically.

What the SEC Actually Approved

The exemption does not simply allow any crypto platform to create synthetic versions of U.S. stocks. Under the SEC framework, qualifying Tokenized Securities Venues, or TSVs, may facilitate trading in tokenized versions of National Market System stocks. The tokenized securities must represent actual securities and provide holders with the same core rights and privileges associated with the traditional shares, including dividend and voting rights. Synthetic tokens that merely track a stock’s price without conveying equivalent ownership rights are excluded.

Issuers also retain an important degree of control. Platforms must notify a public company before offering a tokenized version of its shares, and the company can object and prevent that tokenized security from being listed on the venue.

That provision addresses one of the largest concerns surrounding early tokenized-stock products offered outside the United States. Some offshore products have provided investors with economic exposure to a stock without necessarily giving them the full legal rights of a shareholder.

The SEC itself drew that distinction earlier this year when it formally described tokenized securities as traditional securities represented through crypto or distributed-ledger technology and differentiated issuer-backed tokenization from third-party structures. In other words, the regulator is attempting to allow the technology to change while preserving the legal nature of the underlying security.

Why Tokenization Matters

Tokenization means representing ownership in an asset through a digital token recorded on a blockchain or similar distributed ledger. For equities, the underlying investment does not necessarily change. An investor may still own an interest tied to the same public company, receive dividends and possess voting rights. What potentially changes is the infrastructure used to record, transfer and settle that ownership.

Advocates argue that this could eventually support round-the-clock trading, faster settlement, fractional ownership and more efficient movement of assets between financial platforms. The potential significance is therefore broader than simply putting stocks on a blockchain.

The traditional U.S. equity system involves exchanges, brokers, custodians, clearing organizations, transfer agents and settlement infrastructure working together. Tokenization could ultimately change how some of those functions interact, particularly if ownership records and settlement increasingly move onto programmable digital ledgers. That transition, however, is likely to be gradual rather than immediate.

The Infrastructure Is Already Being Built

Thursday’s action does not arrive in isolation. The Depository Trust & Clearing Corporation, which sits at the center of U.S. securities clearing and settlement, has already been testing tokenized securities with financial institutions and market participants and has been developing a broader tokenization service.

Private-sector platforms have also moved rapidly. Custodial tokenized-security structures, regulated onchain trading platforms and blockchain-based settlement systems are progressing from pilot projects toward real market infrastructure. Taken together, those developments suggest tokenized equities are moving beyond the proof-of-concept stage.

Nasdaq Is Already Positioning for This Transition

Nasdaq has been particularly active in preparing for tokenized markets. Earlier this year, the SEC approved Nasdaq’s proposal to enable securities to trade on its exchange in tokenized form. Nasdaq subsequently announced an equity-token framework designed to preserve issuer control, shareholder rights, regulatory protections and corporate governance as equities move onto blockchain infrastructure.

Last week, Nasdaq went another step further, agreeing to invest $100 million in Payward, the parent company of Kraken, while expanding the companies’ work on Nasdaq Equity Tokens and always-on trading infrastructure.

That development was the subject of a recent Channelchek article, ‘Nasdaq Deepens Push Into Tokenized Stocks With $100 Million Payward Investment.’ Today’s SEC action provides additional regulatory context for that strategy: the market infrastructure Nasdaq and Payward are developing now has a clearer path toward deployment in the United States.

The Clarity Act Failed – But Tokenization Is Still Moving Forward

Thursday’s regulatory progress comes only two days after a significant legislative setback for the broader digital-asset industry. The Senate failed to advance the Clarity Act in a procedural vote, falling short of the votes required to move the measure forward. The bill would have established a comprehensive regulatory structure for digital assets and clarified responsibilities between agencies including the SEC and Commodity Futures Trading Commission.

For investors, however, the distinction between cryptocurrencies and tokenized securities is important. Tokenized stocks are still securities. Their underlying economic and legal characteristics remain governed by securities law even if blockchain technology is used to represent ownership or process transactions.

That allows the SEC to address some tokenization questions through its existing authority even while Congress continues debating a much broader framework for digital assets. The result is an unusual regulatory picture: comprehensive crypto legislation remains unresolved, while specific pieces of tokenized capital-market infrastructure continue advancing.

Investor Protections Remain Part of the Debate

Not everyone agrees that exemptions are the best way to introduce tokenized equities. Traditional market participants have raised concerns about liquidity fragmentation, price discovery and whether tokenized venues could weaken protections embedded in the National Market System.

The SEC’s temporary framework appears designed partly to address those concerns by limiting eligible products, preserving shareholder rights and allowing issuers to block tokenized versions of their securities. The five-year duration is also significant: rather than establishing a permanent regulatory regime immediately, the SEC is effectively creating a controlled period in which tokenized markets can develop while regulators gather data and determine what longer-term rules may be appropriate.

Could 24/7 Stock Trading Actually Happen?

One of the most visible potential changes is extended trading hours. Cryptocurrency markets operate continuously, while U.S. stock markets still revolve around defined sessions even as exchanges gradually expand overnight trading.

Blockchain-based securities infrastructure could make continuous trading easier technically because tokenized assets can move between investors without relying on exactly the same operating hours as existing market systems. But technology is only part of the equation. Liquidity, market surveillance, corporate actions, settlement, investor disclosures and price discovery all become more complicated if trading occurs around the clock.

The arrival of tokenized equities therefore does not mean the traditional market structure disappears overnight. More likely, conventional exchanges, clearing systems and blockchain-based platforms will increasingly overlap.

A Potentially Important Shift for Public Companies

The development could eventually matter for public issuers as much as it does for trading platforms. Tokenized ownership records could potentially improve shareholder communications, automate corporate actions and make it easier to manage voting, dividends and other ownership rights.

Nasdaq has emphasized that issuers should remain at the center of tokenization rather than simply having third-party platforms create digital representations of their shares without their involvement. The SEC’s issuer-objection provision moves in the same direction.

That could ultimately produce a tokenization model that looks less like the crypto industry replacing traditional markets and more like existing capital markets gradually adopting blockchain technology underneath their current legal structure.

The Bigger Story Is Market Infrastructure

Tokenized stocks can easily be described as another crypto product, but that may understate what is happening. The larger story is the modernization of the infrastructure underlying capital markets.

DTCC is preparing tokenized securities infrastructure. Nasdaq is developing tokenized equity systems. Major banks, brokers, asset managers and trading firms are participating in industry efforts. Regulated platforms have begun executing tokenized securities transactions. And now the SEC has created a temporary pathway for additional onchain trading venues to enter the U.S. market.

None of that guarantees tokenized equities will replace the existing system, nor does it resolve every regulatory issue surrounding digital assets. But it suggests the conversation has moved considerably beyond whether tokenization is theoretically possible. The more relevant question is becoming how much of the traditional financial system will ultimately adopt it.

Tuesday’s failed Clarity Act vote demonstrated that broad digital-asset legislation remains politically and legally difficult. Thursday’s SEC action demonstrates something equally important: the development of tokenized securities does not necessarily have to wait for Congress to resolve every question surrounding cryptocurrency.

For investors, that distinction may prove important. The broader crypto regulatory framework remains unsettled, but the infrastructure for putting traditional securities onchain continues moving forward – and increasingly, some of the largest institutions in U.S. capital markets are helping build it.

Aethlon Medical and North Immunology Agree to Merger, Bringing Atopic Dermatitis Biotech to Nasdaq

Aethlon Medical (NASDAQ: AEMD) and privately held North Immunology have entered into a definitive all-stock merger that will effectively take North public and create a Nasdaq-listed biotechnology company focused on immune and inflammatory diseases.

The combined company will operate as North Immunology, Inc. and is expected to trade under the new Nasdaq ticker NRTX. Existing North shareholders and investors participating in a concurrent financing are expected to own approximately 95.25% of the combined company, while pre-merger Aethlon shareholders are expected to own approximately 4.75%. The transaction values the combined company at approximately $346.5 million on a pro forma equity basis, including the financing.

Alongside the merger, North has secured an oversubscribed $180 million private placement backed by healthcare-focused institutional investors including Bain Capital Life Sciences, Janus Henderson Investors, Deep Track Capital, Longitude Capital, Soleus Capital, Farallon-managed funds and others. The financing is expected to fund operations into the second half of 2028 and support clinical development of North’s lead drug candidate, NOR-101. The transaction is expected to close in the first quarter of 2027, subject to shareholder, Nasdaq and other customary approvals.

A Reverse Merger Centered on North Immunology

Although the companies describe the transaction as a merger, the ownership and management structure make it functionally a reverse merger. North’s existing management team will lead the combined company, and its existing board – supplemented by new independent directors – is expected to become the board of the public entity. Aethlon’s Nasdaq listing and corporate structure provide North with a route to the public markets while the newly financed company concentrates its resources on North’s immunology pipeline.

That makes the transaction quite different from a conventional strategic acquisition in which the buyer absorbs the target’s assets and management. Here, North becomes the operating company that survives economically, while Aethlon shareholders retain a relatively small ownership stake.

Aethlon CEO James Frakes said the structure gives existing shareholders an opportunity to participate in North’s pipeline while preserving potential value from Aethlon’s legacy assets. Those legacy assets include the Hemopurifier, Aethlon’s clinical-stage blood-filtration device designed to remove cancer-promoting exosomes and certain life-threatening viruses from circulation. Aethlon shareholders immediately prior to closing are expected to receive contingent value rights, or CVRs, entitling them to potential proceeds if the Hemopurifier business is subsequently sold, licensed or otherwise monetized.

NOR-101 Becomes the Center of the Investment Story

The combined company will be built primarily around NOR-101, North Immunology’s half-life-extended bispecific antibody targeting both IL-13 and IL-18.

North is developing the drug initially for atopic dermatitis, the most common form of eczema. The chronic inflammatory skin disease can cause itching, lesions and recurring flare-ups, and moderate-to-severe cases increasingly are treated with biologic therapies or other systemic drugs.

The rationale behind NOR-101 is to attack two different components of the inflammatory response simultaneously. IL-13 is an established target associated with type 2 inflammation, while IL-18 is associated with additional inflammatory pathways. North believes blocking both could potentially address a broader spectrum of disease biology than therapies focused on type 2 inflammation alone.

The company has reported an approximately 42-day half-life in a non-human primate pharmacokinetic study, an attribute that could eventually support less frequent dosing if it translates into humans. NOR-101 remains preclinical, however, meaning the thesis still has to be demonstrated in patients.

North expects to begin a Phase 1a study in the first quarter of 2027, with interim pharmacokinetic and safety data expected by midyear. The company then plans to begin Phase 1b and Phase 2b studies in atopic dermatitis during 2027, with topline results from both studies anticipated in 2028.

Atopic Dermatitis Has Become a Highly Competitive Market

North is entering a field that offers substantial commercial opportunity but also an increasingly high clinical bar. Biologic therapies have transformed treatment of moderate-to-severe atopic dermatitis. Sanofi and Regeneron’s Dupixent, which inhibits IL-4 and IL-13 signaling, established the category, while Eli Lilly’s Ebglyss directly targets IL-13. AbbVie’s JAK inhibitor Rinvoq provides another systemic treatment option.

The strategic value pharmaceutical companies are assigning to differentiated eczema therapies was underscored this summer when AbbVie agreed to acquire Apogee Therapeutics for $10.9 billion. Apogee’s lead asset is a long-acting anti-IL-13 antibody that produced encouraging Phase 2 results and is designed in part to reduce injection frequency relative to existing biologics.

IL-18 is also attracting attention. Earlier this year, Evommune reported positive Phase 2a results for an experimental IL-18-targeting therapy in moderate-to-severe atopic dermatitis, sending its shares sharply higher following the data. Those developments provide scientific and commercial context for North’s decision to combine IL-13 and IL-18 inhibition in a single molecule, but they also demonstrate how competitive the field has become.

Differentiation Will Be Critical

Simply producing another effective eczema therapy may no longer be enough. Recent industry developments show that drugmakers are increasingly demanding meaningful improvements in efficacy, durability, convenience or safety before committing substantial additional capital to new atopic dermatitis programs.

Sanofi, for example, recently abandoned plans to seek approval for the atopic dermatitis drug amlitelimab after concluding that its clinical profile would not represent a sufficiently meaningful improvement over available therapies. Johnson & Johnson also discontinued development of an experimental eczema therapy earlier this year after an interim analysis failed to clear the company’s efficacy threshold.

That creates both the opportunity and the challenge for NOR-101. North is attempting to distinguish the candidate through dual-pathway inhibition and potentially extended dosing intervals, but investors will ultimately need human clinical data showing that those characteristics translate into meaningful improvements for patients. The first important test begins next year.

$180 Million Gives North a Longer Development Runway

The concurrent financing is an important component of the transaction. Clinical-stage biotechnology companies frequently use reverse mergers to access public markets, but the resulting companies can still face immediate capital needs. North is entering the public market with approximately $180 million of expected gross financing proceeds, including the conversion of roughly $34 million in convertible notes and related amounts.

Management expects that capital to fund operations into the second half of 2028, which would carry the company through several planned clinical milestones for NOR-101. The investor syndicate is also notable because it includes several established life sciences investors rather than relying principally on smaller retail-oriented financing sources. For investors evaluating the transaction, that does not eliminate clinical risk, but it provides North with a substantially stronger balance sheet as it enters human testing.

Aethlon Shareholders Retain Exposure to the Legacy Business

For existing Aethlon shareholders, the transaction effectively separates two investment propositions. Their 4.75% expected ownership of the combined company provides exposure to North Immunology and NOR-101, while the CVR preserves potential future value from Aethlon’s existing Hemopurifier program if those assets can be monetized.

Aethlon has been developing the Hemopurifier as an extracorporeal therapeutic device capable of depleting circulating cancer-promoting exosomes and certain viruses. The FDA has granted the technology Breakthrough Device designation in both oncology and life-threatening viral disease settings, and Aethlon has been conducting an early-stage study in solid-tumor patients receiving checkpoint inhibitors. Whether those assets ultimately generate meaningful CVR proceeds will depend on a future sale, licensing agreement or other transaction, making that component inherently uncertain.

Related Immunology Company in Noble Capital Markets Coverage

Eledon Pharmaceuticals (NASDAQ: ELDN) offers a related immunology example within Noble Capital Markets research coverage. Eledon is developing tegoprubart, an anti-CD40L antibody intended to modulate immune responses in organ and islet transplantation. Like NOR-101, its therapeutic approach targets a defined immune signaling pathway, although the diseases, mechanisms and stages of development are quite different. Eledon is covered by Noble Capital Markets.

North Immunology Prepares for the Public Markets

For Aethlon, the agreement represents a fundamental change in corporate direction. For North Immunology, it provides a Nasdaq listing, substantial new capital and a path to move its lead program into human trials without pursuing a traditional IPO.

The resulting company will bear North’s name, use its management team and focus primarily on its pipeline, making the transaction best understood as a reverse merger built around a newly financed immunology company.

The scientific thesis is straightforward: IL-13 inhibition is already validated in atopic dermatitis, while emerging research suggests additional inflammatory pathways such as IL-18 may contribute to disease in patients who remain inadequately treated. Whether simultaneously targeting both pathways can produce a differentiated therapy remains unproven.

With roughly $180 million in financing and the first NOR-101 clinical study expected to begin in early 2027, investors should not have to wait long for the combined company to begin generating the human data that will ultimately determine whether that strategy can compete in one of immunology’s most active therapeutic markets.

Release – GeoVax Confirms Bundibugyo Ebola Vaccine Construct

GeoVax, Inc.

Research News and Market Data on GOVX

BDBV-Specific Construct Developed Using GeoVax Proprietary Rapid Cloning Technology and Builds on Established Filovirus Vaccine Experience

GEO-MVA (Mpox/Smallpox Vaccine) Targeted for Phase 3 Initiation Remains Company Priority

ATLANTA, GA – September 16, 2026 – GeoVax Labs, Inc. (Nasdaq: GOVX), a biotechnology company developing vaccines and immunotherapies against infectious diseases and solid tumor cancers, today announced the development of a vaccine construct targeting Bundibugyo virus (BDBV), the cause of the ongoing Bundibugyo virus disease outbreak in the Democratic Republic of Congo.

The BDBV construct was generated using GeoVax’s proprietary MVA-based rapid-cloning technology, designed to enable rapid insertion or replacement of vaccine antigens in response to emerging infectious disease threats. The construct represents a milestone step toward a potential BDBV vaccine candidate.  Full characterization and animal evaluation are necessary prior to clinical evaluation.

The BDBV work builds upon GeoVax’s existing MVA-based developmental-stage filovirus vaccine portfolio targeting Zaire Ebola virus, Sudan Ebola virus and Marburg virus. These earlier programs have generated encouraging efficacy results in established preclinical models, including nonhuman primate challenge studies, with results presented publicly and published in peer-reviewed scientific journals. This body of work provides a scientific and technical foundation for applying GeoVax’s MVA platform to BDBV.

“While GEO-MVA remains our primary development focus, the ongoing, expanding BDBV outbreak represents an opportunity to apply capabilities developed through years of MVA and filovirus research,” said David Dodd, Chairman and Chief Executive Officer of GeoVax. “The successful generation of this BDBV-specific MVA construct demonstrates the responsiveness of our platform and builds on our published preclinical experience across Zaire Ebola, Sudan Ebola and Marburg, including encouraging results in nonhuman primate challenge studies. As global organizations advance multiple BDBV vaccine approaches, we believe this combination of filovirus experience, rapid construct generation and next-generation MVA technologies warrants further evaluation.”

Growing Global Focus on BDBV Vaccine Development

Bundibugyo virus disease is a severe filovirus infection for which there is currently no licensed BDBV-specific vaccine. The World Health Organization (WHO) has called for accelerated development and evaluation of BDBV-specific vaccines and other countermeasures and has established a target product profile to guide vaccine development.

The urgency surrounding BDBV has also prompted increased global investment in vaccine development. In August 2026, the Coalition for Epidemic Preparedness Innovations (CEPI) announced funding of up to $16.5 million to advance another MVA-based BDBV vaccine candidate through preclinical development and toward an early-stage clinical trial in Africa. The program is part of a broader CEPI strategy to advance multiple BDBV vaccine approaches.

GeoVax believes its BDBV construct and extensive body of MVA-based filovirus experience may warrant consideration within this expanding global development effort. In addition to its rapid-cloning technology, GeoVax is advancing MVA technologies directed toward single-dose vaccination, continuous cell-line manufacturing and alternative delivery approaches. The Company also recognizes the importance of regional manufacturing and is committed to evaluating manufacturing partnerships, including in Africa, as part of future MVA-based vaccine development programs.

“Our BDBV work provides another tangible example of how an adaptable vaccine platform and established scientific expertise can potentially contribute to outbreak preparedness,” Dodd concluded. “We look forward to exploring opportunities with global health, government and scientific partners to further evaluate the BDBV construct and our broader filovirus capabilities.”

About GeoVax

GeoVax Labs, Inc. is a clinical-stage biotechnology company focused on the development of vaccines and immunotherapies addressing high-consequence infectious diseases and solid tumor cancers. GeoVax’s priority program is GEO-MVA, a Modified Vaccinia Ankara (MVA)–based vaccine targeting mpox and smallpox. The program is advancing under an expedited regulatory pathway, with plans to initiate a pivotal Phase 3 clinical trial in the second half of 2026, to address critical global needs for expanded orthopoxvirus vaccine supply and biodefense preparedness. In oncology, GeoVax is developing Gedeptin®, a gene-directed enzyme prodrug therapy (GDEPT) designed to enhance immune checkpoint inhibitor activity. Gedeptin has completed a multicenter Phase 1/2 clinical trial in advanced head and neck cancer and is being advanced into combination strategies, including planned neoadjuvant and first-line settings. GeoVax maintains a global intellectual property portfolio supporting its infectious disease and oncology programs and continues to evaluate strategic partnerships and funding opportunities aligned with its development priorities. For more information, visit www.geovax.com.

Forward-Looking Statements

This release contains forward-looking statements regarding GeoVax’s business plans. The words “believe,” “look forward to,” “may,” “estimate,” “continue,” “anticipate,” “intend,” “should,” “plan,” “could,” “target,” “potential,” “is likely,” “will,” “expect” and similar expressions, as they relate to us, are intended to identify forward-looking statements. We have based these forward-looking statements largely on our current expectations and projections about future events and financial trends that we believe may affect our financial condition, results of operations, business strategy and financial needs. Actual results may differ materially from those included in these statements due to a variety of factors, including whether: GeoVax is able to obtain acceptable results from ongoing or future clinical trials of its investigational products, GeoVax’s immuno-oncology products and preventative vaccines can provoke the desired responses, and those products or vaccines can be used effectively, GeoVax’s viral vector technology adequately amplifies immune responses to cancer antigens, GeoVax can develop and manufacture its immuno-oncology products and preventative vaccines with the desired characteristics in a timely manner, GeoVax’s immuno-oncology products and preventative vaccines will be safe for human use, GeoVax’s vaccines will effectively prevent targeted infections in humans, GeoVax’s immuno-oncology products and preventative vaccines will receive regulatory approvals necessary to be licensed and marketed, GeoVax raises required capital to complete development, there is development of competitive products that may be more effective or easier to use than GeoVax’s products, GeoVax will be able to enter into favorable manufacturing and distribution agreements, and other factors, over which GeoVax has no control.

Further information on our risk factors is contained in our periodic reports on Form 10-Q and Form 10-K that we have filed and will file with the SEC. Any forward-looking statement made by us herein speaks only as of the date on which it is made. Factors or events that could cause our actual results to differ may emerge from time to time, and it is not possible for us to predict all of them. We undertake no obligation to publicly update any forward-looking statement, whether as a result of new information, future developments or otherwise, except as may be required by law.

Company Contact:

[email protected]

678-384-7220

Media Contact:

Jessica Starman

[email protected]

Release – SERV, Swiss Export Risk Insurance, Supports Guarantee of USD 212.5 Million for Capex of First Phosphate Mine Project in Quebec, Canada

First Phosphate Corp.

Research News and Market Data on PHOS

September 16, 2026 5:00 AM EDT | Source: First Phosphate Corp.

Saguenay, Québec–(Newsfile Corp. – September 16, 2026) – First Phosphate Corp. (NASDAQ: PHOS) (CSE: PHOS) (OTCQX: FRSPF) (FSE: KD0) (“First Phosphate” or the “Company“) is pleased to announce that it has received a Letter of Support from Swiss Export Risk Insurance (“SERV”) for approximately USD 212.5 Million for the purchase of Swiss machinery and equipment for its igneous phosphate mine project, as well as goods and services for the construction of its processing facility in Saguenay-Lac-St-Jean, Quebec, Canada.

SERV is prepared to consider insurance/guarantees in support of a buyer credit financing based on an assumed eligible Swiss export contract value of USD 250 million where SERV would consider supporting a financed amount of approximately USD 212.5 million, corresponding to 85% of such contract value. Should the final eligible Swiss export contract value be higher, SERV would be prepared to consider a correspondingly higher financing amount.

In accordance with the prevailing OECD guidelines, SERV would be prepared to provide cover of up to 95% of the eligible financed amount. The financed amount may include up to 85% of the export contract value, eligible local costs of up to 50% of the export contract value, capitalized interest during construction, and the export credit agency premium.

A sufficient portion of the project is expected to be sourced from Switzerland to be eligible for SERV coverage. SERV may also seek reinsurance from other export credit agencies in respect of significant portions of the project sourced outside Switzerland.

About First Phosphate Corp

First Phosphate (NASDAQ: PHOS) (CSE: PHOS) (OTCQX: FRSPF) (FSE: KD0) is a mineral exploration and development and clean technology company dedicated to building and reshoring a vertically integrated mine-to-market supply chain for the production of LFP batteries in North America. Target markets include energy storage, data centers, robotics, mobility, and national security.

First Phosphate’s flagship Bégin-Lamarche property, located in Saguenay-Lac-Saint-Jean, Québec, Canada, represents a rare North American igneous phosphate resource producing high-purity phosphate characterized by very low levels of impurities.

For further information, please contact:

Armand MacKenzie
President
Tel: +1 (514) 618-5289

Investor Relations: [email protected]
Media Relations: [email protected]
Website: www.FirstPhosphate.com

Follow First Phosphate:

X: https://x.com/FirstPhosphate
LinkedIn: https://www.linkedin.com/company/first-phosphate

– 30 –

Forward-Looking Information and Cautionary Statements

This news release contains certain statements and information that may be considered “forward-looking statements” and “forward looking information” within the meaning of applicable securities laws. In some cases, but not necessarily in all cases, forward-looking statements and forward-looking information can be identified by the use of forward-looking terminology such as “plans”, “targets”, “expects” or “does not expect”, “is expected”, “an opportunity exists”, “is positioned”, “estimates”, “intends”, “assumes”, “anticipates” or “does not anticipate” or “believes”, or variations of such words and phrases or statements that certain actions, events or results “may”, “could”, “would”, “might”, “will” or “will be taken”, “occur” or “be achieved” and other similar expressions. In addition, statements in this news release that are not historical facts are forward looking statements, including, among other things: the Company and SERV entering into of a definitive agreement and the terms thereof; the Company’s actual expenditures on equipment and services, and the source and value thereof; and the results of SERV’s due diligence and other enquiries Although the Company believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance and actual results or developments may differ materially from those forward-looking statements. Factors that could cause actual results to differ materially from those in forward-looking statements include development and exploration successes, continued availability of capital and financing, and general economic, market or business conditions. These statements are based on a number of assumptions including, among other things: that engineering and construction timetables and capital costs for the Company’s, exploration, development and expansion projects are correctly estimated and not affected by unforeseen circumstances; the ability to obtain financing for its proposed operations on acceptable terms; no material deterioration in general business and economic conditions; no material delays in obtaining permits and other approvals; no significant disruptions affecting the activities of the Company or its ability to access required project equipment and services, and operating supplies in sufficient quantities and on a timely basis; inflation and prices for Company project inputs being approximately consistent with anticipated levels; the ability to complete the exploration and development programs consistent with the Company’s expectations; commodity price expectations including assumptions for P2O5; the Company’s relationship with local municipalities and First Nations remaining consistent with the Company’s expectations; the Company’s relationship with other third-party partners and suppliers remaining consistent with the Company’s expectations; and government relations and actions being consistent with Company expectations. Investors are cautioned that any such statements are not guarantees of future performance and actual results or developments may differ materially from those projected in the forward-looking statements. Accordingly, readers should not place undue reliance on the forward-looking information contained in this press release. The Company does not assume any obligation to update or revise its forward-looking statements, whether because of new information, future events or otherwise, except as required by applicable law. All forward-looking information contained in this release is qualified by these cautionary statements.

info

Source: First Phosphate Corp.

Release – DLH Secures Follow-On NHLBI IT Services Award Valued at Up to $43.7 Million

logo

Research News and Market Data on DLHC

September 16, 2026

PDF Version

ATLANTA, Sept. 16, 2026 (GLOBE NEWSWIRE) — DLH Holdings Corp. (NASDAQ: DLHC) (“DLH” or the “Company”), a leading provider of digital, engineering, and scientific solutions for health and defense missions, today announced that it has been awarded a task order to continue providing high-quality information technology services for the National Heart, Lung, and Blood Institute (“NHLBI”).

DLH has performed on this mission since 2018. The task order, valued at up to $43.7 million, includes a base period and multiple options aggregating to a two-and-a-half-year period of performance. The Company will provide services in support of approximately 2,000 NHLBI scientific and administrative employees and contractors.

Under this task order, DLH will build on its existing implementation of artificial intelligence for IT operations (“AIOps”) and automation to improve service efficiency, system reliability, data integrity, cybersecurity, and compliance. Services include:

  • Scientific technology support
  • Application support services
  • Tiered service desk
  • Configuration management
  • Infrastructure operations across on-premises and cloud environments
  • Cybersecurity operations

“By combining scientific expertise with cloud, cybersecurity, application support, and AIOps capabilities, DLH remains a trusted partner for customers seeking mission-critical federal health technology services,” said DLH President & CEO Kathryn JohnBull. “We are pleased that this award extends our longstanding relationship with NHLBI. We expect to continue driving technology modernization, improved operating efficiency through automation, and reduced risk in support of the organization’s critical biomedical research mission.”

About DLH

DLH (NASDAQ: DLHC) enhances technology, public health, and cyber security readiness missions through science, technology, cyber, and engineering solutions and services. Our experts solve some of the most complex and critical missions faced by federal customers, leveraging digital transformation, artificial intelligence, advanced analytics, cloud-based applications, telehealth systems, and more. With a world-class workforce dedicated to the idea that “Your Mission is Our Passion,” DLH brings a unique combination of government sector experience, proven methodology, and unwavering commitment to innovative solutions to improve the lives of millions. For more information, visit www.DLHcorp.com.

Contact Information:

Investor Relations

[email protected]

Media

[email protected]

Safe Harbor Statement under the Private Securities Litigation Reform Act of 1995:

This press release may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements relate to future events or DLH’s future financial performance. Any statements that refer to expectations, projections or other characterizations of future events or circumstances or that are not statements of historical fact (including without limitation statements to the effect that the Company or its management “believes”, “expects”, “anticipates”, “plans”, “intends” and similar expressions) should be considered forward-looking statements that involve risks and uncertainties which could cause actual events or DLH’s actual results to differ materially from those indicated by the forward-looking statements. Forward-looking statements in this release include, among others, statements regarding expected contract performance, future task order value, and anticipated operational benefits. These statements reflect our belief and assumptions as to future events that may not prove to be accurate. Our actual results may differ materially from such forward-looking statements due to a variety of factors, including: the failure to achieve the anticipated benefits of any future acquisition (including anticipated future financial operating performance and results); the inability to retain employees and customers; contract awards in connection with re-competes for present business and/or competition for new business; our ability to manage our debt obligations; compliance with bank financial and other covenants; changes in client budgetary priorities; government contract procurement (such as bid and award protests, small business set asides, loss of work due to organizational conflicts of interest, etc.) and termination risks; significant delays or reductions in appropriations for our programs and broader changes in U.S. government funding and spending patterns; legislation that amends or changes discretionary spending levels or budget priorities; legal, regulatory, and political changes from the federal government that could result in economic uncertainty; the impact of inflation and higher interest rates; and other risks described in our SEC filings. For a discussion of such risks and uncertainties which could cause actual results to differ from those contained in the forward-looking statements, see “Risk Factors” in the Company’s periodic reports filed with the SEC, including our Annual Report on Form 10-K for the fiscal year ended September 30, 2025, as well as interim quarterly filings thereafter. The forward-looking statements contained herein are not historical facts, but rather are based on current expectations, estimates, assumptions and projections about our industry and business. Such forward-looking statements are made as of the date hereof and may become outdated over time. The Company does not assume any responsibility for updating forward-looking statements.

Release – MAIA Biotechnology Doses First U.S. Patient in Ongoing Phase 2 Non-Small Cell Lung Cancer Clinical Trial

Primary Logo

Research News and Market Data on MAIA

September 16, 2026 8:15am EDT Download as PDF

Milestone follows FDA clearance of MAIA’s amended investigational new drug (IND) submission highlighting improved manufacturing capabilities and efficiencies 

U.S. expansion is funded by a $2.3 million NIH grant to MAIA to support third-line treatment evaluation

CHICAGO, Sept. 16, 2026 (GLOBE NEWSWIRE) — MAIA Biotechnology, Inc. (NYSE American: MAIA) (“MAIA”, the “Company”), a clinical-stage biopharmaceutical company focused on developing targeted immunotherapies for cancer, today announced that the first U.S. patient has been dosed in its Phase 2 THIO-101 trial expansion evaluating its telomere-targeting lead candidate, ateganosine, in third-line non-small cell lung cancer (NSCLC). The U.S. Phase 2 expansion is funded by a $2.3 million grant from the National Institutes of Health (NIH) to support third-line treatment evaluation and MAIA has activated 3 sites in the U.S.

MAIA holds FDA Fast Track designation for ateganosine, a dual mechanism therapy designed to break down telomere structure and function in cancer cells while inducing immune activation. Prior data from THIO-101 Parts A and B show overall survival (OS) beyond 24 months in eight patients receiving ateganosine sequenced with a checkpoint inhibitor.

“We have worked diligently to advance ateganosine into the U.S. market, and dosing the first patient in the United States represents a major milestone for our ongoing Phase 2 clinical trial,” said Vlad Vitoc, M.D., Founder and Chief Executive Officer of MAIA. “Our collaborations with some of the nation’s top institutions and foremost oncologists further strengthen the trial as we evaluate ateganosine for patients in advanced stages of this exceedingly hard-to-treat disease. We believe the data generated through the THIO-101 program may also support a potential pathway toward FDA accelerated approval. With patients now enrolled across four continents, the study has evolved into a truly global effort focused on addressing a critical unmet need in cancer care.”

About Ateganosine

Ateganosine (THIO, 6-thio-dG or 6-thio-2’-deoxyguanosine) is a first-in-class investigational telomere-targeting agent currently in clinical development to evaluate its activity in non-small cell lung cancer (NSCLC). Telomeres, along with the enzyme telomerase, play a fundamental role in the survival of cancer cells and their resistance to current therapies. The modified nucleotide 6-thio-2’-deoxyguanosine induces telomerase-dependent telomeric DNA modification, DNA damage responses, and selective cancer cell death. Ateganosine-damaged telomeric fragments accumulate in cytosolic micronuclei and activates both innate (cGAS/STING) and adaptive (T-cell) immune responses. The sequential treatment of ateganosine followed by PD-(L)1 inhibitors resulted in profound and persistent tumor regression in advanced, in vivo cancer models by induction of cancer type–specific immune memory. Ateganosine is presently developed as a second or later line of treatment for NSCLC for patients that have progressed beyond the standard-of-care regimen of existing checkpoint inhibitors.

About THIO-101 Phase 2 Clinical Trial

THIO-101 is a multicenter, open-label, dose finding Phase 2 clinical trial. It is the first trial designed to evaluate ateganosine’s anti-tumor activity when followed by PD-(L)1 inhibition. The trial is testing the hypothesis that low doses of ateganosine administered prior to cemiplimab (Libtayo®) will enhance and prolong immune response in patients with advanced NSCLC who previously did not respond or developed resistance and progressed after first-line treatment regimen containing another checkpoint inhibitor. The trial design has two primary objectives: (1) to evaluate the safety and tolerability of ateganosine administered as an anticancer compound and a priming immune activator (2) to assess the clinical efficacy of ateganosine using Overall Response Rate (ORR) as the primary clinical endpoint. The expansion of the study will assess overall response rates (ORR) in advanced NSCLC patients receiving third line (3L) therapy who were resistant to previous checkpoint inhibitor treatments (CPI) and chemotherapy. Treatment with ateganosine followed by cemiplimab (Libtayo®) has shown an acceptable safety profile to date in a heavily pre-treated population. For more information on this Phase II trial, please visit ClinicalTrials.gov using the identifier NCT05208944.

About MAIA Biotechnology, Inc.

MAIA is a targeted therapy, immuno-oncology company focused on the development and commercialization of potential first-in-class drugs with novel mechanisms of action that are intended to meaningfully improve and extend the lives of people with cancer. Our lead program is ateganosine (THIO), a potential first-in-class cancer telomere targeting agent in clinical development for the treatment of NSCLC patients with telomerase-positive cancer cells. For more information, please visit www.maiabiotech.com.

Forward Looking Statements

MAIA cautions that all statements, other than statements of historical facts contained in this press release, are forward-looking statements. Forward-looking statements are subject to known and unknown risks, uncertainties, and other factors that may cause our or our industry’s actual results, levels or activity, performance or achievements to be materially different from those anticipated by such statements. The use of words such as “may,” “might,” “will,” “should,” “could,” “expect,” “plan,” “anticipate,” “believe,” “estimate,” “project,” “intend,” “future,” “potential,” or “continue,” and other similar expressions are intended to identify forward looking statements. However, the absence of these words does not mean that statements are not forward-looking. For example, all statements we make regarding (i) the initiation, timing, cost, progress and results of our preclinical and clinical studies and our research and development programs, (ii) our ability to advance product candidates into, and successfully complete, clinical studies, (iii) the timing or likelihood of regulatory filings and approvals, (iv) our ability to develop, manufacture and commercialize our product candidates and to improve the manufacturing process, (v) the rate and degree of market acceptance of our product candidates, (vi) the size and growth potential of the markets for our product candidates and our ability to serve those markets, and (vii) our expectations regarding our ability to obtain and maintain intellectual property protection for our product candidates, are forward looking. All forward-looking statements are based on current estimates, assumptions and expectations by our management that, although we believe to be reasonable, are inherently uncertain. Any forward-looking statement expressing an expectation or belief as to future events is expressed in good faith and believed to be reasonable at the time such forward-looking statement is made. However, these statements are not guarantees of future events and are subject to risks and uncertainties and other factors beyond our control that may cause actual results to differ materially from those expressed in any forward-looking statement. Any forward-looking statement speaks only as of the date on which it was made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law. In this release, unless the context requires otherwise, “MAIA,” “Company,” “we,” “our,” and “us” refers to MAIA Biotechnology, Inc. and its subsidiaries.

Investor Relations Contact
+1 (872) 270-3518
[email protected]

Primary Logo

Source: MAIA Biotechnology, Inc.

Released September 16, 2026

Fed Raises Rates for First Time Since 2023 as Inflation Fight Reenters Center Stage

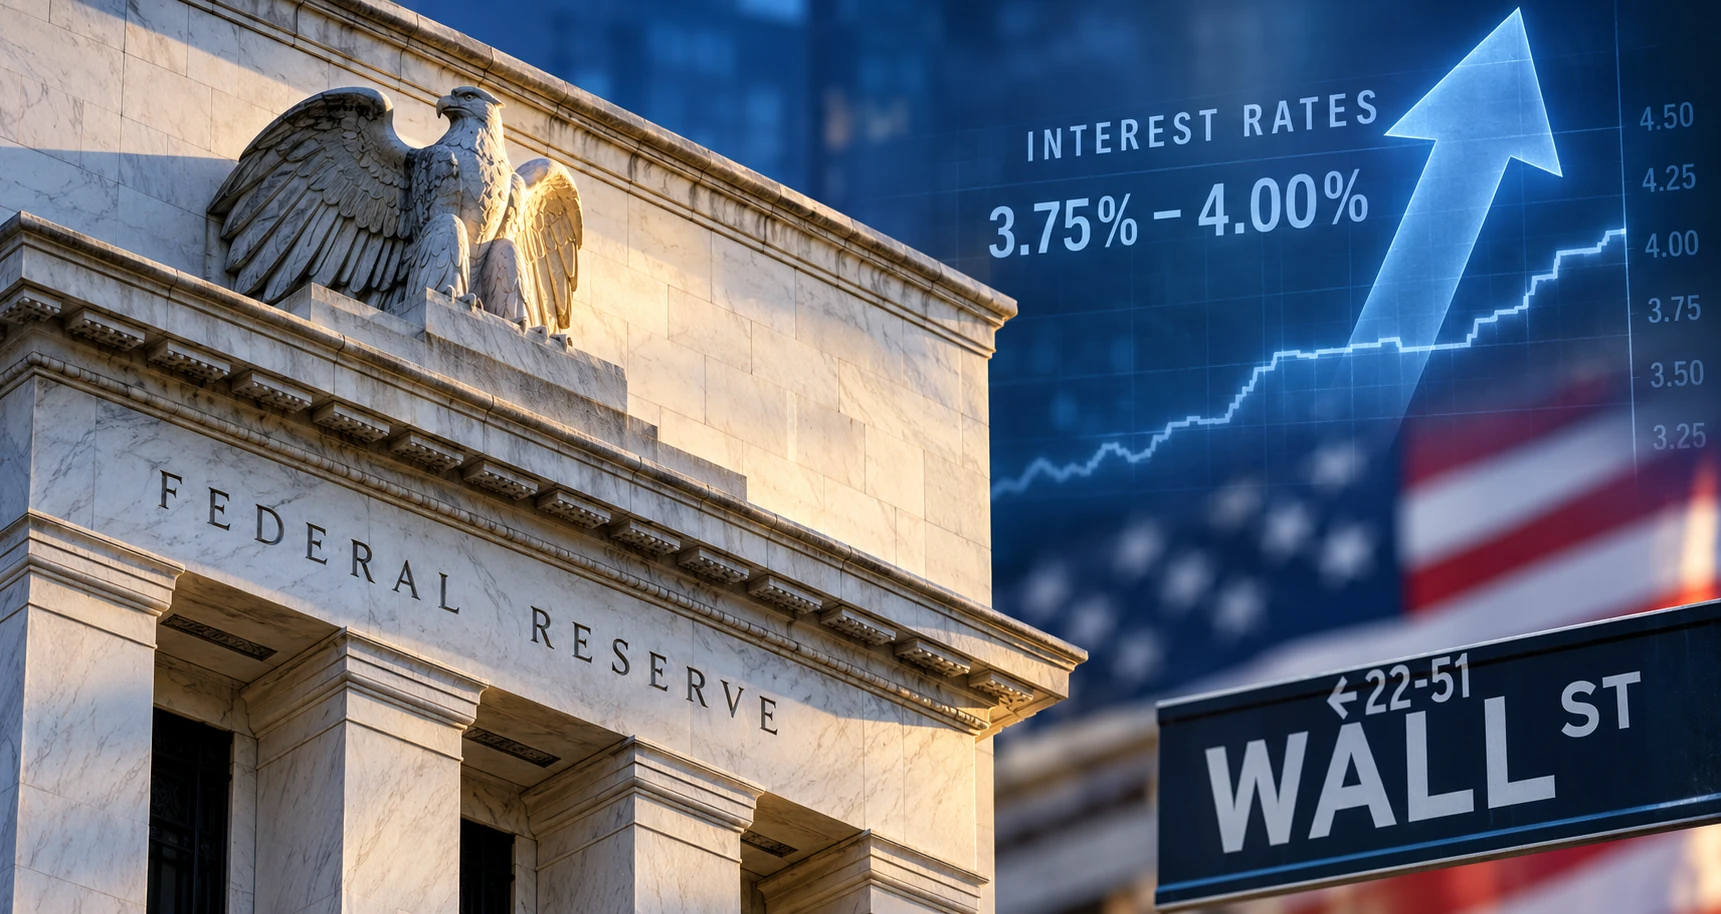
The Federal Reserve raised interest rates Wednesday for the first time in more than three years, reversing course as persistent inflation and renewed energy pressures pushed policymakers back toward tighter monetary policy.

The Federal Open Market Committee voted 12-0 to increase the federal funds target range by 25 basis points to 3.75% to 4.00%. In its statement, the Fed said economic activity continues to expand at a solid pace, domestic spending remains resilient, productivity growth is strong and capital investment is robust, while inflation remains elevated.

The move itself had been widely expected. The more important message for investors came from the Fed’s updated projections and Chair Kevin Warsh’s press conference: policymakers are not signaling that Wednesday’s increase will necessarily be a one-time adjustment.

A majority of Fed officials now expect at least one additional rate increase before the end of 2026, while the median projection points to rates around 4.1% at year-end. Twelve of 18 officials projected one more increase this year, while another four anticipated two additional hikes could be appropriate.

Warsh reinforced that message in unusually direct terms, telling reporters that “inflation is too high and has been for too long.”

For investors, that changes the conversation. After years in which markets focused largely on when interest rates would fall, the Federal Reserve is once again signaling that rates can move higher if inflation fails to return toward its 2% target.

Why the Fed Raised Rates Now

The Fed’s decision reflects an economy that has proven resilient even as inflation has remained stubbornly above target. In Wednesday’s statement, policymakers said economic activity is expanding at a solid pace, domestic spending remains resilient and capital investment is robust. Employment conditions also remain relatively stable, with job gains keeping pace with growth in the workforce and unemployment changing little.

That strength gives the Fed more room to concentrate on inflation. Price pressures have intensified in recent months, particularly through energy. Higher oil and gasoline prices tied to geopolitical disruptions have pushed headline inflation higher, while underlying inflation has also remained above the Fed’s comfort zone.

The Fed’s updated projections reflect that concern. Officials now expect overall inflation of roughly 3.7% in 2026 and core inflation of about 3.4%, both slightly higher than their June estimates. Policymakers still expect inflation to moderate next year, but the path back toward 2% has become slower and less certain. That combination — persistent inflation and an economy that has not weakened dramatically — made another rate increase easier to justify.

Energy Makes the Inflation Problem More Complicated

The current inflation backdrop is particularly difficult because a meaningful portion of the pressure originates outside the traditional reach of monetary policy. Higher interest rates cannot increase crude-oil production, repair energy infrastructure or eliminate geopolitical disruptions. The Fed can only influence demand by making borrowing and spending more expensive.

But energy inflation does not always remain isolated. Higher gasoline and diesel prices can raise transportation costs, more expensive jet fuel can affect airfare, and higher shipping and manufacturing costs can eventually filter into the prices of goods and services throughout the economy.

The Fed therefore faces a difficult balancing act. Policymakers may want to avoid overreacting to a temporary oil shock, but they also do not want elevated energy prices to become embedded in broader inflation expectations. That concern helps explain the language in Wednesday’s statement that the rate increase should support a “timelier return” to the Fed’s 2% inflation objective.

A Major Reversal in the Rate Cycle

Wednesday’s move is historically significant because it marks the Fed’s first increase since July 2023. The previous tightening cycle ultimately pushed the upper end of the federal funds target range to 5.50% in 2023 before the Fed eventually began cutting rates as inflation moderated. By 2026, the target range had fallen back to 3.50% to 3.75%.

Now the direction has reversed again. That matters because the Fed is not tightening from near-zero rates, as it did earlier in the decade. It is raising borrowing costs from a level that was already restrictive compared with much of the post-financial-crisis period. The implication is that households and businesses are entering this renewed tightening phase while already dealing with relatively expensive credit.

What Higher Rates Mean for Investors

A quarter-point increase in the federal funds rate does not translate directly into a quarter-point move across every market, but it raises the baseline cost of short-term money throughout the financial system. Credit-card rates, floating-rate business loans and other short-term borrowing costs tend to respond relatively quickly. Mortgage rates are more closely tied to longer-term Treasury yields, but higher Fed rates can still contribute to tighter financial conditions more broadly.

For equity investors, the bigger issue is valuation. Higher interest rates increase the discount rate investors use when valuing future corporate earnings. That tends to weigh most heavily on companies whose valuations depend heavily on profits expected far into the future.

At the same time, fixed income becomes more competitive. When investors can earn attractive yields on government securities, money-market funds and high-quality bonds, equities must offer a more compelling expected return to justify the additional risk. That does not mean stocks automatically decline when rates rise. Earnings growth, economic strength and company-specific fundamentals still matter. But the hurdle rate for owning risk assets becomes higher.

Small Caps Face Pressure — but Not Uniformly

Smaller public companies can be particularly sensitive to higher interest rates because they often rely more heavily on bank financing, floating-rate debt or repeated access to capital markets. That means refinancing risk becomes increasingly important.

A small-cap company with high debt and weak free cash flow may face significantly higher borrowing costs as older debt matures. By contrast, a company with strong cash generation, low leverage and limited near-term refinancing needs can gain a relative advantage over more indebted competitors.

Higher rates can therefore create greater dispersion within the small-cap market rather than producing the same outcome for every company. There are also sector-specific opportunities. Banks may benefit if a more favorable yield curve improves lending spreads without producing a major deterioration in credit quality. Industrials tied to domestic investment can continue to benefit if economic activity remains strong. Companies with cash-rich balance sheets may also become more competitive in acquisitions because leveraged buyers face higher financing costs.

For small-cap investors, the environment places a greater premium on balance-sheet strength, profitability, cash flow and financing discipline.

Treasury Yields Remain a Critical Variable

The Fed’s decision comes against the backdrop of another important development: long-term Treasury yields have recently moved back toward levels not seen since before the financial crisis. The 10-year Treasury yield has hovered near 5%, while longer-term yields remain elevated.

Those rates matter enormously because they influence mortgage rates, corporate bond yields and equity valuations more directly than the overnight federal funds rate in many parts of the economy. Interestingly, the bond market did not respond to Wednesday’s hike with a straightforward surge in yields. The 10-year Treasury yield slipped to roughly 4.95%, while the 2-year yield finished around 4.65% after initially moving around following the announcement.

That reaction highlights an important paradox. If investors believe the Fed is serious about bringing inflation under control, tighter policy today can sometimes reduce inflation expectations and help stabilize longer-term interest rates. In other words, a rate hike can increase short-term borrowing costs while potentially helping prevent an even larger increase in long-term yields.

Wall Street Initially Struggles to Interpret the Message

Markets were volatile as investors digested the Fed’s decision and Warsh’s comments. Equities initially moved around the flatline before diverging across the major indexes. The Dow came under pressure during the afternoon, while the S&P 500 and Nasdaq were more resilient as investors balanced the prospect of additional rate hikes against easing oil prices and relatively healthy economic growth.

That mixed reaction makes sense because Wednesday’s decision contains both negative and potentially constructive elements for investors. Higher rates raise financing costs and can pressure equity valuations. At the same time, the Fed’s willingness to respond aggressively to inflation can reinforce confidence that policymakers will not allow price pressures to become permanently entrenched.

That distinction is important. Markets generally dislike inflation uncertainty because it makes future corporate profits, interest rates and asset valuations harder to estimate. A credible inflation response may therefore carry short-term costs while improving longer-term visibility.

What the Fed Is Signaling Next

The updated projections suggest Wednesday’s increase may not be the end of the tightening cycle. A majority of Fed officials expect at least one more hike before year-end, while a smaller group sees the possibility of two additional increases. The median forecast then shows rates remaining largely unchanged through 2027.

Warsh, however, stopped short of committing to a predetermined path. That means upcoming inflation, employment and spending data will take on increased importance. If oil prices ease and inflation begins moving convincingly lower, the Fed could decide that limited additional tightening is sufficient. If energy costs remain elevated and inflation spreads more broadly through the economy, policymakers would have a stronger case for additional increases.

Economic growth will matter as well. As long as consumer spending, employment and business investment remain resilient, the Fed has more flexibility to focus on inflation. A meaningful weakening in those areas would make further tightening considerably more difficult.

Political Pressure Adds Another Layer

The decision also arrives during an unusual period for the central bank. President Donald Trump appointed Warsh as Fed chair earlier this year after repeatedly calling for lower interest rates. Since taking office, Warsh has emphasized that the Fed’s decisions will be driven by inflation, employment and its congressional mandate rather than political preferences.

Wednesday’s unanimous increase therefore puts the central bank on a different policy path from the lower-rate stance publicly advocated by the president. The Fed’s institutional independence matters to financial markets because confidence in monetary policy can influence inflation expectations and long-term Treasury yields.

If investors believe the central bank will tolerate excessive inflation because of political pressure, they may demand higher yields to compensate for future purchasing-power risk. If they believe the Fed will act when necessary, even when doing so is politically unpopular, that credibility can help anchor longer-term expectations.

A Different Market Environment

For much of the past year, the primary debate on Wall Street centered on when the Federal Reserve would cut interest rates and how quickly borrowing costs might decline. Wednesday’s move changes that narrative.

The Fed has now demonstrated that rates can move in either direction when economic conditions warrant it. More importantly, policymakers are signaling that further tightening remains possible if inflation does not improve. For investors, that means the outlook for inflation, energy prices and Treasury yields becomes even more important.

Companies with weak balance sheets or heavy refinancing needs could face additional pressure. Businesses with strong cash flow, low leverage and pricing power may be better positioned. Banks and other financial companies could benefit under certain yield-curve conditions, while savers and fixed-income investors may continue earning yields that were unavailable for much of the previous decade.

The rate increase itself was widely anticipated. The more important message from Washington is that the inflation fight is not over, and the Federal Reserve is prepared to keep monetary policy restrictive until it sees clearer evidence that price pressures are returning toward its 2% objective.

For investors, the question now shifts from whether the Fed would raise rates in September to how many additional increases may be required — and which companies are best positioned for a world in which the cost of money stays higher for longer.

Xenetic Biosciences and Santersus Agree to All-Stock Combination to Create Nasdaq-Listed NET Therapeutics Company

Xenetic Biosciences (NASDAQ: XBIO) and privately held Santersus AG have entered into a definitive share exchange agreement that would combine the two biotechnology companies and create a Nasdaq-listed company focused on therapies targeting neutrophil extracellular traps, or NETs.

Under the agreement, Xenetic will acquire all outstanding shares of Santersus in exchange for newly issued Xenetic common stock. Following closing, Santersus shareholders are expected to own approximately 85% of the combined company, while existing Xenetic shareholders are expected to own approximately 15%. The combined company is expected to be renamed Santersus Bio, Inc. and trade on Nasdaq under the ticker SNTS.

Although Xenetic is technically the acquiring entity, the ownership and governance structure make the transaction more akin to a strategic combination than a conventional acquisition. Santersus shareholders will hold the large majority of the post-transaction equity, Santersus management is expected to lead the combined company, and the new board is expected to include six Santersus nominees and two Xenetic nominees.

Building a Broader NET-Targeting Platform

The strategic rationale centers on combining complementary approaches to targeting NETs.

NETs are web-like structures released by neutrophils as part of the immune response. While they can help trap pathogens, excessive or persistent NET formation has also been implicated in inflammation, thrombosis, tissue injury and disease progression across a range of conditions.

Santersus is developing NucleoCapture, a therapeutic blood-filtration platform designed to remove circulating NETs and related pathogenic components directly from the bloodstream. The company has been pursuing applications in conditions including sepsis, systemic lupus erythematosus and liver transplantation.

Xenetic brings a different approach through its DNase platform, which is designed to enzymatically degrade NETs. Xenetic has been developing this approach primarily in oncology, including as a potential way to improve the effectiveness of cancer therapies such as CAR-T by reducing the protective effects NETs may provide within the tumor microenvironment.

The combined company would therefore have both extracorporeal and biologic approaches to the same broad target, creating a portfolio that spans inflammatory disease, transplantation and oncology.

Santersus Brings the Lead Clinical-Stage Asset

Santersus’ NucleoCapture platform is expected to become the principal clinical development focus of the combined company. The technology is designed to filter NETs and other disease-associated extracellular material from circulating blood without broadly suppressing the immune system. Santersus has positioned the platform for acute and immune-mediated conditions where excessive NET formation may contribute to disease severity.

The company’s development programs include sepsis, lupus and liver transplantation, areas where treatment options can be limited and where severe inflammatory responses may cause substantial organ damage. For Xenetic, the transaction significantly broadens its development pipeline while moving the combined organization closer to clinically advanced opportunities than Xenetic would have on its own.

Governance Reflects the Economic Structure

The post-transaction governance reinforces the fact that this is not a typical buyer-target acquisition. Santersus’ leadership is expected to run the combined company, while Xenetic will contribute its Nasdaq listing, existing programs and corporate infrastructure. The board composition is also expected to tilt heavily toward Santersus, consistent with the roughly 85/15 ownership split.

That makes the transaction structurally similar to other biotech combinations in which a private company gains access to the public markets through a merger with an existing listed entity. For investors, the key point is that the future investment thesis will be driven primarily by Santersus’ clinical programs and the broader NET-targeting strategy, rather than by Xenetic’s historical business alone.

Why NET Biology Is Drawing Interest

The scientific interest in NETs has grown as researchers have linked excessive NET formation to a wide range of inflammatory, thrombotic and immune-mediated diseases. In sepsis, NETs may contribute to microvascular obstruction, inflammation and organ damage. In autoimmune disease, persistent NET formation has been associated with immune dysregulation. In transplantation, the same inflammatory mechanisms may contribute to ischemia-reperfusion injury and graft dysfunction.

That broad biological relevance creates opportunities, but it also raises an important development challenge: showing that targeting NETs can translate into meaningful clinical outcomes across specific indications. The combined Santersus/Xenetic company will need to demonstrate not only that NET burden can be reduced, but that doing so improves patient outcomes in well-defined patient populations.

A Broader Biotech Theme: Controlling Harmful Immune Responses

The transaction also fits into a wider biotechnology trend involving therapies designed to control damaging immune activity without broadly shutting down the immune system.

One related company followed by Noble Capital Markets is Eledon Pharmaceuticals (NASDAQ: ELDN). Eledon is developing tegoprubart, an anti-CD40L antibody designed to prevent immune rejection in organ and islet-cell transplantation while avoiding some of the limitations associated with conventional immunosuppressive drugs. Noble research has highlighted Eledon’s kidney-transplant and islet-transplant programs as the company advances tegoprubart through clinical development.

The mechanisms are different, but the strategic overlap is clear: both Santersus and Eledon are pursuing more targeted ways to address harmful immune activity in settings where excessive inflammation or immune rejection can drive poor outcomes.

Cadrenal Adds a Critical-Care Parallel

Another Noble-covered company with a related critical-care angle is Cadrenal Therapeutics (NASDAQ: CVKD). Cadrenal is developing therapies for serious thrombotic and cardiovascular conditions, including tecarfarin and CAD-1005. Its pipeline includes programs in heparin-induced thrombocytopenia and other acute-care settings where thrombosis and coagulation abnormalities can create significant clinical risk.

Again, the biology is different, but Cadrenal provides another example of a small-cap biotechnology company targeting severe, high-risk conditions where existing therapies may be inadequate and where improved control of inflammation, coagulation or immune dysfunction could have meaningful clinical value.

A Public-Market Reset for Xenetic

For Xenetic shareholders, the transaction represents a major reset of the company’s strategic direction. If completed, the combined company will be much more heavily defined by Santersus, both economically and operationally. Existing Xenetic shareholders will retain a minority position in a broader NET-targeting platform that includes multiple clinical indications and a new management team.

For Santersus, the agreement provides a path to the U.S. public markets and access to a Nasdaq-listed platform without pursuing a traditional initial public offering. The result is a combination designed to create a more diversified biotechnology company around a relatively focused scientific thesis: that excessive NET formation plays a meaningful role across inflammatory, transplant and oncology indications, and that directly targeting those NETs could create new therapeutic opportunities.

If the transaction closes as planned, investors will be evaluating the new Santersus Bio less as a continuation of Xenetic and more as a newly assembled NET therapeutics company with a substantially different pipeline, ownership structure and clinical focus.

Release – Clinical Trial of the Oral Drug NV-387 to Treat Ebola to Start Next Week, Hoping to Reduce Fatalities and Spread, As the Largest Ebola Outbreak is Expanding in 
DR Congo with 48% Crude Fatality Rate, Says NanoViricides

Clinical Trial of the Oral Drug NV-387 to Treat Ebola to Start Next Week, Hoping to Reduce Fatalities and Spread, As the Largest Ebola Outbreak is Expanding in 
DR Congo with 48% Crude Fatality Rate, Says NanoViricides

Research News and Market Data on NNVC

Tuesday, 15 September 2026 09:25 AM

Topic: 

Company Update

SHELTON, CT / ACCESS Newswire / September 15, 2026 / NanoViricides, Inc. (NYSE American:NNVC) (the “Company”), a clinical stage leader developing antiviral drugs that viruses cannot escape, announces that its Phase II Clinical Trial of NV-387 Oral Gummies as a Treatment for the Current Bundibugyo Ebolavirus and other Ebola viruses in the Democratic Republic of Congo (“DRC”) is scheduled to start next week at an Ebola Treatment Center in the Ituri province.

“NV-387 being an oral drug with broad-spectrum antiviral properties, everyone is rooting for it and hoping that it is effective against Ebola in the this clinical trial,” said Anil R. Diwan, PhD, President of the Company, adding, “The Bundibugyo virus for which there is no known treatment or vaccine is causing an unprecedented, rapidly spreading, disease outbreak with a crude fatality rate as high as 48%. We hope that NV-387 can help save lives.”

Currently, a clinical trial called “PARTNERS” was started as of July 2, 20261 to evaluate two drugs that both require delivery by infusion. Approximately 300 patients have already been enrolled in this trial across four groups, namely (i) Infusion of a monoclonal antibody cocktail, MBP134, (ii) Infusion of Remdesivir, (iii) Infusion of MBP134 plus Infusion of Remdesivir, and (iv) a control group with local standard of care.

Infusions are inherently unscalable for the extent of the current ebola outbreak in the resource-poor areas in DRC. Additionally, infusion treatment also increases risks to health care workers such as needle-sticks, as well as due to patient handling and possible blood exposure.

NV-387 is currently the only orally administered drug in clinical trials to the best of our knowledge, and this is why medical professionals in the field are looking forward to success in the clinical trial of NV-387.

Oral NV-387 was compared with Intravenously given Remdesivir given in animal studies of a lethal coronavirus infection model when NV-387 was originally developed as a treatment for COVID-19. NV-387 Oral was found to be superior in extending survival of the lethally infected animals when compared to Remdesivir I.V. in this study. Therefore, the Company believes that NV-387 oral drug can be reasonably expected to provide superior activity compared to at least remdesivir infusion that is already in the PARTNERS clinical trial.

Antibodies are easily overcome by viruses in the field, as was experienced during the COVID-19 pandemic. All antibody drugs that received emergency use approvals lost efficacy within a few months due to mutations in the SARS-CoV-2, an RNA virus. Ebola Bundibugyo is an RNA virus with likely similar rates of mutation. It remains to be seen if and how long MBP134 remains effective during the current Ebola outbreak, even if found to be effective and approved, for use.

The Bundibugyo virus is highly unlikely to escape NV-387, unlike in the case of antibodies such as MBP134. This is because NV-387 mimics a portion of the cell surface that is essential for all Ebola viruses to cause productive infection, no matter how different they are.

“Comparing NV-387 to currently available therapeutics under study leads us to rationally anticipate at least partial success in the proposed clinical trial,” said Dr. Diwan, warning, “However, it is the data from the clinical trial that will tell us if NV-387 is effective and can become an important pillar in response to this Ebola Outbreak Crisis in DRC.”

The clinical trial is entitled with a descriptive title: “An adaptive, multi-centre Phase IIA/IIB clinical trial of NV-387 oral gummies plus optimised supportive care in adults with Ebola virus disease (Bundibugyo or other orthoebolaviruses): a single-arm safety and dose run-in (Phase IIA) followed by a randomised, controlled, open-label efficacy evaluation with independent blinded-endpoint adjudication (Phase IIB).” Prof. Patrick de Marie Chimusa Katoto is the principal investigator leading this clinical trial, as previously announced by the Company. Om Sai is the CRO leading the Company’s Phase II clinical trial of NV-387 Oral Gummies as a Treatment for Mpox in DRC, and the same CRO is also leading this Ebola clinical trial.

The clinical trial is registered in the Pan African Clinical Trials Registry (pactr.samrc.ac.za) database. The unique identification number for this clinical trial is PACTR202608748555077.

It is anticipated that the first Ebola patient dosing with NV-387 oral gummies under this clinical trial can be expected to occur next week, barring impediments caused by the very ebola disease outbreak that the trial is designed to respond to.

The current Ebola Virus Disease (EVD) caused by the Bundibogyo ebolavirus (BDBV) is now the largest ever ebola outbreak, as well as the fastest growing ebola outbreak in DRC.

As of September 10, 2026, there have been 7,022 confirmed cases, 3,398 confirmed deaths, and 1,671 confirmed recoveries in DRC, according to the WHO daily report 2. In comparison, as of August 14, 2026, there were reported 4,945 confirmed cases and 2,325 confirmed deaths due to this virus. The crude fatality rate (crude CFR) 3 is about 48% .

The actual probability of an infected person dying is about 67%, with about 1/3rd of patients recovering in DRC (ibid #2 footnote).

This Ebola outbreak is now the fastest growing ebola outbreak in the world. Additionally, it is also possibly the deadliest ebola outbreak. At this rate, the current outbreak is on track to exceed the worst ever ebola zaire outbreak in West Africa in 2014-2016 4. In that outbreak, 28,616 cases and 11,310 deaths were recorded across Guinea, Liberia and Sierra Leone, according to the World Health Organization.

Schools have reopened normally in the Ebola affected regions across DRC, despite the well understood risk of transmission in schools. Teaching and implementing hygienic measures such as use of hand sanitizers and frequent hand washing is expected to minimize risk, enabling the children to have in-class education. The alternative of remote learning is very difficult to implement in resource-poor environments, and risks the children’s education itself. If cases occur, schools would be shut down. The risk is high, particularly because the crude case fatality rate (CFR) in children is at 60%, much greater than the CFR for adults at sub-50% 5.

Additionally, health care workers (HCW) are at high risk, despite personal protective equipment, because of close contact with the patients. At least 43 HCWs have died from Ebola and at least 160 have contracted the disease 6.

The need for an oral drug to combat this disease is thus obvious. An oral drug to treat patients, to prevent contacts from contracting the disease, and to keep healthcare workers safe, is sorely needed to combat this outbreak. There is a tremendous urgency to validate a drug that works against this ebolavirus in short and decisive clinical trials for minimizing further spread by treating patients and for saving lives. Om Sai CRO, in consultation with renowned scientists in DRC, has designed the Phase II clinical trial with this particular objective.

An oral drug called obeldesivir, which is related to the known drug remdesivir that previously failed in clinical trials against Ebola Zaire, is being tried in a clinical trial, but only as a preventative measure, and not as a treatment of active infection.

In contrast, in the PARTNERS clinical trial, infusions of antibody cocktails and of remdesivir are being tried. This trial will require over 1,000 patients to be treated and may not yield results for several months. A similar large collaborative clinical trial effort in the West Africa 2014-2016 outbreak resulted in US FDA approval of two antibody drugs only specifically for EBOV Zaire, which are not deemed to be useful in the current outbreak without further clinical trials.

Three different vaccines are also expected to enter into clinical trials for efficacy within months, according to the WHO 7. Ervebo, a vaccine developed for Ebola Zaire, is being deployed in a research protocol to health care workers. Its efficacy against BDBV needs to be evaluated in a clinical trial, according to WHO.

As of now, there is practically no risk from this Ebola outbreak for the USA, according to the CDC. The US has imposed strict travel restrictions to avoid any possible introduction of the ebola virus into the USA. The CDC is intimately involved in the Ebola response with 150 personnel deployed within DRC for the efforts (ibid #1).

NanoViricides has retained Om Sai Clinical Research Private Limited, India, (Om Sai CRO) as the CRO for this Phase II clinical trial for Ebola in DRC. Om Sai CRO has been instrumental in putting together the team with Prof. Katoto and other renowned experts and with support from the University of Bukavu and in the Ebola-affected region to lead and execute the clinical trial of NV-387 Oral Gummies as a Treatment for Ebola viruses in DRC.

As the Ebola outbreak continues to expand, several limitations on travel are being instated. There are also limitations on availability of resources such as PPE and diagnostic kits, which are compounded by the travel and other restrictions. These on-ground situations have caused delays in our efforts, and we anticipate such delays to continue due to the tenuous outbreak situation.

This Ebola outbreak continues to increase in spread and is now present in at least six provinces in DRC and threatening South Sudan 8. More concerning is the fact that over 80% of new cases are outside of known contact lists, leading to the projection that the extent of the outbreak is at least two times or more larger than the reported confirmed cases. Additionally, Ebola is now found to have spread into displacement camps that host over 4.4 million displaced persons due to internal warfare, adding another high risk population pool with poor drinking water, sanitation and medical resources to further fuel this outbreak, according to the UN New Service.

There is no approved Treatment or Vaccine for the new variant of the Bundibugyo Ebolavirus (BDBV) that is causing the current rapidly expanding outbreak of the Ebolavirus Disease (EVD) in DRC. The rare Bundibugyo strain of Ebola virus causing the current outbreak appears to be its new variant, likely freshly introduced from some animal source 9, such as fruit bats.

“Although this antiviral (Remdesivir) proved to be ineffective at targeting the Zaire Ebolavirus, there remains hope that it could have some benefit against the Bundibugyo virus, particularly if used in combination with MBP-134,” according to an article in Forbes explaining the “PARTNERS” clinical trial by the WHO organized collaboration 10. The article also notes that MBP134 contains two separate antibodies designed to, taken together, recognize multiple Ebola species.

Antibodies are highly specific to a particular strain of the virus and usually are not very effective against variants of the same virus that arise in the field. Viruses also escape antibodies readily by mutations in the field.

NV-387 is a broad-spectrum antiviral that mimics the host-side features that the virus requires, and is likely to be effective against Ebola viruses because they use the same host-side feature mimicked by NV-387.

NV-387 Oral Gummies is a drug product readily delivered orally. It does not even require swallowing effort or water, because it dissolves in the mouth by itself, simplifying delivery for even sick individuals with swallowing difficulties.

This oral delivery is an important feature that puts NV-387, a broad-spectrum antiviral, as being superior to the other approaches.

“Only safe and effective broad-spectrum antiviral drugs like NV-387 that can effectively tackle most viral infections will enable the world to combat viruses and defend the global population in the war against known and unknown nanoscopic enemies that are viruses,” commented Dr. Diwan, adding, “Today, NV-387 is the only drug in clinical development with such broad-spectrum potential that promises to combat diverse epidemics like Mpox and Ebola, to the best of our knowledge.”

While there is currently minimal risk of Ebola in the USA, the CDC’s mathematical models suggested this Central African outbreak could grow to 10,000 to 20,000 cases and 2,000 to 4,000 deaths within just three months, rivaling the largest outbreak to date in 2014-2016 11. Unfortunately, the outbreak appears to be even more aggressive than the CDC model, with over 2,000 deaths in less than three months, over 4,000 confirmed cases, and over 10,000 estimated total cases 12.

The outbreak which was declared a Public Health Emergency of International Concern (“PHEIC”) by the WHO on May 17, 2026, continues to rapidly expand, outpacing containment efforts. The outbreak arose in a high traffic region bordering the Democratic Republic of Congo (DRC), with travel contacts to Uganda, and South Sudan and with 11 more nations in Africa at risk 13.

NV-387 is a broad-spectrum antiviral that mimics the host-side feature called heparan sulfate proteoglycan (HSPG) that over 90-95% of human pathogenic viruses require for infecting cells. No matter how much the virus changes in the field, it continues to use HSPG, and therefore it cannot escape the drug NV-387. In contrast, Remdesivir is a small molecule inhibitor of the viral RDRP enzyme needed for making copies of the viral genome, and the virus can possibly escape by small number of mutations.

All Ebola viruses utilize HSPG as the attachment receptor prior to gaining entry into the cell. Thereafter, followed by entry into the cell inside endosomes, the ebolavirus surface glycoprotein is substantially degraded, opening up its site for binding to its cognate receptor called NPC1, thereby entering into the cytoplasm where the next steps in its replication begin.

Thus there is a strong rationale that NV-387 could be highly effective against Ebola virus infections, not just Bundibugyo, but also the Sudan and other viruses for which there are no treatments.

All previous anti-Ebola efforts have been focused on vaccines and antibodies 14. This has led to approval of therapies that are specific to the Ebolavirus Zaire strain only, albeit with limited effectiveness. This leaves out all other filoviruses of consequence: Sudan, Marburg, and the more rare Bundibugyo with no treatment or vaccine.

In contrast, if NV-387, as a broad-spectrum antiviral, is found to be effective against the Bundibugyo virus, it will likely be effective against all ebolaviruses and possibly all filoviruses; that would be a game changer for pandemic preparedness.

The case fatality rate of ebolaviruses has generally been approximately 50% in recent outbreaks, with improvements in care, including hydration therapy, corticosteroids, and other usual symptomatic treatments. Ebola viruses spread via bodily fluid secretions including fomites/sputum, as well as semen/genital secretions. Ebola virus can remain in survivors even as many as 965 days after the disease without symptoms, and can transmit through bodily secretions, suggesting possible latency. Many recent outbreaks have been ignited as a result of such reawakened-transmitted virus from a survivor. Sexual transmission was documented even as late as 482 days after disease. This persistence and possible latency of ebolavirus in immune-privileged organs (e.g. brain, eyes, gonads, where antibodies are not operative) makes it a uniquely serious threat for global transmission and sustained outbreaks.

At present, BDBV has been consistently demonstrating high crude CFR of 48% in DRC. Therefore, BDBV is of great concern as a potential pandemic disease. However, it is believed that ebolaviruses do not transmit via respiratory droplets or aerosols and rather require extensive contact with bodily fluids of an infected person. In addition, within DRC and internationally, certain protective quarantine measures for travel from the outbreak areas have been implemented.

Therefore, currently there is no apparent threat of a global pandemic.

An irony is that because of the high case fatality rate (CFR) approaching 50%, the spread of ebolaviruses remains rather limited. If a variant emerges with a reduced CFR, say in the range of 5-15%, the potential threat of global pandemic from such an outbreak would increase substantially.

With ever-increasing global travel, local outbreaks such as ebola can quickly travel far and wide potentially causing global pandemics, as was the case with COVID-19, if not caught in time. It is not feasible to produce a new vaccine and a new set of antibody drugs to combat every possible virus. Even if vaccines and antibodies are produced, the virus would escape by generating variants, as the world has witnessed during the COVID-19 pandemic.

The US Government is active in ensuring that suspected or confirmed ebolavirus cases do not enter the general population in the USA. To this end, travel from DRC has been restricted, with pre-travel quarantine requirements imposed, and suspect travelers are directed to screening at specific airports and may be further quarantined.

Travelers going to and from Central Africa need to constantly check travel restrictions as well as travel limitations in light of these changing outbreak conditions.

ABOUT NANOVIRICIDES

NanoViricides, Inc. (the “Company”) (www.nanoviricides.com) is a clinical stage company that is creating special purpose nanomaterials for antiviral therapy. The Company’s novel nanoviricide™ class of drug candidates and the nanoviricide™ technology are based on intellectual property, technology and proprietary know-how of TheraCour Pharma, Inc. The Company has a Memorandum of Understanding with TheraCour for the development of drugs based on these technologies for all antiviral infections. The MoU does not include cancer and similar diseases that may have viral origin but require different kinds of treatments.

The Company has obtained broad, exclusive, sub-licensable, field licenses to drugs developed in several licensed fields from TheraCour Pharma, Inc. The Company’s business model is based on licensing technology from TheraCour Pharma Inc. for specific application verticals of specific viruses, as established at its foundation in 2005.

Our lead drug candidate is NV-387, a broad-spectrum antiviral drug that we plan to develop as a treatment of RSV, COVID, Long COVID, Influenza, and other respiratory viral infections, as well as MPOX/Smallpox infections. Our other advanced drug candidate is NV-HHV-1 for the treatment of Shingles. The Company cannot project an exact date for filing an IND for any of its drugs because of dependence on a number of external collaborators and consultants. The Company is currently focused on advancing NV-387 into Phase II human clinical trials.

NV-CoV-2 (API NV-387) is our nanoviricide drug candidate for COVID-19 that does not encapsulate remdesivir. NV-CoV-2-R is our other drug candidate for COVID-19 that is made up of NV-387 with remdesivir encapsulated within its polymeric micelles. The Company believes that since remdesivir is already US FDA approved, our drug candidate encapsulating remdesivir is likely to be an approvable drug, if safety is comparable. Remdesivir is developed by Gilead. The Company has developed both of its own drug candidates NV-CoV-2 and NV-CoV-2-R independently.

The Company is also developing drugs against a number of viral diseases including oral and genital Herpes, viral diseases of the eye including EKC and herpes keratitis, H1N1 swine flu, H5N1 bird flu, seasonal Influenza, HIV, Hepatitis C, Rabies, Dengue fever, and Ebola virus, among others. NanoViricides’ platform technology and programs are based on the TheraCour® nanomedicine technology of TheraCour, which TheraCour licenses from AllExcel. NanoViricides holds a worldwide exclusive perpetual license to this technology for several drugs with specific targeting mechanisms in perpetuity for the treatment of the following human viral diseases: Human Immunodeficiency Virus (HIV/AIDS), Hepatitis B Virus (HBV), Hepatitis C Virus (HCV), Rabies, Herpes Simplex Virus (HSV-1 and HSV-2), Varicella-Zoster Virus (VZV), Influenza and Asian Bird Flu Virus, Dengue viruses, Japanese Encephalitis virus, West Nile Virus, Ebola/Marburg viruses, and certain Coronaviruses. The Company intends to obtain a license for RSV, Poxviruses, and/or Enteroviruses if the initial research is successful. As is customary, the Company must state the risk factor that the path to typical drug development of any pharmaceutical product is extremely lengthy and requires substantial capital. As with any drug development efforts by any company, there can be no assurance at this time that any of the Company’s pharmaceutical candidates would show sufficient effectiveness and safety for human clinical development. Further, there can be no assurance at this time that successful results against coronavirus in our lab will lead to successful clinical trials or a successful pharmaceutical product.

This press release contains forward-looking statements that reflect the Company’s current expectation regarding future events. Actual events could differ materially and substantially from those projected herein and depend on a number of factors. Certain statements in this release, and other written or oral statements made by NanoViricides, Inc. are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. You should not place undue reliance on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and which could, and likely will, materially affect actual results, levels of activity, performance or achievements. The Company assumes no obligation to publicly update or revise these forward-looking statements for any reason, or to update the reasons actual results could differ materially from those anticipated in these forward-looking statements, even if new information becomes available in the future. Important factors that could cause actual results to differ materially from the company’s expectations include, but are not limited to, those factors that are disclosed under the heading “Risk Factors” and elsewhere in documents filed by the company from time to time with the United States Securities and Exchange Commission and other regulatory authorities. Although it is not possible to predict or identify all such factors, they may include the following: demonstration and proof of principle in preclinical trials that a nanoviricide is safe and effective; successful development of our product candidates; our ability to seek and obtain regulatory approvals, including with respect to the indications we are seeking; the successful commercialization of our product candidates; and market acceptance of our products.

The phrases “safety”, “effectiveness” and equivalent phrases as used in this press release refer to research findings including clinical trials as the customary research usage and do not indicate evaluation of safety or effectiveness by the US FDA.

FDA refers to US Food and Drug Administration. IND application refers to “Investigational New Drug” application. cGMP refers to current Good Manufacturing Practices. CMC refers to “Chemistry, Manufacture, and Controls”. CHMP refers to the Committee for Medicinal Products for Human Use, which is the European Medicines Agency’s (EMA) committee responsible for human medicines. API stands for “Active Pharmaceutical Ingredient”. WHO is the World Health Organization. R&D refers to Research and Development.

Contact:
NanoViricides, Inc.
[email protected]

Public Relations Contact:
[email protected]

Source: NanoViricides, Inc.

1 https://www.reuters.com/business/healthcare-pharmaceuticals/trial-bundibugyo-ebola-treatment-starts-drc-who-says-2026-07-02/

2 https://www.who.int/emergencies/alert-and-response, retrieved on Monday September 14, 2026 at 14:10 EDT. See also, https://www.cdc.gov/ebola/situation-summary/index.html.

3 The Crude CFR is calculated simply by dividing the confirmed deaths by the confirmed number of cases on the same reporting date. It ignores the fact that the deaths are actually occurring in patients that were confirmed infected several days earlier; i.e. the time lag of sickness is not accounted for in the crude CFR. If it is accounted for, the actual fatality rate per confirmed infection (Infected Fatality Rate or IFR) would be much higher than the crude CFR. For example, if one assumes an average time lag of 21 days (Aug 14 to Sept 5), then the IFR on September 5 would be (3,175/4,945 = ) 64%. Not all infections are reported or confirmed by lab tests; however, it is likely that most deaths are counted. This produces a large uncertainty in such CFR and IFR estimates. Another way to estimate IFR would be to simply take a ratio of confirmed deaths to that of confirmed deaths plus confirmed recoveries. This metric, probability of death, is more robust and insensitive to the lag times, except it ignores patients that are still in hospital. The p(death) based on this metric is (using Sept. 10 numbers,(3,398)/(3,398 +1,671) = 67% . That said, a number of cases as well as deaths remain unconfirmed or unreported because of the regional issues.

4 https://www.telegraph.co.uk/global-health/science-and-disease/ebola-outbreak-doubling-every-20-days-warns-un-chief/

5 https://www.news4jax.com/news/world/2026/09/01/schools-resume-classes-in-congos-ebola-epicenter-despite-concerns-from-parents-and-teachers/ .

6 https://www.ft.com/content/abd30cb8-08f6-4a1a-a92b-f1fcc339ea82?syn-25a6b1a6=1&signupConfirmation=success

7 https://www.yahoo.com/news/science/articles/congo-ebola-outbreak-slows-epicentre-050000953.html

8 https://www.aljazeera.com/news/2026/7/20/ebola-death-toll-in-drc-surges-to-at-least-930-as-outbreak-gathers-pace

https://www.aljazeera.com/news/2026/7/16/ebola-spreading-more-quickly-in-drc-while-uganda-is-close-to-being-virus-free

9 https://virological.org/t/initial-genomes-from-may-2026-bundibugyo-virus-disease-outbreak-in-the-democratic-republic-of-the-congo-and-uganda/1032

10 https://www.forbes.com/sites/omerawan/2026/07/07/new-clinical-trials-offer-hope-in-the-fight-against-ebola-in-the-democratic-republic-of-congo/

11 https://www.cdc.gov/media/releases/2026/update-on-ebola-outbreak-in-the-democratic-republic-of-the-congo-and-uganda-6-5-2026.html

12 The WHO and Africa CDC have estimated that the confirmed case number substantially under-represents actual case numbers which could be at least double or even more than confirmed cases. See #5.

13 https://www.forbes.com/sites/maryroeloffs/2026/05/25/african-health-officials-on-ebola-this-is-too-much-live-updates/

14 Substantial work was also performed to develop small chemical potentially broad-spectrum agents. Remdesivir was the only small chemical that entered the PALM clinical trials ca. 2018-2019 but failed to show effectiveness. Small chemicals are readily escaped by viruses often with just single mutations.

SOURCE: NanoViricides

Release – MAIA Biotechnology Announces Open Market Purchases of Company Stock by Long-Standing Board Member and CEO

Primary Logo

Research News and Market Data on MAIA

September 15, 2026 8:15am EDT Download as PDF

CHICAGO, Sept. 15, 2026 (GLOBE NEWSWIRE) — MAIA Biotechnology, Inc. (NYSE American: MAIA) (“MAIA”, the “Company”), a clinical-stage biopharmaceutical company focused on developing immunotherapies for cancer, today announced that Board member Ramiro Guerrero, JD, LL.M. has increased his ownership stake in the Company through open market purchases totaling approximately $252,284. A total of 185,078 shares of MAIA common stock were acquired by Mr. Guerrero between August 20, 2026, and September 10, 2026, at an average common stock price of $1.36. MAIA also announced that 73,000 shares of MAIA common stock were acquired by Founder and CEO Vlad Vitoc, M.D. on September 14, 2026, at an average common stock price of $1.37.

“Our increased investments reflect the confidence we share across our leadership team in MAIA’s science, clinical strategy and long-term commercial potential,” said Dr. Vitoc. “With a growing body of clinical evidence supporting the ateganosine program, we believe MAIA is entering an increasingly important period in its development.”

“As MAIA has stated previously, its ongoing pivotal Phase 3 trial offers a statistically high probability of technical success,” Mr. Guerrero added. “I continue to believe MAIA is well positioned to create a great deal of value for its shareholders over time.”

MAIA’s ongoing pivotal Phase 3 trial THIO-104 evaluates ateganosine sequenced with checkpoint inhibitor cemiplimab versus investigator’s choice in third-line non-small cell lung cancer (NSCLC). Statistical assessments of ateganosine suggest a high probability of technical success and potential early full commercial approval if Phase 3 interim data is consistent with Phase 2 THIO-101 trial results. MAIA recently announced positive initial efficacy data from the ongoing Phase 2 THIO-101 clinical trial expansion, Part C, with third-line studies showing a disease control rate (DCR) of 90.5%1 in the efficacy evaluable population who had at least one tumor scan after starting treatment. 

As of September 14, 2026, MAIA’s directors and officers hold a 21.34% stake in the Company.

About Ateganosine

Ateganosine (THIO, 6-thio-dG or 6-thio-2’-deoxyguanosine) is a first-in-class investigational telomere-targeting agent currently in clinical development to evaluate its activity in non-small cell lung cancer (NSCLC). Telomeres, along with the enzyme telomerase, play a fundamental role in the survival of cancer cells and their resistance to current therapies. The modified nucleotide 6-thio-2’-deoxyguanosine induces telomerase-dependent telomeric DNA modification, DNA damage responses, and selective cancer cell death. Ateganosine-damaged telomeric fragments accumulate in cytosolic micronuclei and activates both innate (cGAS/STING) and adaptive (T-cell) immune responses. The sequential treatment of ateganosine followed by PD-(L)1 inhibitors resulted in profound and persistent tumor regression in advanced, in vivo cancer models by induction of cancer type–specific immune memory. Ateganosine is presently developed as a second or later line of treatment for NSCLC for patients that have progressed beyond the standard-of-care regimen of existing checkpoint inhibitors.

About MAIA Biotechnology, Inc.

MAIA is a targeted therapy, immuno-oncology company focused on the development and commercialization of potential first-in-class drugs with novel mechanisms of action that are intended to meaningfully improve and extend the lives of people with cancer. Our lead program is ateganosine (THIO), a potential first-in-class cancer telomere targeting agent in clinical development for the treatment of NSCLC patients with telomerase-positive cancer cells. For more information, please visit www.maiabiotech.com.

Forward Looking Statements

MAIA cautions that all statements, other than statements of historical facts contained in this press release, are forward-looking statements. Forward-looking statements are subject to known and unknown risks, uncertainties, and other factors that may cause our or our industry’s actual results, levels or activity, performance or achievements to be materially different from those anticipated by such statements. The use of words such as “may,” “might,” “will,” “should,” “could,” “expect,” “plan,” “anticipate,” “believe,” “estimate,” “project,” “intend,” “future,” “potential,” or “continue,” and other similar expressions are intended to identify forward looking statements. However, the absence of these words does not mean that statements are not forward-looking. For example, all statements we make regarding (i) the initiation, timing, cost, progress and results of our preclinical and clinical studies and our research and development programs, (ii) our ability to advance product candidates into, and successfully complete, clinical studies, (iii) the timing or likelihood of regulatory filings and approvals, (iv) our ability to develop, manufacture and commercialize our product candidates and to improve the manufacturing process, (v) the rate and degree of market acceptance of our product candidates, (vi) the size and growth potential of the markets for our product candidates and our ability to serve those markets, and (vii) our expectations regarding our ability to obtain and maintain intellectual property protection for our product candidates, are forward looking. All forward-looking statements are based on current estimates, assumptions and expectations by our management that, although we believe to be reasonable, are inherently uncertain. Any forward-looking statement expressing an expectation or belief as to future events is expressed in good faith and believed to be reasonable at the time such forward-looking statement is made. However, these statements are not guarantees of future events and are subject to risks and uncertainties and other factors beyond our control that may cause actual results to differ materially from those expressed in any forward-looking statement. Any forward-looking statement speaks only as of the date on which it was made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law. In this release, unless the context requires otherwise, “MAIA,” “Company,” “we,” “our,” and “us” refers to MAIA Biotechnology, Inc. and its subsidiaries.

Investor Relations Contact
+1 (872) 270-3518
[email protected]


1 As of July 6, 2026

Primary Logo

Source: MAIA Biotechnology, Inc.

Released September 15, 2026