Kratos Defense & Security (KTOS) – A Solid Third Quarter


Tuesday, November 10, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. Kratos reported another strong quarter with revenue at the midpoint of guidance and adjusted EBITDA exceeding the high end of guidance. The Company’s third-quarter results reflect Kratos’ position as a leading defense technology, hardware, software, and systems company, aligned with the Department of War’s priorities and reindustrialization efforts, in our view. 

3Q26 Results. Third quarter 2026 revenues of $471.8 million increased by $124.2 million year-over-year. We had projected $462 million. KGS revenue grew 52.5% to $397.2 million, while KUS segment revenue declined to $74.6 million from $87.2 million due to the absence of a $16.1 million Valkyrie sale completed last year. Adjusted EBITDA was $50.9 million versus $30.8 million. Kratos reported adjusted earnings per share of $0.24 for the third quarter of 2026, compared to $0.14 for the third quarter of 2025. We had projected $41 million and $0.22/sh, respectively.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

V2X (VVX) – Strong Third Quarter Results


Tuesday, November 03, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. V2X delivered another strong quarter, with revenue growth and double-digit increases in net income and diluted EPS. Results reflect consistent execution and continued demand for V2X’s mission-critical capabilities. V2X experienced another quarter of strong cash generation and maintained a healthy balance sheet. With this flexibility, the Company is continuing to invest in priority growth areas, including expanding capacity in engineering and product capabilities.

3Q26 Results. Third-quarter revenue of $1.271 billion was up from $1.167 billion and exceeded our $1.19 billion estimate. Adjusted EBITDA came in at $88.6 million, up from $85.2 million in 3Q25 and above our $86 million estimate. Adjusted EPS was $1.64, up 19% y-o-y, and exceeded our $1.46 projection.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

T3 Defense (DFNS) – A New Acquisition


Wednesday, October 28, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Acquisition. T3 Defense has entered into a definitive agreement to acquire KeepZone AI from Nexera Technologies. KeepZone expands T3’s offerings into the Homeland Security vertical. The acquisition allows T3 to expand its commercial reach while providing the Company with a U.S. presence and active channels in North America, Latin America, and the Gulf. We view the proposed acquisition as another building block in T3’s efforts to build a mission-critical defense business embedded at critical chokepoints.

Details. Initial consideration is $1.0 million, payable in common stock (and, to the extent required by a 4.9% beneficial ownership limitation, pre-funded warrants), priced at the average closing price of T3 Defense common stock for the five trading days preceding closing. Nexera is also eligible for an earn-out equal to 50% of KeepZone’s standalone net profit generated during the 24 months following the closing, calculated on the first $10.0 million of net profit and therefore capped at $5.0 million, payable in cash. Closing is expected within 60 days.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Kratos Defense & Security (KTOS) – A Tuck-in and Other News


Monday, October 19, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

A Tuck-in. Last week, Kratos acquired Jetset Airmotive from its founders. Jetset’s MRO operations on PT6A turbine engines complement Kratos’ existing MRO operations conducted through its Oklahoma-based CTS subsidiary. Based on previous such transactions, we believe the acquisition was structured as 50% KTOS shares and 50% cash, which would imply roughly $50 million in total. With an estimated $40-$50 million in revenue and typical 13-14% EBITDA margins, Jetset was purchased for approximately 1x revenue and 9x EBITDA. The acquisition should add about $5+ million to annual EBITDA.

New Contracts. Kratos has been awarded more than $100 million over multiple contracts to develop prototype mission applications and cyber capabilities, providing space intelligence data in support of joint operations across the space and cyberspace domains. The contracts will leverage Kratos’ software products, analytics, and expertise in RF, signal processing, cybersecurity, and software development, establishing a proven technology base that can be adapted and integrated to meet emerging space and cyber mission requirements.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

V2X (VVX) – Follow-on Award


Thursday, September 24, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Business. V2X continues to add business with a recent follow-on award from the Air Force for base support services and a position on an ID/IQ supporting the Air Force’s Carriage Equipment Production Effort for the Long Range Standoff (LRSO) cruise missile program. Such awards demonstrate V2X’s strong position to bid for and win new and expanded business, in our opinion.

Follow-on. The Department of War announced that V2X Systems has been awarded an undefinitized contract action with a not-to-exceed ceiling price of $231.8 million, a modification to a previously awarded contract for base support services in support of the Iraq F-16 program. The modification brings the total cumulative face value of the contract to $594.2 million. Work will be performed at Martyr BG Ali Flaih Air Base, Iraq, and is expected to be completed by July 17, 2027. Foreign Military Sales funds in the amount of $115.9 million are being obligated at the time of award.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Swarmer to Acquire Ratel Robotics for Up to $224 Million, Expanding Into Unmanned Ground Systems

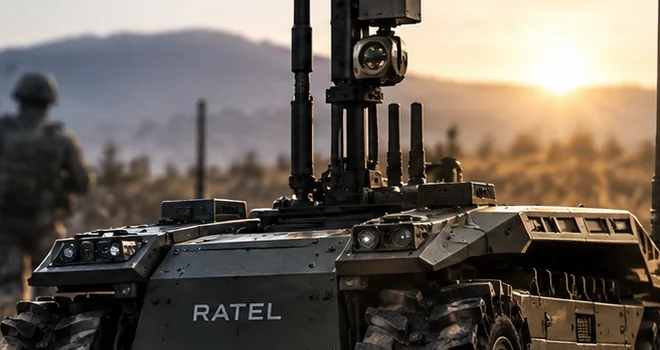
Swarmer, Inc. (NASDAQ: SWMR) announced Thursday that it has entered into a definitive agreement to acquire Ratel Robotics, a leading Ukrainian manufacturer of unmanned ground vehicles, in a transaction valued at up to $224 million if all earnout milestones are achieved.

The acquisition would mark Swarmer’s first major deal under Chairman Erik Prince and significantly expand the company beyond autonomous drone software by adding a portfolio of combat-proven ground vehicles already being used in Ukraine for logistics, casualty evacuation, reconnaissance, demining and drone-launch missions.

The consideration will consist of a mix of cash and stock, with closing subject to customary legal, regulatory and shareholder approvals. More than 300 Ratel employees are expected to join Swarmer following the transaction, bringing the combined company to nearly 500 employees. Ratel founder and CEO Taras Ostapchuk is expected to remain in his role and report to Swarmer President and U.S. CEO Alex Fink.

From Drone Software to a Broader Autonomous Platform

Swarmer has built its business around vendor-agnostic autonomy software designed to allow a single operator to control large numbers of unmanned systems in real time. Its technology focuses on swarm coordination, distributed decision-making and integration across multiple unmanned platforms rather than manufacturing individual drones itself.

The company says its systems have supported more than 100,000 real-world combat missions in Ukraine since first being deployed there in April 2024. That operating history has given Swarmer access to large amounts of battlefield telemetry, sensor data and operational feedback that can be used to improve autonomous performance and resilience.

Ratel adds the hardware side of that equation. Its unmanned ground vehicles are designed for missions that place soldiers at particularly high risk, including supply delivery, casualty evacuation, engineering operations, mine clearance and strike support. The company is also expanding into unmanned aerial systems, mobile workshops and solar-powered trailers.

For Swarmer, the strategic logic is to combine its autonomy software with a broader base of battlefield-tested platforms rather than remaining solely at the software layer.

Ratel Brings Scale and Existing Defense Contracts

Ratel is not an early-stage prototype developer. The company has already secured approximately $86 million in contracts this year and is in discussions with multiple NATO countries through the “Build With Ukraine” initiative.

According to Swarmer, Ratel products represented approximately 37% of the 11 billion Ukrainian hryvnia, or roughly $247 million, spent by Ukraine’s Ministry of Defense Procurement Agency on unmanned ground vehicle contracts between January 1 and April 18, 2026.

That installed base is particularly important in a defense market increasingly emphasizing systems that have already been tested in active combat environments. Ratel’s serial Ratel H and Ratel M vehicles carry NATO stock numbers and AQAP 2110 certification, giving the company a foundation for expansion beyond Ukraine.

Ground Robots Are Becoming a Bigger Part of Modern Warfare

The acquisition also reflects a broader shift in defense technology. Ukraine has become one of the world’s most active proving grounds for unmanned systems, with aerial drones receiving much of the attention early in the war. Ground robotics, however, are increasingly being used for missions where sending personnel creates unnecessary risk, including logistics, reconnaissance, casualty evacuation and perimeter support.

That trend fits directly with Swarmer’s view of Ratel’s vehicles as more than standalone ground robots. Management believes UGVs can serve as mobile launch platforms for drones, interceptors and other autonomous assets, creating integrated systems that operate across both ground and air domains.

Consolidation Comes to Ukraine’s Defense-Tech Industry

The transaction may also be significant as an early example of consolidation within Ukraine’s highly fragmented defense-technology sector. The country has developed hundreds of drone and robotics companies during the war, many of which have built products quickly around immediate battlefield requirements. That decentralized ecosystem helped accelerate innovation, but it has also produced a large number of relatively small manufacturers that can face difficulty scaling production, accessing Western capital and selling into larger NATO procurement programs.

Swarmer itself appears to be positioning the transaction as the beginning of a broader platform strategy. Prince has said the company intends to assemble battlefield-tested systems into a more integrated defense-technology offering, suggesting additional acquisitions could eventually follow.

Building an Integrated Autonomous Defense Company

For investors, the acquisition changes the profile of Swarmer in an important way. Until now, the company’s core value proposition has centered on the software layer — providing autonomy, coordination and decision-making capabilities that can work across different unmanned platforms. Ratel would add manufacturing, physical systems, existing government contracts and a sizable workforce operating directly inside Ukraine’s defense ecosystem.

That combination could allow Swarmer to pursue larger integrated programs while continuing to deploy its autonomy technology across third-party systems. Ratel extends that strategy onto the ground.

If the transaction closes and the two companies successfully integrate their technologies, Swarmer would emerge with a much broader portfolio spanning autonomous software, aerial systems and unmanned ground vehicles — all built around technologies that have already been exposed to real-world combat conditions.

For a defense industry increasingly focused on autonomy, interoperability and reducing the number of personnel placed in high-risk environments, that could make the Ratel acquisition more than simply an expansion of Swarmer’s product catalog. It could be an early step toward building a larger, multi-domain autonomous defense platform.

Investors following the broader defense technology sector can also explore Noble Capital Markets coverage of T3 Defense (NASDAQ: DFNS), a defense-focused holding company pursuing growth through acquisitions, and Kratos Defense & Security Solutions (NASDAQ: KTOS), whose portfolio includes unmanned systems and other national security technologies.

T3 Defense (DFNS) – Reports 2Q26 Results


Monday, August 24, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. T3 Defense filed its 10Q for the quarter ended June 30, 2026. The Company did not issue a press release on the quarterly results, nor did management hold a conference call. Revenue came in below our expectations, but gross margin and operating loss were better than expected. Non-cash items significantly impacted the bottom line. We hope to speak with management shortly to provide a deeper review of the quarter and update our models.

2Q26 Results. Revenue was $4.0 million, below our $4.5 million projection. Gross margin was 25.4% exceeding our 11.1% estimate. T3 reported an operating loss of $3.4 million compared to our projection of a $3.9 million loss. Net loss from continuing operations was $85.7 million and net loss was $81.4 million. T3 reported a loss per share of $182.80 (adjusted for the recent 1-for-125 reverse stock split).


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Kratos Defense & Security (KTOS) – That Didn’t Take Long


Friday, August 07, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

From Opportunity to Reality. Less than 48 hours after speaking of these potential opportunities (among a bunch of other opportunities), Kratos has been awarded a U.S. Army contract related to the Javelin Missile System, and Kratos partner Boeing announced it has been awarded a funding contract to begin supplying long-range JDAMs that incorporate Kratos turbojet engines.

JDAM. The Air Force awarded Boeing a $75 million production contract to begin supplying long-range JDAMs. The long-range variant adds a Kratos TDI-J85 turbojet providing 200 pounds of thrust to enable jets to attack from a much safer distance. The 2027 National Defense Authorization Act includes about $277 million for 1,150 upgraded JDAM guidance tail kits with M-Code GPS for the legacy munitions. Industry experts note the new version will cost far less than more exquisite stand-off munitions, so they should be considered as an affordable mass capability, playing right into Kratos’ key strengths, in our opinion.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Kratos Defense & Security (KTOS) – Strong 2Q26 Top Line Growth; Momentum Continues to Build


Wednesday, August 05, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. Kratos’ second quarter results reflect strong execution by the Company, in our view. The Company’s strategy, including making internally funded investments to be first-to-market with relevant hardware and software that is engineered up front for affordable mass production at scale and is aligned with the Department of War’s priorities, continues to resonate, in our view.

2Q26 Results. Revenues for the second quarter were $458.8 million, above management’s guide of $400 million-$410 million. We were at $405 million. Adjusted EBITDA for the second quarter was $38.2 million, above the high end of the estimated range of $30 million-$35 million, reflecting the increased revenue and revenue mix. We had forecast $33 million. GAAP net income for 2Q26 was $4.4 million, and GAAP EPS was $0.02, compared to $2.9 million and  $0.02, respectively, for 2Q25. Adjusted EPS was $0.21 for 2Q26, compared to $0.11 for 2Q25.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

V2X (VVX) – Solid Second Quarter Results


Tuesday, August 04, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. V2X’s reported strong second quarter performance reflecting consistent strategic execution, robust demand for the Company’s differentiated capabilities, and continued alignment to national security priorities. The Company’s recent awards across modernization, global training, aerospace, and mission readiness reinforce the value of V2X’s end-to-end solutions, ability to support global no-fail missions, and pursuit of profitable growth opportunities, in our view.

2Q26 Results. V2X reported revenue of $1.26 billion, up $178.3 million year-over-year, representing a 16.5% increase. We were at $1.2 billion. Adjusted EBITDA was $89.8 million, with a margin of 7.1%, representing an increase of 9% from the prior year. We had forecast $87 million and a 7.3% margin. Adjusted EPS came in at $1.64, up from $1.33 last year. We were at $1.44.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Kratos Defense & Security (KTOS) – More New Business


Wednesday, July 22, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

New Business. Kratos continues to receive new business, confirming the large growth opportunities available, in our view. The new business highlights the Company’s operating philosophy of having the right products, in the right space, at the right time. The recent awards add to the pile of new business Kratos has been awarded so far in 2026.

C-UAS Award. Kratos was awarded a sole-source, single-award Indefinite Delivery/Indefinite Quantity (IDIQ) contract for approximately $156 million by the U.S. Department of Energy’s National Nuclear Security Administration (NNSA) Office of Secure Transportation (OST) in support of Project Solar Shield. Under this new contract award, Kratos will provide mobile Counter-Unmanned Aircraft System (C-UAS) platforms designed to support OST’s critical National Security mission. The OST is responsible for the safe and secure ground and air transportation of nuclear weapons, weapon components, and special nuclear materials. Kratos was selected following a rigorous technical evaluation.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

T3 Defense (DFNS) – Stock Split Complete


Tuesday, July 21, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Reverse Stock Split. As outlined in prior reports, T3 underwent a 1-for-125 reverse stock split to regain compliance with Nasdaq regulations. As a result, the number of outstanding shares declined from approximately 139.8 million to approximately 1.1 million. We adjusted our model to reflect the impact on earnings per share.

Impact. Assuming the stock split only impacts the forward quarters, the 2Q adjusted net loss increases to $2.87/sh, 3Q to a loss of $2.16/sh, and 4Q to a net loss of $1.75/sh, up from a previous projected net loss of $0.06/sh, $0.03/sh, and $0.02 per share, respectively, Full year net loss increases to $3.90/sh, up from a prior full year net loss forecast of $0.50/sh. If we adjusted 1Q26 EPS loss to the 1.1 million outstanding shares, full-year net loss rises to $30.26/sh, which includes a number of one-time non-cash charges. The share change does not impact our estimates for adjusted EBITDA, which remains at a loss of $6 million for 2026.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Lockheed Martin Unveiled a Patriot Missile That Costs Half as Much. The Real Story Is What It Means for the Defense Supply Chain

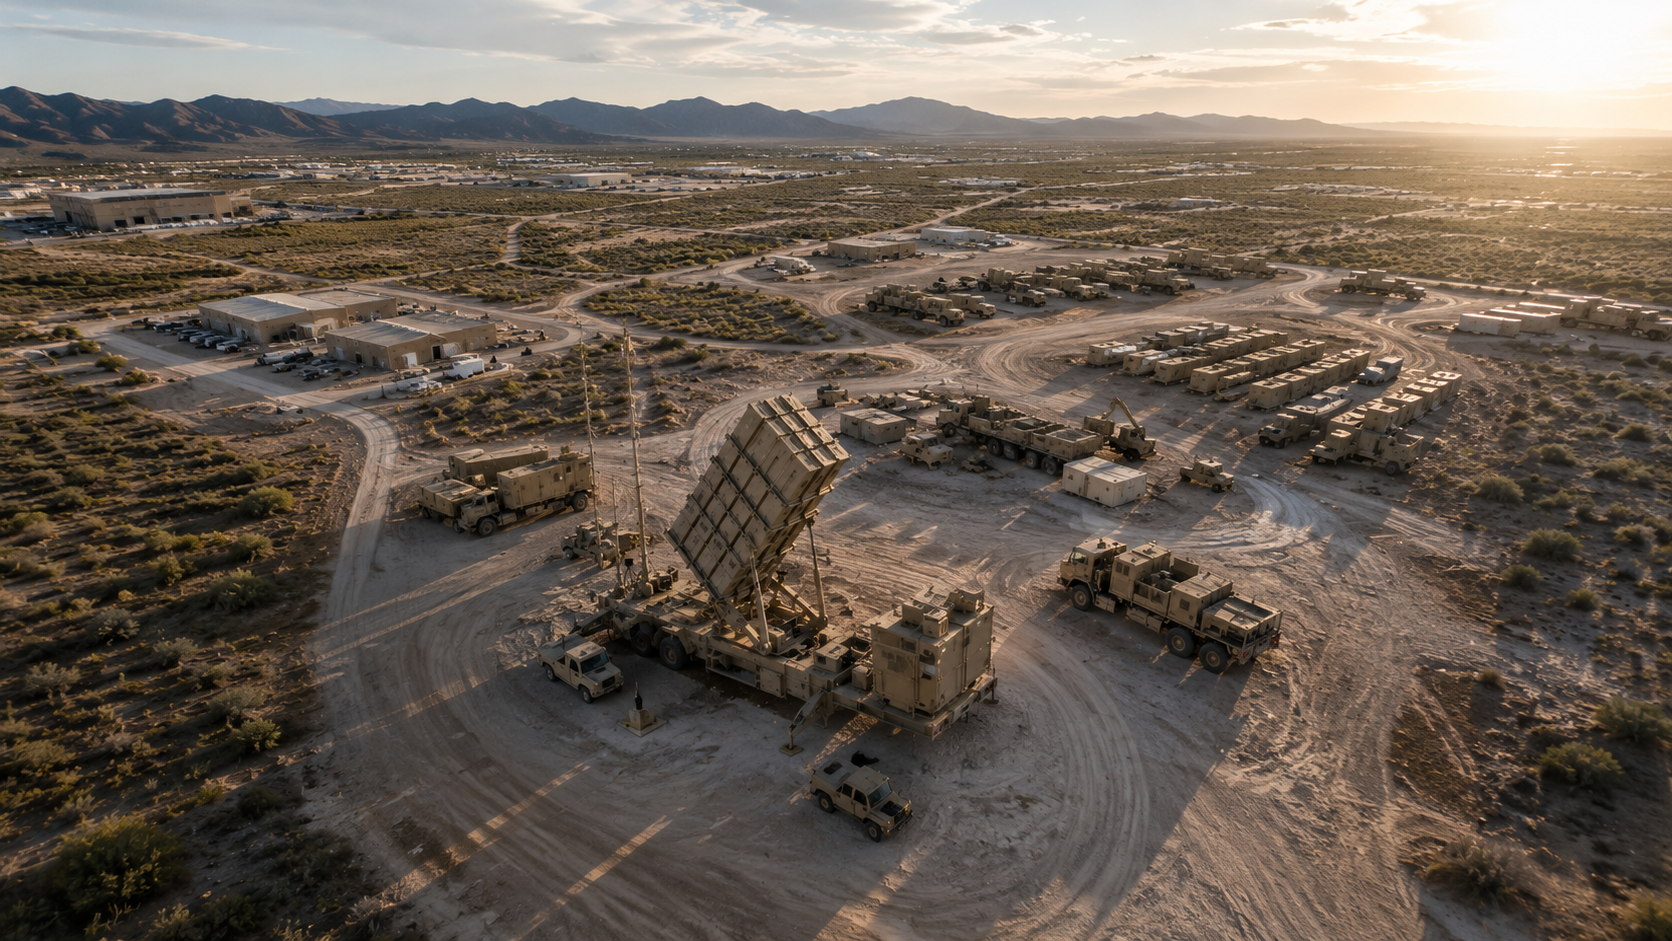
Lockheed Martin introduced a new, lower-cost version of its Patriot interceptor at the Farnborough Airshow on Monday, a move that reflects how fundamentally the economics of air defense have changed under the pressure of real-world conflict. The PAC-3 Adapted Capability Effector, or PAC-3 ACE, is projected to cost less than half the price of the current PAC-3 MSE interceptor, which runs approximately $4 million per missile according to US Army budget documents. Initial production is expected to begin within 36 months, developed and manufactured jointly with US and European industry partners.

The announcement is not just a product launch. It is a direct response to a cost asymmetry problem that the Iran conflict has made impossible to ignore.

The Math That Forced the Decision

Throughout Operation Epic Fury, US forces in the Middle East have burned through finite interceptor stockpiles to counter Iranian drones that cost a fraction of the missiles used to destroy them. A single PAC-3 MSE interceptor costs roughly $4 million. An Iranian Shahed drone costs approximately $35,000. When you are spending more than 100 times the cost of the threat to defeat it, the economics of attrition work against you regardless of how effective the technology is.

That disparity has pushed the Pentagon and its prime contractors to rethink the entire approach to air defense procurement. The Missile Defense Agency launched a Low-Cost Interceptor program in late 2025 with a target price of $750,000 per unit. Lockheed’s PAC-3 ACE, at under $2 million, sits in the middle of the cost spectrum between that target and the current MSE, offering a bridge solution that can enter production faster because it is built on existing PAC-3 guidance technology and is compatible with legacy Patriot systems and the Integrated Battle Command System.

The European Manufacturing Push

Lockheed is not building this missile alone. The company has signaled its intention to develop PAC-3 ACE jointly with European defense partners and has expressed interest in eventually producing an entirely European-sourced variant manufactured on the continent. This follows a July 7 memorandum of understanding with German arms manufacturer Rheinmetall to establish the first European production center for the Army Tactical Missile System.

The pattern is clear: Lockheed is investing in distributed manufacturing capacity across allied nations rather than concentrating production domestically. That approach strengthens the broader defense industrial base, reduces supply chain bottlenecks, and gives NATO members the ability to produce and stockpile interoperable interceptors locally rather than depending entirely on American production during a crisis.

Where Small Cap Defense and Industrial Companies Fit

For investors tracking the defense and industrial sectors below the $2 billion market cap threshold, the shift toward distributed, cost-optimized defense manufacturing creates a meaningful opportunity set. When a prime contractor like Lockheed commits to building cheaper weapons with a broader supplier base across multiple countries, it pulls smaller specialized manufacturers, component suppliers, and defense services companies into the production chain.

Defense services contractors like V2X, which provides mission-critical support across military operations and logistics, and specialized defense technology companies like T3 Defense sit in the exact part of the ecosystem that benefits when defense procurement scales horizontally rather than concentrating vertically through a single prime. Precision component manufacturers like NN Inc., which produces highly engineered parts for defense and industrial applications, are also positioned in the supply chain that affordable, high-volume interceptor production would activate.

The defense industry spent decades optimizing for performance at any cost. The Iran conflict exposed that model’s limitations in real time. What comes next is a manufacturing and procurement shift toward affordability, volume, and distributed production, and the smaller companies with the right capabilities are the ones best positioned to fill the gaps the primes cannot fill alone.