LAS VEGAS–(BUSINESS WIRE)–Sep. 23, 2026– Xerox Holdings Corporation (NASDAQ: XRX) today announced a major production print portfolio expansion as part of PRINTING United Expo 2026, introducing three new press platforms and enhancements to existing presses.
With these introductions, Xerox is deepening its commitment to production print with an inkjet portfolio spanning cut-sheet and continuous-feed, alongside a new 6-color flagship press for graphic arts. Integrated with the Xerox end-to-end production ecosystem of presses, workflow automation software, media expertise and lifecycle services, the new offerings extend specialty color and intelligent automation capabilities across the broader portfolio, helping print providers bring more work in-house, streamline production and pursue new revenue opportunities.
“PRINTING United is the ideal stage to show how Xerox is driving the future of production print,” said Terry Antinora, President, Global Production Print Services at Xerox. “We’re giving print providers a complete inkjet portfolio, embellishment, intelligent automation, and AI-powered tools that help them grow, differentiate, and win. Everything we’re launching is designed to improve customer profitability — not just increase print volume.”
Attendees can explore the following additions to the Xerox production print portfolio:
Xerox® Proficio™ Jet CS1100: A B3 cut-sheet inkjet press that delivers speeds of up to 300 images per minute. New Xerox-developed printheads and a high-definition ink formulation deliver 1200 × 1200 dots per inch resolution with 2-bit variable-drop imaging for precise dot placement. A scalable drying architecture supports media up to 350 grams per square meter, including coated stocks. The platform enables print providers to shift a wider range of work, from transactional and direct mail to graphic communications and commercial print, onto a single press without compromising quality.
Xerox® Proficio™ Jet CF1200: An industrial continuous-feed inkjet press that delivers speeds of up to 525 feet per minute at 1200 dpi within a compact 28-foot footprint. The smallest 20-inch press in its class handles between 4 million and 30 million Letter / A4 impressions per month, helping high-volume print providers increase capacity, operate more efficiently and protect margins.
Xerox® Proficio™ PX700 FLX: A new graphic arts production press that delivers speeds of up to 120 pages per minute and supports up to six colors inline at rated speed. New Fluorescent Green specialty toner further expands the color gamut and improves RGB accuracy when paired with Fluorescent Pink. Intelligent automation helps reduce operator intervention and improve consistency, enabling print providers to create differentiated, high-value applications.
Xerox® Proficio™ PX300 and PX500 feature updates: Enhanced with new Beyond CMYK and fifth-color options, including Gold, Silver and White, the Proficio PX300 and Proficio PX500 expand opportunities for metallic effects and printing on dark and transparent media. The Proficio PX300 now also features the Xerox® PredictPrint Media Manager, which uses AI-assisted cloud intelligence to simplify media setup and optimize color stability.
At PRINTING United, Xerox will host demonstrations and discussions on generative AI for specialty print, workflow analytics and automation through Xerox® FreeFlow® Core and Xerox® FreeFlow® Vision Connect Software, and generative AI, along with business development resources available through the Genesis Initiative. The Xerox Genesis Initiative helps creative teams maximize the value of Beyond CMYK technologies through specialty inks and embellishments, and application development resources.
To learn more, visit Xerox at PRINTING United booth #N6729 or explore the company’s production print portfolio at Xerox.com.
About Xerox Holdings Corporation (NASDAQ: XRX)
Xerox is a global technology company with more than 120 years of innovation leadership. We design, manufacture, deliver, and support print, IT, and digital services for nearly 200,000 clients worldwide. Our integrated, AI-powered portfolio includes managed and production print, document management, workflow automation, cybersecurity, cloud managed services, IT infrastructure and collaboration technology. Serving clients from growing SMBs to 90 percent of the Fortune 500, Xerox supports leading healthcare, government, financial services, education, legal, retail and commercial organizations. Through direct sales and a global network of channel partners, we deliver the technology, expertise, and support organizations need to operate efficiently, securely and at scale.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
High-visibility NFL Agreement. Codere recently announced a multi-year agreement with the NFL, establishing it as the league’s Official Betting Partner in Mexico. In our view, the high-visibility partnership strengthens its presence in a key market, increases brand awareness, deepens customer engagement opportunities, and enhances brand credibility.
Details. The agreement is set to run for three years and includes annual sponsorship of one NFL game in Mexico City and Super Bowl sponsorship rights in Mexico. The agreement kicks off with the November 22, 2026, 49ers–Vikings matchup and Super Bowl LXI in Los Angeles in February 2027. The partnership also creates fan engagement opportunities through hospitality programs, VIP experiences, promotional events across multiple Mexican cities, and official NFL merchandise.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Veteran BPO executives Mark Lyndsell and Troy Sanders join TOG as the company expands its global delivery capabilities and advances its Experience Process Outsourcing strategy
ST. PETERSBURG, Fla., Sept. 17, 2026 (GLOBE NEWSWIRE) — The Office Gurus (TOG), a business segment of Superior Group of Companies, Inc. (NASDAQ: SGC), announced the appointments of Mark Lyndsell as Executive Vice President of Global Operations and Troy Sanders as Vice President of Business Development. Together, they bring more than six decades of BPO, contact center, operations and sales leadership experience to TOG.
“TOG has reached an important point in our evolution,” said Dominic Leide, President of The Office Gurus. “Mark and Troy bring the experience and leadership to help us significantly scale the successful, technology-driven platform we’ve built.”
Lyndsell brings more than 30 years of global operations experience, most recently as Senior Vice President, Delivery, Americas at TTEC, leading a multi-country delivery organization generating approximately $850 million in annual revenue. As EVP of Global Operations, he will lead TOG’s global operations, focusing on operational excellence and advancing the company’s Experience Process Outsourcing (EPO) delivery model.
Sanders brings more than 30 years of BPO and contact center sales leadership experience, including new business development for organizations such as iQor and Startek. As VP of Business Development, he will focus on expanding TOG’s new-client pipeline and brings the relationship-based sales mentality that TOG values.
The appointments support TOG’s continued advancement of its EPO strategy and its investment in GuruSuite iX, its AI-enabled technology ecosystem supporting agent performance, quality assurance, training and customer interaction automation. “Our objective isn’t simply to become bigger – it’s to become a better, more capable partner for our clients,” Leide said.
Disclosure Regarding Forward-Looking Statements
Certain matters discussed in this press release are “forward-looking statements” intended to qualify for the safe harbors from liability established by the Private Securities Litigation Reform Act of 1995. These forward-looking statements can generally be identified by use of the words “may,” “will,” “should,” “could,” “expect,””anticipate,” “estimate,” “believe,” “intend,” “project,” “potential,” or “plan” or the negative of these words or other variations on these words or comparable terminology. Forward-looking statements in this press release include statements regarding the Company’s capital allocation strategy and growth. Such forward-looking statements are subject to certain risks and uncertainties that may materially adversely affect the anticipated results. Such risks and uncertainties include, but are not limited to, the factors described in the Company’s filings with the Securities and Exchange Commission (“SEC”), including those risks described in Item 1A of our Annual Report on Form 10-K for the fiscal year ended December 31, 2025 entitled “Risk Factors” and the Quarterly Report on Form 10-Q for the quarter ended June 30, 2026. Shareholders, potential investors and other readers are urged to consider these factors carefully in evaluating the forward-looking statements made herein and are cautioned not to place undue reliance on such forward-looking statements. The forward-looking statements made herein are only made as of the date of this press release and we disclaim any obligation to publicly update such forward-looking statements to reflect subsequent events or circumstances, except as may be required by law.
About The Office Gurus
The Office Gurus is a global provider of customer experience and business process outsourcing solutions, combining engaged people, operational expertise and AI-enabled technology to help organizations improve customer experience and business performance.
About Superior Group of Companies, Inc. (SGC)
Established in 1920, Superior Group of Companies is comprised of three attractive business segments each serving large, fragmented and growing addressable markets. Across Healthcare Apparel, Branded Products and Contact Centers, each segment enables businesses to create extraordinary brand engagement experiences for their customers and employees. SGC’s commitment to service, quality, advanced technology, and omnichannel commerce provides unparalleled competitive advantages. We are committed to enhancing shareholder value by continuing to pursue a combination of organic growth and strategic acquisitions. For more information, visit www.superiorgroupofcompanies.com.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
A strong finish to fiscal 2026. Fiscal Q4 revenue was $268.1 million, up 18% from the prior-year period, capping a solid year in which revenue increased 8% to $1.15 billion. Full-year adjusted EBITDA increased 14% to $41.5 million, while gross margin expanded 80 basis points to 13.3%, reflecting favorable product mix and improved operating performance.
Growth is broadening across the portfolio. Physical entertainment remained healthy, with fiscal 2026 vinyl revenue increasing 13%, CDs up 25%, and physical movies up 22%, supported by strong consumer demand and expanded studio relationships with Paramount and Amazon MGM. Higher-value businesses are also gaining traction, with collectibles revenue up 45% and distribution and fulfillment fees up 26%.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Strong Q2 Results. The company reported Q2 revenue of $81.8 million and adj. EBITDA of $18.0 million, both of which were above our estimates of $80.8 million and $6.8 million, respectively. Solid Q2 results were driven by double-digit revenue growth across DTC and wholesale channels, improved operating leverage, and a $10.4 million tariff refund benefit. Notably, when excluding the refund, adj. EBITDA was approximately $7.6 million, still above our estimate.
DTC and Wholesale Gain Momentum. Direct-to-Consumer (DTC) revenue increased 13.7% to $32.4 million, while wholesale revenue grew 10.4% to $49.4 million. DTC benefited from strength across stores and e-commerce, while an expanding full-price customer base and favorable demand for women’s and men’s collections supported both channels.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q4 results reflect continued top-line pressure. Fiscal Q4 revenue declined 12.9% to $293.1 million, with Consumer Floral & Gifts down 13.4% and Gourmet Foods & Gift Baskets down 15.4%, partially offset by 1.9% growth at BloomNet. Adjusted EBITDA was a loss of $31.0 million compared with a loss of $24.2 million in the prior-year period, as revenue deleverage and cost pressures more than offset operating efficiencies.
Underlying trends provide signs of progress. Importantly, Consumer Floral & Gifts gross margin rose 220 basis points to 40.7%, while contribution margin remained relatively stable. Management also indicated that the flowers category is now generating positive sales on many days and weeks, providing early evidence that changes to merchandising, fulfillment, and the digital customer experience may be improving the underlying revenue trajectory.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Copart (NASDAQ: CPRT) is making the largest acquisition in its history, agreeing to buy ACV Auctions (NYSE: ACVA) for approximately $1.9 billion in cash in a deal that would significantly broaden Copart’s reach across the vehicle remarketing market.
Under the agreement announced Thursday, Copart will pay $10.50 per share for ACV, representing a premium of approximately 45% to ACV’s unaffected closing price on August 10, the last trading day before reports of a potential transaction surfaced, and a 41% premium to its 30-day volume-weighted average price through September 9. The deal is expected to close by the end of 2026, subject to customary conditions.
Investors responded quickly. ACV shares surged roughly 44% in premarket trading Friday, moving close to the $10.50 offer price, while Copart shares were also higher before the open.
Expanding Beyond Salvage Auctions
Copart is best known for online auctions of salvage and damaged vehicles, with a global buyer network spanning approximately 1 million members in more than 185 countries. The company operates more than 250 locations across 11 countries and sold more than 4 million vehicles over the past year.
ACV gives Copart a much stronger position in a different part of the market: dealer-to-dealer wholesale vehicle sales.
ACV operates a digital marketplace that allows dealers and commercial sellers to buy and sell used vehicles online, supported by inspection technology, vehicle condition data and AI-powered valuation tools. That business complements Copart’s strength in salvage disposition and international resale, allowing the combined company to participate across more of the vehicle lifecycle.
Management describes the combination as creating a full-spectrum digital remarketing platform spanning dealer trade-ins, wholesale remarketing, salvage disposition and international resale.
What Vehicle Remarketing Actually Means
Vehicle remarketing is the process of reselling used vehicles after they leave their original owner, lease, rental fleet, insurance claim or dealership inventory.
It is a large but fragmented ecosystem. Insurance companies sell damaged or totaled vehicles. Dealers wholesale cars they do not want to keep in inventory. Rental companies and fleet operators periodically dispose of large numbers of vehicles. Financial institutions remarket repossessed or off-lease vehicles.
Historically, many of those transactions ran through physical auctions. Increasingly, they are moving online.
Copart helped pioneer that transition in salvage vehicles, while ACV built a digital-first marketplace aimed primarily at dealers. Bringing the two together gives Copart access to a much broader pool of vehicles before they ever reach the salvage portion of the market.
That is the strategic logic behind the transaction: rather than serving only one segment of the resale process, Copart wants to participate in more of the market from the time a vehicle leaves a dealership or fleet through its eventual wholesale, salvage or export sale.
ACV Adds Data and Technology
The acquisition is not only about auction volume.
ACV has invested heavily in inspection technology and data services designed to give buyers more confidence when purchasing vehicles remotely. Its tools include digital condition reports, valuation systems and AI-driven inventory analytics for dealers.
Copart said combining those capabilities with its own technology and extensive vehicle dataset could create one of the industry’s largest pools of vehicle condition information. Management believes that data can support improved pricing, inspection and resale decisions across the combined platform.
The companies also see potential to cross-sell buyers and sellers between their marketplaces, expand transportation services and grow commercial vehicle activity.
Scale Matters in Online Auto Auctions
The economics of vehicle marketplaces tend to improve with scale.
More sellers attract more buyers, while more buyers can improve auction liquidity and pricing for sellers. A larger transaction base also generates more vehicle data, which can improve valuation models and inspection tools.
Copart already brings substantial physical infrastructure to that equation. Its more than 250 locations provide storage, logistics and processing capabilities that ACV, as a more digitally focused business, does not have at the same scale. ACV contributes a national dealer and inspector network along with its dealer-facing technology.
That combination gives the merged business both digital reach and physical infrastructure — an increasingly important distinction as the auto-auction industry moves further online.
A New Growth Avenue for Copart
The deal also comes as Copart looks for additional growth beyond its core salvage business.
Recent industry commentary has pointed to slower vehicle-volume growth in some parts of the salvage market, creating an incentive for established operators to broaden their exposure to traditional wholesale vehicles and technology-enabled services.
ACV provides that expansion immediately.
Copart said the transaction should accelerate revenue growth and expects it to be roughly neutral to earnings per share in the first full year of ownership before becoming accretive beginning in fiscal 2028. The company plans to fund the acquisition entirely with cash on hand, and the transaction is not subject to a financing condition.
ACV will continue operating as an independent subsidiary of Copart under its existing leadership after the acquisition closes.
Market Reaction Reflects the Deal Premium
The sharp move in ACV shares is largely a straightforward response to the acquisition price.
The stock jumped more than 40% after the announcement and traded near the $10.50 cash offer Friday morning, effectively closing much of the gap between its prior market price and the agreed transaction value.
Interestingly, investors also reacted positively to Copart. Its shares rose about 6% in premarket trading despite the company reporting quarterly results that were somewhat softer than expected, suggesting the market sees meaningful strategic value in the acquisition.
That is notable because large acquisitions often pressure the buyer’s stock initially as investors weigh integration costs, execution risks and the price being paid.
In this case, the early reaction suggests investors are focused on the opportunity for Copart to expand into a larger portion of the vehicle remarketing market.
Building an End-to-End Vehicle Marketplace
For Copart, ACV represents more than simply adding another auction platform.
The acquisition gives the company an immediate foothold in dealer-to-dealer wholesale vehicles, adds a suite of data and valuation technologies and expands the number of transactions that can flow through its global buyer network and physical infrastructure.
It also moves Copart closer to becoming an end-to-end vehicle remarketing platform capable of serving vehicles across a much broader range of conditions and ownership situations.
For investors, the question now becomes whether Copart can successfully connect ACV’s dealer marketplace with its own enormous global auction network and infrastructure.
If it can, the company’s largest-ever acquisition could open a meaningful new growth channel well beyond the salvage auctions that built the business.
Net Sales Increased 11.7% to $81.8 Million vs. 2Q25 Raises Full Year Fiscal 2026 Guidance
NEW YORK–(BUSINESS WIRE)– Vince Holding Corp. (Nasdaq: VNCE) (“VNCE” or the “Company”), a global retail platform, today reported its financial results for the second quarter ended August 1, 2026.
Brendan Hoffman, Chief Executive Officer of VNCE said, “We delivered strong results this quarter, with excellent growth across both our direct-to-consumer and wholesale channels, and this momentum gives us confidence to raise our full-year guidance. Importantly, the recent completion of the OVO acquisition marks a pivotal moment for our Company. We are entering the streetwear market through a brand with deep cultural roots and an authentic customer connection, and we’re bringing to it the operating discipline and infrastructure that have driven Vince’s turnaround. The acquisition provides a significant growth runway and we see meaningful opportunities to expand OVO’s retail presence and launch wholesale distribution through longstanding relationships, positioning the combined platform for substantial long-term value creation.”
In this press release, the Company is presenting its financial results in conformity with U.S. generally accepted accounting principles (“GAAP”) as well as on an “adjusted” basis. Adjusted results presented in this press release are non-GAAP financial measures. See “Non-GAAP Financial Measures” below for more information about the Company’s use of non-GAAP financial measures.
For the second quarter ended August 1, 2026:
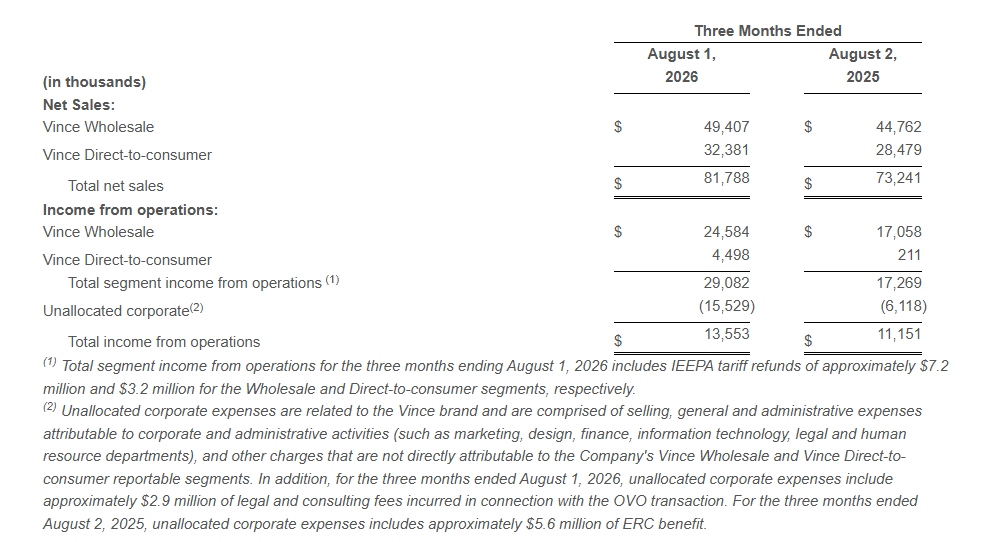
Total Company net sales increased 11.7% to $81.8 million compared to $73.2 million in the second quarter of fiscal 2025. The year-over-year increase was driven by a 13.7% increase in the direct-to-consumer segment and a 10.4% increase in the wholesale segment.
Gross profit was $49.8 million, or 60.9% of net sales, compared to gross profit of $36.9 million, or 50.4% of net sales, in the second quarter of fiscal 2025. The increase in gross margin for the second quarter of fiscal 2026 includes a favorable impact of $10.4 million related to the IEEPA tariff refund, which offset the unfavorable impact from higher product costing which contributed negatively by approximately 160 basis points, and the unfavorable impact from higher freight costs of approximately 130 basis points. The gross margin rate, excluding the benefit of the tariff refund, was 48.2% in line with the Company’s expectations.
Selling, general, and administrative expenses were $36.3 million, or 44.3% of sales, compared to $25.8 million, or 35.2% of sales, in the second quarter of fiscal 2025. The increase in SG&A dollars was primarily driven by anniversarying last year’s $5.6 million benefit from the receipt of payroll tax credit payments from the U.S. Department of the Treasury under the Employee Retention Credit program (the “ERC benefit”) as well as $2.9 million related to transaction costs associated with the acquisition of October’s Very Own (“OVO”) operating business (“OVO transaction”).
Income from operations was $13.6 million compared to income from operations of $11.2 million in the same period last year. Adjusted income from operations, which includes the benefit from tariff refunds in the second quarter of fiscal 2026, was $16.4 million compared to $5.5 million in the same period last year.
Income tax expense was $3.1 million compared to an income tax expense of $0.1 million in the same period last year. The expense is due to the impact of applying the Company’s estimated annual effective tax rate to the year-to-date ordinary pre-tax income.
Net income was $10.6 million or $0.80 per diluted share compared to net income of $12.1 million or $0.93 per diluted share in the same period last year. Adjusted net income, which includes the benefit from tariff refunds in the second quarter of fiscal 2026, was $13.5 million or $1.02 per diluted share compared to $4.9 million or $0.38 in the same period last year.
Adjusted EBITDA*, which includes the benefit from tariff refunds in the second quarter of fiscal 2026, was $18.0 million compared to $6.7 million in the same period last year.
The Company ended the quarter with 53 company-operated Vince stores.
Second Quarter Review
Net sales increased 11.7% to $81.8 million as compared to the second quarter of fiscal 2025.
Wholesale segment sales increased 10.4% to $49.4 million compared to the second quarter of fiscal 2025.
Direct-to-consumer segment sales increased 13.7% to $32.4 million compared to the second quarter of fiscal 2025.
Income from operations excluding unallocated corporate expenses was $29.1 million compared to income from operations of $17.3 million in the same period last year.
Net Sales and Operating Results by Segment:
Balance Sheet
At the end of the second quarter of fiscal 2026, total borrowings under the Company’s debt agreements totaled $12.3 million and the Company had $63.6 million of excess availability under its revolving credit facility.
Net inventory at the end of the second quarter of fiscal 2026 was $73.4 million compared to $76.7 million at the end of the second quarter of fiscal 2025. The year-over-year decrease in inventory includes approximately $2.6 million of IEEPA refunds.
During the quarter ended August 1, 2026, the Company did not make any offerings or sales of shares of common stock under the Virtu At-the-Market Offering. At August 1, 2026, $0.9 million was available under the Virtu At-the-Market Offering.
October’s Very Own (“OVO”) Acquisition
As previously announced on August 27, 2026, the Company completed the acquisition of the operating business of OVO, a globally recognized lifestyle brand which delivered nearly $50 million in sales in calendar year 2025. VNCE now owns and will operate OVO’s business as OVO’s core apparel and retail licensee, strengthening its partnership with Authentic Brands Group (“Authentic”) and expanding its multi-brand platform strategy beyond Vince, with opportunity to build on OVO’s existing operations using its scale and infrastructure to support the brand’s next phase of growth. The Company sees opportunity to grow OVO sales to over $100 million and deliver Adjusted EBITDA margins in the low double digit percentage range by fiscal 2030. VNCE acquired the OVO operating business for a nominal cash purchase and also acquired a minority stake in OVO’s intellectual property through the cash purchase of a 5% equity interest in the IP holding entity newly formed by majority-owner, Authentic, for $6 million.
Outlook
The Company is providing its outlook for the Vince Business for the third quarter of fiscal 2026 and raising its outlook for the Vince Business for the full year fiscal 2026. The Company’s outlook now considers the benefit of tariff refunds resulting from the Supreme Court’s decision on the IEEPA tariffs. The following outlook does not include the OVO Business.
For the third quarter of fiscal 2026 the Company expects the following for the Vince Business:
Net sales to increase approximately 5% to 8% compared to the prior year period.
Adjusted operating income as a percentage of net sales to be approximately 7.5% to 8.5%.
Adjusted EBITDA as a percentage of net sales to be approximately 8.5% to 9.5%.
For fiscal 2026 the Company expects the following for the Vince Business:
Net sales to increase approximately 8% to 10% compared to the prior year.
Adjusted operating income as a percentage of net sales to be approximately 7.5% to 8.0%.
Adjusted EBITDA as a percentage of net sales to be approximately 9.0% to 9.5%.
*Non-GAAP Financial Measures
In addition to reporting financial results in accordance with GAAP, the Company has provided, with respect to the financial results relating to the three and six months ended August 1, 2026 and August 2, 2025, adjusted EBITDA, which is a non-GAAP measure. Adjusted EBITDA is calculated as earnings before interest, taxes, depreciation and amortization, share-based compensation, capitalized cloud computing amortization, OVO transaction costs, and ERC Benefit. For the three and six months ended August 1, 2026 and August 2, 2025 respectively, the Company has provided adjusted income from operations, adjusted income (loss) before income taxes and equity in net income of equity method investment, adjusted income (loss) before equity in net income of equity method investment, adjusted net income, and adjusted earnings per share, which are non-GAAP measures, in order to eliminate the effect of the OVO transaction costs, ERC benefit, and Discrete Tax Effect Associated with ERC benefit.
The Company believes that the presentation of these non-GAAP measures facilitates an understanding of the Company’s continuing operations without the impact associated with the aforementioned items. While these types of events can and do recur periodically, they are excluded from the indicated financial information due to their impact on the comparability of earnings across periods. Non-GAAP financial measures should not be considered in isolation from, or as a substitute for, financial information prepared in accordance with GAAP. A reconciliation of GAAP to non-GAAP results has been provided in Exhibit 3 and Exhibit 4 to this press release.
Conference Call
A conference call to discuss the second quarter results will be held today, September 10, 2026, at 8:30 a.m. ET, hosted by Vince Holding Corp. Chief Executive Officer, Brendan Hoffman, and Chief Financial Officer, Yuji Okumura. During the conference call, the Company may make comments concerning business and financial developments, trends and other business or financial matters. The Company’s comments, as well as other matters discussed during the conference call, may contain or constitute information that has not been previously disclosed.
Those who wish to participate in the call may do so by dialing (833) 461-5787, conference ID 879266281. Any interested party will also have the opportunity to access the call via the Internet at http://investors.vince.com/. To listen to the live call, please go to the website at least 15 minutes early to register and download any necessary audio software. For those who cannot listen to the live broadcast, a recording will be available for 12 months after the date of the event. Recordings may be accessed at http://investors.vince.com.
ABOUT VINCE HOLDING CORP.
Vince Holding Corp. is a global retail platform that operates the Vince brand women’s and men’s ready to wear business and the October’s Very Own (“OVO”) brand apparel and accessories business. Vince, established in 2002, is a leading global luxury apparel and accessories brand best known for creating elevated yet understated pieces for every day effortless style. Vince operates 41 full-price retail stores, 12 outlet stores, and its e-commerce site, vince.com, as well as through premium wholesale channels globally. OVO is a Canadian lifestyle brand originally founded in 2008 by Aubrey “Drake” Graham and a Toronto collective offering premium apparel and accessories. OVO operates 12 flagship retail stores worldwide and its e-commerce site, octobersveryown.com. Please visit investors.vince.com for more information.
Forward-Looking Statements: This document, and any statements incorporated by reference herein contain forward-looking statements under the Private Securities Litigation Reform Act of 1995. Forward-looking statements include the statements under “Outlook” above as well as statements regarding, among other things, our current expectations about possible or assumed future results of operations of the Company and are indicated by words or phrases such as “may,” “will,” “should,” “believe,” “expect,” “seek,” “anticipate,” “intend,” “estimate,” “plan,” “target,” “project,” “forecast,” “envision” and other similar phrases. Although we believe the assumptions and expectations reflected in these forward-looking statements are reasonable, these assumptions and expectations may not prove to be correct and we may not achieve the results or benefits anticipated. These forward-looking statements are not guarantees of actual results, and our actual results may differ materially from those suggested in the forward-looking statements. These forward-looking statements involve a number of risks and uncertainties, some of which are beyond our control, including, without limitation: changes to and unpredictability in the trade policies and tariffs imposed by the U.S. and the governments of other nations; general economic conditions; our ability to maintain adequate cash flow from operations or availability under our revolving credit facility to meet our liquidity needs; restrictions on our operations under our credit facilities; our ability to improve our profitability; our ability to maintain our larger wholesale partners; our ability to accurately forecast customer demand for our products; our ability to maintain the license agreement relating to the Vince brand with ABG Vince; ABG Vince’s expansion of the Vince brand into other categories and territories; ABG Vince’s approval rights and other actions; our ability to realize the benefits of our strategic initiatives; our ability to make lease payments when due; our ability to open retail stores under favorable lease terms and operate and maintain new and existing retail stores successfully; our operating experience and brand recognition in international markets; our ability to remediate the identified material weakness in our internal control over financial reporting; our ability to comply with domestic and international laws, regulations and orders; increased scrutiny regarding our approach to sustainability matters and environmental, social and governance practices; competition in the apparel and fashion industry; our ability to attract and retain key personnel; seasonal and quarterly variations in our revenue and income; the protection and enforcement of intellectual property rights relating to the Vince brand; our ability to successfully integrate, operate and grow the OVO business (the “OVO Transaction”) and realize the anticipated benefits of the OVO Transaction; the extent of our foreign sourcing; our reliance on independent manufacturers; our ability to ensure the proper operation of the distribution facilities by third-party logistics providers; fluctuations in the price, availability and quality of raw materials; the ethical business and compliance practices of our independent manufacturers; our ability to mitigate system or data security issues, such as cyber or malware attacks, as well as other major system failures; our ability to adopt, optimize and improve our information technology systems, processes and functions; our ability to comply with privacy-related obligations; our status as a “controlled company”; our status as a “smaller reporting company”; and other factors as set forth from time to time in our Securities and Exchange Commission filings, including those described under “Item 1A—Risk Factors” in our Annual Report on Form 10-K and Quarterly Reports on Form 10-Q. We intend these forward-looking statements to speak only as of the time of this release and do not undertake to update or revise them as more information becomes available, except as required by law.
Reports Fiscal Year 2026Revenue of $1.50 billion, a Net Loss of $134.8 million, which includes a $45.2 million Non-Cash Goodwill and Intangible Impairment Charge, and Adjusted EBITDA1 of $2.9 million
Company Amends Credit Agreement to Enhance Financial Flexibility and Evaluates a Range of Capital Raising Options to Optimize Capital Structure and Support Strategic Initiatives
Provides Outlook for Fiscal Year 2027
JERICHO, N.Y.–(BUSINESS WIRE)– 1-800-FLOWERS.COM, Inc. (NASDAQ: FLWS), a leading provider of thoughtful expressions designed to help inspire customers to give more, connect more, and build more and better relationships, today reported results for its Fiscal 2026 fourth quarter and year ended June 28, 2026.
“Fiscal 2026 was a year of meaningful progress as we strengthened the foundation of our business and positioned the Company for its next phase of transformation,” said Adolfo Villagomez, Chief Executive Officer of 1-800-Flowers.com. “We strengthened our leadership team, began to modernize our digital and marketing capabilities, simplified how we operate, and became a more customer-first, data-driven organization. As we enter fiscal 2027, accelerating the recovery of our revenue trends is our highest priority. We will continue building these capabilities while increasingly putting them to work to improve customer acquisition, engagement, and retention and to drive better business performance over time.”
“As part of our continued efforts to enhance our financial flexibility and support the ongoing transformation of the business, we recently amended our credit agreement to provide additional financial flexibility,” continued Mr. Villagomez. “We are also evaluating a range of options, including the sale of non-strategic assets and capital raising options, intended to optimize our capital structure and support investments in our transformation and drive future growth. While this work is underway, we remain focused on executing our fiscal 2027 priorities and improving the fundamental drivers of our business.”
Credit Agreement Amendment
The Company announced that it has amended its credit agreement to extend its existing covenant relief and provide the Company with additional flexibility to use a portion of the proceeds from potential asset sales to invest in strategic initiatives and support the ongoing transformation of the business. Additional information regarding the amendment can be found in the Company’s Form 8-K filed with the SEC on September 10, 2026.
Evaluation of Capital Raising Options
The Company is also evaluating a range of options intended to optimize its capital structure and provide additional capital to support investments in its transformation and drive future growth. The potential options may include, but are not limited to, one or more public or private debt or equity financings, potential divestitures of non-strategic assets, or other capital structure transactions. The Company has retained Guggenheim Securities, LLC as its financial advisor in connection with this evaluation. There can be no assurance that the evaluation will result in any transaction or outcome or, if one or more transactions ensue, what the terms of any such transaction might be. The Company is in the early stages of the evaluation and will not comment further during the process.
Fiscal 2026 Fourth Quarter Performance
Total consolidated revenues decreased 12.9% to $293.1 million, compared with the prior year period, primarily reflecting a strategic shift to improve marketing effectiveness and profitability. Consumer Floral & Gifts revenues declined 13.4%, Gourmet Foods & Gift Baskets revenues, which were impacted by the timing of Easter, declined 15.4%, while BloomNet revenues increased 1.9%.
Gross profit margin decreased 80 basis points to 34.7%, compared with 35.5% in the prior year period, primarily due to deleveraging on the sales decline, higher commodity costs and inventory reserves, partially offset by the Company’s cost reduction and operational efficiency initiatives, along with an approximately $7 million benefit related to tariff refunds.
Operating expenses decreased $16.7 million year-to-year to $158.2 million. Excluding non-recurring charges and the impact of the Company’s non-qualified deferred compensation plan in both periods, operating expenses decreased $8.9 million as compared with the prior year to $150.8 million, primarily due to lower marketing and labor costs.
Net loss for the quarter was $52.3 million, or $(0.82) per diluted share, as compared to a net loss of $(51.9) million, or $(0.82) per share, in the prior year period.
Adjusted net loss1 was $(51.6) million, or $(0.80) per diluted share, compared with an Adjusted net loss1 of $(43.8) million, or $(0.69) per share, in the prior year period.
Adjusted EBITDA1 loss for the quarter was $(31.0) million, compared with Adjusted EBITDA1 loss of $(24.2) million in the prior year period.
(1)
Refer to “Definitions of Non-GAAP Financial Measures” and the tables attached at the end of this press release for reconciliation of non-GAAP results to applicable GAAP results.
Fiscal Year 2026 Performance
Total consolidated revenues decreased 10.8% to $1.50 billion, compared with total consolidated revenues of $1.69 billion in the prior year period.
Gross profit margin decreased 70 basis points to 38.0%, compared with 38.7% in the prior year period, primarily due to deleveraging on the sales decline, higher commodity costs and inventory reserves, partially offset by the Company’s cost reduction and operational efficiency initiatives. Excluding the impact of non-recurring charges in the year ago period, gross profit margin decreased 110 basis points as compared with the prior year period.
Operating expenses decreased $158.6 million to $698.5 million, as compared with the prior year period. Excluding non-recurring charges and the impact of the Company’s non-qualified deferred compensation plan in both periods, operating expenses decreased by $62.0 million to $633.3 million, as compared with the prior year.
Net loss for the fiscal year was $(134.8) million or $(2.11), per diluted share, which includes a $45.2 million non-cash goodwill and intangible impairment charge, compared with a net loss of $(200.0) million, or $(3.13) per diluted share, in the prior year period, which included a non-cash goodwill and intangible impairment charge of $143.8 million.
Adjusted net loss1 was $(77.5) million, or $(1.21) per diluted share, compared with Adjusted net loss1 of $(52.5) million, or $(0.82) per diluted share, in the prior year period.
Adjusted EBITDA1 for the fiscal year was $2.9 million, as compared with $29.2 million in the prior year period.
Segment Results
The Company provides Fiscal 2026 fourth quarter and full year selected financial results for its Gourmet Foods & Gift Baskets, Consumer Floral & Gifts, and BloomNet® segments in the tables attached to this release and as follows:
Gourmet Foods & Gift Baskets: For the quarter, revenues decreased 15.4% to $85.8 million, as compared with the prior year period. Gross profit margin decreased 830 basis points from the prior year period to 17.7% due to deleveraging on the sales decline and increased tariff, commodity and shipping costs. The segment contribution margin1 loss was $23.4 million, compared with segment contribution margin loss of $19.0 million in the prior year period, excluding severance costs.
For the full fiscal year, revenue decreased 5.2% to $768.5 million. Gross profit margin decreased 130 basis points to 35.5%. Excluding non-recurring costs in both years, segment contribution margin1 for the year was $52.7 million, compared with $58.8 million in the prior year.
Consumer Floral & Gifts: For the quarter, revenues decreased 13.4% to $182.8 million, as compared with the prior year period. Gross profit margin increased 220 basis points from the prior year period to 40.7% on lower commodity and shipping costs. The segment contribution margin1 was $17.1 million, compared with $17.4 million in the prior year period, excluding severance and impairment costs.
For the full fiscal year, revenues decreased 17.7% to $638.9 million, as compared with the prior year period. Gross profit margin increased 10 basis points from the prior year period to 39.4%. Excluding the non-recurring costs in both years, segment contribution margin was $48.6 million, compared with $50.5 million in the prior year.
BloomNet: For the quarter, revenues increased 1.9% to $24.7 million, as compared with the prior year period. Gross profit margin increased 190 basis points from the prior year period to 48.8%. The segment contribution margin1 was $7.4 million, compared with $6.5 million in the prior year period, excluding severance costs.
For the full fiscal year, revenues decreased 1.9% to $96.8 million, as compared with the prior year period. Gross profit margin decreased 10 basis points from the prior year period to 48.4%. Excluding the impact of the severance charges, segment contribution margin1 for the year was $27.2 million, compared with $29.3 million in the prior year.
Fiscal Year 2027 Outlook
During Fiscal 2027, the Company expects to continue reinvesting a significant portion of the cost savings achieved through its operational efficiency initiatives into strategic growth investments. These investments include further modernization of the Company’s marketing capabilities, continued development of its marketing technology platform, enhancements to its digital customer experience and personalization capabilities, and other initiatives designed to strengthen customer acquisition, engagement, and retention.
While the Company expects the benefits of these investments to build over multiple years, management believes Fiscal 2027 marks the next phase of its transformation. The Company will continue to build key capabilities while increasingly leveraging the investments made during Fiscal 2026 to improve operating performance and create sustainable long-term value.
For Fiscal 2027, the Company expects net revenues to decline in the mid-single digit range compared with Fiscal 2026. The Company expects Fiscal 2027 adjusted EBITDA of $10 million to $15 million, which includes approximately $12 million of additional compensation expense versus Fiscal 2026.
Conference Call
The Company will conduct a conference call to discuss its financial results today, September 10, 2026, at 8:00 a.m. (ET). The conference call will be webcast from the Investors section of the Company’s website at www.1800flowersinc.com. A recording of the call will be posted on the Investors section of the Company’s website within two hours of the call’s completion.
Definitions of Non-GAAP Financial Measures:
We sometimes use financial measures derived from consolidated financial information, but not presented in our financial statements prepared in accordance with U.S. generally accepted accounting principles (“GAAP”). Certain of these are considered “Non-GAAP financial measures” under the U.S. Securities and Exchange Commission rules. Non-GAAP financial measures referred to in this document are either labeled as “Non-GAAP,” “adjusted” or designated as such with a “1”. See below for definitions and the reasons why we use these non-GAAP financial measures. Where applicable, see the Selected Financial Information below for reconciliations of these non-GAAP measures to their most directly comparable GAAP financial measures. Reconciliations for forward-looking figures would require unreasonable efforts at this time because of the uncertainty and variability of the nature and amount of certain components of various necessary GAAP components, including, for example, those related to compensation, tax items, amortization or others that may arise during the year, and the Company’s management believes such reconciliations would imply a degree of precision that would be confusing or misleading to investors. For the same reasons, the Company is unable to address the probable significance of the unavailable information. The lack of such reconciling information should be considered when assessing the impact of such disclosures.
EBITDA and Adjusted EBITDA:
We define EBITDA as net income (loss) before interest, taxes, depreciation, and amortization. Adjusted EBITDA is defined as EBITDA adjusted for the impact of stock-based compensation, Non-Qualified Deferred Compensation Plan (“NQDC”) investment appreciation/depreciation, goodwill and intangible impairment and for certain items affecting period-to-period comparability. See Selected Financial Information for details on how EBITDA and Adjusted EBITDA were calculated for each period presented. The Company presents EBITDA and Adjusted EBITDA because it considers such information meaningful supplemental measures of its performance and believes such information is frequently used by the investment community in the evaluation of similarly situated companies. The Company uses EBITDA and Adjusted EBITDA as factors to determine the total amount of incentive compensation available to be awarded to executive officers and other employees. The Company’s credit agreement uses EBITDA and Adjusted EBITDA-related items to determine its interest rate and to measure compliance with certain covenants. EBITDA and Adjusted EBITDA are also used by the Company to evaluate and price potential acquisition candidates. EBITDA and Adjusted EBITDA have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of the Company’s results as reported under GAAP. Some of the limitations are: (a) EBITDA and Adjusted EBITDA do not reflect changes in, or cash requirements for, the Company’s working capital needs; (b) EBITDA and Adjusted EBITDA do not reflect the interest expense, or the cash requirements necessary to service interest or principal payments, on the Company’s debts; and (c) although depreciation and amortization are non-cash charges, the assets being depreciated and amortized may have to be replaced in the future and EBITDA does not reflect any cash requirements for such capital expenditures. EBITDA and Adjusted EBITDA should only be used on a supplemental basis combined with GAAP results when evaluating the Company’s performance.
Segment Contribution Margin and Adjusted Segment Contribution Margin:
We define Segment Contribution Margin as earnings before interest, taxes, depreciation, and amortization, before the allocation of corporate overhead expenses. Adjusted Segment Contribution Margin is defined as Segment Contribution Margin adjusted for certain items affecting period-to-period comparability. See Selected Financial Information for details on how Segment Contribution Margin and Adjusted Segment Contribution Margin were calculated for each period presented. When viewed together with our GAAP results, we believe Segment Contribution Margin and Adjusted Segment Contribution Margin provide management and users of the financial statements meaningful information about the performance of our business segments. Segment Contribution Margin and Adjusted Segment Contribution Margin are used in addition to and in conjunction with results presented in accordance with GAAP and should not be relied upon to the exclusion of GAAP financial measures. The material limitation associated with the use of Segment Contribution Margin and Adjusted Segment Contribution Margin is that they are an incomplete measure of profitability as they do not include all operating expenses or non-operating income and expenses. Management compensates for this limitation when using these measures by looking at other GAAP measures, such as Operating Income (Loss) and Net Income (Loss).
Adjusted Net Income (Loss) and Adjusted or Comparable Net Income (Loss) Per Common Share:
We define Adjusted Net Income (Loss) and Adjusted or Comparable Net Income (Loss) Per Common Share as Net Income (Loss) and Net Income (Loss) Per Common Share adjusted for certain items affecting period-to-period comparability. See Selected Financial Information below for details on how Adjusted Net Income (Loss) Per Common Share and Adjusted or Comparable Net Income (Loss) Per Common Share were calculated for each period presented. We believe that Adjusted Net Income (Loss) and Adjusted or Comparable Net Income (Loss) Per Common Share are meaningful measures because they increase the comparability of period-to-period results. Since these are not measures of performance calculated in accordance with GAAP, they should not be considered in isolation of, or as a substitute for, GAAP Net Income (Loss) and Net Income (Loss) Per Common Share, as indicators of operating performance and they may not be comparable to similarly titled measures employed by other companies.
Free Cash Flow:
We define Free Cash Flow as net cash provided by (used in) operating activities less capital expenditures. The Company considers Free Cash Flow to be a liquidity measure that provides useful information to management and investors about the amount of cash generated by the business after the purchases of fixed assets, which can then be used to, among other things, invest in the Company’s business, make strategic acquisitions, strengthen the balance sheet, and repurchase stock or retire debt. Free Cash Flow is a liquidity measure that is frequently used by the investment community in the evaluation of similarly situated companies. Since Free Cash Flow is not a measure of performance calculated in accordance with GAAP, it should not be considered in isolation or as a substitute for analysis of the Company’s results as reported under GAAP. A limitation of the utility of Free Cash Flow as a measure of financial performance is that it does not represent the total increase or decrease in the Company’s cash balance for the period.
About 1-800-FLOWERS.COM, Inc.
1-800-FLOWERS.COM, Inc. is a leading provider of thoughtful expressions designed to help inspire customers to give more, connect more, and build more and better relationships. The Company’s e-commerce business platform features an all-star family of brands, including: 1-800-Flowers.com®, 1-800-Baskets.com®, Card Isle®, Cheryl’s Cookies®, Harry & David®, PersonalizationMall.com®, Shari’s Berries®, FruitBouquets.com®, Things Remembered®, Moose Munch®, The Popcorn Factory®, Wolferman’s Bakery®, Vital Choice®, Simply Chocolate® and Scharffen Berger®. Through the Celebrations Passport® loyalty program, which provides members with free standard shipping and no service charge on eligible products across our portfolio of brands, 1-800-FLOWERS.COM, Inc. strives to deepen relationships with customers. The Company also operates BloomNet®, an international floral and gift industry service provider offering a broad-range of products and services designed to help its members grow their businesses profitably; Napco℠, a resource for floral gifts and seasonal décor; and DesignPac®, a manufacturer of gift baskets and towers. 1-800-FLOWERS.COM, Inc. was recognized among America’s Most Trustworthy Companies by Newsweek for 2024. 1-800-FLOWERS.COM, Inc. was also recognized as one of America’s Most Admired Workplaces for 2025 by Newsweek and was named to the Fortune 1000 list in 2022. Shares in 1-800-FLOWERS.COM, Inc. are traded on the NASDAQ Global Select Market, ticker symbol: FLWS. For more information, visit 1800flowersinc.com.
FLWS-COMP
FLWS-FN
Special Note Regarding Forward Looking Statements:
This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements represent the Company’s current expectations or forecasts concerning future events; they do not relate strictly to historical or current facts. Such statements can generally be identified by words such as “anticipate,” “estimate,” “expect,” “project,” “intend,” “plan,” “believe,” “foresee,” “forecast,” “likely,” “should,” “will,” “target,” or similar words or phrases. These forward-looking statements are subject to risks, uncertainties, and other factors, many of which are outside of the Company’s control, which could cause actual results to differ materially from the results expressed or implied in the forward-looking statements, including, but not limited to, statements relating to future actions; the Company’s ability to leverage its operating platform and reduce its operating expense ratio; its ability to successfully integrate acquired businesses and assets; its ability to successfully execute its strategic priorities; its ability to cost effectively acquire and retain customers and drive purchase frequency; the outcome of contingencies, including legal proceedings in the normal course of business; its ability to compete against existing and new competitors; its ability to manage expenses associated with sales and marketing and necessary general and administrative and technology investments; its ability to reduce promotional activities and achieve more efficient marketing programs; and general consumer sentiment and industry and economic conditions that may affect levels of discretionary customer purchases of the Company’s products. The Company cannot guarantee that any forward-looking statement will be realized. Achievement of future results is subject to risk, uncertainties and potentially inaccurate assumptions. Should known or unknown risks or uncertainties materialize, or should underlying assumptions prove inaccurate, actual results could differ materially from past results and those anticipated, estimated or projected. You should bear this in mind as you consider forward-looking statements. The Company undertakes no obligation to publicly update any of the forward-looking statements, whether because of new information, future events or otherwise, made in this release or in any of its SEC filings. Consequently, you should not consider any such list to be a complete set of all potential risks and uncertainties. For a more detailed description of these and other risk factors, refer to the Company’s SEC filings, including the Company’s Annual Reports on Form 10-K and its Quarterly Reports on Form 10-Q.
VNCE Will Own OVO’s Operating Business and a 5% Stake in OVO’s Intellectual Property Alongside Authentic Brands Group and OVO Co-Founder Aubrey “Drake” Graham
Transaction Expected to be Accretive to VNCE in Fiscal 2027
VNCE Expects to Deliver Second Quarter Fiscal 2026 Results At the High End of Guidance
NEW YORK–(BUSINESS WIRE)– Vince Holding Corp. (Nasdaq: VNCE) (“VNCE” or the “Company”), a global retail platform today announced it has completed the acquisition of the operating business of October’s Very Own (“OVO”), a globally recognized lifestyle brand. VNCE now will own and operate OVO’s business as OVO’s core apparel and retail licensee, marking the first expansion of its multi-brand platform strategy beyond Vince, and will build on OVO’s existing operations using its scale and infrastructure to support the brand’s next phase of growth.
This transaction also further deepens VNCE’s partnership with Authentic Brands Group (“Authentic”), a global entertainment platform, who has acquired a majority stake in OVO’s intellectual property (“OVO IP”). A portion of the proceeds from the sale of OVO IP will be used to strengthen OVO’s balance sheet and support VNCE’s growth strategy for the business. This transaction combines Authentic’s brand management expertise with VNCE’s proven capabilities in merchandising and operating ready-to-wear brands, creating a new revenue stream for VNCE. As part of this expanded partnership, VNCE will own 5% of the OVO IP and has entered into a long-term license agreement for use of the OVO IP.
This transaction advances VNCE’s strategy to diversify its revenue and earnings by leveraging its platform and operating expertise. This transaction is expected to:
Provide VNCE access to the fast growing global streetwear market.
Fuel OVO’s U.S. growth by:
Store and e-commerce expansion by leveraging VNCE’s scale and infrastructure.
Launch OVO’s wholesale business through VNCE’s established wholesale relationships with key national department store partners.
Optimize OVO’s operations while design and creative functions for each brand remain separate.
Give VNCE the Canadian-based infrastructure to open Vince stores and expand e-commerce and wholesale.
Founded by Aubrey “Drake” Graham, Oliver El-Khatib, and Noah “40” Shebib, OVO has established itself as one of the most recognized brands in contemporary streetwear. Known for its distinctive owl logo and black-and-gold aesthetic, the brand has built its reputation on collaboration-led product drops and a close connection to its customer base. OVO currently operates 12 stores across Canada, the United States, and the United Kingdom, in addition to its e-commerce platform.
“We are thrilled to welcome OVO into our portfolio and to partner with Drake and Authentic in building on the brand’s strong foundation to support its next phase of growth,” said Brendan Hoffman, Chief Executive Officer of VNCE. “This transaction also deepens our relationship with Authentic Brands Group, a partner supporting our multi-brand platform strategy to broaden our portfolio of brands, business models, and distribution channels, and drive long-term value for all stakeholders. We are committed to preserving the authenticity and meaningful customer relationships that have driven OVO’s success to date.”
“We are proud to welcome OVO to Authentic and to expand our partnership with VNCE, whose operating expertise makes them an ideal partner to grow the business,” said Jamie Salter, Founder and Executive Chairman of Authentic. “Together, we see significant opportunity to introduce OVO into new categories, channels, and markets while staying true to the creative vision and community that have made the brand so special. The success we’ve had partnering with VNCE gives us great confidence in their stewardship of OVO’s business and we look forward to exploring future opportunities to utilize the VNCE platform.”
“We’re just a couple kids from Toronto who started something we believed in, here we are 20 years later, same kids with bigger dreams. Authentic and VNCE are the perfect partners to help us continue to grow,” said Drake.
Transaction Details
Under the terms of the transaction, Authentic formed a new subsidiary which holds OVO’s IP, under which Authentic owns 51%, Drake owns 44%, and VNCE owns the remaining 5%. A portion of the proceeds from the sale of OVO’s IP was used to strengthen the balance sheet of OVO’s operating business, which VNCE then acquired. VNCE remains well-capitalized, with a strong balance sheet that supports both this transaction and its continued growth in the Vince business.
VNCE and Authentic have entered into a license agreement granting VNCE the exclusive right to use OVO’s IP to manufacture and sell licensed apparel worldwide, in exchange for payment of a royalty fee to Authentic.
VNCE’s acquisition includes all of OVO’s existing operating companies, assets and liabilities, including its retail stores, e-commerce platform, and wholesale relationships across Canada, the United States, and the United Kingdom. VNCE will retain OVO’s existing team and continue to operate the business from its Toronto headquarters as it builds out the brand’s next phase of growth.
Vince and OVO will maintain separate brand operations and creative teams, with VNCE serving its contemporary customer and OVO continuing to serve its streetwear audience.
Second Quarter Fiscal 2026 Outlook
Based on continued momentum in the business, VNCE expects to deliver Q2 fiscal 2026 results at the high-end of its prior guidance ranges, excluding any benefit from tariff refunds.
These amounts are based on currently available information and are subject to change, including potential adjustments related to customary financial closing procedures and period-end accruals for the fiscal quarter ending August 1, 2026.
The Company plans to share more on its results when its report its second quarter fiscal 2026 results by September 15, 2026.
DISCLOSURES REGARDING FORWARD-LOOKING STATEMENTS
This document, and any statements incorporated by reference herein, contain forward-looking statements under the Private Securities Litigation Reform Act of 1995. Forward-looking statements include the statements under “Transaction Details” and “Second Quarter Fiscal 2026 Outlook” above as well as statements regarding, among other things, our current expectations about possible or assumed future results of operations of the Company and are indicated by words or phrases such as “may,” “will,” “should,” “believe,” “expect,” “seek,” “anticipate,” “intend,” “estimate,” “plan,” “target,” “project,” “forecast,” “envision” and other similar phrases. Although we believe the assumptions and expectations reflected in these forward-looking statements are reasonable, these assumptions and expectations may not prove to be correct and we may not achieve the results or benefits anticipated. These forward-looking statements are not guarantees of actual results, and our actual results may differ materially from those suggested in the forward-looking statements. These forward-looking statements involve a number of risks and uncertainties, some of which are beyond our control, including, without limitation: the expected effects of the acquisition of OVO’s existing operations, assets and liabilities (the “OVO Acquisition”) on the Company; our ability to integrate OVO with the Company, changes to and unpredictability in the trade policies and tariffs imposed by the U.S. and the governments of other nations; general economic conditions; our ability to maintain adequate cash flow from operations or availability under our revolving credit facility to meet our liquidity needs; restrictions on our operations under our credit facilities; our ability to improve our profitability; our ability to maintain our larger wholesale partners; our ability to accurately forecast customer demand for our products; our ability to maintain the license agreement relating to the Vince brand with ABG Vince; ABG Vince’s expansion of the Vince brand into other categories and territories; ABG Vince’s approval rights and other actions; our ability to realize the benefits of our strategic initiatives; our ability to make lease payments when due; our ability to open retail stores under favorable lease terms and operate and maintain new and existing retail stores successfully; our operating experience and brand recognition in international markets; our ability to remediate the identified material weakness in our internal control over financial reporting; our ability to comply with domestic and international laws, regulations and orders; increased scrutiny regarding our approach to sustainability matters and environmental, social and governance practices; competition in the apparel and fashion industry; our ability to attract and retain key personnel; seasonal and quarterly variations in our revenue and income; the protection and enforcement of intellectual property rights relating to the Vince brand; the extent of our foreign sourcing; our reliance on independent manufacturers; our ability to ensure the proper operation of the distribution facilities by third-party logistics providers; fluctuations in the price, availability and quality of raw materials; the ethical business and compliance practices of our independent manufacturers; our ability to mitigate system or data security issues, such as cyber or malware attacks, as well as other major system failures; our ability to adopt, optimize and improve our information technology systems, processes and functions; our ability to comply with privacy-related obligations; our status as a “controlled company”; our status as a “smaller reporting company”; and other factors as set forth from time to time in our Securities and Exchange Commission filings, including those described in our Annual Report on Form 10-K and Quarterly Reports on Form 10-Q. We intend these forward-looking statements to speak only as of the time of this release and do not undertake or revise them as more information becomes available, except as required by law.
About Vince Holding Corp.
Vince Holding Corp. is a global retail platform that operates the Vince brand women’s and men’s ready-to-wear business. Vince, established in 2002, is a leading global luxury apparel and accessories brand best known for creating elevated yet understated pieces for everyday effortless style. Vince Holding Corp. operates 42 full-price retail stores, 12 outlet stores, and its e-commerce site, as well as through premium wholesale channels globally. Please visit www.vince.com for more information.
About October’s Very Own
October’s Very Own (OVO) is a Canadian lifestyle brand led by CEO Drex Jancar and founded by Aubrey “Drake” Graham, Oliver El-Khatib, and Noah “40” Shebib. OVO offers premium apparel and accessories and is known for its distinctive owl logo and black-and-gold aesthetic. The brand has grown into a globally recognized enterprise with 12 flagship stores and a worldwide e-commerce presence.
About Authentic Brands Group
Authentic Brands Group (Authentic) is a global brand and entertainment platform that owns and invests in iconic intellectual property and cultural assets. It accelerates brands through a set of specialized businesses that combine powerful storytelling, premium content, unforgettable live experiences and global commerce. Through a network of more than 1,700 best-in-class licensees and strategic partners across 150 countries and expansive distribution, Authentic’s brands drive more than $38 billion in annual systemwide retail sales worldwide.
Authentic’s diversified portfolio spans more than 50 brands and reaches nearly one billion social media followers. Its roster includes Reebok, Champion, Shaquille O’Neal, David Beckham, Kevin Hart, Sports Illustrated, Elvis Presley, Muhammad Ali, Marilyn Monroe, GUESS, Care Bears, Aéropostale, Nautica, Eddie Bauer, Lucky Brand, Nine West, Brooks Brothers, Juicy Couture, Vince Camuto, Izod, Van Heusen, Dockers, Ted Baker, Hart Schaffner Marx, Vince, OVO, Barneys New York, Judith Leiber, Quiksilver, Spyder, Billabong, Volcom, Roxy, RVCA, DC Shoes, Prince, Sperry and Hunter.
The Personal Consumption Expenditures price index, the inflation measure the Federal Reserve targets most closely, rose 3.7% year over year in July, up from 3.6% in June, the Commerce Department reported Wednesday, coming in a touch stronger than economists had expected. Core PCE, which strips out volatile food and energy prices and is viewed as the cleaner read on underlying inflation pressure, held at 3.3% year over year, showing no improvement from the prior month.
This is the exact data release we flagged as pivotal heading into Fed Chair Kevin Warsh’s upcoming Jackson Hole speech, and it landed on the more hawkish side of the range economists had modeled. The result directly conflicts with earlier reports that had shown consumer price inflation cooling over the prior couple of months, reinforcing just how genuinely unresolved the inflation picture remains heading into the fall.
The Fed has held its policy rate steady in a range of 3.50% to 3.75% since December. Warsh has publicly committed to bringing inflation back to target, but has offered no clear signal on whether he believes that can happen without additional rate increases, and Wednesday’s data does nothing to support the case that it will happen on its own. Heather Long, chief economist at Navy Federal Credit Union, put it bluntly, the United States still has an inflation problem, and argued the latest data buys Warsh some time to wait and assess, but that he will need to be considerably clearer about what specific conditions would actually prompt him to raise rates.
Markets moved quickly to reprice the odds. Fed funds futures now reflect roughly a 44% probability of a September rate hike, up from about 36% just before this report, and traders are now fully pricing in that the Fed will have raised its policy rate by year end.
For companies operating below the $2 billion market cap threshold, this shift in rate expectations carries direct and immediate consequences. Small and microcap businesses typically carry considerably more variable-rate debt than large cap companies, meaning every incremental increase in the probability of a Fed hike translates into a real, measurable increase in borrowing costs across this segment of the market. This report also sharpens the stakes for Warsh’s Jackson Hole address, which now arrives with markets meaningfully more convinced a hike is coming than they were just days ago, making his tone and language around this data the most consequential signal small cap investors will get before the Fed’s actual September decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Gamescom 2026 AAA unveiling. Snail announced its Gamescom 2026 lineup, headlined by the unveiling of its second internally developed AAA title in the 9 Yin Sutra universe, set in a parallel timeline and alternate universe to 9Yin Sutra: Immortal, which debuted at ChinaJoy on July 30th. In our note on August 12th, we had identified an unannounced AAA reveal at Gamescom as a near-term event, and the release confirms it.
The franchise builds. Both 9 Yin Sutra titles draw on the established Age of Wushu IP, offering different treatments of the same martial arts setting. Along with these titles, Snail will also show For The Stars, its space-survival AAA project. In our view, concentrating two out of the three AAA projects within a single IP family should improve development and marketing efficiency, while also making outcomes across those titles more correlated.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
DODGEVILLE, Wis., Aug. 20, 2026 (GLOBE NEWSWIRE) — Lands’ End, Inc. (NASDAQ: LE) will host a conference call at 8:30 a.m. Eastern Time on Thursday, September 3, 2026, to discuss its second quarter fiscal 2026 financial results.
A news release will be issued before the call and also be available on the Company’s investor relations website. Listeners may access a live broadcast of the conference call on the Company’s investor relations website: https://investors.landsend.com/ in the Events and Presentations section. An online archive of the broadcast will be available at approximately noon on September 3, 2026.
About Lands’ End, Inc.
Lands’ End, Inc. (NASDAQ: LE) is a leading digital retailer of solution-based apparel, swimwear, outerwear, accessories, footwear, home products and uniforms. Lands’ End offers products online at www.landsend.com, through third-party distribution channels and Company Operated stores. Lands’ End also offers products to businesses and schools, for their employees and students, through the Outfitters distribution channel. Lands’ End is a classic American lifestyle brand that creates solutions for life’s every journey.
CONTACTS:
Lands’ End, Inc. Bernard McCracken Chief Financial Officer (608) 935-4100
Investor Relations: ICR, Inc. Tom Filandro (646) 277-1235 [email protected]