Release – 1-800-FLOWERS.COM, Inc. to Release its Fiscal 2026 Fourth Quarter and Year-End Results on Thursday, September 10, 2026

1-800-FLOWERS.COM, Inc. – link to home page

Research News and Market Data on FLWS

Aug 19, 2026

JERICHO, N.Y.–(BUSINESS WIRE)– 1-800-FLOWERS.COM, Inc. (NASDAQ: FLWS) (the “Company”),a leading provider of thoughtful expressions designed to help inspire customers to give more, connect more, and build more and better relationships, today announced that the Company will release financial results for its fiscal 2026 fourth quarter and year-end on Thursday, September 10, 2026. The press release will be issued before the market opens and will be followed by a conference call with members of senior management at 8:00 a.m. (ET).

The conference call will be available via live webcast on the Investors section of the Company’s website at www.1800flowersinc.com/investors. A replay of the webcast will be available shortly after the live event has concluded. A telephone replay of the call will be available beginning at 2:00 p.m. (ET) on September 10, 2026, through September 17, 2026, by dialing (855) 669-9658 or (412) 317-0088 for international callers; the passcode is 8022292.

Special Note Regarding Forward-Looking Statements:

Some of the statements contained in the Company’s press release and conference call regarding its fiscal 2026 fourth quarter and year-end results, other than statements of historical fact, may be forward-looking within the meaning of the Private Securities Litigation Reform Act of 1995. These statements involve risks and uncertainties that could cause actual results to differ materially from those expressed or implied in the applicable statements. For a more detailed description of these and other risk factors, please refer to the Company’s SEC filings including its Annual Reports and Forms 10-K and 10-Q available at the Investor Relations section of the Company’s website at 1800flowersinc.com. The Company expressly disclaims any intent or obligation to update any of the forward-looking statements made in the scheduled conference call and any recordings thereof, or in any of its SEC filings, except as may be otherwise stated by the Company.

About 1-800-FLOWERS.COM, Inc.

1-800-FLOWERS.COM, Inc. is a leading provider of thoughtful expressions designed to help inspire customers to share more, connect more, and build more and better relationships. The Company’s e-commerce business platform features an all-star family of brands, including: 1-800-Flowers.com®, 1-800-Baskets.com®, Card Isle®, Cheryl’s Cookies®, Harry & David®, PersonalizationMall.com®, Shari’s Berries®, FruitBouquets.com®, Things Remembered®, Moose Munch®, The Popcorn Factory®, Wolferman’s Bakery®, Vital Choice®, Simply Chocolate® and Scharffen Berger®. Through the Celebrations Passport® loyalty program, which provides members with free standard shipping and no service charge on eligible products across our portfolio of brands, 1-800-FLOWERS.COM, Inc. strives to deepen relationships with customers. The Company also operates BloomNet®, an international floral and gift industry service provider offering a broad range of products and services designed to help members grow their businesses profitably; Napco℠, a resource for floral gifts and seasonal décor; and DesignPac®, a manufacturer of gift baskets and towers. 1-800-FLOWERS.COM, Inc. was recognized among America’s Most Trustworthy Companies by Newsweek for 2024. 1-800-FLOWERS.COM, Inc. was also recognized as one of America’s Most Admired Workplaces for 2025 by Newsweek and was named to the Fortune 1000 list in 2022. Shares in 1-800-FLOWERS.COM, Inc. are traded on the NASDAQ Global Select Market, ticker symbol: FLWS. For more information, visit 1800flowersinc.com.

FLWS-COMP
FLWS-FN

View source version on businesswire.com: https://www.businesswire.com/news/home/20260819221041/en/

Investors Contact:

Andy Milevoj

[email protected]

Media:

[email protected]

Source: 1-800-FLOWERS.COM, Inc.

Xcel Brands (XELB) – Commercialization Advances: Building Toward a Second-Half Revenue Inflection


Monday, August 17, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q2 results were softer than expected, largely due to timing. Revenue was approximately $1.1 million, compared with $1.3 million in the prior-year period, reflecting the Judith Ripka divestiture and delays associated with QVC’s bankruptcy and vendor-credit issues. Importantly, the QVC-related disruptions appear to have largely been resolved.

Commercialization remains the key story as the creator portfolio moves into the market. With the portfolio’s social media reach having expanded from roughly 5 million to more than 46 million followers, we believe the company has assembled a compelling audience from which to build consumer brands. The next several quarters should provide evidence regarding Xcel’s ability to convert that audience into sustainable royalty revenue.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Release – ACCO Brands to Acquire Trust

ACCO Brands Logo

Research News and Market Data on ACCO

08/14/2026

  • Trust designs and markets computer and gaming peripherals across Europe and Latin America, extending ACCO Brands’ Kensington, PowerA and EPOS technology peripherals portfolio
  • Transaction accelerates ACCO Brands’ pivot toward higher-growth technology peripherals categories, which on a pro forma basis will generate approximately $500 million in annual sales
  • Adds scale in large, growing categories sold through retail, online and B2B channels
  • Trust generates approximately $100 million in annual revenue and is expected to be modestly accretive to adjusted EPS in the first 12 months
  • Expect to realize cost synergies of approximately $5 to $8 million

LAKE ZURICH, Ill.–(BUSINESS WIRE)– ACCO Brands Corporation (NYSE: ACCO), a global leader in branded office and learning products and technology accessories, today announced it has entered into a definitive agreement to acquire Trust, a European provider of computer and gaming accessories, from Egeria, a pan-European investment firm.

Founded in 1983 and headquartered in the Netherlands, Trust is a well-recognized consumer electronics brand with more than 40 years of presence in PC accessories, gaming, smart home and mobile accessories. The company offers a comprehensive product portfolio spanning keyboards, mice, headsets, speakers, webcams, chargers, and gaming peripherals, sold through a broad network of leading retailers, e-commerce platforms, and B2B channels. Trust operates an asset-light model with outsourced manufacturing and scalable sourcing and serves customers in Europe and Latin America.

“Building on the strategic pivot to an enhanced focus on faster-growing categories and the recent acquisition of EPOS, Trust adds a well-established brand and an impressive peripherals lineup that complements Kensington, PowerA and EPOS, deepening our presence in some of the largest and fastest-growing categories in technology peripherals,” said Tom Tedford, ACCO Brands President and CEO. “This acquisition continues the shift of our product and brand portfolio toward higher-growth technology peripherals, which will now approach $500 million in annual sales on a pro forma basis. We expect to deliver cost synergies as we integrate Trust into our European platform.”

“Joining ACCO Brands is an exciting next chapter for Trust,” said Jeroen Hoogland, CEO of Trust. “ACCO Brands’ global scale, supply chain, and channel relationships will help us accelerate innovation and reach even more consumers and business customers across Europe and beyond.”

Trust generates approximately $100 million in annual revenue and is expected to be modestly accretive to adjusted EPS in the first 12 months. ACCO Brands expects to realize cost synergies of approximately $5 to $8 million, within 18 months after closing.

The transaction will be financed through borrowings under ACCO Brands’ revolving credit facility, with limited impact to pro forma leverage. The transaction is expected to close in late third quarter or early fourth quarter, subject to customary closing conditions, including applicable competition authority approvals.

About ACCO Brands Corporation

ACCO Brands is the leader in branded consumer products that enable productivity, confidence and enjoyment while working, when learning and while playing. Our widely recognized brands include AT-A-GLANCE®, Five Star®, Kensington®, Leitz®, Mead®, PowerA®, Swingline®, Tilibra® and many others. More information about ACCO Brands Corporation (NYSE: ACCO) can be found at www.accobrands.com.

About Egeria

Established in 1997, Egeria is an independent pan-European investment company. Its private equity practice is focused on healthy mid-sized companies primarily in the Benelux and DACH regions. Guided by its core philosophy, “Boldly Building Together,” Egeria believes in building businesses through close collaboration, entrepreneurial spirit, and shared ownership with management teams. Egeria’s private equity portfolio comprises investments in more than 20 companies with combined revenues of around €3.0 billion and over 14,000 employees. For more information, please visit egeriagroup.com.

Forward-Looking Statements

Statements contained herein, other than statements of historical fact, particularly those anticipating future financial performance, business prospects, growth, strategies, business operations and similar matters, results of operations, liquidity and financial condition, and those relating to synergies, cost reductions, anticipated pre-tax savings, restructuring costs and the satisfaction of closing conditions for the subject transaction are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These statements are based on the beliefs and assumptions of management based on information available to us at the time such statements are made. These statements, which are generally identifiable by the use of the words “will,” “believe,” “expect,” “intend,” “anticipate,” “estimate,” “forecast,” “future,” “project,” “plan,” and similar expressions, are subject to certain risks and uncertainties, are made as of the date hereof, and we undertake no duty or obligation to update them. Forward-looking statements are subject to the occurrence of events outside the Company’s control and actual results, and the timing of events may differ materially from those suggested or implied by such forward-looking statements due to numerous factors that involve substantial known and unknown risks and uncertainties. Investors and others are cautioned not to place undue reliance on forward-looking statements when deciding whether to buy, sell or hold the Company’s securities.

Our outlook is based on certain assumptions which we believe to be reasonable under the circumstances. These include, without limitation, assumptions regarding consumer demand, tariffs, global geopolitical and economic uncertainties, and fluctuations in foreign currency exchange rates; and the other factors described below.

Among the factors that could cause our actual results to differ materially from our forward-looking statements are: the occurrence of any event, change or other circumstances that could give rise to the right of ACCO Brands or Egeria to terminate the transaction, the possibility that the transaction is not completed or, if completed, that the anticipated benefits of the transaction are not realized when expected or at all, including as a result of the impact of, or problems arising from, obtaining regulatory approvals, the integration of Trust, operating costs and business disruption following the transaction, the integration of Trust products and our ability to realize synergies in the integration, as well as changes in trade policy and regulations, including changes in trade agreements and the imposition of tariffs, and the resulting consequences; global political and economic uncertainties; a limited number of large customers account for a significant percentage of our sales; sales of our products are affected by general economic and business conditions globally and in the countries in which we operate; risks associated with foreign currency exchange rate fluctuations; challenges related to the highly competitive business environment in which we operate; our ability to develop and market innovative products that meet consumer demands and to expand into new and adjacent product categories; our ability to successfully expand our business in emerging markets and the exposure to greater financial, operational, regulatory, compliance and other risks in such markets; the continued decline in the use of certain of our products; risks associated with seasonality, the sufficiency of investment returns on pension assets, risks related to actuarial assumptions, changes in government regulations and changes in the unfunded liabilities of a multi-employer pension plan; any impairment of our intangible assets; our ability to secure, protect and maintain our intellectual property rights, and our ability to license rights from major gaming console makers and video game publishers to support our gaming accessories business; our ability to grow profitably through acquisitions, and successfully integrate them; our ability to successfully execute our multi-year restructuring and cost savings program and realize the anticipated benefits; continued disruptions in the global supply chain; risks associated with inflation and other changes in the cost or availability of raw materials, transportation, labor, and other necessary supplies and services and the cost of finished goods; risks associated with outsourcing production of certain of our products, information technology systems and other administrative functions; the failure, inadequacy or interruption of our information technology systems or their supporting infrastructure; risks associated with a cybersecurity incident or information security breach, including that related to a disclosure of personally identifiable information; risks associated with our indebtedness, including limitations imposed by restrictive covenants, our debt service obligations, and our ability to comply with financial ratios and tests; a change in or discontinuance of our stock repurchase program or the payment of dividends; product liability claims, recalls or regulatory actions; the impact of litigation or other legal proceedings; the impact of additional tax liabilities stemming from our global operations and changes in tax laws, regulations and tax rates; our failure to comply with applicable laws, rules and regulations and self-regulatory requirements, the costs of compliance and the impact of changes in such laws; our ability to attract and retain qualified personnel; the volatility of our stock price; risks associated with circumstances outside our control, including those caused by telecommunication failures, labor strikes, power and/or water shortages, public health crises, such as the occurrence of contagious diseases, severe weather events, war, terrorism and other geopolitical incidents; and other risks and uncertainties described in “Part I, Item 1A. Risk Factors” in our Annual Report on Form 10-K for the year ended December 31, 2025, and in other reports we file with the Securities and Exchange Commission.

For further information:

Christopher McGinnis
Investor Relations
(847) 796-4320

Kori Reed
Media Relations
(224) 501-0406

Source: ACCO Brands Corporation

SKYX Platforms (SKYX) – Another Quarter of Growth


Friday, August 14, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. SKYX Platforms just completed its 10th consecutive quarter of year-over-year growth. The Company is trending positively, generating record second quarter 2026 revenues. The Company’s builder and hotel segments are continuing to grow. With savings of up to 90% of time for installation or renovation, and up to 90% of the cost of renovation and installations, we believe SKYX’s value proposition is very strong in the hotels and builders segments. We believe the positive trends will continue to accelerate through the balance of 2026 as the Company continues to build out and execute on its channel strategy.

2Q26 Results. Revenue in 2Q26 rose 9.6% y-o-y to $25.27 million and was above our $24 million projection, with the increase due to an expansion of sales of SKYX products. The Company reported an adjusted EBITDA loss of $3.5 million, up slightly from last year’s $2.6 million loss. Net loss totaled $8.48 million, or $0.06/sh, versus a $9.1 million net loss, or $0.08/sh, in 2Q25.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Xcel Brands, Inc. Announces Second Quarter 2026 Financial Results

Primary Logo

Research News and Market Data on XELB

August 13, 2026 at 4:05 PM EDT

PDF Version

  • Net loss on a GAAP basis was $2.5 million for the current quarter compared with $4.0 million net loss for the prior year quarter.
  • EBITDA for the current quarter was negative $0.48 million compared with negative$0.30 million EBITDA for the prior year quarter which is a 40% improvement when adjusted for a non-recurring expense reduction from an Employee Tax Credit received in Q2 last year and compared with negative $0.70 for the first quarter, a 32% improvement over Q1, 2026

NEW YORK, Aug. 13, 2026 (GLOBE NEWSWIRE) — Xcel Brands, Inc. (NASDAQ: XELB) (“Xcel” or the “Company”), a media and consumer products company with significant expertise in building influencer lead brands, live-steam shopping and social commerce, today announced its financial results for the quarter ended June 30, 2026.

Robert W. D’Loren, Chairman and Chief Executive Officer of Xcel commented, “Our second quarter earnings on an Adjusted EBITDA basis were the best since June 2024, this was driven by the product launch of two of our new influencer led brands and additional reductions in operating expenses. I am very excited by the enormous potential of these brands going into the future. The recent changes in the search box since Google went to AI Mode, will make video content created by influencers that are authorities in their category part of the cited AI answer. I am excited to be managing a portfolio of brands that generate awareness through a combined existing audience of over 46 million people.”

Second Quarter 2026 Financial Results

Total revenue for the second quarter of 2026 was $1.1 million, representing a decrease of approximately $0.2 million (-14%) from the prior year quarter. This year-over-year decrease was primarily attributable to divestiture of the Judith Ripka brand.

Direct operating costs and expenses were essentially flat from the prior year quarter of approximately $1.9 million. It should be noted that the prior year quarter included an expense reduction of approximately $0.50 million from an employee retention credit refund. Excluding this prior year, non-recurring expense reduction, direct operating expenses decreased by approximately $0.50 million from the prior year quarter.

Net loss attributable to Xcel Brands stockholders for the quarter was approximately $2.5 million, or $(0.40) per share, compared with net loss of $4.0 million, or $(1.66) per share, for the prior year quarter.

After adjusting certain cash and non-cash items, current quarter results on a non-GAAP basis were a net loss of approximately $1.3 million, or $(0.21) per share and net loss of approximately $0.9 million, or $(0.37) per share, for the prior year quarter. Adjusted EBITDA was negative $0.48 million for the current quarter, compared with Adjusted EBITDA of negative $0.30 million for the prior year quarter. The second quarter EBITDA, when excluding the non-recurring expense reduction referenced above, Adjusted EBITDA improved by approximately $0.32 million.

Six Month 2026 Financial Results

Total revenue for the current six-month period was $2.3 million, representing a decrease of approximately $0.4 million (-14%) from the prior year period. This year-over-year decrease was primarily attributable to divestiture of the Judith Ripka brand.

Direct operating costs and expenses decreased approximately $0.2 million from the prior year six months to $4.0 million in the current six months. When factoring in the prior year period, non-recurring expense reduction, the decrease in direct operating expenses would have been approximately $0.7 million. Currently, the Company has reduced its direct operating expenses to an expected run rate of less than $8 million per annum.

Net loss attributable to Xcel Brands stockholders for the current six months was approximately $5.0 million, or $(0.82) per share, compared with net loss of $6.8 million, or $(2.84) per share, for the prior year period.

After adjusting certain cash and non-cash items, the current six month period results on a non-GAAP basis were a net loss of approximately $2.7 million, or $(0.44) per share and net loss of approximately $2.3 million, or $(0.95) per share, for the prior year period. Adjusted EBITDA was negative $1.2 million for the current six months, compared with Adjusted EBITDA of negative $1.0 million for the prior year period. The current six month EBITDA, when excluding the non-recurring expense reduction referenced above, Adjusted EBITDA improved by approximately $0.3 million.

Balance Sheet

The Company’s balance sheet on June 30, 2026, reflected stockholders’ equity of approximately $12 million, unrestricted cash and cash equivalents of approximately $0.4 million. The Company’s balance sheet on June 30, 2026, also reflected approximately $12 million of long-term debt.

The Company’s working capital on June 30, 2026 (exclusive of the current portion of lease obligations and deferred revenue was negative $1.3 million. On January 21, 2026, the Company entered into a common stock purchase agreement, pursuant to which the buyer has committed to purchase up to $15.0 million of the Company’s common stock. Under the terms and conditions of this agreement, the Company has the right, but not the obligation, to sell up to $15.0 million of the Company’s common stock. The actual amount and timing of any sales of Common Stock will be determined by the Company at its discretion.

Conference Call and Webcast

The Company will host a conference call with members of the executive management team to discuss these results with additional comments and details at 9:00 a.m. Eastern Time on August 14, 2026. A webcast of the conference call will be available live on the Investor Relations section of Xcel’s website at www.xcelbrands.com. Interested parties unable to access the conference call via the webcast may dial 800-715-9871 or 646-307-1963 and use the conference ID 4300396. A replay of the webcast will be available on Xcel’s website.

About Xcel Brands

Xcel Brands, Inc. (NASDAQ: XELB) is a media and consumer products company engaged in the design, licensing, marketing, live streaming, and social commerce sales of branded apparel, footwear, accessories, fine jewelry, home goods and other consumer products, and the acquisition of dynamic consumer lifestyle brands. Xcel was founded in 2011 with a vision to reimagine shopping, entertainment, and social media as social commerce. Xcel owns the Halston and C. Wonder brands, as well as the co-branded collaboration brands Tower Hill by Christie Brinkley, Trust. Respect. Love by Cesar Millan, GemmaMade by Gemma Stafford and Off/Duty by Coco Rocha brand and holds noncontrolling interests or long-term license agreement in Mesa Mia by Jenny Martinez. Xcel also owns and manages the Longaberger by Shannon Doherty brand through its controlling interest in Longaberger Licensing, LLC. Xcel is pioneering a modern consumer products sales strategy which includes the promotion and sale of products under its brands through interactive television, digital live-stream shopping, social commerce, brick-and-mortar retailers, and e-commerce channels to be everywhere its customer’s shop. The company’s previously owned and current brands have generated more than $5 billion in retail sales via livestreaming in interactive television and digital channels alone and has over 20,000 hours of content production time in live-stream and social commerce. The brand portfolio reaches more than 46 million social media followers with broadcast reaching 200 million households. Headquartered in New York City, Xcel Brands is led by an executive team with significant live streaming, production, merchandising, design, marketing, retailing, and licensing experience, and a proven track record of success in elevating branded consumer products companies. For more information, visit www.xcelbrands.com.

Forward Looking Statements

This press release contains forward-looking statements. All statements other than statements of historical fact contained in this press release, including statements regarding future events, our future financial performance, business strategy and plans and objectives of management for future operations, are forward-looking statements. We have attempted to identify forward-looking statements by terminology including “anticipates,” “believes,” “can,” “continue,” “ongoing,” “could,” “estimates,” “expects,” “intends,” “may,” “appears,” “suggests,” “future,” “likely,” “goal,” “plans,” “potential,” “projects,” “predicts,” “seeks,” “should,” “would,” “guidance,” “confident” or “will” or the negative of these terms or other comparable terminology. These forward-looking statements include, but are not limited to, statements regarding our anticipated revenue, expenses, profitability, strategic plans and capital needs. These statements are based on information available to us on the date hereof and our current expectations, estimates and projections and are not guarantees of future performance. Forward-looking statements involve known and unknown risks, uncertainties, assumptions and other factors, including, without limitation, the risks discussed in the “Risk Factors” section and elsewhere in the Company’s Annual Report on form 10-K for the year ended December 31, 2024 and its other filings with the SEC, which may cause our or our industry’s actual results, levels of activity, performance or achievements to differ materially from those expressed or implied by these forward-looking statements. Moreover, we operate in a very competitive and rapidly changing environment. New risks emerge from time to time, and it is not possible for us to predict all risk factors, nor can we address the impact of all factors on our business or the extent to which any factor, or combination of factors, may cause our actual results to differ materially from those contained in any forward-looking statements. You should not place undue reliance on any forward-looking statements. Except as expressly required by the federal securities laws, we undertake no obligation to update any forward-looking statements, whether as a result of new information, future events, changed circumstances or any other reason.

For further information please contact:
Seth Burroughs
Xcel Brands
[email protected]

Non-GAAP net income and non-GAAP diluted EPS are non-GAAP unaudited terms. We define non-GAAP net income as net income (loss) attributable to Xcel Brands, Inc. stockholders, exclusive of amortization of trademarks, income (loss) from equity method investments, stock-based compensation and cost of licensee warrants, asset impairment charges, loss on extinguishment of debt and income taxes. Non-GAAP net income (loss) and non-GAAP diluted EPS measures do not include the tax effect of the aforementioned adjusting items, due to the nature of these items and the Company’s tax strategy.

Adjusted EBITDA is a non-GAAP unaudited measure, which we define as net income (loss) attributable to Xcel Brands, Inc. stockholders before interest and finance expenses, accretion of lease liability for exited leases, income taxes, other state and local franchise taxes, depreciation and amortization, income (loss) from equity method investments, asset impairment charges, stock-based compensation and cost of licensee warrants, and costs associated with restructuring of operations. Costs associated with restructuring of operations include operating losses generated by certain of our businesses that have been restructured or discontinued (i.e., wholesale apparel and fine jewelry), as well as non-cash charges associated with the restructuring of certain contractual arrangements.

Management uses non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA as measures of operating performance to assist in comparing performance from period to period on a consistent basis and to identify business trends relating to our results of operations. Management believes non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA are also useful because these measures adjust for certain costs and other events that management believes are not representative of our core business operating results, and thus these non-GAAP measures provide supplemental information to assist investors in evaluating our financial results.

Non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA should not be considered in isolation or as alternatives to net income, earnings per share, or any other measure of financial performance calculated and presented in accordance with GAAP. Given that non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA are financial measures not deemed to be in accordance with GAAP and are susceptible to varying calculations, our non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA may not be comparable to similarly titled measures of other companies, including companies in our industry, because other companies may calculate these measures in a different manner than we do. In evaluating non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA, you should be aware that in the future we may or may not incur expenses similar to some of the adjustments in this document. Our presentation of non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA does not imply that our future results will be unaffected by these expenses or any unusual or non-recurring items. When evaluating our performance, you should consider non-GAAP net income, non-GAAP diluted EPS, and Adjusted EBITDA alongside other financial performance measures, including our net income and other GAAP results, and not rely on any single financial measure.

View full release here.

Source: Xcel Brands, Inc
Snail (SNAL) – Setting the Stage for a Stronger Second Half


Wednesday, August 12, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q2 Results Were Soft, Ahead of a Busier Second Half. Second quarter revenue declined to $19.7 million from $22.2 million, while bookings decreased to $21.8 million from $27.1 million, and EBITDA was a $3.0 million loss versus a $2.4 million loss in the prior-year period. Despite the softer quarter, first-half revenue increased 11.1% to $47.0 million, while EBITDA improved to a loss of $0.6 million from a loss of $5.8 million. 

Second-Half Setup Improves Following Major ARK Content Releases. Shortly after quarter-end, Snail released Tides of Fortune, Genesis Part 1 Ascended, and Dragontopia, establishing a more active content cadence for the remainder of 2026. Management believes the broader ARK slate through 2027 provides a strong foundation for improved monetization and revenue visibility. 


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

July CPI Report Preview: Inflation Expected to Ease to 3.4% as Fed Weighs a September Rate Hike

What the July CPI Report Is Expected to Show

New inflation data due out Wednesday is expected to show consumer prices rising 3.4% year over year in July, according to economists surveyed by Bloomberg, a slight improvement from June’s 3.5% annual increase. On a monthly basis, economists expect prices to rise just 0.1% from June, when the Consumer Price Index posted a surprise 0.4% monthly decline.

Core inflation, which strips out volatile food and energy costs and is the measure the Federal Reserve watches most closely, is expected to come in at 2.5% year over year and 0.2% month over month. Both figures would represent continued, if gradual, progress toward the Fed’s 2% inflation target, even as the overall trajectory remains well above where policymakers want it.

Why Energy Prices Complicate the Inflation Picture

The July reading arrives against a genuinely unusual backdrop. Energy prices rose over the course of the month after the ceasefire between the United States and Iran broke down and oil prices moved higher in response. Despite that renewed volatility, gasoline prices at the pump remained slightly lower on average in July than they were in June, according to data from the US Energy Information Administration.

That divergence between crude oil price movement and retail gasoline prices reflects the lag between wholesale energy costs and what consumers actually pay at the pump, and it is one reason economists still expect the headline CPI figure to show only modest sequential price growth despite the renewed geopolitical volatility.

What a Hot Inflation Print Would Mean for the September Fed Meeting

The stakes attached to Wednesday’s release extend well beyond the number itself. A hotter-than-expected inflation reading would likely push a divided Federal Reserve toward raising interest rates at its September meeting, even as other parts of the economy show signs of cooling. That tension is precisely what makes this month’s data release so consequential. The Fed is currently navigating contradictory signals: inflation readings remain well above target, while the labor market has shown genuine weakness, with the July jobs report showing the US economy shed 23,000 jobs, far short of what economists had expected.

As of this week, traders are pricing in roughly 50-50 odds of a 25 basis point rate hike at the Fed’s September meeting, according to CME FedWatch data, reflecting just how finely balanced the policy decision has become.

What the July CPI Report Means for Small Cap Investors

For companies operating below the $2 billion market cap threshold, Wednesday’s inflation data carries direct implications for the cost of capital heading into the fall. Small and microcap companies typically carry more variable-rate debt than their large cap counterparts, making them more sensitive to shifts in rate expectations than almost any other segment of the market.

A cooler-than-expected CPI print would strengthen the case for the Fed to hold steady in September, providing meaningful relief for smaller, more leveraged companies. A hotter print, particularly one showing energy-driven price pressure spreading into core categories, would sharpen the odds of a rate hike and extend the higher-cost-of-capital environment that has weighed on small cap valuations throughout much of this year. Either way, Wednesday’s release is one of the most consequential data points small cap investors will see before the Fed’s September decision.

Release – Xcel Brands to Host Second Quarter 2026 Earnings Call on August 14, 2026

Primary Logo

Research News and Market Data on XELB

August 11, 2026 at 4:00 PM EDT

PDF Version

NEW YORK, Aug. 11, 2026 (GLOBE NEWSWIRE) — Xcel Brands, Inc. (NASDAQ: XELB) (“Xcel” or the “Company”), today announced that it will report its second quarter 2026 financial results on August 13, 2026. The Company will hold a conference call with the investment community on August 14, 2026, at 9:30 a.m. ET.

A webcast of the conference call will be available live on the Investor Relations section of Xcel’s website at https://xcelbrands.co/pages/events-and-presentations or directly at https://edge.media-server.com/mmc/p/p3z3y7nz

Interested parties unable to access the conference call via the webcast may dial 800-715-9871 or 646-307-1963 and use the Conference ID 4300396. A replay of the webcast will be available on Xcel’s website.

About Xcel Brands

Xcel Brands, Inc. (NASDAQ: XELB) is a media and consumer products company engaged in the design, licensing, marketing, live streaming, and social commerce sales of branded apparel, footwear, accessories, fine jewelry, home goods and other consumer products, and the acquisition of dynamic consumer lifestyle brands. Xcel was founded in 2011 with a vision to reimagine shopping, entertainment, and social media as social commerce. Xcel owns the Halston and C. Wonder brands, as well as the co-branded collaboration brands Tower Hill by Christie Brinkley, Trust. Respect. Love by Cesar Millan, GemmaMade by Gemma Stafford and Off/Duty by Coco Rocha brand and holds noncontrolling interests or long-term license agreement in Mesa Mia by Jenny Martinez. Xcel also owns and manages the Longaberger by Shannon Doherty brand through its controlling interest in Longaberger Licensing, LLC. Xcel is pioneering a modern consumer products sales strategy which includes the promotion and sale of products under its brands through interactive television, digital live-stream shopping, social commerce, brick-and-mortar retailers, and e-commerce channels to be everywhere its customer’s shop. The company’s previously owned and current brands have generated more than $5 billion in retail sales via livestreaming in interactive television and digital channels alone and has over 20,000 hours of content production time in live-stream and social commerce. The brand portfolio reaches more than 46 million social media followers with broadcast reaching 200 million households. Headquartered in New York City, Xcel Brands is led by an executive team with significant live streaming, production, merchandising, design, marketing, retailing, and licensing experience, and a proven track record of success in elevating branded consumer products companies. For more information, visit www.xcelbrands.com.

For further information please contact:

Seth Burroughs
Xcel Brands
[email protected]

Primary Logo

The Beachbody Company (BODI) – Finding Its Footing in Retail


Tuesday, August 11, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Another profitable quarter. Q2 revenue of $49.6 million exceeded the midpoint of guidance, while adjusted EBITDA of $6.7 million exceeded the high end and marked the company’s 11th consecutive quarter of positive adjusted EBITDA. While revenues were in line, the company exceeded our $4.5 million adj. EBITDA estimate. 

Retail traction encouraging. Shakeology distribution expanded to 131 Sprouts stores, with early reorders supporting favorable sell-through, while the company recently launched in 481 Vitamin Shoppe locations. Approximately 12 additional retail decisions are expected between mid-September and late November.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Back-to-School and the Stock Market: Is There Really a September Effect?

Every August, the same scene plays out: parents load up shopping carts with notebooks and sneakers, and almost like clockwork the stock market starts to wobble. Investors call this the “September Effect,” and it’s one of the most searched market patterns every fall. So is there really a connection between back-to-school season and the stock market? Here’s what the data says.

Is September Really the Worst Month for the Stock Market?

Since 1928, the S&P 500 has averaged a return of roughly -1.1% in September, by far the worst of any month on the calendar, and the only month with a meaningfully negative long-run average. August and September together have been the weakest back-to-back stretch since 1945. The index has closed lower in September more than half the time since 1928, no other month drops that often.

This year, back-to-school spending is bigger than ever. The National Retail Federation projects total 2026 back-to-school spending, kindergarten through college, will hit $146.8 billion, up from $128.2 billion in 2025, with college spending crossing $100 billion for the first time. So does all that retail activity actually move the market? Not directly, but the timing overlap is too consistent to ignore.

Why Does the Stock Market Drop in September? 3 Theories

1. Traders come back from summer vacation. The most credible explanation has nothing to do with school supplies and everything to do with vacation schedules. Trading volume and volatility run low through the summer as fund managers and everyday investors take time off. When everyone returns after Labor Day, that quiet gives way to a concentrated wave of rebalancing, all landing in the same few weeks.

2. Household spending shifts to essentials. As families shift spending toward school supplies and tuition, discretionary spending elsewhere slows, and consumer routines reset to budget-conscious mode. Some analysts argue that shift filters into earnings expectations right as September begins. It’s a compelling theory, but worth being honest about, it’s a theory, not a proven cause.

3. Mutual funds “window dress” before fiscal year-end. Many mutual funds close their fiscal year on September 30th, and beforehand, managers often trim losers and buy winners to make year-end portfolios look better, a practice known as “window dressing.” That selling pressure adds to September weakness for reasons that have nothing to do with backpacks or lunchboxes.

Does the September Effect Actually Predict Market Crashes?

Not on its own. Some of September’s worst historical drops happened during bear markets already underway for entirely unrelated reasons, the Great Depression, the dot-com crash, the 2008 financial crisis. The calendar didn’t cause those crashes; it just happened to be the backdrop. When the broader market has strong momentum heading into September, the seasonal weakness has historically shown up far less, if at all.

Should You Change Your Investing Strategy for September?

The back-to-school season and stock market weakness share a calendar and a shift in investor psychology, but the relationship is a tendency, not a rule. The smarter takeaway isn’t to sell in August and buy back in October. It’s to recognize seasonal patterns are noise layered on top of the real drivers: economic data, interest rates, and corporate earnings, and to stay invested through the noise rather than trying to trade around it.

This September, as retailers report record back-to-school numbers, the real story to watch isn’t the calendar. It’s what that spending says about the health of the consumer, because that, unlike seasonality, actually moves markets.

Nielsen’s $2.15 Billion DoubleVerify Deal: A 30% Premium That Still Locks In a Loss

Nielsen is buying DoubleVerify for $13.60 a share in cash — a 30% premium, the press release says. That premium is real. It’s also about half of what DoubleVerify’s stock fetched the day it went public. Both things are true at once, and the gap between them is the most instructive part of this deal.

Here’s what happened. On Wednesday, Nielsen — itself taken private by a private equity consortium a few years back — agreed to acquire DoubleVerify (NYSE: DV) in an all-cash deal worth roughly $2.15 billion in enterprise value. Shareholders get $13.60 per share, a 30% premium to the stock’s 60-trading-day average through August 5. The deal should close by the first quarter of 2027, after which DoubleVerify delists from the NYSE, becomes a private company under Nielsen, and keeps its name. Providence Equity, which owns about 12%, has agreed to vote in favor.

DoubleVerify isn’t a broken company — and that’s the point. It’s the leading independent platform for ad verification: the plumbing that confirms a digital ad impression was actually seen by a real person, in a brand-safe place, free of fraud. It’s accredited, embedded in the workflows of the world’s biggest advertisers, and it works — 2025 revenue landed around $748 million, up roughly 14%, with real profit and strong free cash flow. A healthy, growing, cash-generative business.

So why is it being bought at $13.60?

Because the market stopped paying up for it. DoubleVerify went public in April 2021 at $27 a share and ran to nearly $47 within months, briefly worth more than $5 billion. Then ad-tech multiples collapsed. Even as the company kept growing revenue and profit year after year, the stock got cut in half, then cut again, bottoming below $8 last year. The business went up and to the right; the multiple went down and to the left. By this week the whole company was worth under $2 billion — less than half its peak value, despite being bigger and more profitable than it was then.

That’s the lesson for anyone hunting the small end of the market. A 30% premium sounds generous until you notice it’s measured off a badly depressed base. IPO buyers are being cashed out at roughly half their money; anyone who chased the 2021 hype is down far more. The premium is genuine against last month’s price — and a permanent loss against the promise the stock once carried.

It also explains the take-private wave we’ve watched all week. When public markets abandon a profitable company and refuse to re-rate it no matter how well it executes, someone with a longer horizon eventually buys the cash flows on the cheap. That’s exactly what Nielsen is doing — and it’s the same logic behind deal after deal in 2026: good small and mid-cap businesses quietly pulled off the public market at prices that reflect the market’s indifference, not the company’s quality.

For DoubleVerify shareholders, it’s a bittersweet exit — a premium today that locks in yesterday’s de-rating. For everyone else, it’s a map. The hunting ground right now is full of profitable, overlooked small-caps trading far below what they’re worth to a patient owner. And the public market keeps losing them, one deal at a time.

Release – BODi Announces Second Amendment to Credit Facility

Placeholder Company

Research News and Market Data on BODI

August 6, 2026

EL SEGUNDO, Calif.–(BUSINESS WIRE)– The Beachbody Company, Inc. (NASDAQ: BODI) (“BODi” or the “Company”), the proactive wellness company delivering nutrition, supplements, and proven fitness programs that help people take control of their health inside and out, today announced it has entered into a second amendment to its credit agreement with Tiger Finance, LLC, as administrative agent and collateral agent. This modification continues to enhance the Company’s financial flexibility through amended covenant terms.

The amendment further streamlines the financial covenant structure, eliminates the billings fixed charge coverage ratio covenant, and adjusts certain other financial covenants, including the minimum digital subscriptions level and the Three Month Total Billings Target. The amended covenants for the Three Month Total Billings target and the minimum Digital Subscriptions level will not be tested if the Company’s cash balance is above $22.5 million. The second amendment reduced the cash balance required to not test these two covenants by approximately $7 million as of the date of the second amendment. The Company must maintain a minimum liquidity level of $18 million, which will decrease by approximately $0.2 million monthly beginning March 1, 2027 to $16 million.

Mark Goldston, Executive Chairman of The Beachbody Company, commented, “We continue to value our relationship with Tiger Finance as a creative, resourceful and supportive partner to BODi. This amendment gives us additional flexibility to execute on our growth strategies as we build on the progress we’ve made in 2026.”

Carl Daikeler, Co-Founder and Chief Executive Officer added: “This amendment reflects the continued strengthening of our balance sheet and supports our ability to invest in growth, including our nutrition and retail initiatives, without compromising the financial discipline that has defined our turnaround.”

The Company’s cash position of $36.6 million on March 31, 2026, exceeded its $23.6 million debt level by $13.0 million. This strong financial position demonstrates the success of its financial transformation and positions BODi for its planned growth initiatives in 2026.

About BODi and The Beachbody Company, Inc.

BODi is the proactive wellness company delivering nutrition, supplements and proven fitness programs that help people take control of their health inside and out. With nearly three decades of experience, BODi, formerly Beachbody, has evolved from a leader in home fitness into a comprehensive health and fitness ecosystem designed to help people achieve their goals and lead healthier, more fulfilling lives. Anchored by science-backed nutrition solutions like Shakeology and supported by its portfolio of proven fitness and habit-building programs, including P90X and INSANITY, BODi is creating a more accessible and effective path to long-term health.

Since its inception, BODi has supported more than 30 million customers in achieving lasting results. The company continues to innovate across nutrition and digital fitness to deliver simple, proven solutions for modern lifestyles.

To subscribe and shop, visit BODi.com. For company and investor information, please visit TheBeachbodyCompany.com.

Investor Relations
[email protected]

Source: The Beachbody Company, Inc.

Release – BODi Expands Retail Presence with Shakeology Now Available at The Vitamin Shoppe Nationwide; Launches New Flavor

Placeholder Company

Research News and Market Data on BODI

August 6, 2026

Brings healthy daily protein and superfood nutrition to nearly 500 locations with the retail debut of Vanilla Whey, now with zero grams of added sugar

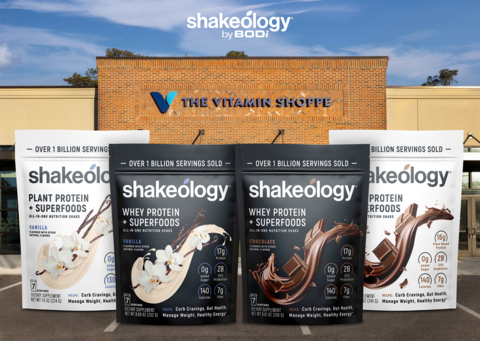
EL SEGUNDO, Calif.–(BUSINESS WIRE)– BODi (NASDAQ: BODI), the proactive wellness company delivering nutrition, supplements, and proven fitness programs that help people take control of their health inside and out, today announced that Shakeology is now available at The Vitamin Shoppe locations nationwide. The Vitamin Shoppe launch reinforces BODi’s commitment to making science-backed wellness more accessible to consumers across the U.S. The retail rollout includes the core flavors of Shakeology’s 0g Added Sugar line: Chocolate Vegan, Chocolate Whey, Vanilla Vegan, and the new, reformulated Vanilla Whey, all available in a convenient 7-serving bag.

BODi expands its retail presence with Shakeology now available at The Vitamin Shoppe nationwide.

BODi expands its retail presence with Shakeology now available at The Vitamin Shoppe nationwide.

Originally launched in 2009 with over a billion servings sold, Shakeology combines high-quality protein with fiber, prebiotics and probiotics, vitamins, minerals, digestive enzymes, adaptogens, antioxidants, greens, and more than 30 superfoods to help support energy, gut health, digestion and regularity, lean muscle, bone health, as well as a healthy immune system. It also helps protect against free radicals and oxidative stress, reduce cravings, and support weight loss, as demonstrated in a clinical study published in the Journal of Nutrition.

Consumers also report meaningful benefits from making Shakeology part of their daily routine. Based on a survey of Shakeology customers*:

  • 86% reported better digestion after one month
  • 84% said it helped reduce junk food cravings
  • 81% said it helped them feel full until their next meal
  • 74% reported increased energy throughout the day

“When we announced our partnership with The Vitamin Shoppe earlier this year, our goal was to make Shakeology more accessible than ever before,” said Carl Daikeler, co-founder and CEO of BODi. “Today, consumers can walk into stores nationwide and purchase Shakeology. Combined with the introduction of Vanilla Whey with zero grams of added sugar launching in retail for the first time, this represents another important step in bringing healthy, science-backed nutrition to more people.”

To locate the nearest The Vitamin Shoppe location, visit https://locations.vitaminshoppe.com. Shakeology is also available at more than 100 Sprouts Farmers Market locations nationwide. BODi continues to expand retail distribution through its strategic partnership with KeHE Distributors, whose network reaches more than 30,000 grocery, supermarket, natural, and online retail locations.

Consumers can also shop the full Shakeology line on BODi.com, including additional flavors such as 0g Added Sugar Café Latte, Cookies & Creamy, and Tropical Strawberry, as well as 14- and 30-serving bags.

*Based on a survey of 1,550 Shakeology customers who consumed Shakeology five or more times per week and exercised three times per week. Better digestion improvement based on 859 Shakeology customers who reported issues with digestion.

About BODi and The Beachbody Company

BODi is a proactive wellness company delivering nutrition, supplements and proven fitness programs that help people take control of their health inside and out. With nearly three decades of experience, BODi, formerly Beachbody, has evolved from a leader in home fitness into a comprehensive health and fitness ecosystem designed to help people achieve their goals and lead healthier, more fulfilling lives. Anchored by science-backed nutrition solutions like Shakeology and supported by its portfolio of proven fitness and habit-building programs, including P90X and INSANITY, BODi is creating a more accessible and effective path to long-term health.

Since its inception, BODi has supported more than 30 million customers in achieving lasting results. The company continues to innovate across nutrition and digital fitness to deliver simple, proven solutions for modern lifestyles.

To subscribe and shop, visit BODi.com. For company and investor information, please visit TheBeachbodyCompany.com.

About The Vitamin Shoppe®

The Vitamin Shoppe® is an omnichannel specialty retailer and wellness lifestyle company with the mission to provide customers with the most trusted products, guidance, and services that support health and performance in every stage of life. Founded in 1977 and headquartered in Secaucus, New Jersey, The Vitamin Shoppe today is an innovation-focused destination for first-to-market brands and breakthrough products, offering a comprehensive assortment of vitamins, supplements, sports nutrition, and on-the-go functional foods and beverages. Beyond hundreds of national brands, its offering includes the proprietary brands The Vitamin Shoppe®, Vthrive The Vitamin Shoppe®, BodyTech®, BodyTech® Elite, plnt®, ProBioCare®, and True Athlete®. The Company serves customers through more than 640 stores nationwide, providing personalized support from knowledgeable Health Enthusiast associates, and online at www.vitaminshoppe.com. It operates strategic partnerships in select international markets in Asia, South America, Central America, and the Caribbean. The Vitamin Shoppe proudly supports the health and wellness of communities through longstanding partnerships with Vitamin Angels and Team Red, White & Blue.

Media Relations:
[email protected]

Investor Relations:
[email protected]

Source: BODi