Alliance Entertainment Holding (AENT) – Building A Higher-Margin Entertainment Platform


Tuesday, October 06, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Noble Virtual Conference Highlights. On October 1, 2026, Bruce Ogilvie, Executive Chairman of Alliance Entertainment, presented at Noble’s October Virtual Emerging Growth Conference. The presentation highlighted an optimistic outlook for fiscal 2027 and opportunities to expand margins through licensing, collectibles, authentication, and fulfillment. A replay is available here.

Favorable revenue and margin expansion outlook. Management expects continued revenue growth and margin expansion in fiscal 2027, supported by continued demand for physical media products and a full year of the company’s high-margin licensing deal with Amazon MGM. Additionally, the company’s return to direct movie sales to Walmart eliminates third-party intermediary fees and restores access to supply chain financing, supporting faster cash collection and higher margins. Management expects the full benefit to become more apparent in fiscal Q2.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

US Trade Deficit Jumps Above $100 Billion as Oil and Gold Imports Surge

The US trade deficit jumped to $105.6 billion in August, a 13.8% increase from July’s revised $92.8 billion and the widest gap since early 2025, the Commerce Department reported Tuesday. Imports rose 4.3% to $420.8 billion, while exports rose just 1.4% to $315.2 billion.

The timing is notable. August was the first month after a new phase of tariffs took effect in late July, including a 10% tariff on top allies such as the European Union and a 12.5% tariff on other nations, including China. Importers also kept bringing in components for AI data centers. Semiconductor imports rose $2.4 billion, though computer accessory imports fell $1.6 billion, leaving overall AI-related imports little changed from July but still elevated.

A more significant driver was industrial supplies. Crude oil imports jumped $3.3 billion and nonmonetary gold imports rose $3.1 billion. The oil figure comes as crude prices have stayed elevated through the Iran conflict, and the gold figure arrives in a year when precious metals have rallied. The surge in goods imports lifted the goods deficit to $136.6 billion, while the services surplus stayed essentially flat.

Mexico remained the largest deficit at $27.7 billion. The gap with Canada widened by $4.1 billion to $7.1 billion in the month talks between the two countries collapsed and new 50% tariffs took effect, a dispute in which crude oil was left out of the tariffs. The deficit with China rose to $16.4 billion from $15.2 billion in July. That was before a visit by Chinese President Xi Jinping, which extended the current trade truce by two months, set a new early 2027 deadline for talks, and produced tariff cuts on an estimated $60 billion worth of goods.

The widening gap matters for growth. One forecasting firm said the jump in imports suggests third-quarter GDP growth will come in well below its 4.0% forecast, possibly closer to 2.5%, noting that the rise in goods imports was broad-based and left net trade as a drag overall. Imports subtract from GDP in the national accounts, so a surge can lower headline growth even when it reflects strong demand.

The next trade report will show whether August’s jump was a one-month surge or the start of a new run higher, and the early 2027 China deadline sets the next hard date for trade policy. Until then, a deficit above $100 billion suggests demand for imported goods remains strong even with higher tariffs in place.

For small and microcap investors, the report is a reminder that trade policy remains a live cost variable. Smaller manufacturers and importers have less room than multinationals to absorb tariff-driven input costs or reroute supply chains, though the extended China truce and announced tariff cuts offer some relief. Russell 2000 companies earn most of their revenue at home, so growth data matter as much as trade headlines, and a third-quarter GDP reading nearer 2.5% than 4.0% would feed into how investors read the Fed’s path after September’s rate hike.

Amazon Just Hit Its Lowest Valuation Ever as a Public Company

Amazon (Nasdaq: AMZN) is being left out of the renewed rush into AI stocks. At about $251 a share, the stock trades at roughly 20 times trailing earnings, its lowest valuation ever as a public company, and it is down about 2.4% over the past month. The move comes just two months after Amazon crossed $3 trillion in market value on the strength of its cloud business.

The contrast with other AI names is sharp. Nvidia is trading at a record high, and AMD just set a record of its own. Meta shares have surged 23% in the past month on enthusiasm for its Muse AI agent, while Microsoft and Alphabet have posted modest gains. Among the Magnificent Seven, only Alphabet screens cheaper than Amazon.

Two issues appear to be holding the stock back. The first is legal. In early September, the Federal Trade Commission and 22 states sued Amazon, alleging its advertising practices overcharged roughly 1.2 million advertisers by about $20 billion between 2019 and today. The agency says Amazon did not disclose reserve-pricing mechanisms that raised costs for advertisers and consumers. Amazon says advertisers are getting greater value from its platform. These are allegations, not findings, but investors are wary that advertising, one of Amazon’s most profitable businesses, could become less lucrative.

The second issue is spending. Amazon’s second-quarter report raised its 2026 capital expenditure plan to approximately $220 billion. One Wall Street estimate now puts 2027 capex at $320 billion and 2028 at $370 billion, which would push free cash flow to roughly negative $50 billion in each of those years. Those are outside estimates, not company guidance. In August, the stock jumped more than 15% in a single session because AWS growth appeared to justify the spending. Now attention is shifting to how much cash the buildout consumes, the same debate that has weighed on Oracle and other heavy AI spenders.

A low multiple is not automatically a bargain. The bull case rests on AWS, which posted $42.2 billion in quarterly revenue, up 36.7% from a year earlier, with a contracted backlog of $496 billion and management saying demand still outstrips available server capacity. The bear case rests on litigation risk, rising capital intensity, and the possibility that free cash flow stays negative for years. The valuation simply shows which argument investors currently find more persuasive.

For small and microcap investors, the lesson is that even the world’s largest companies are priced on narrative as much as fundamentals. Capital is flowing toward stocks tied to the AI storyline while discounting those carrying heavy spending or regulatory overhang. Smaller suppliers of power, cooling, and components into data center buildouts benefit from Amazon’s spending whether or not its stock rewards it, but they also depend on that spending continuing if its cash flow tightens. Valuation gaps like this one are also a reminder that investor attention can leave fundamentally strong companies undervalued, something smaller companies experience more often than most.

Gate Bioscience Expands Its Lilly Deal to More Than $870 Million, Adding a New Drug Target

Gate Bioscience, a privately held drug discovery company, announced Monday that it has expanded its research and licensing agreement with Eli Lilly (NYSE: LLY) in a deal now potentially worth more than $870 million. The original agreement, announced in July 2025, was worth up to $856 million. The expansion adds one drug target, with an option to add a second.

Gate will receive an upfront payment and research funding for the added target, plus an additional payment if the second target is selected. Neither company disclosed the size of the upfront payment. Gate is also eligible for milestone payments and royalties on global sales of any products that result.

The science behind the partnership takes a different approach to disease. Gate uses its platform to discover oral small-molecule drugs designed to eliminate proteins that have been difficult to target with existing medicines. Many conventional drugs work by blocking a protein’s activity, but some disease-driving proteins offer no good place for a drug to bind. A drug built to remove the protein altogether can reach targets once considered out of reach.

The two companies have split the work along familiar lines. Gate leads discovery, while Lilly takes over late-stage preclinical and clinical development, manufacturing, and commercialization. Lilly holds exclusive worldwide rights to products developed against the selected targets.

The deal fits a pattern in Lilly’s strategy this year. The company has acquired Merida Biosciences, which is developing biologics that eliminate disease-causing autoantibodies, and AtaiBeckley, a clinical-stage mental health company, while also signing earlier-stage platform partnerships like this one. Buying finished assets and renting promising discovery engines are two ways of filling the same pipeline.

The headline number deserves context. The expansion lifts the potential value by only about $14 million over the original agreement, which shows how these figures work. Partnership values are usually quoted at their maximum, with most of the money tied to development and sales milestones that may never be paid. The undisclosed upfront payment is the figure that actually reaches the company’s balance sheet.

The same partnership playbook is open to smaller companies pursuing oral small-molecule medicines. Cocrystal Pharma, which uses a structure-based discovery platform to develop antiviral drugs, and Cardiff Oncology, whose lead candidate onvansertib is an oral small molecule being studied in colorectal cancer, work in different therapeutic areas than Gate, and neither focuses on protein elimination. But both illustrate the model investors are watching: a differentiated discovery approach or oral drug candidate that could eventually attract a larger development partner.

For investors tracking small and microcap biotech, the takeaway cuts both ways. Large pharma remains willing to sign collaborations worth hundreds of millions of dollars with private platform companies before any drug reaches the clinic, a sign of continued appetite for differentiated discovery technology. But a platform deal is not an approved product. The upfront cash, the pace of milestone payments, and whether the partner keeps selecting targets matter most, and investors weighing smaller developers with similar partnership ambitions should read the fine print on all three.

Vince Holding Corp. (VNCE) – OVO Growth Roadmap Comes Into Focus


Monday, October 05, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Insights From Noble’s Emerging Growth Conference. We recently hosted Vince Holding Corp. CEO Brendan Hoffman and CFO Yuji Okumura for a fireside chat at Noble Capital Markets’ Emerging Growth Virtual Equity Conference. The discussion provided additional insight into the strength of the core Vince business and, importantly, management’s strategy to leverage its operating platform to accelerate growth at the recently acquired OVO business. Click here to view the presentation. Vince participated in the conference on October 2.

Core Vince Momentum Remains Healthy. We believe the underlying Vince business remains on solid footing, supported by strength across both direct-to-consumer and wholesale. Second-quarter revenue rose 11.7% to $81.8 million, with DTC up 13.7% and wholesale up 10.4%, providing a solid foundation as management begins integrating OVO.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Star Equity Holdings, Inc. (STRR) – Noble October Virtual Conference


Monday, October 05, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Noble Virtual Conference. Star Equity CEO Jeff Eberwein presented at the Noble Virtual Conference. Highlights included the Harte Hanks proposed acquisition, efforts to monetize non-cash-flowing assets, and future financial goals.  A rebroadcast is available at https://www.channelchek.com/videos/star-equity-holdings-strr-noble-capital-markets-virtual-conference-replay-october-2026.

Harte Hanks. Harte Hanks has completed its go-shop period, and while other proposals were received, the Harte Hanks Board has not determined that any proposal constitutes a Superior Proposal to the Star proposal. Mr. Eberwein noted that both companies are moving forward to complete the announced deal, hopefully by year-end.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

SKYX Platforms (SKYX) – Noble October Virtual Conference


Monday, October 05, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Noble Virtual Conference. SKYX Platforms CEO Leonard Sokolow presented at the Noble Virtual Conference. Highlights included the Deako acquisition, development agreements, and product introductions.  A rebroadcast is available at https://www.channelchek.com/videos/skyx-platforms-corp-skyx-noble-capital-markets-virtual-conference-replay-october-2026.

Deako Acquisition. Management does expect cost synergies, but the larger piece of the pie, in our view, is the ability to provide an A-to-Z solution across the electronic real estate of homes, buildings, and hotels, where power, control, sensing, and AI intelligence will reside. The combination will put SKYX at the forefront of data sharing in smart home systems, opening multiple high-margin revenue opportunities, in our opinion.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Sky Harbour Group (SKYH) – Noble October Virtual Conference.


Monday, October 05, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Noble Virtual Conference. Sky Harbour Senior Vice President Tim Herr presented at the Noble Virtual Conference. Highlights included macro tailwinds, client mix, and long-term goals. A rebroadcast is available at https://www.channelchek.com/videos/sky-harbour-skyh-noble-capital-markets-virtual-conference-replay-october-2026.

Macro Tailwinds. The total square footage of the aviation fleet continues to increase, driven by an increased number of aircraft operating-driven by both business and consumer demand-and the increasing size of the aircraft fleet. U.S. Business-Class total square footage, Sky Harbour’s target market, has risen by 73% over the past 15 years. On the supply side, no new major airports have been built since the early 1990s. The available land at or surrounding airports continues to shrink.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

NN (NNBR) – Another Milestone In Cleaning Up The Capital Structure


Monday, October 05, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Capital Structure. On Friday, NN  announced it had entered into a securities purchase agreement for a private investment in public equity financing (PIPE) that is expected to result in net proceeds of approximately $50 million. A majority of the proceeds will be used to eliminate the outstanding Series D preferred stock. NNBR shares rose 24% on the news, closing at $4.51. We view Friday’s announcement positively, placing NN in a much stronger financial position to pursue extensive growth opportunities.

Details. NN will issue an aggregate of 16.1 million shares of common stock (or prefunded warrants in lieu thereof) at a price of $3.30 per share (or $3.29 per pre-funded warrant). Each pre-funded warrant has an exercise price of $0.01 per share of common stock and will be immediately exercisable. There are 10 investors making this investment, a mix of existing shareholders and new shareholders. The deal was significantly oversubscribed. The deal is expected to close on October 5th.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

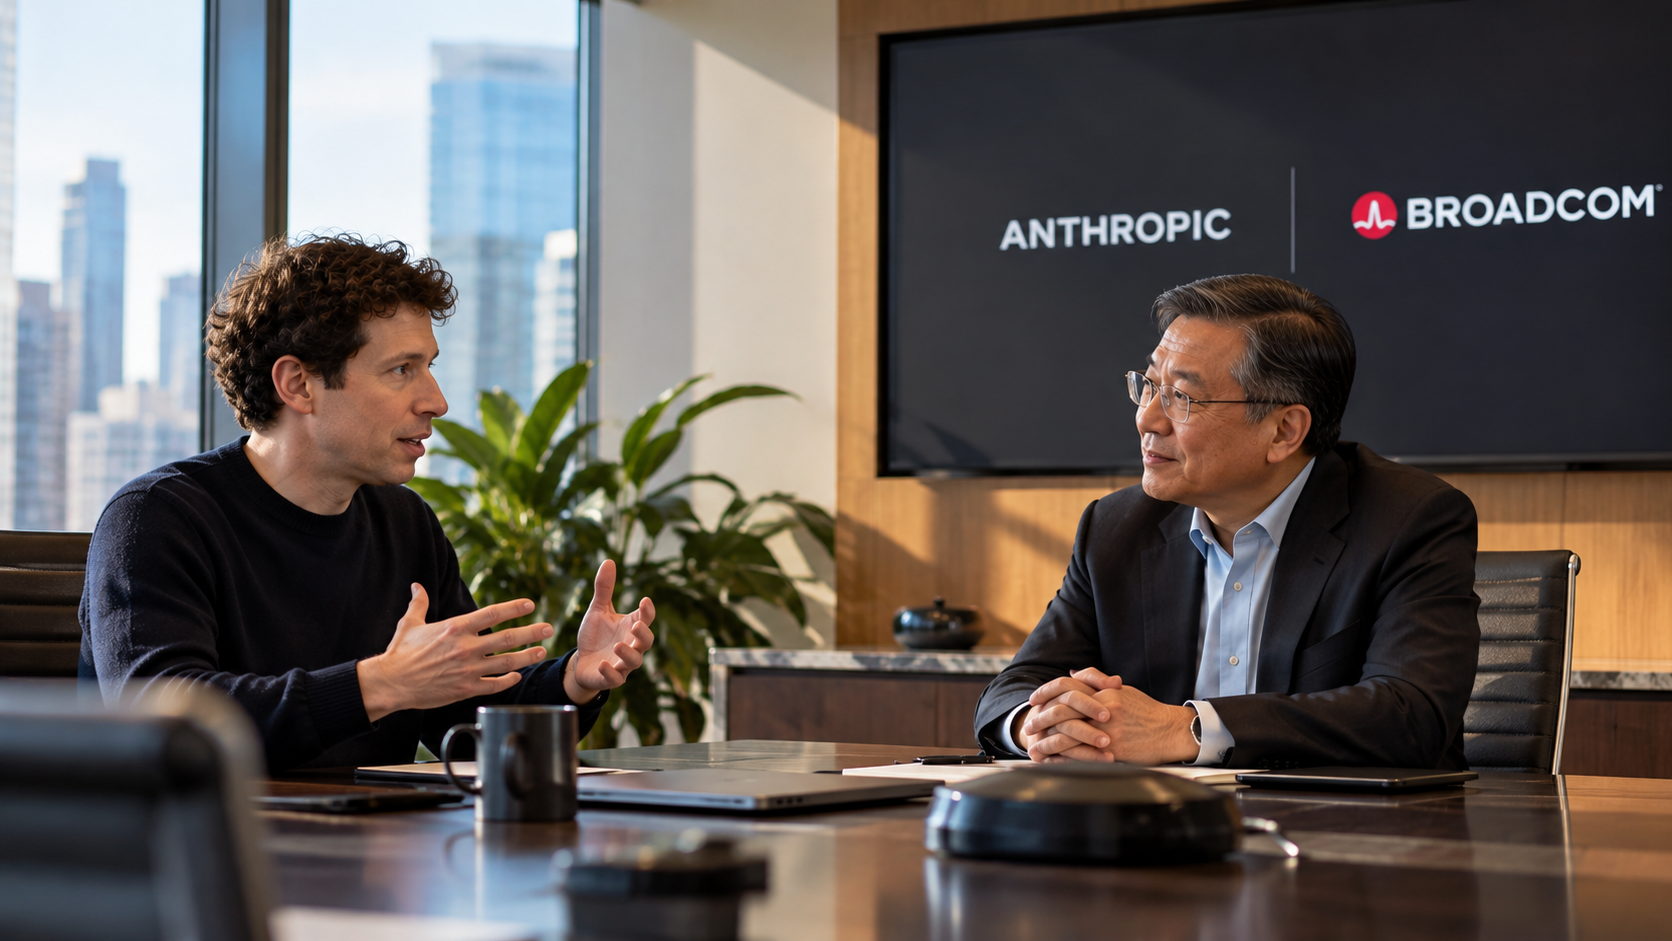
Broadcom Will Lend Anthropic Up to $42 Billion. It’s the Third Big Tech Company Doing This

Anthropic’s confidential IPO prospectus, obtained by Reuters, reveals that Broadcom has agreed to lend the AI company up to $42 billion to help fund its infrastructure buildout. The arrangement makes Broadcom the third major technology company, following Amazon and Microsoft, to both finance and supply computing capacity to Anthropic simultaneously, a structure that has drawn mounting scrutiny across the AI industry over the past several months.

The concern is straightforward. Each of these companies provides capital to Anthropic, which Anthropic then uses to purchase computing services from that same company. Anthropic’s own spending with Broadcom is expected to grow so large that the AI lab will become Broadcom’s single largest compute customer by 2027. The relationship extends beyond simple chip purchases as well. Broadcom is also providing Anthropic with equipment leasing and financing arrangements, according to Reuters, deepening the financial interdependence between the two companies beyond a standard customer relationship.

This builds directly on a partnership announced in April, when Anthropic revealed a three-way arrangement with Broadcom and Google under which Google will supply its own Tensor Processing Unit capacity to Anthropic beginning in 2027. Broadcom, notably, is the company that designs Google’s TPUs, meaning Broadcom now sits on multiple sides of Anthropic’s compute supply chain simultaneously, as both a direct lender and as the designer of chips Anthropic will access through a separate cloud partner.

Broadcom is not acting in isolation here. Nvidia and AMD have each extended similar funding arrangements to their own major AI lab customers, including both OpenAI and Anthropic, with those labs then using the capital to pay for access to the same companies’ high-performance chips. The pattern has become common enough across the industry that it now has a name, circular financing, and it has become one of the more closely watched risk factors in the entire AI infrastructure buildout.

The systemic concern is what happens if any single link in that chain breaks. If one major AI lab or chip supplier in these circular arrangements were to stumble, whether through a funding shortfall, a demand slowdown, or a failure to meet compute obligations, the interconnected nature of these deals raises the risk of a chain reaction spreading across multiple companies at once, with implications extending well beyond the AI sector into the broader equity markets that have leaned heavily on AI-driven earnings growth over the past several years.

For investors tracking this space, the Broadcom-Anthropic arrangement is best understood as the latest data point in a theme we’ve tracked closely across several recent stories. Nvidia’s record $150 billion buyback expansion drew scrutiny partly because of circular financing concerns raised on its own earnings call. BlackRock’s $12.3 billion bond offering to fund Meta’s data center campus and CoreWeave’s aggressive capital expenditure guidance both reflect the same underlying dynamic, debt and vendor financing being used at massive scale to fund an AI buildout whose ultimate revenue payoff remains, in some cases, still unproven.

For investors in the small and microcap space, the direct read-through is more nuanced than it might first appear. Smaller companies supplying components, materials, and specialized hardware into this ecosystem benefit from the sheer scale of spending these arrangements represent, $42 billion from a single lender to a single customer is a genuinely enormous demand signal. But that same scale is precisely what makes the systemic risk real. A supply chain this interconnected and this reliant on vendor financing rather than organic cash flow is more fragile than the headline spending figures alone suggest, and investors evaluating smaller AI infrastructure suppliers should weigh that structural risk alongside the genuine demand opportunity it represents.

Flowco Closes $113 Million Acquisition of Lifting Solutions, Expanding Into Canada and the Middle East

Flowco Holdings (NYSE: FLOC), a provider of production optimization and artificial lift solutions for the oil and natural gas industry, announced Thursday it has closed its acquisition of Lifting Solutions Energy Services, a vertically integrated manufacturer of artificial lift technology headquartered in Edmonton, Alberta. Flowco paid approximately $113 million in cash based on a CAD/USD exchange rate of 0.71, funded through borrowings under its asset-based lending facility. The deal was structured on a cash-free, debt-free basis, and sellers are eligible for up to C$10 million in additional contingent consideration tied to Lifting Solutions’ 2027 financial performance, payable in early 2028.

Founded in 2014, Lifting Solutions specializes in continuous rod, a differentiated alternative to conventional rod lift strings, and progressing cavity pumps, both technologies used to extract oil from wells as they move into later stages of production. The company has developed proprietary rod coatings and pump technologies in-house, designed specifically to extend equipment run times and reduce the workover and lifting costs producers face over a well’s lifespan. Lifting Solutions serves customers across Canada, the United States, the Middle East, and other international markets.

Flowco’s leadership described the acquisition as broadening the company’s ability to serve customers throughout the entire life of a well, extending its artificial lift portfolio into later-life applications where continuous rod and progressing cavity pump technology are particularly well suited. Lifting Solutions’ founder framed the combination as bringing together two complementary businesses capable of supporting continued growth together that neither could achieve as easily independently. Beyond the technology itself, the deal gives Flowco a scaled Canadian operating platform and an established international presence, creating a foundation to accelerate growth across Canada, the Middle East, and other global markets, while opening cross-selling opportunities across both companies’ existing customer relationships. Flowco expects the transaction to be accretive to both earnings and free cash flow per share.

The acquisition arrives on the heels of a strong recent stretch for Flowco. The company reported second quarter 2026 revenue of $235.9 million, net income of $30.9 million, and adjusted EBITDA of $93.9 million, and has returned capital to shareholders through both a regular quarterly dividend and a special one-time dividend declared earlier this year.

For investors tracking the small and microcap energy services space, this deal continues a consolidation pattern we detailed closely when covering both Magnolia Oil and Gas’s acquisition of WildFire Energy and Enbridge’s purchase of Salt Creek Midstream’s gathering business earlier this year. As producers focus capital discipline on maximizing output from existing wells rather than aggressive new drilling, technology that extends well life and reduces lifting costs becomes increasingly valuable, and companies supplying that technology, including smaller independent producers that stand to benefit directly from lower operating costs on aging wells, remain well positioned in the current environment. Artificial lift and production optimization are not the flashiest corners of the energy sector, but they sit at the center of how operators extract maximum value from the wells they already have, a theme likely to remain relevant as capital discipline continues to define the industry.

Resolution Minerals Ltd (RML) – Horse Heaven Advances on Multiple Fronts


Thursday, October 01, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Horse Heaven takes center stage. In fiscal 2026, Resolution Minerals repositioned the company around its 100%-owned Horse Heaven Antimony-Tungsten-Gold-Silver Project in Idaho following its acquisition in July 2025. During the year, Resolution initiated and expanded drilling, made gold discoveries at Golden Gate North and South, advanced the high-grade Antimony Ridge system, acquired the Johnson Creek processing site and historical tungsten stockpiles, and initiated metallurgical programs across gold, antimony, and tungsten.

Golden Gate continues to expand. Following the June 30 fiscal year-end, Resolution completed its 2026 Golden Gate drilling program with 42 diamond holes totaling 12,236 meters. Recent assays from Golden Gate South extended the mineralized zone to approximately 600 meters in width and returned the highest gold grades reported to date at Horse Heaven, including one meter grading 14.8 g/t Au and 10.2 meters grading 1.83 g/t Au. Assays remained pending for 36 holes, providing a pipeline of additional results.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Kodiak Copper Corp. (KDKCF) – Kay Copper Advances


Thursday, October 01, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Transaction moves toward closing. Kodiak Copper has filed the initial TSX Venture Exchange listing application for Kay Copper and executed definitive agreements covering the combination of Kodiak’s Mohave project with Teck’s Copper Hill project in Arizona. The transaction is intended to create a well-funded, U.S.-focused copper explorer with two drill-ready porphyry projects. Completion is expected in October 2026, subject to TSX Venture Exchange (TSXV) acceptance and other customary closing conditions.

Financing is in place. In connection with the transaction, approximately C$5.37 million was raised through a subscription receipt financing at C$0.25 per receipt, in addition to an earlier C$830,000 financing. The proceeds are intended to fund exploration at Mohave and Copper Hill during 2026 and 2027. Following closing, Kodiak and Teck are each expected to own approximately 26.4% of Kay Copper.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.