U.S. Economy Adds 165,000 Jobs in October, Beating Expectations as Unemployment Falls to 4.1%

The U.S. labor market delivered a stronger-than-expected performance in October, adding 165,000 jobs and easing concerns about a prolonged hiring slowdown. The surprisingly strong employment report suggests the American economy remains resilient, although it also raises questions about the Federal Reserve’s next move on interest rates.

According to data released Friday by the Bureau of Labor Statistics, nonfarm payrolls increased by 165,000 in October, significantly exceeding economists’ expectations of approximately 65,000 jobs. The unemployment rate edged down from 4.2% in September to 4.1%, reinforcing signs of stability in the labor market.

The report represents a notable improvement from September, when employers added a revised 60,000 jobs. August’s employment figures were also revised higher, from 133,000 to 186,000, bringing the combined upward revisions for the previous two months to 84,000 jobs.

Hiring was particularly strong across professional and business services, healthcare, and transportation, suggesting that employment growth is extending into several important areas of the economy.

Professional and business services led the gains, adding 70,000 jobs during October. Healthcare and social assistance contributed approximately 55,100 positions, while transportation and warehousing added another 24,800 jobs.

Manufacturing also showed encouraging signs, adding 19,000 jobs, including gains in computer and electronic products, fabricated metals, and motor vehicles. The improvement could provide a positive signal for industrial companies and businesses supplying equipment and components to manufacturers.

However, the labor market remains uneven. Leisure and hospitality lost approximately 13,000 jobs, while wholesale trade employment declined by 9,100, demonstrating that not every sector is experiencing the same momentum.

Wage growth remained another important component of the report.

Average hourly earnings increased 0.4% in October to $38.00, representing a 3.1% increase over the past year. While higher wages support household purchasing power, continued wage growth could complicate efforts to bring inflation sustainably toward the Federal Reserve’s 2% target.

For investors, the stronger employment figures present both opportunities and challenges.

A resilient labor market can support consumer spending, business investment, and corporate earnings. Companies across retail, manufacturing, healthcare, and transportation may benefit if employment growth translates into sustained demand for goods and services.

Small-cap companies, many of which depend heavily on domestic economic activity, could be particularly sensitive to these developments.

A stronger economy can create opportunities for smaller businesses to expand operations, attract customers, and improve revenue growth. However, the interest-rate outlook remains an important consideration.

The Federal Reserve must balance supporting employment with maintaining price stability. Stronger hiring and wage growth could reduce the urgency for additional interest-rate cuts, potentially keeping borrowing costs elevated for longer.

That environment can be challenging for smaller companies that rely on bank loans or variable-rate financing to fund expansion.

For investors evaluating small-cap and microcap opportunities, companies with manageable debt, improving cash flow, and sustainable revenue growth may be better positioned to benefit from economic resilience while navigating higher financing costs.

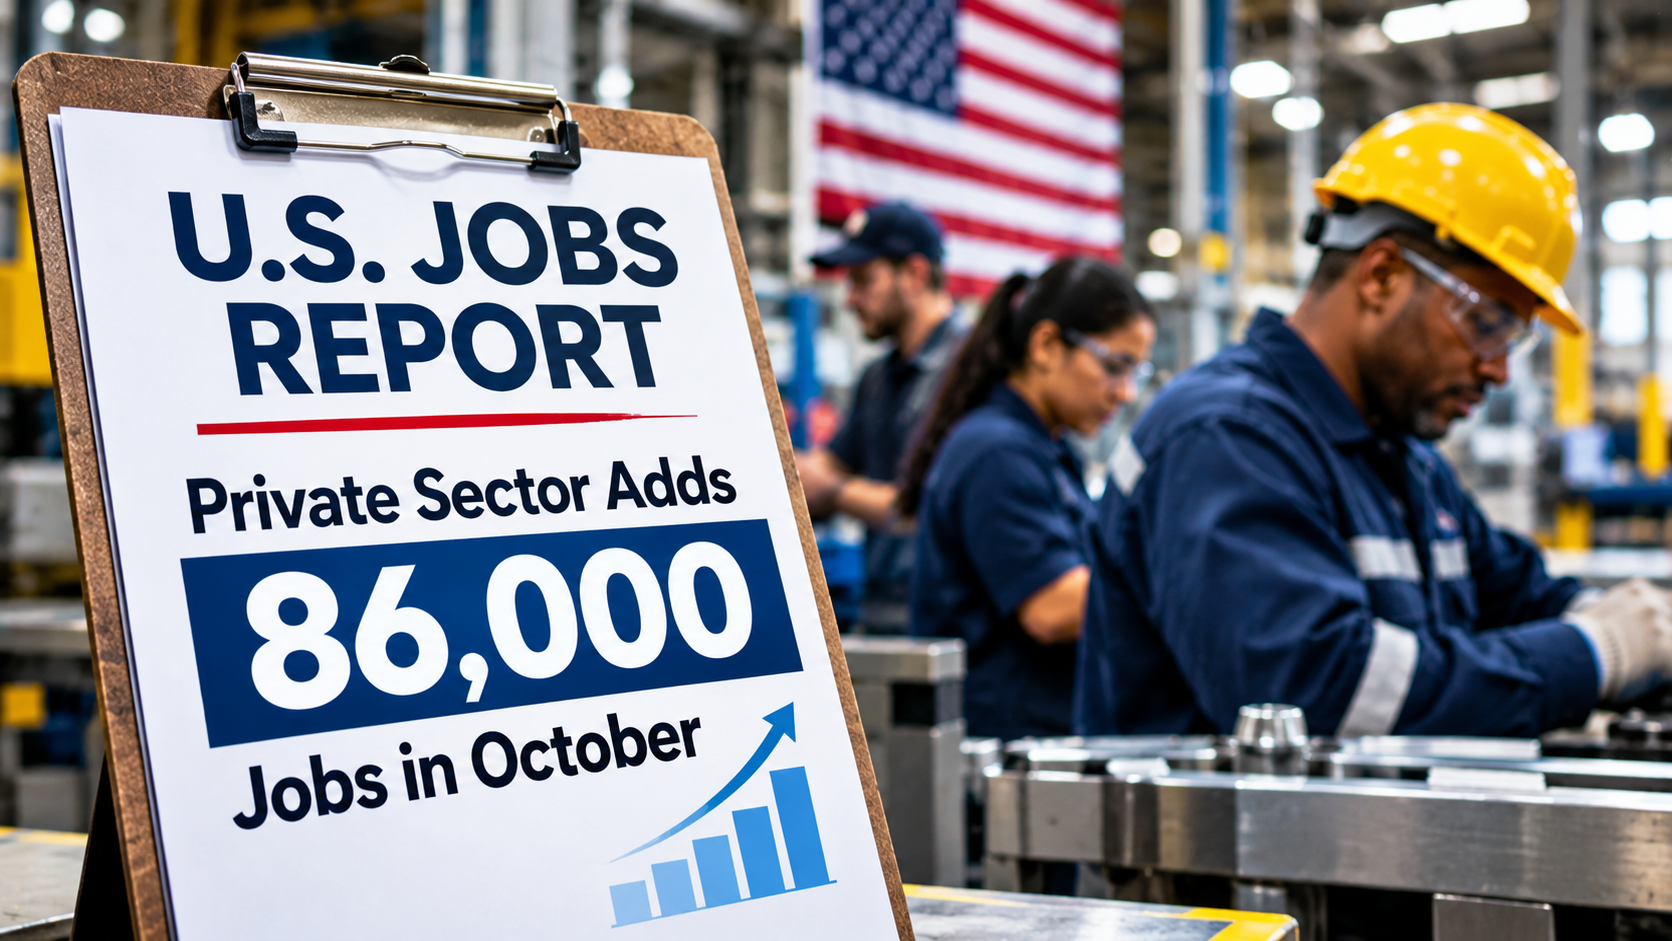
The October report also follows Wednesday’s ADP employment data, which showed private employers adding 86,000 jobs, providing another indication that hiring conditions may be stabilizing after a period of slower growth.

Despite the encouraging headline numbers, the labor market has not returned to the rapid hiring pace experienced earlier in the economic expansion. Employers continue to approach staffing decisions cautiously, and employment gains remain concentrated in selected industries.

Nevertheless, October’s results suggest the U.S. economy entered the final quarter of 2026 on firmer footing than many economists anticipated.

For Wall Street, attention now turns to upcoming inflation data and Federal Reserve commentary, which could help determine whether stronger economic growth will support a broader market rally or delay the interest-rate relief many investors have been anticipating.
U.S. Job Openings Rise to 7.5 Million, but Slow Hiring Signals Continued Labor Market Uncertainty

U.S. job openings climbed to 7.5 million in September, exceeding economists’ expectations and suggesting that demand for workers remains resilient despite a prolonged slowdown in hiring. However, the latest government data also revealed a labor market where employers remain hesitant to expand payrolls, even as layoffs stay relatively low.

According to the Bureau of Labor Statistics’ Job Openings and Labor Turnover Survey (JOLTS), released Tuesday, November 3, job openings increased by approximately 333,000 to 7.523 million in September, compared with a revised 7.190 million in August.

The reading exceeded economists’ forecasts of approximately 7.1 million available positions and marked the highest level of job openings since May.

The job openings rate increased to 4.5% from 4.3% in August, indicating that businesses continue to have positions available even as broader economic uncertainty influences hiring decisions.

Despite the increase in available jobs, actual hiring activity showed only modest improvement.

Employers hired approximately 5.4 million workers during September, up from 5.3 million in August. The national hiring rate edged higher to 3.4% from 3.3%, reinforcing concerns that companies remain cautious about adding employees.

Economists have increasingly described the current employment environment as a “low-hire, low-fire” labor market, characterized by limited recruitment activity alongside relatively few layoffs.

For workers, this combination can create a challenging employment environment. Employees with existing jobs generally face less immediate risk of losing their positions, while unemployed individuals and those seeking career changes may encounter fewer opportunities to secure new employment.

The latest report also showed that layoffs and discharges declined to approximately 1.64 million in September, down from 1.77 million in August. The layoffs rate decreased to 1.0% from 1.1%, suggesting that employers are generally choosing to retain existing workers rather than implement widespread workforce reductions.

Meanwhile, voluntary quits increased to approximately 3.4 million, with the quits rate rising to 2.1% from 1.9% in August.

An increase in voluntary departures can indicate improving worker confidence, as employees may become more willing to leave their current positions when they believe alternative opportunities are available.

Hiring trends varied across industries.

Accommodation and food services recorded an increase of approximately 158,000 hires, reflecting stronger recruitment activity in hospitality-related businesses. State and local government, excluding education, reported an increase of approximately 104,000 job openings.

Manufacturing and other industrial sectors also continued to show demand for workers, although the pace of hiring remained uneven across the broader economy.

The mixed employment picture presents an important challenge for the Federal Reserve as policymakers evaluate inflation, economic growth, and the appropriate path for interest rates.

A labor market with limited layoffs may help sustain household incomes and consumer spending, potentially supporting economic activity. However, persistently slow hiring could eventually weaken wage growth and reduce opportunities for workers entering or returning to the labor force.

For small-cap companies, employment conditions are particularly important because smaller businesses often have fewer financial resources to absorb changes in labor costs, borrowing expenses, and consumer demand.

Companies in retail, hospitality, manufacturing, and business services may benefit from a stable employment environment that supports consumer spending. At the same time, businesses looking to expand could face challenges balancing payroll costs with uncertain demand.

Investors will now turn their attention to Friday’s October employment report for a more comprehensive assessment of labor market conditions.

Economists surveyed by Bloomberg expect the economy to have added approximately 65,000 jobs in October, following an increase of just 29,000 positions in September.

The unemployment rate is expected to remain near 4.2%, suggesting that the labor market continues to avoid a sharp deterioration despite slower job creation.

September’s JOLTS report offers a cautiously encouraging signal that businesses still need workers, but the modest pace of hiring indicates that employers remain reluctant to commit to substantial workforce expansion.

For investors, the central question is whether improving job openings will eventually translate into stronger hiring or whether the economy will remain in a prolonged period of limited employment growth.

The answer could have significant implications for Federal Reserve policy, consumer confidence, and the performance of small-cap stocks in the months ahead.

Private Payrolls Miss Expectations in June as Hiring Slows. Thursday’s Report Will Tell the Full Story

The US labor market showed signs of cooling Wednesday morning, and the timing could not be more consequential. Private employers added just 98,000 jobs in June according to ADP’s monthly payroll report, falling well short of the 120,000 economists had anticipated. The miss comes one day before the government’s official employment situation report, which is expected to show a gain of approximately 115,000 positions and is being released Thursday rather than Friday due to the July 4 holiday market closure.

After months of surprisingly strong job gains that helped keep the Federal Reserve locked in a hawkish posture, the June ADP number introduces a new variable into the rate conversation at precisely the moment investors needed clarity most.

What the Data Actually Shows

The 98,000 figure represents a meaningful deceleration from May’s revised 122,000 and an even sharper slowdown from the blowout 172,000 gain reported in the government’s May payroll data. ADP’s chief economist described the report as reflecting a labor market caught between two forces: workers are taking longer to find new positions, while certain industries are simultaneously running into labor supply constraints. The net effect is a slowdown in job creation that is neither a collapse nor a continuation of the strength that characterized the spring.

Other labor market indicators released this week paint a slightly more constructive picture. Layoff announcements fell in June, and job openings for May came in stronger than economists had predicted at 7.6 million. But hiring activity itself remained weak, reinforcing a pattern the Federal Reserve’s Beige Book described last month as a “low-hire, low-fire environment” in which companies are holding headcount steady rather than expanding.

Why Thursday Matters More

The ADP report is a useful directional signal, but the government’s nonfarm payrolls report is the data point the Fed actually uses in its policy deliberations. Thursday’s number will land less than two weeks after Fed Chair Kevin Warsh’s first FOMC meeting, where the committee dropped its easing bias and signaled through its dot plot that nine of 18 officials expect at least one rate hike before year-end.

A strong Thursday print would reinforce that hawkish posture and keep rate hike probabilities elevated. A miss particularly one that aligns with ADP’s softening signal — would complicate the committee’s case for tightening and could mark the first meaningful crack in the “higher-for-longer” narrative that has dominated rate expectations since March.

The Small Cap Implications

For companies in the sub-$2 billion market cap space, the difference between those two outcomes is material. Small and microcap companies carry disproportionately more variable-rate debt than their large cap counterparts, making them acutely sensitive to shifts in rate expectations. A labor market that is genuinely cooling gives the Fed room to hold rather than hike, which would be a direct and immediate benefit to smaller balance sheets that have been absorbing elevated borrowing costs all year.

At the same time, a slowing labor market carries its own risk for consumer-facing small caps. Fewer jobs means less consumer spending power, and the companies most exposed to discretionary spending: restaurants, specialty retail, travel, and leisure feel that pressure faster than most. The staffing and employment services sector, where several smaller publicly traded companies operate, is also a direct read on hiring trends.

Wednesday’s ADP report is a warning flare, not a verdict. Thursday morning’s number is the one that will actually move the Fed’s thinking, the bond market, and the cost of capital for every small company in America.

Hiring Rebounds in February—But the Details Tell a More Complicated Labor Story

U.S. private employers added 63,000 jobs in February, marking the strongest monthly gain since July and coming in ahead of economist expectations for roughly 50,000 new roles. The figures, released by payroll processor ADP, suggest the labor market may be regaining some footing after a sluggish start to the year.

Still, a closer look at the report reveals a labor market that remains uneven beneath the surface.

January’s already weak employment reading was revised downward to just 11,000 jobs added, underscoring the fragile hiring environment that characterized much of 2025. February’s improvement, while notable, was driven by only a handful of sectors rather than broad-based hiring across the economy.

Healthcare and education services led the way, adding 58,000 positions, reflecting steady structural demand tied to demographic trends and an aging U.S. population. Construction also contributed meaningfully with 19,000 new jobs, a gain some economists link to ongoing infrastructure activity and continued investment in data-center development tied to AI and cloud expansion.

But strength in those areas masked emerging weakness elsewhere.

Professional and business services—one of the largest white-collar employment categories—shed 30,000 jobs during the month. The sector includes consulting, accounting, marketing, legal services, and administrative roles, making the decline notable for the broader knowledge-economy workforce.

Manufacturing and certain business service segments also experienced job losses, highlighting the uneven distribution of hiring demand across the economy.

In fact, the wage premium for workers switching employers fell to a record low in February, a signal that labor market mobility may be slowing. Historically, job-changers have been able to command meaningfully higher pay increases than employees staying with their current companies.

ADP reported that annual pay growth for workers staying in their roles rose 4.5%, while job changers saw a median pay increase of 6.3%—a gap that has narrowed significantly compared with earlier years of the post-pandemic labor boom.

The report arrives amid continued headlines about layoffs across parts of the corporate landscape. Companies including Block, Whirlpool, and eBay have recently announced workforce reductions, in some cases tied to restructuring initiatives or technological shifts such as artificial intelligence adoption.

For investors, the mixed signals in the ADP report reinforce a theme that has defined the labor market over the past year: slow hiring paired with relatively low layoffs. Employers appear cautious about expanding headcount aggressively, but they also remain reluctant to shed workers after the labor shortages experienced earlier in the decade.

The market will receive a more comprehensive picture of the employment landscape when the U.S. Labor Department releases its official February jobs report later this week. Historically, ADP data does not always align perfectly with the government’s figures, but it often provides an early directional signal.

For now, February’s numbers point to a labor market that may be stabilizing—but one still marked by sector divergence and cooling worker bargaining power.

January Jobs Report Beats Expectations, but Annual Revisions Reveal Slowing Labor Market

The US labor market delivered a surprise to the upside in January, adding 130,000 jobs — roughly double economists’ expectations — while the unemployment rate edged down to 4.3%, according to Labor Department data released Wednesday.

Economists surveyed ahead of the report had forecast a gain of around 65,000 jobs, though estimates varied widely, ranging from modest growth to outright job losses. Instead, payroll growth came in near the top end of projections, offering a near-term boost to confidence about the resilience of the labor market.

But beneath the headline strength, substantial downward revisions to last year’s data paint a much weaker picture of overall job creation. Updated figures show the economy added just 181,000 jobs for the entirety of 2025 — sharply revised down from the previously reported 584,000. That marks the slowest pace of annual job growth outside of a recession since 2003.

On average, the economy added only about 15,000 jobs per month last year, underscoring the extent of the slowdown. Revisions also shaved gains from the final months of 2025, with November payroll growth lowered to 41,000 from 56,000 and December reduced slightly to 48,000.

The report was initially scheduled for release last Friday but was delayed by a brief partial government shutdown, heightening anticipation among investors and policymakers. January’s report is often closely watched because it includes annual benchmark revisions that incorporate more complete data from unemployment insurance tax records and other sources. This year’s revisions showed that for the 12 months ending in March 2025, the economy added 898,000 fewer jobs than previously estimated — a significant adjustment, though slightly improved from an earlier estimate of 911,000 fewer jobs.

The January rebound comes after private-sector data suggested a bruising start to the year for job seekers, with limited hiring activity reported in early surveys. The stronger-than-expected payroll figure may ease some immediate concerns, but the broader trend suggests a labor market that has cooled considerably from the rapid hiring pace seen in previous years.

Administration officials have sought to temper expectations around job growth, arguing that slower hiring may reflect structural changes rather than economic weakness. They point to a shrinking labor force, driven in part by stricter immigration policies, as well as productivity gains that allow companies to expand output without significantly increasing headcount.

The unemployment rate’s slight decline to 4.3% indicates continued stability in the job market, with layoffs remaining relatively contained. However, the sharp downward revisions raise questions about how much underlying momentum remains in the economy.

For markets and policymakers, the report presents a mixed signal. January’s job gains suggest that the labor market retains pockets of strength, but the broader revisions confirm that hiring slowed dramatically last year. As the Federal Reserve evaluates the path of interest rates, the balance between cooling job growth and stable unemployment will be a key factor in determining whether the economy can maintain steady expansion without reigniting inflationary pressures.

The January report may have exceeded expectations, but the longer-term trend signals a labor market that is steady — not surging — and increasingly dependent on productivity and structural shifts rather than rapid hiring to drive growth.

Consumer Sentiment Climbs, But Challenges Remain Amid Inflation and Job Concerns

Consumer sentiment in the United States showed a modest rebound in February, reaching its highest level since last August, according to the University of Michigan’s Index of Consumer Sentiment. The reading came in at 57.3, up 1.6 points from January, surpassing economists’ expectations of a decline to 55. While this represents an encouraging short-term improvement, sentiment remains significantly below last year’s highs, reflecting ongoing concerns about inflation, job security, and long-term economic stability.

Compared with February 2025, when sentiment stood at 64.7, the index is down 11.4%, and roughly 20% below the peak levels recorded last year. Joanne Hsu, director of surveys of consumers at the University of Michigan, emphasized that “recent monthly increases have been small — well under the margin of error — and the overall level of sentiment remains very low from a historical perspective.” According to Hsu, Americans continue to worry about the erosion of personal finances due to high prices and the elevated risk of job loss.

The February report highlights mixed signals from the labor market. Jobless claims came in higher than expected this week, suggesting some near-term labor market pressures. Yet, data from Challenger, Gray & Christmas show that December job cuts were at their lowest level since 2023. Official jobs data from the Bureau of Labor Statistics (BLS) is scheduled for release on February 11, after delays caused by a partial government shutdown, which had postponed the initial report.

Inflation expectations also showed improvement in February. Survey respondents now anticipate a 3.5% increase in prices over the next year, down from 4% previously. This is the lowest expected inflation since January 2025, though it remains above the pre-pandemic range of roughly 2.3% to 3%. The BLS is set to release its latest inflation report on February 13, which will provide further clarity on the trajectory of price growth.

Interestingly, consumer sentiment appears increasingly tied to exposure to financial markets. Those with the largest stock portfolios reported surging confidence, while sentiment among households without stock holdings stagnated at historically low levels. Hsu noted that this divergence underscores the unequal impact of financial markets on Americans’ perceptions of the economy.

The survey also reflected nuanced changes in economic expectations. Modest improvements were reported in consumers’ assessments of current personal finances and buying conditions for durable goods, but these were offset by a slight decline in expectations for long-run business conditions. Overall, the February data presents a picture of cautious optimism: consumers are slightly more confident than in recent months, yet significant economic anxieties remain.

As Americans navigate high prices and labor market uncertainties, the path forward for consumer confidence remains fragile. Analysts will be closely watching upcoming jobs and inflation reports for further signals, particularly as financial market volatility and global economic pressures continue to influence sentiment. For now, February’s reading offers a small but notable lift in confidence, reminding policymakers and businesses alike that while the recovery is underway, it remains uneven across different segments of the population.

America’s Hiring Stall: What the Weak Jobs Market Means for Investors in 2026

The final U.S. jobs report of 2025 delivered a sobering message: the labor market has slowed to a crawl. With just 50,000 jobs added in December, the year closed with the weakest pace of hiring outside of a recession in more than two decades. For investors—particularly those focused on small-cap stocks—this shift carries important implications as the economy enters 2026.

Total payroll growth for 2025 reached only 584,000 jobs, a dramatic fall from the roughly 2 million jobs added in 2024. Monthly gains averaged fewer than 50,000 positions, a level economists say is consistent with stagnation rather than expansion. While the unemployment rate dipped modestly to 4.4%, the decline was driven more by a shrinking labor force than by robust hiring.

Digging deeper, the data reveals a fragile employment landscape. Job creation was heavily concentrated in healthcare and social assistance, which together accounted for the majority of gains. Outside of those sectors, many industries experienced flat or negative hiring trends. Economists warn that future data revisions could show that overall employment actually contracted during parts of the year.

This environment has produced what many describe as a “no-hire, no-fire” economy. Companies are reluctant to lay off workers, but equally hesitant to expand payrolls amid higher borrowing costs, slower consumer demand, and lingering uncertainty around policy and global growth. For workers, this has translated into longer job searches and declining confidence. The share of unemployed individuals out of work for more than six months has risen sharply, signaling deeper structural weakness.

For investors, especially in the small-cap space, these conditions cut both ways. Slower job growth tends to pressure consumer spending, which can weigh on revenue for domestically focused companies. At the same time, a cooling labor market strengthens the case for interest rate relief later in 2026. If the Federal Reserve responds to weakening employment trends with rate cuts, smaller companies—often more sensitive to financing costs—could benefit disproportionately.

There are also early signs that the slowdown may be stabilizing. Layoff announcements declined in December, and private payroll data suggests hiring may be finding a floor. Some economists believe the worst of the labor market deceleration could already be behind us, setting the stage for a gradual recovery rather than a sharp downturn.

For small-cap investors, selectivity will be key. Businesses with strong balance sheets, pricing power, and exposure to resilient sectors may outperform if growth remains muted. Meanwhile, any meaningful improvement in hiring or labor participation could act as a catalyst for a broader re-rating across the small-cap universe.

As 2026 unfolds, the jobs market will remain a critical signal to watch. Whether this slowdown proves to be a pause—or a warning—will shape market sentiment, monetary policy, and investment opportunity in the months ahead.

US Labor Market Shows Continued Weakness as November Job Openings Miss Expectations

The US labor market’s sluggish trajectory continued in November, with newly released government data revealing a sharper-than-expected decline in job openings and historically weak hiring activity. The figures paint a picture of an economy caught in what economists are calling a “no-hire, no-fire” limbo, where employers remain cautious about expansion while largely avoiding layoffs.

According to the Job Openings and Labor Turnover Survey from the Bureau of Labor Statistics, there were 7.15 million job openings at the end of November, falling short of the 7.6 million economists had projected. This marks a continuation of the downward trend in available positions, with October’s figures also revised lower from 7.7 million to 7.45 million. The decline was particularly pronounced in accommodation and food services as well as transportation and warehousing, though construction showed some gains.

The timing of these weakness signals is notable, as November also saw the unemployment rate climb to a four-year high of 4.6%. This combination of rising joblessness and declining opportunities suggests the labor market may be losing momentum more rapidly than many forecasters anticipated.

Perhaps most concerning is the collapse in hiring activity. The hiring rate dropped to just 3.2% in November, marking one of the weakest readings since the Great Recession. Only April 2020, during the depths of the pandemic lockdowns, recorded a lower rate at 3.1%. Heather Long, chief economist at Navy Federal Credit Union, characterized the situation bluntly as a “hiring recession,” noting that virtually no jobs have been added outside the healthcare sector since April.

The data reveals an economy where workers and employers alike are playing it safe. While separations held steady at 5.1 million—unchanged from both October and the previous year—the quits rate rose to 2%. This metric, traditionally viewed as a gauge of worker confidence, suggests employees retain some optimism about finding new opportunities, even as hiring activity stalls.

Not all indicators are pointing downward, however. Data from payroll processor ADP showed private employers added 41,000 positions in December, recovering from losses in the previous month. Bank of America’s internal employment analysis echoed this modest improvement, suggesting that the worst of the labor market slowdown may be behind us. The bank’s institute noted that while the “low-hire, low-fire” dynamic persists, there are signs that the deceleration may have stabilized.

As markets await Friday’s official unemployment data for December, the November figures serve as a reminder of the delicate balance facing policymakers. The Federal Reserve must navigate between supporting a weakening labor market and managing inflation concerns, all while employers demonstrate reluctance to commit to significant workforce expansion.

The coming months will be critical in determining whether this represents a temporary soft patch or the beginning of a more sustained period of labor market weakness.

November Jobs Report Signals Labor Softening—but Leaves the Fed on Hold

The November jobs report offered fresh signs that the U.S. labor market is cooling, but not enough to materially alter the Federal Reserve’s near-term policy outlook. While the data points to slower hiring and a higher unemployment rate, policymakers and economists broadly agree that the figures fall short of triggering an immediate shift toward additional rate cuts.

According to the latest report, the U.S. economy added 64,000 jobs in November, a modest rebound after a net loss of 105,000 jobs in October. At the same time, the unemployment rate rose to 4.6%, its highest level in more than four years. Under normal circumstances, a jump of that magnitude might raise alarms at the Fed. This time, however, the context surrounding the data matters just as much as the headline numbers.

Economists caution that recent employment figures may be distorted by technical and temporary factors, including the lingering effects of the government shutdown that spanned October and part of November. The Labor Department itself flagged higher-than-usual uncertainty in the data, citing lower survey response rates, changes in weighting methodology, and the use of a two-month analysis window instead of a single month. These quirks make it harder to draw firm conclusions about the true underlying trend in the labor market.

A significant portion of the weakness also stems from government employment. Federal payrolls declined sharply as deferred resignations tied to earlier buyout programs finally showed up in official counts. Since peaking earlier in the year, federal employment has fallen by more than a quarter-million jobs. While that has pushed the unemployment rate higher, it does not necessarily reflect broader weakness in private-sector hiring.

At the same time, labor force participation rose in November, suggesting that more people are actively looking for work. That dynamic can temporarily lift the unemployment rate even if the economy is not deteriorating rapidly. In other words, the increase in joblessness may be more about shifting labor supply than collapsing demand.

Federal Reserve Chair Jerome Powell has repeatedly emphasized the need for caution when interpreting recent data. He has noted that both labor and inflation metrics may be distorted, not just volatile, and warned against overreacting to any single report. Some Fed watchers believe monthly payroll growth may be overstated and that underlying job creation could be closer to flat or slightly negative—a scenario consistent with a late-cycle slowdown rather than an outright downturn.

For now, the November report reinforces the Fed’s patient stance. Labor market softness appears real, but there is little evidence that the broader economy has stalled. Inflation trends and upcoming employment data, particularly for December and January, will be critical in determining whether policymakers feel confident enough to resume cutting rates.

In short, November’s jobs data neither forces the Fed’s hand nor closes the door on future easing. It keeps policymakers in wait-and-see mode—alert to downside risks, but not yet convinced that the economy requires immediate additional support.

U.S. Job Openings Fall to Lowest Level Since Early 2021 as Hiring Slows

Job openings across the United States have fallen to their lowest level in more than four and a half years, signaling that the once-resilient labor market is losing momentum. According to data from Indeed, employment opportunities dropped sharply in October as the prolonged government shutdown weighed on business confidence and hiring activity.

Indeed’s Job Postings Index fell to 101.9 as of October 24, marking the weakest reading since early February 2021. The index, which uses February 2020 as a baseline of 100, has slipped 0.5% since the beginning of October and is down about 3.5% since mid-August. The decline extends a downward trend that began earlier in the year, reflecting growing caution among employers amid economic uncertainty and tighter credit conditions.

Under normal circumstances, the Bureau of Labor Statistics (BLS) would have released its monthly Job Openings and Labor Turnover Survey (JOLTS) this week, a closely watched gauge of labor market health. However, with the federal government still partially shut down, economists have turned to private data sources like Indeed for real-time insights. The latest official JOLTS report, released in August, showed job openings at 7.23 million—down 7% from January and roughly flat compared with July—confirming that hiring appetite has been cooling for months.

Indeed’s internal dashboard also points to a softening in wage growth alongside the decline in job postings. The firm’s data shows advertised wages rising 2.5% year-over-year in August, compared to a 3.4% pace in January. Slower wage gains suggest that employers are facing less competition for workers than they did during the post-pandemic hiring boom, when labor shortages and rapid inflation pushed pay rates sharply higher.

The Federal Reserve has taken note of the cooling trend. Last week, the Fed’s policy-setting committee voted 10–2 to cut its benchmark interest rate by a quarter point, lowering the target range to 3.75%–4%. Officials cited growing risks to the labor market as a key reason for easing policy, even as inflation remains nearly a full percentage point above the central bank’s 2% target.

Fed Governor Lisa Cook highlighted the slowdown in a recent speech, noting that data from Indeed and other private sources show hiring activity weakening in real time. “We’re seeing a clear deceleration in job postings,” she said. “There’s reason to be concerned because unemployment has ticked up slightly over the summer.”

Economists, unable to rely on the usual stream of government data, have estimated that the October jobs report—had it been released—would have shown a net loss of around 60,000 positions and an increase in the unemployment rate to 4.5%.

Taken together, the latest indicators suggest that the U.S. job market, while still historically strong, is shifting from its rapid post-pandemic recovery into a slower, more cautious phase. If the current trends continue, policymakers may face increasing pressure to balance inflation control with the need to prevent a deeper slowdown in employment growth.

Jobless Claims Fall to 218,000, Beating Expectations as Economic Data Shows Resilience

U.S. jobless claims unexpectedly declined last week, signaling continued resilience in the labor market even as hiring has slowed and the Federal Reserve keeps a close eye on economic momentum.

Initial claims for unemployment benefits totaled a seasonally adjusted 218,000 for the week ending Sept. 20, according to the Labor Department. That was a drop of 14,000 from the prior week’s upwardly revised level and came in well below the consensus forecast of 235,000. Continuing claims, which measure those still receiving benefits, edged slightly lower to 1.926 million.

The latest claims figures arrive against a backdrop of uncertainty about the economy’s trajectory. Payroll growth has cooled, and job openings remain at multiyear lows. The Fed recently responded by cutting its benchmark borrowing rate by a quarter percentage point to a range of 4% to 4.25%, its first reduction of 2025. Policymakers cited rising risks to employment as one factor behind the decision.

Still, the claims data suggests companies remain hesitant to lay off workers despite a noticeable pullback in hiring. Volatility in weekly figures continues, with Texas accounting for a sizable portion of recent swings, but the broader picture points to a labor market that is holding firmer than many expected.

Beyond the employment data, Thursday also brought signs of strength in other corners of the economy. Gross domestic product for the second quarter was revised sharply higher to an annualized gain of 3.8%. That marked a half-point improvement from the prior estimate and reflected stronger consumer spending than initially reported. Personal consumption, which makes up about two-thirds of U.S. economic activity, rose at a 2.5% pace, well above earlier estimates and the tepid 0.6% increase seen in the first quarter.

Durable goods orders added to the positive picture. Purchases of long-lasting items such as appliances, aircraft, and computers climbed 2.9% in August, defying forecasts for a decline and reversing a steep drop from July. Even excluding transportation equipment, orders grew 0.4% in the month and 1.9% when defense-related spending was excluded, underscoring broad-based demand.

The housing sector, which has been under pressure from higher borrowing costs, also showed signs of improvement. Sales of newly built homes jumped 20.5% in August, the largest monthly gain since early 2022. Existing home sales came in slightly ahead of expectations at an annualized rate of 4 million.

Taken together, the data paints a picture of an economy that continues to expand despite headwinds from tighter credit conditions, shifting trade policies, and global geopolitical challenges. Markets currently anticipate that the Fed will follow through with two more rate cuts before the end of the year, at its October and December meetings.

While policymakers acknowledge that growth is being restrained by elevated borrowing costs, they also see resilience across consumer spending, business investment, and labor markets. That combination has kept the outlook more balanced than some had feared heading into the final stretch of 2025.

US Jobs Revision Wipes Out 911,000 Positions, Raising Alarms About Economic Momentum

The U.S. labor market just got a reality check — and it’s a sobering one. A government revision revealed that the economy employed 911,000 fewer people as of March 2025 than initially reported, exposing a far weaker job market than policymakers and the public had believed. The new data, released by the Bureau of Labor Statistics (BLS), shows the slowdown began months before the summer headlines of weakening payrolls and rising unemployment.

The revision, covering the 12 months between March 2024 and March 2025, slashes average monthly job gains from an already modest 147,000 to just 71,000. For context, that’s less than half the pace originally reported and a figure that suggests the labor market was cooling long before the recent downturn. Economists had anticipated downward revisions, but the scale was startling — many expected about 700,000 fewer jobs, while the actual figure exceeded even the most pessimistic forecasts.

Industries that once looked like pillars of resilience proved more fragile under scrutiny. Leisure and hospitality was revised down by 176,000 jobs, erasing gains that had been touted as proof of post-pandemic recovery strength. Professional and business services followed with a downward revision of 158,000 jobs, signaling weakness in white-collar employment as well. Overall, the private sector absorbed the brunt, losing 880,000 jobs in the revision, while government payrolls were adjusted down by 31,000.

These annual revisions are routine, as the BLS incorporates more accurate data like unemployment insurance filings. But the magnitude of recent adjustments has been unusually large, feeding political tensions and raising questions about the reliability of initial reporting. Last year’s revision cut 818,000 jobs, landing right in the middle of the presidential campaign and fueling criticism from then-candidate Donald Trump.

Now, President Trump is in office and once again pointing to the BLS, accusing it of producing “phony” numbers. He has already dismissed the agency’s former commissioner and nominated E.J. Antoni, a vocal critic from the Heritage Foundation, to lead the bureau. Antoni’s confirmation battle will likely intensify after this revision, as the administration pushes for overhauls in how labor data is collected and reported.

Beyond politics, the numbers matter for the Federal Reserve, which is under pressure to respond to slowing job growth and signs of economic fragility. Trump and his allies argue Fed Chair Jerome Powell has been “too late” in cutting rates, claiming the central bank clung too rigidly to its 2% inflation target at the expense of growth. The White House could now use these revisions as further evidence to press its case.

For millions of Americans, though, the revisions underscore a more personal reality. A job market once presented as resilient is now revealed to have been much shakier. With fewer jobs than thought, weaker household income growth, and rising uncertainty, the labor market is entering a precarious phase. The debate in Washington may revolve around statistics, but the impact is being felt in homes and businesses across the country.

Labor Market Shows Unexpected Strength as Job Openings Surge in May

The American labor market delivered a surprise in May, with job openings climbing to their highest point in over six months, according to fresh government data that has caught economists and Federal Reserve watchers off guard.

The Bureau of Labor Statistics reported Tuesday that available positions reached 7.76 million at the end of May, representing a substantial jump from April’s 7.39 million openings. This figure significantly exceeded analyst predictions, which had anticipated job openings would remain relatively flat at approximately 7.3 million positions.

The unexpected surge in available positions marks the strongest showing for job openings since November 2024, suggesting that despite broader economic uncertainties, employers continue to maintain robust demand for workers across various sectors.

While the job opening data painted an optimistic picture, other components of the Job Openings and Labor Turnover Survey revealed a more nuanced employment landscape. Hiring activity actually declined during the month, with companies bringing on 5.5 million new employees compared to 5.61 million in April. This translated to a hiring rate of 3.4%, down from the previous month’s 3.5%.

The data reveals what labor economists have characterized as a market in equilibrium, where demand for workers remains strong but actual hiring activity has moderated from the rapid pace seen in recent years. Both hiring and voluntary quit rates are currently operating near decade-low levels, indicating a more measured approach to job market transitions.

Interestingly, the quit rate—often viewed as a barometer of worker confidence—edged upward to 2.1% from April’s 2.0%. This modest increase suggests that while employees remain cautious about making career moves, some are beginning to show renewed confidence in finding alternative employment opportunities.

The labor market data arrives at a critical juncture for monetary policy discussions. Financial markets are closely monitoring employment trends as the Federal Reserve weighs potential interest rate adjustments in response to evolving economic conditions.

Current market expectations indicate approximately a 23% probability of a rate cut at the Fed’s July meeting, with odds rising to 96% for at least one reduction by the September meeting. The stronger-than-expected job opening figures could influence these calculations, as robust labor demand typically supports arguments against immediate monetary easing.

The employment picture becomes more complex when considering recent policy developments, including the implementation of new trade measures under the Trump administration. Economists are watching for any signs that tariff policies might be affecting hiring patterns or business confidence across different industries.

Market participants will receive additional labor market insights Thursday when the Bureau of Labor Statistics releases the comprehensive June employment report. Economists are forecasting a continued moderation in hiring activity, with projections calling for 110,000 new nonfarm payroll additions—a notable decline from recent months.

The unemployment rate is expected to tick slightly higher to 4.3%, which would represent a modest increase from the current 4.2% level. If these projections prove accurate, they would reinforce the narrative of a labor market that remains fundamentally healthy but is operating at a more sustainable pace than the breakneck hiring seen in the post-pandemic recovery period.

As one economist noted, while hiring activity remains below historical norms, the combination of low layoff rates and steady job creation suggests the labor market has achieved a state of relative stability rather than deterioration. This balance could prove beneficial for both workers and employers as the economy navigates ongoing policy transitions and global economic uncertainties.