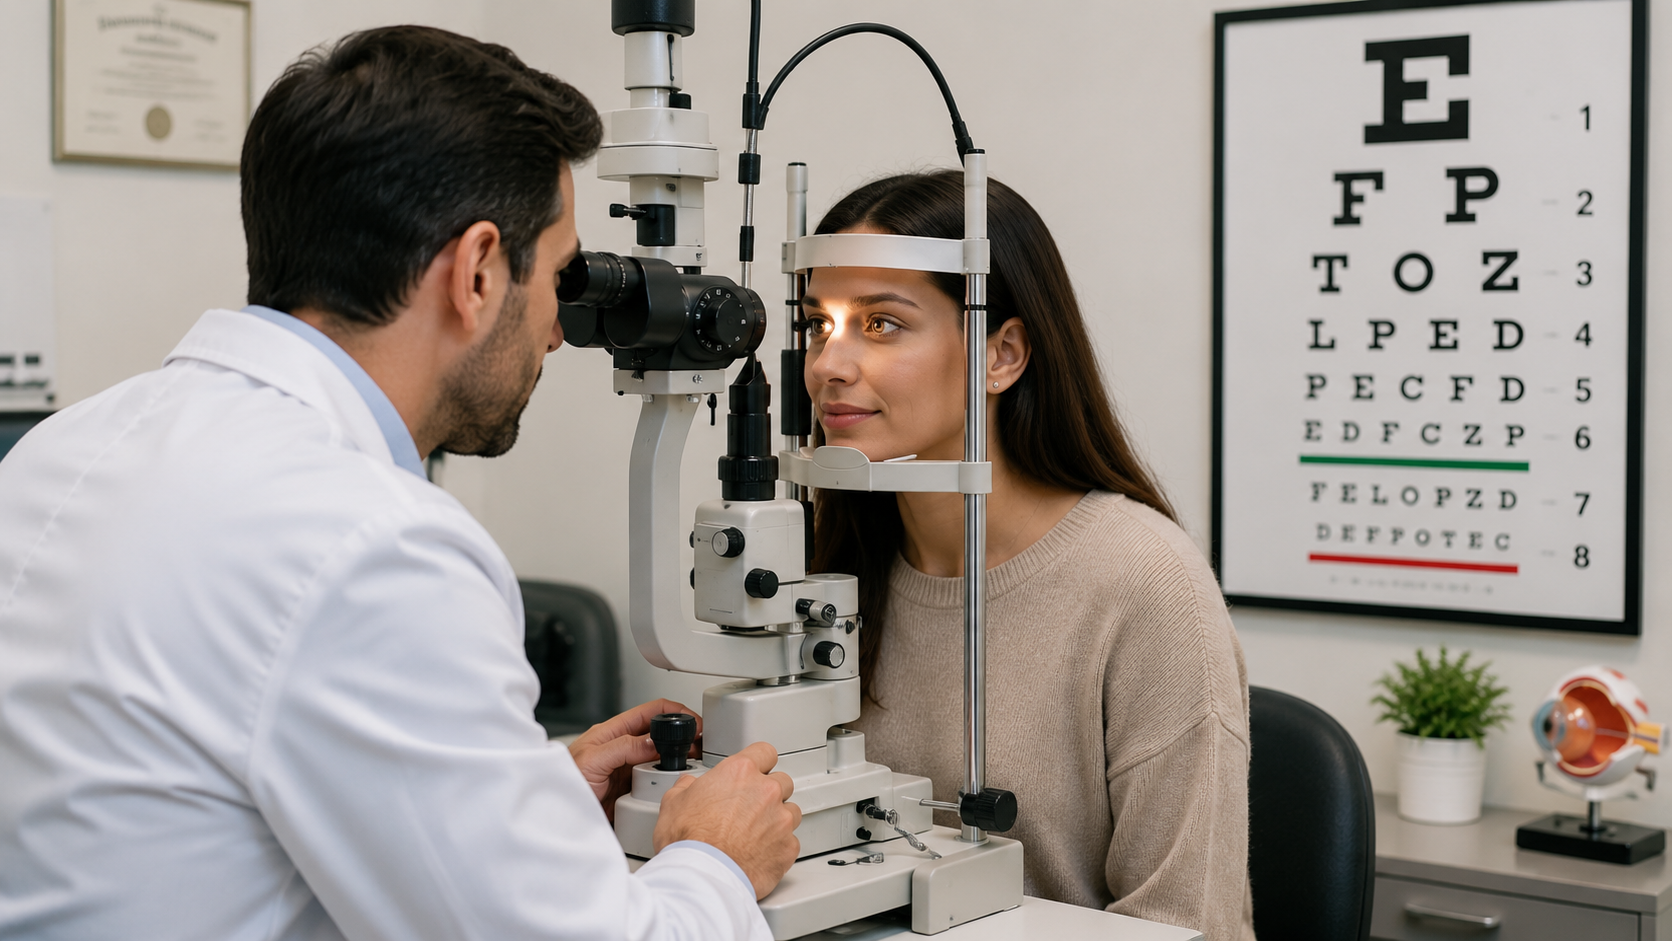
Tarsus Pharmaceuticals (Nasdaq: TARS) announced Thursday it has entered into a definitive agreement to acquire privately held Alkeus Pharmaceuticals, adding gildeuretinol, an investigational once-daily oral therapy for Stargardt disease, to its growing eye care pipeline. Under the terms of the agreement, Tarsus will pay approximately $450 million upfront, including $270 million in cash, with up to $350 million in additional milestone payments and low-to-mid single digit royalties on future product sales.
Alongside the acquisition, Tarsus secured $125 million in gross proceeds through an oversubscribed private placement equity financing, giving the company additional capital to fund the integration and continued clinical development of its expanding pipeline. The deal is expected to close later in 2026, subject to customary closing conditions.
What Alkeus Brings to Tarsus
Stargardt disease is a rare, inherited retinal disorder that currently has no FDA-approved treatments, making it exactly the kind of high unmet need indication that commands significant strategic value despite years remaining before any potential approval. Gildeuretinol has already been studied in more than 400 individuals, demonstrating a favorable tolerability and efficacy profile, and has received both Breakthrough Therapy and Orphan Drug designations from the FDA, two regulatory signals that typically accelerate development timelines and reflect meaningful confidence in a drug’s underlying science.
The catch, and the reason this deal is genuinely a long-term bet, is timing. Topline data from the pivotal Phase 3 NORTHSTAR trial is not expected until the second half of 2029, meaning Tarsus is paying $450 million upfront for an asset that will not produce a definitive readout for roughly three more years.
A Pattern, Not a One-Off Deal
This is not Tarsus’s first eye care acquisition this year. The Alkeus deal builds directly on the company’s recent acquisition of iRenix Medical, which brought IRX-101, a potential ocular antiseptic, into the fold. Combined with its existing pipeline, which includes TP-04 for ocular rosacea and TP-05 for Lyme disease prevention, both currently in Phase 2, Tarsus is deliberately assembling one of the more comprehensive eye care pipelines in the industry rather than remaining a single-product company.
That strategy is being funded by genuine commercial strength. Tarsus reported second quarter 2026 net product sales of $173.9 million for its lead commercial product XDEMVY, an increase of more than 69% year over year, and raised its full-year 2026 XDEMVY sales guidance to a range of $685 million to $705 million. That accelerating commercial performance gives Tarsus the balance sheet flexibility to fund a multi-year pipeline bet like Alkeus while continuing to invest across its broader portfolio.
What It Means for Investors Tracking Ophthalmology and Rare Disease
For investors tracking small and mid cap companies in ophthalmology and inherited retinal disease, this transaction reinforces just how much strategic value the market continues to assign to differentiated science addressing conditions with no approved treatment options, even when the definitive clinical proof point sits years in the future. The broader inherited retinal disease space remains an area of active development, with companies like Ocugen continuing to advance gene therapy programs targeting similar categories of rare, previously untreatable retinal conditions.
Tarsus is betting that being the eye care company with the deepest pipeline, not just the strongest single product, is what builds durable value over the next decade. The market’s initial reaction, with shares pulling back modestly in premarket trading, suggests investors are still digesting the size of the bet relative to how far away the payoff actually is.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Overview. CoreCivic’s 2Q26 financial results exceeded management expectations, driven by lower operating costs and slightly higher populations from U.S. Immigration and Customs Enforcement. Recent contracts at 4 facilities added $80.1 million to revenue and $20.1 million to operating income in the quarter. These facilities continue to be in various stages of activation.
2Q26 Results. Revenue increased 27.3% y-o-y to $684.9 million and was above our $618 million projection. Adjusted EBITDA was $109.4 million, compared to $103.3 million in 2Q25 and our $108.9 million estimate. Adjusted net income was $37.7 million, or $0.38 per diluted share, in 2Q26, compared with $39.7 million and $0.36, respectively, last year. We would note 2Q25 EPS benefited from $11.6 million, or $0.08 per share, of Employee Retention Credits, along with interest thereon, available under the CARES Act. Excluding the CARES Act benefit, 2Q26 adjusted EPS would have reflected more pronounced y-o-y growth.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Overview. The ONE Group Hospitality’s second quarter 2026 results underscore the momentum the Company is building across the portfolio, driven by the continued strength of the Company’s Vibe Dining brands. Consolidated comparable sales were positive, with positive transaction growth across all segments. Quarterly margin performance was strong, with the consolidated margin expanding 110 basis points to 16.4%.
2Q26 Results. ONE Group reported 2Q26 revenue of $200.5 million, down 3.3% from $207.4 million for the same quarter last year. The decrease was primarily attributable to the closed grill concept restaurants, partially offset by an increase in comparable restaurant sales and sales from new restaurants opened since July 2025. Adjusted EBITDA attributable to ONE Group was $21.1 million in 2Q26 compared to $23.4 million in 2Q25, a decrease of 9.7%, primarily due to increased investment in marketing during the quarter and an increase in general and administrative expenses, excluding stock-based compensation.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Overview. NN delivered strong financial performance in 2Q26 with record results in many areas. The Company’s 5-pillar growth program is delivering results. New sales are higher margin, attached to higher-growth-rate end markets, and mostly immediate 2026 startup. The second half of 2026 is expected to reflect continued momentum and strong financial performance.
2Q26 Results. Net sales for 2Q26 were $128.7 million, an increase of 19.3% compared to net sales of $107.9 million for the same period in 2025. We were at $116 million. Adjusted EBITDA was $17.9 million, an increase of 36.1% compared to adjusted EBITDA of $13.2 million for 2Q25, primarily driven by improved sales mix and operating performance. We had projected $15 million. Adjusted net income was $5.5 million, or $0.11 per diluted common share, an increase of $4.7 million, or $0.09 per diluted common share, compared to adjusted net income of $0.7 million, or $0.02 per diluted common share, in 2Q25. We were at $2.2 million and $0.04, respectively.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Accretive Strategic Acquisition. InPlay Oil announced the acquisition of a private oil and gas producer for C$54.25 million, adding approximately 1,400 boe/d of oil-weighted production and increasing company-wide production to more than 20,100 boe/d. The acquired assets are contiguous with InPlay’s existing operations, enabling approximately C$2.5 million of annual cost synergies, while adding 50 drilling locations and immediately enhancing adjusted funds flow and free adjusted funds flow on a per-share basis. The transaction is expected to close by the end of August, subject to customary closing conditions. Post-close, InPlay expects to have more than 450 total drilling locations, including approximately 230 Tier-1 locations.
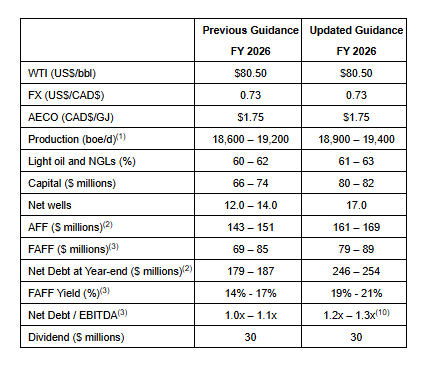
Corporate Guidance. InPlay continues to execute strongly, with recent Cardium wells materially outperforming expectations and being drilled ahead of schedule, allowing InPlay to expand its 2026 drilling program to 17 net wells on a pro forma basis. Reflecting stronger operational performance and the acquisition, management increased 2026 guidance, including adjusted funds flow (AFF) to C$161 million to C$169 million, free adjusted funds flow (FAFF) to C$79 million to C$89 million, and FAFF yield to 19% to 21%, despite higher capital spending of C$80 million to C$82 million.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Overview. Information Services Group had a very strong second quarter, generating the highest quarterly revenue since 2023. Growth in the quarter was led by Europe, up 10%, and the Americas, up 7%, while recurring revenues reached a new quarterly high of $30 million, driven by the Company’s AI-centered research and governance services.
2Q26 Results. Reported revenues for the second quarter were $65.5 million, up 6.4% from $61.6 million in the prior year, and above our $63 million projection. Second-quarter adjusted EBITDA was $9.4 million, up 13% y-o-y. Adjusted EBITDA margin was 14.3%, compared with 13.5% in the prior year’s second quarter. We were at $8.45 million and 13.4%, respectively. ISG reported adjusted net income for 2Q26 of $5.0 million, or $0.10 per share, compared with adjusted net income of $4.1 million, or $0.08 per share, in 2Q25. We had projected $4.4 million and $0.09/sh.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Awards. Graham Corporation was awarded two contracts for a combined value of over $43 million. These awards reflect the continued demand the Company is seeing across its defense platforms. The revenue for the contracts will be reflected in the Company’s first and second fiscal year 2027 backlog.
MK48 Mod 7 Heavyweight Torpedo. The first award is a follow-on fourth option year supporting the MK48 Mod 7 Heavyweight Torpedo program, awarded in the first quarter of fiscal 2027, which ended June 30, 2026. The Company will continue to provide alternators and regulators under this option year.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Federal Funding for Begin-Lamarche. First Phosphate Corp. has finalized agreements with the Government of Canada to receive C$4.84 million in non-repayable funding through Natural Resources Canada’s First and Last Mile Fund to support infrastructure planning for its Bégin-Lamarche phosphate deposit in Québec. The new funding builds on the C$16.7 million previously awarded by NRCan in March 2026, demonstrating continued federal support for advancing the strategic critical minerals project.
Investments in Infrastructure Planning. The funding will support two key initiatives: 1) approximately C$3.07 million for studies and design of a 161-kV power transmission line and substations, and 2) approximately C$1.77 million for planning a new mine access road and evaluating upgrades to bypass roads to support transportation between Begin-Lamarche and regional infrastructure, including rail links and the Port of Saguenay. Both projects include technical, environmental, and economic studies, engineering design, and consultation with indigenous communities and the public.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Eli Lilly jumped as much as 7% Wednesday after another quarter that made one thing clear: the appetite for weight-loss drugs isn’t slowing down. For small-cap investors, though, the trillion-dollar stock isn’t the story. What that demand does to the hunt for the next obesity drug is.
First, the quarter. Lilly raised its 2026 revenue forecast to a range of $85 billion to $87 billion, up from a prior ceiling near $85 billion, and beat on adjusted earnings — all powered by its GLP-1 franchise. It has momentum behind it, too: the FDA approved Foundayo, the pill version of its weight-loss drug, earlier this year, and next-generation candidate retatrutide is on track for an FDA filing early next year. The stock has climbed more than 40% since late April.
Here’s the read-through for the small end of the market.
Obesity is now the most valuable franchise in all of pharma, and the two giants that own it — Lilly and Novo Nordisk — are in a full sprint to stay ahead. That sprint runs straight through small-cap biotech. Building a differentiated metabolic drug from scratch is slow and uncertain; buying one that already has promising human data is faster. Big pharma has shown, again and again, that it will pay enormous premiums for early obesity and metabolic assets. Every small-cap sitting on a credible next-generation candidate — an oral GLP-1, an amylin, a muscle-sparing combination — is wearing a target because of quarters like this one.
There’s a second, quieter beneficiary: the supply chain. A demand curve this steep needs manufacturing, and that lifts the unglamorous names that make it possible — the peptide contract manufacturers, the auto-injector and drug-delivery specialists, and now the oral-formulation capacity that Foundayo’s approval just validated. It’s the same picks-and-shovels logic behind the bioprocessing consolidation we’ve watched all summer: when a therapy category explodes, the companies supplying the tools get pulled along, and often bought.
Now the discipline, because this is where enthusiasm gets expensive. Obesity biotech is binary and badly overcrowded. For every small-cap with a genuine shot at the next blockbuster, a dozen are running me-too molecules that will quietly fail in the clinic. And many of the credible names already trade on takeout hope, which means a chunk of the premium is baked in before any deal is announced. The filter is differentiated, de-risked clinical data — an asset the giants can’t easily replicate and would rather buy. Everything else is a lottery ticket.
The takeaway is simple. The mega-cap headline is demand. The small-cap opportunity is the arms race that demand is funding. Lilly’s quarter didn’t just reward Lilly shareholders — it reminded every deal team in pharma that owning the future of obesity may be cheaper to buy than to build. Watch the small-caps holding data the giants can’t ignore.
CALGARY, AB, Aug. 5, 2026 /CNW/ — InPlay Oil Corp. (TSX: IPO) (TASE: IPO) (OTCQX: IPOOF) (“InPlay” or the “Company“) is pleased to announce that it has entered into a definitive agreement today to acquire a private oil and gas producer for cash consideration of $54.25 million, prior to closing adjustments (the “Acquisition“).
The Acquisition supports InPlay’s long-term strategy of building a disciplined and sustainable light oil focused growth company. The Acquisition builds on InPlay’s proven track record of executing highly accretive acquisitions, having successfully completed five strategic acquisitions over the past decade that have helped increase production 10x and grow total proved plus probable reserves 13.5x. The acquired assets are currently producing approximately 1,400 boe/d(1) (85% light oil and NGLs) which will increase InPlay’s production to over 20,100 boe/d(1) (62 – 63% light oil and NGLs), with light oil production expected to increase to over 10,500 bbl/d. The high oil weighting of the acquired assets further enhances InPlay’s strong netbacks, providing meaningful accretion to Adjusted Funds Flow (“AFF“)(2) and Free Adjusted Funds Flow (“FAFF“)(3) on a per share basis. The acquired assets generate strong cash flow and free cash flow which will enhance InPlay’s shareholder return strategy. InPlay is forecasted to generate FAFF of approximately $79 – $89 million for 2026 on a pro forma basis, including only four months for the acquired assets, which equates to a FAFF yield(3) of 20%. InPlay pays a dividend of $0.09 per month ($1.08 per year), which equates to a dividend yield of 7.2%. In addition, InPlay recently implemented a Normal Course Issuer Bid, pursuant to which the Company repurchased 0.5% of basic shares outstanding for cancellation during the month of June.
ACQUISITION HIGHLIGHTS
Highly Accretive Acquisition Metrics: Purchase price represents 2.0x net operating income(3) and 27% FAFF yield; per-share accretion of 18% to both AFF and FAFF on an annualized basis; 12% accretion to oil production per share, and 9% accretion to funds flow per barrel netback.
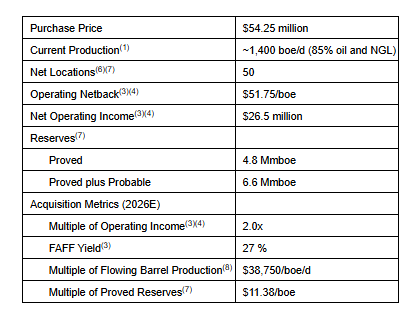
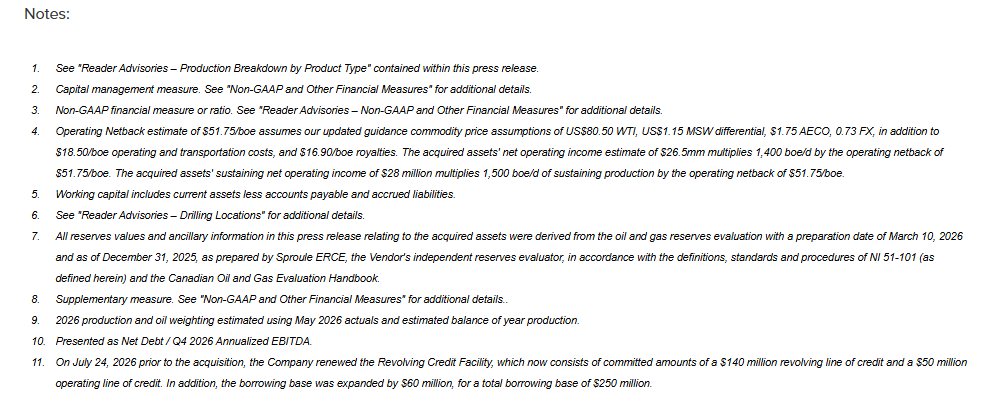
Enhanced Free Adjusted Funds Flow with Growth Potential: InPlay forecasts the acquired assets require sustaining capital of approximately $12 million to reach and maintain production of approximately 1,500 boe/d. Based on an operating netback(3) of approximately $51.75/boe(4), the acquired assets generate sustaining net operating income(3) of $28 million and FAFF of $16 million prior to accounting for synergies.
Acquired Assets are Contiguous with InPlay Assets Providing Significant Synergies: The acquired assets directly offset the Company’s existing operations and are supported by Company owned and operated facilities and infrastructure, creating meaningful operational synergies and enhancing the efficiency of future development. The Company expects to integrate the acquired assets without adding corporate office personnel. As a result of these synergies, the Acquisition is expected to generate approximately $2.5 million in annual cost savings, with the majority captured immediately post closing.
Expands InPlay’s Belly River Position: Pro forma the Acquisition, InPlay will be producing approximately 2,000 boe/d(1) from the Belly River, which at approximately 85% liquids weighting offers strong netbacks and high rate of return development opportunities.
Sustainability and Drilling Inventory: The acquired assets include 50 identified drilling locations, 75% of which are Tier 1 inventory(6) with expected payouts of less than 1.5 years at US $70/bbl WTI pricing.
“This Acquisition represents another important step in advancing InPlay’s strategy of building a disciplined, sustainable light oil company which includes strategic acquisitions” commented Doug Bartole, President and Chief Executive Officer of InPlay. “While modest in size, the Acquisition is a smart and highly accretive transaction that is expected to generate meaningful value relative to the capital invested. The acquired assets are highly complementary to our existing operations, provide meaningful operating and infrastructure synergies, and add a deep inventory of high-return drilling opportunities within our core area. The Acquisition is expected to be immediately accretive to adjusted funds flow and free adjusted funds flow per share, while maintaining conservative leverage and further enhancing our ability to generate sustainable returns for shareholders.”
ACQUISITION DETAILS
InPlay has entered into an arrangement agreement (the “Arrangement Agreement“) with a privately held arm’s length oil and gas producer (the “Vendor“), to acquire all of the issued and outstanding shares of the Vendor for cash consideration of $54.25 million, prior to closing adjustments. Concurrent with the execution of the Arrangement Agreement, certain shareholders of the Vendor, representing in excess of 72% of the Vendor shares outstanding, have entered into irrevocable written resolutions in support of the Acquisition. The Acquisition is expected to close by the end of August 2026, subject to the satisfaction or waiver of customary closing conditions.
The Acquisition will be funded by a draw on InPlay’s $190 million credit facility, with an expanded borrowing base totalling $250 million(11). Based on pro forma guidance as outlined below, InPlay anticipates Q4-2026 net debt to EBITDA(3) of 1.2x – 1.3x. The Company retains strong financial flexibility including an estimated working capital(5) surplus at June 30, 2026 of approximately $19.4 million and maintains unique access to the Israeli bond and equity markets. InPlay’s series A senior unsecured bonds (which are listed on the Tel Aviv Stock Exchange) are currently trading at a yield to maturity of approximately 6.1% and include a tap feature of approximately $115 million.
The acquired assets are currently producing approximately 1,400 boe/d with the latest well coming on stream in Q1 2026. InPlay plans to drill 2.0 net Belly River wells on the acquired assets post-closing and forecasts the acquired assets will require sustaining capital of approximately $12 million to reach and maintain annual average production of approximately 1,500 boe/d. Based on an operating netback of approximately $51.75/boe, the acquired assets generate sustaining net operating income of $28 million, resulting in sustaining FAFF of $16 million. The acquired assets contain 50 net drilling locations, and subject to supportive commodity prices, the acquired assets are expected to offer strong growth potential in excess of the target sustaining production.
The Acquisition’s purchase price represents approximately 2.0x operating income and is highly accretive to InPlay on both AFF and FAFF per share metrics while maintaining conservative corporate leverage ratios. A summary of the relevant metrics of the Acquisition is as follows:
OPERATIONS UPDATE
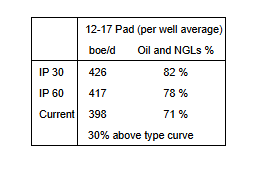
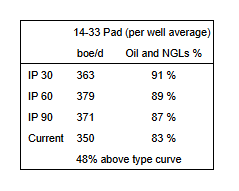
InPlay’s capital program for the second quarter of 2026 consisted of completing and bringing online three gross (3.0 net) Cardium wells in Pembina drilled in the first quarter of 2026, and the drilling and completion of three gross (3.0 net) additional Cardium wells also in Pembina. The most recent three wells were drilled approximately 40 days ahead of schedule, as the Company was able to access the field earlier than is normally anticipated during spring break-up. These wells were brought on production in late May and have materially exceeded internal expectations. Initial production (“IP“) rates for these three wells are as follows:
The three wells drilled in the first quarter continue to deliver strong results ahead of internal expectations. The IP rates for these wells are as follows:
InPlay’s year to date capital program has been completed below budget, resulting in strong capital efficiencies and continuing the “more with less” performance achieved in 2025. Supported by enhanced efficiencies and strong commodity prices, InPlay now plans to drill a total of 15.0 net Cardium wells in 2026, including 7.0 net Cardium wells during the second half of the year, for total capital expenditures of approximately $73 – $74 million, prior to incorporating the expanded pro forma capital program. This compares with InPlay’s original 2026 capital program of $66 million to $74 million, which contemplated the drilling of 12.0 to 14.0 net wells.
Additionally, InPlay plans to drill 2.0 net Belly River wells on the newly acquired assets, bringing the pro forma 2026 drilling program to a total of 17.0 net wells and combined capital expenditures of approximately $80 – $82 million.
In addition, InPlay plans to accelerate its asset retirement closure spend to reduce its decommissioning liability. This increase in asset retirement spending is supported by enhanced FAFF resulting from a more efficient 2026 capital program, stronger commodity prices and an expanded asset base associated with the Acquisition.
UPDATED 2026 PRO FORMA GUIDANCE
InPlay is also updating its previously announced 2026 guidance as follows:
ADVISORS
Burnet, Duckworth & Palmer LLP is acting as legal counsel to InPlay with respect to the Acquisition.
National Bank Financial Inc. (“NBF”) is acting as Exclusive Financial Advisor to the Vendor with respect to the Acquisition. NBF has provided the Vendor with a fairness opinion that the consideration to be received by the shareholders of the Vendor is fair, from a financial point of view, to the shareholders of the Vendor.
An updated corporate presentation will be available on our website in due course. For further information please contact:
Doug Bartole President and Chief Executive Officer InPlay Oil Corp. Telephone: (587) 955-0632
Kevin Leonard Vice President Corporate & Business Development InPlay Oil Corp. Telephone: (587) 955-0635
Wall Street woke up Wednesday to more of what it’s gotten all week: record highs, falling oil, and a fragile peace headline out of the Middle East. The financial press will lead with the Dow. The more useful question for anyone investing below the mega-cap tier is what cheaper crude actually does to small caps.
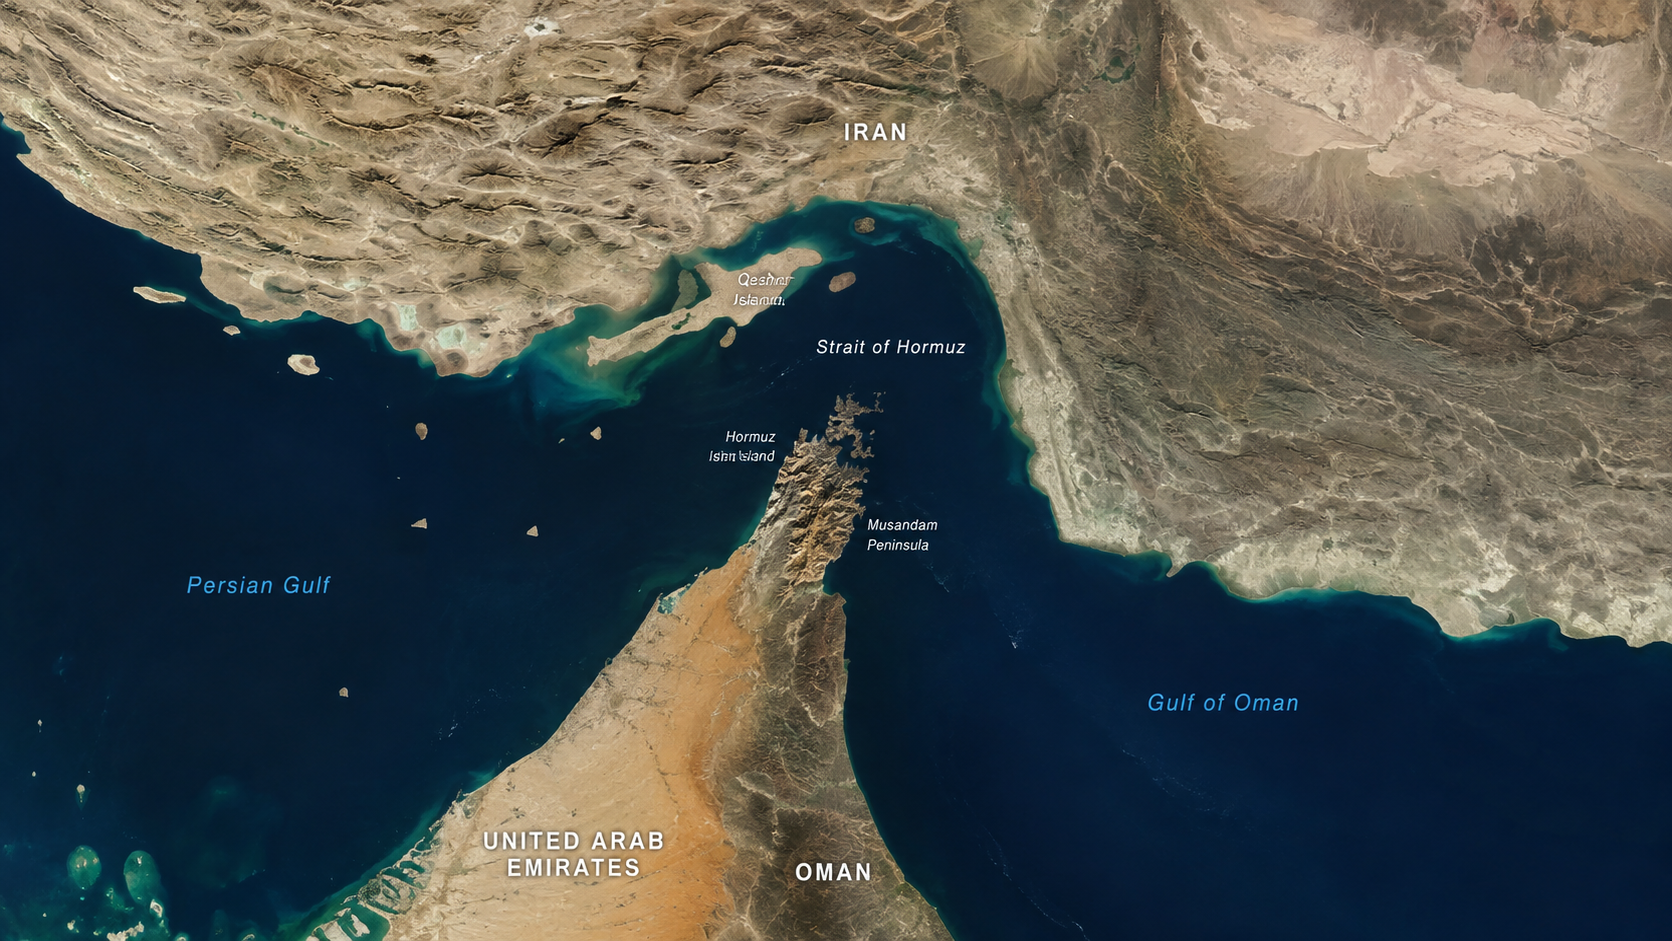
Start with the setup. After a searing rally that pushed the S&P 500 and Dow to record closes Tuesday, US futures steadied Wednesday morning. Oil fell for a third straight session — Brent slipped near $78 and WTI dropped under $75 — on growing hope that the Strait of Hormuz, the chokepoint for roughly a fifth of the world’s oil, could reopen. Qatar said a US–Iran proposal has been drafted, and Iran is reportedly weighing whether to let European navies clear mines from the waterway. Asia cheered it overnight, with South Korea’s KOSPI jumping 4%. Gold pushed higher, the VIX stayed calm, and Russell 2000 futures held firm.
Here’s why small-cap investors should care more than the headline suggests.
Small companies are the most exposed to the price of energy — and the most helped when it falls. They’re overwhelmingly domestic, they run thinner margins, and they lack the global hedging desks and pricing power of the mega-caps. When crude drops, the input-cost relief flows straight to the bottom line of small-cap industrials, transports, manufacturers, and consumer names. Cheaper oil is, in effect, a stealth margin boost for the exact companies that live closest to the edge on the income statement.
There’s a second-order effect that matters even more. Lower oil feeds disinflation, disinflation keeps the Fed’s rate-cut path alive, and small caps are the single most rate-sensitive corner of the market. Pair that with this week’s soft ADP jobs number and you get a macro mix that has historically favored the little guys.
Now the honest other side, because it cuts both ways. Energy is a meaningful slice of the Russell 2000, and cheaper crude squeezes small-cap exploration and production names hard. If your small-cap exposure leans toward oil and gas, this is a headwind, not a tailwind. The net effect depends entirely on what you own.
Step back, though, and the direction of travel is the story. The rally is finally broadening beyond the handful of AI mega-caps that carried it for two years — the Russell is joining the record run, not watching from the sidelines. A de-risking geopolitical backdrop, falling oil, and an easing Fed is the kind of trifecta that tends to reward the laggards. For two years, small caps have been the laggard.
One caveat to keep front and center: this peace is fragile, and a single headline could send oil right back up. Don’t build a thesis on a diplomatic maybe. But watch the setup. While everyone fixates on the Dow printing another record, the more interesting move may be one rung down the market-cap ladder — where the companies most helped by cheap oil and cheap money have been overlooked the longest.
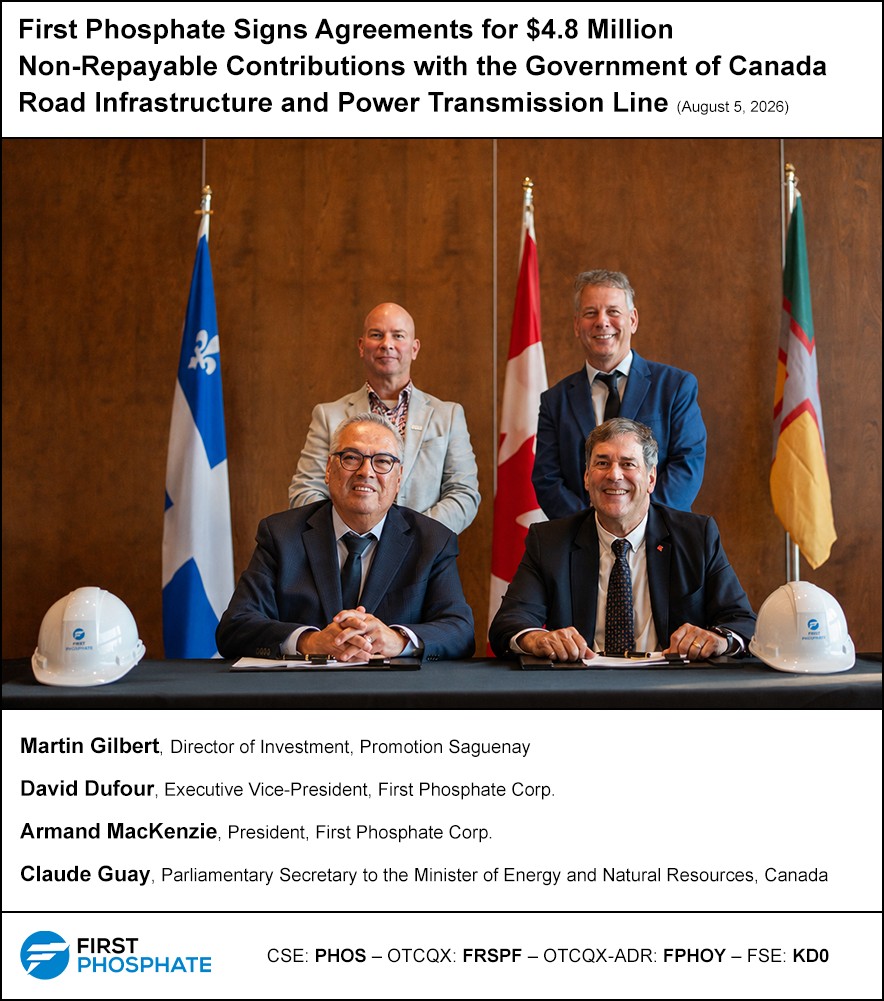
Saguenay, Québec–(Newsfile Corp. – August 5, 2026) – First Phosphate Corp. (CSE: PHOS) (OTCQX: FRSPF) (OTCQX ADR: FPHOY) (FSE: KD0) (“First Phosphate” or the “Company“) is pleased to announce that it has finalized additional agreements for a total of $4.84 million non-repayable contributions from the Government of Canada through Natural Resources Canada’s (“NRCan”) First and Last Mile Fund (“FLMF”) for the development of the Bégin-Lamarche Phosphate Deposit.
These contributions for $4.84 million comprise two components (power transmission infrastructure and road infrastructure) and build, in addition, to the $16.7M in funding already made available by NRCan in March 2026 through the Global Partnerships Initiative to support the advancement of First Phosphate’s Bégin-Lamarche deposit.
Power Transmission Line for the Sustainable Development of the Bégin-Lamarche Phosphate Deposit
First Phosphate will conduct a study to confirm the viability of clean energy infrastructure, including site selection and the identification of connection corridors, a feasibility study, and the design of a 161-kV transmission line and substations in the Saguenay-Lac-Saint-Jean region. The Project will include technical analyses, cost estimates, environmental studies, and public and Indigenous consultation. The total non-repayable contribution for this project will be approximately $3.07 million.
Road Infrastructure for the Responsible Development of the Bégin-Lamarche Phosphate Deposit
First Phosphate will carry out the preparatory work necessary for the construction of a new access road and will identify the preferred option for upgrading bypass roads to support transportation between the Bégin-Lamarche phosphate mine and regional infrastructure, including rail links and the Port of Saguenay. The Project will include pre-feasibility and feasibility studies (technical, environmental, and economic), design of the work, required environmental studies, as well as a traffic analysis and public and indigenous consultation. The total non-repayable contribution for this project will be approximately $1.77 million.
“Canada has what the world wants, and we are building the infrastructure required to get those resources to diverse markets,” said the Honourable Tim Hodgson, Minister of Energy and Natural Resources. “Investments like these help unlock our full potential by connecting projects to the infrastructure they need to move forward – creating jobs, strengthening supply chains and delivering lasting prosperity for Quebec and Canada.”
“Canada and Quebec have an opportunity to become a reliable supplier of the critical minerals the world needs for the technologies and industries of the future,” said Claude Guay, Parliamentary Secretary to the Minister of Energy and Natural Resources. “We are supporting critical minerals projects in Saguenay-Lac-Saint-Jean and beyond to strengthen Canadian supply chains, create economic opportunities, and build Canada Strong.”
“This support from the Government of Canada for First Phosphate sends a strong message to our investors and partners in Quebec, Canada, and internationally,” said Armand MacKenzie, President of First Phosphate. “It reinforces confidence in our ability to carry out this strategic mining project and deliver our high-purity igneous phosphate to the market on schedule.”
These projects will support the production of critical minerals in the Saguenay-Lac-Saint-Jean region of Quebec and address gaps in clean energy and transportation infrastructure that limit the production and expansion of critical minerals in the Saguenay-Lac-Saint-Jean region of Quebec. The financial contribution covers eligible activities planned through 2030, in accordance with the terms of the agreement.
Qualified Person
The scientific and technical disclosure for First Phosphate included in this news release has been reviewed and approved by Steeve Lavoie, P.Geo. Mr. Lavoie is Chief Geologist of First Phosphate and a Qualified Person under National Instrument 43-101 – Standards of Disclosure of Mineral Projects (“NI 43-101”).
About Natural Resources Canada
Natural Resources Canada (“NRCan”) is the federal department responsible for developing policies and programs to ensure the sustainable and responsible development of Canada’s natural resources. Through its initiatives and funding programs, including the First and Last Mile Fund, NRCan supports projects that contribute to stronger supply chains, industrial innovation, and Canada’s competitiveness in the energy, mining and forest products sectors.
About First Phosphate Corp
First Phosphate (CSE: PHOS) (OTCQX: FRSPF) (OTCQX ADR: FPHOY) (FSE: KD0) is a mineral exploration and development and clean technology company dedicated to building and reshoring a vertically integrated mine-to-market supply chain for the production of LFP batteries in North America. Target markets include energy storage, data centers, robotics, mobility, and national security.
First Phosphate’s flagship Bégin-Lamarche property, located in Saguenay-Lac-Saint-Jean, Québec, Canada, represents a rare North American igneous phosphate resource producing high-purity phosphate characterized by very low levels of impurities.
Forward-Looking Information and Cautionary Statements
This release includes certain statements that may be deemed “forward-looking information”. Any statement that discusses predictions, expectations, beliefs, plans, projections, objectives, assumptions, future events or performance (often but not always using phrases such as “expects”, or “does not expect”, “is expected”, “anticipates” or “does not anticipate”, “plans”, “budget”, “scheduled”, “forecasts”, “estimates”, “believes” or “intends” or variations of such words and phrases or stating that certain actions, events or results “may” or “could”, “would”, “might” or “will” be taken to occur or be achieved) are not statements of historical fact and may be forward-looking information. In particular, this press release contains forward-looking information relating to, among other things: completion and results of studies preparatory work, and the future production of critical minerals and the benefits arising therefrom.
Although the Company believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance and actual results or developments may differ materially from those forward-looking statements. Factors that could cause actual results to differ materially from those in forward-looking statements include market prices, development and exploration successes, and continued availability of capital and financing and general economic, market or business conditions. These statements are based on a number of assumptions including, among other things, assumptions regarding general business and economic conditions that engineering and construction timetables and capital costs for the Company’s, exploration, development and expansion projects are correctly estimated and not affected by unforeseen circumstances; the ability to obtain financing for its proposed operations on acceptable terms; no material deterioration in general business and economic conditions; no material delays in obtaining permits and other approvals; no significant disruptions affecting the activities of the Company or its ability to access required project equipment and services, and operating supplies in sufficient quantities and on a timely basis; inflation and prices for Company project inputs being approximately consistent with anticipated levels; the ability to complete the exploration and development programs consistent with the Company’s expectations; commodity price expectations including assumptions for P2O5; the Company’s relationship with local municipalities and First Nations remaining consistent with the Company’s expectations; the Company’s relationship with other third-party partners and suppliers remaining consistent with the Company’s expectations; and government relations and actions being consistent with Company expectations. Investors are cautioned that any such statements are not guarantees of future performance and actual results or developments may differ materially from those projected in the forward-looking statements. Accordingly, readers should not place undue reliance on the forward-looking information contained in this press release. The Company does not assume any obligation to update or revise its forward-looking statements, whether because of new information, future events or otherwise, except as required by applicable law. All forward-looking information contained in this release is qualified by these cautionary statements.
Follows Sales of Two Detention Facilities in California
BRENTWOOD, Tenn., Aug. 05, 2026 (GLOBE NEWSWIRE) — CoreCivic, Inc. (NYSE: CXW) (CoreCivic or the Company) announced today that it has completed the sales of its 1,600-bed Prairie Correctional Facility in Appleton, Minnesota and its 1,033-bed Midwest Regional Reception Center in Leavenworth, Kansas to the United States of America and its assigns, by and through the Department of Homeland Security for an aggregate gross sales price of $734.0 million, including $495.6 million for the Prairie Correctional Facility and $238.4 million for the Midwest Regional Reception Center. These purpose-built facilities were specifically designed to care for individuals in a secure environment. After federal and state income taxes of approximately $182.2 million and transaction costs, the Company anticipates its net proceeds from these asset sales to be approximately $522.5 million. The Company currently expects to use the net proceeds for general corporate purposes, which may include debt reduction and the repurchase of the Company’s common stock.
The Company currently expects to continue to operate the Prairie Correctional Facility and Midwest Regional Reception Center under the existing management contracts with Immigration & Customs Enforcement (ICE), although the terms of the management contracts may be modified to reflect the change in ownership. However, the Company can provide no assurance that it will continue to manage these facilities in the future, or that the terms of the existing management agreements will remain the same. As has always been the case, ICE has the ability to terminate the management contracts for non-appropriation of funds or for convenience. The management contracts for the Prairie Correctional Facility and Midwest Regional Reception Center expire in August 2031 and September 2027, respectively. Following the sale of these facilities, the Company will own or control via a long-term lease 61 correctional, detention, and reentry facilities with a total design capacity of approximately 67,000 beds and manage an additional eight facilities it does not own with a total design capacity of 13,000 beds.
Patrick Swindle, CoreCivic’s President and Chief Executive Officer, commented, “We are further demonstrating the value of the Company’s underlying real estate portfolio through the sales of our Prairie Correctional Facility and Midwest Regional Reception Center, following our sales of two detention centers in California last month. We remain committed to growing the Company’s businesses and returning value to our shareholders, while remaining a dependable and flexible partner for government.”
In addition to the recently completed facility sales, the Company has recently begun discussions with ICE about the potential acquisition of additional detention facilities from the Company. These discussions are in preliminary stages, and the Company can provide no assurance that any additional sales will occur.
About CoreCivic
CoreCivic is a diversified, government-solutions company with the scale and experience needed to solve tough government challenges in flexible, cost-effective ways. CoreCivic provides a broad range of solutions to government partners that help build safer, healthier, and more productive communities one person at a time through residential corrections, detention, and reentry management, complementary service offerings to the corrections industry that include pharmaceutical, transportation, and alternatives to incarceration, and government real estate solutions. CoreCivic is the nation’s largest owner of partnership correctional, detention and residential reentry facilities, and one of the largest operators of such facilities in the United States. CoreCivic has been a flexible and dependable partner for government for more than 40 years. CoreCivic’s employees are driven by a deep sense of service, high standards of professionalism and a responsibility to help government better the public good. Learn more at www.corecivic.com.
Forward-Looking Statements
This press release contains statements as to our beliefs and expectations of the outcome of future events that are “forward-looking” statements as defined within the meaning of the Private Securities Litigation Reform Act of 1995, as amended. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from the statements made. These include, but are not limited to, the risks and uncertainties associated with: (i) changes in government policy, legislation and regulations that affect utilization of the private sector for corrections, detention, and residential reentry services, in general, or our business, in particular, including, but not limited to, the continued utilization of our correctional and detention facilities by the federal government as a consequence of presidential executive orders, changes in how the federal government, including ICE, elects to use our detention capacity or otherwise procures alternative detention capacity, and the impact of any changes to immigration reform and sentencing laws (we do not, under longstanding policy, lobby for or against policies or legislation that would determine the basis for, or duration of, an individual’s incarceration or detention); (ii) our ability to obtain and maintain correctional, detention, and residential reentry facility management contracts because of reasons including, but not limited to, sufficient governmental appropriations, contract compliance, negative publicity and effects of inmate disturbances; (iii) changes in the privatization of the corrections and detention industry, the acceptance of our services, the timing of the opening of new facilities and the commencement of new management contracts (including the extent and pace at which new contracts are utilized), as well as our ability to utilize available beds; (iv) our ability to successfully activate idle facilities in a timely manner in order to meet the growth in demand for our facilities and services from the federal government that has occurred as a result of changes in policies and actions of the current presidential administration, and to realize projected returns resulting therefrom; (v) general economic and market conditions, including, but not limited to, the impact governmental budgets can have on our contract renewals and renegotiations, per diem rates, and occupancy; (vi) fluctuations in our operating results because of, among other things, changes in occupancy levels; competition; contract renegotiations or terminations including as a result of a change in facility ownership; inflation and other increases in costs of operations, including a rise in labor costs; fluctuations in interest rates and risks of operations; (vii) government budget uncertainty, the impact of debt ceilings and government shutdowns, including partial shutdowns, and changing budget priorities; (viii) our ability to successfully identify and consummate future development and acquisition opportunities, integrate their operations, and realize projected returns resulting therefrom; (ix) the availability of debt and equity financing on terms that are favorable to us, or at all; (x) our ability to successfully consummate the sales of additional company-owned assets, including the potential sale of additional facilities to ICE, on a timely basis and on commercially favorable terms; and (xi) the intended use of proceeds from the facility sales described in this press release. Other factors that could cause operating and financial results to differ are described in the filings we make from time to time with the Securities and Exchange Commission.
We take no responsibility for updating the information contained in this press release following the date hereof to reflect events or circumstances occurring after the date hereof or the occurrence of unanticipated events or for any changes or modifications made to this press release or the information contained herein by any third-parties, including, but not limited to, any wire or internet services, except as may be required by law.
Contact:
Investors: Jeb Bachmann – Managing Director, Investor Relations – (615) 263-3024 Media – Steve Owen – Vice President, Communications – (615) 263-3107