Lindblad Expeditions Expands Experiential Travel Portfolio With White Desert and Echo Charlie Acquisition

Lindblad Expeditions Holdings (NASDAQ: LIND) is making the largest acquisition in its history, acquiring a 60% majority stake in White Desert Antarctica and Echo Charlie for approximately $61 million in cash, plus roughly $6 million for cash on the balance sheet and customary adjustments.

The transaction gives Lindblad a stronger position in high-end experiential travel by adding a luxury Antarctic operator and a new aviation-focused adventure brand to a portfolio that already spans expedition cruising, wildlife travel, cycling, cultural trips and other specialty experiences. Lindblad said White Desert and Echo Charlie will continue to operate as stand-alone brands while gaining access to the company’s broader distribution, resources and operating platform.

For investors, the deal is notable not only because of its size relative to Lindblad’s acquisition history, but because it extends the company beyond its traditional marine-expedition roots and further into premium land- and air-based travel.

Adding Luxury Antarctica and Aviation to the Portfolio

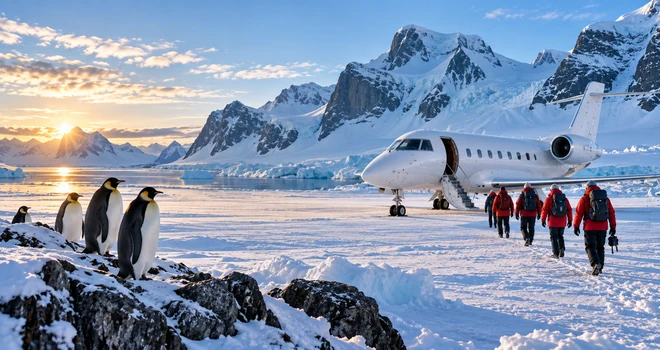
White Desert was founded in 2005 by polar explorer Patrick Woodhead and specializes in flying guests directly into the Antarctic interior.

Its itineraries include trips to the Geographic South Pole and visits to an Emperor penguin colony of more than 20,000 birds, combining access to remote areas with luxury accommodations and extensive logistics. The company employs more than 150 people from 18 nationalities and has built its brand around aviation, safety and small-scale high-end travel.

Echo Charlie takes the aviation concept outside Antarctica. The newer brand operates luxury adventure journeys aboard a restored DC-3 carrying just 12 guests, with itineraries designed around remote destinations including Colombia, Patagonia, the Faroe Islands and Greenland. Lindblad sees the platform as a way to broaden its reach into places that are difficult to access through conventional commercial travel.

Woodhead will remain chairman of White Desert and CEO of Echo Charlie and will also join Lindblad as Strategic Innovation Advisor. That founder-led continuity appears deliberate. Lindblad has used a similar model in prior acquisitions, allowing specialty brands to retain their identity while plugging into the parent company’s broader infrastructure and customer base.

Lindblad Continues Building a Multi-Brand Travel Platform

The transaction fits a strategy Lindblad has been pursuing for years: expanding from expedition cruising into a broader collection of differentiated travel businesses.

The company now describes itself as operating across air, land and sea, with brands including National Geographic-Lindblad Expeditions, Natural Habitat Adventures, Off the Beaten Path, DuVine Cycling + Adventure Co., Classic Journeys and Wineland-Thomson Adventures, along with White Desert and Echo Charlie.

Natural Habitat Adventures, for example, expanded Lindblad into land-based wildlife and ecotourism, including polar bear expeditions in Canada, Alaskan wildlife trips and African safaris. That acquisition helped establish the template for adding specialty experiential brands rather than simply expanding the company’s cruise fleet.

White Desert and Echo Charlie push that strategy further. Rather than purchasing additional ship capacity, Lindblad is adding specialized aviation capabilities and premium experiences that potentially allow it to serve existing customers in different ways. That could be important because affluent adventure travelers often purchase multiple types of trips rather than remaining loyal to a single travel format.

The Deal Comes as Lindblad’s Core Business Is Growing

Lindblad is making the acquisition from a position of improving operating momentum.

In the second quarter of 2026, total revenue increased 19% to $199.2 million, while adjusted EBITDA rose 31% to $32.5 million. Occupancy increased to 91% from 86%, and the Lindblad segment posted a record second-quarter net yield of $1,294 per available guest night.

The company also raised its full-year guidance alongside the acquisition announcement. Lindblad now expects 2026 tour revenue of $850 million to $880 million and adjusted EBITDA of $140 million to $148 million, reflecting both the additions of White Desert and Echo Charlie and continued strength in the existing business.

That backdrop matters because acquisitions are generally easier to absorb when the underlying platform is already growing. Lindblad is not relying solely on M&A to generate momentum; its existing operations have also been posting higher revenue, occupancy and yields.

Why Experiential Travel Is Attracting Investment

The broader industry backdrop helps explain the strategic appeal.

Adventure and experiential travel have moved well beyond a niche segment. The Adventure Travel Trade Association estimates the global outbound adventure-travel market at approximately $1.16 trillion, with 67% of international travelers classified as “open to adventure.” The organization says travelers increasingly prioritize new experiences, cultural connection, off-the-beaten-path destinations and sustainability.

Its 2026 industry survey also found that nearly 60% of adventure-tour operators reported revenue growth in 2025, while 61% expect higher net profits in 2026. Operators cited new customers, geographic expansion and product diversification as important drivers.

The luxury end of the market is particularly relevant to Lindblad’s acquisition. Virtuoso’s 2026 Luxe Report ranked Antarctica as the top adventure destination and one of the leading destinations on the rise. Expedition cruising was also among the year’s leading travel trends, while 45% of surveyed advisors reported increasing demand for “ultraluxe” travel such as highly private and hyper-personalized experiences.

Those trends line up closely with what White Desert and Echo Charlie offer: small guest counts, difficult-to-reach destinations and experiences that are difficult to replicate independently.

Luxury Travel Has Been More Resilient

Another factor is the relative strength of affluent travelers.

The broader travel market has become increasingly bifurcated, with value-conscious consumers becoming more selective while wealthier travelers continue spending on premium experiences. Travel industry analysts have noted that luxury cruising and highly differentiated experiences have generally held up better than mass-market categories in 2026.

That has encouraged more travel companies to move upscale. Luxury hotel brands including Ritz-Carlton, Four Seasons and others have been expanding into yachts and cruises, while expedition operators increasingly combine remote destinations with hotel-level service. The common theme is that the product is becoming less about transportation and more about access, exclusivity and the experience itself.

White Desert fits directly into that trend.

A Different Kind of Scale

Unlike conventional cruise acquisitions, the strategic value here is not necessarily about adding thousands of passengers.

Echo Charlie carries just 12 travelers at a time, and White Desert is built around small-scale Antarctic access. That scarcity is part of the product.

For Lindblad, the opportunity is therefore to expand the value of each customer relationship rather than simply add capacity. A traveler who has already booked a National Geographic-Lindblad expedition or a Natural Habitat wildlife trip may also be a potential customer for a White Desert Antarctic journey or a highly specialized Echo Charlie itinerary.

That creates cross-selling opportunities across brands while preserving the exclusivity that supports premium pricing. It also diversifies Lindblad geographically and operationally. The company remains heavily associated with ships and expedition cruising, but the portfolio increasingly includes land and aviation experiences that do not depend on adding cruise capacity.

Travelzoo Offers Another View Into Experiential Travel Demand

Investors interested in the broader experiential travel theme can also look at Travelzoo (NASDAQ: TZOO), which is covered by Noble Capital Markets.

Travelzoo operates a global travel and experiences platform that connects its members with curated travel, entertainment and lifestyle offers. While its business model differs significantly from Lindblad’s direct ownership of expedition brands, both companies participate in a travel market increasingly shaped by consumers seeking distinctive experiences rather than simply transportation and lodging.

Noble Capital Markets provides research coverage of Travelzoo, giving Channelchek readers another publicly traded company through which to follow trends in premium and experiential travel.

Building a Broader Experiential Travel Company

The White Desert and Echo Charlie acquisition represents more than an expansion of Lindblad’s Antarctica business.

It advances the company’s transformation from a primarily expedition-cruise operator into a diversified experiential travel platform spanning ships, wildlife expeditions, cycling tours, cultural travel and now specialized aviation.

The immediate financial contribution remains relatively modest compared with Lindblad’s overall revenue base, but strategically the transaction opens another avenue for selling premium experiences to a customer base already inclined toward remote and adventure-oriented travel.

With adventure tourism becoming increasingly mainstream while affluent travelers continue prioritizing highly personalized experiences, Lindblad is betting that the next stage of growth will come not simply from carrying more passengers, but from offering more ways to reach places most travelers cannot easily reach on their own.
Addus HomeCare to Acquire AccentCare Personal Care Division for $275 Million

Addus HomeCare (NASDAQ: ADUS) is expanding its footprint in the home-based care market with an agreement to acquire the personal care division of AccentCare for approximately $275 million.

The transaction covers AccentCare’s personal care operations outside New York and does not include its home health or hospice businesses. The acquired operations serve an average daily census of approximately 13,700 clients across 10 states and are expected to contribute roughly $280 million in annualized revenue to Addus.

Addus said the deal would increase its revenue base by approximately 19% and is expected to be accretive to financial results. The company plans to fund the acquisition through a combination of cash on hand and borrowings under its revolving credit facility.

Expanding Scale in Personal Care

Personal care is already the largest part of Addus’ business.

Unlike skilled home health, which typically involves nurses or therapists providing medically necessary services, personal care generally helps patients with activities of daily living such as bathing, dressing, meal preparation and mobility.

Addus primarily serves elderly, chronically ill and disabled individuals who might otherwise be at greater risk of hospitalization or institutional care. Its payors include government agencies, managed care organizations, insurers and private-pay clients.

That business has also been the company’s primary growth engine. Personal care represented 78.4% of Addus revenue in the second quarter of 2026, while organic revenue in the segment increased 6.8% from a year earlier. Addus has benefited from both increased service volumes and reimbursement increases in important markets including Texas and Illinois.

The AccentCare transaction adds considerable scale to that existing operation.

More Density — and Six New States

The acquisition strengthens Addus in four states where it already has significant personal care operations: Texas, Illinois, California and Arizona.

It also adds operations in Colorado, Georgia, Minnesota, Pennsylvania, Tennessee and Washington, giving Addus entry into six additional markets through the transaction.

For a labor-intensive business like home care, geographic density can matter. Larger local operations can improve caregiver recruiting, scheduling and administrative efficiency while also making a provider more important to managed care organizations and other payors looking for partners capable of serving broad patient populations.

Addus Chairman and CEO Dirk Allison said the acquisition would deepen the company’s presence in key markets while strengthening its ability to work with managed care and value-based care partners.

After the transaction, Addus will be adding those operations to an organization that already serves roughly 62,500 consumers through 264 locations across 24 states.

Why Home-Based Care Continues to Attract Buyers

The transaction also reflects a broader consolidation trend across home-based healthcare.

The long-term investment case is relatively straightforward: the U.S. population is aging, many patients would prefer to receive care at home, and home-based services can often be less expensive than institutional settings such as skilled nursing facilities.

Those characteristics have continued to attract strategic buyers and private-equity-backed operators despite a more difficult reimbursement and labor environment. Industry data show 55 home health and hospice transactions were announced during the first half of 2026, only modestly below the 58 transactions recorded during the same period last year.

Personal care can be particularly attractive because demand is tied closely to long-term demographic trends rather than episodic medical procedures.

The business is not without challenges. Recruiting and retaining caregivers remains difficult across the industry, while reimbursement levels — particularly in Medicaid-funded programs — can have a substantial impact on margins. Buyers have consequently become more selective, placing greater emphasis on operating quality, reimbursement exposure, compliance and local market density.

That environment tends to favor larger operators with established infrastructure and access to capital.

Addus Has Been an Active Consolidator

The AccentCare deal is consistent with a strategy Addus has been pursuing for several years.

The company completed three acquisitions during 2025 and has continued adding operations in 2026, including personal care assets in Indiana. Management has repeatedly said acquisitions remain an integral component of its growth strategy, particularly where transactions allow Addus to increase density in existing markets or enter attractive new geographies.

On the company’s most recent earnings call, Allison said Addus was seeing an increased number of personal care businesses come to market as sellers became more comfortable with the reimbursement environment.

He also indicated that the company remained active in evaluating transactions, suggesting the AccentCare agreement may be part of a broader consolidation strategy rather than a one-off expansion.

The $275 million purchase price is also significant relative to the approximately $280 million in annualized revenue Addus expects to acquire, although revenue alone does not indicate the profitability or ultimate economics of the transaction.

AccentCare Narrows Its Focus

For AccentCare, the agreement represents a partial portfolio reshaping rather than an exit from home-based healthcare.

The company will retain its home health, palliative care and hospice businesses, which together form a large national post-acute care platform. AccentCare says it serves more than 200,000 patients and clients annually across more than 280 locations in 30 states and the District of Columbia.

AccentCare CEO Laura Tortorella said Addus was a natural owner for the personal care operation because of its focus and scale in the segment, while the transaction allows AccentCare to continue concentrating on its remaining care businesses.

Building a Larger Home-Care Platform

For Addus, the strategic rationale is primarily about scale.

The company is adding approximately 13,700 daily clients, $280 million of annualized revenue and a broader geographic footprint to a personal care business that already represents nearly four-fifths of its revenue.

That scale could become increasingly important as home-based healthcare evolves toward larger managed-care relationships and value-based reimbursement arrangements. Larger operators are generally better positioned to invest in technology, caregiver recruitment, compliance and administrative infrastructure while serving patients across multiple markets.

The transaction still requires regulatory approvals and customary closing conditions, and Addus has not yet provided a specific closing date.

If completed as planned, however, the AccentCare acquisition would further establish Addus as one of the larger multi-state personal care providers at a time when demographic trends, healthcare costs and patient preferences continue pushing more care into the home.

Copart Makes Largest-Ever Acquisition With $1.9 Billion Deal for ACV Auctions

Copart (NASDAQ: CPRT) is making the largest acquisition in its history, agreeing to buy ACV Auctions (NYSE: ACVA) for approximately $1.9 billion in cash in a deal that would significantly broaden Copart’s reach across the vehicle remarketing market.

Under the agreement announced Thursday, Copart will pay $10.50 per share for ACV, representing a premium of approximately 45% to ACV’s unaffected closing price on August 10, the last trading day before reports of a potential transaction surfaced, and a 41% premium to its 30-day volume-weighted average price through September 9. The deal is expected to close by the end of 2026, subject to customary conditions.

Investors responded quickly. ACV shares surged roughly 44% in premarket trading Friday, moving close to the $10.50 offer price, while Copart shares were also higher before the open.

Expanding Beyond Salvage Auctions

Copart is best known for online auctions of salvage and damaged vehicles, with a global buyer network spanning approximately 1 million members in more than 185 countries. The company operates more than 250 locations across 11 countries and sold more than 4 million vehicles over the past year.

ACV gives Copart a much stronger position in a different part of the market: dealer-to-dealer wholesale vehicle sales.

ACV operates a digital marketplace that allows dealers and commercial sellers to buy and sell used vehicles online, supported by inspection technology, vehicle condition data and AI-powered valuation tools. That business complements Copart’s strength in salvage disposition and international resale, allowing the combined company to participate across more of the vehicle lifecycle.

Management describes the combination as creating a full-spectrum digital remarketing platform spanning dealer trade-ins, wholesale remarketing, salvage disposition and international resale.

What Vehicle Remarketing Actually Means

Vehicle remarketing is the process of reselling used vehicles after they leave their original owner, lease, rental fleet, insurance claim or dealership inventory.

It is a large but fragmented ecosystem. Insurance companies sell damaged or totaled vehicles. Dealers wholesale cars they do not want to keep in inventory. Rental companies and fleet operators periodically dispose of large numbers of vehicles. Financial institutions remarket repossessed or off-lease vehicles.

Historically, many of those transactions ran through physical auctions. Increasingly, they are moving online.

Copart helped pioneer that transition in salvage vehicles, while ACV built a digital-first marketplace aimed primarily at dealers. Bringing the two together gives Copart access to a much broader pool of vehicles before they ever reach the salvage portion of the market.

That is the strategic logic behind the transaction: rather than serving only one segment of the resale process, Copart wants to participate in more of the market from the time a vehicle leaves a dealership or fleet through its eventual wholesale, salvage or export sale.

ACV Adds Data and Technology

The acquisition is not only about auction volume.

ACV has invested heavily in inspection technology and data services designed to give buyers more confidence when purchasing vehicles remotely. Its tools include digital condition reports, valuation systems and AI-driven inventory analytics for dealers.

Copart said combining those capabilities with its own technology and extensive vehicle dataset could create one of the industry’s largest pools of vehicle condition information. Management believes that data can support improved pricing, inspection and resale decisions across the combined platform.

The companies also see potential to cross-sell buyers and sellers between their marketplaces, expand transportation services and grow commercial vehicle activity.

Scale Matters in Online Auto Auctions

The economics of vehicle marketplaces tend to improve with scale.

More sellers attract more buyers, while more buyers can improve auction liquidity and pricing for sellers. A larger transaction base also generates more vehicle data, which can improve valuation models and inspection tools.

Copart already brings substantial physical infrastructure to that equation. Its more than 250 locations provide storage, logistics and processing capabilities that ACV, as a more digitally focused business, does not have at the same scale. ACV contributes a national dealer and inspector network along with its dealer-facing technology.

That combination gives the merged business both digital reach and physical infrastructure — an increasingly important distinction as the auto-auction industry moves further online.

A New Growth Avenue for Copart

The deal also comes as Copart looks for additional growth beyond its core salvage business.

Recent industry commentary has pointed to slower vehicle-volume growth in some parts of the salvage market, creating an incentive for established operators to broaden their exposure to traditional wholesale vehicles and technology-enabled services.

ACV provides that expansion immediately.

Copart said the transaction should accelerate revenue growth and expects it to be roughly neutral to earnings per share in the first full year of ownership before becoming accretive beginning in fiscal 2028. The company plans to fund the acquisition entirely with cash on hand, and the transaction is not subject to a financing condition.

ACV will continue operating as an independent subsidiary of Copart under its existing leadership after the acquisition closes.

Market Reaction Reflects the Deal Premium

The sharp move in ACV shares is largely a straightforward response to the acquisition price.

The stock jumped more than 40% after the announcement and traded near the $10.50 cash offer Friday morning, effectively closing much of the gap between its prior market price and the agreed transaction value.

Interestingly, investors also reacted positively to Copart. Its shares rose about 6% in premarket trading despite the company reporting quarterly results that were somewhat softer than expected, suggesting the market sees meaningful strategic value in the acquisition.

That is notable because large acquisitions often pressure the buyer’s stock initially as investors weigh integration costs, execution risks and the price being paid.

In this case, the early reaction suggests investors are focused on the opportunity for Copart to expand into a larger portion of the vehicle remarketing market.

Building an End-to-End Vehicle Marketplace

For Copart, ACV represents more than simply adding another auction platform.

The acquisition gives the company an immediate foothold in dealer-to-dealer wholesale vehicles, adds a suite of data and valuation technologies and expands the number of transactions that can flow through its global buyer network and physical infrastructure.

It also moves Copart closer to becoming an end-to-end vehicle remarketing platform capable of serving vehicles across a much broader range of conditions and ownership situations.

For investors, the question now becomes whether Copart can successfully connect ACV’s dealer marketplace with its own enormous global auction network and infrastructure.

If it can, the company’s largest-ever acquisition could open a meaningful new growth channel well beyond the salvage auctions that built the business.

Neurocrine to Acquire Soleno Therapeutics, Expanding Rare Disease and Endocrinology Portfolio

Neurocrine Biosciences (NASDAQ: NBIX) announced it has entered into a definitive agreement to acquire Soleno Therapeutics (NASDAQ: SLNO) for $53.00 per share in cash, representing a total equity value of approximately $2.9 billion. The offer reflects a premium of roughly 34% to Soleno’s April 2 closing price and 51% to its 30-day volume-weighted average price.

The acquisition adds VYKAT™ XR (diazoxide choline), the first and only FDA-approved treatment for hyperphagia in Prader-Willi syndrome (PWS), to Neurocrine’s growing portfolio of first-in-class therapies. The transaction is expected to close within 90 days, subject to customary conditions and regulatory approvals.

Expanding a High-Growth Portfolio

With the addition of VYKAT XR, Neurocrine will have three marketed, first-in-class therapies:

  • INGREZZA® (valbenazine) – a VMAT2 inhibitor for tardive dyskinesia and Huntington’s chorea, generating $2.51 billion in 2025 revenue
  • CRENESSITY® (crinecerfont) – approved in late 2024 for congenital adrenal hyperplasia, with $301 million in 2025 revenue
  • VYKAT XR – approved in March 2025 for PWS, delivering $190 million in 2025 revenue

Together, these therapies position Neurocrine for sustained revenue growth and portfolio diversification through the end of the decade.

A Transformative Therapy in a High-Unmet-Need Market

VYKAT XR addresses hyperphagia, the defining and life-threatening symptom of Prader-Willi syndrome, a rare genetic disorder affecting approximately 10,000 patients in the U.S. The condition leads to persistent hunger, compulsive food-seeking behavior, and significant metabolic and behavioral challenges.

Since its U.S. launch in the second quarter of 2025, VYKAT XR has seen strong early adoption, including $92 million in fourth-quarter revenue alone. The therapy is expected to generate approximately $450 million in revenue this year and is supported by intellectual property protection extending into the mid-2040s.


“This transaction will advance Neurocrine’s mission to deliver life-changing treatments while accelerating our revenue growth and portfolio diversification strategy,” said Kyle W. Gano, Ph.D., Chief Executive Officer of Neurocrine. “We look forward to expanding VYKAT XR’s reach and strengthening our leadership in delivering transformative medicines.”

Strategic Entry Into Metabolic Disease

The acquisition also marks Neurocrine’s entry into metabolic disorders, complementing its existing endocrinology focus. This comes as the broader market sees heightened competition following the success of GLP-1 drugs such as Eli Lilly’s Zepbound and Novo Nordisk’s Wegovy.

Neurocrine believes its expertise in CRF1 receptor antagonists and endocrine pathways may offer differentiated approaches, particularly in addressing concerns around muscle loss associated with current obesity treatments.

Analysts suggest the deal provides a more immediate and practical pathway into metabolic disease compared to earlier-stage internal programs, which still face regulatory and competitive hurdles.

Financial and Transaction Details

Under the agreement, Neurocrine will launch a tender offer to acquire all outstanding Soleno shares. Following completion, a subsidiary will merge with Soleno, converting remaining shares into the same $53.00 per share cash consideration.

The transaction will be funded through a combination of cash on hand and a modest amount of pre-payable debt. Notably, the deal is not subject to financing conditions.

Both companies’ boards have approved the transaction.

Market Reaction

Shares of Soleno surged approximately 34.5% in premarket trading following the announcement, reflecting investor confidence in the deal’s premium and strategic rationale.

Outlook

The acquisition is expected to:

  • Strengthen Neurocrine’s leadership in rare disease and endocrinology
  • Expand its commercial footprint with a durable, first-in-class therapy
  • Enhance long-term revenue visibility and growth profile
  • Deliver operational synergies through integration

With VYKAT XR as a foundational asset and continued pipeline progress, Neurocrine is positioning itself for sustained value creation in both rare disease and metabolic markets.

Global M&A Hits $2.6 Trillion in 2025, Fueled by AI and Growth Ambitions

Key Points:
– Global M&A value reaches $2.6 trillion YTD, the highest since the 2021 post-pandemic surge.
– AI, big tech, and private equity lead activity despite fewer total deals and tariff tensions.
– U.S. megadeals and renewed corporate confidence drive optimism for more deals ahead.

Global mergers and acquisitions (M&A) activity has surged to $2.6 trillion year-to-date, making 2025 the most active year since the 2021 boom, as companies aggressively pursue growth and innovation—particularly in artificial intelligence. The total value of deals has risen 28% from the same period last year, even though the actual number of transactions is down 16%, according to data from Dealogic.

Several U.S. megadeals have fueled the resurgence, including Union Pacific’s proposed $85 billion acquisition of Norfolk Southern and OpenAI’s massive $40 billion funding round led by Japan’s SoftBank. These transactions signal a bold appetite for scale and future-proofing in the face of evolving technologies and regulatory dynamics.

What’s driving this momentum? Experts say companies are seeking to stay ahead in a transformative AI race, while adapting to a more settled political and regulatory environment following the initial uncertainties surrounding the Trump administration’s trade tariffs and antitrust posture.

Private equity has also re-entered the scene with major moves. Examples include Sycamore Partners’ $10 billion buyout of Walgreens Boots Alliance and Advent’s revised $6.4 billion bid for UK firm Spectris. These moves show that buyout firms are growing confident in valuations and exit opportunities once again.

While healthcare led the charge in previous years, technology and electronics are now driving deal volume, especially in the U.S. and UK. Notable moves include Samsung’s $1.7 billion acquisition of FlaktGroup, which specializes in data center cooling—an essential infrastructure for AI systems.

The largest deal in EMEA this year came from Palo Alto Networks, which acquired Israeli cybersecurity company CyberArk for $25 billion. Rising AI-driven threats have made cybersecurity a top priority, prompting record valuations in the space.

Looking ahead, dealmakers at JPMorgan and other institutions remain bullish. The combination of AI demand, digital infrastructure needs, and steady leadership in corporate boardrooms suggests that the second half of 2025 could see even more high-profile M&A activity.

For further insights on cross-border opportunities, especially for European healthcare and life sciences firms, explore our on-demand webinar: Beyond Borders: Unlocking U.S Growth for European Health Care & Life Sciences.

Social Mobile to Acquire Sonim Technologies in $20 Million All-Cash Deal

Deal Enhances Social Mobile’s Position in Enterprise Mobility and Expands Carrier Channel Reach

In a strategic move to strengthen its leadership in the enterprise mobility space, Social Mobile announced it has entered into a definitive agreement to acquire the assets and liabilities of Sonim Technologies (NASDAQ: SONM). The all-cash transaction is valued at $20 million, including a $5 million potential earn-out, and is expected to close in the fourth quarter of 2025, pending customary closing conditions.

The acquisition aligns with Social Mobile’s long-term strategy to expand its footprint in the purpose-built enterprise mobility market. Sonim Technologies, known for its rugged mobile solutions trusted by first responders, government agencies, and Fortune 500 companies, brings a complementary product portfolio and proven expertise in mission-critical communications to Social Mobile’s custom enterprise offerings.

“This acquisition creates a powerful synergy between Sonim’s durable, field-tested devices and Social Mobile’s scalable, custom mobility solutions,” said a spokesperson for Social Mobile. “Together, we are better positioned to deliver innovative, secure, and tailored mobility ecosystems that meet the evolving needs of our global clients.”

Sonim’s Board of Directors has approved the agreement.

Founded in 1999, Sonim Technologies has established itself as a leading U.S. provider of ultra-rugged phones, wireless data devices, and accessories, with a distribution footprint across North America, EMEA, and Asia-Pacific. The company’s products are widely adopted in industries where durability, security, and performance are non-negotiable.

For Social Mobile, a Google-certified Android Enterprise Gold Partner, this acquisition not only enhances its enterprise-grade product suite but also significantly expands its sellable addressable market, particularly through carrier channels where Sonim has longstanding relationships.

Social Mobile specializes in developing custom mobility solutions for clients across healthcare, transportation, retail, and defense. With over 15 million devices distributed globally, the company offers end-to-end services from design and deployment to lifecycle management, ensuring product availability and operational efficiency at scale.

As enterprise mobility demand continues to rise, the combined capabilities of Social Mobile and Sonim are expected to unlock new revenue opportunities and deliver greater value to customers looking for rugged, reliable, and custom-built mobile solutions.

Novartis to Acquire Regulus Therapeutics in $1.7 Billion Biotech Buyout

Key Points:
– Novartis to acquire Regulus for up to $1.7B, including $7/share upfront and $7/share tied to farabursen approval.
– Farabursen, a potential first-in-class ADPKD treatment, heads into Phase 3 with FDA alignment.
– Boosts Novartis’s kidney disease pipeline and commitment to innovation in rare conditions.

Novartis AG announced plans to acquire Regulus Therapeutics Inc. in a transaction valued at up to $1.7 billion, reinforcing the Swiss pharmaceutical giant’s strategy to deepen its portfolio in renal and genetic disease treatments. The deal includes an upfront cash payment of $7.00 per share, representing approximately $800 million in equity value, and an additional $7.00 per share tied to a regulatory milestone via a contingent value right (CVR), pending approval of Regulus’s lead drug candidate, farabursen.

Farabursen is being developed as a novel treatment for autosomal dominant polycystic kidney disease (ADPKD), a condition with limited current options and significant unmet clinical need. If approved, farabursen could become the first systemic therapy of its kind in this indication, offering a potentially superior safety and efficacy profile compared to existing treatments.

The acquisition reflects a growing trend in the biopharma sector where large-cap pharmaceutical companies pursue innovative pipelines through targeted M&A. In recent quarters, the industry has seen an uptick in transactions focused on small to mid-sized biotech firms that specialize in high-impact therapies for rare or underserved diseases. Regulus’s focus on microRNA-based therapies, a field once viewed as experimental, is now receiving renewed attention as advances in RNA technology improve target precision and therapeutic delivery.

For Novartis, the move expands its nephrology franchise and bolsters its pipeline in genetic disorders, aligning with the company’s long-term innovation strategy. Financially, the deal signals confidence in both Regulus’s platform and farabursen’s development prospects. The 274% premium to Regulus’s 60-day volume-weighted average price underscores the strategic value Novartis sees in the program.

The transaction is expected to close in the second half of 2025, subject to regulatory approval and the successful tender of a majority of Regulus’s outstanding shares. Once finalized, Regulus will become a wholly owned subsidiary of Novartis, with its operations and development programs integrated into Novartis’s global R&D structure.

The deal may also serve as a bellwether for continued consolidation in biotech, particularly among companies advancing oligonucleotide or RNA-based therapeutics. Investors are likely to see the acquisition as further validation of microRNA platforms, potentially reinvigorating interest in similar early-stage biotech firms.

At a time when cost pressures and generic competition are accelerating across the pharmaceutical landscape, acquiring promising assets with a clear regulatory path remains a preferred strategy for growth. For Regulus, integration with Novartis offers the financial and operational muscle needed to take farabursen through the final stages of development and, if approved, to global markets.

As the biotech sector continues to recalibrate from recent valuation contractions, strategic acquisitions like this illustrate the enduring value of focused innovation, especially in areas with limited treatment alternatives and high unmet demand.

TPG to Acquire Altus Power in $2.2 Billion Deal

Key Points:
– TPG Rise Climate will acquire Altus Power for $5.00 per share in a $2.2 billion deal, taking the company private to accelerate clean energy expansion.
– Altus Power’s Board of Directors unanimously approved the transaction, which represents a 66% premium to its October 2024 stock price and is expected to close in Q2 2025.
– This acquisition aligns with TPG Rise Climate’s strategy to scale climate solutions, leveraging its expertise in clean energy infrastructure to support Altus Power’s growth.

Altus Power, the largest owner of commercial-scale solar in the U.S., has announced that it has entered into a definitive agreement to be acquired by TPG through its TPG Rise Climate Transition Infrastructure strategy. Under the terms of the agreement, TPG will acquire Altus at $5.00 per share, valuing the company at approximately $2.2 billion, including outstanding debt. Upon completion of the transaction, Altus Power will become a privately held company.

Strategic Rationale and Market Impact

On October 15, 2024, Altus Power initiated a formal review of strategic alternatives. Today’s purchase price represents a 66% premium to Altus’ closing price on that date. The company expects this acquisition to bolster its ability to provide greater value to both commercial and Community Solar customers while expanding access to clean electric power.

“This transaction represents a pivotal moment for Altus Power,” said Gregg Felton, CEO of Altus Power. “We are incredibly excited to partner with TPG Rise Climate to continue to build our position as the leading commercial-scale provider of clean electric power to businesses and households from coast to coast. TPG Rise Climate’s deep expertise in the clean energy sector, investment-oriented mindset, and value-driven approach to infrastructure development align perfectly with our vision. This partnership strengthens our ability to serve both our Community Solar and commercial clients with clean electric power at a time when demand for power is expected to grow substantially. As a private company, Altus Power will be better positioned for continued long-term growth, which we believe will allow us to scale our operations, drive innovation, and enhance the value we deliver to our customers. Together with TPG Rise Climate, we believe we are poised to accelerate clean energy adoption and ensure more businesses and communities have access to the power they need for a sustainable future.”

Transaction Details

  • The Board of Directors of Altus has unanimously approved the transaction and recommends that Altus stockholders vote to adopt the merger agreement.
  • The deal is contingent upon majority approval by Class A stockholders.
  • The transaction is expected to close in Q2 2025.

About TPG Rise Climate

TPG Rise Climate is the dedicated climate investing platform of TPG, a leading global alternative asset management firm. With dedicated pools of capital across private equity, transition infrastructure, and the Global South, TPG Rise Climate focuses on climate-related investments that benefit from the expertise of TPG’s investment professionals and its global network of executives, advisors, and corporate partners. As part of TPG’s $25 billion global impact investing platform, TPG Rise Climate invests broadly in the climate sector, emphasizing clean electrons, clean molecules and materials, and negative emissions.

About Altus Power

Altus Power is a leader in commercial-scale solar energy, providing clean, renewable energy solutions for businesses and communities across the U.S. The company is currently traded on the New York Stock Exchange under the ticker symbol AMPS.

Above Food to Acquire Palm Global Technologies, Expanding into Agri-Tech and Sustainable Innovation

Key Points:
– Above Food Ingredients Inc. (NASDAQ: ABVE) has signed a Letter of Intent to acquire Palm Global Technologies Ltd. in a $180 million share exchange, expanding into Agri-Tech, FinTech, and carbon credit securitization.
– Palm Global’s proprietary AI, blockchain, and decentralized finance technologies will enhance Above Food’s vertically integrated food systems, supporting sustainable agriculture and economic empowerment for millions of farmers.
– Following the acquisition, Palm Global’s Peter Knez will become Chairman and CEO of the combined companies, with definitive agreements expected to be finalized and closed in the near term.

Above Food Ingredients Inc. (NASDAQ: ABVE), a leader in sustainable, vertically integrated food systems, has signed a Letter of Intent (LOI) to acquire Palm Global Technologies Ltd., a next-generation innovator in technology, sustainability, and global food markets. The acquisition is expected to strengthen Above Food’s position in Agri-Tech, FinTech, and carbon credit securitization, further advancing its commitment to sustainable food production and innovation.

Strategic Rationale and Industry Impact

The transaction will integrate Above Food’s vertically integrated food systems with Palm Global’s groundbreaking technologies, alliances, and global reach. Palm Global’s proprietary AI, blockchain, and decentralized finance technologies are designed to drive economic empowerment, education, and sustainable growth, particularly in underserved markets, benefiting tens of millions of farmers worldwide.

“This transformative acquisition positions Above Food to redefine global agriculture and sustainability while unlocking a number of significant opportunities in high-growth markets,” said Lionel Kambeitz, Founder and CEO of Above Food. “Palm Global’s innovative technologies, combined with its mission to drive economic empowerment, align perfectly with our vision for sustainable food solutions worldwide.”

Palm Global’s Technological and Strategic Contributions

  • AI, Blockchain, and DeFi Technologies – Palm Global’s solutions enhance efficiency, security, and accessibility in the global food supply chain.
  • Partnerships with Governments and Institutions – Palm Global collaborates with entities like the Peace for Life Foundation, IIMSAM, and global institutions to accelerate technology adoption among farmers.
  • Strategic Global Alliances – The acquisition allows Above Food to leverage Palm Global’s extensive partnerships to develop, utilize, and maximize R&D capabilities in agronomy and genomics.

The newly combined entity will enable innovative initiatives such as regenerative agriculture and grow-to-order food solutions, creating customized approaches to meet evolving consumer and agricultural needs.

Transaction Details and Leadership Transition

  • The LOI outlines a share exchange valuing Palm Global at approximately $180 million.
  • Definitive agreements are expected this month, with approvals and closing anticipated soon after.
  • Peter Knez, currently on Palm Global’s Board of Directors, will assume the role of Chairman and CEO of the combined companies.

Future Outlook

This merger is set to enhance global food security, promote sustainable agriculture, and create economic opportunities in underserved markets through technological innovation and strategic partnerships. By combining resources, Above Food and Palm Global aim to drive the next wave of transformation in sustainable food production and agricultural technology.

Teladoc Health to Acquire Catapult Health, Expanding Preventive and At-Home Care Offerings

Key Points:
– Teladoc Health is acquiring Catapult Health for $65 million to enhance its preventive care and at-home diagnostic testing capabilities, further strengthening its integrated healthcare solutions.
– Catapult Health’s VirtualCheckup program will enable Teladoc to expand its chronic condition management services and seamlessly connect high-risk patients to virtual care programs.
– This acquisition comes as Teladoc seeks to regain momentum following its 2020 Livongo acquisition, which initially valued the combined company at $37 billion but has since declined to a market cap under $2 billion.

Teladoc Health has announced a definitive agreement to acquire Catapult Health, a move aimed at strengthening its preventive care and chronic condition management capabilities while expanding its at-home diagnostic testing offerings. This acquisition aligns with Teladoc’s strategy to enhance virtual care accessibility and effectiveness for its over 93 million members.

Catapult Health is recognized for its innovative approach to at-home wellness and diagnostic testing, which integrates virtual clinical support and high-touch patient engagement. Teladoc plans to leverage these capabilities to further enrich its industry-leading suite of integrated healthcare solutions.

“This acquisition will help advance our strategy in meaningful ways — from giving more members access to convenient and impactful wellness and preventive care, to unlocking greater value for our customers,” said Chuck Divita, Chief Executive Officer of Teladoc Health. “Catapult Health brings an experienced team and a strong culture of innovation, and we are thrilled to welcome them to Teladoc Health.”

Strategic Objectives and Synergies

Teladoc Health’s integrated care strategy is built on four key pillars:

  • Expanding Membership and Service Utilization – Enhancing the accessibility and engagement of healthcare services for existing and new members.
  • Leveraging Clinical Expertise and Product Breadth – Strengthening healthcare outcomes by integrating a broader range of clinical solutions.
  • Growing International Presence – Extending Teladoc’s reach beyond domestic markets to serve a global population.
  • Advancing Mental Health Solutions – Building upon its existing leadership in virtual mental health services.

Catapult Health’s flagship VirtualCheckup program exemplifies its innovation in preventive care. The at-home wellness exam provides members with a simple diagnostic kit, allowing them to collect blood samples, measure blood pressure, and submit other key health data. Following this, a virtual consultation with a licensed healthcare professional ensures timely assessment and guidance.

For members identified with high-risk factors or chronic conditions, Catapult’s clinicians can seamlessly enroll them into Teladoc’s condition management programs, including diabetes, hypertension, pre-diabetes, and weight management. Additionally, members can be referred to Teladoc’s virtual mental health specialists and primary care providers for continued support.

Transaction Details

The acquisition is structured as an all-cash transaction valued at $65 million, with up to $5 million in contingent earnout consideration. Catapult Health reported $30 million in trailing 12-month revenue as of Q3 2024. Upon closing, Catapult will be integrated into Teladoc’s Integrated Care segment. The deal is expected to close in Q1 2025.

Impact and Market Expansion

Catapult Health currently serves over 3 million people through its partnerships with hundreds of employer clients. The company is recognized for its strong customer satisfaction, clinical outcomes, and cost-saving benefits, including an estimated $1,400 average savings per participant over a three-year period due to early disease detection and health risk identification.

Teladoc’s Market Challenges and Context

This acquisition comes after a tumultuous period for Teladoc. Following its acquisition of Livongo in 2020, the combined companies had an enterprise value of $37 billion. However, Teladoc’s stock has struggled since then, with a current market capitalization just under $2 billion. The acquisition of Catapult Health represents a strategic effort to regain momentum and strengthen its position in the evolving telehealth market.

Duckhorn Wine Portfolio to be Acquired by Private Equity Firm Butterfly in $1.95 Billion Deal

Key Points:
– The Duckhorn Portfolio is being acquired by private equity firm Butterfly in an all-cash deal valued at $1.95 billion, offering a 65.3% premium to shareholders.
– The acquisition will return Duckhorn to private ownership and includes popular luxury wine brands such as Decoy, Sonoma-Cutrer, Kosta Browne, and Duckhorn Vineyards.
– Butterfly, a private equity firm with a focus on the food and beverage industry, aims to accelerate Duckhorn’s growth, adding it to a portfolio that includes companies like QDOBA and Chosen Foods.

The Duckhorn Portfolio (NYSE: NAPA), a leading luxury wine producer, announced that it has entered into a definitive agreement to be acquired by Butterfly, a private equity firm, in an all-cash transaction valued at $1.95 billion. This acquisition marks a significant milestone for Duckhorn, which will transition from a public to a private company.

Transaction Details and Shareholder Premium

As part of the deal, Duckhorn shareholders will receive $11.10 per share, representing a 65.3% premium over the volume-weighted average stock price for the 90-day period ending on October 4, 2024. Duckhorn originally went public five years ago, and this acquisition will once again return the company to private ownership. The transaction is expected to close this winter, subject to customary regulatory approvals and closing conditions.

Duckhorn’s board will have the right to terminate the agreement if a better proposal from a third party is made during the 45-day “go-shop” period, which expires on November 20, 2024.

Continued Growth for Duckhorn’s Premium Brands

The Duckhorn Portfolio, established in 1976, is recognized as a premier luxury wine producer in the United States, with popular brands like Decoy, Sonoma-Cutrer, Kosta Browne, and Duckhorn Vineyards. The company reported fiscal year sales growth of 0.7%, reaching $406 million through July 2024. With distribution to over 50 countries, Duckhorn has cemented its position as a leader in the high-end wine market.

This transaction is expected to accelerate the company’s growth and expansion under Butterfly’s ownership. Butterfly’s strategy of partnering with leading food and beverage companies aligns with Duckhorn’s ambitions to expand its luxury wine portfolio.

Butterfly’s Expanding Food and Beverage Investments

Butterfly is a private equity firm focused on investments in the “seed-to-fork” food ecosystem across North America. Its diverse portfolio includes companies like Milk Specialties Global, Chosen Foods, MaryRuth Organics, and QDOBA. Butterfly’s goal is to collaborate with category-leading food and beverage businesses and deliver consistent returns for its investors.

This deal also marks the third time Duckhorn has been under private equity ownership. GI Partners initially invested in Duckhorn in 2007, while TSG Consumer Partners took control in 2016 for approximately $600 million before the company filed for an IPO in 2021.

Apple Ramps Up AI Capabilities With Acquisition of Startup DarwinAI

Apple is making a concerted push to bring generative artificial intelligence capabilities to its core products and services, as evidenced by its recent acquisition of Canadian startup DarwinAI.

The iPhone maker purchased the AI company earlier this year, according to a report from Bloomberg. While Apple remained characteristically tight-lipped about the deal’s financial terms or strategic rationale, the move signals Apple is accelerating its efforts to match rivals like Microsoft and Google in deploying advanced AI across its offerings.

DarwinAI specialized in using artificial intelligence for visual inspection and analysis during the manufacturing process. Its technology served customers across multiple industries to automatically detect defects and anomalies in components through AI-powered computer vision models.

As part of the acquisition, dozens of DarwinAI employees have been absorbed into Apple’s artificial intelligence division, the report states. This influx of AI talent and technical expertise could prove critical as Apple looks to develop its own large language models and generative AI applications.

Alexander Wong, an AI researcher from the University of Waterloo who co-founded DarwinAI, has assumed a director role overseeing portions of Apple’s AI group. His background aligns with DarwinAI’s focus on building compact, efficient AI systems that can run on-device without constant cloud connectivity.

This thrust toward making AI work smoothly and privately on iPhones, iPads and Macs represents a key priority for Apple as it races to integrate generative AI across its mobile operating systems and productivity software over the next year.

At the company’s annual shareholder meeting in early March, CEO Tim Cook confirmed Apple’s intentions to “break new ground in generative AI in 2024,” citing the “breakthrough potential” and “transformative opportunities” it creates for enhancing user experiences around productivity, problem-solving and more.

Specific areas where Apple may deploy generative AI span Siri’s voice assistant capabilities, automated summarization in apps like Mail and Messages, and content creation tools within Pages, Keynote and other office productivity programs. The technology could even extend to areas like automated music playlist curation.

For the AppleCare product support team, generative AI may be leveraged to better assist customers troubleshoot technical issues by suggesting solutions based on conversational prompts. This could represent a major upgrade over today’s more manually intensive processes.

Ultimately, Apple’s biggest advantages revolve around its ability to build tighter hardware/software integration and maintain strict privacy guardrails unavailable to cloud-based rivals. The company aims to run its generative AI models directly on user devices rather than routing data to remote servers – a key differentiator from competitors like Microsoft and Google.

“We see incredible breakthrough potential for generative AI, which is why we’re currently investing significantly in this area,” Cook told shareholders.

Still, Apple faces an uphill battle catching up to the generative AI leaders. While the iPhone maker’s cautious approach focuses on curating secure AI experiences, companies like OpenAI, Anthropic and Google have rapidly advanced their public-facing products and pushed the boundaries of what’s possible with large language models.

Microsoft has already integrated AI co-pilots across its entire suite of Office apps and cloud services through partnerships with OpenAI, Anthropic and others. Google has made generative AI like Bard a centerpiece of its efforts to modernize search and productivity tools.

With developers and companies increasingly exploring AI customization and co-pilots that can streamline workflows, Apple may feel pressure to open up its ecosystem to third-party generative AI tools in the near future.

The DarwinAI acquisition represents an early step for Apple to transform itself into a formidable AI player. But just like the company’s iconic “Get a Mac” ads from years past, it may take some additional star power and rebranding to recast Apple as the face of consumer-friendly, privacy-focused artificial intelligence going forward.

Blue Apron to be Acquired by Wonder Group in $103 Million Deal

Blue Apron Holdings, Inc. (Nasdaq: APRN), a pioneer in the meal kit industry, has announced a definitive merger agreement with Wonder Group, a company founded by entrepreneur Marc Lore, known for redefining at-home dining and food delivery. The merger agreement, unanimously approved by Blue Apron’s Board of Directors, is set to create a leading mealtime platform and offers Blue Apron stockholders $13.00 per share in cash, totaling approximately $103 million.

Blue Apron’s merger agreement with Wonder Group comes as part of a strategic shift for the company, which had recently transitioned to an asset-light business model following the sale of its operational infrastructure and a strategic partnership with FreshRealm. The $13.00 per share purchase price represents a substantial 137% premium to the closing price on September 28, 2023, and a noteworthy 77% premium to the 30-day volume-weighted average price of the company’s Class A common stock.

Wonder’s acquisition of Blue Apron aims to revolutionize mealtime, offering consumers greater choice, flexibility, and convenience through their combined brands. The partnership is expected to enhance both companies’ abilities to provide chef-curated meals with high-quality ingredients to a broader customer base across the United States. Following the completion of the transaction, Wonder intends to maintain Blue Apron’s current nationwide operations under the Blue Apron brand, leveraging synergies between consumer-facing apps and delivery logistics.

Linda Findley, President, and CEO of Blue Apron, expressed her excitement about the merger, stating, “The Blue Apron brand and products that our customers know and love will stay the same, with more opportunity for product expansion in the future. Further, the transaction delivers immediate and certain value for Blue Apron stockholders at a significant premium over recent trading prices.”

Marc Lore, Founder and CEO of Wonder Group, also shared his enthusiasm for the partnership, saying, “We couldn’t be more excited to welcome Blue Apron to the Wonder platform and look forward to working with Linda and her exceptional team.”

In response to this significant development, Blue Apron shares have surged by over 130% today, reflecting investor optimism about the merger agreement. This marks a remarkable shift in fortunes for the company, which had faced challenges since its initial public offering in 2017. Year-to-date, Blue Apron shares had been down by 44%.

Since its initial public offering in 2017, Blue Apron has faced numerous challenges that have significantly impacted its fortunes. Despite having achieved a valuation of $2 billion just six years ago, the company encountered hurdles including layoffs, struggles in expanding its customer base, and fierce competition from industry giants such as Amazon and Kroger. While Blue Apron experienced a brief boost in demand during the height of the COVID-19 pandemic, this momentum proved challenging to sustain. Today’s merger agreement with Wonder Group represents a pivotal moment for the pioneering meal kit company, offering the potential for renewed growth and innovation in an evolving food delivery landscape. The acquisition of Blue Apron by Wonder Group represents a pivotal moment for the pioneering meal kit company. Blue Apron’s merger with Wonder is set to redefine at-home dining and food delivery, offering customers enhanced mealtime experiences with chef-curated meals. The substantial premium offered to Blue Apron stockholders demonstrates the confidence in this strategic partnership. As Blue Apron transitions into the Wonder platform, it will be interesting to observe how this union revitalizes the company and expands its presence in the evolving food delivery landscape.