Release – Newsmax Surpasses 25 Million Social Media Followers

May 6, 2026

BOCA RATON, FL / ACCESS Newswire / May 6, 2026 / Newsmax Inc. (NYSE:NMAX) (“Newsmax” or the “Company”) today announced a major milestone in its digital expansion, surpassing 25 million followers across all social media platforms.

Newsmax continuous and significant growth in social media followers – up 25% from a year ago – underscores the brand’s accelerating reach and deepening engagement with audiences nationwide.

The Company reported 25.4 million total social media followers, driven by strong growth across nearly every platform.

This milestone comes alongside record-setting audience metrics, including 104.18 million in Q1 2026 Facebook user reach-a 44% increase quarter-over-quarter and an impressive 119% increase compared to the first quarter of 2025.

The Company noted that this marks the largest Facebook reach in Newsmax history.

“This growth shows that Newsmax is truly touching a nerve with audiences,” said Christopher Ruddy, CEO of Newsmax. “We are continuing to execute on our strategy to reach all people on all platforms, and the results speak for themselves.”

Newsmax’s social media expansion reflects sustained momentum across both established and emerging platforms:

  • Facebook: 6.2 million followers (+22% since June 2025)
  • YouTube Live: 2.6 million followers (+8%)
  • Truth Social: 6.9+ million followers (+61%)
  • Twitter/X: 3.7+ million followers (+7%)
  • Instagram: 2.2 million followers (+13%)
  • Gettr: 1.5 million followers (+25%)
  • TikTok: 188,000+ followers (+52%)

This widespread growth highlights Newsmax’s ability to connect with audiences across diverse demographics and content ecosystems, from traditional social giants to emerging alternative platforms.

Beyond social media, Newsmax continues to see strong performance across its broader digital footprint.

The Newsmax App has now surpassed 13 million downloads, reflecting growing demand for direct-to-consumer streaming access to the network’s programming.

The Newsmax App allows users to easily access the free Newsmax2 streaming channel, Newsmax.com, as well as the Newsmax+ paid service offering the regular Newsmax channel.

Combined with its social reach, these figures illustrate a rapidly expanding, multi-platform media presence that allows Newsmax to engage audiences wherever they consume content.

The Company attributes its growth to a combination of timely news coverage, opinion programming and a strong connection with viewers seeking fresh perspectives in the media landscape.

“Passion for our brand remains incredibly strong,” Ruddy added. “We’re seeing audiences actively seek out Newsmax across platforms, share our content and become part of a growing community that values our reporting and viewpoint.”

About Newsmax

Newsmax Inc. is listed on the NYSE (NMAX) and operates, through Newsmax Broadcasting LLC, one of the nation’s leading news outlets, the Newsmax channel. The fourth highest-rated network is carried on all major pay TV providers. Newsmax’s media properties reach more than 50 million Americans regularly through Newsmax TV, the Newsmax App, its popular website Newsmax.com, and publications such as Newsmax Magazine. Through its social media accounts, Newsmax reaches over 25 million combined followers. Reuters Institute has said Newsmax is one of the top U.S. news brands and Forbes has called Newsmax “a news powerhouse.”

Investor Contacts

Newsmax Investor Relations
[email protected]

SOURCE: Newsmax Inc.

Release – Lion Zone Delivers Second Best Intersection Ever As Power Metallic intercepts 22.00 Meters of 11.46% CuEqRec¹ in Hole 26-095

TORONTO, May 6, 2026 /CNW/ – Power Metallic Mines Inc. (the “Company” or “Power Metallic”(TSXV: PNPN) (OTCBB: PNPNF) (Frankfurt: IVV1) is pleased to provide additional assays from its winter 2026 drill program.

Lion Zone MRE In-fill program

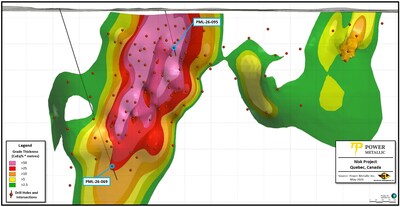
Figure 1 – Lion Zone MRE Drill holes reported in this news release (CNW Group/Power Metallic Mines Inc.)
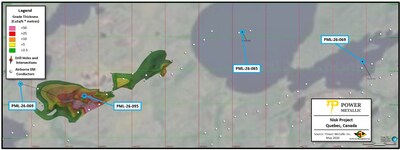
Figure 2 – Location of Drill holes reported in this news release (CNW Group/Power Metallic Mines Inc.)

Additional drill holes continued to add and refine the high-grade Lion Zone ahead of the 2026 Mineral Resource Estimate (MRE). The infill drill holes in this release cover approximately 560 m down plunge extent from the core of the Lion Zone (PML-26-095) to central southwestern Lion area (PML-26-069) (Figure 1). These holes highlight both the robust near surface mineralization as well as returning the deepest high-grade intercept at Lion. These holes will be incorporated into future mineral resource estimates and highlight the potential for open pit development.

Continued evolution and support of the modelled interpretation of the Lion Zone is evidenced by PML-26-095 which intersected the interpreted core of the Lion Zone with wide intersections of high-grade copper near surface with 22.00 m @ 11.46% CuEqRec1 including 6.50 m @ 18.59% CuEqRec1 and including 4.00 m @18.62% CuEqRec1 (Table 1).

Hole PML-26-069 tested the zone approximately 560 m south-southwest down plunge of PML-26-095 at a vertical depth of 600 m containing a moderate grade of 6.58 m @ 4.00% CuEqRecincluding a high-grade interval of 2.82 m @ 8.26% CuEqRec1.

Table 1: Lion Results – Winter 2026
HoleFromToLengthAuAgCuPdPtNiCuEq Rec*
(m)(m)(m)(g/t)( g/t )( %)(g/t)( g/t )( %)( %)
LION MRE 
PML-26-069674.18680.766.580.367.761.434.310.610.124.00
Including674.18677.002.820.4813.402.949.671.400.198.26
PML-26-095155.00177.0022.002.8223.374.924.795.120.2711.46
Including155.00159.004.000.6044.958.624.7618.180.4518.62
And Including160.50167.006.501.1542.889.4111.695.980.5618.59
And Including172.00175.003.0017.1211.793.412.270.040.0917.12
Note: Reported length is downhole distance; true width based on model projections is estimated as 85% of downhole length

1Copper Equivalent Rec Calculation (CuEqRec1)
CuEqRec represents CuEq calculated based on the following metal prices (USD) : 2,360.15 $/oz Au, 27.98 $/oz Ag, 1,215.00 $/oz Pd, 1000.00 $/oz Pt, 4.00 $/lb Cu, 10.00 $/lb Ni and 22.50 $/lb Co., and recovered grades based on recent locked-cycle metallurgical recoveries by SGS Canada Inc (see press release Jan 21, 2006).

Exploratory Drilling – East of Tiger

Drill holes PML-26-065, and -076, located to the east of Tiger (Figure 2), were designed to test modeled anomalies derived from the 2025 airborne VTEM survey. Both holes hit anomalous mineralization of sub-economic grades including 1 m of 0.19% Cu at 39.5-40.5 m and 1 m of 0.81 g/t Pt at 96.5-97.5m (PML-26-065). PML-25-076 displayed Lion style assemblages of Au-Cu-Ni-Pd-Pt from 207-233.5 m, averaging 0.1% CuEq

Power Metallic is expecting more assay results from the MRE drilling and regional exploration in the weeks to come.

“The Lion Zone continues to deliver high grade intersections that are more than an order of magnitude beyond the grade of the average producing copper mine. Hole PML-26-095 represents our second-best intersection to date. Results demonstrate that both grade and thickness are being maintained and, in places, increasing as we advance toward our inaugural Mineral Resource Estimate in the third quarter of 2026. Lots more to come!” commented Terry Lynch, CEO & Director.

Qualified Person

Joseph Campbell, P. Geo, VP Exploration at Power Metallic, is the qualified person who has reviewed and approved the technical disclosure contained in this news release.

About Power Metallic Mines Inc.

Power Metallic is a Canadian exploration company focused on advancing the Nisk Project Area (Nisk–Lion–Tiger)–a high–grade Copper–PGE, Nickel, gold and silver system–toward Canada’s next polymetallic mine.

On 1 February 2021, Power Metallic (then Chilean Metals) secured an option to earn up to 80% of the Nisk project from Critical Elements Lithium Corp. (TSX–V: CRE). Following the June 2025 purchase of 313 adjoining claims (~167 km²) from Li–FT Power, the Company now controls ~330 km² and roughly 50 km of prospective basin margins.

Power Metallic is expanding mineralization at the Nisk and Lion discovery zones, evaluating the Tiger target, and exploring the enlarged land package through successive drill programs.

Beyond the Nisk Project Area, Power Metallic indirectly has an interest in significant land packages in British Columbia and Chile, by its 50% share ownership position in Chilean Metals Inc., which were spun out from Power Metallic via a plan of arrangement on February 3, 2025.

It also owns 100% of Power Metallic Arabia which owns 100% interest in the Jabul Baudan exploration license in The Kingdon of Saudi Arabia’s Jabal Said Belt. The property encompasses over 200 square kilometres in an area recognized for its high prospectivity for copper gold and zinc mineralization. The region is known for its massive volcanic sulfide (VMS) deposits, including the world-class Jabal Sayid mine and the promising Umm and Damad deposit.

For further information, readers are encouraged to contact:
Power Metallic Mines Inc.
The Canadian Venture Building
82 Richmond St East, Suite 202
Toronto, ON

Neither the TSX Venture Exchange nor its Regulation Services Provider accepts responsibility for the adequacy or accuracy of this release.

QAQC and Sampling

GeoVector Management Inc (“GeoVector”) is the Consulting company retained to perform the actual drilling program, which includes core logging and sampling of the drill core.

All core in this news release is either HQ or NQ sized core. Drill core is re-fitted and measured. Geotech on core includes photographs (wet & dry), rock quality index, magnetic susceptibility, conductivity, and recovery estimates. Core is logged for lithology, mineralogy, and structural features, and sample intervals are delineated and tagged.

Sampled core is mechanically sawn, and half-core is retained for future reference. GeoVector’s QAQC program includes regular insertion of CRM standards, duplicates, and blanks into the sample stream with a stringent review of all results. QAQC and data validation was performed, and no material errors were observed.

All samples were submitted to and analyzed at Activation Laboratories Ltd (“Actlabs”), a commercial laboratory independent of Power Metallic with no interest in the Project. Actlabs is an ISO 9001 and 17025 certified and accredited laboratories. Samples submitted through Actlabs are run through standard preparation methods and analysed using RX-1 (Dry, crush (< 7 kg) up to 80% passing 2 mm, riffle split (250 g) and pulverize (mild steel) to 95% passing 105 μm) preparation methods, and using 1F2 (ICP-OES) and 1C-OES – 4-Acid near total digestion + Gold-Platinum-Palladium analysis and 8-Peroxide ICP-OES, for regular and over detection limit analysis. Pegmatite samples are analyzed using UT7 – Li up to 5%, Rb up to 2% method. Actlabs also undertake their own internal coarse and pulp duplicate analysis to ensure proper sample preparation and equipment calibration.

Cautionary Note Regarding Forward-Looking Statements

This message contains certain statements that may be deemed “forward-looking statements” concerning the Company within the meaning of applicable securities laws. Forward-looking statements are statements that are not historical facts and are generally, but not always, identified by the words “expects,” “plans,” “anticipates,” “believes,” “intends,” “estimates,” “projects,” “potential,” “indicates,” “opportunity,” “possible” and similar expressions, or that events or conditions “will,” “would,” “may,” “could” or “should” occur. Although the Company believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance, are subject to risks and uncertainties, and actual results or realities may differ materially from those in the forward-looking statements. Such material risks and uncertainties include, but are not limited to, among others; the timing for various drilling plans; the ability to raise sufficient capital to fund its obligations under its property agreements going forward and conduct drilling and exploration; to maintain its mineral tenures and concessions in good standing; to explore and develop its projects; changes in economic conditions or financial markets; the inherent hazards associates with mineral exploration and mining operations; future prices of nickel and other metals; changes in general economic conditions; accuracy of mineral resource and reserve estimates; the potential for new discoveries; the ability of the Company to obtain the necessary permits and consents required to explore, drill and develop the projects and if accepted, to obtain such licenses and approvals in a timely fashion relative to the Company’s plans and business objectives for the applicable project; the general ability of the Company to monetize its mineral resources; and changes in environmental and other laws or regulations that could have an impact on the Company’s operations, compliance with environmental laws and regulations, dependence on key management personnel and general competition in the mining industry.

SOURCE Power Metallic Mines Inc.

For further information on Power Metallic Mines Inc., please contact: Duncan Roy, VP Investor Relations, 416-580-3862, [email protected]

Release – Tonix Pharmaceuticals Secures Commercial Payer Coverage for TONMYA®, Providing Access for ~35 Million U.S. Patients

Primary Logo

May 06, 2026 7:00am EDT

Agreement with leading group purchasing organization (GPO) provides access to approximately 35 million U.S. commercial lives (20% of ~177 million commercial lives in the U.S.)

TONMYA (cyclobenzaprine HCl sublingual tablets), the first FDA-approved treatment for fibromyalgia in adults in more than 15 years, commercially launched in November 2025

TONMYA is a first-in-class non-opioid analgesic indicated for the treatment of fibromyalgia in adults as a daily bedtime medicine for long-term use

BERKELEY HEIGHTS, N.J., May 06, 2026 (GLOBE NEWSWIRE) — Tonix Pharmaceuticals Holding Corp. (Nasdaq: TNXP), a fully integrated, commercial biotechnology company, today announced an agreement effective May 1, 2026, with a leading group purchasing organization (GPO) that provides coverage to approximately 35 million U.S. commercial lives, representing approximately 20% of the roughly 177 million commercial lives in the U.S., with standard utilization management criteria, for TONMYA® (cyclobenzaprine HCl sublingual tablets).

“This agreement is an important milestone in expanding patient access to TONMYA,” said Seth Lederman, M.D., President and Chief Executive Officer of Tonix Pharmaceuticals. “We are encouraged by this first partnership with managed care and look forward to continuing to pursue additional coverage across commercial and government channels.”

Dr. Lederman continued, “TONMYA is a first-in-class non-opioid analgesic indicated for the treatment of fibromyalgia in adults. TONMYA is the first new FDA-approved treatment option for fibromyalgia in over 15 years. Fibromyalgia patients have experienced dissatisfaction with available therapies, with 85% of first-line treatments failing due to efficacy and tolerability issues.1,2 We are committed to providing patient access to TONMYA by continuing to engage with commercial payers on its value and offering a patient support program to help patients access their prescribed medication.”

Tonix also continues to progress discussions with Medicare and Medicaid. To date, TONMYA is covered under Medicaid in 38 states for approximately 55 million lives representing 73% of the roughly 75 million Medicaid lives.

The TONMYA Together Support Program offers a savings program to eligible, commercially insured patients through local pharmacies and through a digital pharmacy service. Terms and conditions apply, subject to change. Learn more at https://www.tonmya.com/savings.

About Fibromyalgia
Fibromyalgia is a chronic pain disorder that is understood to result from amplified sensory and pain signaling within the central nervous system. Fibromyalgia afflicts more than 10 million adults in the U.S., approximately 90% of whom are women. Symptoms of fibromyalgia include chronic widespread pain, nonrestorative sleep, fatigue, and morning stiffness. Other associated symptoms include cognitive dysfunction and mood disturbances, including anxiety and depression. Individuals suffering from fibromyalgia struggle with their daily activities, have impaired quality of life, and frequently are disabled. Physicians and patients report common dissatisfaction with currently marketed products.

About TONMYA® (cyclobenzaprine HCl sublingual tablets)
TONMYA (cyclobenzaprine HCl sublingual tablets) is a patented sublingual tablet formulation of cyclobenzaprine hydrochloride which provides rapid transmucosal absorption and reduced production of a long half-life active metabolite, norcyclobenzaprine, due to bypass of first-pass hepatic metabolism. As a multifunctional agent with potent binding and antagonist activities at the 5-HT2A serotonergic, α1-adrenergic, H1-histaminergic, and M1-muscarinic receptors, TONMYA was approved on August 15, 2025, by the FDA for the treatment of fibromyalgia in adults. TONMYA is the first new prescription medicine approved for fibromyalgia in more than 15 years. TONMYA was investigated as TNX-102 SL. TNX-102 SL is also being developed to treat acute stress disorder (ASD)/acute stress reaction (ASR), and major depressive disorder (MDD). The United States Patent and Trademark Office (USPTO) issued United States Patent No. 9636408 in May 2017, Patent No. 9956188 in May 2018, Patent No. 10117936 in November 2018, Patent No. 10,357,465 in July 2019, and Patent No. 10736859 in August 2020. The Protectic™ protective eutectic and Angstro-Technology™ formulation claimed in the patent are important elements of Tonix’s proprietary TONMYA composition. These patents are expected to provide TONMYA with U.S. market exclusivity until 2034/2035.

Citations
1Robinson RL, et al. Pain Med. 2012 13(10):1366-76. doi: 10.1111; 85% received drug treatment.
2EVERSANA primary physician research, May 2024; commissioned by Tonix.

Tonix Pharmaceuticals Holding Corp.
Tonix Pharmaceuticals* is a fully integrated, commercial-stage biotechnology company focused on central nervous system (CNS) and immunology treatments in areas of high unmet medical need. TONMYA® (cyclobenzaprine HCl sublingual tablets 2.8 mg) is the first new treatment for fibromyalgia in adults in more than 15 years. Tonix’s CNS commercial infrastructure supports its marketed products, including its acute migraine products, Zembrace® Symtouch® (sumatriptan injection 3 mg) and Tosymra® (sumatriptan nasal spray 10 mg). Tonix is investigating TONMYA in Phase 2 clinical trials to evaluate its potential in major depressive disorder and acute stress disorder/acute stress reaction. Tonix is also advancing a pipeline of immunology programs, including TNX-4800, a Phase 2 ready long-acting human anti-Borrelia OspA monoclonal antibody (mAb) for the prevention of Lyme disease in the U.S., and TNX-1500, a Phase 2 ready third-generation CD154/CD40 ligand (CD40L) inhibitor for the prevention of kidney transplant rejection. In addition, Tonix is progressing TNX-2900 (intranasal potentiated oxytocin), which is Phase 2 ready for the treatment of Prader-Willi syndrome, a rare disease. To learn more, visit www.tonixpharma.com.

*Tonix’s product development candidates are investigational new drugs or biologics; their efficacy and safety have not been established and have not been approved for any indication.

Zembrace SymTouch and Tosymra are registered trademarks of Tonix Medicines. TONMYA is a registered trademark of Tonix Pharma Limited. All other marks are property of their respective owners.

Forward Looking Statements
Certain statements in this press release are forward-looking within the meaning of the Private Securities Litigation Reform Act of 1995 including those relating to the completion of the offering, the satisfaction of customary closing conditions, the intended use of proceeds from the offering and other statements that are predictive in nature. These statements may be identified by the use of forward-looking words such as “anticipate,” “believe,” “forecast,” “estimate,” “expect,” and “intend,” among others. There are a number of factors that could cause actual events to differ materially from those indicated by such forward-looking statements. These factors include, but are not limited to, risks related to the failure to successfully launch and commercialize TONMYA® and any of our approved products; risks related to the failure to obtain FDA clearances or approvals and noncompliance with FDA regulations; risks related to the timing and progress of clinical development of our product candidates; our need for additional financing; uncertainties of patent protection and litigation; uncertainties of government or third party payor reimbursement; limited research and development efforts and dependence upon third parties; and substantial competition. As with any pharmaceutical under development, there are significant risks in the development, regulatory approval and commercialization of new products. Tonix does not undertake an obligation to update or revise any forward-looking statement. Investors should read the risk factors set in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025, as filed with the SEC on March 12, 2026, and periodic reports filed with the SEC on or after the date thereof. Tonix does not undertake an obligation to update or revise any forward-looking statement. All of Tonix’s forward-looking statements are expressly qualified by all such risk factors and other cautionary statements. The information set forth herein speaks only as of the date thereof.

Investor Contacts
Jessica Morris
Tonix Pharmaceuticals 
[email protected]  
(862) 799-8599 

Brian Korb 
astr partners 
(917) 653-5122 
[email protected] 

Media Contacts
Deborah Elson
Tonix Pharmaceuticals
[email protected]

Ray Jordan 
Putnam Insights 
[email protected] 

INDICATION
TONMYA is indicated for the treatment of fibromyalgia in adults.

CONTRAINDICATIONS
TONMYA is contraindicated:

In patients with hypersensitivity to cyclobenzaprine or any inactive ingredient in TONMYA. Hypersensitivity reactions may manifest as an anaphylactic reaction, urticaria, facial and/or tongue swelling, or pruritus. Discontinue TONMYA if a hypersensitivity reaction is suspected. With concomitant use of monoamine oxidase (MAO) inhibitors or within 14 days after discontinuation of an MAO inhibitor. Hyperpyretic crisis seizures and deaths have occurred in patients who received cyclobenzaprine (or structurally similar tricyclic antidepressants) concomitantly with MAO inhibitors drugs.

During the acute recovery phase of myocardial infarction, and in patients with arrhythmias, heart block or conduction disturbances, or congestive heart failure. In patients with hyperthyroidism.

WARNINGS AND PRECAUTIONS
Embryofetal toxicity: Based on animal data, TONMYA may cause neural tube defects when used two weeks prior to conception and during the first trimester of pregnancy. Advise females of reproductive potential of the potential risk and to use effective contraception during treatment and for two weeks after the final dose. Perform a pregnancy test prior to initiation of treatment with TONMYA to exclude use of TONMYA during the first trimester of pregnancy.

Serotonin syndrome: Concomitant use of TONMYA with selective serotonin reuptake inhibitors (SSRIs), serotonin norepinephrine reuptake inhibitors (SNRIs), tricyclic antidepressants, tramadol, bupropion, meperidine, verapamil, or MAO inhibitors increases the risk of serotonin syndrome, a potentially life-threatening condition. Serotonin syndrome symptoms may include mental status changes, autonomic instability, neuromuscular abnormalities, and/or gastrointestinal symptoms. Treatment with TONMYA and any concomitant serotonergic agent should be discontinued immediately if serotonin syndrome symptoms occur and supportive symptomatic treatment should be initiated. If concomitant treatment with TONMYA and other serotonergic drugs is clinically warranted, careful observation is advised, particularly during treatment initiation or dosage increases.

Tricyclic antidepressant-like adverse reactions: Cyclobenzaprine is structurally related to TCAs. TCAs have been reported to produce arrhythmias, sinus tachycardia, prolongation of the conduction time leading to myocardial infarction and stroke. If clinically significant central nervous system (CNS) symptoms develop, consider discontinuation of TONMYA. Caution should be used when TCAs are given to patients with a history of seizure disorder, because TCAs may lower the seizure threshold. Patients with a history of seizures should be monitored during TCA use to identify recurrence of seizures or an increase in the frequency of seizures.

Atropine-like effects: Use with caution in patients with a history of urinary retention, angle-closure glaucoma, increased intraocular pressure, and in patients taking anticholinergic drugs.

CNS depression and risk of operating a motor vehicle or hazardous machinery: TONMYA monotherapy may cause CNS depression. Concomitant use of TONMYA with alcohol, barbiturates, or other CNS depressants may increase the risk of CNS depression. Advise patients not to operate a motor vehicle or dangerous machinery until they are reasonably certain that TONMYA therapy will not adversely affect their ability to engage in such activities. Oral mucosal adverse reactions: In clinical studies with TONMYA, oral mucosal adverse reactions occurred more frequently in patients treated with TONMYA compared to placebo. Advise patients to moisten the mouth with sips of water before administration of TONMYA to reduce the risk of oral sensory changes (hypoesthesia). Consider discontinuation of TONMYA if severe reactions occur.

ADVERSE REACTIONS
The most common adverse reactions (incidence ≥2% and at a higher incidence in TONMYA-treated patients compared to placebo-treated patients) were oral hypoesthesia, oral discomfort, abnormal product taste, somnolence, oral paresthesia, oral pain, fatigue, dry mouth, and aphthous ulcer.

DRUG INTERACTIONS
MAO inhibitors: Life-threatening interactions may occur.

Other serotonergic drugs: Serotonin syndrome has been reported.

CNS depressants: CNS depressant effects of alcohol, barbiturates, and other CNS depressants may be enhanced.

Tramadol: Seizure risk may be enhanced.

Guanethidine or other similar acting drugs: The antihypertensive action of these drugs may be blocked.

USE IN SPECIFIC POPULATIONS
Pregnancy: Based on animal data, TONMYA may cause fetal harm when administered to a pregnant woman. The limited amount of available observational data on oral cyclobenzaprine use in pregnancy is of insufficient quality to inform a TONMYA-associated risk of major birth defects, miscarriage, or adverse maternal or fetal outcomes. Advise pregnant women about the potential risk to the fetus with maternal exposure to TONMYA and to avoid use of TONMYA two weeks prior to conception and through the first trimester of pregnancy. Report pregnancies to the Tonix Medicines, Inc., adverse-event reporting line at 1-888-869-7633 (1-888-TNXPMED).

Lactation: A small number of published cases report the transfer of cyclobenzaprine into human milk in low amounts, but these data cannot be confirmed. There are no data on the effects of cyclobenzaprine on a breastfed infant, or the effects on milk production. The developmental and health benefits of breastfeeding should be considered along with the mother’s clinical need for TONMYA and any potential adverse effects on the breastfed child from TONMYA or from the underlying maternal condition.

Pediatric use: The safety and effectiveness of TONMYA have not been established.

Geriatric patients: Of the total number of TONMYA-treated patients in the clinical trials in adult patients with fibromyalgia, none were 65 years of age and older. Clinical trials of TONMYA did not include sufficient numbers of patients 65 years of age and older to determine whether they respond differently from younger adult patients.

Hepatic impairment: The recommended dosage of TONMYA in patients with mild hepatic impairment (HI) (Child Pugh A) is 2.8 mg once daily at bedtime, lower than the recommended dosage in patients with normal hepatic function. The use of TONMYA is not recommended in patients with moderate HI (Child Pugh B) or severe HI (Child Pugh C). Cyclobenzaprine exposure (AUC) was increased in patients with mild HI and moderate HI compared to subjects with normal hepatic function, which may increase the risk of TONMYA-associated adverse reactions.

Please see additional safety information in the full Prescribing Information. To report suspected adverse reactions, contact Tonix Medicines, Inc. at 1-888-869-7633, or the FDA at 1-800-FDA-1088 or www.fda.gov/medwatch.

Source: Tonix Pharmaceuticals Holding Corp.

Released May 6, 2026
The Numbers Don’t Lie: Small Caps Are Outrunning the S&P 500 — and the Institutional Money Is Finally Catching Up

For years, the story of the U.S. equity market was written by a handful of mega-cap technology names. That story is being rewritten in 2026, and small-cap investors are the ones holding the pen.

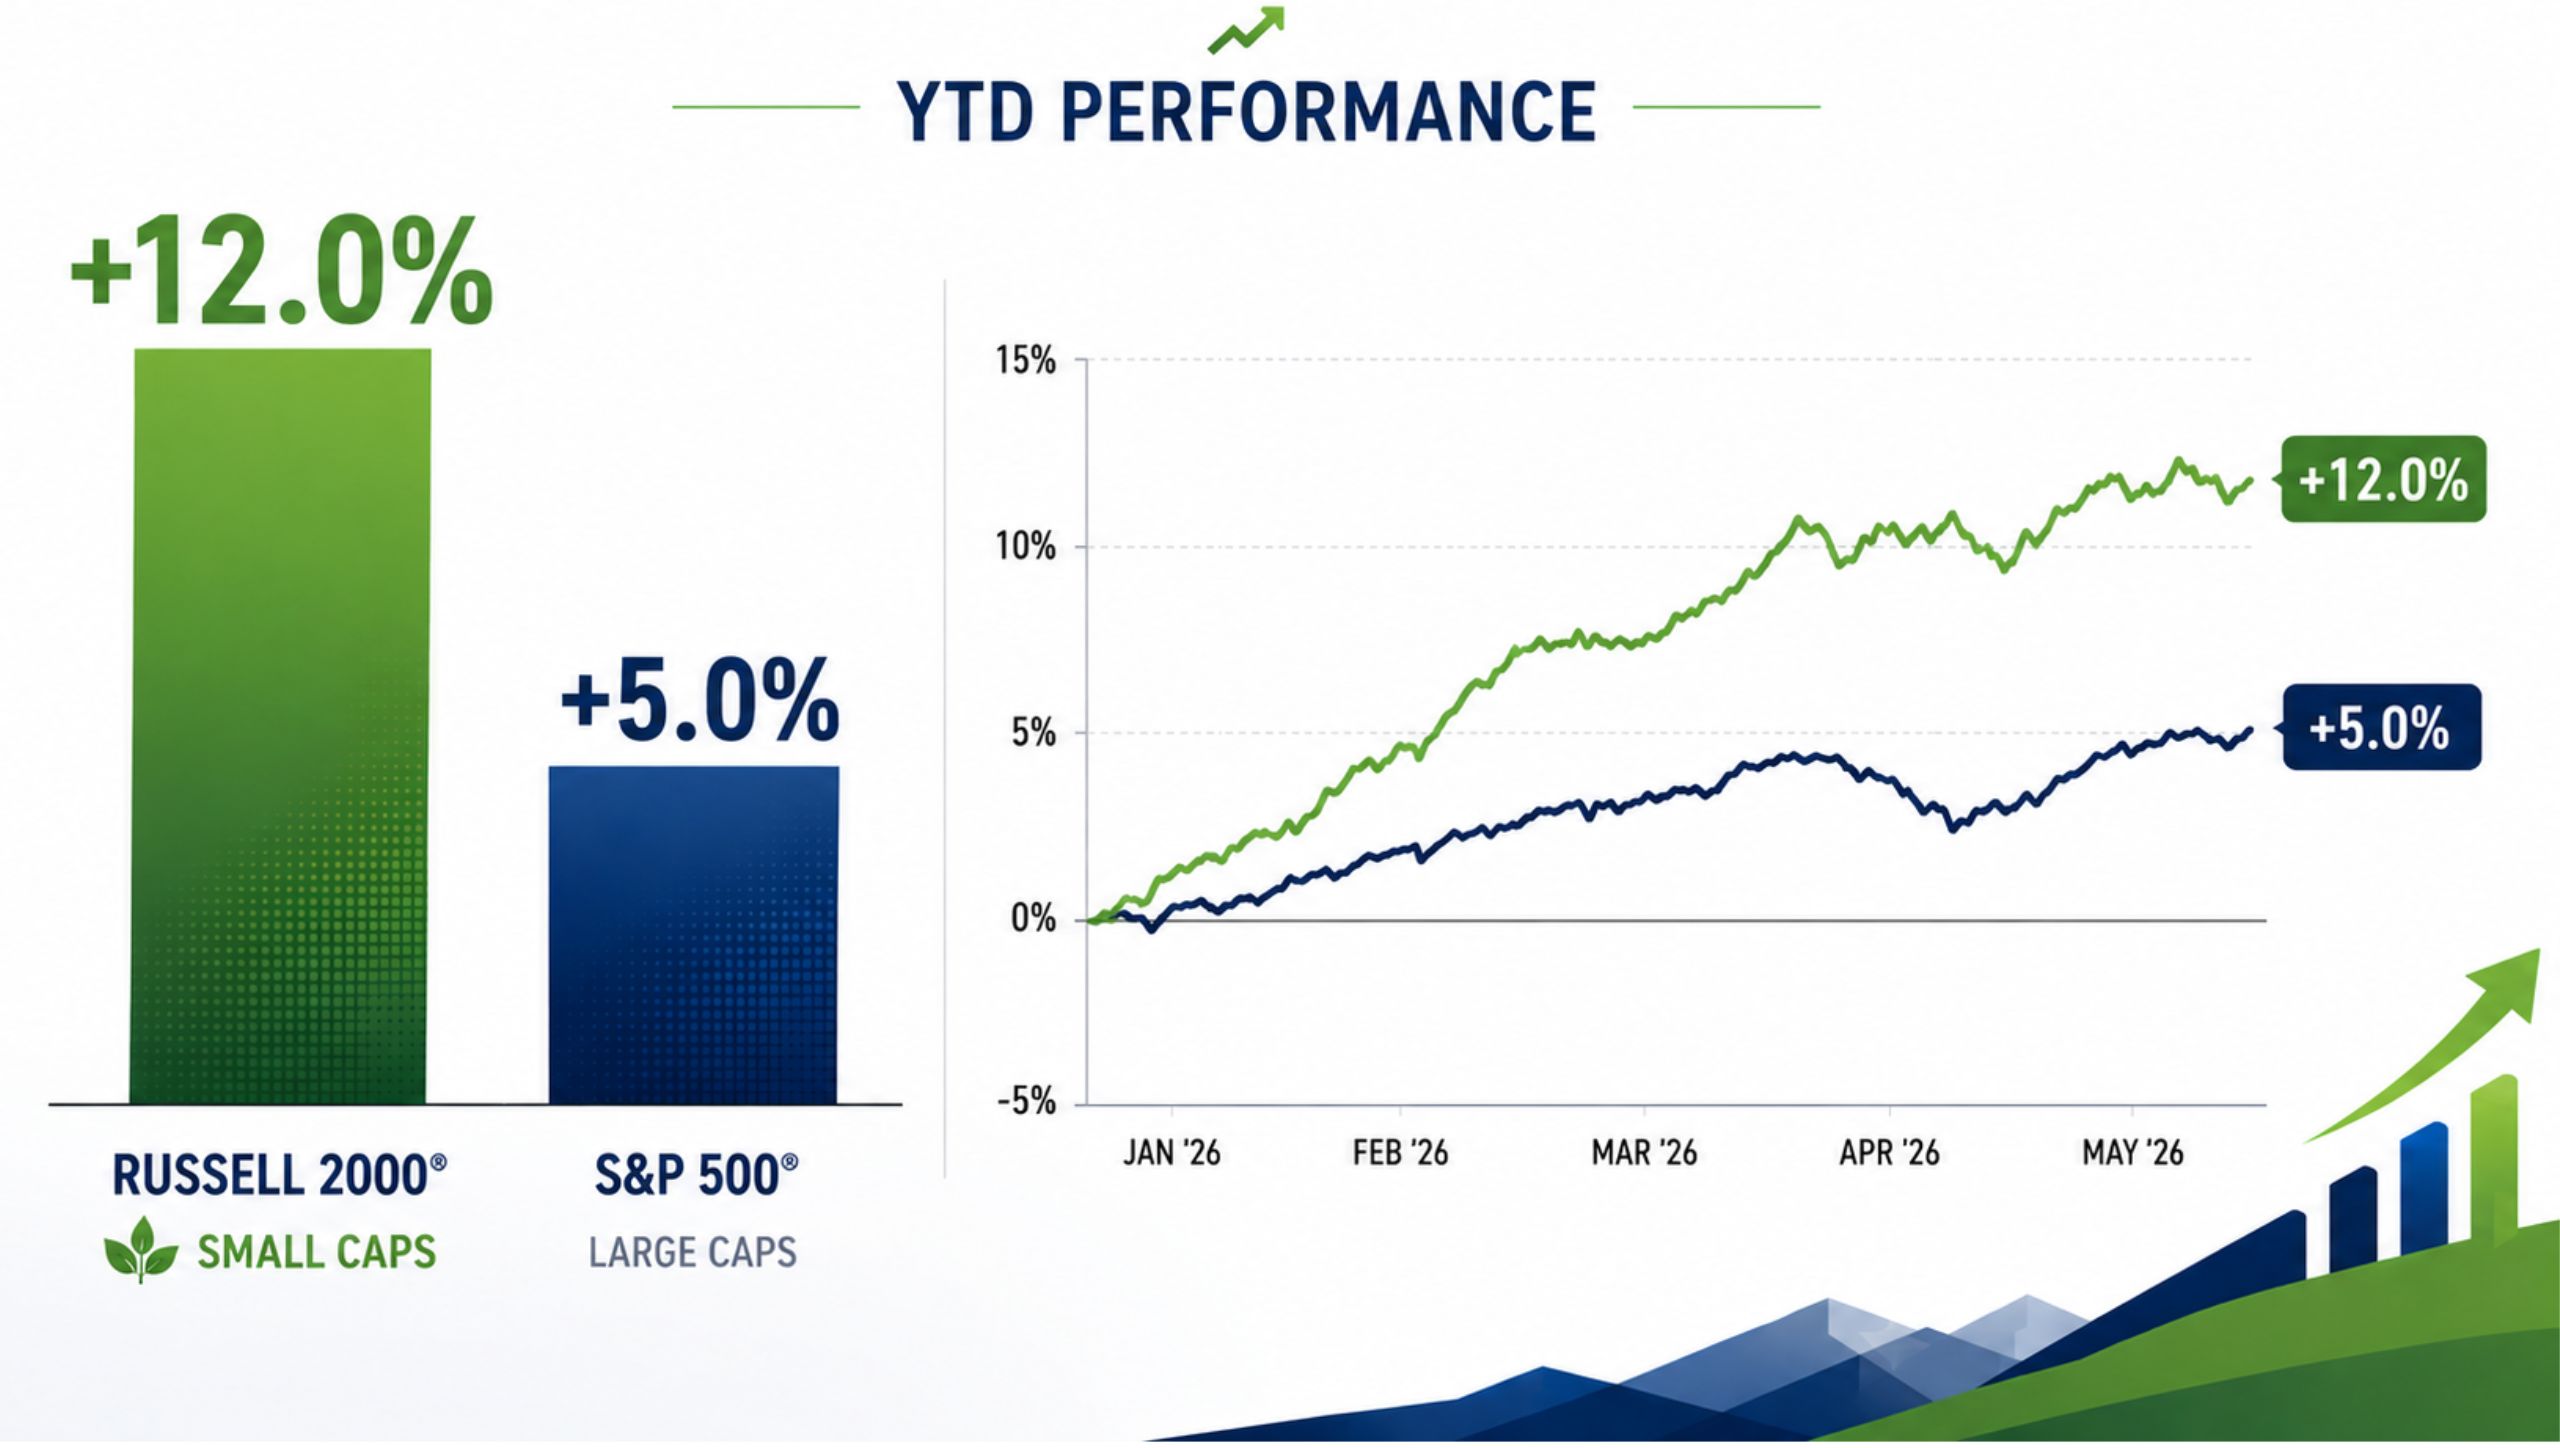
The Russell 2000 is up approximately 12% year-to-date, more than double the S&P 500’s roughly 5% gain over the same period. That gap isn’t noise — it reflects a meaningful structural shift in where capital is flowing and why.

The earnings picture is the starting point. Small-cap companies are projected to deliver 18% to 22% earnings growth for the full year in 2026, compared to roughly 13% for large caps. Analyst forecasts extend that outperformance into 2027 as well, with another 17–18% growth expected — suggesting this isn’t a one-quarter anomaly but the early stage of a sustained cycle.

The valuation argument reinforces the case. The S&P 500 currently trades near 28 times earnings. The Russell 2000 trades around 18 times. The S&P 600 — widely considered the higher-quality small-cap benchmark — sits near 16 times forward earnings. That’s a discount of roughly 40% to large caps. Historically, gaps of that magnitude don’t persist; they close, and when they do, small-cap investors collect outsized returns.

The macro setup has been equally supportive. The Federal Reserve’s rate-cutting cycle throughout 2025, which brought the federal funds rate to the 3.50%–3.75% range, disproportionately benefited smaller companies that carry more floating-rate debt. As interest expense declined, margins expanded — and earnings started to catch up to valuations.

M&A activity is amplifying the opportunity. U.S. transaction volume for deals over $100 million is up 25% by deal count and 43% by value in early 2026, with private equity firms deploying capital after years of sitting on record dry powder. For small-cap shareholders, that dealmaking environment creates a meaningful premium opportunity — acquisitions of quality small-cap targets at 30–40% premiums are not uncommon in the current environment.

Domestic revenue exposure is adding another layer of appeal. In an environment where tariff uncertainty and global supply chain risk remain real considerations, companies with predominantly U.S.-focused revenue streams are commanding renewed investor attention. Many small and microcap companies fit that profile by nature.

None of this means every small-cap stock is a buy. The rotation is rewarding companies with strong balance sheets, reliable cash flow, and a defensible market position. Those carrying excessive debt or lacking a clear path to profitability are being bypassed. The quality filter is real.

But for investors who track the small and microcap space — the roughly $250 million to $2 billion market cap range where institutional coverage is thin and price discovery is still happening — the current setup represents one of the more compelling opportunities in recent memory. The window doesn’t stay open indefinitely.

Ocugen (OCGN) – 1Q26 Reported With Senior Convertible Note Offering


Wednesday, May 06, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Clinical Progress During 1Q26 Reviewed. Ocugen reported 1Q26 loss of $19.1 million or $(0.06) per share, slightly higher than we estimated. On its quarterly conference call, management reiterated several important clinical milestones in the coming year. The company also completed an offering of $115 million in Convertible Senior Notes, which we estimate is enough cash to bring its three lead products to market and fund operations through early 2028. The proposal to allow for a reverse split has been dropped from the Annual Meeting agenda.

Senior Note Offering Provides Sufficient Cash For Product Introductions. The cash balance on March 31, 2026, was $32.2 million, including proceeds of $37.5 million from warrant exercise in 1Q26. Today, the company completed the sale of $115 million in 6.75% Convertible Senior Notes. including an option for the buyer to purchase an additional $15 million in the next 13 days. These Notes should add about $99.5 million to the cash balance. Based on our estimates, we believe this is sufficient to fund operations through the filing of the BLAs and product introductions expected in 2026-2028.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

SelectQuote (SLQT) – Strong Q3 Execution Highlights Profitability and Cash Flow Strength


Wednesday, May 06, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Strong Q3 Adj EBITDA. The company reported fiscal Q3 revenue of $430.9 million and adj. EBITDA of $44.6M. While revenue was modestly lower than our estimate of $449.0M, adj. EBITDA strongly outperformed our estimate of $35.0M. Notably, adj. EBITDA benefited from a favorable $14.0M adjustment to commissions receivables and continued operational discipline.

Underlying profitability remains solid. Normalized EBITDA margins were approximately 7% after excluding the one-time commission benefit. Core operating performance appears to be improving. The Senior segment demonstrated resilience despite ongoing headwinds in Medicare Advantage. Healthcare Services (SelectRx) revenue grew 5% YoY to $199M, driven by continued membership growth and higher prescription utilization per member.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

FreightCar America (RAIL) – First Quarter 2026 Review and Outlook


Wednesday, May 06, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q1′ 2026 financial results. RAIL generated a Q1′ 2026 adjusted net loss of $479 thousand or $(0.04) per share, compared to adjusted net income of $1.6 million or $0.05 per share in Q1′ 2025. We had projected net income of $550 thousand or $0.02 per share. Revenue declined to $64.3 million compared to $96.3 million during the prior year period, while railcar deliveries fell to 577 compared to 710 units in the prior year period and our estimate of 700 units. Adjusted EBITDA declined to $3.2 million compared to $6.4 million in Q1′ 2025 and our estimate of $5.8 million.

FY 2026 guidance maintained. Management reiterated its FY 2026 guidance. Railcar deliveries are expected to be in the range of 4,000 to 4,500, revenue in the range of $500 to $550 million, and adjusted EBITDA of $41 to $50 million. Based on management’s commentary during the investor call, we believe the 2026 guidance is achievable.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Commercial Vehicle Group (CVGI) – First Look 1Q26 Results


Wednesday, May 06, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. Commercial Vehicle Group reported better-than-expected results in the first quarter of 2026, returning to revenue growth at the consolidated level. Electrical Systems led the way with 13.9% revenue growth, while Global Seating sales were up 1.5% in the quarter. Management reaffirmed full-year guidance.

1Q26 Results. Consolidated revenue of $171.5 million was up 1% y-o-y and exceeded our $160 million projection. Adjusted gross margin expanded 200bp sequentially and was up 150 bp y-o-y. Adjusted operating income was flat at $2 million, while adjusted EBITDA fell to $4.8 million from $5.8 million in the prior year quarter due to higher SG&A costs. CVG reported adjusted net loss of $3.4 million, or $0.10/sh, versus an adjusted loss of $2.6 million, or $0.08/sh, last year partly driven by higher interest expense.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Agnico Eagle’s Arm Snaps Up Canadian Phosphate Asset — and the Market Is Taking Notice

When a subsidiary of one of the world’s most respected gold miners pivots to phosphate, the market listens. That’s exactly what happened Monday when Avenir Minerals Limited — established as a subsidiary of Agnico Eagle Mines — announced a definitive agreement to acquire Fox River Resources Corporation (OTCQX: FXRVF) in an all-cash deal valued at approximately C$94.3 million.

Fox River shareholders will receive C$1.10 per share, representing a 20% premium to the stock’s 30-day volume-weighted average price as of May 1, 2026. The Fox River board unanimously recommended shareholders vote in favor of the transaction, and insiders holding roughly 23.5% of shares outstanding have already signed voting support agreements. Asset manager Adrian Day Asset Management, controlling approximately 14.7% of shares, has also committed to vote in favor. The deal is expected to close in early Q3 2026, pending court and shareholder approval.

The target asset is the Martison Phosphate Project near Hearst, Ontario — a high-grade, large-scale igneous phosphate deposit designed as a vertically integrated operation capable of producing domestic phosphate fertilizers as well as purified phosphoric acid (PPA) for the lithium iron phosphate (LFP) battery industry. A preliminary economic assessment completed in April 2022 underpins the project’s economic viability.

Avenir’s rationale is straightforward: secure a platform-level entry into critical minerals with scale, infrastructure proximity, and dual-market optionality. The Martison project sits at the intersection of two secular demand drivers — food security and the energy transition — and that combination is increasingly rare and valuable.

The Ripple Effect: First Phosphate Catches a Bid

The Fox River deal is already sending a signal to the broader igneous phosphate sector. First Phosphate Corp. (CSE: PHOS | OTCQX: FRSPF) — the most advanced pure-play igneous phosphate developer in North America — is trading up roughly 16% today as investors connect the dots.

First Phosphate is developing the Bégin-Lamarche Property in Saguenay–Lac-Saint-Jean, Quebec, a high-grade igneous phosphate deposit hosting 41.5 Mt Indicated at 6.49% P2O5 and 214 Mt Inferred at 6.01% P2O5, targeting an estimated 24-year mine life. Unlike sedimentary phosphate, igneous deposits produce low-impurity phosphate — the preferred input for battery-grade PPA used in LFP cathode production. The company recently completed final warrant exercises generating roughly C$3 million in gross proceeds and carries over C$20 million in cash with no debt.

The broader macro backdrop gives this deal its urgency. LFP batteries now account for roughly 60% of global battery chemistry deployment, up from just 20% in 2020. China controls nearly all of the world’s LFP production capacity. With phosphate now on the U.S. critical minerals list and North American governments actively funding domestic battery supply chains, high-quality igneous phosphate deposits outside of China are becoming strategic assets — not just mining plays.

The Avenir-Fox River transaction is a data point that validates the thesis. A major mining conglomerate, known for capital discipline, deploying nearly C$100 million into an early-stage igneous phosphate project signals institutional conviction that the phosphate supply gap is real and the window to secure quality assets is narrowing.

First Phosphate’s 16% move today reflects how quickly institutional sentiment can shift when a credible acquirer puts real capital behind an asset class — and igneous phosphate in Canada just got a very public vote of confidence.

Michael Burry Bails on GameStop — and His Exit Says Everything About the eBay Deal

When the investor who called the 2008 housing crash walks away from a position, the market pays attention. Michael Burry, the Scion Asset Management founder made famous by The Big Short, confirmed Monday that he exited his entire GameStop (NYSE: GME) stake — and the reason behind the move cuts straight to the heart of one of the most audacious M&A proposals in recent memory.

The trigger: GameStop’s unsolicited, nonbinding offer to acquire eBay (NASDAQ: EBAY) for approximately $55.5 billion in cash and stock — a deal that would be roughly four times the size of GameStop itself.

The Deal That Broke the Thesis

GameStop CEO Ryan Cohen announced Sunday that the company has offered $125 per share for eBay, structured as a 50/50 split between cash and GameStop common stock. The bid carries a roughly 20% premium to eBay’s last closing price and a 46% premium relative to where the stock traded in early February — around the time GameStop began quietly accumulating a 5% stake in the e-commerce platform.

To fund the cash portion, GameStop has secured a nonbinding highly confident letter from TD Bank for approximately $20 billion in debt financing. The company also holds roughly $9.4 billion in cash. However, a significant funding gap remains, with estimates suggesting the deal falls roughly $16 billion short of the implied transaction value — a gap Cohen suggested could be bridged through additional stock issuance.

Cohen’s vision centers on leveraging GameStop’s roughly 1,600 U.S. retail locations as fulfillment and drop-off points for eBay transactions, along with a targeted $2 billion in annualized cost reductions within 12 months of closing. He sees eBay as a severely undermanaged asset with the potential to significantly grow its earnings under tighter operational discipline.

Why Burry Left

Burry’s exit wasn’t impulsive — it was disciplined. His investment thesis for GameStop was built around the idea that the company could evolve into a Berkshire Hathaway-style holding vehicle: lean, cash-rich, and deploying capital conservatively. The eBay deal, as structured, blows that framework up entirely.

The pro forma leverage from the transaction would push the combined company’s Debt/EBITDA ratio well above 5x — a level that Burry had identified as a hard ceiling for his investment case. Interest coverage ratios under 4.0x further complicated the math. Burry noted on his Substack that this was his first sale since launching the newsletter, underscoring how seriously he viewed the deal as a departure from GameStop’s core value proposition.

GME shares fell more than 2% in after-hours trading following Burry’s announcement and have declined over 10% from recent highs.

Burry’s departure doesn’t necessarily doom the deal or GameStop’s stock — but it does crystallize a growing tension between Cohen’s aggressive growth ambitions and the disciplined capital allocation thesis that attracted institutional-minded investors to GME in the first place.

eBay has acknowledged receiving the proposal and confirmed its board will review the offer. Markets remain skeptical — eBay shares are trading well below the $125 offer price, a clear signal that investors are pricing in a low probability of the deal closing as proposed.

For small and microcap investors watching from the sidelines, the GameStop-eBay saga is a masterclass in how quickly an investment thesis can be rewritten — and why leverage assumptions matter as much as the deal itself.

GDEV (GDEV) – Improved Profitability Appears Sustainable (Corrected Copy)


Tuesday, May 05, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Solid Q4 results. The company reported Q4 revenue of $90.0 million and adj. EBITDA of $15.0 million. While revenue was modestly below our estimate of $99.0 million, adj. EBITDA was in line with our estimate of $15.1 million. Notably, the strong adj. EBITDA figure was largely driven by more efficient use of marketing spend, which decreased approximately 25% compared to the prior year period.

Key operating metrics. Bookings and monthly paying users (MPU) decreased by 7% and 10%, respectively, compared with the prior year period, but the decrease was expected as the company is focused on the quality of gameplay and retaining high-quality users. Furthermore, the company’s strategy appears to be paying off, as average bookings per paying user (ABPPU) increased from $102 in Q4’24 to $106 in Q4’25.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

V2X (VVX) – Strong First Quarter Results


Tuesday, May 05, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. V2X reported better-than-expected first-quarter results. Revenue increased 23% year-over-year to $1.25 billion, marking a record year-over-year organic growth rate for V2X. The growth was driven primarily by the ramp-up of training, foreign military sales, rapid prototyping, and engineering programs, as well as some discrete activities to support a national security customer.

1Q26 Results. Revenue came in at $1.254 billion, ahead of our $1.15 billion projection. Adjusted EBITDA of $85.6 million increased from $67 million last year and was above our $73.8 million projection. First quarter adjusted EPS was $1.53, up 55% year-over-year.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Superior Group of Companies (SGC) – Execution Driving Earnings Upside


Tuesday, May 05, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Solid start to the year. First quarter revenue of $141 million increased 3% year over year, reflecting steady demand across the company’s diversified business lines. Results were in line with expectations for a seasonally softer first quarter and positioned the company well for its typical back-end weighted growth profile. 

Branded Products’ momentum continues. Segment revenue increased 5% year over year for the second consecutive quarter, supported by volume gains within existing accounts. Management indicated that RFP activity is at its highest level in recent memory, suggesting a strong pipeline that should support continued growth throughout 2026. In addition, Contact Centers are stabilizing with improving trends. 


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.