Release – Nutriband Appoints Decorated Navy SEAL and Veterans Health Advocate Robert J. O’Neill to Advisory Board

Nutriband-logo

Research News and Market Data on NTRB

GlobeNewswire

Friday, September 25, 2026, 8:00:00 AM EDT

ORLANDO, Fla., Sept. 25, 2026 (GLOBE NEWSWIRE) — Nutriband Inc. (NASDAQ:NTRB) (NASDAQ:NTRBW) today announced the appointment of Robert J. O’Neill to its Advisory Board. O’Neill is a highly decorated former U.S. Navy SEAL, New York Times best-selling author, and nationally recognized speaker on leadership and resilience.

O’Neill served 16 years in the U.S. Navy, including eight years with the Naval Special Warfare Development Group (SEAL Team Six), and took part in more than 400 combat missions across four theaters of war. He is widely known for his role in Operation Neptune’s Spear, the 2011 mission that resulted in the death of Osama bin Laden. Over his career he was decorated more than 50 times, including two Silver Stars and four Bronze Stars with Valor. He is the author of the New York Times best-selling memoir The Operator: Firing the Shots That Killed Osama bin Laden and My Years as a SEAL Team Warrior, and is a regular contributor to national media on leadership, decision-making under pressure, and national security.

O’Neill remains closely connected to the military and veteran community, and has been a visible advocate for expanding access to emerging health treatments, including appearing alongside fellow veterans at this year’s White House executive order signing aimed at accelerating research and access to psychedelic-assisted therapies through the VA. His continued engagement with veteran service organizations and the broader military community reflects a career-long commitment to those he served alongside. His experience in fighting for adequate care pairs perfectly with Nutriband’s advancement of AVERSA as the company continues towards approval and commercialization of AVERSA Fentanyl which would be the worlds first and only abuse deterrent fentanyl patch if approved.

“Rob has spent his career operating at the highest levels of pressure, precision, and decision-making, and he’s continued that same commitment through his advocacy for adequate care and the military community he comes from,” said Gareth Sheridan, CEO of Nutriband Inc. “Those are exactly the qualities we look for as we scale Nutriband and AVERSA™ into new markets, and his perspective will be a real asset to our team as we continue to grow.”

Nutriband’sAdvisory Board supports the Company’s executive team on strategy, growth, and execution as it advances its pipeline of abuse-deterrent transdermal products, including AVERSA™ Fentanyl.

About Nutriband Inc.

We are primarily engaged in the development of a portfolio of transdermal pharmaceutical products. Our lead product under development is an abuse deterrent fentanyl patch incorporating our AVERSA™ abuse deterrence technology. AVERSA™ technology can be incorporated into any transdermal patch to prevent the abuse, misuse, diversion, and accidental exposure of drugs with abuse potential.

The Company’s website is www.nutriband.com. Any material contained in or derived from the Company’s websites or any other website is not part of this press release.

Forward-Looking Statements

Certain statements contained in this press release, including, without limitation, statements containing the words “believes,” “anticipates,” “expects” and words of similar import, constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Such forward-looking statements involve both known and unknown risks and uncertainties. The Company’s actual results may differ materially from those anticipated in its forward-looking statements as a result of a number of factors, including those including the Company’s ability to develop its proposed abuse-deterrent fentanyl transdermal system and other proposed products, its ability to obtain patent protection for its abuse technology, its ability to obtain the necessary financing to develop products and conduct the necessary clinical testing, its ability to obtain Federal Food and Drug Administration approval to market any product it may develop in the United States and to obtain any other regulatory approval necessary to market any product in other countries, including countries in Europe, its ability to market any product it may develop, its ability to create, sustain, manage or forecast its growth; its ability to attract and retain key personnel; changes in the Company’s business strategy or development plans; competition; business disruptions; adverse publicity and international, national and local general economic and market conditions and risks generally associated with an undercapitalized developing company, as well as the risks contained under “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in the Company’s periodic and current reports on Form 10-K, Forms 10-Q and 8-K and the Company’s other filings with the Securities and Exchange Commission. Except as required by applicable law, we undertake no obligation to revise or update any forward-looking statements to reflect any event or circumstance that may arise after the date hereof.

Contact Information:
Nutriband Inc.
Phone: 407-377-6695
Email: [email protected]

Source: Nutriband Inc.

© 2026 GlobeNewswire, Inc.

Akamai Lands $11.6 Billion Anthropic Deal, Shares Soar

Akamai Technologies just landed one of the biggest AI infrastructure contracts of the year — and Wall Street noticed immediately. Shares jumped as much as 20% in after-hours trading Thursday after the company announced an $11.6 billion seven-year contract with artificial intelligence giant Anthropic.

The agreement will support Anthropic’s CPU workload requirements through Akamai Cloud’s distributed AI infrastructure and software. It builds on momentum Akamai already had this year — the new commitment adds to more than $2.8 billion in multi-year Cloud Infrastructure Services commitments the company had previously announced.

The most interesting part of this deal isn’t just the dollar figure — it’s the structure. Instead of a straightforward services contract, Akamai issued a warrant to Anthropic for the purchase of non-voting convertible Series B Preferred Stock representing 7.7 million shares of Akamai’s common stock on an as-converted basis — up to approximately 5% of the company’s outstanding common stock, at an exercise price of $111.33 per share.

That equity doesn’t vest all at once. About 2% of Akamai’s common stock outstanding is expected to vest in connection with the $11.6 billion commitment announced Thursday, while the remaining approximately 3% would vest through the successful expansion of the commitment up to an additional $9 billion within the seven-year term of the warrant. The incentive structure is tiered: each additional $3 billion purchase of cloud services will result in the vesting of approximately 1% of Akamai’s common stock outstanding. In plain terms — the more compute Anthropic buys, the more of Akamai it can end up owning. It aligns both companies’ incentives: Anthropic gets a discount-like mechanism tied to usage, and Akamai locks in a customer that’s motivated to keep scaling with them rather than shop around.

Akamai co-founder and CEO Dr. Tom Leighton framed it as validation of the company’s infrastructure push, saying he was pleased Anthropic chose Akamai’s capabilities for building and operating AI infrastructure at scale.

On the cost side, total capital expenditures related to the $11.6 billion commitment are estimated to be approximately $5.5 billion. Akamai says the deal won’t disrupt this year’s numbers — the company expects no impact to its 2026 revenue guidance — but it will front-load spending: an increase of approximately $1.7 billion in capital expenditures in 2026 to secure and pre-purchase critical supply chain components, including memory.

This is another data point in the broader trend of AI labs locking in long-term infrastructure capacity years in advance — and paying for it partly in equity, which ties the infrastructure providers’ stock performance directly to AI demand. For a company like Akamai, historically known more for content delivery than AI compute, this deal is a signal that it’s repositioning itself as a serious player in AI infrastructure — and the market rewarded that repositioning instantly with a 20% pop.

Release – Lucibeth N. Mayberry Named President and CEO and Director of CoreCivic Patrick D. Swindle Steps Down Due to Health Reasons

CoreCivic

Research News and Market Data on CXW

September 25, 2026

PDF Version

BRENTWOOD, Tenn., Sept. 25, 2026 (GLOBE NEWSWIRE) — CoreCivic, Inc. (NYSE: CXW) (“CoreCivic” or the “Company”) announced today that the Board of Directors of the Company has appointed Lucibeth N. Mayberry as President and Chief Executive Officer of the Company. Patrick D. Swindle has resigned as President and Chief Executive Officer due to health reasons. Mr. Swindle has served as President and Chief Executive Officer since January 1, 2026, following his appointment as President and Chief Operating Officer on January 1, 2025. In addition, Mr. Swindle resigned from CoreCivic’s Board, and Ms. Mayberry has been appointed to fill the vacancy.

Mr. Swindle said, “It is with a heavy heart that I am announcing my decision to resign as President and CEO of CoreCivic, as I pursue treatment for stage four metastatic pancreatic cancer. It has been the greatest professional honor of my life to serve as President and CEO of this Company. We have an excellent leadership team at CoreCivic, and Lucibeth has been an indispensable member of our executive leadership team, with whom I’ve worked closely for nineteen years on many critical strategic matters for the Company, including the property sales we announced earlier this year. Lucibeth is one of the most capable and principled leaders I know, and I have no doubt that under her stewardship, this Company will continue to grow and make a difference in the lives of the individuals entrusted to our care.”

Ms. Mayberry said, “Patrick is not only a remarkable leader but a valued colleague and a dear friend. I am personally thankful for his mentorship and his numerous contributions to CoreCivic, not just as Chief Executive Officer, but over the course of his many years with the Company. Patrick has been instrumental in leading CoreCivic through a significant period of development and change during his time as President and CEO. I am fully committed to continuing the current capital allocation strategy, maintaining our focus on operational excellence, and look forward to building on the progress already underway.”

Mark Emkes, chair of the Board of Directors, commented, “On behalf of the Board of Directors, I thank Patrick and extend our very best wishes to him and his family. Patrick helped make the Company stronger and more flexible and positioned the Company well for the future. We are profoundly grateful for everything Patrick has given to this organization, and we are honored that he will continue to lend his guidance as a special advisor during this transition. In appointing Lucibeth, the Board is recognizing her significant leadership and the trust she has earned across the organization. She has a deep understanding of our business, a proven ability to execute strategic initiatives, and the full confidence of the Board to lead CoreCivic forward while continuing the strategy that has strengthened the Company and created value for shareholders.”

Ms. Mayberry has served as the Executive Vice President and Chief Strategy Officer since May 2025. From October 2022 to May 2025, Ms. Mayberry served as the Executive Vice President and Chief Innovation Officer. Prior to assuming that role, Ms. Mayberry served as Executive Vice President, Real Estate from May 2015 until October 2022. She has previously served in various roles at CoreCivic since May 2003, including as Vice President, Deputy Chief Development Officer; Vice President, Research, Contract and Proposals; and as Managing Director, State Partnership Relations. Ms. Mayberry holds a bachelor’s degree from the University of Tennessee, a juris doctor from Vanderbilt University, and a Master of Laws degree in taxation from the University of Florida.

About CoreCivic

CoreCivic is a diversified, government-solutions company with the scale and experience needed to solve tough government challenges in flexible, cost-effective ways. We provide a broad range of solutions to government partners that help build safer, healthier, and more productive communities one person at a time through residential corrections, detention, and reentry management, adjacent service offerings that include pharmaceutical, transportation, and alternatives to incarceration, and government real estate solutions. We are the nation’s largest owner of partnership correctional, detention and residential reentry facilities, and one of the largest operators of such facilities in the United States. We have been a flexible and dependable partner for government for more than 40 years. Our employees are driven by a deep sense of service, high standards of professionalism and a responsibility to help government better the public good. Learn more at www.corecivic.com.

Cautionary Note Regarding Forward-Looking Statements

This press release contains statements as to our beliefs and expectations of the outcome of future events that are “forward-looking” statements as defined within the meaning of the Private Securities Litigation Reform Act of 1995, as amended, including, but not limited to, statements concerning the transition of executive leadership at CoreCivic. These forward-looking statements may include such words as “anticipate,” “estimate,” “expect,” “project,” “plan,” “intend,” “believe,” “may,” “will,” “should,” “can have,” “likely,” and other words and terms of similar meaning in connection with any discussion of the timing or nature of future operating or financial performance or other events. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from the statements made. Important factors that could cause actual results to differ from our expectations are described in the filings made from time to time by CoreCivic with the Securities and Exchange Commission (“SEC”) and include the risk factors described in CoreCivic’s Annual Report on Form 10-K for the year ended December 31, 2025, filed with the SEC on February 20, 2026 and subsequent filings.

CoreCivic takes no responsibility for updating the information contained in this press release following the date hereof to reflect events or circumstances occurring after the date hereof or the occurrence of unanticipated events or for any changes or modifications made to this press release or the information contained herein by any third-parties, including, but not limited to, any wire or internet services, except as may be required by law.

52053606.2

Contact:Investors: Jeb Bachmann – Managing Director, Investor Relations – (615) 263-3024
Media: Steve Owen – Vice President, Communications – (615) 263-3107

Release – Ocugen Receives Provisional Approval and Priority Designation Under the Longevity and Regenerative Therapies Act in The Bahamas to Provide OCU400 to Patients for Treatment of Retinitis Pigmentosa

Research News and Market Data on OCGN

September 25, 2026

PDF Version

  • Ocugen will provide its investigational modifier gene therapy OCU400 through an expanded access program (EAP), with the goal of enabling the first patient to be treated for retinitis pigmentosa (RP) within 90 days, following full approval by the Longevity and Regenerative Therapies Board (LARTA Board)
  • In partnership with the LARTA Board, Ocugen intends to address global access and unmet need through commercial pricing evidenced with cost-effectiveness for a one-time broad treatment of RP
  • A novel modifier gene therapy for RP, OCU400 is advancing through Phase 3, with topline data expected in 1Q 2027 and a Biologics License Application submission planned for 2Q 2027

MALVERN, Pa., Sept. 25, 2026 (GLOBE NEWSWIRE) — Ocugen, Inc. (“Ocugen” or the “Company”) (NASDAQ: OCGN), a pioneering biotechnology leader in gene therapies for blindness diseases, today announced that OCU400 has been granted provisional approval and priority designation from the LARTA Board, the regulatory agency responsible for reviewing and approving longevity and regenerative therapy programs within the Commonwealth of The Bahamas. Ocugen will supply OCU400 through an EAP, with the goal of treating the first RP patient within 90 days, following full LARTA approval.

“Our partnership marks an important milestone for Ocugen – creating a unique opportunity to provide global access through the Bahamas to OCU400 for people suffering from retinitis pigmentosa,” said Dr. Shankar Musunuri, Chairman, CEO and Co-Founder of Ocugen. “This landmark collaboration demonstrates the potential of our differentiated gene therapy platform and represents an exciting step toward expanding the reach of our innovative, one-time treatments for patients with serious retinal diseases.”

LARTA Priority Designation
LARTA Priority Designation recognizes the scientific and clinical promise of a program and its potential to address significant unmet medical need. When granted alongside Provisional LARTA Approval, it places the program on a structured pathway of enhanced regulatory engagement and expedited coordination, designed to advance it towards Full Approval, operational readiness and responsible patient access.

About OCU400
OCU400 is a modifier gene therapy candidate, currently in Phase 3, targeting a broad RP indication – from early-to late-stage disease; pediatric to adult patients – and is designed to treat mutations caused by more than 100 genes. It is based on a nuclear hormone receptor gene called NR2E3 which regulates diverse physiological functions within the retina, such as photoreceptor development and maintenance, metabolism, phototransduction, inflammation, and cell survival. Retinal cells in RP patients have a dysfunctional gene network, and OCU400 is designed to reset this network to reestablish a healthy cellular homeostasis. OCU400 has been granted Regenerative Medicine Advanced Therapy (RMAT) and Orphan Drug Designation (ODD) by the U.S. Food and Drug Administration (FDA), and Orphan Medicinal Product Designation (OMPD) by the European Medicines Agency (EMA).

About Ocugen, Inc.
Ocugen, Inc. is a pioneering biotechnology company developing gene therapies for blindness diseases. The Company’s breakthrough modifier gene therapy platform has the potential to address significant unmet medical needs across large patient populations through a gene-agnostic approach. Unlike traditional gene therapies and gene-editing technologies that target a single gene mutation, Ocugen’s modifier gene therapies are designed to address the underlying disease biology by restoring balance across multiple gene networks. The Company is currently advancing programs for inherited retinal diseases and other causes of blindness that affect millions worldwide, including retinitis pigmentosa, Stargardt disease, and geographic atrophy, an advanced form of dry age-related macular degeneration. Discover more at www.ocugen.com and follow us on LinkedIn and X.

Cautionary Note on Forward-Looking Statements
This press release contains forward-looking statements within the meaning of The Private Securities Litigation Reform Act of 1995, including, but not limited to, statements regarding strategy, business plans and objectives for Ocugen’s clinical programs, plans and timelines for the preclinical and clinical development of Ocugen’s product candidates, including the therapeutic potential, clinical benefits and safety thereof, expectations regarding timing, success and data announcements of current ongoing preclinical and clinical trials, including the timing of enrollment and data readouts, the ability to initiate new clinical programs, statements regarding the ability to treat the first patient 90 days after obtaining Provisional LARTA Approval and Priority Designation in The Bahamas, qualitative assessments of available data, potential benefits, expectations for ongoing clinical trials, anticipated regulatory filings and anticipated development timelines, statements regarding potential market size and commercial possibilities of Ocugen’s product candidates, which are subject to risks and uncertainties. We may, in some cases, use terms such as “predicts,” “believes,” “potential,” “proposed,” “continue,” “estimates,” “anticipates,” “expects,” “plans,” “intends,” “may,” “could,” “might,” “will,” “should,” or other words that convey uncertainty of future events or outcomes to identify these forward-looking statements. Such statements are subject to numerous important factors, risks, and uncertainties that may cause actual events or results to differ materially from our current expectations, including, but not limited to, the risks that receipt of Provisional LARTA Approval and Priority Designation may not lead to faster regulatory review and Full Approval; that preliminary, interim and top-line clinical trial results may not be indicative of, and may differ from, final clinical data; that unfavorable new clinical trial data may emerge in ongoing clinical trials or through further analyses of existing clinical trial data; that earlier non-clinical and clinical data and testing may not be predictive of the results or success of later clinical trials; and that clinical trial data are subject to differing interpretations and assessments, including by regulatory authorities. These and other risks and uncertainties are more fully described in our filings with the Securities and Exchange Commission (SEC), including the risk factors described in the section entitled “Risk Factors” in the quarterly and annual reports that we file with the SEC. Any forward-looking statements that we make in this press release speak only as of the date of this press release. Except as required by law, we assume no obligation to update forward-looking statements contained in this press release whether as a result of new information, future events, or otherwise, after the date of this press release.

Contacts:

Investors:
Candice Masse
astr partners
[email protected]

Media:
Chris Clark
[email protected]

Release – Conduent to Host Investor Day on September 30, 2026

Research News and Market Data on CNDT

September 24, 2026

Corporate Earnings/Financial

Conduent Incorporated (Nasdaq: CNDT), a global technology-driven business solutions and services company, today announced that it will host an Investor Day on Wednesday, September 30, 2026, from 8:25 a.m. ET – 12:30 p.m. ET at The Pierre Hotel in New York City.

Harsha V. Agadi, President and Chief Executive Officer, and members of Conduent’s executive leadership team will provide an overview of the company’s long-term strategy, portfolio priorities and growth opportunities across its markets, followed by a question-and-answer session.

The Investor Day live webcast will be open to the public and will be available at investor.conduent.com . The presentation slides will be posted at investor.conduent.com when the presentation begins, and a replay will be available on the site for 90 days following the event.

The Company may discuss material information at the Investor Day. Presentation materials will be furnished on a Form 8-K and will be available on the site.

About Conduent
Conduent is a global technology-enabled operating partner that helps businesses and governments simplify complexity, modernize mission critical operations and deliver measurable outcomes through AI, automation, data and human expertise. Learn more at www.conduent.com .

Note: To receive RSS news feeds, visit www.news.conduent.com . For open commentary, industry perspectives and views, visit https://x.com/Conduent , http://www.linkedin.com/company/Conduent or http://www.facebook.com/Conduent .

Trademarks
Conduent is a trademark of Conduent Incorporated in the United States and/or other countries. Other names may be trademarks of their respective owners.

Forward-Looking Statements
This release contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, each as amended, including statements regarding the Company’s Investor Day and the long-term strategy, portfolio priorities and growth opportunities to be discussed there. These statements are not guarantees of future performance. They are based on management’s current expectations and assumptions and are subject to known and unknown risks and uncertainties, many of which are outside the Company’s control, that could cause actual results to differ materially from those expressed or implied, including the factors described under Risk Factors in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025 and in its subsequent Quarterly Reports on Form 10-Q, which are available at investor.conduent.com and www.sec.gov . Forward-looking statements speak only as of the date of this release, and the Company undertakes no obligation to update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law.

Media Contact:
Remy Kaul, Conduent, [email protected]

Investor Relations Contact:
Nick Goel, Conduent, [email protected]

Treasury Yields Keep Climbing. Even Fed-Adjacent Voices Are Taking Notice

The bond market selloff we detailed just yesterday didn’t ease up, it accelerated. The 10-year Treasury yield climbed as high as 5.12% Wednesday, extending its climb to the highest level since 2007. The 30-year yield touched 5.4%, its highest level since 2004, while the 5-year yield also jumped to levels last seen in 2007. Rates have held at these elevated levels since.

The reaction from BlackRock’s chief investment officer of global fixed income carries particular weight given his background. Rick Rieder, who was among the finalists considered for the Federal Reserve chair position that ultimately went to Kevin Warsh, described the situation plainly, calling it not a crisis but an eye-opener, and something investors genuinely need to think through carefully. Coming from someone who was seriously considered for the job now shaping the Fed’s response to exactly this kind of market stress, that framing is worth taking seriously.

The catalysts behind the move are the same ones we’ve tracked closely this week, oil prices advancing again and business activity data coming in hotter than expected, both reinforcing concerns that the Fed may need to raise rates further. Fed officials are doing little to calm those fears. New York Fed President John Williams said Thursday it would be reasonable to expect another rate hike before year-end to bring inflation under control, echoing comments Fed Governor Michael Barr made just a day earlier. That’s now two sitting Fed officials publicly reinforcing the hawkish posture Warsh struck at his Jackson Hole speech last month, a signal that this isn’t isolated commentary but a genuinely coordinated message from the committee.

What makes Rieder’s specific choice of words notable is the distinction he’s drawing. Calling something an eye-opener rather than a crisis suggests this isn’t a moment of panic or dysfunction in the bond market itself, but rather a signal worth taking seriously about where borrowing costs are actually headed, and for how long. That’s a meaningfully different read than the alarm bells some market commentary has sounded, and it’s coming from someone with genuine insider perspective on how the Fed is likely thinking about this exact tradeoff.

For companies operating below the $2 billion market cap threshold, the practical stakes haven’t changed from what we outlined yesterday, they’ve simply intensified. Small and microcap businesses carry disproportionately more variable-rate debt than large cap peers, and every additional basis point on the 10-year and 30-year yields translates into real, rising borrowing costs for exactly this segment of the market. With two Fed officials now on record supporting further hikes and yields showing no sign of retreating, the higher-cost-of-capital environment weighing on small caps looks increasingly like the new baseline rather than a temporary spike, something worth watching closely heading into year-end.

V2X (VVX) – Follow-on Award


Thursday, September 24, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Business. V2X continues to add business with a recent follow-on award from the Air Force for base support services and a position on an ID/IQ supporting the Air Force’s Carriage Equipment Production Effort for the Long Range Standoff (LRSO) cruise missile program. Such awards demonstrate V2X’s strong position to bid for and win new and expanded business, in our opinion.

Follow-on. The Department of War announced that V2X Systems has been awarded an undefinitized contract action with a not-to-exceed ceiling price of $231.8 million, a modification to a previously awarded contract for base support services in support of the Iraq F-16 program. The modification brings the total cumulative face value of the contract to $594.2 million. Work will be performed at Martyr BG Ali Flaih Air Base, Iraq, and is expected to be completed by July 17, 2027. Foreign Military Sales funds in the amount of $115.9 million are being obligated at the time of award.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

NN (NNBR) – Raises Full Year Revenue and Adjusted EBITDA Guide


Thursday, September 24, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

A Raise. For the third time in 2026, NN management raised full-year guidance, reflecting the positive momentum of the business, in our view. Full-year revenue is now expected to be in the $470-$490 million range, with adjusted EBITDA now projected to be in the $58-$68 million range, up from a prior $460-$480 million and $55-$65 million, respectively. Initial 2026 guidance called for revenue in the $445-$465 million range and adjusted EBITDA in the $50-$60 million range.

Management Commentary. NN management noted, “Our business continues to build momentum as we ramp up in our key growth markets of Data Center, Defense & Electronics, and Medical, where demand for our solutions remains strong and actively expanding. Our year-to-date results and year-to-go forecast underpin this improved guidance and reflect the steady performance of our growth and cost programs.”


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

NanoViricides (NNVC) – Phase 2 Clinical Trial For HV-387 In MPox Begins


Thursday, September 24, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Phase 2 Trial Patient Enrollment Has Started. NanoViricides has begun enrolling patients in the Phase 2 clinical trial testing NV-387 for MPox Virus Infection in the Democratic Republic of Congo (DRC). This meets our expected timeframe for the start of the trial, with preliminary results expected in late 4Q26. We anticipate a second trial testing NV-387 to start shortly in the same region.

Phase 2 Trial Design. The trial is an open-label study designed to evaluate the efficacy and safety of NV-387 compared with the standard of care. The trial is being conducted in Lodja, Sankuru Province, DRC, a remote province not (yet) affected by the Ebola outbreaks seen in other regions. NV-387 is formulated as an oral solid (gummies) that does not require refrigeration or cold storage, making it practical to administer in remote regions.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Mortgage Rates Just Hit a Two-Year High — Here’s What’s Going On

Homebuyers hoping to catch a break before the year winds down are getting the opposite. The average 30-year mortgage rate jumped to 7.37% on Thursday, the highest level since May 2024, and it’s part of a broader climb that’s been building for weeks. Other trackers, which move a bit slower day to day, confirm the trend: Freddie Mac put the weekly average at 7.03%, while the Mortgage Bankers Association calculated it at 7.12% — both the highest readings since May 2024. As of today, purchase rates on a 30-year fixed sit around 7.20%, with 15-year fixed loans closer to 6.69%. Refinance rates are running similarly, at roughly 7.13% for a 30-year fixed and 6.59% for a 15-year.

The reason rates keep climbing comes down to the bond market. Mortgage rates track the 10-year Treasury yield closely, and that yield has been on a tear, topping 5.1% this week for the first time in 19 years. Investors are demanding more return on that debt because of rising concern over oil prices, persistent inflation, and expectations that the Federal Reserve may need to hike rates further rather than ease up. When bond investors get spooked about inflation eating into their returns, they sell, yields rise to compensate, and mortgage rates follow right along. The timing is especially rough for buyers hoping to close before the 2026 season wraps and everyone shifts attention to the holidays.

What this actually means depends on where you sit. For buyers, every fraction of a percentage point compounds over 30 years — on a $400,000 loan, the gap between a 6.5% and 7.4% rate works out to roughly $230 more per month, or over $80,000 across the life of the loan. That’s exactly why locking your rate once you’ve found the house matters so much in a volatile stretch like this. For anyone considering a refinance, the math is less about whether now is universally “good” and more about your personal break-even point — the common rule of thumb is that it’s worth it if you can drop your rate by one to two percentage points, but you have to weigh that against closing costs, which typically run 2% to 6% of the loan amount, and how long you actually plan to stay in the home. And regardless of which side you’re on, the things you can control still move the needle: credit score, debt-to-income ratio, and down payment size all directly affect the rate a lender offers, so shopping around across banks, credit unions, and mortgage-specific lenders is worth the effort even when the overall market is expensive.

Zoomed out, today’s rates sting compared to the pandemic-era lows everyone remembers — the lowest 30-year rate on record was 2.65% back in January 2021, and it’s extremely unlikely we see anything close to that again soon. But rates near 7.4% are still within a historically normal range once you look back further than the last five years. That’s not much comfort if you’re staring down a monthly payment, but it’s useful context for understanding where we actually are, versus where we got used to being.

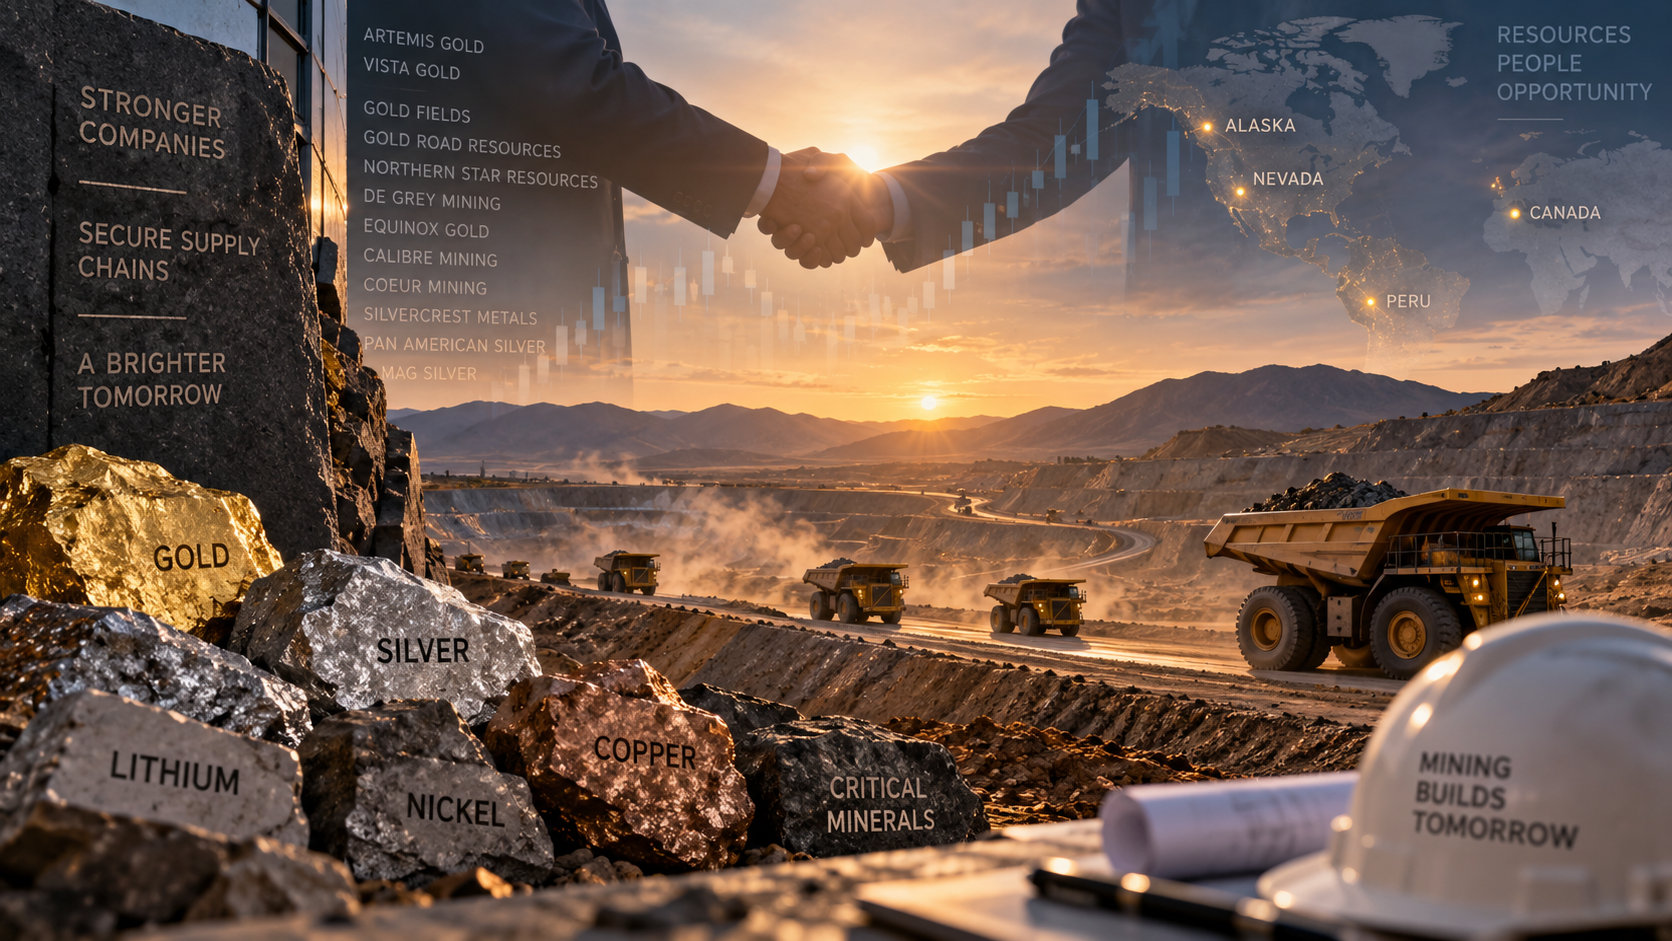
Junior Mining Consolidation Isn’t Coming. It’s Already Underway

The Artemis Gold acquisition of Vista Gold we covered earlier this week wasn’t an isolated event. It was one data point in what industry data increasingly confirms is a genuine, extended wave of consolidation sweeping through the junior and intermediate mining sector, and the drivers behind it suggest this cycle has real staying power rather than representing a short-term spike.

The numbers tell a clear story. Global mining M&A totaled roughly $93.7 billion in completed deals during 2025, and gold and silver assets alone accounted for more than 77% of total deal volume in early 2026. The list of major transactions reads like a sector-wide roll-up already in progress, Gold Fields acquiring Gold Road Resources for approximately $2.4 billion, Northern Star Resources buying De Grey Mining for roughly $3.3 billion, Equinox Gold’s $2.8 billion purchase of Calibre Mining, Coeur Mining’s $1.7 billion acquisition of SilverCrest Metals, and Pan American Silver’s $2.1 billion takeover of MAG Silver. Mining stocks claimed a record 60% of the spots on this year’s TSX30, the annual ranking of Canada’s top-performing stocks, a genuinely striking signal of where investor capital has been flowing.

Three forces are converging to drive this cycle, and each appears structural rather than cyclical. First, reserve depletion. Major producers spent much of the 2010s underinvesting in exploration during a prolonged bear market, and many are now confronting genuinely thinning production pipelines that organic exploration alone cannot refill quickly enough. Acquiring juniors with already-defined, advanced-stage resources is simply faster than starting from scratch. Second, sustained strength in gold and silver prices has given larger producers the cash flow and equity currency to pursue acquisitions, while depressed valuations among smaller developers following years of underperformance have made those same juniors attractively priced targets. Third, and increasingly important, critical minerals supply security has become an explicit policy priority, with roughly a third of surveyed industry executives specifically expecting consolidation in this category as governments and producers alike race to secure supply chains independent of Chinese dominance, a theme we detailed closely when covering the Greenland security agreement earlier this year.

Industry analysts point to a fairly consistent profile among likely takeover targets, advanced-stage resources located in stable, Tier-1 mining jurisdictions, high-grade or district-scale potential, reasonable valuations following recent market corrections, and experienced management teams with a track record of either developing or successfully exiting projects.

That profile is worth keeping in mind when evaluating smaller companies in this space. Junior developers advancing resources in favorable jurisdictions such as Century Lithium, working a lithium project in Nevada, Kuya Silver, developing precious metals assets in Peru, Tectonic Metals, advancing gold exploration in Alaska, and Power Metallic Mines, exploring nickel and copper deposits in Quebec, all sit in exactly the category this consolidation wave has been targeting, smaller companies with defined, advanced-stage projects in stable jurisdictions that larger, cash-generative producers are actively seeking to acquire.

None of this guarantees any individual company becomes a takeover target, and early-stage mining developers carry substantial execution, financing, and geological risk regardless of broader sector M&A trends. But the structural case for continued consolidation, depleted major-producer pipelines, strong commodity prices, and mounting critical minerals policy pressure, looks considerably more durable than a passing trend.

Take a moment and take a look at more small cap mining companies by taking a look at Noble Capital Markets’ Analyst Mark Reichman’s coverage list.

Release – Phase II Clinical Trial of NV-387 as a Treatment for Monkeypox (MPox) Has Begun in DRC, Announces NanoViricides

Research News and Market Data on NNVC

Wednesday, 23 September 2026 08:30 AM

Topic: 

Company Update

SHELTON, CT / ACCESS Newswire / September 23, 2026 / NanoViricides, Inc. (NYSE American:NNVC) (the “Company”) today announced that the Phase II Clinical Trial of the Company’s Novel Broad-Spectrum Antiviral Drug NV-387 as a Treatment for Monkeypox Virus Infection has begun with enrollment of first patients in the Democratic Republic of Congo (DRC).

This clinical trial was registered in the Pan African Clinical Trials Registry database (pactr.samrc.ac.za). The unique identification number for this clinical trial is PACTR202609506749917.

The clinical trial is entitled: “An adaptive international, multi-center, randomized, open-label, interventional, parallel group, phase II (IIa and IIb) clinical trial to evaluate the efficacy and safety of a new chemical entity NV-387 formulated as oral gummies in comparison to standard of care, administered in patients with clinical signs of mpox disease and laboratory confirmed or presumptive hmpxv infection.”

The Principal Investigator for this clinical trial is Prof. Vivi Maketa Tevuzula, MD, MSc, PhD, Professor in the Department of Tropical Medicine at the University of Kinshasa and Principal Investigator at the Institut Multisectoriel pour l’Amélioration du Bien-être (IMABE), Kinshasa, DRC. Her work focuses on infectious diseases, including clinical trials demonstrating the safety and efficacy of novel drugs, and safety, immunogenicity, and efficacy of vaccines, as well as health systems research in resource-limited settings. She has served as principal investigator on multiple international studies on malaria, Mpox, and vaccine-preventable diseases, and leads interdisciplinary research on genomic surveillance and One Health approaches.

Bayer Foundation awarded Dr. Vivi Maketa with the prestigious Early Excellence in Science Award 2023 in Medical Science, recognizing her exceptional contributions to the design and implementation of research projects on infectious and neglected tropical diseases i.

“We are pleased to have Professor Maketa lead this clinical trial,” said Anil R. Diwan, PhD, President and Executive Chairman of the Company, adding, “This is the very first Phase II clinical trial of the broad-spectrum antiviral drug NV-387 and aims to explore its safety and effectiveness in Mpox.”

There is no approved drug for Mpox. Clinical trials of a drug called tecovirimat (TPOXX, SIGA) have previously failed to demonstrate efficacy against both Mpox Clade II and Mpox Clade I. Tecovirimat was approved by US FDA for Smallpox under the Animal Rule provision.

A pan-African clinical trial called “MOSA” of a drug called brincidofovir, which is approved by US FDA for Smallpox under the Animal Rule provision, that started in January, 2025, is currently ongoing. As of January 2026, according to a press release, this study’s Data Safety and Monitoring Board (DSMB) did not identify any new safety concern after the first 50 patients were randomized, and the trial plans to enrol a further 50 patients in the first half of 2026, to perform interim efficacy analysis of brincidofovir ii. Brincidofovir requires constant physician care due to dose-limiting liver and gastro-intestinal toxicity concerns iii.

NV-387 could become the “go to” pandemic response drug if it is successful in this Phase II MPox clinical trial, and becomes a FDA-licensed (approved) drug. US Government SNS stockpiling contracts for existing smallpox drugs TPOXX and TEMBEXA have been in several hundreds of millions of dollars, representing an equivalent potential opportunity for NV-387.

The Phase II clinical trial for NV-387 as a treatment of mpox is being conducted at Lodja in Sankuru province in DRC. As of now, this province is not an ebola-affected region.

Professor Maketa’s team is already on site in DRC. In addition, The team of our CRO from India, Om Sai Clinical Research Pvt. Ltd., is also on site in DRC to start the clinical trial.

Lodja is a remote location and mpox cases are continuing to occur in that area. This is a resource-poor region. Setting up the clinical sites required several months of effort because of the resource limitations at the hospital.

MPox Clade I is endemic in DRC and all cases in the clinical trial are expected to be of the Clade I virus. The other prominent MPox virus, MPox Clade II is substantially less severe an infection than MPox Clade I.

MPox Clade II has become endemic in the USA, circulating at low levels. It primarily affects a limited population of Men-having-Sex-with-Men (MSM), because of transmission during sexual activity.

MPox is an “Orphan Disease” in the USA. NanoViricides has applied to the US FDA for Orphan Drug Designation (ODD) of NV-387 for the treatment of MPox. This ODD, assuming it is granted, would enable several benefits including frequent meetings with FDA, waiver of certain FDA fees, certain R&D credits, as well as extension in exclusivity in marketing once approved.

These ODD benefits can have a positive economic impact for NanoViricides estimated in the range of tens of millions of dollars.

MPox Clade I cases in the USA have been slowly increasing. As of August 27, 2026, since November 2024, there have been more than 50 confirmed cases of Mpox Clade I in the USA, all of which were either travelers to Mpox-manifesting countries or regions, or contacts of such travelers, according to the CDC iv. Community spread of the MPXV Clade I is likely occurring, with 3 cases of MPox Clade I with no travel to Africa, in California in unconnected persons, according to the CDC v. However, the potential for a widespread outbreak remains low.

From 2023-2025, about 1,700-2,800 cases of Mpox Clade II were confirmed in the USA, mostly occurring in men-having-sex-with men and associated sexual partners, according to the CDC (ibid #4). Clade II is transmitted via skin abrasions.

Thus MPox is becoming important in the USA from the perspective of pandemic preparedness and response. Although there is a vaccine originally developed for smallpox, namely, Jynneos, that is in use to prevent MPox (primarily in clade II contacts), its immune protection was found to wane rapidly in a clinical study vi. The effectiveness of this vaccine is limited, at 36% for one dose and 66% for 2 doses against the less pathogenic MPox Clade II vii.

The vaccine effectiveness is likely to be much less against the more severe MPox Clade I.

Vaccines do not protect in the first few weeks, limiting their usefulness during pandemic.

We believe that there will be a strong opportunity for NV-387 for pandemic preparedness and response for the threats of Mpox and Smallpox in the USA if this Phase II clinical trial of NV-387 for the treatment of Mpox is successful. The two drugs in the USA Strategic National Stockpile (SNS), TPOXX and TEMBEXA, would be unsuitable for pandemic response if MPox Clade I spreads. Although both of these drugs are approved for Smallpox, a bioterrorism agent, under the FDA animal rule, the clinical trial failure of tecovirimat against Mpox which is a much less severe and far less lethal disease compared to Smallpox raises questions about its possible utility in a Smallpox bioterrorism event. In addition, the known toxicity profile and warnings for brincidofovir make it unsuitable for wide-scale deployment in a large outbreak scenario.

“NV-387, our broad-spectrum antiviral drug is poised to cause a revolution in treatment of viral diseases, just as antibiotics revolutionized the treatment of bacterial diseases,” said Anil R. Diwan, Ph.D., adding “NV-387 is designed to mimic human cells to trap and destroy the virus. This single drug can target over 90-95% of human pathogenic viruses due to this biomimicry, which is reminiscent of the antibiotic penicillin that targets a large number of human pathogenic bacteria.”

NV-387 was found to possess strong antiviral activity against an orthopoxvirus in an animal model that is considered an important model to establish potential effectiveness against MPox and Smallpox viruses, as all of these viruses belong to the same family of orthopoxviruses.

In fact, NV-387 effectiveness matched the effectiveness of the small chemical drug tecovirimat in two different models of infection, one was direct skin infection, and the other was a direct lung infection, by the virus.

Escape of virus from tecovirimat is known to occur by a single point mutation in a viral protein called VP-37.

Vaccines, antibodies, and small chemical drugs such as tecovirimat for MPox/Smallpox, or oseltamivir (Tamiflu®), baloxavir (Xofluza®) for Influenza are readily escaped by viruses simply by introduction of small changes that viruses undergo when they are faced with these challenges in the field.

In contrast, escape of virus from NV-387 is highly unlikely because no matter how much the virus changes in the field, it continues to use sulfated proteoglycans such as HSPG as “attachment receptor” in order to cause cell infection. NV-387 mimics the sulfated proteoglycan signature feature that the viruses require.

NV-387 is a host-mimetic drug that “looks like a cell” to the virus, displaying numerous ligands that mimic the sulfated proteoglycan, enticing the virus to bind to and become engulfed by the NV-387 dynamic shape-shifting polymeric micelle.

Therefore development of NV-387, a broad-spectrum host-mimetic, direct-acting antiviral drug that the viruses cannot escape even as they change constantly, will be revolutionary once the drug undergoes regulatory development for approval for use in humans.

New viruses and existing viruses acquiring greater pathology and infectivity are bound to keep appearing in time. To combat such threats, we need to develop broad-spectrum drug arsenal that the viruses cannot escape. Vaccines and antibodies simply will not do, and their limitations have become clearly evident during the COVID-19 pandemic.

About NanoViricides

NanoViricides, Inc. (the “Company”) (www.nanoviricides.com) is a clinical stage company that is creating special purpose nanomaterials for antiviral therapy. The Company’s novel nanoviricide™ class of drug candidates and the nanoviricide™ technology are based on intellectual property, technology and proprietary know-how of TheraCour Pharma, Inc. The Company has a Memorandum of Understanding with TheraCour for the development of drugs based on these technologies for all antiviral infections. The MoU does not include cancer and similar diseases that may have viral origin but require different kinds of treatments.

The Company has obtained broad, exclusive, sub-licensable, field licenses to drugs developed in several licensed fields from TheraCour Pharma, Inc. The Company’s business model is based on licensing technology from TheraCour Pharma Inc. for specific application verticals of specific viruses, as established at its foundation in 2005.

Our lead drug candidate is NV-387, a broad-spectrum antiviral drug that we plan to develop as a treatment of RSV, COVID, Long COVID, Influenza, and other respiratory viral infections, as well as MPOX/Smallpox infections. Our other advanced drug candidate is NV-HHV-1 for the treatment of Shingles. The Company cannot project an exact date for filing an IND for any of its drugs because of dependence on a number of external collaborators and consultants. The Company is currently focused on advancing NV-387 into Phase II human clinical trials.

NV-CoV-2 (API NV-387) is our nanoviricide drug candidate for COVID-19 that does not encapsulate remdesivir. NV-CoV-2-R is our other drug candidate for COVID-19 that is made up of NV-387 with remdesivir encapsulated within its polymeric micelles. The Company believes that since remdesivir is already US FDA approved, our drug candidate encapsulating remdesivir is likely to be an approvable drug, if safety is comparable. Remdesivir is developed by Gilead. The Company has developed both of its own drug candidates NV-CoV-2 and NV-CoV-2-R independently.

The Company is also developing drugs against a number of viral diseases including oral and genital Herpes, viral diseases of the eye including EKC and herpes keratitis, H1N1 swine flu, H5N1 bird flu, seasonal Influenza, HIV, Hepatitis C, Rabies, Dengue fever, and Ebola virus, among others. NanoViricides’ platform technology and programs are based on the TheraCour® nanomedicine technology of TheraCour, which TheraCour licenses from AllExcel. NanoViricides holds a worldwide exclusive perpetual license to this technology for several drugs with specific targeting mechanisms in perpetuity for the treatment of the following human viral diseases: Human Immunodeficiency Virus (HIV/AIDS), Hepatitis B Virus (HBV), Hepatitis C Virus (HCV), Rabies, Herpes Simplex Virus (HSV-1 and HSV-2), Varicella-Zoster Virus (VZV), Influenza and Asian Bird Flu Virus, Dengue viruses, Japanese Encephalitis virus, West Nile Virus, Ebola/Marburg viruses, and certain Coronaviruses. The Company intends to obtain a license for RSV, Poxviruses, and/or Enteroviruses if the initial research is successful. As is customary, the Company must state the risk factor that the path to typical drug development of any pharmaceutical product is extremely lengthy and requires substantial capital. As with any drug development efforts by any company, there can be no assurance at this time that any of the Company’s pharmaceutical candidates would show sufficient effectiveness and safety for human clinical development. Further, there can be no assurance at this time that successful results against coronavirus in our lab will lead to successful clinical trials or a successful pharmaceutical product.

This press release contains forward-looking statements that reflect the Company’s current expectation regarding future events. Actual events could differ materially and substantially from those projected herein and depend on a number of factors. Certain statements in this release, and other written or oral statements made by NanoViricides, Inc. are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. You should not place undue reliance on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and which could, and likely will, materially affect actual results, levels of activity, performance or achievements. The Company assumes no obligation to publicly update or revise these forward-looking statements for any reason, or to update the reasons actual results could differ materially from those anticipated in these forward-looking statements, even if new information becomes available in the future. Important factors that could cause actual results to differ materially from the company’s expectations include, but are not limited to, those factors that are disclosed under the heading “Risk Factors” and elsewhere in documents filed by the company from time to time with the United States Securities and Exchange Commission and other regulatory authorities. Although it is not possible to predict or identify all such factors, they may include the following: demonstration and proof of principle in preclinical trials that a nanoviricide is safe and effective; successful development of our product candidates; our ability to seek and obtain regulatory approvals, including with respect to the indications we are seeking; the successful commercialization of our product candidates; and market acceptance of our products.

The phrases “safety”, “effectiveness” and equivalent phrases as used in this press release refer to research findings including clinical trials as the customary research usage and do not indicate evaluation of safety or effectiveness by the US FDA.

Where stated with an ® , the name is a registered trademark, which belongs to the owner of the trademark name.

FDA refers to US Food and Drug Administration. IND application refers to “Investigational New Drug” application. cGMP refers to current Good Manufacturing Practices. CMC refers to “Chemistry, Manufacture, and Controls”. CHMP refers to the Committee for Medicinal Products for Human Use, which is the European Medicines Agency’s (EMA) committee responsible for human medicines. API stands for “Active Pharmaceutical Ingredient”. WHO is the World Health Organization. R&D refers to Research and Development.

Contact:
NanoViricides, Inc.
[email protected]

Public Relations Contact:
[email protected]

i https://www.bayer-foundation.com/lets-spotlight-our-science-talents-dr-vivi-maketa

ii https://mpx-response.eu/a-first-safety-interim-analysis-of-mosa-shows-no-signal-of-safety-concerns-with-brincidofovir-a-potential-antiviral-to-fight-mpox/

iii According to the drug label (prescribing information), brincidofovir (“TEMBEXA”) carries a black box warning, and has warnings for elevations in hepatic transaminases and bilirubin (liver toxicity) and diarrhea and other gastrointestinal adverse events. Brincidofovir administration must be performed under physician care with continuous evaluation of liver toxicity.

iv https://www.cdc.gov/monkeypox/situation-summary/index.html

v https://www.aha.org/news/headline/2025-10-29-cdc-says-3-cases-severe-mpox-california-may-be-linked-august-case

vi https://www.cidrap.umn.edu/mpox/amid-new-mpox-outbreak-study-suggests-waning-protection-jynneos-vaccine

vii From the Mpox Emergency Response Team, CDC (2023-05) “Vaccine Effectiveness of JYNNEOS against Mpox Disease in the United States,” N Engl J Med 2023;388:2434-43.

SOURCE: NanoViricides
Release – MAIA Biotechnology Expands Pivotal Phase 3 THIO-104 Non-Small Cell Lung Cancer Trial into Spain and Portugal

Primary Logo

Research News and Market Data on MAIA

September 23, 2026 9:17am EDT Download as PDF

THIO-104 advances toward key 2027 interim survival analysis

CHICAGO, Sept. 23, 2026 (GLOBE NEWSWIRE) — MAIA Biotechnology, Inc. (NYSE American: MAIA) (“MAIA”, the “Company”), a clinical-stage biopharmaceutical company focused on developing immunotherapies for cancer, today announced that it has received regulatory approval by the Spanish Agency for Medicines and Medical Devices (AEMPS) and Portugal’s National Authority of Medicines and Health Products (INFARMED) to begin screening patients for its ongoing pivotal Phase 3 THIO-104 clinical trial in non-small cell lung cancer (NSCLC).

Spain and Portugal represent important European markets for NSCLC, with an estimated 30,000 new cases annually across the two countries. Spain has a substantial lung cancer burden associated with historical tobacco exposure, with lung cancer incidence among women continuing to rise. In Portugal, NSCLC accounts for approximately 82% of lung cancer cases, the highest proportion reported among five European populations evaluated in a comparative study.

“Expanding THIO-104 into Spain and Portugal represents another important step in the execution of our pivotal Phase 3 program,” said Vlad Vitoc, M.D., Chairman and Chief Executive Officer of MAIA. “Clinical trial participation can provide patients with access to investigational therapies in markets where access to newly approved lung cancer treatments has historically lagged. By establishing THIO-104 sites in Spain and Portugal, we are broadening access to a potentially important new treatment option for patients with advanced NSCLC who have progressed following standard of care treatments.”

To date, THIO-104 has enrolled 65 NSCLC patients resistant to chemotherapy and checkpoint inhibitor treatments at 28 clinical sites in 6 European countries and 10 sites in Taiwan. Among the six European countries, sites in Hungary, Poland, and Turkey are actively enrolling and dosing patients from populations with the highest lung cancer incidence and mortality rates in Europe and globally.1

MAIA targets 100 patients dosed in THIO-104 by year-end 2026 and expects to have sufficient survival data to conduct an interim data analysis in 2027.

About Ateganosine

Ateganosine (THIO, 6-thio-dG or 6-thio-2’-deoxyguanosine) is a first-in-class investigational telomere-targeting agent currently in clinical development to evaluate its activity in non-small cell lung cancer (NSCLC). Telomeres, along with the enzyme telomerase, play a fundamental role in the survival of cancer cells and their resistance to current therapies. The modified nucleotide 6-thio-2’-deoxyguanosine induces telomerase-dependent telomeric DNA modification, DNA damage responses, and selective cancer cell death. Ateganosine-damaged telomeric fragments accumulate in cytosolic micronuclei and activates both innate (cGAS/STING) and adaptive (T-cell) immune responses. The sequential treatment of ateganosine followed by PD-(L)1 inhibitors resulted in profound and persistent tumor regression in advanced, in vivo cancer models by induction of cancer type–specific immune memory. Ateganosine is presently developed as a second or later line of treatment for NSCLC for patients that have progressed beyond the standard-of-care regimen of existing checkpoint inhibitors.

About MAIA Biotechnology, Inc.

MAIA is a targeted therapy, immuno-oncology company focused on the development and commercialization of potential first-in-class drugs with novel mechanisms of action that are intended to meaningfully improve and extend the lives of people with cancer. Our lead program is ateganosine (THIO), a potential first-in-class cancer telomere targeting agent in clinical development for the treatment of NSCLC patients with telomerase-positive cancer cells. For more information, please visit www.maiabiotech.com.

Forward Looking Statements

MAIA cautions that all statements, other than statements of historical facts contained in this press release, are forward-looking statements. Forward-looking statements are subject to known and unknown risks, uncertainties, and other factors that may cause our or our industry’s actual results, levels or activity, performance or achievements to be materially different from those anticipated by such statements. The use of words such as “may,” “might,” “will,” “should,” “could,” “expect,” “plan,” “anticipate,” “believe,” “estimate,” “project,” “intend,” “future,” “potential,” or “continue,” and other similar expressions are intended to identify forward looking statements. However, the absence of these words does not mean that statements are not forward-looking. For example, all statements we make regarding (i) the initiation, timing, cost, progress and results of our preclinical and clinical studies and our research and development programs, (ii) our ability to advance product candidates into, and successfully complete, clinical studies, (iii) the timing or likelihood of regulatory filings and approvals, (iv) our ability to develop, manufacture and commercialize our product candidates and to improve the manufacturing process, (v) the rate and degree of market acceptance of our product candidates, (vi) the size and growth potential of the markets for our product candidates and our ability to serve those markets, and (vii) our expectations regarding our ability to obtain and maintain intellectual property protection for our product candidates, are forward looking. All forward-looking statements are based on current estimates, assumptions and expectations by our management that, although we believe to be reasonable, are inherently uncertain. Any forward-looking statement expressing an expectation or belief as to future events is expressed in good faith and believed to be reasonable at the time such forward-looking statement is made. However, these statements are not guarantees of future events and are subject to risks and uncertainties and other factors beyond our control that may cause actual results to differ materially from those expressed in any forward-looking statement. Any forward-looking statement speaks only as of the date on which it was made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law. In this release, unless the context requires otherwise, “MAIA,” “Company,” “we,” “our,” and “us” refers to MAIA Biotechnology, Inc. and its subsidiaries.

Investor Relations Contact
+1 (872) 270-3518
[email protected]


1 Sources: Global Cancer Observatory (GLOBOCAN), European Cancer Information System (ECIS), World Cancer Research Fund

Primary Logo

Source: MAIA Biotechnology, Inc.

Released September 23, 2026