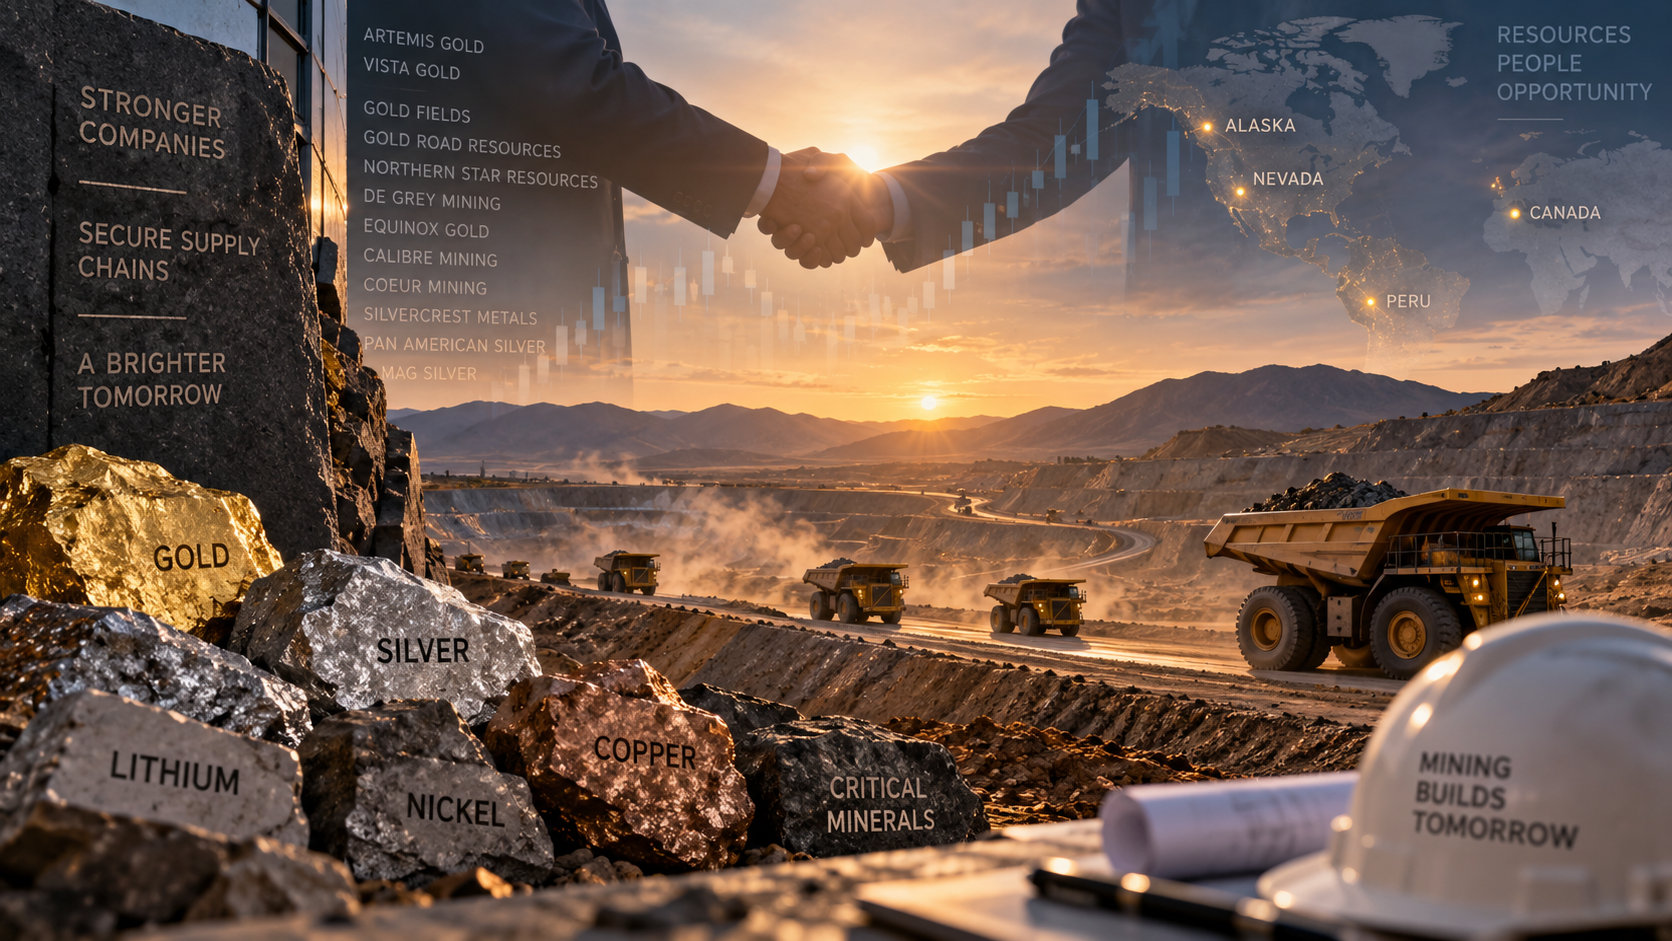
The Artemis Gold acquisition of Vista Gold we covered earlier this week wasn’t an isolated event. It was one data point in what industry data increasingly confirms is a genuine, extended wave of consolidation sweeping through the junior and intermediate mining sector, and the drivers behind it suggest this cycle has real staying power rather than representing a short-term spike.
The numbers tell a clear story. Global mining M&A totaled roughly $93.7 billion in completed deals during 2025, and gold and silver assets alone accounted for more than 77% of total deal volume in early 2026. The list of major transactions reads like a sector-wide roll-up already in progress, Gold Fields acquiring Gold Road Resources for approximately $2.4 billion, Northern Star Resources buying De Grey Mining for roughly $3.3 billion, Equinox Gold’s $2.8 billion purchase of Calibre Mining, Coeur Mining’s $1.7 billion acquisition of SilverCrest Metals, and Pan American Silver’s $2.1 billion takeover of MAG Silver. Mining stocks claimed a record 60% of the spots on this year’s TSX30, the annual ranking of Canada’s top-performing stocks, a genuinely striking signal of where investor capital has been flowing.
Three forces are converging to drive this cycle, and each appears structural rather than cyclical. First, reserve depletion. Major producers spent much of the 2010s underinvesting in exploration during a prolonged bear market, and many are now confronting genuinely thinning production pipelines that organic exploration alone cannot refill quickly enough. Acquiring juniors with already-defined, advanced-stage resources is simply faster than starting from scratch. Second, sustained strength in gold and silver prices has given larger producers the cash flow and equity currency to pursue acquisitions, while depressed valuations among smaller developers following years of underperformance have made those same juniors attractively priced targets. Third, and increasingly important, critical minerals supply security has become an explicit policy priority, with roughly a third of surveyed industry executives specifically expecting consolidation in this category as governments and producers alike race to secure supply chains independent of Chinese dominance, a theme we detailed closely when covering the Greenland security agreement earlier this year.
Industry analysts point to a fairly consistent profile among likely takeover targets, advanced-stage resources located in stable, Tier-1 mining jurisdictions, high-grade or district-scale potential, reasonable valuations following recent market corrections, and experienced management teams with a track record of either developing or successfully exiting projects.
That profile is worth keeping in mind when evaluating smaller companies in this space. Junior developers advancing resources in favorable jurisdictions such as Century Lithium, working a lithium project in Nevada, Kuya Silver, developing precious metals assets in Peru, Tectonic Metals, advancing gold exploration in Alaska, and Power Metallic Mines, exploring nickel and copper deposits in Quebec, all sit in exactly the category this consolidation wave has been targeting, smaller companies with defined, advanced-stage projects in stable jurisdictions that larger, cash-generative producers are actively seeking to acquire.
None of this guarantees any individual company becomes a takeover target, and early-stage mining developers carry substantial execution, financing, and geological risk regardless of broader sector M&A trends. But the structural case for continued consolidation, depleted major-producer pipelines, strong commodity prices, and mounting critical minerals policy pressure, looks considerably more durable than a passing trend.