Dream Finders Wins Beazer for $2.2 Billion After a Months-Long Chase

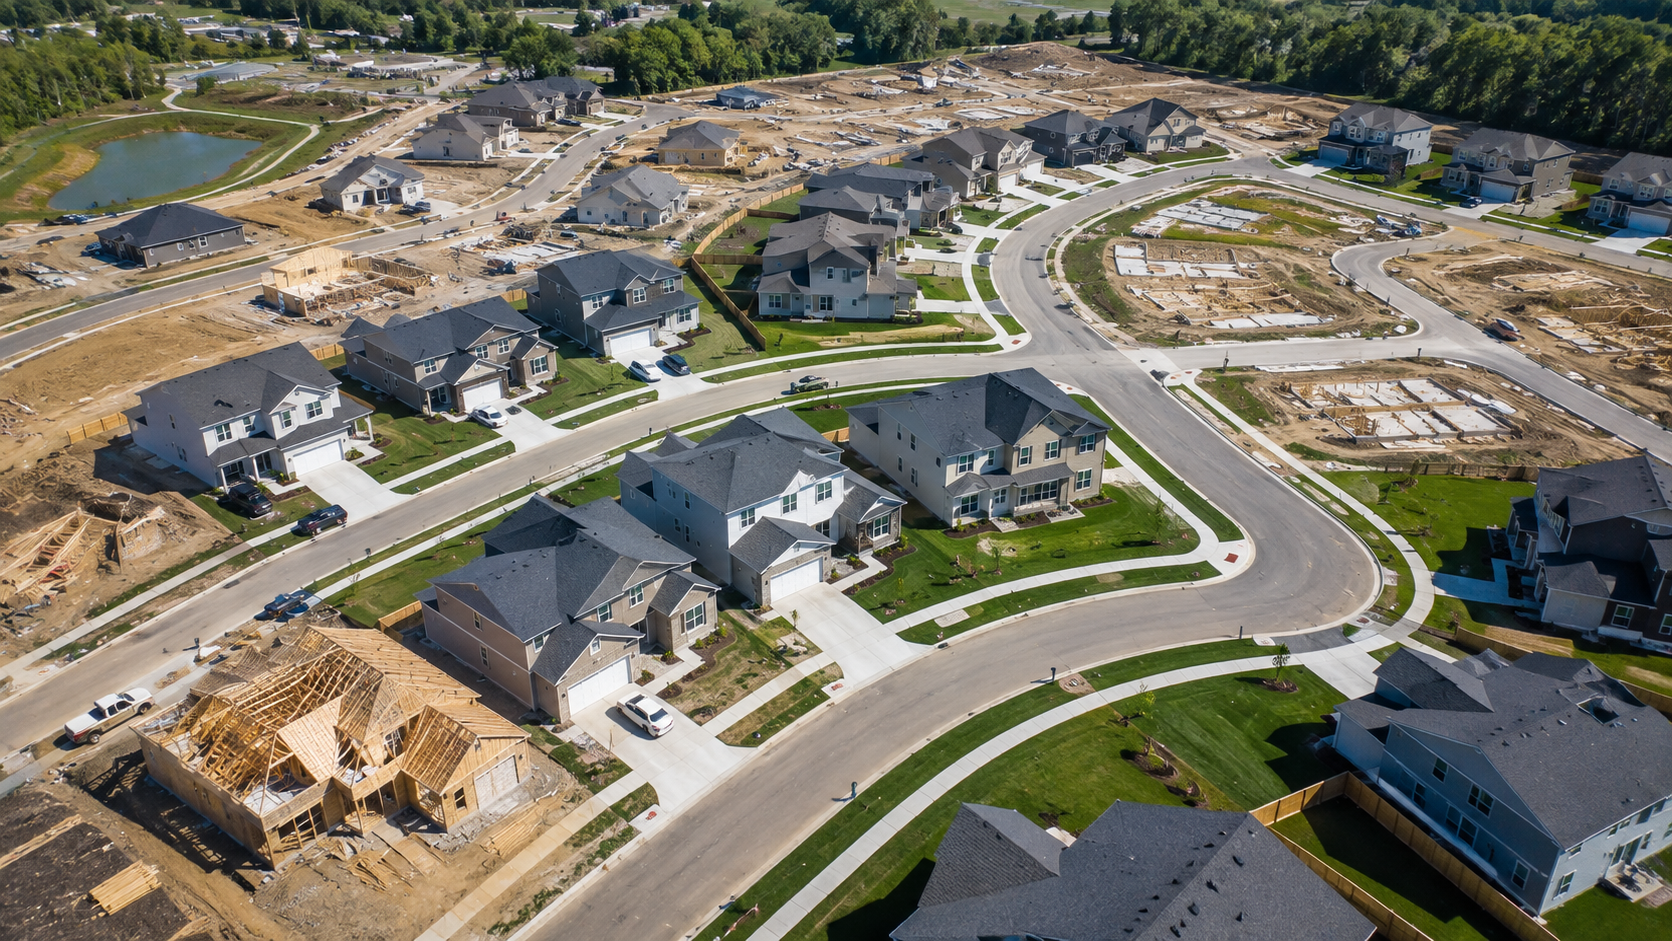
Dream Finders Homes finally got its target. After pursuing Beazer Homes in public for three months, the two builders agreed Wednesday to a deal — and the way it came together says a lot about what beaten-down small-caps are actually worth.

The terms: Dream Finders (NYSE: DFH) will acquire Beazer (NYSE: BZH) in an all-cash transaction worth roughly $2.2 billion in enterprise value, paying $33.50 a share. The combination creates the sixth-largest homebuilder in the country, spanning 26 markets and about 520 active communities across the Southeast, Mid-Atlantic, Texas, the West and the Midwest. Dream Finders expects more than $100 million in annual cost synergies and says the deal will be double-digit-percentage accretive to earnings in year one. It’s targeted to close in the fourth quarter, pending Beazer shareholder and regulatory approval.

This didn’t come out of nowhere. Dream Finders first bid for Beazer back in May, took its case public to pressure Beazer’s board, then raised its offer — from an initial proposal, to $32 a share in late June, to the final $33.50. Beazer resisted, then came to the table. Its CEO framed the outcome plainly: a significant, certain cash return for shareholders in an uncertain market. A persistent acquirer wore down a reluctant target, and both sides decided a bird in hand beat the alternative.

Now the part worth slowing down for. That $33.50 is roughly a 70% premium to where Beazer traded before Dream Finders’ pursuit went public — and it’s still only 0.8 times Beazer’s book value. Both numbers are true at once. Beazer’s stock, like much of the homebuilding sector, had been trading well below the accounting value of its land and finished homes, because high mortgage rates and shaky affordability had the market pricing builders for a downturn. So Dream Finders is buying hard assets for less than book value while handing Beazer’s shareholders a fat premium over where those same assets were being valued. The public market underpriced the balance sheet; a strategic buyer pounced.

That’s the pattern small-cap investors should file away, because it’s the same one running through deal after deal this year. When public markets discount an entire sector below the value of its assets, buyers with a longer horizon step in and roll up the cheap ones. Homebuilding is consolidating — scale drives down costs on purchasing, overhead, and in-house mortgage and title — and the cheapest way to buy scale right now is to buy a rival trading below book. Expect more of it while rates stay high and small builders stay cheap.

None of this is free money. Dream Finders is layering on financing and integration risk, housing demand is genuinely uncertain, and buying below book only pays if those assets hold their value. Beazer’s holders get certainty; Dream Finders’ holders are making a leveraged bet that scale wins.

The headline is “sixth-largest homebuilder.” The quieter lesson is the useful one: in a market that’s written off rate-sensitive sectors, real value is sitting in plain view on small-cap balance sheets — and patient buyers are the ones collecting it.
Nielsen’s $2.15 Billion DoubleVerify Deal: A 30% Premium That Still Locks In a Loss

Nielsen is buying DoubleVerify for $13.60 a share in cash — a 30% premium, the press release says. That premium is real. It’s also about half of what DoubleVerify’s stock fetched the day it went public. Both things are true at once, and the gap between them is the most instructive part of this deal.

Here’s what happened. On Wednesday, Nielsen — itself taken private by a private equity consortium a few years back — agreed to acquire DoubleVerify (NYSE: DV) in an all-cash deal worth roughly $2.15 billion in enterprise value. Shareholders get $13.60 per share, a 30% premium to the stock’s 60-trading-day average through August 5. The deal should close by the first quarter of 2027, after which DoubleVerify delists from the NYSE, becomes a private company under Nielsen, and keeps its name. Providence Equity, which owns about 12%, has agreed to vote in favor.

DoubleVerify isn’t a broken company — and that’s the point. It’s the leading independent platform for ad verification: the plumbing that confirms a digital ad impression was actually seen by a real person, in a brand-safe place, free of fraud. It’s accredited, embedded in the workflows of the world’s biggest advertisers, and it works — 2025 revenue landed around $748 million, up roughly 14%, with real profit and strong free cash flow. A healthy, growing, cash-generative business.

So why is it being bought at $13.60?

Because the market stopped paying up for it. DoubleVerify went public in April 2021 at $27 a share and ran to nearly $47 within months, briefly worth more than $5 billion. Then ad-tech multiples collapsed. Even as the company kept growing revenue and profit year after year, the stock got cut in half, then cut again, bottoming below $8 last year. The business went up and to the right; the multiple went down and to the left. By this week the whole company was worth under $2 billion — less than half its peak value, despite being bigger and more profitable than it was then.

That’s the lesson for anyone hunting the small end of the market. A 30% premium sounds generous until you notice it’s measured off a badly depressed base. IPO buyers are being cashed out at roughly half their money; anyone who chased the 2021 hype is down far more. The premium is genuine against last month’s price — and a permanent loss against the promise the stock once carried.

It also explains the take-private wave we’ve watched all week. When public markets abandon a profitable company and refuse to re-rate it no matter how well it executes, someone with a longer horizon eventually buys the cash flows on the cheap. That’s exactly what Nielsen is doing — and it’s the same logic behind deal after deal in 2026: good small and mid-cap businesses quietly pulled off the public market at prices that reflect the market’s indifference, not the company’s quality.

For DoubleVerify shareholders, it’s a bittersweet exit — a premium today that locks in yesterday’s de-rating. For everyone else, it’s a map. The hunting ground right now is full of profitable, overlooked small-caps trading far below what they’re worth to a patient owner. And the public market keeps losing them, one deal at a time.

Why Friday’s Jobs Report Is a Bigger Deal for Small Caps Than the S&P 500

Everyone will watch Friday’s jobs report for what it says about the Fed. Small-cap investors should watch it more closely than anyone — because no corner of the market is more exposed to the number, and none needs a more specific outcome.

Here’s the setup. Economists expect the US economy added about 80,000 jobs in July, with unemployment holding steady at 4.2%. That would be a step up from June’s soft 57,000. The supporting data this week has been a mixed bag that mostly leans benign: job openings barely moved, ADP’s private hiring gauge came in light but wages for job-switchers ticked higher, and the outplacement firm Challenger reported fewer planned layoffs and more planned hiring. A Bank of America analysis even suggested payroll growth may have picked up in July, with the gains skewed toward lower-income households — whose after-tax pay is now growing faster than higher earners’ for the first time since late 2024.

So why does this matter more to small caps than to the giants at the top of the index?

Because small companies live and die on the cost of capital. They carry more floating-rate debt, they refinance more often, and they lack the fortress balance sheets and overseas cash piles that insulate the mega-caps. When the Fed’s rate path shifts, it moves small caps first and hardest. And the jobs report is the single biggest input into that path. They’re also overwhelmingly domestic, so the health of the US labor market is the health of their customers.

Now the part that makes Friday genuinely tricky: small caps need a Goldilocks number.

Too hot, and the story turns against them. A blowout print sends Treasury yields higher and pushes rate cuts further out — exactly what played out midweek, with yields climbing and the Russell 2000 slipping while the Dow gave back its record run. Too cold, and a different fear takes over: small caps are the most economically sensitive part of the market, so a number weak enough to whisper “recession” hits them harder than anyone. What they want is the narrow middle — cooling enough to keep the Fed cutting, steady enough to keep the expansion intact.

The timing raises the stakes. This lands just as small-cap earnings growth has finally started outpacing large-caps and the market’s rally is broadening beyond a handful of AI names. A friendly jobs number could be the spark that extends that rotation. An ugly one could smother it before it gets going.

One caution worth keeping in view: don’t overtrade a single data point. Payroll figures have been noisy and heavily revised lately — June disappointed, earlier months were marked down — and the reliability of the data itself has been a live debate. One print is a data point, not a trend.

Still, watch Friday closely. The headlines will fixate on the top-line number and the Fed. The more interesting question sits one rung down the market-cap ladder: whether small caps get the number they need to keep their moment alive.

Tarsus Pays $450 Million for a Drug That Won’t Have Data Until 2029

Tarsus Pharmaceuticals (Nasdaq: TARS) announced Thursday it has entered into a definitive agreement to acquire privately held Alkeus Pharmaceuticals, adding gildeuretinol, an investigational once-daily oral therapy for Stargardt disease, to its growing eye care pipeline. Under the terms of the agreement, Tarsus will pay approximately $450 million upfront, including $270 million in cash, with up to $350 million in additional milestone payments and low-to-mid single digit royalties on future product sales.

Alongside the acquisition, Tarsus secured $125 million in gross proceeds through an oversubscribed private placement equity financing, giving the company additional capital to fund the integration and continued clinical development of its expanding pipeline. The deal is expected to close later in 2026, subject to customary closing conditions.

What Alkeus Brings to Tarsus

Stargardt disease is a rare, inherited retinal disorder that currently has no FDA-approved treatments, making it exactly the kind of high unmet need indication that commands significant strategic value despite years remaining before any potential approval. Gildeuretinol has already been studied in more than 400 individuals, demonstrating a favorable tolerability and efficacy profile, and has received both Breakthrough Therapy and Orphan Drug designations from the FDA, two regulatory signals that typically accelerate development timelines and reflect meaningful confidence in a drug’s underlying science.

The catch, and the reason this deal is genuinely a long-term bet, is timing. Topline data from the pivotal Phase 3 NORTHSTAR trial is not expected until the second half of 2029, meaning Tarsus is paying $450 million upfront for an asset that will not produce a definitive readout for roughly three more years.

A Pattern, Not a One-Off Deal

This is not Tarsus’s first eye care acquisition this year. The Alkeus deal builds directly on the company’s recent acquisition of iRenix Medical, which brought IRX-101, a potential ocular antiseptic, into the fold. Combined with its existing pipeline, which includes TP-04 for ocular rosacea and TP-05 for Lyme disease prevention, both currently in Phase 2, Tarsus is deliberately assembling one of the more comprehensive eye care pipelines in the industry rather than remaining a single-product company.

That strategy is being funded by genuine commercial strength. Tarsus reported second quarter 2026 net product sales of $173.9 million for its lead commercial product XDEMVY, an increase of more than 69% year over year, and raised its full-year 2026 XDEMVY sales guidance to a range of $685 million to $705 million. That accelerating commercial performance gives Tarsus the balance sheet flexibility to fund a multi-year pipeline bet like Alkeus while continuing to invest across its broader portfolio.

What It Means for Investors Tracking Ophthalmology and Rare Disease

For investors tracking small and mid cap companies in ophthalmology and inherited retinal disease, this transaction reinforces just how much strategic value the market continues to assign to differentiated science addressing conditions with no approved treatment options, even when the definitive clinical proof point sits years in the future. The broader inherited retinal disease space remains an area of active development, with companies like Ocugen continuing to advance gene therapy programs targeting similar categories of rare, previously untreatable retinal conditions.

Tarsus is betting that being the eye care company with the deepest pipeline, not just the strongest single product, is what builds durable value over the next decade. The market’s initial reaction, with shares pulling back modestly in premarket trading, suggests investors are still digesting the size of the bet relative to how far away the payoff actually is.

Graham (GHM) – New Awards


Thursday, August 06, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Awards. Graham Corporation was awarded two contracts for a combined value of over $43 million. These awards reflect the continued demand the Company is seeing across its defense platforms. The revenue for the contracts will be reflected in the Company’s first and second fiscal year 2027 backlog.

MK48 Mod 7 Heavyweight Torpedo. The first award is a follow-on fourth option year supporting the MK48 Mod 7 Heavyweight Torpedo program, awarded in the first quarter of fiscal 2027, which ended June 30, 2026. The Company will continue to provide alternators and regulators under this option year.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Everyone’s Watching Record Highs. Smart Money Is Watching Oil and Small Caps

Wall Street woke up Wednesday to more of what it’s gotten all week: record highs, falling oil, and a fragile peace headline out of the Middle East. The financial press will lead with the Dow. The more useful question for anyone investing below the mega-cap tier is what cheaper crude actually does to small caps.

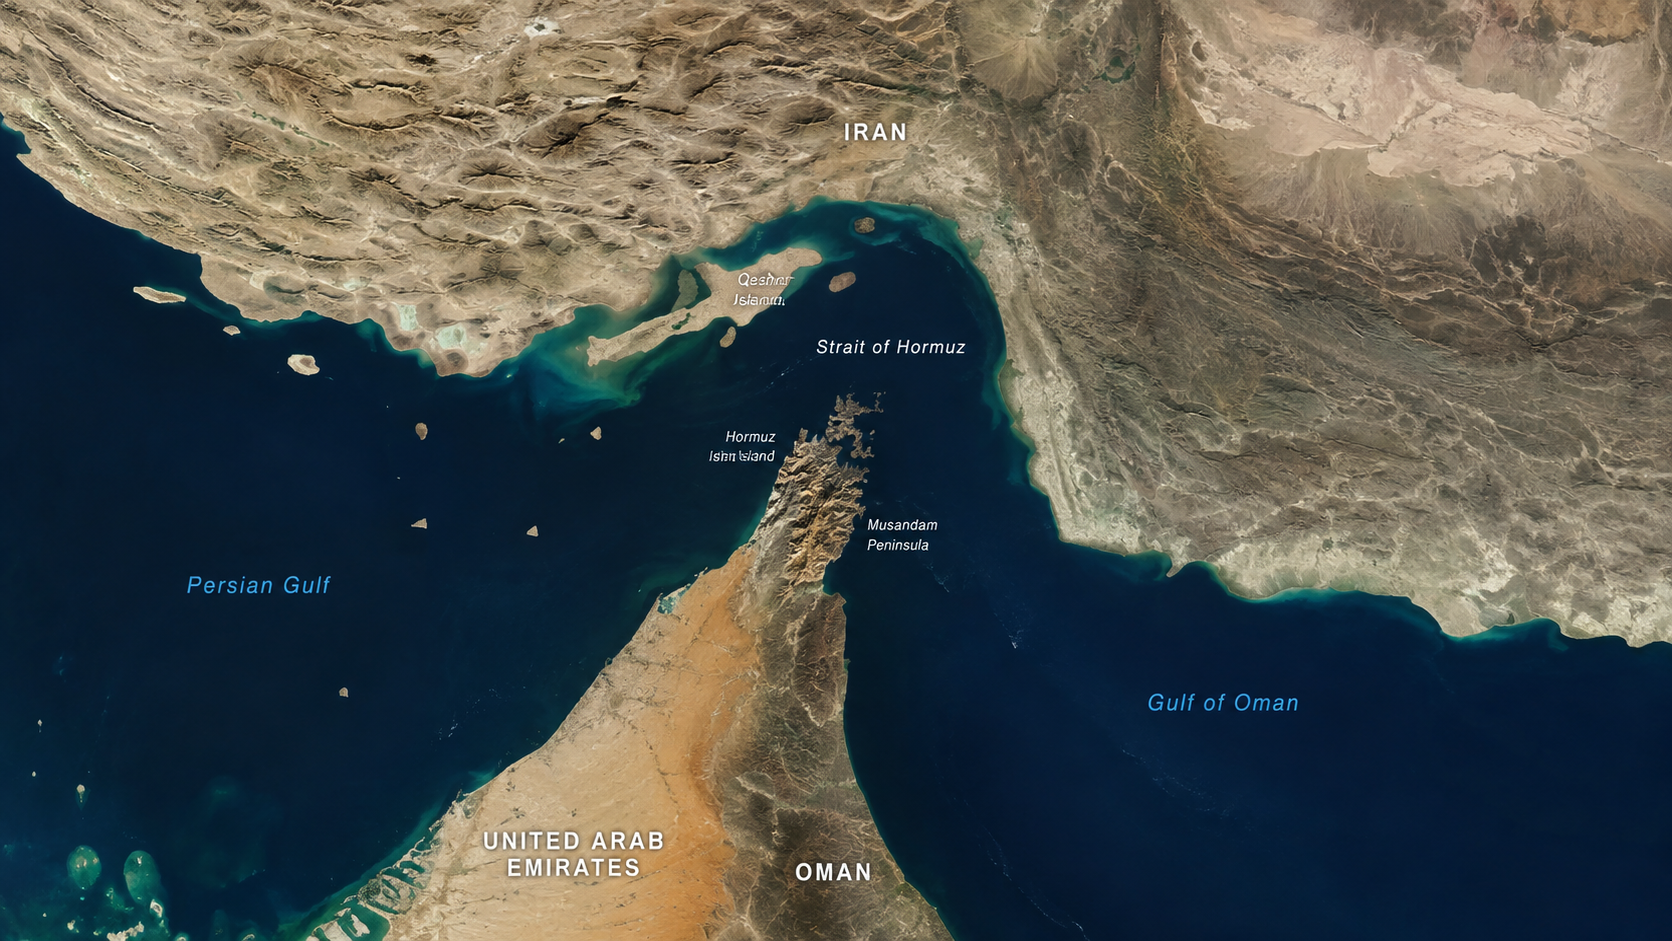
Start with the setup. After a searing rally that pushed the S&P 500 and Dow to record closes Tuesday, US futures steadied Wednesday morning. Oil fell for a third straight session — Brent slipped near $78 and WTI dropped under $75 — on growing hope that the Strait of Hormuz, the chokepoint for roughly a fifth of the world’s oil, could reopen. Qatar said a US–Iran proposal has been drafted, and Iran is reportedly weighing whether to let European navies clear mines from the waterway. Asia cheered it overnight, with South Korea’s KOSPI jumping 4%. Gold pushed higher, the VIX stayed calm, and Russell 2000 futures held firm.

Here’s why small-cap investors should care more than the headline suggests.

Small companies are the most exposed to the price of energy — and the most helped when it falls. They’re overwhelmingly domestic, they run thinner margins, and they lack the global hedging desks and pricing power of the mega-caps. When crude drops, the input-cost relief flows straight to the bottom line of small-cap industrials, transports, manufacturers, and consumer names. Cheaper oil is, in effect, a stealth margin boost for the exact companies that live closest to the edge on the income statement.

There’s a second-order effect that matters even more. Lower oil feeds disinflation, disinflation keeps the Fed’s rate-cut path alive, and small caps are the single most rate-sensitive corner of the market. Pair that with this week’s soft ADP jobs number and you get a macro mix that has historically favored the little guys.

Now the honest other side, because it cuts both ways. Energy is a meaningful slice of the Russell 2000, and cheaper crude squeezes small-cap exploration and production names hard. If your small-cap exposure leans toward oil and gas, this is a headwind, not a tailwind. The net effect depends entirely on what you own.

Step back, though, and the direction of travel is the story. The rally is finally broadening beyond the handful of AI mega-caps that carried it for two years — the Russell is joining the record run, not watching from the sidelines. A de-risking geopolitical backdrop, falling oil, and an easing Fed is the kind of trifecta that tends to reward the laggards. For two years, small caps have been the laggard.

One caveat to keep front and center: this peace is fragile, and a single headline could send oil right back up. Don’t build a thesis on a diplomatic maybe. But watch the setup. While everyone fixates on the Dow printing another record, the more interesting move may be one rung down the market-cap ladder — where the companies most helped by cheap oil and cheap money have been overlooked the longest.

FreightCar America (RAIL) – RAIL Provides Updated Outlook; Webinar at 11:00 AM ET


Tuesday, August 04, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Second Quarter FY 2026 Financial Results. RAIL generated a 2Q FY26 adjusted net loss to common stockholders of $821.0 thousand, or $(0.02) per share, compared to adjusted net income of $3.8 million, or $0.11 per share, during the prior year period. We had projected net income of $350 thousand or $0.01 per share. Gross margin as a percentage of revenue amounted to 5.5% compared to 15.0% in 2Q FY 2025. Revenue and rail car deliveries declined to $113.1 million and 927, compared to $118.6 million and 939 during the prior year period. We had forecast revenue of $112.3 million and deliveries of 923. Adj. EBITDA amounted to $1.2 million compared to $9.3 million in 2Q FY 2025 and our estimate of $5.7 million. We had projected higher gross margin.

Updated FY 2026 Guidance. Management updated its FY 2026 guidance. Railcar deliveries are expected to be in the range of 3,500 to 3,900, revenue in the range of $410 to $460 million, and adj. EBITDA in the range of $36 to $44 million. Prior guidance projected railcar deliveries in the range of 4,000 to 4,500, revenue in the range of $500 to $550 million, and adj. EBITDA in the range of $41 to $50 million. Our current estimates are at the low end of prior guidance. We will update our estimates following today’s investor call.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Supernus and Indivior Are Merging to Build a $2.2 Billion CNS Powerhouse

Supernus Pharmaceuticals (Nasdaq: SUPN) and Indivior Pharmaceuticals (Nasdaq: INDV) announced Monday they have entered into a definitive agreement to combine in a tax-free, all-stock merger of equals, creating a new company focused entirely on central nervous system disease. The combined entity will be named Supernus, Inc., trade on the Nasdaq Global Market under the ticker SUPN, and be headquartered in Rockville, Maryland.

The transaction is expected to generate pro forma net revenue of approximately $2.2 billion and pro forma adjusted EBITDA of $888 million, alongside roughly $125 million in expected annual cost synergies. Closing is targeted for the fourth quarter of 2026, subject to shareholder and regulatory approvals, and the boards of both companies have unanimously approved the deal.

How the Merger Is Structured

The deal terms reveal a genuine merger of equals rather than a straightforward acquisition. Supernus stockholders will receive 1.5401 shares of Indivior common stock for each Supernus share they hold, resulting in Indivior stockholders owning approximately 56.5% of the combined company and Supernus stockholders owning approximately 43.5%, on a fully diluted basis.

Ahead of closing, Indivior stockholders will also receive a one-time special cash dividend totaling $1.0 billion. That dividend will be funded through a combination of existing cash on hand and a $650 million term loan facility committed by Citibank. Jack Khattar, currently President and CEO of Supernus, will lead the combined company in that same role, while Tony Kingsley, currently a member of Indivior’s board, will serve as Board Chair.

Two Complementary CNS Franchises Coming Together

The strategic logic centers on scale and portfolio diversification within neuroscience. Supernus has built its business around psychiatric and neurological conditions, while Indivior has focused heavily on addiction treatment. Together, the combined company will market 11 differentiated commercial medicines spanning psychiatry, neurology, and addiction, a breadth that neither company could offer independently at this scale.

That diversification matters strategically because CNS drug development is notoriously difficult, with high clinical failure rates and long development timelines. A combined commercial portfolio spanning multiple CNS subcategories reduces the company’s dependence on any single therapeutic area or product cycle, while giving it a broader sales and marketing infrastructure to support both existing products and future pipeline candidates.

A Financially Disciplined Combination

Alongside the merger announcement, Supernus also raised its fiscal 2026 sales guidance, moving its prior range of $1.215 billion to $1.285 billion up to a new range of $1.295 billion to $1.365 billion, above the consensus estimate of $1.245 billion, a signal of underlying business strength independent of the transaction itself.

The combined company is projected to carry net debt of roughly $878 million against its earnings base, translating to a net leverage ratio below 1 times EBITDA. That conservative balance sheet is a notable feature of the deal, giving the newly formed Supernus, Inc. meaningful financial flexibility to continue investing in its internal pipeline while also pursuing additional strategic acquisitions once the merger closes.

What It Means for Investors Tracking Specialty Pharma

For investors following small and mid cap pharmaceutical companies, this deal illustrates a consolidation pattern that continues to play out across specialty therapeutic areas. Two mid-sized companies, each strong in a narrower CNS niche, are combining to build the kind of commercial scale, balance sheet strength, and portfolio diversification that increasingly determines competitive positioning in specialty pharma, without either company needing to be acquired outright by a larger strategic buyer. The broader CNS space remains one of the more active areas of biopharmaceutical development, with clinical-stage companies like NeuroSense Therapeutics continuing to advance novel approaches to neurological disease even as larger, more established players consolidate around commercial scale.

Amazon Surged 10% After AWS Posted Its Best Quarter in Years. The Company Is Raising Its AI Spending to $220 Billion

Amazon shares jumped 10% in premarket trading Friday after the company topped second quarter expectations, driven by an acceleration in Amazon Web Services that one analyst covering the stock described as a genuine home run for the company. The results stood in sharp contrast to the mixed reception several other mega cap earnings reports have received this season.

AWS generated $42.2 billion in second quarter revenue, up 36.7% year over year, with strength across both its core cloud business and its expanding AI services. Amazon disclosed that its AI and custom chip businesses have each individually surpassed a $25 billion annualized revenue run rate, a figure that underscores just how quickly the AI infrastructure side of the business has scaled. The company’s custom chip business is now growing at a triple-digit year-over-year rate.

A Record Quarter of Growth

CEO Andy Jassy told investors on the earnings call that AWS added over $4.6 billion in revenue quarter over quarter, roughly 80% more than the company’s largest previous quarterly increase. The segment’s backlog now stands at $496 billion, growing at a triple-digit rate year over year. Jassy noted that customers continue choosing AWS for the breadth of its capabilities, particularly the ability to run AI inference near existing applications and data, a capability AWS offers more extensively than its competitors.

AWS is now running at approximately a $170 billion annual revenue run rate, more than four times larger than it was in 2019, illustrating the scale of growth the cloud division has achieved over the past several years.

The Capex Number That Matters

Heading into the report, Wall Street had been closely watching two things: AWS growth and capital expenditures tied to AI infrastructure. Amazon delivered on both fronts, but not in the direction some investors might have expected given the market’s recent skepticism toward AI spending. The company raised its full-year capital expenditure guidance to approximately $220 billion, up from its prior guidance of roughly $200 billion.

In a market environment where companies like Oracle and Tesla have seen their stocks punished for similarly aggressive AI-related spending increases, Amazon’s reception was notably different. Wall Street appeared willing to look past the higher spending given AWS’s accelerating growth and expanding operating margins, a combination that suggests the capital is translating into measurable revenue rather than simply funding future capacity that has yet to prove out. Jassy indicated that demand for AI and cloud computing continues to outstrip available server capacity, with planned 2027 expansion already largely booked into 2028.

What It Means for Smaller Companies in the AI Supply Chain

For investors tracking the broader technology and infrastructure ecosystem, Amazon’s report offers a useful counterpoint to the AI spending anxiety that has weighed on chip and infrastructure names throughout the summer. When a hyperscaler raises capital expenditure guidance and the market responds positively rather than punitively, it signals renewed confidence that AI infrastructure demand remains durable, at least when that spending is paired with visible, accelerating revenue growth like AWS delivered this quarter.

That distinction matters considerably for smaller companies supplying components, power infrastructure, cooling systems, and specialized hardware into the broader AI buildout. A $220 billion capital expenditure plan does not get executed through Amazon’s own engineering teams alone. It flows through an extensive supplier base, and this quarter’s results suggest that demand signal remains firmly intact even as some large cap names in the space have faced renewed investor scrutiny in recent weeks.

Release – Summit Midstream Corporation Schedules Second Quarter 2026 Earnings Call

Summit Midstream Partners Logo. (PRNewsFoto/Summit Midstream Partners)

Research News and Market Data on SMC

PDF Version

HOUSTON, July 30, 2026 /PRNewswire/ — Summit Midstream Corporation (NYSE: SMC) (“Summit”, “SMC” or the “Company”) announced today that it will report operating and financial results for the second quarter of 2026 on Monday, August 10, 2026, after the close of trading on the New York Stock Exchange.

Second Quarter 2026 Earnings Call

SMC will host a conference call at 10:00 a.m. Eastern on August 11, 2026, to discuss its quarterly operating and financial results. The call can be accessed via teleconference at: Q2 2026 Summit Midstream Corporation Earnings Conference Call (https://register-conf.media-server.com/register/BI8cebf785fce846a9bb80ae80660d3cbc). Once registration is completed, participants will receive a dial-in number along with a personalized PIN to access the call. While not required, it is recommended that participants join 10 minutes prior to the event start. The conference call, live webcast and archive of the call can be accessed through the Investors section of SMC’s website at www.summitmidstream.com.

About Summit Midstream Corporation

SMC is a value-driven corporation focused on developing, owning and operating midstream energy infrastructure assets that are strategically located in the core producing areas of unconventional resource basins, primarily shale formations, in the continental United States. SMC provides natural gas, crude oil and produced water gathering, processing and transportation services pursuant to primarily long-term, fee-based agreements with customers and counterparties in five unconventional resource basins: (i) the Williston Basin, which includes the Bakken and Three Forks shale formations in North Dakota; (ii) the Denver-Julesburg Basin, which includes the Niobrara and Codell shale formations in Colorado and Wyoming; (iii) the Fort Worth Basin, which includes the Barnett Shale formation in Texas; (iv) the Arkoma Basin, which includes the Woodford and Caney shale formations in Oklahoma; and (v) the Piceance Basin, which includes the Mesaverde formation as well as the Mancos and Niobrara shale formations in Colorado. SMC has an equity method investment in Double E Pipeline, LLC, which provides interstate natural gas transportation service from multiple receipt points in the Delaware Basin to various delivery points in and around the Waha Hub in Texas. SMC is headquartered in Houston, Texas.

Forward-Looking Statements

This press release includes certain statements concerning expectations for the future that are forward-looking within the meaning of the federal securities laws. Forward-looking statements include, without limitation, any statement that may project, indicate or imply future results, events, performance or achievements and may contain the words “expect,” “intend,” “plan,” “anticipate,” “estimate,” “believe,” “will be,” “will continue,” “will likely result,” and similar expressions, or future conditional verbs such as “may,” “will,” “should,” “would” and “could.” In addition, any statement concerning future financial performance (including future revenues, earnings or growth rates), payment of dividends on any series of stock, ongoing business strategies and possible actions taken by SMC or its subsidiaries are also forward-looking statements. Forward-looking statements also contain known and unknown risks and uncertainties (many of which are difficult to predict and beyond management’s control) that may cause SMC’s actual results in future periods to differ materially from anticipated or projected results. An extensive list of specific material risks and uncertainties affecting SMC is contained in its 2025 Annual Report on Form 10-K filed with the Securities and Exchange Commission (the “SEC”) on March 16, 2026, as amended and updated from time to time. Any forward-looking statements in this press release are made as of the date of this press release and SMC undertakes no obligation to update or revise any forward-looking statements to reflect new information or events.

Cision View original content to download multimedia:https://www.prnewswire.com/news-releases/summit-midstream-corporation-schedules-second-quarter-2026-earnings-call-302839502.html

SOURCE Summit Midstream Corporation

[email protected]

ICE Just Paid $6 Billion to Fix One of Finance’s Last Analog Corners

Intercontinental Exchange announced this morning it will acquire MarketAxess Holdings for $167 per share in cash, a 33% premium that values the fixed income trading platform at roughly $6 billion in equity value and $5.7 billion in total enterprise value. It’s a deal aimed squarely at a problem that has persisted through decades of financial market modernization: the bond market still trades like it’s 1995.

That is not an exaggeration. The global fixed income market carries an estimated $145.1 trillion in outstanding debt, dwarfing the equity markets in size, yet bond trading remains disproportionately manual, conducted bilaterally over phone calls and instant messages between dealers, with wide bid-ask spreads and limited price transparency. Stocks solved this problem years ago through centralized, electronic exchanges. Bonds never fully did, and that gap is exactly what ICE is paying to close.

MarketAxess brings the piece ICE has been missing. The platform connects roughly 2,100 institutional investors and broker-dealers across more than 90 countries, enabling electronic trading in corporate bonds, municipal debt, emerging market bonds, and U.S. Treasuries. ICE, meanwhile, has spent years building out the surrounding infrastructure, a retail and wealth-focused bond trading franchise, fixed income data and analytics, and a global index business, without ever owning the institutional execution network to tie it all together. ICE Chair and CEO Jeff Sprecher framed the deal as a continuation of a strategy the company has run for two decades: find the largest, least efficient corners of finance and rebuild them with better technology, the same playbook ICE has already applied to energy markets, credit default swaps, and mortgage technology.

The financial structure of the deal is worth noting for what it signals about ICE’s confidence in the combination. The transaction is being financed entirely in cash through newly issued debt, a mix of bonds, a term loan, and commercial paper, and ICE is simultaneously increasing its quarterly share repurchase baseline to $400 million from $350 million rather than pausing buybacks to conserve cash. The company expects the deal to be accretive to adjusted earnings per share in its first full year, with $100 million in annual run-rate cost synergies expected within three years. ICE’s gross leverage will begin at 3.4 times pro forma EBITDA, with a target of returning to 3.0 times or below within 18 to 24 months, a timeline that suggests management views the combined business as strongly cash generative even while absorbing new debt.

For a deal of this size in market infrastructure, the strategic logic is straightforward enough that it barely needs translation. Consolidated liquidity pools tend to produce tighter pricing and lower transaction costs for everyone trading on them, which is the same network effect that has driven exchange consolidation across asset classes for years. MarketAxess CEO Chris Concannon pointed to the complementary nature of the two businesses, MarketAxess brings the institutional trading network, ICE brings retail protocols, data, and connectivity, as the combination’s core rationale.

The deal still requires MarketAxess shareholder approval and customary regulatory clearances, with closing targeted for the first half of 2027. Boards at both companies have already approved it unanimously.

Grant Thornton Just Paid a 54% Premium to Buy CBIZ. It Is the Biggest Accounting Deal in 25 Years

Grant Thornton Advisors announced Wednesday it has entered into a definitive agreement to acquire CBIZ (NYSE: CBZ), a professional services firm listed on the New York Stock Exchange, in an all-cash transaction with an enterprise value of $5 billion. Under the terms of the deal, CBIZ shareholders will receive $55.00 per share, representing a 54% premium to the company’s 30-day volume-weighted average price and roughly an 18% premium to CBIZ’s most recent closing price. The transaction is described as the largest of its kind in more than 25 years.

The deal is backed by New Mountain Capital, which previously led a May 2024 investment in Grant Thornton Advisors and has now committed $5.2 billion in financing to support this acquisition as well. CBIZ’s board unanimously approved the transaction and is recommending shareholders vote in favor of it. Closing is targeted for the fourth quarter of 2026, subject to shareholder and regulatory approval.

A Genuine Industry Heavyweight

The combination reshapes the upper tier of the professional services industry. CBIZ currently ranks No. 8 on Accounting Today’s 2026 Top 100 Firms list with $2.8 billion in revenue, while Grant Thornton sits at No. 9 with $2.5 billion. Once combined, the merged firm is expected to become the fifth-largest professional services provider in the United States, generating more than $5 billion in domestic revenue and nearly $7.5 billion globally, operating across more than 20 countries with a workforce exceeding 34,500 professionals.

CBIZ President and CEO Jerry Grisko called it a historic combination with a strong cultural and strategic fit, framing the deal as one that creates new opportunity for employees while delivering significant value to shareholders.

What the Deal Is Actually Built Around

The stated strategic rationale centers on three areas: expanding Grant Thornton’s AI-enabled service delivery capabilities, growing its multinational footprint, and deepening industry specialization across both firms’ combined client base. As part of the restructuring, CBIZ’s Benefits and Insurance Services segment will be spun off as an independent, growth-oriented company, a signal that the combined entity intends to sharpen its focus on core advisory, tax, and accounting services rather than retain every existing business line.

The deal includes a go-shop period running through August 27, 2026, during which CBIZ may solicit superior competing proposals, alongside standard no-shop and termination provisions once that window closes. CBIZ’s board also adopted change-in-control severance, retention, and transaction bonus programs the same day the deal was announced, a customary step designed to retain key personnel through the transition.

The Numbers Behind the Timing

The announcement landed alongside CBIZ’s own second quarter results. For the first half of 2026, the company reported revenue of $1.53 billion, up modestly year over year, with net income rising 4.1% to $171.4 million and adjusted diluted earnings per share increasing 3.6% to $3.44. CBIZ also repurchased approximately 2.5 million shares for roughly $70 million during the period, while reducing net leverage to 3.4 times, down from the prior year.

Why This Matters Beyond Accounting

For investors tracking consolidation trends across professional and business services, this deal reinforces a pattern playing out broadly this year. Private equity-backed platforms are aggressively pursuing scale in fragmented service industries, betting that combining AI capability, specialized talent, and multinational reach creates durable competitive advantages that smaller, standalone firms increasingly struggle to match on their own.

Apple Passed Nvidia as the World’s Most Valuable Company. Spending Less on AI Just Became a Winning Strategy

Apple reclaimed the title of the world’s most valuable public company Monday, overtaking Nvidia as its stock pushed toward a record high close. Apple’s market capitalization reached approximately $4.94 trillion, edging past Nvidia’s $4.83 trillion. The shift caps a remarkable turnaround for a company that spent much of the past two years being criticized for lagging behind its peers on artificial intelligence investment.

Apple shares have climbed more than 22% year to date, outperforming every other member of the so-called Magnificent Seven. The reason is almost the inverse of what drove the group’s dominance over the past two years. Investors are increasingly rewarding Apple precisely because it has not spent aggressively on AI infrastructure, treating capital discipline as a genuine strength rather than a competitive weakness.

The Capex Divide Reshaping Big Tech

Data tracked through Yahoo Finance’s AlphaSpace shows Apple’s capital expenditures have actually declined over the past three quarters, a striking contrast to nearly every other major technology company racing to build AI infrastructure. That restraint stands in sharp relief against Alphabet, which raised its capital spending outlook last week to fund its AI infrastructure buildout, and Tesla, which increased spending to support its robotaxi and robotics ambitions. Shares of both companies fell following their respective earnings reports. Alphabet is up only about 3% year to date, and Tesla has tumbled roughly 30% over the same period.

The market’s message has become increasingly clear this earnings season. Companies spending aggressively on AI capacity are being asked hard questions about return on that investment, while companies demonstrating they can capture AI-driven demand without ballooning capital expenditures are being rewarded with premium valuations.

A Pivotal Week Ahead

Apple reports earnings Thursday after the closing bell, and the report carries added significance beyond the usual quarterly scrutiny. Investors will be watching closely for signs the company can scale its Apple Intelligence features across its device lineup without a meaningful increase in capital expenditures or pressure on operating margins. If Apple can demonstrate that its AI strategy works within its existing capital-light framework, it would validate the market’s current thesis in dramatic fashion.

The timing carries additional weight. Thursday will mark Tim Cook’s final earnings call as CEO before he steps down September 1 to become executive chairman, with John Ternus, a longtime hardware engineering veteran at Apple, taking over as chief executive. Microsoft, Amazon, and Meta all report later this week as well, and all three are expected to announce further increases in AI-related spending, setting up a direct contrast with Apple’s approach in real time.

What This Means for the Broader Market

For investors tracking the AI infrastructure ecosystem, the leadership change at the top of the market matters beyond Apple and Nvidia individually. It reinforces a theme that has run through this entire earnings season: the market is no longer rewarding AI spending simply because it is AI spending. It is scrutinizing whether that capital is translating into visible product outcomes and sustainable margins.

That distinction has real implications down the market cap spectrum. Smaller companies supplying components, software, and infrastructure into the AI buildout are increasingly being evaluated on the same terms, whether their growth is funded responsibly or whether it depends on the kind of unchecked capital expenditure that has weighed on stocks like Alphabet and Tesla this earnings season. Apple’s ascent back to the top is, in part, the market rewarding exactly the kind of capital discipline that investors are now demanding across the board.