Euroseas Ltd. was formed on May 5, 2005 under the laws of the Republic of the Marshall Islands to consolidate the ship owning interests of the Pittas family of Athens, Greece, which has been in the shipping business over the past 140 years. Euroseas trades on the NASDAQ Capital Market under the ticker ESEA. Euroseas operates in the container shipping market. Euroseas’ operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company, which is responsible for the day-to-day commercial and technical management and operations of the vessels. Euroseas employs its vessels on spot and period charters and through pool arrangements.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
New time charter for the EM Spetses. Euroseas Ltd. announced a new time charter for its 1,740 twenty-foot equivalent feeder containership, EM Spetses, for a minimum period of 22 to a maximum period of 24 months, at the option of the charterer, at a gross daily rate of $21,500. The new charter will commence on April 12, 2026, in direct continuation of its present charter, and represents a daily increase of over $3,000 compared to the vessel’s current rate.
Incremental EBITDA with Expanded Coverage. The charter is expected to generate approximately $8.9 million in EBITDA over the minimum term and increase Euroseas’ charter coverage to approximately 87% in 2026, 71% in 2027, and 41% in 2028. The higher rate on the new time charter reflects a tight container market with limited vessel availability. Demand in the feeder segment remains strong as operators secure vessels to meet their requirements.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
EuroDry Ltd. was formed on January 8, 2018 under the laws of the Republic of the Marshall Islands to consolidate the drybulk fleet of Euroseas Ltd. into a separate listed public company. EuroDry was spun-off from Euroseas Ltd. on May 30, 2018; it trades on the NASDAQ Capital Market under the ticker EDRY. EuroDry operates in the dry cargo, drybulk shipping market. EuroDry’s operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company and Eurobulk (Far East) Ltd. Inc., which are responsible for the day- to-day commercial and technical management and operations of the vessels. EuroDry employs its vessels on spot and period charters and under pool agreements.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Increasing FY 2026 estimates. We have increased our FY 2026 revenue, adjusted EBITDA, and adjusted EPS estimates to $60.8 million, $25.5 million, and $2.82, respectively, from $57.3 million, $22.4 million, and $1.46. The upward revisions are driven by higher expected vessel earnings, with our forecast average TCE rate rising to $14,743 from $13,873 previously.
Eurodry’s sweet spot. Eurodry owns and operates vessels in the middle of the size range of dry bulk carriers, or 50,000 to 85,000 dead weight tons (dwt), which present the most flexible employment opportunities. EDRY’s fleet consists of 11 vessels with a total carrying capacity of 766,420 dwt. With two Ultramax vessels of 63,500 dwt each under construction and scheduled for delivery in the second and third quarters of 2027, the total carrying capacity will increase to 893,000 dwt. Growth will be driven by the charter rate environment, coupled with fleet growth. While EDRY continues to renew and modernize its fleet, it expects to acquire and consolidate smaller owners.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
ATHENS, Greece, Feb. 11, 2026 (GLOBE NEWSWIRE) — Euroseas Ltd. (NASDAQ: ESEA, the “Company” or “Euroseas”), an owner and operator of container carrier vessels and provider of seaborne transportation for containerized cargoes, announced today a new time charter contract for its 2007-built 1,740 teu feeder containership, EM Spetses, for a minimum period of 22 to a maximum period of 24 months, at the option of the charterer, at a gross daily rate of $21,500. The new charter period will commence on April 12, 2026, in direct continuation of its present charter, and represents a daily increase of over $3,000 over the vessel’s current rate.
Aristides Pittas, Chairman and CEO of Euroseas, commented: “We are very pleased to that we have extended the time charter contract for our 2007-built EM Spetses with a top-class charterer, in direct continuation of its present charter, for 22-24 months at a profitable rate of $21,500. This fixture highlights that despite the upcoming Lunar New Year holidays, activity across the feeder segment remains firm, as operators move to secure their requirements amid a tight container chartering market with very limited tonnage availability. The charter is expected to generate about $8.9 million of EBITDA over the minimum contracted period and increases our charter coverage for 2026, 2027, and 2028 to about 87%, 71% and 41% respectively.”
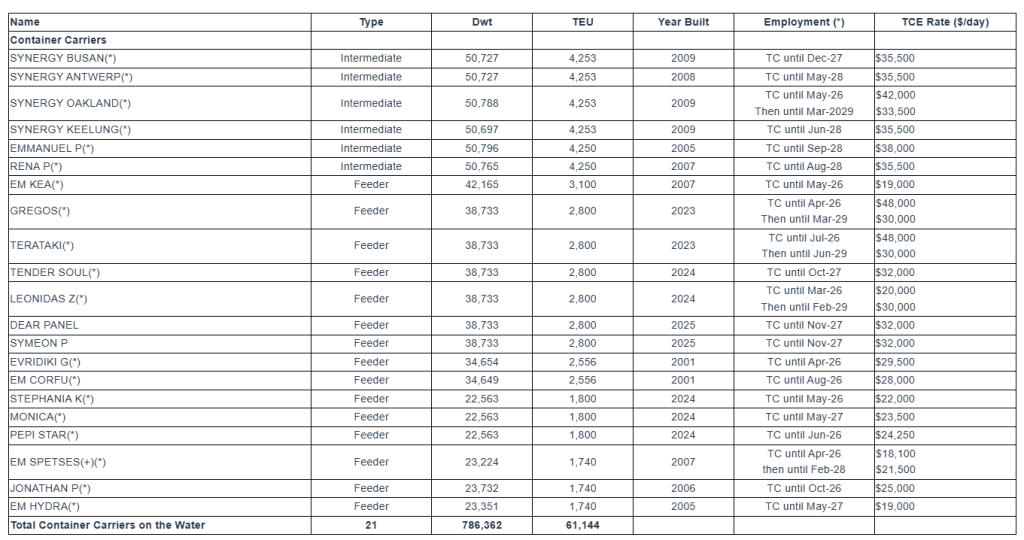
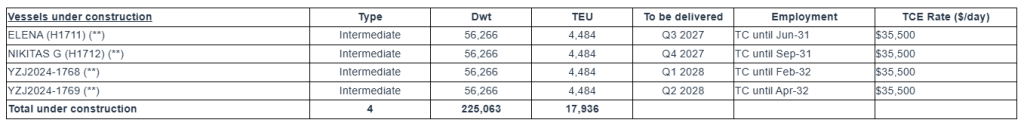
Fleet Profile: The Euroseas Ltd. fleet profile is currently as follows:
Notes: (*)TC denotes time charter. Charter duration indicates the earliest redelivery date; all dates listed are the earliest redelivery dates under each TC unless the contract rate is lower than the current market rate in which cases the latest redelivery date is assumed; vessels with the latest redelivery date shown are marked by (+). (**) The charterer has the option until Nov-2026 to extend the charters by one year with the rate for the five-year period becoming $32,500/day.
About Euroseas Ltd.
Euroseas Ltd. was formed on May 5, 2005 under the laws of the Republic of the Marshall Islands to consolidate the ship owning interests of the Pittas family of Athens, Greece, which has been in the shipping business over the past 150 years. Euroseas trades on the NASDAQ Capital Market under the ticker ESEA.
Euroseas operates in the container shipping market. Euroseas’ operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company, which is responsible for the day-to-day commercial and technical management and operations of the vessels. Euroseas employs its vessels on spot and period charters and through pool arrangements.
The Company has a fleet of 21 vessels, including 15 Feeder containerships and 6 Intermediate containerships with a cargo capacity of 61,144 teu. After the delivery of four intermediate containership newbuildings in 2027 and 2028, respectively, Euroseas’ fleet will consist of 25 vessels with a total carrying capacity of 79,080 teu.
Forward Looking Statement
This press release contains forward-looking statements (as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended) concerning future events and the Company’s growth strategy and measures to implement such strategy; including expected vessel acquisitions and entering into further time charters. Words such as “expects,” “intends,” “plans,” “believes,” “anticipates,” “hopes,” “estimates,” and variations of such words and similar expressions are intended to identify forward-looking statements. Although the Company believes that the expectations reflected in such forward-looking statements are reasonable, no assurance can be given that such expectations will prove to have been correct. These statements involve known and unknown risks and are based upon a number of assumptions and estimates that are inherently subject to significant uncertainties and contingencies, many of which are beyond the control of the Company. Actual results may differ materially from those expressed or implied by such forward-looking statements. Factors that could cause actual results to differ materially include, but are not limited to changes in the demand for containerships, competitive factors in the market in which the Company operates; risks associated with operations outside the United States; and other factors listed from time to time in the Company’s filings with the Securities and Exchange Commission. The Company expressly disclaims any obligations or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in the Company’s expectations with respect thereto or any change in events, conditions or circumstances on which any statement is based.
Seanergy Maritime Holdings Corp. is a prominent pure-play Capesize shipping company listed in the U.S. capital markets. Seanergy provides marine dry bulk transportation services through a modern fleet of Capesize vessels. The Company’s operating fleet consists of 18 vessels (1 Newcastlemax and 17 Capesize) with an average age of approximately 13.4 years and an aggregate cargo carrying capacity of approximately 3,236,212 dwt. Upon completion of the delivery of the previously announced Capesize vessel acquisition, the Company’s operating fleet will consist of 19 vessels (1 Newcastlemax and 18 Capesize) with an aggregate cargo carrying capacity of approximately 3,417,608 dwt. The Company is incorporated in the Marshall Islands and has executive offices in Glyfada, Greece. The Company’s common shares trade on the Nasdaq Capital Market under the symbol “SHIP”.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Increasing Q4 and FY 2025 estimates. We have increased our FY 2025 revenue, adjusted EBITDA, and adjusted earnings per share (EPS) estimates to $157.0 million, $81.0 million, and $1.14, respectively, from $153.2 million, $77.9 million, and $1.07. Our full year estimates reflect higher fourth quarter revenue, adjusted EBITDA, and EPS of $48.3 million, $28.2 million, and $0.56, respectively, compared to our previous estimates of $44.5 million, $25.0 million, and $0.49. We are now forecasting fourth quarter and full year average time charter equivalent rates of $26,000 per day and $20,672 per day, versus prior forecasts of $23,900 and $20,147. We forecast fourth quarter and full year operating days of 1,800 and 7,163, respectively, compared to our prior estimates of 1,780 and 7,143.
Raising FY 2026 estimates. We have also increased our FY 2026 revenue, adjusted EBITDA, and adjusted EBITDA estimates to $176.2 million, $96.7 million, and $1.70, respectively, from $165.2 million, $89.1 million, and $1.44. We now forecast an average TCE rate of $24,063 compared to our previous estimate of $22,238.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Patrick McCann, CFA, Research Analyst, Noble Capital Markets, Inc.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Pricing announced for upcoming bond issuance. Sky Harbour priced $150 million of Series 2026 private activity tax-exempt bonds at par to yield 6.0%, with a mandatory tender on January 1, 2031, and an expected closing on or about February 12, 2026. The transaction is another example of the company’s tax-advantaged financing toolkit and deepens its access to institutional municipal investors.
Deal upsized on strong investor demand. The transaction was initially marketed at $100 million but was upsized to $150 million after receiving approximately $450 million of orders from 18 institutional investors. In our view, the oversubscription supports growing investor comfort in the asset base, the cash flow ramp, and the repeatable development playbook.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
VSE Corporation’s agreement to acquire Precision Aviation Group (PAG) for approximately $2.025 billion marks a transformational moment—not just for the company, but for the broader aviation aftermarket industry. The deal positions VSE as a scaled, pure-play aviation aftermarket leader with global reach, expanded technical capabilities, and a clearer path to sustained margin expansion.
Under the terms of the agreement, VSE will acquire PAG from GenNx360 Capital Partners for $1.75 billion in cash and roughly $275 million in equity, with the potential for an additional $125 million earnout tied to PAG’s 2026 performance. Including expected synergies, the transaction values PAG at about 13.5x expected 2025 adjusted EBITDA—an assertive but strategic multiple in a high-margin, mission-critical segment.
Founded in 1996 and headquartered in Atlanta, PAG has built a best-in-class platform across aviation maintenance, repair, and overhaul (MRO), parts distribution, and proprietary repair solutions. With 29 locations worldwide, over 1,000 employees, and more than 175,000 repairs completed annually, PAG serves commercial aviation, business and general aviation, rotorcraft, and defense customers. PAG expects to generate approximately $615 million in adjusted revenue in 2025.
The strategic logic is clear. By combining PAG with VSE’s existing aviation operations, the company expects to increase pro forma aviation revenue by roughly 50% in 2025 and significantly deepen its exposure to higher-margin aftermarket services. The combined entity is expected to operate around 60 locations globally, enhancing customer proximity, turnaround times, and aircraft-on-ground support—key differentiators in a sector where reliability and speed are paramount.
Margin expansion is central to the deal thesis. PAG’s adjusted EBITDA margin is expected to be immediately accretive, and VSE believes the combined company can exceed a 20% consolidated adjusted EBITDA margin over the next few years. This improvement is expected to be driven by increased proprietary repair content, operational leverage, procurement efficiencies, and more than $15 million in anticipated annual synergies from cross-selling, insourcing, and network optimization.
Beyond scale, the acquisition meaningfully broadens VSE’s technical capabilities. PAG’s four business units—component services, engine services, avionics, and proprietary solutions—complement VSE’s existing offerings and enhance its ability to extend asset life and reduce total cost of ownership for customers. This expanded portfolio strengthens VSE’s positioning as a mission-critical partner across multiple aviation end markets, including defense, which adds resilience through economic cycles.
Management commentary underscores the long-term ambition. VSE CEO John Cuomo described the acquisition as a “pivotal moment” in building a differentiated, higher-margin aviation aftermarket platform. PAG CEO David Mast emphasized the cultural and strategic alignment between the two organizations, while GenNx360 signaled confidence through a substantial equity rollover.
Financially, VSE enters the transaction from a position of strength. Preliminary 2025 results point to revenue of approximately $1.1 billion and adjusted EBITDA approaching $180 million, with positive free cash flow for the full year. The cash portion of the deal is supported by a fully committed bridge facility, and the transaction is expected to close in the second quarter of 2026, pending regulatory approvals.
Taken together, the VSE–PAG combination reflects a broader industry trend: consolidation around scaled platforms with proprietary capabilities, predictable cash flows, and high barriers to entry. If executed as planned, this deal could redefine VSE’s growth trajectory—and set a new benchmark for value creation in the aviation aftermarket.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Updated Estimates. We tweaked our fourth quarter 2025 estimates after speaking with management. The changes do not impact our belief in the investment case for Commercial Vehicle Group. We maintained our revenue estimate at $146 million. Gross margin has been lowered to 10.3% from 11% previously. We are now estimating an adjusted net loss of $5 million, or $0.15 per share. Adjusted EBITDA is now $2.8 million. For the full year, we are at revenue of $640.2 million and adjusted EBITDA of $18.3 million.
Green Shoots? Recent data from FTR and ACT could indicate an improved Class 8 truck environment in 2026, although we would need to see multiple months of positive developments before jumping in with both feet. According to FTR, December Class 8 truck orders of 42,200 units were the highest level since October 2022. Meanwhile, ACT raised its expectation for Class 8 production in 2026 to 246,000 units, up from a prior 205,000, and nearly flat with 2025.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
BYD Co., the Chinese electric vehicle giant, has hit a major milestone, surpassing Tesla Inc. to claim the title of the world’s largest electric vehicle maker in 2025. The achievement comes amid a challenging backdrop for China’s auto market, with heightened domestic competition and shifting government incentives.
The Shenzhen-based company delivered a total of 4.6 million vehicles last year, representing a 7.7% increase from 2024, and meeting the full-year sales target it set in September. Nearly half of these vehicles—2.26 million—were fully electric, with the remainder comprising plug-in hybrid models. In contrast, Tesla’s full-year deliveries are projected to reach approximately 1.66 million vehicles, marking its second consecutive annual decline. The US automaker’s fourth-quarter shipments alone were down 11% from a year earlier.
BYD’s milestone was reflected in market performance, with its Hong Kong-listed shares rising as much as 2.3% on the first trading day of 2026. Despite this growth, the company faces significant pressure in the year ahead. China’s reduction of certain EV purchase incentives and an influx of new domestic models have intensified competition. Geely Automobile Holdings Ltd. and Xiaomi Corp., among others, have launched new vehicles that are capturing consumer attention, making the domestic landscape more challenging.
Chief Executive Officer Wang Chuanfu acknowledged that BYD’s technological lead over competitors has narrowed, affecting domestic sales. However, he expressed confidence in the company’s 120,000-strong engineering team and hinted at upcoming breakthroughs that could help BYD regain an edge.
International markets have emerged as a bright spot for BYD. Overseas deliveries reached 1.05 million units in 2025, surpassing expectations and helping offset domestic softness. The company has set ambitious targets for 2026, aiming to sell between 1.5 million and 1.6 million vehicles outside China. Analysts from Deutsche Bank and Morgan Stanley forecast that new product launches and a refreshed technology platform could further strengthen BYD’s global competitiveness.
Nevertheless, the company faces financial and regulatory hurdles. BYD posted back-to-back quarterly profit declines in 2025 and has been at the center of China’s efforts to curb aggressive EV discounting. This regulatory scrutiny may accelerate consolidation within the industry and reshape the competitive hierarchy.
Tesla, meanwhile, is grappling with its own set of challenges. Production line adjustments for the redesigned Model Y slowed early 2025 deliveries, while the US elimination of federal EV purchase incentives is expected to weigh on demand. Additionally, CEO Elon Musk’s controversial political profile has reportedly deterred some buyers, further complicating the company’s outlook.
Despite these headwinds, BYD appears poised to maintain its lead. Analyst estimates suggest total sales could reach 5.3 million units in 2026, allowing the company to solidify its position as the top global EV maker. With growing overseas momentum, strategic product launches, and continued investment in technology, BYD is not just overtaking Tesla—it is reshaping the global electric vehicle landscape.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Acquisition of Carly Railcar Components. FreightCar America acquired Carly Railcar Components, LLC (CRC), a family-owned railcar component distributor founded in 1995. Carly operates warehouse facilities in Orange, Texas, and Irwin, Pennsylvania, supplying AAR M-1003 approved original equipment manufacturer (OEM) railcar components to repair shops, railroads, private car owners, and industrial customers. The company also operates a core exchange program for reconditioned parts. The purchase price was not disclosed.
Increased Scale and a Complementary Product Portfolio. The transaction strengthens RAIL’s aftermarket distribution business with a focus on running repair components, those parts that are frequently replaced to keep the railcar operational. This product category complements RAIL’s core offerings and product mix. RAIL customers will benefit from a larger catalog of ready-to-ship railcar components. The acquisition is expected to be immediately accretive, and RAIL expects to realize meaningful operational improvements across the combined network, including increased purchasing power with OEMs.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
CHICAGO, Dec. 22, 2025 (GLOBE NEWSWIRE) — FreightCar America, Inc. (NASDAQ: RAIL) (“FreightCar America” or the “Company”), a diversified manufacturer and supplier of railroad freight cars, railcar parts and components, today announced that it has completed the acquisition of Carly Railcar Components, LLC (“CRC”), a family-owned, leading distributor of railcar components.
The acquisition strengthens FreightCar America’s aftermarket distribution business with a focus on running-repair components, a frequently replaced and highly recurring product category that complements the Company’s core offerings and product mix. Through the acquisition, the Company’s customers will benefit from reduced lead times and a larger catalog of ready-to-ship railcar components.
“Carly Railcar Components brings highly complementary capabilities that strengthen our position in the railcar aftermarket. CRC’s long-standing presence in component distribution and its established regional footprint, including a Houston-area facility in Orange, Texas, enhances our ability to serve customers with greater speed, reliability and product availability. This acquisition advances our strategic initiatives to build complementary capabilities that deliver enhanced value to our customers,” said Nicholas Randall, President and Chief Executive Officer of FreightCar America.
“We are excited to welcome Carly Railcar Components to the FreightCar America platform,” said Mike Riordan, Vice President, Chief Financial Officer & Treasurer of FreightCar America. “CRC has built a strong business with deep customer relationships. Combining their capabilities with our commercial and supply chain excellence will allow us to deliver exceptional value to our customers, while at the same time allowing us to realize meaningful operational improvements across the combined network. This acquisition is consistent with our disciplined capital allocation framework and is expected to be immediately accretive to FreightCar America as we scale our aftermarket business.”
About Carly Railcar Components
Founded in 1995, Carly Railcar Components distributes OEM railcar components and operates a core-exchange program for reconditioned parts. The company serves repair shops, railroads, private car owners and other industrial customers. CRC is one of the major component distributors in North America and has a strong reputation for profitable growth, quality and customer service. To learn more about Carly Railcar Components, visit www.carlyrailcar.com.
AboutFreightCarAmerica
FreightCar America, headquartered in Chicago, Illinois, is a leading designer, producer and supplier of railroad freight cars, railcar parts and components. We also specialize in railcar repairs, complete railcar rebody services and railcar conversions that repurpose idled rail assets back into revenue service. Since 1901, our customers have trusted us to build quality railcars that are critical to economic growth and instrumental to the North American supply chain. To learn more about FreightCar America, visit www.freightcaramerica.com.
Tesla shares moved sharply higher Monday after confirmation that the company has begun testing its Robotaxi service without a safety driver, a milestone that investors and analysts see as a major step toward fully autonomous transportation.
The rally followed social media footage showing a Tesla Robotaxi operating in Austin, Texas with no human driver inside the vehicle. The video quickly gained traction after Ashok Elluswamy, who leads Tesla’s AI and autonomous driving efforts, acknowledged the clip with a brief but telling comment: “And so it begins.” Tesla CEO Elon Musk later confirmed the development, stating that testing is underway with no occupants in the car.
Shares of Tesla rose roughly 4% following the confirmation, pushing the stock closer to its prior all-time highs and reinforcing renewed optimism around the company’s long-promised autonomy strategy. The move lends credibility to Musk’s recent claim that Tesla is only weeks away from unsupervised robotaxi operations.
Austin has emerged as the proving ground for Tesla’s Robotaxi ambitions, with limited deployments already underway using safety drivers. The latest test suggests the company is moving closer to removing that final safeguard, a critical hurdle before broader commercial expansion. Musk has previously said Tesla plans to expand Robotaxi testing beyond Austin and the San Francisco Bay Area into markets such as Phoenix and Nevada.
Wall Street bulls were quick to seize on the news. Wedbush analyst Dan Ives reiterated his long-standing optimism on Tesla, describing the development as the beginning of the company’s “autonomous chapter.” In a note to clients, Ives said 2026 could be a defining year for Tesla as autonomous driving and robotics move from concept to scale.
According to Ives, Tesla is on track for an accelerated Robotaxi rollout across the U.S., with volume production of the company’s purpose-built Cybercab expected to begin in the spring. The futuristic two-seat vehicle, unveiled last year without a steering wheel or pedals, has become central to Tesla’s long-term autonomous strategy.
Early feedback on Tesla’s latest Full Self-Driving software has also added fuel to the rally. Automotive reviewers and journalists who have tested the newest version report smoother driving behavior and fewer required interventions compared with prior iterations. While competitors like Alphabet-backed Waymo still lead in publicly reported safety metrics, the gap appears to be narrowing.
The market reaction highlights a broader shift in how investors are valuing Tesla. Rather than focusing solely on vehicle deliveries and margins, attention is increasingly turning to software, AI, and recurring revenue opportunities tied to autonomy. Wedbush maintains an Outperform rating on the stock and a $600 price target, arguing that autonomous driving could unlock a path toward a multi-trillion-dollar valuation.
Still, challenges remain. Regulatory approval, public trust, and demonstrable safety performance will be essential before Tesla can scale Robotaxi services nationwide. But for the first time in years, tangible evidence appears to support Tesla’s autonomy narrative.
For investors, the confirmation of driverless Robotaxi testing marks more than just a technical achievement — it signals that Tesla’s long-awaited autonomous future may finally be arriving.
Euroseas Ltd. was formed on May 5, 2005 under the laws of the Republic of the Marshall Islands to consolidate the ship owning interests of the Pittas family of Athens, Greece, which has been in the shipping business over the past 140 years. Euroseas trades on the NASDAQ Capital Market under the ticker ESEA. Euroseas operates in the container shipping market. Euroseas’ operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company, which is responsible for the day-to-day commercial and technical management and operations of the vessels. Euroseas employs its vessels on spot and period charters and through pool arrangements.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
New time charters. Euroseas Ltd. announced new three-year forward time charter contracts for three of its modern, fuel-efficient 2,800 TEU containerships, the M/V Leonidas Z, M/V Gregos, and M/V Terataki. All three charters are for a minimum period of 35 to a maximum period of 37 months at the charterer’s option, and will be performed at a gross daily rate of $30,000. The new charter periods are expected to generate approximately $75 million of EBITDA over the minimum contracted period and lift charter coverage for 2026, 2027, and 2028 to roughly 82.5%, 66.5%, and 42%, respectively.
Updating estimates. Reflecting the updated coverage, we are modestly reducing our 2026 estimates. We now forecast 2026 revenue, adjusted EBITDA, and EPS of $229.3 million, $161.4 million, and $17.39, respectively, compared with our prior estimates of $230.0 million, $162.1 million, and $17.49. Despite the slight downward revisions, Euroseas’ contracted rates, and 2026 outlook continue to show strong year-over-year growth.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Great Lakes Dredge & Dock Corporation is the largest provider of dredging services in the United States. In addition, Great Lakes is fully engaged in expanding its core business into the rapidly developing offshore wind energy industry. The Company has a long history of performing significant international projects. The Company employs experienced civil, ocean and mechanical engineering staff in its estimating, production and project management functions. In its over 131-year history, the Company has never failed to complete a marine project. Great Lakes owns and operates the largest and most diverse fleet in the U.S. dredging industry, comprised of approximately 200 specialized vessels. Great Lakes has a disciplined training program for engineers that ensures experienced-based performance as they advance through Company operations. The Company’s Incident-and Injury-Free® (IIF®) safety management program is integrated into all aspects of the Company’s culture. The Company’s commitment to the IIF® culture promotes a work environment where employee safety is paramount.
Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Funding Remains Strong. Even though the Federal government is operating under a CR, business has been as usual for Great Lakes. Funding for the U.S. Army Corps is at a record level of $8.7 billion, the seventh consecutive year of record budgets for the Corps. The $1.5 billion Disaster Relief funding remains available. And under WRDA several large capital projects, such as New York and Texas, are expected to come to market in the next few years.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.