Diana Shipping Moves to Acquire Remaining Genco Shares in Strategic Expansion Bid

Diana Shipping Inc. has taken a significant step toward expanding its position in the global dry bulk sector with a proposal to acquire the remaining outstanding shares of Genco Shipping & Trading Limited. The company, which currently holds roughly 14.8% of Genco’s shares, is offering $20.60 per share in cash for full ownership—an offer designed to deliver immediate value while reshaping the competitive landscape of dry bulk shipping.

The proposed price reflects a meaningful premium across several metrics. It sits 15% above Genco’s most recent closing price before the announcement and more than 20% above the price recorded when Diana’s initial ownership stake became public earlier this year. It also aligns with the top end of Genco’s 10-year trading range, positioning the offer as a timely opportunity for shareholders to realize cash returns without waiting for market-driven movements in the cyclical shipping sector.

For Diana Shipping, the acquisition would represent a strategic expansion of its fleet capacity and operational leverage. Genco operates one of the industry’s more modern, fuel-efficient dry bulk fleets, which includes a mix of Capesize, Ultramax, and Supramax vessels. Integrating these assets into Diana’s platform would give the combined entity greater scale, more flexibility in vessel deployment, and broader exposure to diverse bulk cargo markets—including iron ore, coal, grain, and minor bulks.

From a timing perspective, Diana believes the market environment supports fleet consolidation. Dry bulk shipping has historically been cyclical, with periods of volatility driven by commodity demand, freight rates, and global trade patterns. Adding Genco’s fleet at this point in the cycle could position the combined company to benefit from future rate improvements, expanded vessel utilization, and optimized operating costs.

Diana has expressed confidence in its ability to finance the acquisition through a new debt facility, supplemented by asset sales where appropriate. The company emphasizes that any post-transaction divestments would be selective, with the goal of maintaining a balanced, efficient fleet while strengthening the overall balance sheet.

Another key component of the proposal is workforce integration. Diana has publicly recognized the value of Genco’s employees and signaled plans to draw from both organizations when forming the management and operational structure of the combined company. This acknowledgment reflects industry-wide awareness that operational expertise—crew management, technical maintenance, and chartering efficiency—is just as vital as vessel count when creating long-term value in shipping.

While the proposal has been unanimously approved by Diana’s board, it remains non-binding and subject to negotiation. There is no guarantee that Genco’s board will move forward on the terms presented, nor that the two companies will reach a final agreement. Diana’s letter outlining the proposal has been filed with the Securities and Exchange Commission as part of its updated Schedule 13D disclosure.

If completed, the acquisition would mark one of the more notable consolidation moves in the dry bulk industry in recent years. For shareholders, it presents a potential path to immediate liquidity. For Diana, it represents a strategic effort to expand scale, enhance fleet efficiency, and strengthen positioning in a global trade environment that continues to evolve.

Euroseas (ESEA) – Staying Nimble in a Dynamic Market Environment


Wednesday, November 19, 2025

Euroseas Ltd. was formed on May 5, 2005 under the laws of the Republic of the Marshall Islands to consolidate the ship owning interests of the Pittas family of Athens, Greece, which has been in the shipping business over the past 140 years. Euroseas trades on the NASDAQ Capital Market under the ticker ESEA. Euroseas operates in the container shipping market. Euroseas’ operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company, which is responsible for the day-to-day commercial and technical management and operations of the vessels. Euroseas employs its vessels on spot and period charters and through pool arrangements.

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Third quarter financial results. Total net revenues for the third quartertotaled $56.9 million, a 5.1% increase year-over-year, but modestly lower than our estimate of $59.2 million. Adjusted EBITDA and EPS were $38.8 million and $4.23, respectively, below our estimates of $41.7 million and $4.40. The lower-than-expected results were due primarily to a greater number of scheduled off-hire days and expenses associated with a special survey and drydock completed on one vessel during the quarter. Total operating expenses amounted to $24.4 million compared to $23.5 million during the prior year period and our $23.1 million estimate. Drydocking expenses were $2.7 million compared to our estimate of $0.6 million.

Revenue and earnings visibility into 2026. With 100% of Q4 2025 operating days secured at an average rate of ~$30,345 per day and 74.7% of 2026 days already covered at higher average rates of ~$31,300 per day, Euroseas has locked in substantial revenue visibility. This robust charter coverage not only underpins earnings but also provides a strong buffer against rate volatility, positioning the company to benefit from sustained high utilization into 2026.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Sky Harbour Group (SKYH) – Unlocking Value Through Campus Activation


Tuesday, November 18, 2025

Patrick McCann, CFA, Research Analyst, Noble Capital Markets, Inc.

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q3 results. Sky Harbour reported Q3 revenue of $7.3 million versus our estimate of $9.3 million, and an adj. EBITDA loss of $2.3 million compared with our projected gain of $0.2 million. Management highlighted that the company is within roughly $1 million of run-rate breakeven, and we expect this threshold to be reached before year end as recently delivered campuses gain tenants.

Lease-up progress and long-term pipeline visibility. Management reaffirmed its goal of reaching 23 long-term ground leases by year end, up from 19 currently. Pre-leasing at Bradley (BDL) and Dulles (IAD) prior to construction demonstrates tenant demand at target rent levels and adds visibility to the 2026 revenue ramp.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Seanergy Maritime (SHIP) – Third Quarter Results Exceed Expectations; Increasing Estimates


Friday, November 14, 2025

Seanergy Maritime Holdings Corp. is a prominent pure-play Capesize shipping company listed in the U.S. capital markets. Seanergy provides marine dry bulk transportation services through a modern fleet of Capesize vessels. The Company’s operating fleet consists of 18 vessels (1 Newcastlemax and 17 Capesize) with an average age of approximately 13.4 years and an aggregate cargo carrying capacity of approximately 3,236,212 dwt. Upon completion of the delivery of the previously announced Capesize vessel acquisition, the Company’s operating fleet will consist of 19 vessels (1 Newcastlemax and 18 Capesize) with an aggregate cargo carrying capacity of approximately 3,417,608 dwt. The Company is incorporated in the Marshall Islands and has executive offices in Glyfada, Greece. The Company’s common shares trade on the Nasdaq Capital Market under the symbol “SHIP”.

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Third quarter results. Seanergy generated third quarter net revenue of $47.0 million compared to $44.4 million during the prior year period and above our $45.1 million estimate. Relative to the third quarter of 2024, revenue growth was driven by an expanded fleet, an increase in operating days, and higher fleet utilization. Third quarter time charter equivalent (TCE) rates and fees from related parties were above our estimates. Operating expenses were in line with expectations, resulting in adjusted EBITDA of $26.6 million and EPS of $0.67, respectively, both ahead of our $25.0 million and $0.50 estimates, respectively.

Market outlook. During the investor call, management highlighted favorable Capesize market supply and demand fundamentals that are expected to support charter rates, including increasing Atlantic-based trade, a historically low order book, and limited shipyard availability. With a 20-vessel fleet consisting purely of Capesize and Newcastlemax vessels and a conservative capital structure, Seanergy is well positioned to benefit from strong Capesize market fundamentals. 


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

EuroDry (EDRY) – Momentum Building into Q4 and 2026


Friday, November 14, 2025

EuroDry Ltd. was formed on January 8, 2018 under the laws of the Republic of the Marshall Islands to consolidate the drybulk fleet of Euroseas Ltd. into a separate listed public company. EuroDry was spun-off from Euroseas Ltd. on May 30, 2018; it trades on the NASDAQ Capital Market under the ticker EDRY. EuroDry operates in the dry cargo, drybulk shipping market. EuroDry’s operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company and Eurobulk (Far East) Ltd. Inc., which are responsible for the day- to-day commercial and technical management and operations of the vessels. EuroDry employs its vessels on spot and period charters and under pool agreements.

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Third quarter financial results. EuroDry reported third quarter 2025 revenues of $15.3 million, in line with expectations of $15.1 million and down slightly from $15.8 million last year due to a smaller fleet. Adjusted EBITDA improved sharply to $4.1 million, up from $0.5 million in Q3 2024, due to lower expenses and stronger utilization. The company operated an average of 12 vessels at a TCE of $13,232/day, modestly above $13,105/day in the prior-year period. Adjusted net loss narrowed to $0.6 million, or $(0.23)/share, compared to a loss of $3.9 million, or $(1.42)/share, last year.

Market outlook. Management indicated that dry-bulk fundamentals continued to strengthen through Q3, supported by improving Chinese import activity, firmer demand across key cargo segments, and increased ton-mile requirements. Limited fleet growth and a historically low orderbook continue to support a tightening supply backdrop as the market moves into 2026. We expect Q4 results to capture more of the recent improvement as earlier charters roll off, though geopolitical uncertainty remains a risk to global trade flows.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

FreightCar America (RAIL) – Third Quarter Results Exceed Expectations


Tuesday, November 11, 2025

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Third quarter results. RAIL generated third-quarter adj. net income of $7.8 million, or $0.24 per share, compared to $7.3 million, or $0.08 per share, during the prior year period. We had forecast net income of $5.6 million, or $0.16 per share. Rail car deliveries were 1,304 units compared to 961 units during the prior year period. Third-quarter gross margin increased to 15.1% compared to 14.3% during the prior year period. Adjusted EBITDA increased 56.1% to $17.0 million, representing a margin of 10.6%, compared to $10.9 million and a margin of 9.6% in the third quarter of 2024. 

Updated corporate guidance. While management still expects 2025 rail car deliveries in the range of 4,500 to 4,900 and adjusted EBITDA in the range of $43 million to $49 million, revenue expectations were lowered to a range of $500 million to $530 million from $530 million to $595 million. Revised revenue expectations reflect changes in the product mix due to a greater number of conversion rail cars versus new rail cars in the second half.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Sky Harbour Group (SKYH) – Noble Virtual Conference Highlights


Tuesday, October 14, 2025

Patrick McCann, CFA, Research Analyst, Noble Capital Markets, Inc.

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Noble virtual conference highlights. Tal Keinan (CEO) and Francisco Gonzalez (CFO) of Sky Harbour Group (NYSE: SKYH) presented at Noble’s Emerging Growth Virtual Conference on October 8–9, 2025. Management highlighted continued lease-up at Phoenix, Dallas, and Denver, steady pre-leasing at Dulles (IAD) and Bradley (BDL), and progress on capital efficiency. A rebroadcast can be found here.

Leasing and pipeline on pace. Operations at Phoenix, Dallas, and Denver are leasing at a good clip, and the company has secured one pre-lease tenant at both IAD and BDL ahead of construction. Sky Harbour now holds long-term ground leases at 18 airports (nine operating, nine in development) and reaffirmed plans to add five more by year-end, bringing the total to 23.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

EuroDry (EDRY) – Recovering Rates and Greater Liquidity Enhance Outlook


Tuesday, October 14, 2025

EuroDry Ltd. was formed on January 8, 2018 under the laws of the Republic of the Marshall Islands to consolidate the drybulk fleet of Euroseas Ltd. into a separate listed public company. EuroDry was spun-off from Euroseas Ltd. on May 30, 2018; it trades on the NASDAQ Capital Market under the ticker EDRY. EuroDry operates in the dry cargo, drybulk shipping market. EuroDry’s operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company and Eurobulk (Far East) Ltd. Inc., which are responsible for the day- to-day commercial and technical management and operations of the vessels. EuroDry employs its vessels on spot and period charters and under pool agreements.

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Vessel sale enhances liquidity. EuroDry recently announced an agreement to sell the M/V Eirini P. to a third party for approximately $8.5 million, with the transaction expected to close in October 2025. The sale is projected to generate a gain of approximately $0.6 million, or roughly $0.21 per share. The proceeds will enhance near-term liquidity and strengthen EuroDry’s flexibility to pursue selective investments in more efficient vessels.

Market environment improving. The dry-bulk market has shown signs of recovery as charter rates have recently rebounded from multi-year lows. The improvement reflects strengthening market sentiment, supported by limited fleet growth and rising expectations for Chinese demand. A historically low orderbook and modest fleet expansion provide a constructive foundation for rate stabilization heading into 2026.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Seanergy Maritime (SHIP) – Strategic Vessel Sale and Improving Capesize Fundamentals


Thursday, October 02, 2025

Seanergy Maritime Holdings Corp. is a prominent pure-play Capesize shipping company listed in the U.S. capital markets. Seanergy provides marine dry bulk transportation services through a modern fleet of Capesize vessels. The Company’s operating fleet consists of 18 vessels (1 Newcastlemax and 17 Capesize) with an average age of approximately 13.4 years and an aggregate cargo carrying capacity of approximately 3,236,212 dwt. Upon completion of the delivery of the previously announced Capesize vessel acquisition, the Company’s operating fleet will consist of 19 vessels (1 Newcastlemax and 18 Capesize) with an aggregate cargo carrying capacity of approximately 3,417,608 dwt. The Company is incorporated in the Marshall Islands and has executive offices in Glyfada, Greece. The Company’s common shares trade on the Nasdaq Capital Market under the symbol “SHIP”.

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Sale of M/V Geniuship. Seanergy announced the sale of the M/V Geniuship, a 170,057 dwt Capesize vessel, for approximately $21.6 million, generating net cash proceeds of $12.0 million and a profit of about $2.5 million. The sale was timed to take advantage of improved vessel valuations while avoiding the costs of the vessel’s scheduled dry-docking. The transaction enhances liquidity, improves near-term earnings, and aligns with the company’s ongoing fleet renewal strategy.

Capesize market gains momentum. The Capesize market has strengthened in recent months, supported by iron ore and bauxite projects in the Atlantic basin and West Africa, while volatility due to tariffs has moderated. The orderbook remains limited, with shipyard slots not available until 2029. Rising vessel values, together with higher construction costs, have further restricted orders. Overall, we expect market conditions to remain favorable, with 2026 showing improvement over 2025.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

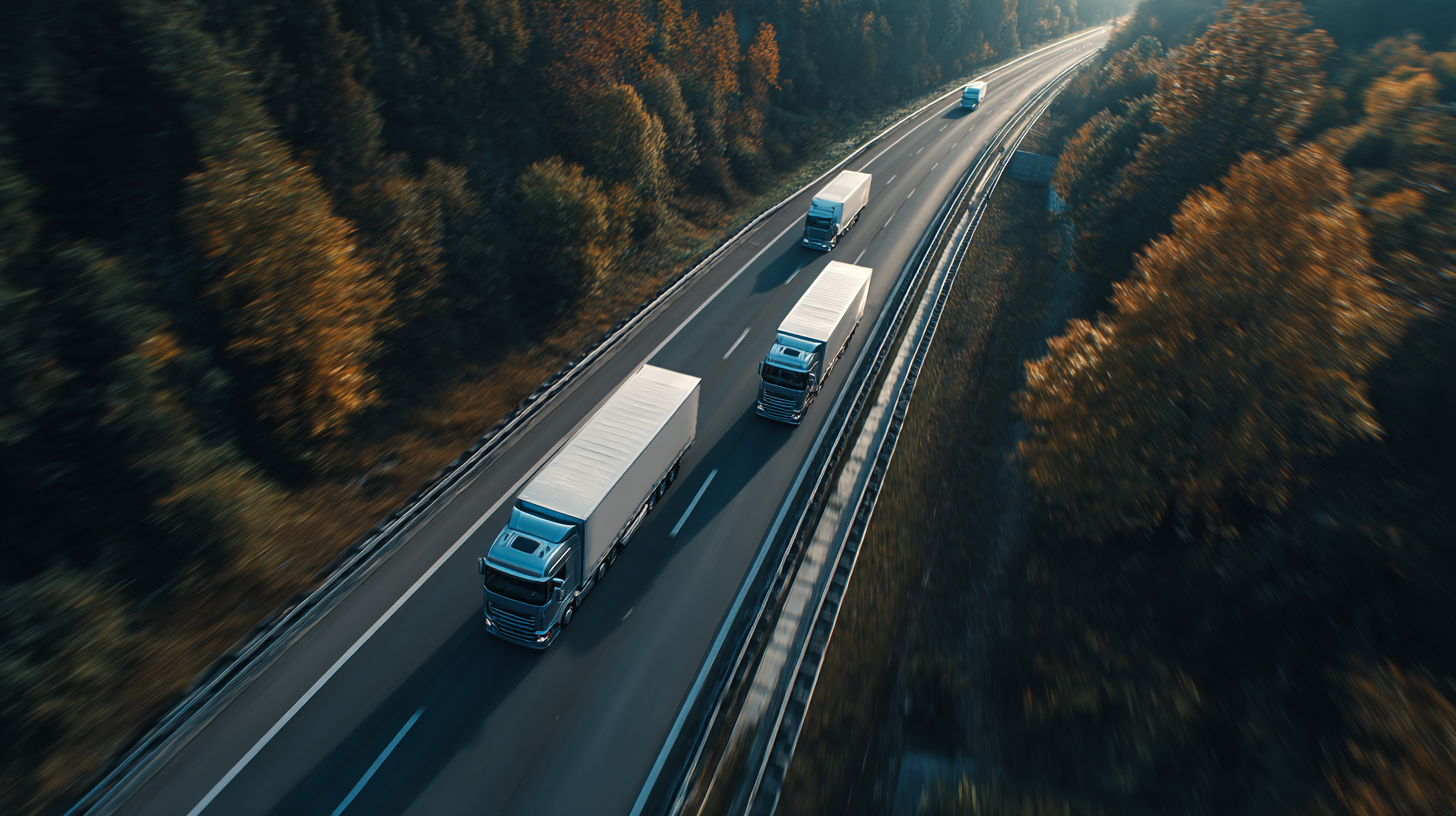
Swedish Self-Driving Truck Startup Einride Secures $100 Million in Funding

Swedish autonomous trucking company Einride has raised approximately $100 million in its latest funding round, attracting investment from firms including EQT Ventures and quantum computing company IonQ. The company did not disclose its current valuation.

Einride said the funding will be used to scale deployment of its electric self-driving trucks, advance its autonomous technology, and expand its customer base across Europe and the United States. The move comes as interest in autonomous freight solutions continues to grow, driven by the potential to reduce transportation costs, improve efficiency, and lower emissions.

Founded in 2016, Einride is part of a new wave of companies developing self-driving freight technology aimed at revolutionizing long-haul logistics. Unlike autonomous passenger vehicles, self-driving trucks typically operate on fixed routes between defined points, often along highways, which reduces complexity and regulatory challenges. By avoiding intersections, pedestrians, and dense urban traffic, companies like Einride can focus on perfecting the technology for predictable, high-volume freight operations.

Einride’s trucks are fully electric and remotely monitored, combining autonomous driving with digital fleet management systems. The company emphasizes sustainability, noting that its electric trucks produce zero tailpipe emissions, making them an attractive solution for companies seeking to decarbonize their supply chains.

The autonomous trucking market has seen significant investment in recent years. According to industry analysts, autonomous freight could dramatically reduce operating costs while increasing safety on long-haul routes. However, the sector still faces regulatory hurdles, particularly regarding safety standards, driverless operation on public highways, and liability in the event of accidents.

Einride has already built a notable track record with several high-profile clients. In 2021, it raised $110 million from investors such as Maersk’s venture capital arm and Singapore state investor Temasek, the same year it expanded into the U.S. market. Its client roster includes GE Appliances, Swedish vegan milk maker Oatly, and tire manufacturer Bridgestone, all of which rely on Einride’s technology for efficient and sustainable freight transport.

The company is also actively developing its digital freight platform, which allows clients to monitor and optimize their logistics operations in real time. By integrating autonomous trucks with advanced fleet management software, Einride aims to provide a fully connected, end-to-end solution for companies looking to modernize their supply chains.

With this latest funding, Einride plans to accelerate the rollout of its fleet and expand research and development efforts, particularly in autonomous navigation, safety systems, and battery efficiency. As the demand for greener and more efficient logistics grows, Einride positions itself at the forefront of a transformative shift in freight transportation.

Release – Seanergy Maritime Announces Profitable Sale of a Capesize Vessel and Expiration of Class E Warrants

Research News and Market Data on SHIP

September 30, 2025 09:00 ET  | Source: Seanergy Maritime Holdings Corp.

GLYFADA, Greece, Sept. 30, 2025 (GLOBE NEWSWIRE) — Seanergy Maritime Holdings Corp. (NASDAQ: SHIP) (the “Company” or “Seanergy”) announced that it has successfully completed the strategic sale of its Capesize vessel, M/V Geniuship, further optimizing its fleet and enhancing liquidity.

The Company also reported the expiration of its Class E warrants on August 20, 2025. Upon the expiration of these warrants, Seanergy has no outstanding warrants or other convertible securities.

Sale of M/V Geniuship

The M/V Geniuship was a 170,057 dwt Capesize bulker, built in 2010 by Sungdong SB in South Korea, which was acquired by Seanergy in 2015. The vessel was sold for a gross price of approximately $21.6 million to an unaffiliated buyer. The delivery was completed successfully on September 10, 2025. The transaction generated net cash proceeds of approximately $12.0 million and is expected to result in an accounting profit of around $2.5 million, which will be recorded on Seanergy’s third quarter financial results.

Expiration of Class E Warrants

The Class E warrants were issued on August 20, 2020, with a five-year term and an exercise price as of the expiration date of $3.98 per share. Following warrant exercises and a tender offer by Seanergy to repurchase warrants in January 2023, Class E warrants to purchase 57,225 common shares remained outstanding as of their expiration date. As of August 20, 2025, the remaining Class E warrants terminated.

Following the expiration of the Class E Warrants and the prior expiration of the Class D warrants in April 2025, Seanergy has no outstanding warrants.

Stamatis Tsantanis, the Company’s Chairman & Chief Executive Officer, stated:

“We are pleased to announce the well-timed sale of our 15-year-old M/V Geniuship, that takes advantage of the favorable valuation environment in the sector. The sale was concluded prior to her upcoming dry-docking, resulting in significant capex savings for Seanergy. Moreover, the approximately $12.0 million net cash sale proceeds after the repayment of the underlying loan strengthened our liquidity position.

“This proactive sale aligns perfectly with our fleet renewal strategy and enhances both our liquidity position and earnings profile.

“The expiration of the Class E warrants along with the prior expiration of the Class D warrants this past April completes the streamlining of our capital structure and removes a longstanding overhang. This is a final step in eliminating legacy dilution risks from outstanding convertible securities and enabling cleaner value recognition for our shareholders.

“With a focused Capesize platform, no outstanding warrants, and a disciplined growth path, we are positioned to capture further upside as market fundamentals strengthen and maximize returns for our shareholders.”

About Seanergy Maritime Holdings Corp.

Seanergy Maritime Holdings Corp. is a prominent pure-play Capesize shipping company publicly listed in the U.S. Seanergy provides marine dry bulk transportation services through a modern fleet of Capesize vessels. The Company’s operating fleet consists of 20 vessels (2 Newcastlemax and 18 Capesize) with an average age of approximately 14.3 years and an aggregate cargo carrying capacity of approximately 3,633,861 dwt.

The Company is incorporated in the Republic of the Marshall Islands and has executive offices in Glyfada, Greece. The Company’s common shares trade on the Nasdaq Capital Market under the symbol “SHIP”.

Please visit our Company website at: www.seanergymaritime.com.

Forward-Looking Statements

This press release contains forward-looking statements (as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended) concerning future events, including with respect to the declaration of dividends, market trends and shareholder returns. Words such as “may”, “should”, “expects”, “intends”, “plans”, “believes”, “anticipates”, “hopes”, “estimates” and variations of such words and similar expressions are intended to identify forward-looking statements. These statements involve known and unknown risks and are based upon a number of assumptions and estimates, which are inherently subject to significant uncertainties and contingencies, many of which are beyond the control of the Company. Actual results may differ materially from those expressed or implied by such forward-looking statements. Factors that could cause actual results to differ materially include, but are not limited to, the Company’s operating or financial results; the Company’s liquidity, including its ability to service its indebtedness; competitive factors in the market in which the Company operates; shipping industry trends, including charter rates, vessel values and factors affecting vessel supply and demand; future, pending or recent acquisitions and dispositions, business strategy, impacts of litigation, areas of possible expansion or contraction, and expected capital spending or operating expenses; risks associated with operations outside the United States; broader market impacts arising from trade disputes or war (or threatened war) or international hostilities, such as between Israel and Hamas or Iran, China and Taiwan and between Russia and Ukraine; risks associated with the length and severity of pandemics, including their effects on demand for dry bulk products and the transportation thereof; and other factors listed from time to time in the Company’s filings with the SEC, including its most recent annual report on Form 20-F. The Company’s filings can be obtained free of charge on the SEC’s website at www.sec.gov. Except to the extent required by law, the Company expressly disclaims any obligations or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in the Company’s expectations with respect thereto or any change in events, conditions or circumstances on which any statement is based.

For further information please contact:

Seanergy Investor Relations
Tel: +30 213 0181 522
E-mail: [email protected]

Capital Link, Inc.
Paul Lampoutis
230 Park Avenue Suite 1540
New York, NY 10169
Tel: (212) 661-7566
Email: [email protected]

Great Lakes Dredge & Dock (GLDD) – A Month of Awards


Thursday, September 18, 2025

Great Lakes Dredge & Dock Corporation is the largest provider of dredging services in the United States. In addition, Great Lakes is fully engaged in expanding its core business into the rapidly developing offshore wind energy industry. The Company has a long history of performing significant international projects. The Company employs experienced civil, ocean and mechanical engineering staff in its estimating, production and project management functions. In its over 131-year history, the Company has never failed to complete a marine project. Great Lakes owns and operates the largest and most diverse fleet in the U.S. dredging industry, comprised of approximately 200 specialized vessels. Great Lakes has a disciplined training program for engineers that ensures experienced-based performance as they advance through Company operations. The Company’s Incident-and Injury-Free® (IIF®) safety management program is integrated into all aspects of the Company’s culture. The Company’s commitment to the IIF® culture promotes a work environment where employee safety is paramount.

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

More Business. Over the past month, Great Lakes continued to be awarded additional business, according to the Department of War’s daily contract awards release. In total, the announced awards (and recall not all awards are included in the daily notice), totaled approximately $80 million, demonstrating Great Lakes’ operating capabilities as well as the ongoing demand from the government.

September. Most recently, Great Lakes was awarded a $27.9 million firm-fixed-price contract for the removal and disposal of hopper dredge material. Work will be performed in Venice, Louisiana, with an estimated completion date of April 7, 2026. Fiscal 2025 civil operation and maintenance funds in the amount of $27.9 million were obligated at the time of the award.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

FreightCar America (RAIL) – RAIL Adopts Stockholder Rights Plan


Thursday, September 18, 2025

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Hans Baldau, Associate Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Protecting the interests of all shareholders. Following a review of the company’s current ownership structure, FreightCar America announced that its Board of Directors adopted a limited-duration stockholder rights plan.The rights plan will expire on August 5, 2026, unless terminated earlier by the Board. The Rights Plan is intended to reduce the likelihood that any person or group gains control of the company through open-market accumulation or other tactics without paying an appropriate control premium. The plan also ensures the Board has sufficient time to make informed decisions that protect the interests of the company and all RAIL shareholders.

Increasing 2026 estimates. We have increased our 2026 EBITDA and EPS estimates to $53.6 million and $0.65, respectively, from $53.2 million and $0.64. Our estimate update reflects stronger deliveries in the second half of the year, with a full-year estimate of 4,850 compared with our previous estimate of 4,800. We now expect quarterly deliveries of: 1Q: 982, 2Q: 1,200, 3Q: 1,284, and 4Q: 1,384. Previously we had assumed: 1Q: 1,346, 2Q: 1,275, 3Q: 1,058, and 4Q: 1,121.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.