PLANTATION, Fla., Aug. 27, 2026 (GLOBE NEWSWIRE) — Alliance Entertainment Holding Corporation (Nasdaq: AENT), a premier distributor, logistics provider, and omnichannel fulfillment partner to the entertainment and pop culture collectibles industry, supplying more than 340,000 unique SKUs across physical media, video games, toys, licensed merchandise, and exclusive collectibles to over 35,000 retail and e-commerce storefronts, will hold a conference call on Thursday, September 10, at 4:30 p.m. Eastern Time to discuss its results for the fiscal year ended June 30, 2026. A press release detailing these results will be issued prior to the call.
Alliance Entertainment Chief Executive Officer Jeff Walker, Chief Financial Officer Amanda Gnecco, and Executive Chairman Bruce Ogilvie will host the conference call, which will be followed by a question-and-answer session. A presentation will accompany the call and can be viewed during the webcast or accessed via the investor relations section of the Company’s website here.
To access the call, please use the following information:
Date:
Thursday, September 10, 2026
Time:
4:30 p.m. Eastern Time, 1:30 p.m. Pacific Time
Toll-free dial-in number:
1-877-407-0784
International dial-in number:
1-201-689-8560
Conference ID:
13762431
Please call the conference telephone number 5-10 minutes prior to the start time. An operator will register your name and organization. If you have any difficulty connecting with the conference call, please contact RedChip Companies at 1-407-644-4256.
A telephone replay of the call will be available approximately three hours after the call concludes and can be accessed through October 10, 2026, using the following information:
Toll-free replay number:
1-844-512-2921
International replay number:
1-412-317-6671
Replay ID:
13762431
About Alliance Entertainment
Alliance Entertainment (NASDAQ: AENT) is a premier distributor and fulfillment partner for the entertainment and pop culture collectibles industry. With more than 340,000 unique in-stock SKUs – including over 57,300 exclusive titles across compact discs, vinyl LPs, DVDs, Blu-rays, and video games – Alliance offers the largest selection of physical media in the market. Our vast catalog also includes licensed merchandise, toys, retro gaming products, and collectibles, serving over 35,000 retail locations and powering e-commerce fulfillment for leading retailers. Alliance also owns and operates proprietary collectibles brands, including Handmade by Robots™, a stylized vinyl figure line featuring licensed characters from leading entertainment franchises, and Alliance Authentic™, a premium platform for authentic, certified, and individually numbered entertainment collectibles. In addition, Alliance operates Endstate Authentic, a dedicated NFC-enabled authentication and digital product identity platform supporting authenticated collectibles, resale, and brand protection. Leveraging decades of operational expertise, exclusive sourcing relationships, and a capital-light, scalable infrastructure, Alliance connects fans and collectors to the products, franchises, and experiences they value across formats and generations. For more information, visit www.aent.com.
For investor inquiries, please contact:
Dave Gentry RedChip Companies, Inc. 1-800-REDCHIP (733-2447) 1-407-644-4256 [email protected]
Total Revenue Growth of 0.9% in Fourth Quarter 2026
Continued expansion of Lucky Strike brand with 159 current Lucky Strike locations
Continued efforts to deploy capital efficiently, driving long-term returns
RICHMOND, Va.–(BUSINESS WIRE)– Lucky Strike Entertainment (NYSE: LUCK), one of the world’s premier owner/operators of location-based entertainment, today provided financial results for the fourth quarter and full year of fiscal year 2026, which ended on June 28, 2026.
Quarter Highlights:
Total revenue increased 0.9% to $303.9 million versus 4Q25
Same-Store Revenue decreased 2.5% versus 4Q25
Net loss of $26.2 million versus net loss of $74.7 million in 4Q25
Adjusted EBITDA of $74.1 million versus $88.7 million in 4Q25
Fiscal Year Highlights:
Revenue increased 3.7% to $1,245.3 million versus the prior year
Same Store Revenue decreased 0.2% versus the prior year
Net loss of $35.8 million versus prior year net loss of $10.0 million
Adjusted EBITDA of $333.2 million versus prior year of $367.7 million
Added six locations during the fiscal year, five through acquisitions and one new build. Additionally, closed five underperforming locations
Total locations in operation as of August 27, 2026, were 366
“Fiscal 2026 marked a meaningful step forward for our business, with our strongest same-store sales performance in years and clear momentum across many of our key revenue streams,” said Thomas Shannon, Founder and CEO. “Importantly, that momentum is broadening. Cumulative organic growth was positive through the first eleven months of the fiscal year, with June driving the full-year decline. Leagues grew and accelerated through the spring, food remained strongly positive, retail bowling continued to grow, and Events turned positive in late spring for the first time in years and remained positive throughout the summer. It is the strongest sustained performance we have seen from that business in a long time.”
“June temporarily interrupted that progress. The first World Cup on American soil in a generation drew millions of consumers to their screens on nights they would typically be out, resulting in sharply negative comps for the month and pulling an otherwise positive quarter and year slightly below zero. We believe it is important to distinguish that temporary disruption from the underlying health of the business. Trends improved immediately following the World Cup Final, and this headwind will not repeat next summer. At our waterparks, a cool and wet start to the summer pressured attendance, but strong pricing and disciplined cost management helped protect profitability.”
“Waterparks represented the biggest operational step forward for us this summer. A year ago, we directly managed only a couple of parks. This summer, we operated a diverse portfolio, including our newest park in Los Angeles, and the organization executed exceptionally well. Per-capita spending increased meaningfully, labor costs declined as we aligned staffing more closely with demand, and both revenue and profitability grew substantially year over year. Importantly, the majority of the summer earnings contribution will be recognized in our September quarter.”
“I have described our business as a coiled spring, and that is exactly how we see it. We are pairing operating momentum with a structurally more disciplined approach to capital allocation. Capital expenditures are down approximately $80 million from their fiscal 2024 peak, and we expect to continue reducing capital spending as we further rationalize the portfolio and complete several existing investment programs. That creates a clear path to meaningfully higher free cash flow and accelerated deleveraging as earnings improve. As we enter fiscal 2027, our guidance is intentionally prudent and reflects the way we are approaching the current environment. We believe the combination of operating momentum, declining capital intensity and financial discipline positions us to deliver profitable growth, stronger free cash flow and a meaningfully improved balance sheet.”
Fiscal Year 2027 Guidance
We remain focused on delivering sustainable, profitable growth and creating meaningful long-term shareholder value. Our strategy is centered on accelerating revenue growth, expanding operating cash flow, and driving higher free cash flow per share through earnings growth and disciplined capital allocation. Looking ahead, our outlook reflects continued organic revenue growth, targeted investments in marketing and technology to strengthen our platform, and incremental contributions from our waterparks in FY27. Together, these initiatives position us to generate stronger cash flow, improve returns on invested capital, and build a more durable earnings growth profile.
Total Revenue Growth:
3% to 5%
Total Revenue:
$1,280M to $1,310M
Adjusted EBITDA:
$340M to $360M
Capital Expenditures:
Approximately $90M
Dividend Declaration
On August 27, 2026, the Board of Directors declared a quarterly cash dividend of $0.06 per share of common stock for the first quarter of fiscal year 2027. The dividend will be payable on September 22, 2026, to stockholders of record on September 8, 2026.
Investor Webcast Information
Listeners may access an investor webcast hosted by Lucky Strike Entertainment. The webcast and results presentation will be accessible at 9:00 AM ET on August 27, 2026, in the Events & Presentations section of the Lucky Strike Entertainment Investor Relations website at https://ir.luckystrikeent.com/.
About Lucky Strike Entertainment
Lucky Strike Entertainment is one of the world’s premier location-based entertainment platforms. With over 360 locations across North America, Lucky Strike Entertainment provides experiential offerings in bowling, amusements, water parks, and family entertainment centers. The Company also owns the Professional Bowlers Association, the major league of bowling and a growing media property that boasts millions of fans around the globe. For more information on Lucky Strike Entertainment, please visit IR.LuckyStrikeEnt.com.
Forward Looking Statements
Some of the statements contained in this press release are forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, that involve risk, assumptions, and uncertainties, such as statements of our plans, objectives, expectations, intentions, and forecasts. These forward-looking statements reflect our views with respect to future events as of the date of this release and are based on our management’s current expectations, estimates, forecasts, projections, assumptions, beliefs, and information. Although management believes that the expectations reflected in these forward-looking statements are reasonable, it can give no assurance that these expectations will prove to have been correct. All such forward-looking statements are subject to risks and uncertainties, many of which are outside of our control, and could cause future events or results to be materially different from those stated or implied in this document. It is not possible to predict or identify all such risks. These risks include, but are not limited to: our ability to design and execute our business strategy; changes in consumer preferences and buying patterns; our ability to compete in our markets; the occurrence of unfavorable publicity; risks associated with long-term non-cancellable leases for our locations; our ability to retain key managers; risks associated with our substantial indebtedness and limitations on future sources of liquidity; our ability to carry out our expansion plans; our ability to successfully defend litigation brought against us; failure to hire and retain qualified employees and personnel; cybersecurity breaches, cyber-attacks and other interruptions to our and our third-party service providers’ technological and physical infrastructures; catastrophic events, including war, terrorism and other conflicts; public health emergencies and pandemics, such as the COVID-19 pandemic, or natural catastrophes and accidents; fluctuations in our operating results; economic conditions, including the impact of increasing interest rates, inflation and recession; and other factors described under the section titled “Risk Factors” in the Company’s Annual Report on Form 10-K filed with the U.S. Securities and Exchange Commission (the “SEC”) by the Company on August 27, 2026, as well as other filings that the Company will make, or has made, with the SEC, such as Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. These factors should not be construed as exhaustive and should be read in conjunction with the other cautionary statements that are included in this press release and in other filings. We expressly disclaim any obligation to publicly update or review any forward-looking statements, except as required by applicable law.
Non-GAAP Financial Measures
To provide investors with information in addition to our results as determined under Generally Accepted Accounting Principles (“GAAP”), we disclose Same Store Revenue and Adjusted EBITDA as “non-GAAP measures”, which management believes provide useful information to investors because each measure assists both investors and management in analyzing and benchmarking the performance and value of our business. Accordingly, management believes that these measurements are useful for comparing general operating performance from period to period, and management relies on these measures for planning and forecasting of future periods. Additionally, these measures allow management to compare our results with those of other companies that have different financing and capital structures. These measures are not financial measures calculated in accordance with GAAP and should not be considered as a substitute for revenue or net income as calculated in accordance with GAAP, and may not be comparable to a similarly titled measure reported by other companies. Our fiscal year 2027 guidance measures (other than revenue) are provided on a non-GAAP basis without a reconciliation to the most directly comparable GAAP measure because the Company is unable to predict with a reasonable degree of certainty certain items contained in the GAAP measures without unreasonable efforts. For the same reasons, the Company is unable to address the probable significance of the unavailable information. Such items include, but are not limited to, acquisition-related expenses, share-based compensation, and other items not reflective of the company’s ongoing operations.
Same Store Revenue represents total Revenue less Non-Location Related Revenue, Revenue from Closed Locations, Service Fee Revenue, if applicable, and Acquired Revenue. Adjusted EBITDA represents Net Income (Loss) before Interest Expense, Income Taxes, Depreciation and Amortization, Impairment and Other Charges, Share-based Compensation, EBITDA from Closed Locations, Foreign Currency Exchange Loss (Gain), Asset Disposition Loss (Gain), Transactional and other advisory costs, System modernization costs, changes in the value of earnouts, and other.
The Company considers Same Store Revenue as an important financial measure because it provides comparable revenue for locations open for the entire duration of both the current and comparable measurement periods.
The Company considers Adjusted EBITDA as an important financial measure because it provides a financial measure of the quality of the Company’s earnings. Other companies may calculate Adjusted EBITDA differently than we do, which might limit its usefulness as a comparative measure. Adjusted EBITDA is used by management in addition to and in conjunction with the results presented in accordance with GAAP. We have presented Adjusted EBITDA solely as a supplemental disclosure because we believe it allows for a more complete analysis of results of operations and assists investors and analysts in comparing our operating performance across reporting periods on a consistent basis by excluding items that we do not believe are indicative of our core operating performance. Adjusted EBITDA has limitations as an analytical tool, and you should not consider it in isolation or as a substitute for analysis of our results as reported under GAAP.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q2 results. Second-quarter revenue of $7.8 million declined 23% year over year and came in 11% below our $8.8 million estimate. The shortfall was concentrated among demand-side platform customers, with spending falling to zero from $2.5 million in the prior-year quarter. Excluding DSP customers, revenue grew 3% in the quarter and 5% year-to-date, suggesting the core managed-campaign business is roughly stable even as the reported line contracts.
Gross margin held with disciplined spending. Gross profit of $2.7 million represented 34% of revenue, down modestly from 35% a year ago and flat with the first quarter. Operating expenses of $5.6 million declined 7% year over year. The adjusted EBITDA loss widened to $2.3 million from $1.5 million a year earlier, well short of our $0.35 million loss estimate, and management’s second-half breakeven target now looks difficult to reach.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Radio’s audience remains considerably more resilient than its advertising performance suggests. Consumer engagement has held up far better than traditional spot revenue, even as podcasts, streaming, and other audio alternatives have proliferated. This disconnect is central to the investment thesis: radio increasingly has a monetization problem rather than an audience problem, creating an opportunity if technology can narrow the gap.
The industry’s transformation is increasingly becoming an ad-tech and digital monetization story. Programmatic buying, improved attribution, first-party data, podcasts, and digital marketing services are expanding radio beyond the traditional station-and-spot model. The opportunity is to use radio’s existing reach, content, and advertiser relationships to participate in a much larger advertising market rather than simply defend its share of traditional radio spending.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Record-Breaking Q2. The company reported its highest quarterly revenue of $54.1 million, up a solid 16.5% YoY, and adj. EBTDA of $5.7 million, both of which beat our estimates of $52.5 million and a loss of $0.675 million, respectively. Notably, the company generated its first profitable quarter as a public company, driven primarily by higher affiliate fees and licensing revenue.
Higher-margin revenue streams gaining momentum. Affiliate fee revenue increased 81.9% to $13.4 million, while licensing revenue increased 563.5% to $4.6 million. In our view, continued affiliate repricing and licensing growth should improve the company’s revenue mix and provide an increasingly important driver of margin expansion.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
LIMASSOL, Cyprus, Aug. 21, 2026 (GLOBE NEWSWIRE) — GDEV Inc. (NASDAQ: GDEV), an international gaming and entertainment company (“GDEV” or the “Company”) released its unaudited financial and operational results for the second quarter and first half-year ended June 30, 2026.
Second quarter 2026 financial highlights:
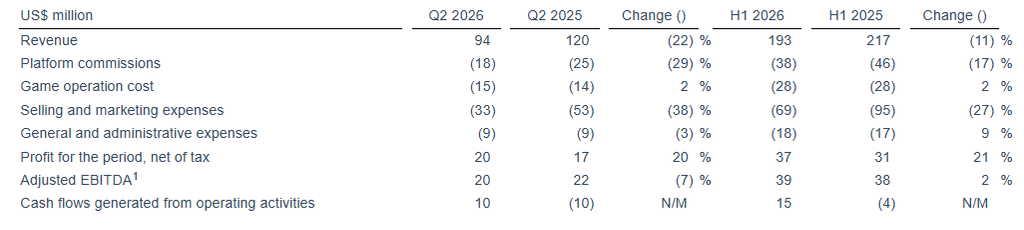
Revenue of $94 million decreased by 22% year-over-year.
Selling and marketing expenses of $33 million decreased by 38% year-over-year.
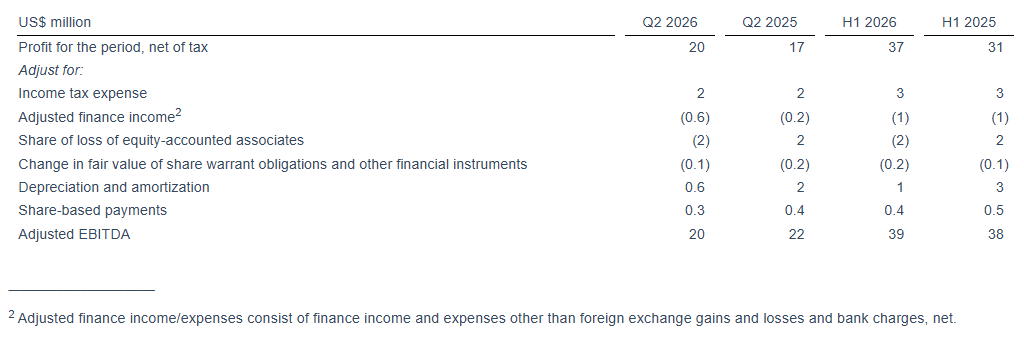
Profit for the period, net of tax, of $20 million in Q2 2026 increased vs. $17 million in Q2 2025.
Adjusted EBITDA amounted to $20 million in Q2 2026 decreased vs. $22 million in Q2 2025.
Second quarter and first half of 2026 financial performance in comparison
Second quarter 2026 financial performance
In the second quarter of 2026, our revenue decreased by $26 million (or 22%) year-over-year and amounted to $94 million. The decrease was primarily driven by a decrease in bookings.
Platform commissions decreased by $7 million (or 29%) in the second quarter of 2026 compared to the same period in 2025 in line with the decrease in revenue.
Game operation costs remained relatively stable at the level of $15 million in the second quarter of 2026 vs. $14 million in the second quarter of 2025.
Selling and marketing expenses in the second quarter of 2026 decreased by $20 million vs. the same period in 2025, amounting to $33 million. This decrease is driven by our continued focus on improving the efficiency of user acquisition activities. The decrease reflects a more selective approach to performance marketing, prioritizing channels that attract players with higher long-term value over broad-scale campaigns aimed at short-term growth.
General and administrative expenses remained stable at $9 million in the second quarters of both 2026 and 2025.
As a result of the factors above, together with (i) the effect of a net foreign exchange loss in the second quarter of 2026 in the amount of $1 million vs. a net foreign exchange gain in the amount of $1 million in the same period of the prior year and (ii) share of profits of equity accounted associates in the second quarter of 2026 in the amount of $2 million vs. the share of losses of equity accounted associates in the amount of $2 million in the same period of the prior year, we recorded a profit for the period, net of tax, of $20 million in the second quarter of 2026 compared with $17 million in the same period of 2025. Adjusted EBITDA in the second quarter of 2026 amounted to $20 million, a decrease of $2 million compared with the same period in 2025 driven primarily by the same factors as those affecting the profit, except for the share of profits or losses of equity accounted associates, which do not impact the Adjusted EBITDA.
Cash flows generated from operating activities were positive $10 million in the second quarter of 2026 compared with negative $10 million in the same period in 2025.
________________________ 1 For more information, see section titled “Presentation of Non-IFRS Financial Measures” on the last two pages of this report, including the reconciliation of the profit for the period, net of tax to the Adjusted EBITDA.
First half of 2026 financial performance
In the first half of 2026, our revenue decreased by $24 million (or 11%) year-over-year to $193 million. This decrease was primarily driven by a decrease in bookings.
Platform commissions decreased by $8 million (or 17%) in the first half of 2026 compared to the same period in 2025, driven by a decrease of revenues recognized from PC platforms.
Game operation cost remained stable at $28 million in the first halves of both 2026 and 2025.
Selling and marketing expenses in the first half of 2026 decreased by $25 million vs. the same period in 2025, amounting to $69 million. This decrease is driven by our continued focus on improving the efficiency of user acquisition activities. The decrease reflects a more selective approach to performance marketing, prioritizing channels that attract players with higher long-term value over broad-scale campaigns aimed at short-term growth.
General and administrative expenses remained relatively stable at $18 million in the first half of 2026 vs. $17 million in 2025.
As a result of the factors above, together with (i) the effect of a net foreign exchange loss in the first half of 2026 in the amount of $2 million vs. a net foreign exchange gain in the amount of $2 million in the same period of prior year and (ii) share of profits of equity accounted associates in the second quarter of 2026 in the amount of $2 million vs. the share of losses of equity accounted associates in the amount of $2 million in the same period of prior year, we recorded a profit for the period, net of tax, of $37 million compared with $31 million in the same period of 2025. Adjusted EBITDA in the first half of 2026 amounted to $39 million, an increase of $1 million compared with the same period in 2025 driven primarily by the same factors as those affecting the profit, except for the share of profits or losses of equity accounted associates, which do not impact the Adjusted EBITDA.
Cash flows generated from operating activities were positive $15 million in the first half of 2026 compared with negative $4 million in the same period in 2025.
Second quarter and first half 2026 operational performance comparison
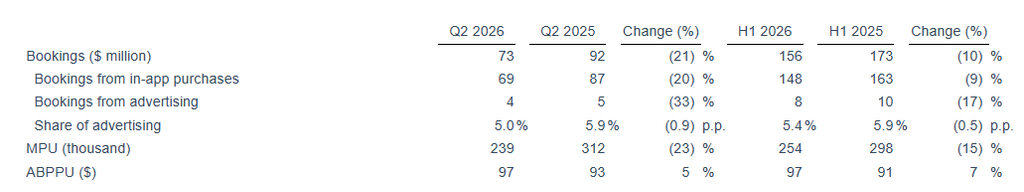
Bookings declined in the second quarter and first half of 2026 to reach $73 million and $156 million, respectively, compared with $92 million and $173 million in the same periods in 2025. The decline was primarily due to a decline in monthly paying users of 23% and 15% in the second quarter and first half of 2026, respectively, vs. the same periods in 2025.
The share of advertisement sales as a percentage of total bookings decreased in the second quarter and first half of 2026 by 0.9 p.p. and 0.5 p.p. vs. the same period in 2025.
In the second quarter of 2026, the share of mobile and PC versions of our games remained relatively stable while in the first half of 2026 we recorded an increase in share of mobile to reach 64% vs. 61% in the same period in 2025 and a decrease in share of PC to reach 36% vs. 39% in the same period in 2025.
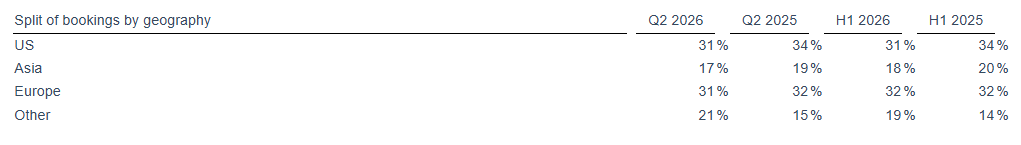
Our split of bookings by geography in the second quarter and first half of 2026 vs. the same periods in 2025 saw a decrease in the share of bookings derived from the US and Asia and an increase in bookings derived from other countries.
Note:
Due to rounding, the numbers presented throughout this release may not precisely add up to the totals. The period-over-period percentage changes are based on the actual numbers and may therefore differ from the percentage changes if those were to be calculated based on the rounded numbers.
Recent developments
On August 13, 2026, the Group entered into a game asset purchase agreement with an unrelated party for the sale of the mobile game “Island Hoppers”, together with all related intellectual property and game assets, for a total consideration of $5.0 million, of which $4.5 million was received upon execution and $0.5 million represents a deferred payment contingent on the satisfaction of a gross revenue condition and completion of the agreed migration obligations.
Island Hoppers contributed approximately 1% to the Group’s bookings in the first half of 2026 and approximately 3% in the year ended December 31, 2025.
As a result of the transaction, deferred revenue related to Island Hoppers’ bookings, totaling $2.1 million as of June 30, 2026, will be recognized on an accelerated basis, providing a one-time uplift to reported revenue in the period of closing.
About GDEV
GDEV is a gaming and entertainment holding company, focused on development and growth of its franchise portfolio across various genres and platforms. With a diverse range of subsidiaries including Nexters and Cubic Games, among others, GDEV strives to create games that will inspire and engage millions of players for years to come. Its franchises, such as Hero Wars, Island Hoppers, Pixel Gun 3D and others have accumulated over 550 million installs and $2.5 billion of bookings worldwide. For more information, please visit www.gdev.inc
Contacts:
Investor Relations Roman Safiyulin | Chief Corporate Development Officer [email protected]
Certain statements in this press release may constitute “forward-looking statements” for purposes of the federal securities laws. Such statements are based on current expectations that are subject to risks and uncertainties. In addition, any statements that refer to projections, forecasts or other characterizations of future events or circumstances, including any underlying assumptions, are forward-looking statements.
The forward-looking statements contained in this press release are based on the Company’s current expectations and beliefs concerning future developments and their potential effects on the Company. There can be no assurance that future developments affecting the Company will be those that the Company has anticipated. Forward-looking statements involve a number of risks, uncertainties (some of which are beyond the Company’s control) or other assumptions. You should carefully consider the risks and uncertainties described in the “Risk Factors” section of the Company’s 2025 Annual Report on Form 20-F, filed by the Company on March 31, 2026, and other documents filed by the Company from time to time with the Securities and Exchange Commission. Should one or more of these risks or uncertainties materialize, or should any of the Company’s assumptions prove incorrect, actual results may vary in material respects from those projected in these forward-looking statements. Forward-looking statements speak only as of the date they are made. Readers are cautioned not to put undue reliance on forward-looking statements, and the Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as may be required under applicable securities laws.
Presentation of Non-IFRS Financial Measures
In addition to the results provided in accordance with IFRS throughout this press release, the Company has provided the non-IFRS financial measure “Adjusted EBITDA” (the “Non-IFRS Financial Measure”). The Company defines Adjusted EBITDA as the profit/loss for the period, net of tax as presented in the Company’s financial statements in accordance with IFRS, adjusted to exclude (i) goodwill and investments in equity-accounted associates’ impairment, (ii) loss on disposal of subsidiaries, (iii) income tax expense, (iv) other financial income, finance income and expenses other than foreign exchange gains and losses and bank charges, (v) change in fair value of share warrant obligations and other financial instruments, (vi) share of loss of equity-accounted associates, (vii) depreciation and amortization, (viii) share-based payments expense and (ix) certain non-cash or other special items that we do not consider indicative of our ongoing operating performance. The Company uses this Non-IFRS Financial Measure for business planning purposes and in measuring its performance relative to that of its competitors. The Company believes that this Non-IFRS Financial Measure is a useful financial metric to assess its operating performance from period-to-period by excluding certain items that the Company believes are not representative of its core business. This Non-IFRS Financial Measure is not intended to replace, and should not be considered superior to, the presentation of the Company’s financial results in accordance with IFRS. The use of the Non-IFRS Financial Measure terms may differ from similar measures reported by other companies and may not be comparable to other similarly titled measures.
Reconciliation of the profit for the period, net of tax to the Adjusted EBITDA
RICHMOND, Va.–(BUSINESS WIRE)– Lucky Strike Entertainment (NYSE: LUCK), one of the world’s premier operators of location-based entertainment, will report financial results for the fourth quarter and full year fiscal 2026 on Thursday, August 27, 2026, before the U.S. stock market opens. Management will discuss the results via webcast at 9:00 AM ET on the same day.
The live webcast, replay, and results presentation will be available in the Events & Presentations section of the Lucky Strike Entertainment Investor Relations website at IR.LuckyStrikeEnt.com.
About Lucky Strike Entertainment
Lucky Strike Entertainment is one of the world’s premier location-based entertainment platforms. With over 360 locations across North America, Lucky Strike Entertainment provides experiential offerings in bowling, amusements, water parks, and family entertainment centers. The company also owns the Professional Bowlers Association, the major league of bowling and a growing media property that boasts millions of fans around the globe. For more information on Lucky Strike Entertainment, please visit IR.LuckyStrikeEnt.com.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Gamescom 2026 AAA unveiling. Snail announced its Gamescom 2026 lineup, headlined by the unveiling of its second internally developed AAA title in the 9 Yin Sutra universe, set in a parallel timeline and alternate universe to 9Yin Sutra: Immortal, which debuted at ChinaJoy on July 30th. In our note on August 12th, we had identified an unannounced AAA reveal at Gamescom as a near-term event, and the release confirms it.
The franchise builds. Both 9 Yin Sutra titles draw on the established Age of Wushu IP, offering different treatments of the same martial arts setting. Along with these titles, Snail will also show For The Stars, its space-survival AAA project. In our view, concentrating two out of the three AAA projects within a single IP family should improve development and marketing efficiency, while also making outcomes across those titles more correlated.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
CULVER CITY, Calif., Aug. 20, 2026 (GLOBE NEWSWIRE) — Snail, Inc. (Nasdaq: SNAL) (“Snail Games” or the “Company”), a leading independent global developer and publisher of interactive digital entertainment, unveils its Gamescom 2026 lineup that includes developing AAA titles, upcoming releases, and content updates across existing titles.
Taking the spotlight at Gamescom 2026 is the 9 Yin Sutra universe. Following the recent ChinaJoy announcement of9 Yin Sutra: Immortal, Snail Games CEO, Hai Shi, will officially unveil another internally developed AAA title, expanding the franchise into a parallel timeline and alternate universe. Both titles are rooted in the acclaimed Age of Wushu IP, offering distinct takes on the martial arts world while building on one of Snail Games’ most established franchises. Alongside the upcoming 9 Yin Sutra titles, Snail Games will also showcase For The Stars, the Company’s other developing AAA title and ambitious space survival experience.
Meanwhile, Honeycomb: The World Beyond is gearing up for its recently announced September 8, 2026 launch. The upcoming survival adventure will be featured at Gamescom, giving attendees an early look at the game ahead of release. Players can also get an early, hands-on experience through a PC-exclusive preview demo expected to launch on August 31, 2026.
Bellwright will celebrate its community of over 1 million players while teasing an upcoming update with one of its most anticipated developments. Consistently the #1 player-requested feature, Bellwright’s latest feature represents a major step in how players will experience and move through the world. The Gamescom showcase will offer an early look at what’s coming while celebrating the community that has helped shape Bellwright.
Leading into Gamescom, Echoes of Elysium has received a new weather-focused tempest that makes rain a more meaningful part of gameplay. Rain now directly affects ships and their contents, with wet components and stored items gaining weight and drag. Certain stations can become inoperable when soaked, while the updated weather system brings a darker, more atmospheric feel to the world.
Visit the Snail Games Booth at Gamescom Hall 8.1 A-041
For Media interested in interviews at Gamescom please reach out to [email protected]
For Creators interested in collaborations please reach out to [email protected]
About Snail, Inc. Snail, Inc. (Nasdaq: SNAL) is a leading global independent developer and publisher of interactive digital entertainment for consumers around the world, with a premier portfolio of premium games designed for use on a variety of platforms, including consoles, PCs, and mobile devices. For more information, please visit: https://snail.com/.
Forward-Looking Statements This press release contains statements that constitute forward-looking statements. Many of the forward-looking statements contained in this press release can be identified by the use of forward-looking words such as “anticipate,” “believe,” “could,” “expect,” “should,” “plan,” “intend,” “may,” “predict,” “continue,” “estimate” and “potential,” or the negative of these terms or other similar expressions. Forward-looking statements appear in a number of places in this press release and include, but are not limited to, statements regarding Honeycomb: The World Beyond gearing up for its recently announced September 8, 2026 launch; the survival adventure being featured at Gamescom, players getting an early hands-on experience through a PC-exclusive preview demo launching August 31; Bellwright teasing one of its most anticipated developments: traversal at Gamescom: Snail Games USA showcasing For The Stars and the 9 Yin Sutra universe; and Snail Games USA’s CEO officially unveiling another new 9 Yin Sutra title at Gamescom, 9 Yin Sutra, expanding the franchise into a parallel timeline and alternate universe. Any forward-looking statements included herein reflect our current views, and they involve certain risks and uncertainties, including, among others, the ability to launch The World Beyond on September 8, 2026 , the PC-exclusive demo and the other new games and titles when anticipated; acceptance of the Company’s titles in the marketplace and the successful development, marketing or sale of our titles and our ability to retain our key employees or maintain our Nasdaq listing. These risks should not be construed as exhaustive and should be read together with the other cautionary statement included in our Annual Report on Form 10-K for the year ended December 31, 2025, subsequent Quarterly Reports on Form 10-Q and current reports on Form 8-K filed with the Securities and Exchange Commission. Any forward-looking statement speaks only as of the date on which it was initially made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, changed circumstances or otherwise, unless required by law.
Investor Contact: John Yi and Steven Shinmachi Gateway Group, Inc. 949-574-3860 [email protected]
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q2 results preview. We expect GDEV’s second-quarter results to reflect continued disciplined user acquisition spending and a focus on profitable growth. For context, Q1 revenue increased 2% to $99 million, while adjusted EBITDA increased 15% to $18 million, benefiting from a 13% decline in selling and marketing expense, as illustrated in Figure #1 Q1 Results. The return to top-line growth, following a revenue decline in fiscal 2025, is encouraging.
Facing a difficult revenue comparison. Q2 will lap a relatively strong year-ago quarter, when revenue increased 13% to $120 million, driven in part by elevated performance marketing investment. As such, we believe the more important read-through will be the company’s ability to sustain engagement and monetization while maintaining its more disciplined approach to marketing expenditures.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
PURCHASE, N.Y., Aug. 17, 2026 (GLOBE NEWSWIRE) — Townsquare Media, Inc. (NYSE: TSQ) (“Townsquare” or the “Company”), a leader in digital advertising and marketing solutions focused on markets outside of the Top 50 in the United States, announced today a strategic digital advertising partnership with Midlands Media Group, a Columbia, S.C.-based multimedia company with two radio stations, a digital news service, a digital ticketing provider, a discount certificate site, and a comprehensive digital advertising platform.
“Midlands Media Group has built a highly local portfolio of radio and digital news brands with engaged audiences and a strong market presence, making them an ideal partner for our digital platform and services,” said Shaun Collignon, CRO of Townsquare Ignite, the Company’s Digital Advertising division. “By combining their multi-channel reach with our proprietary technology, data-driven strategy, and execution expertise, we are well positioned to unlock new revenue opportunities and drive meaningful, measurable growth.”
In 2024, Townsquare launched its Media Partnerships division as part of Townsquare Ignite, its Digital Advertising segment, to bring its industry-leading digital solutions to other local media companies. The division provides a white-label service that allows partners to tap into the same data-driven strategies and proprietary technology that have powered Townsquare’s success, with digital now contributing more than half of the Company’s total revenue and profit.
This partnership with Midlands Media Group is one of 16 strategic alliances Townsquare has established under this initiative, collectively expanding the Company’s reach into 41 new markets beyond its owned and operated footprint, including those in the Top 50 markets. Townsquare will work closely with Midlands Media Group, which operates in the #90-ranked MSA in the United States, to deliver customized, data-driven advertising solutions tailored to local, regional, and national clients, helping to grow their digital business while enhancing the value of their trusted broadcast and multimedia platforms.
“This alliance reflects our continued commitment to helping leading local media companies to more fully monetize their audiences across platforms and deliver stronger results for their clients,” Collignon added.
“Midlands Media Group is very excited to partner with Townsquare Ignite to further expand our digital solutions capabilities. After extensive evaluation and industry experience, we believe Townsquare Ignite is best-in-class and fully committed to digital growth. Their team and technology position us to accelerate results for our clients across all platforms,” said Keith Stover, President & CEO of Midlands Media Group.
Marie Stover, Chief Operating Officer of Midlands Media Group, added: “Our unique focus is to super-serve the marketing needs of local businesses in our community. Adding Townsquare Ignite’s digital marketing component to our market-leading radio and news products positions us to deliver fully integrated campaigns that are authentic, high-impact, and measurable. We look forward to what this partnership will bring to our clients and communities.”
About Townsquare Media, Inc. Townsquare is a community-focused digital and broadcast media and digital marketing solutions company principally focused outside the top 50 markets in the U.S. Townsquare Ignite, our robust digital advertising division, specializes in helping businesses of all sizes connect with their target audience through data-driven, results based strategies, by utilizing a) our proprietary digital programmatic advertising technology stack with an in-house demand and data management platform and b) our owned and operated portfolio of more than 400 local news and entertainment websites and mobile apps along with a network of leading national music and entertainment brands, collecting valuable first party data. Townsquare Interactive, our subscription digital marketing services business, partners with SMBs to help manage their digital presence by providing a SAAS business management platform, website design, creation and hosting, search engine optimization and other digital services. And through our portfolio of local radio stations strategically situated outside the Top 50 markets in the United States, we provide effective advertising solutions for our clients and relevant local content for our audiences. For more information, please visit www.townsquaremedia.com, www.townsquareinteractive.com, and www.townsquareignite.com.
About Midlands Media Group Midlands Media Group is a Columbia, S.C.-based multimedia company and the only locally owned and operated media company in the Columbia market. The company connects local audiences and businesses through two radio stations, a digital news service, a digital ticketing provider, a discount certificate platform and a comprehensive suite of digital advertising solutions.
CULVER CITY, Calif., Aug. 14, 2026 (GLOBE NEWSWIRE) — Snail, Inc. (Nasdaq: SNAL) (“Snail Games” or the “Company”), a leading independent global developer and publisher of interactive digital entertainment, today highlighted several recent milestones across its gaming portfolio, including a newly released title, upcoming PixARK content, and continued development of the indie portfolio.
Stoneguard, developed by a two-person independent development team and published under the Wandering Wizard label, launched on Steam Early Access and has achieved a “Mostly Positive” rating from Steam users to date. The Early Access launch provides the development team with an opportunity to continue refining the game based on player feedback while expanding its content and features.
Wandering Wizard also released a new demo and trailer for Veil of Madness, providing players with an updated look at the upcoming first-person psychological horror deckbuilding game. The latest materials are intended to allow players to experience the game ahead of its full release later this year as development continues.
Alongside the new content for its indie label, Snail Games has released a new demo for Dead Party, a sequel to the title Dead Block. The new demo represents the latest development milestone and provides players with an early opportunity to experience the co-op party action game.
Snail Games has also announced the official release date for PixARK: Terracrypt, the voxel-based sandbox survival game’s first premium expansion, set to launch on Steam on August 26, 2026. As the largest expansion created for PixARK, Terracrypt will deliver more than 200 hours of gameplay, 80 new creatures, and 12 new biomes.
Snail Games intends to continue providing updates on its portfolio as projects progress toward additional releases, demonstrations, and milestones. With a robust slate of ARK content, alongside AAA and indie titles in development, the Company remains focused on executing against its pipeline through the second half of 2026.
About Snail, Inc. Snail, Inc. (Nasdaq: SNAL) is a leading global independent developer and publisher of interactive digital entertainment for consumers around the world, with a premier portfolio of premium games designed for use on a variety of platforms, including consoles, PCs, and mobile devices. For more information, please visit: https://snail.com/.
About Wandering Wizard Wandering Wizard is passionately committed to championing indie game developers. We provide a platform for fresh voices, revolutionary ideas, and daring experiments within the indie gaming realm. Embracing the inherent risks of indie game development, we partner with creators worldwide to enrich the global gaming community with inclusive, inspiring, and innovative gaming experiences. For more information, please visit: wanderingwizard.com.
Forward-Looking Statements: This press release contains statements that constitute forward-looking statements. Many of the forward-looking statements contained in this press release can be identified by the use of forward-looking words such as “anticipate,” “believe,” “could,” “expect,” “should,” “plan,” “intend,” “may,” “predict,” “continue,” “estimate” and “potential,” or the negative of these terms or other similar expressions. Forward-looking statements appear in a number of places in this press release and include, but are not limited to, statements regarding Snail’s intent, belief or current expectations. These forward-looking statements include information about possible or assumed future results of Snail’s business, financial condition, results of operations, liquidity, plans and objectives. The statements Snail makes regarding the following matters are forward-looking by their nature: the Early Access launch providing an opportunity to continue refining a game based on player feedback while expanding its content and features; the demo and trailer for Veil of Madness allowing players to experience the game ahead of its full release later this year as development continues; the Company’s continued exploration of artificial intelligence and interactive technologies; Snail Games’ intent to continue providing updates on its portfolio and its projects progressing toward additional releases, demonstrations, and milestones; and the Company’s efforts to become a world-class game developer and publisher with a diversified portfolio and a technological leader in the wide range of interactive entertainment space.
Any forward-looking statements included herein reflect our current views, and they involve certain risks and uncertainties, including, among others, acceptance of our titles in the marketplace and the successful development, marketing or sale of our titles and our ability to retain our key employees or maintain our Nasdaq listing. These risks should not be construed as exhaustive and should be read together with the other cautionary statement included in our Annual Report on Form 10-K for the year ended December 31, 2025, subsequent Quarterly Reports on Form 10-Q and current reports on Form 8-K filed with the Securities and Exchange Commission. Any forward-looking statement speaks only as of the date on which it was initially made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, changed circumstances or otherwise, unless required by law.
Investor Contact: John Yi and Steven Shinmachi Gateway Group, Inc. 949-574-3860 [email protected]
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q2 exceeded expectations. Revenue declined 6.5% year over year to $26.4 million, beating our estimate of $25.5 million by 3.5%. Additionally, adj. EBITDA of approximately $1.1 million compared favorably with our $0.1 million estimate. The beat reflected growth in blended digital revenue, which cushioned double-digit declines across the traditional broadcast business.
Digital continues to scale. Blended digital offering grew 60.8% during the quarter and was up 76.4% for the first 6 months of the year. Digital reached 19% of gross revenue in the first half compared with 14% a year ago. Management has brought search capabilities in-house with three dedicated specialists, hired and trained ten digital campaign managers, and migrated digital fulfillment to a new platform. In our view, the pace of blended digital growth is the most encouraging development in the quarter and the clearest evidence that the multi-year platform build is beginning to convert.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.