Junior Mining Consolidation Isn’t Coming. It’s Already Underway

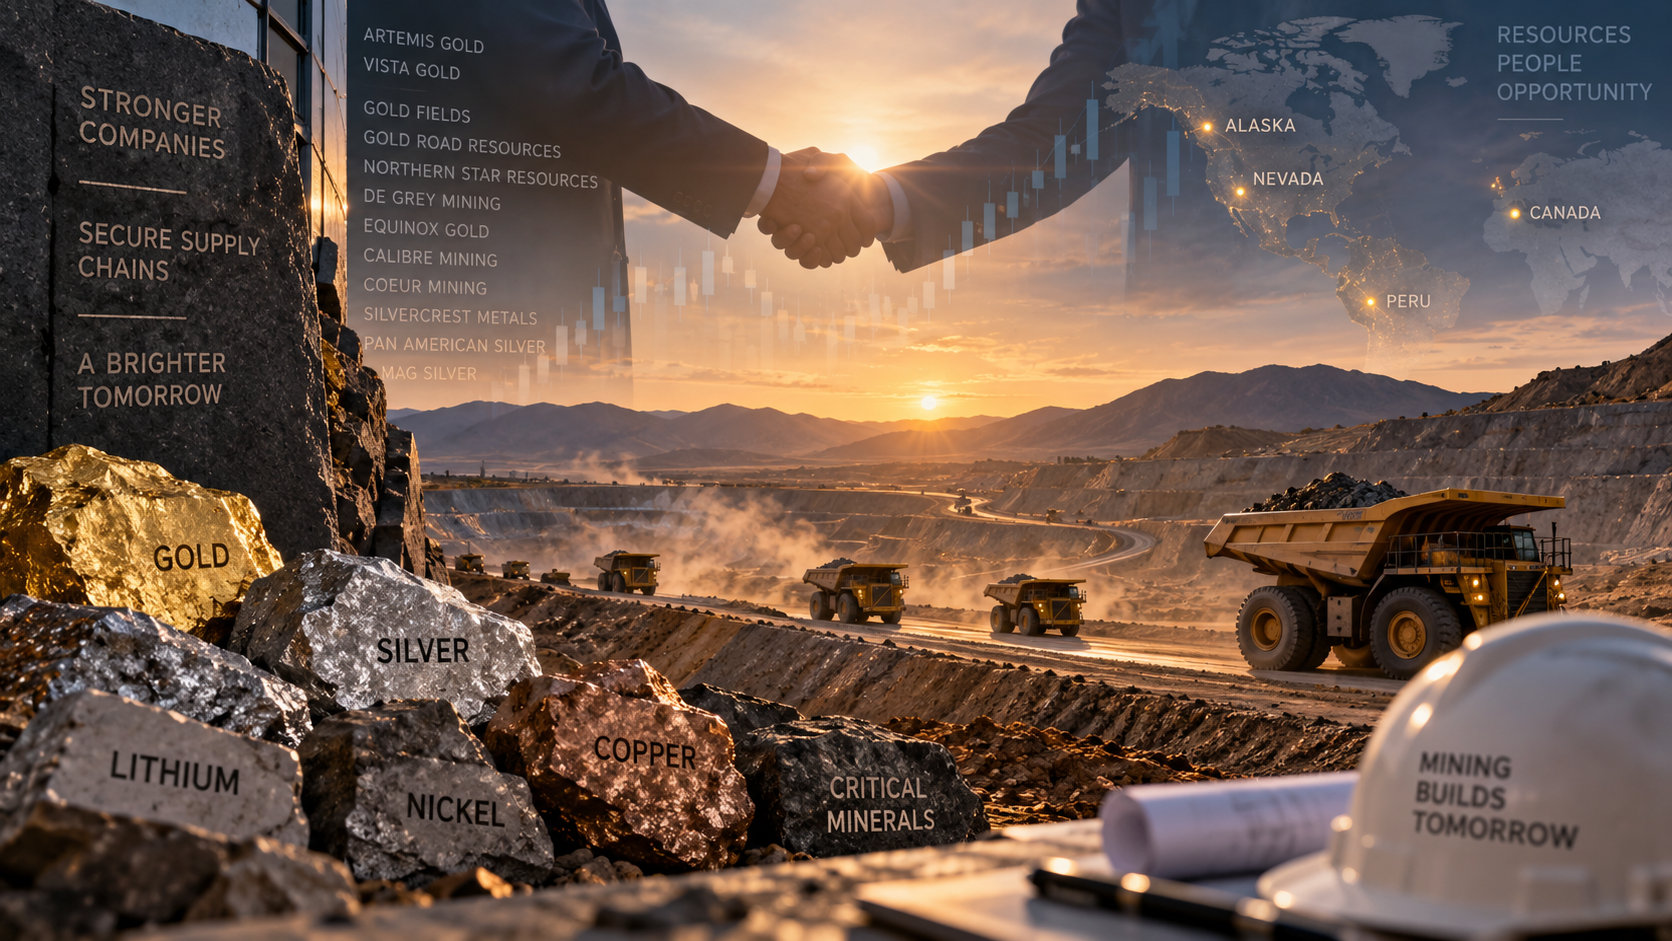
The Artemis Gold acquisition of Vista Gold we covered earlier this week wasn’t an isolated event. It was one data point in what industry data increasingly confirms is a genuine, extended wave of consolidation sweeping through the junior and intermediate mining sector, and the drivers behind it suggest this cycle has real staying power rather than representing a short-term spike.

The numbers tell a clear story. Global mining M&A totaled roughly $93.7 billion in completed deals during 2025, and gold and silver assets alone accounted for more than 77% of total deal volume in early 2026. The list of major transactions reads like a sector-wide roll-up already in progress, Gold Fields acquiring Gold Road Resources for approximately $2.4 billion, Northern Star Resources buying De Grey Mining for roughly $3.3 billion, Equinox Gold’s $2.8 billion purchase of Calibre Mining, Coeur Mining’s $1.7 billion acquisition of SilverCrest Metals, and Pan American Silver’s $2.1 billion takeover of MAG Silver. Mining stocks claimed a record 60% of the spots on this year’s TSX30, the annual ranking of Canada’s top-performing stocks, a genuinely striking signal of where investor capital has been flowing.

Three forces are converging to drive this cycle, and each appears structural rather than cyclical. First, reserve depletion. Major producers spent much of the 2010s underinvesting in exploration during a prolonged bear market, and many are now confronting genuinely thinning production pipelines that organic exploration alone cannot refill quickly enough. Acquiring juniors with already-defined, advanced-stage resources is simply faster than starting from scratch. Second, sustained strength in gold and silver prices has given larger producers the cash flow and equity currency to pursue acquisitions, while depressed valuations among smaller developers following years of underperformance have made those same juniors attractively priced targets. Third, and increasingly important, critical minerals supply security has become an explicit policy priority, with roughly a third of surveyed industry executives specifically expecting consolidation in this category as governments and producers alike race to secure supply chains independent of Chinese dominance, a theme we detailed closely when covering the Greenland security agreement earlier this year.

Industry analysts point to a fairly consistent profile among likely takeover targets, advanced-stage resources located in stable, Tier-1 mining jurisdictions, high-grade or district-scale potential, reasonable valuations following recent market corrections, and experienced management teams with a track record of either developing or successfully exiting projects.

That profile is worth keeping in mind when evaluating smaller companies in this space. Junior developers advancing resources in favorable jurisdictions such as Century Lithium, working a lithium project in Nevada, Kuya Silver, developing precious metals assets in Peru, Tectonic Metals, advancing gold exploration in Alaska, and Power Metallic Mines, exploring nickel and copper deposits in Quebec, all sit in exactly the category this consolidation wave has been targeting, smaller companies with defined, advanced-stage projects in stable jurisdictions that larger, cash-generative producers are actively seeking to acquire.

None of this guarantees any individual company becomes a takeover target, and early-stage mining developers carry substantial execution, financing, and geological risk regardless of broader sector M&A trends. But the structural case for continued consolidation, depleted major-producer pipelines, strong commodity prices, and mounting critical minerals policy pressure, looks considerably more durable than a passing trend.

Take a moment and take a look at more small cap mining companies by taking a look at Noble Capital Markets’ Analyst Mark Reichman’s coverage list.

Release – Phase II Clinical Trial of NV-387 as a Treatment for Monkeypox (MPox) Has Begun in DRC, Announces NanoViricides

Research News and Market Data on NNVC

Wednesday, 23 September 2026 08:30 AM

Topic: 

Company Update

SHELTON, CT / ACCESS Newswire / September 23, 2026 / NanoViricides, Inc. (NYSE American:NNVC) (the “Company”) today announced that the Phase II Clinical Trial of the Company’s Novel Broad-Spectrum Antiviral Drug NV-387 as a Treatment for Monkeypox Virus Infection has begun with enrollment of first patients in the Democratic Republic of Congo (DRC).

This clinical trial was registered in the Pan African Clinical Trials Registry database (pactr.samrc.ac.za). The unique identification number for this clinical trial is PACTR202609506749917.

The clinical trial is entitled: “An adaptive international, multi-center, randomized, open-label, interventional, parallel group, phase II (IIa and IIb) clinical trial to evaluate the efficacy and safety of a new chemical entity NV-387 formulated as oral gummies in comparison to standard of care, administered in patients with clinical signs of mpox disease and laboratory confirmed or presumptive hmpxv infection.”

The Principal Investigator for this clinical trial is Prof. Vivi Maketa Tevuzula, MD, MSc, PhD, Professor in the Department of Tropical Medicine at the University of Kinshasa and Principal Investigator at the Institut Multisectoriel pour l’Amélioration du Bien-être (IMABE), Kinshasa, DRC. Her work focuses on infectious diseases, including clinical trials demonstrating the safety and efficacy of novel drugs, and safety, immunogenicity, and efficacy of vaccines, as well as health systems research in resource-limited settings. She has served as principal investigator on multiple international studies on malaria, Mpox, and vaccine-preventable diseases, and leads interdisciplinary research on genomic surveillance and One Health approaches.

Bayer Foundation awarded Dr. Vivi Maketa with the prestigious Early Excellence in Science Award 2023 in Medical Science, recognizing her exceptional contributions to the design and implementation of research projects on infectious and neglected tropical diseases i.

“We are pleased to have Professor Maketa lead this clinical trial,” said Anil R. Diwan, PhD, President and Executive Chairman of the Company, adding, “This is the very first Phase II clinical trial of the broad-spectrum antiviral drug NV-387 and aims to explore its safety and effectiveness in Mpox.”

There is no approved drug for Mpox. Clinical trials of a drug called tecovirimat (TPOXX, SIGA) have previously failed to demonstrate efficacy against both Mpox Clade II and Mpox Clade I. Tecovirimat was approved by US FDA for Smallpox under the Animal Rule provision.

A pan-African clinical trial called “MOSA” of a drug called brincidofovir, which is approved by US FDA for Smallpox under the Animal Rule provision, that started in January, 2025, is currently ongoing. As of January 2026, according to a press release, this study’s Data Safety and Monitoring Board (DSMB) did not identify any new safety concern after the first 50 patients were randomized, and the trial plans to enrol a further 50 patients in the first half of 2026, to perform interim efficacy analysis of brincidofovir ii. Brincidofovir requires constant physician care due to dose-limiting liver and gastro-intestinal toxicity concerns iii.

NV-387 could become the “go to” pandemic response drug if it is successful in this Phase II MPox clinical trial, and becomes a FDA-licensed (approved) drug. US Government SNS stockpiling contracts for existing smallpox drugs TPOXX and TEMBEXA have been in several hundreds of millions of dollars, representing an equivalent potential opportunity for NV-387.

The Phase II clinical trial for NV-387 as a treatment of mpox is being conducted at Lodja in Sankuru province in DRC. As of now, this province is not an ebola-affected region.

Professor Maketa’s team is already on site in DRC. In addition, The team of our CRO from India, Om Sai Clinical Research Pvt. Ltd., is also on site in DRC to start the clinical trial.

Lodja is a remote location and mpox cases are continuing to occur in that area. This is a resource-poor region. Setting up the clinical sites required several months of effort because of the resource limitations at the hospital.

MPox Clade I is endemic in DRC and all cases in the clinical trial are expected to be of the Clade I virus. The other prominent MPox virus, MPox Clade II is substantially less severe an infection than MPox Clade I.

MPox Clade II has become endemic in the USA, circulating at low levels. It primarily affects a limited population of Men-having-Sex-with-Men (MSM), because of transmission during sexual activity.

MPox is an “Orphan Disease” in the USA. NanoViricides has applied to the US FDA for Orphan Drug Designation (ODD) of NV-387 for the treatment of MPox. This ODD, assuming it is granted, would enable several benefits including frequent meetings with FDA, waiver of certain FDA fees, certain R&D credits, as well as extension in exclusivity in marketing once approved.

These ODD benefits can have a positive economic impact for NanoViricides estimated in the range of tens of millions of dollars.

MPox Clade I cases in the USA have been slowly increasing. As of August 27, 2026, since November 2024, there have been more than 50 confirmed cases of Mpox Clade I in the USA, all of which were either travelers to Mpox-manifesting countries or regions, or contacts of such travelers, according to the CDC iv. Community spread of the MPXV Clade I is likely occurring, with 3 cases of MPox Clade I with no travel to Africa, in California in unconnected persons, according to the CDC v. However, the potential for a widespread outbreak remains low.

From 2023-2025, about 1,700-2,800 cases of Mpox Clade II were confirmed in the USA, mostly occurring in men-having-sex-with men and associated sexual partners, according to the CDC (ibid #4). Clade II is transmitted via skin abrasions.

Thus MPox is becoming important in the USA from the perspective of pandemic preparedness and response. Although there is a vaccine originally developed for smallpox, namely, Jynneos, that is in use to prevent MPox (primarily in clade II contacts), its immune protection was found to wane rapidly in a clinical study vi. The effectiveness of this vaccine is limited, at 36% for one dose and 66% for 2 doses against the less pathogenic MPox Clade II vii.

The vaccine effectiveness is likely to be much less against the more severe MPox Clade I.

Vaccines do not protect in the first few weeks, limiting their usefulness during pandemic.

We believe that there will be a strong opportunity for NV-387 for pandemic preparedness and response for the threats of Mpox and Smallpox in the USA if this Phase II clinical trial of NV-387 for the treatment of Mpox is successful. The two drugs in the USA Strategic National Stockpile (SNS), TPOXX and TEMBEXA, would be unsuitable for pandemic response if MPox Clade I spreads. Although both of these drugs are approved for Smallpox, a bioterrorism agent, under the FDA animal rule, the clinical trial failure of tecovirimat against Mpox which is a much less severe and far less lethal disease compared to Smallpox raises questions about its possible utility in a Smallpox bioterrorism event. In addition, the known toxicity profile and warnings for brincidofovir make it unsuitable for wide-scale deployment in a large outbreak scenario.

“NV-387, our broad-spectrum antiviral drug is poised to cause a revolution in treatment of viral diseases, just as antibiotics revolutionized the treatment of bacterial diseases,” said Anil R. Diwan, Ph.D., adding “NV-387 is designed to mimic human cells to trap and destroy the virus. This single drug can target over 90-95% of human pathogenic viruses due to this biomimicry, which is reminiscent of the antibiotic penicillin that targets a large number of human pathogenic bacteria.”

NV-387 was found to possess strong antiviral activity against an orthopoxvirus in an animal model that is considered an important model to establish potential effectiveness against MPox and Smallpox viruses, as all of these viruses belong to the same family of orthopoxviruses.

In fact, NV-387 effectiveness matched the effectiveness of the small chemical drug tecovirimat in two different models of infection, one was direct skin infection, and the other was a direct lung infection, by the virus.

Escape of virus from tecovirimat is known to occur by a single point mutation in a viral protein called VP-37.

Vaccines, antibodies, and small chemical drugs such as tecovirimat for MPox/Smallpox, or oseltamivir (Tamiflu®), baloxavir (Xofluza®) for Influenza are readily escaped by viruses simply by introduction of small changes that viruses undergo when they are faced with these challenges in the field.

In contrast, escape of virus from NV-387 is highly unlikely because no matter how much the virus changes in the field, it continues to use sulfated proteoglycans such as HSPG as “attachment receptor” in order to cause cell infection. NV-387 mimics the sulfated proteoglycan signature feature that the viruses require.

NV-387 is a host-mimetic drug that “looks like a cell” to the virus, displaying numerous ligands that mimic the sulfated proteoglycan, enticing the virus to bind to and become engulfed by the NV-387 dynamic shape-shifting polymeric micelle.

Therefore development of NV-387, a broad-spectrum host-mimetic, direct-acting antiviral drug that the viruses cannot escape even as they change constantly, will be revolutionary once the drug undergoes regulatory development for approval for use in humans.

New viruses and existing viruses acquiring greater pathology and infectivity are bound to keep appearing in time. To combat such threats, we need to develop broad-spectrum drug arsenal that the viruses cannot escape. Vaccines and antibodies simply will not do, and their limitations have become clearly evident during the COVID-19 pandemic.

About NanoViricides

NanoViricides, Inc. (the “Company”) (www.nanoviricides.com) is a clinical stage company that is creating special purpose nanomaterials for antiviral therapy. The Company’s novel nanoviricide™ class of drug candidates and the nanoviricide™ technology are based on intellectual property, technology and proprietary know-how of TheraCour Pharma, Inc. The Company has a Memorandum of Understanding with TheraCour for the development of drugs based on these technologies for all antiviral infections. The MoU does not include cancer and similar diseases that may have viral origin but require different kinds of treatments.

The Company has obtained broad, exclusive, sub-licensable, field licenses to drugs developed in several licensed fields from TheraCour Pharma, Inc. The Company’s business model is based on licensing technology from TheraCour Pharma Inc. for specific application verticals of specific viruses, as established at its foundation in 2005.

Our lead drug candidate is NV-387, a broad-spectrum antiviral drug that we plan to develop as a treatment of RSV, COVID, Long COVID, Influenza, and other respiratory viral infections, as well as MPOX/Smallpox infections. Our other advanced drug candidate is NV-HHV-1 for the treatment of Shingles. The Company cannot project an exact date for filing an IND for any of its drugs because of dependence on a number of external collaborators and consultants. The Company is currently focused on advancing NV-387 into Phase II human clinical trials.

NV-CoV-2 (API NV-387) is our nanoviricide drug candidate for COVID-19 that does not encapsulate remdesivir. NV-CoV-2-R is our other drug candidate for COVID-19 that is made up of NV-387 with remdesivir encapsulated within its polymeric micelles. The Company believes that since remdesivir is already US FDA approved, our drug candidate encapsulating remdesivir is likely to be an approvable drug, if safety is comparable. Remdesivir is developed by Gilead. The Company has developed both of its own drug candidates NV-CoV-2 and NV-CoV-2-R independently.

The Company is also developing drugs against a number of viral diseases including oral and genital Herpes, viral diseases of the eye including EKC and herpes keratitis, H1N1 swine flu, H5N1 bird flu, seasonal Influenza, HIV, Hepatitis C, Rabies, Dengue fever, and Ebola virus, among others. NanoViricides’ platform technology and programs are based on the TheraCour® nanomedicine technology of TheraCour, which TheraCour licenses from AllExcel. NanoViricides holds a worldwide exclusive perpetual license to this technology for several drugs with specific targeting mechanisms in perpetuity for the treatment of the following human viral diseases: Human Immunodeficiency Virus (HIV/AIDS), Hepatitis B Virus (HBV), Hepatitis C Virus (HCV), Rabies, Herpes Simplex Virus (HSV-1 and HSV-2), Varicella-Zoster Virus (VZV), Influenza and Asian Bird Flu Virus, Dengue viruses, Japanese Encephalitis virus, West Nile Virus, Ebola/Marburg viruses, and certain Coronaviruses. The Company intends to obtain a license for RSV, Poxviruses, and/or Enteroviruses if the initial research is successful. As is customary, the Company must state the risk factor that the path to typical drug development of any pharmaceutical product is extremely lengthy and requires substantial capital. As with any drug development efforts by any company, there can be no assurance at this time that any of the Company’s pharmaceutical candidates would show sufficient effectiveness and safety for human clinical development. Further, there can be no assurance at this time that successful results against coronavirus in our lab will lead to successful clinical trials or a successful pharmaceutical product.

This press release contains forward-looking statements that reflect the Company’s current expectation regarding future events. Actual events could differ materially and substantially from those projected herein and depend on a number of factors. Certain statements in this release, and other written or oral statements made by NanoViricides, Inc. are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. You should not place undue reliance on forward-looking statements since they involve known and unknown risks, uncertainties and other factors which are, in some cases, beyond the Company’s control and which could, and likely will, materially affect actual results, levels of activity, performance or achievements. The Company assumes no obligation to publicly update or revise these forward-looking statements for any reason, or to update the reasons actual results could differ materially from those anticipated in these forward-looking statements, even if new information becomes available in the future. Important factors that could cause actual results to differ materially from the company’s expectations include, but are not limited to, those factors that are disclosed under the heading “Risk Factors” and elsewhere in documents filed by the company from time to time with the United States Securities and Exchange Commission and other regulatory authorities. Although it is not possible to predict or identify all such factors, they may include the following: demonstration and proof of principle in preclinical trials that a nanoviricide is safe and effective; successful development of our product candidates; our ability to seek and obtain regulatory approvals, including with respect to the indications we are seeking; the successful commercialization of our product candidates; and market acceptance of our products.

The phrases “safety”, “effectiveness” and equivalent phrases as used in this press release refer to research findings including clinical trials as the customary research usage and do not indicate evaluation of safety or effectiveness by the US FDA.

Where stated with an ® , the name is a registered trademark, which belongs to the owner of the trademark name.

FDA refers to US Food and Drug Administration. IND application refers to “Investigational New Drug” application. cGMP refers to current Good Manufacturing Practices. CMC refers to “Chemistry, Manufacture, and Controls”. CHMP refers to the Committee for Medicinal Products for Human Use, which is the European Medicines Agency’s (EMA) committee responsible for human medicines. API stands for “Active Pharmaceutical Ingredient”. WHO is the World Health Organization. R&D refers to Research and Development.

Contact:
NanoViricides, Inc.
[email protected]

Public Relations Contact:
[email protected]

i https://www.bayer-foundation.com/lets-spotlight-our-science-talents-dr-vivi-maketa

ii https://mpx-response.eu/a-first-safety-interim-analysis-of-mosa-shows-no-signal-of-safety-concerns-with-brincidofovir-a-potential-antiviral-to-fight-mpox/

iii According to the drug label (prescribing information), brincidofovir (“TEMBEXA”) carries a black box warning, and has warnings for elevations in hepatic transaminases and bilirubin (liver toxicity) and diarrhea and other gastrointestinal adverse events. Brincidofovir administration must be performed under physician care with continuous evaluation of liver toxicity.

iv https://www.cdc.gov/monkeypox/situation-summary/index.html

v https://www.aha.org/news/headline/2025-10-29-cdc-says-3-cases-severe-mpox-california-may-be-linked-august-case

vi https://www.cidrap.umn.edu/mpox/amid-new-mpox-outbreak-study-suggests-waning-protection-jynneos-vaccine

vii From the Mpox Emergency Response Team, CDC (2023-05) “Vaccine Effectiveness of JYNNEOS against Mpox Disease in the United States,” N Engl J Med 2023;388:2434-43.

SOURCE: NanoViricides
Release – MAIA Biotechnology Expands Pivotal Phase 3 THIO-104 Non-Small Cell Lung Cancer Trial into Spain and Portugal

Primary Logo

Research News and Market Data on MAIA

September 23, 2026 9:17am EDT Download as PDF

THIO-104 advances toward key 2027 interim survival analysis

CHICAGO, Sept. 23, 2026 (GLOBE NEWSWIRE) — MAIA Biotechnology, Inc. (NYSE American: MAIA) (“MAIA”, the “Company”), a clinical-stage biopharmaceutical company focused on developing immunotherapies for cancer, today announced that it has received regulatory approval by the Spanish Agency for Medicines and Medical Devices (AEMPS) and Portugal’s National Authority of Medicines and Health Products (INFARMED) to begin screening patients for its ongoing pivotal Phase 3 THIO-104 clinical trial in non-small cell lung cancer (NSCLC).

Spain and Portugal represent important European markets for NSCLC, with an estimated 30,000 new cases annually across the two countries. Spain has a substantial lung cancer burden associated with historical tobacco exposure, with lung cancer incidence among women continuing to rise. In Portugal, NSCLC accounts for approximately 82% of lung cancer cases, the highest proportion reported among five European populations evaluated in a comparative study.

“Expanding THIO-104 into Spain and Portugal represents another important step in the execution of our pivotal Phase 3 program,” said Vlad Vitoc, M.D., Chairman and Chief Executive Officer of MAIA. “Clinical trial participation can provide patients with access to investigational therapies in markets where access to newly approved lung cancer treatments has historically lagged. By establishing THIO-104 sites in Spain and Portugal, we are broadening access to a potentially important new treatment option for patients with advanced NSCLC who have progressed following standard of care treatments.”

To date, THIO-104 has enrolled 65 NSCLC patients resistant to chemotherapy and checkpoint inhibitor treatments at 28 clinical sites in 6 European countries and 10 sites in Taiwan. Among the six European countries, sites in Hungary, Poland, and Turkey are actively enrolling and dosing patients from populations with the highest lung cancer incidence and mortality rates in Europe and globally.1

MAIA targets 100 patients dosed in THIO-104 by year-end 2026 and expects to have sufficient survival data to conduct an interim data analysis in 2027.

About Ateganosine

Ateganosine (THIO, 6-thio-dG or 6-thio-2’-deoxyguanosine) is a first-in-class investigational telomere-targeting agent currently in clinical development to evaluate its activity in non-small cell lung cancer (NSCLC). Telomeres, along with the enzyme telomerase, play a fundamental role in the survival of cancer cells and their resistance to current therapies. The modified nucleotide 6-thio-2’-deoxyguanosine induces telomerase-dependent telomeric DNA modification, DNA damage responses, and selective cancer cell death. Ateganosine-damaged telomeric fragments accumulate in cytosolic micronuclei and activates both innate (cGAS/STING) and adaptive (T-cell) immune responses. The sequential treatment of ateganosine followed by PD-(L)1 inhibitors resulted in profound and persistent tumor regression in advanced, in vivo cancer models by induction of cancer type–specific immune memory. Ateganosine is presently developed as a second or later line of treatment for NSCLC for patients that have progressed beyond the standard-of-care regimen of existing checkpoint inhibitors.

About MAIA Biotechnology, Inc.

MAIA is a targeted therapy, immuno-oncology company focused on the development and commercialization of potential first-in-class drugs with novel mechanisms of action that are intended to meaningfully improve and extend the lives of people with cancer. Our lead program is ateganosine (THIO), a potential first-in-class cancer telomere targeting agent in clinical development for the treatment of NSCLC patients with telomerase-positive cancer cells. For more information, please visit www.maiabiotech.com.

Forward Looking Statements

MAIA cautions that all statements, other than statements of historical facts contained in this press release, are forward-looking statements. Forward-looking statements are subject to known and unknown risks, uncertainties, and other factors that may cause our or our industry’s actual results, levels or activity, performance or achievements to be materially different from those anticipated by such statements. The use of words such as “may,” “might,” “will,” “should,” “could,” “expect,” “plan,” “anticipate,” “believe,” “estimate,” “project,” “intend,” “future,” “potential,” or “continue,” and other similar expressions are intended to identify forward looking statements. However, the absence of these words does not mean that statements are not forward-looking. For example, all statements we make regarding (i) the initiation, timing, cost, progress and results of our preclinical and clinical studies and our research and development programs, (ii) our ability to advance product candidates into, and successfully complete, clinical studies, (iii) the timing or likelihood of regulatory filings and approvals, (iv) our ability to develop, manufacture and commercialize our product candidates and to improve the manufacturing process, (v) the rate and degree of market acceptance of our product candidates, (vi) the size and growth potential of the markets for our product candidates and our ability to serve those markets, and (vii) our expectations regarding our ability to obtain and maintain intellectual property protection for our product candidates, are forward looking. All forward-looking statements are based on current estimates, assumptions and expectations by our management that, although we believe to be reasonable, are inherently uncertain. Any forward-looking statement expressing an expectation or belief as to future events is expressed in good faith and believed to be reasonable at the time such forward-looking statement is made. However, these statements are not guarantees of future events and are subject to risks and uncertainties and other factors beyond our control that may cause actual results to differ materially from those expressed in any forward-looking statement. Any forward-looking statement speaks only as of the date on which it was made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events or otherwise, except as required by law. In this release, unless the context requires otherwise, “MAIA,” “Company,” “we,” “our,” and “us” refers to MAIA Biotechnology, Inc. and its subsidiaries.

Investor Relations Contact
+1 (872) 270-3518
[email protected]


1 Sources: Global Cancer Observatory (GLOBOCAN), European Cancer Information System (ECIS), World Cancer Research Fund

Primary Logo

Source: MAIA Biotechnology, Inc.

Released September 23, 2026

Release – Xerox Announces Major Production Print Portfolio Expansion at PRINTING United Expo 2026

Xerox

Research News and Market Data on XRX

PDF Version

September 23, 2026

LAS VEGAS–(BUSINESS WIRE)–Sep. 23, 2026– Xerox Holdings Corporation (NASDAQ: XRX) today announced a major production print portfolio expansion as part of PRINTING United Expo 2026, introducing three new press platforms and enhancements to existing presses.

With these introductions, Xerox is deepening its commitment to production print with an inkjet portfolio spanning cut-sheet and continuous-feed, alongside a new 6-color flagship press for graphic arts. Integrated with the Xerox end-to-end production ecosystem of presses, workflow automation software, media expertise and lifecycle services, the new offerings extend specialty color and intelligent automation capabilities across the broader portfolio, helping print providers bring more work in-house, streamline production and pursue new revenue opportunities.

“PRINTING United is the ideal stage to show how Xerox is driving the future of production print,” said Terry Antinora, President, Global Production Print Services at Xerox. “We’re giving print providers a complete inkjet portfolio, embellishment, intelligent automation, and AI-powered tools that help them grow, differentiate, and win. Everything we’re launching is designed to improve customer profitability — not just increase print volume.”

Attendees can explore the following additions to the Xerox production print portfolio:

  • Xerox® Proficio™ Jet CS1100: A B3 cut-sheet inkjet press that delivers speeds of up to 300 images per minute. New Xerox-developed printheads and a high-definition ink formulation deliver 1200 × 1200 dots per inch resolution with 2-bit variable-drop imaging for precise dot placement. A scalable drying architecture supports media up to 350 grams per square meter, including coated stocks. The platform enables print providers to shift a wider range of work, from transactional and direct mail to graphic communications and commercial print, onto a single press without compromising quality.
  • Xerox® Proficio™ Jet CF1200: An industrial continuous-feed inkjet press that delivers speeds of up to 525 feet per minute at 1200 dpi within a compact 28-foot footprint. The smallest 20-inch press in its class handles between 4 million and 30 million Letter / A4 impressions per month, helping high-volume print providers increase capacity, operate more efficiently and protect margins.
  • Xerox® Proficio™ PX700 FLX: A new graphic arts production press that delivers speeds of up to 120 pages per minute and supports up to six colors inline at rated speed. New Fluorescent Green specialty toner further expands the color gamut and improves RGB accuracy when paired with Fluorescent Pink. Intelligent automation helps reduce operator intervention and improve consistency, enabling print providers to create differentiated, high-value applications.
  • Xerox® Proficio™ PX300 and PX500 feature updates: Enhanced with new Beyond CMYK and fifth-color options, including Gold, Silver and White, the Proficio PX300 and Proficio PX500 expand opportunities for metallic effects and printing on dark and transparent media. The Proficio PX300 now also features the Xerox® PredictPrint Media Manager, which uses AI-assisted cloud intelligence to simplify media setup and optimize color stability.

At PRINTING United, Xerox will host demonstrations and discussions on generative AI for specialty print, workflow analytics and automation through Xerox® FreeFlow® Core and Xerox® FreeFlow® Vision Connect Software, and generative AI, along with business development resources available through the Genesis Initiative. The Xerox Genesis Initiative helps creative teams maximize the value of Beyond CMYK technologies through specialty inks and embellishments, and application development resources.

To learn more, visit Xerox at PRINTING United booth #N6729 or explore the company’s production print portfolio at Xerox.com.

About Xerox Holdings Corporation (NASDAQ: XRX)

Xerox is a global technology company with more than 120 years of innovation leadership. We design, manufacture, deliver, and support print, IT, and digital services for nearly 200,000 clients worldwide. Our integrated, AI-powered portfolio includes managed and production print, document management, workflow automation, cybersecurity, cloud managed services, IT infrastructure and collaboration technology. Serving clients from growing SMBs to 90 percent of the Fortune 500, Xerox supports leading healthcare, government, financial services, education, legal, retail and commercial organizations. Through direct sales and a global network of channel partners, we deliver the technology, expertise, and support organizations need to operate efficiently, securely and at scale.

Note: To receive RSS news feeds, visit www.news.xerox.com. For open commentary, industry perspectives and views, visit www.linkedin.com/company/xerox or www.youtube.com/XeroxCorp.

View source version on businesswire.com: https://www.businesswire.com/news/home/20260923599586/en/

Media Contact
Justin Capella, Xerox, [email protected]

Source: Xerox Holdings Corporation

Release – NN, Inc. Raises Full-Year 2026 Guidance Ranges for Net Sales and Adjusted EBITDA

Primary Logo

Research News and Market Data on NNBR

PDF Version

CHARLOTTE, N.C., Sept. 22, 2026 (GLOBE NEWSWIRE) — NN, Inc. (NASDAQ: NNBR) a global leader in precision manufacturing, today announced that it is raising its full-year 2026 guidance ranges for Net Sales and Adjusted EBITDA.

Updated Full-Year 2026 Guidance

MetricPrior GuidanceUpdated Guidance
Net Sales$460 million – $480 million$470 million – $490 million
Adjusted EBITDA$55 million – $65 million$58 million – $68 million
   

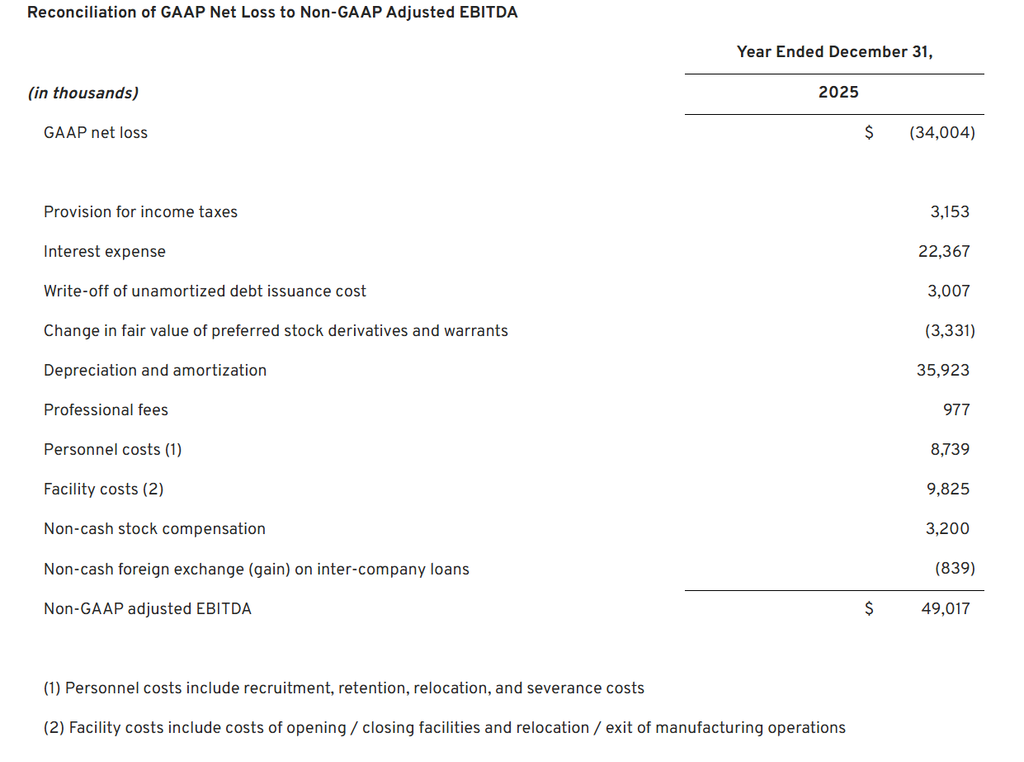
Management’s updated guidance for 2026 Net Sales at midpoint is $480 million, up $58 million, or 14% versus full-year 2025 Net Sales.

Management’s updated guidance for 2026 Adjusted EBITDA at midpoint is $63 million, up $14 million, or 29% versus full-year 2025 Adjusted EBITDA.

Chief Executive Officer Harold Bevis commented, “Our business continues to build momentum as we ramp up in our key growth markets of Data Center, Defense & Electronics, and Medical, where demand for our solutions remains strong and actively expanding. Our year-to-date results and year-to-go forecast underpin this improved guidance and reflect the steady performance our growth and cost programs.

NN is continuing to invest forward in its 5 Pillar growth end markets and this is translating to increased success and higher results. Raising our full-year 2026 guidance for net sales and adjusted EBITDA reflects our confidence in the performance of the business. We remain focused on our balanced plans for delivering profitable growth and improved cost productivity for our customers and shareholders.”

NN, Inc. will provide additional detail and updated guidance when it reports third quarter 2026 results on October 28, 2026.

About NN, Inc.
NN, Inc. (NASDAQ: NNBR) is an entrepreneurial manufacturing company specializing in manufacturing micron-toleranced precision metal componentry for high-growth end markets, especially Data Center, Electric Grid, Medical, Defense, and High-Value Vehicle systems. Founded in 1980, NN serves over 700 customers on 4 continents through its 2,550 person workforce operating out of 27 global plants. This footprint enables rapid innovation and global scaled solutions. For more information, visit nninc.com.

Forward Looking Statements
This press release may contain forward-looking statements regarding our business, operations, and financial performance. Such statements are based on current expectations and assumptions that are subject to a number of risks and uncertainties. Actual results could differ materially. Please refer to our most recently filed Form 10-K and our Form 10-Q for the period following that Form 10-K, including the risk factors described therein. We undertake no obligation to update any forward-looking statement, except as required by law. Given these risks and uncertainties, investors are cautioned not to place undue reliance on such forward-looking statements.

This press release contains certain financial measures not presented in accordance with U.S. generally accepted accounting principles (“GAAP”) such as adjusted EBITDA (the “non-GAAP financial measures”). These non-GAAP financial measures are not calculated in accordance with GAAP and should not be considered in isolation from, or as a substitute for, the most directly comparable GAAP measures, and may not be comparable to similarly titled measures used by other companies. Management uses these non-GAAP financial measures, together with the comparable GAAP measures, to evaluate the Company’s operating performance and underlying business trends across periods on a consistent basis, and to assist in operational and financial decision-making, including with respect to internal budgeting and resource allocation. Reconciliations of each non-GAAP financial measure to its most directly comparable GAAP measure are set forth in the tables accompanying this presentation. A reconciliation of forward-looking non-GAAP financial measures to the most directly comparable GAAP measures is not provided because the Company cannot reasonably predict certain items necessary for such reconciliation without unreasonable efforts.

Investor Relations: 
Joe Caminiti
[email protected]  
312-445-2870 

Oil Just Fell to a Two-Week Low. Saudi Arabia and Iraq Are Quietly Rerouting Around the Strait of Hormuz

Oil prices extended a six-session decline Wednesday, with Brent crude falling to $98.16 a barrel and West Texas Intermediate dropping to $89.01, both settling at roughly two-week lows. Brent closed below $100 a barrel Tuesday for the first time since September 8, a notable reversal after weeks of escalation-driven price spikes that we’ve tracked closely throughout this conflict.

Two forces are driving the decline, and both matter for understanding where oil heads next. The first is diplomatic. President Trump warned Tuesday that the US could take severe action against Iran, while simultaneously saying his envoys had held productive talks with Iranian mediators in New York and describing real momentum toward reaching a deal to end the nearly seven-month war. Markets appear to be choosing to price in the possibility of talks succeeding, even amid continued tough rhetoric on both sides.

The second, more concrete factor is supply, and it’s arguably the more important development. Saudi Arabia restarted its East-West Pipeline to the Red Sea on Tuesday, a route that reroutes roughly 4 million barrels per day, about 4% of global oil supply, around the Strait of Hormuz entirely. The pipeline had been shut since September 11 following drone attacks Saudi Arabia has blamed on Iraqi militia forces. Saudi Arabia is also now offering additional barrels to Asian refiners for pickup outside the strait altogether. Iraq is following a similar playbook, with its oil minister confirming exports have climbed above 3 million barrels per day and stating the country expects to boost shipments routed through Turkey to more than 600,000 barrels per day. Shiptracking data shows Iraqi exports climbing in August from July’s levels, though they still remain below the roughly 3.4 to 3.7 million barrel per day pace seen before the war began.

Adding further downward pressure, industry data released Tuesday showed US crude inventories rose by 1.8 million barrels last week, catching analysts off guard, who had broadly expected a decline.

For investors tracking the small and microcap space, this shift is worth watching closely, and it cuts in the opposite direction from what we detailed when covering diesel’s all-time high and the broader oil surge earlier this month. Consumer-facing companies in transportation, logistics, and hospitality, squeezed hard by the run-up in fuel costs, stand to benefit if this decline holds and extends toward the pump, a group that includes companies like Commercial Vehicle Group, a supplier to the trucking industry, and The ONE Group Hospitality, a restaurant operator directly exposed to consumer discretionary spending. Domestic energy producers, conversely, face renewed margin pressure as prices retreat from the highs that supported their economics all summer, a dynamic worth watching for companies like InPlay Oil and Alliance Resource Partners. Whether this reversal proves durable likely depends on whether the diplomatic momentum Trump described translates into an actual agreement, or whether these alternative supply routes simply prove temporary workarounds to a conflict still very much unresolved.

Eledon Pharmaceuticals (ELDN) – Tegoprubart Extension Study Maintains Improvement Over Tacrolimus


Wednesday, September 23, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Long-Term Data Updated At Transplant Conference. Eledon presented an update to the Phase 2 BESTOW Extension study at the International Congress of The Transplantation Society. Analysis up to 24 months after transplantation showed that patients treated with tegoprubart had statistically significant improvements in kidney function compared with patients treated with tacrolimus. Separately, tegoprubart has also received Fast Track designation from the FDA in the kidney transplant indication.

Updated Extension Study Data. Patients completing the BESTOW trial were entered into an Extension Stage to follow outcomes after the trial period ended. At 18, 21, and 24 months, tegoprubart patients had a higher eGFR of about 71 mL/min/1.73m2 compared with 58 mL/min/1.73m2 for tacrolimus, with differences that were statistically significant. Tegoprubart patients showed a continued improvement in eGFR after the trial, while tacrolimus patients showed a gradual but steady decline.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Century Lithium Corp. (CYDVF) – Advancing Plans for a Stand-Alone Merchant Chlor-Alkali Plant


Wednesday, September 23, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Advancing a merchant chlor-alkali plant. Century Lithium plans to develop a commercial-scale chlor-alkali plant in the Western United States that would produce chlorine, hydrochloric acid, and sodium hydroxide from sodium chloride, water, and electricity. The plant is expected to initially produce at a rate of 300 short tons per day (st/d) of chlorine, with potential expansion to 600 st/d depending on regional demand and the supply needs of Angel Island.

Early offtake interest provides commercial support. Century has signed eight non-binding Memorandums of Understanding (MOUs) that could collectively fully utilize the plant’s initial production, while discussions with additional customers are ongoing. The company is evaluating sites in Nevada and Utah based on power, feedstock, rail access, permitting, and proximity to customers, with final site selection expected following completion of due diligence.

Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Noble Capital Markets Emerging Growth Virtual Equity Conference – October 2026 – Presenting Companies

October 1 Schedule

All times Eastern

11:30am – Kodiak Copper (KDKCF)
12:30pm – Gevo (GEVO)

October 2 Schedule

All times Eastern

9:00am – Kaltura (KLTR)
9:30am – Idaho Copper (COPR)

Participating in 1×1 Meetings Only

Nvidia’s Stock Got Cheaper While Its Business Got Stronger

Here’s a genuinely strange fact about the world’s most valuable company. Nvidia shares are trading at less than 17 times expected profit over the next 12 months, the cheapest valuation the stock has carried in more than a decade. That multiple is roughly half what Nvidia commanded in 2025, when its revenue and profit growth were actually slower than they are now, and it’s down sharply from more than 25 times earnings estimates as recently as May.

Normally, a stock getting cheaper while its fundamentals get stronger would be viewed as an obvious buying opportunity. What makes this situation genuinely worth examining is that the market appears to be sending a very specific signal, expressing real skepticism about whether Nvidia’s current earnings power is sustainable, even as the numbers themselves remain extraordinary. Nvidia’s revenue and net income are projected to jump 90% and 99%, respectively, in the current fiscal year, up from 65% growth for both metrics the year before, and the company recently guided for 70% sales growth in fiscal 2028, well above the 45% growth analysts had previously expected.

The disconnect gets stranger when you compare Nvidia to its own sector. Nvidia shares are up 22% in 2026, the second-best performance among the Magnificent Seven behind only Apple. That sounds strong until you look at the rest of the semiconductor industry, which is up nearly 76% this year. Rivals Intel and AMD have each gained more than 180%, and memory chipmaker Micron has led the pack. Nvidia currently ranks as the fifth-worst performer within its own sector index, which as a whole trades at roughly 20 times estimated profit, still cheaper than Nvidia carried a year ago, but meaningfully richer than where Nvidia sits today. Nvidia’s CEO addressed this tension directly at a recent industry conference, describing the company as what he called the world’s first and only growth value stock, arguing it is simultaneously growing rapidly and becoming more undervalued at the same time, a combination he characterized as widely misunderstood by the market.
Part of what’s weighing on the valuation is margin pressure. Nvidia posted a 75% gross margin last quarter, but that figure is projected to shrink to below 72% in the fourth quarter before recovering, driven largely by rising costs for components like memory chips. There’s also a competitive undercurrent building. Several of Nvidia’s largest customers, including Meta and Alphabet, have been developing their own AI chips in-house, and as more hyperscalers pursue that path, some market strategists expect Nvidia’s dominant market position to erode gradually over time, which would put continued pressure on margins rather than allow them to recover.

Not everyone reads the setup as bearish, however. Other market observers argue the more relevant question is what would actually need to happen for Nvidia’s current valuation to be justified, either a meaningful pullback in hyperscaler AI spending or a regulatory shift that slows AI development materially, and neither scenario currently looks likely. Under that view, a stock priced as though slower growth is already baked in, while actual demand signals continue pointing higher, represents a favorable entry point rather than a warning sign.

For investors tracking the broader AI infrastructure and semiconductor supply chain, this divergence between Nvidia and its smaller, faster-moving peers is worth watching closely, a topic we’ve followed since the earlier days of the sector’s AI-driven repricing. Smaller companies supplying components, materials, and specialized hardware into this same ecosystem are, in effect, operating in a market where investors are actively debating whether the dominant player’s premium is deserved or overextended, a debate whose outcome will likely ripple through valuations across the entire chip supply chain, not just Nvidia’s own stock.

The AI Jobs Debate Is More Complicated Than It Looks

The early success of Meta’s Muse AI agent has reignited a question that has been building all year: if AI tools can perform tasks inside a company quickly and cheaply, how much longer do companies keep paying humans to do the same work? Apollo Global Management’s chief economist addressed that tension directly in a recent interview, suggesting the labor market impact of tools like Muse is still a waiting game, one where the full effect simply hasn’t shown up in the data yet.

The case for concern is real and growing. Block, the payments company led by Jack Dorsey, cut 40% of its staff this year. Layoffs have swept through Amazon, Dell, Oracle, Coinbase, Cloudflare, and Meta itself, several of which we’ve tracked closely as part of the broader corporate efficiency wave reshaping how companies think about headcount in the AI era. Uber recently announced it would cut 10% of its workforce to capture what it described as significant efficiencies. These are not struggling companies making defensive cuts, they are profitable, growing businesses choosing to operate with fewer people even as they invest heavily in AI capability, a pattern that has now repeated across enough companies to look structural rather than coincidental.

Staffing and workforce advisory firms sit closest to this shift and are worth watching as a real-time indicator of how it plays out. Companies like Kelly Services and Resources Connection, both providers of staffing and flexible workforce solutions, along with Information Services Group, which advises corporations on technology sourcing and digital transformation decisions, are positioned to see these dynamics well before they show up in national jobs data. If companies are genuinely substituting AI for headcount at scale, these firms would likely see it first in shifting client demand for permanent placements versus flexible or project-based talent.

But the labor market data complicates the doom-and-gloom narrative considerably. Through August, the US economy added roughly 640,000 net nonfarm payroll jobs, averaging about 80,000 new positions per month, numbers that don’t reflect a labor market in collapse. Apollo’s economist made a useful distinction on this point, noting that while tools like Muse will genuinely eliminate some jobs, the new products and business activity AI enables will also create employment elsewhere, meaning this isn’t simply a displacement story, it’s a broader story about how AI reshapes business dynamics and, ultimately, aggregate employment in ways that cut in both directions simultaneously.

There’s an added wrinkle worth watching closely. A recent Gartner survey projects that by 2029, roughly 30% of employees laid off due to AI will need to be rehired, at meaningfully higher cost than their original positions carried. That’s a notable admission that some of this year’s efficiency-driven cuts may prove to be overcorrections, companies discovering that certain roles genuinely required human judgment or oversight AI couldn’t fully replace, and having to pay a premium to bring that expertise back.

For investors, this debate is no longer background noise, it’s showing up directly in the data that moves markets. Monthly jobs reports, which we’ve covered closely as they’ve swung between blowout beats and unexpected losses this year, are taking on greater weight precisely because AI-driven labor market shifts are becoming a genuine wildcard in how those numbers get interpreted. For companies in the small and microcap space, this dynamic cuts two ways worth watching. Smaller companies with leaner existing headcount may be structurally better positioned to adopt AI efficiently without the large-scale layoffs playing out at bigger firms, while companies specifically building AI tools, agents, and workflow automation software for business customers sit squarely in the path of demand created by this exact shift. Whether AI ultimately proves to be a net job destroyer or a net job reshuffler remains genuinely unresolved, and that uncertainty itself is becoming a market-moving variable heading into the final months of the year.

Release – Nutriband Confirms Warrants Will Expire September 30 Without Extension or Repricing

Nutriband-logo

Research News and Market Data on NTRB

GlobeNewswire

Tuesday, September 22, 2026, 8:00:00 AM EDT

ORLANDO, Fla., Sept. 22, 2026 (GLOBE NEWSWIRE) — Nutriband Inc. (NASDAQ:NTRB) (NASDAQ:NTRBW) confirmed today that its outstanding warrants (NASDAQ:NTRBW) will expire on September 30, 2026 at 5PM ET as scheduled. The Company will not extend the expiration date and will not reprice the warrants.

Warrant holders may exercise at the current strike price of $6.43 per share until the expiration date. Warrants not exercised by that date will expire in their entirety and be removed from the NTRBW Nasdaq listing.

There are currently 910,904 warrants outstanding, representing $5,856,112 in potential proceeds to the Company if fully exercised at the $6.43 strike price.

Key dates and terms:

  • Expiration date: September 30, 20265PM ET
  • Strike price: $6.43 per warrant
  • Warrants outstanding: 910,904
  • No extension. No repricing.

Shareholders and warrant holders are advised to act before the deadline if they intend to exercise. Nutriband will continue to provide updates on Company developments in the coming weeks.

About Nutriband Inc.

We are primarily engaged in the development of a portfolio of transdermal pharmaceutical products. Our lead product under development is an abuse deterrent fentanyl patch incorporating our AVERSA™ abuse deterrence technology. AVERSA™ technology can be incorporated into any transdermal patch to prevent the abuse, misuse, diversion, and accidental exposure of drugs with abuse potential.

The Company’s website is www.nutriband.com. Any material contained in or derived from the Company’s websites or any other website is not part of this press release.

Forward-Looking Statements

Certain statements contained in this press release, including, without limitation, statements containing the words “believes,” “anticipates,” “expects” and words of similar import, constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Such forward-looking statements involve both known and unknown risks and uncertainties. The Company’s actual results may differ materially from those anticipated in its forward-looking statements as a result of a number of factors, including those including the Company’s ability to develop its proposed abuse-deterrent fentanyl transdermal system and other proposed products, its ability to obtain patent protection for its abuse technology, its ability to obtain the necessary financing to develop products and conduct the necessary clinical testing, its ability to obtain Federal Food and Drug Administration approval to market any product it may develop in the United States and to obtain any other regulatory approval necessary to market any product in other countries, including countries in Europe, its ability to market any product it may develop, its ability to create, sustain, manage or forecast its growth; its ability to attract and retain key personnel; changes in the Company’s business strategy or development plans; competition; business disruptions; adverse publicity and international, national and local general economic and market conditions and risks generally associated with an undercapitalized developing company, as well as the risks contained under “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” in the Company’s periodic and current reports on Form 10-K, Forms 10-Q and 8-K and the Company’s other filings with the Securities and Exchange Commission. Except as required by applicable law, we undertake no obligation to revise or update any forward-looking statements to reflect any event or circumstance that may arise after the date hereof.

Contact Information:
Nutriband Inc.
Phone: 407-377-6695
Email: [email protected]

Source: Nutriband Inc.

© 2026 GlobeNewswire, Inc.

Release – Power Metallic Extends Lion 25% Deeper as Power Metallic Intercepts 5.70 Meters of 14.00% CuEqRec¹ in Hole 26-125

Research News and Market Data on PNPF

Sep 22, 2026

TORONTO, Sept. 22, 2026 – Power Metallic Mines Inc. (the “Company” or “Power Metallic”) (TSXV: PNPN) (OTCBB: PNPNF) (Frankfurt: IVV1) is pleased to provide the first assays of extensional deep drilling of assay results from its Summer 2026 drill program. Prior to the summer drill program drilling concentrated on improving the density of drill intercepts for the recently announced MRE to increase the confidence of modelling Lion, particularly within the range of a potential future open pit, and to bring the vast majority of the known deposit as of the end of the winter program (end April 2026) to Drill Indicated category.

For the summer drill program Power Metallic has carried out widely spaced exploration drilling on geological and geophysical (EM) targets and more importantly begun a program of extending the Lion deposit to depth below the outline of the MRE model. The two holes reported here are the first assays to be completed on this deep drilling.

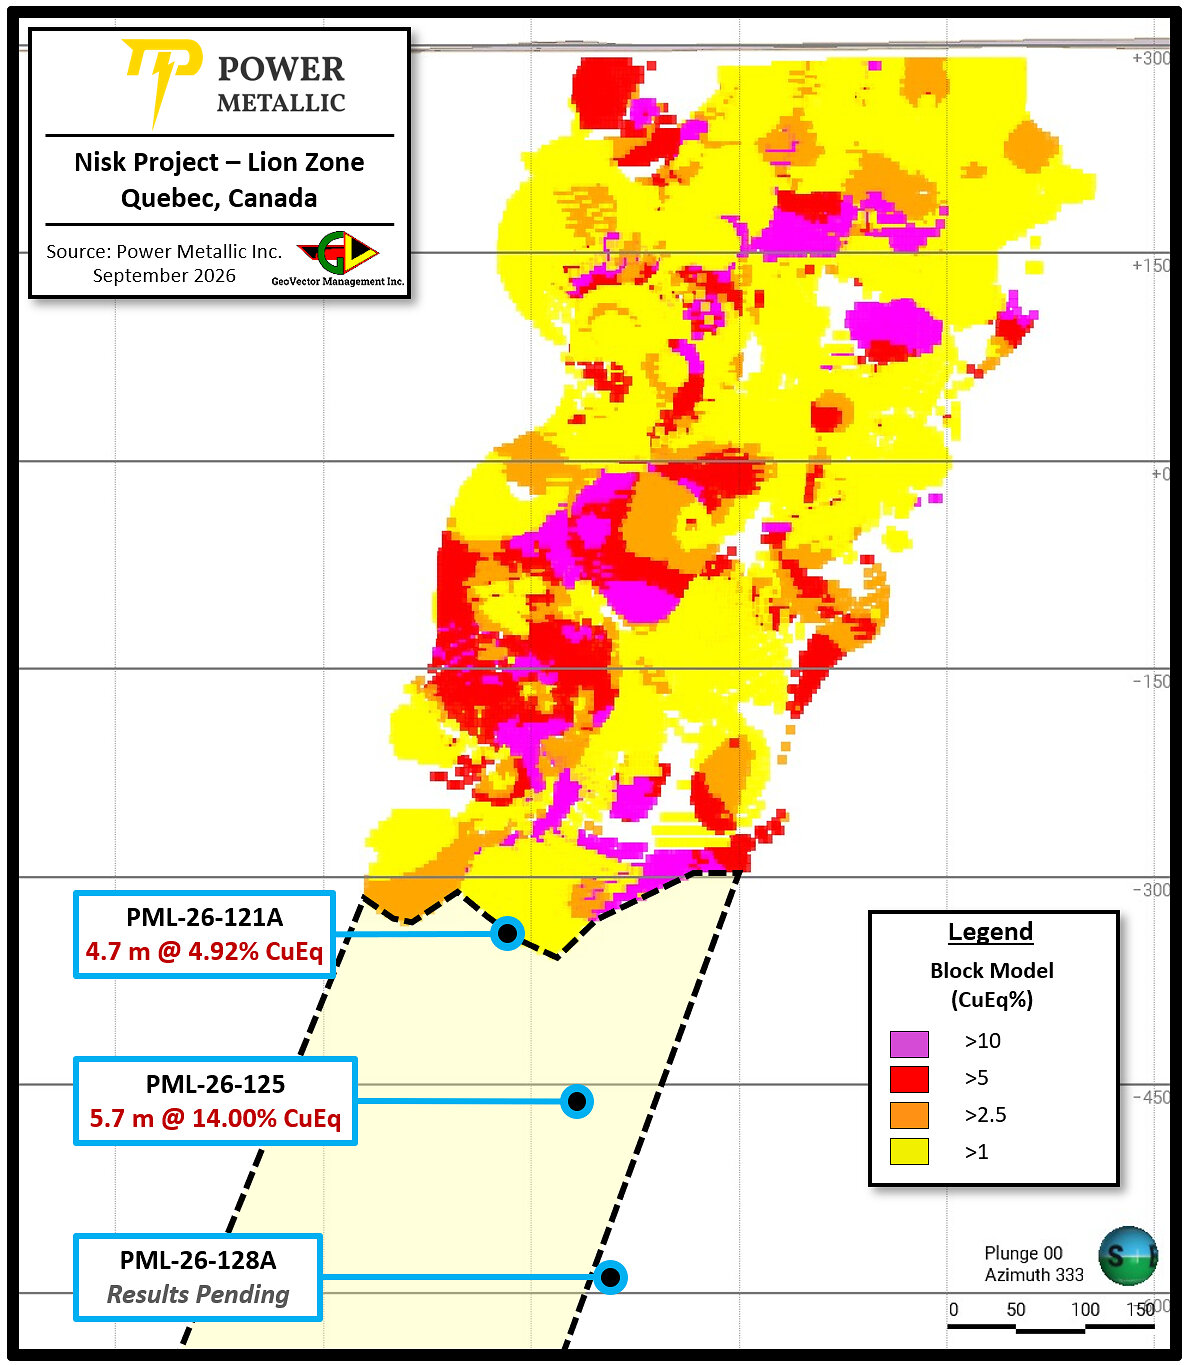
Hole PML-26-125 is the deepest assay results to date at Lion at a vertical depth of nearly 800m vertical depth, well below the current MRE. Prior to Hole PML-26-125 The deepest reported hole intersecting the core of the Lion shoot to date (PML-25-002) intersected 1.95 metres at 7.95% CuEqRec* at approximately 610 metres vertical depth. This hole was targeted on the projected center of the Lion plunge approximately 150m below the previous deepest hole and intersected 5.7m of massive to semi-massive copper sulphides (Table 1). An earlier drill hole, PML-26-121a targeted the western side of the projected plunge of Lion at a vertical depth of nearly 650 meters and intersected disseminated to semi-massive copper sulphides. A subsequent hole (PML-26-128) tested the eastern side of the interpreted Lion plunge at nearly 900 meters vertical depth, showing disseminated and massive veinlets of copper sulphides, with assays pending (Figure 1). All three of these holes firmly established that the Lion deposit continues at depth and has not been fully delineated.

Table 1: Lion Results – Summer 2026
HoleFromToLengthAuAgCuPdPtNiCuEq Rec*
(m)(m)(m)(g/t)( g/t )( %)(g/t)(g/t )( %)( %)
PML-26-121a666.30674.007.700.2618.421.033.700.280.143.28
Including666.30671.004.700.3528.371.516.450.450.144.92
Including666.30668.001.700.6672.413.3416.251.210.1611.93
PML-26-125845.80851.505.700.3061.5711.422.480.260.4114.00
Including846.70848.852.150.5592.0420.304.720.510.6024.62
1Copper Equivalent Rec Calculation (CuEqRec1)
CuEqRec represents CuEq calculated based on the following metal prices (USD) : 2,360.15 $/oz Au, 27.98 $/oz Ag, 1,215.00 $/oz Pd, 1000.00 $/oz Pt, 4.00 $/lb Cu, 10.00 $/lb Ni and 22.50 $/lb Co., and recovered grades based on recent locked-cycle metallurgical recoveries by SGS Canada Inc (see press release Jan 21, 2006).
2 Reported length is downhole distance; true width based on model projections is estimated as 85% of downhole length
Figure 1 – Lion Deep Drill holes reported in this news release overlain on Lion zone MRE models (X-Section) and MRE block model (Long Section) with hole locations related to potential plunge extension below MRE models)

Power Metallic is expecting more assay results from the Lion deep drilling and regional exploration in the weeks to come.

Terry Lynch, CEO of Power Metallic, commented:
We are in the unique position due to the high grade and near surface nature of our project to advance development of what the world needs in Critical Minerals, namely Copper and PGEs, but also continue our multifaceted exploration approach to allow the resource to grow substantially between now and the end of 2027. Today’s results pushed us over 25% deeper than the deepest hole used in our recently announced MRE and it did so with significantly higher grades. We have visibility down over 50% deeper and visibly it looks like we are still in the Lion Zone. As we have seen with the great hit Talon Metals recently had deposits can get thicker and richer at depth. The blessing in Lion is our mineralization starts at surface and extends down making it very economic to mine and explore. We are excited to get back to exploration!

Qualified Person

Joseph Campbell, P. Geo, VP Exploration at Power Metallic, is the qualified person who has reviewed and approved the technical disclosure contained in this news release.

About Power Metallic Mines Inc.

Power Metallic is a Canadian exploration company focused on advancing the Nisk Project Area (Nisk–Lion–Tiger)—a high–grade Copper–PGE, Nickel, gold and silver system—toward Canada’s next polymetallic mine.

On 1 February 2021, Power Metallic (then Chilean Metals) secured an option to earn up to 80% of the Nisk project from Critical Elements Lithium Corp. (TSX–V: CRE). Following the June 2025 purchase of 313 adjoining claims (~167 km²) from Li–FT Power, the Company now controls ~330 km² and roughly 50 km of prospective basin margins.

Power Metallic is expanding mineralization at the Nisk and Lion discovery zones, evaluating the Tiger target, and exploring the enlarged land package through successive drill programs. Beyond the Nisk Project Area, Power Metallic indirectly has an interest in significant land packages in British Columbia and Chile, by its 50% share ownership position in Chilean Metals Inc., which were spun out from Power Metallic via a plan of arrangement on February 3, 2025.

It also owns 100% of Power Metallic Arabia which owns 100% interest in the Jabul Baudan exploration license in The Kingdon of Saudi Arabia’s Jabal Said Belt. The property encompasses over 200 square kilometres in an area recognized for its high prospectivity for copper gold and zinc mineralization. The region is known for its massive volcanic sulfide (VMS) deposits, including the world-class Jabal Sayid mine and the promising Umm and Damad deposit.

For further information, readers are encouraged to contact:
Power Metallic Mines Inc.
The Canadian Venture Building
82 Richmond St East, Suite 202
Toronto, ON

Neither the TSX Venture Exchange nor its Regulation Services Provider accepts responsibility for the adequacy or accuracy of this release.

QAQC and Sampling

GeoVector Management Inc (“GeoVector”) is the Consulting company retained to perform the actual drilling program, which includes core logging and sampling of the drill core.

All core in this news release is either HQ or NQ sized core. Drill core is re-fitted and measured. Geotech on core includes photographs (wet & dry), rock quality index, magnetic susceptibility, conductivity, and recovery estimates. Core is logged for lithology, mineralogy, and structural features, and sample intervals are delineated and tagged.

Sampled core is mechanically sawn, and half-core is retained for future reference. GeoVector’s QAQC program includes regular insertion of CRM standards, duplicates, and blanks into the sample stream with a stringent review of all results. QAQC and data validation was performed, and no material errors were observed.

All samples were submitted to and analyzed at Activation Laboratories Ltd (“Actlabs”), a commercial laboratory independent of Power Metallic with no interest in the Project. Actlabs is an ISO 9001 and 17025 certified and accredited laboratories. Samples submitted through Actlabs are run through standard preparation methods and analysed using RX-1 (Dry, crush (< 7 kg) up to 80% passing 2 mm, riffle split (250 g) and pulverize (mild steel) to 95% passing 105 μm) preparation methods, and using 1F2 (ICP-OES) and 1C-OES – 4-Acid near total digestion + Gold-Platinum-Palladium analysis and 8-Peroxide ICP-OES, for regular and over detection limit analysis. Pegmatite samples are analyzed using UT7 – Li up to 5%, Rb up to 2% method. Actlabs also undertake their own internal coarse and pulp duplicate analysis to ensure proper sample preparation and equipment calibration.

Cautionary Note Regarding Forward-Looking Statements

This message contains certain statements that may be deemed “forward-looking statements” concerning the Company within the meaning of applicable securities laws. Forward-looking statements are statements that are not historical facts and are generally, but not always, identified by the words “expects,” “plans,” “anticipates,” “believes,” “intends,” “estimates,” “projects,” “potential,” “indicates,” “opportunity,” “possible” and similar expressions, or that events or conditions “will,” “would,” “may,” “could” or “should” occur. Although the Company believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance, are subject to risks and uncertainties, and actual results or realities may differ materially from those in the forward-looking statements. Such material risks and uncertainties include, but are not limited to, among others; the timing for various drilling plans; the ability to raise sufficient capital to fund its obligations under its property agreements going forward and conduct drilling and exploration; to maintain its mineral tenures and concessions in good standing; to explore and develop its projects; changes in economic conditions or financial markets; the inherent hazards associates with mineral exploration and mining operations; future prices of nickel and other metals; changes in general economic conditions; accuracy of mineral resource and reserve estimates; the potential for new discoveries; the ability of the Company to obtain the necessary permits and consents required to explore, drill and develop the projects and if accepted, to obtain such licenses and approvals in a timely fashion relative to the Company’s plans and business objectives for the applicable project; the general ability of the Company to monetize its mineral resources; and changes in environmental and other laws or regulations that could have an impact on the Company’s operations, compliance with environmental laws and regulations, dependence on key management personnel and general competition in the mining industry.