Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q2 results. Second-quarter revenue of $7.8 million declined 23% year over year and came in 11% below our $8.8 million estimate. The shortfall was concentrated among demand-side platform customers, with spending falling to zero from $2.5 million in the prior-year quarter. Excluding DSP customers, revenue grew 3% in the quarter and 5% year-to-date, suggesting the core managed-campaign business is roughly stable even as the reported line contracts.
Gross margin held with disciplined spending. Gross profit of $2.7 million represented 34% of revenue, down modestly from 35% a year ago and flat with the first quarter. Operating expenses of $5.6 million declined 7% year over year. The adjusted EBITDA loss widened to $2.3 million from $1.5 million a year earlier, well short of our $0.35 million loss estimate, and management’s second-half breakeven target now looks difficult to reach.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Radio’s audience remains considerably more resilient than its advertising performance suggests. Consumer engagement has held up far better than traditional spot revenue, even as podcasts, streaming, and other audio alternatives have proliferated. This disconnect is central to the investment thesis: radio increasingly has a monetization problem rather than an audience problem, creating an opportunity if technology can narrow the gap.
The industry’s transformation is increasingly becoming an ad-tech and digital monetization story. Programmatic buying, improved attribution, first-party data, podcasts, and digital marketing services are expanding radio beyond the traditional station-and-spot model. The opportunity is to use radio’s existing reach, content, and advertiser relationships to participate in a much larger advertising market rather than simply defend its share of traditional radio spending.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Record-Breaking Q2. The company reported its highest quarterly revenue of $54.1 million, up a solid 16.5% YoY, and adj. EBTDA of $5.7 million, both of which beat our estimates of $52.5 million and a loss of $0.675 million, respectively. Notably, the company generated its first profitable quarter as a public company, driven primarily by higher affiliate fees and licensing revenue.
Higher-margin revenue streams gaining momentum. Affiliate fee revenue increased 81.9% to $13.4 million, while licensing revenue increased 563.5% to $4.6 million. In our view, continued affiliate repricing and licensing growth should improve the company’s revenue mix and provide an increasingly important driver of margin expansion.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
LIMASSOL, Cyprus, Aug. 21, 2026 (GLOBE NEWSWIRE) — GDEV Inc. (NASDAQ: GDEV), an international gaming and entertainment company (“GDEV” or the “Company”) released its unaudited financial and operational results for the second quarter and first half-year ended June 30, 2026.
Second quarter 2026 financial highlights:
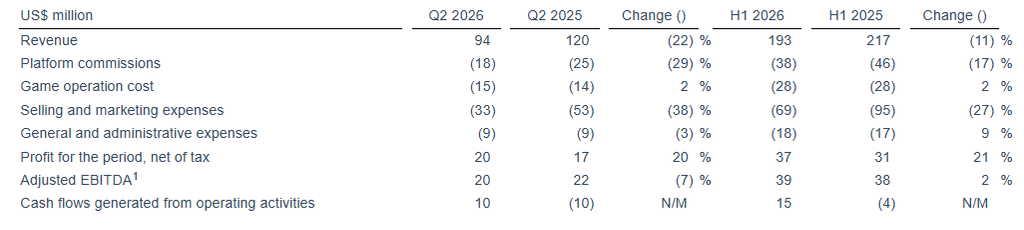
Revenue of $94 million decreased by 22% year-over-year.
Selling and marketing expenses of $33 million decreased by 38% year-over-year.
Profit for the period, net of tax, of $20 million in Q2 2026 increased vs. $17 million in Q2 2025.
Adjusted EBITDA amounted to $20 million in Q2 2026 decreased vs. $22 million in Q2 2025.
Second quarter and first half of 2026 financial performance in comparison
Second quarter 2026 financial performance
In the second quarter of 2026, our revenue decreased by $26 million (or 22%) year-over-year and amounted to $94 million. The decrease was primarily driven by a decrease in bookings.
Platform commissions decreased by $7 million (or 29%) in the second quarter of 2026 compared to the same period in 2025 in line with the decrease in revenue.
Game operation costs remained relatively stable at the level of $15 million in the second quarter of 2026 vs. $14 million in the second quarter of 2025.
Selling and marketing expenses in the second quarter of 2026 decreased by $20 million vs. the same period in 2025, amounting to $33 million. This decrease is driven by our continued focus on improving the efficiency of user acquisition activities. The decrease reflects a more selective approach to performance marketing, prioritizing channels that attract players with higher long-term value over broad-scale campaigns aimed at short-term growth.
General and administrative expenses remained stable at $9 million in the second quarters of both 2026 and 2025.
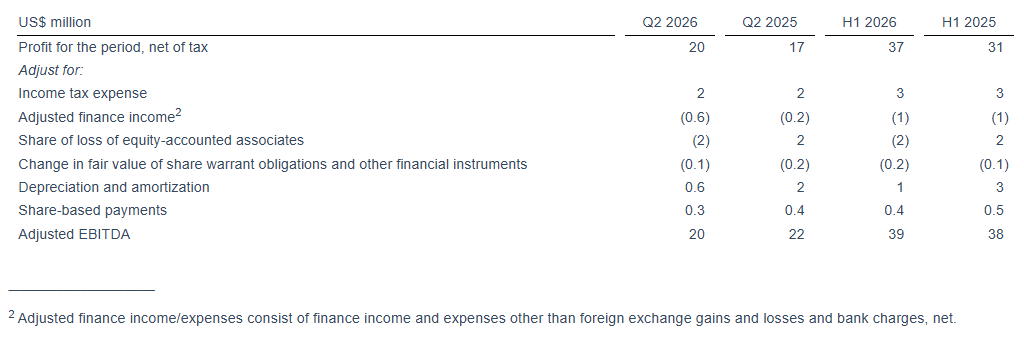
As a result of the factors above, together with (i) the effect of a net foreign exchange loss in the second quarter of 2026 in the amount of $1 million vs. a net foreign exchange gain in the amount of $1 million in the same period of the prior year and (ii) share of profits of equity accounted associates in the second quarter of 2026 in the amount of $2 million vs. the share of losses of equity accounted associates in the amount of $2 million in the same period of the prior year, we recorded a profit for the period, net of tax, of $20 million in the second quarter of 2026 compared with $17 million in the same period of 2025. Adjusted EBITDA in the second quarter of 2026 amounted to $20 million, a decrease of $2 million compared with the same period in 2025 driven primarily by the same factors as those affecting the profit, except for the share of profits or losses of equity accounted associates, which do not impact the Adjusted EBITDA.
Cash flows generated from operating activities were positive $10 million in the second quarter of 2026 compared with negative $10 million in the same period in 2025.
________________________ 1 For more information, see section titled “Presentation of Non-IFRS Financial Measures” on the last two pages of this report, including the reconciliation of the profit for the period, net of tax to the Adjusted EBITDA.
First half of 2026 financial performance
In the first half of 2026, our revenue decreased by $24 million (or 11%) year-over-year to $193 million. This decrease was primarily driven by a decrease in bookings.
Platform commissions decreased by $8 million (or 17%) in the first half of 2026 compared to the same period in 2025, driven by a decrease of revenues recognized from PC platforms.
Game operation cost remained stable at $28 million in the first halves of both 2026 and 2025.
Selling and marketing expenses in the first half of 2026 decreased by $25 million vs. the same period in 2025, amounting to $69 million. This decrease is driven by our continued focus on improving the efficiency of user acquisition activities. The decrease reflects a more selective approach to performance marketing, prioritizing channels that attract players with higher long-term value over broad-scale campaigns aimed at short-term growth.
General and administrative expenses remained relatively stable at $18 million in the first half of 2026 vs. $17 million in 2025.
As a result of the factors above, together with (i) the effect of a net foreign exchange loss in the first half of 2026 in the amount of $2 million vs. a net foreign exchange gain in the amount of $2 million in the same period of prior year and (ii) share of profits of equity accounted associates in the second quarter of 2026 in the amount of $2 million vs. the share of losses of equity accounted associates in the amount of $2 million in the same period of prior year, we recorded a profit for the period, net of tax, of $37 million compared with $31 million in the same period of 2025. Adjusted EBITDA in the first half of 2026 amounted to $39 million, an increase of $1 million compared with the same period in 2025 driven primarily by the same factors as those affecting the profit, except for the share of profits or losses of equity accounted associates, which do not impact the Adjusted EBITDA.
Cash flows generated from operating activities were positive $15 million in the first half of 2026 compared with negative $4 million in the same period in 2025.
Second quarter and first half 2026 operational performance comparison
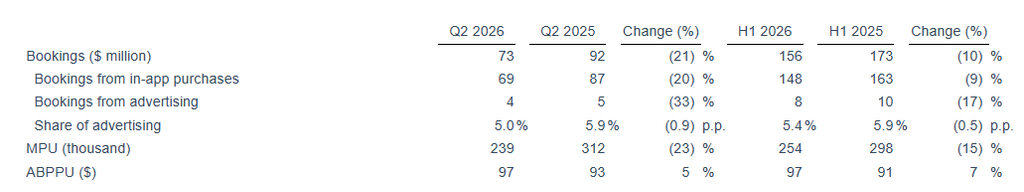
Bookings declined in the second quarter and first half of 2026 to reach $73 million and $156 million, respectively, compared with $92 million and $173 million in the same periods in 2025. The decline was primarily due to a decline in monthly paying users of 23% and 15% in the second quarter and first half of 2026, respectively, vs. the same periods in 2025.
The share of advertisement sales as a percentage of total bookings decreased in the second quarter and first half of 2026 by 0.9 p.p. and 0.5 p.p. vs. the same period in 2025.
In the second quarter of 2026, the share of mobile and PC versions of our games remained relatively stable while in the first half of 2026 we recorded an increase in share of mobile to reach 64% vs. 61% in the same period in 2025 and a decrease in share of PC to reach 36% vs. 39% in the same period in 2025.
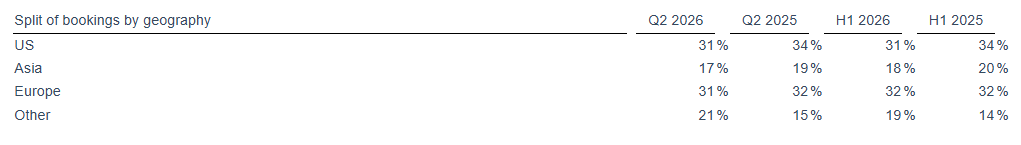
Our split of bookings by geography in the second quarter and first half of 2026 vs. the same periods in 2025 saw a decrease in the share of bookings derived from the US and Asia and an increase in bookings derived from other countries.
Note:
Due to rounding, the numbers presented throughout this release may not precisely add up to the totals. The period-over-period percentage changes are based on the actual numbers and may therefore differ from the percentage changes if those were to be calculated based on the rounded numbers.
Recent developments
On August 13, 2026, the Group entered into a game asset purchase agreement with an unrelated party for the sale of the mobile game “Island Hoppers”, together with all related intellectual property and game assets, for a total consideration of $5.0 million, of which $4.5 million was received upon execution and $0.5 million represents a deferred payment contingent on the satisfaction of a gross revenue condition and completion of the agreed migration obligations.
Island Hoppers contributed approximately 1% to the Group’s bookings in the first half of 2026 and approximately 3% in the year ended December 31, 2025.
As a result of the transaction, deferred revenue related to Island Hoppers’ bookings, totaling $2.1 million as of June 30, 2026, will be recognized on an accelerated basis, providing a one-time uplift to reported revenue in the period of closing.
About GDEV
GDEV is a gaming and entertainment holding company, focused on development and growth of its franchise portfolio across various genres and platforms. With a diverse range of subsidiaries including Nexters and Cubic Games, among others, GDEV strives to create games that will inspire and engage millions of players for years to come. Its franchises, such as Hero Wars, Island Hoppers, Pixel Gun 3D and others have accumulated over 550 million installs and $2.5 billion of bookings worldwide. For more information, please visit www.gdev.inc
Contacts:
Investor Relations Roman Safiyulin | Chief Corporate Development Officer [email protected]
Certain statements in this press release may constitute “forward-looking statements” for purposes of the federal securities laws. Such statements are based on current expectations that are subject to risks and uncertainties. In addition, any statements that refer to projections, forecasts or other characterizations of future events or circumstances, including any underlying assumptions, are forward-looking statements.
The forward-looking statements contained in this press release are based on the Company’s current expectations and beliefs concerning future developments and their potential effects on the Company. There can be no assurance that future developments affecting the Company will be those that the Company has anticipated. Forward-looking statements involve a number of risks, uncertainties (some of which are beyond the Company’s control) or other assumptions. You should carefully consider the risks and uncertainties described in the “Risk Factors” section of the Company’s 2025 Annual Report on Form 20-F, filed by the Company on March 31, 2026, and other documents filed by the Company from time to time with the Securities and Exchange Commission. Should one or more of these risks or uncertainties materialize, or should any of the Company’s assumptions prove incorrect, actual results may vary in material respects from those projected in these forward-looking statements. Forward-looking statements speak only as of the date they are made. Readers are cautioned not to put undue reliance on forward-looking statements, and the Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as may be required under applicable securities laws.
Presentation of Non-IFRS Financial Measures
In addition to the results provided in accordance with IFRS throughout this press release, the Company has provided the non-IFRS financial measure “Adjusted EBITDA” (the “Non-IFRS Financial Measure”). The Company defines Adjusted EBITDA as the profit/loss for the period, net of tax as presented in the Company’s financial statements in accordance with IFRS, adjusted to exclude (i) goodwill and investments in equity-accounted associates’ impairment, (ii) loss on disposal of subsidiaries, (iii) income tax expense, (iv) other financial income, finance income and expenses other than foreign exchange gains and losses and bank charges, (v) change in fair value of share warrant obligations and other financial instruments, (vi) share of loss of equity-accounted associates, (vii) depreciation and amortization, (viii) share-based payments expense and (ix) certain non-cash or other special items that we do not consider indicative of our ongoing operating performance. The Company uses this Non-IFRS Financial Measure for business planning purposes and in measuring its performance relative to that of its competitors. The Company believes that this Non-IFRS Financial Measure is a useful financial metric to assess its operating performance from period-to-period by excluding certain items that the Company believes are not representative of its core business. This Non-IFRS Financial Measure is not intended to replace, and should not be considered superior to, the presentation of the Company’s financial results in accordance with IFRS. The use of the Non-IFRS Financial Measure terms may differ from similar measures reported by other companies and may not be comparable to other similarly titled measures.
Reconciliation of the profit for the period, net of tax to the Adjusted EBITDA
RICHMOND, Va.–(BUSINESS WIRE)– Lucky Strike Entertainment (NYSE: LUCK), one of the world’s premier operators of location-based entertainment, will report financial results for the fourth quarter and full year fiscal 2026 on Thursday, August 27, 2026, before the U.S. stock market opens. Management will discuss the results via webcast at 9:00 AM ET on the same day.
The live webcast, replay, and results presentation will be available in the Events & Presentations section of the Lucky Strike Entertainment Investor Relations website at IR.LuckyStrikeEnt.com.
About Lucky Strike Entertainment
Lucky Strike Entertainment is one of the world’s premier location-based entertainment platforms. With over 360 locations across North America, Lucky Strike Entertainment provides experiential offerings in bowling, amusements, water parks, and family entertainment centers. The company also owns the Professional Bowlers Association, the major league of bowling and a growing media property that boasts millions of fans around the globe. For more information on Lucky Strike Entertainment, please visit IR.LuckyStrikeEnt.com.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Gamescom 2026 AAA unveiling. Snail announced its Gamescom 2026 lineup, headlined by the unveiling of its second internally developed AAA title in the 9 Yin Sutra universe, set in a parallel timeline and alternate universe to 9Yin Sutra: Immortal, which debuted at ChinaJoy on July 30th. In our note on August 12th, we had identified an unannounced AAA reveal at Gamescom as a near-term event, and the release confirms it.
The franchise builds. Both 9 Yin Sutra titles draw on the established Age of Wushu IP, offering different treatments of the same martial arts setting. Along with these titles, Snail will also show For The Stars, its space-survival AAA project. In our view, concentrating two out of the three AAA projects within a single IP family should improve development and marketing efficiency, while also making outcomes across those titles more correlated.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
CULVER CITY, Calif., Aug. 20, 2026 (GLOBE NEWSWIRE) — Snail, Inc. (Nasdaq: SNAL) (“Snail Games” or the “Company”), a leading independent global developer and publisher of interactive digital entertainment, unveils its Gamescom 2026 lineup that includes developing AAA titles, upcoming releases, and content updates across existing titles.
Taking the spotlight at Gamescom 2026 is the 9 Yin Sutra universe. Following the recent ChinaJoy announcement of9 Yin Sutra: Immortal, Snail Games CEO, Hai Shi, will officially unveil another internally developed AAA title, expanding the franchise into a parallel timeline and alternate universe. Both titles are rooted in the acclaimed Age of Wushu IP, offering distinct takes on the martial arts world while building on one of Snail Games’ most established franchises. Alongside the upcoming 9 Yin Sutra titles, Snail Games will also showcase For The Stars, the Company’s other developing AAA title and ambitious space survival experience.
Meanwhile, Honeycomb: The World Beyond is gearing up for its recently announced September 8, 2026 launch. The upcoming survival adventure will be featured at Gamescom, giving attendees an early look at the game ahead of release. Players can also get an early, hands-on experience through a PC-exclusive preview demo expected to launch on August 31, 2026.
Bellwright will celebrate its community of over 1 million players while teasing an upcoming update with one of its most anticipated developments. Consistently the #1 player-requested feature, Bellwright’s latest feature represents a major step in how players will experience and move through the world. The Gamescom showcase will offer an early look at what’s coming while celebrating the community that has helped shape Bellwright.
Leading into Gamescom, Echoes of Elysium has received a new weather-focused tempest that makes rain a more meaningful part of gameplay. Rain now directly affects ships and their contents, with wet components and stored items gaining weight and drag. Certain stations can become inoperable when soaked, while the updated weather system brings a darker, more atmospheric feel to the world.
Visit the Snail Games Booth at Gamescom Hall 8.1 A-041
For Media interested in interviews at Gamescom please reach out to [email protected]
For Creators interested in collaborations please reach out to [email protected]
About Snail, Inc. Snail, Inc. (Nasdaq: SNAL) is a leading global independent developer and publisher of interactive digital entertainment for consumers around the world, with a premier portfolio of premium games designed for use on a variety of platforms, including consoles, PCs, and mobile devices. For more information, please visit: https://snail.com/.
Forward-Looking Statements This press release contains statements that constitute forward-looking statements. Many of the forward-looking statements contained in this press release can be identified by the use of forward-looking words such as “anticipate,” “believe,” “could,” “expect,” “should,” “plan,” “intend,” “may,” “predict,” “continue,” “estimate” and “potential,” or the negative of these terms or other similar expressions. Forward-looking statements appear in a number of places in this press release and include, but are not limited to, statements regarding Honeycomb: The World Beyond gearing up for its recently announced September 8, 2026 launch; the survival adventure being featured at Gamescom, players getting an early hands-on experience through a PC-exclusive preview demo launching August 31; Bellwright teasing one of its most anticipated developments: traversal at Gamescom: Snail Games USA showcasing For The Stars and the 9 Yin Sutra universe; and Snail Games USA’s CEO officially unveiling another new 9 Yin Sutra title at Gamescom, 9 Yin Sutra, expanding the franchise into a parallel timeline and alternate universe. Any forward-looking statements included herein reflect our current views, and they involve certain risks and uncertainties, including, among others, the ability to launch The World Beyond on September 8, 2026 , the PC-exclusive demo and the other new games and titles when anticipated; acceptance of the Company’s titles in the marketplace and the successful development, marketing or sale of our titles and our ability to retain our key employees or maintain our Nasdaq listing. These risks should not be construed as exhaustive and should be read together with the other cautionary statement included in our Annual Report on Form 10-K for the year ended December 31, 2025, subsequent Quarterly Reports on Form 10-Q and current reports on Form 8-K filed with the Securities and Exchange Commission. Any forward-looking statement speaks only as of the date on which it was initially made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, changed circumstances or otherwise, unless required by law.
Investor Contact: John Yi and Steven Shinmachi Gateway Group, Inc. 949-574-3860 [email protected]
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q2 results preview. We expect GDEV’s second-quarter results to reflect continued disciplined user acquisition spending and a focus on profitable growth. For context, Q1 revenue increased 2% to $99 million, while adjusted EBITDA increased 15% to $18 million, benefiting from a 13% decline in selling and marketing expense, as illustrated in Figure #1 Q1 Results. The return to top-line growth, following a revenue decline in fiscal 2025, is encouraging.
Facing a difficult revenue comparison. Q2 will lap a relatively strong year-ago quarter, when revenue increased 13% to $120 million, driven in part by elevated performance marketing investment. As such, we believe the more important read-through will be the company’s ability to sustain engagement and monetization while maintaining its more disciplined approach to marketing expenditures.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
PURCHASE, N.Y., Aug. 17, 2026 (GLOBE NEWSWIRE) — Townsquare Media, Inc. (NYSE: TSQ) (“Townsquare” or the “Company”), a leader in digital advertising and marketing solutions focused on markets outside of the Top 50 in the United States, announced today a strategic digital advertising partnership with Midlands Media Group, a Columbia, S.C.-based multimedia company with two radio stations, a digital news service, a digital ticketing provider, a discount certificate site, and a comprehensive digital advertising platform.
“Midlands Media Group has built a highly local portfolio of radio and digital news brands with engaged audiences and a strong market presence, making them an ideal partner for our digital platform and services,” said Shaun Collignon, CRO of Townsquare Ignite, the Company’s Digital Advertising division. “By combining their multi-channel reach with our proprietary technology, data-driven strategy, and execution expertise, we are well positioned to unlock new revenue opportunities and drive meaningful, measurable growth.”
In 2024, Townsquare launched its Media Partnerships division as part of Townsquare Ignite, its Digital Advertising segment, to bring its industry-leading digital solutions to other local media companies. The division provides a white-label service that allows partners to tap into the same data-driven strategies and proprietary technology that have powered Townsquare’s success, with digital now contributing more than half of the Company’s total revenue and profit.
This partnership with Midlands Media Group is one of 16 strategic alliances Townsquare has established under this initiative, collectively expanding the Company’s reach into 41 new markets beyond its owned and operated footprint, including those in the Top 50 markets. Townsquare will work closely with Midlands Media Group, which operates in the #90-ranked MSA in the United States, to deliver customized, data-driven advertising solutions tailored to local, regional, and national clients, helping to grow their digital business while enhancing the value of their trusted broadcast and multimedia platforms.
“This alliance reflects our continued commitment to helping leading local media companies to more fully monetize their audiences across platforms and deliver stronger results for their clients,” Collignon added.
“Midlands Media Group is very excited to partner with Townsquare Ignite to further expand our digital solutions capabilities. After extensive evaluation and industry experience, we believe Townsquare Ignite is best-in-class and fully committed to digital growth. Their team and technology position us to accelerate results for our clients across all platforms,” said Keith Stover, President & CEO of Midlands Media Group.
Marie Stover, Chief Operating Officer of Midlands Media Group, added: “Our unique focus is to super-serve the marketing needs of local businesses in our community. Adding Townsquare Ignite’s digital marketing component to our market-leading radio and news products positions us to deliver fully integrated campaigns that are authentic, high-impact, and measurable. We look forward to what this partnership will bring to our clients and communities.”
About Townsquare Media, Inc. Townsquare is a community-focused digital and broadcast media and digital marketing solutions company principally focused outside the top 50 markets in the U.S. Townsquare Ignite, our robust digital advertising division, specializes in helping businesses of all sizes connect with their target audience through data-driven, results based strategies, by utilizing a) our proprietary digital programmatic advertising technology stack with an in-house demand and data management platform and b) our owned and operated portfolio of more than 400 local news and entertainment websites and mobile apps along with a network of leading national music and entertainment brands, collecting valuable first party data. Townsquare Interactive, our subscription digital marketing services business, partners with SMBs to help manage their digital presence by providing a SAAS business management platform, website design, creation and hosting, search engine optimization and other digital services. And through our portfolio of local radio stations strategically situated outside the Top 50 markets in the United States, we provide effective advertising solutions for our clients and relevant local content for our audiences. For more information, please visit www.townsquaremedia.com, www.townsquareinteractive.com, and www.townsquareignite.com.
About Midlands Media Group Midlands Media Group is a Columbia, S.C.-based multimedia company and the only locally owned and operated media company in the Columbia market. The company connects local audiences and businesses through two radio stations, a digital news service, a digital ticketing provider, a discount certificate platform and a comprehensive suite of digital advertising solutions.
CULVER CITY, Calif., Aug. 14, 2026 (GLOBE NEWSWIRE) — Snail, Inc. (Nasdaq: SNAL) (“Snail Games” or the “Company”), a leading independent global developer and publisher of interactive digital entertainment, today highlighted several recent milestones across its gaming portfolio, including a newly released title, upcoming PixARK content, and continued development of the indie portfolio.
Stoneguard, developed by a two-person independent development team and published under the Wandering Wizard label, launched on Steam Early Access and has achieved a “Mostly Positive” rating from Steam users to date. The Early Access launch provides the development team with an opportunity to continue refining the game based on player feedback while expanding its content and features.
Wandering Wizard also released a new demo and trailer for Veil of Madness, providing players with an updated look at the upcoming first-person psychological horror deckbuilding game. The latest materials are intended to allow players to experience the game ahead of its full release later this year as development continues.
Alongside the new content for its indie label, Snail Games has released a new demo for Dead Party, a sequel to the title Dead Block. The new demo represents the latest development milestone and provides players with an early opportunity to experience the co-op party action game.
Snail Games has also announced the official release date for PixARK: Terracrypt, the voxel-based sandbox survival game’s first premium expansion, set to launch on Steam on August 26, 2026. As the largest expansion created for PixARK, Terracrypt will deliver more than 200 hours of gameplay, 80 new creatures, and 12 new biomes.
Snail Games intends to continue providing updates on its portfolio as projects progress toward additional releases, demonstrations, and milestones. With a robust slate of ARK content, alongside AAA and indie titles in development, the Company remains focused on executing against its pipeline through the second half of 2026.
About Snail, Inc. Snail, Inc. (Nasdaq: SNAL) is a leading global independent developer and publisher of interactive digital entertainment for consumers around the world, with a premier portfolio of premium games designed for use on a variety of platforms, including consoles, PCs, and mobile devices. For more information, please visit: https://snail.com/.
About Wandering Wizard Wandering Wizard is passionately committed to championing indie game developers. We provide a platform for fresh voices, revolutionary ideas, and daring experiments within the indie gaming realm. Embracing the inherent risks of indie game development, we partner with creators worldwide to enrich the global gaming community with inclusive, inspiring, and innovative gaming experiences. For more information, please visit: wanderingwizard.com.
Forward-Looking Statements: This press release contains statements that constitute forward-looking statements. Many of the forward-looking statements contained in this press release can be identified by the use of forward-looking words such as “anticipate,” “believe,” “could,” “expect,” “should,” “plan,” “intend,” “may,” “predict,” “continue,” “estimate” and “potential,” or the negative of these terms or other similar expressions. Forward-looking statements appear in a number of places in this press release and include, but are not limited to, statements regarding Snail’s intent, belief or current expectations. These forward-looking statements include information about possible or assumed future results of Snail’s business, financial condition, results of operations, liquidity, plans and objectives. The statements Snail makes regarding the following matters are forward-looking by their nature: the Early Access launch providing an opportunity to continue refining a game based on player feedback while expanding its content and features; the demo and trailer for Veil of Madness allowing players to experience the game ahead of its full release later this year as development continues; the Company’s continued exploration of artificial intelligence and interactive technologies; Snail Games’ intent to continue providing updates on its portfolio and its projects progressing toward additional releases, demonstrations, and milestones; and the Company’s efforts to become a world-class game developer and publisher with a diversified portfolio and a technological leader in the wide range of interactive entertainment space.
Any forward-looking statements included herein reflect our current views, and they involve certain risks and uncertainties, including, among others, acceptance of our titles in the marketplace and the successful development, marketing or sale of our titles and our ability to retain our key employees or maintain our Nasdaq listing. These risks should not be construed as exhaustive and should be read together with the other cautionary statement included in our Annual Report on Form 10-K for the year ended December 31, 2025, subsequent Quarterly Reports on Form 10-Q and current reports on Form 8-K filed with the Securities and Exchange Commission. Any forward-looking statement speaks only as of the date on which it was initially made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, changed circumstances or otherwise, unless required by law.
Investor Contact: John Yi and Steven Shinmachi Gateway Group, Inc. 949-574-3860 [email protected]
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
George Proost, Research Associate, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Q2 exceeded expectations. Revenue declined 6.5% year over year to $26.4 million, beating our estimate of $25.5 million by 3.5%. Additionally, adj. EBITDA of approximately $1.1 million compared favorably with our $0.1 million estimate. The beat reflected growth in blended digital revenue, which cushioned double-digit declines across the traditional broadcast business.
Digital continues to scale. Blended digital offering grew 60.8% during the quarter and was up 76.4% for the first 6 months of the year. Digital reached 19% of gross revenue in the first half compared with 14% a year ago. Management has brought search capabilities in-house with three dedicated specialists, hired and trained ten digital campaign managers, and migrated digital fulfillment to a new platform. In our view, the pace of blended digital growth is the most encouraging development in the quarter and the clearest evidence that the multi-year platform build is beginning to convert.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
A milestone quarter. Newsmax reported record Q2 revenue of $54.1 million, up 16.5%, while Adjusted EBITDA improved to $5.7 million from a loss of $3.8 million, and the company generated its first quarterly net income as a public company. We believe the results provide an important early indication of the operating leverage inherent in the business model.
Higher-margin revenue streams gaining momentum. Affiliate fee revenue increased 81.9% to $13.4 million, while licensing revenue increased 563.5% to $4.6 million. In our view, continued affiliate repricing and licensing growth should improve the company’s revenue mix and provide an increasingly important driver of margin expansion.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Reddit (NYSE: RDDT) will join the S&P 500 before markets open on Tuesday, August 18, S&P Dow Jones Indices announced Thursday, sending shares as much as 15% higher in after-hours and premarket trading. The stock will replace AvalonBay Communities, which is exiting the index following its acquisition by fellow S&P 500 member Equity Residential, a deal shareholders overwhelmingly approved this week. The combined entity will drop both legacy names and begin trading as Vivmark Residential once the transaction closes.
This is an off-cycle inclusion, triggered by the vacancy AvalonBay’s departure created rather than a scheduled quarterly rebalance, which is exactly the same mechanism we detailed in our earlier coverage of the Russell reconstitution process, index committees filling open seats based on eligibility rules rather than a fixed calendar.
The Detail That Actually Unlocked This Move
The most instructive part of this story is not the price pop itself, it is what made Reddit eligible in the first place. S&P’s index committee requires candidates to demonstrate sustained profitability, and Reddit did not post a full fiscal year of positive GAAP net income until 2025, when the company reported roughly $530 million in net income on $2.2 billion in revenue. That single financial milestone is what flipped Reddit from ineligible to eligible, ending months of speculation about when the company might finally clear the bar. Reddit becomes only the second pureplay social media company in the S&P 500, alongside Meta, with larger, longer-established platforms like Pinterest and Snap still falling short on scale.
Context Matters Here: This Is a Bounce, Not Just a Breakout
It is worth noting Reddit shares had fallen more than 22% over the prior month and were down roughly 31% year to date heading into this announcement, following concerns about Google search traffic dependency and AI-driven changes to how users discover content. Part of Thursday’s surge likely reflects short covering as much as new buying interest, with roughly 13% of Reddit’s available float sold short heading into the news, representing several days worth of potential buy-side pressure if those positions unwind.
Why the “Index Effect” Has Weakened Over Time
Academic research has long documented what is known as the index effect, a historical tendency for stocks to see a price bump between an inclusion announcement and the effective date, as funds tracking the S&P 500 are forced to buy shares regardless of valuation. That effect has thinned considerably over the past decade, largely because active managers now anticipate these moves and front-run them, meaning much of the price reaction happens on the announcement itself rather than during the actual passive buying window. History also offers a caution here. When Workday’s S&P 500 inclusion was announced in December 2024, shares initially jumped roughly 10%, only to fall 19% from that peak in the weeks after actually joining the index, a reminder that an inclusion pop and sustained outperformance are not the same thing.
For investors following the small cap space, this story is a useful real-time illustration of a dynamic that applies at every level of the market, not just the S&P 500. Whether it is a company graduating into the Russell 1000 from the Russell 2000 or, as in this case, into the S&P 500 itself, forced passive buying can create a genuine, mechanical demand shock independent of a company’s underlying fundamentals. Understanding that distinction, between a stock moving because trillions in indexed capital must now own it and a stock moving because its business has fundamentally improved, is one of the more useful lenses an investor can apply across market cap ranges.