Eli Lilly to Acquire Calytrix Bio for Up to $1.5 Billion, Expanding Rare Blood Cancer Pipeline

Eli Lilly (NYSE: LLY) is expanding its oncology portfolio with an agreement to acquire privately held biotechnology company Calytrix Bio for up to $1.5 billion in cash, highlighting continued pharmaceutical industry interest in innovative treatments for rare diseases and early-stage drug development.

Announced Monday, November 16, the transaction will give Lilly access to an experimental therapy targeting the genetic drivers of two rare blood cancers: essential thrombocythemia and myelofibrosis. The acquisition also reinforces the company’s strategy of expanding beyond its blockbuster diabetes and weight-loss treatments.

Under the agreement, Calytrix shareholders could receive up to $1.5 billion, including an upfront cash payment and additional payments tied to clinical and regulatory milestones. The companies did not disclose the upfront amount or an expected closing date.

Calytrix is developing precision therapies for myeloproliferative neoplasms, a group of blood cancers characterized by abnormal blood cell production in the bone marrow.

Its lead program focuses on essential thrombocythemia and myelofibrosis associated with mutations in the calreticulin gene, commonly known as CALR.

Essential thrombocythemia can cause excessive platelet production, increasing the risk of blood clots and other complications. Myelofibrosis can lead to bone marrow scarring, impaired blood cell production, and potentially serious symptoms.

Existing treatments can help manage these conditions, but patients may continue to face significant disease-related complications.

Calytrix’s investigational therapy is designed to address the underlying disease mechanism rather than solely controlling symptoms.

The company’s lead candidate is a biparatopic antibody targeting mutant calreticulin, or mCALR. The approach is intended to recognize multiple forms of the mutation, including Type 1 and Type 2, while potentially sparing healthy tissue.

By selectively targeting cells responsible for driving the disease, researchers hope to develop a treatment capable of modifying its progression.

However, the therapy remains preclinical and has not yet demonstrated safety or effectiveness in human trials. Its development will require clinical testing and regulatory review before any potential commercialization.

For Lilly, the acquisition adds another experimental program to its expanding cancer treatment portfolio.

The pharmaceutical giant already markets Jaypirca, a treatment for certain blood cancers, and has been actively pursuing acquisitions to strengthen its pipeline across multiple therapeutic areas.

Calytrix represents another investment in an emerging biotechnology platform where successful clinical development could eventually address an important unmet medical need.

The deal is also noteworthy because of Calytrix’s relatively short operating history.

Founded in 2025 by J.P. Morgan Life Sciences Private Capital, the company received early financial backing from Westlake BioPartners and later completed a Series B financing led by Avoro Ventures.

Its acquisition agreement illustrates how pharmaceutical companies may assign substantial potential value to promising scientific programs before they reach clinical trials.

For investors following small-cap biotechnology companies, the transaction highlights the strategic importance of differentiated drug candidates, proprietary technologies, and treatments targeting diseases with limited therapeutic options.

Large pharmaceutical companies frequently look to smaller developers to expand research pipelines, potentially creating acquisition opportunities for businesses with compelling scientific assets.

However, the $1.5 billion figure represents the maximum potential consideration, not a guaranteed upfront purchase price. The eventual amount depends on achieving specified development milestones.

The transaction also underscores the considerable uncertainty associated with early-stage biotechnology investments, where promising laboratory findings do not always translate into successful clinical treatments.

For now, Lilly’s agreement to acquire Calytrix provides another example of major pharmaceutical companies investing in innovative therapies despite the risks associated with drug development.

If Calytrix’s approach proves successful, the acquisition could strengthen Lilly’s presence in rare blood cancers while advancing efforts to develop treatments that address the underlying causes of disease.

SKYX Platforms (SKYX) – Continuing to Make Progress on the A-to-Z Goal


Monday, November 16, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. SKYX Platforms reported record revenue for 3Q26, marking the 11th consecutive quarter of y-o-y revenue growth. Post-quarter-end, the Deako merger was consummated, expanding SKYX’s product line and builder channel pipeline to approximately 4 million units. We believe SKYX’s A-to-Z platform positions the Company to capitalize on future demand for smart buildings.

3Q26 Results. Revenue was $25.7 million, up 7.4% y-o-y. We had projected $27 million. Gross margin improved 250 basis points y-o-y to 31.4%. We were at 28.9%. SKYX reduced cash burn by 15.5% y-o-y to a use of $4.2 million in 3Q26. Net loss to common shareholders was $6.7 million, or a loss of $0.05/sh, versus a net loss of $7.9 million, or a loss of $0.07/sh, in 3Q25. We were at a net loss of $7.9 million, or a loss of $0.06/sh.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Saga Communications (SGA) – Digital Gains Amid Headwinds


Monday, November 16, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q3 Operating Results. The company reported Q3 revenue of $26.7 million, down 5.4% year over year and modestly below our $27.6 million estimate, as traditional advertising declines outweighed increased political spending. Adj. EBITDA fell to approximately $0.3 million from $1.1 million, as lower revenue more than offset the 1.7% reduction in station operating expenses.

Underlying Business Trends. While Local, national, and non-traditional advertising decreased year over year, digital revenue increased to $4.9 million from $4.6 million, with blended digital growth of 24.9%. Non-blended digital declined 7%, primarily reflecting streaming weakness. Management highlighted larger customer relationships, longer contracts, and increased spending among blended advertising clients as encouraging signs of improving sales execution.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

QuoteMedia Inc. (QMCI) – Enterprise Growth Drives Margin Expansion


Monday, November 16, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Roughly in line Q3 results. QuoteMedia reported Q3 revenue of $5.6 million, up 8.7% year over year and 1.5% below our $5.7 million estimate. Adjusted EBITDA increased 22.6% to $0.5 million, modestly below our $0.6 million estimate. Gross margin expanded to 54.2% from 48.5%, reflecting revenue growth and lower amortization expenses, partially offset by higher expensed software development costs.

Enterprise growth accelerates. Interactive Content and Data APIs revenue increased 16.6% to $3.0 million, supported by new customers and higher revenue per customer. Notably, a major enterprise agreement to replace a larger incumbent provider began generating revenue during the quarter. We believe these customer wins demonstrate QuoteMedia’s ability to compete effectively against larger market data providers.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Eledon Pharmaceuticals (ELDN) – 3Q26 Reported As Clinical Trial Preparations Continue


Monday, November 16, 2026

Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Phase 3 Expected Shortly. Eledon reported a 3Q26 loss of $3.9 million, or $(0.03) per share, including a non-cash gain of $17.0 million from the Changes in Fair Value of Warrant Liabilities. The Operating Loss of $21.7 million was consistent with our estimated $22.9 million operating expense. The Phase 3 LEGACY trial is expected to begin by YE2026, while the islet cell transplant trial has begun. Cash on hand on September 30, 2026, was $69.7 million.

Phase 3 LEGACY Trial Expected By YE2026. The Phase 3 LEGACY trial to prevent kidney transplant rejection is on schedule to begin during 4Q26. The primary endpoint in the trial is non-inferiority of a composite score of BPAR, graft loss, and death. The objective of the Phase 2 BESTOW trial was to characterize tegoprubart safety and efficacy, with these data points included as secondary endpoints. We continue to believe investors misunderstood the results.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Century Lithium Corp. (CYDVF) – Century Lithium Advances Demonstration Plant Permitting


Monday, November 16, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Water Pollution Control Permit Received. Century Lithium recently announced that the Nevada Division of Environmental Protection (NDEP) issued a Water Pollution Control Permit for its Tonopah Demonstration Plant, supporting the company’s 100%-owned Angel Island Lithium Project in Nevada.

Construction Preparations and Permitting. Century Lithium has completed the plant’s concrete foundation and purchased a steel building. The next milestone is Federal Aviation Administration (FAA) approval, pending completion of its environmental review, which will allow building construction to proceed. Before operations begin, the company must certify two existing tailings ponds, submit updated operating plans and a notice of intent to operate, and complete an NDEP inspection. The company already holds an air quality operating permit. These approvals are separate from permitting for the commercial Angel Island project.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Alliance Entertainment Holding (AENT) – Physical Media Strength Drives Growth


Monday, November 16, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q1 Revenue Beats Estimates; EBITDA Growth Lags. The company reported fiscal Q1 revenue of $278.8 million, up 9.8% year over year and 3.9% above our estimate. Growth reflected stronger movie, physical music, and collectibles sales, which more than offset weakness in gaming. Adj. EBITDA increased approximately 1% to $12.3 million, as higher operating expenses absorbed much of the gross profit increase.

Strength in Physical Media. Movie revenue increased 20% to $101.1 million, supported by expanded distribution through Paramount and Amazon MGM Studios. Higher unit sales and pricing drove vinyl and CD revenue growth of 14% and 22%, respectively. Collectibles revenue rose 87% to $11.9 million, benefiting from expanded licensed offerings and Handmade by Robots. Gaming sales declined 40%, reflecting reduced availability of Microsoft products.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Microcap Stocks Trade at Steep Discounts to Large Caps, Creating Potential Opportunities for Investors

While Wall Street continues to focus on trillion-dollar technology companies and the performance of major stock indexes, a potentially compelling investment opportunity may be developing at the opposite end of the market. New research highlights a substantial valuation gap between microcap stocks and larger publicly traded companies, raising questions about whether smaller, overlooked businesses could offer attractive opportunities for long-term investors.

According to research from Verdad Advisors highlighted by Barron’s on November 13, U.S. microcap stocks trade at approximately 5.9 times enterprise value to earnings before interest, taxes, depreciation, and amortization (EV/EBITDA). By comparison, companies in the S&P 500 trade at approximately 19.4 times EBITDA.

The difference is striking. On this measure, microcap companies trade at roughly a 70% discount to their large-cap counterparts, suggesting investors are paying substantially less for each dollar of operating earnings generated by smaller businesses.

The valuation gap extends beyond the United States. European microcaps trade at approximately 4.2 times EBITDA, while Japanese microcaps trade at just 2.8 times, according to the research.

These disparities highlight how investor capital has increasingly concentrated in larger, more established companies, leaving many smaller businesses with comparatively limited attention.

Much of the enthusiasm surrounding artificial intelligence and major technology platforms has benefited the largest companies in the market. Meanwhile, smaller businesses often receive less institutional research coverage, experience lower trading volumes, and attract fewer investment dollars.

For investors willing to conduct detailed research, that lack of attention can create opportunities to identify businesses whose valuations may not fully reflect their underlying fundamentals.

The investment case is not based solely on inexpensive stock prices.

Smaller companies can offer meaningful growth potential through expanding market share, introducing new products, improving operating margins, and pursuing strategic acquisitions. Because they begin from smaller revenue bases, successful execution can sometimes produce substantial percentage increases in earnings.

Recent market research also points to improving fundamentals across parts of the small-cap universe, suggesting that earnings growth could become an increasingly important driver of investor interest.

Another potential catalyst is a shift in market leadership.

If investors begin diversifying away from highly valued mega-cap technology stocks, smaller companies trading at more modest valuations could attract renewed attention. A broader market rally would potentially benefit businesses that have been overlooked during the concentration of investment capital in a relatively small group of companies.

The valuation gap also creates opportunities for mergers and acquisitions.

Larger corporations and private equity investors may find smaller publicly traded companies attractive acquisition targets when their market valuations are significantly below those of comparable larger businesses.

However, inexpensive valuations do not automatically make a stock a bargain.

Microcap companies often face greater financial risks, limited liquidity, higher borrowing costs, and greater sensitivity to economic conditions. Some businesses trade at low multiples because of declining revenue, excessive debt, weak profitability, or uncertain growth prospects.

That makes fundamental analysis particularly important.

Investors should evaluate balance-sheet strength, cash flow generation, competitive positioning, management execution, and the potential catalysts that could lead to improved financial performance.

For the small-cap and microcap market, the current valuation disparity presents an interesting contrast to the enthusiasm surrounding the largest publicly traded companies.

While major indexes remain heavily influenced by a handful of technology leaders, opportunities may exist among smaller businesses operating across industrials, healthcare, technology, energy, and other sectors.

The question is whether improving earnings, renewed institutional interest, and potential acquisition activity can begin narrowing the valuation gap.

For investors focused on identifying emerging growth opportunities, the next compelling investment story may not come from Wall Street’s biggest companies, but from smaller businesses that have yet to attract widespread attention.

Take a moment to take a look at Noble’s research analysts’ universe of coverage for more emerging growth companies.

U.S. Home Sales Plunge 5.5% as Mortgage Rates Hit 7.33%, Deepening Housing Affordability Crisis

The U.S. housing market suffered another setback in October as existing-home sales fell to their lowest level in more than 16 years, highlighting the growing impact of elevated mortgage rates and persistent affordability challenges on American households.

According to the National Association of Realtors (NAR), existing-home sales declined 5.5% from September to a seasonally adjusted annual rate of 3.75 million units. Transactions were down 8.8% compared with October 2025, marking the weakest sales pace since August 2010.

The slowdown comes as mortgage rates continue to climb, making homeownership increasingly expensive for prospective buyers already facing elevated property prices.

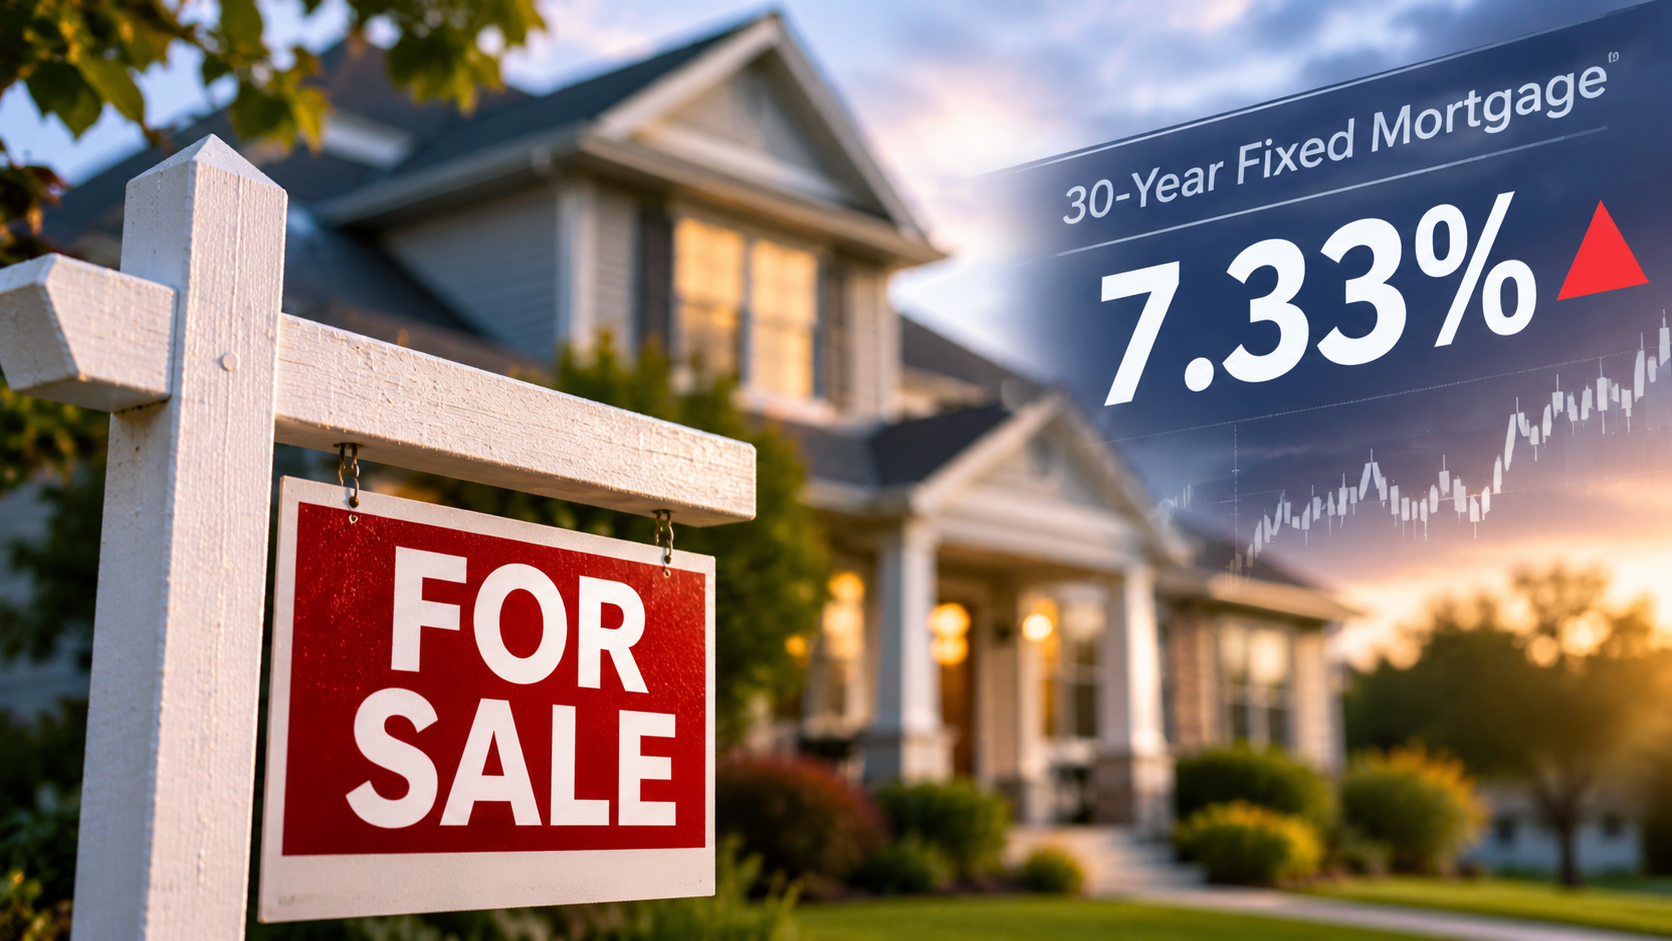
The average 30-year fixed mortgage rate reached 7.33% in October, up from 6.86% in September and 6.25% a year earlier, according to Freddie Mac data cited by NAR.

For buyers financing a $400,000 mortgage, that increase from last year’s rate translates into approximately $280 more in monthly principal and interest payments, creating another financial obstacle for households considering a purchase.

Despite weakening demand, home prices have remained remarkably resilient.

The national median existing-home sales price reached $416,700 in October, representing a 0.4% increase from the previous year. It marked the 40th consecutive month of annual price increases, illustrating the continuing disconnect between housing affordability and property valuations.

However, signs of improving inventory conditions are emerging.

The number of homes available for sale increased to 1.59 million, up 4.6% from a year earlier. That represents a 5.1-month supply at the current sales pace, compared with 4.4 months in October 2025.

More available inventory could eventually provide buyers with additional negotiating power, particularly in markets where sellers have become accustomed to rapid transactions and rising prices.

Regional data showed that the weakness was widespread.

Existing-home sales declined 9.7% in the West, 6.5% in the South, and 3.2% in the Midwest. Sales remained unchanged in the Northeast.

First-time buyers accounted for just 29% of transactions, down from 32% a year earlier, underscoring the challenges facing households attempting to enter the housing market.

The implications extend beyond real estate.

Housing transactions generate economic activity across mortgage lending, brokerage services, home improvement, furniture, appliances, and other consumer industries. Fewer transactions can reduce spending across these categories, potentially affecting companies that depend on residential turnover.

Building materials suppliers and installation contractors also face a complicated environment as higher financing costs influence construction activity and renovation decisions.

The slowdown helps explain why some construction-related companies are seeking greater exposure to commercial and industrial markets.

Installed Building Products (NYSE: IBP), for example, recently announced its acquisition of Old Dominion Group, expanding its commercial and industrial installation capabilities while reducing its relative dependence on residential construction.

The transaction illustrates how businesses exposed to housing cycles are attempting to diversify into infrastructure, data centers, and other construction markets.

For investors, the housing slowdown also creates a broader question about the direction of interest rates.

If inflation remains elevated and borrowing costs stay high, housing affordability could remain under pressure. Conversely, declining mortgage rates could release pent-up demand from buyers who have postponed purchases.

NAR has indicated that substantial potential demand remains, particularly among households waiting for financing conditions to improve.

For now, October’s report highlights an economy in which housing remains a significant source of financial strain.

Whether the market begins recovering will depend on mortgage rates, household incomes, available inventory, and the willingness of sellers to adjust expectations.

Until those conditions improve, housing-related businesses may continue facing a challenging operating environment, even as opportunities emerge for companies positioned to navigate the slowdown.

Star Equity Holdings, Inc. (STRR) – A Mixed Quarter


Friday, November 13, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. The operating environment for both the Business Services and Building Solutions segments remained challenging in the third quarter, resulting in weaker-than-expected results. Nonetheless, we believe Star Equity continues to set itself up to capitalize on a turnaround in the operating environment.

3Q26 Results. Revenue of $53.9 million rose 12.4% y-o-y, but was down from a pro forma $62.1 million last year. We had forecast $56.1 million. Adjusted EBITDA came in at $1.5 million, down from $3.1 million on a pro forma basis and versus our $1.6 million estimate. Adjusted net loss was $0.26/sh versus adjusted pro forma EPS of $0.18 in 3Q25. We had estimated a loss of $0.28/sh on an adjusted basis.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Snail (SNAL) – Strong Results Validate Content Strategy


Friday, November 13, 2026

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Strong Q3 Results. The company reported Q3 revenue of $33.1 million, an increase of 139.2% year over year, driven by stronger ARK sales and a favorable change in deferred revenue recognition. EBITDA improved to $7.2 million, representing a 21.8% margin, compared with a loss of $9.7 million in the prior-year period.

Bookings Rebound. ARK: Survival Ascended (ASA) sold approximately 1.2 million units, up 700,000 year over year, supported by three major downloadable content (DLC) releases in July. Average daily active users reached 121,000, with a peak of 184,000. Bookings increased 30.4% to $23 million, driven by stronger ASA and Bellwright sales. We believe the response reinforces demand for new ARK content and supports the company’s monetization strategy.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Seanergy Maritime (SHIP) – Third Quarter Review and Outlook


Friday, November 13, 2026

Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.

Richard Magnusen, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Third Quarter Results Exceed Expectations. Seanergy Maritime reported third-quarter net revenue of $57.5 million, up 22% year over year, while adjusted EBITDA increased 41% to $40.8 million. Adjusted EPS rose to $1.25 from $0.67 in the prior-year period. Revenue, adjusted EBITDA, and adjusted EPS exceeded our estimates of $55.4 million, $35.0 million, and $0.95, respectively, driven by stronger-than-anticipated charter rates, lower operating expenses, and noncash adjustments.

Outlook for 2026 and 2027. Management projects average fourth-quarter TCE rates of approximately $33,284 per day, with 86% of expected operating days already fixed at an estimated $32,923 per day. Full-year 2026 TCE rates are expected to average approximately $31,000 per day, up 48% compared with 2025. During the earnings call, management characterized $32,000 to $35,000 per day as a reasonable Capesize market rate assumption for 2027. Strong third-quarter results and fourth-quarter guidance support upward revisions to our 2026 adjusted EBITDA and adjusted EPS estimates, while fleet expansion should increase earnings capacity beginning in 2027.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Saga Communications (SGA) – Digital Strategy Progress, Margin Pressure Persists


Friday, November 13, 2026

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q3 Operating Results. Saga reported Q3 revenue of $26.7 million, down 5.4% year-over-year and modestly below our $27.6 million estimate, as traditional advertising declines outweighed increased political spending. Adj. EBITDA fell to approximately $0.3 million from $1.1 million, as lower revenue more than offset the 1.7% reduction in station operating expenses.

Underlying Business Trends. While Local, national, and non-traditional advertising decreased year over year, digital revenue increased to $4.9 million from $4.6 million, with blended digital growth of 24.9%. Non-blended digital declined 7%, primarily reflecting streaming weakness. Management highlighted larger customer relationships, longer contracts, and increased spending among blended advertising clients as encouraging signs of improving sales execution.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.