Release – VivoPower’s Tembo Launches KOVA, its 4WD All-Electric Dual-Motor Platform and Utility Pickup Truck

Research News and Market Data on VIVO

November 13, 2026 08:14 ET  | Source: VivoPower PLC

Tembo KOVA is a five-seat dual-cab electric pickup truck with a motor on each axle, configured for demanding off-road and rugged on-road B2B fleet applications

Tembo KOVA will be available in Australia, New Zealand, the Philippines and Nepal

88 kWh CATL LFP battery with OEM partner manufacturer-stated range of up to 510 km (CLTC) and 460 km (WLTP)

Payload of up to 1,200 kg, braked towing capacity of up to 3,000 kg, gross vehicle mass (GVM) of 3,520 kg and gross combination mass (GCM) of 6,520 kg

Peak combined output of up to 200 kW and 485 Nm; DC fast charging from 20% to 80% in approximately 45 minutes through a CCS port

Tembo KOVA sits alongside the Tembo Tusker and Tembo EUV E-Power (E-Conversion) models, giving fleet customers the choice of a new electric vehicle or electrification of an existing one

LONDON, UK / EINDHOVEN, NETHERLANDS, Nov. 13, 2026 (GLOBE NEWSWIRE) — VivoPower PLC (Nasdaq: VIVO) (“VivoPower” or the “Company”), a leading B Corp-certified global developer and owner of powered land and data center infrastructure for AI compute applications, today announced that its electric vehicle subsidiary, Tembo e-LV B.V. (“Tembo”), has launched Tembo KOVA, a new all-electric four-wheel-drive (4WD) truck. Tembo KOVA is intended for fleet customers seeking a practical electric utility pickup for demanding off-road and on-road applications, including mining, agriculture, energy, construction, infrastructure, government and safari tourism.

KOVA stands for Kinetic Off-road Vehicle Architecture, Tembo’s dual-motor electric 4WD pickup offering configured for demanding off-road terrain and rugged on-road fleet duty.

Kevin Chin, Executive Chairman and CEO, said: “Most of the fleet operator demand we see across our key markets is for 4WD utility pickup trucks, based on our in-the-field customer business development activities across multiple industries. The introduction of Tembo KOVA adds a 4WD electric utility pickup well suited to demanding off-road and rugged on-road fleet use cases, positioning Tembo to address growing customer interest driven by high and volatile diesel prices in our key markets. We are pleased to be able to offer the Tembo KOVA to fleet operators in Australia, New Zealand, the Philippines and Nepal. In turn, adding a dedicated 4WD pickup to our lineup is expected to help Tembo compete in the fast-growing electric 4WD pickup segment and support its path toward profitable growth.”

Addressable Markets

Tembo estimates that approximately 223,000 new four-wheel-drive (4WD) pickup trucks will be sold in 2026 across the four markets in which Tembo KOVA will be offered, with an estimated annual market value of approximately US$9 billion covering all powertrains, at current retail prices; these estimates are not the battery-electric market or a forecast of Tembo sales. Australia is the largest of these markets, accounting for approximately 83% of estimated 2026 units and 86% of estimated value.

Electrification of the 4WD pickup segment in these markets is increasing off a low base, with battery-electric 4WD pickups effectively absent in 2024 as initial offerings have only recently been introduced. Based on Company estimates derived from industry registration, import and model-level data, battery-electric 4WD pickup sales across the four launch markets are estimated to have grown from approximately 100 units in 2025 to an annualized pace of approximately 1,200 units in 2026. This still accounts for less than 1% of new 4WD pickup sales. In the table below, the 2026E EV and hybrid column is broader than battery-electric models and also includes plug-in hybrid and full-hybrid 4WD pickups.

The table below sets out Tembo’s estimates of new pickup truck sales in each launch country. Four-wheel-drive models account for approximately 80% of the approximately 278,000 new pickups estimated to be sold across the four markets in 2026. The 4WD share is highest in Australia and New Zealand, at approximately 89% in both markets, and lower in the Philippines and Nepal, at approximately 32% and 25% respectively.

Estimated 4WD Pickup Markets in Tembo KOVA Launch Countries1

MarketAll new pickups, 2026E (units)2New 4WD EV and hybrid pickups, 2026E (units)3New 4WD pickups, 2026E (units)3Est. market value p.a., 2026E (local currency)4Est. market value p.a., 2026E (US$)5
Australia~209,000~24,800~186,400A$11.2 billionUS$7.7 billion
New Zealand~27,000~2,950~24,000NZ$1.48 billionUS$0.8 billion
Philippines~38,000~2,300~12,000PHP 26.8 billionUS$0.4 billion
Nepal6~4,180~50~1,030NPR 6.8 billionUS$0.1 billion
Total~278,000~30,100~223,400n/a~US$9.0 billion


1
“All new pickups” covers every new pickup truck sold, both two-wheel drive (4×2) and four-wheel drive (4×4), across all powertrains. “New 4WD pickups” is the four-wheel-drive subset only, which is the segment in which Tembo KOVA competes. Two-wheel-drive pickups, which make up most of the pickup market in the Philippines and Nepal, are excluded from the 4WD columns and from the estimated market values.

2 Company estimates of all new pickup trucks, two-wheel drive and four-wheel drive. Australia: Federal Chamber of Automotive Industries (FCAI) VFACTS 4×2 and 4×4 pickup/cab-chassis segments under A$100,000, with 2026E based on annualized January to October 2026 VFACTS 4×2 and 4×4 sales; excludes approximately 9,000 US full-size pickups a year. New Zealand: estimated from reported 4×2 and 4×4 registrations. Philippines: based on industry association reporting (excluding the Toyota Tamaraw utility vehicle) without the non-reporting-distributor adjustment included in the 4WD estimate in note 3; the implied Philippine 4WD share therefore reflects different coverage bases. Nepal: all pickup imports, including single cab and electric models, for fiscal year 2082/83.

3 Company estimates. Australia: 2026E based on FCAI VFACTS January to October 2026 4×4 pickup sales plus November to December 2025 sales adjusted for the year-to-date change. New Zealand and the Philippines: estimated from industry light commercial vehicle data and model-level 4×4 shares, as no official 4WD pickup series is published. Excludes US full-size pickups. EV and hybrid 4WD pickups (a subset of New 4WD pickups) include battery-electric, plug-in hybrid (including externally chargeable range-extended) and full-hybrid 4WD pickups, and exclude 48-volt mild hybrids and two-wheel-drive models. These are rounded Company estimates derived from available sales, registration and import data and assumed model and drivetrain mixes, within estimated ranges of approximately 23,900 to 26,100 units for Australia, 2,790 to 3,115 for New Zealand, 1,400 to 3,400 for the Philippines and 30 to 85 for Nepal. Nepal uses fiscal year 2082/83 imports as a proxy for sales. Philippine 4WD pickup estimates include an adjustment of approximately 2,000 units for distributors that do not report to the industry association, and Philippine EV and hybrid estimates are particularly uncertain.

4 Units multiplied by estimated average retail prices including local taxes: Australia A$60,300 (list price before on-road costs); New Zealand NZ$61,500; Philippines PHP 2.23 million; Nepal NPR 6.6 million. Figures represent total retail spend across all powertrains and are not a forecast of Tembo KOVA sales or revenue.

5 Converted at exchange rates on November 13, 2026: A$1 = US$0.6805; NZ$1 = US$0.5546; US$1 = PHP 63.56; US$1 = NPR 150.78.

6 Nepal: estimated from Department of Customs pickup import data and an assumed 4×4 share. 2026E is fiscal year 2082/83 (mid-July 2025 to mid-July 2026). This period is not directly comparable with the calendar-year estimates for the other markets.

Expanding Fleet Electrification Options

Tembo KOVA joins the Tembo Tusker (100% Electric) and Tembo EUV E-Power (E-Conversion) models, giving fleet operators a broader choice of electric utility solutions. Depending on fleet replacement cycles, operating conditions and total cost of ownership, Tembo can support customers considering either a new electric vehicle or the electrification of an existing vehicle.

Tembo’s fleet engagement approach considers duty cycles, load requirements, charging needs and potential operational savings. Aftersales support, parts availability and application-specific requirements form part of those customer discussions.

Vehicle Overview and Key Specifications

The five-seat dual cab combines an 88 kWh lithium iron phosphate (LFP) battery from CATL with a dual-motor 4WD drivetrain, for a manufacturer-stated range of up to 510 km on the CLTC laboratory test cycle and 460 km on the WLTP cycle. The front motor delivers up to 70 kW and 165 Nm, and the rear motor delivers up to 130 kW and 320 Nm. Peak combined output is up to 200 kW and 485 Nm of torque.

Tembo KOVA has front coil springs, rear leaf springs, four-wheel disc brakes and a manufacturer-stated maximum payload of up to 1,200 kg and manufacturer-stated braked towing capacity of up to 3 metric tons (3,000 kg). AC and DC charging are supported through a CCS port, with DC charging from 20% to 80% in approximately 45 minutes. Manufacturer-listed safety equipment includes autonomous emergency braking (AEB), stability control, ABS with electronic brake-force distribution, hill hold, an electronic parking brake and front airbags. The cabin features a 12.3-inch display with Apple CarPlay and Android Auto. CATL, Apple CarPlay and Android Auto are trademarks of their respective owners.

Tembo KOVA: Key Specifications

DrivetrainFour-wheel drive; front and rear motors
Battery88 kWh LFP, CATL
Peak motor powerFront 70 kW; rear 130 kW
Peak motor torqueFront 165 Nm; rear 320 Nm
Peak combined output200 kW; 485 Nm
RangeUp to 510 km (CLTC) and 460 km (WLTP); laboratory cycles, manufacturer-stated
DC charging (20% to 80%)Approximately 45 minutes, CCS
Towing capacityUp to 3 metric tons (3,000 kg), braked (within GCM)
PayloadUp to 1,200 kg (manufacturer-stated; reduced by occupants, options and tongue weight)
GVM and GCM3,520 kg and 6,520 kg respectively
Curb weight2,180 kg
Dimensions (L × W × H)5,624 × 1,920 × 1,865 mm
Wheelbase3,513 mm
Ground clearance200 mm
Tray (dual cab)1,810 × 1,620 × 515 mm
Seating5
Top speed120 km/h


Note: Specifications are manufacturer-stated figures for the reference configuration and remain subject to change, local homologation and final market configuration. Maximum payload and towing cannot necessarily be achieved simultaneously. CLTC range, which typically yields higher figures than WLTP, and DC charging times are laboratory or test figures; actual range and charging speeds vary with load, towing, terrain, weather and charger output.

About VivoPower

Originally founded in 2014 and listed on Nasdaq since 2016, VivoPower is an award-winning B Corporation with data center and powered land infrastructure across Norway, Finland, and the United Arab Emirates. The Company’s mission is to be the independent, trusted partner for sovereign nations that develop and operate sustainable data center infrastructure, ensuring sovereign control over power, data, and national intelligence. In doing so, VivoPower helps sovereign nations bridge the gap between their energy assets and their AI ambitions by providing the Power-to-X infrastructure necessary to build and control their own domestic intelligence hubs.

About Tembo

Tembo provides electric utility vehicle solutions for ruggedized off-road, on-road and customized fleet applications across sectors including mining, agriculture, energy, construction, infrastructure, government and safari tourism. Its portfolio includes new electric utility vehicles and conversion solutions designed to help fleet owners evaluate electrification opportunities and optimize asset utilization. Tembo is a subsidiary of VivoPower.

Forward-Looking Statements

This communication includes certain statements that may constitute “forward-looking statements” for purposes of the U.S. federal securities laws. Forward-looking statements include, but are not limited to, statements that refer to projections, forecasts, or other characterizations of future events or circumstances, including any underlying assumptions. The words “anticipate,” “believe,” “continue,” “could,” “estimate,” “expect,” “intends,” “may,” “might,” “plan,” “possible,” “potential,” “predict,” “project,” “should,” “would” and similar expressions may identify forward-looking statements, but the absence of these words does not mean that a statement is not forward-looking. Forward-looking statements may include, for example, statements about the specifications, performance, pricing and availability of Tembo KOVA, anticipated interest from customers and fleet operators, the expansion of Tembo’s fleet electrification portfolio, estimates of the size, value and growth of the markets for new 4WD pickup trucks and battery-electric 4WD pickup trucks in Australia, New Zealand, the Philippines and Nepal, or the benefits of the events or transactions described in this communication. These statements are based on VivoPower’s management’s current expectations or beliefs and are subject to risk, uncertainty, and changes in circumstances. Actual results may vary materially from those expressed or implied by the statements herein due to changes in economic, business, competitive and/or regulatory factors, and other risks and uncertainties affecting the operation of VivoPower’s business. These risks, uncertainties and contingencies include changes in business conditions, fluctuations in customer demand, changes in accounting interpretations, management of rapid growth, intensity of competition from other providers of products and services, changes in general economic conditions, geopolitical events and regulatory changes, and other factors set forth in VivoPower’s filings with the United States Securities and Exchange Commission. Specifically in relation to Tembo KOVA, vehicle specifications and performance figures are stated figures that may be subject to change, range figures are based on the CLTC and WLTP laboratory test cycles and actual range will vary, and the timing, locations, pricing and ordering arrangements for the vehicle have not yet been finalized. Commercial availability in each market is subject to local vehicle homologation and regulatory approvals, with market-specific specifications, pricing, ordering arrangements and delivery timing to be confirmed. Market size, market value and electric vehicle sales figures are Company estimates derived from third-party industry and customs data, modeled assumptions, average retail prices and exchange rates as of November 13, 2026; they are not forecasts of Tembo KOVA sales or revenue, and actual market volumes, prices and growth may differ materially. Additional risks include reliance on third-party vehicle and battery suppliers; delays in or failure to obtain market-specific homologation and other approvals; changes to specifications following validation or customer trials; supply, logistics, warranty, servicing and parts constraints; charging availability; changes in vehicle taxes, incentives and energy prices; and failure to convert customer interest into orders, deliveries and profitable sales. Market estimates involve classification, reporting-period, pricing and exchange-rate assumptions, and historical figures are not forward-looking statements merely because they are described as estimates. The information set forth herein should be read in light of such risks. VivoPower is under no obligation to, and expressly disclaims any obligation to, update or alter its forward-looking statements whether as a result of new information, future events, changes in assumptions or otherwise, except as required by applicable law.

Contact

Shareholder Inquiries
[email protected]
Release – SelectQuote, Inc. Announces 1-for-20 Reverse Stock Split

Select Quote

Research News and Market Data on SLQT

11/13/2026

OVERLAND PARK, Kan.–(BUSINESS WIRE)– SelectQuote, Inc. (NYSE: SLQT) (“SelectQuote” or the “Company”) today announced that its board of directors (the “Board”) has approved a 1-for-20 reverse stock split of the Company’s common stock and a proportionate reduction in the number of authorized shares of common stock. At the Company’s Annual Meeting of Stockholders (the “Annual Meeting”) on November 10, 2026, the Company’s stockholders approved an amendment to the Company’s Sixth Amended and Restated Certificate of Incorporation to effect a reverse stock split at a ratio between 1-for-10 and 1-for-20, with the exact ratio to be determined by the Board.

The reverse stock split is intended to help the Company regain compliance with the minimum stock price requirement for continued listing on the New York Stock Exchange.

“This is an important step that aligns with our commitment to remain listed on the NYSE. While we do not believe our current equity valuation reflects the strength of our business, SelectQuote remains an industry leader with a compelling opportunity ahead. Our differentiated insurance distribution and healthcare services businesses, improving cash flow profile, and strong balance sheet provide a solid foundation for continued growth. We expect to generate more than $60 million in operating cash flow this year and have a commissions receivable balance in excess of $1 billion. Together, these strengths position SelectQuote to continue innovating, leading our markets, and delivering world-class service to the millions of customers we serve.” said Tim Danker, SelectQuote’s CEO.

The reverse stock split is expected to become effective at 11:59 p.m. Eastern Time on November 16, 2026. Shares of the Company’s common stock are expected to begin trading on a split-adjusted basis on the New York Stock Exchange at market open on November 17, 2026 under the existing trading symbol “SLQT” and a new CUSIP number of 816307 409.

Information for SelectQuote Stockholders

In connection with the reverse stock split, every 20 shares of the Company’s common stock issued and outstanding immediately prior to the effective time will be automatically reclassified and combined into 1 share of common stock. The 1-for-20 reverse stock split will reduce the number of outstanding shares of the Company’s common stock from 180,185,985 to approximately 9,009,299. Proportional adjustments will be made to the number of shares of the Company’s common stock subject to outstanding equity awards and warrants, as well as the applicable exercise price. The total number of authorized shares of the Company’s common stock will be reduced from 700,000,000 to 35,000,000.

Computershare Trust Company, N.A., the transfer agent for the Company’s common stock, will act as the exchange agent, and may be contacted at (800) 736-3001.

No fractional shares of common stock will be issued as a result of the reverse stock split. Any stockholders of common stock who would have been entitled to receive fractional shares as a result of the reverse stock split will instead receive cash payments in lieu of such fractional shares.

For more information on the reverse stock split, please refer to the proxy materials in connection with the Annual Meeting, which materials can be accessed through the investor relations portion of the Company’s website at ir.selectquote.com and on the United States Securities and Exchange Commission’s (“SEC”) EDGAR website, sec.gov.

Forward Looking Statements

This release contains forward-looking statements. These forward-looking statements reflect our current views with respect to, among other things, future events and our financial performance. These statements are often, but not always, made through the use of words or phrases such as “may,” “should,” “could,” “predict,” “potential,” “believe,” “will likely result,” “expect,” “continue,” “will,” “anticipate,” “seek,” “estimate,” “intend,” “plan,” “projection,” “would” and “outlook,” or the negative version of those words or other comparable words or phrases of a future or forward-looking nature. These forward-looking statements are not historical facts, and are based on current expectations, estimates and projections about our industry, management’s beliefs and certain assumptions made by management, many of which, by their nature, are inherently uncertain and beyond our control. Accordingly, we caution you that any such forward-looking statements are not guarantees of future performance and are subject to risks, assumptions and uncertainties that are difficult to predict. Although we believe that the expectations reflected in these forward-looking statements are reasonable as of the date made, actual results may prove to be materially different from the results expressed or implied by the forward-looking statements. There are or will be important factors that could cause our actual results to differ materially from those indicated in these forward-looking statements, including, but not limited to, the following: our reliance on a limited number of insurance carrier partners and any potential termination of those relationships or failure to develop new relationships; existing and future laws and regulations affecting the health insurance market; changes in health insurance products offered by our insurance carrier partners and the health insurance market generally; insurance carriers offering products and services directly to consumers; changes to commissions paid by insurance carriers and underwriting practices; competition with brokers, exclusively online brokers and carriers who opt to sell policies directly to consumers; competition from government-run health insurance exchanges; developments in the U.S. health insurance system; our dependence on revenue from carriers in our senior segment and downturns in the senior health as well as life, automotive and home insurance industries; our ability to develop new offerings and penetrate new vertical markets; risks from third-party products; failure to enroll individuals during the Medicare annual enrollment period; our ability to attract, integrate and retain qualified personnel; our dependence on lead providers and ability to compete for leads; failure to obtain and/or convert sales leads to actual sales of insurance policies; access to data from consumers and insurance carriers; accuracy of information provided from and to consumers during the insurance shopping process; cost-effective advertisement through internet search engines; ability to contact consumers and market products by telephone; our use of artificial intelligence and other emerging technologies; global economic conditions, including inflation; disruption to operations as a result of future acquisitions; significant estimates and assumptions in the preparation of our financial statements; impairment of goodwill; potential litigation and other legal proceedings or inquiries; our existing and future indebtedness; our ability to maintain compliance with our debt covenants; access to additional capital; our ability to regain and maintain compliance with NYSE listing standards; failure to protect our intellectual property and our brand; fluctuations in our financial results caused by seasonality; accuracy and timeliness of commissions reports from insurance carriers; timing of insurance carriers’ approval and payment practices; factors that impact our estimate of the constrained lifetime value of commissions per policyholder; changes in accounting rules, tax legislation and other legislation; disruptions or failures of our technological infrastructure and platform; failure to maintain relationships with third-party service providers; cybersecurity breaches or other attacks involving our systems or those of our insurance carrier partners or third-party service providers; our ability to protect consumer information and other data; failure to market and sell Medicare plans effectively or in compliance with laws; and other factors related to our pharmacy business, including manufacturing or supply chain disruptions, access to and demand for prescription drugs, changes in reimbursement rates under our contracts with pharmacy benefit managers, and regulatory changes or other industry developments that may affect our pharmacy operations. For a further discussion of these and other risk factors that could impact our future results and performance, see the section entitled “Risk Factors” in the most recent Annual Report on Form 10-K and subsequent periodic reports filed by us with the Securities and Exchange Commission. Accordingly, you should not place undue reliance on any such forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and, except as otherwise required by law, we do not undertake any obligation to publicly update or review any forward-looking statement, whether as a result of new information, future developments or otherwise.

About SelectQuote:

Founded in 1985, SelectQuote (NYSE: SLQT) pioneered the model of providing unbiased comparisons from multiple, highly-rated insurance companies, allowing consumers to choose the policy and terms that best meet their unique needs. Two foundational pillars underpin SelectQuote’s success: a strong force of highly-trained and skilled agents who provide a consultative needs analysis for every consumer, and proprietary technology that sources and routes high-quality leads. Today, the Company operates an ecosystem offering high touchpoints for consumers across insurance, pharmacy, and virtual care.

With an ecosystem offering engagement points for consumers across insurance, Medicare, pharmacy, and value-based care, the company now has three core business lines: SelectQuote Senior, SelectQuote Healthcare Services, and SelectQuote Life. SelectQuote Senior serves the needs of a demographic that sees around 10,000 people turn 65 each day with a range of Medicare Advantage and Medicare Supplement plans. SelectQuote Healthcare Services is comprised of the SelectRx Pharmacy, a Patient-Centered Pharmacy Home™ (PCPH) accredited pharmacy, SelectPatient Management, a provider of chronic care management services, and Healthcare Select which proactively connects consumers with a wide breadth of healthcare services supporting their needs.

Investor Relations:
Sloan Bohlen
877-678-4083
[email protected]

Media:
Matt Gunter
913-286-4931
[email protected]

Source: SelectQuote, Inc.

Release – CVG Announces Inducement Grants Under Nasdaq Listing Rule 5635(c)(4)

CVG-Corporate

Research News and Market Data on CVGI

November 12, 2026

NEW ALBANY, Ohio, Nov. 12, 2026 (GLOBE NEWSWIRE) — CVG (NASDAQ: CVGI) (“CVG” or the “Company”), a diversified industrial products and services company, today announced that, in connection with the previously announced appointment of David Ruppel as President and Chief Executive Officer effective November 9, 2026, CVG granted Mr. Ruppel equity awards as a material inducement to his acceptance of employment with CVG in accordance with Nasdaq Listing Rule 5635(c)(4). The awards were approved by CVG’s independent directors on October 30, 2026 and were granted outside of CVG’s Second Amended and Restated 2020 Equity Incentive Plan (the “Plan”), but are subject to terms and conditions consistent with those of awards granted under the Plan.

On November 9, 2026, CVG granted Mr. Ruppel the following awards:

  • Make-whole awards in respect of unvested equity awards that Mr. Ruppel forfeited upon leaving his prior employer, Littelfuse, Inc., consisting of (i) 611,481 restricted shares of CVG common stock, which vest 50% on each of November 9, 2027 and November 9, 2028, and (ii) 384,552 performance shares at target (up to 769,104 shares at maximum), which may be earned from 0% to 200% of target based on CVG’s relative total shareholder return for the performance period from January 1, 2027 through December 31, 2028 and, to the extent earned, vest on December 31, 2028; and
  • An initial long-term incentive award with a target value of $1,600,000, consisting of (i) 198,757 restricted shares of CVG common stock, which vest in three substantially equal annual installments on March 31, 2028, March 31, 2029 and March 31, 2030, and (ii) 298,136 performance shares at target (up to 596,272 shares at maximum), which may be earned from 0% to 200% of target based on the same performance measures, weightings, goals and payout methodology to be established for the 2027 performance share awards to CVG’s other executive officers, for the performance period from January 1, 2027 through December 31, 2029 and, to the extent earned, vest on December 31, 2029.

In the aggregate, the awards cover 2,175,614 shares of CVG common stock, assuming maximum performance under the performance share awards. The number of shares subject to the awards was determined using the November 9, 2026 closing prices of CVG common stock and, for the make-whole awards, Littelfuse, Inc. common stock. Vesting of the awards is generally subject to Mr. Ruppel’s continued employment with CVG through the applicable vesting date, subject to accelerated vesting in certain circumstances as provided in the applicable award agreements. The restricted shares will vest in full upon Mr. Ruppel’s death or disability, upon a termination of his employment by CVG without cause or by him for good reason within 13 months following a change in control, or upon a change in control in which the restricted shares are not assumed or substituted, and the performance shares will be earned at the greater of target and actual performance upon a change in control.

About CVG

CVG is a global provider of systems, assemblies and components to global commercial vehicle markets and electric vehicle markets. We deliver real solutions to complex design, engineering and manufacturing problems while creating positive change for our customers, industries and communities we serve. Information about the Company and its products is available on the internet at www.cvgrp.com.

Investor Relations Contact:
Ross Collins or Nathan Skown
Alpha IR Group
[email protected]

Primary Logo

Source: Commercial Vehicle Group, Inc.

Release – QuoteMedia Reports 9% Revenue Growth for Q3 2026

Primary Logo

Research News and Market Data on QMCI

PHOENIX, Nov. 12, 2026 (GLOBE NEWSWIRE) — QuoteMedia, Inc. (OTCQB: QMCI), a provider of financial market data and technology solutions, today announced financial results for the quarter ended September 30, 2026. Revenue increased 9% to $5.6 million, compared with $5.2 million for the same period in 2025.

For more than two decades, QuoteMedia has focused on becoming the market data and technology partner financial institutions can rely on for comprehensive solutions, responsive service and compelling value.

Today, banks, brokerage firms, wealth managers, private equity firms and other financial organizations are increasingly seeking flexible, cost-effective alternatives to traditional market data providers. QuoteMedia addresses that demand through a broad suite of streaming market data feeds, XML/JSON APIs, financial content and analytics, and desktop and mobile applications including Quotestream Professional.

Our technology platform is designed to support organizations ranging from emerging financial firms to large-scale enterprise deployments. The breadth of our solutions allows clients to consolidate services with a single provider while giving QuoteMedia opportunities to expand those relationships as client requirements grow.

Highlights for Q3 2026 include the following:

  • Quarterly revenue increased 9%, or $446,872, to $5,601,427 in Q3 2026 from $5,154,555 in Q3 2025.
  • Gross margin improved to 54%, compared with 48% in the same quarter last year.
  • Adjusted EBITDA(1) increased $85,327 to $462,989 in Q3 2026, compared with $377,662 in Q3 2025.
  • Net loss decreased $209,637 to $157,555 in Q3 2026, compared with a net loss of $367,192 in Q3 2025.

Management Commentary

“We are pleased with the progress QuoteMedia has made during the third quarter, with year-over-year improvements across all of our key financial performance measures,” said Robert J. Thompson, Chairman of the Board at QuoteMedia. “We achieved solid revenue growth, expanded our gross margins, increased adjusted EBITDA, and significantly reduced our net loss. These results reflect the ongoing benefits of our focus on operational performance, continued demand for our market data and technology solutions, and our success in securing new business.

“During the quarter, we completed several significant new client agreements, further strengthening our enterprise customer base and expanding our revenue opportunities. We are also in the final stages of contract review with another major prospective client, a large financial institution, for which project work is already underway. We anticipate bringing this agreement to completion in the near term. These developments, combined with a strong pipeline of additional enterprise opportunities, position us well for continued growth.”

Reported earnings continue to reflect the accounting treatment and timing of development investments made in prior periods. As our development activities increasingly focus on enhancing, refining, and maintaining our existing product suite, a greater proportion of current development expenditures are recognized as operating expenses rather than capitalized. At the same time, amortization of development costs capitalized in previous periods remains elevated, though the impact of these historical development costs on reported earnings is expected to diminish over time as those assets fully amortize. These factors continue to affect reported earnings and EBITDA, but do not represent a corresponding reduction in current-period cash flow.

Outlook

“We believe the improvements achieved during the third quarter reflect positive underlying momentum in our business as we showed gains across all key metrics, and we expect this momentum to continue through the fourth quarter and in fiscal 2027,” added Robert J. Thompson. “The successful completion of several significant new client agreements and the advancement of additional major enterprise opportunities provide a solid foundation for future growth.

“Our sales pipeline remains strong, and we continue to see opportunities to expand our relationships with existing clients, attract new enterprise customers, and broaden the reach of our market data and technology solutions. With several new enterprise agreements now secured and additional significant opportunities nearing completion, we expect these relationships to contribute increasingly to revenue as implementation progresses through the remainder of 2026 and into 2027. We remain focused on executing our growth strategy, improving operating performance, and building sustainable long-term value for our shareholders.”

Conference Call Details

QuoteMedia will host a conference call on Friday, November 13, 2026, at 2:00 PM Eastern Time to discuss our Q3 2026 financial results and provide a business update.

Conference Call Details:

Date: November 13, 2026

Time: 2:00 PM Eastern

Conference Link “Dial Me”: https://link.meetingpanel.com/?id=quotemedia-q3-results

Dial-in numbers: 888-999-3182 Primary, 848-280-6330 Alternate

Conference ID: 3818457 PIN: 2420

An audio rebroadcast of the call will be available later at: www.quotemedia.com 

About QuoteMedia

QuoteMedia is a leading software developer and cloud-based syndicator of financial market information and streaming financial data solutions to media, corporations, online brokerages, and financial services companies. The Company licenses interactive stock research tools such as streaming real-time quotes, market research, news, charting, option chains, filings, corporate financials, insider reports, market indices, portfolio management systems, and data feeds. QuoteMedia provides industry leading market data solutions and financial services for companies such as the Nasdaq Stock Exchange, TMX Group (TSX Stock Exchange), Canadian Securities Exchange (CSE), London Stock Exchange Group, FIS, U.S. Bank, Bank of Montreal (BMO), Broadridge Financial Systems, JPMorgan Chase, Scotiabank, CI Financial, Canaccord Genuity Corp., Hilltop Securities, Zacks Investment Research, Bombardier, Telus International, Business Wire, PR Newswire, The Goldman Sachs Group, Regal Securities, ChoiceTrade, Cetera Financial Group, Dynamic Trend, Inc., Aviso Financial Inc., Securities, CNW Group, iA Private Wealth, Ally Invest, Inc., Suncor, Leede Jones Gable, Firstrade Securities, Charles Schwab, First Financial, Stock-Trak, Mergent, Cision and others. Quotestream®, QMod™ and Quotestream Connect™ are trademarks of QuoteMedia. For more information, please visit www.quotemedia.com.

Forward-Looking Statements

Statements about QuoteMedia’s future expectations, including future revenue, earnings, growth trajectory, pipeline opportunities, product development, and all other statements in this press release other than historical facts are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. QuoteMedia intends that such forward-looking statements be subject to the safe harbors created thereby. These statements are based on current expectations, estimates, and projections about the company’s business based, in part, on assumptions made by management. These statements are not guarantees of future performance and involve risks, uncertainties, and assumptions that are difficult to predict. Therefore, actual outcomes and results may differ materially from what is expressed or forecasted in such forward-looking statements due to numerous factors, including those described from time to time in the Company’s SEC reports and filings, which are available at www.sec.gov. All forward-looking statements speak only as of the date on which they are made, and the Company does not undertake any obligation to update any forward-looking statement to reflect events or circumstances after the date of this release.

Below are the specific forward-looking statements included in this press release:

  • We anticipate bringing this agreement to completion in the near term. These developments, combined with a strong pipeline of additional enterprise opportunities, position us well for continued growth.
  • We believe the improvements achieved during the third quarter reflect positive underlying momentum in our business, and we expect this momentum to continue through the fourth quarter and throughout fiscal 2027.
  • With several new enterprise agreements now secured and additional significant opportunities nearing completion, we expect these relationships to contribute increasingly to revenue as implementation progresses through the remainder of 2026 and into 2027.

QuoteMedia Investor Relations

Dave Shworan
Email: [email protected] 
Call: (250) 954-3216 ext. 2101

View full release here.

Release – Eledon Pharmaceuticals Reports Third Quarter 2026 Financial Results and Recent Business Highlights

Research News and Market Data on ELDN

November 12, 2026

PDF Version

Planned global Phase 3 LEGACY trial of tegoprubart in kidney transplantation remains on track to initiate in Q4 2026

FDA cleared the Company’s IND application for a planned registrational path study of tegoprubart in islet cell transplantation for patients with type 1 diabetes

FDA Fast Track designation granted to tegoprubart for the prevention of rejection in kidney transplantation

Cash, cash equivalents and short-term investments of $69.7 million with cash runway into Q2 2027

IRVINE, Calif., Nov. 12, 2026 (GLOBE NEWSWIRE) — Eledon Pharmaceuticals, Inc. (“Eledon”) (Nasdaq: ELDN) today reported its third quarter 2026 operating and financial results and provided recent business highlights.

“We continue to execute across our key strategic priorities and make meaningful progress in the tegoprubart clinical program across multiple transplant types, including plans to initiate our global Phase 3 LEGACY trial in kidney transplantation by year end,” said David-Alexandre C. Gros, M.D., Chief Executive Officer of Eledon. “New patient-reported outcomes data from the Phase 2 BESTOW program further strengthened the evidence supporting tegoprubart’s differentiated profile compared to today’s standard of care immunosuppression therapy, while investigator-initiated studies and compassionate-use protocols help expand our understanding of tegoprubart and its therapeutic potential in different transplant settings where significant unmet needs remain.”

Third Quarter 2026 Business Highlights

Kidney Transplantation

  • New patient-reported outcomes data from the Phase 2 BESTOW clinical program were presented at the American Society of Nephrology (ASN) Kidney Week 2026 Annual Meeting in October 2026. Results demonstrated sustained improvements in quality of life and symptom burden in kidney transplant recipients treated with tegoprubart compared with tacrolimus, today’s standard of care immunosuppression therapy. Tegoprubart-treated patients demonstrated a mean improvement on the total Modified Transplant Symptom Occurrence and Symptom Distress Scale (MTSOSD-59R) at 12 months while tacrolimus-treated patients experienced a mean worsening of symptom occurrence. Patients treated with tegoprubart also experienced a statistically significant improvement on the Kidney Disease Quality of Life Short Form (KDQOL-SF) Symptoms and Problems Scale through 12 months following transplantation compared with tacrolimus.
  • Updated long-term data from the Phase 2 BESTOW extension study were presented at the International Congress of the Transplantation Society (TTS) in September 2026. Tegoprubart-treated patients maintained statistically significantly higher mean estimated glomerular filtration rate (eGFR) at 18, 21, and 24 months, with an approximately 13 mL/min/1.73m2 advantage over tacrolimus at month 24 (71 vs. 58 mL/min/1.73m2 (95% CI: 2.6, 23.3)). There were no reported cases of biopsy-proven acute rejection (BPAR) in the tegoprubart arm beyond six months post-transplant compared with seven BPAR events in the tacrolimus arm.
  • The first highly sensitized kidney transplant patient was dosed with tegoprubart under a compassionate-use protocol at Duke University Medical Center. Highly sensitized patients requiring a kidney transplant face a substantial unmet need because pre-existing antibodies can significantly limit access to compatible donor organs and increase the risk of antibody-mediated rejection and graft loss post-transplant.
  • The third patient was treated as part of the investigator-initiated study evaluating tegoprubart for kidney transplant tolerance induction at Massachusetts General Hospital (MGH).
  • Tegoprubart received Fast Track designation from the U.S. Food and Drug Administration (FDA) for the prevention of rejection in kidney transplantation.

Islet Cell Transplantation

  • The FDA cleared the Investigational New Drug (IND) application for a planned Company-sponsored, registrational path clinical trial evaluating tegoprubart for the prevention of allograft rejection in type 1 diabetes (T1D) patients undergoing pancreatic islet cell transplantation.
  • The first patients were enrolled in an investigator-initiated clinical trial underway at the University of Chicago Medicine Transplant Institute, evaluating tegoprubart for the prevention of allograft rejection in patients with T1D and renal dysfunction from chronic kidney disease who are receiving an islet cell transplant.
  • The first islet cell transplant recipient was dosed with tegoprubart under a compassionate-use protocol allowing patients to switch from tacrolimus-based immunosuppression therapy due to calcineurin inhibitor-related renal dysfunction.
  • The University of Chicago Medicine Transplant Institute expanded its ongoing investigator-initiated study evaluating tegoprubart as the core immunosuppressant for T1D patients undergoing islet cell transplantation by enrolling three additional subjects. This will help build on previously reported study results in the 12 patients treated to date, who have achieved 100% insulin independence and demonstrated stable islet graft function through 22 months of follow-up with a favorable tolerability profile. No evidence of nephrotoxicity, hypertension, or neurotoxicity, which are side effects often associated with calcineurin inhibitors such as tacrolimus, has been observed to date.

Anticipated Upcoming Milestones

The Company anticipates the following milestones over the next 12 months:

  • Initiate global Phase 3 LEGACY trial of tegoprubart in kidney transplantation in the fourth quarter of 2026. The LEGACY trial is expected to enroll approximately 600 patients, with a primary endpoint of non-inferiority of tegoprubart versus tacrolimus at 52 weeks based on a composite of BPAR, graft loss, and death.
  • Initiate a Company-sponsored, registrational path study evaluating tegoprubart in T1D patients undergoing islet cell transplantation.
  • Initiate an investigator-led study evaluating tegoprubart for the prevention of organ rejection in patients receiving a de novo liver transplant.
  • Receive FDA regulatory guidance on the path to market for tegoprubart in kidney xenotransplantation.

Third Quarter 2026 Financial Results

Cash, cash equivalents and short-term investments totaled $69.7 million as of September 30, 2026, compared to $133.3 million as of December 31, 2025. The Company expects cash, cash equivalents and short-term investments currently on hand to fund operations into Q2 2027.

Research and development (R&D) expenses for the third quarter of 2026 were $17.8 million, including $0.9 million of non-cash stock-based compensation expense, compared to $15.0 million, including $1.1 million of non-cash stock-based compensation expense, for the comparable period in 2025.

General and administrative (G&A) expenses for the third quarter of 2026 were $3.9 million, including $1.0 million of non-cash stock-based compensation expense, compared to $4.1 million, including $1.4 million of non-cash stock-based compensation expense, for the comparable period in 2025.

Net loss for the third quarter of 2026 was $3.9 million, or $0.03 per basic common share, compared to a net loss of $17.5 million, or $0.21 per basic common share, for the comparable period in 2025. Net loss in the third quarter of 2026 included a non-cash gain of $17.0 million from changes in the fair value of warrant liabilities, while the 2025 net loss included a non-cash gain of $0.6 million from such changes. Excluding the non-cash items related to changes in the fair value of warrant liabilities, Eledon would have recorded a net loss of $21.0 million for the three months ended September 30, 2026, and $18.0 million for the three months ended September 30, 2025.

About Eledon Pharmaceuticals and tegoprubart

Eledon Pharmaceuticals, Inc. is a clinical stage biotechnology company that is developing immune-modulating therapies for the management and treatment of life-threatening conditions. The Company’s lead investigational product is tegoprubart, an anti-CD40L antibody with high affinity for the CD40 Ligand, a well-validated biological target that has broad therapeutic potential. The central role of CD40L signaling in both adaptive and innate immune cell activation and function positions it as an attractive target for non-lymphocyte depleting, immunomodulatory therapeutic intervention. The Company is building upon a deep historical knowledge of anti-CD40L biology to conduct preclinical and clinical studies in kidney allograft transplantation, xenotransplantation, islet cell transplantation, liver transplantation, and amyotrophic lateral sclerosis (ALS). Eledon is headquartered in Irvine, California. For more information, please visit the Company’s website at www.eledon.com.

Follow Eledon Pharmaceuticals on social media: LinkedIn; X

Forward-Looking Statements

This press release contains forward-looking statements that involve substantial risks and uncertainties. Any statements about the Company’s future expectations, plans and prospects, including statements about planned clinical trials, the development of product candidates, expected timing for initiation of future clinical trials, expected timing for receipt of data from clinical trials, the Company’s capital resources and ability to finance planned clinical trials, as well as other statements containing the words “believes,” “anticipates,” “plans,” “expects,” “estimates,” “intends,” “predicts,” “projects,” “targets,” “looks forward,” “could,” “may,” and similar expressions, constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Specifically, our ability to achieve our anticipated future development and corporate milestones depends on our ability to obtain additional financing on acceptable terms. Forward-looking statements are inherently uncertain and are subject to numerous risks and uncertainties, including: our short operating history and shifts in our business strategy; our operating losses since inception; our need for additional funding to develop our lead drug candidate and our ability to secure additional funding on acceptable terms or at all; the impact of issuances of our common stock, including the possibility of dilution or a decline in our stock price; our ability to successfully develop our product candidates; unfavorable global economic and financial market conditions; the regulatory environment of our business and our ability to obtain required regulatory approvals; results of non-clinical studies and clinical trials, and risks that non-clinical studies or early clinical trials may not be predictive of results of later-stage clinical trials; delays or difficulties in enrollment of patients in clinical trials; our ability to attract and retain our executives and key employees; legislation of the pharmaceutical and healthcare industries; cybersecurity and data privacy risks; the ability of our products to achieve marketing approval; competition in our industry; our ability to obtain insurance coverage; our dependence on contract research organizations; our ability to protect our intellectual property; public health crises; our ability to maintain proper and effective internal control over financial reporting and other risks disclosed in our Annual Report on Form 10-K for the year ended December 31, 2025, filed with the Securities and Exchange Commission on March 19, 2026. Actual results may differ materially from those indicated by such forward-looking statements as a result of various factors. These risks and uncertainties, as well as other risks and uncertainties that could cause the Company’s actual results to differ materially from the forward-looking statements contained herein, are discussed in our Annual Report on Form 10-K, and other filings with the U.S. Securities and Exchange Commission, which can be found at www.sec.gov. Any forward-looking statements contained in this press release speak only as of the date hereof and not of any future date, and the Company expressly disclaims any intent to update any forward-looking statements, whether as a result of new information, future events or otherwise.

Investor Contact:

Stephen Jasper
Gilmartin Group
(858) 525-2047
[email protected]

Media Contact:

Jenna Urban
CG Life
(212) 253-8881
[email protected]

Primary Logo

Source: Eledon Pharmaceuticals, Inc.

View full release here.

SKYX Reports Record Revenue of $25.7M in Q-3 2026 Compared to $23.9M in Q-3 2025 and 11 Consecutive Quarters of Growth YoY

Research News and Market Data on SKYX

November 12, 2026 16:05 ET  | Source: SKYX Platforms Corp.

Gross profit rises in Q-3 by 11% to a record $8.1 million as SKYX continues to expand its market penetration

Company maintains a strong cash position with $21 million in cash, cash equivalents and restricted cash at September 30, 2026. Management believes it has sufficient cash to support its path to cash-flow positive

SKYX Deako merger expands the builder channel pipeline to approximately 4 million units with an expected average selling price of $50 per product

Since the merger, SKYX and Deako have announced they expect to supply approximately 210,000 units to three prominent builders

MIAMI, Nov. 12, 2026 (GLOBE NEWSWIRE) — SKYX Platforms Corp. (NASDAQ: SKYX) (the “Company” or “SKYX”), an award-winning, highly disruptive advanced plug and play smart home and AI platform technology company with over 120 U.S. and global pending and issued patents and with a mission to make homes and buildings advanced, smart and safe as the new standard, today reported financial and operating results for the third quarter and nine months ended September 30, 2026, and provided business updates.

SKYX will host a conference call today, November 12, 2026, at 4:30 p.m. Eastern Time to discuss the results and recent developments. Conference call and webcast information appears below.

Third Quarter 2026 Financial Highlights

  • Revenue increased 7.4% to $25.7 million from $23.9 million in the third quarter of 2025.
  • Gross profit increased 11% to $8.1 million from $7.3 million in the second quarter of 2026.
  • Gross margin increased by 9% to 31.4%, compared to 28.9% in the second quarter of 2026.
  • $21 million in cash, cash equivalents, and restricted cash as of September 30, 2026, compared with $10 million on December 31, 2025.
  • A majority of Company’s inventory payments to vendors are paid after the Company receives payments from its customers, continuing to leverage its rapid conversion of its e-commerce sales into cash, advancing its cash position using the “Dell Working Capital Model”, and lowering its cost of capital.
  • Net cash used in operating activities decreased by 15.5% to $4.2 million from $5.0 million in the third quarter of 2025. Management believes it has sufficient cash to support its path to cash flow positive.
  • Interest-bearing debt, after debt discounts, decreased $3.6 million to $14.7 million, maturing 2030, from $18.3 million at year-end.
  • Adjusted EBITDA loss, a non-GAAP measure, decreased 18.7% to $2.9 million from $3.5 million in the second quarter of 2026. Adjusted EBITDA loss per share, a non-GAAP measure, decreased to $0.02 compared with $0.03 in the second quarter of 2026.

Deako Merger and Builder Programs

Subsequent to quarter-end, SKYX completed its merger with Deako on October 13, 2026, combining SKYX’s ceiling-based plug-and-play and smart home technologies with Deako’s wall-based plug & play smart home and lighting platform. Deako generated revenues of more than $26 million in 2025, has shipped more than 35 million units over five years, and has provided its solutions to more than 50 U.S. homebuilders. Deako also recently extended supply agreements with D.R. Horton and Stone Martin. Following the merger, SKYX announced the following builder programs:

  • Maronda Homes: SKYX announced its first major builder program, with an expectation to supply more than 80,000 units of their smart home technologies to more than 1,000 homes, including projects in Ohio, Georgia, Maryland and Pennsylvania.
  • Home Creations: SKYX announced a second major builder program, with more than 60,000 units expected for more than 700 homes in Oklahoma and Texas.
  • Stone Martin: SKYX announced a third home builder program with approximately 70,000 units expected for more than 850 homes in Alabama and Georgia.
  • Together, the Home Creations, Maronda and Stone Martin home builder programs are expected to represent more than 210,000 units across more than 2,500 homes. Deliveries are expected through 2027.
  • The combined SKYX and Deako pipeline is estimated at approximately 4 million units, with an expected average selling price of approximately $50 per product.
  • Management believes the full product portfolio could increase Deako’s revenue per home by up to five times.
  • The merger is expected to reduce annual cash expenses by more than $6 million.
  • Merger is expected to create future revenue opportunities through product upgrades and interchangeability, AI-enabled services, monitoring, subscriptions and licensing.
  • In consideration for the merger, SKYX issued 25,000,000 shares of common stock, subject to a 12-month full lock-up (followed by quarterly leak-out releases at 12, 15, 18, and 21 months after the closing, with share sales subject to a Rule 10b5-1 trading plan).

Hospitality and International Expansion

  • SKYX signed an agreement to supply its technologies to two 65-story luxury Trump Towers in Hyderabad, India, comprising more than 2.2 million square feet. The Company expects to deploy tens of thousands of units in the project.
  • SKYX announced plans to supply its technologies to a Marriott city-center hotel renovation in Durham, North Carolina. In Europe, its technology is expected to become a brand standard for developer Group OTT, which has developed more than 250 hotels and buildings. Previously announced hotel projects included the Grand Hotel du Parc in France and the Hotel Mozart Prague, with OTT Heritage Hospitality supporting marketing to the broader European hotel market.
  • The Company’s future project opportunities include Miami’s $4 billion Smart City development and projects in North Carolina, Austin, San Antonio, South Florida, New York, Europe, Saudi Arabia and Egypt.

Retail Technology and Licensing

  • Turbo Heater Ceiling Fans. Company reported that based on growing sales and winter demand for its patented all-in-one turbo heater ceiling fan, it will launch an additional four models in larger and smaller sizes 20” 44” 52” and 60” and in five different colors including white, black, brush nickel, gold, and bronze in addition to its original 24” model across national retailers and its e-commerce platform comprised of multiple websites in the fourth quarter. Retail channel includes The Home Depot, Lowe’s, Target, Walmart, and Amazon.
  • Licensing. SKYX has signed a licensing agreement with lighting company Eurofase and plans to pursue additional licensing opportunities. It is also planning an AI-driven system for its e-commerce platform intended to improve conversion rates and sales. The Company has secured manufacturing partnerships in the United States, Vietnam, Taiwan, China and Cambodia.

Safety Code Standardization

  • Company’s code standardization team continues to pursue mandatory safety-code standardization for its electrical ceiling outlet and receptacle technology. The code team is led by Mark Earley, former head of the National Electrical Code (NEC), and Eric Jacobson, former President and CEO of the American Lighting Association. The Company’s reported progress includes ANSI/NEMA voting to approve its product specification and its technology being voted into 10 segments of the NEC Code Book. Mandatory adoption remains a Company objective.

Management Commentary

Company’s Management, Board members, and Senior Advisors include former CEO’s and executives from Fortune 100 companies including Nielsen, Microsoft, Disney, GE, The Home Depot, Office Depot, Chrysler, among others.

The Company reported revenue of $25.7 million for the third quarter of 2026, up 7.4% from $23.9 million in the third quarter of 2025. This marks the Company’s 11th consecutive quarter of year-over-year revenue growth. The Company continues to expand its channel strategy across the builder, professional, commercial, hospitality and retail markets.

Gross profit increased 11% to $8.1 million in the third quarter of 2026 from $7.3 million in the second quarter of 2026. Gross margin increased by 9% to 31.4%, compared to 28.9% in the second quarter of 2026. For the first nine months of 2026, gross profit increased 8.4% to $22.0 million from $20.3 million in the comparable 2025 period.

We are encouraged by the opportunities created by the Deako merger, completed after quarter-end on October 13, 2026. Deako’s established relationships with more than 50 U.S. homebuilders provide an additional sales channel for SKYX’s ceiling-based technologies alongside Deako’s plug & play wall-switch and intelligent lighting platform. Since the close of the merger, we announced supplying three prominent builders approximately 210,000 units to over 2,500 homes including Maronda Homes, Home Creations and Stone Martin. These follow recently announced builder initiatives where we could supply hundreds of thousands of units in India, Europe, the Middle East including Saudi Arabia and Egypt, the $4 billion mixed-use smart city development in the Little River District in the heart of Miami, and projects in Pittsford, New York; North Carolina; Austin, Texas; and San Antonio, Texas. We continue to address the builder/commercial segments, large online and brick-and-mortar retail partners as well as our future potential to realize revenues from licensing, subscription, monitoring, and AI services. The combined product portfolio of SKYX and Deako creates opportunities for upgrades, interchangeability and future recurring revenue.

Our e-commerce platform of 60 lighting and home décor websites continues to support marketing, distribution and sales to professional and retail customers. We also continue to pursue hospitality projects, international opportunities and technology licensing. Management is focused on its path towards being cash flow positive, supported by expected annual cash expense savings of more than $6 million from the Deako merger and expansion across our sales channels.

Third Quarter 2026 Financial Information

For SEC filings and financial information, visit the Company’s investor relations website at https://ir.skyplug.com/sec-filings/.

Non-GAAP Financial Measures
Management uses adjusted EBITDA, which adjusts GAAP net loss for interest, depreciation and amortization, share-based payments and other adjustments, as a supplemental measure to evaluate operating performance and inform financial and strategic planning. Adjusted EBITDA excludes significant expenses required by GAAP and is subject to inherent limitations. It should be considered in addition to GAAP net loss and cash flows used in operating activities. Investors should not rely on any single financial measure to evaluate the Company’s business.

About SKYX Platforms Corp. (NASDAQ: SKYX)

SKYX Platforms Corp. (NASDAQ: SKYX) is an advanced smart home, artificial intelligence (AI), and plug-and-play technology platform company with a mission to make homes and buildings safe, advanced, and smart as the new standard. Following its merger with Deako, Inc., SKYX combines complementary technologies designed to simplify the installation, integration, and upgrading of smart home and building systems across residential, commercial, builder, and hospitality markets.

The merged company offers a broad portfolio of plug-and-play platform technologies and products spanning ceiling and wall electrical infrastructure, intelligent lighting and switches, smart home and AI-enabled solutions, and other connected home and building applications. By bringing together SKYX’s ceiling-based technologies and Deako’s established wall-switch platform, the company enables a more comprehensive approach to smart homes and buildings, reducing the complexity associated with traditional wired installations while enhancing convenience, safety, and functionality.

SKYX has a combined portfolio of more than 120 issued and pending in the U.S. and internationally patents and patent applications relating to smart home and building platforms, AI, and plug-and-play technologies. Including its wholly owned subsidiary, Deako, SKYX has supplied and expects to supply plug & play smart lighting technologies to more than 60 U.S. homebuilders and builders. The merger expands SKYX’s opportunities across the homebuilder, professional, commercial, and hospitality markets, while creating potential for future recurring revenue through product upgrades and interchangeability, AI-enabled services, monitoring, subscriptions, and licensing.

In addition to its technology platforms, SKYX owns an e-commerce platform comprised of 60 e-commerce lighting and home décor websites serving retail and commercial customers. Through its combined technologies and product portfolio, SKYX is focused on advancing the adoption of smart, connected, and safer environments in homes and buildings across the United States and internationally.

For more information, please visit www.skyx.com and www.deako.com.

Forward-Looking Statements

Certain statements made in this press release are not based on historical facts but are forward-looking statements. These statements can be identified by the use of forward-looking terminology such as “aim,” “anticipate,” “believe,” “can,” “could,” “continue,” “estimate,” “expect,” “evaluate,” “forecast,” “guidance,” “intend,” “likely,” “may,” “might,” “objective,” “ongoing,” “outlook,” “plan,” “potential,” “predict,” “probable,” “project,” “seek,” “should,” “target,” “view,” “will,” or “would,” or the negative thereof or other variations thereon or comparable terminology, although not all forward-looking statements contain these words. These statements reflect the Company’s reasonable judgment with respect to future events and are subject to risks, uncertainties and other factors, many of which have outcomes difficult to predict and may be outside our control, that could cause actual results or outcomes to differ materially from those in the forward-looking statements. Such risks and uncertainties include statements relating to the Company’s ability to successfully launch, commercialize, develop additional features and achieve market acceptance of its products and technologies and integrate its products and technologies with third-party platforms or technologies; the Company’s ability to achieve positive cash flows and realize anticipated merger savings and other benefits; the Company’s efforts and ability to drive the adoption of its products and technologies as a standard feature, including their use in homes, hotels, offices and cruise ships; the Company’s ability to capture market share; the Company’s estimates of its potential addressable market and demand for its products and technologies; the Company’s ability to raise additional capital to support its operations as needed, which may not be available on acceptable terms or at all; the Company’s ability to continue as a going concern; the Company’s ability to execute on any sales and licensing or other strategic opportunities; the possibility that any of the Company’s products will become National Electrical Code (NEC)-code or otherwise code mandatory in any jurisdiction, or that any of the Company’s current or future products or technologies will be adopted by any state, country, or municipality, within any specific timeframe or at all; risks arising from mergers, acquisitions, joint ventures and other collaborations; the Company’s ability to attract and retain key executives and qualified personnel; guidance provided by management, which may differ from the Company’s actual operating results; the potential impact of unstable market and economic conditions, including recent measures adopted by the federal government, on the Company’s business, financial condition, and stock price; and other risks and uncertainties described in the Company’s filings with the Securities and Exchange Commission, including its periodic reports on Form 10-K and Form 10-Q. There can be no assurance as to any of the foregoing matters. Any forward-looking statement speaks only as of the date of this press release, and the Company undertakes no obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by U.S. federal securities laws.

Investor Relations Contacts

Jeff Ramson
PCG Advisory
[email protected]

Ronald A. Both
Encore Investor Relations
[email protected]
Dial-In Information:

Conference Call and Webcast Details

EventSKYX Platforms Corp. Third Quarter 2026 Earnings Conference Call
DateThursday, November 12, 2026
Time4:30 p.m. Eastern Time
Participant dial-inU.S./Canada (Toll-Free): 1-877-407-0792 or International: 1-201-689-8263
Webcasthttps://viavid.webcasts.com/starthere.jsp?ei=1782763&tp_key=c59bf1a1a2

Call me™: https://callme.viavid.com/viavid/?callme=true&passcode=13760591&h=true&info=company&r=true&B=6

Participants may use the dial-in numbers above and be assisted by an operator or use the Call me™ link for instant telephone access. The Call me™ link will become active 15 minutes before the scheduled start time.

Please connect at least 10 minutes before the start of the call to ensure timely participation.

Telephone Replay

A telephone replay is expected to be available approximately three hours after the conference call and will remain available through Saturday, December 12, 2026, at 11:59 p.m. Eastern Time.

Replay Dial-In:

  • U.S./Canada (Toll-Free): 1-844-512-2921
  • International: 1-412-317-6671

Access ID: 13763842

Release – Snail, Inc. Reports Third Quarter 2026 Financial Results

Snail, Inc logo

Research News and Market Data on SNAL

November 12, 2026 at 4:05 PM EST

PDF Version

CULVER CITY, Calif., Nov. 12, 2026 (GLOBE NEWSWIRE) — Snail, Inc. (Nasdaq: SNAL) (“Snail Games” or the “Company”), a leading global independent developer and publisher of interactive digital entertainment, today announced financial results for the third quarter ended September 30, 2026.

Third Quarter 2026 and Recent Operational Highlights

ARK Franchise Updates:

  • ARK: Survival Evolved (“ASE”):
    • Units sold were approximately 559,000 for the third quarter of 2026
    • During the third quarter of 2026, average daily active users (“DAU”) were approximately 99,000 and peak DAU was approximately 126,000
  • ARK: Survival Ascended (“ASA”):
    • Units sold were approximately 1.2 million for the third quarter of 2026
    • During the third quarter of 2026, average DAU was approximately 121,000 and peak DAU was approximately 184,000
    • Launched ARK: Genesis Part 1 Ascended, ARK: Tides of Fortune, and shadow-dropped ARK: Dragontopia
    • Released ARK: Dragontopia content updates in July and September 2026
    • Released the Cerberax fantastic tame under the ARK: Fantastic Tames Season 1 Pack
    • Released a major update for the ARK: Astraeos downloadable content (“DLC”)
    • Upcoming tames and content releases planned for ARK: Fantastic Tames Season 1 and ARK: Dragontopia in November and December 2026
  • ARK: Ultimate Mobile Edition (“ARK Mobile”)
    • Approximately 14.5 million downloads as of September 30, 2026
    • During the third quarter of 2026, average DAU was approximately 134,000
  • OtherARKIPs
    • Released PixARK: Terracrypt DLC
    • Debuted the first public demo of ARK: Survival of the Fittest during ChinaJoy 2026

Game Portfolio and Business Updates:

  • AAA Game Pipeline
    • Officially unveiled 9 Yin Sutra: Immortal at ChinaJoy 2026, revealing a new trailer and Steam page
    • Publicly debuted 9 Yin Sutra: Wuxia at Gamescom 2026, revealing a new trailer and Steam page
    • Showcased For The Stars at Gamescom 2026, releasing a new gameplay trailer and exclusive demos for attending media
    • Showcased 9 Yin Sutra: Immortal and For The Stars during the IGN Fan Fest event
  • Launched Honeycomb: The World Beyond across Steam, Epic Games Store, PlayStation 5, and Xbox Series X|S
  • Showcased a new playable demo of Bellwright at Gamescom 2026, previewing its highly requested traversal update planned for the end of 2026
  • Launched Stoneguard on Steam Early Access and achieved a “Mostly Positive” rating from Steam users to date
  • Launched The Fame Game II: LA Heartbreaker, receiving an “Overwhelmingly Positive” Steam rating to date with more than 500 reviews
  • Launched Dead Party on Steam
  • Released new demos for Dead Party, Whispers of West Grove, and Veil of Madness during Steam Next Fest

Business and Operational Updates

  • Egofold, the Company’s subsidiary, publicly debuted the AI Ranch initiative and Non-Human Player™ (NHP), an AI gaming companion for consumers, at the Ai4 2026 conference
  • As of September 30, 2026, SaltyTV released 350+ short film dramas

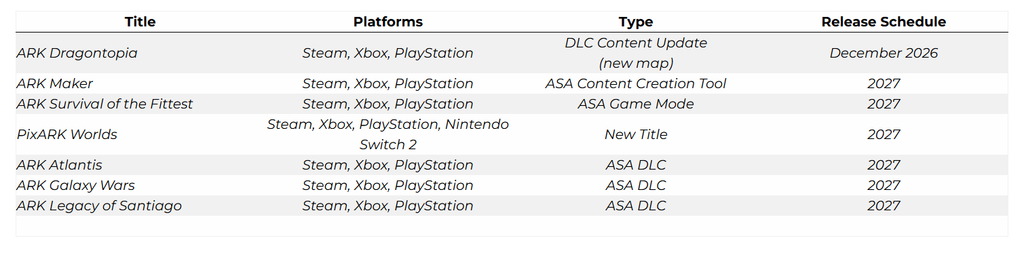
ARK Content Pipeline

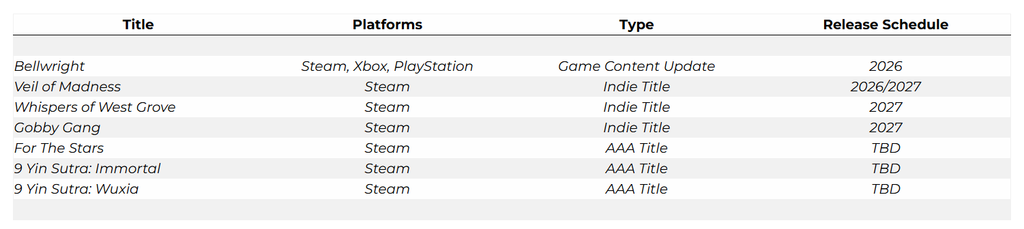
Diversified Content Pipeline

Management Commentary

“Our third quarter results reflected the continued execution of our ARK content pipeline, which extends through 2027 and remains a key driver of engagement and monetization across ASA,” said Snail CEO Hai Shi. “The release of three ASA DLCs at the beginning of the quarter provided a strong foundation for our performance, demonstrating the importance of our ongoing content strategy to expand the franchise’s reach and longevity.

“Beyond our revenue-generating ARK content, the past several months have provided valuable opportunities to showcase the breadth and progress of our broader development portfolio. We unveiled and publicly debuted our two 9 Yin Sutra titles at ChinaJoy and Gamescom, supported by new trailers and the official launch of their respective Steam pages. These milestones mark important steps in building early awareness and engagement, particularly among the IP’s established fan base in China. We also featured For The Stars at Gamescom, where we released a new gameplay trailer and offered exclusive demos to attending media, and again at IGN Fan Fest. The positive reception and continued development progress across these projects reinforce our confidence in the commercial potential of our AAA pipeline. As these highly anticipated titles continue advancing toward launch, industry events and community engagement initiatives remain important platforms to build momentum and provide players with greater visibility into our development progress.

“Looking ahead, we are encouraged by the opportunities in front of us. We expect our recently released titles, together with the anticipated ARK: Dragontopia skyworld map in December, to support fourth quarter performance. More importantly, our visibility beyond the current year remains strong. With an established ARK content roadmap extending throughout 2027 and multiple AAA titles continuing to make solid development progress toward key milestones, we believe we are well positioned to build on the momentum generated this year. Our focus remains on disciplined execution, consistent content delivery, and advancing our high-conviction development initiatives.”

Third Quarter 2026 Financial Highlights

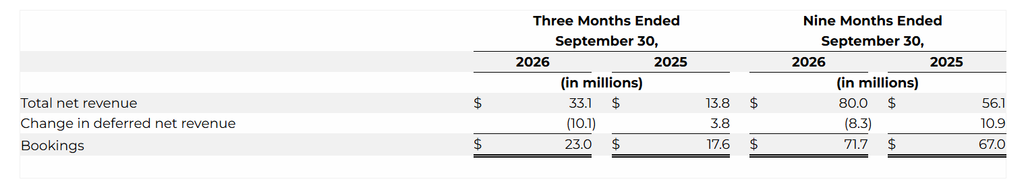
Net revenues increased 139.2% to $33.1 million compared to $13.8 million in the same period last year. The increase was primarily due to a $13.9 million change in deferred revenue, a $4.9 million increase in ASA sales, which was primarily driven by the base game and the release of ARK: Tides of Fortune and ARK: Dragontopia, a $1.0 million increase in Bellwright sales, and a $0.4 million increase in Honeycomb: The World Beyond sales, partially offset by a decrease of $0.5 million in ASE sales, a decrease of $0.2 million in ARK Mobile sales, and a decrease of $0.2 million in SaltyTV sales.

Total units sold increased 73.3% to 2.0 million units compared to 1.1 million units in the same period last year, primarily driven by increased sales of ASA by 0.7 million units and an increase in sales of Bellwright of 0.1 million units.

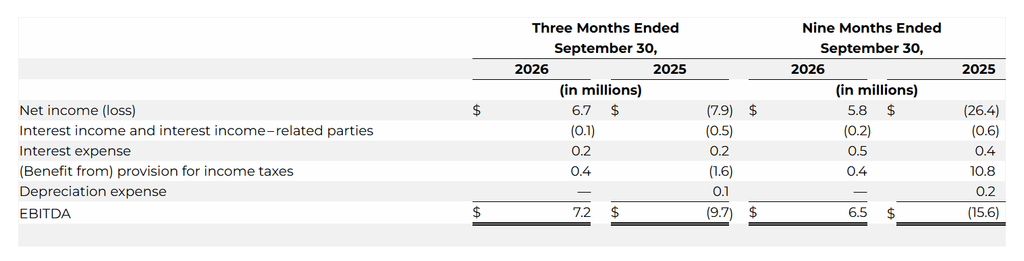
Net income improved to $6.7 million compared to a net loss of $(7.9) million in the same period last year. The increase was primarily due to an increase in gross profit of $17.6 million, partially offset by an increase in the provision for income taxes of $2.0 million, an increase in total operating expenses of $0.6 million, and an increase in total other expense of $0.5 million.

Bookings increased 30.4% to $23.0 million compared to $17.6 million in the same period last year. The increase was primarily due to higher sales of ASA and Bellwright, partially offset by a decrease in bookings from ASE.

EBITDA improved to $7.2 million compared to $(9.7) million in the same period last year. The increase was primarily driven by the $14.5 million increase in net income, a decrease in interest income and interest income – related parties of $0.4 million, and an increase in the provision of income taxes of $2.0 million.

Nine Months 2026 Financial Highlights

Net revenues increased 42.6% to $80.0 million compared to $56.1 million in the same period last year. The increase was primarily due to the change in deferred revenue of $19.2 million, an increase in ASA sales of $4.8 million, which was primarily driven by the sales of the base game, ARK: Bob’s Tall Tales, ARK: Lost Colony, and the newly released ARK: Tides of Fortune and ARK: Dragontopia, an increase of $4.6 million in Bellwright sales, and an increase of $0.4 million in Honeycomb: The World Beyond sales. The increase in revenue was partially offset by a decrease in ASE revenue of $3.2 million, a decrease in ARK Mobile revenue of $1.5 million, and a decrease in SaltyTV application revenue of $0.4 million.

Total units sold increased 28.0% to 6.2 million units compared to 4.8 million units in the same period last year, primarily due to an increase in ASA sales of 1.7 million units and an increase in Bellwright sales of 0.3 million units, partially offset by a decrease in ASE sales of 0.8 million units.

Net income improved to $5.8 million compared to a net loss of $(26.4) million in the same period last year. The improvement was primarily due to an increase in revenue of $23.9 million, a decrease in the provision of income taxes of $10.4 million, and a decrease in cost of revenue of $0.3 million, partially offset by an increase in total operating expenses of $1.9 million and total other expense of $0.6 million.

Bookings increased 7.0% to $71.7 million compared to $67.0 million in the same period last year. The increase was primarily due to higher sales of ASA and Bellwright, which benefited from promotional pricing during the period, offset by ASE as the title continued to mature and consumer demand shifted toward ASA and its related downloadable content.

EBITDA improved to $6.5 million compared to $(15.6) million in the same period last year. The increase was primarily due to an increase in net income of $32.1 million, partially offset by a decrease in provision for income taxes of $10.4 million.

As of September 30, 2026, unrestricted cash was $12.1 million compared to $8.6 million as of December 31, 2025.

Use of Non-GAAP Financial Measures

In addition to the financial results determined in accordance with U.S. generally accepted accounting principles, or GAAP, Snail believes EBITDA, as a non-GAAP measure, and Bookings as a key operating metric, are useful in evaluating its operating performance. Bookings and EBITDA are non-GAAP and key operating financial measures that are presented as supplemental disclosures and should not be construed as alternatives to net income (loss) or revenue as indicators of operating performance, nor as alternatives to cash flow provided by operating activities as measures of liquidity, both as determined in accordance with GAAP. Snail supplementally presents Bookings and EBITDA because they are key operating measures used by management to assess financial performance. Bookings adjusts for the impact of deferrals and, Snail believes, provides a useful indicator of sales in a given period. Management believes Bookings and EBITDA are useful to investors and analysts in highlighting trends in Snail’s operating performance. At the same time, other measures can differ significantly depending on long-term strategic decisions regarding capital structure, the tax jurisdictions in which Snail operates, and capital investments.

Bookings is defined as the net amount of products and services sold digitally or physically in the period. Bookings is equal to revenues, excluding the impact from deferrals. Below is a reconciliation of total net revenue to Bookings, the closest GAAP financial measure.

We define EBITDA as net income (loss) before (i) interest expense, (ii) interest income, (iii) provision for (benefit from) income taxes and (iv) depreciation expense. The following table provides a reconciliation from net income (loss) to EBITDA:

Webcast Details

The Company will host a webcast at 4:30 PM ET today to discuss its third quarter 2026 financial and operational results. Participants may access the live webcast and replay via the link here or on the Company’s investor relations website at https://investor.snail.com/.

About Snail, Inc.

Snail, Inc. (Nasdaq: SNAL) is a leading, global independent developer and publisher of interactive digital entertainment for consumers around the world, with a premier portfolio of premium games designed for use on a variety of platforms, including consoles, PCs, and mobile devices. For more information, please visit: https://snail.com/.

Forward-Looking Statements

This press release contains statements that constitute forward-looking statements. Many of the forward-looking statements contained in this press release can be identified by the use of forward-looking words such as “anticipate,” “believe,” “could,” “expect,” “should,” “plan,” “intend,” “may,” “predict,” “continue,” “estimate” and “potential,” or the negative of these terms or other similar expressions. Forward-looking statements appear in a number of places in this press release and include, but are not limited to, statements regarding Snail’s intent, belief or current expectations. These forward-looking statements include information about possible or assumed future results of Snail’s business, financial condition, results of operations, liquidity, plans and objectives. The statements Snail makes regarding the following matters are forward-looking by their nature: upcoming tames and content releases for ARK: Fantastic Tames Season 1 and ARK: Dragontopia in November and December 2026; the further development of Bellwright, including the traversal update planned for the end of 2026; the commercial potential of Snail’s AAA pipeline; Snail’s ARK content pipeline extending through 2027 and Snail’s ongoing content strategy to expand the franchise’s reach and longevity; Snail’s recently released titles, together with the anticipated ARK: Dragontopia skyworld map in December supporting fourth quarter performance; and being well positioned to build on the momentum generated this year.
Any forward-looking statements included herein reflect our current views, and they involve certain risks and uncertainties, including, among others, acceptance of our titles in the marketplace and the successful development, marketing or sale of our titles and our ability to retain our key employees or maintain our Nasdaq listing. These risks should not be construed as exhaustive and should be read together with the other cautionary statement included in our Annual Report on Form 10-K for the year ended December 31, 2025, subsequent Quarterly Reports on Form 10-Q and current reports on Form 8-K filed with the Securities and Exchange Commission. Any forward-looking statement speaks only as of the date on which it was initially made. We undertake no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, changed circumstances or otherwise, unless required by law.

Investor Contact:

John Yi and Steven Shinmachi
Gateway Group, Inc.
949-574-3860
[email protected]
View full release here.

Release – Saga Communications, Inc. Announces Date and Time of 3rd Quarter 2026 Earnings Release and Conference Call

Research News and Market Data on SGA

Oct 12, 2026

PDF Version

GROSSE POINTE FARMS, Mich., Oct. 12, 2026 (GLOBE NEWSWIRE) — Saga Communications, Inc. (Nasdaq: SGA) announced today that it will release its 3rd Quarter 2026 Earnings results at 9:00 a.m. EST on Thursday, November 12, 2026. The company will be holding a conference call on the same date at 11:00 a.m. EST. The dial-in numbers are as follows:

Domestic and International Dial-in Number: (973) 528-0008
Conference Entry Code: 707110

The Company requests that all parties that have a question that they would like to submit to the Company please email the inquiry by 10:00 a.m. EST on November 12, 2026, to [email protected]. The Company will discuss, during the limited period of the conference call, those inquiries it deems of general relevance and interest. Only inquiries made in compliance with the foregoing will be discussed during the call.

Saga’s earnings release will contain certain non-GAAP financial measures including station operating income, trailing 12-month consolidated EBITDA, and same station financial information. A reconciliation of all non-GAAP financial measures to the most directly comparable GAAP measures will be provided in the earnings release.

Saga is a media company whose business is devoted to acquiring, developing, and operating broadcast properties with a focus on providing opportunities complimentary to our core radio business including digital, e-commerce, local on-line news services and non-traditional revenue initiatives. Saga owns or operates broadcast properties in 28 markets, including 82 FM and 28 AM radio stations and 78 metro signals. For additional information, contact us at (313) 886-7070 or visit our website at www.sagacom.com.

Contact:
Samuel D. Bush
(313) 886-7070

Release – Beasley Broadcast Group to Report 2026 Third Quarter Financial Results, Host Conference Call and Webcast on November 13

Beasley Broadcast Group, Inc. Logo

Research News and Market Data on BBGI

Nov 12, 2026 7:00am ESTlinkedinfacebookxemailreddit

NAPLES, Fla., Nov. 12, 2026 /PRNewswire/ — Beasley Broadcast Group, Inc. (Nasdaq: BBGI) (“Beasley” or the “Company”), a multi-platform media company, announced today that it will report its 2026 third quarter financial results after the market closes on Friday, November 13, 2026. The Company will host a conference call and webcast at 4.30 p.m. ET that morning to review the results.

To access the conference call, interested parties may dial +1 833-461-5787 or +1 585-542-9983, conference ID  999 289 758 (domestic and international callers). Participants can also listen to a live webcast of the call at the Company’s website at www.bbgi.com. Please allow 15 minutes to register and download and install any necessary software. Following its completion, a replay of the webcast can be accessed for five days on the Company’s website, www.bbgi.com.

Questions from analysts, institutional investors and debt holders may be e-mailed to [email protected] at any time up until 4.30 p.m. ET on November 13, 2026. Management will answer as many questions as possible during the conference call and webcast (provided the questions are not addressed in their prepared remarks).

About Beasley Broadcast Group

Beasley Broadcast Group, Inc. (www.bbgi.com) was founded in 1961 by George G. Beasley and owns a total of 47 AM and FM stations in 9 large- and mid-size markets in the United States. Beasley radio stations reach over 17 million unique consumers weekly over-the-air, online and on smartphones and tablets, and millions regularly engage with the Company’s brands and personalities through digital platforms such as Facebook, X, text, apps and email. For more information, please visit www.bbgi.com.

For further information, or to receive future Beasley Broadcast Group news announcements via e-mail, please contact Beasley Broadcast Group, at 239-263-5000 or [email protected].

Cision View original content to download multimedia:https://www.prnewswire.com/news-releases/beasley-broadcast-group-to-report-2026-third-quarter-financial-results-host-conference-call-and-webcast-on-november-13-302937443.html

SOURCE Beasley Media Group, Inc.

Release – Euroseas Ltd. Sets Date for the Release of Third Quarter 2026 Results, Conference Call and Webcast

Research News and Market Data on ESEA

November 12, 2026 10:00 ET  | Source: Euroseas

ATHENS, Greece, Nov. 12, 2026 (GLOBE NEWSWIRE) — Euroseas Ltd. (NASDAQ: ESEA), an owner and operator of container carrier vessels and provider of seaborne transportation for containerized cargoes, announced today that it will release its financial results for the third quarter ended September 30, 2026, on November 17, 2026 before market opens in New York.

On the same day, Tuesday, November 17, 2026, at 9:30 a.m. Eastern Time, the Company’s management will host a conference call and webcast to discuss the results.

Conference Call details:

Participants should dial into the call 10 minutes before the scheduled time using the following numbers: 877 405 1226 (US Toll-Free Dial In) or +1 201 689 7823 (US and Standard International Dial In). Please quote “Euroseas” to the operator and/or conference ID13763766. Click here for additional participant International Toll -Free access numbers.

Alternatively, participants can register for the call using the call me option for a faster connection to join the conference call. You can enter your phone number and let the system call you right away. Click here for the call me option.

Audio Webcast– Slides Presentation:

There will be a live and then archived webcast of the conference call and accompanying slides, available on the Company’s website. To listen to the archived audio file, visit our website http://www.euroseas.gr and click on Company Presentations under our Investor Relations page. Participants to the live webcast should register on the website approximately 10 minutes prior to the start of the webcast.

The slide presentation for the third quarter ended September 30, 2026, will also be available in PDF format minutes prior to the conference call and webcast, accessible on the company’s website (www.euroseas.gr) on the webcast page. Participants to the webcast can download the PDF presentation.

About EuroseasLtd.

Euroseas Ltd. was formed on May 5, 2005 under the laws of the Republic of the Marshall Islands to consolidate the ship owning interests of the Pittas family of Athens, Greece, which has been in the shipping business over the past 150 years. Euroseas trades on the NASDAQ Capital Market under the ticker ESEA.
Euroseas operates in the container shipping market. Euroseas’ operations are managed by Eurobulk Ltd., an ISO 9001:2008 and ISO 14001:2004 certified affiliated ship management company, which is responsible for the day-to-day commercial and technical management and operations of the vessels. Euroseas employs its vessels on spot and period charters and through pool arrangements.

After the sale of M/V Evridiki G, the Company will have a fleet of 20 vessels, including 14 Feeder containership and 6 Intermediate containerships with a cargo capacity of 58,588 teu. After the delivery of four intermediate and eight feeder containership newbuildings between 2027 and 2029, Euroseas’ fleet will consist of 32 vessels with a total carrying capacity of 94,840 teu.

Visit the Company’s website www.euroseas.gr

Company Contact Investor Relations / Financial Media

Tasos Aslidis
Chief Financial Officer Euroseas Ltd.
11 Canterbury Lane,
Watchung, NJ 07069
Tel. (908) 301-9091
E-mail: [email protected]

Nicolas Bornozis Markella Kara Capital Link, Inc.
230 Park Avenue, Suite 1540 New York, NY 10169
Tel. (212) 661-7566
E-mail: [email protected]

Release – KBS Builders Wins $2 Million Contract for Workforce Housing Project on Nantucket

Star Equity Holdings

Research News and Market Data on STRR

Nov 12, 2026

Download PDF

OLD GREENWICH, Conn., Nov. 12, 2026 (GLOBE NEWSWIRE) — Star Equity Holdings, Inc. (Nasdaq: STRR; STRRP) (“Star” or the “Company”), a diversified holding company, announced today that its wholly owned subsidiary, KBS Builders, Inc. (“KBS”), has signed an approximately $2 million contract to manufacture a workforce housing project on Nantucket, Massachusetts.

The contract covers the manufacture of 12 modules to provide approximately 8,000 square feet of workforce housing. The two-story building is designed with a 140-mph wind rating and additional features to enhance safety in Nantucket’s coastal weather environment. Production has already commenced and delivery is projected before year end 2026. Workforce housing and assisted living now represent a growing share of the Building Solutions division’s backlog.

Jeff Eberwein, CEO of Star, noted, “We are proud to win another workforce housing contract on Nantucket, reinforcing our strong market presence in the region as well as the continued confidence our customers place in KBS’s modular solutions. Winning repeat business on Nantucket is the clearest evidence that KBS delivers on schedule and on budget in one of the most logistically demanding markets in New England, and these awards improve factory utilization and the earnings power of our Building Solutions division.”

Thatcher Butcher, President of KBS, added, “This award highlights KBS’s ability to take on a logistically challenging island project and deliver it with certainty, speed, and quality. Building in a controlled factory environment removes weather risk from the critical path and compresses the on-site schedule – advantages that are magnified on an island where every material and trade must be delivered by water. We are proud of this project and look forward to continuing to partner with the Nantucket community to deliver more high-quality housing to the island.”

KBS Builders has established itself as a leader in modular construction, providing customized solutions for multifamily, workforce housing, student housing, and hospitality sectors. By combining precision manufacturing with streamlined logistics and installation processes, KBS enables developers to accelerate project timelines while maintaining consistent quality and cost control.

About Star Equity Holdings, Inc.
Star Equity Holdings, Inc. is a diversified holding company that seeks to build long-term shareholder value by acquiring, managing, and growing businesses with strong fundamentals and market opportunities. Its current structure comprises four divisions: Building Solutions, Business Services, Energy Services, and Investments. For more information visit www.starequity.com.

Building Solutions
The Building Solutions division operates in three specialties: (i) modular building manufacturing; (ii) structural wall panel and wood foundation manufacturing, including building supply distribution operations; and (iii) glue-laminated timber (glulam) column, beam, and truss manufacturing.

Business Services
The Business Services division provides flexible and scalable recruitment solutions to a global clientele, servicing organizations at all levels, from entry-level positions to the C-suite. The division focuses on mid-market and enterprise organizations worldwide, partnering consultatively with talent acquisition, HR, and procurement leaders to build diverse, high-impact teams and drive business success.

Energy Services
The Energy Services division engages in the rental, sale, and repair of downhole tools used in the oil and gas, geothermal, mining, and water-well industries.

Investments
The Investments division manages and finances the Company’s real estate assets as well as its investment positions in private and public companies.

Forward-Looking Statements

This press release contains statements that the Company believes to be “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, Section 21E of the Securities Exchange Act of 1934, as amended, and the Private Securities Litigation Reform Act of 1995. All statements other than statements of historical fact included in this press release, including statements regarding the Company’s future financial condition, results of operations, business operations and business prospects, are forward-looking statements. Words such as “anticipate,” “estimate,” “expect,” “project,” “intend,” “plan,” “predict,” “believe,” and similar words, expressions, and variations of these words and expressions are intended to identify forward-looking statements. All forward-looking statements are subject to important factors, risks, uncertainties, and assumptions, including industry and economic conditions that could cause actual results to differ materially from those described in the forward-looking statements. Such factors, risks, uncertainties, and assumptions include, but are not limited to, (1) global economic fluctuations, (2) changes in the cost and availability of commodities, materials, and equipment, (3) risks related to providing uninterrupted service to clients, (4) the ability of clients to terminate their relationship with the Company at any time, (5) risks associated with real estate ownership, (6) the Company’s ability to successfully achieve its strategic initiatives, (7) risks related to fluctuations in the Company’s operating results from quarter to quarter, (8) risks related to potential acquisitions or dispositions of businesses by the Company, (9) our profitability and growth being tied to the success of our operating businesses, (10) risks associated with our financial investments in other businesses, (11) our ability to improve existing products and services and develop, introduce, and market new products and services successfully, (12) the loss of or material reduction in our business with any of the Company’s largest customers, (13) competition in the Company’s markets, (14) risks related to potential decreases in demand for products, (15) our ability to maintain costs at an acceptable level, (16) the negative cash flows and operating losses that may recur in the future, (17) risks related to international operations, including foreign currency fluctuations, political events, trade wars, natural disasters or health crises, including the Russia-Ukraine war, and potential conflict in the Middle East, (18) risks relating to how future credit facilities may affect or restrict our operating flexibility, (19) our ability to generate or borrow sufficient cash to make payments on our indebtedness, (20) risks related to indebtedness, (21) risks associated with the Company’s investment strategy, (22) the Company’s dependence on key management personnel, (23) the Company’s ability to attract and retain highly skilled professionals, management, and advisors, (24) the Company’s ability to collect accounts receivable, (25) the Company’s exposure to legal proceedings, investigations and disputes, and limits on related insurance coverage, (26) the Company’s ability to utilize net operating loss carryforwards, (27) the potential for goodwill impairment, (28) volatility of the Company’s stock price, (29) risks related to our historically low trading volume, (30) risks related to securities or industry analysts, (31) the Company’s ability to declare dividends, (32) risks associated with failure to pay dividends on our Series A Preferred Stock, (33) our history of annual net losses, (34) risks related to our international operations, (35) risks related to compliance with federal and state laws, regulations, and other rules, (36) our exposure to employment-related claims, legal liability, and costs from clients, employees, and regulatory authorities, (37) risks related to the imposition of licensing or tax requirements or new regulations, (38) the effect of Anti-takeover provisions in our organizational documents, (39) the effect of the protective amendment contained in our Restated Certificate of Incorporation, (40) the impact of our stockholder rights plan, or “poison pill,” on stockholder decision making, (41) risks related to our scaled disclosure requirements as a smaller reporting company, (42) the Company’s heavy reliance on information systems and the impact of potentially losing or failing to develop technology, (43) the adverse impacts of cybersecurity threats and attacks, and (44) risks related to the use of new and evolving technologies, and (45) those risks set forth in “Risk Factors in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025.” The foregoing list should not be construed to be exhaustive. Actual results could differ materially from the forward-looking statements contained in this press release. In view of these uncertainties, you should not place undue reliance on any forward-looking statements, which are based on our current expectations. These forward-looking statements speak only as of the date of this press release. The Company assumes no obligation, and expressly disclaims any obligation, to update any forward-looking statements, whether as a result of new information, future events or otherwise.

For more information contact:
The Equity Group
Lena Cati
Senior Vice President
212-836-9611
[email protected]

Release – Alliance Entertainment Reports First Quarter Fiscal 2027 Revenue Growth of 10% and GAAP Net Income Growth of 56%

Research News and Market Data on AENT

GAAP diluted EPS increased 50% to $0.15 as net income reached $7.6 million

Gross profit increased 13% to $42.1 million; gross margin expanded to 15.1%

Physical movie revenue increased 20%; vinyl revenue rose 14% and CD revenue grew 22%

Collectibles revenue increased 87%

PLANTATION, Fla., Nov. 12, 2026 (GLOBE NEWSWIRE) — Alliance Entertainment Holding Corporation (Nasdaq: AENT), a scaled entertainment commerce and collectibles platform serving content owners, brands, retailers and fans across music, movies, gaming, licensed merchandise and collectibles, with proprietary brands, authentication technology and reach across more than 35,000 retail and e-commerce storefronts, today reported its financial and operational results for the first quarter of fiscal 2027, ended September 30, 2026.

First Quarter Fiscal 2027 Financial Highlights

  • Net Revenues: Increased 10% to $278.8 million, compared with $254.0 million in the first quarter of fiscal 2026.
  • Gross Profit and Margin: Gross profit increased 13% to $42.1 million from $37.2 million, while gross margin expanded 50 basis points to 15.1% from 14.6%.
  • GAAP Net Income and EPS: Net income increased 56% to $7.6 million, compared with $4.9 million in the prior-year quarter. GAAP diluted earnings per share increased 50% to $0.15 from $0.10.
  • Operating Income: Operating income was $10.6 million, compared with $10.5 million in the prior-year quarter.
  • Adjusted EBITDA: Increased approximately 1% to $12.3 million, compared with $12.2 million in the prior-year quarter.
  • Adjusted Net Income and Adjusted Diluted EPS: Adjusted net income was $7.2 million, compared with $7.3 million in the prior-year quarter, while adjusted diluted earnings per share remained unchanged at $0.14.
  • Interest Expense: Decreased 49% to $1.2 million from $2.3 million, reflecting lower borrowing costs following the Company’s October 2025 refinancing.
  • Operating Cash Flow: Net cash provided by operating activities increased 58% to $4.3 million, compared with $2.7 million in the prior-year quarter.
  • Liquidity: The Company ended the quarter with approximately $48.9 million of availability under its $120 million revolving credit facility, along with $33.4 million of additional collateral-supported borrowing capacity above the facility’s current commitment limit. This excess collateral capacity could support a future expansion of the credit facility, subject to applicable conditions and lender approval.

“Fiscal 2027 is off to a strong start, with 10% revenue growth, higher gross margins and significant improvement in GAAP net income and earnings per share,” said Jeff Walker, Chief Executive Officer of Alliance Entertainment. “Physical music, movies and collectibles all grew, with collectibles revenue up 87%. For a long time, so much of the conversation was about streaming replacing physical formats. But what we’ve seen consistently is that fans who can listen to an album or watch a movie online still want something special they can own and collect. The entertainment industry is increasingly recognizing the value of these highly engaged consumers-the superfans-and the growing demand for physical products that we’ve been seeing for years.”

“We believe everybody is a superfan of something, and those fans want products that bring them closer to what they love,” Walker continued. “And when you offer a limited edition or an exclusive collectible, that adds another dimension, because now they have a unique product not everybody else has. This is right in our wheelhouse. We have the studio and label relationships, the retail reach and the fulfillment capabilities to get these products into fans’ hands. What’s exciting is that as more content owners look for ways to serve these fans, they need partners who understand both the products and how to bring them to market. That creates a lot of opportunity for Alliance.”

“First-quarter results reflect continued revenue growth and gross margin improvement, along with the benefits of our strengthened financing structure,” said Amanda Gnecco, Chief Financial Officer of Alliance Entertainment. “Gross profit increased approximately 13%, outpacing revenue growth, while interest expense declined nearly 49% following our refinancing with Bank of America. GAAP net income increased 56% to $7.6 million, benefiting from lower borrowing costs and a favorable non-cash change in the fair value of warrant liabilities.”

“We also made progress on our objective of improving cash generation,” Gnecco added. “Operating cash flow increased to $4.3 million from $2.7 million a year ago, despite continued investment in inventory to support customer demand and anticipated sales activity as we enter the holiday season. As we move through fiscal 2027, our priorities remain focused on profitable growth, working-capital efficiency, expense discipline and improving operating leverage. With lower borrowing costs and substantial availability under our revolving credit facility, we believe we have the financial flexibility to support our strategic initiatives while continuing to strengthen the business.”

Strategic & Operating Highlights

  • Physical Movie Growth Supported by Major Studio Relationships: Physical movie revenue increased 20% to $101.1 million, compared with $84.0 million in the prior-year quarter. Growth benefited from new releases and expanded retail availability through the Company’s exclusive physical-media distribution relationships with Paramount and Amazon MGM Studios.
  • Vinyl and CDs Delivered Double-Digit Growth: Vinyl revenue increased 14% to $86.7 million from $75.8 million, while CD revenue increased 22% to $41.2 million from $33.9 million. New releases, reissues and collectible editions supported physical music demand, with both formats benefiting from higher unit sales and average selling prices.
  • Collectibles Revenue Increased 87%: Collectibles revenue increased to $11.9 million from $6.4 million, supported by expanded licensed merchandise offerings, broader sourcing initiatives and vendor relationships, and the Company’s owned Handmade by Robots™ brand. Collectibles represented 4.3% of quarterly revenue, compared with 2.5% in the prior-year period.
  • Distribution and Fulfillment Revenue Increased 18%: Distribution and fulfillment fee revenue increased to $5.7 million from $4.8 million, reflecting higher demand for the Company’s distribution, fulfillment and value-added logistics services.
  • Authentication and Digital Product Identity Development Continued: Alliance continued developing NFC-enabled authentication and digital product identity capabilities through Endstate Authentic and Alliance Authentic™. These initiatives are designed to support product verification, provenance, preservation and authenticated resale across premium physical entertainment and collectibles.
  • Technology and Automation Initiatives Focused on Productivity: Alliance continued investing in warehouse automation and expanding its use of artificial intelligence to streamline workflows and improve financial and operational processes. These efforts are intended to reduce manual work and support more efficient operations as the business grows.

First Quarter Fiscal 2027 Financial Review

Net revenues for the first quarter of fiscal 2027 increased $24.9 million, or 10%, to $278.8 million from $254.0 million in the prior-year quarter. Revenue growth was driven primarily by higher sales of physical movies, vinyl records, CDs and collectibles, partially offset by declines in gaming and digital downloads.

Physical movie revenue increased $17.1 million, or 20%, to $101.1 million, supported by higher unit volumes and the Company’s expanding relationships with major studios. Vinyl revenue increased $10.9 million, or 14%, to $86.7 million, while CD revenue increased $7.3 million, or 22%, to $41.2 million. Collectibles revenue increased $5.5 million, or 87%, to $11.9 million, reflecting continued expansion in licensed merchandise and proprietary products. These increases were partially offset by an $18.4 million decline in gaming revenue, primarily reflecting lower product availability and the absence of certain prior-year sales associated with the Nintendo Switch 2 launch.

Gross profit increased $5.0 million, or approximately 13%, to $42.1 million from $37.2 million in the prior-year quarter. Gross margin improved 50 basis points to 15.1% from 14.6%, reflecting stronger product margins and favorable contributions from the Company’s evolving product mix.

Total operating expenses increased to $31.5 million from $26.6 million in the prior-year quarter, primarily reflecting higher selling, general and administrative expenses and distribution and fulfillment costs. Distribution and fulfillment expenses increased to $12.0 million from $9.9 million, driven primarily by higher warehouse payroll and operating costs associated with increased business activity, specialized product handling and fulfillment requirements. Selling, general and administrative expenses increased to $17.9 million from $15.1 million, reflecting higher employee-related expenses, professional-service costs and investments supporting the Company’s strategic initiatives.

Operating income was $10.6 million, compared with $10.5 million in the prior-year quarter. The increase in gross profit was substantially offset by higher operating expenses as the Company continued supporting revenue growth and investing in its operational capabilities.

Interest expense decreased $1.1 million, or 49%, to $1.2 million from $2.3 million in the prior-year quarter. The decrease primarily reflected a reduction in the Company’s average effective interest rate to 5.3% from 8.4% following the October 2025 refinancing of its revolving credit facility with Bank of America. Lower borrowing costs more than offset the impact of higher average borrowings during the quarter.

GAAP net income increased $2.7 million, or 56%, to $7.6 million from $4.9 million in the prior-year quarter. GAAP diluted earnings per share increased 50% to $0.15 from $0.10. The year-over-year improvement reflected lower interest expense and a favorable change in the fair value of warrant liabilities, partially offset by higher income tax expense. The Company recorded a non-cash gain of approximately $0.9 million related to warrant remeasurement during the quarter, compared with a non-cash loss of approximately $1.5 million in the prior-year period.

Adjusted EBITDA increased approximately 1% to $12.3 million from $12.2 million in the prior-year quarter. Adjusted net income was $7.2 million, while adjusted diluted earnings per share remained unchanged at $0.14. These non-GAAP measures exclude certain items that management does not consider representative of ongoing operating performance, including non-cash warrant remeasurement adjustments.

Net cash provided by operating activities increased to $4.3 million from $2.7 million in the prior-year quarter. Operating cash flow benefited from the Company’s higher earnings and changes in working capital, including increased accounts payable, partially offset by higher inventory and receivables. Inventory increased to $152.0 million at September 30, 2026, from $126.6 million at June 30, 2026, reflecting investment to support sales growth and anticipated customer demand.

At September 30, 2026, the Company had approximately $70.8 million outstanding under its $120 million revolving credit facility, with approximately $49.2 million of availability. The Company remained in compliance with applicable credit facility covenants. Management continues to prioritize working-capital efficiency, inventory productivity, receivable collections and disciplined capital allocation while supporting growth across physical entertainment, collectibles, fulfillment and authentication technologies.

Conference Call

Alliance Entertainment Chief Executive Officer Jeff Walker, Chief Financial Officer Amanda Gnecco, and Executive Chairman Bruce Ogilvie will host the conference call, which will be followed by a question-and-answer session. A presentation will accompany the call and can be viewed during the webcast or accessed via the investor relations section of the Company’s website here.

To access the call, please use the following information:

Date:Thursday, November 12, 2026
Time:4:30 p.m. Eastern Time, 1:30 p.m. Pacific Time
Toll-free dial-in number:1-844-825-9789
International dial-in number:1-412-317-5180
Conference ID:10213070

Please call the conference telephone number 5-10 minutes prior to the start time. An operator will register your name and organization. If you have any difficulty connecting with the conference call, please contact RedChip Companies at 1-407-644-4256.

The conference call will be broadcast live and available for replay at https://viavid.webcasts.com/starthere.jsp?ei=1781348&tp_key=9221210ff0 and via the investor relations section of the Company’s website here.

A telephone replay of the call will be available approximately three hours after the call concludes and can be accessed through December 12, 2026, using the following information:

Toll-free replay number:1-844-512-2921
International replay number:1-412-317-6671
Replay ID:10213070


About Alliance Entertainment

Alliance Entertainment (NASDAQ: AENT) is a premier distributor and fulfillment partner for the entertainment and pop culture collectibles industry. With more than 340,000 unique in-stock SKUs – including over 57,300 exclusive titles across compact discs, vinyl LPs, DVDs, Blu-rays, and video games – Alliance offers the largest selection of physical media in the market. Our vast catalog also includes licensed merchandise, toys, retro gaming products, and collectibles, serving over 35,000 retail locations and powering e-commerce fulfillment for leading retailers. Alliance also owns and operates proprietary collectibles brands, including Handmade by Robots™, a stylized vinyl figure line featuring licensed characters from leading entertainment franchises, and Alliance Authentic™, a premium platform for authentic, certified, and individually numbered entertainment collectibles. In addition, Alliance operates Endstate Authentic, a dedicated NFC-enabled authentication and digital product identity platform supporting authenticated collectibles, resale, and brand protection. Leveraging decades of operational expertise, exclusive sourcing relationships, and a capital-light, scalable infrastructure, Alliance connects fans and collectors to the products, franchises, and experiences they value across formats and generations. For more information, visit www.aent.com.

Forward Looking Statements

Certain statements included in this Press Release that are not historical facts are forward-looking statements for purposes of the safe harbor provisions under the United States Private Securities Litigation Reform Act of 1995. Forward-looking statements generally are accompanied by words such as “believe,” “may,” “will,” “estimate,” “continue,” “anticipate,” “intend,” “expect,” “should,” “would,” “plan,” “predict,” “potential,” “seem,” “seek,” “future,” “outlook,” and similar expressions that predict or indicate future events or trends or that are not statements of historical matters. These forward-looking statements include, but are not limited to, statements regarding estimates and forecasts of other financial and performance metrics and projections of market opportunity. These statements are based on various assumptions, whether identified in this Press Release, and on the current expectations of Alliance’s management and are not predictions of actual performance. These forward-looking statements are provided for illustrative purposes only and are not intended to serve as and must not be relied on by an investor as, a guarantee, an assurance, a prediction, or a definitive statement of fact or probability. Actual events and circumstances are difficult or impossible to predict and will differ from assumptions. Many actual events and circumstances are beyond the control of Alliance. These forward-looking statements are subject to a number of risks and uncertainties, including risks relating to the anticipated growth rates and market opportunities; changes in applicable laws or regulations; the ability of Alliance to execute its business model, including market acceptance of its systems and related services; Alliance’s reliance on a concentration of suppliers for its products and services; increases in Alliance’s costs, disruption of supply, or shortage of products and materials; Alliance’s dependence on a concentration of customers, and failure to add new customers or expand sales to Alliance’s existing customers; increased Alliance inventory and risk of obsolescence; Alliance’s significant amount of indebtedness; our ability to refinance our existing indebtedness; risks that a breach of the revolving credit facility could result in the lender declaring a default and that the full outstanding amount under the revolving credit facility could be immediately due in full, which would have severe adverse consequences for the Company; known or future litigation and regulatory enforcement risks, including the diversion of time and attention and the additional costs and demands on Alliance’s resources; Alliance’s business being adversely affected by increased inflation, uncertainty regarding tariffs, higher interest rates and other adverse economic, business, and/or competitive factors; geopolitical risk and changes in applicable laws or regulations; as well as our financial condition and results of operations; substantial regulations, which are evolving, and unfavorable changes or failure by Alliance to comply with these regulations; product liability claims, which could harm Alliance’s financial condition and liquidity if Alliance is not able to successfully defend or insure against such claims; availability of additional capital to support business growth; and the inability of Alliance to develop and maintain effective internal controls.

For investor inquiries, please contact:

Dave Gentry
RedChip Companies, Inc.
1-800-REDCHIP (733-2447)
1-407-644-4256
[email protected]

View full release here.

Release – Xcel Brands to Host Third Quarter 2026 Earnings Call on November 16, 2026

Primary Logo

Research News and Market Data on XELB

PDF Version

NEW YORK, Nov. 12, 2026 (GLOBE NEWSWIRE) — Xcel Brands, Inc. (NASDAQ: XELB) (“Xcel” or the “Company”), today announced that it will report its third quarter 2026 financial results on November 16, 2026. The Company will hold a conference call with the investment community on November 16, 2026, at 5:00 p.m. ET.

A webcast of the conference call will be available live on the Investor Relations section of Xcel’s website at https://xcelbrands.co/pages/events-and-presentations or directly at https://edge.media-server.com/mmc/p/hm8gb29z

Interested parties unable to access the conference call via the webcast may dial 800-715-9871 or 646-307-1963 and use the Conference ID 1412493. A replay of the webcast will be available on Xcel’s website.

About Xcel Brands

Xcel Brands, Inc. (NASDAQ: XELB) is a media and consumer products company engaged in the design, licensing, marketing, live streaming, and social commerce sales of branded apparel, footwear, accessories, home goods, pet products and other consumer products, and the development of creator or influencer-led brands and the acquisition of dynamic consumer lifestyle brands. Xcel was founded in 2011 with a vision to reimagine shopping, entertainment, and social media as social commerce. Xcel owns the Halston and C. Wonder brands, as well as the co-branded creator or influencer-led brands Tower Hill by Christie Brinkley, Trust.Respect.Love by Cesar Millan, GemmaMade by Gemma Stafford, and Off/Duty by Coco Rocha, and holds a long-term license agreement in Mesa Mia by Jenny Martinez. Xcel also owns and manages the Longaberger by Shannon Doherty brand through its controlling interest in Longaberger Licensing, LLC. Xcel is pioneering a modern consumer products sales strategy which includes the promotion and sale of products under its brands through television, digital live-stream shopping, social commerce, brick-and-mortar retailers, and e-commerce channels to be everywhere its customer’s shop. The company’s previously owned and current brands have generated more than $5 billion in retail sales via livestreaming in television and digital channels alone and has over 20,000 hours of content production time in live-stream and social commerce. The brand portfolio reaches more than 46 million social media followers with broadcast reaching over 200 million households. Headquartered in New York City, Xcel Brands is led by an executive team with significant live streaming, production, merchandising, design, marketing, retailing, and licensing experience, and a proven track record of success in elevating branded consumer products companies. For more information, visit www.xcelbrands.com

For further information please contact:

Xcel Brands
[email protected]