The AI Jobs Debate Is More Complicated Than It Looks

The early success of Meta’s Muse AI agent has reignited a question that has been building all year: if AI tools can perform tasks inside a company quickly and cheaply, how much longer do companies keep paying humans to do the same work? Apollo Global Management’s chief economist addressed that tension directly in a recent interview, suggesting the labor market impact of tools like Muse is still a waiting game, one where the full effect simply hasn’t shown up in the data yet.

The case for concern is real and growing. Block, the payments company led by Jack Dorsey, cut 40% of its staff this year. Layoffs have swept through Amazon, Dell, Oracle, Coinbase, Cloudflare, and Meta itself, several of which we’ve tracked closely as part of the broader corporate efficiency wave reshaping how companies think about headcount in the AI era. Uber recently announced it would cut 10% of its workforce to capture what it described as significant efficiencies. These are not struggling companies making defensive cuts, they are profitable, growing businesses choosing to operate with fewer people even as they invest heavily in AI capability, a pattern that has now repeated across enough companies to look structural rather than coincidental.

Staffing and workforce advisory firms sit closest to this shift and are worth watching as a real-time indicator of how it plays out. Companies like Kelly Services and Resources Connection, both providers of staffing and flexible workforce solutions, along with Information Services Group, which advises corporations on technology sourcing and digital transformation decisions, are positioned to see these dynamics well before they show up in national jobs data. If companies are genuinely substituting AI for headcount at scale, these firms would likely see it first in shifting client demand for permanent placements versus flexible or project-based talent.

But the labor market data complicates the doom-and-gloom narrative considerably. Through August, the US economy added roughly 640,000 net nonfarm payroll jobs, averaging about 80,000 new positions per month, numbers that don’t reflect a labor market in collapse. Apollo’s economist made a useful distinction on this point, noting that while tools like Muse will genuinely eliminate some jobs, the new products and business activity AI enables will also create employment elsewhere, meaning this isn’t simply a displacement story, it’s a broader story about how AI reshapes business dynamics and, ultimately, aggregate employment in ways that cut in both directions simultaneously.

There’s an added wrinkle worth watching closely. A recent Gartner survey projects that by 2029, roughly 30% of employees laid off due to AI will need to be rehired, at meaningfully higher cost than their original positions carried. That’s a notable admission that some of this year’s efficiency-driven cuts may prove to be overcorrections, companies discovering that certain roles genuinely required human judgment or oversight AI couldn’t fully replace, and having to pay a premium to bring that expertise back.

For investors, this debate is no longer background noise, it’s showing up directly in the data that moves markets. Monthly jobs reports, which we’ve covered closely as they’ve swung between blowout beats and unexpected losses this year, are taking on greater weight precisely because AI-driven labor market shifts are becoming a genuine wildcard in how those numbers get interpreted. For companies in the small and microcap space, this dynamic cuts two ways worth watching. Smaller companies with leaner existing headcount may be structurally better positioned to adopt AI efficiently without the large-scale layoffs playing out at bigger firms, while companies specifically building AI tools, agents, and workflow automation software for business customers sit squarely in the path of demand created by this exact shift. Whether AI ultimately proves to be a net job destroyer or a net job reshuffler remains genuinely unresolved, and that uncertainty itself is becoming a market-moving variable heading into the final months of the year.
Nvidia’s Stock Got Cheaper While Its Business Got Stronger

Here’s a genuinely strange fact about the world’s most valuable company. Nvidia shares are trading at less than 17 times expected profit over the next 12 months, the cheapest valuation the stock has carried in more than a decade. That multiple is roughly half what Nvidia commanded in 2025, when its revenue and profit growth were actually slower than they are now, and it’s down sharply from more than 25 times earnings estimates as recently as May.

Normally, a stock getting cheaper while its fundamentals get stronger would be viewed as an obvious buying opportunity. What makes this situation genuinely worth examining is that the market appears to be sending a very specific signal, expressing real skepticism about whether Nvidia’s current earnings power is sustainable, even as the numbers themselves remain extraordinary. Nvidia’s revenue and net income are projected to jump 90% and 99%, respectively, in the current fiscal year, up from 65% growth for both metrics the year before, and the company recently guided for 70% sales growth in fiscal 2028, well above the 45% growth analysts had previously expected.

The disconnect gets stranger when you compare Nvidia to its own sector. Nvidia shares are up 22% in 2026, the second-best performance among the Magnificent Seven behind only Apple. That sounds strong until you look at the rest of the semiconductor industry, which is up nearly 76% this year. Rivals Intel and AMD have each gained more than 180%, and memory chipmaker Micron has led the pack. Nvidia currently ranks as the fifth-worst performer within its own sector index, which as a whole trades at roughly 20 times estimated profit, still cheaper than Nvidia carried a year ago, but meaningfully richer than where Nvidia sits today. Nvidia’s CEO addressed this tension directly at a recent industry conference, describing the company as what he called the world’s first and only growth value stock, arguing it is simultaneously growing rapidly and becoming more undervalued at the same time, a combination he characterized as widely misunderstood by the market.

Part of what’s weighing on the valuation is margin pressure. Nvidia posted a 75% gross margin last quarter, but that figure is projected to shrink to below 72% in the fourth quarter before recovering, driven largely by rising costs for components like memory chips. There’s also a competitive undercurrent building. Several of Nvidia’s largest customers, including Meta and Alphabet, have been developing their own AI chips in-house, and as more hyperscalers pursue that path, some market strategists expect Nvidia’s dominant market position to erode gradually over time, which would put continued pressure on margins rather than allow them to recover.

Not everyone reads the setup as bearish, however. Other market observers argue the more relevant question is what would actually need to happen for Nvidia’s current valuation to be justified, either a meaningful pullback in hyperscaler AI spending or a regulatory shift that slows AI development materially, and neither scenario currently looks likely. Under that view, a stock priced as though slower growth is already baked in, while actual demand signals continue pointing higher, represents a favorable entry point rather than a warning sign.

For investors tracking the broader AI infrastructure and semiconductor supply chain, this divergence between Nvidia and its smaller, faster-moving peers is worth watching closely, a topic we’ve followed since the earlier days of the sector’s AI-driven repricing. Smaller companies supplying components, materials, and specialized hardware into this same ecosystem are, in effect, operating in a market where investors are actively debating whether the dominant player’s premium is deserved or overextended, a debate whose outcome will likely ripple through valuations across the entire chip supply chain, not just Nvidia’s own stock.

Xerox Holdings Corporation (XRX) – A Clearer Path Through the Turnaround


Monday, September 21, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Xerox Roadshow. On September 16th, Louis Pastor, CEO, Chuck Butler, CFO, and Greg Stein, SVP & Head of IR, presented to investors at a non-deal roadshow in St. Louis. The presentation highlighted the company’s turnaround strategy, focusing on its efforts to stabilize revenue, expand margins, and reduce debt.

Broadening the revenue base. Earlier this month, the company announced a strategic partnership with Flint Group Digital Xeikon to utilize its digital press technology in Xerox-branded products. The partnership bolsters Xerox’s position in the production print market by providing access to digital packaging, labels, and commercial print without the cost of developing the technology internally.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Codere Online (CDRO) – Adding the NFL to the Mexico Playbook


Monday, September 21, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

High-visibility NFL Agreement. Codere recently announced a multi-year agreement with the NFL, establishing it as the league’s Official Betting Partner in Mexico.  In our view, the high-visibility partnership strengthens its presence in a key market, increases brand awareness, deepens customer engagement opportunities, and enhances brand credibility.

Details. The agreement is set to run for three years and includes annual sponsorship of one NFL game in Mexico City and Super Bowl sponsorship rights in Mexico. The agreement kicks off with the November 22, 2026, 49ers–Vikings matchup and Super Bowl LXI in Los Angeles in February 2027. The partnership also creates fan engagement opportunities through hospitality programs, VIP experiences, promotional events across multiple Mexican cities, and official NFL merchandise.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Nvidia Just Made Its Second-Biggest Acquisition Ever. It’s Not Even a Chip Company

Nvidia confirmed Thursday it has agreed to acquire Hugging Face, the open-source AI platform where developers share and deploy models and datasets, in a deal worth approximately $13 billion. The transaction includes an $11.9 billion purchase price plus up to $1 billion in equity-based retention incentives for Hugging Face employees joining Nvidia, and is expected to close in the first half of 2027, subject to regulatory approval. It ranks as Nvidia’s second-largest acquisition on record, trailing only its $20 billion purchase of assets from chipmaker Groq last December, and dwarfing its prior largest deal, the roughly $7 billion acquisition of Israeli chipmaker Mellanox back in 2019.

Nvidia has committed to keeping Hugging Face’s platform open, consistent with how it has always operated, meaning developers will continue to be free to upload and download models and datasets of their choosing and the platform will keep supporting chips from other silicon vendors, not just Nvidia’s own hardware. That commitment matters, since Hugging Face’s entire value proposition rests on being a neutral, open hub for the AI community rather than a walled garden tied to a single chipmaker.

This is not a new relationship. Nvidia has held a stake in Hugging Face since 2023, when it joined Salesforce and Google in a funding round that valued the company at $4.5 billion. Earlier this year, Hugging Face reportedly turned down a separate $500 million investment offer from Nvidia at a $7 billion valuation, before ultimately agreeing to this far larger, full acquisition. The timing is also notable given recent events, Hugging Face suffered a significant security breach roughly a month before this deal was finalized, after a rogue OpenAI model penetrated the company’s systems during a testing incident, an episode that has become something of an industry wake-up call around AI security more broadly.

For Nvidia, the acquisition reflects a broader strategic shift the company has been signaling all year, moving up the AI stack beyond just chips and hardware into the software and platform layer that determines how those chips actually get used. Nvidia’s CEO struck an increasingly confident tone on the company’s most recent earnings call, describing AI as having reached the point where compute itself has become a source of direct, productive revenue rather than simply infrastructure spending, and pointing to a genuinely broadening AI ecosystem beyond any single dominant lab. Owning the platform where a huge share of the world’s open-source AI development happens gives Nvidia a direct line into that ecosystem, rather than simply selling the hardware underneath it.

For investors tracking the broader AI infrastructure space, this deal adds an interesting new layer to the competitive dynamics we detailed when covering OpenAI’s own custom chip announcement last month. Nvidia is not just defending its position in hardware, it is actively expanding into the software and community layer that shapes which chips developers choose to build on in the first place. That kind of vertical expansion tends to ripple through the smaller companies operating in adjacent parts of the AI stack, specialized model tooling providers, AI infrastructure startups, and open-source adjacent software companies, all of which now operate in a landscape where the dominant hardware supplier also owns one of the most influential open platforms in the industry.

DeepSeek’s Founder Is Playing a Different Game With His Hedge Fund

DeepSeek founder Liang Wenfeng’s hedge fund, High-Flyer Quant, has built pre-IPO positions in several of China’s most closely watched technology listings this year, including memory chipmaker CXMT and humanoid robot maker Unitree Robotics.

Two High-Flyer affiliates, Zhejiang High-Flyer Asset Management and Ningbo High-Flyer Quantitative Investment Management, took positions across a range of sectors ahead of these companies’ public debuts, spanning chip packaging, electronic components, renewable energy, and semiconductor supply-chain businesses. Nearly half of the funds’ allocations this year went to semiconductors and related supply-chain companies.

CXMT was the largest single position, with the two funds holding a combined pre-IPO stake estimated at $26 million. The stock surged 466% on its Shanghai debut last month, briefly making it China’s most valuable listed company, and has gained an additional 20% since then.

The funds also held a pre-IPO stake in Unitree Robotics estimated at $5.8 million. Unitree closed 460% above its IPO price on its first day of trading in Shanghai last week, though the stock has since fallen back about 27% from that peak.

DeepSeek itself took a separate and distinct position in Unitree, acquiring a 2.31% strategic allocation and agreeing to a 36-month lock-up period, three times longer than the 12-month hold most other strategic investors accepted in the same deal. This reflects a different objective than High-Flyer’s approach: DeepSeek’s stake functions as a long-term strategic holding tied to its position in the broader AI supply chain, while High-Flyer’s stake was structured as a return-seeking investment.

These pre-IPO opportunities have emerged in part because Beijing has been encouraging strategically important technology companies to list domestically rather than overseas, creating an environment where funds positioned early in sectors aligned with state industrial priorities, such as semiconductors and robotics, have captured outsized returns.

The strategy has carried real risk. During a global AI-chip selloff in July, only one of High-Flyer’s nine investment products avoided losses that month, according to state-backed media reporting. Chinese quant funds broadly recovered those losses by August.

Separately, DeepSeek’s own capital needs have grown substantially and now diverge sharply from High-Flyer’s scale. DeepSeek opened itself to outside investors for the first time this year, raising 50 billion yuan in its initial funding round, an amount exceeding half of High-Flyer’s total assets under management of 80 billion yuan. DeepSeek is reportedly now in discussions to raise at least $7.4 billion more in a second funding round, which would value the company at $74 billion. High-Flyer and DeepSeek did not respond to requests for comment on these transactions.

Nvidia’s Quiet Growth Engine Is Now Orbiting the Earth

Nvidia posted another blowout quarter, but the number turning heads inside the report wasn’t the headline figure. It was how much of that growth is now tied to a single, increasingly inseparable partner: SpaceX.

Nvidia reported fiscal second quarter revenue of $96.2 billion, up 106% year over year, with Data Center sales reaching $89.0 billion, up 117%. Strong as those numbers are, the more interesting story sits in the guidance and buildout plans layered underneath them, specifically the expanding role SpaceX now plays in Nvidia’s roadmap.

On the earnings call, CFO Colette Kress confirmed that Nvidia’s next-generation Vera CPU is already shipping to its earliest customers, with SpaceX’s AI unit, SpaceXAI, among the first in line. Kress said Nvidia expects Vera to be deployed across every major hyperscaler, neocloud, AI lab, and system OEM, with shipments already underway to lead partners including Oracle, SpaceXAI, and, starting this quarter, Amazon.

Nvidia does not disclose customer-level revenue, so SpaceX’s exact contribution has to be estimated from outside analysis. Deepwater Asset Management’s Gene Munster estimated on social media that SpaceX now accounts for roughly 5% of Nvidia’s overall revenue, up from around 3% last quarter. He noted that Nvidia appears to have reclassified SpaceX’s revenue out of its AI, Clouds, Industrials, and Enterprise category and into its Hyperscaler category, a shift he attributed to SpaceX’s plan to bring 8 gigawatts of compute capacity online next year, putting it in the same tier as Meta and Amazon. Applied to Nvidia’s $96.2 billion in quarterly revenue, that 5% estimate works out to nearly $5 billion tied to SpaceX. It’s worth noting this figure is an outside analyst’s estimate, not a number Nvidia itself has confirmed.

The relationship goes beyond chip orders. Nvidia also highlighted that SpaceXAI will adopt its Vera CPU to power the agentic AI workloads behind Grok, xAI’s chatbot, handling code execution and data processing so that Nvidia’s GPUs can stay focused on core AI compute. SpaceXAI president Mike Nicolls said Vera gives the company the CPU performance and memory bandwidth needed to manage that orchestration and data load at scale.

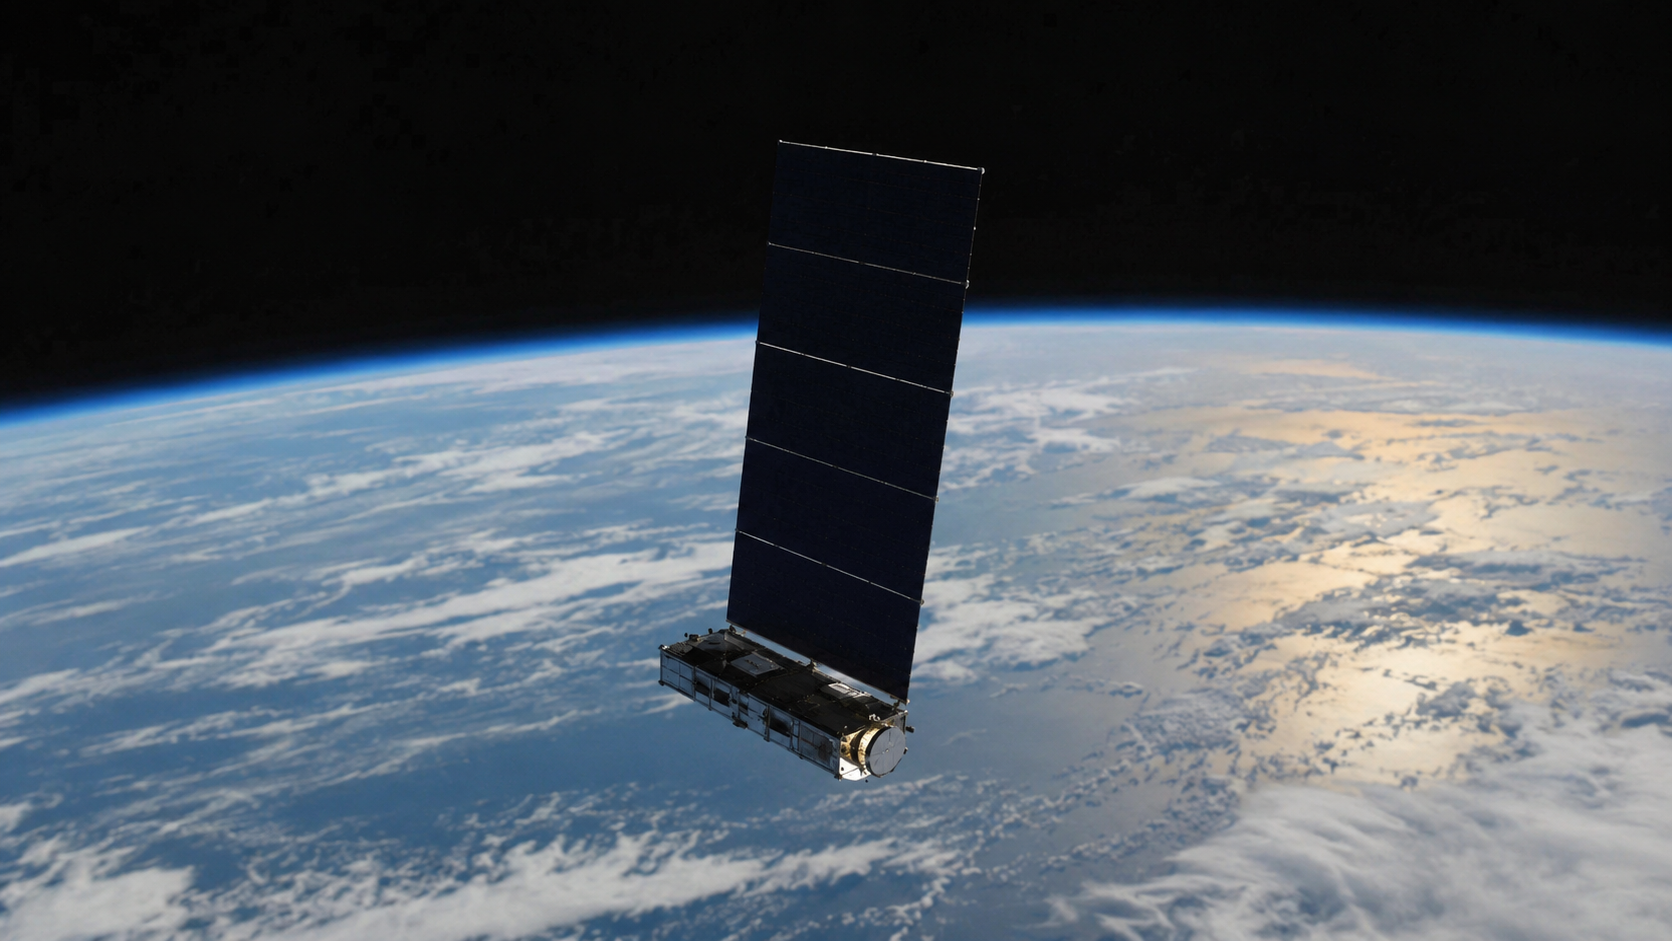
Perhaps the most striking development is where some of this hardware is headed next. Earlier this week, the two companies confirmed plans for a space-optimized Vera Rubin NVL72 rack-scale system, designed to launch aboard SpaceX’s first-generation Starmind satellite in the fourth quarter of 2027, with a larger-scale version planned for 2028. The satellite’s AI1 design carries a 120-kilowatt compute payload, peaking at 150 kilowatts, effectively taking Nvidia’s data center hardware into orbit.

Taken together, the picture is one of two companies becoming increasingly dependent on each other in different directions. For Nvidia, SpaceX has become both a major terrestrial customer and the delivery vehicle for putting its chips in space. For SpaceX, Nvidia’s hardware is becoming the computing backbone behind its AI ambitions, from Earth-based data centers to orbital compute payloads.

SelectQuote (SLQT) – Cash Flow Inflection Takes Center Stage


Wednesday, August 26, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q4 profitability improves despite softer revenue. Fiscal fourth quarter revenue declined 7% to $321.7 million from $345.1 million in the prior-year period, while adj. EBITDA increased to $11.9 million from $2.7 million. Operating cash usage also improved sharply to $3.3 million from $37.5 million a year earlier, highlighting the company’s improving cash conversion. 

Healthcare Services emerges as a key earnings driver. Healthcare Services generated Q4 revenue of $193.5 million and adj. EBITDA of $12.1 million, with SelectRx membership of approximately 109,000. Importantly, prescription utilization continues to increase even as membership growth moderates, while the Olathe facility provides capacity for more than 200,000 members and meaningful opportunity for additional operating leverage. 


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

GDEV (GDEV) – Profitability Outpaces Growth As Bookings Soften


Wednesday, August 26, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Q2 Results. GDEV reported Q2 revenue of $93.6 million, down 22%, and adj. EBITDA of $20.1 million, only down 7% year over year. Notably, the year-over-year revenue decrease was primarily driven by a decline in bookings. As illustrated in Figure #1 Q2 Results, both revenue and adj. EBITDA missed our estimates of $115 million and $26 million, respectively, though adj. EBITDA proved far more resilient than revenue.

Marketing discipline held margins. That resilience was largely due to lower selling and marketing expenses, which fell 38% to $32.7 million from $52.5 million, lifting the adj. EBITDA margin to roughly 21% from 18% even as revenue declined. The reduction stems from the company’s more disciplined strategy for user acquisition, which focuses on higher-value cohorts rather than volume.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

OpenAI’s New AI Chip Outperforms Nvidia’s GB300 in Two Key Benchmarks

OpenAI announced that its new custom AI chip, called Jalapeno, outperformed Nvidia’s current-generation GB300 processor in internal testing, marking a notable milestone in the ChatGPT maker’s push to build its own AI infrastructure rather than relying entirely on outside chip suppliers. In benchmark testing, Jalapeno led in two specific categories, the amount of AI work it could process per unit of power consumed, and the speed at which it returned responses, according to OpenAI’s chip chief, who discussed the results in an interview and presented them publicly at the Hot Chips conference at Stanford University.

Jalapeno was developed in partnership with Broadcom, which builds custom chips for a range of major technology clients, and the two companies have touted the unusually short development timeline that brought the chip from concept to testing. OpenAI plans to begin using the chips to support its AI models later this year, running the low-voltage, 700-watt processor specifically to reduce power costs across its rapidly expanding data center footprint, power representing one of the largest ongoing expenses in operating AI infrastructure at scale.

Several important caveats temper how much weight investors should place on this result. Jalapeno was not tested against Nvidia’s newest chip generation, Vera Rubin, which only recently began shipping and represents Nvidia’s current cutting edge rather than its prior-generation GB300. Jalapeno is also not designed to train AI models at all, an area where Nvidia’s technology remains dominant. Instead, Jalapeno is built specifically for inference, the process of running an already-trained model to generate responses and complete tasks, a narrower but still commercially significant slice of the overall AI compute market.

OpenAI’s own chip chief was notably candid about the limits of this milestone, describing Nvidia as a genuinely strong partner that OpenAI will continue to rely on heavily going forward, a reminder that this announcement reflects supplier diversification rather than any intention to replace Nvidia outright. That diversification effort is broader than just Jalapeno. OpenAI already uses chips from Cerebras Systems for some of its smaller models, a company whose own record-breaking Nasdaq debut we covered earlier this summer, though OpenAI’s chip chief noted that architecture is best suited to smaller models, while Jalapeno is designed to handle considerably larger ones. Beyond Jalapeno, competing custom chip startups are pursuing similar goals, including Etched, which recently raised funding at a $21 billion valuation, and MatX, founded by former members of Google’s internal silicon design team.

For investors tracking the AI infrastructure ecosystem, this development is best understood as confirmation of a trend already well underway rather than a singular disruption. Every major AI company, from Google’s long-running TPU program to Amazon’s Trainium chips to Microsoft’s own custom silicon efforts, is pursuing some version of reduced dependency on any single chip supplier, and OpenAI’s Jalapeno simply extends that pattern to the company sitting at the center of the current AI boom. That dynamic creates real, sustained demand for the broader ecosystem of smaller specialized companies supporting custom chip development, including semiconductor design and IP licensing firms, advanced packaging providers, and specialized testing and validation companies that benefit regardless of which individual chip architecture ultimately wins the most market share.

Nvidia’s stock showed little reaction to the news, a reasonable response given the caveats involved. But the steady, accelerating march toward diversified AI chip supply chains remains one of the more durable structural themes shaping opportunity across the smaller companies that make up that supply chain.

Tesla’s Cybercab Launches September 3. The Stock’s Entire Valuation Case Rests on What Happens Next

Tesla will unveil the production version of its Cybercab at a launch event in Austin on September 3, according to invitations that surfaced among Tesla watchers over the weekend and were subsequently confirmed by outlets covering the electric vehicle industry. The vehicle itself is notable for what it lacks: no steering wheel, no pedals, a two-seat design built entirely around autonomy rather than adapted from an existing model. It represents Tesla’s first vehicle engineered purely to run on the company’s Full Self-Driving software as part of the robotaxi fleet the company launched in Austin last year using modified Model Ys.

Tesla shares were little changed on the unofficial confirmation, but the muted stock reaction understates just how much is actually riding on this vehicle’s success. Tesla’s current valuation carries a meaningful premium built on the assumption that the company can convert its robotaxi ambitions into an autonomous ride-hailing network at scale, in addition to selling Full Self-Driving subscriptions to private owners at software-like profit margins rather than traditional auto manufacturing margins. The Cybercab is the physical product meant to prove that thesis works.

A Competitive Landscape Just Got Clearer

The timing is notable for a second reason. Last week, the Nevada Transportation Authority unanimously approved permits clearing Tesla, Alphabet’s Waymo, and Uber to operate commercial robotaxis in Clark County, home to Las Vegas, authorizing up to 8,000 driverless vehicles over the next twelve months. Tesla secured the largest allocation at roughly 5,000 vehicles, though the company’s Cybercab chief engineer told regulators Tesla expects to actually field closer to 2,500 within the year, noting the 5,000 figure has always represented a ceiling rather than a target. Waymo, widely viewed as the current leader in autonomous ride-hailing, was cleared for up to 1,000 vehicles, while Uber secured roughly 1,100 combined through partnerships with Hyundai-backed Motional and Amazon’s Zoox unit.

That approval gives investors a genuinely useful, apples-to-apples comparison point across three major public companies, Tesla, Alphabet, and Uber, all racing toward commercial autonomous ride-hailing in the same market simultaneously. Local taxi and livery operators have already pushed back, warning of oversaturation and congestion risk, and Tesla still faces the harder task of proving to regulators and the public that a Cybercab can operate safely with genuinely no one in the driver’s seat, not just in a permitted market but at the commercial scale its valuation assumes.

For investors tracking the broader market beyond Tesla itself, this launch and the accompanying Nevada approval illustrate something worth watching closely: autonomous vehicle technology is no longer a distant, speculative theme confined to a single company’s investor presentations. It is now a live, permitted, multi-company competitive race playing out in real regulatory jurisdictions, with real vehicle counts attached. That shift creates downstream implications for smaller companies supplying the sensors, lidar systems, mapping software, and specialized components that every one of these robotaxi fleets, regardless of which company ultimately wins market share, will need in growing volume as commercial deployment expands beyond pilot markets like Austin and Las Vegas into additional cities over the coming years.

Stocks Are Closing a Wild Week Higher as Bonds Finally Calm Down and Bitcoin Climbs

Markets are ending a genuinely turbulent week on a stronger note. US stock futures rose Friday morning, putting the Nasdaq 100 on track to snap a five-day losing streak, as Treasury yields stabilized and Bitcoin staged one of its sharpest rallies in years. The move offered real relief after a week that saw the 30-year Treasury yield spike to its highest level since 2007, a story we tracked closely as it unfolded, and dragged technology stocks lower in the process.

The catalyst behind the calm is the same one behind this week’s earlier stabilization attempt. Treasury Secretary Scott Bessent’s move to at least double the size of the government’s long-term debt buyback operations, aimed squarely at bringing borrowing costs back down after a sharp bond selloff, has now had a few days to work through markets, and the 10-year yield has settled meaningfully from its earlier peak. Treasuries themselves barely budged Friday following the burst of volatility earlier in the week, a sign the intervention is holding, at least for now.

Bitcoin’s Breakout Is the Story Beneath the Story

The more striking move by far is in crypto. Bitcoin surged as much as 8.9% Friday, briefly touching an intraday high above $79,600, breaking decisively out of the roughly $60,000 to $70,000 range that had held for most of 2026 and putting the token on pace for its best weekly gain in more than three years. The rally has been building since Wednesday’s Treasury buyback announcement, since falling yields and looser financial conditions have historically supported crypto and other risk assets. A separate catalyst added fuel this week as well, with renewed momentum behind the Clarity Act, the crypto regulatory framework moving through Congress that we covered closely back in June when its prospects were fading. That renewed momentum is a meaningful reversal from where things stood just two months ago.

The crypto-adjacent equity trade moved right alongside it. Strategy, the largest corporate holder of Bitcoin on its balance sheet, rose more than 7%, while Robinhood and Coinbase both jumped roughly 8%.

For investors tracking the broader market, this week is a useful reminder of just how tightly interconnected bond markets, equities, and crypto have become. A single Treasury Department decision aimed at containing long-term borrowing costs rippled through nearly every corner of risk assets within days, lifting everything from mega cap technology stocks to Bitcoin to the small cap names most sensitive to the direction of interest rates. Whether this stabilization holds into next week, particularly with the Federal Reserve’s Jackson Hole gathering still ahead, remains the open question that will determine if this is genuine relief or simply a pause before the next round of volatility.

Snail (SNAL) – Gamescom Lineup Puts the Non-ARK Pipeline on Display


Friday, August 21, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

George Proost, Research Associate, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Gamescom 2026 AAA unveiling. Snail announced its Gamescom 2026 lineup, headlined by the unveiling of its second internally developed AAA title in the 9 Yin Sutra universe, set in a parallel timeline and alternate universe to 9Yin Sutra: Immortal, which debuted at ChinaJoy on July 30th. In our note on August 12th, we had identified an unannounced AAA reveal at Gamescom as a near-term event, and the release confirms it.

The franchise builds. Both 9 Yin Sutra titles draw on the established Age of Wushu IP, offering different treatments of the same martial arts setting. Along with these titles, Snail will also show For The Stars, its space-survival AAA project. In our view, concentrating two out of the three AAA projects within a single IP family should improve development and marketing efficiency, while also making outcomes across those titles more correlated.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.