Release – Xcel Brands Announces Exploration of Strategic Alternatives for Non-Core Legacy Assets to Optimize Balance Sheet

Primary Logo

Research News and Market Data on XELB

November 9, 2026 at 8:00 AM EST

PDF Version

NEW YORK, Nov. 09, 2026 (GLOBE NEWSWIRE) — Xcel Brands, Inc. (NASDAQ: XELB) (“Xcel” or the “Company”), a leading media and consumer products company specializing in creator or influencer-led brands, social commerce, and livestream shopping, today announced that its Board of Directors has initiated a process to explore strategic alternatives for certain of its non-core legacy assets. The strategic initiative aims to streamline the Company’s operational focus while strengthening its balance sheet.

As part of this process, the Company intends to evaluate a range of potential transactions, including but not limited to the sale or divestiture of select legacy consumer brands and related intellectual property that fall outside of its core, focus on digital-first, creator or influencer-led live commerce partnerships.

Robert W. D’Loren, Chairman and Chief Executive Officer of Xcel Brands, commented: “Over the past several quarters, Xcel has successfully pivoted toward a highly scalable, asset-light social commerce model powered by category expert creators or influencers and advanced digital platforms. As we accelerate momentum behind our newest co-brands, optimizing our capital structure becomes a top priority. By exploring strategic alternatives for these non-core legacy assets, we believe we may be able to enhance our financial flexibility and position Xcel to maximize long-term value for our shareholders.”

The Company has not set a definitive timetable for completion of the evaluation process. There can be no assurance that this exploration process will result in any transaction or other strategic alternative being successfully concluded. Xcel does not intend to disclose developments with respect to this process unless and until its Board of Directors has approved a specific transaction or otherwise determines that disclosure is necessary or appropriate.

About Xcel Brands

Xcel Brands, Inc. (NASDAQ: XELB) is a media and consumer products company engaged in the design, licensing, marketing, live streaming, and social commerce sales of branded apparel, footwear, accessories, fine jewelry, home goods, pet products and other consumer products, and the acquisition of dynamic consumer lifestyle brands. Xcel was founded in 2011 with a vision to reimagine shopping, entertainment, and social media as social commerce. Xcel is an industry leader in developing influencer led brands and owns the Halston and C. Wonder brands, as well as the co-branded influencer led brands Tower Hill by Christie Brinkley, Trust. Respect. Love by Cesar Millan, GemmaMade by Gemma Stafford and OFF/DUTY by Coco Rocha brand and holds a long-term license agreement in Mesa Mia by Jenny Martinez. Xcel also owns and manages the Longaberger by Shannon Doherty brand through its controlling interest in Longaberger Licensing, LLC. Xcel is pioneering a modern consumer products sales strategy which includes the promotion and sale of products under its brands through interactive television, digital live-stream shopping, social commerce, brick-and-mortar retailers, and e-commerce channels to be everywhere its customers’ shop. The company’s previously owned and current brands have generated more than $5 billion in retail sales via livestreaming in interactive television and digital channels alone and have over 20,000 hours of content production time in live-stream and social commerce. The brand portfolio reaches more than 46 million social media followers with broadcast reaching 200 million households. Headquartered in New York City, Xcel Brands is led by an executive team with significant live streaming, production, merchandising, design, marketing, retailing, and licensing experience, and a proven track record of success in elevating branded consumer products companies. For more information, visit www.xcelbrands.com.

For further information please contact:

Xcel Brands

[email protected]

Forward-Looking Statements

This press release contains forward-looking statements. All statements other than statements of historical fact contained in this press release, including statements regarding future events, our future financial performance, business strategy and plans and objectives of management for future operations, are forward-looking statements. We have attempted to identify forward-looking statements by terminology including “anticipates,” “believes,” “can,” “continue,” “ongoing,” “could,” “estimates,” “expects,” “intends,” “may,” “appears,” “suggests,” “future,” “likely,” “goal,” “plans,” “potential,” “projects,” “predicts,” “seeks,” “should,” “would,” “guidance,” “confident” or “will” or the negative of these terms or other comparable terminology. These forward-looking statements include, but are not limited to, statements regarding our anticipated revenue, expenses, profitability, strategic plans and capital needs. These statements are based on information available to us on the date hereof and our current expectations, estimates and projections and are not guarantees of future performance. Forward-looking statements involve known and unknown risks, uncertainties, assumptions and other factors, including, without limitation, the risks discussed in the “Risk Factors” section and elsewhere in the Company’s Annual Report on form 10-K for the year ended December 31, 2024 and its other filings with the SEC, which may cause our or our industry’s actual results, levels of activity, performance or achievements to differ materially from those expressed or implied by these forward-looking statements. Moreover, we operate in a very competitive and rapidly changing environment. New risks emerge from time to time, and it is not possible for us to predict all risk factors, nor can we address the impact of all factors on our business or the extent to which any factor, or combination of factors, may cause our actual results to differ materially from those contained in any forward-looking statements. You should not place undue reliance on any forward-looking statements. Except as expressly required by the federal securities laws, we undertake no obligation to update any forward-looking statements, whether as a result of new information, future events, changed circumstances or any other reason.

Investor Relations Contact:
Xcel Brands, Inc.
Investor Relations Team
Email: [email protected]

Primary Logo

Release – Century Lithium’s Angel Island Mine Plan of Operations Deemed Complete by BLM, Advancing Project Toward Environmental Review

Century Lithium

Research News and Market Data on CYDCF

November 9, 2026 – Vancouver, Canada – Century Lithium Corp. (TSXV: LCE) (OTCQX: CYDVF) (Frankfurt: C1Z) (“Century Lithium” or “the Company”) is pleased to announce that the U.S. Bureau of Land Management (“BLM”), Battle Mountain District, Tonopah Field Office, has reviewed and determined that the Mine Plan of Operations and Nevada Reclamation Permit Application (“PoO” or “Plan”) for the Company’s 100%-owned Angel Island Lithium Project (“Angel Island” or the “Project”) in Esmeralda County, Nevada, USA, is complete. The determination advances Angel Island toward environmental review under the National Environmental Policy Act (“NEPA”).

“The BLM’s completeness determination is an important milestone for Angel Island. It confirms that our Project is ready to move into the environmental review phase of the process,” said Bill Willoughby, President and CEO of Century Lithium. “We’ve been focused on finishing the remaining baseline studies and are working closely with the BLM and the third-party NEPA contractor as we move toward the environmental analysis part of the process.”

BLM Completeness Determination

In a letter dated November 3, 2026, the BLM notified Century Lithium that it has reviewed the Plan and determined it to be complete under 43 CFR § 3809.411. The Plan defines the components of the Project and will serve as the basis for the BLM’s environmental review and analysis pursuant to the NEPA. Upon completion of the NEPA analyses and the public scoping process, the PoO will be revised as necessary, at which point the BLM can officially approve the PoO.

Next Steps Toward Environmental Review

Completion of the remaining baseline studies related to the proposed water supply pipeline route is pending. At this stage, the BLM will issue a letter documenting completion and acceptance of all required baseline studies and reports and will determine the appropriate level of NEPA review for the Project, either an Environmental Assessment or Environmental Impact Statement. Now that the PoO has been deemed complete, the third-party NEPA contractor will begin preparation of the Supplemental Information Report (“SIR”) and the Supplemental Environmental Reports (“SERs”) to support the NEPA document followed by the environmental analysis of Project. The Company will provide updates on the review process and schedule once that determination is made.

Permitting Timeline

Angel Island is a Transparency Project under the Federal Permitting Improvement Steering Council’s FAST-41 program, with the BLM serving as lead agency. The Permitting Dashboard for Federal Infrastructure Projects currently shows a target date of February 4, 2028, for issuance of the Record of Decision for the Project. As with any federal schedule, this timetable may change as the review progresses, and the Company will provide updates as key milestones are reached.

ABOUT CENTURY LITHIUM CORP.

Century Lithium Corp. is an advanced-stage lithium development company focused on its 100%-owned Angel Island lithium project in Esmeralda County, Nevada. Angel Island hosts one of the largest known sedimentary lithium deposits in the United States and is designed with an integrated, end-to-end process for the on-site production of battery-grade lithium carbonate to support the electric vehicle and battery storage markets.

The Company has developed a patent-pending process that incorporates hydrochloric acid leaching combined with direct lithium extraction to produce battery-grade lithium carbonate. As part of the integrated chlor-alkali process, Angel Island is designed to produce sodium hydroxide as a co-product, with planned surplus sales expected to lower operating costs, reduce reliance on externally sourced reagents, and minimize environmental impacts.

Century Lithium is currently advancing Angel Island through the permitting process.

Century Lithium trades on the TSX Venture Exchange under the symbol “LCE” the OTCQX under the symbol “CYDVF”, and on the Frankfurt Stock Exchange under the symbol “C1Z”.

To learn more, please visit centurylithium.com.

ON BEHALF OF CENTURY LITHIUM CORP.

WILLIAM WILLOUGHBY, PhD., PE
President & Chief Executive Officer

For further information, please contact:
Spiros Cacos | Vice President, Investor Relations
Direct: +1 604 764 1851
Toll Free: 1 800 567 8181
[email protected]
centurylithium.com

NEITHER THE TSX VENTURE EXCHANGE NOR ITS REGULATION SERVICES PROVIDER ACCEPTS RESPONSIBILITY FOR THE ADEQUACY OR ACCURACY OF THE CONTENT OF THIS NEWS RELEASE.

Cautionary Note Regarding Forward-Looking Statements

This release contains certain forward-looking statements within the meaning of applicable Canadian securities legislation. In certain cases, forward-looking statements can be identified by the use of words such as “plans”, “expects” or “does not anticipate”, or “believes”, or variations of such words and phrases or statements that certain actions, events or results “may”, “could”, “would”, “might” or “will be taken”, “occur” or “be achieved” and similar expressions suggesting future outcomes or statements regarding an outlook.

Forward-looking statements relate to any matters that are not historical facts and statements of our beliefs, intentions and expectations about developments, results and events which will or may occur in the future, without limitation, statements with respect to the acceptance of the remaining environmental baseline studies, the level of NEPA review to be determined by the BLM, the NEPA environmental review and permitting schedule for the Project, the timing of a decision on and approval of the PoO, the potential development and value of the Project, and the Company’s future development plans.

These and other forward-looking statements and information are subject to various known and unknown risks and uncertainties, many of which are beyond the ability of the Company to control or predict, that may cause their actual results, performance or achievements to be materially different from those expressed or implied thereby, and are developed based on assumptions about such risks, uncertainties and other factors set out herein. These risks include those described under the heading “Risk Factors” in the Company’s most recent annual information form and its other public filings, copies of which can be under the Company’s profile at www.sedarplus.ca. The Company expressly disclaims any obligation to update-forward-looking information except as required by applicable law. No forward-looking statement can be guaranteed, and actual future results may vary materially. Accordingly, readers are advised not to place reliance on forward-looking statements or information. Furthermore, Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability.

Release – Superior Group of Companies Reports Third Quarter 2026 Results

Primary Logo

Research News and Market Data on SGC

Total net sales of $146.0 million, up 5% over prior year third quarter
Net income of $2.6 million versus $2.7 million in prior year third quarter
Adjusted EBITDA of $6.7 million versus $7.5 million in prior year third quarter
Tightens full-year Outlook

ST. PETERSBURG, Fla., Nov. 09, 2026 (GLOBE NEWSWIRE) — Superior Group of Companies, Inc. (NASDAQ: SGC) (the “Company”), today announced its third quarter 2026 results.

“We drove solid overall top line growth from continued momentum in our Branded Products and Contact Centers segments,” said Michael Benstock, Chief Executive Officer. “New leadership in Healthcare Apparel continues to execute toward a more focused product strategy to improve margins and reduce working capital requirements in the quarters ahead. On a consolidated basis, we were able to hold EPS essentially flat versus the prior year quarter despite incremental charges associated with our strategic shift in Healthcare Apparel. We look forward to finishing the year with growth in both sales and earnings compared to 2025, and with a solid balance sheet that provides the foundation for continued strategic investment such as our recent acquisition of Select VoiceCom and the return of capital to shareholders.”

Third Quarter Results

For the third quarter ended September 30, 2026, net sales were $146.0 million, up 5% from third quarter 2025 net sales of $138.5 million. Net income was $2.6 million or $0.17 per diluted share compared to net income of $2.7 million or $0.18 per diluted share for the third quarter of 2025.

2026 Full-Year Outlook

The Company tightened its full-year 2026 net sales forecast to a range of $578.0 million to $585.0 million, from its previous range of $572.0 million to $585.0 million, up from 2025 net sales of $566.2 million. It also tightened its full-year adjusted earnings per diluted share forecast to a range of $0.60 to $0.66, from its previous range of $0.54 to $0.66, up from $0.46 in 2025 and representing 43% growth at the high end.

Webcast and Conference Call

The Company will host a webcast and conference call at 8:00am Eastern Time today. The live webcast and archived replay can be accessed in the investor relations section of the Company’s website at https://ir.superiorgroupofcompanies.com/Presentations. Interested individuals may also join the teleconference by dialing 1-844-861-5505 for U.S. dialers and 1-412-317-6586 for international dialers. The Canadian toll-free number is 1-866-605-3852. Please ask to be joined to the Superior Group of Companies call. A telephone replay of the teleconference will be available through November 23, 2026. To access the replay, dial 1-855-669-9658 in the United States or Canada, or 1-412-317-0088 from international locations. Please reference conference number 8522694 for replay access.

Disclosure Regarding Forward-Looking Statements

Certain matters discussed in this press release are “forward-looking statements“ intended to qualify for the safe harbors from liability established by the Private Securities Litigation Reform Act of 1995. These forward-looking statements can generally be identified by use of the words “may,” “will,” “should,” “could,” “expect,” “anticipate,” “estimate,” “believe,” “intend,” “project,” “potential,“ or “plan“ or the negative of these words or other variations on these words or comparable terminology. Forward-looking statements in this press release include 2026 guidance of net sales and earnings per diluted share and may also include, without limitation: (1) projections of revenue, income, and other items relating to our financial position and results of operations, including short term and long term plans for cash, (2) statements of our plans, objectives, strategies, goals and intentions, (3) statements regarding the capabilities, capacities, market position and expected development of our business operations and (4) statements of expected industry and general economic trends.

Such forward-looking statements are subject to certain risks and uncertainties that may materially adversely affect the anticipated results. Such risks and uncertainties include, but are not limited to, the following: the impact of competition; the impact of global conflicts, such as the Russia-Ukraine War and the joint U.S.-Israeli War with Iran in 2026, oil and natural gas prices, uncertainties related to tariffs, duties, trade wars and related matters, supply disruptions, inflationary environments (including with respect to shipping costs and the cost of finished goods and raw materials), employment levels (including labor shortages), and general economic and political conditions in the areas of the world in which the Company operates or from which it sources its supplies or the areas of the United States of America (“U.S.“ or “United States“) in which the Company‘s customers are located; changes in the healthcare, retail chain, food service, transportation and other industries where uniforms and service apparel are worn; our ability to identify suitable acquisition targets, discover liabilities associated with such businesses during the diligence process, successfully integrate any acquired businesses, or successfully manage our expanding operations; the price and availability of raw materials; attracting and retaining senior management and key personnel; the Company’s ability to maintain effective internal control over financial reporting; and other factors described in the Company‘s filings with the Securities and Exchange Commission (“SEC”), including those risks described in Item 1A of our Annual Report on Form 10-K for the fiscal year ended December 31, 2025 entitled “Risk Factors” and the Quarterly Report on Form 10-Q for the quarter ended September 30, 2026. Shareholders, potential investors and other readers are urged to consider these factors carefully in evaluating the forward-looking statements made herein and are cautioned not to place undue reliance on such forward-looking statements. The forward-looking statements made herein are only made as of the date of this press release and we disclaim any obligation to publicly update such forward-looking statements to reflect subsequent events or circumstances, except as may be required by law.

About Superior Group of Companies, Inc. (SGC):

Established in 1920, Superior Group of Companies is comprised of three attractive business segments each serving large, fragmented and growing addressable markets. Across Healthcare Apparel, Branded Products and Contact Centers, each segment enables businesses to create extraordinary brand engagement experiences for their customers and employees. SGC’s commitment to service, quality, advanced technology, and omnichannel commerce provides unparalleled competitive advantages. We are committed to enhancing shareholder value by continuing to pursue a combination of organic growth and strategic acquisitions. For more information, visit www.superiorgroupofcompanies.com.

Investor Relations Contact:
[email protected]

View full release here.

Release – Superior Group of Companies Declares Regular Quarterly Cash Dividend

Research News and Market Data on SGC

ST. PETERSBURG, Fla., Nov. 06, 2026 (GLOBE NEWSWIRE) — The Board of Directors of Superior Group of Companies, Inc. (NASDAQ: SGC) today announced that it has declared a quarterly dividend of $0.14 per share, payable November 25, 2026, to shareholders of record as of November 16, 2026.

About Superior Group of Companies, Inc. (SGC):
Established in 1920, Superior Group of Companies is comprised of three attractive business segments each serving large, fragmented and growing addressable markets. Across Healthcare Apparel, Branded Products and Contact Centers, each segment enables businesses to create extraordinary brand engagement experiences for their customers and employees. SGC’s commitment to service, quality, advanced technology, and omnichannel commerce provides unparalleled competitive advantages. We are committed to enhancing shareholder value by continuing to pursue a combination of organic growth and strategic acquisitions. For more information, visit www.superiorgroupofcompanies.com.

Contact:
Investor Relations
[email protected]

Release – Seanergy Maritime Announces the Date for the Third Quarter and Nine Months Ended September 30, 2026, Financial Results, Conference Call, and Webcast

Research News and Market Data on SHIP

November 06, 2026 09:00 ET  | Source: Seanergy Maritime Holdings Corp.

Earnings Release: Thursday, November 12, 2026, Before Market Open in New York 
Conference Call and Webcast: Thursday, November 12, 2026, at 10:00 a.m. Eastern Time

GLYFADA, Greece, Nov. 06, 2026 (GLOBE NEWSWIRE) — Seanergy Maritime Holdings Corp. (the “Company” or “Seanergy”) (NASDAQ: SHIP) announced today that it will release its financial results for the third quarter and nine months ended September 30, 2026, prior to the open of the market in New York on Thursday, November 12, 2026.

Seanergy’s senior management will conduct a conference call and simultaneous Internet webcast to review these results on Thursday, November 12, 2026, at 10:00 a.m. Eastern Time.

Audio Webcast:
There will be a live, and then archived, webcast of the conference call available through the Company’s website. To listen to the archived audio file, visit our website, following the Webcast & Presentations section under our Investor Relations page. Participants to the live webcast should register on Seanergy’s website approximately 10 minutes prior to the start of the webcast, by following this link.

Conference Call Details:
Participants have the option to register for the call using the following link. You can use any number from the list or add your phone number and let the system call you right away.

About Seanergy Maritime Holdings Corp.
Seanergy Maritime Holdings Corp. is a prominent pure-play Capesize shipping company publicly listed in the U.S. Seanergy provides marine dry bulk transportation services through a modern fleet of Capesize vessels. The Company owns or operates under finance leases 19 vessels (2 Newcastlemax and 17 Capesize) with an average age of approximately 15.3 years and an aggregate cargo carrying capacity of 3,463,843 dwt. Upon the sale of the M/V Dukeship and the delivery of the seven newbuilding vessels and one secondhand Capesize vessel, the Company will own or operate under finance leases 26 vessels (3 Newcastlemax and 23 Capesize), with an aggregate cargo carrying capacity of approximately 4,763,552 dwt.

The Company is incorporated in the Republic of the Marshall Islands and has executive offices in Glyfada, Greece. The Company’s common shares trade on the Nasdaq Capital Market under the symbol “SHIP”.

Please visit our Company website at: www.seanergymaritime.com.

Forward-Looking Statements
This press release contains forward-looking statements (as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended) concerning future events, including with respect to declaration of dividends, market trends and shareholder returns. Words such as “may”, “should”, “expects”, “intends”, “plans”, “believes”, “anticipates”, “hopes”, “estimates” and variations of such words and similar expressions are intended to identify forward-looking statements. These statements involve known and unknown risks and are based upon a number of assumptions and estimates, which are inherently subject to significant uncertainties and contingencies, many of which are beyond the control of the Company. Actual results differ materially from those expressed or implied by such forward-looking statements. Factors that could cause actual results to differ materially include, but are not limited to, the Company’s operating or financial results; the Company’s liquidity, including its ability to service its indebtedness; competitive factors in the market in which the Company operates; shipping industry trends, including charter rates, vessel values and factors affecting vessel supply and demand; future, pending or recent acquisitions and dispositions, business strategy, impacts of litigation, areas of possible expansion or contraction, and expected capital spending or operating expenses; risks associated with operations outside the United States; risks arising from trade disputes between the U.S. and China, including the re-imposition of reciprocal port fees; broader market impacts arising from trade disputes or war (or threatened war) or international hostilities, such as between the U.S. and Israel and Iran, the U.S. and Venezuela, China and Taiwan and Russia and Ukraine; risks associated with the length and severity of pandemics; and other factors listed from time to time in the Company’s filings with the SEC, including its most recent annual report on Form 20-F. The Company’s filings can be obtained free of charge on the SEC’s website at www.sec.gov. Except to the extent required by law, the Company expressly disclaims any obligations or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in the Company’s expectations with respect thereto or any change in events, conditions or circumstances on which any statement is based.

For further information please contact:
Seanergy Investor Relations
Tel: +30 213 0181 522
E-mail: [email protected]

Capital Link, Inc.
Paul Lampoutis
230 Park Avenue Suite 1540
New York, NY 10169
Tel: (212) 661-7566
Email: [email protected]

Release – Cosmos Health’s CosmoFarm Begins Commissioning New Automated Order-Processing and Vehicle-Loading Infrastructure, Advancing Capacity That Could Support Over $120 Million in Annual Revenue

Cosmos Health logo

Research News and Market Data on COSM

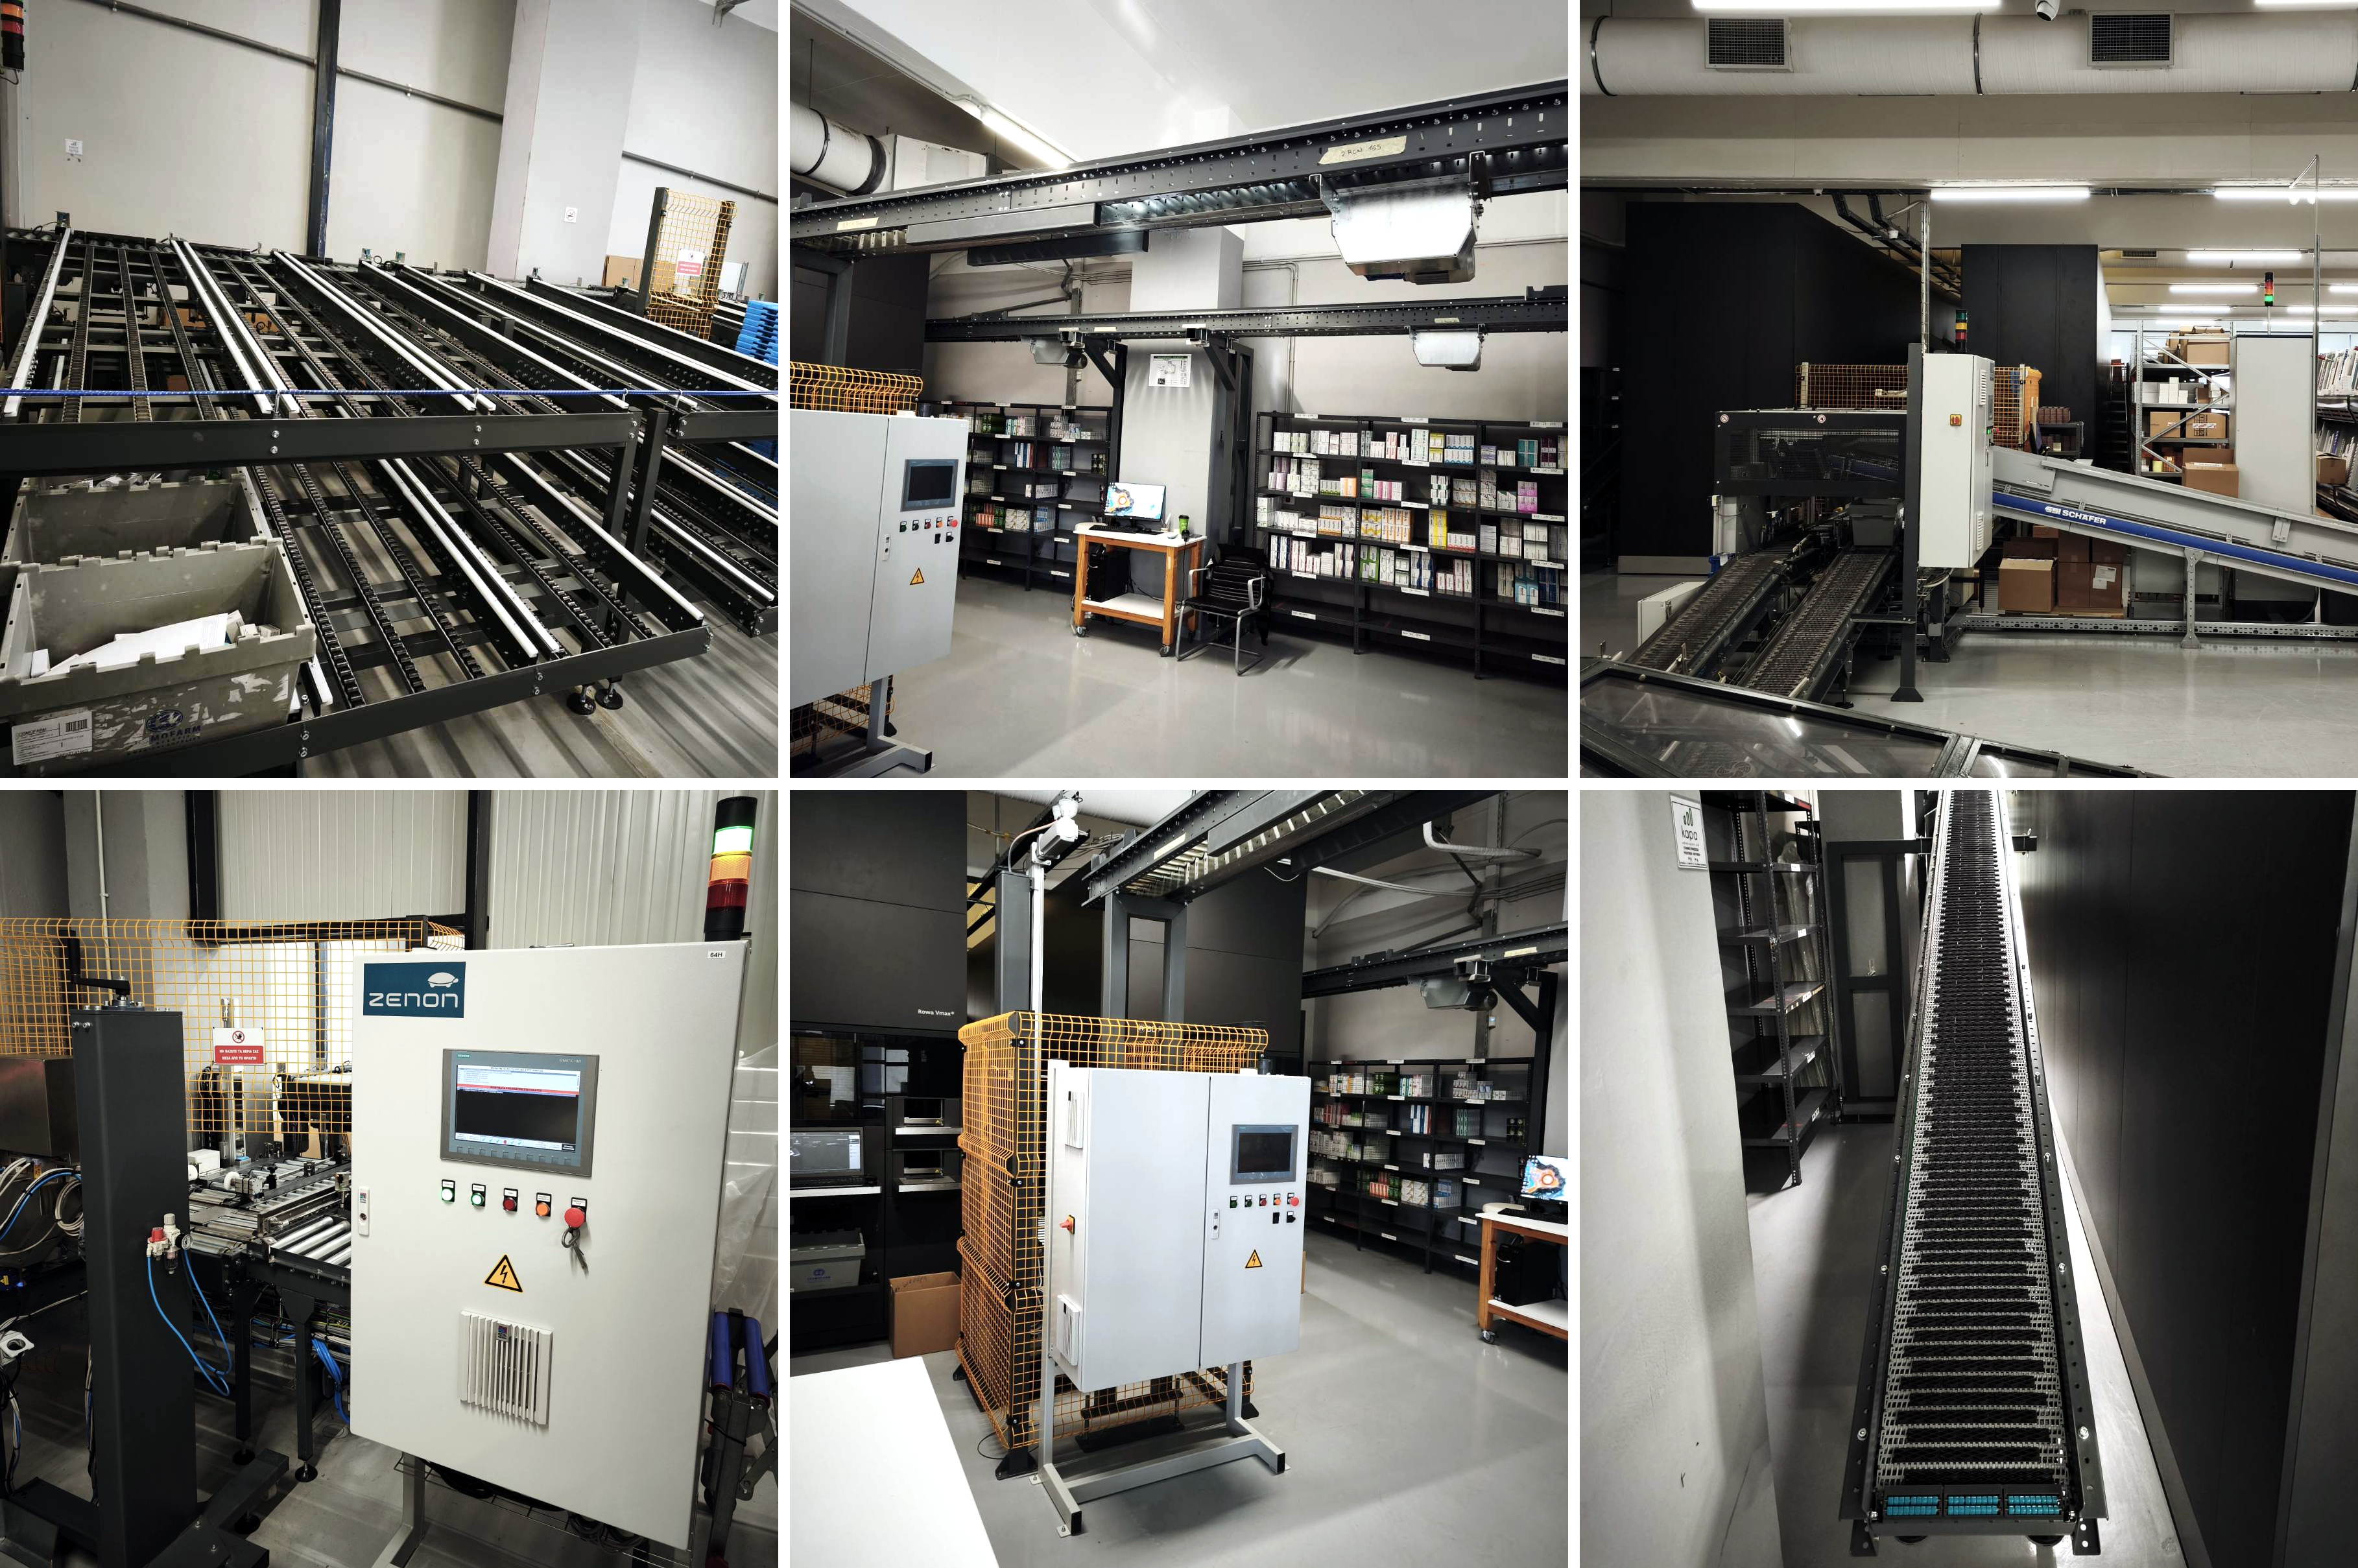
New order-processing line: automated handling cell and roller conveyor now being commissioned at CosmoFarm’s distribution center in Peristeri, Athens, designed to move more orders through the facility in less time

New vehicle-loading lanes: multiple rows of roller flow lanes designed to significantly reduce the time needed to load each delivery vehicle

Earlier dispatch: faster processing and loading are expected to get vehicles on the road sooner, supporting earlier pharmacy deliveries and capacity for additional routes

Acquisition pipeline: CosmoFarm has an active letter of intent to acquire a network with approximately €10 million (approximately $11.3 million) in annual gross revenue, which, if completed, would be its largest acquisition to date

Ongoing automation program: the new infrastructure is part of CosmoFarm’s multi-year program in robotics, automation and artificial intelligence

CHICAGO, IL / ACCESS Newswire / November 5, 2026 / Cosmos Health Inc. (“Cosmos Health” or the “Company”) (NASDAQ:COSM),a diversified, vertically integrated global healthcare group, today announced that its wholly owned pharmaceutical distribution subsidiary, CosmoFarm S.A. (“CosmoFarm”), is commissioning new automated order-processing and vehicle-loading infrastructure at its distribution center in Peristeri, western Athens, designed to move pharmacy orders through the facility and onto delivery vehicles faster.

Faster from Order to Dispatch

The new order-processing line consists of an automated handling cell fed by a roller conveyor, designed to automate the handling of orders ahead of dispatch. Engineers are currently configuring and testing the equipment on site.

Alongside the new line, CosmoFarm has installed multiple rows of inclined roller flow lanes to speed the movement of completed orders onto delivery vehicles. Together, the two installations are designed to significantly reduce processing and loading times, allowing vehicles to depart earlier. The Company expects to report operational results once the new infrastructure is fully up and running.

Automation at CosmoFarm’s distribution center in Peristeri, Athens

Building on a Record of Growth

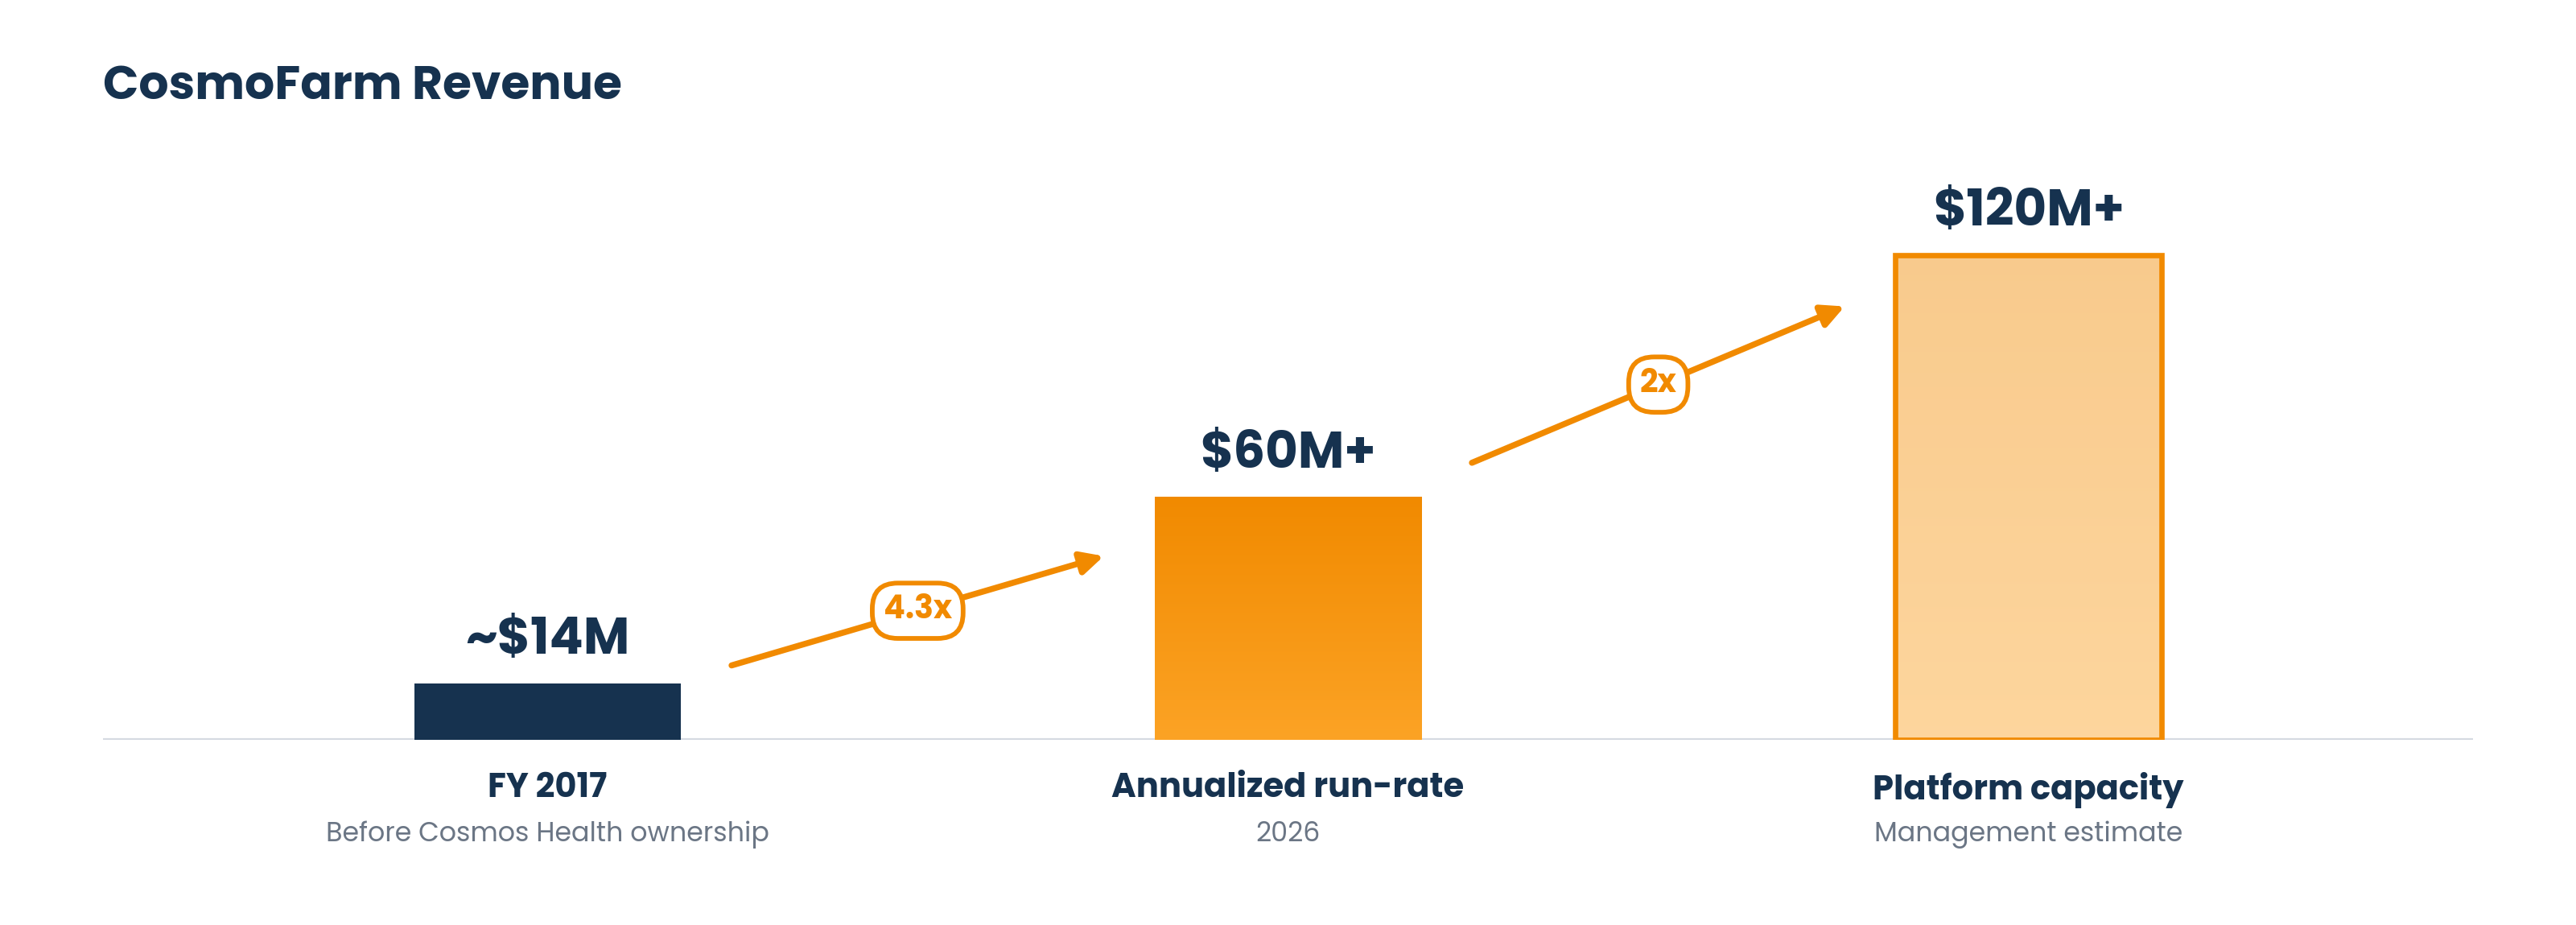
The investment builds on strong growth at CosmoFarm, which reached a previously disclosed annualized revenue run-rate of over $60 million based on second-quarter 2026 revenue, with this momentum continuing into the third quarter. That is more than four times its revenue before Cosmos Health acquired the business. It serves approximately 360 pharmacies daily within a network of more than 1,500, and faster processing and loading are expected to allow it to add more pharmacies to established routes at limited incremental cost.

With its ongoing investments in robotics, automation and artificial intelligence, including the new processing and loading infrastructure, the Company believes the CosmoFarm platform could support over $120 million in annual revenue.

Capacity for Consolidation

The added capacity also supports CosmoFarm’s consolidation strategy in Greece’s fragmented pharmaceutical wholesale market. Since 2019, CosmoFarm has completed multiple bolt-on acquisitions of regional distribution networks, integrating their customers onto its automated platform, and the expanded infrastructure positions it to absorb further acquired volume.

A further network acquisition remains at the letter of intent stage. The target network generates approximately €10 million (approximately $11.3 million) in annual gross revenue and is owned by an established pharmaceutical company that has served the Greek market for almost 40 years. If completed, it would be CosmoFarm’s largest acquisition to date. The transaction is subject to a definitive agreement and customary closing conditions, and there can be no assurance that it will be completed.

CEO Commentary

Greg Siokas, CEO of Cosmos Health, stated: “CosmoFarm has grown more than four times under our ownership, and speed is what wins and keeps pharmacies in our market. This investment is designed to process orders faster and get our vehicles on the road sooner, which should mean better service for our customers and more capacity on every route.

“We expect it to help us keep adding pharmacies, organically and through acquisitions, without adding proportional cost, and the letter of intent we signed this year would, if completed, be our largest acquisition yet. It is the next step in building CosmoFarm into a platform that could support over $120 million in annual revenue.”

CosmoFarm | A Cosmos Health Company

About Cosmos Health Inc.

Cosmos Health Inc. (NASDAQ: COSM), incorporated in 2009 in Nevada, is a diversified, vertically integrated global healthcare group. The Company owns a portfolio of proprietary pharmaceutical and nutraceutical brands, including Sky Premium Life®, Mediterranation®, bio-bebe®, C-Sept® and C-Scrub®. Through its subsidiary Cana Laboratories S.A., licensed under European Good Manufacturing Practices (GMP) and certified by the European Medicines Agency (EMA), it manufactures pharmaceuticals, food supplements, cosmetics, biocides, and medical devices within the European Union. Cosmos Health also distributes a broad line of pharmaceuticals and parapharmaceuticals, including branded generics and OTC medications, to retail pharmacies and wholesale distributors through its subsidiaries in Greece and the UK. Furthermore, the Company has established R&D partnerships targeting major health disorders such as obesity, diabetes, and cancer, enhanced by artificial intelligence drug repurposing technologies, and focuses on the R&D of novel patented nutraceuticals, specialized root extracts, proprietary complex generics, and innovative OTC products. Cosmos Health has also entered the telehealth space through the acquisition of ZipDoctor, Inc., based in Texas, USA. With a global distribution platform, the Company is currently expanding throughout Europe, Asia, and North America, and has offices and distribution centers in Thessaloniki and Athens, Greece, and in Harlow, UK. More information is available at www.cosmoshealthinc.com, www.skypremiumlife.com, www.cana.gr, www.zipdoctor.co, www.cloudscreen.gr, as well as LinkedIn and X.

Forward-Looking Statements

With the exception of the historical information contained in this news release, the matters described herein may contain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Words such as “believes,” “expects,” “anticipates,” “intends,” “projects,” “estimates,” “plans,” and similar expressions, or future or conditional verbs such as “will,” “should,” “would,” “may,” and “could,” generally identify forward-looking statements, although not all forward-looking statements contain these words. These statements involve risks and uncertainties that may individually or materially affect the matters discussed herein for a variety of reasons outside the Company’s control, including, but not limited to: the Company’s ability to raise sufficient financing to implement its business plan; the effectiveness of its digital asset strategies, including accumulation and yield-generating activities; the impact of the war in Ukraine and ongoing conflicts in the Middle East and other regions on the Company’s business, operations, and the economy in general; the Company’s ability to successfully develop and commercialize its proprietary products and technologies; the timing, execution, regulatory clearance, valuation, structuring, and completion of any potential asset-backed or tokenized financing program; the legal, regulatory, and technological risks associated with digital assets and blockchain-based financial structures; the conversion of contract manufacturing pipeline volumes into production and revenue, including the timing, volume and terms of orders placed under multi-year agreements; the realization of anticipated gross margins; the timing, cost and completion of planned capital investments; changes in interest rates; changes in foreign currency exchange rates, commodity or other price inflation and deflation; our ability to issue debt on terms and at rates acceptable to us; the impact and expected outcome of investigations, inquiries, claims, and litigation; the challenges of operating in international markets; the adequacy of insurance coverage; the effect of accounting charges and of adopting certain accounting standards; the impact of legal and regulatory changes, including changes to tax laws and regulations; guidance for fiscal 2026 and beyond and financial outlook. Forward-looking statements are based on currently available information and our current assumptions, expectations and projections about future events. You should not rely on our forward-looking statements. These statements are not guarantees of future performance and are subject to future events, risks and uncertainties – many of which are beyond our control, dependent on the actions of third parties, or currently unknown to us – as well as potentially inaccurate assumptions that could cause actual results to differ materially from our historical experience and our expectations and projections. These risks and uncertainties include, but are not limited to, those described from time to time in our periodic reports filed with the SEC and available at the SEC’s website (www.sec.gov). There also may be other factors that we cannot anticipate or that are not described herein, generally because we do not currently perceive them to be material. Such factors could cause results to differ materially from our expectations. Forward-looking statements speak only as of the date they are made, and we do not undertake to update these statements other than as required by law. You are advised, however, to review any further disclosures we make on related subjects in our filings with the Securities and Exchange Commission and in our other public statements.

Investor Relations Contact:

BDG Communications
[email protected]

Note: CosmoFarm figures are based on management data, are preliminary and unaudited, and may differ from amounts in the Company’s financial statements. The annualized run-rate is calculated from second-quarter 2026 revenue, takes into account third-quarter 2026 results, and is not a forecast. U.S. dollar figures reflect euro/U.S. dollar exchange rate changes. Expected improvements and revenue capacity are management estimates based on current expectations; actual results may differ materially.

SOURCE: Cosmos Health Inc.

View the original press release on ACCESS Newswire

Release – InPlay Oil Corp. Announces Third Quarter 2026 Financial and Operating Results and Preliminary 2027 Guidance Highlighted by 15% Per Share Growth in Oil Production

Research News and Market Data on IPOOF

Nov 05, 2026, 07:30 ET

CALGARY, AB, Nov. 5, 2026 /CNW/ — InPlay Oil Corp. (TSX: IPO) (TASE: IPO) (OTCQX: IPOOF) (“InPlay” or the “Company”) is pleased to announce its financial and operating results for the three and nine months ended September 30, 2026, together with preliminary 2027 production and capital guidance. InPlay’s unaudited interim financial statements and notes, and Management’s Discussion and Analysis (“MD&A”) for the three and nine months ended September 30, 2026 will be available at “www.sedarplus.ca” and the Company’s website at “www.inplayoil.com“. An updated corporate presentation will be available on our website in due course.

Message to Shareholders:

During the third quarter, InPlay continued its track record of completing highly accretive strategic transactions through the acquisition of a private oil and gas producer. The acquisition was 28% accretive to both Adjusted Funds Flow (“AFF”)(1) and Free Adjusted Funds Flow (“FAFF”)(2) on a per share basis and enhanced InPlay’s capacity to generate FAFF going forward. It also expanded InPlay’s producing asset base and drilling inventory adjacent to existing operations, strengthening our platform for continued development. Third-quarter results reflect just over five weeks of results from this complementary acquisition in our core area.

The third quarter marked InPlay’s most active capital program of the year, drilling seven (6.7 net) horizontal wells along with the initiation of drilling operations on an additional one (1.0 net) well prior to quarter-end. The Company also participated in two (0.2 net) non-operated Pembina wells that were drilled in September and brought on production in early November.

Two Cardium wells drilled in the quarter were brought on production in mid-September and have performed ahead of internal expectations. These wells achieved average initial production (“IP”) rates of 231 boe/d (97% light oil and NGLs) per well over their first 30 days of production and they are currently producing at a rate of 344 boe/d (88% light oil and NGLs) per well, significantly ahead of internal oil type curves.

Three additional Cardium wells were brought on production in late-October and are currently in the clean-up phase. InPlay also commenced development drilling on its newly acquired Belly River assets. Drilling began on a two-well pad in late September with the first well being fully drilled by quarter-end. Both wells have been brought on production in the past few days.

Drilling also began on a separate two-well Cardium pad in late September, with the first well being fully drilled by quarter-end. Both wells have now been drilled, are currently being completed and are expected to come on production mid-November. Wet weather has delayed the availability of frac crews by two to three weeks from originally planned.

The Company’s 2026 capital program is substantially complete, with expenditures to date below budget. Strong capital efficiencies supported the previously announced expansion of the drilling program where the number of planned wells increased by 30% with only a 15% increase in capital (from mid-point).

The third quarter included significant capital investment with only two (2.0 net) wells brought on production during the period. Seven (4.9 net) wells drilled in the third quarter, along with an additional two (2.0 net) wells drilled through quarter end, are coming on production in a short, four-week window through mid-November. This substantial influx of new production, combined with the strong commodity price outlook, are expected to drive record fourth quarter AFF and FAFF, providing strong operational momentum heading into 2027.

Reflecting the strong 2026 production performance to date, and notwithstanding weather related delays, InPlay reiterates its 2026 average annual production guidance of 18,900 – 19,400 boe/d(3) (61% – 63% light oil and NGLs). Based on current strip pricing, the Company has increased forecast 2026 AFF by 10% to $178 – $184 million. Forecast FAFF has increased by 19% to $96 – $104 million, representing a FAFF yield of 19% – 21%. Year-end net debt to annualized Q4 2026 EBITDA is forecast at 1.0x – 1.1x.

Preliminary 2027 Guidance

InPlay is excited to provide preliminary 2027 production and capital guidance. With 2027 WTI strip pricing of approximately US$80/bbl and AECO pricing below $2.00/GJ, the Company’s capital program will target increased organic growth through focused oil-weighted drilling, including expanded Belly River development on newly acquired lands. This focus prioritizes higher-value oil production over total boe volumes, with over 85% of our revenue coming from oil.

Key highlights of the preliminary 2027 capital program include:

  • Capital program of $95 – $105 million.
  • Production of 20,100 – 21,000 boe/d(3) (64% – 65% light oil and NGLs).
    • Oil production per share growth of 15%(5) from 2026.
    • Total production per share growth of 8%(5) from 2026.
  • AFF of $206 – $218 million, a 17%(5) increase from 2026.
  • FAFF of $101 – $123 million, a 12%(5) increase from 2026.
  • FAFF yield of 22%(5), among the highest of Canadian-listed E&P companies.
  • Capital expenditures represent 47%(5) of AFF. Capital expenditures plus dividends represent 61%(5) of AFF.

InPlay’s forecast FAFF of $101 – $123 million is expected to support the Company’s dividend, significant share repurchases and material debt reduction. Share repurchases represent a compelling opportunity to enhance shareholder value as the Company believes the prevailing market price of its Common Shares does not reflect the underlying intrinsic value. Strong FAFF generation and debt reduction are also expected to increase financial capacity for further accretive acquisitions, building on InPlay’s track record of delivering per share growth.

The table below outlines InPlay’s 2027 preliminary guidance:

Preliminary
2027 Guidance
(6)
WTI (US$/bbl)$80.00
FX (US$/CAD$)0.72
AECO (CAD$/GJ)$1.90
Production (boe/d) (3)20,100 – 21,000
Oil production (bbl/d)10,725 – 11,110
Capital ($ millions)$95 – $105
AFF ($ millions) (1)$206 – $218
FAFF ($ millions) (2)$101 – $123

InPlay retains flexibility to adjust activity as commodity prices, services availability and costs evolve. The Company may advance a portion of its 2027 capital program into December 2026 to retain its drilling rig and crew following their exceptionally strong performance in 2026. This would also allow the Company to secure services ahead of an anticipated period of high industry activity in Western Canada during the first quarter of 2027.

InPlay expects to announce its finalized 2027 capital budget and guidance in January 2027, following Board approval. Preliminary guidance remains subject to refinement as the Company completes its planning process and assesses prevailing market conditions.

Third Quarter 2026 Highlights:

  • Achieved average quarterly production of 19,254 boe/d(1) (62% light crude oil and NGLs), a 3% increase from Q2 2026.
  • Improved light oil production to 9,565 bbl/d, a 5% increase from Q3 2025 driving strong per boe netbacks and returns.
  • Realized operating income(2) of $61.7 million, a 78% increase from Q3 2025, and an operating income profit margin(2) of 52%, a 19% improvement from Q3 2025. Operating netbacks(2) improved to $34.85/boe, an increase of 75% compared to Q3 2025.
  • Delivered record AFF of $51.4 million ($1.86 per basic share(4)), a 92% increase from Q3 2025.
  • Generated FAFF of $29.0 million.
  • Returned $7.5 million ($0.27/share) to shareholders through monthly dividends (6.0% yield relative to current share price). Cumulative dividends declared since November 2022 total approximately $90 million ($4.41/share), including dividends declared to date in Q4 2026.
  • Repurchased and cancelled 0.7% of outstanding common shares during the quarter. Since the initiation of purchases under our Normal Course Issuer Bid (“NCIB”) in June 2026, 2.1% of the Company’s outstanding common shares have been repurchased and cancelled to date.
  • Successfully closed the accretive acquisition of a private light oil weighted producer on August 21, 2026 for $54.4 million, adding 1,400 boe/d (85% light oil and NGLs) of production at closing and 50 net drilling locations with short payout periods in our core area.
  • On July 24, 2026, the Company renewed its Senior Credit Facility, which now consists of committed amounts of a $140 million revolving line of credit and a $50 million operating line of credit. In addition, the borrowing base was expanded by $60 million, for a total borrowing base of $250 million.

Third Quarter 2026 Financial & Operations Overview:

InPlay completed an active capital program during the third quarter, investing $22.3 million to drill and complete two (2.0 net) Cardium wells, drill four (3.7 net) Cardium wells and one (1.0 net) Belly River well. Drilling operations also began on an additional one (1.0 net) Belly River well which finished in the fourth quarter. Operational execution remained strong, with drilling and completion operations executed on budget despite periods of wet weather during the quarter. 

Quarterly production averaged 19,254 boe/d(1) (62% light crude oil and NGLs), representing a 3% increase from the second quarter of 2026. Crude oil production remained strong averaging 9,565 bbl/d, a 5% increase from the third quarter of 2025.

Improved oil prices and strong light oil production resulted in InPlay delivering AFF of $51.4 million ($1.86/share), a second consecutive quarterly record and a 92% increase from the third quarter of 2025. InPlay also returned $7.5 million ($0.27/share) to shareholders through dividends. Since November 2022, InPlay has declared $90 million ($4.41/share) in dividends, including dividends declared to date in the fourth quarter. In addition, the Company spent $3.3 million repurchasing common shares during the quarter, representing approximately 0.7% of outstanding common shares. Since the initiation of purchases under the NCIB in June 2026, InPlay has repurchased approximately 2.1% of outstanding common shares.  

Financial and Operating Results:

Three months ended
September 30
Nine months ended
September 30
2026202520262025
Financial  (CDN – $millions)
Oil and natural gas sales118.879.3331.4209.9
Adjusted funds flow(1)51.426.8126.383.7
    Per share – basic(4)1.860.964.553.59
    Per share – diluted(4)1.760.964.303.59
    Per boe(3)29.0115.3624.6618.93
Comprehensive income (loss)(2.1)(4.8)(13.9)(10.9)
Per share – basic(0.08)(0.17)(0.50)(0.47)
Per share – diluted(0.08)(0.17)(0.50)(0.47)
Dividends7.57.522.619.5
Per share – declared0.270.270.810.84
Capital expenditures – PP&E and E&E22.322.361.540.8
Property acquisitions54.3(1.7)54.7291.9
Net debt(1)(257.5)(228.4)(257.5)(228.4)
Shares outstanding27.527.827.527.8
Basic weighted-average shares27.627.827.823.3
Diluted weighted-average shares29.227.829.323.3
Operational
Daily production volumes
Light and medium crude oil (bbls/d)9,5659,1229,2567,647
Natural gas liquids (boe/d)2,3472,3342,2892,105
Conventional natural gas (Mcf/d)44,05545,08143,26038,596
Total (boe/d)19,25418,97018,75516,185
Realized prices(4)
Light and medium crude oil & NGLs ($/bbls)101.9272.3597.6872.88
Conventional natural gas ($/Mcf)1.760.751.991.51
Total ($/boe)67.0745.4764.7247.50
Operating netbacks ($/boe)(2)
Oil and natural gas sales67.0745.4764.7247.50
Royalties(12.18)(7.13)(10.55)(6.56)
Transportation expense(1.07)(0.87)(1.02)(0.85)
Operating costs(18.97)(17.61)(18.83)(16.06)
  Operating netback(2)34.8519.8634.3124.03
Realized gain (loss) on derivative contracts(0.31)1.07(3.95)0.35
  Operating netback (including realized derivative contracts) (2)34.5420.9330.3624.38

On behalf of our employees, management team and Board of Directors, we thank our shareholders for their continued support. With an expanded portfolio of high-quality light oil assets and a deep inventory of attractive drilling opportunities, InPlay is well positioned to build on its operational momentum through the remainder of 2026 and into 2027. We remain focused on disciplined capital allocation, sustainable acquisition and organic growth and debt reduction while continuing to return capital to shareholders and create long-term value.

For further information please contact:

Doug Bartole                                                       Kevin Leonard 
President and Chief Executive Officer                Vice President Corporate & Business Development
InPlay Oil Corp.                                                   InPlay Oil Corp. 
Telephone: (587) 955-0632                                 Telephone: (587) 955-0635

Notes:
1.Capital management measure. See “Non-GAAP and Other Financial Measures” contained within this press release.
2.Non-GAAP financial measure or ratio that does not have a standardized meaning under International Financial Reporting Standards (IFRS) and GAAP and therefore may not be comparable with the calculations of similar measures for other companies. Please refer to “Non-GAAP and Other Financial Measures” contained within this press release and in our most recently filed MD&A.
3.See “Production Breakdown by Product Type” at the end of this press release.
4.Supplementary financial measure. See “Non-GAAP and Other Financial Measures” contained within this press release.
5.Based on mid-point of 2026 guidance or 2027 preliminary guidance where applicable.
6.InPlay’s preliminary 2027 guidance reflects management’s current expectations and is based on a proposed capital program that remains subject to Board approval. The final capital program and associated guidance may differ materially.

View full release here.

SOURCE InPlay Oil Corp.

Release – NETSOL Technologies to report fiscal first quarter 2027 results on November 12

NETSOL Technologies, Inc.

Research News and Market Data on NTWK

Download as PDF

November 05, 2026

Company to discuss results for the fiscal first quarter ended September 30, 2026, highlighting key developments and its outlook for the rest of fiscal 2027

ENCINO, Calif., Nov. 05, 2026 (GLOBE NEWSWIRE) — NETSOL Technologies, Inc. (Nasdaq: NTWK), a provider of AI-enabled solutions and services powering OEMs, dealerships and financial institutions to sell, finance and lease assets, will hold a conference call on Thursday, November 12, 2026, at 9:00 am Eastern Time (6:00 am Pacific Time) to discuss its financial results for the fiscal first quarter of 2027 ended September 30, 2026. A question-and-answer session will follow management’s prepared remarks.

Date: Thursday, November 12, 2026
Time: 9:00 am Eastern Time (6:00 am Pacific Time)
Participant listening: 1-877-407-0789 or 1-201-689-8562

The conference call will also be broadcast live and available for replay here (the link will be made active 15 minutes prior to scheduled start time), along with additional replay access being provided through the company information section of NETSOL’s website.

Telephone replays will be made available approximately 3 hours after conference end time.

Telephone replay
Replay dial-in: 1-844-512-2921 or 1-412-317-6671
Replay expiration: Thursday, November 26, 2026 at 11:59 PM ET
Access ID: 13763709

About NETSOL Technologies
NETSOL Technologies delivers state-of-the-art solutions for asset finance, leasing and digital automotive retail, serving automotive and equipment OEMs, dealerships, auto captives and financial institutions across over 30 countries. Since its inception in 1997, NETSOL has been at the cutting edge of technology, pioneering innovations with its asset finance solutions, and today leverages advanced AI and cloud services to meet the complex needs of the global market. Renowned for its deep industry expertise, customer-centric approach and commitment to excellence, NETSOL fosters strong partnerships with its customers, ensuring their success in an ever-evolving landscape. With a rich history of innovation, ethical business practices and a focus on sustainability, NETSOL is dedicated to empowering businesses worldwide, securing its position as the trusted partner for leading firms around the globe.

Forward-Looking Statements
This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the company’s products and services, expectations for future operations, and other statements that are not historical facts. These forward-looking statements may be identified by terminology such as “expects,” “anticipates,” “believes,” “intends,” “plans,” “projects,” “targets,” and similar expressions. These statements are not guarantees of future performance and are subject to a number of risks, uncertainties, and assumptions that are difficult to predict. Factors that could cause actual results to differ materially include, but are not limited to, the timing of customer go-lives and contract renewals, the rate of adoption of AI-enabled product capabilities, foreign currency volatility, and other factors discussed in NETSOL’s most recent Annual Report on Form 10-K and subsequent Quarterly Reports on Form 10-Q filed with the U.S. Securities and Exchange Commission. Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date hereof. NETSOL undertakes no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events, or otherwise.

Investor Relations Contact:
Investor Relations
(818) 222-9195
[email protected]

Primary Logo

Source: NETSOL Technologies Inc.

Released November 5, 2026

Release – Kelly Reports Third-Quarter 2026 Earnings

Research News and Market Data on KELYA

November 5, 2026

PDF Version

TROY, Mich., Nov. 05, 2026 (GLOBE NEWSWIRE) — Kelly (Nasdaq: KELYA, KELYB), a leading specialty talent solutions provider, today announced results for the third quarter of 2026.

  • Q3 revenue of $0.9 billion, down 0.8% year-over-year, an improvement of 500 basis points (“bps”) versus the prior quarter; underlying revenue, which excludes previously disclosed discrete impacts, grew 2.3% year-over-year
  • ETM underlying revenue grew 7.7% (2.4% reported) while SET underlying revenue decreased 0.8% (2.0% reported). The underlying performance for ETM and SET improved 460 bps and 220 bps versus the prior quarter, respectively
  • Q3 operating earnings of $0.6 million; $6.1 million of operating earnings on an adjusted basis
  • Adjusted EBITDA of $21.3 million and adjusted EBITDA margin of 2.3%, which expanded 50 bps on a year-over-year basis resulting from improved gross profit rate and continued SG&A discipline

Chris Layden, chief executive officer, said, “In the third quarter, we delivered results above the midpoint of our guidance, driven by meaningful progress on our growth and efficiency initiatives along with increasingly constructive demand trends. Year-over-year revenue improved sequentially for a third consecutive quarter, and we drove adjusted EBITDA margin expansion over the prior year period. Our performance reflects positive operational momentum across much of our portfolio, as ETM pivoted to positive year-over-year revenue growth in the quarter and SET delivered another quarter of sequential revenue improvement. We remain well positioned to capitalize on increasing demand while continuing to drive margin expansion and long-term value creation.”

Financial Results for the 13-week period ended September 27, 2026:

Revenue of $0.9 billion, a 0.8% decrease compared to the corresponding quarter of 2025 and an improvement of 500 bps versus the prior quarter. Discrete impacts associated with the previously disclosed reduced demand for U.S. federal government contractors in the SET segment and from three large commercial customers in the ETM segment totaled approximately 3.1%, resulting in an underlying revenue increase of approximately 2.3%. Underlying revenue performance includes overall growth from improved demand and new business in the ETM segment, including growth in staffing and each of the talent solutions specialties. Offsetting the growth were declines in SET, which showed continued sequential improvement, and Education segments. Within the SET segment, the Science and Engineering specialties grew year-over-year, while the Technology specialty continued to strengthen sequentially. The Education segment continues to be impacted by declines in demand primarily driven by reduced student enrollment in key markets.

Operating earnings of $0.6 million, compared to a loss of $102.1 million reported in the third quarter of 2025. Prior year operating loss reflected a non-cash goodwill impairment charge totaling $102.0 million. Adjusted operating earnings1 were $6.1 million in the third quarter of 2026 and $4.3 million in the third quarter of 2025. Adjusted EBITDA1 of $21.3 million, an increase of 29.1% versus the prior year period. Adjusted EBITDA margin of 2.3%, an increase of 50 bps versus the prior year, reflects 20 bps higher gross margin and volume-related and structural expense management actions including benefits from our acquisition integration and technology modernization efforts. ETM and SET showed year-over-year improvement in their adjusted EBITDA margin while Education was negative due to the school year seasonality. Both ETM and SET improved their adjusted EBITDA margins measurably versus the prior quarter.

Income tax expense of $1.2 million, compared to income tax expense of $46.4 million reported in the third quarter of 2025, with the change primarily driven by the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, income tax expense of $2.6 million, compared to income tax benefit of $3.8 million in the third quarter of 2025.

Loss per share was $0.05 compared to loss per share of $4.26 in the third quarter of 2025, and reflects the impact of the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, earnings per share was $0.07 in the third quarter of 2026 compared to $0.17 per share in the corresponding quarter of 2025.

Financial Results for the 39-week period ended September 27, 2026:

Revenue of $3.0 billion, a 6.1% decrease compared to the corresponding period in 2025. Discrete impacts associated with the reduced demand for U.S. federal government contractors in the SET segment and from three large commercial customers in the ETM segment totaled approximately 5.4%, resulting in an underlying revenue decline of approximately 0.7%. Underlying revenue performance includes overall growth from improved demand in the ETM segment, including growth in each of the talent solutions specialties, along with growth in the Telecom specialty and improved performance in the Science and Engineering specialties within the SET segment. Offsetting this growth was continued lower demand in the other specialties within the SET segment, largely the Technology specialty, along with a decline in the Education segment driven by delayed prior year contract decisions and declines in demand primarily driven by reduced student enrollment in key markets.

Operating earnings of $11.6 million, compared to a loss of $69.1 million reported over the same period in 2025. Prior year operating loss reflected a non-cash goodwill impairment charge totaling $102.0 million. Adjusted operating earnings1 were $29.5 million in the first nine months of 2026 and $51.0 million in the corresponding period of 2025. Adjusted EBITDA1 of $68.2 million, a decrease of 22.9% versus the prior year period. Adjusted EBITDA margin of 2.3%, a decrease of 50 bps, reflects near-term margin pressure in ETM, Education, and SET driven by lower gross margins and timing of revenue trends, partially offset by volume-related and structural expense management actions including benefits from our acquisition integration and technology modernization efforts.

Income tax expense of $3.4 million, compared to income tax expense of $49.1 million reported over the same period in 2025, with the change primarily driven by the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, income tax expense of $7.9 million, compared to income tax expense of $3.4 million in the corresponding period of 2025.

Earnings per share was $0.10, compared to loss per share of $3.56 in the same period of 2025, and reflects the impact of the valuation allowance and goodwill impairment charges in the prior year. On an adjusted basis1, earnings per share was $0.46 for the first nine months of 2026 compared to $1.10 per share in the corresponding period of 2025.

1 Adjusted measures represent non-GAAP financial measures. Refer to our reconciliation of non-GAAP financial measures to the most closely related GAAP measure included in this document.

Financial Outlook for Fiscal Fourth Quarter 2026

The Company’s financial outlook assumes no material change in the macroeconomic environment relative to the third quarter, and is consistent with the full year expectations set in February of this year. For the fourth quarter, expectations for revenue growth and adjusted EBITDA margin have been adjusted relative to our prior view largely due to the delayed return to growth in our Education business and near-term incremental demand pressure from one discrete ETM customer, and are as follows:

  • Fourth Quarter of 2026 – Expect revenue to be flat to up 1% on a year-over-year basis and adjusted EBITDA margin expansion of 180 to 200 bps year-over-year resulting in a margin of 3.8% to 4.0%.
    • Outlook includes the impact of an extra fiscal week in the fourth quarter, which benefits revenue growth by approximately 3 points in the fourth quarter, but negatively impacts adjusted EBITDA.
  • Full Year 2026 – On a full year basis, expect a mid-single digit total revenue decline and adjusted EBITDA margin of 2.6% to 2.7%, reflecting flat to 10 bps of year-over-year improvement.

Quarterly Cash Dividend and Share Repurchase Renewal and Extension:

Kelly also reported that on November 4, 2026, its board of directors declared a dividend of $0.075 per share. The dividend is payable on December 2, 2026 to stockholders of record as of the close of business on November 18, 2026.

On November 4, 2026, the board of directors approved the renewal and extension of the Company’s share repurchase program without an expiration date, which authorized the repurchase of up to $50.0 million of Class A common stock. The new authorization is inclusive of the amount that remained available under the prior authorization, which was superseded and replaced.

In conjunction with its earnings release, Kelly has published a financial presentation and will host a live webcast of a conference call at 9 a.m. ET on November 5 to review the financial and operational results from the quarter. The presentation and a link to the live webcast will be accessible through the Company’s public website on the Investor Relations page under Events & Presentations. The webcast will be recorded, and a replay will be available within one hour of completion of the event through the same link as the live webcast.

Forward-Looking Statements:

This release contains statements that are forward-looking in nature and, accordingly, are subject to risks and uncertainties. These statements are made under the “safe harbor” provisions of the U.S. Private Securities Litigation Reform Act of 1995. Statements that are not historical facts, including statements about Kelly’s financial expectations, are forward-looking statements. Factors that could cause actual results to differ materially from those contained in this release include, but are not limited to, (i) changing market and economic conditions, (ii) disruption in the labor market and weakened demand for human capital resulting from technological advances, competitive pressures and pricing, loss of large corporate customers and government contractor requirements, (iii) the impact of laws and regulations (including federal, state and international tax laws), (iv) unexpected changes in claim trends on workers’ compensation, unemployment, disability and medical benefit plans, (v) litigation and other legal liabilities (including tax liabilities) in excess of our estimates, (vi) our ability to achieve our business’s anticipated growth strategies, (vii) our future business development, results of operations and financial condition, (viii) damage to our brands, (ix) dependence on third parties for the execution of critical functions, (x) conducting business in foreign countries, including foreign currency fluctuations, (xi) availability of temporary workers with appropriate skills required by customers, (xii) cyberattacks or other breaches of network or information technology security, and (xiii) other risks, uncertainties and factors discussed in this release and in the Company’s filings with the Securities and Exchange Commission. In some cases, forward-looking statements can be identified by words or phrases such as “may,” “will,” “expect,” “anticipate,” “target,” “aim,” “estimate,” “intend,” “plan,” “believe,” “potential,” “continue,” “is/are likely to” or other similar expressions. All information provided in this press release is as of the date of this press release and we undertake no obligation to update any forward-looking statement, whether as a result of new information, future events, or otherwise, except as required by law.

About Kelly®

Kelly Services, Inc. (Nasdaq: KELYA, KELYB) helps companies recruit and manage skilled workers and helps job seekers find great work. Since inventing the staffing industry in 1946, we have become experts in the many industries and local and global markets we serve. With a network of suppliers and partners around the world, we connect approximately 375,000 people with work every year. Our suite of outsourcing and consulting services and solutions ensures companies have the people they need, when and where they are needed most. Headquartered in Troy, Michigan, we empower businesses and individuals to access limitless opportunities in industries such as science, engineering, technology, education, manufacturing, retail, finance, and energy. Revenue in 2025 was $4.3 billion. Learn more at kellyservices.com.

KLYA-FIN

View full release here.

Release – Lucky Strike Entertainment Reports First Quarter Results for Fiscal Year 2027

 Lucky Strike Entertainment Investor Relations site

Research News and Market Data on LUCK

11/05/2026

RICHMOND, Va.–(BUSINESS WIRE)– Lucky Strike Entertainment (NYSE: LUCK), one of the world’s premier owner/operators of location-based entertainment, today provided financial results for the first quarter of the 2027 fiscal year, which ended on September 27, 2026.

Highlights:

  • Total revenue increased 3.5% to $302.6 million versus 1Q26
  • Same-store revenue decreased 2.6% versus 1Q26
  • Net loss of $25.7 million versus net loss of $13.8 million in 1Q26
  • Adjusted EBITDA of $72.1 million versus $72.7 million in 1Q26
  • Net cash provided by operating activities of $17.1 million versus net cash used of $6.4 million in 1Q26
  • Capital expenditures of $21.5 million versus $25.9 million in 1Q26
  • Unveiled the refreshed AMF brand and converted 42 additional locations to the Lucky Strike brand during the quarter; 182 Lucky Strike locations as of November 5, 2026
  • Total locations in operation as of November 5, 2026, were 366

“Revenue grew in the first quarter, helped by our first full summer with two new water parks, and while same-store revenue was down, it improved every month and September comped positive,” said Thomas Shannon, Founder and CEO. “We are in a better place than a year ago, but a negative comp is a negative comp, and fixing it comes first.”

“The decline was in retail bowling, our walk-in business, and in alcohol, which is down across the restaurant industry. Events, leagues, food and non-alcoholic beverage grew. Events has now matched or beaten last year for six straight months, and the holiday book is ahead, led by corporate events, while smaller, price-sensitive parties remain under pressure, as the lower-end consumer has for several quarters. Leagues grew despite starting later this fall. California, still our weakest market, narrowed the gap every month and comped slightly positive in September.”

“The water parks were meaningfully more profitable than last year, and with the parks now closed, our focus is next season’s pass sales and pricing, where this year’s lesson is to sell earlier.”

“Capital spending in the quarter was the lowest in five years, and we expect the full year at roughly half its fiscal 2024 peak. With capital spending down, no acquisitions and lower litigation costs, we expect to direct meaningful free cash flow, plus proceeds from a few non-core asset sales, to debt reduction. The Board has also suspended our quarterly dividend. That is a decision about where the next dollar goes, not a change in our view of the long-term earnings power of the business.”

Fiscal Year 2027 Guidance
The Company is reaffirming the fiscal year 2027 guidance provided on August 27, 2026. We remain focused on delivering sustainable, profitable growth and creating meaningful long-term shareholder value. Our strategy is centered on accelerating revenue growth, expanding operating cash flow, and driving higher free cash flow per share through earnings growth and disciplined capital allocation. Looking ahead, our outlook reflects continued organic revenue growth, targeted investments in marketing and technology to strengthen our platform, and incremental contributions from our waterparks in FY27. Together, these initiatives position us to generate stronger cash flow, improve returns on invested capital, and build a more durable earnings growth profile.

Total Revenue Growth:3% to 5%
Total Revenue:$1,280M to $1,310M
Adjusted EBITDA:$340M to $360M
Capital Expenditures:Approximately $90M

Dividend
The Board of Directors has suspended the Company’s quarterly cash dividend on its common stock. The capital retained will be directed toward accelerating the Company’s deleveraging plan and positioning the Company to drive shareholder value. The Board will continue to evaluate the dividend as part of its regular review of capital allocation priorities.

Investor Webcast Information
Listeners may access an investor webcast hosted by Lucky Strike Entertainment. The webcast and results presentation will be accessible at 9:00 AM ET on November 5, 2026 in the Events & Presentations section of the Lucky Strike Entertainment Investor Relations website at https://ir.luckystrikeent.com/.

About Lucky Strike Entertainment
Lucky Strike Entertainment is one of the world’s premier location-based entertainment platforms. With over 360 locations across North America, Lucky Strike Entertainment provides experiential offerings in bowling, amusements, water parks, and family entertainment centers. The Company also owns the Professional Bowlers Association, the major league of bowling and a growing media property that boasts millions of fans around the globe. For more information on Lucky Strike Entertainment, please visit IR.LuckyStrikeEnt.com.

Forward Looking Statements
Some of the statements contained in this press release are forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, that involve risk, assumptions, and uncertainties, such as statements of our plans, objectives, expectations, intentions, and forecasts. These forward-looking statements reflect our views with respect to future events as of the date of this release and are based on our management’s current expectations, estimates, forecasts, projections, assumptions, beliefs, and information. Although management believes that the expectations reflected in these forward-looking statements are reasonable, it can give no assurance that these expectations will prove to have been correct. All such forward-looking statements are subject to risks and uncertainties, many of which are outside of our control, and could cause future events or results to be materially different from those stated or implied in this document. It is not possible to predict or identify all such risks. These risks include, but are not limited to: our ability to design and execute our business strategy; changes in consumer preferences and buying patterns; our ability to compete in our markets; the occurrence of unfavorable publicity; risks associated with long-term non-cancellable leases for our locations; our ability to retain key managers; risks associated with our substantial indebtedness and limitations on future sources of liquidity; our ability to carry out our expansion plans; our ability to successfully defend litigation brought against us; failure to hire and retain qualified employees and personnel; cybersecurity breaches, cyber-attacks and other interruptions to our and our third-party service providers’ technological and physical infrastructures; catastrophic events, including war, terrorism and other conflicts; public health emergencies and pandemics, such as the COVID-19 pandemic, or natural catastrophes and accidents; fluctuations in our operating results; economic conditions, including the impact of increasing interest rates, inflation and recession; and other factors described under the section titled “Risk Factors” in the Company’s Annual Report on Form 10-K filed with the U.S. Securities and Exchange Commission (the “SEC”) by the Company on August 27, 2026, as well as other filings that the Company will make, or has made, with the SEC, such as Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. These factors should not be construed as exhaustive and should be read in conjunction with the other cautionary statements that are included in this press release and in other filings. We expressly disclaim any obligation to publicly update or review any forward-looking statements, except as required by applicable law.

View full release here.

Lucky Strike Entertainment Corporation Investor Relations
[email protected]

Source: Lucky Strike Entertainment Corporation

Release – The GEO Group Reports Third Quarter 2026 Results and Updates Full Year 2026 Guidance

Research News and Market Data on GEO

November 5, 2026

PDF Version

  • 3Q26 Revenues Increased 12% to $761.1 Million
  • 3Q26 Net Income Attributable to GEO Operations of $49.2 Million
  • 3Q26 Adjusted Net Income Increased 48% to $51.8 Million
  • 3Q26 Adjusted EBITDA Increased 21% to $145.3 Million 
  • Guidance for FY26 Revenues of $2.975-$3.025 Billion
  • Guidance for FY26 Net Income Attributable to GEO Operations Increased to $726.3-$730.5 Million, Including Gain on Sale of Adelanto, Calif. ICE Complex 
  • Guidance for FY26 Adjusted Net Income Increased to $185-$190 Million, or $1.40-$1.44 Per Diluted Share
  • Guidance for FY26 Adjusted EBITDA Increased to $568-$573 Million

BOCA RATON, Fla.–(BUSINESS WIRE)–Nov. 5, 2026– The GEO Group, Inc. (NYSE: GEO) (“GEO”, “we” or the “Company”), a leading provider of contracted support services for secure facilities, processing centers, and reentry centers, as well as enhanced in-custody rehabilitation, post-release support, and electronic monitoring programs, reported its financial results for the third quarter 2026 and updated fourth quarter 2026 and full year 2026 financial guidance.

For the third quarter 2026, we reported total revenues of $761.1 million compared to $682.3 million for the third quarter 2025, reflecting a 12 percent increase. We reported third quarter 2026 net income attributable to GEO Operations of $49.2 million, or $0.37 per diluted share, compared to net income attributable to GEO Operations of $173.9 million, or $1.24 per diluted share, for the third quarter 2025, which included a gain on asset divestitures and other unusual or non-recurring items.

Third quarter 2026 results reflect $3.5 million, pre-tax, in combined non-cash contingent liability and litigation and settlement costs, start-up expenses, transaction fees, employee restructuring expenses, and close-out expenses. Excluding these items, we reported adjusted net income for the third quarter 2026 of $51.8 million, or $0.39 per diluted share, compared to $35.0 million, or $0.25 per diluted share, for the third quarter 2025, reflecting a 48 percent increase.

We reported third quarter 2026 Adjusted EBITDA of $145.3 million, compared to $120.1 million for the third quarter 2025, reflecting a 21 percent increase.

George C. Zoley, GEO’s Chairman, Chief Executive Officer and Founder, said, “Our diversified business units have continued to deliver strong financial and operational performance throughout 2026, and our third quarter 2026 results marked a record-breaking quarter for GEO, with the highest level of quarterly revenues and adjusted EBITDA ever reported in our company’s history. Our better-than-expected performance in 2026 has been driven by the significant revenue growth from the new or expanded contracts that we entered into throughout 2025. So far in 2026, we have had an even more successful year, entering into new or expanded contracts with an overall value of approximately $500 million in incremental annual revenues.”

“We are pleased with the recent $950 million sale of the Adelanto, California U.S. Immigration and Customs Enforcement (“ICE”) Complex, and we remain engaged in an active process for the potential sale of multiple other company-owned facilities to ICE. Given the intrinsic value of our assets, including 48,000 owned beds; our strong financial performance in providing diversified secure support services; and our expected future growth, we believe that our stock continues to be significantly undervalued and that share repurchases are therefore a paramount capital allocation priority for our Company,” Zoley added.

Results for the First Nine Months of 2026

For the first nine months of 2026, we reported total revenues of $2.2 billion compared to $1.9 billion for the first nine months of 2025, reflecting a 14 percent increase. We reported net income attributable to GEO Operations for the first nine months of 2026 of $135.1 million, or $1.02 per diluted share, compared to net income attributable to GEO Operations of $222.6 million, or $1.58 per diluted share, for the first nine months of 2025, which included a gain on asset divestitures and other unusual or non-recurring items.

Results for the first nine months of 2026 reflect $5.6 million, pre-tax, in combined loss on asset divestitures/impairment, non-cash contingent liability and litigation and settlement costs, start-up expenses, transaction fees, employee restructuring expenses, and close-out expenses. Excluding these items, we reported adjusted net income for the first nine months of 2026 of $139.2 million, or $1.05 per diluted share, compared to $85.3 million, or $0.61 per diluted share, for the first nine months of 2025, reflecting a 63 percent increase.

We reported Adjusted EBITDA for the first nine months of 2026 of $418.7 million, compared to $338.5 million for the first nine months of 2025, reflecting a 24 percent increase.

Operational Highlights

We entered into a five-year support services contract, effective July 9, 2026, with ICE for the activation of a federal immigration processing center at the 1,188-bed Big Horn Facility in Hudson, Colorado, while also entering into a lease agreement with the facility owner. The Big Horn Facility support services contract is expected to generate approximately $85 million in annual revenues in the first full year of operations.

We entered into a five-year support services contract, effective August 1, 2026, with ICE for the activation of a federal immigration processing center at our GEO-owned, 1,320-bed Rivers Facility in Winton, North Carolina. The Rivers Facility support services contract is expected to generate approximately $80 million in annual revenues in the first full year of operations.

The City of Big Spring, Texas entered into a 10-year intergovernmental service agreement with ICE, effective November 1, 2026, for the activation of a federal immigration processing center at the 2,329-bed Big Spring Complex in Texas (the “Big Spring Complex”), consisting of the 1,404-bed Flightline Facility and the 925-bed Cedar Hill Facility. GEO will provide support services at the Big Spring Complex, which is expected to generate approximately $200 million in annual revenues for GEO in the first full year of operations.

Under all three contracts, ICE will reimburse GEO for the capital expenditures needed to reactivate these four facilities, as well as provide funding for start-up expenses during the activation period. We expect the activation of the Big Horn Facility and Rivers Facility to be completed by the end of 2026, with both facilities expected to achieve normalized operations and earnings contribution in early 2027, while the activation of the Big Spring Complex is expected to be completed by the end of the first quarter of 2027, with normalized operations and earnings contribution expected in the second quarter of 2027.

We entered into a new 10-year management contract, effective October 28, 2026, with ICE for the continued provision of support services at the GEO-owned 1,635-bed Northwest ICE Processing Center located in Tacoma, Washington. The new 10-year contract is expected to generate approximately $140 million in annual revenues for GEO and continue through October 27, 2036.

Facility Sales

On October 2, 2026, we completed the sales of the 1,280-bed Adelanto West ICE Processing Center, 660-bed Adelanto East ICE Processing Center, and 704-bed Desert View Annex located in Adelanto, California (the “Adelanto Complex”) to the United States of America and its assigns, by and through the Department of Homeland Security, for an aggregate gross sales price of $950 million, with net proceeds of approximately $705 million after federal and state taxes and transaction fees and expenses. We expect to continue providing support services under our existing contract with ICE for the Adelanto Complex, which has a full term effective through December 19, 2034.

In addition to these completed sales, we remain engaged in an active process for the sale of multiple other company-owned facilities to ICE, subject to mutual agreement on price and GEO’s continued management of those facilities under long-term support services contracts. At this time, there is no definitive agreement in place and no precise timeline for the closing of any additional transactions, and we can provide no assurance that any additional transactions will occur.

Financial Guidance

Today, we updated our financial guidance for the fourth quarter and full year 2026. For the fourth quarter 2026, we increased our Net Income Attributable to GEO Operations guidance to a range of $591 million to $595.5 million, which includes the gain on sale of the Adelanto Complex. We increased our fourth quarter 2026 Adjusted Net Income guidance to a range of $46 million to $51 million, or a range of $0.35 to $0.39 per diluted share, on quarterly revenues of $777 million to $827 million. We increased our fourth quarter 2026 Adjusted EBITDA guidance to a range of $149 million to $154 million.

For the full year 2026, we increased Net Income Attributable to GEO Operations guidance to a range of $726.3 million to $730.5 million, which includes the gain on sale of the Adelanto Complex in the fourth quarter of 2026. We increased full year 2026 Adjusted Net Income guidance to a range of $185 million to $190 million, or a range of $1.40 to $1.44 per diluted share, on annual revenues of $2.975 billion to $3.025 billion and based on an effective tax rate of approximately 28 percent, inclusive of known discrete items. We increased our full year 2026 Adjusted EBITDA guidance to a range of $568 million to $573 million. We expect total unreimbursed capital expenditures for the full year 2026 to be between $140 million and $150 million.

Balance Sheet

On October 5, 2026, we entered into an Amended and Restated Credit Agreement to extend the maturity of our $550 million Revolving Credit Facility to July 14, 2031 and to increase our restricted payments capacity, including share repurchases.

On October 15, 2026, we used the proceeds from the sale of the Adelanto Complex to complete the redemption of our $650 million, 8.625% Senior Secured Notes due 2029 (the “2029 Senior Secured Notes”). Following the redemption of the 2029 Senior Secured Notes, our outstanding corporate debt totals $625 million, consisting of our 10.250% Senior Unsecured Notes due 2031 (the “2031 Senior Unsecured Notes”).

Our available liquidity is approximately $600 million, including cash on hand and Revolving Credit Facility availability.

We are permitted to make unlimited restricted payments, including share repurchases, under our Credit Agreement, to the extent the Company’s total leverage ratio (as defined therein) calculated on a pro forma basis after giving effect to such restricted payment would be equal to or less than 2.25 to 1.00 and no default exists thereunder.

Additionally, under the Indenture governing the 2031 Senior Unsecured Notes, we are permitted to make unlimited restricted payments, including share repurchases, to the extent the Company’s consolidated total leverage ratio (as defined therein) calculated on a pro forma basis after giving effect to such restricted payment would be equal to or less than 2.00 to 1.00 and no default exists thereunder.

Share Repurchase Program

On October 5, 2026, we announced that our Board of Directors approved a $750 million increase to our share repurchase program, from $500 million to $1.25 billion, which is effective through December 31, 2029.

As of November 5, 2026, we had repurchased approximately 10.1 million shares of GEO common stock at an aggregate cost of approximately $177 million under our $1.25 billion share repurchase authorization, bringing our current outstanding share count to approximately 132 million and leaving approximately $1.07 billion of repurchase authorization available under the share repurchase program.

Repurchases of GEO’s outstanding common stock will be made in accordance with applicable securities laws and may be made at our senior management’s discretion from time to time in the open market, by block purchase, through privately negotiated transactions, pursuant to a trading plan, or otherwise in compliance with Rule 10b-18 under the Securities Exchange Act of 1934, as amended. The authorization for the share repurchase program may be extended, increased, decreased, suspended or terminated by our Board of Directors in its discretion at any time.

Repurchases of our common stock (and the timing thereof) will depend upon market conditions, regulatory requirements, the Company’s existing obligations, including our Credit Agreement, other corporate liquidity requirements and priorities and other factors as may be considered in the Company’s sole discretion. The authorization for the share repurchase program does not obligate GEO to purchase any particular amount of the Company’s common stock.

Conference Call Information

We have scheduled a conference call and webcast for today at 1:00 PM (Eastern Time) to discuss our third quarter 2026 financial results as well as our outlook. The call-in number for the U.S. is 1-877-250-1553 and the international call-in number is 1-412-542-4145. In addition, a live audio webcast of the conference call may be accessed on the Webcasts section under the News, Events and Reports tab of GEO’s investor relations webpage at investors.geogroup.com. A replay of the webcast will be available on the website for one year. A telephonic replay of the conference call will be available through November 12, 2026, at 1-855-669-9658 (U.S.) and 1-412-317-0088 (International). The participant passcode for the telephonic replay is 2402738.

About The GEO Group

The GEO Group, Inc. (NYSE: GEO) is a leading diversified government service provider, specializing in design, financing, development, and support services for secure facilities, processing centers, and community reentry centers in the United States, Australia, South Africa, and the United Kingdom. GEO’s diversified services include enhanced in-custody rehabilitation and post-release support through the award-winning GEO Continuum of Care®, secure transportation, electronic monitoring, community-based programs, and correctional health and mental health care. GEO’s worldwide operations include the ownership and/or delivery of support services for 97 facilities totaling approximately 76,000 beds, including idle facilities and projects under development, with a workforce of up to approximately 20,000 employees.

Reconciliation Tables and Supplemental Information

GEO has made available Supplemental Information which contains reconciliation tables of Net Income Attributable to GEO Operations to Adjusted Net Income, and Net Income to EBITDA and Adjusted EBITDA, along with supplemental financial and operational information on GEO’s business and other important operating metrics. The reconciliation tables are also presented herein. Please see the section below titled “Note to Reconciliation Tables and Supplemental Disclosure – Important Information on GEO’s Non-GAAP Financial Measures” for information on how GEO defines these supplemental Non-GAAP financial measures and reconciles them to the most directly comparable GAAP measures. GEO’s Reconciliation Tables can be found herein and in GEO’s Supplemental Information available on GEO’s investor webpage at investors.geogroup.com.

Note to Reconciliation Tables and Supplemental Disclosure –
Important Information on GEO’s Non-GAAP Financial Measures

Adjusted Net Income, EBITDA, and Adjusted EBITDA are non-GAAP financial measures that are presented as supplemental disclosures. GEO has presented herein certain forward-looking statements about GEO’s future financial performance that include non-GAAP financial measures, including Net Debt, Net Leverage, and Adjusted EBITDA. The determination of the amounts that are included or excluded from these non-GAAP financial measures is a matter of management judgment and depends upon, among other factors, the nature of the underlying expense or income amounts recognized in a given period.

While we have provided a high-level reconciliation for the guidance ranges for full year 2026, we are unable to present a more detailed quantitative reconciliation of the forward-looking non-GAAP financial measures to their most directly comparable forward-looking GAAP financial measures because management cannot reliably predict all of the necessary components of such GAAP measures. The quantitative reconciliation of the forward-looking non-GAAP financial measures will be provided for completed annual and quarterly periods, as applicable, calculated in a consistent manner with the quantitative reconciliation of non-GAAP financial measures previously reported for completed annual and quarterly periods.

Net Debt is defined as gross principal debt less cash on hand. Net Leverage is defined as Net Debt divided by Adjusted EBITDA.

EBITDA is defined as net income adjusted by adding provisions for income tax, interest expense, net of interest income, and depreciation and amortization. Adjusted EBITDA is defined as EBITDA adjusted for (gain)/loss on asset divestitures/impairment, pre-tax, net loss attributable to noncontrolling interests, stock-based compensation expenses, pre-tax, non-cash contingent liability and litigation settlement costs, pre-tax, start-up expenses, pre-tax, transaction fees, pre-tax, employee restructuring expenses, pre-tax, close-out expenses, pre-tax, other non-cash revenue and expenses, pre-tax, and certain other adjustments as defined from time to time.

Given the nature of our business as a real estate owner and support services provider, we believe that EBITDA and Adjusted EBITDA are helpful to investors as measures of our operational performance because they provide an indication of our ability to incur and service debt, to satisfy general operating expenses, to make capital expenditures, and to fund other cash needs or reinvest cash into our business.

We believe that by removing the impact of our asset base (primarily depreciation and amortization) and excluding certain non-cash charges, amounts spent on interest and taxes, and certain other charges that are highly variable from year to year, EBITDA and Adjusted EBITDA provide our investors with performance measures that reflect the impact to operations from trends in occupancy rates, per diem rates and operating costs, providing a perspective not immediately apparent from net income.

The adjustments we make to derive the non-GAAP measures of EBITDA and Adjusted EBITDA exclude items which may cause short-term fluctuations in income from continuing operations and which we do not consider to be the fundamental attributes or primary drivers of our business plan and they do not affect our overall long-term operating performance. EBITDA and Adjusted EBITDA provide disclosure on the same basis as that used by our management and provide consistency in our financial reporting, facilitate internal and external comparisons of our historical operating performance and our business units and provide continuity to investors for comparability purposes.

Adjusted Net Income is defined as net income attributable to GEO operations adjusted for certain items which by their nature are not comparable from period to period or that tend to obscure GEO’s actual operating performance, including for the periods presented (gain)/loss on asset divestitures/impairment, pre-tax, loss on extinguishment of debt, pre-tax, non-cash contingent liability and litigation and settlement costs, pre-tax, start-up expenses, pre-tax, transaction fees, pre-tax, employee restructuring expenses, pre-tax, close-out expenses, pre-tax, and the tax effect of adjustments to net income attributable to GEO operations.

Safe-Harbor Statement

This press release contains forward-looking statements regarding future events and future performance of GEO that involve risks and uncertainties that could materially and adversely affect actual results, including statements regarding GEO’s financial guidance for the fourth quarter and full year of 2026, GEO’s belief that its stock continues to be undervalued, the $1.25 billion share repurchase program authorized by GEO’s Board of Directors and GEO’s capital allocation priorities, the anticipated timing and annualized revenues related to the activation of certain facilities and new and amended contracts, GEO’s continued engagement in an active process for the sale of multiple company-owned facilities, GEO’s ability to capture additional growth opportunities, and the Company’s efforts to strengthen its capital structure and enhance shareholder value through capital returns. Forward-looking statements generally can be identified by the use of forward-looking terminology such as “may,” “will,” “expect,” “anticipate,” “intend,” “plan,” “believe,” “seek,” “estimate,” or “continue” or the negative of such words and similar expressions. Risks and uncertainties that could cause actual results to vary from current expectations and forward-looking statements contained in this press release include, but are not limited to: (1) GEO’s ability to meet its financial guidance for the fourth quarter and full year of 2026 given the various risks to which its business is exposed; (2) GEO’s ability to execute on the $1.25 billion share repurchase program authorized by GEO’s Board of Directors on the timeline it expects; (3) GEO’s ability to deleverage and repay, refinance or otherwise address its debt maturities in an amount and on terms commercially acceptable to GEO, and on the timeline it expects or at all; (4) GEO’s ability to identify and successfully complete any potential sales of company-owned assets and businesses or potential acquisitions of assets or businesses on commercially advantageous terms on a timely basis, or at all; (5) changes in federal and state government policy, orders, directives, legislation and regulations that affect public-private partnerships with respect to secure, correctional and detention facilities, processing centers and reentry centers; (6) changes in federal immigration policy; (7) public and political opposition to the use of public-private partnerships with respect to secure correctional and detention facilities, processing centers and reentry centers; (8) the impact of any future global pandemic on GEO and GEO’s ability to mitigate the risks associated with such pandemic; (9) GEO’s ability to sustain or improve company-wide occupancy rates at its facilities; (10) fluctuations in GEO’s operating results, including as a result of contract activations, contract terminations, contract renegotiations, changes in occupancy levels and increases in GEO’s operating costs; (11) general economic and market conditions, including changes to governmental budgets and their impact on new contract terms, contract renewals, renegotiations, per diem rates, fixed payment provisions, and occupancy levels; (12) GEO’s ability to address inflationary pressures related to labor-related expenses and other operating costs; (13) GEO’s ability to timely open facilities as planned, profitably manage such facilities and successfully integrate such facilities into GEO’s operations without substantial costs; (14) GEO’s ability to win management contracts for which it has submitted proposals and to retain existing management contracts; (15) risks associated with GEO’s ability to control operating costs associated with contract start-ups; (16) GEO’s ability to successfully pursue growth opportunities and continue to create shareholder value; (17) GEO’s ability to obtain financing or access the capital markets in the future on acceptable terms or at all; (18) any adverse impact on GEO’s financial results caused by any past or future federal government shutdown; (19) risks associated with the U.S. Supreme Court agreeing to hear GEO’s appeal in the Nwauzor case and GEO’s ability to prevail on the merits; and (20) other factors contained in GEO’s Securities and Exchange Commission periodic filings, including its Form 10-K, 10-Q and 8-K reports, many of which are difficult to predict and outside of GEO’s control.

View full release here.

View source version on businesswire.com: https://www.businesswire.com/news/home/20261104896862/en/

Pablo E. Paez (866) 301 4436
Executive Vice President, Corporate Relations

Source: The GEO Group, Inc.
Release – 1-800-FLOWERS.COM, Inc. Reports Fiscal 2027 First Quarter Results

1-800-FLOWERS.COM, Inc. – link to home page

Research News and Market Data on FLWS

Nov 05, 2026

Reports Revenue of $171.4 million, a Net Loss from Continuing Operations of $50.6 million, and an Adjusted EBITDA1 Loss from Continuing Operations of $31.9 million

Updates Fiscal 2027 Outlook to Reflect the Impact of the Previously Announced Sale of PersonalizationMall.com and Things Remembered

JERICHO, N.Y.–(BUSINESS WIRE)– 1-800-FLOWERS.COM, Inc. (NASDAQ: FLWS), a leading gifting company focused on inspiring customers to give more, connect more, and build more meaningful relationships, today reported results for its Fiscal 2027 first quarter ended September 27, 2026.

“We entered fiscal 2027 with a clear priority on strengthening our primary websites, 1-800-Flowers.com and Harry & David, which represent the greatest opportunity to improve our overall performance,” said Adolfo Villagomez, Chief Executive Officer. “During the fiscal first quarter, we began to see signs of progress across our primary websites, with improving net order demand trends and a moderation in the pace of year-over-year declines. While we are still in the early stages of our transformation, these developments are encouraging and suggest that our initiatives are beginning to take hold.”

“We are also making progress in simplifying our business and strengthening our financial position,” said James Langrock, Chief Financial Officer. “Following our announcement last quarter that we were evaluating capital-raising options, we completed the sale of PersonalizationMall.com and Things Remembered during the fiscal second quarter and entered into an agreement to sell our Jacksonville, FL facility. These actions reflect our continued focus on optimizing our capital structure, reducing debt and providing capital to invest in initiatives that improve performance. Additionally, we updated our segment reporting structure to better reflect how we now operate and manage the business, while providing investors with greater visibility into our performance.”

Beginning with the first quarter of fiscal 2027, the Company has revised its reportable segment structure to better reflect how the business is organized, managed and evaluated today. Under the new structure, the Company will report results across E-Commerce, Wholesale and Other, and BloomNet, replacing its previous Consumer Floral & Gifts, Gourmet Foods & Gift Baskets and BloomNet segments.

The E-Commerce segment includes sales made directly to customers through the Company’s owned websites, third-party marketplaces, and its business-to-business (B2B) operations. The Wholesale and Other segment primarily includes sales of products to retailers and other distribution partners. The BloomNet segment primarily includes sales of products and services to florists in its member network.

This change reflects the evolution of the Company’s operating model over the past year, including a greater focus on managing the business across channels and functions rather than primarily by individual brands and product categories. The new structure is intended to provide greater alignment between the Company’s financial reporting and how management evaluates performance, allocates resources and identifies opportunities for profitable growth.

Additionally, beginning this quarter, the Company will provide a breakdown of net order demand trends between its primary websites, which include 1-800-Flowers.com and Harry & David, and the Company’s other websites. These trends reflect orders placed directly through the Company’s owned websites and mobile apps by both individual and business customers. Orders placed through third-party marketplaces or through the Company’s B2B sales representatives are excluded. This additional disclosure is intended to provide investors with greater visibility into the performance of the Company’s primary websites and the progress of its initiatives to strengthen these businesses.

Fiscal 2027 First Quarter Performance

  • Total consolidated revenues decreased 11.1% to $171.4 million, compared with the prior year period. E-Commerce segment revenues declined 12.3% to $128.4 million, compared with the prior-year period, reflecting continued weakness across the Company’s other websites and business-to-business (B2B) operations, partially offset by improving demand trends across its primary websites, where the Company has concentrated its resources and investments. Wholesale and Other segment revenues decreased 10.7% to $20.5 million, while BloomNet segment revenues decreased 3.6% to $22.3 million, both compared with the prior year period.
  • Gross profit margin decreased 120 basis points to 34.1%, compared with 35.3% in the prior year period, reflecting lower sales volume, higher fuel surcharges, and promotional strategy testing, partially offset by savings from the Company’s cost efficiency initiatives.
  • Operating expenses decreased $10.3 million year-over-year to $105.0 million. Excluding non-recurring charges and the impact of the Company’s non-qualified deferred compensation plan in both periods, operating expenses decreased $10.6 million as compared with the prior year to $102.3 million, primarily due to lower marketing and labor costs.
  • Net loss from continuing operations for the quarter was $(50.6) million, or $(0.79) per diluted share, as compared to a net loss from continuing operations of $(49.0) million, or $(0.77) per share, in the prior year period.
  • Adjusted net loss1 from continuing operations was $(49.8) million, or $(0.78) per diluted share, compared with an Adjusted net loss1 from continuing operations of $(49.0) million, or $(0.77) per share, in the prior year period.
  • Adjusted EBITDA1 loss from continuing operations for the quarter was $(31.9) million, compared with an Adjusted EBITDA1 loss from continuing operations of $(31.7) million in the prior year period.
(1)Refer to “Definitions of Non-GAAP Financial Measures” and the tables attached at the end of this press release for reconciliation of non-GAAP results to applicable GAAP results.

Jacksonville, FL Facility Sale

As part of its ongoing efforts to optimize its capital structure and enhance financial flexibility, the Company has entered into an agreement to sell its Jacksonville, FL facility for approximately $10 million, subject to due diligence and customary closing conditions. Proceeds from the transaction are expected to support debt reduction and strategic investments in the business.

Fiscal Year 2027 Outlook

Following the recently announced divestiture of PersonalizationMall.com and Things Remembered, the Company is updating its fiscal 2027 outlook to reflect the expected impact of the transaction.

The updated outlook reflects the expected impact of the divestiture, including the removal of the divested businesses from the Company’s results following the closing of the transaction, as well as the planned reinvestment of a portion of the proceeds in revenue-generating initiatives across its primary websites.

For fiscal 2027, the Company now expects total revenues to decline between 2% to 5% and Adjusted EBITDA of approximately $10 million to $15 million.

Conference Call

The Company will conduct a conference call to discuss its financial results today, November 5, 2026, at 8:00 a.m. (ET). The conference call will be webcast from the Investors section of the Company’s website at www.1800flowersinc.com. A recording of the call will be posted on the Investors section of the Company’s website within two hours of the call’s completion.

Definitions of non-GAAP Financial Measures:

We sometimes use financial measures that are not presented in our financial statements prepared in accordance with U.S. generally accepted accounting principles (“GAAP”). These measures are considered non-GAAP financial measures under the rules of the U.S. Securities and Exchange Commission. Non-GAAP financial measures referred to in this document are either labeled as “non-GAAP,” “adjusted” or designated as such with a “1”. See below for definitions and the reasons why we use these non-GAAP financial measures. See the Selected Financial Information below for reconciliations of these non-GAAP measures to their most directly comparable GAAP financial measures. Reconciliations for forward-looking figures would require unreasonable efforts at this time because of the uncertainty and variability of the nature and amount of certain components of various necessary GAAP components, including, for example, those related to compensation, tax items, amortization or others that may arise during the year, and the Company’s management believes such reconciliations would imply a degree of precision that would be confusing or misleading to investors. For the same reasons, the Company is unable to address the probable significance of the unavailable information. The lack of such reconciling information should be considered when assessing the impact of such disclosures.

We define our non-GAAP financial measures as follows:

EBITDA and Adjusted EBITDA: We define EBITDA as net income (loss) from continuing operations before interest, taxes, depreciation, and amortization. Adjusted EBITDA is defined as EBITDA adjusted for the impact of stock-based compensation, Non-Qualified Deferred Compensation Plan (“NQDC”) investment appreciation/depreciation, and for certain items affecting period-to-period comparability. See Selected Financial Information for details on how EBITDA and Adjusted EBITDA were calculated for each period presented. The Company presents EBITDA and Adjusted EBITDA because it considers such information meaningful supplemental measures of its performance and believes such information is frequently used by the investment community in the evaluation of similarly situated companies. The Company uses EBITDA and Adjusted EBITDA as factors to determine the total amount of incentive compensation available to be awarded to executive officers and other employees. The Company’s credit agreement uses EBITDA and Adjusted EBITDA-related items to determine its interest rate and to measure compliance with certain covenants. EBITDA and Adjusted EBITDA are also used by the Company to evaluate and price potential acquisition candidates. EBITDA and Adjusted EBITDA have limitations as analytical tools and should not be considered in isolation or as a substitute for analysis of the Company’s results as reported under GAAP. Some of the limitations are: (a) EBITDA and Adjusted EBITDA do not reflect changes in, or cash requirements for, the Company’s working capital needs; (b) EBITDA and Adjusted EBITDA do not reflect the interest expense, or the cash requirements necessary to service interest or principal payments, on the Company’s debts; and (c) although depreciation and amortization are non-cash charges, the assets being depreciated and amortized may have to be replaced in the future and EBITDA does not reflect any cash requirements for such capital expenditures. EBITDA and Adjusted EBITDA should only be used on a supplemental basis combined with GAAP results when evaluating the Company’s performance.

Adjusted Net Income (Loss) and Adjusted or Comparable Net Income (Loss) Per Common Share: We define Adjusted Net Income (Loss) and Adjusted or Comparable Net Income (Loss) Per Common Share as Net Income (Loss) from continuing operations and Net Income (Loss) Per Common Share from continuing operations adjusted for certain items affecting period-to-period comparability. See Selected Financial Information below for details on how Adjusted Net Income (Loss) Per Common Share and Adjusted or Comparable Net Income (Loss) Per Common Share were calculated for each period presented. We believe that Adjusted Net Income (Loss) and Adjusted or Comparable Net Income (Loss) Per Common Share are meaningful measures because they increase the comparability of period-to-period results. Since these are not measures of performance calculated in accordance with GAAP, they should not be considered in isolation of, or as a substitute for, GAAP Net Income (Loss) and Net Income (Loss) Per Common Share, as indicators of operating performance and they may not be comparable to similarly titled measures employed by other companies.

Free Cash Flow: We define Free Cash Flow as net cash provided by (used in) operating activities from continuing operations less capital expenditures. The Company considers Free Cash Flow to be a liquidity measure that provides useful information to management and investors about the amount of cash generated by the business after the purchases of fixed assets, which can then be used to, among other things, invest in the Company’s business, make strategic acquisitions, strengthen the balance sheet, and repurchase stock or retire debt. Free Cash Flow is a liquidity measure that is frequently used by the investment community in the evaluation of similarly situated companies. Since Free Cash Flow is not a measure of performance calculated in accordance with GAAP, it should not be considered in isolation or as a substitute for analysis of the Company’s results as reported under GAAP. A limitation of the utility of Free Cash Flow as a measure of financial performance is that it does not represent the total increase or decrease in the Company’s cash balance for the period.

Segment Profitability Measure:

Segment Contribution Margin: We define Segment Contribution Margin as segment revenues less cost of sales, credit card fees, and direct advertising costs directly attributable to the respective segments. Segment Contribution Margin is the measure of segment profit or loss regularly reviewed by the Company’s Chief Operating Decision Maker to evaluate segment performance and allocate resources and is reported in accordance with ASC 280, Segment Reporting. The Company believes Segment Contribution Margin provides useful information to investors in evaluating the performance of its reportable segments. Segment Contribution Margin excludes certain expenses that are managed centrally and are not allocated to the Company’s reportable segments. Accordingly, Segment Contribution Margin should be considered in conjunction with the Company’s consolidated results reported in accordance with GAAP.

Key Operating Metrics:

The Company uses certain operating metrics to evaluate its business performance and assess underlying trends. These metrics are supplemental to the Company’s financial results reported in accordance with GAAP.

Net Order Demand: We define Net Order Demand as the value of customer orders placed through the Company’s owned websites and apps by both individual and business customers during the period, regardless of when the related orders are fulfilled and revenue is recognized. It excludes third-party marketplace orders and B2B orders placed through our sales representatives. The Company’s primary websites include 1-800-Flowers.com and Harry & David, while the Company’s other websites include the remaining websites in the Company’s portfolio. The Company considers Net Order Demand to be an operating metric that provides useful information to management and investors in evaluating underlying customer demand, business performance and trends in customer purchasing activity. Net Order Demand differs from Net Sales reported in accordance with GAAP, primarily due to differences in the timing of order placement, fulfillment and revenue recognition. Accordingly, Net Order Demand should not be considered in isolation or as a substitute for the Company’s reported Net Sales.

About 1-800-FLOWERS.COM, Inc.

1-800-FLOWERS.COM, Inc. (NASDAQ: FLWS) is a leading gifting company focused on inspiring customers to give more, connect more, and build more meaningful relationships. The Company offers a broad selection of flowers, gifts, and gourmet foods to help customers celebrate life’s special moments.

The Company’s family of brands is led by 1-800-Flowers.com® and Harry & David®, and includes other well-recognized gifting brands such as Cheryl’s Cookies®, Shari’s Berries®, and Moose Munch®. Through its e-commerce platform and Celebrations Passport® loyalty program, the Company strives to make gifting easier and more convenient for customers. The Company also operates BloomNet®, a provider of products and services to the floral industry, as well as wholesale businesses Napco℠ and DesignPac®.

For more information, visit 1800flowersinc.com.

FLWS-COMP
FLWS-FN

Special Note Regarding Forward Looking Statements:

This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements represent the Company’s current expectations or forecasts concerning future events; they do not relate strictly to historical or current facts. Such statements can generally be identified by words such as “anticipate,” “estimate,” “expect,” “project,” “intend,” “plan,” “believe,” “foresee,” “forecast,” “likely,” “should,” “will,” “target,” or similar words or phrases. These forward-looking statements are subject to risks, uncertainties, and other factors, many of which are outside of the Company’s control, which could cause actual results to differ materially from the results expressed or implied in the forward-looking statements, including, but not limited to, statements relating to future actions; the Company’s ability to leverage its operating platform and reduce its operating expense ratio; its ability to successfully integrate acquired businesses and assets; its ability to successfully execute its strategic priorities; its ability to cost effectively acquire and retain customers and drive purchase frequency; the outcome of contingencies, including legal proceedings in the normal course of business; its ability to compete against existing and new competitors; its ability to manage expenses associated with sales and marketing and necessary general and administrative and technology investments; its ability to reduce promotional activities and achieve more efficient marketing programs; and general consumer sentiment and industry and economic conditions that may affect levels of discretionary customer purchases of the Company’s products. The Company cannot guarantee that any forward-looking statement will be realized. Achievement of future results is subject to risk, uncertainties and potentially inaccurate assumptions. Should known or unknown risks or uncertainties materialize, or should underlying assumptions prove inaccurate, actual results could differ materially from past results and those anticipated, estimated or projected. You should bear this in mind as you consider forward-looking statements. The Company undertakes no obligation to publicly update any of the forward-looking statements, whether because of new information, future events or otherwise, made in this release or in any of its SEC filings. Consequently, you should not consider any such list to be a complete set of all potential risks and uncertainties. For a more detailed description of these and other risk factors, refer to the Company’s SEC filings, including the Company’s Annual Reports on Form 10-K and its Quarterly Reports on Form 10-Q.

View full release here.

View source version on businesswire.com: https://www.businesswire.com/news/home/20261105805964/en/

Investor Contact:

Andy Milevoj

[email protected]

Media Contact:

[email protected]

Source: 1-800-FLOWERS.COM, Inc.

Release – Graham Corporation Reports Second Quarter Fiscal 2027 Results

Graham Corporation

Research News and Market Data on GHM

November 05, 2026 6:30am ESTDownload as PDF

Second Quarter Fiscal 2027 Highlights:

  • Net sales of $69.8 million, increased 6% compared to the prior year reflecting strength of diversified revenue base and the addition of FlackTek
  • Gross profit increased 38% to $19.7 million; Gross profit margin was 28.2%, up 650 basis points compared to the prior year reflecting improved mix and operational efficiencies
  • Net income per diluted share was $0.39 an increase of 39%; Adjusted net income per diluted share(1) was $0.52 an increase of 68%
  • Adjusted EBITDA (1) increased 64% to $10.3 million; Adjusted EBITDA margin(1) was 14.8%, up 530 basis points compared to the prior year
  • Orders (2) were $73.7 million; Book-to-Bill (2) ratio of 1.1x and record backlog (2) of $561.3 million marking the seventh consecutive quarter of record quarterly backlog(2)
  • Strong cash generation with $46.7 million of cash provided by operating activities during the second quarter; cash of $71.4 million and no outstanding debt at quarter end
  • Reaffirming full year fiscal 2027 guidance for net sales and adjusted EBITDA

BATAVIA, N.Y.–(BUSINESS WIRE)– Graham Corporation (NYSE: GHM) (“GHM” or the “Company”), a global leader in the design and manufacture of mission critical fluid, power, heat transfer, vacuum, and advanced mixing technologies for the Defense, Space, and Energy & Process industries, today reported financial results for its second quarter for the fiscal year ending March 31, 2027 (“fiscal 2027”).

Graham’s President and Chief Executive Officer, Matthew J. Malone stated, “Our second quarter results reflect strong execution across the business, highlighted by growth in Defense and Space, significant margin expansion and continued momentum across our end markets. Our record backlog of $561 million provides strong visibility into future growth and reinforces our confidence in the long-term opportunities ahead.”

Mr. Malone continued, “We are very pleased with the progress of FlackTek’s integration and the continued execution of our strategic initiatives, including the successful completion of our first customer test at our new cryogenic testing facility and the groundbreaking of our new facility in Arvada. We believe these investments position us to capitalize on expanding opportunities in Space and Defense, as well as emerging high-growth markets such as advanced defense systems and small modular reactors, while advancing toward our long-term financial targets.”

1 Adjusted net income per diluted share, Adjusted EBITDA and Adjusted EBITDA margin are non-GAAP measures. See attached tables and other information for important disclosures regarding Graham’s use of these non-GAAP measures.
2 Orders, backlog and book-to-bill ratio are key performance metrics. See “Key Performance Indicators” below for important disclosures regarding Graham’s use of these metrics.

Second Quarter Fiscal 2027 Performance Review
(All comparisons are with the same prior-year period unless noted otherwise.)

*Graham believes that, when used in conjunction with measures prepared in accordance with U.S. generally accepted accounting principles (“GAAP”), adjusted net income, adjusted net income per diluted share, adjusted EBITDA and adjusted EBITDA margin, which are non-GAAP measures, help in the understanding of its operating performance. See attached tables and other information provided at the end of this press release for important disclosures regarding Graham’s use of these non-GAAP measures.

Net sales for the second quarter of fiscal 2027 were $69.8 million, up $3.7 million, or 6%, compared with the second quarter of fiscal 2026, a result of our diversified revenue base and the acquisition of FlackTek, which contributed $9.5 million of revenue in the quarter. The increase was across multiple markets, including a $5.1 million, or 12%, increase in sales to the Defense market, driven by the timing of project milestones, new programs, growth of existing programs and capacity, and the addition of FlackTek, partially offset by approximately $10.0 million of lower material receipts in the second quarter of fiscal 2027. Defense represented 66% of net sales for the quarter. Sales to the Space market increased $2.4 million, or 59%, over the prior year second quarter, primarily due to the impacts of commercialization and accelerated launch cadences, the ramp up of existing programs, and the FlackTek acquisition. Sales to the Energy & Process markets decreased $3.7 million, or 17%, primarily due to softness in investments on large capital project activity caused by geopolitical uncertainties and decreases in sales to customers outside the U.S., partially offset by growth in New Energy markets and the addition of FlackTek. Aftermarket sales to the Energy & Process and Defense markets of $8.6 million decreased 3% from the prior year quarter but remained at high levels.

Gross profit for the second quarter of fiscal 2027 was $19.7 million or 28.2% of sales, compared with $14.3 million, or 21.7% of sales, in the prior-year period. The 650-basis point increase in gross profit margin reflects operational improvements on new and existing programs, the addition of FlackTek, and the mix of sales, in particular the composition of the current mix of programs in the Space and Defense markets, as well as a high level of material receipts in the second quarter of fiscal 2026, which carry a lower profit margin.

Selling, general and administrative expense (“SG&A”), including intangible amortization, for the second quarter of fiscal 2027 increased $3.4 million, or 34%, over the prior year second quarter. Acquisition and integration expenses contributed $0.7 million of the increase, and incremental SG&A from the acquisition of FlackTek accounted for $2.3 million. The balance of the increase mainly reflects ongoing investment in people, processes and technology, expected to total approximately $2.5 million of incremental cost in fiscal 2027, partially offset by a reduction to the Barber-Nichols Performance Bonus, which ended in fiscal 2026. During the second quarter of fiscal 2026, the Company recorded $1.1 million related to the Barber-Nichols Performance Bonus, inclusive of applicable payroll taxes and no corresponding expense was recorded in the second quarter of fiscal 2027.

Cash Management and Balance Sheet

Cash and cash equivalents as of September 30, 2026, were $71.4 million, compared with $27.0 million at the end of the previous quarter and $6.6 million at March 31, 2026.

Net cash provided by operating activities was $46.7 million during the second quarter of fiscal 2027 and $34.1 million for the first six months of the fiscal year, primarily reflecting the timing of accounts receivable collections and customer deposits, as well as higher cash net income.

Capital expenditures, net for the second quarter of fiscal 2027 were $2.2 million, and $4.9 million for the first six months, supporting the Company’s growth and productivity improvement initiatives.

As of September 30, 2026, the Company had no debt outstanding and $74.7 million available under its revolving credit facility.

Orders, Backlog, and Book-to-Bill Ratio

See supplemental data filed with the Securities and Exchange Commission on Form 8-K and provided on the Company’s website for a further breakdown of orders and backlog by market. See “Key Performance Indicators” below for important disclosures regarding Graham’s use of these metrics ($ in millions).

Orders for the second quarter of fiscal 2027 were $73.7 million, compared with $83.2 million in the prior year second quarter. Defense orders in the quarter were $41.8 million. Space market orders totaled $10.6 million, or 1.7x net Space sales for the quarter and $25.0 million, or 2.0x net Space sales, for the first six months of fiscal 2027. Total Aftermarket orders for the Energy & Process and Defense markets increased 91% to $18.3 million for the second quarter of fiscal 2027.

Note that our orders can be lumpy given the nature of our business, particularly large capital projects and multi-year Defense orders, which can be significantly larger.

Backlog at quarter end was a record $561.3 million, a 12% increase over the prior-year period, with Defense backlog up 10% and Space backlog up 108%. For the quarter, the Company achieved a book-to-bill ratio of 1.1x, and 1.2x for the first six months of fiscal 2027, ahead of the Company’s annual target of 1.1x. Management expects approximately 30% to 35% of backlog to convert to sales within the next twelve months, 20% to 25% within one to two years, and the remainder beyond two years. Approximately 83% of our backlog as of September 30, 2026, was to the Defense market, which provides stability and visibility for future revenue growth.

Fiscal 2027 Outlook

(1)Includes approximately $4.5 million to $5.5 million of equity-based compensation, net acquisition & integration costs, and enterprise resource planning (“ERP”) conversion costs included in SG&A expense.
(2)Includes approximately $2.5 million of incremental costs to invest in people, processes, and technology to enable future growth and accelerate the commercialization of Graham products and technologies.
(3)Excludes net interest (income) expense, income taxes, depreciation, and amortization from net income, as well as approximately $6.0 million to $7.0 million of equity-based compensation, net acquisition & integration costs, and ERP conversion costs.
(4)See “Forward-Looking Non-GAAP Measures” below for additional information.

Graham’s Chief Financial Officer, Christopher J. Thome, said, “Our second quarter results demonstrate continued improvement in profitability, with adjusted EBITDA increasing 64% year-over-year and adjusted EBITDA margin expanding 530 basis points. We generated $46.7 million in operating cash flow during the second quarter and ended the quarter with $71.4 million in cash and no outstanding debt, providing significant financial flexibility to support our organic and inorganic growth initiatives.”

Mr. Thome continued, “Based on our first-half performance and expectations for the remainder of the year, we are reaffirming our full-year fiscal 2027 guidance of net sales and adjusted EBITDA, have made minor updates to full-year fiscal 2027 guidance on gross margin based on mix and better execution, SG&A expense based on higher acquisition and integration related expenses, and updates to capital expenditures based on timing of major projects. We remain focused on maintaining financial discipline and driving continued operational improvements as we execute against our long-term objectives.”

Webcast and Conference Call

GHM’s management will host a conference call and live webcast on November 5, 2026, at 11:00 a.m. Eastern Time (“ET”) to review its financial results as well as its strategy and outlook. The review will be accompanied by a slide presentation, which will be made available immediately prior to the conference call on GHM’s investor relations website.

A question-and-answer session will follow the formal presentation. GHM’s conference call can be accessed by calling (877) 407-0784, or (201) 689-8560 (International). Alternatively, the webcast can be monitored from the events section of GHM’s investor relations website.

A telephonic replay will be available from 3:00 p.m. ET today through Thursday, November 12, 2026. To listen to the archived call, dial (844) 512-2921 and enter conference ID number 13762712, or access the webcast replay via the Company’s website at ir.grahamcorp.com, where a transcript will also be posted once available.

About Graham Corporation

Graham is a global leader in the design and manufacture of mission critical fluid, power, heat transfer, vacuum, and advanced mixing technologies for the Defense, Space, Energy & Process industries. Graham Corporation and its family of global brands are built upon world-renowned engineering expertise, proprietary technologies, as well as its responsive and flexible service and the unsurpassed quality customers have come to expect from the Company’s products and systems. Graham Corporation routinely posts news and other important information on its website, grahamcorp.com, where additional information on Graham Corporation and its businesses can be found.

Safe Harbor Regarding Forward Looking Statements

This news release contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended.

Forward-looking statements are subject to risks, uncertainties and assumptions and are identified by words such as “continue,” “estimate,” “expects,” “focus,” “future,” “opportunities,” “outlook,” “believes,” “could,” “guidance,” “may”, “will,” “plan,” “strategy,” and other similar words. All statements addressing operating performance, events, or developments that Graham Corporation expects or anticipates will occur in the future, including but not limited to, profitability of future projects and the business, its ability to deliver to plan, its ability to continue to strengthen relationships with customers in the Defense industry, its ability to secure future projects and applications, expected expansion and growth opportunities, anticipated sales, revenues, adjusted EBITDA, adjusted EBITDA margins, capital expenditures and SG&A expenses, the timing of conversion of backlog to sales, orders, market presence, profit margins, tax rates, foreign sales operations, customer preferences, changes in market conditions in the industries in which it operates, changes in general economic conditions and customer behavior, forecasts regarding the timing and scope of the economic recovery in its markets, and its acquisition and growth strategy, are forward-looking statements. Because they are forward-looking, they should be evaluated in light of important risk factors and uncertainties. These risk factors and uncertainties are more fully described in Graham Corporation’s most recent Annual Report filed with the Securities and Exchange Commission (the “SEC”), included under the heading entitled “Risk Factors”, and in other reports filed with the SEC.

Should one or more of these risks or uncertainties materialize or should any of Graham Corporation’s underlying assumptions prove incorrect, actual results may vary materially from those currently anticipated. In addition, undue reliance should not be placed on Graham Corporation’s forward-looking statements. Except as required by law, Graham Corporation disclaims any obligation to update or publicly announce any revisions to any of the forward-looking statements contained in this news release.

View full release here.

View source version on businesswire.com: https://www.businesswire.com/news/home/20261105758252/en/

For more information, contact:

Christopher J. Thome
Vice President – Finance and CFO
Phone: (585) 343-2216

Tom Cook
Investor Relations
(203) 682-8250
[email protected]

Source: Graham Corporation

Released November 5, 2026