Release – Kratos Target Systems Utilized During Successful MDA-Joint Flight Test Experiment-01 Mission

Primary Logo

Research News and Market Data on KTOS

August 10, 2026

PDF Version

SAN DIEGO, Aug. 10, 2026 (GLOBE NEWSWIRE) — Kratos Defense & Security Solutions, Inc. (Nasdaq: KTOS), a technology company in defense, national security, and global markets, announced today its role in supporting the Missile Defense Agency (MDA) and Japan Maritime Self-Defense Force (JMSDF) during the Japan Flight Test Experiment (JFTX)-01, conducted March 17 and 19 off the East Coast of the United States.

JFTX-01 marks an important step in the testing of Japan’s Aegis System Equipped Vessel (ASEV) Shipset 1, validating next-generation radar and missile defense capabilities. In collaboration with MDA and JMSDF, Kratos provided target vehicles for two tracking events, enabling the SPY-7 radar, a key next generation component of the Aegis Weapon System, to successfully detect, track, and deliver simulated engagement solutions. The exercise generated key datasets supporting system performance evaluation and risk reduction ahead of future ASEV development milestones.

“Our team’s proven ability to rapidly deliver reliable, mission-relevant target vehicles was central to the success of JFTX-01,” said Dave Carter, President of Kratos Defense & Rocket Support Services. “Kratos target vehicles provide realistic threat representation, ensuring allied navies can test and validate advanced tracking and engagement solutions with confidence.”

JFTX-01, led by MDA, showcased ongoing technological cooperation between Japan and the United States. Kratos target vehicles enabled the SPY-7 radar, built on technology derived from MDA’s Long Range Discrimination Radar, to collect critical data on search, detection, identification, and tracking in complex operational environments. The two live tracking events concluded with virtual target engagements, providing Japan and its partners with datasets needed to advance shipboard missile defense and inform future system deliveries.

“At Kratos, we are dedicated to investing in and deploying real, mission-relevant products and systems that strengthen the capabilities of the U.S. warfighter and our allies,” said Eric DeMarco, President and CEO of Kratos. “Our history of rapid development and fielding, combined with affordability as a technology, ensures that systems like Aegis are tested using operationally relevant target vehicles leading to maximum tactical readiness. This JFTX-01 achievement reaffirms Kratos’ leadership in advancing national and global security.”

About Kratos Defense & Security Solutions
Kratos Defense & Security Solutions, Inc. (NASDAQ: KTOS) is a technology, products, system and software company addressing defense, national security, and commercial markets. Kratos makes true internally funded research, development, capital and other investments, to rapidly develop, produce and field solutions that address our customers’ mission critical needs and requirements. At Kratos, affordability is a technology, and we seek to utilize proven, leading-edge approaches and technology, not unproven bleeding edge approaches or technology, with Kratos’ approach designed to reduce cost, schedule and risk, enabling us to be first to market with cost effective solutions. We believe that Kratos is known as an innovative disruptive change agent in the industry, a company that is an expert in designing products and systems up front for successful rapid, large quantity, low-cost future manufacturing which is a value-add competitive differentiator for our large traditional prime system integrator partners and also to our government and commercial customers. Kratos intends to pursue program and contract opportunities as the prime or lead contractor when we believe that our probability of win (PWin) is high and any investment required by Kratos is within our capital resource comfort level. We intend to partner and team with a large, traditional system integrator when our assessment of PWin is greater or required investment is beyond Kratos’ comfort level. Kratos’ primary business areas include virtualized ground systems for satellites and space vehicles including software for command & control and telemetry, tracking and control, jet powered unmanned aerial drone systems, hypersonic vehicles and rocket systems, propulsion systems for drones, missiles, loitering munitions, supersonic systems, space craft and launch systems, C5ISR and microwave electronic products for missile, radar, missile defense, space, satellite, counter unmanned aircraft systems, directed energy, communication and other systems, and virtual & augmented reality training systems for the warfighter. For more information, visit www.KratosDefense.com and follow Kratos on LinkedIn and X.

Notice Regarding Forward-Looking Statements
Certain statements in this press release may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are made on the basis of the current beliefs, expectations and assumptions of the management of Kratos and are subject to significant risks and uncertainty. Investors are cautioned not to place undue reliance on any such forward-looking statements. All such forward-looking statements speak only as of the date they are made, and Kratos undertakes no obligation to update or revise these statements, whether because of new information, future events or otherwise. Although Kratos believes that the expectations reflected in these forward-looking statements are reasonable, these statements involve many risks and uncertainties that may cause actual results to differ materially from what may be expressed or implied in these forward-looking statements. For a further discussion of risks and uncertainties that could cause actual results to differ from those expressed in these forward-looking statements, as well as risks relating to the business of Kratos in general, see the risk disclosures in the Annual Report on Form 10-K of Kratos for the year ended December 28, 2025, and in subsequent reports on Forms 10-Q and 8-K and other filings made with the Security and Exchange Commission by Kratos.

Press Contact:
Claire Cantrell
[email protected]

Kratos Investor Information:
877-934-4687
[email protected]

Release – CoreCivic Announces $500 Million Accelerated Share Repurchase Agreement

CoreCivic

Research News and Market Data on CXW

August 10, 2026

PDF Version

BRENTWOOD, Tenn., Aug. 10, 2026 (GLOBE NEWSWIRE) — CoreCivic, Inc. (NYSE: CXW) (CoreCivic or the Company) announced today that is has entered into an accelerated share repurchase agreement (“ASR Agreement”) with a financial institution (“Dealer”) to repurchase $500 million of the Company’s common stock, par value $0.01 per share (the “Common Stock”), as part of its existing capacity of $755.8 million under the Company’s recently announced expanded share repurchase program, which was approved by the Company’s Board of Directors on August 4, 2026. Upon completion of the ASR Agreement, the Company anticipates that approximately $255.8 million of share repurchase authorization will remain available under the Company’s existing share repurchase program.

The Company will make a payment of $500 million to the Dealer on August 10, 2026, and expects to receive an initial delivery of approximately 12.4 million shares of Common Stock from the Dealer, pursuant to the ASR Agreement. The final number of shares to be repurchased by the Company will be based on the average of the daily volume-weighted average price of the Common Stock during the term of the ASR Agreement, less a discount and subject to adjustments pursuant to the ASR Agreement. At settlement, the Dealer may be required to deliver additional shares of Common Stock to the Company, or under certain circumstances, the Company may be required to deliver shares of Common Stock or to make a cash payment, at its election, to the Dealer.   The final settlement of the transaction under the ASR Agreement is scheduled to occur prior to the end of the second quarter of 2027.

2026 Revised Financial Guidance

As a result of the execution of the ASR Agreement, the Company is providing the following updated financial guidance for the full year 2026:

 Updated Guidance
Full Year 2026
Prior Full Year 2026 Guidance
Issued August 5, 2026
Net income$1.492 billion to $1.511 billion$1.497 billion to $1.516 billion
Adjusted Net Income$157.0 million to $165.0 million$161.5 million to $169.5 million
Diluted EPS$15.62 to $15.82$15.00 to $15.20
Adjusted Diluted EPS$1.64 to $1.73$1.62 to $1.70
FFO per diluted share$2.66 to $2.75$2.59 to $2.68
Normalized FFO per diluted share$2.68 to $2.77$2.61 to $2.70
EBITDA$2.216 billion to $2.236 billion$2.222 billion to $2.242 billion
Adjusted EBITDA$434.5 million to $439.5 million$440.5 million to $445.5 million


The updated guidance reflects the Company’s current expectations for the financial impact from the ASR Agreement, which includes the expected initial delivery of approximately 12.4 million shares, a reduction to interest income as a result of the deployment of $500 million of cash on hand pursuant to the ASR Agreement, and the corresponding impact on per share results from the reduction in weighted average shares outstanding.

About CoreCivic

CoreCivic is a diversified, government-solutions company with the scale and experience needed to solve tough government challenges in flexible, cost-effective ways. CoreCivic provides a broad range of solutions to government partners that help build safer, healthier, and more productive communities one person at a time through residential corrections, detention, and reentry management, complementary service offerings to the corrections industry that include pharmaceutical, transportation, and alternatives to incarceration, and government real estate solutions. CoreCivic is the nation’s largest owner of partnership correctional, detention and residential reentry facilities, and one of the largest operators of such facilities in the United States. CoreCivic has been a flexible and dependable partner for government for more than 40 years. CoreCivic’s employees are driven by a deep sense of service, high standards of professionalism and a responsibility to help government better the public good. Learn more at www.corecivic.com.

Forward-Looking Statements

This press release contains statements as to our beliefs and expectations of the outcome of future events that are “forward-looking” statements as defined within the meaning of the Private Securities Litigation Reform Act of 1995, as amended. These forward-looking statements include statements regarding the Company’s recently announced expanded share repurchase program, the Company’s funding of the transactions contemplated by the ASR Agreement, the Company’s expectations regarding the financial impact resulting from the transactions contemplated by the ASR Agreement and the Company’s 2026 financial performance. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from the statements made. These include, but are not limited to, the risks and uncertainties associated with: (i) changes in government policy, legislation and regulations that affect utilization of the private sector for corrections, detention, and residential reentry services, in general, or our business, in particular, including, but not limited to, the continued utilization of our correctional and detention facilities by the federal government as a consequence of presidential executive orders, changes in how the federal government, including ICE, elects to use our detention capacity or otherwise procures alternative detention capacity, and the impact of any changes to immigration reform and sentencing laws (we do not, under longstanding policy, lobby for or against policies or legislation that would determine the basis for, or duration of, an individual’s incarceration or detention); (ii) our ability to obtain and maintain correctional, detention, and residential reentry facility management contracts because of reasons including, but not limited to, sufficient governmental appropriations, contract compliance, negative publicity and effects of inmate disturbances; (iii) changes in the privatization of the corrections and detention industry, the acceptance of our services, the timing of the opening of new facilities and the commencement of new management contracts (including the extent and pace at which new contracts are utilized), as well as our ability to utilize available beds; (iv) our ability to successfully activate idle facilities in a timely manner in order to meet the growth in demand for our facilities and services from the federal government that has occurred as a result of changes in policies and actions of the current presidential administration, and to realize projected returns resulting therefrom; (v) general economic and market conditions, including, but not limited to, the impact governmental budgets can have on our contract renewals and renegotiations, per diem rates, and occupancy; (vi) fluctuations in our operating results because of, among other things, changes in occupancy levels; competition; contract renegotiations or terminations including as a result of a change in facility ownership; inflation and other increases in costs of operations, including a rise in labor costs; fluctuations in interest rates and risks of operations; (vii) government budget uncertainty, the impact of debt ceilings and government shutdowns, including partial shutdowns, and changing budget priorities; (viii) our ability to successfully identify and consummate future development and acquisition opportunities, integrate their operations, and realize projected returns resulting therefrom; (ix) the availability of debt and equity financing on terms that are favorable to us, or at all and (x) our ability to successfully consummate the sales of additional company-owned assets, including the potential sale of additional facilities to ICE, on a timely basis and on commercially favorable terms. Other factors that could cause operating and financial results to differ are described in the filings we make from time to time with the Securities and Exchange Commission.

We take no responsibility for updating the information contained in this press release following the date hereof to reflect events or circumstances occurring after the date hereof or the occurrence of unanticipated events or for any changes or modifications made to this press release or the information contained herein by any third-parties, including, but not limited to, any wire or internet services, except as may be required by law.

NOTE TO SUPPLEMENTAL FINANCIAL INFORMATION

Adjusted Net Income, EBITDA, Adjusted EBITDA, FFO, and Normalized FFO, and, where appropriate, their corresponding per share metrics are non-GAAP financial measures. The Company believes that these measures are important operating measures that supplement discussion and analysis of the Company’s results of operations and are used to review and assess operating performance of the Company and its properties and their management teams. The Company believes that it is useful to provide investors, security analysts, and other interested parties disclosures of its results of operations on the same basis that is used by management.  

FFO, in particular, is a widely accepted non-GAAP supplemental measure of performance of real estate companies, grounded in the standards for FFO established by the National Association of Real Estate Investment Trusts (NAREIT).   NAREIT defines FFO as net income computed in accordance with GAAP, excluding gains (or losses) from sales of property and extraordinary items, plus depreciation and amortization of real estate and impairment of depreciable real estate and after adjustments for unconsolidated partnerships and joint ventures calculated to reflect funds from operations on the same basis. As a company with extensive real estate holdings, we believe FFO and FFO per share are important supplemental measures of our operating performance and believe they are frequently used by securities analysts, investors and other interested parties in the evaluation of REITs and other real estate operating companies, many of which present FFO and FFO per share when reporting results. EBITDA, Adjusted EBITDA, and FFO are useful as supplemental measures of performance of the Company’s properties because such measures do not take into account depreciation and amortization, or with respect to EBITDA, the impact of the Company’s tax provisions and financing strategies. Because the historical cost accounting convention used for real estate assets requires depreciation (except on land), this accounting presentation assumes that the value of real estate assets diminishes at a level rate over time.   Because of the unique structure, design and use of the Company’s properties, management believes that assessing performance of the Company’s properties without the impact of depreciation or amortization is useful. The Company may make adjustments to FFO from time to time for certain other income and expenses that it considers non-recurring, infrequent or unusual, even though such items may require cash settlement, because such items do not reflect a necessary or ordinary component of the ongoing operations of the Company.   Normalized FFO excludes the effects of such items. The Company calculates Adjusted Net Income by adding to GAAP Net Income expenses associated with the Company’s debt repayments and refinancing transactions, and certain impairments and other charges that the Company believes are unusual or non-recurring to provide an alternative measure of comparing operating performance for the periods presented.

Other companies may calculate Adjusted Net Income, EBITDA, Adjusted EBITDA, FFO, and Normalized FFO differently than the Company does, or adjust for other items, and therefore comparability may be limited.   Adjusted Net Income, EBITDA, Adjusted EBITDA, FFO, and Normalized FFO and, where appropriate, their corresponding per share measures are not measures of performance under GAAP, and should not be considered as an alternative to cash flows from operating activities, a measure of liquidity or an alternative to net income as indicators of the Company’s operating performance or any other measure of performance derived in accordance with GAAP.   This data should be read in conjunction with the Company’s consolidated financial statements and related notes included in its filings with the Securities and Exchange Commission.

Release – U.S. Marine Corps Awards V2X Up to $500M Logistics Integration Support Contract

V2X

Research News and Market Data on VVX

August 10, 2026

RESTON, Va., Aug. 10, 2026 /PRNewswire/ — V2X Inc. (NYSE: VVX) has been awarded a contract with a base value of approximately $391 million, with a potential value of up to $500 million including all option periods under the contract ceiling, by the U.S. Marine Corps Logistics Command to provide Logistics Integration Support Services for the Marine Force Storage Command’s Secondary Repairable (SECREP) program.

Under the contract, V2X will coordinate the complex repair and sustainment process for secondary repairable components, helping ensure critical equipment is restored efficiently and returned to service in support of Marine Corps readiness. The program leverages an extensive network of original equipment manufacturers, military depots, and industry partners to repair and manage mission-essential components across the Marine Corps’ logistics enterprise.

“Readiness begins with sustainment, and V2X is proud to continue supporting the U.S. Marine Corps with integrated logistics solutions that keep critical equipment mission ready,” said Jeremy C. Wensinger, President and Chief Executive Officer of V2X. “This award reflects our proven ability to manage complex sustainment operations that improve availability, strengthen supply chain performance, and deliver value to our customer.”

V2X has supported the Marine Corps’ SECREP program for more than twenty years delivering logistics expertise that helps reduce costs, improve repair cycle times, and increase equipment availability. Through proven supply chain management, repair coordination, and lifecycle sustainment capabilities, V2X enables the Marine Corps to maximize operational readiness while extending the service life of critical assets.

The contract builds on V2X’s broad portfolio of integrated logistics and sustainment programs supporting customers worldwide. By combining engineering, supply chain management, and mission support expertise, V2X delivers innovative solutions that enhance readiness and ensure warfighters have the equipment they need to accomplish their missions.

About V2X
V2X builds innovative solutions that integrate physical and digital environments by aligning people, actions, and technology. V2X is embedded in all elements of a critical mission’s lifecycle to enhance readiness, optimize resource management, and boost security. The company provides innovation spanning national security, defense, civilian, and international markets. With a global team of approximately 16,000 professionals, V2X enables mission success by injecting AI and machine learning capabilities to meet today’s toughest challenges across all operational domains.

Investor Contact
Mike Smith, CFA
Vice President, Treasury, Corporate Development and Investor Relations
[email protected] 
719-637-5773

Media Contact
Angelica Spanos Deoudes
Senior Director, Marketing and Communications
[email protected] 
571-338-5195

Cision View original content to download multimedia:https://www.prnewswire.com/news-releases/us-marine-corps-awards-v2x-up-to-500m-logistics-integration-support-contract-302846601.html

SOURCE V2X, Inc.

Release – Greenwich LifeSciences Extends Lock-up of Directors and Officers to January 31, 2027

Greenwich LifeSciences

Research News and Market Data on GLSI

 Download as PDFAugust 10, 2026 6:00am EDT

STAFFORD, Texas, Aug. 10, 2026 (GLOBE NEWSWIRE) — Greenwich LifeSciences, Inc. (Nasdaq: GLSI) (the “Company”), a clinical-stage biopharmaceutical company focused on its Phase III clinical trial, FLAMINGO-01, which is evaluating Fast Track designated GLSI-100, an immunotherapy to prevent breast cancer recurrences, today announced that its Board of Directors has extended the lock-up of the shares owned by the Company’s directors, officers, and existing pre-IPO investors to January 31, 2027 which is approximately 76 months from the date of the Company’s IPO. During this period, current officers, directors and certain shareholders will not be able to sell their shares of the Company’s common stock unless otherwise modified by the Board of Directors. After January 31, 2027, the quantity of these locked-up shares that can be sold daily and over various periods of time will be restricted under a leak-out plan unless otherwise modified by the Board of Directors.

The Board could choose to end all or a small percentage of the 100% lock-up at any time for any reason, including prior to any data announcements, interim analyses, strategic transactions, such as an acquisition or partnership, or financial transactions, such as royalty or strategic investor transactions that provide a potential bridge to commercialization. The Board could also choose to implement a pre-determined leak-out plan and/or a 10b5-1 selling program at any time for any reason that allows for the organized independent selling of some of the locked-up shares by a third party over a specified period of time. Such decisions may or may not be announced at the time of the board’s decision.

CEO Snehal Patel commented, “We attended and presented at the BIO conference in June 2026 and plan to attend the BIO-Europe conference later this year, where strategic and financing transactions can be originated or concluded. With the further derisking of the Phase III clinical trial, more than doubling of enrollment and event rate, interest from leading clinicians and hospitals in up to 200 sites in the US and Europe, screening of over 1,500 patients, and the transformation of the interim analysis into a big pharma like study similar in design to recent large breast cancer studies, we are expecting a continued up-tick in the quantity and seriousness of such discussions.”

About Greenwich LifeSciences, Inc.

Greenwich LifeSciences is a clinical-stage biopharmaceutical company focused on the development of GP2, an immunotherapy to prevent breast cancer recurrences in patients who have previously undergone surgery. GP2 is a 9 amino acid transmembrane peptide of the HER2 protein, a cell surface receptor protein that is expressed in a variety of common cancers, including expression in 75% of breast cancers at low (1+), intermediate (2+), and high (3+ or over-expressor) levels. Greenwich LifeSciences has commenced a Phase III clinical trial, FLAMINGO-01. For more information on Greenwich LifeSciences, please visit the Company’s website at www.greenwichlifesciences.com and follow the Company’s Twitter at https://twitter.com/GreenwichLS.

Forward-Looking Statement Disclaimer

Statements in this press release contain “forward-looking statements” that are subject to substantial risks and uncertainties. All statements, other than statements of historical fact, contained in this press release are forward-looking statements. Forward-looking statements contained in this press release may be identified by the use of words such as “anticipate,” “believe,” “contemplate,” “could,” “estimate,” “expect,” “intend,” “seek,” “may,” “might,” “plan,” “potential,” “predict,” “project,” “target,” “aim,” “should,” “will,” “would,” or the negative of these words or other similar expressions, although not all forward-looking statements contain these words. Forward-looking statements are based on Greenwich LifeSciences Inc.’s current expectations and are subject to inherent uncertainties, risks and assumptions that are difficult to predict, including statements regarding the intended use of net proceeds from the public offering; consequently, actual results may differ materially from those expressed or implied by such forward-looking statements. Further, certain forward-looking statements are based on assumptions as to future events that may not prove to be accurate. These and other risks and uncertainties are described more fully in the section entitled “Risk Factors” in Greenwich LifeSciences’ Annual Report on the most recent Form 10-K for the year ended December 31, 2025, and other periodic reports filed with the Securities and Exchange Commission. Forward-looking statements contained in this announcement are made as of this date, and Greenwich LifeSciences, Inc. undertakes no duty to update such information except as required under applicable law.

Company Contact
Snehal Patel
Investor Relations
Office: (832) 819-3232
Email: [email protected]

Investor & Public Relations Contact for Greenwich LifeSciences
Dave Gentry
RedChip Companies Inc.
Office: 1-800-RED CHIP (733 2447)
Email: [email protected]

Primary Logo

Source: Greenwich LifeSciences, Inc.

Released August 10, 2026

Release – Star Equity Holdings to Release Second Quarter 2026 Financial Results on August 14

Star Equity Holdings

Research News and Market Data on STRR

Aug 7, 2026

Download PDF

OLD GREENWICH, Conn., Aug. 07, 2026 (GLOBE NEWSWIRE) — Star Equity Holdings, Inc. (Nasdaq: STRR and STRRP) (“Star” or the “Company”), a diversified holding company, announced today that it will release its financial results for the second quarter ended June 30, 2026, before the open of the market on Friday, August 14, 2026.

A conference call is scheduled for 10:00 a.m. ET on Friday, August 14, 2026, to discuss the results and management’s outlook. The call may be accessed by dialing:

  • Toll Free: 1-833-890-6161
  • International: 1-412-504-9848

A simultaneous webcast of the call may be accessed online from the Events & Presentations link, on the Investor Relations page of the Star Equity website at: https://www.starequity.com/events-and-presentations/presentations.

An archived replay of the webcast will be available shortly after the end of the conference call.

About Star Equity Holdings, Inc.
Star Equity Holdings, Inc. is a diversified holding company that seeks to build long-term shareholder value by acquiring, managing, and growing businesses with strong fundamentals and market opportunities. Its current structure comprises four segments: Building Solutions, Business Services, Energy Services, and Investments. For more information visit www.starequity.com.

Building Solutions
The Building Solutions division operates in three specialties: (i) modular building manufacturing; (ii) structural wall panel and wood foundation manufacturing, including building supply distribution operations; and (iii) glue-laminated timber (glulam) column, beam, and truss manufacturing.

Business Services
The Business Services division provides flexible and scalable recruitment solutions to a global clientele, servicing organizations at all levels, from entry-level positions to the C-suite. The division focuses on mid-market and enterprise organizations worldwide, partnering consultatively with talent acquisition, HR, and procurement leaders to build diverse, high-impact teams and drive business success.

Energy Services
The Energy Services division engages in the rental, sale, and repair of downhole tools used in the oil and gas, geothermal, mining, and water-well industries.

Investments
The Investments division manages and finances the Company’s real estate assets as well as its investment positions in private and public companies.

For more information contact:
The Equity Group
Lena Cati
Senior Vice President
212-836-9611
[email protected]

Gyre Therapeutics Reports Second Quarter 2026 and Year-to-Date Financial Results and Provides Business Update

Research News and Market Data on GYRE

August 7, 2026

PDF Version

Q2 2026 revenue of $29.1 million; GAAP basic EPS: $(0.12)

Full year 2026 revenue guidance of $100.5 to $111.0 million affirmed

NDA for F351 (hydronidone) for CHB-induced liver fibrosis accepted by China’s CDE in May 2026

SAN DIEGO, Aug. 07, 2026 (GLOBE NEWSWIRE) — Gyre Therapeutics, Inc. (Gyre, Gyre Therapeutics or the Company) (Nasdaq: GYRE), an innovative, commercial-stage biopharmaceutical company with operations in the United States and China, today announced financial results for the second quarter ended June 30, 2026, and provided a business update.

Dr. Ying Luo, President and Chief Executive Officer of Gyre Therapeutics, commented, “I am very pleased with Gyre’s progress over this last quarter, the highlights of which include the acquisition of Cullgen with its robust degrader pipeline and strong executive team, the NMPA acceptance of an NDA for F351 for CHB liver fibrosis, Gyre’s second major product candidate after ETUARY™, and increased sales from our Gyre Pharmaceuticals division, which demonstrates our commercialization capabilities.”

Second Quarter Business Highlights and Upcoming Milestones

Commercial Products:

ETUARYTM (pirfenidone), the Company’s primary product approved in China for idiopathic pulmonary fibrosis (IPF), generated $28.0 million in sales for the quarter ended June 30, 2026, compared to $23.5 million for the same period in 2025. EtorelTM (nintedanib ethanesulfonate soft capsules), which was launched in June 2025 and is indicated for systemic sclerosis-associated interstitial lung disease (SSc-ILD) and progressive pulmonary fibrosis (PPF), generated $0.3 million in sales for the quarter ended June 30, 2026 compared to $1.6 million for the same period in 2025. ContivaTM (avatrombopag maleate tablets), launched in March 2025 and indicated for thrombocytopenia in adults with chronic liver disease and immune thrombocytopenic purpura, generated $0.9 million in sales for the quarter ended June 30, 2026, compared to $1.5 million for the same period in 2025.

Pipeline Development Updates

F351 (hydronidone):

In May 2026, Gyre announced that the Center for Drug Evaluation (CDE) of China’s National Medical Products Administration (NMPA) accepted its New Drug Application (NDA) for F351 (hydronidone) as a treatment for chronic hepatitis B (CHB)-induced liver fibrosis. The acceptance came after Gyre submitted the NDA through its majority-owned subsidiary Gyre Pharmaceuticals Co., Ltd. (Gyre Pharmaceuticals) following the priority review status for F351 granted by the NMPA in March.

Pirfenidone (ETUARYTM):

A Phase 3 trial of pirfenidone for the treatment of pneumoconiosis (PD) in the People’s Republic of China (PRC) completed enrollment in 2025. A total of 272 patients were enrolled evaluating the efficacy and safety of 52 weeks of pirfenidone capsule treatment in patients with PD versus placebo. The final patient is expected to complete the study by the fourth quarter of 2026.

In April 2026, Gyre initiated its adaptive Phase 2/3 clinical trial in oncology-related pulmonary complications, with the first patient enrolled. The trial is evaluating pirfenidone for radiation-induced lung injury (RILI), including cases complicated by immune-related pneumonitis, at leading oncology centers.

Dr. Luo added, “Following the close of our acquisition of Cullgen, we gained a portfolio of targeted protein degraders and degrader-antibody conjugates, while also expanding our pipeline into cancer, inflammatory diseases, cancer pain and solid tumors. We now have a full-spectrum pipeline consisting of clinical and IND-enabling assets to address multiple therapeutic areas with a focus on fibrosis and inflammatory diseases, plus a next-generation TPD/DAC platform to complement our legacy, commercial-stage fibrosis platform.  We believe the latter provides long-term upside, especially with our China-based innovation capabilities driving cost efficiencies for early-stage development.”

Cullgen Acquisition Closes in the Second Quarter of 2026

On May 4, 2026, Gyre Therapeutics acquired Cullgen Inc. (Cullgen) in an all-stock transaction valued at approximately $300 million and Cullgen became a wholly owned subsidiary of Gyre. Upon the closing of this transaction, Cullgen’s former Chief Executive Officer (CEO), Dr. Ying Luo, was appointed President and CEO of Gyre and joined Gyre’s Board. Additionally, Yue Xiong, former Chief Scientific Officer (CSO) of Cullgen, was appointed CSO of Gyre, Thomas Eastling, former Chief Financial Officer (CFO) of Cullgen, was appointed CFO of Gyre, and Ping Zhang was named Chairman. The combined company remains headquartered in San Diego with subsidiaries in Beijing and Shanghai, with roughly 740 employees, and numerous announced therapeutic programs spanning inflammation/pain and cancer.

The transaction has been accounted for as a transaction between entities under common control. Accordingly, the accompanying unaudited condensed consolidated financial statements have been retrospectively recast for all periods presented during which the Company and Cullgen were under common control to reflect the combined financial position and results of operations of the Company and Cullgen as if the common-control transfer had occurred at the beginning of the earliest period presented.

Updates on Programs in Development Following Cullgen Acquisition

CG001419 for cancer pain and solid tumors: Following the successful completion of a Phase 1 study in Australia of 78 healthy volunteers in December 2025, Gyre is now planning a Phase 2 study to further evaluate CG001419 in cancer-induced bone pain (CIBP) or other metastatic cancer pain syndromes.

CG001419 continues to separately be evaluated in a Phase 1 trial in China for the treatment of solid tumors.

CG009301 for AML:  The second product candidate from Cullgen, CG009301, is a GSPT1 Degrader for acute myeloid leukemia (AML), a fast-growing cancer of the blood and bone marrow.  This candidate continues to be studied in a Phase 1 dose-escalation trial being conducted in China in patients with high-risk hematologic malignancies.

Dual-degrader programs, next-generation TPDs: Gyre expects to submit Investigational New Drug (IND) applications in the United States and/or China in the first quarter of 2027 for two additional Cullgen degrader assets: CG923308, a CDK2-Cyclin E dual degrader for solid tumor indications, and CG620953, a TYK2-JAK1 dual degrader for autoimmune diseases.

DACs, next-generation ADCs: Additional candidates include degrader antibody conjugates (DACs), which are considered to be the next generation of antibody drug conjugates (ADCs), and which are in development to target both solid tumors and hematological malignancies by pairing distinct protein degraders with tumor-specific antibodies.

Financial Results

Cash Position

As of June 30, 2026, Gyre held $43.3 million in cash and cash equivalents, $14.1 million in short-term bank deposits, $17.5 million in short-term investment, and $28.4 million in long-term certificates of deposit, totaling $103.2 million. Compared to $116.1 million as of December 31, 2025, total cash decreased by $12.9 million, or 11%, primarily driven by a decrease in short-term investment of $10.6 million.

Financial Results for the Three Months Ended June 30, 2026

  • Revenues: Revenues for the three months ended June 30, 2026 were $29.1 million, compared to $29.7 million for the same period in 2025, representing a $0.6 million, or 2%, decrease. Gyre Pharmaceuticals revenue increased during the period, primarily driven by higher ETUARYTM sales volumes resulting from ETUARYTM focused marketing efforts, despite lower ContivaTM and EtorelTM product revenues earned following the implementation of China’s national centralized procurement program. The increase was offset by a $3.0 million decrease in collaboration revenue from the Collaboration, Option, and License Agreement with Astellas Pharma Inc. (the Astellas Agreement) which ended in March 2026, resulting in an overall decrease in revenues of $0.6 million, or 2%, compared to the prior-year period.
  • Cost of Revenues: For the three months ended June 30, 2026, cost of revenues was $2.2 million, compared to $1.2 million for the same period in 2025. The $1.0 million, or 92%, increase was primarily driven by a $0.7 million increase in production costs associated with EtorelTM products, a $0.2 million increase in production costs for ETUARYTM, and a $0.1 million increase in stock-based compensation expense.
  • Selling and Marketing Expense: For the three months ended June 30, 2026, selling and marketing expense was $13.8 million, compared to $15.2 million for the same period in 2025. The $1.4 million, or 9%, decrease was primarily attributable to a $2.5 million decrease in promotional and conference expenses as certain promotional objectives were achieved in the first quarter of 2026, reducing spending in the second quarter, partially offset by a $0.6 million increase in stock-based compensation expenses, and a $0.5 million increase in personnel-related costs, primarily due to increased sales commissions resulting from higher sales volumes during the second quarter of 2026.
  • Research and Development Expense: For the three months ended June 30, 2026, research and development expense was $19.1 million, compared to $8.4 million for the same period in 2025. The $10.8 million, or 129%, increase was primarily related to a $4.7 million increase in external clinical research expenses, mainly attributable to the F351 Phase 3C experimental review expense; a $4.8 million increase for the milestone payment Gyre Pharmaceuticals owed to GNI Group Ltd. (GNI) related to China’s NMPA acceptance of NDA for F351 as a treatment for CHB-induced liver fibrosis; a $0.7 million increase in pre-clinical expenses, and a $0.6 million increase in facilities, depreciation and other expenses.
  • General and Administrative Expense: For the three months ended June 30, 2026, general and administrative expense was $7.9 million, compared to $7.3 million for the same period in 2025. The $0.6 million, or 8%, increase was primarily driven by a $0.9 million increase in personnel costs related to the Company’s internal restructuring, and a $0.2 million increase in miscellaneous expenses, partially offset by a $0.2 million decrease in stock-based compensation expenses and a $0.3 million decrease in professional fees.
  • Transaction Costs: For the three months ended June 30, 2026, $0.5 million in transaction costs were incurred in connection with the acquisition of Cullgen closed in early May 2026.
  • Loss from Operations: For the three months ended June 30, 2026, loss from operations was $14.4 million, compared to loss from operations of $2.2 million for the same period in 2025. The $12.1 million increase was primarily driven by an increase in total operating expenses including transaction costs, increased stock-based compensation, expanded marketing expenses for EtorelTM and ContivaTM, and Phase 3C and other clinical trial and pre-clinical activities.
  • Net (Loss) Income: For the three months ended June 30, 2026, net loss was $14.3 million, compared to net loss of $2.2 million for the same period in 2025. The $12.0 million increase in net loss was primarily driven by an increase in operating expenses of $11.5 million, a decrease in other income of $0.7 million, and a decrease in revenue of $0.6 million, partially offset by a decrease in income tax expense of $0.8 million.
  • Non-GAAP Adjusted Net Income: For the three months ended June 30, 2026, non-GAAP adjusted net loss was $12.2 million, compared to non-GAAP adjusted net loss of $0.6 million for the same period in 2025. The $11.6 million decrease was primarily driven by an increase in operating expenses of $10.3 million, a decrease in other income of $0.7 million, and a decrease in revenue of $0.6 million.

Financial Results for the Six Months Ended June 30, 2026

  • Revenues: Revenues for the six months ended June 30, 2026, were $53.5 million, compared to $60.3 million for the same period in 2025, resulting in a $6.8 million decrease. Revenue from Gyre Pharmaceuticals increased during the period, primarily driven by higher ETUARYTM sales volumes resulting from ETUARYTM focused marketing efforts, despite lower ContivaTM and EtorelTM product revenues following the implementation of China’s national centralized procurement program. The overall increase in revenue from Gyre Pharmaceuticals was offset by a $9.6 million decrease in collaboration revenue under the Astellas Agreement which ended in March 2026.
  • Cost of Revenues: For the six months ended June 30, 2026, cost of revenues was $3.4 million, compared to $2.0 million for the same period in 2025. The $1.4 million increase was primarily driven by higher EtorelTM product costs of $1.1 million and increased stock-based compensation expense of $0.3 million.
  • Selling and Marketing Expense: For the six months ended June 30, 2026, selling and marketing expense was $27.9 million, compared to $26.0 million for the same period in 2025. The $1.9 million increase was primarily attributable to a $1.6 million increase in stock-based compensation expense, and a $0.4 million increase in promotional and conference expenses, partially offset by a $0.1 million decrease in travel and other expense.
  • Research and Development Expense: For the six months ended June 30, 2026, research and development expense was $30.6 million, compared to $16.4 million for the same period in 2025. The $14.2 million increase was primarily related to an $8.9 million increase in external clinical research expenses, mainly attributable to the F351 Phase 3C experimental review expense; a $0.4 million increase in personnel-related expenses including stock-based compensation expenses, a $4.8 million increase for the milestone payment Gyre Pharmaceuticals owed to GNI related to China’s NMPA acceptance of NDA for F351 as a treatment for CHB-induced liver fibrosis; a $0.5 million increase in pre-clinical expenses, and a $0.4 million increase in materials and utilities expenses, partially offset by a $0.8 million decrease in facilities, depreciation and other expenses.
  • General and Administrative Expense: For the six months ended June 30, 2026, general and administrative expense was $18.0 million, compared to $15.4 million for the same period in 2025. The $2.6 million increase was primarily driven by a $2.7 million increase in personnel costs related to the Company’s internal restructuring, a $0.9 million increase in miscellaneous expenses, a $0.6 million increase in stock-based compensation expenses, partially offset by a $1.6 million decrease in professional fees.
  • Transaction Costs: For the six months ended June 30, 2026, $3.8 million in transaction costs were incurred in connection with the termination of proposed merger between Cullgen and Pulmatrix, Inc. in February 2026 and $3.1 million were incurred related to the acquisition of Cullgen, which transaction closed in early May 2026, totaling $6.9 million.
  • (Loss) Income from Operations: For the six months ended June 30, 2026, loss from operations was $33.3 million, compared to $0.3 million income from operations for the same period in 2025. The $33.6 million decrease was primarily driven by an increase in total operating expense including transaction costs, increased stock-based compensation, expanded marketing expenses for EtorelTM and ContivaTM, and Phase 3C and other clinical trial and pre-clinical activities.
  • Net (Loss) Income: For the six months ended June 30, 2026, net loss was $32.8 million, compared to $2.7 million net income for the same period in 2025. The $35.6 million increase was primarily driven by an increase in operating expenses of $26.9 million, a decrease in other income of $3.1 million, and a decrease in revenue of $6.8 million, partially offset by a decrease in income tax expense of $1.2 million.
  • Non-GAAP Adjusted Net (Loss) Income: For the six months ended June 30, 2026, non-GAAP adjusted net loss was $21.1 million, compared to $3.7 million non-GAAP adjusted net income for the same period in 2025. The decrease was primarily driven by an increase in operating expenses of $17.2 million, a decrease in other income of $0.8 million, and a decrease in revenue of $6.8 million.

Use of Non-GAAP Financial Measures by Gyre Therapeutics, Inc.

Gyre reports financial results in accordance with accounting principles generally accepted in the United States (GAAP). This release presents the financial measure “adjusted net income,” which is not calculated in accordance with GAAP. The most directly comparable GAAP measure for this non-GAAP financial measure is “net income.” Adjusted net income presents Gyre’s results of operations after excluding gain from change in fair value of warrants, stock-based compensation, provision for income taxes, transaction costs and loss on disposal of assets, net. This is meant to supplement, and not substitute, Gyre’s financial information presented in accordance with GAAP. Adjusted net income as defined by Gyre may not be comparable to similar non-GAAP measures presented by other companies. Management believes that presenting adjusted net income provides investors with additional useful information in evaluating Gyre’s performance and valuation. See the reconciliation of adjusted net income to net income in the section titled “Reconciliation of GAAP to Non-GAAP Financial Measures” below.

About F351

F351 is Gyre’s lead development candidate for the treatment of liver fibrosis that is being developed for two different indications. It is a structurally modified derivative of pirfenidone designed to optimize metabolic properties while targeting the TGF-β1 signaling pathway, a key mediator of fibrogenesis. Gyre is developing F351 for two primary indications: CHB-associated liver fibrosis in the PRC and MASH-associated liver fibrosis initially in the United States.

In the United States, Gyre has completed a Phase 1 clinical trial in healthy volunteers evaluating F351’s safety, tolerability, and PK. Gyre is further analyzing China Phase 3 study results of F351, together with new pre-clinical results obtained to determine an optimal regulatory path for Phase 2 studies in MASH fibrosis.

About Gyre Pharmaceuticals

Gyre Pharmaceuticals Co., Ltd., a subsidiary of Gyre Therapeutics, Inc., is a commercial-stage biopharmaceutical company committed to the research, development, manufacturing and commercialization of innovative drugs for organ fibrosis. Its flagship product, ETUARY™ (pirfenidone capsule), was the first approved treatment for IPF in the PRC in 2011 and has maintained a prominent market share over the past several years. In addition, Gyre Pharmaceuticals’ pipeline includes F351 (hydronidone), a structural analogue of pirfenidone, which demonstrated statistically significant fibrosis regression after 52 weeks of treatment in a pivotal Phase 3 clinical trial in CHB-associated liver fibrosis in the PRC. In May 2026, China’s National Medical Products Administration (NMPA) accepted Gyre Pharmaceuticals’ New Drug Application (NDA) for F351 as a treatment for CHB-induced liver fibrosis, which is liver damage resulting from the infection of the hepatitis B virus (HBV). F351 received Breakthrough Therapy designation by the CDE of the NMPA in March 2021. Gyre Pharmaceuticals is also developing treatments for PD, RILI with or without immune-related pneumonitis, chronic obstructive pulmonary disease (COPD), pulmonary arterial hypertension (PAH) and acute/acute-on-chronic liver failure (ALF/ACLF). As of June 30, 2026, Gyre Therapeutics owns a 69.7% equity interest in Gyre Pharmaceuticals.

About Gyre Therapeutics

Gyre Therapeutics is a commercial-stage biopharmaceutical company headquartered in San Diego, CA focused on the development and commercialization of small-molecule therapeutics with its most advanced programs addressing organ fibrosis and inflammatory diseases.

Gyre’s wholly-owned subsidiary, Cullgen Inc., is a clinical-stage biopharmaceutical company focused on the discovery and development of targeted protein degrader and DAC therapies for critical conditions including cancer and inflammatory diseases. Cullgen has created a portfolio of highly selective targeted protein degrader and DAC product candidates designed to potently and efficiently eliminate therapeutically relevant proteins in patients.

Forward-Looking Statements

This press release contains “forward-looking statements” within the meaning of the “safe harbor” provisions of the Private Securities Litigation Reform Act of 1995, which statements are subject to substantial risks and uncertainties and are based on estimates and assumptions. All statements, other than statements of historical facts included in this press release, are forward-looking statements, including statements concerning: the development and commercial potential and potential benefits of F351; the timing and progression of commercial approval of F351; and the timing of Gyre’s IND application, and, if the IND becomes effective, initiation of a Phase 2 clinical trial for F351. In some cases, you can identify forward-looking statements by terms such as “may,” “might,” “will,” “objective,” “intend,” “should,” “could,” “can,” “would,” “expect,” “believe,” “design,” “estimate,” “predict,” “potential,” “plan” or the negative of these terms, and similar expressions intended to identify forward-looking statements. These statements reflect our plans, estimates, and expectations, as of the date of this press release. These statements involve known and unknown risks, uncertainties and other factors that could cause our actual results to differ materially from the forward-looking statements expressed or implied in this press release. Actual results and the timing of events could differ materially from those anticipated in such forward-looking statements as a result of these risks and uncertainties, which include, without limitation: unexpected costs, charges or expenses resulting from the acquisition; potential adverse reactions or changes to business relationships resulting from the announcement or completion of the acquisition; the risk that the combined company may not be able to successfully integrate the businesses and realize the expected benefits of the acquisition in a timely manner or at all; the uncertainties associated with Gyre’s and Cullgen’s product candidates, as well as risks associated with the clinical development and regulatory approval of product candidates, including potential delays in the commencement, enrollment and completion of clinical trials; risks related to the inability of the combined entity to obtain sufficient additional capital to continue to advance these product candidates and its pre-clinical programs; uncertainties in obtaining successful clinical results for product candidates and unexpected costs that may result therefrom; risks related to the failure to realize any value from product candidates and pre-clinical programs being developed and anticipated to be developed in light of inherent risks and difficulties involved in successfully bringing product candidates to market; risks associated with the possible failure to realize certain anticipated benefits of the acquisition, including with respect to future financial and operating results. Additional risks and factors are identified under “Risk Factors” in Gyre’s Annual Report on Form 10-K for the year ended December 31, 2025 filed on March 13, 2026, and in other filings with the Securities and Exchange Commission.

Gyre expressly disclaims any obligation to update any forward-looking statements whether as a result of new information, future events or otherwise, except as required by law.

Contact:

Gyre Therapeutics, Inc.

Thomas Eastling, CFO
[email protected]

Investors

Chuck Padala
Managing Director, LifeSci Advisors
[email protected]

View full release here.
Release – BODi Announces Second Amendment to Credit Facility

Placeholder Company

Research News and Market Data on BODI

August 6, 2026

EL SEGUNDO, Calif.–(BUSINESS WIRE)– The Beachbody Company, Inc. (NASDAQ: BODI) (“BODi” or the “Company”), the proactive wellness company delivering nutrition, supplements, and proven fitness programs that help people take control of their health inside and out, today announced it has entered into a second amendment to its credit agreement with Tiger Finance, LLC, as administrative agent and collateral agent. This modification continues to enhance the Company’s financial flexibility through amended covenant terms.

The amendment further streamlines the financial covenant structure, eliminates the billings fixed charge coverage ratio covenant, and adjusts certain other financial covenants, including the minimum digital subscriptions level and the Three Month Total Billings Target. The amended covenants for the Three Month Total Billings target and the minimum Digital Subscriptions level will not be tested if the Company’s cash balance is above $22.5 million. The second amendment reduced the cash balance required to not test these two covenants by approximately $7 million as of the date of the second amendment. The Company must maintain a minimum liquidity level of $18 million, which will decrease by approximately $0.2 million monthly beginning March 1, 2027 to $16 million.

Mark Goldston, Executive Chairman of The Beachbody Company, commented, “We continue to value our relationship with Tiger Finance as a creative, resourceful and supportive partner to BODi. This amendment gives us additional flexibility to execute on our growth strategies as we build on the progress we’ve made in 2026.”

Carl Daikeler, Co-Founder and Chief Executive Officer added: “This amendment reflects the continued strengthening of our balance sheet and supports our ability to invest in growth, including our nutrition and retail initiatives, without compromising the financial discipline that has defined our turnaround.”

The Company’s cash position of $36.6 million on March 31, 2026, exceeded its $23.6 million debt level by $13.0 million. This strong financial position demonstrates the success of its financial transformation and positions BODi for its planned growth initiatives in 2026.

About BODi and The Beachbody Company, Inc.

BODi is the proactive wellness company delivering nutrition, supplements and proven fitness programs that help people take control of their health inside and out. With nearly three decades of experience, BODi, formerly Beachbody, has evolved from a leader in home fitness into a comprehensive health and fitness ecosystem designed to help people achieve their goals and lead healthier, more fulfilling lives. Anchored by science-backed nutrition solutions like Shakeology and supported by its portfolio of proven fitness and habit-building programs, including P90X and INSANITY, BODi is creating a more accessible and effective path to long-term health.

Since its inception, BODi has supported more than 30 million customers in achieving lasting results. The company continues to innovate across nutrition and digital fitness to deliver simple, proven solutions for modern lifestyles.

To subscribe and shop, visit BODi.com. For company and investor information, please visit TheBeachbodyCompany.com.

Investor Relations
[email protected]

Source: The Beachbody Company, Inc.

Release – NeuroSense Completes PrimeC Pre-NDS Process and Advances Toward December 2026 Filing with Health Canada

Research News and Market Data on NRSN

Final meeting minutes reflect alignment with Health Canada on the planned content and structure of the ALS submission

CAMBRIDGE, Mass., Aug. 6, 2026 /PRNewswire/ — NeuroSense Therapeutics Ltd. (NASDAQ: NRSN) (“NeuroSense”), a late-stage clinical biotechnology company focused on developing disease-modifying treatments for neurodegenerative diseases, today announced that it is targeting December 2026 for the filing of a New Drug Submission (“NDS”) with Health Canada for PrimeC, its lead therapeutic candidate for amyotrophic lateral sclerosis (“ALS”).

The filing target follows the successful finalization of the Pre-NDS process with Health Canada and the associated meeting minutes. The discussions with Health Canada provided alignment regarding the content and structure of the submission. Health Canada has also indicated that it has no concerns with the Company’s proposed filing timeline and advised the Company to target early December.

NDS is the Canadian equivalent of a New Drug Application (NDA) in the United States. Following the successful completion of the Pre-NDS process, the application will undergo an administrative screening and, if accepted for review, a comprehensive scientific evaluation. Health Canada’s target review timeline for a standard NDS is approximately 300 days following acceptance for review.

“We now have an alignment with the Canadian regulator and a clear operational target,” said Alon Ben-Noon, Chief Executive Officer of NeuroSense. “Our team is advancing the remaining clinical, biomarker, manufacturing and regulatory components of the NDS, with the objective of filing in December 2026. Canada represents an important potential market for PrimeC and, more importantly, an opportunity to bring a promising therapy to people living with ALS.”

Significant need for additional ALS treatments in Canada

Based on publicly reported Canadian data1, over 3,000 Canadians are currently living with ALS, and approximately 1,000 Canadians are diagnosed with the disease each year. Given the limited treatment options available and their modest clinical benefit, ALS remains a progressive and fatal neurodegenerative disease with substantial unmet medical need.

Health Canada-approved treatments for the broad ALS population include riluzole and edaravone. Based on the publicly reported Canadian list price assessed by the Canadian Agency for Drugs and Technologies in Health, now Canada’s Drug Agency, oral edaravone carries an estimated annual drug-acquisition cost of approximately C$120,000 (approximately US$85,000) per patient. Actual prices paid by public drug plans may differ because of confidential pricing arrangements and negotiated rebates.

NeuroSense believes these market dynamics underscore both the considerable healthcare burden associated with ALS and the need for additional therapies capable of meaningfully affecting disease progression and survival.

PrimeC clinical evidence

The planned NDS will be supported by the totality of evidence generated through NeuroSense’s Phase 2b PARADIGM clinical program, including:

  • Achievement of the study’s prespecified primary TDP-43 biomarker endpoint;
  • Long-term clinical outcomes demonstrating consistent effects on ALSFRS-R decline;
  • Statistically significant ~15-month median survival benefit (HR 0.35, p=0.0037);
  • Consistent findings across PrimeC’s multi-pathway biomarker program; and
  • A favorable safety and tolerability profile during extended treatment and follow-up.

NeuroSense is progressing the Canadian NDS in parallel with preparations for PARAGON, its confirmatory Phase 3 clinical study of PrimeC in ALS.

About NeuroSense

NeuroSense Therapeutics is a late-clinical stage biotechnology company developing novel treatments for severe neurodegenerative diseases, including amyotrophic lateral sclerosis (ALS) and Alzheimer’s disease. The Company’s lead product candidate, PrimeC, is a novel oral therapy designed to target multiple key biological pathways underlying disease progression, including neuroinflammation, oxidative stress and dysregulated iron metabolism.

NeuroSense has recently completed analysis of long-term follow-up data from its Phase 2b PARADIGM study in ALS, supporting meaningful slowing of disease progression. The Company also reported significant biological activity across multiple biomarkers associated with ALS, including microRNAs, supporting PrimeC’s multi-target mechanism of action and representing a potentially important advance in the treatment of ALS.

NeuroSense has received clearance from the U.S. Food and Drug Administration (FDA) to initiate a pivotal Phase 3 clinical trial (PARAGON) in ALS, which is expected to enroll approximately 300 participants, primarily in the United States.

For additional information, we invite you to visit our website and follow us on LinkedIn, YouTube and X. Information that may be important to investors may be routinely posted on our website and these social media channels.

About PrimeC

PrimeC, NeuroSense’s lead drug candidate, is a novel extended-release oral formulation composed of a unique fixed-dose combination of two FDA-approved drugs: ciprofloxacin and celecoxib. PrimeC is designed to target several key mechanisms that contribute to neuron degeneration, inflammation, iron accumulation and impaired ribonucleic acid (“RNA”) regulation, with the potential to inhibit disease progression.

About ALS

Amyotrophic lateral sclerosis (“ALS”) is an incurable neurodegenerative disease that causes complete paralysis and death within 2-5 years from diagnosis. Every year, more than 5,000 people are diagnosed with ALS in the U.S. alone, with an annual disease burden of $1 billion. The number of people living with ALS is expected to grow by 24% by 2040 in the U.S. and EU.

Forward-Looking Statements

This press release contains “forward-looking statements” that are subject to substantial risks and uncertainties. All statements, other than statements of historical fact, contained in this press release are forward-looking statements. Forward-looking statements contained in this press release may be identified by the use of words such as “anticipate,” “believe,” “contemplate,” “could,” “estimate,” “expect,” “intend,” “seek,” “may,” “might,” “plan,” “potential,” “predict,” “project,” “target,” “aim,” “should,” “will” “would,” or the negative of these words or other similar expressions, although not all forward-looking statements contain these words. Forward-looking statements are based on NeuroSense Therapeutics’ current expectations and are subject to inherent uncertainties, risks and assumptions that are difficult to predict and include statements regarding the timing of the filing of the NDS with Health Canada for PrimeC, the timing of review by Health Canada of the NDS and the commercial potential of PrimeC. Further, certain forward-looking statements are based on assumptions as to future events that may not prove to be accurate. The future events and trends may not occur and actual results could differ materially and adversely from those anticipated or implied in the forward looking statements. These risks include risks of delay in the planned filing of the NDS with Health Canada; the risk of delay in the review by Health Canada of the NDS; the risk that Health Canada will not approve the NDS; the uncertainty regarding the commercial potential of PrimeC; uncertainty regarding outcomes and the timing of current and future clinical trials; the risk that PrimeC will not advance towards later-stage development, timing for reporting data, including from the study of PrimeC in Alzheimer’s disease; that the study will not be successful; the ability of NeuroSense to remain listed on Nasdaq; and other risks and uncertainties set forth in NeuroSense’s filings with the Securities and Exchange Commission (SEC). You should not rely on these statements as representing our views in the future. More information about the risks and uncertainties affecting NeuroSense is contained under the heading “Risk Factors” in the Annual Report on Form 20-F filed with the Securities and Exchange Commission on March 31, 2026 and NeuroSense’s subsequent filings with the SEC. Forward-looking statements contained in this announcement are made as of this date, and NeuroSense undertakes no duty to update such information except as required under applicable law.

1 https://news.ontario.ca/en/release/1003213/ontario-first-in-canada-to-provide-coverage-for-new-als-treatment?utm_source=chatgpt.com

Logo – https://mma.prnewswire.com/media/1707291/NeuroSense_Therapeutics_Logo.jpg

SOURCE NeuroSense

For further information: For further information: Email: [email protected] | Tel: +972 (0)9 799 6183

Release – Virginia Awards Conduent Contract to Manage and Modernize Medicaid Program Delivery Systems

Research News and Market Data on CNDT

Award extends Conduent’s 25-year relationship with Virginia Medicaid and accelerates modernization efforts

August 06, 2026

Government Healthcare Services

Conduent Incorporated (Nasdaq: CNDT), a global technology-driven business solutions and services company, today announced that the Virginia Department of Medical Assistance Services (DMAS) has awarded the company a contract to continue operating, and modernize, the Commonwealth’s systems that support Virginia Medicaid. The contract, which spans up to 14 years, extends Conduent’s relationship with Virginia’s Medicaid program that began in 2001.

Under the new agreement, Conduent will use its modular Conduent Medicaid Suite (CMdS) to modernize Virginia’s Medicaid Enterprise Systems and Fiscal Agent Services Solution. These entail claims processing, finance, call center services, reporting, and other core functions. This transition to an integrated, dynamic solution will help DMAS improve access to information, reduce fraud risks, and strengthen program performance. Members, providers, and staff will benefit from enhanced user experiences, supporting better health outcomes for the approximately 1.6 million Virginians enrolled in Medicaid.

Conduent will also deploy Conduent CXNow , its cloud-based Customer Experience-as-a-Service platform used by government agencies and commercial clients. Powered by AI, automation, and analytics, CXNow will streamline customer interactions across phone and chat, expand self-service options, and improve overall service quality. For the Commonwealth, these enhancements will drive additional cost savings and operational efficiency.

“We are honored to continue our long-standing collaboration with Virginia to enhance Medicaid outcomes through modernization, advanced technologies, and improved business processes,” said Anna Sever, President, Government Solutions at Conduent. “Through strong collaboration and teamwork, we are committed to delivering exceptional value to the Commonwealth and improving the lives of Virginians.”

The new contract includes a two-year design and implementation phase, followed by a six-year base term and six one-year options. It also includes continued management of incoming and outgoing mail services supporting the Medicaid program.

Conduent’s Government Solutions supports government healthcare programs across the country, delivering a range of innovative solutions such as Medicaid management and provider services, pharmacy benefits management, eligibility and enrollment support, and case management solutions. The business also provides agencies with government payments and child support services. In 2025 alone, Conduent processed over 454 million Medicaid claims and disbursed approximately $80 billion in government benefit payments.

About Conduent

Conduent delivers digital business solutions and services spanning the commercial, government and transportation spectrum – creating valuable outcomes for its clients and the millions of people who count on them. The Company leverages cloud computing, artificial intelligence, machine learning, automation and advanced analytics to deliver mission-critical solutions. Through a dedicated global team of approximately 48,000 associates, process expertise and advanced technologies, Conduent’s solutions and services digitally transform its clients’ operations to enhance customer experiences, improve performance, increase efficiencies and reduce costs. Conduent adds momentum to its clients’ missions in many ways including disbursing approximately $80 billion in government payments annually, enabling approximately 2.0 billion customer service interactions annually, empowering millions of employees through HR services every year and processing over 14 million tolling transactions every day. Learn more at www.conduent.com .

Note: To receive RSS news feeds, visit www.news.conduent.com . For open commentary, industry perspectives and views, visit https://x.com/Conduent , http://www.linkedin.com/company/Conduent or http://www.facebook.com/Conduent .

Trademarks

Conduent is a trademark of Conduent Incorporated in the United States and/or other countries. Other names may be trademarks of their respective owners.

View source version on businesswire.com: https://www.businesswire.com/news/home/20260806411810/en/

Media:
Neil Franz, Conduent, [email protected] , +1-240-687-0127

Investor Relations:
Conduent, [email protected]

Media Contacts

Neil Franz

Conduent

[email protected]

+1-240-687-0127

Release – Snail, Inc. Sets Second Quarter 2026 Conference Call for Tuesday, August 11, 2026 at 4:30 p.m. ET

Snail, Inc logo

Research News and Market Data on SNAL

August 6, 2026 at 8:30 AM EDT

PDF Version

CULVER CITY, Calif., Aug. 06, 2026 (GLOBE NEWSWIRE) — Snail, Inc. (Nasdaq: SNAL) (“Snail Games” or the “Company”), a leading global independent developer and publisher of interactive digital entertainment, will hold a conference call and webcast on Tuesday, August 11, 2026 at 4:30 p.m. Eastern time (1:30 p.m. Pacific time) to discuss its financial results for the second quarter ended June 30, 2026.

Snail Games management will host the conference call and webcast, followed by a question-and-answer period. Participants may listen to the live webcast and replay via the link here or on the Company’s investor relations website at https://investor.snail.com/.

About Snail, Inc.
Snail, Inc. (Nasdaq: SNAL) is a leading, global independent developer and publisher of interactive digital entertainment for consumers around the world, with a premier portfolio of premium games designed for use on a variety of platforms, including consoles, PCs, and mobile devices. For more information, please visit: https://snail.com/.

Investor Contact:
John Yi and Steven Shinmachi
Gateway Group, Inc.
949-574-3860
[email protected]

Release – Kratos Receives U.S. Army Contract to Develop a Next-Generation Seeker for the Javelin Missile System

Primary Logo

Research News and Market Data on KTOS

August 6, 2026

PDF Version

SAN DIEGO, Aug. 06, 2026 (GLOBE NEWSWIRE) — Kratos Defense & Security Solutions, Inc. (Nasdaq: KTOS), a technology company in defense, national security, and global markets, announced today that it has been awarded a contract by the U.S. Army Combat Capabilities Development Command (DEVCOM) Command, Control, Communications, Computers, Cyber, Intelligence, Surveillance and Reconnaissance (C5ISR) Center to develop an Enhanced Seeker for the Javelin Close Combat Missile System.

Kratos will develop, build, and test a next-generation infrared seeker that addresses obsolescence in the current Javelin guidance section, improving the lethality of one of the U.S. Army’s most critical close combat weapons for the next decade. The work will be performed at Kratos’ Advanced Manufacturing Center in Birmingham, Alabama, with testing at U.S. Army Government facilities.

“Kratos has made the investments, built the credentialed team, and delivered the capabilities to win, execute, and deliver a production-ready seeker that keeps Javelin lethal for the Soldiers who depend on it,” said Michael Johns, Senior Vice President, Kratos SRE, Inc. “We are proud to support the U.S. Army in sustaining one of its most important close combat weapons, and this award is a reflection of everything Kratos stands for: affordable, mission-critical hardware, delivered.”

Kratos brings decades of missile seeker development heritage to this program and a vertically integrated manufacturing capability that positions the company to deliver production-ready hardware affordably and on schedule. The contract also directly supports the Secretary of War’s priority to strengthen the U.S. munitions industrial base.

About Kratos Defense & Security Solutions
Kratos Defense & Security Solutions, Inc. (Nasdaq: KTOS) is a technology, products, system and software company addressing the defense, national security, and global markets. Kratos makes true internally funded research, development, capital and other investments, to rapidly develop, produce and field solutions that address our customers’ mission critical needs and requirements. At Kratos, affordability is a technology, and we seek to utilize proven, leading-edge approaches and technology, not unproven bleeding-edge approaches, with Kratos’ approach designed to reduce cost, schedule and risk, enabling us to be first to market with cost effective solutions. We believe that Kratos is known as an innovative disruptive change agent in the industry, a company that is an expert in designing products and systems up front for successful rapid, large quantity, low-cost future manufacturing which is a value-add competitive differentiator for our large traditional prime system integrator partners and also to our government and commercial customers. Kratos’ primary business areas include virtualized ground systems for satellites and space vehicles; jet-powered unmanned aerial drone systems; advanced vehicles and rocket systems; propulsion systems for drones, missiles, loitering munitions, supersonic systems, spacecraft, and launch systems; C5ISR and microwave electronic products for missile, radar, missile defense, space, satellite, counter-UAS, directed energy, communication, and other systems; and virtual and augmented reality training systems for the warfighter. For more information, visit www.KratosDefense.com and follow Kratos on LinkedIn and X.

Notice Regarding Forward-Looking Statements
Certain statements in this press release may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements are made on the basis of the current beliefs, expectations and assumptions of the management of Kratos and are subject to significant risks and uncertainty. Investors are cautioned not to place undue reliance on any such forward-looking statements. All such forward-looking statements speak only as of the date they are made, and Kratos undertakes no obligation to update or revise these statements, whether as a result of new information, future events or otherwise. Although Kratos believes that the expectations reflected in these forward-looking statements are reasonable, these statements involve many risks and uncertainties that may cause actual results to differ materially from what may be expressed or implied in these forward-looking statements. For a further discussion of risks and uncertainties that could cause actual results to differ from those expressed in these forward-looking statements, as well as risks relating to the business of Kratos in general, see the risk disclosures in the Annual Report on Form 10-K of Kratos for the year ended December 29, 2025, and in subsequent reports on Forms 10-Q and 8-K and other filings made with the SEC by Kratos.

Press Contact: 
Claire Cantrell
[email protected]

Investor Relations: 
877-934-4687
[email protected]

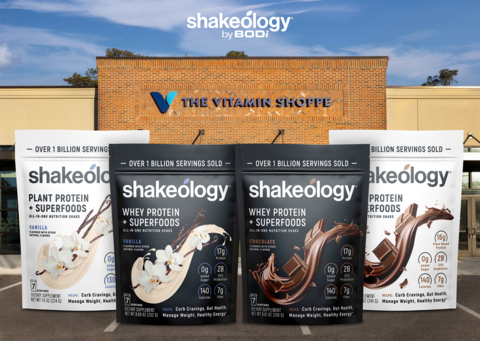
Release – BODi Expands Retail Presence with Shakeology Now Available at The Vitamin Shoppe Nationwide; Launches New Flavor

Placeholder Company

Research News and Market Data on BODI

August 6, 2026

Brings healthy daily protein and superfood nutrition to nearly 500 locations with the retail debut of Vanilla Whey, now with zero grams of added sugar

EL SEGUNDO, Calif.–(BUSINESS WIRE)– BODi (NASDAQ: BODI), the proactive wellness company delivering nutrition, supplements, and proven fitness programs that help people take control of their health inside and out, today announced that Shakeology is now available at The Vitamin Shoppe locations nationwide. The Vitamin Shoppe launch reinforces BODi’s commitment to making science-backed wellness more accessible to consumers across the U.S. The retail rollout includes the core flavors of Shakeology’s 0g Added Sugar line: Chocolate Vegan, Chocolate Whey, Vanilla Vegan, and the new, reformulated Vanilla Whey, all available in a convenient 7-serving bag.

BODi expands its retail presence with Shakeology now available at The Vitamin Shoppe nationwide.

BODi expands its retail presence with Shakeology now available at The Vitamin Shoppe nationwide.

Originally launched in 2009 with over a billion servings sold, Shakeology combines high-quality protein with fiber, prebiotics and probiotics, vitamins, minerals, digestive enzymes, adaptogens, antioxidants, greens, and more than 30 superfoods to help support energy, gut health, digestion and regularity, lean muscle, bone health, as well as a healthy immune system. It also helps protect against free radicals and oxidative stress, reduce cravings, and support weight loss, as demonstrated in a clinical study published in the Journal of Nutrition.

Consumers also report meaningful benefits from making Shakeology part of their daily routine. Based on a survey of Shakeology customers*:

  • 86% reported better digestion after one month
  • 84% said it helped reduce junk food cravings
  • 81% said it helped them feel full until their next meal
  • 74% reported increased energy throughout the day

“When we announced our partnership with The Vitamin Shoppe earlier this year, our goal was to make Shakeology more accessible than ever before,” said Carl Daikeler, co-founder and CEO of BODi. “Today, consumers can walk into stores nationwide and purchase Shakeology. Combined with the introduction of Vanilla Whey with zero grams of added sugar launching in retail for the first time, this represents another important step in bringing healthy, science-backed nutrition to more people.”

To locate the nearest The Vitamin Shoppe location, visit https://locations.vitaminshoppe.com. Shakeology is also available at more than 100 Sprouts Farmers Market locations nationwide. BODi continues to expand retail distribution through its strategic partnership with KeHE Distributors, whose network reaches more than 30,000 grocery, supermarket, natural, and online retail locations.

Consumers can also shop the full Shakeology line on BODi.com, including additional flavors such as 0g Added Sugar Café Latte, Cookies & Creamy, and Tropical Strawberry, as well as 14- and 30-serving bags.

*Based on a survey of 1,550 Shakeology customers who consumed Shakeology five or more times per week and exercised three times per week. Better digestion improvement based on 859 Shakeology customers who reported issues with digestion.

About BODi and The Beachbody Company

BODi is a proactive wellness company delivering nutrition, supplements and proven fitness programs that help people take control of their health inside and out. With nearly three decades of experience, BODi, formerly Beachbody, has evolved from a leader in home fitness into a comprehensive health and fitness ecosystem designed to help people achieve their goals and lead healthier, more fulfilling lives. Anchored by science-backed nutrition solutions like Shakeology and supported by its portfolio of proven fitness and habit-building programs, including P90X and INSANITY, BODi is creating a more accessible and effective path to long-term health.

Since its inception, BODi has supported more than 30 million customers in achieving lasting results. The company continues to innovate across nutrition and digital fitness to deliver simple, proven solutions for modern lifestyles.

To subscribe and shop, visit BODi.com. For company and investor information, please visit TheBeachbodyCompany.com.

About The Vitamin Shoppe®

The Vitamin Shoppe® is an omnichannel specialty retailer and wellness lifestyle company with the mission to provide customers with the most trusted products, guidance, and services that support health and performance in every stage of life. Founded in 1977 and headquartered in Secaucus, New Jersey, The Vitamin Shoppe today is an innovation-focused destination for first-to-market brands and breakthrough products, offering a comprehensive assortment of vitamins, supplements, sports nutrition, and on-the-go functional foods and beverages. Beyond hundreds of national brands, its offering includes the proprietary brands The Vitamin Shoppe®, Vthrive The Vitamin Shoppe®, BodyTech®, BodyTech® Elite, plnt®, ProBioCare®, and True Athlete®. The Company serves customers through more than 640 stores nationwide, providing personalized support from knowledgeable Health Enthusiast associates, and online at www.vitaminshoppe.com. It operates strategic partnerships in select international markets in Asia, South America, Central America, and the Caribbean. The Vitamin Shoppe proudly supports the health and wellness of communities through longstanding partnerships with Vitamin Angels and Team Red, White & Blue.

Media Relations:
[email protected]

Investor Relations:
[email protected]

Source: BODi

Release – Kelly Reports Second-Quarter 2026 Earnings

Research News and Market Data on OCGN

August 6, 2026

PDF Version

TROY, Mich., Aug. 06, 2026 (GLOBE NEWSWIRE) — Kelly (Nasdaq: KELYA, KELYB), a leading specialty talent solutions provider, today announced results for the second quarter of 2026.

  • Q2 revenue of $1.0 billion, with year-over-year decline improving approximately 500 basis points (“bps”) versus the prior quarter; underlying revenue decline excluding previously disclosed discrete items improved 270 bps versus the prior quarter
  • Underlying revenue year-over-year performance reflects strength in the ETM and SET segments with each improved at least 300 bps versus the prior quarter, along with a 40 bps improvement for the Education segment
  • Q2 operating earnings of $16.1 million; $19.3 million of operating earnings on an adjusted basis
  • Q2 adjusted EBITDA of $31.1 million and adjusted EBITDA margin of 3.0%, improved 110 bps on a year-over-year basis versus the prior quarter resulting from stable year-over-year gross profit rate and continued SG&A discipline
  • Company increases its fiscal 2026 revenue outlook, now expecting a low-to-mid-single digit decline, and affirms its adjusted EBITDA margin expectation of modest year-over-year growth driven by accelerating underlying revenue growth and operating efficiencies

Chris Layden, chief executive officer, said, “In the second quarter, we measurably exceeded our guidance for both revenue and adjusted EBITDA margin driven by growing momentum from our growth and efficiency initiatives as well as constructive demand trends in parts of our portfolio. We delivered sequential improvements in each of our businesses as we continued to capitalize on organic growth drivers. Notably, Kelly’s adjusted EBITDA margin returned to 3.0% in the quarter, demonstrating our ability to generate operating leverage in pursuit of growth. Our progress strengthens our conviction in our strategy and reinforces our confidence in our expectation of further measurable improvement in our year-over-year performance as we progress through the second half of the year.”

Financial Results for the thirteen-week period ended June 28, 2026:

Revenue of $1.0 billion, a 5.8% decrease compared to the corresponding quarter of 2025. Discrete impacts associated with the previously disclosed reduced demand for U.S. federal government contractors in the SET segment and from three large commercial customers in the ETM segment totaled approximately 5.2%, resulting in an underlying revenue decline of approximately 0.6%. Underlying revenue performance includes overall growth from improved demand and new business in the ETM segment, including growth in staffing and each of the talent solutions specialties. Offsetting the growth was a measurably improved year-over-year decline within the SET segment which reflects continued year-over-year growth in the Telecom specialty and reduced declines in each of the SET specialties. SET revenue grew sequentially for the first time in over two years. Additionally, the Education segment showed an improved year-over-year decline which continues to be driven by delayed prior year contract decisions and declines in student enrollment in key markets.

Operating earnings of $16.1 million, compared to earnings of $22.2 million reported in the second quarter of 2025. Adjusted earnings1 were $19.3 million in the second quarter of 2026 and $24.6 million in the second quarter of 2025. Adjusted EBITDA1 of $31.1 million, a decrease of 15.9% versus the prior year period. Adjusted EBITDA margin of 3.0%, a decrease of 40 bps but improved 110 bps versus the prior quarter, reflects 10 bps lower gross margin partially offset by volume-related and structural expense management actions including benefits from our acquisition integration and technology modernization efforts. ETM showed year-over-year stability in its adjusted EBITDA margin while Education and SET both declined. Both ETM and SET improved their adjusted EBITDA margins measurably versus the prior quarter.

Income tax expense of $3.0 million, compared to income tax expense of $0.9 million reported in the second quarter of 2025. On an adjusted basis1, income tax expense of $3.8 million, compared to income tax expense of $2.5 million in the second quarter of 2025.

Earnings per share was $0.31 compared to earnings per share of $0.52 in the second quarter of 2025. On an adjusted basis1, earnings per share was $0.37 in the second quarter of 2026 compared to $0.54 per share in the corresponding quarter of 2025.

Financial Results for the 26-week period ended June 28, 2026:

Revenue of $2.1 billion, an 8.3% decrease compared to the corresponding period in 2025. Discrete impacts associated with the reduced demand for U.S. federal government contractors in the SET segment and from three large commercial customers in the ETM segment totaled approximately 6.3%, resulting in an underlying revenue decline of approximately 2.0%. Underlying revenue performance includes overall growth from improved demand in the ETM segment, including growth in each of the talent solutions specialties, along with growth in the Telecom specialty and improved performance in the Science and Engineering specialties within the SET segment. Offsetting this growth was continued lower demand in the other specialties within the SET segment, largely the Technology specialty, along with a decline in the Education segment driven by delayed prior year contract decisions and declines in student enrollment in key markets.

Operating earnings of $11.0 million, compared to earnings of $33.0 million reported over the same period in 2025. Adjusted earnings1 were $23.4 million in the first six months of 2026 and $46.7 million in the corresponding period of 2025. Adjusted EBITDA1 of $46.9 million, a decrease of 34.8% versus the prior year period. Adjusted EBITDA margin of 2.3%, a decrease of 90 bps, reflects near-term margin pressure in ETM, Education, and SET driven by lower gross margins and timing of revenue trends, partially offset by volume-related and structural expense management actions including benefits from our acquisition integration and technology modernization efforts.

Income tax expense of $2.2 million, compared to income tax expense of $2.7 million reported over the same period in 2025. On an adjusted basis1, income tax expense of $5.3 million, compared to income tax expense of $7.2 million in the corresponding period of 2025.

Earnings per share was $0.15, compared to earnings per share of $0.67 in the same period of 2025. On an adjusted basis1, earnings per share were $0.40 for the first six months of 2026 compared to $0.93 per share in the corresponding period of 2025.

1 Adjusted measures represent non-GAAP financial measures. Refer to our reconciliation of non-GAAP financial measures to the most closely related GAAP measure included in this document.

Financial Outlook For Fiscal 2026:

The Company’s 2026 financial outlook has improved for revenue and remains unchanged for Adjusted EBITDA margin relative to the initial view previously disclosed, assumes no material change in the macroeconomic environment in the coming quarters, and is as follows:

  • Third Quarter of 2026 – Expect year-over-year improvement relative to second quarter, with overall underlying revenue growth of 1% to 2%, and total revenue to be flat to a decline of 2% versus the prior year. Adjusted EBITDA margin in the low 2% range, representing 40 to 50 bps of year-over-year improvement relative to the prior year.
    • Outlook includes the seasonality impact of the Education business due to schools being out of session for the majority of the quarter which results in sequential revenue and profitability declines versus the second quarter.
  • Fourth Quarter of 2026 – Expect substantial improvement in year-over-year performance versus third quarter for both revenue and adjusted EBITDA margin resulting in mid-to-upper single digits revenue growth and approximately 200 bps of year-over-year adjusted EBITDA margin expansion resulting in adjusted EBITDA margin of approximately 4%.
    • Outlook includes the impact of an extra fiscal week in the fourth quarter, which benefits revenue growth by approximately 4 points in the quarter, but negatively impacts adjusted EBITDA.
  • Full Year 2026 – On a full year basis, expect low-to-mid single digit total revenue decline and a 10 to 20 bps year-over-year improvement in adjusted EBITDA margin.

Quarterly Cash Dividend:

Kelly also reported that on August 4, 2026, its board of directors declared a dividend of $0.075 per share. The dividend is payable on September 2, 2026 to stockholders of record as of the close of business on August 19, 2026.

In conjunction with its earnings release, Kelly has published a financial presentation and will host a live webcast of a conference call at 9 a.m. ET on August 6 to review the financial and operation results from the quarter. The presentation and a link to the live webcast will be accessible through the Company’s public website on the Investor Relations page under Events & Presentations. The webcast will be recorded, and a replay will be available within one hour of completion of the event through the same link as the live webcast.

Forward-Looking Statements:

This release contains statements that are forward looking in nature and, accordingly, are subject to risks and uncertainties. These statements are made under the “safe harbor” provisions of the U.S. Private Securities Litigation Reform Act of 1995. Statements that are not historical facts, including statements about Kelly’s financial expectations, are forward-looking statements. Factors that could cause actual results to differ materially from those contained in this release include, but are not limited to, (i) changing market and economic conditions, (ii) disruption in the labor market and weakened demand for human capital resulting from technological advances, competitive pressures and pricing, loss of large corporate customers and government contractor requirements, (iii) the impact of laws and regulations (including federal, state and international tax laws), (iv) unexpected changes in claim trends on workers’ compensation, unemployment, disability and medical benefit plans, (v) litigation and other legal liabilities (including tax liabilities) in excess of our estimates, (vi) our ability to achieve our business’s anticipated growth strategies, (vii) our future business development, results of operations and financial condition, (viii) damage to our brands, (ix) dependence on third parties for the execution of critical functions, (x) conducting business in foreign countries, including foreign currency fluctuations, (xi) availability of temporary workers with appropriate skills required by customers, (xii) cyberattacks or other breaches of network or information technology security, and (xiii) other risks, uncertainties and factors discussed in this release and in the Company’s filings with the Securities and Exchange Commission. In some cases, forward-looking statements can be identified by words or phrases such as “may,” “will,” “expect,” “anticipate,” “target,” “aim,” “estimate,” “intend,” “plan,” “believe,” “potential,” “continue,” “is/are likely to” or other similar expressions. All information provided in this press release is as of the date of this press release and we undertake no obligation to update any forward-looking statement, whether as a result of new information, future events, or otherwise, except as required by law.

About Kelly®

Kelly Services, Inc. (Nasdaq: KELYA, KELYB) helps companies recruit and manage skilled workers and helps job seekers find great work. Since inventing the staffing industry in 1946, we have become experts in the many industries and local and global markets we serve. With a network of suppliers and partners around the world, we connect approximately 375,000 people with work every year. Our suite of outsourcing and consulting services and solutions ensures companies have the people they need, when and where they are needed most. Headquartered in Troy, Michigan, we empower businesses and individuals to access limitless opportunities in industries such as science, engineering, technology, education, manufacturing, retail, finance, and energy. Revenue in 2025 was $4.3 billion. Learn more at kellyservices.com.

KLYA-FIN

ANALYST & MEDIA CONTACT:
Scott Thomas
(248) 251-7264
[email protected]

View full release here.