Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
New Deal. Hot on the heels of the Maronda Homes announcement, SKYX Platforms revealed an agreement to supply 60,000 units of its smart home technologies for over 700 homes to be built by Home Creations. The units are expected to be provided over the next 12 months. We believe these are the first of many agreements to be awarded in the future for SKYX products in the home builder vertical.
Home Creations. Founded in 1981, Home Creations is a family-founded homebuilder serving Oklahoma and the Houston, Texas, market. Significantly, Home Creations combines energy-efficient construction with smart home features. The firm’s Oklahoma City homes are nearly 53% more energy-efficient than typical new homes and include Deako smart lighting, a smart thermostat, smart locks, and an app-enabled garage door. Every home is HERS-verified by a certified RESNET energy rater and backed by a 10-year structural warranty.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Drilling expands the gold zone. Resolution Minerals reported additional drill results from Golden Gate North at its 100%-owned Horse Heaven project in Idaho, confirming gold mineralization over an area measuring at least 500 meters along strike, 200 meters in width, and 300 meters in depth. The results expand the known mineralized footprint and strengthen the potential for a sizable near-surface gold system.
Broad mineralized intervals. Three newly reported drill holes intersected extensive gold mineralization beginning at the surface, including 324 meters grading 0.49 grams per tonne (g/t) gold and 322 meters grading 0.37 g/t gold. Although grades remain relatively modest, the continuity and scale of mineralization are encouraging and support further evaluation of potential bulk tonnage mineralization.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Robert LeBoyer, Senior Vice President, Equity Research Analyst, Biotechnology, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
New Data Presentation On Quality of Life and Symptoms. Eledon presented data from the Phase 2 BESTOW trial at the American Society of Nephrology Annual Kidney Week 2026 meeting. The presentation compared patients receiving tegoprubart with those receiving tacrolimus, showing improvements in quality of life and reductions in symptom burden at 12 months. We believe these findings support prior data on efficacy, safety, and tolerability.
Patient Evaluations. Data from two accepted clinical evaluations, MTSOSD-59R and KDQOL-SF, showed substantial, lasting improvements in quality of life and reductions in transplant-related side effects. We see these patient-reported outcomes as consistent with prior reductions in BPAR (Biopsy-Proven Acute Rejection), improvements in eGFR, and improvements in factors that contribute to long-term graft failure.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Mark Reichman, Managing Director, Equity Research Analyst, Natural Resources, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Third Quarter Financial Results. Alliance Resource Partners reported third-quarter 2026 revenue of $603.0 million, up 5.5% year-over-year and 9.3% sequentially. Net income attributable to ARLP increased 46.8% to $139.6 million, or $1.08 per unit, compared with $0.73 a year ago and $0.61 in the second quarter. Adjusted EBITDA attributable to ARLP increased 26.3% to $233.9 million, reflecting stronger coal operations and record oil and gas royalty contributions.
Operating Performance Strengthens. Coal sales increased 7.4% year-over-year to 9.35 million tons, supported by resumed production at Hamilton and strong performance at River View and Tunnel Ridge. Segment Adjusted EBITDA expense per ton decreased 13.1% to $35.64, contributing to an 18.6% increase in Coal Operations Segment Adjusted EBITDA to $186.8 million. The AllDale III and IV acquisition contributed to record oil and gas royalty production of 1.45 million barrels of oil equivalent, while attributable segment Adjusted EBITDA increased 61.4% to $43.6 million.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Additional cost savings identified. The company highlighted $50 million in annualized run-rate cost savings achieved ahead of schedule in fiscal 2026 and identified an additional $15 million to $20 million in potential annualized savings for fiscal 2027. We believe these initiatives could support a recovery in profitability, although the timing and extent of the EBITDA contribution remain uncertain.
Focus on financial flexibility. The company highlighted an amendment to its credit agreement that extends covenant relief and provides greater flexibility in using asset-sale proceeds. In addition, the company is evaluating financing alternatives, including potential debt or equity transactions and nonstrategic asset divestitures.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
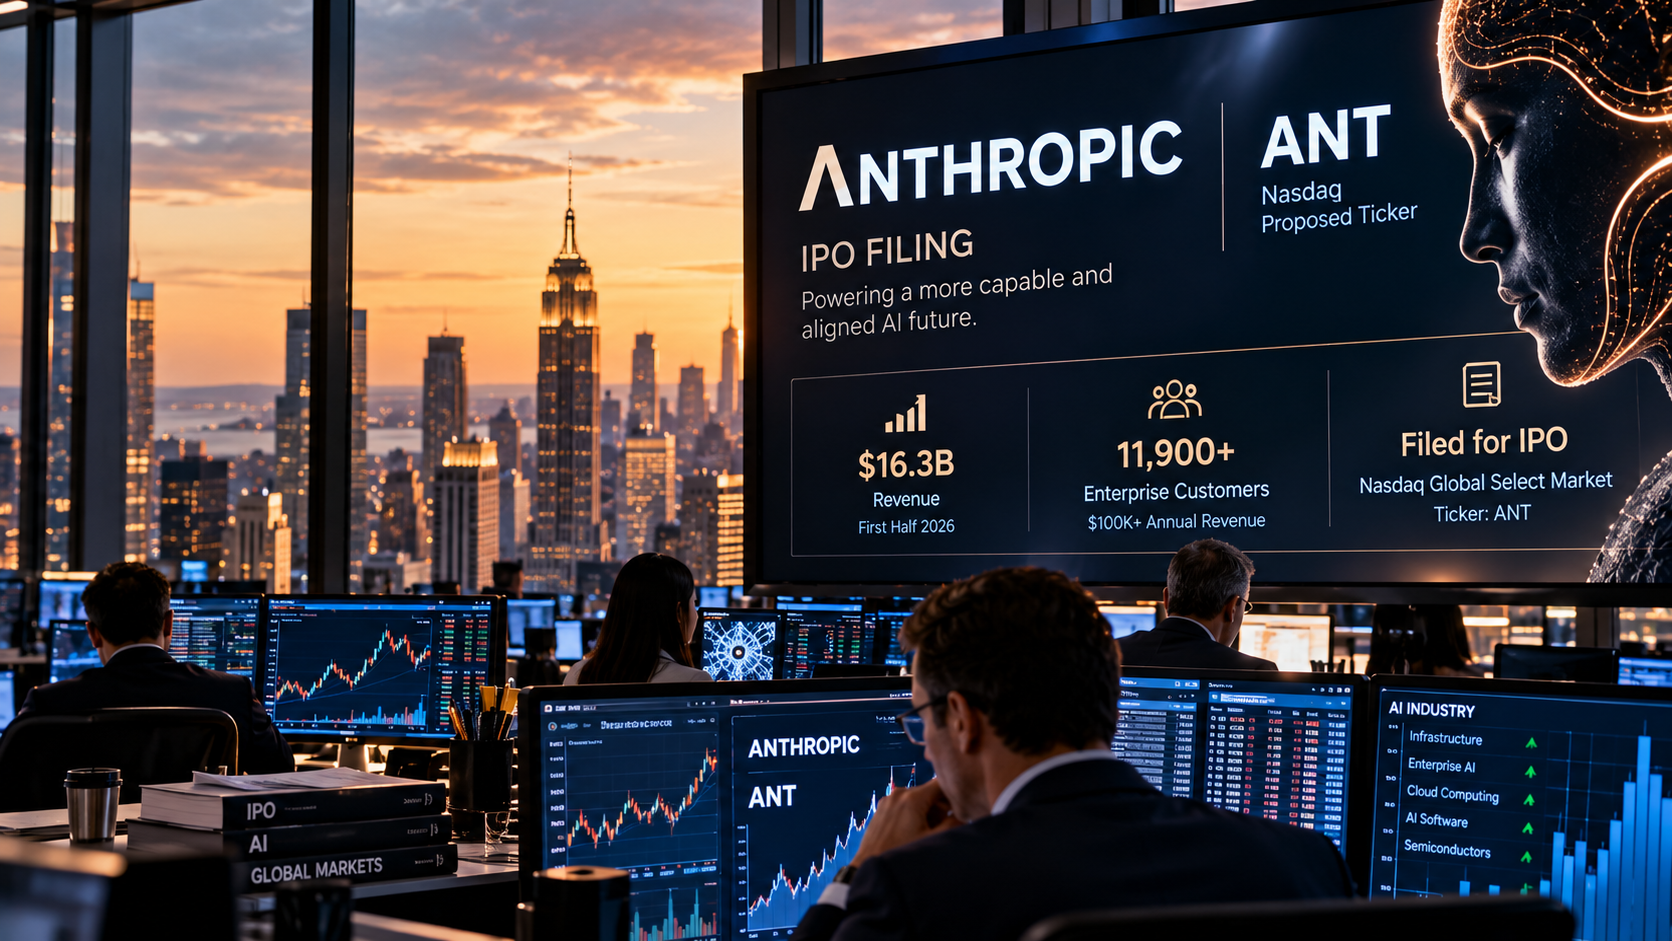
Anthropic, the artificial intelligence company behind the Claude chatbot, officially filed for an initial public offering on Monday, October 26, moving closer to what could become one of the largest stock market debuts in history. The highly anticipated filing provides investors with their most detailed look yet at the company’s explosive revenue growth, substantial financial commitments, and plans to compete in the rapidly expanding AI industry.
The company filed a Form S-1 registration statement with the Securities and Exchange Commission and intends to list its Class A common stock on the Nasdaq Global Select Market under the ticker symbol ANT. Goldman Sachs and Morgan Stanley are leading the offering, although the company has not yet disclosed its proposed share price, number of shares, or total fundraising target.
The filing revealed that Anthropic generated $16.3 billion in revenue during the first six months of 2026, compared with approximately $1.2 billion during the same period last year. That represents nearly fourteenfold growth, underscoring the accelerating demand for advanced AI models and enterprise applications.
Despite the rapid expansion, Anthropic reported a net loss of approximately $80.7 billion for the first half of 2026. Much of that figure reflects noncash accounting adjustments related to the changing value of convertible debt rather than direct operating expenses. Its operating loss was approximately $693 million, improving from roughly $2.1 billion a year earlier.
The financial disclosures highlight a central challenge facing the artificial intelligence industry: translating extraordinary revenue growth into sustainable profitability while funding increasingly expensive computing infrastructure.
Anthropic has committed substantial resources to cloud computing, data centers, and the advanced processors required to train and operate its AI models. These investments are essential to competing with companies such as OpenAI and Google, but they also create significant financial obligations.
Enterprise customers have become an important driver of Anthropic’s growth. As of September 30, the company reported more than 11,900 customers generating at least $100,000 in annual revenue, including approximately 1,900 customers spending more than $1 million annually.
The company has attracted significant backing from major technology companies, including Amazon and Google, which have invested billions of dollars while supporting its computing infrastructure needs.
Anthropic’s potential valuation has also attracted considerable attention. Recent reports indicate that some investors have discussed a valuation around $1.5 trillion, down from earlier expectations approaching $2 trillion. However, those figures remain market estimates rather than an officially announced IPO valuation.
The public offering comes during a period of heightened scrutiny surrounding artificial intelligence investments. Investors have increasingly questioned whether the industry’s enormous spending on computing capacity will generate sufficient returns, contributing to volatility across technology stocks.
For the broader equity market, Anthropic’s IPO could become an important test of investor appetite for high-growth technology companies. Its reception may influence how investors evaluate other AI businesses preparing to raise capital or enter public markets.
That impact could extend to smaller technology companies developing AI software, cybersecurity tools, enterprise automation platforms, and specialized applications. A successful offering could strengthen interest in the sector, while concerns about profitability and valuations could reinforce investor selectivity.
The filing also outlines a governance structure that would allow Anthropic’s seven co-founders to retain 50.1% of shareholder voting power, giving them significant influence over the company’s direction after its public debut.
Although Anthropic has not announced a final IPO date, reports suggest trading could begin in November, subject to regulatory review and market conditions.
For investors, the filing marks a defining moment in the commercialization of artificial intelligence. Anthropic’s financial results demonstrate enormous demand for AI technology, but its costs, governance structure, and potential valuation will be central considerations as Wall Street prepares for the company’s public debut.
Tegoprubart-treated patients demonstrated a mean improvement on the total MTSOSD-59R symptom occurrence scale at 12 months while tacrolimus-treated patients experienced a mean worsening of symptom occurrence
Statistically significant improvement on the KDQOL-SF Symptoms and Problems Scale among tegoprubart-treated patients through 12 months following kidney transplantation versus tacrolimus
Results further validate the differentiated clinical profile of tegoprubart and potential to transform standard of care in kidney transplantation
IRVINE, Calif., Oct. 26, 2026 (GLOBE NEWSWIRE) — Eledon Pharmaceuticals, Inc. (“Eledon”) (Nasdaq: ELDN) today announced new positive patient-reported outcomes data from the Phase 2 BESTOW clinical trial of tegoprubart, its novel investigational immunosuppression therapy. The data showed significant, sustained improvements in health-related quality of life and symptom burden through 12 months compared with standard of care tacrolimus following kidney transplantation. The results were featured in an oral presentation at the American Society of Nephrology (ASN) Kidney Week 2026 Annual Meeting held October 21-25, 2026, in Denver, Colorado.
“The patient-reported outcomes presented at ASN Kidney Week provide perhaps the clearest picture yet of what tegoprubart’s differentiated profile means for transplant patients in everyday life,” said David-Alexandre C. Gros, M.D., Chief Executive Officer of Eledon. “We previously reported encouraging BESTOW results across efficacy, kidney function and safety measures, which alone strengthened our belief in tegoprubart. The additional findings presented demonstrate that these clinical outcomes were accompanied by substantial and importantly sustained improvements in quality of life and reductions in transplant-related symptom burden. Giving transplant patients an effective, safer and more tolerable alternative to tacrolimus addresses one of the most important unmet needs in organ transplantation, and collectively, these data further support the potential of tegoprubart to become a transformative new treatment option for kidney transplant recipients.”
“Success after kidney transplantation is measured not only by preventing rejection and preserving graft function, but also by how patients feel and function in their everyday lives,” said presenting author Andrew Adams, M.D., Ph.D., Professor of Surgery and Chief, Division of Transplantation, John S. Najarian Surgical Chair in Clinical Transplantation, Department of Surgery, University of Minnesota. “What is particularly compelling about these BESTOW results is the consistency of the patient-reported benefits when treated with tegoprubart compared with tacrolimus following kidney transplant. We observed broad improvements in quality-of-life measures together with remarkably favorable outcomes in transplant-specific symptom reporting. The extent of separation between treatment groups suggests patients receiving tegoprubart may experience meaningful quality of life advantages while maintaining strong clinical outcomes as previously reported from BESTOW.”
Patient-Reported Outcomes Results
Patient-reported outcomes were assessed using the Modified Transplant Symptom Occurrence and Symptom Distress Scale (MTSOSD-59R) and the Kidney Disease Quality of Life Short Form (KDQOL-SF) Symptoms and Problems Scale, both validated measures of symptom burden. Baseline scores were similar between treatment groups. Collectively, the consistency of findings across both the KDQOL-SF and MTSOSD-59R assessments suggests that reductions in transplant-related symptom burden with tegoprubart may contribute to the improvements observed in patient-reported quality of life and further supports the differentiated clinical profile of tegoprubart compared to tacrolimus observed in the Phase 2 BESTOW clinical trial.
On the MTSOSD-59R assessment, tegoprubart-treated patients reported continued reductions in symptom occurrence from baseline at Months 6 and 12, whereas symptom occurrence in the tacrolimus arm initially declined through Month 6 before returning to slightly above baseline levels at Month 12.
CI, confidence interval; KDQOL-SF, Kidney Disease Quality of Life Short Form; MTSOSD-59R, Modified Transplant Symptom Occurrence Scale- 59 Items Revised; SEM, standard error of the mean; tac, tacrolimus; tego, tegoprubart.
Tegoprubart demonstrated greater symptom improvement than tacrolimus in 22 of 23 domains where differential improvement was observed, including neurological, gastrointestinal, metabolic, and physical symptom categories. In addition, tacrolimus demonstrated greater symptom worsening in 22 of 22 domains where differential symptom worsening was observed.
On the KDQOL-SF assessment, kidney transplant patients treated with tegoprubart demonstrated improvements from baseline across all five subscales through Month 12. In the KDQOL-SF scale, a change of 3-5 points can be considered clinically significant, and tegoprubart was thus associated with a clinically and statistically significant improvement in the symptoms and problems subscale compared with tacrolimus at Month 12, with mean changes from baseline of 9.0 and 3.3 points, respectively (p<0.05). Consistent with these findings, the SF-12 mental component summary score increased by 1.5 points in the tegoprubart arm compared to a decline of 1.6 points in the tacrolimus arm, representing a 3.1-point between-group difference.
a Higher scores indicate better HRQoL; a change of 3–5 points can be considered clinically significant1. Baseline values were similar across all outcomes. *p < 0.05. HRQoL, health-related quality of life; KDQOL-SF, Kidney Disease Quality of Life Short-Form instrument; SEM, standard error of the mean; SF-12, 12-item short-form survey; tac, tacrolimus; tego, tegoprubart.1. KDOQI. Am J Kidney Dis 2007;50:471–530.
Details of the oral presentation at ASN Kidney Week 2026 are below:
Title: Patient-Reported Outcomes in the Phase 2 BESTOW Trial Comparing Tegoprubart to Tacrolimus in Kidney Transplant Recipients Presenter: Andrew B. Adams, M.D., Ph.D., Department of Surgery, University of Minnesota Medical School; Minneapolis, Minnesota Abstract Publication Number: FR-OR084 Session Title: The Changing Landscape of Kidney Transplantation: Clinical Innovation, Outcomes, and Healthy Policy Session Date and Time: Friday, October 23, 2026, from 4:30 p.m. to 6:00 p.m. MDT Session Room: Mile High Ballroom 4A (Convention Center) Presentation Time: 4:40 p.m. to 4:50 p.m. MDT
About Eledon Pharmaceuticals and tegoprubart
Eledon Pharmaceuticals, Inc. is a clinical stage biotechnology company that is developing immune-modulating therapies for the management and treatment of life-threatening conditions. The Company’s lead investigational product is tegoprubart, an anti-CD40L antibody with high affinity for the CD40 Ligand, a well-validated biological target that has broad therapeutic potential. The central role of CD40L signaling in both adaptive and innate immune cell activation and function positions it as an attractive target for non-lymphocyte depleting, immunomodulatory therapeutic intervention. The Company is building upon a deep historical knowledge of anti-CD40L biology to conduct preclinical and clinical studies in kidney allograft transplantation, xenotransplantation, islet cell transplantation, liver transplantation and amyotrophic lateral sclerosis (ALS). Eledon is headquartered in Irvine, California. For more information, please visit the Company’s website at www.eledon.com.
Follow Eledon Pharmaceuticals on social media: LinkedIn; X
Forward-Looking Statements
This press release contains forward-looking statements that involve substantial risks and uncertainties. Any statements about the company’s future expectations, plans and prospects, including statements about planned clinical trials, the development of product candidates, expected timing for initiation of future clinical trials, expected timing for receipt of data from clinical trials, as well as other statements containing the words “believes,” “anticipates,” “plans,” “expects,” “estimates,” “intends,” “predicts,” “projects,” “targets,” “looks forward,” “could,” “may,” and similar expressions, constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Specifically, our ability to achieve our anticipated future development and corporate milestones depends on our ability to obtain additional financing on acceptable terms. Forward-looking statements are inherently uncertain and are subject to numerous risks and uncertainties, including: our short operating history and shifts in our business strategy; our operating losses since inception; our need for additional funding to develop our lead drug candidate and our ability to secure additional funding on acceptable terms or at all; the impact of issuances of our common stock, including in the possibility of dilution or a decline in our stock price; our ability to successfully develop our product candidates; unfavorable global economic and financial market conditions; the regulatory environment of our business and our ability to obtain required regulatory approvals; results of non-clinical studies and clinical trials, and risks that non-clinical studies or early clinical trials may not be predictive of results of later-stage clinical trials; delays or difficulties in enrollment of patients in clinical trials; our ability to attract and retain our executives and key employees; legislation of the pharmaceutical and healthcare industries; cybersecurity and data privacy risks; the ability of our products to achieve marketing approval; competition in our industry; our ability to obtain insurance coverage; our dependence on contract research organizations; our ability to protect our intellectual property; public health crises; our ability to maintain proper and effective internal control over financial reporting and other risks disclosed in our Annual Report on Form 10-K for the year ended December 31, 2025, filed with the Securities and Exchange Commission on March 19, 2026. Actual results may differ materially from those indicated by such forward-looking statements as a result of various factors. These risks and uncertainties, as well as other risks and uncertainties that could cause the company’s actual results to differ materially from the forward-looking statements contained herein, are discussed in our Annual 10-K, and other filings with the U.S. Securities and Exchange Commission, which can be found at www.sec.gov. Any forward-looking statements contained in this press release speak only as of the date hereof and not of any future date, and the company expressly disclaims any intent to update any forward-looking statements, whether as a result of new information, future events or otherwise.
OLD GREENWICH, Conn., Oct. 26, 2026 (GLOBE NEWSWIRE) — Star Equity Holdings, Inc. (Nasdaq: STRR and STRRP) (“Star” or the “Company”), a diversified holding company, announced today that its wholly owned Alliance Drilling Tools (“ADT”) business, part of the Company’s Energy Services division, has expanded its customer support capabilities in the Rocky Mountain region through an affiliate’s acquisition of a privately held Vernal, Utah-based machine shop that provides repair, rebuild, and machining services for well fishing tools, drill pipe, and other drilling equipment. The transaction closed on October 23, 2026, and the shop will work alongside ADT’s existing Vernal operation.
The acquisition serves a critical energy services niche in the region, helping customers reduce downtime and improve rig productivity by getting essential equipment back in service quickly. The business operates from an approximately 6,300-square-foot facility on two acres located minutes from ADT’s existing Vernal operation.
Adding these in-house capabilities makes ADT’s Vernal operation a full-service location. With geographically centralized tool rental, machining, repair, and rebuild services, ADT can support customers across more of the tool life cycle while gaining more direct control over service quality and turnaround time. The expanded capabilities also position ADT to more actively pursue oil and gas drilling work in the Uinta Basin, as well as mining and geothermal opportunities across the region.
Jeff Eberwein, CEO of Star, commented, “Expanding our Energy Services division’s capabilities is a key part of our strategy to grow, and adding in-house machining in Vernal is a natural next step in that effort. With Star’s financial support and ADT’s customer base, operating platform, and equipment, we believe the Vernal shop can add capacity, take on more work, and build on its established customer relationships. We expect this addition to create long-term value for Star’s shareholders.”
Ryan Thomas, President of ADT, added, “Having our own machine shop in Vernal lets us respond faster, rely less on outside machining, and offer customers a true one-stop shop in the Uinta Basin. We have relied on this shop for our machining needs in Vernal for more than a decade, and its people are a terrific culture fit. We are excited to welcome the team.”
About Star Equity Holdings, Inc.
Star Equity Holdings, Inc. is a diversified holding company that seeks to build long-term shareholder value by acquiring, managing, and growing businesses with strong fundamentals and market opportunities. Its current structure comprises four divisions: Building Solutions, Business Services, Energy Services, and Investments. For more information, visit www.starequity.com.
Building Solutions
The Building Solutions division operates in three specialties: (i) modular building manufacturing; (ii) structural wall panel and wood foundation manufacturing, including building supply distribution operations; and (iii) glue-laminated timber (glulam) column, beam, and truss manufacturing.
Business Services
The Business Services division provides flexible and scalable recruitment solutions to a global clientele, servicing organizations at all levels, from entry-level positions to the C-suite. The division focuses on mid-market and enterprise organizations worldwide, partnering consultatively with talent acquisition, HR, and procurement leaders to build diverse, high-impact teams and drive business success.
Energy Services
The Energy Services division engages in the rental, sale, and repair of downhole tools used in the oil and gas, geothermal, mining, and water-well industries.
Investments The Investments division manages and finances the Company’s real estate assets as well as its investment positions in private and public companies.
Forward-Looking Statements This press release contains statements that the Company believes to be “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, Section 21E of the Securities Exchange Act of 1934, as amended, and the Private Securities Litigation Reform Act of 1995. All statements other than statements of historical fact included in this press release, including statements regarding the Company’s future financial condition, results of operations, business operations, and business prospects, are forward-looking statements. Words such as “anticipate,” “estimate,” “expect,” “project,” “intend,” “plan,” “predict,” “believe,” and similar words, expressions, and variations of these words and expressions are intended to identify forward-looking statements. All forward-looking statements are subject to important factors, risks, uncertainties, and assumptions, including industry and economic conditions, that could cause actual results to differ materially from those described in the forward-looking statements. Such factors, risks, uncertainties, and assumptions include, but are not limited to, (1) global economic fluctuations, (2) changes in the cost and availability of commodities, materials, and equipment, (3) risks related to providing uninterrupted service to clients, (4) the ability of clients to terminate their relationship with the Company at any time, (5) risks associated with real estate ownership, (6) the Company’s ability to successfully achieve its strategic initiatives, (7) risks related to fluctuations in the Company’s operating results from quarter to quarter, (8) risks related to potential acquisitions or dispositions of businesses by the Company, (9) our profitability and growth being tied to the success of our operating businesses, (10) risks associated with our financial investments in other businesses, (11) our ability to improve existing products and services and develop, introduce, and market new products and services successfully, (12) the loss of or material reduction in our business with any of the Company’s largest customers, (13) competition in the Company’s markets, (14) risks related to potential decreases in demand for products, (15) our ability to maintain costs at an acceptable level, (16) the negative cash flows and operating losses that may recur in the future, (17) risks related to international operations, including foreign currency fluctuations, political events, trade wars, natural disasters or health crises, including the Russia-Ukraine war, and potential conflict in the Middle East, (18) risks relating to how future credit facilities may affect or restrict our operating flexibility, (19) our ability to generate or borrow sufficient cash to make payments on our indebtedness, (20) risks related to indebtedness, (21) risks associated with the Company’s investment strategy, (22) the Company’s dependence on key management personnel, (23) the Company’s ability to attract and retain highly skilled professionals, management, and advisors, (24) the Company’s ability to collect accounts receivable, (25) the Company’s exposure to legal proceedings, investigations, and disputes, and limits on related insurance coverage, (26) the Company’s ability to utilize net operating loss carryforwards, (27) the potential for goodwill impairment, (28) volatility of the Company’s stock price, (29) risks related to our historically low trading volume, (30) risks related to securities or industry analysts, (31) the Company’s ability to declare dividends, (32) risks associated with failure to pay dividends on our Series A Preferred Stock, (33) our history of annual net losses, (34) risks related to our international operations, (35) risks related to compliance with federal and state laws, regulations, and other rules, (36) our exposure to employment-related claims, legal liability, and costs from clients, employees, and regulatory authorities, (37) risks related to the imposition of licensing or tax requirements or new regulations, (38) the effect of anti-takeover provisions in our organizational documents, (39) the effect of the protective amendment contained in our Restated Certificate of Incorporation, (40) the impact of our stockholder rights plan, or “poison pill,” on stockholder decision making, (41) risks related to our scaled disclosure requirements as a smaller reporting company, (42) the heavy reliance on information systems and the impact of potentially losing or failing to develop technology, (43) the adverse impacts of cybersecurity threats and attacks, (44) risks related to the use of new and evolving technologies, and (45) those risks set forth in “Risk Factors” in the Company’s Annual Report on Form 10-K for the year ended December 31, 2025. The foregoing list should not be construed to be exhaustive. Actual results could differ materially from the forward-looking statements contained in this press release. In view of these uncertainties, you should not place undue reliance on any forward-looking statements, which are based on our current expectations. These forward-looking statements speak only as of the date of this press release. The Company assumes no obligation, and expressly disclaims any obligation, to update any forward-looking statements, whether as a result of new information, future events, or otherwise.
Eledon Pharmaceuticals (NASDAQ: ELDN) announced new positive Phase 2 clinical trial results Monday showing that its investigational kidney transplant therapy, tegoprubart, delivered sustained improvements in patient-reported quality of life and transplant-related symptoms compared with tacrolimus, a commonly used immunosuppressive treatment.
The findings, presented at the American Society of Nephrology’s Kidney Week 2026 meeting in Denver, add to previously reported results from Eledon’s Phase 2 BESTOW trial and highlight the potential for a new approach to managing immune suppression following kidney transplantation.
Kidney transplant recipients typically require lifelong immunosuppressive medications to prevent their immune systems from rejecting donated organs. Although existing treatments have significantly improved transplant outcomes, they can produce side effects that affect patients’ daily lives and long-term health.
Eledon’s tegoprubart is designed to address this challenge by targeting CD40 ligand, a protein involved in activating immune responses. Unlike traditional immunosuppressive therapies, the investigational antibody aims to regulate immune activity through a different biological pathway.
The latest BESTOW findings focused on patient-reported outcomes, including physical symptoms, emotional well-being, and overall quality of life during the first year following transplantation.
Researchers evaluated patients using two established assessment tools: the Modified Transplant Symptom Occurrence and Symptom Distress Scale and the Kidney Disease Quality of Life Short Form.
At 12 months, patients receiving tegoprubart demonstrated continued improvements in overall symptom occurrence, while patients treated with tacrolimus experienced a slight worsening compared with their baseline measurements.
Tegoprubart also showed greater symptom improvement in 22 of 23 categories where differences between the treatment groups were observed. These included neurological, gastrointestinal, metabolic, and physical symptoms.
One of the most notable findings involved the Kidney Disease Quality of Life assessment. Patients receiving tegoprubart reported an average nine-point improvement on the Symptoms and Problems Scale, compared with a 3.3-point improvement among patients receiving tacrolimus.
The difference was statistically significant, with Eledon noting that a change of three to five points on the scale can be considered clinically meaningful.
Additional findings suggested potential benefits for mental well-being. Patients treated with tegoprubart experienced a 1.5-point improvement in the mental component summary score, compared with a 1.6-point decline in the tacrolimus group.
The findings suggest that tegoprubart’s potential benefits may extend beyond preventing organ rejection to improving how transplant recipients feel and function in everyday life.
For Eledon, the results provide additional evidence supporting the differentiated clinical profile of its lead drug candidate. Previous BESTOW findings addressed measures of efficacy, kidney function, and safety, while the newly presented data provide further insight into the patient experience.
The development is relevant to investors because kidney transplantation represents a specialized therapeutic market in which effective treatments that reduce medication-related complications could address an important unmet medical need.
However, tegoprubart remains investigational and has not received regulatory approval. Additional clinical development and regulatory review will be necessary before its potential commercial use can be established.
Eledon is also exploring the broader applications of its anti-CD40L technology across other transplantation settings and immune-related conditions, including islet cell transplantation, liver transplantation, and amyotrophic lateral sclerosis.
The latest results underscore growing interest in developing more targeted immunosuppressive treatments that balance the prevention of organ rejection with patients’ long-term quality of life.
For small-cap biotechnology investors, Eledon’s findings represent another clinical development milestone as the company works to advance tegoprubart and demonstrate its potential as an alternative to existing kidney transplant therapies.
Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.
Richard Magnusen, Research Analyst, Noble Capital Markets, Inc.
Refer to the full report for the price target, fundamental analysis, and rating.
Initiating coverage with an Outperform rating. We believe Cosmos Health is positioned for a meaningful improvement in profitability as its revenue mix shifts toward higher-margin proprietary healthcare products and pharmaceutical manufacturing. The company’s established wholesale distribution business provides a revenue base, while its expanding U.S. direct-to-consumer operations could become an increasingly important driver of earnings growth.
U.S. direct-to-consumer sales are gaining momentum. Management expects approximately $15 million in fourth-quarter 2026 U.S. e-commerce revenue and $10.5 million in gross profit, reflecting the rapid expansion of its proprietary nutraceutical business. Active U.S. subscriptions reached 8,940 as of October 19, although customer retention and marketing efficiency remain important considerations as the business scales.
Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.
This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).
*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision.
Roche is expanding its oncology pipeline through a licensing agreement with Zymeworks (NASDAQ: ZYME) valued at up to $813 million, highlighting continued interest from major pharmaceutical companies in experimental cancer treatments developed by smaller biotechnology firms.
The agreement, announced October 23, 2026, gives Swiss pharmaceutical giant Roche exclusive worldwide rights to develop and commercialize ZW209, an investigational therapy designed to treat certain cancers, including small-cell lung cancer.
Under the agreement, Zymeworks will receive an upfront payment of $55 million, followed by an additional $40 million if Roche initiates a planned Phase 1b clinical trial. The biotechnology company could also receive up to $718 million in development, commercial, and sales-related milestone payments, along with royalties on future sales of approved treatments.
The full $813 million value is contingent on achieving specified milestones and does not represent guaranteed revenue.
ZW209 belongs to an emerging class of cancer therapies known as trispecific T-cell engagers. These treatments are designed to help the immune system recognize and attack cancer cells by connecting immune cells with specific targets found on tumors.
The experimental drug targets DLL3, a protein frequently expressed in small-cell lung cancer and certain other neuroendocrine tumors but generally found at low levels in healthy tissue.
ZW209 is designed to engage DLL3 while simultaneously interacting with two proteins on immune cells, CD3 and CD28. This approach aims to stimulate an immune response against cancer cells while potentially improving the effectiveness and durability of treatment.
The drug remains in early clinical development, and its safety and effectiveness in patients have not yet been established.
Zymeworks will conduct the Phase 1a portion of the clinical program in collaboration with Roche, which will fund the study. Roche will subsequently assume responsibility for global development and commercialization.
The first patient is expected to enter the study before the end of 2026, according to Zymeworks management.
For investors, the transaction illustrates an important strategy in the biotechnology industry: smaller drug developers can use licensing agreements to secure funding and share clinical development risks while retaining opportunities for future milestone payments and royalties.
These partnerships can be particularly valuable for emerging biotechnology companies, where clinical trials require substantial investment and successful commercialization often depends on extensive manufacturing, regulatory, and distribution capabilities.
Roche’s decision to partner on ZW209 before human efficacy data are available also underscores the importance pharmaceutical companies place on differentiated scientific platforms and promising early-stage research.
The agreement reflects broader interest in innovative oncology treatments, including immunotherapies and therapies designed to target specific biological mechanisms involved in cancer.
Within Noble Capital Markets’ research coverage universe, Greenwich LifeSciences (NASDAQ: GLSI) is developing an investigational immunotherapy for breast cancer, while Cardiff Oncology (NASDAQ: CRDF) is advancing onvansertib, an experimental cancer treatment targeting the PLK1 enzyme. Although their technologies differ from ZW209, these companies illustrate the range of oncology approaches being pursued by emerging biotechnology developers. Neither company is involved in the Roche-Zymeworks agreement.
The transaction also highlights the potential financial importance of early-stage biotechnology partnerships. Rather than acquiring entire companies, larger pharmaceutical businesses can license individual drug candidates, gaining access to promising technologies while limiting their initial financial commitments.
However, significant risks remain. Experimental cancer treatments face lengthy clinical trials, regulatory scrutiny, and uncertainty surrounding patient outcomes. Milestone payments depend on future progress, and many investigational therapies never reach commercialization.
The Roche-Zymeworks agreement remains subject to customary closing conditions, including applicable antitrust clearance.
For small-cap biotechnology investors, the deal provides another example of how innovative drug-development platforms can attract major pharmaceutical partners. As competition for differentiated cancer treatments continues, licensing agreements may remain an important source of funding and strategic validation for emerging biotech companies.
Conduent Incorporated (Nasdaq: CNDT) (“Conduent” or the “Company”), a global technology-enabled operating partner, today announced the successful closing of a comprehensive $447 million refinancing transaction. The transaction extends the Company’s $357 million revolving credit facility through May 2029 and adds $90 million in additional commitments from its existing bank lenders, including a $15 million letter of credit facility, reflecting confidence in the Company’s strategy. Together with the Company’s recent and announced divestitures, including the use of proceeds to repay debt, these actions advance Conduent’s strategy to delever and de-risk its business and create greater flexibility to execute ASCEND 2026–28, the Company’s strategic plan outlined at its recent Investor Day.
The transaction establishes new revolving credit facilities with a group of existing bank lenders and rolls certain commitments under the existing revolver into the new facilities, extending maturities from October 2026 and May 2028 to May 2029.
The transaction builds on Conduent’s recently completed sale of its Public Transit business and the announced sale of its Tolling business. Together, these portfolio actions and the refinancing are expected to reduce the Company’s surety bond and letter-of-credit portfolio by approximately $550 million upon completion of the announced Tolling sale, significantly reducing financial encumbrances and releasing capital currently supporting those instruments.
With maturities extended to 2029, Conduent can continue investing in its core businesses and executing ASCEND 2026–28, the Company’s plan to accelerate profitable growth by standardizing its operations, specializing in the core solutions where it can lead and win, and scaling its go-to-market capabilities. The Company’s government and commercial programs, which millions of people rely on every day, continue without interruption.
“Deleveraging and de-risking are important priorities as we advance ASCEND 2026–28. We’ve extended our maturities, secured additional commitments from our banking partners and used divestiture proceeds to repay debt. Together with a meaningful reduction in our surety bond and letter-of-credit requirements, these actions strengthen our financial foundation and give us greater flexibility to invest in our core businesses and execute our strategy. They also support our mission to be the premier AI-led and technology-enabled business process partner for Government and Commercial clients, helping them modernize operations, enhance customer and constituent experiences, and achieve measurable business outcomes. Our banking partners’ commitment of new capital reflects their confidence in our strategy and our ability to execute ASCEND 2026–28,” said Harsha V. Agadi, Conduent President and Chief Executive Officer.
Lazard served as strategic advisor to Conduent.
About Conduent Conduent is a global technology-enabled operating partner that helps businesses and governments simplify complexity, modernize mission-critical operations and deliver measurable outcomes through AI, automation, data and human expertise. Learn more at www.conduent.com.
Forward-Looking Statements This press release may contain “forward-looking statements” as defined in the Private Securities Litigation Reform Act of 1995, as amended. The words “anticipate,” “believe,” “estimate,” “expect,” “plan,” “intend,” “will,” “aim,” “should,” “could,” “forecast,” “target,” “may,” “continue to,” “endeavor,” “if,” “growing,” “projected,” “potential,” “likely,” “see,” “ahead,” “further,” “going forward,” “on the horizon,” and similar expressions (including the negative and plural forms of such words and phrases), as they relate to us, are intended to identify forward-looking statements, but the absence of these words does not mean that a statement is not forward-looking. These statements include, but may not be limited to, statements regarding the Company’s Public Transit and Tolling business sales and our ability to meet the requirements and obligations under the new revolving credit facilities entered into in connection with the Transaction. These statements reflect our current views with respect to future events and are subject to certain risks, uncertainties and assumptions, many of which are outside of our control, that could cause actual results to differ materially from those expected or implied by such forward-looking statements contained in this press release, any exhibits to this press release and other public statements we make. Important factors and uncertainties that could cause our actual results to differ materially from those in our forward-looking statements include, but are not limited to: our significant indebtedness and the terms of such indebtedness; our ability to refinance, extend or replace our indebtedness on acceptable terms or at all; our failure to obtain or maintain a satisfactory credit rating and financial performance; and other factors that are set forth in the “Risk Factors” and other sections of our Annual Report on Form 10-K, as well as in our Quarterly Reports on Form 10-Q and Current Reports on Form 8-K filed with or furnished to the Securities and Exchange Commission. Any forward-looking statements made by us in this press release speak only as of the date on which they are made. We are under no obligation to, and expressly disclaim any obligation to, update or alter our forward-looking statements, whether because of new information, subsequent events or otherwise, except as required by law.
Trademarks Conduent is a trademark of Conduent Incorporated in the United States and/or other countries. Other names may be trademarks of their respective owners.
LAKE ZURICH, Ill.–(BUSINESS WIRE)– ACCO Brands Corporation (NYSE: ACCO) today announced that its board of directors has declared a quarterly cash dividend of $0.075 per share. The dividend will be paid on December 9, 2026, to stockholders of record as of the close of business on November 20, 2026.
About ACCO Brands Corporation ACCO Brands is the leader in branded consumer products that enable productivity, confidence and enjoyment while working, when learning and while playing. Our widely recognized brands include AT-A-GLANCE®, Five Star®, Kensington®, Leitz®, Mead®, PowerA®, Swingline®, Tilibra® and many others. More information about ACCO Brands Corporation (NYSE: ACCO) can be found at www.accobrands.com.