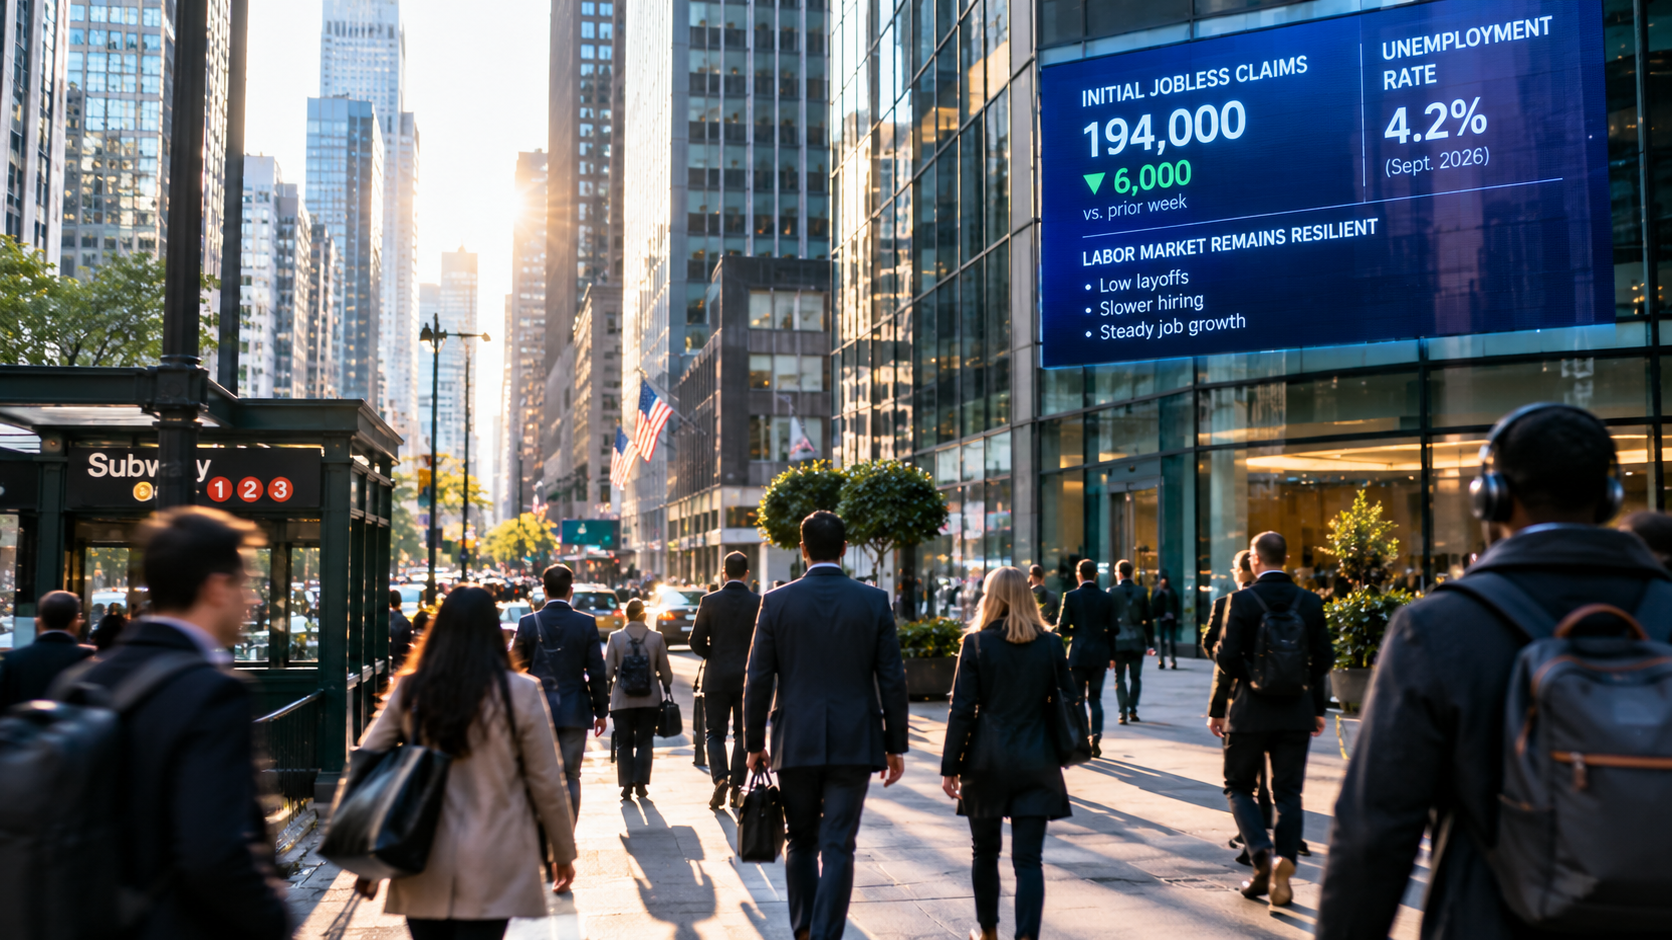
New applications for unemployment benefits in the United States fell to one of their lowest levels in nearly six decades, offering fresh evidence that American businesses are holding onto workers despite slower hiring, elevated borrowing costs, and persistent inflation concerns.
According to data released Thursday by the Labor Department, initial jobless claims declined by 6,000 to a seasonally adjusted 194,000 for the week ending October 17. The figure came in below economists’ expectations of 200,000 and marked the sixth consecutive week that claims remained at or below that level.
The latest reading approaches the 189,000 claims recorded in July, the lowest level since 1969. The four-week moving average, which helps smooth weekly fluctuations, declined by 1,000 to 197,750, reinforcing signs that layoffs remain historically low.
The report provides a potentially reassuring signal for investors concerned about the strength of the U.S. economy. Despite higher energy prices, trade uncertainty, and elevated interest rates, employers have largely avoided widespread layoffs.
However, the labor market presents a more complicated picture beneath the headline numbers.
While businesses are retaining existing employees, many remain cautious about expanding their workforces. Economists have characterized the current environment as a “low-hire, low-fire” labor market, where job security remains relatively strong but opportunities for unemployed workers are more limited.
That distinction was evident in continuing unemployment claims, which measure the number of Americans receiving benefits after their initial week. Continuing claims increased by 25,000 to approximately 1.73 million for the week ending October 10.
The increase suggests that some unemployed Americans may be taking longer to find new positions, even as the overall pace of layoffs remains subdued.
Recent employment data further illustrates the uneven recovery in hiring. U.S. employers added just 29,000 jobs in September, following a stronger gain of 133,000 in August. The unemployment rate stood at 4.2%, indicating that the labor market remains relatively stable despite slower job creation.
For Wall Street, the latest unemployment figures arrive at a critical moment for Federal Reserve monetary policy.
The central bank raised its benchmark interest rate by a quarter percentage point in September, bringing the target range to 3.75%–4.00%. Policymakers continue balancing the need to contain inflation against the risk that restrictive borrowing costs could eventually weaken economic activity.
Higher energy prices linked to the conflict involving Iran have complicated that calculation by increasing inflationary pressure on businesses and consumers.
Historically low unemployment claims could give the Federal Reserve additional flexibility to maintain elevated interest rates while monitoring inflation. Economists generally expect policymakers to leave rates unchanged at their upcoming meeting, although another increase remains possible later this year.
The implications extend across financial markets. Interest-rate expectations influence Treasury yields, mortgage costs, corporate borrowing, and equity valuations, particularly among growth-oriented technology companies.
Small-cap companies can also be sensitive to changes in financing conditions because many rely more heavily on external capital to support expansion, research, and operations.
For investors, the latest report offers encouraging evidence that the U.S. economy continues to avoid widespread job losses. Nevertheless, the combination of limited hiring, persistent inflation risks, and higher borrowing costs leaves important questions about the sustainability of economic growth.
With the Federal Reserve’s next policy decision approaching, investors will closely monitor upcoming inflation and employment reports for clues about the direction of interest rates through the remainder of 2026.