Cencora to Acquire American Oncology Network for $2.4 Billion in Major Cancer Care Expansion

Cencora (NYSE: COR) has announced an agreement to acquire American Oncology Network (OTCQX: AONC) in a transaction valued at up to $2.4 billion, expanding the pharmaceutical distribution giant’s presence in community-based cancer care. The deal, announced October 21, 2026, will add a physician-led network of more than 350 oncology providers operating across 21 states to Cencora’s growing healthcare services platform.

The acquisition represents another significant step in Cencora’s strategy to expand beyond traditional pharmaceutical distribution and strengthen its relationships with healthcare providers. By integrating American Oncology Network’s clinical infrastructure and practice management capabilities, Cencora aims to support independent cancer specialists while improving patient access to advanced treatments.

Under the agreement, American Oncology Network is valued at $2.3 billion at closing, with an additional $100 million potentially payable through contingent value rights tied to specified conditions. Cencora already owns approximately 4% of the company and has agreed to acquire the remaining equity interests, subject to a potential ownership rollover by existing shareholders.

If eligible shareholders retain a combined 25% stake, Cencora expects to pay approximately $1.7 billion at closing to increase its ownership to 75%. The transaction remains subject to regulatory approvals, shareholder approval, and customary closing conditions.

Founded in 2018, American Oncology Network provides operational and administrative support to independent oncology practices, allowing physicians to concentrate on patient care. Its services include practice management, technology, and access to integrated healthcare resources designed to help smaller cancer treatment centers compete in an increasingly complex healthcare environment.

For Cencora, the acquisition expands its physician-led oncology management services organization into 12 additional states. The company expects the combination to create opportunities to strengthen cancer treatment delivery, expand practice support capabilities, and improve operational efficiency.

The transaction also highlights the growing importance of community oncology as cancer treatments become increasingly specialized and expensive. Independent oncology practices face mounting challenges involving reimbursement, drug procurement, technology investment, and administrative costs. Larger healthcare organizations are responding by building networks that provide centralized resources while allowing physicians to retain control over clinical decisions.

The expansion comes as biotechnology companies continue developing innovative cancer treatments that could eventually reach patients through community oncology practices. Companies such as Greenwich LifeSciences (NASDAQ: GLSI), which is developing an investigational immunotherapy for breast cancer, and MAIA Biotechnology (NYSE American: MAIA), which is advancing a telomere-targeting cancer treatment, illustrate the broader pipeline of emerging oncology therapies. Neither company is involved in the announced transaction.

For investors, the deal underscores how pharmaceutical distribution companies are seeking additional growth opportunities in specialized healthcare services. Expanding into oncology practice management could provide Cencora with deeper relationships across the cancer treatment market while supporting demand for pharmaceutical products and services.

Cencora expects the acquisition to contribute positively to adjusted diluted earnings per share beginning in the second year following completion. The company also raised its fiscal 2026 adjusted earnings outlook to at least $17.90 per share, reflecting strength in its U.S. Healthcare Solutions business.

The acquisition illustrates a broader shift toward integrated cancer care, where pharmaceutical distribution, clinical services, and healthcare technology increasingly operate within connected networks. As cancer treatments continue evolving, companies capable of supporting both drug delivery and community-based medical practices could play a larger role in shaping the future of oncology care.
Salesforce to Acquire Braze for $5.7 Billion as AI-Powered Marketing Competition Intensifies

The $47.50-per-share deal represents a 58% premium as Salesforce expands its customer engagement capabilities and strengthens its position in AI-driven enterprise software.

Salesforce (NYSE: CRM) has announced an agreement to acquire customer engagement platform Braze (NASDAQ: BRZE) for approximately $5.66 billion in enterprise value, marking another major investment in artificial intelligence and enterprise software. The all-cash transaction, announced October 20, offers Braze shareholders $47.50 per share, representing a roughly 58% premium to the company’s previous closing price of $30.04.

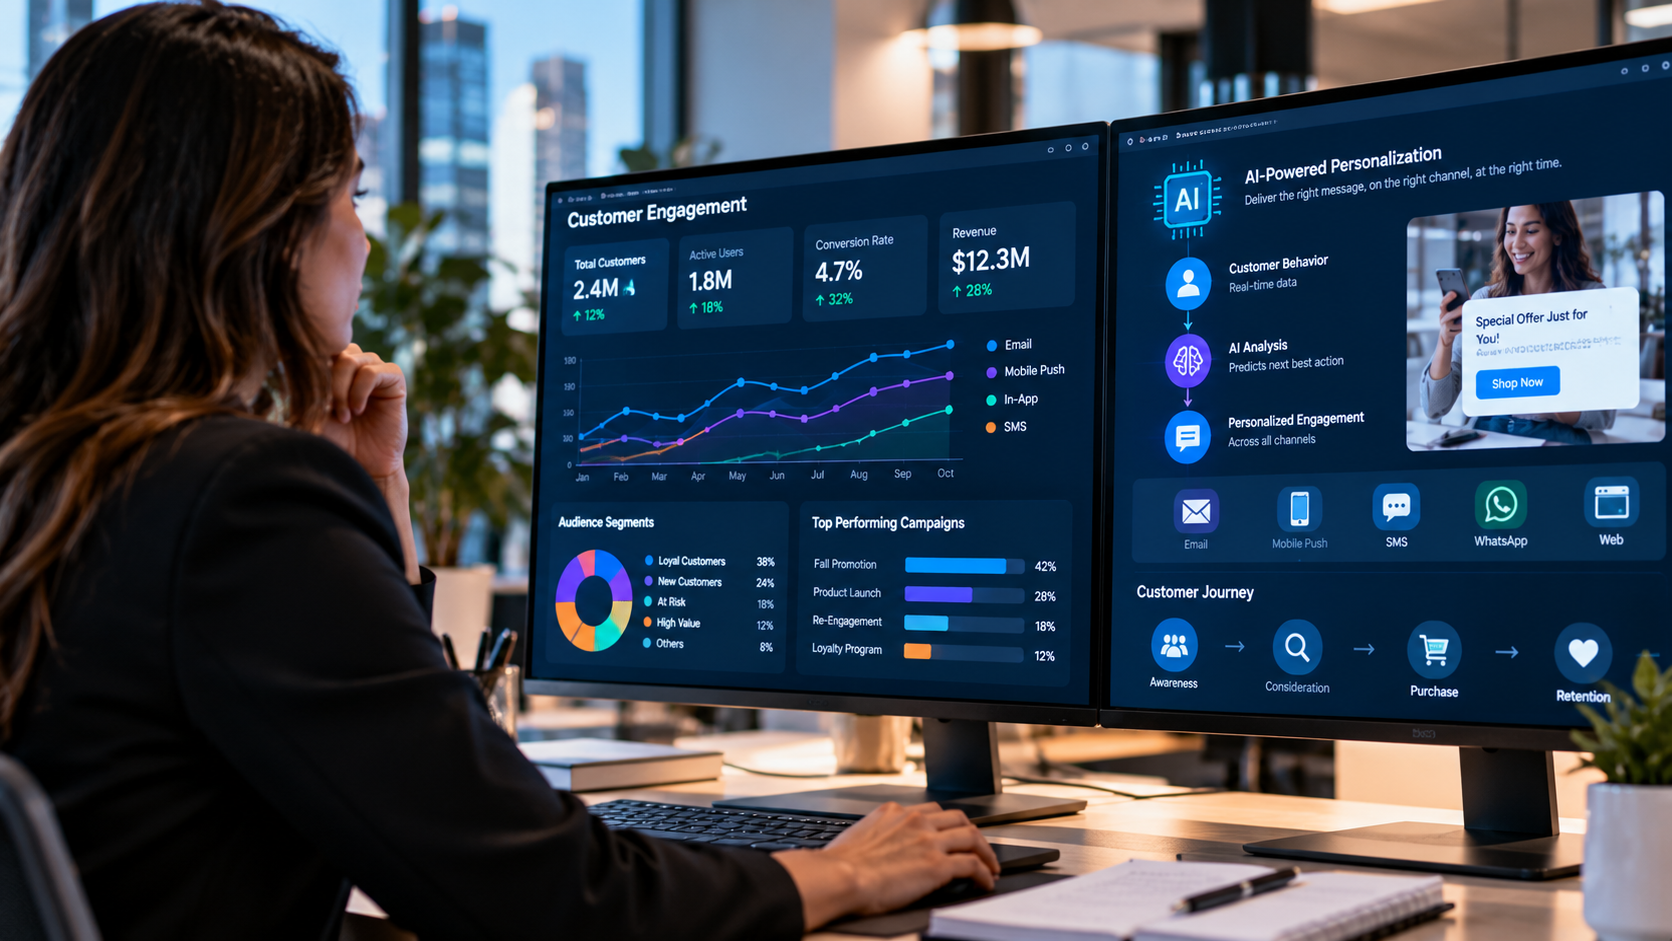
The acquisition is designed to strengthen Salesforce’s marketing technology capabilities by combining its customer relationship management platform with Braze’s real-time customer engagement tools. The deal reflects growing demand for AI-powered software that helps businesses personalize customer interactions, improve marketing efficiency, and increase customer retention.

Braze specializes in helping companies communicate with customers across multiple digital channels, including email, mobile applications, websites, text messaging, and WhatsApp. Its technology analyzes customer behavior and allows businesses to deliver personalized messages based on individual preferences, purchasing activity, and engagement patterns.

The company serves approximately 2,770 customers, including Canva, Instacart, Urban Outfitters, Venmo, and Equinox. Its AI-powered platform, BrazeAI, helps businesses determine the most effective content, communication channels, and timing for customer interactions.

For Salesforce, the acquisition represents an opportunity to expand its Marketing Cloud platform while integrating Braze’s capabilities with its broader artificial intelligence strategy. Salesforce has increasingly focused on developing autonomous AI agents through Agentforce, enabling businesses to automate customer service, sales, and marketing activities.

Combining these technologies could allow businesses to move beyond traditional marketing automation toward more intelligent systems capable of responding to customer behavior in real time. For example, an AI-powered platform could identify when a customer abandons an online purchase and automatically deliver a personalized offer through the most effective communication channel.

The transaction also highlights intensifying competition across the enterprise software industry as major technology providers race to incorporate artificial intelligence into their products. Companies are investing heavily in automation, predictive analytics, and customer data platforms to help businesses improve productivity and generate measurable returns from AI adoption.

Investor reaction reflected the significant premium attached to the acquisition. Braze shares surged approximately 51% in early trading following the announcement, while Salesforce shares declined around 2% as investors evaluated the purchase price and potential integration costs.

The acquisition values Braze at more than six times projected annual revenue, illustrating the substantial valuations being placed on software companies offering differentiated AI capabilities and recurring subscription revenue.

For investors, the transaction reinforces the strategic importance of customer data and personalized engagement as businesses increasingly adopt artificial intelligence. It also raises questions about whether larger software companies can successfully integrate acquired technologies while maintaining profitability and delivering meaningful returns on investment.

The deal is expected to close during Salesforce’s fiscal year 2028, subject to shareholder approval, regulatory clearance, and customary closing conditions. Salesforce indicated that the acquisition is not expected to change its fiscal 2027 financial guidance.

The $5.7 billion transaction underscores a broader shift in enterprise technology, where artificial intelligence is transforming how companies interact with customers. As competition intensifies, businesses offering advanced automation, real-time analytics, and AI-driven personalization could become increasingly attractive acquisition targets for larger technology companies seeking to expand their capabilities.

Big Pharma’s Patent Cliff Could Spark a New Wave of Small-Cap Biotech Acquisitions

Major pharmaceutical companies are approaching a significant patent cliff that could accelerate mergers and acquisitions across the biotechnology sector. With an estimated $300 billion to $400 billion in pharmaceutical revenue facing patent-related pressure beginning in 2028, large drugmakers are looking for ways to replenish their pipelines and offset potential losses from expiring blockbuster drug patents.

For small-cap biotechnology companies, this shift could create new opportunities through acquisitions, licensing agreements, and strategic partnerships. Companies developing innovative treatments in oncology, gene therapy, and immunology may benefit from increased industry interest as major pharmaceutical manufacturers search for their next generation of revenue-producing therapies.

What Is the Big Pharma Patent Cliff?

The pharmaceutical patent cliff refers to the expiration of patent protection or market exclusivity on major branded medications. Once these protections expire, generic drugs and biosimilars can enter the market, potentially reducing sales of previously protected products.

For pharmaceutical companies that rely heavily on blockbuster medications, the resulting revenue pressure can be substantial. Replacing that revenue often requires years of research, clinical development, and regulatory approvals.

As a result, major drugmakers may increasingly look beyond their internal research programs to acquire or partner with smaller biotechnology companies developing promising treatments.

Why Patent Expirations Could Drive Biotech Mergers and Acquisitions

Acquiring smaller biotechnology companies can provide large pharmaceutical manufacturers with access to innovative drug candidates, specialized technologies, and established clinical development programs.

Rather than developing every new treatment internally, pharmaceutical companies can pursue acquisitions, licensing agreements, or strategic partnerships to expand their pipelines.

Oncology, immunology, rare diseases, and other specialized therapeutic areas remain important areas of strategic interest.

For small-cap biotech companies, these relationships can provide access to capital and development resources. However, the potential for acquisition interest depends on factors such as clinical results, intellectual property protection, regulatory progress, and the strategic priorities of prospective partners.

Small-Cap Biotech Companies Advancing New Treatments

Several emerging biotechnology companies are developing treatments in therapeutic areas relevant to the pharmaceutical industry’s long-term growth strategies.

Cardiff Oncology (CRDF): Advancing Onvansertib for Colorectal Cancer

Cardiff Oncology (NASDAQ: CRDF) is developing onvansertib, a PLK1 inhibitor being studied in combination with standard therapies for metastatic colorectal cancer.

The company has reported encouraging Phase 2 clinical results and outlined plans for a registrational trial, subject to additional financing.

Cardiff Oncology’s development program illustrates the type of clinical-stage innovation occurring within the small-cap biotechnology sector, particularly in oncology, where companies continue to investigate new approaches to treating difficult cancers.

Ocugen (OCGN): Gene Therapy and Strategic Licensing Opportunities

Ocugen (NASDAQ: OCGN) is developing gene therapies targeting inherited retinal diseases.

The company has pursued regional licensing opportunities as part of its broader development strategy, demonstrating how smaller biotechnology firms can seek additional resources while retaining certain commercial rights.

Licensing agreements can provide an alternative to outright acquisitions, allowing pharmaceutical partners to access emerging technologies without assuming the full cost of developing or purchasing a company.

Eledon Pharmaceuticals (ELDN): Immunology and Kidney Transplant Research

Eledon Pharmaceuticals (NASDAQ: ELDN) is advancing treatments involving immune modulation, including tegoprubart, an investigational therapy being studied in kidney transplantation.

Its development program reflects ongoing innovation in immunology and transplantation, therapeutic areas where unmet medical needs continue to drive research.

Cardiff Oncology, Ocugen, and Eledon represent different approaches to drug development. Their inclusion illustrates the diversity of clinical-stage innovation within the small-cap biotechnology sector and does not imply that acquisition discussions involving these companies are underway.

What Should Small-Cap Biotech Investors Watch?

Although the pharmaceutical patent cliff may encourage additional dealmaking, acquisition potential alone should not determine how investors evaluate biotechnology companies.

Clinical progress remains a critical consideration, particularly for companies that have not yet generated meaningful commercial revenue.

Investors following the sector should pay attention to several developments:

  • Clinical trial results: Positive data can strengthen a company’s development outlook, while disappointing results can create significant setbacks.
  • Regulatory milestones: Progress toward pivotal trials and potential approvals can influence a company’s prospects.
  • Cash reserves and financing: Many clinical-stage biotechnology companies depend on external capital to fund research and development.
  • Intellectual property: Patent protection and other exclusivity rights can influence the commercial value of emerging therapies.
  • Licensing and partnership announcements: Strategic agreements may provide financing, development support, or commercial opportunities.

Investors should also distinguish between acquisitions and licensing arrangements. Pharmaceutical companies may choose partnerships that provide access to promising treatments without taking on the full financial and operational responsibilities of an acquisition.

Could the Patent Cliff Accelerate Biotech M&A Activity?

Following a slowdown in biotechnology dealmaking over the summer, industry observers anticipate renewed acquisition interest as pharmaceutical companies prepare for upcoming patent expirations.

For the small-cap biotechnology sector, increased dealmaking could have implications beyond individual takeover transactions.

Strategic acquisitions and partnerships may establish valuation benchmarks for emerging therapeutic platforms, create financing opportunities, and influence investor sentiment across the industry.

However, these potential benefits remain dependent on clinical success, market conditions, and the willingness of larger pharmaceutical companies to pursue transactions.

As major drugmakers prepare for substantial patent-related revenue pressure, smaller biotechnology companies developing innovative treatments could play an increasingly important role in the industry’s long-term growth strategy.

Scholastic to Acquire Children’s Publisher Cottage Door Press for $71 Million

Scholastic Corporation (Nasdaq: SCHL) announced Tuesday it has signed a definitive agreement to acquire Cottage Door Press, an independent publisher of early childhood books, for approximately $71 million before customary purchase price adjustments. The deal is expected to close by the end of 2026, pending shareholder approval from one of the sellers, third-party consents, new licensing agreements with certain key licensors, and the completion of a pre-closing separation of Cottage Door’s Luna StoryTime interactive toy line, which will be spun off and is not part of the transaction. Scholastic plans to fund the purchase with cash on hand and borrowings under its existing revolving credit facility.

Founded in 2014, Cottage Door Press has grown into the largest independent children’s publisher in the United States and one of the fastest-growing companies in the industry. It built its business around board books and novelty formats designed for interaction and discovery, an early childhood category Scholastic has identified as a key area for growth. Cottage Door generated approximately $45 million in net revenue and was solidly profitable over the twelve months ended May 31, 2026, implying a purchase price of roughly 1.6 times trailing revenue.

Scholastic executives framed the deal as a strategic fit that pairs Cottage Door’s product innovation and retailer relationships with Scholastic’s distribution scale, including its school-based book clubs and book fairs, classroom libraries, and retail and online channels reaching more than 135 countries. The publisher will operate inside Scholastic’s Children’s Book Group and is expected to keep its existing team and entrepreneurial structure intact following the close, rather than being folded entirely into Scholastic’s operations. Greenhill, a Mizuho affiliate, advised Cottage Door on the transaction.

Financially, Scholastic expects the deal to contribute to both revenue growth and adjusted EBITDA in fiscal 2027, and to become accretive, including anticipated synergies, in its second year following closing. Management pointed to further benefits over time as Cottage Door’s titles move through Scholastic’s broader distribution network and as manufacturing and operating efficiencies are realized.

For a company the size of Scholastic, a $71 million acquisition is a relatively contained bet, but it reflects a broader pattern playing out across consumer publishing and media right now: established players with strong distribution networks acquiring smaller, faster-growing, founder-led brands rather than attempting to build the same creative momentum internally. That dynamic is worth watching for investors tracking small and microcap consumer products and publishing companies more broadly. A profitable, founder-built niche publisher generating $45 million in revenue was able to command a meaningful acquisition premium by building genuine category leadership in a specific format, a reminder that scale is not the only path to an attractive exit in consumer media. Smaller companies with differentiated products, loyal retailer relationships, and disciplined profitability continue to be exactly the kind of targets larger, cash-generative acquirers are actively seeking out.

Xenetic Biosciences and Santersus Agree to All-Stock Combination to Create Nasdaq-Listed NET Therapeutics Company

Xenetic Biosciences (NASDAQ: XBIO) and privately held Santersus AG have entered into a definitive share exchange agreement that would combine the two biotechnology companies and create a Nasdaq-listed company focused on therapies targeting neutrophil extracellular traps, or NETs.

Under the agreement, Xenetic will acquire all outstanding shares of Santersus in exchange for newly issued Xenetic common stock. Following closing, Santersus shareholders are expected to own approximately 85% of the combined company, while existing Xenetic shareholders are expected to own approximately 15%. The combined company is expected to be renamed Santersus Bio, Inc. and trade on Nasdaq under the ticker SNTS.

Although Xenetic is technically the acquiring entity, the ownership and governance structure make the transaction more akin to a strategic combination than a conventional acquisition. Santersus shareholders will hold the large majority of the post-transaction equity, Santersus management is expected to lead the combined company, and the new board is expected to include six Santersus nominees and two Xenetic nominees.

Building a Broader NET-Targeting Platform

The strategic rationale centers on combining complementary approaches to targeting NETs.

NETs are web-like structures released by neutrophils as part of the immune response. While they can help trap pathogens, excessive or persistent NET formation has also been implicated in inflammation, thrombosis, tissue injury and disease progression across a range of conditions.

Santersus is developing NucleoCapture, a therapeutic blood-filtration platform designed to remove circulating NETs and related pathogenic components directly from the bloodstream. The company has been pursuing applications in conditions including sepsis, systemic lupus erythematosus and liver transplantation.

Xenetic brings a different approach through its DNase platform, which is designed to enzymatically degrade NETs. Xenetic has been developing this approach primarily in oncology, including as a potential way to improve the effectiveness of cancer therapies such as CAR-T by reducing the protective effects NETs may provide within the tumor microenvironment.

The combined company would therefore have both extracorporeal and biologic approaches to the same broad target, creating a portfolio that spans inflammatory disease, transplantation and oncology.

Santersus Brings the Lead Clinical-Stage Asset

Santersus’ NucleoCapture platform is expected to become the principal clinical development focus of the combined company. The technology is designed to filter NETs and other disease-associated extracellular material from circulating blood without broadly suppressing the immune system. Santersus has positioned the platform for acute and immune-mediated conditions where excessive NET formation may contribute to disease severity.

The company’s development programs include sepsis, lupus and liver transplantation, areas where treatment options can be limited and where severe inflammatory responses may cause substantial organ damage. For Xenetic, the transaction significantly broadens its development pipeline while moving the combined organization closer to clinically advanced opportunities than Xenetic would have on its own.

Governance Reflects the Economic Structure

The post-transaction governance reinforces the fact that this is not a typical buyer-target acquisition. Santersus’ leadership is expected to run the combined company, while Xenetic will contribute its Nasdaq listing, existing programs and corporate infrastructure. The board composition is also expected to tilt heavily toward Santersus, consistent with the roughly 85/15 ownership split.

That makes the transaction structurally similar to other biotech combinations in which a private company gains access to the public markets through a merger with an existing listed entity. For investors, the key point is that the future investment thesis will be driven primarily by Santersus’ clinical programs and the broader NET-targeting strategy, rather than by Xenetic’s historical business alone.

Why NET Biology Is Drawing Interest

The scientific interest in NETs has grown as researchers have linked excessive NET formation to a wide range of inflammatory, thrombotic and immune-mediated diseases. In sepsis, NETs may contribute to microvascular obstruction, inflammation and organ damage. In autoimmune disease, persistent NET formation has been associated with immune dysregulation. In transplantation, the same inflammatory mechanisms may contribute to ischemia-reperfusion injury and graft dysfunction.

That broad biological relevance creates opportunities, but it also raises an important development challenge: showing that targeting NETs can translate into meaningful clinical outcomes across specific indications. The combined Santersus/Xenetic company will need to demonstrate not only that NET burden can be reduced, but that doing so improves patient outcomes in well-defined patient populations.

A Broader Biotech Theme: Controlling Harmful Immune Responses

The transaction also fits into a wider biotechnology trend involving therapies designed to control damaging immune activity without broadly shutting down the immune system.

One related company followed by Noble Capital Markets is Eledon Pharmaceuticals (NASDAQ: ELDN). Eledon is developing tegoprubart, an anti-CD40L antibody designed to prevent immune rejection in organ and islet-cell transplantation while avoiding some of the limitations associated with conventional immunosuppressive drugs. Noble research has highlighted Eledon’s kidney-transplant and islet-transplant programs as the company advances tegoprubart through clinical development.

The mechanisms are different, but the strategic overlap is clear: both Santersus and Eledon are pursuing more targeted ways to address harmful immune activity in settings where excessive inflammation or immune rejection can drive poor outcomes.

Cadrenal Adds a Critical-Care Parallel

Another Noble-covered company with a related critical-care angle is Cadrenal Therapeutics (NASDAQ: CVKD). Cadrenal is developing therapies for serious thrombotic and cardiovascular conditions, including tecarfarin and CAD-1005. Its pipeline includes programs in heparin-induced thrombocytopenia and other acute-care settings where thrombosis and coagulation abnormalities can create significant clinical risk.

Again, the biology is different, but Cadrenal provides another example of a small-cap biotechnology company targeting severe, high-risk conditions where existing therapies may be inadequate and where improved control of inflammation, coagulation or immune dysfunction could have meaningful clinical value.

A Public-Market Reset for Xenetic

For Xenetic shareholders, the transaction represents a major reset of the company’s strategic direction. If completed, the combined company will be much more heavily defined by Santersus, both economically and operationally. Existing Xenetic shareholders will retain a minority position in a broader NET-targeting platform that includes multiple clinical indications and a new management team.

For Santersus, the agreement provides a path to the U.S. public markets and access to a Nasdaq-listed platform without pursuing a traditional initial public offering. The result is a combination designed to create a more diversified biotechnology company around a relatively focused scientific thesis: that excessive NET formation plays a meaningful role across inflammatory, transplant and oncology indications, and that directly targeting those NETs could create new therapeutic opportunities.

If the transaction closes as planned, investors will be evaluating the new Santersus Bio less as a continuation of Xenetic and more as a newly assembled NET therapeutics company with a substantially different pipeline, ownership structure and clinical focus.

EverBank and WaFd Strike $3.9 Billion Reverse Merger to Create $75 Billion Regional Bank

EverBank Financial Corp and WaFd, Inc. (NASDAQ: WAFD) announced a $3.9 billion reverse merger Monday that would create a regional banking company with approximately $75 billion in assets and a substantially larger national footprint.

Under the agreement, privately held EverBank Financial Corp will merge into WaFd, with WaFd remaining the publicly traded holding company. Following completion of the transaction, however, WaFd will adopt the EverBank Financial Corp name and begin trading on the Nasdaq under the new ticker symbol EVBK. EverBank will be treated as the accounting acquirer.

The structure effectively provides EverBank and its private investors with a path back to the public markets while giving WaFd shareholders exposure to a significantly larger banking platform.

EverBank investors, including funds managed by Stone Point Capital, Warburg Pincus, Reverence Capital Partners, Sixth Street and Bayview Asset Management, along with TIAA, are expected to own approximately 59.2% of the combined company. Existing WaFd shareholders would own the remaining 40.8%.

Building Scale Across Markets and Banking Channels

The combination brings together two banks with notably different but complementary footprints.

Jacksonville-based EverBank had approximately $46.7 billion in assets and $37.7 billion in deposits as of June 30, with a business built around nationwide digital banking as well as financial centers in California, Florida and New York. Seattle-based WaFd had approximately $27.6 billion in assets and $21.0 billion in deposits, supported by more than 200 branches across nine western states.

Together, the companies are expected to have roughly $75 billion in assets, $58 billion in loans and $59 billion in deposits, with 254 branches across the country.

That combination gives the enlarged bank something each institution currently has less of on its own: EverBank adds a scalable national digital deposit platform and broader commercial lending capabilities, while WaFd contributes a substantial branch network, established commercial relationships and significant commercial real estate lending expertise.

Both institutions have also been shifting their businesses toward commercial banking and away from a heavier historical reliance on residential and consumer lending. Management expects the combination to provide additional opportunities across commercial lending, SBA lending, wealth management and other fee-generating businesses.

A Significant Earnings Boost for WaFd Shareholders

The financial projections are a major component of the transaction.

The companies expect the merger to increase WaFd’s 2027 earnings per share by approximately 29%, while producing a return on tangible common equity of approximately 15% once anticipated cost synergies are fully realized. Management also expects the tangible book value dilution associated with the deal to be earned back in less than two years.

Those figures could be particularly important for investors evaluating the transaction. Bank mergers frequently offer compelling strategic arguments around scale, deposits and geographic expansion, but ultimately depend on whether anticipated cost savings and revenue opportunities translate into improved shareholder returns.

Here, management is putting forward a relatively aggressive near-term earnings-accretion target alongside the strategic benefits of the combination.

EverBank Leadership Takes the Helm

The post-merger management structure also reflects EverBank’s larger economic ownership of the combined institution.

EverBank CEO Greg Seibly will become chief executive officer of the combined company, while current WaFd CEO Brent Beardall will serve as president. EverBank Chairman Robert Radway will chair the combined company.

The new board will have 13 members, including seven directors representing legacy EverBank and six representing legacy WaFd.

Although WaFd is technically the surviving publicly traded holding company, EverBank’s shareholders will hold the majority of the equity and its leadership will occupy several of the most important positions – characteristics that help explain the transaction’s reverse-merger designation.

Another Sign of Consolidation in Regional Banking

The EverBank-WaFd combination also arrives as scale has become increasingly important for regional banks facing higher technology and compliance costs, intense competition for deposits and continued pressure to diversify revenue.

At roughly $75 billion in assets, the combined institution would move into the upper tier of U.S. regional banks while retaining a footprint well below that of the country’s largest money-center institutions. The merger could provide the organization with greater resources to spread technology and operating costs across a larger asset and deposit base while broadening its geographic and product diversification.

The transaction is expected to close in early 2027, subject to regulatory approvals, approval from WaFd shareholders and other customary closing conditions. It is expected to be tax-free to shareholders of both companies.

For WaFd investors, the focus will now turn to whether the companies can deliver the projected 29% earnings accretion and successfully integrate two banking models that, while complementary, have developed around very different geographic and customer footprints. If management can execute on those targets, the reverse merger could transform WaFd from a primarily western regional bank into a considerably larger national banking franchise.

Fulcrum Therapeutics Is Becoming a Migraine Drug Company. Here Is How

Fulcrum Therapeutics (Nasdaq: FULC) announced Monday it has entered into a definitive agreement to merge with privately held Slate Medicines in an all-stock transaction. The combined company will operate under the Slate Medicines name and pivot entirely away from Fulcrum’s original rare hematological disease pipeline toward Slate’s portfolio of next-generation migraine therapeutics. Alongside the merger, the companies announced an oversubscribed $245 million private placement from a syndicate of healthcare investors, expected to fund the combined operations into 2029.

This deal follows one of the more difficult stretches in Fulcrum’s history, and understanding that context is essential to understanding why this transaction exists at all. In June, Fulcrum discontinued development of pociredir, its lead drug candidate for sickle cell disease, after the FDA raised concerns about the drug’s benefit-risk profile in a recent meeting. Regulators specifically flagged an unexpectedly high rate of secondary hematologic malignancies observed in patients treated with a chemically related PRC2 inhibitor from another company, a drug that its own manufacturer had voluntarily pulled from shelves worldwide earlier this year. Fulcrum’s stock fell more than 50% on the news, and the company subsequently laid off 48 of its 57 employees, roughly 85% of its workforce, while beginning a formal review of strategic alternatives that included a merger, business combination, or other transaction. As of March 31, Fulcrum held $333.3 million in cash and marketable securities, enough runway to keep the company operating into 2029 on its own. Separately, and worth noting for full transparency, a law firm publicly announced last week it is investigating potential securities law violations tied to Fulcrum’s disclosures around the pociredir discontinuation. That investigation is ongoing and its outcome, if any, is not yet known.

Slate’s lead candidate, SLTE-1009, is a clinical-stage subcutaneous monoclonal antibody targeting PACAP and VIP pathways, developed as a potentially best-in-class preventative treatment for migraine. Migraine remains a large and underserved therapeutic market, and antibody-based preventative treatments targeting neuropeptide pathways have become one of the more actively pursued mechanisms in the space over the past several years.

A Familiar Small Cap Biotech Pattern

This transaction follows a structure we have covered before on ChannelChek: a publicly traded biotech whose original clinical program failed, leaving it with a Nasdaq listing, meaningful cash reserves, and no viable path forward on its own, becomes the vehicle through which a well-funded private biotech gains public market access without pursuing a traditional IPO. Rather than navigating the lengthy IPO process independently, Slate secures a public listing, a syndicate of institutional capital, and immediate resources to advance its lead asset, all in a single coordinated transaction.

For investors tracking this space, the Fulcrum-Slate combination is a useful reminder that a failed clinical trial does not automatically end a company’s story, particularly when meaningful cash remains on the balance sheet. It also underscores a genuine risk worth weighing carefully: shareholders who bought into Fulcrum’s original rare disease thesis are now effectively invested in an entirely different company, pursuing an unrelated therapeutic area, following a transaction that arrives while questions about the prior program’s disclosures remain unresolved. Reverse mergers of this type can create real value when the incoming asset is genuinely differentiated, but investors should evaluate the new company on its own clinical and commercial merits rather than assuming continuity with the business they originally invested in.

Star Equity Holdings, Inc. (STRR) – Second Quarter Results And An Acquisition


Monday, August 17, 2026

Joe Gomes, CFA, Managing Director, Equity Research Analyst, Generalist , Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Overview. In the second quarter, Business Services delivered modest revenue growth, with gross profit down slightly year-over-year, while Energy Services posted strong year-over-year gains in revenue, gross profit, and adjusted EBITDA, reflecting activity increases and new client wins in the geothermal and mining industries. Building Solutions remained below management expectations due to market softness and contract timing.

2Q26 Results. Second quarter 2026 revenue was $54.9 million versus a pro forma $59.2 million in 2Q25. We were at $64 million. The delta was in Building Solutions, which continues to operate in a challenging environment. Adjusted EBITDA was $2.2 million versus a pro forma $8.5 million, which included a $5.5 million gain. Star reported an adjusted loss of $0.15/sh in 2Q26 compared to EPS of $0.20/sh in 2Q25.


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

Nielsen’s $2.15 Billion DoubleVerify Deal: A 30% Premium That Still Locks In a Loss

Nielsen is buying DoubleVerify for $13.60 a share in cash — a 30% premium, the press release says. That premium is real. It’s also about half of what DoubleVerify’s stock fetched the day it went public. Both things are true at once, and the gap between them is the most instructive part of this deal.

Here’s what happened. On Wednesday, Nielsen — itself taken private by a private equity consortium a few years back — agreed to acquire DoubleVerify (NYSE: DV) in an all-cash deal worth roughly $2.15 billion in enterprise value. Shareholders get $13.60 per share, a 30% premium to the stock’s 60-trading-day average through August 5. The deal should close by the first quarter of 2027, after which DoubleVerify delists from the NYSE, becomes a private company under Nielsen, and keeps its name. Providence Equity, which owns about 12%, has agreed to vote in favor.

DoubleVerify isn’t a broken company — and that’s the point. It’s the leading independent platform for ad verification: the plumbing that confirms a digital ad impression was actually seen by a real person, in a brand-safe place, free of fraud. It’s accredited, embedded in the workflows of the world’s biggest advertisers, and it works — 2025 revenue landed around $748 million, up roughly 14%, with real profit and strong free cash flow. A healthy, growing, cash-generative business.

So why is it being bought at $13.60?

Because the market stopped paying up for it. DoubleVerify went public in April 2021 at $27 a share and ran to nearly $47 within months, briefly worth more than $5 billion. Then ad-tech multiples collapsed. Even as the company kept growing revenue and profit year after year, the stock got cut in half, then cut again, bottoming below $8 last year. The business went up and to the right; the multiple went down and to the left. By this week the whole company was worth under $2 billion — less than half its peak value, despite being bigger and more profitable than it was then.

That’s the lesson for anyone hunting the small end of the market. A 30% premium sounds generous until you notice it’s measured off a badly depressed base. IPO buyers are being cashed out at roughly half their money; anyone who chased the 2021 hype is down far more. The premium is genuine against last month’s price — and a permanent loss against the promise the stock once carried.

It also explains the take-private wave we’ve watched all week. When public markets abandon a profitable company and refuse to re-rate it no matter how well it executes, someone with a longer horizon eventually buys the cash flows on the cheap. That’s exactly what Nielsen is doing — and it’s the same logic behind deal after deal in 2026: good small and mid-cap businesses quietly pulled off the public market at prices that reflect the market’s indifference, not the company’s quality.

For DoubleVerify shareholders, it’s a bittersweet exit — a premium today that locks in yesterday’s de-rating. For everyone else, it’s a map. The hunting ground right now is full of profitable, overlooked small-caps trading far below what they’re worth to a patient owner. And the public market keeps losing them, one deal at a time.

Perfect (PERF) – Merger Agreement Signed; Share Performance Now Tied to Closing


Monday, August 03, 2026

Michael Kupinski, Director of Research, Equity Research Analyst, Digital, Media & Technology , Noble Capital Markets, Inc.

Jacob Mutchler, Research Analyst, Noble Capital Markets, Inc.

Refer to the full report for the price target, fundamental analysis, and rating.

Definitive merger agreement signed. Perfect has entered into a definitive agreement to be acquired by a consortium led by founder and CEO Alice Chang for $2.00 per share in cash. A higher bid remains possible, but unlikely given buyer protections. 

Transaction risk materially reduced. The merger was unanimously approved by the Board following the recommendation of an independent Special Committee. In addition, the buyer group has secured voting support representing approximately 53.4% of the outstanding shares and 81.2% of the Company’s voting power. There is an 8% dissenting-share condition, although the controlling group’s voting support still makes shareholder approval highly likely. 


Get the Full Report

Equity Research is available at no cost to Registered users of Channelchek. Not a Member? Click ‘Join’ to join the Channelchek Community. There is no cost to register, and we never collect credit card information.

This Company Sponsored Research is provided by Noble Capital Markets, Inc., a FINRA and S.E.C. registered broker-dealer (B/D).

*Analyst certification and important disclosures included in the full report. NOTE: investment decisions should not be based upon the content of this research summary. Proper due diligence is required before making any investment decision. 

argenx Pays an 86% Premium for Forte Biosciences. What Made a Clinical-Stage Biotech Worth $2.2 Billion

argenx (Euronext & Nasdaq: ARGX) announced Monday it has entered into a definitive agreement to acquire Forte Biosciences (Nasdaq: FBRX) for $77 per share in cash, a total equity value of approximately $2.2 billion. The price represents an 86% premium to Forte’s volume-weighted average trading price since July 9, when the company reported positive Phase 1b data in vitiligo. That is an unusually large premium even by the standards of this year’s active biotech M&A market, and it reflects just how quickly clinical data can transform a small cap company’s valuation.

The transaction is structured as a cash tender offer funded entirely from argenx’s existing cash on hand, with no financing condition attached. Closing is expected in the third quarter of 2026, subject to a majority of Forte shares being tendered and clearance under the Hart-Scott-Rodino Antitrust Improvements Act.

From Strategic Investor to Full Acquirer

This deal did not appear out of nowhere. argenx had already made a strategic investment in Forte Biosciences prior to this announcement, giving it an early window into the company’s clinical progress before committing to a full buyout. That structure, investing first and acquiring later once the data supports it, reflects a disciplined approach that reduces risk for the acquirer while still preserving the option to move quickly once a program proves itself out.

The proof came fast. Forte’s lead asset, FB102, is a first-in-class anti-CD122 antibody that recently delivered statistically significant Phase 1b results in vitiligo, following earlier positive Phase 1b data in celiac disease reported last year, with Phase 2 celiac data expected in the second half of 2026. Those clinical readouts were the direct trigger for argenx’s decision to convert its strategic stake into a full acquisition.

Why CD122 Biology Matters

FB102’s mechanism targets pathogenic T-cell and NK-cell activity through CD122 biology, a distinct approach from the antibody mechanisms already in argenx’s portfolio, which includes efgartigimod, empasiprubart, adimanebart, and ARGX-121. Rather than duplicating existing capability, the acquisition broadens argenx’s ability to address autoimmune disease through an entirely different dimension of immune system dysfunction.

The commercial upside extends well beyond vitiligo and celiac disease. Management described FB102 as having pipeline-in-a-product potential, meaning the same molecule could eventually address multiple autoimmune conditions including alopecia areata, each representing a separate commercial opportunity from a single clinical asset. That kind of multi-indication potential is precisely what allows a clinical-stage company with no approved products to command a multibillion-dollar acquisition price.

What It Signals for Small Cap Biotech Investors

For investors tracking clinical-stage companies in the small and microcap immunology and autoimmune disease space, the Forte transaction reinforces a pattern that has defined biotech M&A throughout 2026. Large, well-capitalized immunology and oncology platforms are increasingly using strategic minority investments as a low-risk way to monitor promising early-stage science, then moving decisively to full acquisitions once clinical data de-risks the program. Statistically significant Phase 1b results, even well ahead of any approval pathway, are proving sufficient to justify premiums approaching 90% over recent trading prices.

That dynamic matters for the broader small cap biotech landscape. Companies advancing differentiated mechanisms in autoimmune disease, a therapeutic area with persistent unmet need and limited recent innovation, are demonstrating that credible early clinical validation can translate into outsized valuation outcomes well before a drug ever reaches the market. The Forte deal is the latest evidence that the current biotech M&A cycle rewards genuine scientific differentiation over scale.

Stripe and Advent Just Offered $53 Billion for PayPal

The biggest potential acquisition in fintech history is now on the table. Stripe, the privately held payments giant valued at $159 billion, and private equity firm Advent International have submitted a joint offer to acquire PayPal Holdings (Nasdaq: PYPL) for $60.50 per share in a deal valued at more than $53 billion. The offer represents a 28% premium to PayPal’s closing price on July 14 and is backed by approximately $50 billion in committed bank financing. PayPal shares surged roughly 18% on the news.

PayPal has not formally responded to the proposal. Stripe and Advent are reportedly pushing to advance discussions over the coming weeks. Under the terms of the offer, the two firms would share ownership of PayPal on an equal basis, with no plans to break up or dismantle the company.

How PayPal Got Here

The offer arrives at a moment of profound vulnerability for a company that once defined digital payments. At its 2021 peak, PayPal commanded a market capitalization of approximately $360 billion. By early 2026, that figure had fallen to as low as $36 billion, a decline of roughly 90% driven by years of slowing growth, intensifying competition from Apple Pay, Google Pay, and a new generation of embedded payment platforms, and repeated failed turnaround attempts that left investors skeptical of the company’s ability to reclaim relevance.

The current leadership team, led by new CEO Enrique Lores who replaced Alex Chriss earlier this year, has launched a restructuring built around a three-unit organizational model and announced plans to cut approximately 20% of the workforce, roughly 4,760 positions, as part of an effort to generate at least $1.5 billion in gross run-rate savings. The company’s full-year 2026 adjusted profit guidance calls for a low-single-digit percentage decline, a forecast that does not inspire confidence in a rapid recovery.

At roughly eight times projected 2026 earnings, PayPal trades at a multiple well below most of its fintech peers, a discounted valuation that has made it an increasingly obvious target for a strategic acquirer with the scale and resources to execute what current management has not been able to deliver.

Why Stripe Wants PayPal

Stripe has built a dominant position in merchant payments infrastructure, powering the backend payment processing for millions of businesses globally. What it lacks is a large-scale consumer payments brand. PayPal, despite its struggles, still maintains one of the most recognized consumer payment platforms in the world, with hundreds of millions of active accounts and deeply embedded relationships with both consumers and merchants across global e-commerce.

Combining the two would create a payments entity spanning both sides of the transaction, merchant infrastructure and consumer wallet, with combined processing volume that would rival any player in the industry. Both companies have also been prominent in bringing stablecoin capabilities onto traditional payment rails, positioning the combined entity at the intersection of legacy digital payments and next-generation blockchain-based settlement.

What It Signals for Smaller Fintech Companies

For investors tracking fintech companies in the small and microcap space, a $53 billion deal for PayPal sends an unmistakable signal about where consolidation pressure is headed. When the largest private payments company in the world moves to acquire the most recognizable consumer payments brand, the competitive dynamics for every smaller player in the ecosystem shift. Niche payment processors, vertical-specific fintech platforms, and emerging stablecoin infrastructure companies either become more attractive acquisition targets themselves or face a combined competitor with unprecedented scale.

The Nuvei-Payoneer combination we covered last month was a $2.75 billion deal built around the same thesis: payments consolidation around platforms that can handle the full transaction lifecycle across borders. The Stripe-PayPal proposal takes that logic and multiplies it by a factor of twenty. The fintech M&A cycle is not winding down. It is escalating to a scale the industry has never seen.

Eli Lilly Pays $3.8 Billion for AtaiBeckley as Big Pharma’s Push Into Mental Health Enters a New Phase

The pharmaceutical industry’s appetite for neuroscience innovation just produced one of the most significant mental health deals in years. Eli Lilly (NYSE: LLY) announced Wednesday it has entered into a definitive agreement to acquire AtaiBeckley (Nasdaq: ATAI), a clinical-stage biopharmaceutical company developing rapid-acting therapies for treatment-resistant depression and other serious mental health conditions. The deal values AtaiBeckley at approximately $2.8 billion in upfront equity consideration, with an additional $1.0 billion in potential milestone-based contingent value rights, bringing the total potential transaction value to approximately $3.8 billion.

AtaiBeckley shareholders will receive $6.75 per share in cash at closing, representing a 40% premium to the stock’s 30-day volume-weighted average trading price. The contingent value rights are tied to specific development and regulatory milestones across the company’s two most advanced programs. The transaction is expected to close in the third quarter of 2026.

What Lilly Is Acquiring

AtaiBeckley’s pipeline is built around a class of compounds called rapid-acting neuroplastogens, therapies designed to restore the brain’s ability to form and strengthen neural connections in regions critical to mood regulation. This is a fundamentally different approach from conventional antidepressants, which primarily target neurotransmitter levels. The distinction matters because treatment-resistant depression, by definition, persists after multiple conventional treatments have failed. Millions of Americans live with it, and the clinical need for a genuinely new mechanism of action is substantial.

The lead asset, BPL-003, is a synthetic form of 5-MeO-DMT delivered as a nasal spray. In a Phase 2b study, the compound demonstrated rapid and durable reductions in depressive symptoms following a single in-clinic visit lasting approximately two hours on average, with beneficial effects persisting for months. The FDA has granted BPL-003 Breakthrough Therapy Designation and Phase 3 activities are already underway.

The second program, VLS-01, is a buccal film formulation of DMT currently advancing in a Phase 2b study for treatment-resistant depression. A third asset, EMP-01, is an R-MDMA compound in Phase 2 development for social anxiety disorder. Together, the pipeline represents one of the most clinically advanced portfolios in the emerging psychedelic-derived therapeutics space.

The Bigger Picture for Neuroscience M&A

Lilly’s move into mental health through the AtaiBeckley acquisition reflects a growing recognition across the pharmaceutical industry that neuroscience, and specifically psychiatry, represents one of the largest underserved therapeutic markets remaining. The company framed the deal explicitly as an expansion of its neuroscience pipeline to address conditions where existing treatments consistently fall short.

The deal structure itself reveals how large pharma is approaching risk in this space. The $2.8 billion upfront payment secures the pipeline and the Phase 3 asset immediately. The $1.0 billion in CVRs ties additional payments to clearly defined regulatory and development milestones, aligning incentives between buyer and seller while limiting downside if programs do not advance as planned.

What It Signals for Small Cap Biotech

For investors tracking clinical-stage neuroscience and CNS-focused companies in the small and microcap space, the Lilly-AtaiBeckley transaction sends a direct signal. Large pharma is now willing to pay nearly $4 billion for a pre-revenue mental health company with Breakthrough Therapy Designation and Phase 3 readiness. That valuation framework applies to other companies advancing differentiated CNS programs through mid-to-late-stage development, including names like NeuroSense Therapeutics, both of which are developing therapies targeting neurological and psychiatric conditions with significant unmet need.

The biotech M&A wave that began with GSK-Nuvalent and AbbVie-Apogee earlier this year has now expanded beyond oncology into neuroscience. The message from large pharma is consistent: validated clinical data, Breakthrough Therapy Designation, and clear regulatory paths in large patient populations are commanding premium valuations regardless of therapeutic area. The pipeline of small cap companies fitting that profile remains deep.